
- Home
- »
- Medical Devices
- »
-
Medical Automation Market Size Report, 2026-2033GVR Report cover

Medical Automation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application Type (Therapeutic Automation, Laboratory & Pharmacy Automation), By End -use (Hospitals & Diagnostic Centers, Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$56.6BMarket Estimate, 2026
$61.6BMarket Forecast, 2033
$117.8BCAGR, 2026–2033
9.7%Medical Automation Market Summary
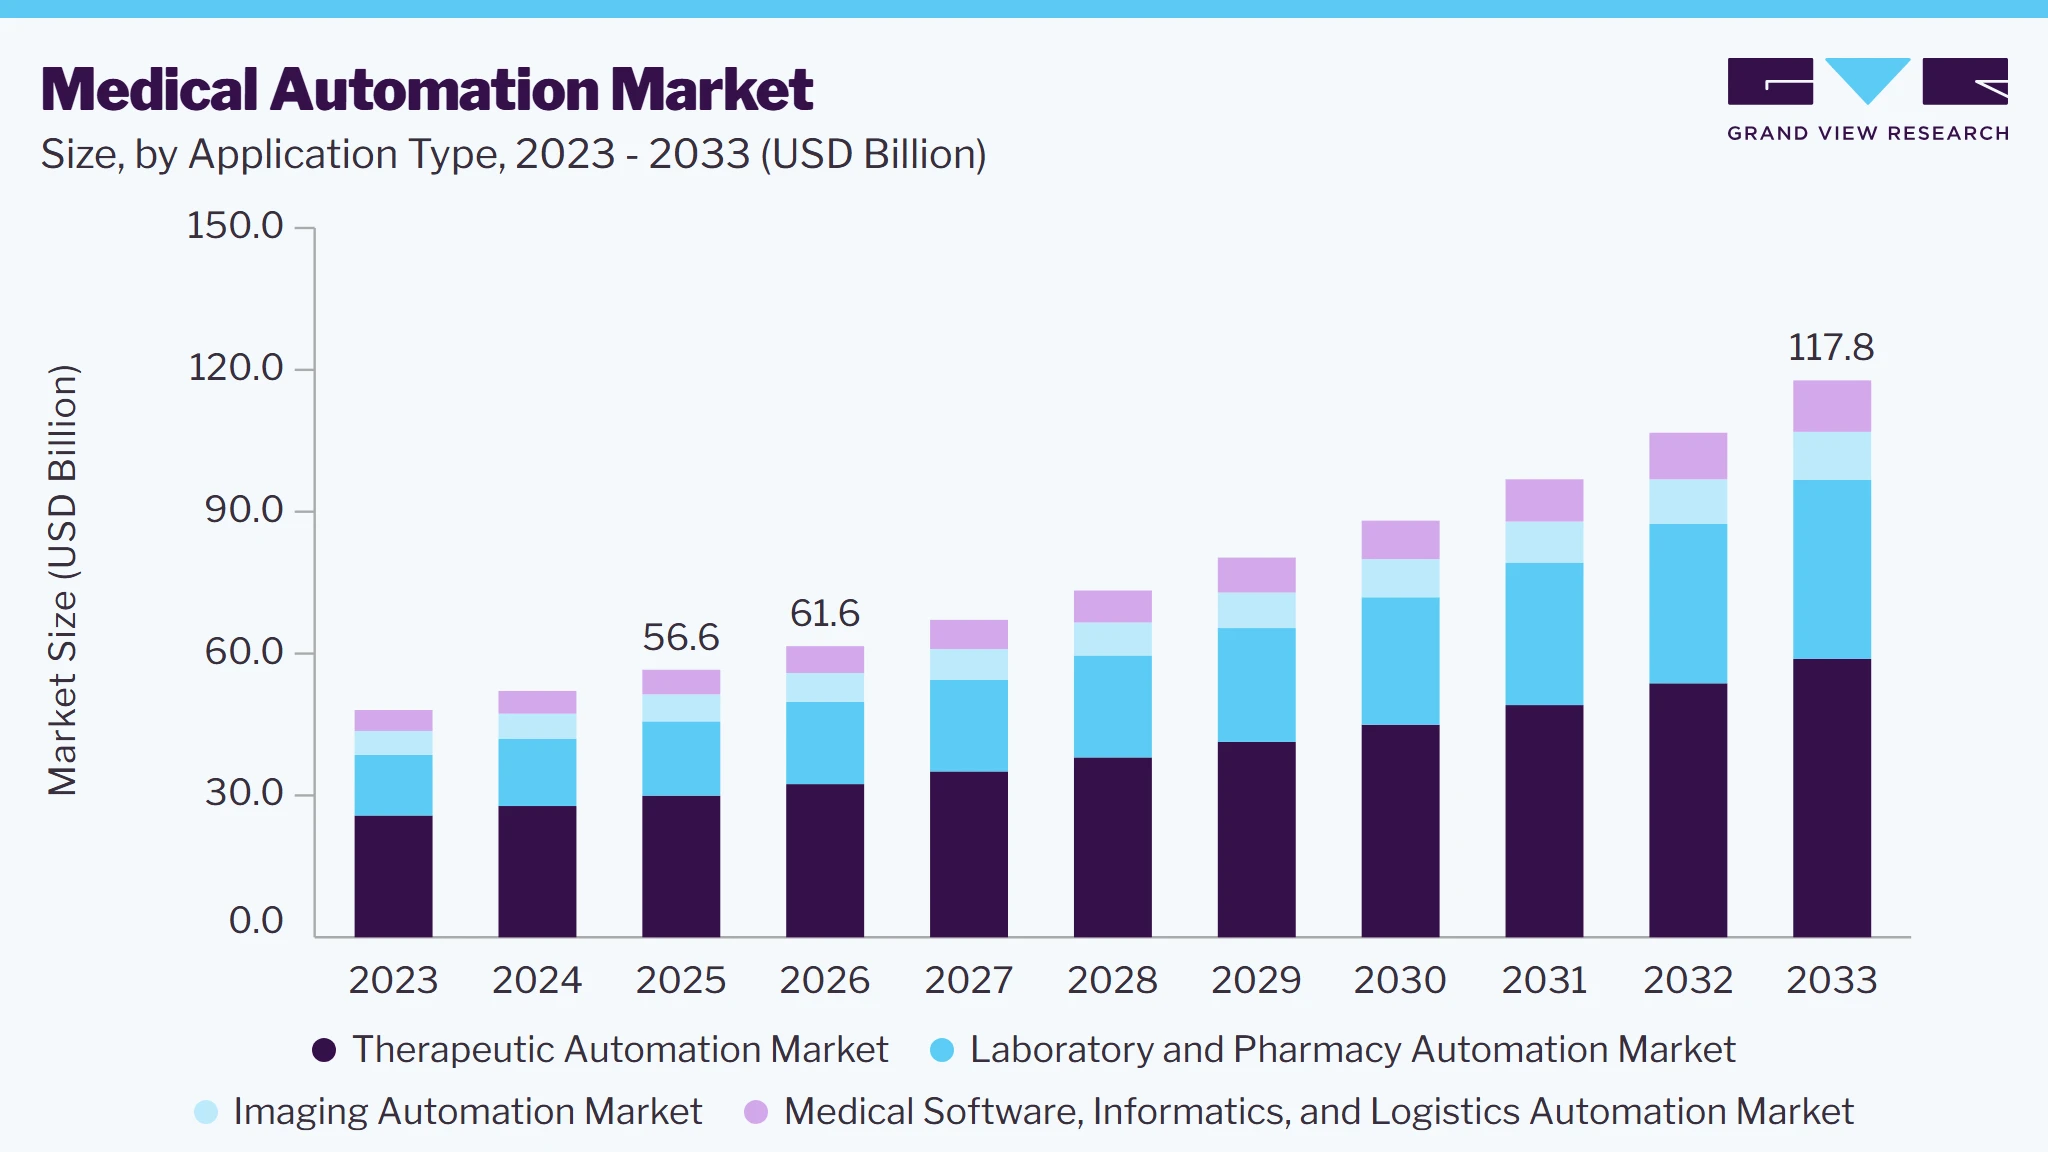
The global medical automation market size was valued at USD 56.6 billion in 2025 and is projected to grow from USD 61.6 billion in 2026 to USD 117.8 billion by 2033, at a CAGR of 9.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 43.5% in 2025. The market is driven by several key factors, including the increasing demand for efficiency and accuracy in healthcare delivery, the rise in chronic diseases necessitating improved diagnostic and treatment options, advancements in technology, and the push for regulatory compliance and enhanced patient safety.
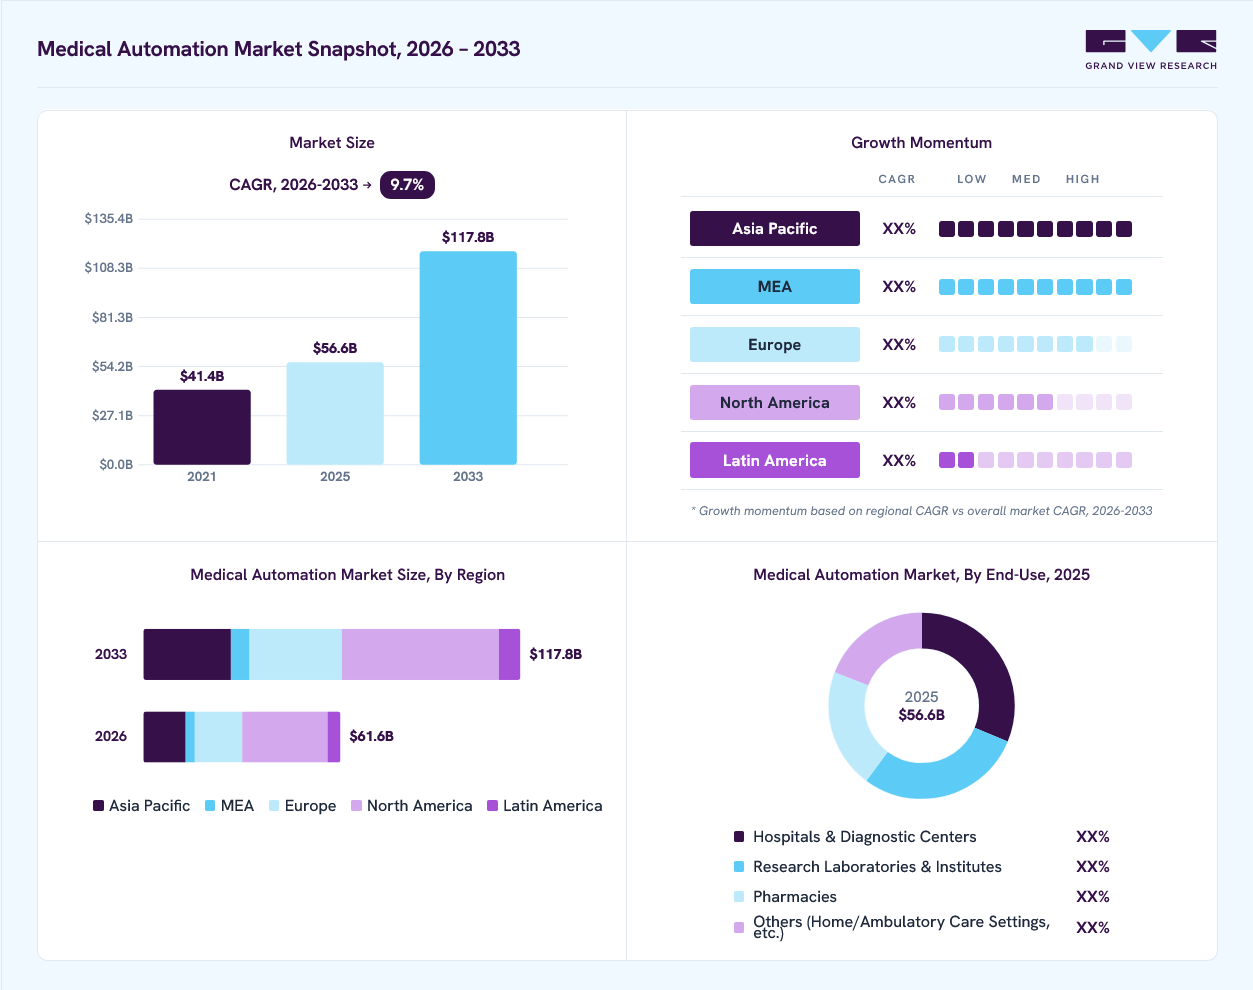 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application type: Therapeutic automation market segment held the largest revenue share of over 53.0% in 2025.
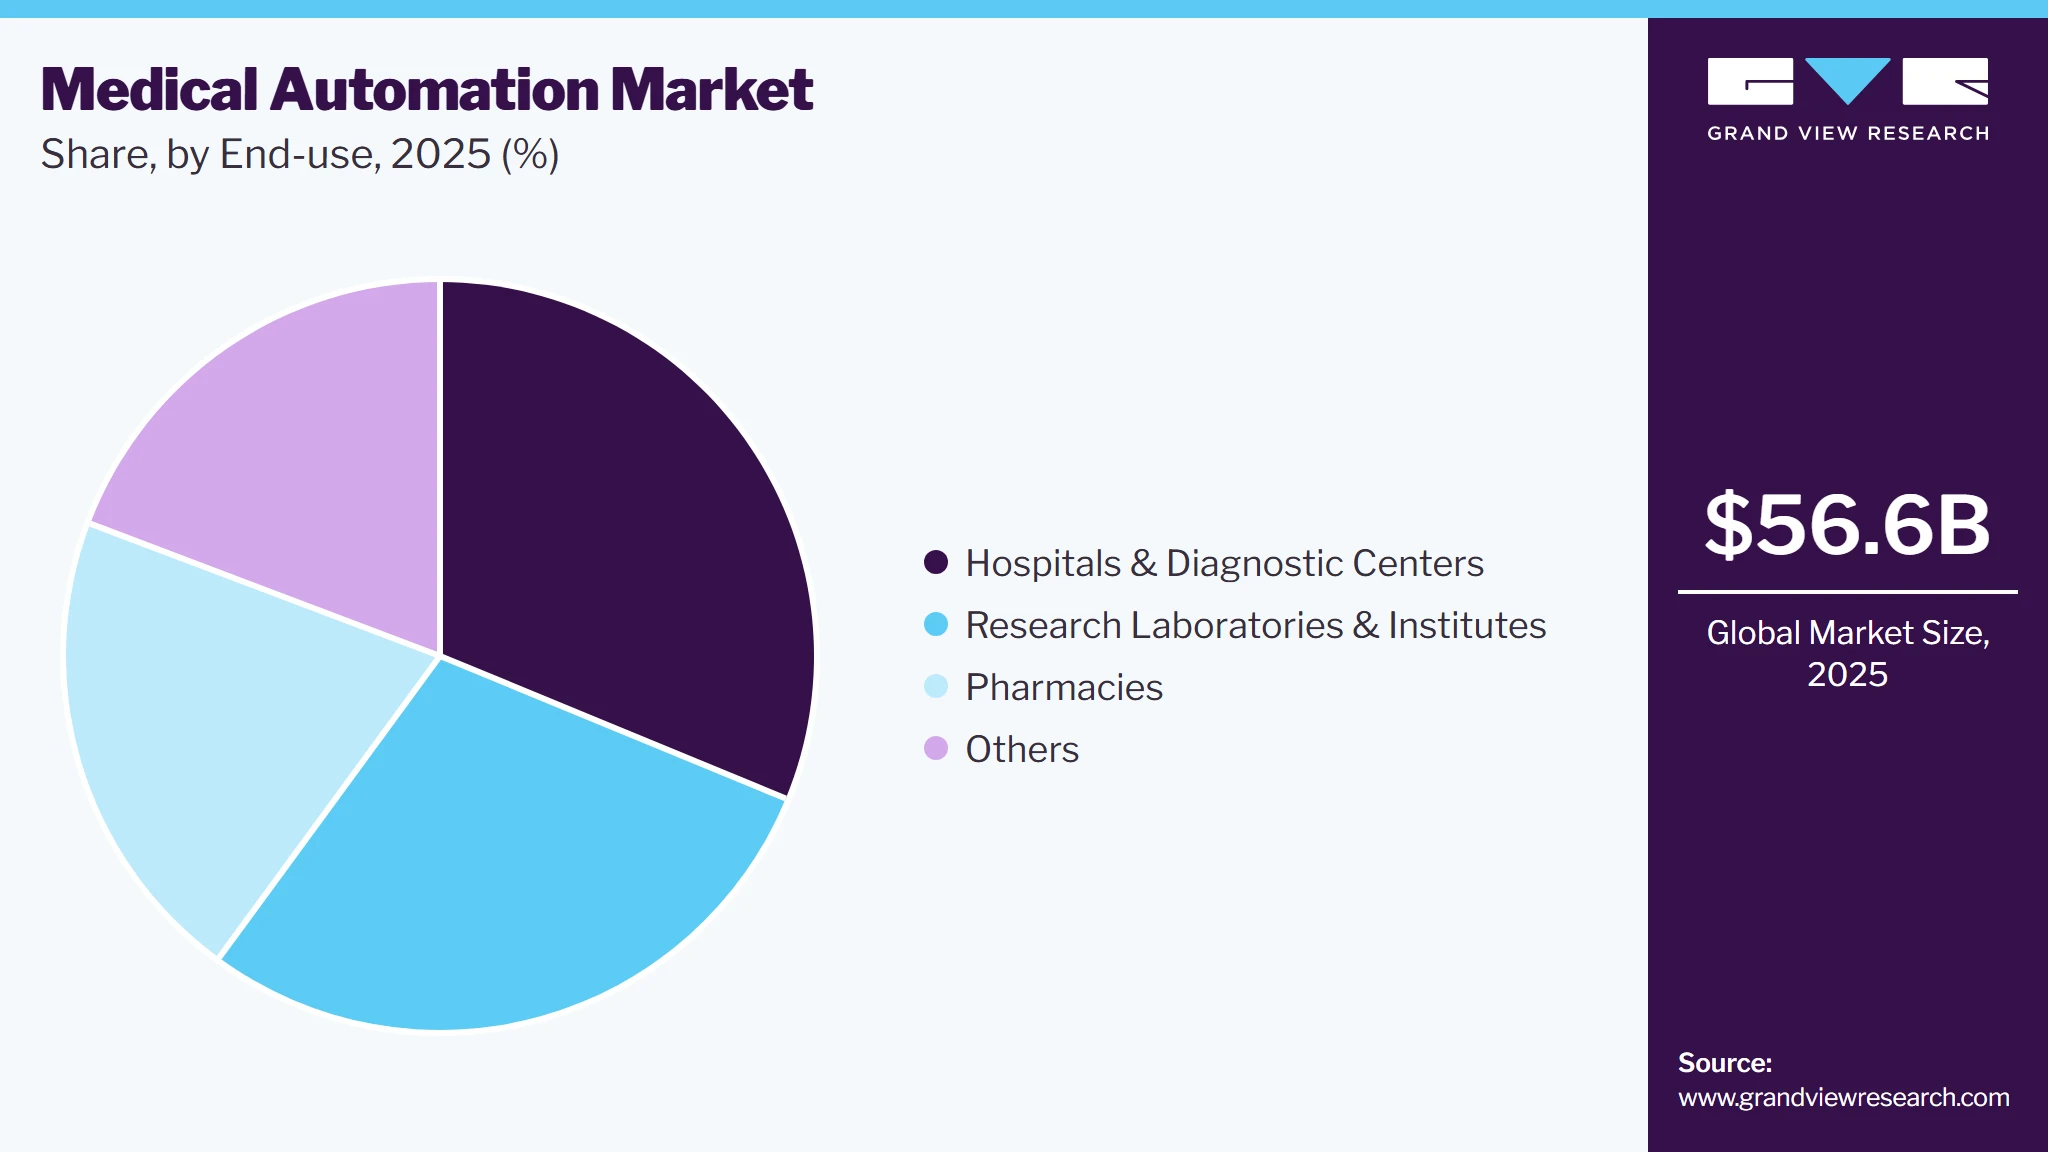
- By end use: Hospitals & diagnostic centers segment held the largest revenue share of over 31.2% in 2025.
Regional Highlights
- Largest regional market: North America (43.5% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 56.6 Billion
- Estimated market size in 2026: USD 61.6 Billion
- Projected market size by 2033: USD 117.8 Billion
- CAGR (2026-2033): 9.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Healthcare providers are under pressure to reduce costs while improving service quality, leading to a significant interest in technologies that streamline processes. According to the National Centre for Biotechnology Information (NCBI), hospitals implement automated laboratory testing and medication management systems, enabling them to serve more patients with better outcomes. This drive for efficiency pushes healthcare organizations to invest in automated solutions to meet rising patient expectations.Technological advancements also play a pivotal role in driving the market. Innovations in artificial intelligence, machine learning, and robotics are transforming healthcare delivery, enabling the development of advanced automated systems that enhance diagnostic accuracy and treatment precision. As technology evolves, healthcare providers increasingly adopt these automated solutions to stay competitive and improve patient care outcomes.
 To learn more about this report, Download Free Sample Report
The push for regulatory compliance and improved patient safety significantly influences the market. Stringent regulations imposed by healthcare authority demand that medical devices and processes adhere to high safety standards, making automation an appealing option for compliance. Automation helps minimize human errors, which can lead to adverse events in patient care.
Market Dynamics
The medical automation market is driven by the growing demand for improved healthcare efficiency, patient safety, and reduced human error across hospitals and healthcare facilities. Increasing adoption of robotic-assisted surgery, laboratory automation, pharmacy automation, and automated imaging systems is accelerating market growth. Advancements in artificial intelligence (AI), machine learning, and connected medical devices are further enhancing the capabilities of automation solutions. Rising healthcare expenditure, increasing surgical procedures, and expanding investments in smart hospitals are also supporting market expansion.
In addition, the growing shortage of healthcare professionals is encouraging providers to automate repetitive clinical and administrative tasks. However, high implementation costs, integration challenges with legacy systems, cybersecurity concerns, and stringent regulatory requirements continue to restrain market growth.
Healthcare organizations are increasingly integrating smart operating rooms, AI-enabled clinical decision support, automated patient monitoring, and interoperable hospital automation platforms to streamline clinical workflows, optimize resource utilization, and improve operational efficiency. These technological advancements are encouraging healthcare providers to modernize their healthcare infrastructure and invest in next-generation medical automation solutions, thereby driving sustained market growth.
For instance, in April 2025, Medtronic announced that its Hugo robotic-assisted surgery (RAS) system successfully achieved the primary safety and effectiveness endpoints in the U.S. Expand URO clinical trial. The milestone represents a significant step toward broader commercialization of the platform and highlights the growing adoption of robotic-assisted surgical technologies aimed at improving clinical precision and expanding automation within modern healthcare environments.
The high implementation and lifecycle costs associated with medical automation systems continue to pose a significant challenge to market growth. The deployment of advanced automation technologies including robotic surgical platforms, laboratory automation systems, automated medication dispensing solutions, intelligent operating rooms, and AI-enabled diagnostic imaging equipment requires substantial upfront capital investment in hardware, software, infrastructure upgrades, and system integration.
The rapid expansion of smart hospitals and AI-powered healthcare automation across emerging economies presents a significant growth opportunity for the medical automation market. Governments and healthcare providers across Asia Pacific, Latin America, and the Middle East are increasing investments in digital healthcare infrastructure, hospital modernization programs, and intelligent medical technologies to improve healthcare accessibility, clinical efficiency, and patient outcomes. For instance, in March 2025, GE HealthCare announced the launch of its AI-enabled Revolution Vibe CT system in India. The platform is designed to improve diagnostic accuracy, enhance imaging workflow efficiency, and expand access to advanced diagnostic technologies, reflecting the company's continued focus on strengthening its presence in emerging markets through AI-powered medical automation and intelligent imaging solutions. Such initiatives are creating substantial demand for automated diagnostic systems, robotic-assisted surgical platforms, laboratory automation, pharmacy automation, and AI-driven clinical workflow solutions.
Market Concentration & Characteristics
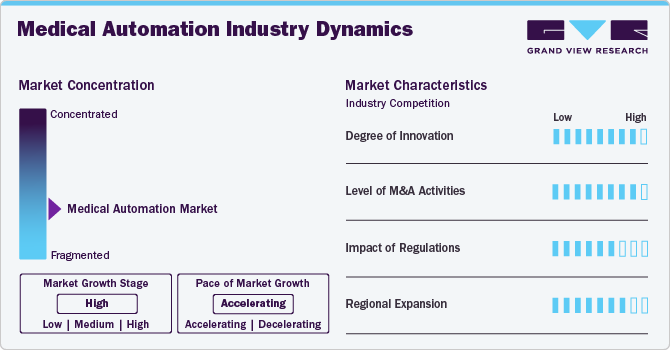
The degree of innovation in the market is high, characterized by rapid advancements in technologies such as artificial intelligence, robotics, and data analytics. Companies are increasingly integrating AI into diagnostic tools and treatment protocols, enhancing accuracy and efficiency. For instance, in July 2024, FUJIFILM Healthcare Americas Corporation launched the APERTO Lucent, a 0.4T MRI system featuring advanced permanent magnet technology and a unique single-pillar design.
The level of mergers and acquisitions (M&A) activities in the market is high, with a continuous flow of strategic partnerships to expand capabilities and market reach. For instance, in May 2023, Aspirion acquired FIRM Revenue Cycle Management Services, Inc. (“FIRM RCM”), which works with hospital systems to recover medical insurance claims that were denied, unpaid, or underpaid.
 To learn more about this report, Download Free Sample Report
The impact of regulations on the market is medium, as compliance with strict healthcare standards is essential for product development and market entry. Regulatory bodies like the FDA in the U.S. and the EMA in Europe impose rigorous guidelines on medical devices and software, affecting the pace of innovation. For instance, in December 2023, Abbott's innovative solution, GLP Systems Track, received approval from the U.S. FDA and is now accessible in the U.S. This system provides laboratories with advanced features to meet high-volume demands and enhance productivity.
Regional expansion in the market is driven by varying factors across key geographies. In North America, advanced healthcare infrastructure, early adoption of cutting-edge technologies, and strong regulatory frameworks are accelerating growth. Europe is witnessing increased investments in automation to improve patient care, driven by government initiatives focused on digital health and aging populations. In the Asia-Pacific region, rapid urbanization, expanding healthcare access, and rising demand for high-quality care are promoting the adoption of medical automation technologies. Countries such as China and India are emerging as significant markets due to growing healthcare expenditure and the need to enhance efficiency in hospitals and clinics. Latin America and the Middle East are also gaining momentum as healthcare providers in these regions seek to modernize operations and address the increasing burden of chronic diseases.
Analyst Perspective
The increasing adoption of robotic-assisted surgery, AI-enabled medical devices, laboratory automation, pharmacy automation, and intelligent imaging systems across healthcare facilities. Healthcare providers are investing in automation technologies to improve operational efficiency, reduce human error, enhance patient safety, and address workforce shortages. Advancements in artificial intelligence, machine learning, computer vision, and connected healthcare technologies are further expanding the capabilities of medical automation solutions.
Leading companies are focusing on product innovation, AI integration, strategic partnerships, and geographic expansion. The growing adoption of smart hospitals, digital operating rooms, and automated laboratory workflows is expected to create growth opportunities, particularly in emerging markets. However, high implementation costs, integration challenges with legacy hospital systems, cybersecurity concerns, and stringent regulatory requirements remain key challenges.
Case Study & Insights
A case study titled “Automating DaVita Labs to Increase Productivity" was published by Siemens Healthcare Private Limited in December 2021. This research shows significant enhancements in performance and efficiency achieved through the automation of diagnostic laboratories, especially when combined with effective implementation and change management strategies.
Challenge:
Creating a new lab with advanced processes and sufficient throughput to replace two high-volume facilities posed significant challenges. Maintaining current throughput in the older facilities until the new lab was operational added complexity. DaVita faced the critical task of training laboratory professionals for the new facility. The presence of various middleware solutions in older facilities hindered cross-training flexibility. Standardizing middleware and equipment solutions was essential to enhance adaptability to volume changes, enabling certification for around 250 team members.
Solution:
DaVita aimed to understand staff perceptions of their laboratories and their expectations for a new facility to enhance collaboration. Together with Siemens Healthineers HCS, they created a tailored survey to gauge employee views. The findings informed a communication strategy addressing identified issues and contributed to training modules for the transition.
The shift to the new laboratory involved more than acquiring new skills; the team needed to adopt a different culture for the project to succeed. Unlike the previous labs, which had distinct workflows based on specific disciplines, the new lab was created as an integrated multidisciplinary space where hematology, chemistry, and immunoassay would operate on a unified system.
“We invested a lot of energy into designing the new multidisciplinary workstations and communicating with the staff on how to move to that model.”
-Senior Manager of Global Healthcare Consulting Solutions at Siemens Healthineers.
Outcome:
The DaVita team views the results as highly favorable. The new facility completely replaced the previous two laboratories. The laboratory professionals at DaVita fully adopted the latest automated systems, and staff engagement levels are at an all-time high. This reflects the outstanding performance of the DaVita team and the effective training and change management implemented by both DaVita and Siemens Healthineers.
Application Type Insights
Based on application type, the therapeutic automation market segment held the largest revenue share of over 53.0% in 2025, primarily due to the increasing adoption of advanced technologies in treatment protocols. Key drivers include the rising prevalence of chronic diseases that require complex treatment regimens and the growing demand for personalized medicine. Automation technologies, such as robotic surgical systems and automated infusion pumps, enhance precision and consistency in therapies, ultimately improving patient outcomes.
In addition, automated drug delivery systems ensure accurate dosing and minimize the risk of medication errors, further solidifying the role of therapeutic automation in modern healthcare. This segment's growth reflects a broader trend toward leveraging technology to enhance treatment efficacy and patient safety in clinical settings.
The laboratory and pharmacy automation segment is expected to grow at the fastest CAGR of 11.51% over the forecast period, driven by the increasing demand for efficiency, accuracy, and rapid turnaround times in diagnostic and pharmaceutical services. In laboratories, automation technologies such as robotic sample handlers and automated analyzers streamline processes, allowing for higher throughput and minimizing human error in test results.
This growth is further propelled by the increasing expansion of key companies. For instance, KMGI Tech Co., Ltd. (MGI), a provider of advanced tools and technologies for life sciences and healthcare research, has announced a strategic expansion of its automation product portfolio. This expansion enhances its offerings in sample pretreatment, sample preparation, and integrated testing, further leveraging MGI's innovative expertise in genetic sequencing and multi-omics technologies. By broadening its automation capabilities, MGI aims to streamline critical research workflows, driving greater efficiency and precision in life science research and clinical applications.
End-use Insights
Based on end use, the hospitals & diagnostic centers segment held the largest revenue share of over 31.2% in 2025. The rising need to enhance operational efficiency, reduce human error, and improve patient outcomes. Increasing patient volumes, coupled with the growing complexity of healthcare services, have prompted hospitals to adopt automation technologies such as robotic surgery systems, automated medication dispensing, and AI-driven diagnostic tools. The shift towards value-based care, which emphasizes improved patient outcomes and cost efficiency, is further boosting the demand for automated systems in hospitals.
 To learn more about this report, Download Free Sample Report
The pharmacies segment is expected to grow at significant CAGR from 2025 to 2030, driven by the increasing demand for efficiency, accuracy, and improved patient safety in medication dispensing and management. As healthcare systems evolve, pharmacies are adopting automated solutions such as robotic dispensing systems, automated pill packaging, and inventory management tools to streamline operations and reduce the risk of human error in medication delivery. The growing prevalence of chronic diseases and an aging population further contribute to the need for efficient pharmacy operations, as more patients require ongoing medication management.
Regional Insights
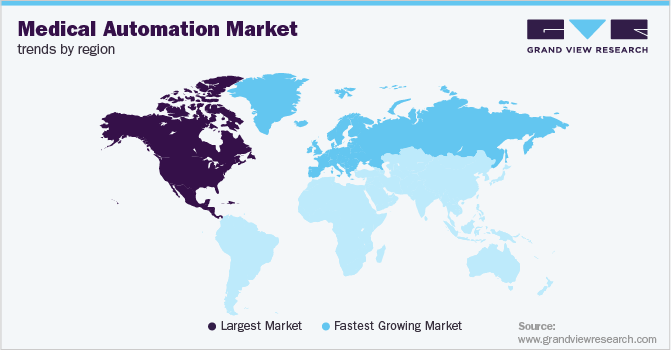
North America dominated the medical automation market with the largest revenue share of 43.5% in 2025. The increasing adoption of robotic surgical systems and automation in laboratory processes enhance precision and efficiency in medical procedures. The region is also witnessing a wave of mergers and acquisitions as companies aim to consolidate their positions and expand their technological capabilities, further fueling advancements in medical automation. For instance, in June 2023, Med-Metrix, LLC acquired Tritech Healthcare Management, LLC (“Tritech”), specializing in complex claims solutions for health systems, hospitals, and other healthcare providers. This acquisition enhances Med-Metrix’s complex claims offerings.
 To learn more about this report, Download Free Sample Report
U.S. Medical Automation Market Trends
The medical automation market in the U.S. held the largest share in the North America region in 2025. The medical automation market in the U.S. is characterized by a strong focus on improving patient safety and reducing operational costs through advanced automation technologies. The regulatory framework plays a crucial role, with regulatory bodies such as the FDA actively promoting automated device use while ensuring compliance with safety standards. For instance, according to article by Healthcare Finance published in February 2021, the U.S. healthcare system is projected to save approximately USD 16.3 billion through automation initiatives, highlighting the financial benefits of these technologies.
Europe Medical Automation Market Trends
The Europe medical automation market is experiencing considerable expansion fueled by technological innovations and a growing need for effective healthcare solutions. A notable trend is the rise in adopting robotic surgery systems and automated diagnostic tools, which enhance precision and reduce patient recovery times. For instance, in June 2023, BD (Becton, Dickinson, and Company) introduced a new automated device designed for preparing samples for clinical diagnostics using flow cytometry.
The medical automation market in the UK is experiencing significant growth, driven by several key factors. Government initiatives, particularly through the National Health Service (NHS), are focused on modernizing healthcare infrastructure and fostering increased adoption of automation technologies. The push for digital health transformation, including the widespread implementation of electronic health records (EHRs) and automated patient management systems, is a major driver.
Germany medical automation market is expected to grow significantly over the forecast period. This growth is driven by rapid technological advancements and a robust healthcare infrastructure. Germany's strong emphasis on research and development fosters an environment conducive to innovation in medical technologies. For instance, in April 2024, Hitachi purchased MA Micro Automation in Germany to boost global growth in the robotic system integration business in the medical and other sectors. Automation integration in laboratory settings is also gaining traction, with automated systems being deployed for sample analysis and processing to improve efficiency and accuracy in diagnostics. This focus on innovation is expected to drive further growth in Germany's medical automation sector.
Asia Pacific Medical Automation Market Trends
The medical automation market in Asia Pacific is driven by a surge in healthcare digitization and the adoption of advanced technologies. India and Australia are witnessing a significant push towards smart healthcare solutions, with innovations such as AI-driven diagnostic tools and telehealth services becoming more mainstream. The growth is further supported by numerous mergers and acquisitions among technology firms aiming to expand their offerings and capabilities in automated healthcare solutions. For instance, in July 2023, Ventra Health acquired ArcMed, an Indian billing and automation firm, enhancing service quality and operational efficiency and supporting growth through increased automation capabilities.
Japan medical automation market is expected to grow significantly over the forecast period. Japan's focus on healthcare innovation, supported by government policies promoting the adoption of automation technologies, fosters the integration of robotics, AI, and automated systems in hospitals and healthcare facilities. The country’s leadership in robotic surgery and precision diagnostics, alongside advancements in AI-driven patient monitoring and telemedicine, further drives market expansion.
The medical automation market in China is witnessing substantial growth fueled by rapid technological advancements and increasing healthcare expenditure. The country saw a rise in partnerships among key players as they strived to enhance their product offerings and expand their market reach. For instance, in February 2022, Siemens Healthineers and Universal Medical Imaging partnered to enhance 5G remote imaging diagnostics for primary healthcare in various regions across China. In addition, the Chinese government implemented policies to promote innovation in medical technologies, leading to the development of homegrown solutions such as automated diagnostic systems and telehealth platforms.
Latin America Medical Automation Market Trends
The Latin America medical automation market is experiencing significant growth driven by increasing healthcare investments and rising demand for efficiency in medical facilities. Countries, including Brazil and Mexico, are focusing on digital health innovations, such as telemedicine and robotic-assisted surgeries, which are becoming more prevalent due to the need for improved healthcare access. In addition, the region is seeing a rise in partnerships and collaborations, with companies launching services that cater to specific regional needs. For instance, in June 2023, CHEQ Technologies entered into a strategic partnership agreement with Opuspac, a provider of medical automation equipment located in Brazil.
Middle East & Africa Medical Automation Market Trends
The medical automation market in the Middle East and Africa is characterized by increasing healthcare infrastructure investments, particularly in the Gulf Cooperation Council (GCC) countries, which are driving the adoption of advanced medical technologies. Governments across the region are focusing on modernizing healthcare services, which include integrating automation for improved efficiency and patient care. The rising burden of chronic diseases, such as diabetes and cardiovascular conditions, is further pushing the demand for automated diagnostic and treatment solutions.
Key Medical Automation Company Insights
The market is characterized by intense competition, with numerous companies having a significant presence. This industry is evolving due to the increasing demand for enhanced products as desired by consumers. Companies are adopting strategies such as launching new products, improving technology, and forming partnerships to maintain competitiveness and achieve better market penetration.
For instance, in February 2023, Faulhaber introduced a new compact linear actuator designed specifically for medical applications. This innovative product aims to enhance precision and efficiency in medical devices, catering to the growing demand for advanced technology in healthcare. Its compact design allows for easy integration into various medical systems.
Key Medical Automation Companies
The following key companies have been profiled for this study on the medical automation market.
-
Accuray Incorporated
-
Tecan Trading AG
-
Medtronic
-
Swisslog Holding AG
-
GE Healthcare
-
Intuitive Surgical Operations, Inc.
-
Stryker
-
Siemens
-
Koninklijke Philips N.V.
-
Danaher Corporation
-
Zimmer Biomet
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Medtronic plc, GE HealthCare Technologies Inc., Stryker Corporation, Siemens Healthineers AG, Koninklijke Philips N.V.)
- Focus on developing AI-enabled medical automation solutions, robotic-assisted surgery platforms, advanced diagnostic imaging systems, laboratory automation, smart operating rooms. Growth strategies include continuous R&D, strategic acquisitions, product launches, and expansion into emerging markets.
- Strong global distribution networks, diversified product portfolios, significant R&D investments, established brand reputation, regulatory expertise, and long-term relationships with hospitals and healthcare providers.
- High product development and manufacturing costs, lengthy regulatory approval processes, integration challenges with existing hospital infrastructure, and premium pricing that may limit adoption in cost-sensitive markets.
Emerging / Specialized Players (Tecan Group AG, Swisslog Holding AG)
- Focus on niche automation solutions such as laboratory automation, liquid handling systems, sample management, healthcare logistics automation, and pharmacy automation. Strategies include product innovation, customized automation solutions, and collaborations.
- Specialized technical expertise, flexible and customized solutions, strong capabilities in laboratory and logistics automation, faster innovation cycles, and strong customer support.
- Smaller global footprint, narrower product portfolios, lower financial resources compared to large multinational companies, and dependence on specific healthcare segments for revenue growth.
Recent Developments
-
In June 2026, Hyro launched Care Intelligence, an AI-powered analytics platform that converts patient interactions with AI agents into actionable insights to improve healthcare access, scheduling, and operational efficiency. Built on over 100 million patient interactions across 2,500+ healthcare facilities, the solution enables health systems to identify access bottlenecks, benchmark AI performance, and optimize patient care workflows.
"The healthcare industry has traditionally measured agentic AI success by activity volume - how many calls were answered or hours were saved. But every time a patient interacts with an AI agent, they are sending signals about unmet demand, access delays, and system friction "Your patients have always been sending these signals; Care Intelligence is the first solution built to receive them. We are giving executives the context they've been missing so they can tie their AI investments directly to measurable operational and financial outcomes.
- Israel Krush, CEO and Co-Founder of Hyro.
-
In February 2026, Keragon launched Keragon AI, a HIPAA-compliant healthcare automation platform that enables clinical and administrative teams to build automated workflows using plain-English prompts without coding. The platform simplifies tasks such as patient intake, referral management, appointment reminders, and EHR data synchronization, helping healthcare organizations improve operational efficiency and reduce administrative workload.
"Healthcare professionals are exhausted by tools that promise efficiency but deliver technical dependency. They know exactly what they want to automate. They just shouldn't need an engineer to do it "Keragon AI removes that translation layer entirely. It puts workflow building in the hands of clinical and operations teams.
- Conno Christou, CEO and co-founder of Keragon.
Medical Automation Market Report Scope
Report Attribute
Details
Market size in 2025
USD 56.6 billion
Estimated market size in 2026
USD 61.6 billion
Projected market size by 2033
USD 117.8 billion
Growth rate
CAGR of 9.7% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, and Kuwait
Key companies profiled
Accuray Incorporated, Tecan Trading AG, Medtronic, Swisslog Holding AG, GE Healthcare, Intuitive Surgical Operations, Inc., Stryker, Siemens, Koninklijke Philips N.V., Danaher Corporation, Zimmer Biomet
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Automation Market Report Segmentation
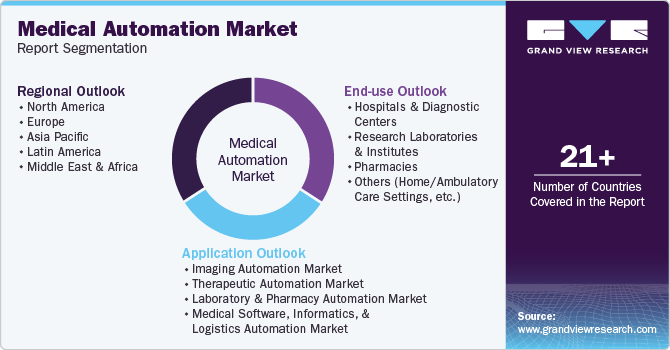
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical automation market report based on application type, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Imaging Automation Market
-
Integrated Image Analysis software systems
-
Medical Intraoperative Imaging
-
iCT
-
iUltrasound
-
iMRI
-
C-arm system
-
-
-
Therapeutic Automation Market
-
Non-Surgical Automation Market
-
Defibrillators
-
Implantable Cardioverter Defibrillators
-
Automated External (Portable) Defibrillators
-
Wearable cardioverter defibrillators
-
-
Electronic Drug Delivery Systems
-
-
Surgical Automation Market
-
Surgical Robotic device
-
Intelligent Operating Rooms
-
Surgical Simulators
-
-
-
Laboratory and Pharmacy Automation Market
-
Laboratory Automation
-
Total Automation (Inclusive of Pre-analysis, Transport Mechanisms, Liquid Handling, Sample Storage, & Analysis)
-
Modular Automation Systems (Inclusive of Specimen Acquisition & Identification & Labelling, Transport Mechanisms, Sample Preparation, Sample Loading & Aspiration, Reagent Handling & Storage, Sample Analysis & Measurements)
-
-
Pharmacy Automation
-
-
Medical Software, Informatics, and Logistics Automation Market
-
Software and Informatics
-
Logistics Automation
-
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals & Diagnostic Centers
-
Research Laboratories & Institutes
-
Pharmacies
-
Others (Home/Ambulatory Care Settings, etc.)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
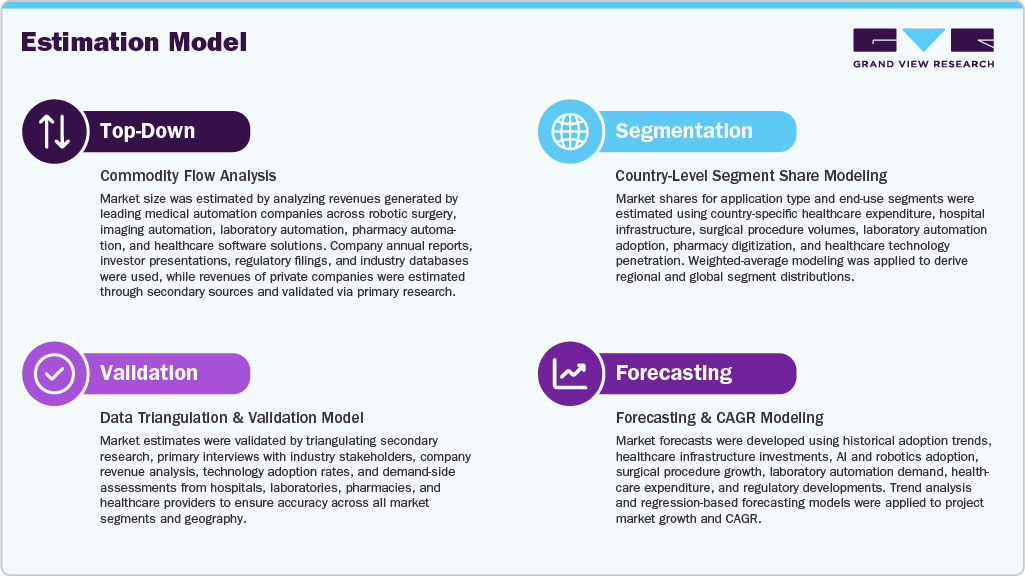
The medical automation market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical automation segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Application Type
Revenue Capture Definition
Imaging Automation
Revenue generated from automated medical imaging technologies and software that facilitate image acquisition, processing, visualization, navigation, and intraoperative guidance for diagnosis and treatment. This includes automated imaging systems, image analysis platforms, and integrated imaging solutions used across hospitals and diagnostic centers. This segment includes subsegments such as Integrated Image Analysis Software Systems, Medical Intraoperative Imaging, iCT, iUltrasound, iMRI, and C-arm System.
Therapeutic Automation
Revenue generated from automated medical technologies designed to support, monitor, or deliver therapeutic interventions with minimal manual intervention. This includes automated systems for both surgical and non-surgical treatment applications. This segment includes subsegments such as Non-Surgical Automation and Surgical Automation.
Laboratory & Pharmacy Automation
Revenue generated from automated laboratory and pharmacy technologies that streamline specimen processing, testing, medication dispensing, inventory management, and workflow optimization across healthcare facilities. This segment includes subsegments such as Laboratory Automation and Pharmacy Automation.
Medical Software, Informatics & Logistics Automation
Revenue generated from healthcare software platforms, medical informatics solutions, and logistics automation technologies that optimize clinical workflows, healthcare data management, material transport, inventory tracking, and operational efficiency across healthcare facilities. This segment includes subsegments such as Software & Informatics and Logistics Automation.
Segment-End Use
Revenue Capture Definition
Hospitals & Diagnostic Centers
Revenue generated from the adoption of medical automation technologies by hospitals, multispecialty healthcare facilities, imaging centers, and diagnostic laboratories for clinical diagnosis, treatment, laboratory operations, pharmacy management, and hospital workflow automation.
Research Laboratories & Institutes
Revenue generated from medical automation systems deployed in academic institutions, biomedical research centers, pharmaceutical research laboratories, and clinical research organizations for research, diagnostics, drug discovery, and laboratory workflow automation.
Pharmacies
Revenue generated from automation technologies implemented in hospital, retail, specialty, and mail-order pharmacies for medication dispensing, prescription processing, inventory management, packaging, and distribution.
Others (Home/Ambulatory Care Settings, etc.)
Revenue generated from medical automation solutions used in home healthcare, ambulatory surgical centers, long-term care facilities, rehabilitation centers, specialty clinics, and other non-hospital healthcare settings.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Comprehensive assessment of 20-25 leading medical automation companies covering product portfolios, AI-enabled automation capabilities, robotic-assisted surgery platforms, laboratory & pharmacy automation solutions, regional revenue contribution, installed base (where available), patent activity, strategic partnerships, M&A, R&D investments, and innovation pipelines. Includes competitive benchmarking across 10-15 performance parameters (technology maturity, automation capabilities, geographic presence, end-user focus, pricing strategy, etc.).
Enables benchmarking of competitors, identification of technology and portfolio gaps, evaluation of partnership/acquisition opportunities, and supports competitive positioning and long-term strategic planning.
Regional Healthcare Automation Adoption & Opportunity Assessment
Quantitative assessment of medical automation adoption across North America, Europe, Asia Pacific, Latin America, and MEA, including market size (USD Mn), CAGR (2025-2033), penetration rates of robotic surgery, laboratory automation, pharmacy automation, and smart hospitals. Includes country-level opportunity mapping for 15-20 key markets, healthcare infrastructure indicators, automation investment trends, and regulatory readiness.
Helps prioritize high-growth markets, quantify regional opportunities, optimize investment allocation, identify adoption barriers, and develop market-entry and regional expansion strategies based on data-driven insights.
Technology, Pricing & Investment Benchmarking
Comparative benchmarking of 30-40 automation technologies/products across robotic surgery, laboratory automation, pharmacy automation, imaging automation, and hospital workflow automation
Supports pricing optimization, technology roadmap development, product differentiation, commercialization planning, investment prioritization, and identification of whitespace opportunities for future innovation.
Frequently Asked Questions About This Report
The global medical automation market size was estimated at USD 56.6 billion in 2025 and is expected to reach USD 61.6 billion in 2026
The global medical automation market is expected to grow at a compound annual growth rate of 9.7% from 2026 to 2033 to reach 117.8 billion by 2033
North America dominated the market and accounted for a revenue share of over 43.5% in 2025, owing to high R&D investments, product launches, and government initiatives. Furthermore, the growth is attributed to the presence of a well-established healthcare infrastructure, which has increased the use of laboratory automation in the region.
Key factors that are driving the market growth include an increase in technological advancement, favorable government supporting medical automation with funding, rising demand for robotic surgery, and increasing adoption of automation in the healthcare system.
Asia Pacific is the fastest-growing region over the forecast period.
Based on application type, the therapeutic automation market segment held the largest revenue share of over 53.0% in 2025.
Based on end use, the hospitals & diagnostic centers segment held the largest revenue share of over 31.2% in 2025.
Some key players operating in the medical automation market include Accuray Incorporated, Tecan Trading AG, Medtronic, Swisslog Holding AG, GE Healthcare, Intuitive Surgical Operations, Inc., Stryker, Siemens, Koninklijke Philips N.V., Danaher Corporation, Zimmer Biomet
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


