
- Home
- »
- Medical Devices
- »
-
Medical Simulation Market Size & Share Report, 2026-2033GVR Report cover

Medical Simulation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product & Services (Healthcare Simulation Software, Simulation Training Services), By Technology (Virtual Patient Simulation, 3D Printing), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.2BMarket Forecast, 2033
$6.7BCAGR, 2026–2033
17.0%Medical Simulation Market Summary
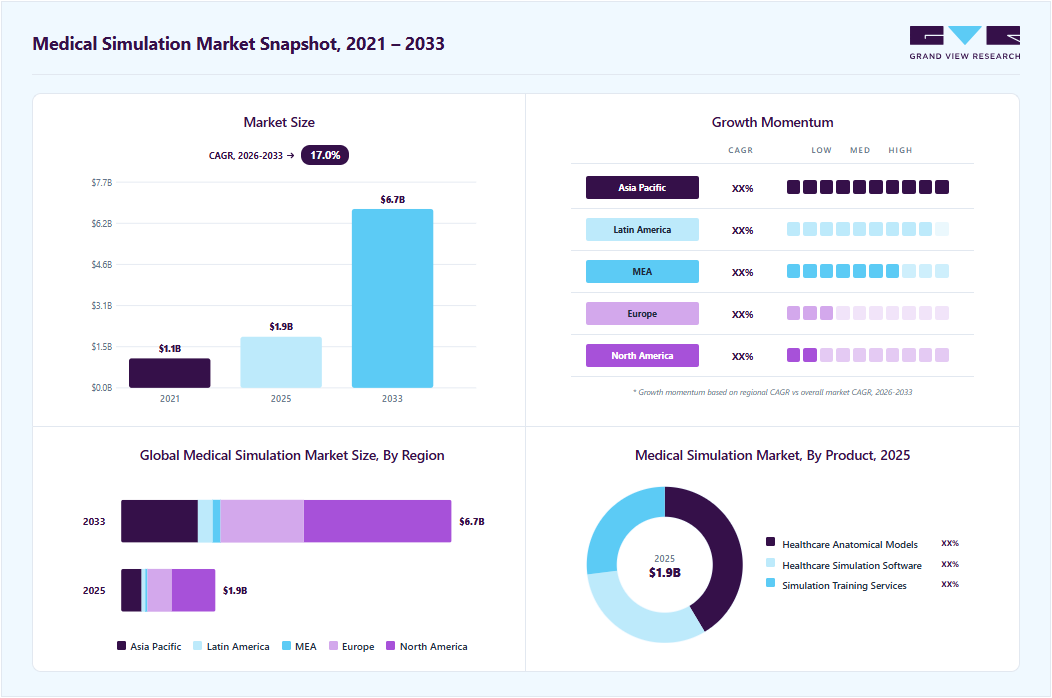
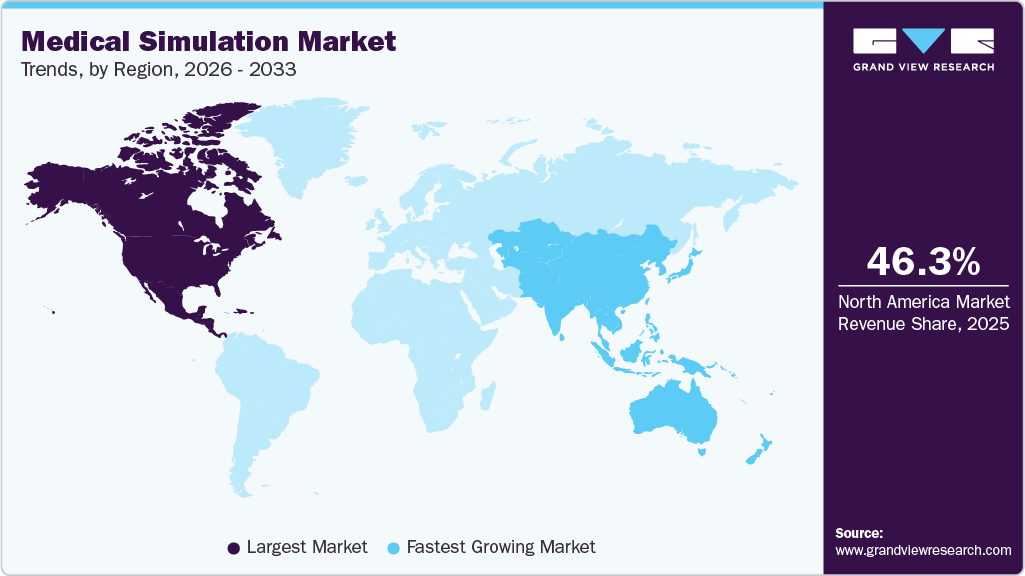
The global medical simulation market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.2 billion in 2026 to USD 6.7 billion by 2033, at a CAGR of 17.0% from 2026 to 2033. The North America held the largest share of 46.3% of the global market in 2025. The growth is driven by a growing emphasis on patient safety and outcomes, a shortage of qualified healthcare professionals, rising use of simulation with a growing demand for innovative and custom training approaches to prevent medical errors, limited access to patients for educational and clinical development purposes, and growing investments in simulation-based healthcare education and training infrastructure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product & service: Healthcare anatomical models segment held the largest market share of 41.4% in 2025.
- By technology: 3D printing segment accounted for the largest market share in 2025.
- By end use: Academic institutes segment accounted for the largest market share of 30.9% in 2025.
Regional Highlights
- Largest regional market: North America (46.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR of 18.2%, 2026-2033)
- By country: The U.S. held the largest market share in North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.2 Billion
- Projected market size by 2033: USD 6.7 Billion
- CAGR (2026-2033): 17.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The shortage of qualified healthcare professionals is a significant driver for the industry, as healthcare systems increasingly rely on simulation-based training to enhance clinical competency, reduce medical errors, and accelerate workforce readiness. Growing shortages across allied health and specialty care are intensifying the need for efficient and scalable training solutions.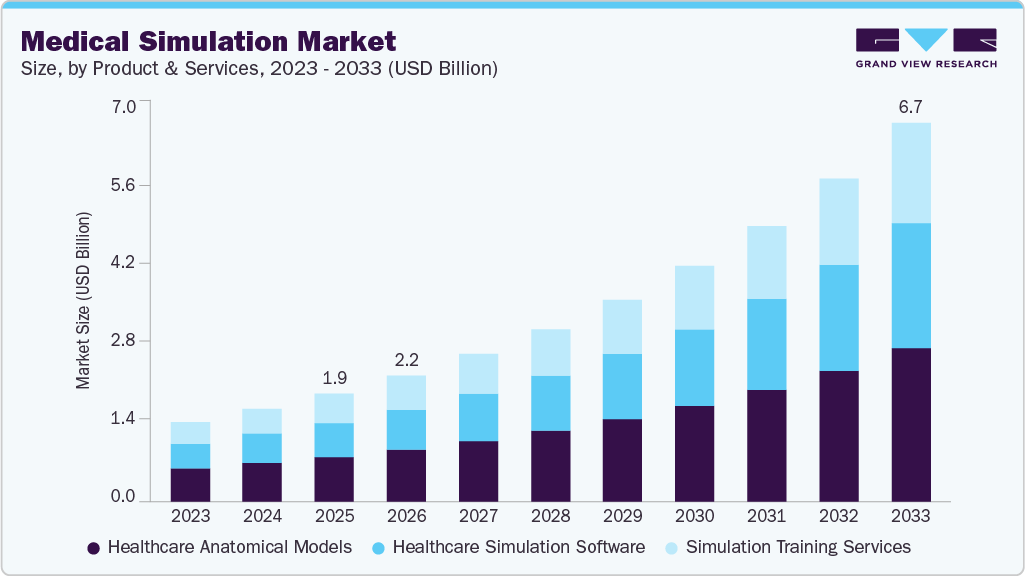 To learn more about this report, Download Free Sample Report
Market Dynamics
Rising investments in simulation-based healthcare education and advanced clinical training infrastructure are significantly driving the growth of the medical simulation market. Healthcare institutions, universities, and research organizations are increasingly adopting VR-based learning platforms, AI-enabled simulation technologies, and high-fidelity training environments to provide immersive, risk-free clinical education and improve workforce preparedness.
Below are some of the notable investments aimed at expanding medical simulation training:
• In April 2026, the All India Institute of Medical Sciences launched a Virtual Reality (VR) training center in collaboration with MediSim VR to enhance medical and nursing education through immersive simulation-based learning. The facility enables students and healthcare professionals to practice clinical procedures in a risk-free environment while supporting AI-enabled VR research for skill development and training standardization.
• In May 2025, Dana-Farber Cancer Institute launched the Ning Zhao & Ge Li Simulation Center to provide advanced, hands-on oncology nursing training through realistic clinical simulations and interdisciplinary learning. The center was established with support from a $10 million donation and aims to strengthen the next generation of oncology nurses while improving patient safety and cancer care outcomes.
• In April 2025, Munster Technological University launched a state-of-the-art Healthcare Simulation Centre at its Kerry campus to help address Ireland’s nursing shortage and strengthen clinical training. The facility features high-fidelity simulation labs, AI-enhanced manikins, and advanced training spaces designed to improve hands-on healthcare education and support plans to double nursing student intake by 2030.
The increasing need to reduce medical errors in clinical practice, along with the rising complexity of procedures, is significantly driving market growth. For instance, Vantari VR, a medical virtual reality company, has found that virtual training reduces medical errors by an impressive 40%. In June 2022, the University of Wollongong (UOW) conducted tests in partnership with Vantari VR and found that the company's training software led to a 32% improvement in student clinicians' performance and a 39% increase in their adherence to safety & hygiene protocols. These results showcase the potential for virtual reality technology to revolutionize medical education & improve patient outcomes.
Healthcare workforce shortages worldwide are prompting institutions to adopt scalable simulation-based training programs to accelerate skill development and standardize educational quality. Regulatory mandates and accreditation requirements emphasizing simulation-based competency validation are also contributing to increased procurement of simulation platforms across hospitals and teaching centers. Growing shortages across allied health and specialty care are intensifying the need for efficient and scalable training solutions. For instance, according to the Health Resources & Services Administration (HRSA), December 2025 estimates highlighted the substantial shortages of health workforce practitioners in the U.S. by 2038, including:
• 43,490 dispensing opticians
• 12,770 respiratory therapists
• 60,610 physical therapists
• 30,400 pharmacists
• 5,310 podiatrists
• 14,840 chiropractors
These workforce gaps are encouraging hospitals, academic institutions, and healthcare organizations to adopt advanced simulation technologies for hands-on training, procedural practice, interdisciplinary collaboration, and continuous skill development, thereby supporting market growth.
Despite strong adoption potential, the high initial setup and operational costs associated with advanced medical simulation systems remain a significant restraint for market growth. High-fidelity mannequins, VR/AR simulation systems, haptic surgical trainers, and AI-integrated software platforms require substantial upfront investment, making adoption difficult for small hospitals, community healthcare centers, and budget-constrained academic institutions.
The integration of Artificial Intelligence (AI), Virtual Reality (VR), Augmented Reality (AR), and cloud-based remote learning technologies presents a significant growth opportunity for the medical simulation market. Healthcare institutions are increasingly demanding immersive, scalable, and data-driven training solutions capable of delivering personalized learning experiences and real-time performance feedback. One of the most notable market trends is the rapid adoption of AI-powered simulation platforms that enable adaptive learning, automated skill assessment, predictive analytics, and intelligent debriefing. AI integration helps institutions measure trainee performance objectively, reduce instructor dependency, and improve training efficiency. Simultaneously, VR/AR technologies are enhancing procedural realism through immersive anatomical visualization and interactive surgical simulations.
Market Concentration & Characteristics
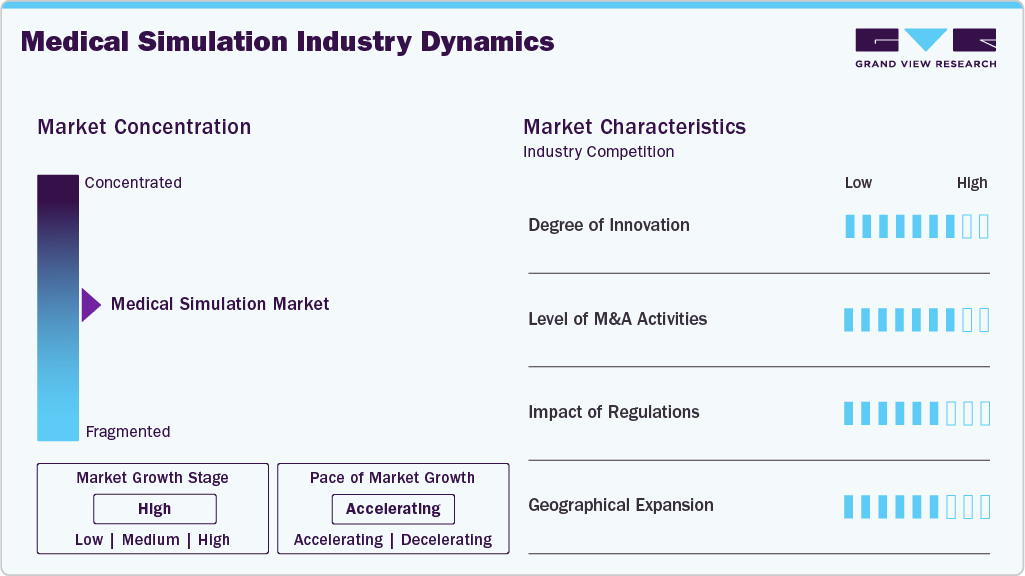
The degree of innovation in the medical simulation industry is high, driven by the increasing integration of artificial intelligence (AI), machine learning (ML), virtual reality (VR), and advanced physiological modeling technologies into simulation platforms. Market participants are focusing on developing high-fidelity simulators capable of replicating complex clinical scenarios with real-time feedback and enhanced realism to improve procedural accuracy and clinical decision-making.
For instance, in February 2026, Maverick Simulation Solutions launched “SIDDH,” an AI-enabled high-fidelity critical care adult patient simulator designed to strengthen hands-on medical training across hospitals and medical colleges. The simulator integrates advanced lung simulation, ultrasound capabilities, and real-time physiological feedback, demonstrating the industry’s growing emphasis on technologically advanced and immersive simulation solutions for critical care and emergency training.
 To learn more about this report, Download Free Sample Report
The level of mergers and acquisitions in the industry is moderate to high, driven by companies seeking to strengthen technological capabilities, expand simulation portfolios, and enhance digital training solutions. For instance, in July 2023, Limbs & Things Ltd acquired eoSurgical, a software specialist and laparoscopic surgical trainer, to enhance its minimally invasive surgical simulation offerings. Such strategic acquisitions support innovation and portfolio expansion across the market.
Medical simulation companies are mandated to abide by several regulations. Governments are introducing new frameworks to regulate the medical simulation industry. For instance, in November 2023, the FDA published final guidance titled Assessing the Credibility of Computational Modeling and Simulation in Medical Device Submissions. This guidance provides a framework for manufacturers to demonstrate the credibility of CM&S models used to support regulatory submissions for medical devices. The guidance specifically applies to physics-based or mechanistic CM&S models and excludes standalone machine learning or artificial intelligence-based models.
Companies within the industry continue to pursue geographic expansion strategies to strengthen their presence in high-growth regions such as Europe and emerging markets. For instance, in March 2025, Surgical Science Sweden AB expanded its global footprint through the acquisition of Intelligent Ultrasound Group PLC (UK-based company), strengthening its presence in the European ultrasound simulation market and enhancing its technological capabilities across the region.
Product & Services Insights
The healthcare anatomical models segment dominated the market, with the largest revenue share of 41.4% in 2025. The growth can be attributed to the increasing focus on patient safety and effective treatment. Furthermore, 3D printing technology is gaining popularity in healthcare settings due to its wide range of applications, including diagnostics, surgical planning, and patient education with anatomical models. Thus, collaborations between medical institutions, technology developers, and anatomical model manufacturers have developed more advanced and effective simulation tools. For instance, in November 2021, Stratasys partnered with Ricoh USA to expand access to point-of-care 3D anatomic modeling solutions for healthcare providers. The collaboration enables hospitals and clinicians to use patient-specific 3D printed anatomical models for surgical planning, medical training, and personalized patient care.
The healthcare simulation software segment is expected to grow at the fastest CAGR of 17.7% during the forecast period from 2026 to 2033. Healthcare simulation software helps in recording audio & video of procedures, annotation, and debriefing. The software records feedback to help assess performance, specifically during training. The increasing recognition of simulation training as an effective healthcare education and skill development method has driven the demand for healthcare simulation software. For instance, in October 2023, Lumeto launched a conversational AI system for healthcare simulation that uses a Large Language Model (LLM) to generate more realistic and practical virtual human responses, animations, & interactions. The technology has been fully integrated into the Involve XR platform, and it has the potential to enhance healthcare simulation programs greatly.
Technology Insights
The 3D printing segment dominated the market with the largest share in 2025. The insights gained from 3D printing simulation contribute to continuous improvement in the printing process. Users can learn from simulations, refine their approaches, and apply best practices to future printing projects. 3D printing simulation allows students and professionals to learn about the intricacies of the 3D printing process, experiment with different parameters, and understand how design choices impact the final product. Moreover, companies are undertaking various strategic initiatives to sustain their position in the market, which also boosts market growth. For instance, in April 2023, 3D Systems and Clarkson College collaborated to create a 3D Printing and Training Center of Excellence for healthcare innovation, education, and patient care. The partnership aims to make 3D printing and visualization accessible to healthcare facilities in the Omaha region.
The virtual patient simulation segment is expected to grow at the fastest CAGR during the forecast period from 2026 to 2033. This growth is driven by increasing focus on patient safety, growing demand for minimally invasive treatments, technological innovations, and increasing efforts by governments to offer high-quality patient care. Moreover, advancements in medical simulation technology are also expanding its applications in healthcare training for professionals, further fueling the market growth. For instance, in May 2023, SimX Virtual Reality Platform released a sepsis scenario for medical simulation. SimX is a virtual reality medical simulation program that offers a range of cases to test learners' abilities to identify and manage medical emergencies while improving their communication & patient management skills.
End Use Insights
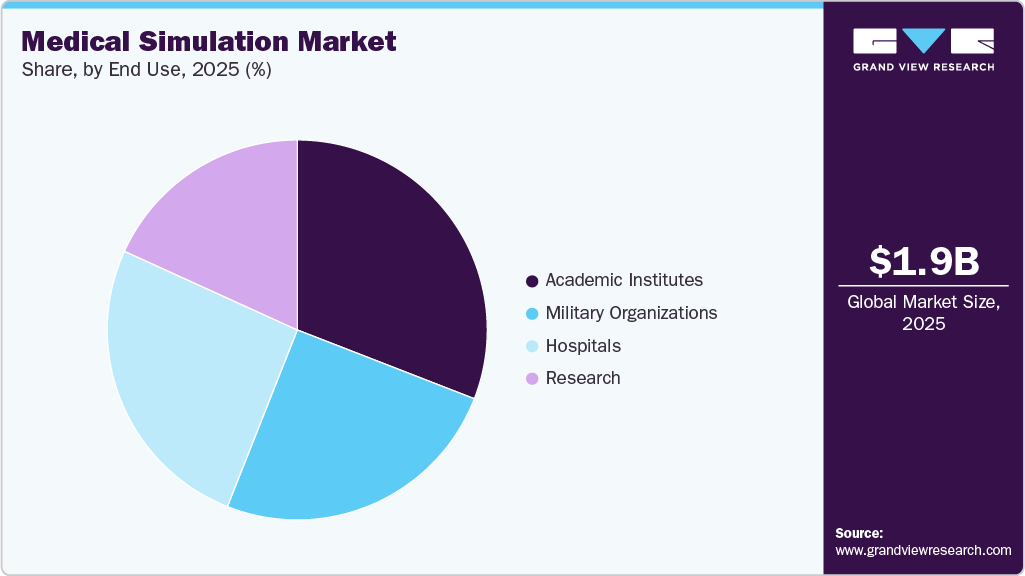
Academic institutes dominated the market with the largest revenue share of 30.9% in 2025. Technological advancements and the need for better patient outcomes drive the requirement for and popularity of Simulation-Based Medical Education (SBME). Furthermore, introducing novel medical simulation models, such as simulation manikins, is expected to boost market growth.
 To learn more about this report, Download Free Sample Report
Simulation manikins train students and medical practitioners in various medical scenarios. These training modalities aim to enhance medical practitioners' clinical skills and competence, making them better prepared to deliver high-quality patient care. For instance, in November 2023, CPS Mumbai launched a modern Simulation Lab to train medical professionals. Equipped with advanced resources and technology, the lab features simulation manikins for various medical disciplines, such as Ares, Lucina, and Arya.
The hospitals segment is expected to grow at the fastest CAGR during the forecast period. Various factors responsible for the growth include the gradual shift of focus to advanced learning, the advent of advanced simulation-based technologies, the full utilization of simulation models in medical surgeries, the rising focus on minimizing errors, and the cost-effectiveness of procedural training for physicians. For instance, in September 2023, The University of Limerick and UL Hospitals Group launched a simulation facility at University Hospital Limerick to train doctors, nurses, and allied health professionals for clinical procedure training.
Regional Insights
North America medical simulation market led with the largest share of 46.3% in 2025. The growth is attributed to the region-wide presence of key players and their high investments in technology. Moreover, key regional hospitals and health systems are undertaking strategic initiatives, such as education and training programs, to provide students & professionals with the ability to develop skills in a realistic environment. For instance, in July 2023, the U.S. Department of Defense announced the launch of a new Healthcare Simulation and Bioskills Center at Naval Medical Center Camp Lejeune. This center aims to support medical professionals with operational and clinical education.
 To learn more about this report, Download Free Sample Report
U.S. Medical Simulation Market Trends
The medical simulation market in the U.S. accounted for the largest share in North America in 2025 due to the introduction of several product & services, supportive government policies, increasing frequency of chronic conditions, technical improvements, and the presence of key companies. For instance, in September 2023, the Des Moines Fire Department (DMFD) and the Simulation in Motion-Iowa (SIM-IA), a simulation clinical learning program by the University of Iowa, launched a medical simulation training truck. This simulation truck featured an ambulance box, video recording for analysis & debriefing, four human patient simulators, and a simulated emergency bay to provide high-quality, evidence-based clinical education to hospital professionals & EMS across the state.
Europe Medical Simulation Market Trends
The medical simulation market in Europe is growing due to an advanced healthcare system in the European Union (EU). Factors contributing to this growth include continuous technological advancements, increasing concerns over patient safety, and the rising demand for minimally invasive treatments. Furthermore, private players largely provide medical simulation training services in Europe, further contributing to regional market growth.
Germany medical simulation market is expected to witness substantial growth owing to a strong national commitment to health IT, which involves strategy and adoption of simulation & models for training and learning purposes by healthcare professionals. In addition, the country's growth can be attributed to the presence of market players undertaking several initiatives. For instance, in August 2023, 3B Scientific, a medical simulation product and anatomical model manufacturer and marketers acquired Lifecast Body Simulation. This acquisition aims to strengthen the global distribution and manufacturing of medical and healthcare education.
The medical simulation market in the UK is experiencing growth due to increasing funding to upgrade healthcare infrastructure and the rising demand for medical simulation. This funding allows for the developing and implementing of advanced simulation technologies and training programs. For instance, in December 2023, The University of Reading opened a new clinical training facility to provide NHS staff and students with vital learning experiences in a simulated hospital environment. The new facility was built with funding of USD 3.5 million (£2.6m) granted by the office for students.
Asia Pacific Medical Simulation Market Trends
The medical simulation market in Asia Pacific is expected to grow at the fastest CAGR during the forecast period due to the increasing demand for innovative technologies, minimally invasive treatments, and patient safety solutions. In addition, the medical simulation market in the region is experiencing growth due to increasing focus on integrating advanced technology into medical personnel training, growing emphasis on patient safety, expanding infrastructure, large population bases, and rapid economic development in countries such as China, India, & South Korea.
China medical simulation market is expected to grow significantly during the forecast period. The growth is due to the government having established action plans for deploying new innovative technology related to healthcare services in China, including 3D printing and telehealth. Furthermore, several workshops and summits are undertaken by academic & research institutes for therapy simulations to educate healthcare professionals. For instance, the 7th China Neuromonitoring Workshop and the 7th Chinese Research Hospital Association Thyroid Disease Summit were held in March 2022 in Zhengzhou. One of the sessions was a virtual simulation on neuromonitoring technology hosted by professors from the China-Japan Alliance Hospital of Jilin University.
The medical simulation market in Japan dominated Asia Pacific in 2025. Advancements in healthcare education, increased emphasis on patient safety, shortage of clinical training opportunities, and increasing healthcare expenditure are expected to boost the medical simulation market in Japan over the forecast period. Moreover, the adoption of innovative technology, 3D printing, healthcare IT, and virtual reality in simulation for learning & training for healthcare professionals to reduce medical errors & improve patient outcomes is driving the market in Japan.
Key Medical Simulation Companies Insights
The companies in the medical simulation market are actively involved in various strategic initiatives, such as partnerships, product launches, and acquisitions. Some of the strong players in the medical simulation market are CAE, Inc., Laerdal Medical, and Surgical Science Sweden AB. These companies offer a variety of medical simulation products to cater to diverse healthcare domains, such as training, emergency care, nursing and patient care, and catheterization, among others.
Key Medical Simulation Companies:
The following key companies have been profiled for this study on the medical simulation market.
- CAE, Inc. (Madison Industries acquired the CAE healthcare division in October 2023)
- Laerdal Medical
- Simulab Corporation
- Limbs & Things Ltd
- Simulaids
- Kyoto Kagaku Co., Ltd
- Gaumard Scientific
- Mentice
- Surgical Science Sweden AB (Intelligent Ultrasound in 2025)
- Operative Experience, Inc.
- Cardionics, Inc.
- VirtaMed AG
- SYNBONE AG
- IngMar Medical
- TruCorp
- KaVo Dental
- Simendo
- Haag-Streit
- Symgery
- HRV Simulation
- Synaptive Medical
- Inovus Limited
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Laerdal Medical
- Expand AI-enabled and high-fidelity simulation portfolios.
- Strengthen partnerships with hospitals and medical institutes globally.
- Strong brand presence and diversified product offerings.
- High R&D capabilities and advanced technology integration.
- High product and operational costs.
- Slower adaptability due to large organizational structures.
Emerging Players: Simendo
- Focus on niche and VR/AR-based simulation solutions.
- Collaborate with academic and healthcare institutions for growth.
- Agile innovation and faster technology adoption.
- Cost-effective and specialized training solutions.
- Limited global reach and brand recognition.
- Lower financial and distribution capabilities.
Recent Developments
-
In February 2025, Surgical Science Sweden AB completed the acquisition of Intelligent Ultrasound Group PLC to strengthen its position in the ultrasound simulation market and expand its presence in the UK. The acquisition enhances Surgical Science’s portfolio with Intelligent Ultrasound’s volumetric ultrasound technology, enabling more advanced and integrated simulation training solutions for healthcare professionals.
-
In February 2025, the Laerdal Medical announced the acquisition of SIMCharacters, strengthening its neonatal and pediatric simulation portfolio. The deal integrates SIMCharacters’ high-fidelity neonatal simulators (Paul, Emily, and Emma) into Laerdal’s global healthcare training ecosystem to enhance clinical education for newborn care professionals.
"We are excited to officially welcome SIMCharacters to the Laerdal team. Their expertise, and innovative products, including neonatal simulators Paul, Emily, and Emma, perfectly complement our existing baby simulation offerings."
- Alf‑Christian Dybdahl, CEO at Laerdal Medical
-
In January 2024, Laerdal Medical announced a global distribution partnership with SIMCharacters, an Austrian company specializing in neonatal simulation technology. The partnership aims to revolutionize medical training and enhance healthcare simulation.
-
In January 2024, CAE Inc.collaborated with SimHawk. This collaboration aims to combine SimHawk's didactic and motion-based learning with CAE Healthcare's manikin-based simulation, ultimately offering a more comprehensive and effective training experience.
-
In October 2023, Madison Industries acquired the healthcare division of CAE, Inc. This acquisition was expected to enhance the share of Madison Industries in the healthcare sector.
-
In June 2023, Wolters Kluwer Health announced collaborating with Laerdal Medical and the National League for Nursing (NLN) to launch vrClinicals for Nursing. This VR-based learning solution is designed to address the gaps in nursing education and prepare students for the real-world pressures of nursing practice.
Medical Simulation Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 billion
Estimated market size in 2026
USD 2.2 billion
Projected market size by 2033
USD 6.7 billion
Growth rate
CAGR of 17.0% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product & services, technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico, UK; Germany; Spain; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
CAE (Madison Industries acquired CAE healthcare division in October 2023), Inc.; Laerdal Medical;Simulab Corporation; Limbs & Things Ltd; Simulaids; Kyoto Kagaku Co., Ltd; Gaumard Scientific; Mentice; Surgical Science Sweden AB (Intelligent Ultrasound in 2025); Operative Experience, Inc.; Cardionics, Inc.; VirtaMed AG; SYNBONE AG; IngMar Medical; TruCorp; KaVo Dental; Simendo; Haag-Streit; Symgery; HRV Simulation; Synaptive Medical; Inovus Limited.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Simulation Market Report Segmentation
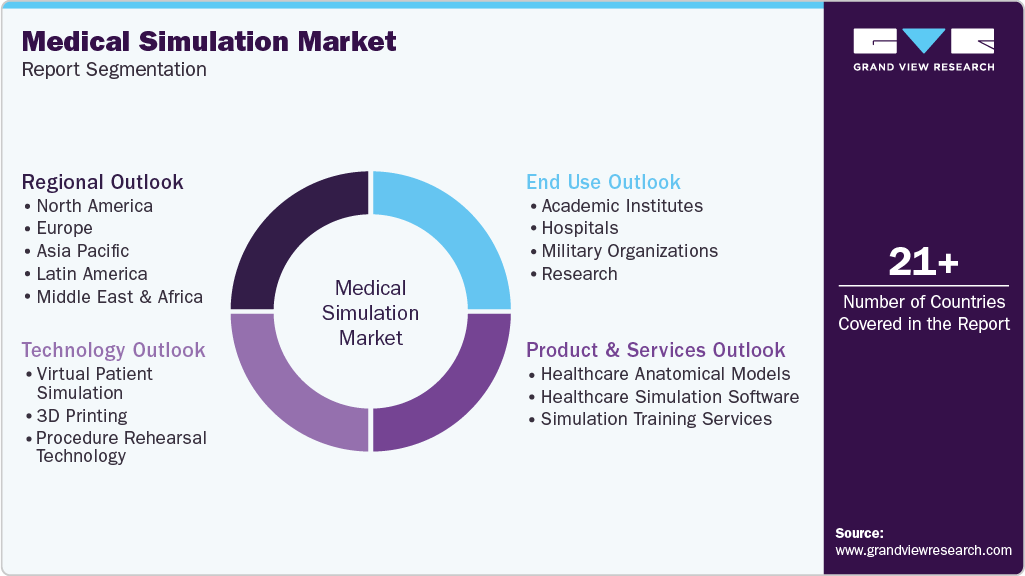
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical simulation market report based on product & services, technology, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product & Services Outlook (Revenue, USD Million, 2021 - 2033)
-
Healthcare Anatomical Models
-
Type 1
-
Patient Simulators
-
Adult
-
Pediatrics and Baby Care
-
-
Task Trainers
-
-
Fidelity
-
Low-fidelity
-
Medium-fidelity
-
High-fidelity
-
-
Type 2
-
Interventional/Surgical Simulators
-
Laparoscopic Surgical Simulators
-
Gynecology Simulators
-
Cardiovascular Simulators
-
Arthroscopic Surgical Simulators
-
Spine Surgical Simulators
-
Other Interventional/Surgical Simulators
-
-
Endovascular Simulators
-
Ultrasound Simulators
-
Dental Simulators
-
Eye Simulators
-
-
-
Healthcare Simulation Software
-
Simulation Training Services
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Virtual Patient Simulation
-
3D Printing
-
Procedure Rehearsal Technology
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Academic Institutes
-
Hospitals
-
Military Organizations
-
Research
-
Medical Device Companies
-
Others
-
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis for Medical Simulation Products Across End Users
Detailed cross-segmentation analysis of medical simulation products, including patient simulators, surgical simulators, ultrasound simulators, task trainers, VR/AR simulation, and web-based simulation platforms across hospitals, academic institutes, military organizations, and research centers. Analysis of adoption trends by specialty, training frequency, and healthcare infrastructure.
Identify the fastest-growing simulation categories across healthcare settings. Evaluate end-user-wise revenue contribution and technology adoption trends. Support targeted product expansion and training program strategies. Highlight whitespace opportunities in AI-enabled and immersive simulation solutions.
Medical Simulation Competitive Landscape & Manufacturing Analysis
Comprehensive assessment of competitor-wise simulation product portfolios, manufacturing capabilities, software integration expertise, regional presence, and strategic partnerships. Benchmarking across high-fidelity, mid-fidelity, and low-fidelity simulation segments. Analysis of pricing strategies, acquisitions, and innovation focus.
Identify competitive advantages in product innovation and digital integration. Evaluate expansion opportunities through partnerships with hospitals and universities. Benchmark manufacturing scale, R&D capabilities, and geographic penetration. Support strategic investment and market entry decisions.
Medical Simulation Pricing & Technology Trend Analysis
Analysis of pricing trends across simulators, VR-based training systems, task trainers, and cloud-based simulation platforms. Assessment of technology adoption, including AI, AR/VR, haptic feedback, and remote simulation learning. Country-level benchmarking of procurement trends and healthcare training investments.
Support region-specific pricing and commercialization strategies. Identify high-growth technology trends and premiumization opportunities. Benchmark adoption of advanced simulation platforms by geography and specialty. Support innovation and product positioning decisions in emerging healthcare training models.
Frequently Asked Questions About This Report
The global medical simulation market size was valued at USD 1.9 billion in 2025 and is estimated at USD 2.2 billion for 2026.
The global medical simulation market is expected to grow at a CAGR of 17.0% from 2026 to 2033, reaching USD 6.7 billion by 2033.
North America dominated the market with a revenue share of 46.3% in 2025.
Asia Pacific is the fastest-growing region over the forecast period, with a CAGR of 18.2% from 2026 to 2033.
The healthcare anatomical models segment led the market with a 41.4% revenue share in 2025, while the healthcare simulation software segment is the fastest-growing.
The 3D printing segment held the largest market share in 2025, while the virtual patient simulation segment is expected to grow at the fastest rate during the forecast period.
The academic institutes segment held the largest revenue share of 30.9% in 2025, while the hospitals segment is expected to grow at the fastest CAGR during the forecast period.
Key factors driving the medical simulation market include the growing emphasis on patient safety and outcomes, shortage of qualified healthcare professionals, rising investments in simulation-based healthcare education and training infrastructure, increasing demand for innovative training approaches to prevent medical errors, limited access to patients for educational purposes, and the integration of AI, VR/AR, and remote simulation platforms.
Some of the key players operating in the medical simulation market include CAE, Inc.; Laerdal Medical; Simulab Corporation; Limbs & Things Ltd; Simulaids; Kyoto Kagaku Co., Ltd; Gaumard Scientific; Mentice; Surgical Science Sweden AB; Operative Experience, Inc.; Cardionics, Inc.; VirtaMed AG; SYNBONE AG; IngMar Medical; TruCorp; KaVo Dental; Simendo; Haag-Streit; Symgery; HRV Simulation; Synaptive Medical; and Inovus Limited.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


