
- Home
- »
- Medical Devices
- »
-
Oxygen Concentrator Market Size, Share Report, 2026-2033GVR Report cover

Oxygen Concentrator Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Portable (New Purchase, Rental), Fixed (New Purchase, Rental)), By Application (Home Care, Non-homecare), By Technology, By Region, And Segment Forecasts
Market Size, 2025
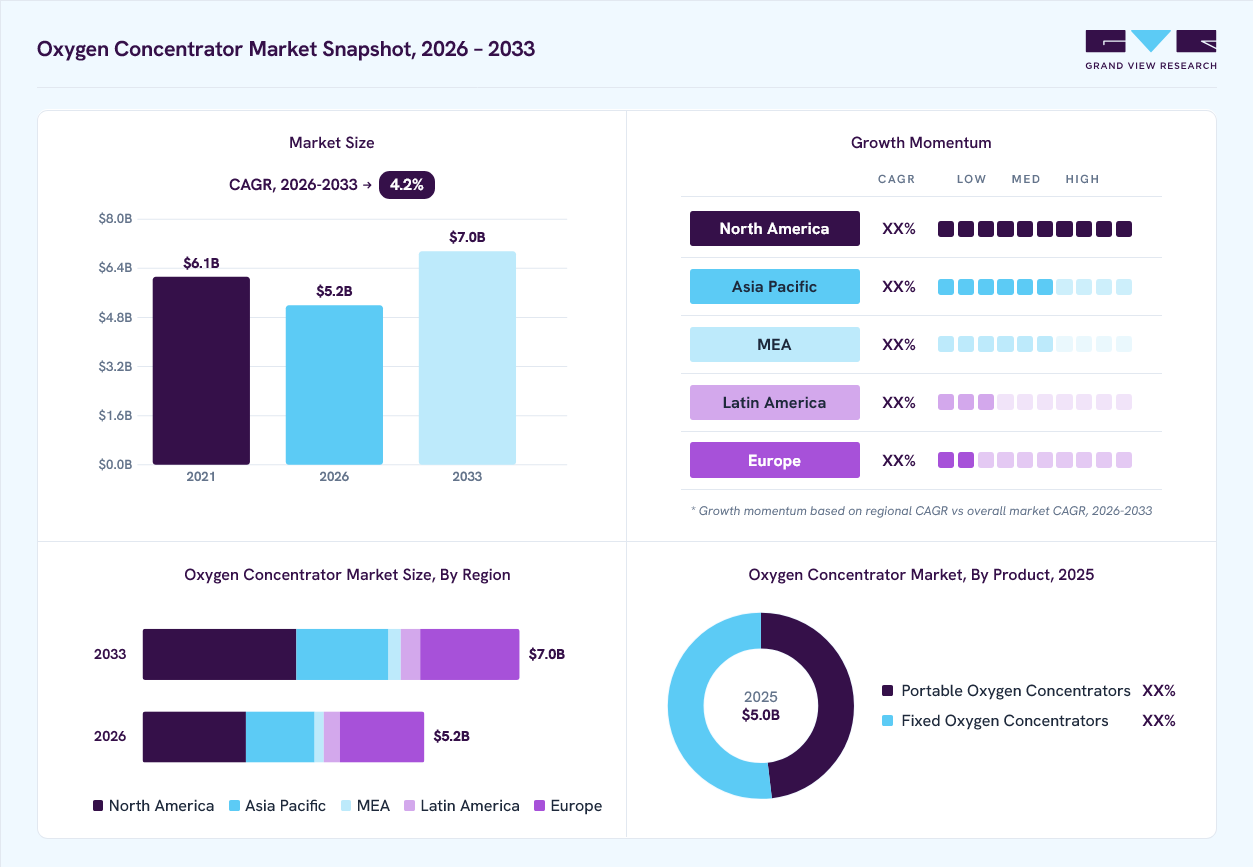
$5.0BMarket Estimate, 2026
$5.2BMarket Forecast, 2033
$7.0BCAGR, 2026–2033
4.2%Oxygen Concentrator Market Summary
The global oxygen concentrator market size was valued at USD 5.0 billion in 2025 and is projected to grow from USD 5.2 billion in 2026 to USD 7.0 billion by 2033, at a CAGR of 4.2% from 2026 to 2033. The market in North America dominated with a revenue share of 35.4% in 2025. This is attributed to the rising prevalence of respiratory disorders such as chronic obstructive pulmonary disease (COPD), asthma, and sleep apnea, coupled with the increasing launch of technologically advanced devices.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Fixed oxygen concentrators segment held the largest market share of 51.9% in 2025.
- By technology: Continuous flow segment held the largest market share of 55.8% in 2025.
- By application: Home care segment held the largest market share of 62.6% in 2025.
Regional Highlights
- Largest regional market: North America (35.4% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.0 Billion
- Estimated market size in 2026: USD 5.2 Billion
- Projected market size by 2033: USD 7.0 Billion
- CAGR (2026-2033): 4.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
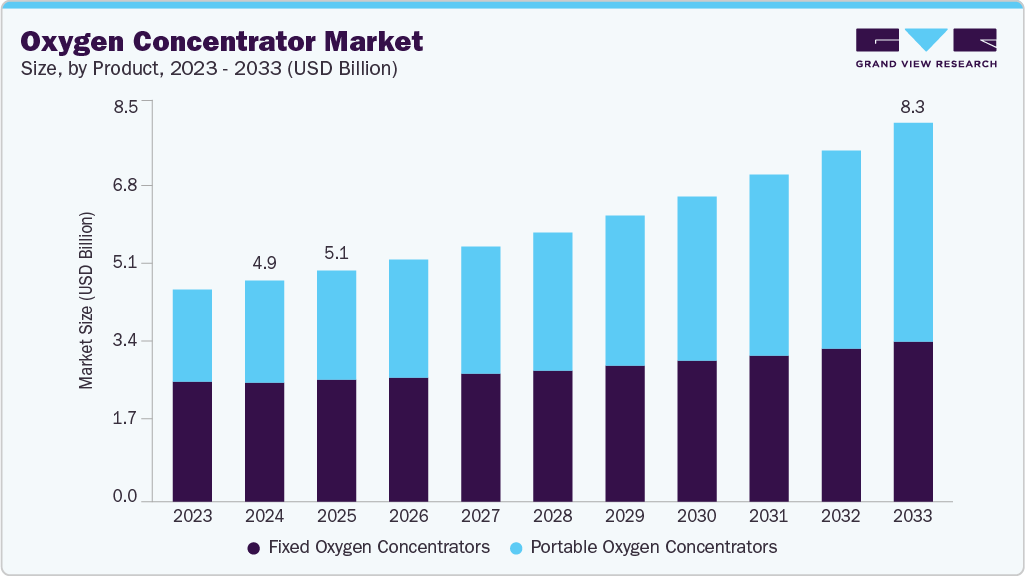
According to the Global Impact of Respiratory Disease study, around 200 million people suffer from COPD globally, resulting in 3.2 million deaths every year. Moreover, favorable reimbursement policies have enhanced the attractiveness of the oxygen concentrators market in the U.S. For instance, in March 2024, a U.S. Congressman introduced the Supplemental Oxygen Access Reform (SOAR) Act to reform and improve access to supplementary oxygen for Medicare beneficiaries. These policies have increased the adoption of oxygen concentrators. In addition, rising healthcare spending is driving the demand for effective diagnosis and treatment of respiratory diseases, thereby boosting the market for oxygen concentrators. According to a Cleveland Clinic article in the U.S, over 1.5 million people rely on supplemental oxygen therapy, using devices such as oxygen tanks and concentrators.Regional governments offer reimbursement policies that cover the cost of POCs for patients with respiratory illnesses. For instance, according to Inogen's 10K form document for the fiscal year ending December 31, 2021, the international market (excluding the U.S.) is attractive for oxygen concentrators due to favorable reimbursement policies in certain countries such as the UK and France. In these countries, portable oxygen concentrators receive more favorable reimbursement than in the U.S.
 To learn more about this report, Download Free Sample Report
Market players also employ strategies such as acquisitions, collaborations, expansions, and new product launches to extend their product offerings and geographical reach. For instance, in June 2025, Inogen launched the Voxi 5 stationary oxygen concentrator, offering an affordable, durable, and quiet continuous flow oxygen therapy solution for long-term care patients in the US, enhancing home respiratory care accessibility. The device features compact design, caster wheels for mobility, a 3-year sieve bed warranty, and advanced filtration technology.
COVID-19 had a limited positive impact on the market, driving increased demand for technologically advanced and cost-effective oxygen concentrators. For example, UNICEF distributed 62,046 concentrators to 104 nations worldwide in July 2021, with approximately 12,788 concentrators sourced from a Chinese trade company. Growing need for emergency treatment and prolonged care for lung diseases in children and adults further propels the industry.
Product Recalls: A Key Restraining Factor in the Oxygen Concentrator Market
Product recalls have emerged as a key restraining factor, hindering the growth of the market. Safety-related issues such as overheating, fire hazards, and material degradation have forced manufacturers to withdraw products from the market, creating supply disruptions and impacting patient and provider confidence. These recalls increase compliance and replacement costs and intensify regulatory scrutiny, ultimately slowing down market expansion.
The table below highlights major recalls
Company
Product Name
Date (Recall Notice or Initiation)
Reason
Impact
GCE Healthcare / Ohio Medical Corporation
ZenO lite Portable Oxygen Concentrator (Model RS-00608-X-S)
May 8, 2025 (initiated); Jun 13, 2025 (posted)
Calibration errors lead to inaccurate oxygen purity readings.
Affects ~36 units; raises concerns over device aging and reliability; prompts stricter QC for long-term performance.
Drive DeVilbiss Healthcare
iGo2 DV6X-619 DC Car Adapter (Rev E) (Accessory for iGo2 Portable Oxygen Concentrator)
Apr 11, 2025 (notice); Jul 17, 2025 (posted)
Car adapter cord overheating/melting due to an assembly defect.
Affects ~89,000 accessories; non-critical but raises safety concerns, replacement costs, and brand trust issues.
Caire, Inc.
FreeStyle Comfort Portable Oxygen Concentrator (Model #AS200-2)
Oct 4, 2024 (initiated); Nov 15, 2024 (posted)
Battery recharge failure due to a non-conforming component.
Small batch (~26 units); minimal direct impact but highlights QC issues in battery components.
Jiangsu Jumao X-Care Medical Equipment Co., Ltd.
JMC5A / TruAire-5 Oxygen Concentrator (Model O2C5L)
Nov 26, 2024 (notice); Dec 9, 2024 (recall initiation); Jan 3, 2025 (posted)
Units overheating, melting, or catching fire.
Class I recall; thousands of units affected; significant safety, regulatory, and reputational impact.
Market Dynamics
The oxygen concentrator market is growing significantly, driven by rising rates of chronic respiratory diseases, an aging population, and increased demand for long-term oxygen therapy. Advances in portable devices and battery performance are improving patient convenience and supporting broader adoption. The shift toward home healthcare is further boosting market growth as more patients choose in-home respiratory care. However, high costs and limited reimbursement in some regions remain barriers to widespread use. Despite these challenges, ongoing innovation, expanding healthcare infrastructure, and greater awareness of respiratory disease management are expected to create strong growth opportunities for market participants.
The rising prevalence of chronic respiratory diseases is a major factor driving the growth of the oxygen concentrator market. Conditions such as chronic obstructive pulmonary disease (COPD), asthma, and interstitial lung disease often require long-term oxygen therapy, which raises demand for oxygen concentrators in both home care and clinical settings. Population aging, rising air pollution, higher smoking rates, and occupational exposure to pollutants further contribute to the global rise in respiratory illnesses.
According to a joint report by the World Health Organization (WHO) and the European Respiratory Society (ERS) published on June 2025, chronic respiratory diseases affect approximately 81.7 million people across the WHO European Region, with many additional cases remaining undiagnosed or misdiagnosed. The report also notes an annual economic burden of USD 21 billion due to insufficient diagnosis and treatment. As awareness grows and healthcare systems focus on early diagnosis and long-term management, the adoption of oxygen concentrators is expected to increase, further supporting market growth.
The high cost of oxygen concentrators, particularly portable oxygen concentrators (POCs), remains a significant restraint to market growth. While these devices offer mobility, convenience, and independence for patients requiring long-term oxygen therapy, their relatively high purchase cost can limit adoption, especially in price-sensitive and developing markets. For instance, portable oxygen concentrators typically start at around USD 2,000 for new devices and approximately USD 1,000 for used devices, with prices varying based on factors such as weight, oxygen output capacity, battery life, and advanced connectivity features. In addition, maintenance expenses, battery replacements, and limited reimbursement coverage in certain regions further increase the total cost of ownership, creating affordability challenges for patients and healthcare providers.
The increasing adoption of home healthcare services is creating significant opportunities in the oxygen concentrator market. Higher healthcare costs, a rise in chronic respiratory diseases, and a preference for home-based treatment are prompting patients and providers to choose home oxygen therapy. Thus, there is a growing demand for user-friendly, reliable, and advanced oxygen concentrators that support long-term care outside traditional healthcare settings. Manufacturers are developing innovative home-use oxygen concentrator products. For instance, in April 2026, Oxymed launched the Inteli 5 LPM, India's first intelligent home oxygen concentrator that automatically adjusts oxygen flow in real time based on a patient's blood oxygen saturation (SpO₂) levels. These advancements improve patient safety, increase treatment efficiency, and support personalized home respiratory care. As global adoption of home healthcare rises, demand for advanced oxygen concentrators is expected to drive substantial market growth.
Market Concentration & Characteristics
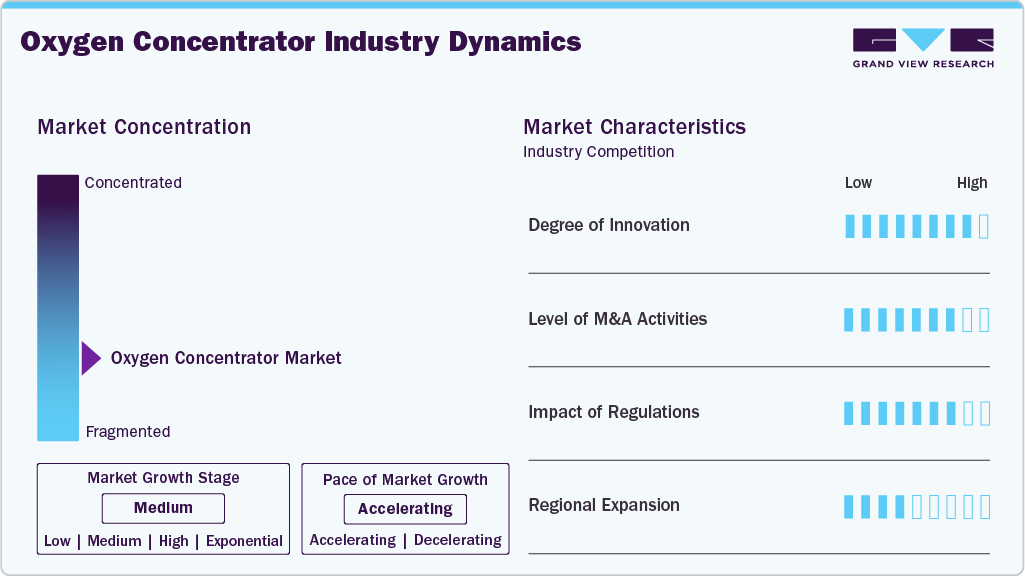
The chart below illustrates the relationship between market concentration, industry characteristics, and industry participants. The x-axis represents the level of industry concentration, ranging from low to high. The y-axis represents various industry characteristics, including industry competition, impact of regulations, level of partnerships & collaborations activities, degree of innovation, and regional expansion. For instance, the oxygen concentrator industry is fragmented, with many providers entering the market. The degree of innovation, the level of partnerships & collaboration activities, and the impact of regulations on the industry is high. However, the regional expansion observes moderate growth.
The degree of innovation in the industry is high. The market is experiencing significant innovation as companies like Inogen are introducing cutting-edge products. For instance, In January 2025, Caire launched IntenOxy 5, a stationary oxygen concentrator in the U.S. and Puerto Rico. This delivers around 95.5% oxygen concentration and operates efficiently with low power consumption.
 To learn more about this report, Download Free Sample Report
“The IntenOxy 5 Stationary Oxygen Concentrator has been an excellent addition to our oxygen therapy portfolio. The unit is a key component to how our DME and HME customers serve their respiratory patients, providing them with an at-home device that delivers the oxygen they need as they navigate activities of daily living,”
-Ken Hosako, president and CEO of Caire.
M&A activities facilitate geographic expansion and market entry for companies. For instance, React Health acquired Invacare's Respiratory line in February 2023. This strategic move bolsters React Health's market standing, broadens its product range, and enhances its ability to serve a wider customer base.
The impact of regulations on the market is high. The market for oxygen concentrator is significantly influenced by various regulations, which play a critical role in shaping the growth, innovation, and operational processes of oxygen concentrator. Regulatory framework for oxygen concentrators represents a significant barrier, particularly in terms of regulatory stringency impact. Companies such as Invacare Corporation and Philips have encountered prolonged consent decrees from the U.S. FDA, illustrating the stringent regulatory environment.
The level of regional expansion in industry is moderate. Expanding into new regions has become a key growth strategy for companies in the market, as it allows them to tap into underserved areas, increase device adoption, and respond to rising demand for respiratory care. For instance, in November 2024, Unitaid launched the East African Program on Oxygen Access (EAPOA) with a USD 22 million investment to expand liquid medical oxygen production in Kenya and Tanzania, aiming to increase regional supply, reduce prices by up to 27%, and save thousands of lives across East and Southern Africa.
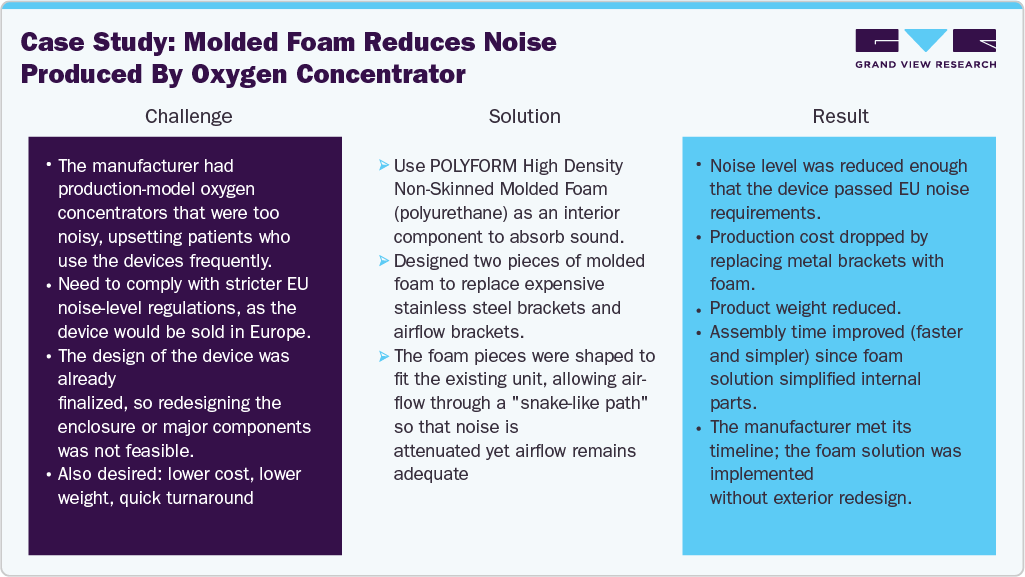
Case Study: Molded Foam Reduces Noise Produced by Oxygen Concentrator
 To learn more about this report, Download Free Sample Report
Key Takeaways:
-
Adoption of high-density non-skinned foam by Polytech reflects a strategic focus on material-driven innovation that reduces noise, weight, and production complexity while enhancing patient comfort and regulatory compliance, positioning manufacturers for stronger market acceptance.
-
Similarly, Porex’s use of sintered porous plastic demonstrates how advanced materials can simultaneously improve device performance, durability, and sterilization capabilities, offering a competitive edge by enhancing user experience and meeting stringent regulatory standards.
Analyst Perspective
The growth of the oxygen concentrator market is driven by the rising prevalence of chronic respiratory diseases, an aging population, and increased demand for long-term oxygen therapy. Higher adoption of home healthcare and a preference for convenient, non-invasive respiratory support are boosting demand for both portable and fixed devices. In addition, advancements in oxygen delivery technology, improved portability, and expanding healthcare infrastructure in developing regions are further increasing market penetration. As effective respiratory care becomes a higher priority for providers and patients, the market is expected to grow sustainably over the forecast period.
Product Insights
Based on product, the fixed oxygen concentrators segment led the market with the largest revenue share of 51.9% in 2025. Fixed oxygen concentrators deliver higher oxygen output, continuous flow therapy, and long-term reliability, making them the preferred choice for patients with severe COPD and chronic respiratory conditions. Their lower cost than portable models and extensive use in home care settings further contribute to the segment's dominance. Moreover, key market players focus on unveiling new fixed medical oxygen concentrator products. For instance, in October 2024, Drive DeVilbiss Healthcare launched the PulmO2 stationary concentrator for low- and middle-income countries, contributing to the large share of the segment.
The portable oxygen concentrators segment is anticipated to witness the fastest CAGR over the forecast period, driven by increasing demand for portable oxygen concentrators owing to their lightweight design, mobility, and battery-powered operation, enabling greater patient freedom and supporting the shift toward home healthcare. To cater to this demand, market players prioritize advancements in battery performance, oxygen purity, and device compactness. For instance, in September 2024, Oxymed introduced its P2 Portable Oxygen Concentrator in India, featuring five pulse flow settings, 90-95% purity, and up to 10 hours of battery life.
Technology Insights
Based on technology, the continuous flow segment led the market with the largest revenue share of 55.8% in 2025. Continuous flow technology provides reliable, uninterrupted oxygen delivery essential for patients with severe COPD and chronic respiratory conditions. Its widespread use in both clinical and home care settings, along with proven effectiveness and affordability compared to newer alternatives, supports the segment's dominant share. In addition, this technology is also widely used in residential and military applications, providing a safer alternative to storing oxygen under pressure.
The pulse flow technology segment is expected to experience the fastest CAGR during the forecast period. The growth is driven by the advantages offered by pulse flow technology, including high mobility, lightweight design, and suitability for patients with active lifestyles. Pulse flow technology is particularly beneficial for treating respiratory conditions that require a lower oxygen delivery rate per minute. It is extensively used in portable oxygen concentrators (POCs). For instance, in October 2024, Inogen, Inc. launched the Inogen Rove 4 portable oxygen concentrator. This oxygen concentrator utilizes pulse-dose intelligent delivery technology.
Application Insights
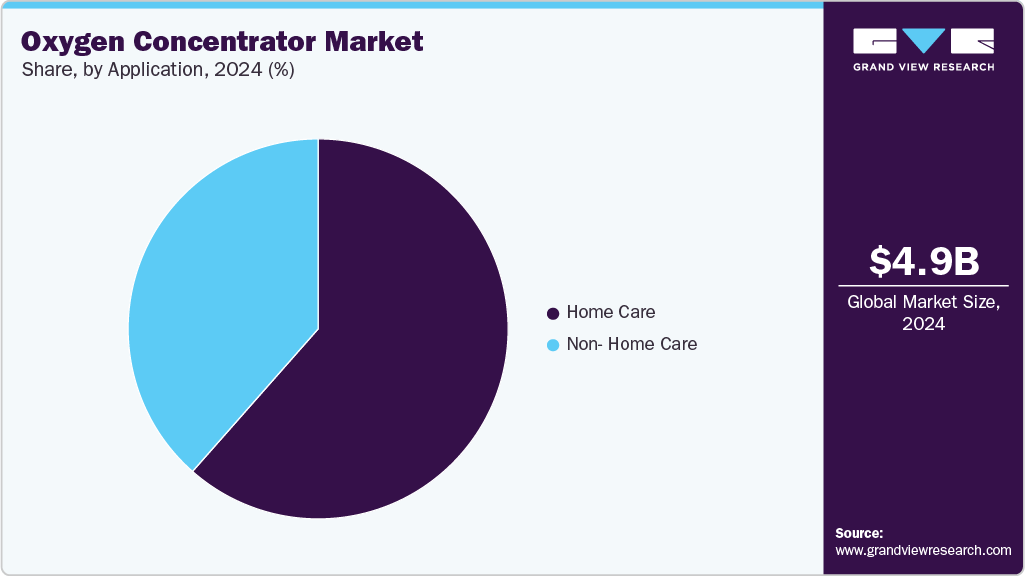
Based on application, the home care segment led the market with the largest revenue share of 62.6% in 2025. Based on application, the market is segmented into home care and non-home care. The home care segment held the largest revenue share in 2024. Technological advancements and the adoption of home therapy in developed countries contribute significantly to the market's revenue share. Availability of a wide range of concentrators for home therapy also plays a crucial role. Moreover, a sizable geriatric population in countries such as Japan, Germany, Italy, and others is expected to drive market growth. In addition, expanding healthcare insurance coverage for oxygen concentrators in many countries further fuels the market growth.
 To learn more about this report, Download Free Sample Report
The non-homecare segment is expected to exhibit at a moderate CAGR over the forecast period, driven by the increased adoption of oxygen therapy in hospitals and clinics. Moreover, an increasing number of hospital admissions due to respiratory diseases contributes to the segment’s growth.
Regional Insights
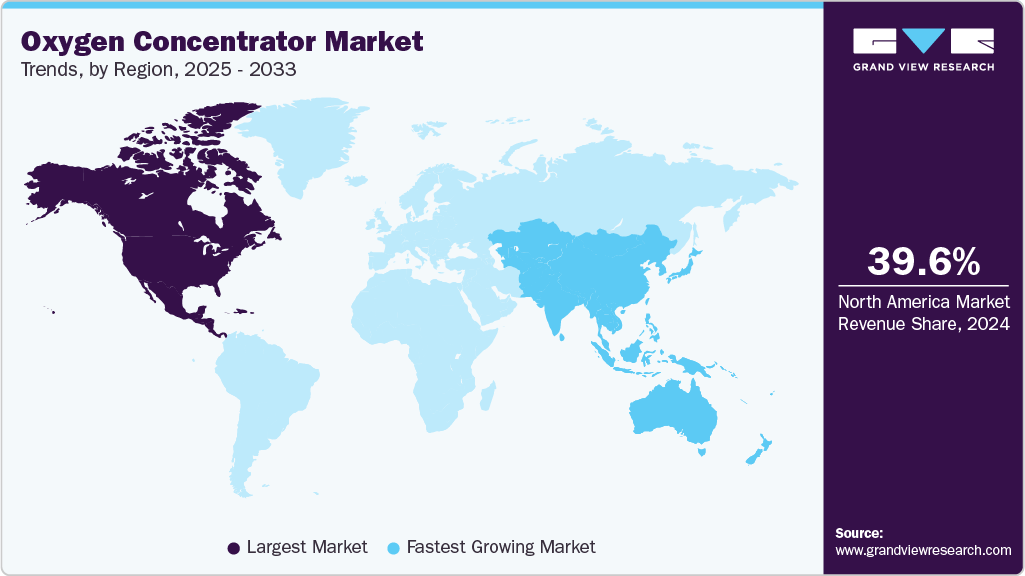
North America dominated the oxygen concentrator market with the largest revenue share of 35.4% in 2025, due to an increase in the prevalence of respiratory conditions such as COPD, asthma, and sleep apnea. For instance, according to the 2024 National Survey by Asthma Canada, over 4.6 million people in Canada are living with asthma, including 900,000 children under 19 and 800,000 adults over 65. Asthma is the third most prevalent chronic disease in the country, with an estimated 317 new diagnoses every day and around 250 deaths annually. In addition, the presence of prominent market leaders in North America are such as Healthcare, Inogen, Inc., and Caire Medical (a subsidiary of NGK Spark Plug), further contributes to the growth of oxygen concentrator industry in North America.
 To learn more about this report, Download Free Sample Report
U.S. Oxygen Concentrator Market Trends
The oxygen concentrator market in the U.S. held the largest share in the North America region in 2025. The oxygen concentrator industry in the U.S. is fueled by rising cases of respiratory diseases such as COPD, asthma, and sleep apnea, along with an aging population requiring long-term oxygen therapy. Increased preference for home-based healthcare and portable medical devices has shifted demand toward lightweight, user-friendly oxygen concentrators that enable greater mobility and independence for patients. Moreover, favorable reimbursement policies have enhanced the attractiveness of the oxygen concentrators in the U.S. market.
Europe Oxygen Concentrator Market Trends
The oxygen concentrator industry in Europe has been evolving rapidly, driven by regulatory advancements, technological innovations, and strategic initiatives by key industry players. For instance, in January 2023, Inogen, Inc. received European Medical Device Regulation (EU MDR) certification from the British Standards Institution (BSI) for its portable oxygen concentrators, enabling their commercialization across the EU. Furthermore, integrating Internet of Things (IoT) and remote monitoring systems into medical oxygen concentrators has seen an increase in adoption over the past years, enhancing real-time monitoring and predictive maintenance capabilities.
The oxygen concentrator industry in the UK is driven by regulatory updates and strategic industry initiatives. In November 2021, the UK government, in collaboration with UNICEF and Oxygen CoLab, launched a project to develop robust oxygen concentrators suitable for low-resource settings, addressing critical care needs during the COVID-19 pandemic. Such initiatives highlight the importance of oxygen therapy equipment in emergency healthcare provisioning, supporting the market growth.
Germany oxygen concentrator industry held a significant share in the European region in 2024, driven by an aging population, rising prevalence of chronic respiratory diseases, and increasing demand for home-based healthcare solutions. For instance, according to Eurostat Data, the Hospital discharge rate for inpatients with respiratory system diseases was 1,300 per 100,000 inhabitants in Germany in 2021. Moreover, strategic initiatives from key industry players and supportive government policies support the growth of the market. For instance, the implementation of the EU Medical Device Regulation in 2021 has elevated safety and efficacy standards for oxygen therapy devices, reinforcing Germany's position as a leader in the European oxygen concentrators market.
Asia Pacific Oxygen Concentrator Market Trends
Asia Pacific oxygen concentrators industry is anticipated to witness significant growth from 2025 to 2033. The growth is attributed to the rising prevalence of respiratory diseases, a rapidly aging population, and an increasing focus on home healthcare. For instance, according to the WHO, the ratio of population aged 60 years and above in the Asia-Pacific region is estimated to increase from 12.2% in 2024 to 22.9% by 2050. In addition, increasing adoption of portable oxygen concentrators, government initiatives, and strategic actions by key players. For instance, in July 2022, OMRON Healthcare, a Japan-based electronics company introduced a portable oxygen concentrator, offering a continuous supply of high-purity oxygen at 5 liters per minute, catering to homecare needs.
The oxygen concentrator industry in Japan is propelled by technological advancements, strategic initiatives by domestic companies, and a robust regulatory framework. Japanese firms such as Teijin Limited and Daikin Industries have focused on developing portable oxygen concentrators tailored for homecare use, aligning with the country's aging population and the government's emphasis on home-based medical care.
China oxygen concentrator industry is experiencing significant growth, driven by government initiatives and strategic collaborations. For instance, in March 2022, Belluscura, a UK-based medical device company, entered into a three-year manufacturing agreement with InnoMax Medical Technology in China to produce its X-PLO2R portable oxygen concentrators. This collaboration facilitated local production and aimed to cater to the growing demand for portable oxygen solutions in the region.
Latin America Oxygen Concentrator Market Trends
The oxygen concentrator industry in Latin America is growing significantly. The presence of untapped opportunities in emerging countries, such as Brazil, is expected to propel the growth of market. In addition, companies such as Caire and GCE are increasingly expanding their presence in the market by launching novel solutions. For instance, in May 2022, CAIRE announced to launch its NewLife Intensity 10 stationary oxygen concentrators & Companion 5 in Latin America in July, pending anticipated approval from the Brazilian Health Regulatory Agency (Anvisa).
“During the past two years, the COVID-19 pandemic oxygen shortages throughout South America have underscored the need to expand CAIRE’s portfolio of equipment available to providers to serve patients prescribed oxygen as they are discharged from the hospital”
-Barry Hassett, vice president of global marketing
Middle East & Africa Oxygen Concentrator Market Trends
The oxygen concentrator industry growth in the Middle East & Africa is attributed to government initiatives, technological advancements, and strategic actions by industry players. In the United Arab Emirates (UAE), the government has prioritized healthcare innovation, leading to increased adoption of portable oxygen concentrators, especially in homecare settings. This shift is supported by investments in advanced healthcare infrastructure and a focus on managing chronic respiratory conditions.
Key Oxygen Concentrator Company Insights
The market is fragmented, with many small and large players operating in this space. This leads to intense competition between smaller players to sustain their position. Strategies such as new product launches and partnerships are playing a key role in propelling the market growth.
Key Oxygen Concentrator Companies
The following key companies have been profiled for this study on the oxygen concentrators market.
-
Respironics (a subsidiary of Koninklijke Philips N.V.) {Effective from January 25, 2024, Philips Respironics halted the sale of their POCs, with end of service scheduled for January 25, 2029.}
-
GF Health Products, Inc.
-
MedaCure Inc.
-
Nidek Medical Products, Inc
-
O2 Concepts
-
React Health
-
CAIRE Inc. (Acquired by Niterra Co., Ltd., formerly known as NGK SPARK PLUG CO., LTD.)
-
DeVilbiss Healthcare (a subsidiary of Drive Medical)
-
GCE Group
-
Compass Health Brands
-
Inogen, Inc.
-
Belluscura
-
Hoyo Scitech Co., Ltd.
-
BPL Medical Technologies
-
XNUO INTERNATIONAL GROUP (USA) HOLDING
-
Teijin Limited
-
BESCO MEDICAL LIMITED
-
Oxymed India
-
KALSTEIN FRANCE
-
Foshan Keyhub Electronic Industries Co., Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Respironics, GF Health Products, Inc., Nidek Medical Products, Inc., CAIRE Inc., DeVilbiss Healthcare, GCE Group, Inogen, Inc., Teijin Limited, BPL Medical Technologies)
- Focus on continuous product innovation and development of advanced portable and fixed oxygen concentrators.
- Expand global distribution networks through strategic partnerships, acquisitions, and healthcare provider collaborations.
- Strong brand recognition and established relationships with hospitals, home care providers, and distributors.
- Extensive product portfolios supported by robust R&D capabilities and regulatory approvals.
- Higher product pricing compared to regional and emerging competitors.
- Slower response to niche market opportunities due to larger organizational structures.
Emerging Players (e.g MedaCure Inc., O2 Concepts, React Health, Compass Health Brands, Belluscura, Hoyo Scitech Co., Ltd., XNUO International Group Holding, Besco Medical Limited, Oxymed India, Kalstein France, Foshan Keyhub Electronic Industries Co., Ltd.)
- Focus on cost-effective product offerings and targeted expansion in high-growth regional markets.
- Invest in portable, lightweight, and technologically advanced oxygen concentrator solutions to gain market share.
High operational flexibility and faster product development cycles.
Competitive pricing strategies that enhance adoption in price-sensitive markets.
- Limited global presence and distribution capabilities.
- Lower brand recognition and fewer financial resources for large-scale expansion and R&D investments.
Recent Developments
-
In January 2026, Oxymed launched the Oxymed Cure, a 5 LPM oxygen concentrator designed to provide affordable oxygen therapy while maintaining medical-quality and service standards. The product was priced about 15% lower than the flagship Oxymed Mini (5 LPM) and aims to expand access to reliable respiratory care and strengthen Oxymed’s position in India’s home oxygen concentrator market.
-
In June 2025, Inogen, Inc. launched the Voxi 5 stationary oxygen concentrator in the U.S. to improve access to high-quality oxygen therapy for long-term care patients. The product expanded Inogen’s respiratory care portfolio beyond portable oxygen concentrators, strengthening its presence in the stationary oxygen therapy segment.
Oxygen Concentrator Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.0 billion
Estimated market size in 2026
USD 5.2 billion
Projected market size by 2033
USD 7.0 billion
Growth rate
CAGR of 4.2% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, technology, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Sweden; Denmark; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Respironics (a subsidiary of Koninklijke Philips N.V.); GF Health Products, Inc.; MedaCure Inc.; Nidek Medical Products, Inc.; O2 Concepts; React Health; CAIRE Inc. (acquired by Niterra Co., Ltd., formerly known as NGK SPARK PLUG CO., LTD.); DeVilbiss Healthcare (a subsidiary of Drive Medical); GCE Group; Compass Health Brands; Inogen, Inc.; Belluscura; Hoyo Scitech Co., Ltd.; BPL Medical Technologies; XNUO International Group Holding; Teijin Limited; Besco Medical Limited; Oxymed India; Kalstein France; Foshan Keyhub Electronic Industries Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Oxygen Concentrator Market Report Segmentation
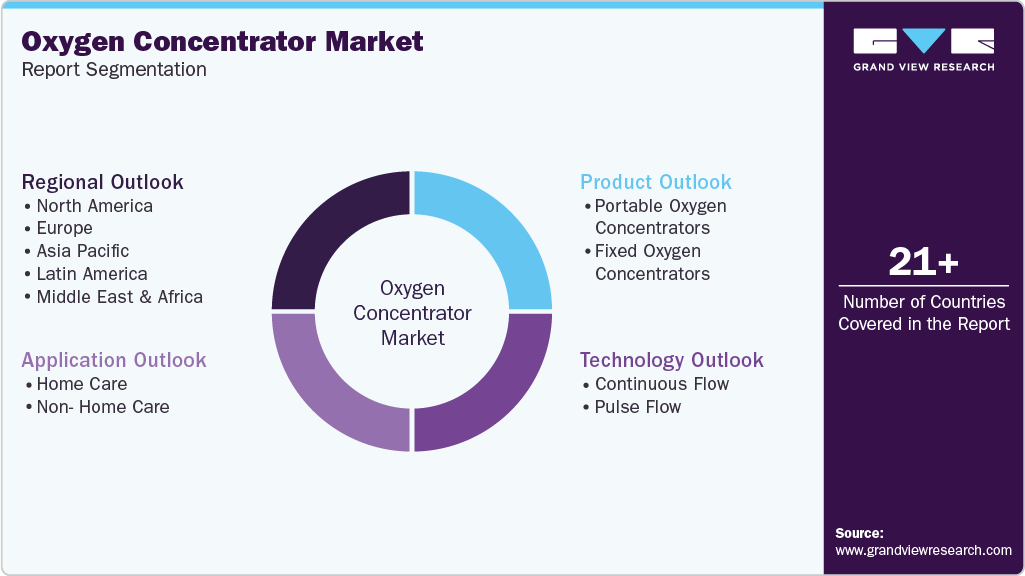
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global oxygen concentrator market report based on product, application, technology, and region:
 To learn more about this report, Download Free Sample Report
-
Products Outlook (Unit Volume, 000'; Revenue, USD Million, 2021 - 2033)
-
Portable Oxygen Concentrators
-
New Purchase
-
Rentals
-
-
Fixed Oxygen Concentrators
-
New Purchase
-
Rentals
-
-
-
Application Outlook (Unit Volume, 000'; Revenue, USD Million, 2021 - 2033)
-
Home Care
-
Non- Home Care
-
-
Technology Outlook (Unit Volume, 000'; Revenue, USD Million, 2021 - 2033)
-
Continuous Flow
-
Pulse Flow
-
-
Regional Outlook (Unit Volume, 000'; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Product
Revenue capture definition
Portable Oxygen Concentrators
Revenue generated from the sale of portable oxygen concentrators, including lightweight and battery-operated devices designed to provide supplemental oxygen while enabling patient mobility. The segment includes devices used across home care, travel, and ambulatory settings for long-term oxygen therapy.
Fixed Oxygen Concentrators
Revenue generated from the sale of stationary oxygen concentrators designed to provide a continuous supply of concentrated oxygen in residential and healthcare settings. The segment includes devices used in homes, hospitals, nursing facilities, and other clinical environments requiring long-duration oxygen therapy.
Segment - Application
Revenue capture definition
Home Care
Revenue generated from oxygen concentrators utilized in residential settings for the treatment and management of chronic respiratory conditions. This includes sales of devices prescribed for home oxygen therapy, long-term respiratory support, and patient self-management outside institutional healthcare facilities.
Non- Home Care
Revenue generated from oxygen concentrators used in healthcare facilities such as hospitals, clinics, ambulatory surgical centers, emergency care centers, rehabilitation facilities, and nursing homes. This segment captures oxygen therapy equipment deployed under professional medical supervision for acute and chronic respiratory care.
Segment - Technology
Revenue capture definition
Continuous Flow
Revenue generated from oxygen concentrators equipped with continuous flow technology that delivers a constant supply of oxygen irrespective of the patient’s breathing cycle. The segment includes both stationary and portable systems designed for patients requiring uninterrupted oxygen delivery.
Pulse Flow
Revenue generated from oxygen concentrators utilizing pulse dose technology, which delivers oxygen in measured bursts synchronized with the patient’s inhalation. The segment primarily includes portable oxygen concentrators designed to enhance battery efficiency, portability, and patient mobility.
Estimation Model
Stage
Description
Top-Down
Commodity Flow Analysis: Market size was estimated by analyzing revenues generated by key oxygen concentrator manufacturers and suppliers of respiratory oxygen therapy devices. Revenue data were collected from company annual reports, investor presentations, product portfolios, regulatory filings, and industry databases. Revenue contributions from private and regional manufacturers were validated through secondary research and primary interviews to determine the overall market size.
Parent Market
Parent Market & Penetration-Based Analysis: The oxygen concentrator market was derived from the broader respiratory care devices market. Market penetration was assessed by evaluating the adoption of oxygen concentrators across home care, hospitals, clinics, ambulatory care centers, and long-term care facilities. The analysis considered the prevalence of chronic respiratory diseases, long-term oxygen therapy utilization rates, aging population trends, and home healthcare adoption to estimate market size.
Segmentation
Country-Level Segment Share Modeling: Market shares for product, application, and technology segments were derived using country-specific healthcare expenditure, respiratory disease prevalence, oxygen therapy adoption rates, healthcare infrastructure, and reimbursement coverage. Weighted-average calculations were used to determine regional and global segment distributions.
Validation
Data Triangulation & Validation Model: Market estimates were validated through triangulation of secondary research, primary interviews, company-level revenue assessments, end-user demand analysis, respiratory disease treatment trends, oxygen therapy utilization patterns, healthcare infrastructure developments, and technological advancements in oxygen concentrator systems to ensure consistency and accuracy across all market segments and geographies.
Forecasting
Forecasting & CAGR Modeling: Market forecasts were developed using historical trends in respiratory care, growth in home healthcare services, increasing prevalence of chronic respiratory diseases such as COPD and asthma, rising geriatric population, expanding access to oxygen therapy, and technological advancements in portable and fixed oxygen concentrators. Regression-based analysis and trend modeling were applied to project future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Volume Analysis by Product Type
Evaluated comprehensive volume analysis of portable oxygen concentrators and fixed oxygen concentrators across major regions and end-use settings
Enabled understanding of demand patterns, production planning, inventory management, and product portfolio optimization
Country-Level Pricing & Reimbursement Analysis
Provided detailed assessment of oxygen concentrator pricing trends, reimbursement policies, and procurement practices across key countries
Supported pricing strategy development, market entry planning, and identification of high-potential regional opportunities
Technology & Innovation Assessment
Provided detailed analysis of advancements in portable oxygen concentrators, battery technologies, oxygen delivery systems, smart monitoring features, and connected respiratory care solutions
Helped identify emerging technology trends, product development opportunities, and competitive differentiation strategies
Frequently Asked Questions About This Report
Key factors that are driving the oxygen concentrator market growth include the rising prevalence of respiratory disorders such as chronic obstructive pulmonary disease (COPD), asthma, and sleep apnea coupled with increasing launch of technologically advanced devices. In addition, increasing demand for portable oxygen concentrators owing to their lightweight design, mobility, and battery-powered operation, enabling greater patient freedom and supporting the shift toward home healthcare is further contributing to the markets growth.
Some key players operating in the oxygen concentrators market include Respironics (a subsidiary of Koninklijke Philips N.V.); GF Health Products, Inc.; MedaCure Inc.; Nidek Medical Products, Inc.; O2 Concepts; React Health; CAIRE Inc. (acquired by Niterra Co., Ltd., formerly known as NGK SPARK PLUG CO., LTD.); DeVilbiss Healthcare (a subsidiary of Drive Medical); GCE Group; Compass Health Brands; Inogen, Inc.; Belluscura; Hoyo Scitech Co., Ltd.; BPL Medical Technologies; XNUO International Group Holding; Teijin Limited; Besco Medical Limited; Oxymed India; Kalstein France; Foshan Keyhub Electronic Industries Co., Ltd.
The fixed oxygen concentrators segment led with a 51.9% revenue share in 2025, while the portable oxygen concentrators segment is the fastest-growing product.
The home care segment led the market with the largest revenue share of 62.6% in 2025.
The global oxygen concentrators market size was valued at USD 5.0 billion in 2025 and is estimated at USD 5.2 billion for 2026.
Continuous flow technology held the highest market share of 55.8% in 2025. TContinuous flow technology provides reliable, uninterrupted oxygen delivery essential for patients with severe COPD and chronic respiratory conditions. Its widespread use in both clinical and homecare settings, along with proven effectiveness and affordability compared to newer alternatives, support the segment's dominant share.
The global oxygen concentrator market is expected to grow at a CAGR of 4.2% from 2026 to 2033, reaching USD 7.0 billion by 2033.
North America dominated the oxygen concentrator market with the largest revenue share of 35.4% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


