
- Home
- »
- Healthcare IT
- »
-
Medical Rehabilitation Services Market Report, 2026-2033GVR Report cover

Medical Rehabilitation Services Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Therapy (Physical Therapy, Occupational Therapy, Speech and Language Therapy), By Setting (Outpatient, Inpatient), By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$286.1BMarket Estimate, 2026
$303.4BMarket Forecast, 2033
$465.2BCAGR, 2026–2033
6.3%Medical Rehabilitation Services Market Summary
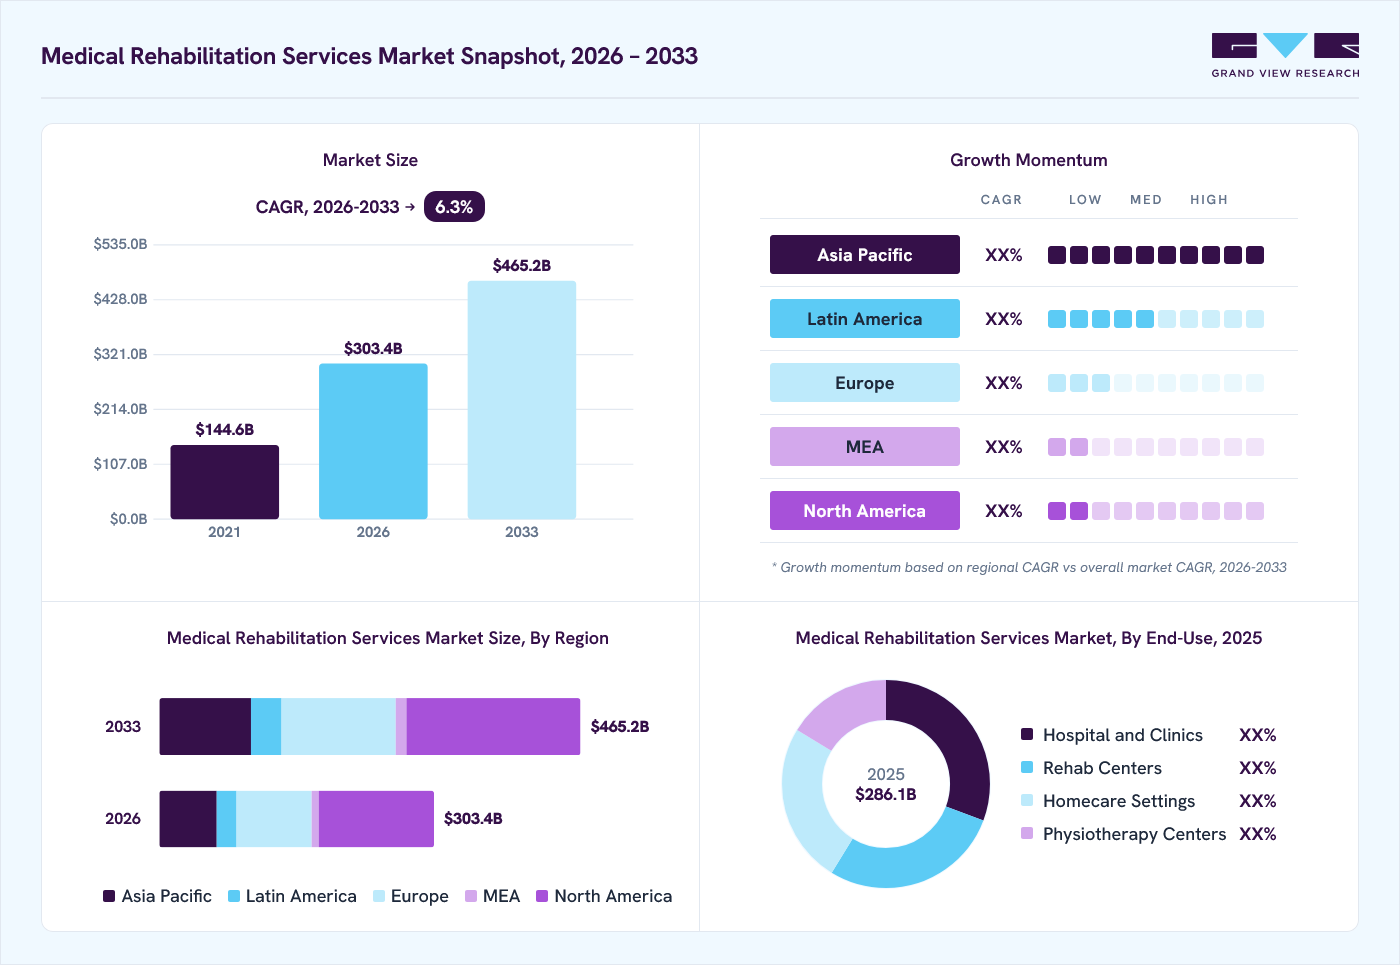
The global medical rehabilitation services market size was valued at USD 286.1 billion in 2025 and is projected to grow from USD 303.4 billion in 2026 to USD 465.2 billion by 2033, at a CAGR of 6.3% from 2026 to 2033. North America dominated the medical rehabilitation services market with the largest revenue share of 42.0% in 2025. Increasing number of patients with neurological, musculoskeletal, and cardiologic conditions is expected to drive the growth of the market over the forecast.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By therapy: Physical therapy segment held the largest market share of 37.1% in 2025.
- By setting: Outpatient segment held the largest market share of 55.1% in 2025.
- By application: Orthopedic segment held the largest market share of 37.4% in 2025.
- By end use: Hospital and clinics segment held the largest market share of 30.7% in 2025.
Regional Highlights
- Largest regional market: North America (42.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 286.1 Billion
- Estimated market size in 2026: USD 303.4 Billion
- Projected market size by 2033: USD 465.2 Billion
- CAGR (2026-2033): 6.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This contributes to the growing demand for comprehensive services to enhance functional improvement. It also helps in pain management, prevention of complications, improve quality of life, and optimize recovery for long-term self-management. The growing incidence of road traffic accidents, particularly in urban and industrial settings, is contributing to an increased need for comprehensive rehabilitation to address the cognitive, physical, and vocational impairments experienced by survivors. According to the WHO factsheet of December 2023, around 20 to 50 million individuals globally every year suffer from non-fatal injuries due to road traffic accidents, with many of them reporting disabilities. The accident survivors often experience chronic disabilities that impact their cognitive, behavioral, psychosocial, physical, and vocational functioning. Effective physical and cognitive interventions enhance recovery and minimize functional disabilities. This is expected to drive the growth of the market over the forecast period.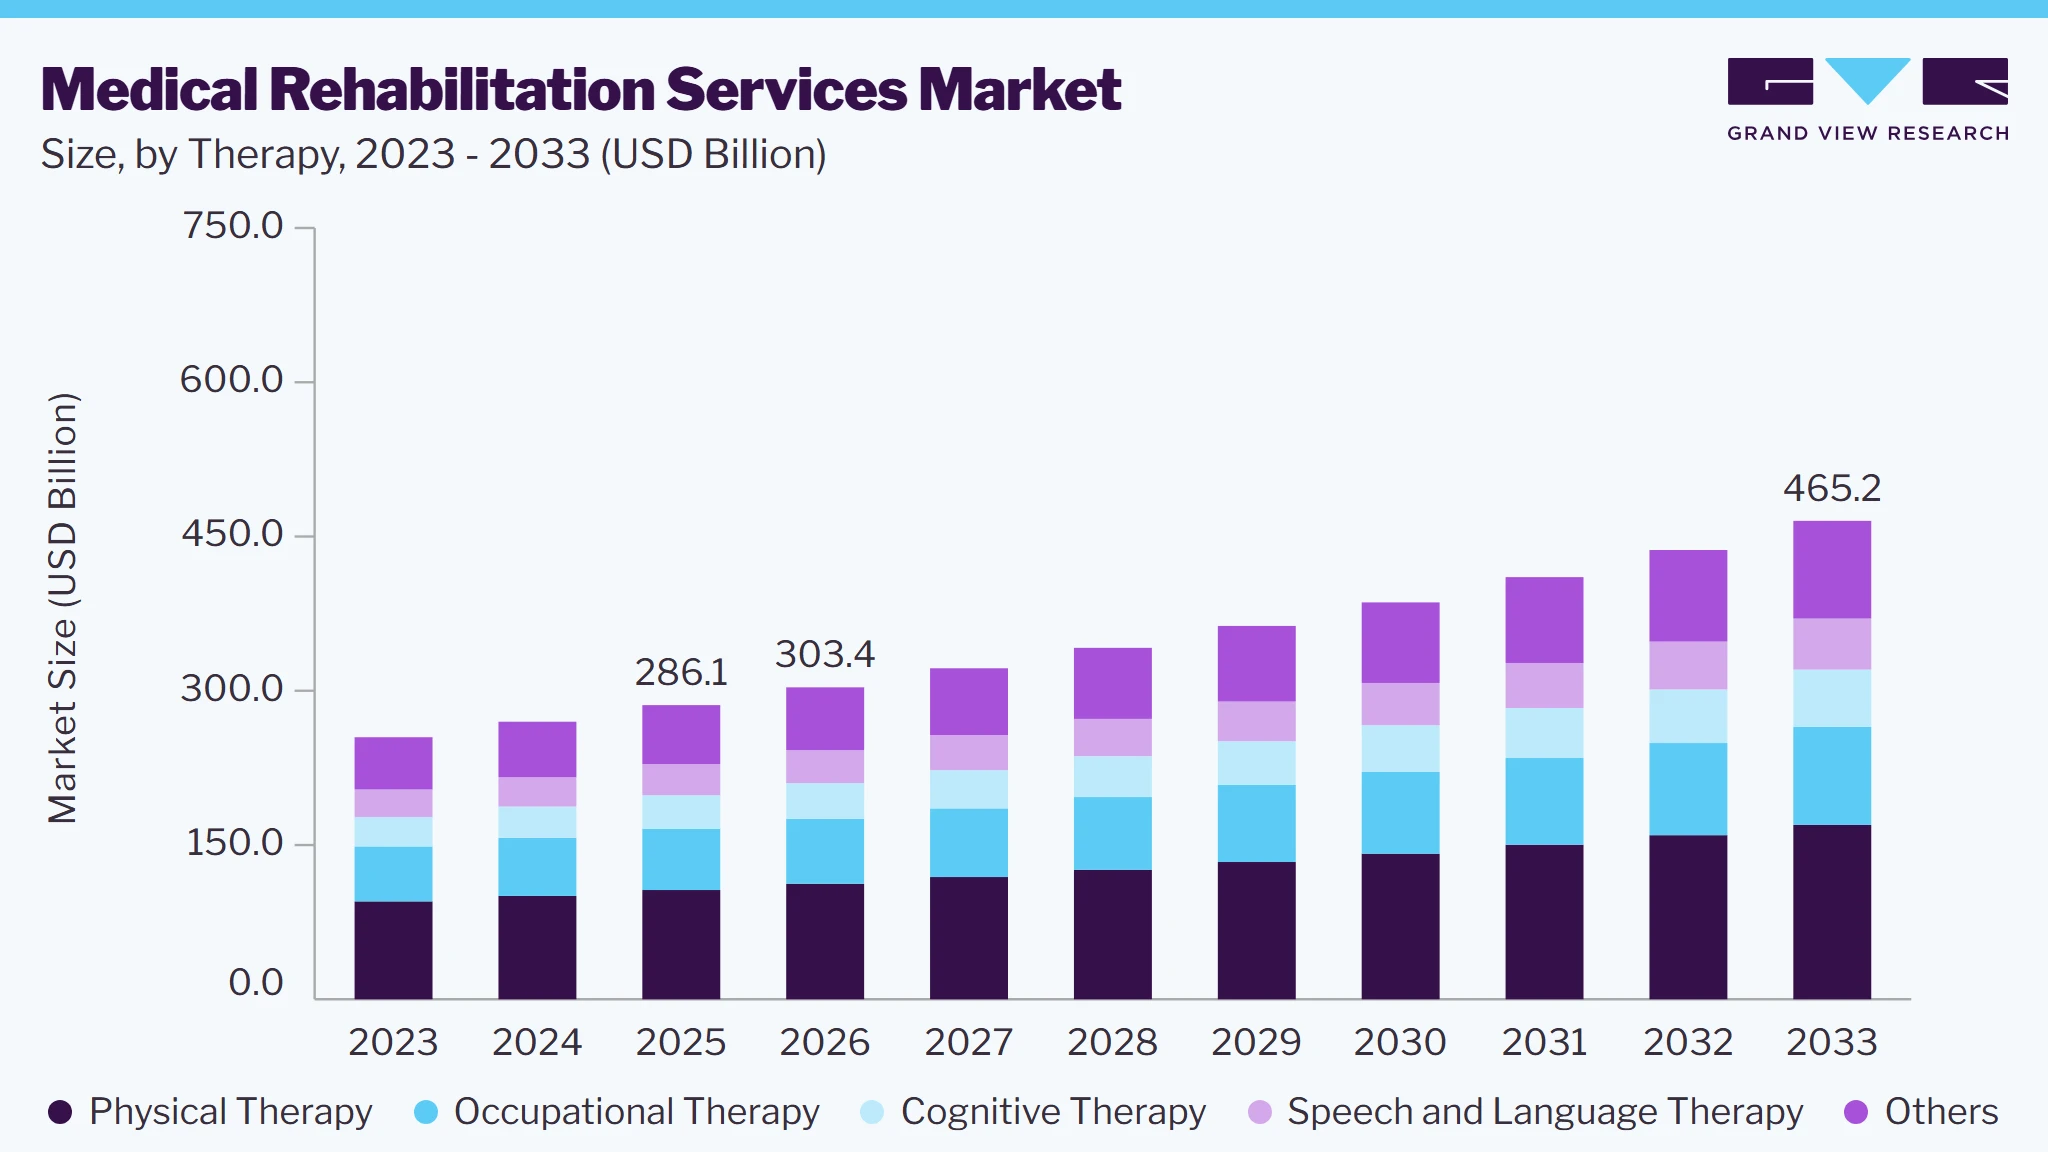 To learn more about this report, Download Free Sample Report
According to the WHO article published in March 2024, neurological conditions affect more than 1 in 3 individuals globally, leading to be the primary cause of illness and disability globally. Rising government initiatives to improve access to rehabilitation boost the growth of the market. These initiatives focus on promoting personal mobility, addressing financial barriers, increasing manpower supply and training, and introducing government schemes. According to the WHO article published in December 2023, a nationwide campaign in Georgia launched to boost referrals for rehabilitation, targeting healthcare professionals nationwide, reaching around 1,000 healthcare professionals in all 11 regions of the U.S. Such government initiatives are expected to contribute to the growing importance and effectiveness, encouraging greater utilization and investment, thereby boosting the demand.
Market Dynamics
The medical rehabilitation services market is growing due to the increasing prevalence of chronic diseases, disabilities, sports injuries, and age-related conditions requiring rehabilitative care. Rising demand for physical, occupational, and speech therapy services, coupled with advancements in rehabilitation technologies and telerehabilitation platforms, is supporting market growth. In addition, growing healthcare expenditure, increasing awareness of early rehabilitation interventions, and the expanding elderly population are driving demand for rehabilitation services. The focus on improving patient outcomes, enhancing functional independence, and reducing hospital readmissions continues to create significant growth opportunities in the market.
The rising number of patients with neurological, musculoskeletal, and cardiologic conditions continues to significantly drive demand for medical rehabilitation services. The increasing burden of these chronic conditions leads to long-term functional impairments, reduced mobility, and a growing need for structured rehabilitation programs focused on recovery, pain management, and improved quality of life. While survival rates improve due to advancements in medical care, a larger patient pool requires post-acute and continuous rehabilitation support across inpatient, outpatient, and homecare settings.
According to a March 2024 study published by the World Health Organization (WHO) and The Lancet Neurology, more than 3 billion people were living with a neurological condition in 2021, making neurological disorders the leading cause of ill health and disability globally. The total burden of these conditions, measured in disability-adjusted life years, has increased by 18% since 1990. Disorders such as stroke, Parkinson’s disease, multiple sclerosis, traumatic brain injuries, and spinal cord injuries often result in long-term physical, cognitive, and functional impairments that require comprehensive rehabilitation interventions.
“Neurological conditions cause great suffering to the individuals and families they affect, and rob communities and economies of human capital,” “This study should serve as an urgent call to action to scale up targeted interventions to allow the growing number of people living with neurological conditions to access the quality care, treatment and rehabilitation they need. It is more important than ever to ensure brain health is better understood, valued and protected, from early childhood to later life.”
- WHO Director-General.
For instance, in April 2024, the WHO reported that over 2.4 billion people globally require rehabilitation services, emphasizing the substantial and growing global need driven by chronic diseases and disability-related conditions. This increasing demand is encouraging healthcare systems to strengthen rehabilitation infrastructure, integrate advanced therapeutic technologies, and expand access to care, thereby fueling market growth.
The shortage of skilled professionals remains a critical restraint in the market, significantly limiting the capacity of healthcare systems to address the growing demand for therapy services. Rehabilitation care requires a multidisciplinary workforce, including physiotherapists, occupational therapists, speech-language pathologists, and rehabilitation specialists, all of whom require specialized training and clinical expertise. However, many regions continue to face persistent workforce shortages, inadequate training infrastructure, and an uneven geographic distribution of professionals, particularly in rural and underserved areas. This gap restricts timely access to rehabilitation services and places additional pressure on existing healthcare providers, leading to increased workloads and potential compromises in care quality.
According to the WHO in April 2024, several countries report fewer than 10 skilled rehabilitation professionals per 1 million population, underscoring the severity of the global workforce shortage. This shortage is further exacerbated by the rising prevalence of chronic diseases, aging populations, and increasing survival rates from acute medical conditions, all of which contribute to a higher demand for long-term rehabilitation. As a result, healthcare systems are facing significant challenges in scaling rehabilitation services, thereby restraining overall market growth.
A significant opportunity in the market is the growing adoption of tele-rehabilitation services, which enables patients to receive rehabilitation care remotely through digital platforms. Advances in telehealth technologies, wearable monitoring devices, and virtual therapy tools are improving access to physical, occupational, and speech therapy, particularly for patients in rural and underserved areas. Tele-rehabilitation reduces travel burdens, enhances treatment adherence, and allows healthcare providers to extend their reach beyond traditional clinical settings. As healthcare systems increasingly prioritize cost-effective and patient-centric care models, the demand for remote rehabilitation services is expected to create substantial growth opportunities for market participants.
Market Concentration & Characteristics
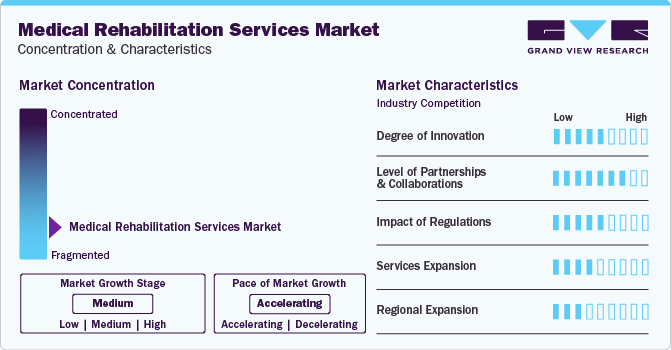
The chart below illustrates the relationship between industry concentration, industry characteristics, and industry participants. The x-axis represents the level of industry concentration, ranging from low to high. The y-axis represents various industry characteristics, including industry competition, level of partnerships & collaborations activities, impact of regulations, service substitutes, and geographic expansion. For instance, the industry is fragmented, with many small players entering the industry and offering new services. The level of partnerships & collaboration activities is medium, and service expansion is high. The impact of regulations on the industry is medium, and the regional expansion of the industry is medium.
 To learn more about this report, Download Free Sample Report
The degree of innovation within the sector is high, driven by advancements in technology, treatment modalities, and patient care approaches. This continuous innovation aims to enhance treatment effectiveness, improve patient outcomes, and optimize delivery. For instance, AI is being used to analyze vast amounts of data, predict patient outcomes, personalize treatment plans, and automate routine tasks.
Partnership and collaboration levels are currently moderate in the industry. This is primarily driven by the industry's effort to address the rising demand for temporary physician staffing through strategic alliances. Additionally, industry players are actively collaborating to mitigate staffing shortages, expand offerings, and adapt to the changing landscape of the healthcare sector. For instance, in August 2023, the Erada Center for Treatment and Rehabilitation collaborated with the University of Colorado's School of Medicine to enhance its treatment programs.
Regulations for these services impact the industry by ensuring quality and safety, which boosts patient trust and demand for the industry. Compliance with these regulations is crucial for healthcare providers to receive payment, thereby influencing the financial viability of these centers and the availability for patients.
Services encompass alternative therapies such as acupuncture, chiropractic care, and massage therapy, offering varied approaches to pain management and mobility improvement. The prevalence of these alternatives depends on regional availability and patient preferences, reducing their impact on the industry moderately.
The level of regional expansion varies, ranging from moderate to high, by increasing accessibility and availability of care. For instance, expanding coverage into rural areas helps to address unmet needs, thereby expanding the patient base. Initiatives, such as establishing new centers and adding advanced technologies in various regions, enhance local healthcare infrastructure.
Analyst Perspective
The medical rehabilitation services market is benefiting from the rising prevalence of chronic diseases, neurological disorders, musculoskeletal conditions, sports injuries, and age-related disabilities, along with growing demand for post-acute and long-term rehabilitative care. Increasing awareness of rehabilitation benefits, expanding healthcare infrastructure, and favorable reimbursement support are driving the adoption of physical, occupational, speech, and cardiac rehabilitation services. Advancements in robotic rehabilitation, virtual reality (VR)-based therapy, tele-rehabilitation, and remote patient monitoring are further improving treatment outcomes and expanding patient access. Companies that offer comprehensive multidisciplinary care, advanced rehabilitation technologies, specialized therapy programs, and seamless patient management solutions will be well positioned to enhance patient outcomes, improve care continuity, and strengthen their competitive position in the evolving medical rehabilitation services market.
Therapy Insights
Based on therapy, the physical therapy segment dominated the market with the largest revenue share of 37.1% in 2025. The segment growth can be attributed to its growing adoption for treating a range of conditions, including musculoskeletal, neurologic, sports injuries, and wound care. Moreover, lower back discomfort, spine, shoulder, rotator cuff injuries, knee diseases, and other sprains & strains are the most prevalent conditions treated with physical therapy.
According to the article published in Journal of the American Medical Association in January 2022, the number of individuals suffering from musculoskeletal disorders in need of rehabilitation increased to 1,713.6 million in 2019 from 1,060.6 million in 1990. As these trends are expected to continue, the demand for physical therapy is expected to boost over the forecast period.
The cognitive therapy segment is expected to grow at the fastest CAGR over the forecast period. Rising cases of drug abuse and alcoholism, linked with growing awareness of their detrimental health effects, are anticipated to drive the demand for cognitive therapy over the forecast period. According to the National Center for Drug Abuse Statistics of March 2024, more than 95,150 individuals in the U.S. died due to alcohol-related issues.
In addition, despite an estimated 15 million people fighting with Alcohol Use Disorder (AUD), less than 8% seek treatment for this condition. Cognitive therapy relieves individuals struggling with alcoholism and drug abuse by addressing underlying thought patterns and behaviors contributing to these conditions. Promoting healthier managing mechanisms and assisting in developing strategies to manage triggers, cognitive therapy plays a crucial role in addiction recovery. This effective approach, coupled with increasing awareness of its benefits, is driving heightened demand for cognitive therapy in addressing alcoholism abuse disorders.
Application Insights
Based on application, the orthopedic segment dominated the market with the largest revenue share of 37.4%. The increasing prevalence of orthopedic conditions, including spinal injuries, arthritis, ankle injuries, and hip injuries, drive growth within the segment throughout the forecast period. According to an NCBI article published in June 2021, around 1.6 million people every year suffer from hip fractures globally. The geriatric population is expected to increase to 2.6 million by 2025 and 4.5 million by 2050. This segment's dominance is further supported by the availability of advanced technologies and equipment in outpatient centers, enhancing the quality of care and outcomes for orthopedic patients.
Sports-related injuries segment is expected to grow at the fastest CAGR over the forecast period. This can be attributed to the increasing number of sports participants, particularly children and adolescents. As more individuals engage in sports and recreational activities, the probability of experiencing injuries increases, leading to a higher demand for therapy adapted to address sports-related injuries.
For instance, in 2024, over 3.5 million children aged 14 and younger sustain injuries each year while participating in sports or recreational activities in the U.S. As the number of sports participants increases, so does the demand to address these injuries, driving growth.This is expected to contribute to the demand for specialized programs and therapy designed to meet the unique needs of athletes and active individuals, thereby driving the growth of the segment.
End-use Insights
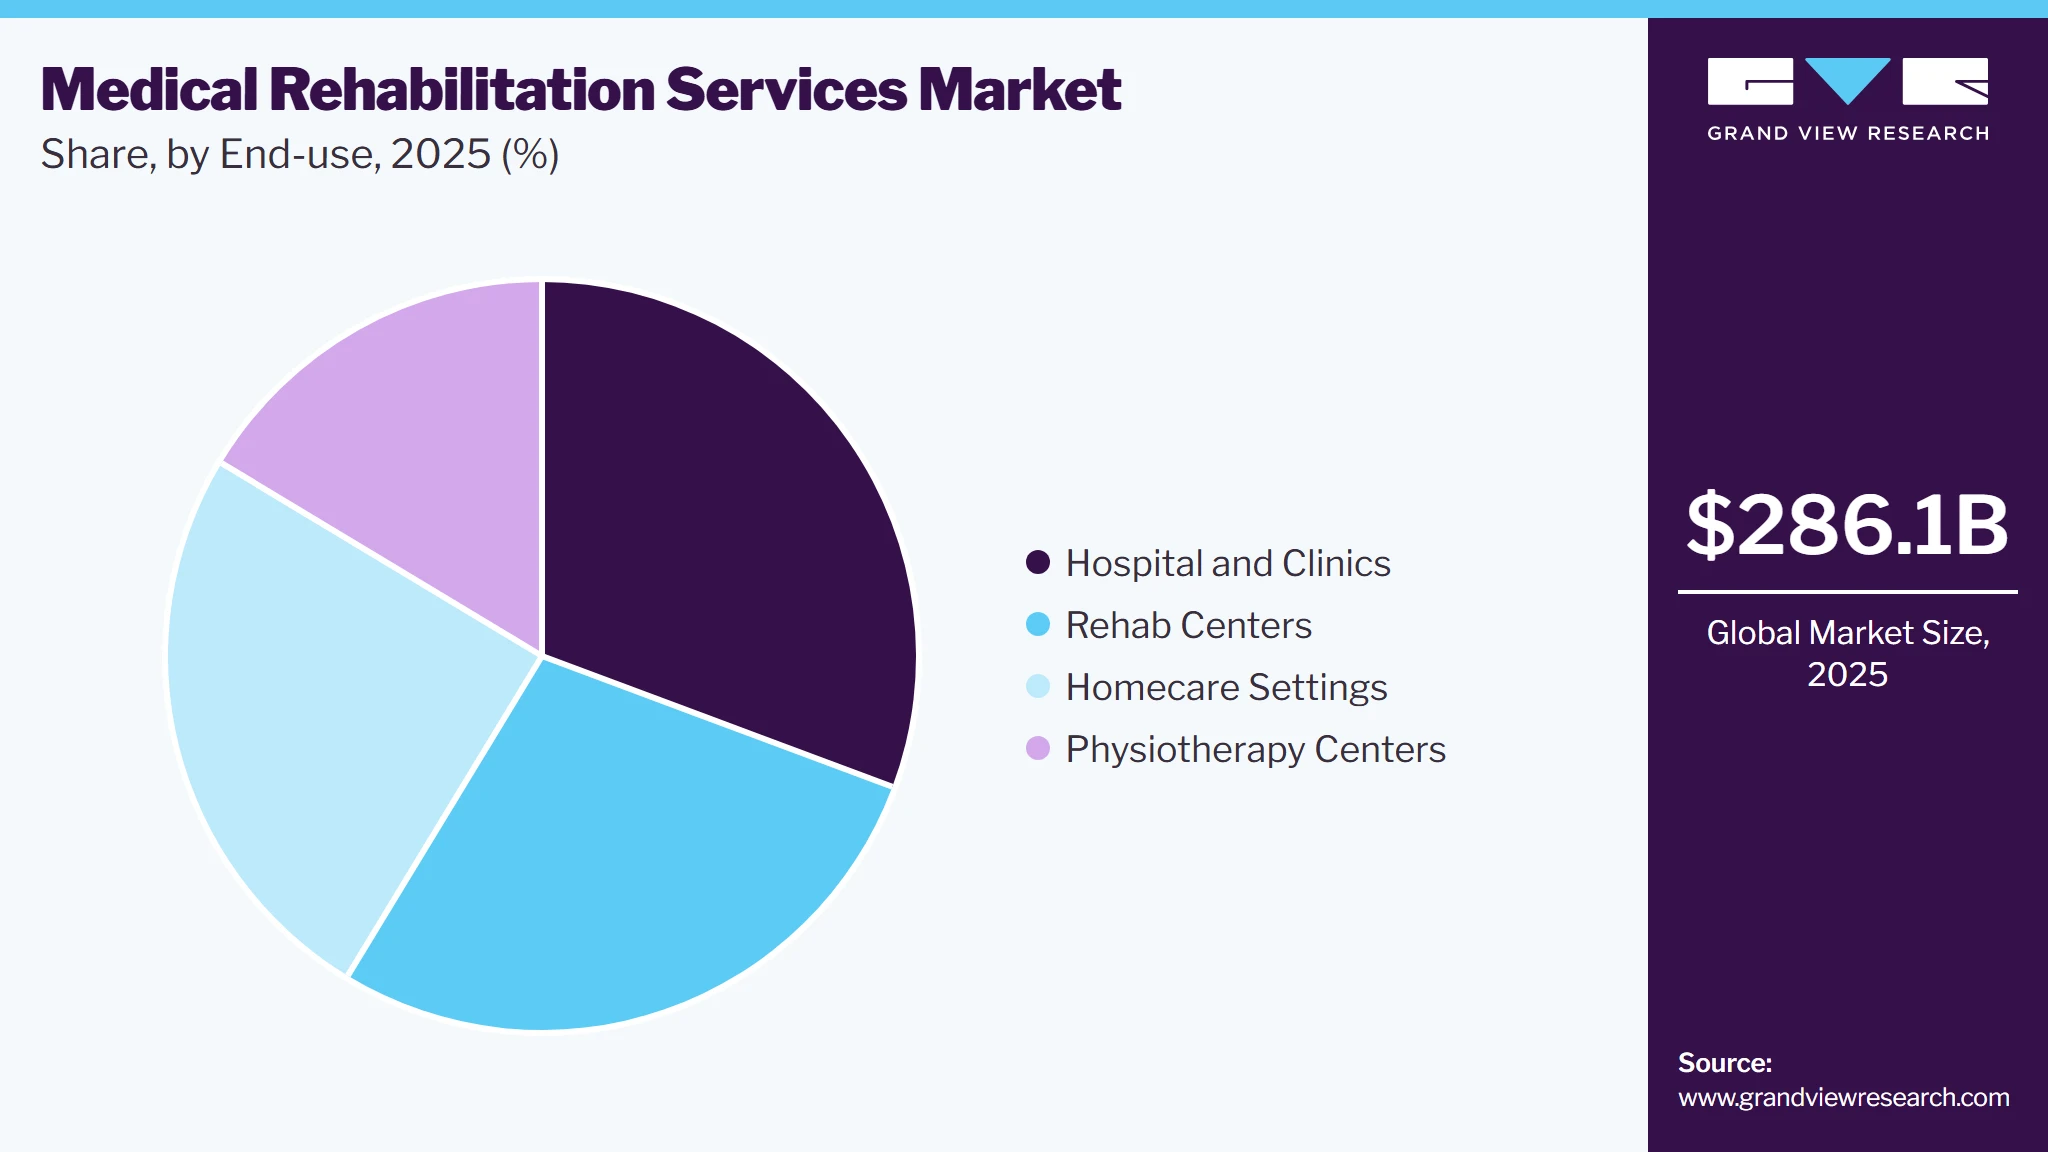
Based on end use, the hospital and clinics segment dominated the market with the largest revenue share of 30.7% in 2025. This is due to the rising inflow of patients opting for these services at hospitals and clinics. Furthermore, hospitals and clinics provide widespread therapy coverage, including physical, occupational, and speech therapy, under one roof, which attracts a broad patient base. These facilities are equipped with advanced medical technology and staffed by highly trained healthcare professionals, ensuring high-quality care and effective outcomes.
 To learn more about this report, Download Free Sample Report
Integrating acute care and rehabilitation within the same facility enhances patient continuity of care and recovery. Additionally, the launch of new settings offering advanced therapy is contributing to the growth of the industry. For instance, in March 2024, Trilife Hospital in Bengaluru, India, opened a new Neurorehabilitation and Sports Medicine Center with 40 beds.
The homecare settings segment is expected to grow at the fastest CAGR over the forecast period. This growth is driven by increasing demand for convenient and personalized services and technological advancements enabling home-based treatments. Factors such as cost-effectiveness, improved patient outcomes, and the need to reduce healthcare facility admissions contribute to expanding therapy in homecare settings. Moreover, technological innovations such as wearables, telemedicine platforms, and remote monitoring systems are making it easier to provide home services, further driving this segment's growth.
Setting Insights
Based on setting, the outpatient segment dominated the market with the largest revenue share of 55.1% in 2025. This can be attributed to the lower cost compared to inpatient settings and the integration of advanced neurorehabilitation technologies into outpatient treatment. The cost of the therapy in outpatient is slightly lower compared to inpatient settings, owing to costs associated with the hospital stay with inpatient care.
As per the article published in the Journal of Rehabilitation Medicine in April 2021, the cost of the therapy was approximately three times greater for inpatient than outpatient therapy in Europe. Physical therapy costs around USD 2,579, occupational costs around USD 2,061, and psychological costs around USD 1,835 in outpatient centers across Europe.
The inpatient segment is expected to grow at a significant rate as inpatient settings often have access to specialized equipment and resources unavailable in outpatient or homecare settings. These include advanced therapeutic devices, rehab technology, and specialized facilities to facilitate fast recovery. The settings offer intensive, long-term recovery therapy to a patient population recovering from severe injuries, complex surgeries, or chronic illnesses that significantly impact their ability to perform daily activities independently.
Regional Insights
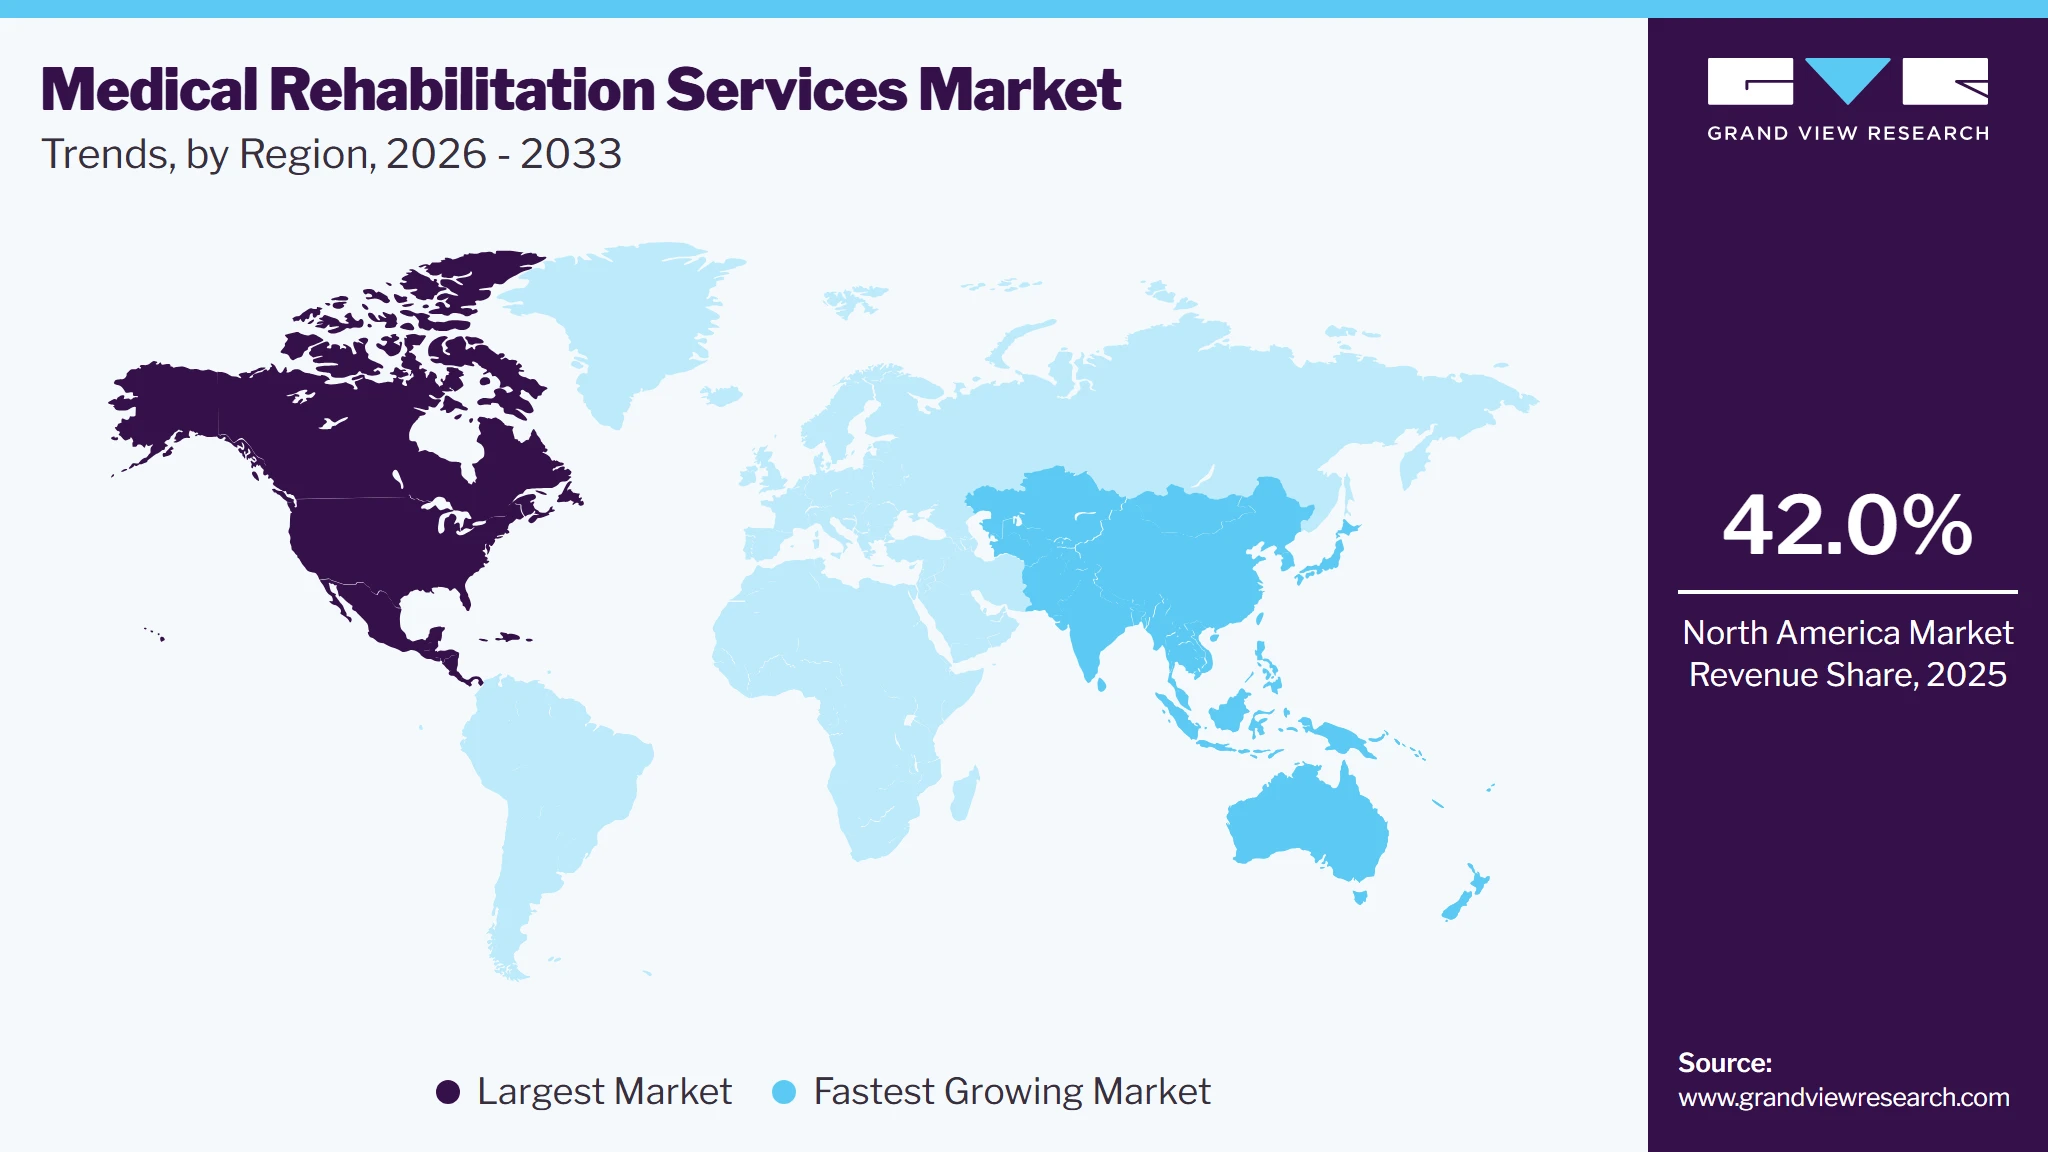
North America dominated the medical rehabilitation services market with the largest revenue share of 42.0% in 2025. The growth of the market in the region was supported by factors such as the accessibility of these therapies in-home care and outpatient facilities, along with favorable reimbursement policies.
 To learn more about this report, Download Free Sample Report
U.S. Medical Rehabilitation Services Market Trends
The medical rehabilitation services market in the U.S. held the largest share in the North America region in 2025, due to well-established healthcare infrastructure, including state-of-the-art facilities. The increasing demand for healthcare services, rising disposable income, and increased healthcare expenditure are expected to contribute to the growth of the industry.
As per the American Physical Therapy Association, since January 1, 2021, Medicare Part B allows physical therapists (PTs) and Physical Therapist Assistants (PTAs) to administer rehabilitative and skilled maintenance therapy, including in various settings such as homes, assisted and independent living facilities, and Skilled Nursing Facilities (SNFs). This change, implemented in the 2021 Physician Fee Schedule Final Rule, permits PTAs to provide skilled maintenance therapy for outpatient care under Medicare Part B.
Europe Medical Rehabilitation Services Market Trends
The medical rehabilitation services market in Europe is anticipated to grow significantly due to the increasing geriatric population to address age-related conditions and improve quality of life. Moreover, advancements in medical technology are enhancing treatment options, leading to improved patient outcomes and increased adoption.These trends are expected to drive industry’s growth, addressing the evolving healthcare needs of the population.
Germany's medical rehabilitation services market held the largest share in the Europe region in 2023. Supportive government policies and initiatives to improve healthcare infrastructure and expand access to rehabilitative therapy are expected to drive market growth. The increasing prevalence of chronic diseases and musculoskeletal disorders in Germany also creates greater demand, contributing to the growth.
The medical rehabilitation services market in UK is expected to witness the fastest growth over the forecast period. Growing awareness among healthcare professionals and patients about the benefits of managing chronic conditions and improving total health is expected to contribute to market growth.
Asia Pacific Medical Rehabilitation Services Market Trends
Asia Pacific medical rehabilitation services marketis expected to witness the fastest growth over the forecast period. Increasing urbanization and sedentary lifestyles contribute to a higher incidence of injuries and musculoskeletal disorders, driving the need for these therapies in the region.
The medical rehabilitation services market in Japan held the largest share in 2023, owing to the rise in aging populations. Japan has one of the world's oldest populations, leading to a higher prevalence of age-related conditions and disabilities. This demographic trend is expected to drive the demand in the country.
India medical rehabilitation services market has witnessed high demand in recent years. The increasing prevalence of non-communicable diseases such as cardiovascular diseases, diabetes, and musculoskeletal disorders is driving demand in India.
Latin America Medical Rehabilitation Services Market Trends
Themedical rehabilitation services market in Latin Americais anticipated to grow significantly due to greater emphasis on mental health rehab therapies to address conditions such as depression, anxiety, and Post-Traumatic Stress Disorder (PTSD).
Brazil medical rehabilitation services market held the largest share in 2023. Brazil has a high incidence of traumatic injuries, including those from road accidents and violence. This contributes to a growing demand for rehabilitative therapies to aid in the recovery of individuals with injuries.
MEA Medical Rehabilitation Services Market Trends
The medical rehabilitation services market in MEA region is anticipated to witness significant growth due to the establishment of specialized centers focusing on specific conditions, such as spinal cord injuries, stroke recovery, and pediatric rehabilitation, addressing the needs of different patient groups.
South Africa medical rehabilitation services market held the largest share in 2023. A supportive regulatory framework that encourages the establishment and operation of centers contributes to the industry expansion. Regulations that standardize and ensure quality care also boost public confidence in these therapies.
Key Medical Rehabilitation Services Company Insights
The industry is highly fragmented and competitive, with the presence of a few major players and a small number of small- & medium-sized care centers. Some emerging companies are Centrex Rehab, BenchMark PT,Carrus Health, ATI Physical Therapy, and NovaCare Rehabilitation.
Key Medical Rehabilitation Services Companies
The following key companies have been profiled for this study on the medical rehabilitation services market.
-
Shirley Ryan AbilityLab
-
Prism Medical
-
Icahn School of Medicine at Mount Sinai
-
Paradigm Healthcare
-
The University of Chicago Medical Center
-
MindMaze Healthcare
-
Lifespan Physical Therapy Services
-
SuVitas
-
nMotion Physical Therapy
-
Therapy Solutions for Kids
-
Athletico Physical Therapy
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Encompass Health Corporation, Genesis HealthCare, Kindred Hospitals, ATI Physical Therapy)
- Expand service networks, invest in advanced rehabilitation technologies, strengthen hospital and payer partnerships.
- Strong brand reputation, broad service portfolio, large patient base, extensive therapist network.
- High operating costs, slower innovation adoption, dependence on reimbursement policies.
Emerging Players (Hinge Health, Sword Health, Kaia Health, RecoveryOne, Reflexion Health)
- Focus on niche therapies, tele-rehabilitation, home-based care, and digital health solutions.
- Greater flexibility, faster innovation, lower costs, personalized care models.
- Limited brand recognition, smaller referral networks, constrained financial resources.
Recent Developments
-
In April 2024, Mumtada Medical Company partnered with the Mass General Brigham to provide advanced rehabilitative services and long-term post-acute care in Saudi Arabia. Mass General Brigham will help in establishing Mumtada Rehabilitation Hospital in Riyadh as the first step in their strategic collaboration.
-
In March 2024 , SportsMed Physical Therapy launched a new service, SportsMed HomeCare, expanding its outpatient physical therapy, occupational therapy, and speech therapy services to homebound patients in the New Jersey & Connecticut regions in the U.S.
-
In October 2023, The Health Service Executive (HSE) launched a new model of care for cardiac rehabilitation in Ireland, focusing on bringing services closer to patients' homes and integrating them across hospital and community settings. This approach emphasizes personalized care plans, early patient contact during hospital stays, and automatic referral to cardiac rehabilitation upon discharge.
-
In February 2023, Datos Health collaborated with Shirley Ryan AbilityLab to provide a remote care platform, Open Care, to the center for an outpatient remote therapeutic monitoring implementation study.
-
In August 2023, PureHealth expanded its offerings by incorporating the National Rehabilitation Center (NRC) into its network. This integration aims to enhance treatment programs, integrate innovative technologies, and establish a national strategy, aligning with Abu Dhabi's commitment to delivering comprehensive healthcare services.
Medical Rehabilitation Services Market Report Scope
Report Attribute
Details
Market size in 2025
USD 286.1 billion
Estimated market size in 2026
USD 303.4 billion
Projected market size by 2033
USD 465.2 billion
Growth rate
CAGR of 6.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Therapy, setting, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Shirley Ryan AbilityLab; Prism Medical; Icahn School of Medicine at Mount Sinai; Paradigm Healthcare; The University of Chicago Medical Center; MindMaze Healthcare; Lifespan Physical Therapy Services; SuVitas; nMotion Physical Therapy; Therapy Solutions for Kids; Athletico Physical Therapy
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Rehabilitation Services Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical rehabilitation services market report based on therapy, setting, application, end-use, and region.
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Physical Therapy
-
Occupational Therapy
-
Cognitive Therapy
-
Speech and Language Therapy
-
Others
-
-
Setting Outlook (Revenue, USD Million, 2021 - 2033)
-
Outpatient
-
Inpatient
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Orthopedic
-
Cardiologic
-
Neurological
-
Pulmonary
-
Sports Related Injuries
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital and Clinics
-
Rehab Centers
-
Homecare Settings
-
Physiotherapy Centers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
Australia
-
India
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
-
Research Methodology
The medical rehabilitation services market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical rehabilitation services segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Therapy
Revenue capture definition
Physical Therapy
Focuses on restoring movement, strength, and physical function through exercises, manual therapy, and specialized equipment, primarily for musculoskeletal, orthopedic, and post-surgical conditions.
Occupational Therapy
Aims to help patients regain the ability to perform daily living and work-related activities by improving motor, cognitive, and functional skills.
Cognitive Therapy
Involves interventions designed to improve cognitive functions such as memory, attention, problem-solving, and decision-making, often used in neurological and brain injury rehabilitation
Speech and Language Therapy
Targets communication disorders, speech impairments, and swallowing difficulties, commonly associated with stroke, neurological disorders, and developmental conditions.
Others
Includes specialized therapies such as respiratory therapy, vocational rehabilitation, and psychological rehabilitation addressing specific patient needs.
Segment - Setting
Revenue capture definition
Outpatient
Rehabilitation services provided without hospital admission, typically through clinics or therapy centers, allowing patients to receive treatment while continuing daily activities.
Inpatient
Intensive rehabilitation services delivered within hospitals or specialized facilities where patients require continuous medical supervision and structured therapy programs.
Segment - Setting
Revenue capture definition
Orthopedic
Rehabilitation for conditions related to bones, joints, ligaments, and muscles,
including fractures, arthritis, and post-surgical recovery.
Cardiologic
Focuses on recovery and functional improvement for patients with cardiovascular conditions, including post-heart attack or cardiac surgery rehabilitation.
Neurological
Addresses disorders affecting the brain, spinal cord, and nerves, such as stroke, Parkinson’s disease, and traumatic brain injuries.
Pulmonary
Designed for patients with chronic respiratory diseases such as COPD and asthma, improving breathing efficiency and physical endurance.
Sports Related Injuries
Rehabilitation for injuries caused by physical activities or sports, including ligament tears, sprains, and muscle injuries.
Others
Includes rehabilitation for conditions such as cancer recovery, pediatric disorders, and chronic pain management.
Segment - End Use
Revenue capture definition
Hospital and Clinics
Provide comprehensive rehabilitation services as part of acute and post-acute care, supported by multidisciplinary medical teams.
Rehab Centers
Specialized facilities focused exclusively on delivering structured rehabilitation programs for various conditions.
Homecare Settings
Rehabilitation services delivered at home through visiting therapists or digital health platforms, supporting convenience and long-term care
Physiotherapy Centers
Dedicated centers primarily offer physical therapy services for musculoskeletal and mobility-related conditions.
Estimation Model
Model Details
This research methodology outlines the process for estimating the size of the global medical rehabilitation services market for the period from 2021 to 2033. The study covers key service segments, including physical therapy, occupational therapy, speech and language therapy, respiratory therapy, cardiac rehabilitation, neurological rehabilitation, sports injury rehabilitation, pediatric rehabilitation, geriatric rehabilitation, and other specialized rehabilitation services across major geographic regions including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
The objective is to develop a robust and defensible market estimate through a combination of bottom-up and top-down approaches supported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis from rehabilitation service volumes, therapy sessions conducted, rehabilitation facility revenues, average treatment costs, and patient utilization rates.
-
Top-Down Checks using healthcare expenditure, prevalence of chronic diseases and disabilities, aging population trends, injury incidence rates, hospital discharge statistics, and healthcare infrastructure data.
-
Primary Research with rehabilitation centers, hospitals, therapy clinics, healthcare providers, rehabilitation specialists, insurers, healthcare administrators, and industry experts.
Step-By-Step Market Estimation Process
-
Rehabilitation Service Utilization Model
This model calculates market size by estimating the number of patients receiving rehabilitation services and the associated annual spending.
Step 1: Cuntry-level data fr rehabilitatin service utilizatin, patient ppulatins, disability prevalence, chrnic disease incidence, and healthcare infrastructure fr 2021–2025 was cllected frm gvernment health agencies, healthcare rganizatins, rehabilitatin assciatins, and public health databases.
Step 2: Rehabilitatin utilizatin rates were applied t estimate the percentage f eligible patients receiving rehabilitatin services annually. Utilizatin rates were derived frm healthcare surveys, rehabilitatin registries, clinical studies, insurance claims databases, and primary interviews.
Step 3: Average annual spending per rehabilitatin patient was estimated using treatment csts, therapy sessin charges, reimbursement rates, prvider billing data, and facility interviews.
Step 4: Market size was calculated by multiplying:
- Number f Rehabilitatin Patients × Average Annual Spending per Patient
Step 5: Calculatins were perfrmed at the cuntry level and subsequently aggregated t reginal and glbal levels.
Step 6: Histrical and frecast grwth rates were incrprated based n aging demgraphics, increasing prevalence f chrnic diseases, rising disability rates, sprts injuries, pst-surgical rehabilitatin demand, and expansin f rehabilitatin infrastructure.
- Rehabilitatin Facility Revenue Extraplatin Mdel
This mdel estimates market size using revenues generated by rehabilitatin service prviders.
Step 1: The number f active rehabilitatin centers, therapy clinics, hspital-based rehabilitatin departments, skilled nursing facilities, and utpatient rehabilitatin prviders by cuntry was identified thrugh healthcare registries, industry assciatins, cmpany disclsures, and prprietary databases.
Step 2: Average annual revenue per rehabilitatin facility was estimated using financial reprts, industry benchmarks, facility interviews, reimbursement data, and market intelligence surces.
Step 3: Facility revenues were adjusted fr reginal differences in treatment csts, reimbursement structures, service mix, patient vlumes, and healthcare spending levels.
Step 4: Cuntry-level market size was calculated by multiplying:
- Number f Rehabilitatin Facilities × Adjusted Average Annual Revenue per Facility
Step 5: Reginal and glbal market values were generated thrugh aggregatin f cuntry-level estimates.
Step 6: Annual adjustments were applied t accunt fr expansin f rehabilitatin centers, adptin f tele-rehabilitatin services, reimbursement plicy changes, technlgical advancements, and healthcare infrastructure investments.
- Therapy Sessin Vlume and Treatment Cst Mdel
This mdel estimates market size based n the vlume f rehabilitatin services delivered and average treatment csts acrss therapy categries.
Step 1: Therapy sessin vlume data was cllected frm rehabilitatin prviders, hspitals, utpatient clinics, healthcare databases, industry publicatins, and rehabilitatin assciatins.
Step 2: Services were categrized int:
-
Physical Therapy
-
ccupatinal Therapy
-
Speech and Language Therapy
-
Respiratry Therapy
-
Cardiac Rehabilitatin
-
Neurlgical Rehabilitatin
-
Sprts Injury Rehabilitatin
-
Pediatric Rehabilitatin
-
Geriatric Rehabilitatin
-
ther Rehabilitatin Services
Step 3: Average treatment csts and therapy duratin were established using prvider pricing data, reimbursement schedules, healthcare claims databases, and expert interviews.
Step 4: Revenue generated by each service categry was calculated by multiplying:
- Number f Therapy Sessins/Treatment Prgrams × Average Cst per Sessin/Prgram
Step 5: Categry-level revenues were aggregated t determine cuntry, reginal, and glbal market sizes.
Step 6: Frecast assumptins incrprated rising rehabilitatin awareness, increasing chrnic disease burden, grwth in pst-acute care services, technlgical innvatins such as rbtic rehabilitatin and virtual therapy, tele-rehabilitatin adptin, and favrable healthcare plicy develpments.
-
Market Validation and Forecasting
The estimates derived from the rehabilitation service utilization model, rehabilitation facility revenue extrapolation model, and therapy session volume and treatment cost model were cross validated through data triangulation. Findings were further verified through primary interviews with rehabilitation service providers, hospital administrators, therapy specialists, healthcare consultants, payers, and industry experts. Final market forecasts were developed by evaluating demographic trends, healthcare expenditure growth, disease prevalence patterns, rehabilitation workforce availability, reimbursement environments, and technological advancements shaping the global medical rehabilitation services market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Patient Rehabilitation Journey & Treatment Adherence Analysis
Conducted a patient-centric assessment tracking rehabilitation pathways from diagnosis and referral through therapy completion and follow-up care. Evaluated treatment adherence factors, patient satisfaction, therapy dropout rates, and rehabilitation outcomes.
Provides actionable insights for improving patient retention, optimizing care pathways, reducing treatment discontinuation, and enhancing rehabilitation effectiveness.
Rehabilitation Service Pricing & Reimbursement Benchmarking Study
Evaluated therapy pricing, reimbursement rates, payer coverage policies, service utilization trends, and regional treatment cost variations across physical, occupational, speech, and specialized rehabilitation services.
Supports pricing strategy development, reimbursement optimization, profitability analysis, contract negotiations, and market positioning.
Outcome-Based Care & Value-Based Rehabilitation Assessment
Evaluated patient outcome measurement frameworks, value-based reimbursement initiatives, and quality performance metrics adopted by rehabilitation providers.
Helps stakeholders align with evolving reimbursement models, improve clinical outcomes, and demonstrate treatment value to payers and healthcare systems.
Frequently Asked Questions About This Report
The physical therapy segment dominated the market with the largest revenue share of 37.1% in 2025.
The orthopedic segment dominated the market with the largest revenue share of 37.4%.
The hospital and clinics segment dominated the market with the largest revenue share of 30.7% in 2025.
The global medical rehabilitation services market was estimated at USD 286.1 billion in 2025 and is expected to reach USD 303.4 billion in 2026.
The global medical rehabilitation services market is expected to grow at a CAGR of 6.3% from 2026 to 2033, reaching USD 465.2 billion by 2033.
Based on setting, the outpatient rehabilitation segment held the largest share in 2025. This can be attributed to the lower cost compared to inpatient settings and the integration of advanced neurorehabilitation technologies into outpatient treatment.
The key players of medical rehabilitation services market are Shirley Ryan AbilityLab, Prism Medical, Icahn School of Medicine at Mount Sinai, Paradigm Healthcare, The University of Chicago Medical Center, MindMaze Healthcare, Lifespan Physical Therapy Services, SuVitas, nMotion Physical Therapy, Therapy Solutions for Kids, Athletico Physical Therapy
The key factors that are driving the market growth are growing demand for comprehensive services to enhance functional improvement, pain management, prevention of complications, improve quality of life, and optimize recovery for long-term self-management.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


