
- Home
- »
- Medical Devices
- »
-
Wound Care Market Size And Share Report, 2026-2033GVR Report cover

Wound Care Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Advanced Wound Dressing, Surgical Wound Care), By Application (Chronic, Acute), By End Use, By Mode Of Purchase, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$25.1BMarket Estimate, 2026
$26.1BMarket Forecast, 2033
$35.1BCAGR, 2026–2033
4.3%Wound Care Market Summary
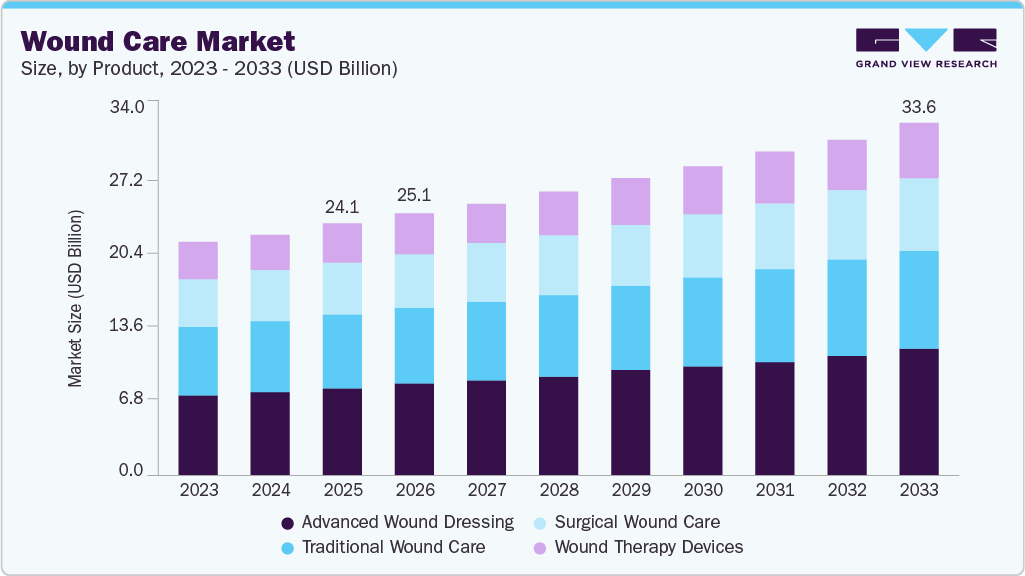
The global wound care market size was valued at USD 25.1 billion in 2025 and is projected to grow from USD 26.1 billion in 2026 to USD 35.1 billion by 2033, at a CAGR of 4.3% from 2026 to 2033. North America dominated the market, accounting for the largest share of 46.9% in 2025. The wound care industry’s growth is primarily driven by the rising prevalence of chronic wounds, including diabetic foot ulcers, pressure injuries, and venous leg ulcers, as well as a growing aging population that is more susceptible to impaired wound healing.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Advanced wound dressing segment held the largest market share in 2025.
- By application: Chronic wounds segment held the largest market share of 59.8% in 2025.
- By end-use: Hospital segment held the largest market share of 36.4% in 2025.
- By mode of purchase: Prescribed segment held the largest market share in 2025.
- By distribution channel: Institutional sales segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (46.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. led North America with the largest revenue share in 2025
Market Size & Forecast
- Market size in 2025: USD 25.1 Billion
- Estimated market size in 2026: USD 26.1 Billion
- Projected market size by 2033: USD 35.1 Billion
- CAGR (2026-2033): 4.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, increasing surgical procedures, trauma and burn cases, the expanding adoption of advanced wound care products, and greater emphasis on reducing healthcare costs through faster healing and improved clinical outcomes continue to support market growth.
 To learn more about this report, Download Free Sample Report
The rising prevalence of chronic wounds, including diabetic foot ulcers, pressure injuries, venous leg ulcers, and arterial ulcers, is a major driver of the wound care market. The increasing burden of diabetes, obesity, vascular diseases, and an aging population has led to a growing number of patients requiring prolonged wound management and advanced treatment solutions. This has accelerated the adoption of advanced wound dressings, negative-pressure wound therapy (NPWT), biologics, and digital wound-monitoring technologies to improve healing outcomes, reduce complications, and lower healthcare costs.
 To learn more about this report, Download Free Sample Report
Prevalence of Wounds (%) in the Medicare Population by Wound Type and Beneficiary Demographics
Beneficiary Demographics
Venous Wounds (Infections)
Pressure Ulcer
Chronic Ulcer
Surgical Wounds (Infections)
Skin Disorders (Infections)
Traumatic Wound
Arterial Wound
Diabetic Foot Ulcer (Infections)
All Wounds
Male (<65 years)
0.6 (2.3)
1.4
2.2
3.5 (4.4)
1.7 (0.03)
2.6
0.4
1.1 (3.2)
12.5
Male (65–75 years)
0.6 (1.6)
0.9
1.5
2.6 (3.1)
2.1 (0.05)
2
0.3
0.7 (2.4)
11
Male (>75 years)
1.3 (3.0)
3.3
3.5
3.8 (4.8)
3.5 (0.13)
4.1
0.7
1.0 (4.6)
19.6
Female (<65 years)
0.6 (2.3)
1.1
1.6
3.4 (5.0)
2.4 (0.04)
2.4
0.3
0.7 (3.1)
13.4
Female (65–75 years)
0.8 (1.7)
0.9
1.4
2.5 (3.3)
2.5 (0.05)
1.8
0.2
0.4 (2.5)
11.7
Female (>75 years)
1.4 (3.2)
3.6
3.7
3.1 (4.0)
2.6 (0.07)
2.7
0.4
0.7 (3.4)
19.6
Source: Wounds APAC 2024
Chronic Wound Epidemiology and Community Care in Europe
-
Europe’s population was estimated at 744.7 million as of 28 January 2025, accounting for approximately 9.21% of the global population (based on United Nations estimates).
-
Chronic wounds had an estimated prevalence of 2.21 cases per 1,000 population across Europe.
-
Approximately 24% of the community population received care from community nursing services, highlighting the significant demand for wound management in community-based healthcare settings.
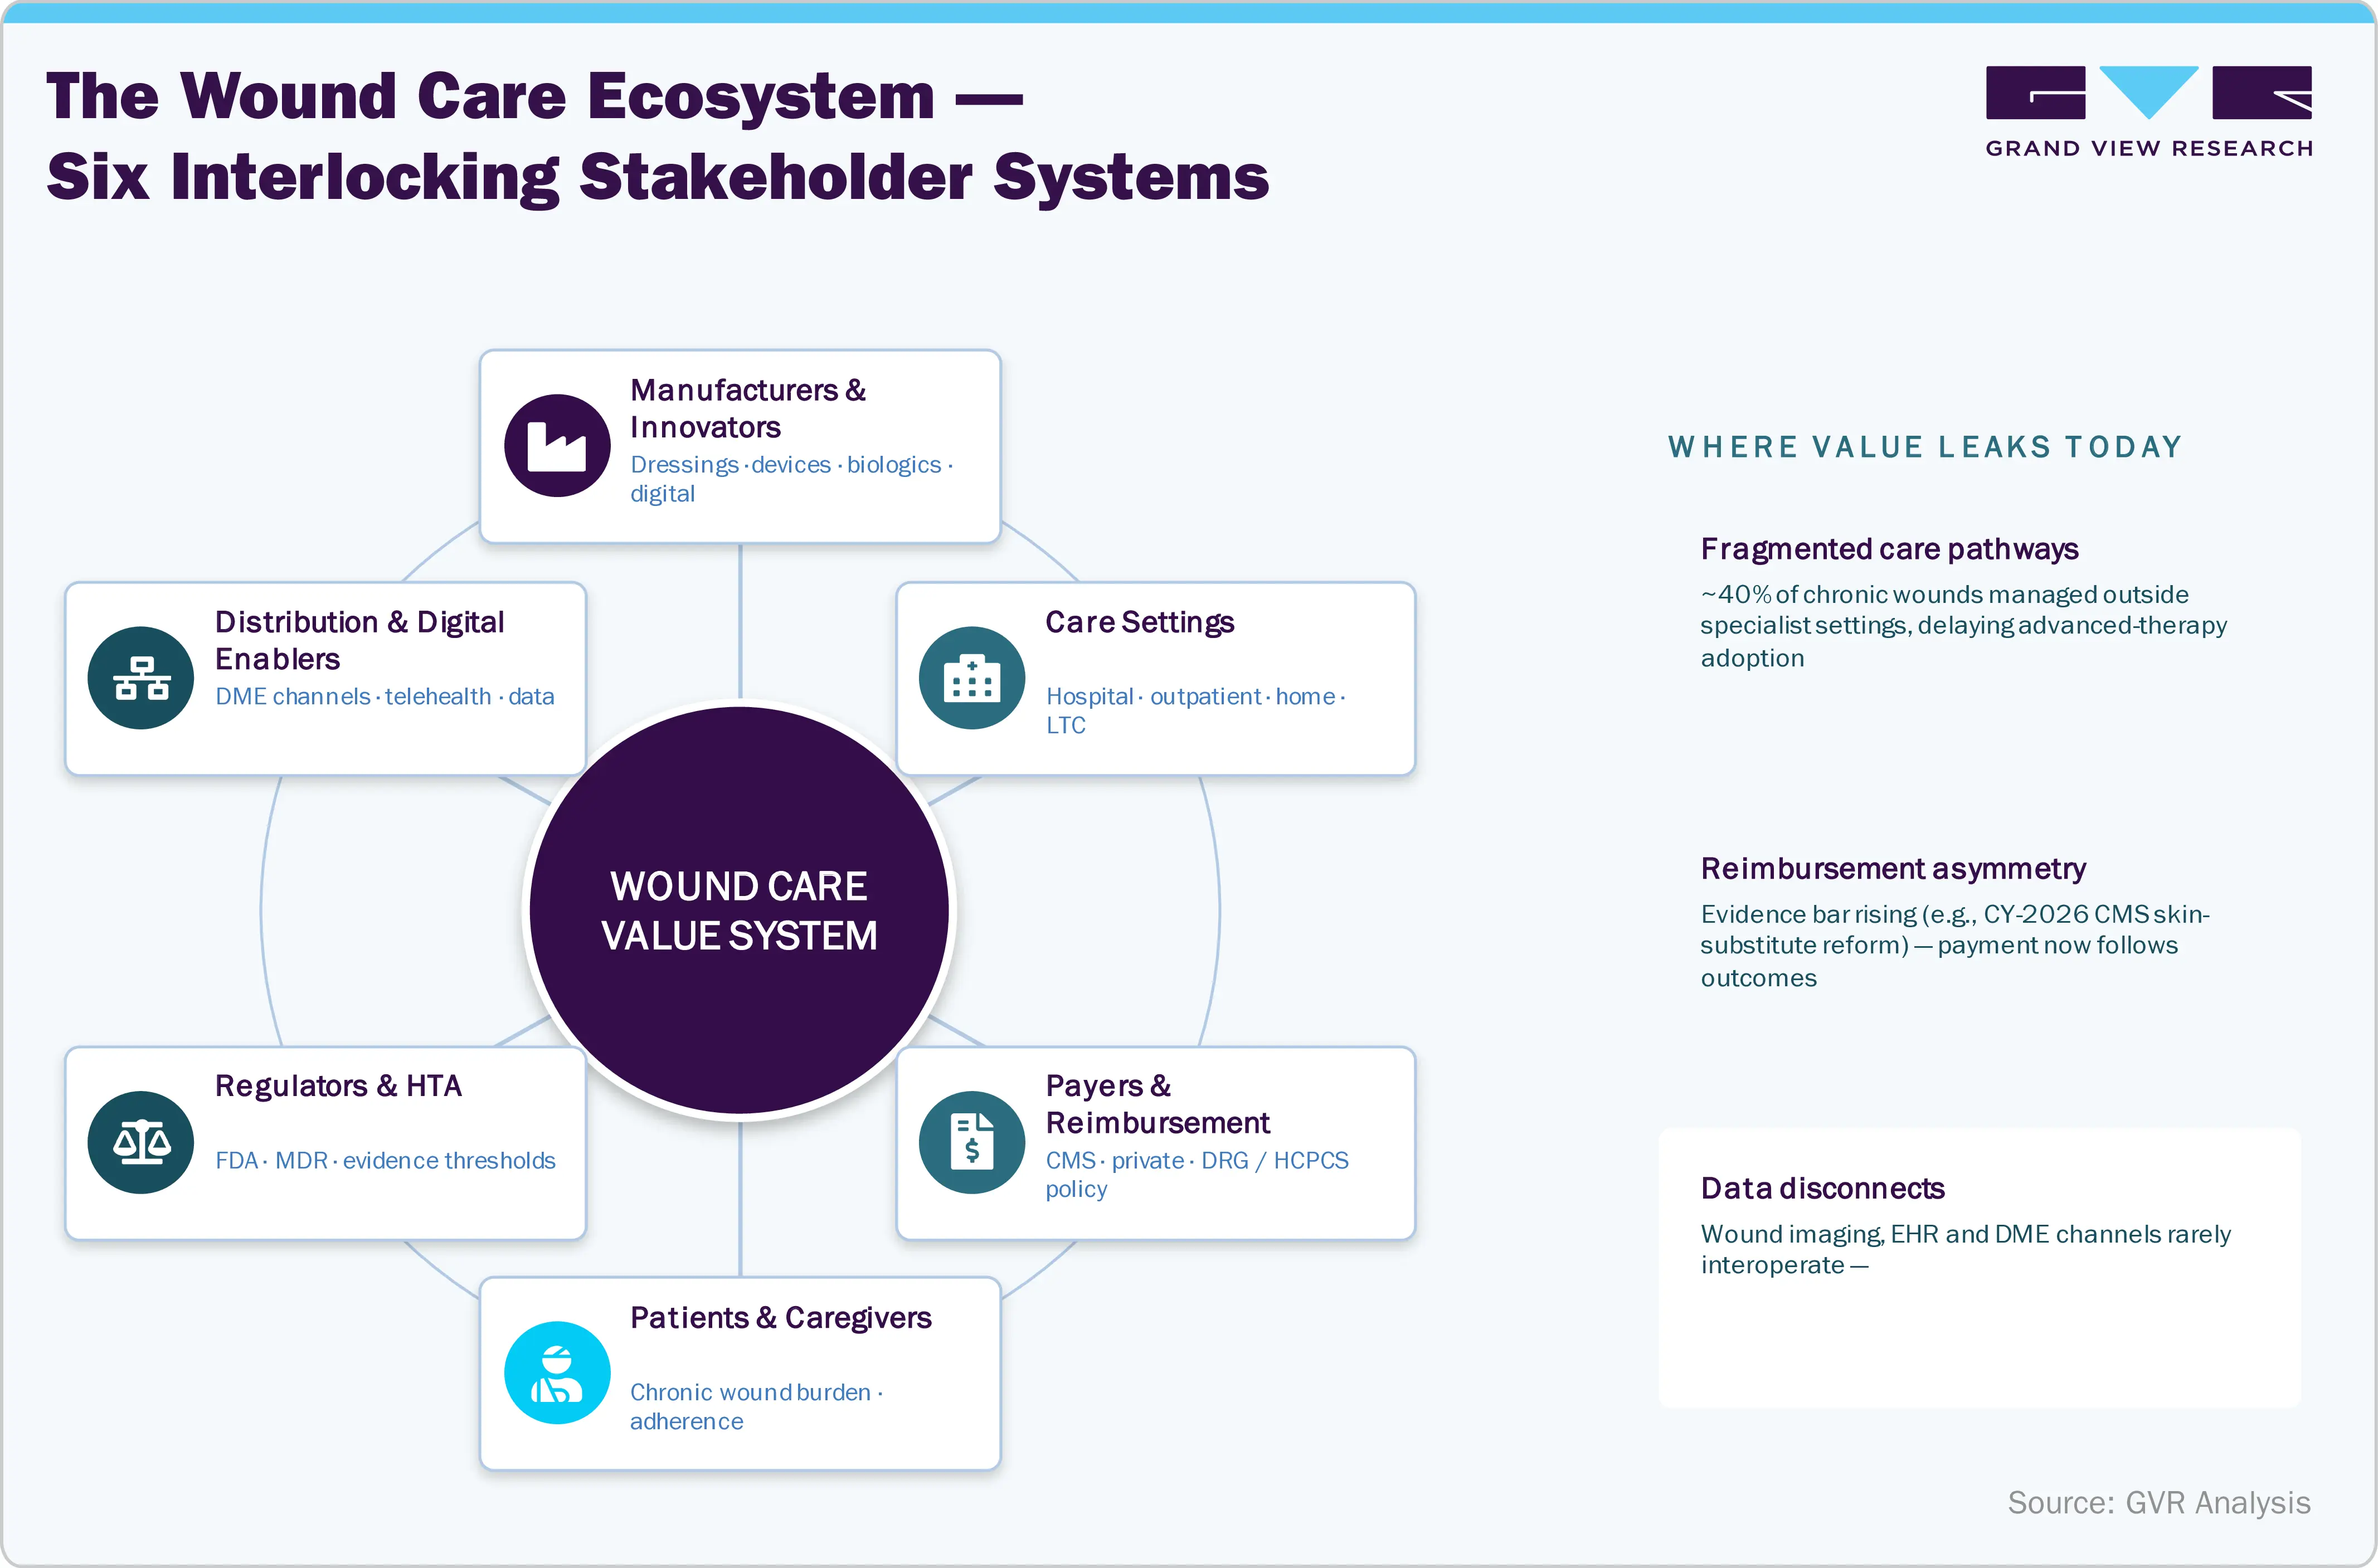
According to a 2025 peer-reviewed review published in a journal of Mary Ann Liebert, chronic wounds represent a substantial public health burden, affecting approximately 1 in 6 U.S. Medicare beneficiaries (~10 million people) and driving billions in healthcare costs annually. The review highlights persistent non-healing and recurrence as major challenges and points to emerging personalized, technology-enabled wound care approaches, such as bioengineered skin substitutes, biomarker-guided treatment, and telehealth, as key to improving outcomes and reducing amputations. The rising prevalence of chronic wounds directly expands patient volumes, accelerates the adoption of advanced therapies, and sustains long-term market growth.
 To learn more about this report, Download Free Sample Report
The global diabetes burden is a significant driver of demand for wound care solutions. According to the IDF Diabetes Atlas 2025, about 589 million adults (20–79 years)-roughly 1 in 9-live with diabetes worldwide, and over 40% of them are undiagnosed. Prevalence is projected to rise to ~853 million by 2050, driven by aging, urbanization, lifestyle changes, obesity, and physical inactivity. Diabetes significantly increases chronic wound risk, especially diabetic foot ulcers and slow-healing sores, which require advanced wound management and long-term care. As diabetes prevalence climbs, health systems will face larger patient populations needing wound care products, protocols, and specialist services. The expanding global diabetes population directly boosts market growth by increasing the incidence of chronic and complex wounds, raising utilization of dressings, regenerative therapies, and clinician-directed interventions year over year.
 To learn more about this report, Download Free Sample Report
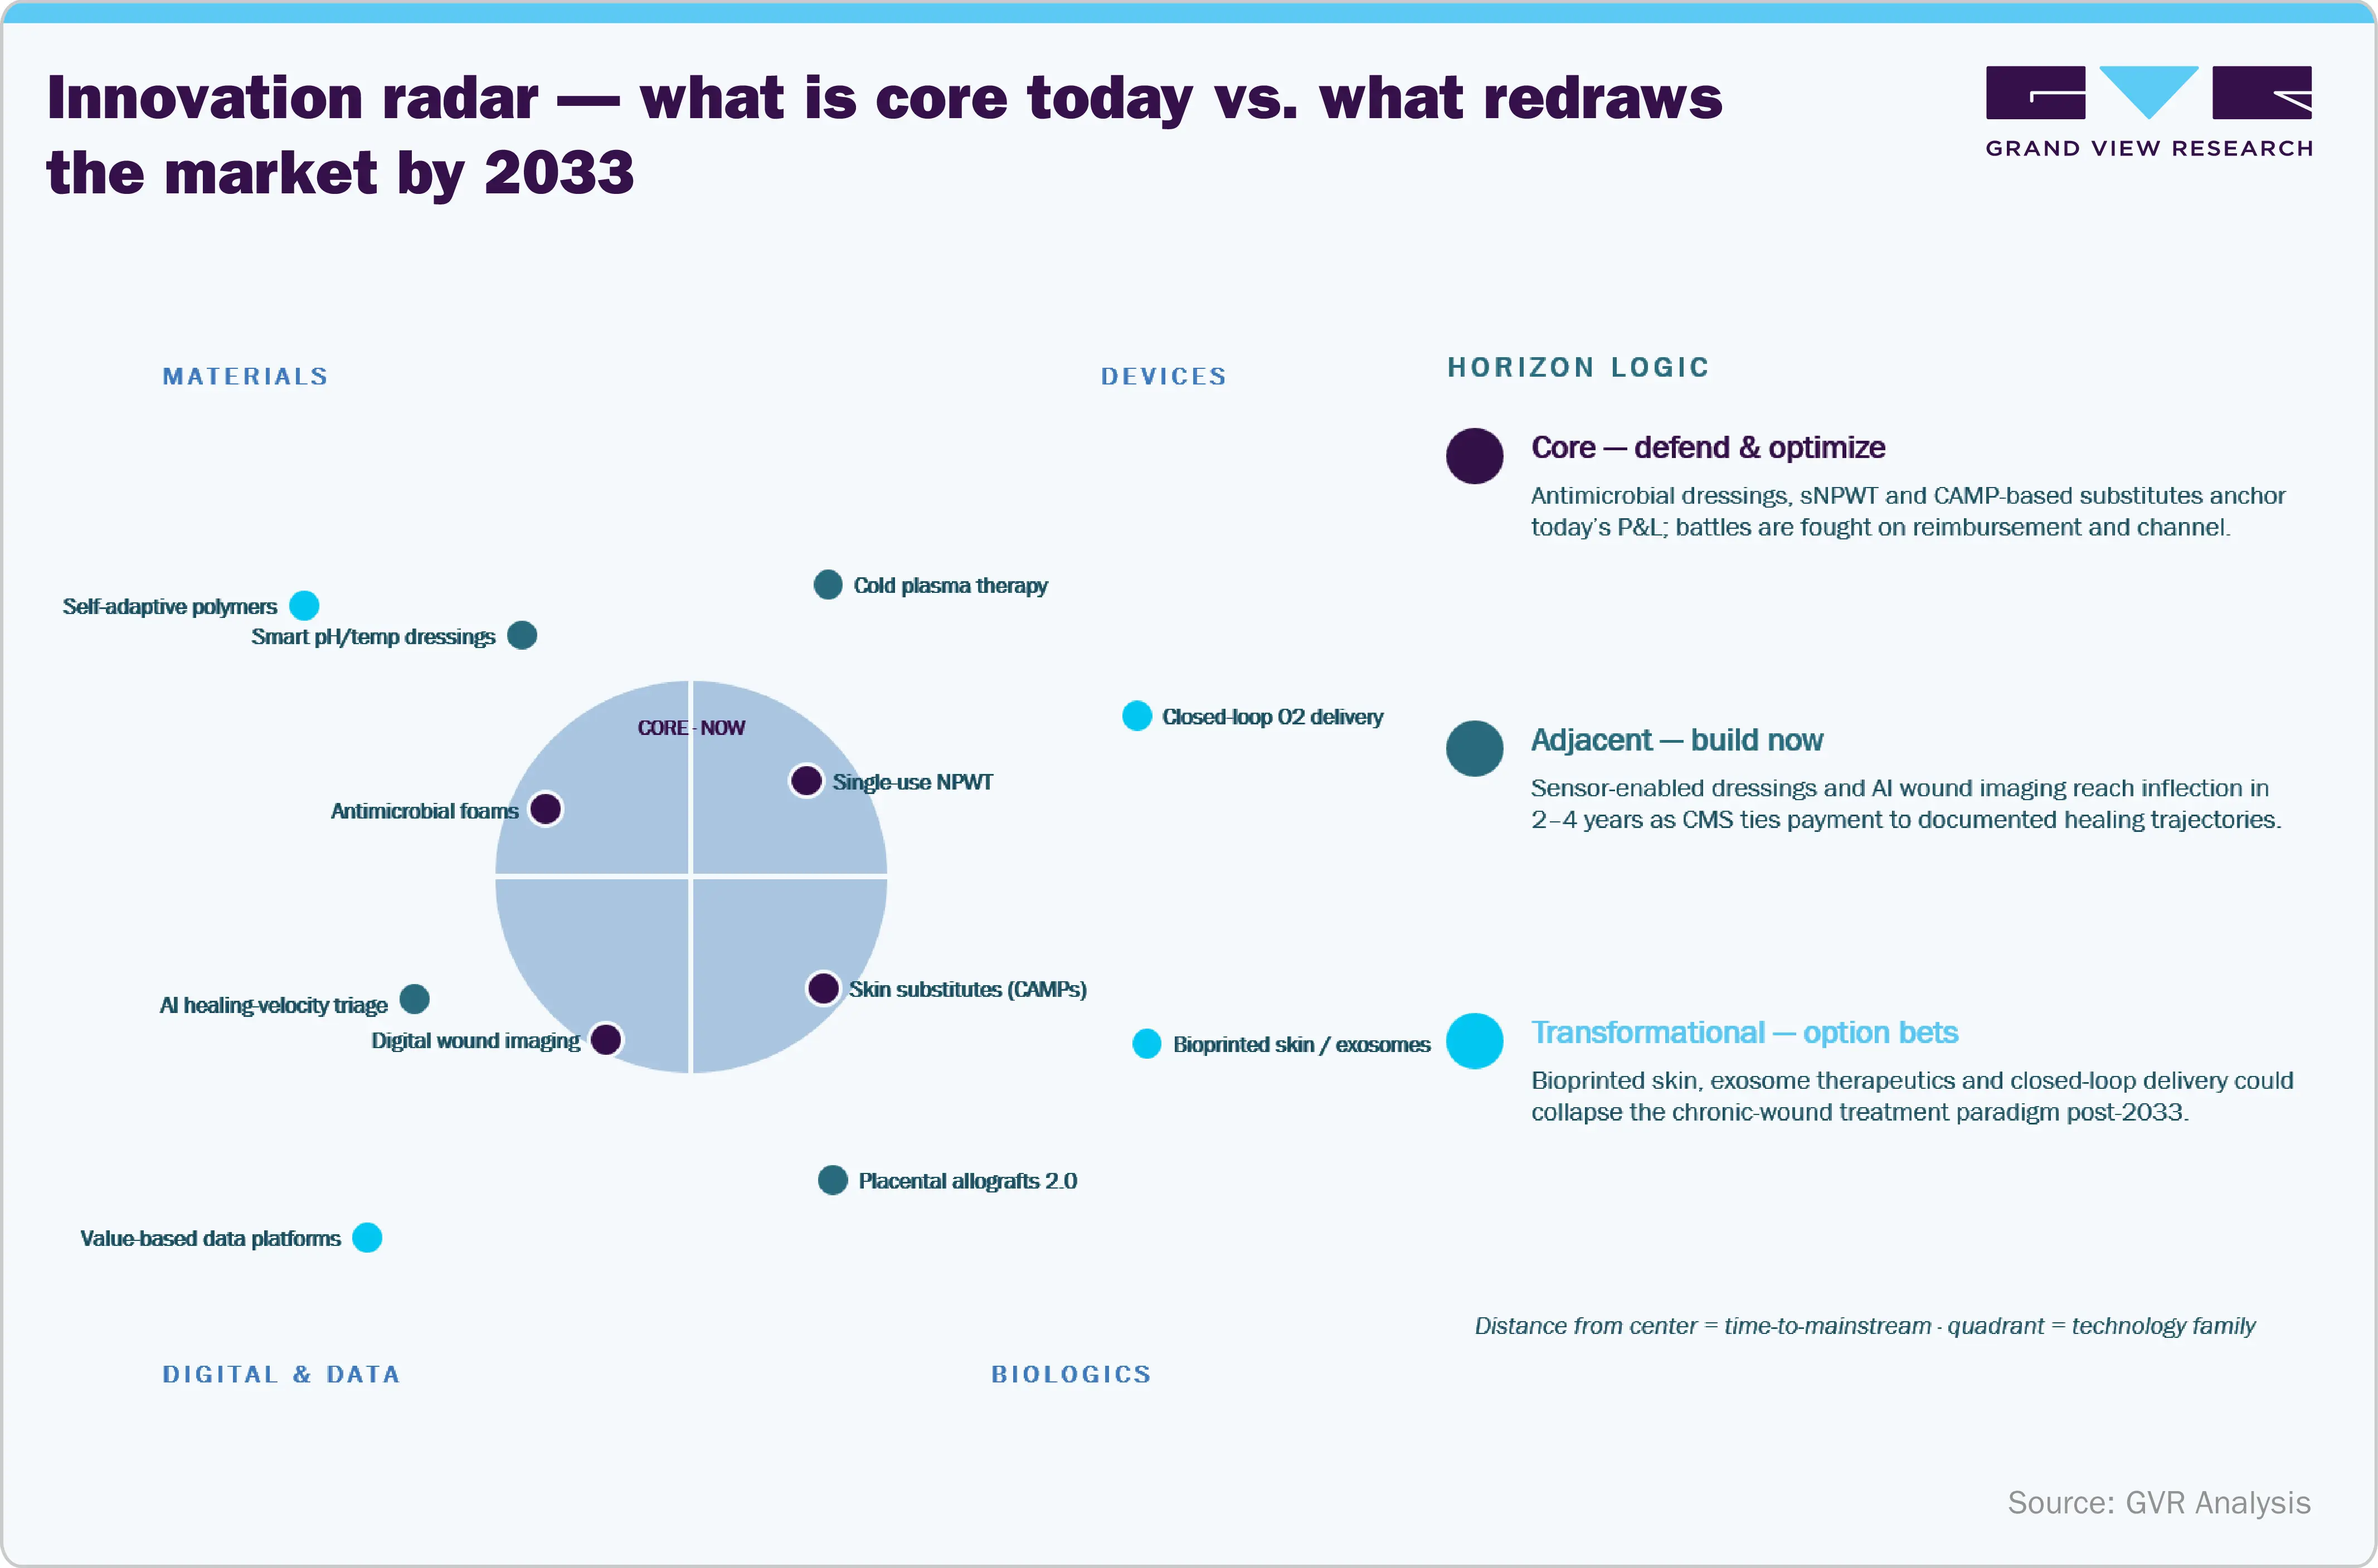
Technological innovation is structurally reshaping the market by improving clinical efficiency, standardizing care pathways, and expanding treatment beyond acute settings. Advances in therapeutic devices, digital platforms, and data-enabled tools are transforming the assessment, treatment, and monitoring of wounds across hospitals, outpatient clinics, and home care settings. One of the most established innovations is negative pressure wound therapy (NPWT), which applies controlled sub-atmospheric pressure to wounds to remove exudate and stimulate granulation, thereby improving healing rates and reducing the length of stay compared with standard care. A 2025 randomized study in The Lancet reported that NPWT significantly shortened time to wound healing compared with usual wound management in complex surgical wounds, demonstrating real-world clinical benefit.
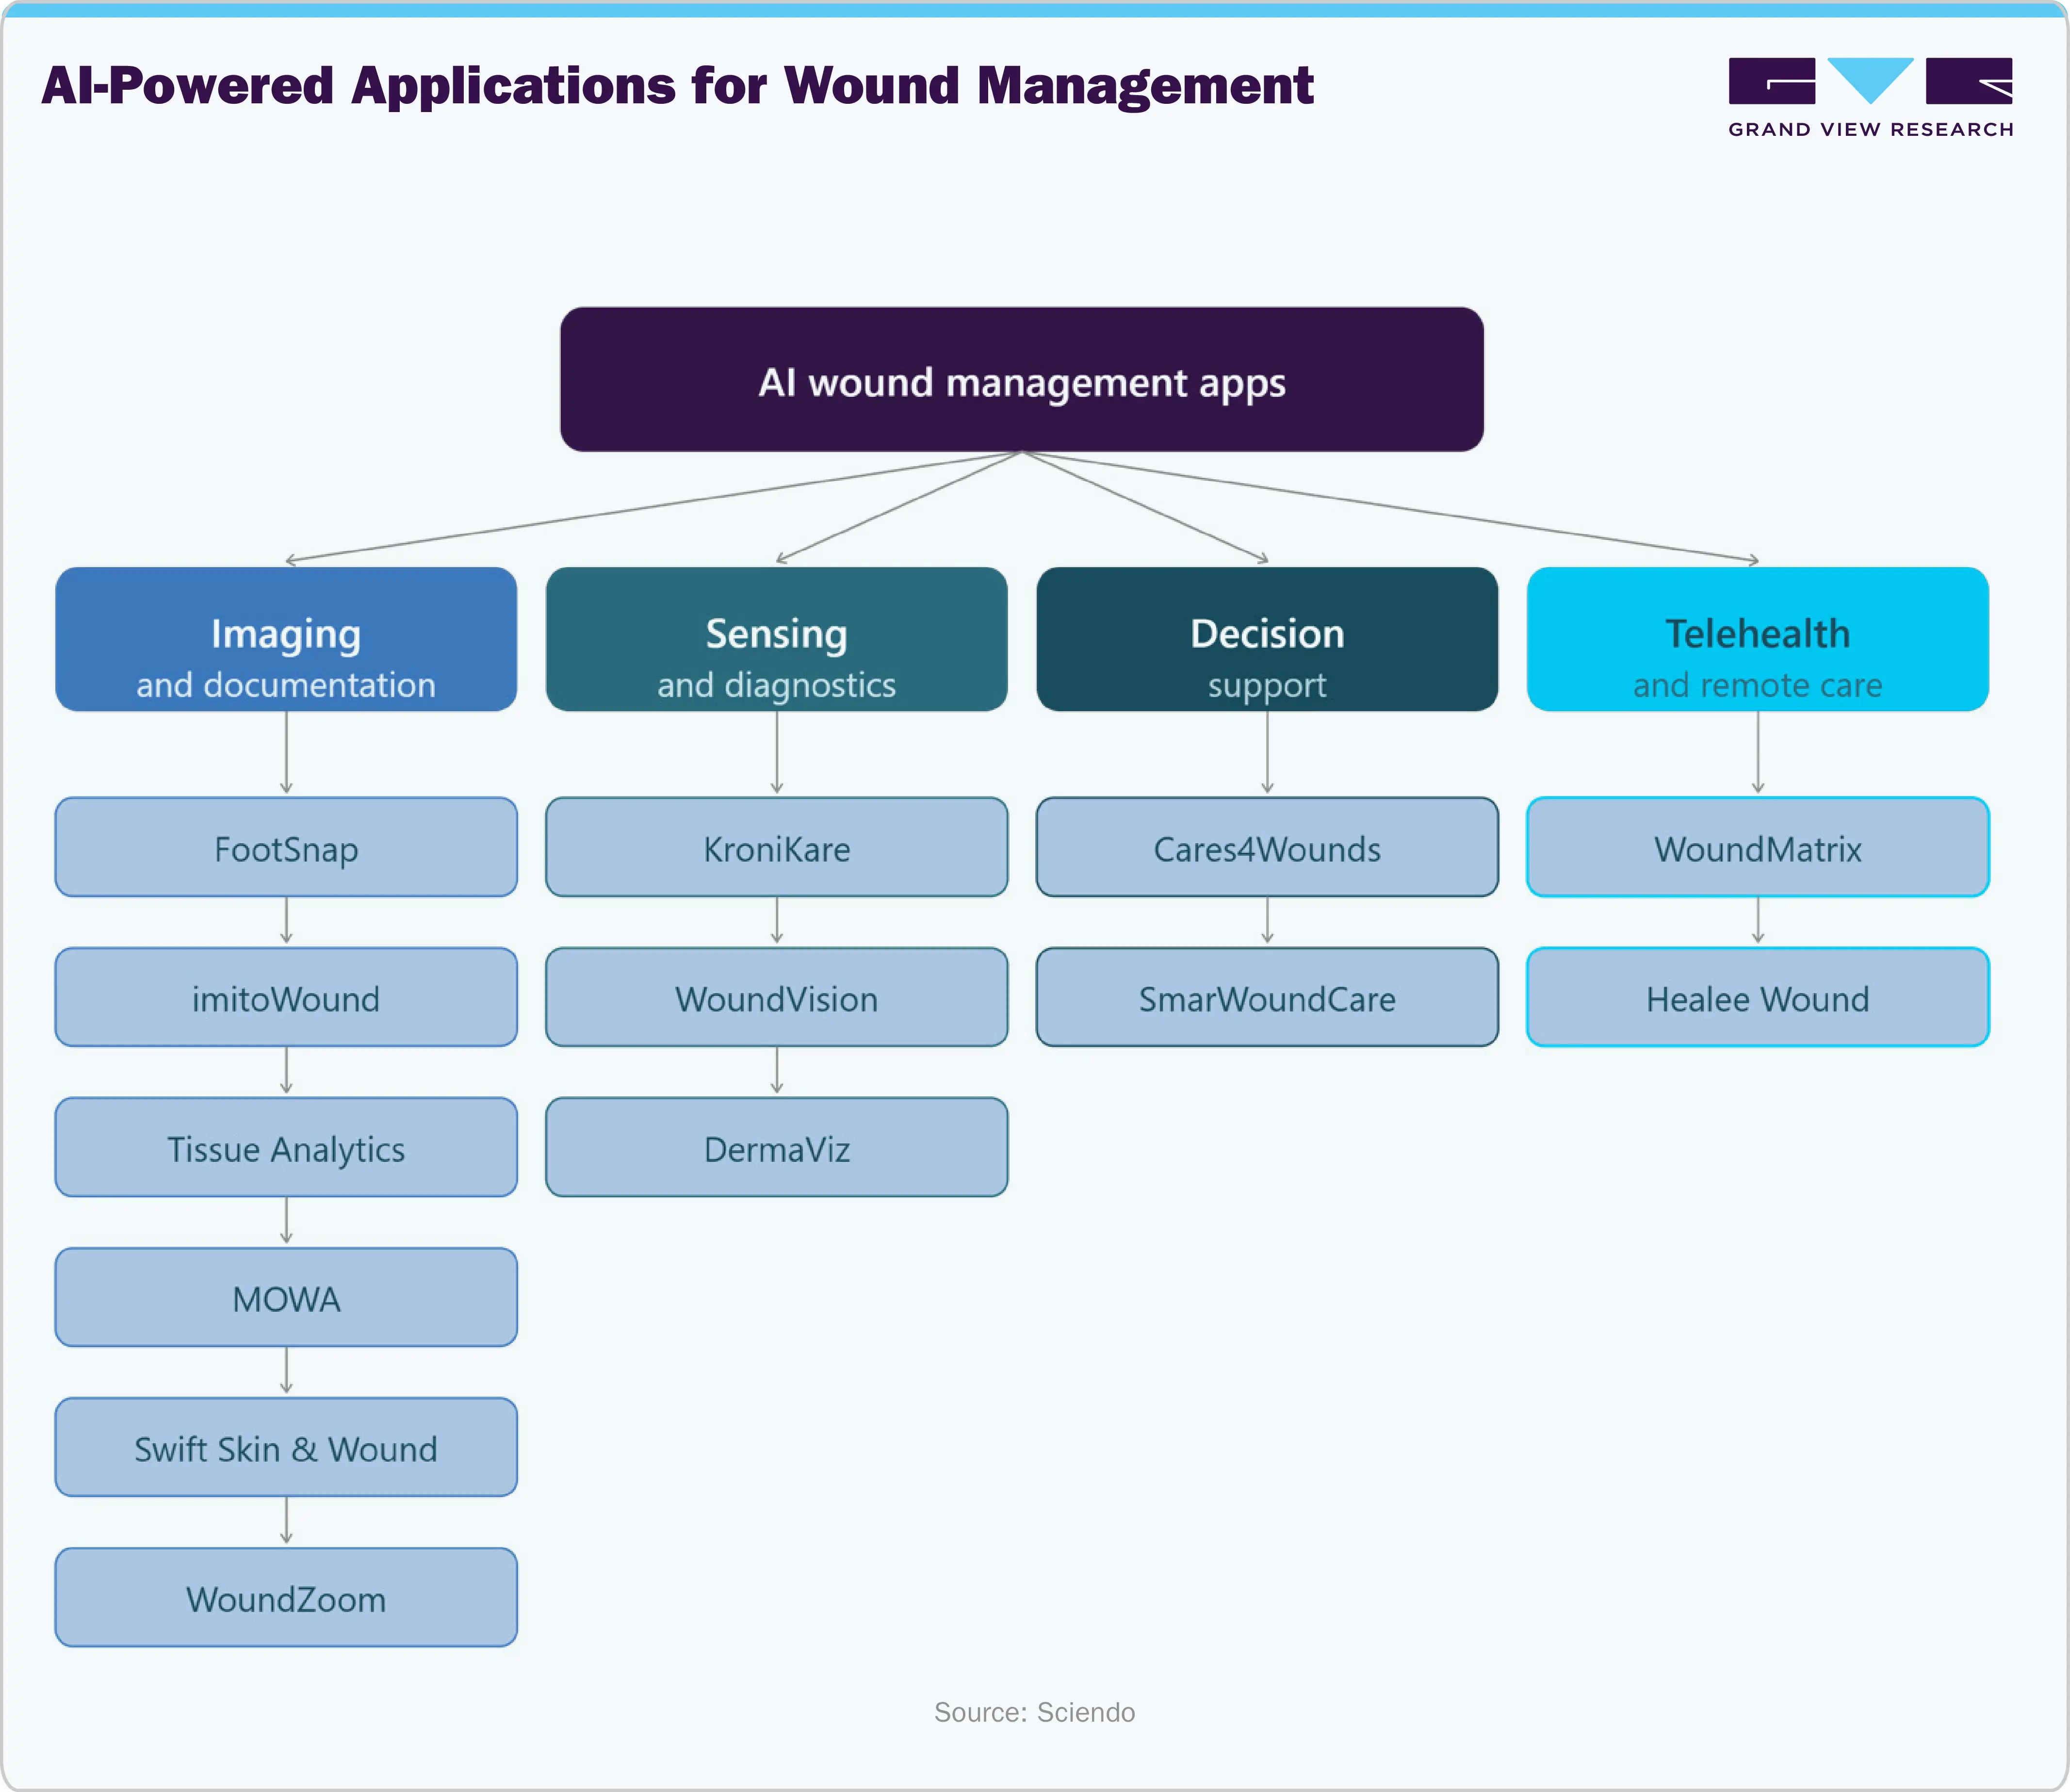
Beyond NPWT, digital health and telemedicine are increasingly integrated into wound care delivery. A 2025 peer-reviewed study published in JMIR Nursing reported that digitally enabled wound care programs supported hospital-level monitoring in home settings, reduced the number of in-person clinical visits, and lowered operational burden, while maintaining or improving wound-healing outcomes. The findings highlight the role of digital platforms in enabling decentralized care models without compromising clinical results.
 To learn more about this report, Download Free Sample Report
AI-assisted and remote monitoring technologies are also advancing, enabling automated wound assessment and predictive analytics to support clinical decision-making, as highlighted in recent consensus discussions on AI’s role in wound assessment and tailored care. Emerging innovations such as continuous monitoring sensors, smart dressings, and portable NPWT devices further extend care in outpatient and home settings. These technologies enable clinicians to intervene earlier, standardize documentation, and reduce costly complications, thereby directly increasing the utilization of advanced wound care products across various care settings.
 To learn more about this report, Download Free Sample Report
Patent activity in the wound care market has grown consistently over the past decade, reflecting increasing investment in advanced wound management technologies. Recent filings indicate a strong shift toward biologics and skin substitutes, smart sensor-enabled dressings, AI-powered digital wound assessment, antimicrobial materials, and next-generation negative pressure wound therapy (NPWT), highlighting the industry's focus on personalized, connected, and clinically effective wound care solutions.
 To learn more about this report, Download Free Sample Report
Regulatory and Reimbursement Trends
The wound care market is undergoing a major regulatory and reimbursement transition as CMS intensifies efforts to address the sharp increase in Medicare spending on advanced wound therapies, particularly skin substitutes and cellular/tissue-based products (CTPs). In 2026, CMS replaced separate Average Sales Price (ASP)-based reimbursement with an "incident-to" supply payment methodology under the Medicare Physician Fee Schedule, a move expected to reduce gross Medicare fee-for-service spending on skin substitute services by nearly 90% while promoting payment accuracy and discouraging inappropriate utilization. Simultaneously, CMS withdrew the proposed Final Local Coverage Determinations (LCDs) for certain skin substitutes, while supporting that future coverage decisions will increasingly depend on strong clinical evidence, stringent documentation, demonstrated medical necessity, and appropriate patient selection. These developments reflect a broader shift toward value-based wound care reimbursement, creating a more challenging environment for high-cost products with limited evidence, while favoring manufacturers and providers that can demonstrate superior healing outcomes, real-world effectiveness, and cost-efficiency across both chronic and acute wound populations.
Market Dynamics
The wound care market is experiencing significant growth driven by the rising prevalence of chronic wounds, increasing surgical procedures, and an aging population that is more susceptible to delayed wound healing. Continuous innovation in advanced wound care products, including bioactive dressings, negative pressure wound therapy, and tissue-engineered skin substitutes, is improving clinical outcomes and expanding treatment options. High treatment costs and reimbursement limitations in certain regions remain key challenges. However, increasing investments in home healthcare, digital wound monitoring, and emerging healthcare infrastructure are creating significant opportunities for market expansion.
The rising prevalence of chronic wounds is a major driver of the wound care market, fueled by the increasing incidence of diabetes, obesity, peripheral artery disease, and an aging population. Conditions such as diabetic foot ulcers, venous leg ulcers, and pressure injuries require prolonged treatment, frequent dressing changes, and advanced wound management solutions to prevent infections and promote healing. As the global burden of chronic wounds continues to grow, healthcare providers are adopting advanced wound dressings, negative pressure wound therapy (NPWT), biologics, and tissue-engineered products, driving sustained demand across the market.
According to the European Wound Management Association (EWMA),
- Chronic wounds affect approximately 2.2 individuals per 1,000 population, highlighting a significant healthcare burden across Europe.
- The point prevalence of venous leg ulcers is estimated at 0.33%–1.01% of the population, contributing substantially to the global burden of chronic wound management.
Limited reimbursement coverage remains a key restraint in the wound care market, particularly for advanced therapies such as skin substitutes, cellular and tissue-based products (CTPs), and negative pressure wound therapy (NPWT). Many public and private payers restrict coverage to specific wound types, clinical indications, or patients who have failed standard care, while requiring extensive documentation and prior authorization. These limitations delay treatment, reduce patient access, and discourage the adoption of high-cost advanced wound care products.
In 2026, CMS implemented a major reimbursement reform, replacing the Average Sales Price (ASP)-based model for most skin substitutes with a single national payment rate to improve payment accuracy and reduce unnecessary Medicare spending. While the policy promotes value-based care, it has lowered reimbursement for many advanced wound care products, creating financial pressure for providers and manufacturers and potentially limiting the use of premium wound care technologies.
The growing demand for advanced biologics and regenerative wound care presents a significant opportunity in the wound care market, driven by the increasing prevalence of chronic wounds and the need for faster, more effective healing. Products such as skin substitutes, growth factors, amniotic membranes, platelet-rich plasma (PRP), and bioengineered tissues are gaining wider adoption due to their ability to promote tissue regeneration and reduce healing time, particularly for diabetic foot ulcers, venous leg ulcers, and pressure ulcers.
Ongoing product innovation, expanding clinical evidence, and increasing regulatory approvals are further accelerating market growth. As healthcare systems prioritize therapies that improve patient outcomes, reduce complications, and lower long-term treatment costs, regenerative wound care solutions are expected to create substantial growth opportunities for manufacturers in both developed and emerging markets.
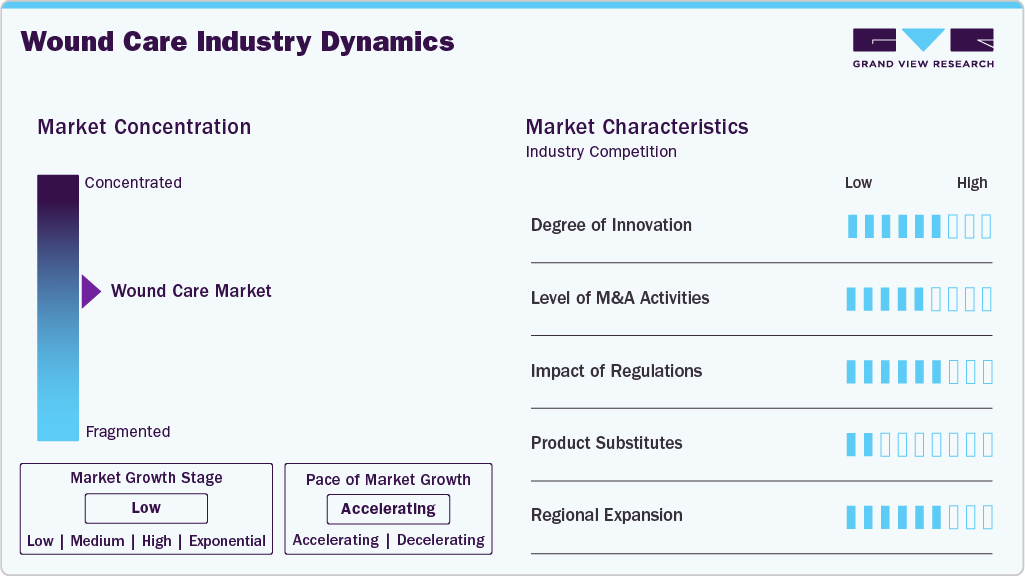
Market Concentration & Characteristics
The market growth stage is low, and the pace of growth is accelerating. The wound care industry is characterized by the rising number of surgical procedures and accidental injuries, as well as the increasing prevalence of chronic wounds.
The wound care market exhibits a high degree of innovation, supported by sustained investment and the development of new products. In March 2025, Convatec received regulatory approval for ConvaNiox, a nitric-oxide-generating dressing for diabetic foot ulcers, introducing a new multimodal treatment approach. Such developments highlight continuous innovation focused on clinical outcomes, materials advancement, and scalable wound care solutions.
 To learn more about this report, Download Free Sample Report
Regulations have a significant impact on the global market for advanced dressings, surgical wound care, traditional products, and wound therapy devices. Products used for chronic and acute wounds are regulated as medical devices, with safety, biocompatibility, and performance requirements set by authorities such as the U.S. Food and Drug Administration. In the U.S., reimbursement and utilization are governed by the Centers for Medicare & Medicaid Services, which sets coverage and documentation criteria for advanced wound therapies.
The wound care industry has experienced moderate to high levels of M&A activity, primarily focused on expanding advanced therapy portfolios and regenerative solutions. In 2025, Solventum announced the acquisition of Acera Surgical, strengthening its position in synthetic tissue matrices for complex wounds. Such transactions reflect strategic moves toward biologicssurgical dressings, matrices, and differentiated therapies supported by clinical evidence.
Product substitutes include systemic antibiotics and medical management, surgical interventions such as debridement or skin grafting, preventive measures like offloading footwear and compression therapy, home remedies in low-resource settings, and clinical observation for minor wounds. These alternatives may reduce short-term use of wound care products but often provide limited control over healing outcomes compared with dedicated wound care solutions.
Regional expansion is driven by investments in localized manufacturing and regulatory approvals that strengthen supply resilience and market access. In November 2025, Mölnlycke established its first wound care manufacturing site in China, marking a strategic expansion of its global production footprint. The new facility in Changshu spans 10,000 m² and aims to begin production of wound care products by late 2026 or early 2027, enhancing supply chain resilience and proximity to key customers. This investment strengthens Mölnlycke’s position in Asia’s wound care industry and aligns with growing regional demand for locally manufactured healthcare solutions.
Analyst Perspective
The wound care market is expected to witness sustained growth over the coming years, supported by the increasing burden of chronic wounds, a rapidly aging population, and the rising prevalence of diabetes and vascular diseases worldwide. The market is shifting significantly from traditional dressings toward advanced wound care solutions, including antimicrobial dressings, negative-pressure wound therapy (NPWT), biologics, and regenerative products, as healthcare providers increasingly focus on improving healing outcomes and reducing hospitalization rates.
Future market expansion will be driven by continuous technological innovation, expanding home healthcare services, AI-enabled wound assessment, and the growing adoption of regenerative wound care therapies. However, reimbursement constraints, pricing pressures, and the high cost of advanced products are expected to remain key challenges. Manufacturers that emphasize clinical evidence, product innovation, cost-effectiveness, and digital integration will be well-positioned to capture emerging growth opportunities in the evolving wound care landscape.
Product Insights
The advanced wound dressings segment dominated the wound care market with the largest share of 35.2% in 2025, and is expected to grow at the fastest CAGR during the forecast period. Advanced wound dressings are primarily used in the management of chronic and non-healing wounds, including diabetic foot ulcers. As a result, the increasing incidence of chronic wounds is directly supporting demand for advanced wound care products.
Published in March 2024 by Bonvadis, an analysis on the global status of diabetic foot ulcers reports that approximately 6.3% of people with diabetes worldwide experience DFUs, with higher prevalence observed in regions such as North America. DFUs are associated with elevated infection risk and account for a significant proportion of non-traumatic lower-limb amputations. These findings highlight the growing burden of chronic wounds and support the continued use of advanced wound dressings as diabetes prevalence increases globally.
The surgical wound care segment is expected to grow at a considerable pace during the forecast period, driven by the rising surgical volumes across hospitals and ambulatory care settings. Growth is linked to increasing prevalence of chronic diseases, aging populations, and higher incidence of trauma and emergency procedures, which drive demand for sutures, staples, tissue adhesives, sealants, and anti-infective dressings. According to the World Health Organization, more than 300 million surgical procedures are performed globally each year, a figure that continues to rise as access to surgical care expands, reinforcing sustained demand for surgical wound care products.
Application Insights
The chronic wounds segment led the wound care industry, accounting for the largest revenue share of 59.8% in 2025, driven by the growing geriatric population and the rising prevalence of long-term conditions such as diabetic foot ulcers, venous pressure ulcers, and other non-healing wounds. This trend is reflected in an epidemiological study published in September 2024 in Cureus, titled “Epidemiological Profile of Chronic Wounds in an Indian Population: A Community-Based Cross-Sectional Observational Study.” The cross-sectional study screened 10,003 individuals in Varanasi district, Uttar Pradesh, India, and reported an overall prevalence of chronic wounds of 1.89 per 1,000 people, with a higher prevalence in rural areas (2.64 per 1,000) than in urban areas (1.57 per 1,000). Among the 19 individuals identified with chronic wounds, diabetic foot ulcers, and neglected or uncared trauma each accounted for 36.8% of cases. These findings highlight the persistent burden of chronic wounds and the need for continued wound management and treatment, particularly for diabetic foot ulcers and trauma-related wounds.
The acute wound segment is expected to grow at a significant CAGR during the forecast period, driven by rising volumes of surgical procedures, trauma cases, and burn injuries across hospital and ambulatory care settings. Increasing access to surgical care, higher rates of emergency interventions, and greater emphasis on timely wound closure and infection prevention are supporting demand for acute wound management products, including surgical dressings, sutures, staples, and anti-infective solutions.
End Use Insights
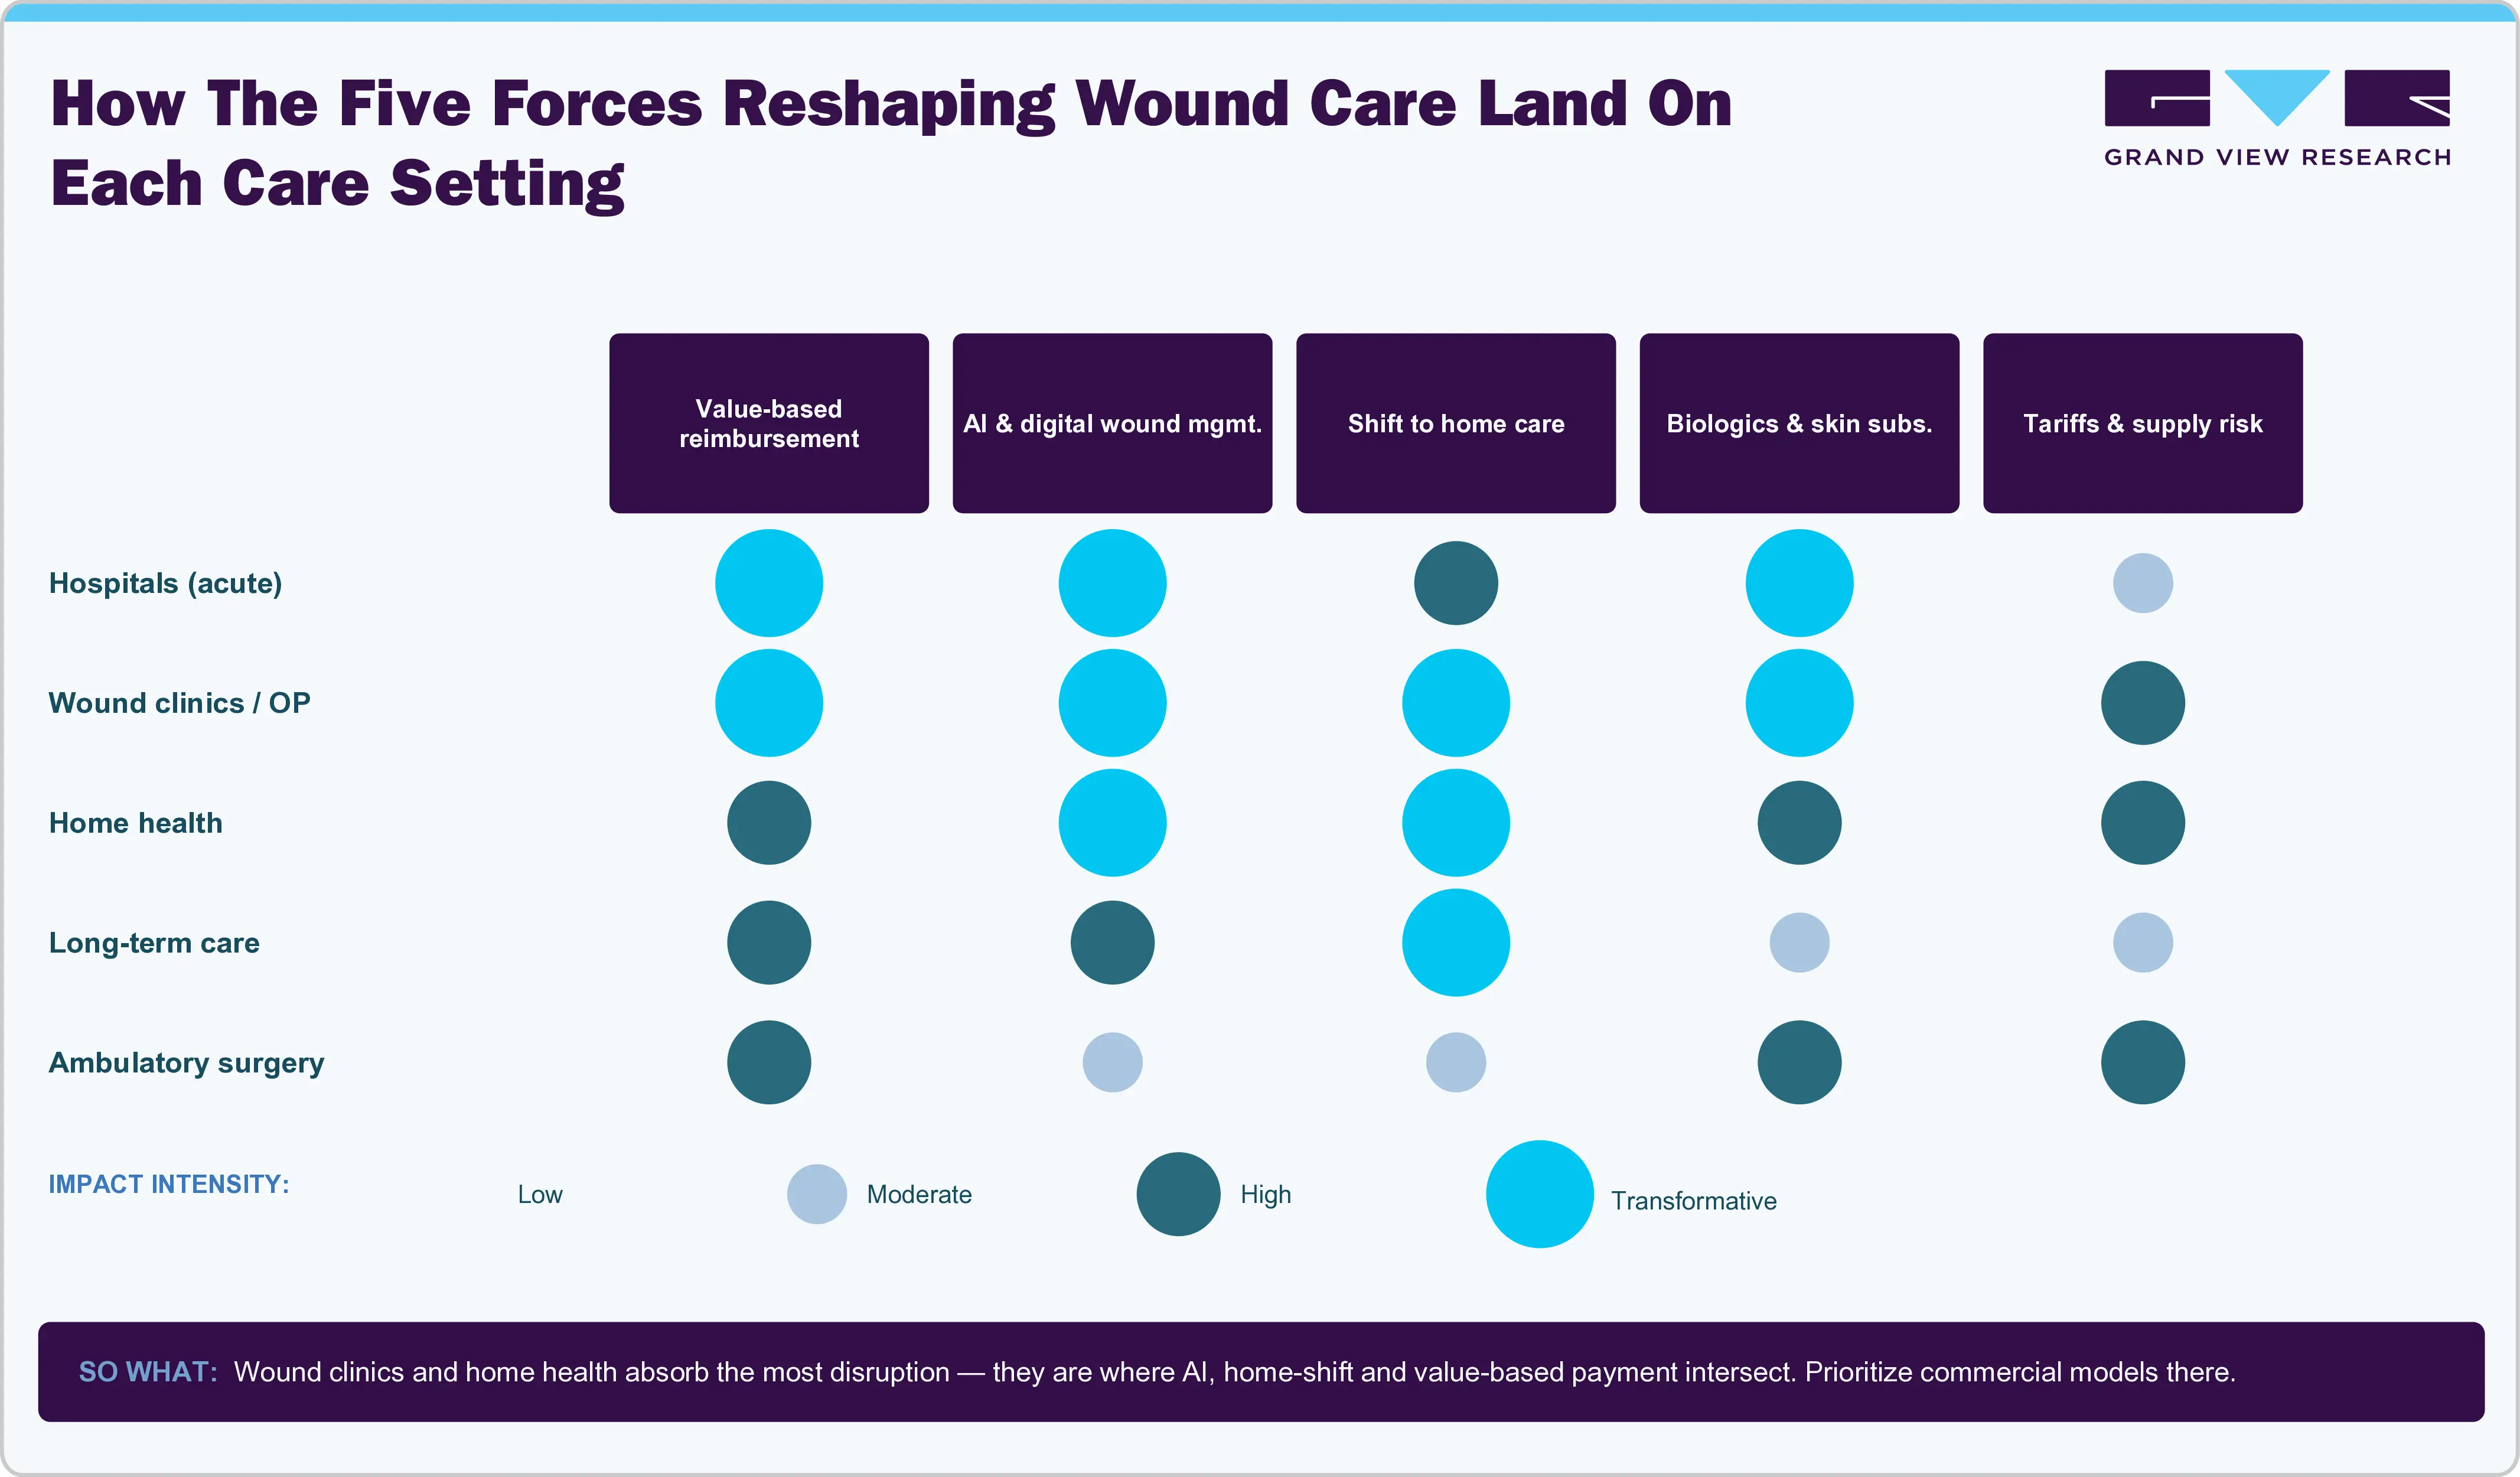
The hospital segment dominated the wound care market, accounting for the largest share of 36.4% in 2025. This growth can be attributed to a global rise in surgical procedures resulting from an inactive lifestyle and an increase in bariatric surgeries, which require the use of wound care products to prevent surgical site infections. Furthermore, surgical wound care dressings and NPWT are especially suitable for hospital use and are not feasible for home care. In addition, hospitals are significant buyers of wound care products, often holding long-term contracts with suppliers. Hence, owing to the aforementioned factors, the segment is anticipated to grow during the forecast period.
 To learn more about this report, Download Free Sample Report
The home healthcare segment is anticipated to grow at a significant CAGR during the forecast period, driven by the increasing shift of wound management from hospitals to home settings. Factors such as the rising prevalence of chronic wounds, an aging population, shorter hospital stays, and increased adoption of home health services are driving demand for wound care products that enable safe and effective treatment outside acute care facilities.
Mode of Purchase Insights
The prescribed segment dominated the wound care market with a share of 70.6% in 2025, and is expected to grow at the fastest CAGR over the forecast period. The prescribed wound care products depend on the type of product and the severity of the wound. For mild to moderate wounds, over-the-counter wound care products, such as bandages, gauze, and antiseptic creams, can be purchased at pharmacies, drugstores, or online retailers. For more severe wounds, prescription wound care products such as wound dressings, wound cleansers, and topical antibiotics may be required. These products can only be obtained with a prescription from a healthcare provider and are available for purchase at a pharmacy.
The non-prescribed (OTC) segment is expected to witness considerable growth over the forecast period, due to an increasing number of acute wounds and injuries. Moreover, industry players are also launching non-prescribed wound care products. For instance, in April 2024, Vomaris made available a bioelectric bandage, PowerHeal, which was cleared by the FDA for over-the-counter use in wound management. Such approvals and launches for non-prescribed wound care products are anticipated to support the segment growth.
Distribution Channel Insights
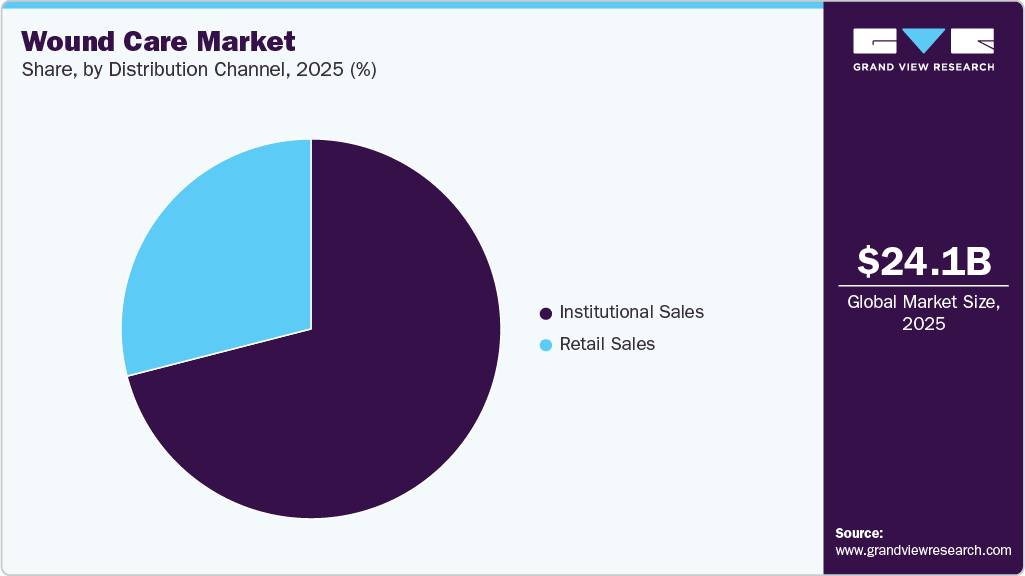
The institutional sales segment dominated the wound care industry, accounting for a 70.8% share in 2025. Manufacturers usually sell products directly to healthcare providers, such as hospitals and clinics, or to patients through direct-to-consumer marketing. This strategy provides manufacturers with greater control over distribution and helps foster stronger customer relationships. Institutional sales primarily involve direct distributors and manufacturers, with hospitals, wound care centers, clinics, nursing homes, long-term care facilities, diagnostic labs, and birth centers typically having long-term contracts with them. Key players are using these long-term agreements to expand their market reach and strengthen their position.
 To learn more about this report, Download Free Sample Report
The retail sales segment is expected to grow at the fastest CAGR during the forecast period. The segment encompasses retail pharmacies, e-commerce platforms, and other outlets. Pharmacies offer numerous benefits to customers, such as a wide range of delivery options and excellent service. Customers typically purchase both prescription and over-the-counter wound care products, including dressings, ointments, and bandages, from retail pharmacies and specialty stores, which may also provide wound care advice. The e-commerce demand is anticipated to grow due to the convenience, affordability, and accessibility of online stores and mail-order services. The growing availability of wound care products through e-commerce, including the rise of eHealth services, is expected to further boost segment growth.
Regional Insights
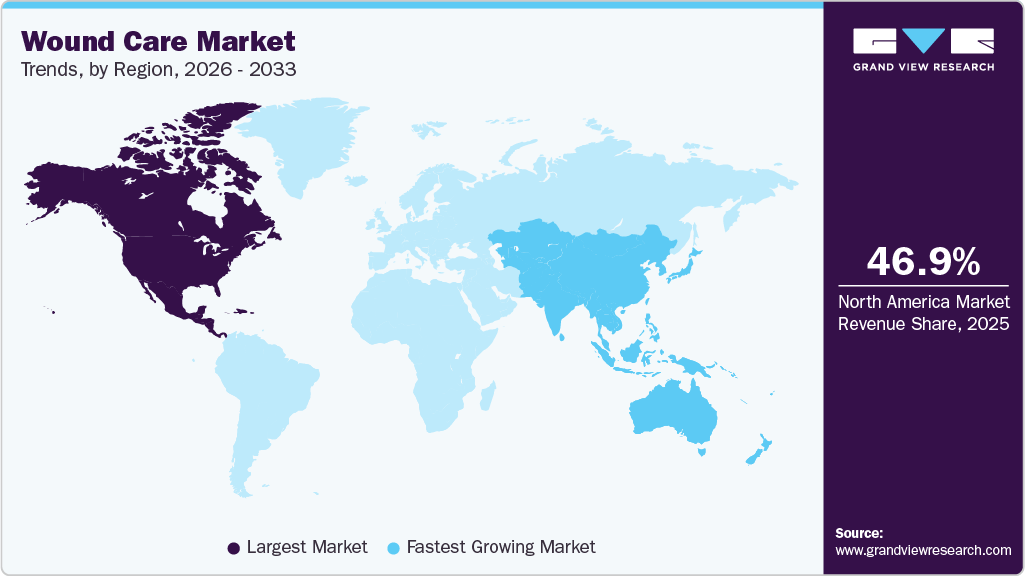
The North America wound care market held the largest revenue share, exceeding 46.9% in 2025. The key growth drivers for the region include a large population base and an increasing patient pool, particularly in the U.S. In addition, the growing geriatric population, which is more susceptible to wounds, will further drive demand for wound care products. According to Statistics Canada, the proportion of individuals aged 65 and older in the total population is projected to grow from 18.9% in 2023 to between 21.9% (slow-aging scenario) and 32.3% (fast-aging scenario) by 2073.
 To learn more about this report, Download Free Sample Report
U.S. Wound Care Market Trends
The U.S. wound care industry held the largest share of North America in 2025, supported by the strong presence of established manufacturers and continued product innovation. For instance, in July 2025, Convatec secured regulatory clearance in the U.S., the UK, the European Union, and Australia for Aquacel ConvaFiber, a next-generation Hydrofiber wound dressing indicated for venous leg ulcers, diabetic foot ulcers, pressure injuries, surgical wounds, and partial-thickness burns. The product enhances Convatec’s Hydrofiber technology through improved absorbency and wound contact and is planned for market availability from 2026, reinforcing the U.S. market’s leadership in advanced wound care adoption.
Europe Wound Care Market Trends
The Europe wound care industry is projected to grow steadily during the forecast period, supported by increasing surgical procedure volumes, greater awareness of structured wound management, and stronger industry–policy collaboration. Ongoing investment continues to support innovation and the adoption of advanced wound care therapies. In December 2025, Mölnlycke was elected to a leadership role within the MedTech Europe Wound Care Sector Working Group, with a mandate to raise awareness of chronic wound challenges, engage policymakers, and promote aligned care pathways and education across European healthcare systems. Collectively, rising clinical demand and coordinated policy engagement are reinforcing market growth outlook across Europe.
The UK wound care market is expected to grow at a moderate pace over the forecast period, driven by an aging population, the rising prevalence of chronic conditions such as diabetes, and the continued adoption of advanced wound care technologies. Increased healthcare spending, national focus on improving wound outcomes, and greater awareness of evidence-based treatments are contributing to steady demand for innovative solutions. Reflecting this trend, in September 2025, AVITA Medical received CE Mark approval under the EU Medical Device Regulation for its RECELL GO system, enabling commercialization in the UK and other European markets. The point-of-care technology uses a small sample of a patient’s own skin to generate Spray-On Skin Cells for use in burns and traumatic or surgical wounds, expanding access to advanced acute wound treatments within the UK healthcare system.
The wound care market in France is projected to grow during the forecast period, driven by the increasing prevalence of chronic conditions, the introduction of innovative products, and significant healthcare spending. For instance, in January 2022, Accel-Heal, a wearable electrical stimulation device for wound management, was launched in France. This single-use, easy-to-use device helps reduce pain and accelerate the healing of chronic wounds.
The German wound care market is experiencing steady growth due to factors such as the rising prevalence of chronic diseases, an aging population, and advancements in wound care technologies. Rising healthcare spending and the demand for advanced wound care solutions further support market growth.
Asia Pacific Wound Care Market Trends
The wound care industry in the Asia Pacific is expected to register the fastest CAGR during the forecast period, driven by significant growth. Key factors include the rising demand for wound care products in Southeast Asian countries such as Indonesia, Malaysia, and Singapore. In addition, the region's increasing healthcare expenditure is expected to further drive market growth. Moreover, the large patient population in countries such as India, China, and Japan can further propel the market growth over the forecast period.
The wound care market in China is expected to grow steadily throughout the forecast period, driven by increasing demand for solutions to address the rising incidence of chronic wounds, such as diabetic foot ulcers. According to the study published by Frontiers in August 2024, the incidence of DFUs ranges from 17.03% to 42.84% (19–22) in China, which is significantly higher than in other nations. Furthermore, the same study also reported a high incidence of amputation among Chinese individuals with DFUs. Thus, the high incidence of DFUs and amputations is anticipated to drive the demand for wound management products.
The wound care market in Japan is expected to experience substantial growth during the forecast period. This growth is driven by several key factors, including the rising number of surgical procedures across the country, which increases the demand for effective wound care solutions. In addition, Japan's rapidly aging population is a significant driver, as elderly individuals are more prone to chronic wounds, pressure ulcers, and surgical complications.
Middle East and Africa Wound Care Market Trends
The MEA wound care industry is expected to witness significant growth in the coming years, driven by rising awareness about wound management, the increasing prevalence of chronic diseases, and growing healthcare expenditure. For instance, the UAE Government reserves a substantial share of the federal budget for the healthcare sector every year. According to federal budget data published in June 2024, approximately USD 1.33 billion was allocated for 2023, increasing to USD 1.260 billion in 2024.
The Saudi Arabia wound care market is anticipated to grow over the forecast period. The growth of the country's market is driven by the rising prevalence of chronic conditions, such as diabetes, an aging population, and growing healthcare investments. Government initiatives to improve healthcare infrastructure, along with increasing awareness of advanced wound care technologies, are further supporting market growth.
The wound care market in Kuwait is expected to grow over the forecast period, driven by the increasing incidence of chronic diseases, particularly diabetes, which leads to a rise in diabetic ulcers and other wound-related conditions. Moreover, growing healthcare expenditure propels the country's market growth.
 To learn more about this report, Download Free Sample Report
The increasing prevalence of chronic wounds such as pressure ulcers is anticipated to drive the demand for wound care products. The prevalence of pressure ulcers in China is estimated to increase by around 22.95% from 2024 to 2030. Wound management products, such as superabsorbent dressings and antibacterial dressings containing silver, are used to treat pressure ulcers. Several major industry players, such as Convatec Group Plc and Mölnlycke Health Care AB, offer dressings for treating pressure ulcers under various brands, such as ConvaMax and Mepilex. Thus, the increasing prevalence of pressure ulcers in numerous countries such as China, India, and South Korea, among others, is anticipated to support the market growth over the forecast period.
Growing Demand for Negative Pressure Wound Therapy (NPWT) Systems
The demand for NPWT is anticipated to increase significantly in the coming years due to the rising incidence of chronic and acute wounds and the growing number of NPWT system launches. Several major companies in the wound care industry have experienced revenue growth driven by rising demand for NPWT systems.
-
For instance, Smith+Nephew reported a growth of 17.0% in the revenue of its Advanced Wound Devices segment in 2023. This growth was driven by both the RENASYS NPWT System and the single-use PICO NPWT System
-
Furthermore, the company also reported continuous demand for its NPWT portfolio in the second quarter (Q2) of 2024. As per the Second Quarter and First Half 2024 Results published by Smith+Nephew, Advanced Wound Devices revenue increased by 8.0% (6.6% reported) due to the strong growth from the single-use PICO NPWT System, VERSAJET Hydrosurgery System, and LEAF Patient Monitoring System
“We are pleased with our 2023 performance, led by our Negative Pressure Wound Therapy portfolio, where we focused on accelerating growth, delivering on the 12-Point Plan.” Rohit Kashyap, President, Advanced Wound Management & Global Commercial Operations, Smith+Nephew.
Key Wound Care Company Insights
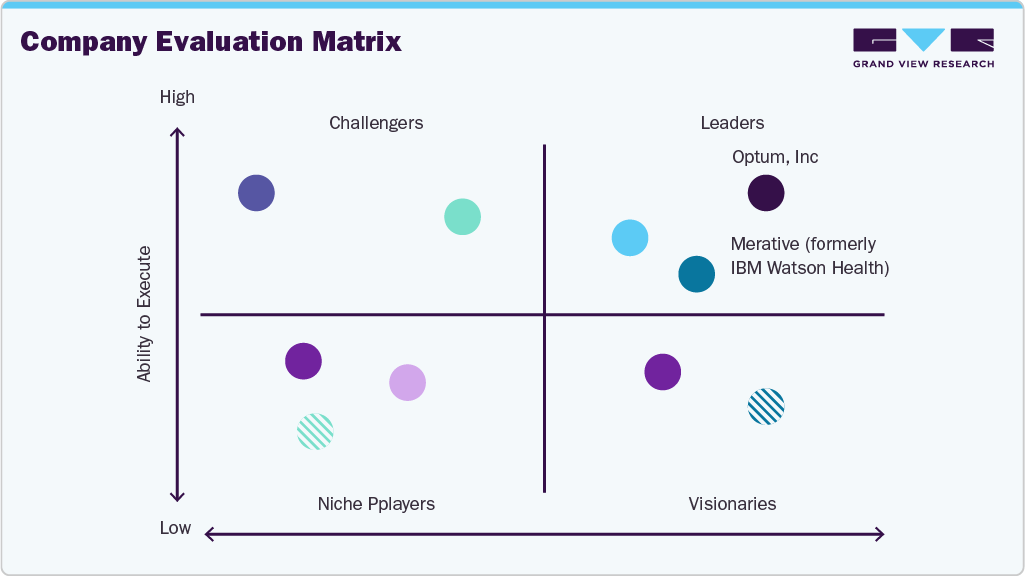
The major players in the market are expanding their portfolios of wound care devices, such as NPWT, to gain a competitive advantage in the coming years. The industry players are also launching antimicrobial wound dressings incorporating silver to meet the growing demand for silver dressings.
Key Wound Care Companies
The following key companies have been profiled for this study on the wound care market.
-
Smith+Nephew
-
Convatec Group PLC
-
Mölnlycke Health Care AB
-
Baxter
-
DeRoyal Industries, Inc.
-
Coloplast Corp
-
Medtronic
-
3M
-
INTEGRA LIFESCIENCES
-
Medline Industries, LP
-
Johnson & Johnson Services, Inc.
-
B. Braun SE
-
MIMEDX Group, Inc.
-
Cardinal Health
-
Organogenesis Inc.
-
Advanced Medical Solutions Group plc
-
Plastod SpA
-
AVERY DENNISON CORPORATION
-
Lohmann Rauscher GmbH & Co. KG
-
Nanordica Medical
-
MBP – MEDICAL BIOMATERIAL PRODUCTS GmbH
-
URGO MEDICAL
 To learn more about this report, Download Free Sample Report
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (3M, Coloplast Corp., Medline, Smith+Nephew, Integra LifeSciences Corporation)
- Expand product portfolios through acquisitions, partnerships, and continuous R&D.
- Focus on advanced wound care solutions, including dressings, NPWT, biologics, and skin substitutes.
- Strong global brand recognition and customer loyalty.
- Broad and diversified product portfolios.
- High operational and manufacturing costs.
- Slower product innovation due to complex organizational structures.
Emerging Players (Nanordica Medical, MBP - Medical Biomaterial Products GmbH, Advanced Medical Solutions Group plc, Plastod SpA)
- Focus on niche technologies such as regenerative medicine, smart dressings, and AI-enabled wound care.
- Develop innovative biologics and tissue-engineered products.
- Faster innovation and product development cycles.
- Strong focus on unmet clinical needs and differentiated technologies.
- Limited financial and commercial resources.
- Smaller manufacturing capacity and distribution network.
Recent Developments
-
In July 2026, Mölnlycke completed construction of its first manufacturing facility in China, which will manufacture wound-care products for the Chinese market. The facility is expected to improve local supply responsiveness and strengthen the company's manufacturing and supply-chain capabilities in China.
-
In November 2025, Convatec reported continued progress across its Advanced Wound Care portfolio, including the launch of ConvaFoam and the rollout of ConvaNiox, while advancing its pipeline of wound-care products, including ConvaFiber, ConvaVac, Flexi-Seal Air, and Cure Aqua.
-
In November 2025, the Department of Atomic Energy (DAE) of India, in collaboration with Cologenesis Healthcare Pvt. Ltd., launched ColoNoX, India’s first nitric oxide–releasing wound dressing for diabetic foot ulcers (DFU). Developed by scientists at the Bhabha Atomic Research Centre, the product received regulatory approval from the Central Drugs Standard Control Organisation (CDSCO) following Phase II and III clinical trials. ColoNoX uses controlled nitric oxide delivery with collagen hydrogel to improve blood flow, reduce infection risk, and support healing in DFUs, addressing a major clinical need among the country’s diabetic population.
-
In October 2025, Convatec announced plans to invest more than USD 1 billion over the next decade to expand its global R&D footprint, reinforcing its innovation strategy in chronic care. The commitment includes USD 600 million for the expansion of R&D facilities in Boston, U.S., increasing capacity by about 50 % by the end of 2025, and £500 million (≈USD 650 million) for a new R&D hub in Manchester, UK, expected to open in 2027.
-
In September 2025, Mölnlycke broke ground on a USD 135 million expansion of its wound care manufacturing facility in Brunswick, Maine, USA, aimed at significantly increasing U.S. production capacity for wound dressings and related products. The project will add new production lines, warehousing, and operations, create jobs (increasing the local workforce by about 10%), and support localized supply to meet rising demand from U.S. healthcare providers. Completion is expected by late 2026 or early 2027.
-
In May 2025, Mölnlycke agreed to acquire P.G.F. Industry Solutions GmbH, the Austrian manufacturer of Granudacyn wound cleansing and moisturizing solutions. The acquisition expands Mölnlycke’s wound care portfolio with wound cleansing products for both acute and chronic wounds, distributed in over 50 countries. This move is intended to strengthen Mölnlycke’s global position in wound care and improve access to cleansing solutions that support wound healing.
-
In May 2025, Mölnlycke announced support for the Wound Care Collaborative Community (WCCC) initiative to develop a standardized pre-clinical testing framework for wound dressings. The collaboration brings together clinicians, procurement teams, regulators, and industry experts to enhance consistency and clinical relevance in dressing evaluations, enabling clinicians to make more informed decisions and guiding product design toward real-world needs. By addressing gaps in current testing standards, the initiative aims to drive innovation and elevate wound dressing performance across the care continuum.
-
In March 2025, Convatec showcased its strongest wound-care innovation pipeline to date at EWMA 2025 in Barcelona. The company highlighted advanced solutions designed to improve healing outcomes, reduce clinical burden, and enhance patient quality of life. Key presentations included next-generation ConvaFoam dressings, new clinical evidence supporting silver-based therapies for hard-to-heal wounds, and reinforcement of its Wound Hygiene protocol. Convatec also hosted innovation forums and competitions, underlining its commitment to advancing evidence-based wound care globally.
Wound Care Market Report Scope
Report Attribute
Details
Market size in 2025
USD 25.1 billion
Estimated market size in 2026
USD 26.1 billion
Projected market size by 2033
USD 35.1 billion
Growth rate
CAGR of 4.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, mode of purchase, distribution channel, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Smith+Nephew; Convatec Group PLC; Mölnlycke Health Care AB; Baxter; DeRoyal Industries, Inc.; Coloplast Corp; Medtronic; 3M; INTEGRA LIFESCIENCES; Medline Industries, LP; Johnson & Johnson Services, Inc.; B. Braun SE; MIMEDX Group, Inc.; Cardinal Health; Organogenesis Inc.; Advanced Medical Solutions Group plc; Plastod SpA; AVERY DENNISON CORPORATION; Lohmann Rauscher GmbH & Co. KG; Nanordica Medical; MBP - MEDICAL BIOMATERIAL PRODUCTS GmbH; URGO MEDICAL
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Wound Care Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global wound care market report based on product, application, end use, mode of purchase, distribution channel, and region:
Global Wound Care Market Report - Table of Contents
Chapter 1. Methodology and Scope
1.1. Market Segmentation and Scope
1.2. Research Methodology
1.3. Information Procurement
1.4. Information or Data Analysis
1.5. Market Formulation & Validation
1.6. Model Details
1.7. List of Data Sources
Chapter 2. Executive Summary
2.1. Market Outlook
2.2. Segment Outlook
2.3. Competitive Insights
Chapter 3. Wound Care Market Variables, Trends & Scope
3.1. Market Lineage Outlook
3.1.1. Parent market outlook
3.2. Market Dynamics
3.2.1. Market driver analysis
3.2.1.1. Increasing prevalence of chronic diseases and conditions affecting wound healing capabilities
3.2.1.2. Rising incidence of burn injuries
3.2.1.3. Introduction of innovative and advanced wound products
3.2.1.4. Rising geriatric population
3.2.1.5. Increasing number of road accidents and trauma injuries
3.2.2. Market restraint analysis
3.2.2.1. High cost of advanced wound care products and chronic wound treatments
3.2.2.2. Delayed diagnosis and lower treatment rates in emerging nations
3.2.3. Market opportunity analysis
3.2.3.1. Improvements in public and private hospital infrastructure
3.2.3.2. Growth potential in emerging economies in the wound care market
3.2.3.3. Rising number of clinical trials
3.2.4. Market challenge analysis
3.2.4.1. Growing number of product recalls
3.2.4.2. Lack of awareness about proper wound care practices and available treatment options
3.3. Wound Care Market Analysis Tools
3.3.1. Industry Analysis - Porter’s
3.3.1.1. Bargaining power of suppliers
3.3.1.2. Bargaining power of buyers
3.3.1.3. Threat of substitutes
3.3.1.4. Threat of new entrants
3.3.1.5. Competitive rivalry
3.3.2. PESTEL Analysis
3.3.2.1. Political & Legal Landscape
3.3.2.2. Economic and Social Landscape
3.3.2.3. Technological landscape
Chapter 4. Wound Care Market: Product Estimates & Trend Analysis
4.1. Segment Dashboard
4.2. Global Wound Care Market Movement Analysis
4.3. Global Wound Care Market Size & Trend Analysis, by Product, 2021 - 2033 (USD Million/Billion)
4.4. Advanced Wound Dressing
4.4.1. Advanced Wound Dressing market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2. Moist
4.4.2.1. Moist market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2.2. Foam Dressing
4.4.2.2.1. Foam Dressing market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2.3. Hydrocolloid Dressings
4.4.2.3.1. Hydrocolloid dressings market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2.4. Film Dressings
4.4.2.4.1. Film dressings market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2.5. Alginate Dressings
4.4.2.5.1. Alginate dressings market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2.6. Hydrogel Dressings
4.4.2.6.1. Hydrogel dressings market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2.7. Collagen Dressings
4.4.2.7.1. Collagen dressings market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.2.8. Other Advanced Dressings
4.4.2.8.1. Other advanced dressings market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3. Antimicrobial
4.4.3.1. Antimicrobial market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3.2. Silver
4.4.3.2.1. Silver market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3.3. Non-silver
4.4.3.3.1. Non-silver market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3.3.2. Honey
4.4.3.3.2.1. Honey market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3.3.3. Iodine
4.4.3.3.3.1. Iodine market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3.3.4. Chitosan
4.4.3.3.4.1. Chitosan market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3.3.5. PHMB
4.4.3.3.5.1. PHMB market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.3.3.6. Others
4.4.3.3.6.1. Others market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.4. Active
4.4.4.1. Active market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.4.2. Biomaterials
4.4.4.2.1. Biomaterials market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.4.3. Skin-substitute
4.4.4.3.1. Skin-substitute market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.4.4.4. Growth Factors
4.4.4.4.1. Growth factors market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
4.5. Surgical wound care
4.5.1. Surgical wound care market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.5.2. Sutures & staples
4.5.2.1. Sutures & staples market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.5.3. Tissue adhesives & sealants
4.5.3.1. Tissue adhesives & sealants market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.5.4. Anti-infective dressing
4.5.4.1. Anti-infective dressing market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.6. Traditional wound care
4.6.1. Traditional wound care market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.6.2. Medical tapes
4.6.2.1. Medical tapes market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.6.3. Cotton
4.6.3.1. Cotton market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.6.4. Bandages
4.6.4.1. Bandages market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.6.5. Gauzes
4.6.5.1. Gauzes market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.6.6. Sponges
4.6.6.1. Sponges market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.6.7. Cleansing agents
4.6.7.1. Cleansing agents market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.7. Wound therapy devices
4.7.1. Wound therapy devices market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.7.2. Negative pressure wound therapy
4.7.2.1. Negative pressure wound therapy market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.7.3. Oxygen and hyperbaric oxygen equipment
4.7.3.1. Oxygen and hyperbaric oxygen equipment market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.7.4. Electric stimulation devices
4.7.4.1. Electric stimulation devices market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.7.5. Pressure relief devices
4.7.5.1. Pressure relief devices market estimates and forecast, 2021 - 2033 (USD Million/Billion)
4.7.6. Others
4.7.6.1. Others market estimates and forecast, 2021 - 2033 (USD Million/Billion)
Chapter 5. Wound Care Market: Application Estimates & Trend Analysis
5.1. Segment Dashboard
5.2. Global Wound Care Market Movement Analysis
5.3. Global Wound Care Market Size & Trend Analysis, by Application, 2021 - 2033 (USD Million/Billion)
5.4. Acute Wounds
5.4.1. Acute wounds market estimates and forecast, 2021 - 2033 (USD Million/Billion)
5.4.2. Surgical & traumatic wounds
5.4.2.1. Surgical & traumatic wounds market estimates and forecast, 2021 - 2033 (USD Million/Billion)
5.4.3. Burns
5.4.3.1. Burns market estimates and forecast, 2021 - 2033 (USD Million/Billion)
5.4.3.2. 1st degree burns
5.4.3.2.1. 1st degree burns market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.4.3.3. 2nd degree burns
5.4.3.3.1. 2nd degree burns market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.4.3.4. 3rd degree burns
5.4.3.4.1. 3rd degree burns market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.5. Chronic Wounds
5.5.1. Chronic wounds market estimates and forecast, 2021 - 2033 (USD Million/Billion)
5.5.2. Diabetic foot ulcers
5.5.2.1. Diabetic foot ulcers market estimates and forecast, 2021 - 2033 (USD Million/Billion)
5.5.3. Pressure ulcers
5.5.3.1. Pressure ulcers market estimates and forecast, 2021 - 2033 (USD Million/Billion)
5.5.3.2. Stage 1
5.5.3.2.1. Stage 1 market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.5.3.3. Stage 2
5.5.3.3.1. Stage 2 market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.5.3.4. Stage 3
5.5.3.4.1. Stage 3 market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.5.3.5. Stage 4
5.5.3.5.1. Stage 4 market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.5.3.6. Deep Tissue Injury
5.5.3.6.1. Deep tissue injury market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
5.5.4. Venous leg ulcers
5.5.4.1. Venous leg ulcers market estimates and forecast, 2021 - 2033 (USD Million/Billion)
5.5.5. Others chronic wounds
5.5.5.1. Others chronic wounds market estimates and forecast, 2021 - 2033 (USD Million/Billion)
Chapter 6. Wound Care Devices: End Use Estimates & Trend Analysis
6.1. Segment Dashboard
6.2. Global Wound Care Market Movement Analysis
6.3. Global Wound Care Market Size & Trend Analysis, by End Use, 2021 - 2033 (USD Million/Billion)
6.4. Hospitals
6.4.1. Hospitals market estimates and forecast, 2021 - 2033 (USD Million/Billion)
6.5. Specialty clinics
6.5.1. Specialty clinics centers market estimates and forecast, 2021 - 2033 (USD Million/Billion)
6.6. Home healthcare
6.6.1. Home healthcare market estimates and forecast, 2021 - 2033 (USD Million/Billion)
6.7. Physician’s office
6.7.1. Physician’s office market estimates and forecast, 2021 - 2033 (USD Million/Billion)
6.8. Nursing Homes
6.8.1. Nursing homes market estimates and forecast, 2021 - 2033 (USD Million/Billion)
6.9. Others
6.9.1. Others market estimates and forecast, 2021 - 2033 (USD Million/Billion)
Chapter 7. Wound Care Market: Mode of Purchase Estimates & Trend Analysis
7.1. Segment Dashboard
7.2. Global Wound Care Market Movement Analysis
7.3. Global Wound Care Market Size & Trend Analysis, by Mode Of Purchase, 2021 - 2033 (USD Million/Billion)
7.4. Prescribed
7.4.1. Prescribed market estimates and forecast, 2021 - 2033 (USD Million/Billion)
7.5. Non-prescribed (OTC)
7.5.1. Non-prescribed (OTC) market estimates and forecast, 2021 - 2033 (USD Million/Billion)
Chapter 8. Wound Care Market: Distribution Channel Estimates & Trend Analysis
8.1. Segment Dashboard
8.2. Global Wound Care Market Movement Analysis
8.3. Global Wound Care Market Size & Trend Analysis, by Distribution Channel, 2021 - 2033 (USD Million/Billion)
8.4. Institutional sales
8.4.1. Institutional sales market estimates and forecast, 2021 - 2033 (USD Million/Billion)
8.5. Retail sales
8.5.1. Retail sales market estimates and forecast, 2021 - 2033 (USD Million/Billion)
Chapter 9. Wound Care Market: Regional Estimates & Trend Analysis
9.1. Regional Dashboard
9.2. Market Size & Forecasts and Trend Analysis, 2021 - 2033
9.3. North America
9.3.1. Market estimates and forecast, 2021 - 2033 (USD Million/Billion)
9.3.2. U.S.
9.3.2.1. Key country dynamics
9.3.2.2. Competitive scenario
9.3.2.3. Regulatory framework
9.3.2.4. Reimbursement scenario
9.3.2.5. U.S. market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.3.3. Canada
9.3.3.1. Key country dynamics
9.3.3.2. Competitive scenario
9.3.3.3. Regulatory framework
9.3.3.4. Reimbursement scenario
9.3.3.5. Canada market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.3.4. Mexico
9.3.4.1. Key country dynamics
9.3.4.2. Competitive scenario
9.3.4.3. Regulatory framework
9.3.4.4. Reimbursement scenario
9.3.4.5. Mexico market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4. Europe
9.4.1. UK
9.4.1.1. Key country dynamics
9.4.1.2. Competitive scenario
9.4.1.3. Regulatory framework
9.4.1.4. Reimbursement scenario
9.4.1.5. UK market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4.2. Germany
9.4.2.1. Key country dynamics
9.4.2.2. Competitive scenario
9.4.2.3. Regulatory framework
9.4.2.4. Reimbursement scenario
9.4.2.5. Germany market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4.3. France
9.4.3.1. Key country dynamics
9.4.3.2. Competitive scenario
9.4.3.3. Regulatory framework
9.4.3.4. Reimbursement scenario
9.4.3.5. France market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4.4. Italy
9.4.4.1. Key country dynamics
9.4.4.2. Competitive scenario
9.4.4.3. Regulatory framework
9.4.4.4. Reimbursement scenario
9.4.4.5. Italy market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4.5. Spain
9.4.5.1. Key country dynamics
9.4.5.2. Competitive scenario
9.4.5.3. Regulatory framework
9.4.5.4. Reimbursement scenario
9.4.5.5. Spain market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4.6. Denmark
9.4.6.1. Key country dynamics
9.4.6.2. Competitive scenario
9.4.6.3. Regulatory framework
9.4.6.4. Reimbursement scenario
9.4.6.5. Denmark market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4.7. Sweden
9.4.7.1. Key country dynamics
9.4.7.2. Competitive scenario
9.4.7.3. Regulatory framework
9.4.7.4. Reimbursement scenario
9.4.7.5. Sweden market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.4.8. Norway
9.4.8.1. Key country dynamics
9.4.8.2. Competitive scenario
9.4.8.3. Regulatory framework
9.4.8.4. Reimbursement scenario
9.4.8.5. Norway market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.5. Asia Pacific
9.5.1. Japan
9.5.1.1. Key country dynamics
9.5.1.2. Competitive scenario
9.5.1.3. Regulatory framework
9.5.1.4. Reimbursement scenario
9.5.1.5. Japan market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.5.2. India
9.5.2.1. Key country dynamics
9.5.2.2. Competitive scenario
9.5.2.3. Regulatory framework
9.5.2.4. Reimbursement scenario
9.5.2.5. India market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.5.3. China
9.5.3.1. Key country dynamics
9.5.3.2. Competitive scenario
9.5.3.3. Regulatory framework
9.5.3.4. Reimbursement scenario
9.5.3.5. China market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.5.4. South Korea
9.5.4.1. Key country dynamics
9.5.4.2. Competitive scenario
9.5.4.3. Regulatory framework
9.5.4.4. Reimbursement scenario
9.5.4.5. South Korea market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.5.5. Australia
9.5.5.1. Key country dynamics
9.5.5.2. Competitive scenario
9.5.5.3. Regulatory framework
9.5.5.4. Reimbursement scenario
9.5.5.5. Australia market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.5.6. Thailand
9.5.6.1. Key country dynamics
9.5.6.2. Competitive scenario
9.5.6.3. Regulatory framework
9.5.6.4. Reimbursement scenario
9.5.6.5. Thailand market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.6. Latin America
9.6.1. Brazil
9.6.1.1. Key country dynamics
9.6.1.2. Competitive scenario
9.6.1.3. Regulatory framework
9.6.1.4. Reimbursement scenario
9.6.1.5. Brazil market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.6.2. Argentina
9.6.2.1. Key country dynamics
9.6.2.2. Competitive scenario
9.6.2.3. Regulatory framework
9.6.2.4. Reimbursement scenario
9.6.2.5. Argentina market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.7. MEA
9.7.1. South Africa
9.7.1.1. Key country dynamics
9.7.1.2. Competitive scenario
9.7.1.3. Regulatory framework
9.7.1.4. Reimbursement scenario
9.7.1.5. South Africa market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.7.2. Saudi Arabia
9.7.2.1. Key country dynamics
9.7.2.2. Competitive scenario
9.7.2.3. Regulatory framework
9.7.2.4. Reimbursement scenario
9.7.2.5. Saudi Arabia market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.7.3. UAE
9.7.3.1. Key country dynamics
9.7.3.2. Competitive scenario
9.7.3.3. Regulatory framework
9.7.3.4. Reimbursement scenario
9.7.3.5. UAE market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
9.7.4. Kuwait
9.7.4.1. Key country dynamics
9.7.4.2. Competitive scenario
9.7.4.3. Regulatory framework
9.7.4.4. Reimbursement scenario
9.7.4.5. Kuwait market estimates and forecasts, 2021 - 2033 (USD Million/Billion)
Chapter 10. Competitive Landscape
10.1. Market Participant Categorization
10.2. Key Company Profiles
10.2.1. Smith+Nephew
10.2.1.1. Company overview
10.2.1.2. Financial performance
10.2.1.3. Product benchmarking
10.2.1.4. Strategic initiatives
10.2.2. Convatec Group PLC
10.2.2.1. Company overview
10.2.2.2. Financial performance
10.2.2.3. Product benchmarking
10.2.2.4. Strategic initiatives
10.2.3. Mölnlycke Health Care AB
10.2.3.1. Company overview
10.2.3.2. Financial performance
10.2.3.3. Product benchmarking
10.2.3.4. Strategic initiatives
10.2.4. Baxter
10.2.4.1. Company overview
10.2.4.2. Financial performance
10.2.4.3. Product benchmarking
10.2.4.4. Strategic initiatives
10.2.5. DeRoyal Industries, Inc.
10.2.5.1. Company overview
10.2.5.2. Financial performance
10.2.5.3. Product benchmarking
10.2.5.4. Strategic initiatives
10.2.6. Coloplast Corp.
10.2.6.1. Company overview
10.2.6.2. Financial performance
10.2.6.3. Product benchmarking
10.2.6.4. Strategic initiatives
10.2.7. Medtronic
10.2.7.1. Company overview
10.2.7.2. Financial performance
10.2.7.3. Product benchmarking
10.2.7.4. Strategic initiatives
10.2.8. 3M
10.2.8.1. Company overview
10.2.8.2. Financial performance
10.2.8.3. Product benchmarking
10.2.8.4. Strategic initiatives
10.2.9. INTEGRA LIFESCIENCES
10.2.9.1. Company overview
10.2.9.2. Financial performance
10.2.9.3. Product benchmarking
10.2.9.4. Strategic initiatives
10.2.10. Medline Industries, LP
10.2.10.1. Company overview
10.2.10.2. Financial performance
10.2.10.3. Product benchmarking
10.2.10.4. Strategic initiatives
10.2.11. Johnson & Johnson Services, Inc.
10.2.11.1. Company overview
10.2.11.2. Financial performance
10.2.11.3. Product benchmarking
10.2.11.4. Strategic initiatives
10.2.12. B. Braun SE
10.2.12.1. Company overview
10.2.12.2. Financial performance
10.2.12.3. Product benchmarking
10.2.12.4. Strategic initiatives
10.2.13. Cardinal Health
10.2.13.1. Company overview
10.2.13.2. Financial performance
10.2.13.3. Product benchmarking
10.2.13.4. Strategic initiatives
10.2.14. Organogenesis Inc.
10.2.14.1. Company overview
10.2.14.2. Financial performance
10.2.14.3. Product benchmarking
10.2.14.4. Strategic initiatives
10.2.15. MIMEDX Group, Inc.
10.2.15.1. Company overview
10.2.15.2. Financial performance
10.2.15.3. Product benchmarking
10.2.15.4. Strategic initiatives
10.2.16. Advanced Medical Solutions Group plc
10.2.16.1. Company overview
10.2.16.2. Financial performance
10.2.16.3. Product benchmarking
10.2.16.4. Strategic initiatives
10.2.17. Plastod SpA
10.2.17.1. Company overview
10.2.17.2. Financial performance
10.2.17.3. Product benchmarking
10.2.17.4. Strategic initiatives
10.2.18. AVERY DENNISON CORPORATION
10.2.18.1. Company overview
10.2.18.2. Financial performance
10.2.18.3. Product benchmarking
10.2.18.4. Strategic initiatives
10.2.19. Lohmann Rauscher GmbH & Co. KG
10.2.19.1. Company overview
10.2.19.2. Financial performance
10.2.19.3. Product benchmarking
10.2.19.4. Strategic initiatives
10.2.20. Nanordica Medical
10.2.20.1. Company overview
10.2.20.2. Financial performance
10.2.20.3. Product benchmarking
10.2.20.4. Strategic initiatives
10.2.21. MBP - MEDICAL BIOMATERIAL PRODUCTS GmbH
10.2.21.1. Company overview
10.2.21.2. Financial performance
10.2.21.3. Product benchmarking
10.2.21.4. Strategic initiatives
10.2.22. URGO MEDICAL
10.2.22.1. Company overview
10.2.22.2. Financial performance
10.2.22.3. Product benchmarking
10.2.22.4. Strategic initiatives
10.3. Heat Map Analysis/ Company Market Position Analysis
10.4. Estimated Company Market Share Analysis, 2024/2025
10.5. List of Other Key Market PlayersList of Tables
Table 1 List of secondary sources
Table 2 List of abbreviations
Table 3 North America wound care market, by country, 2021 - 2033 (USD Million/Billion)
Table 4 North America wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 5 North America wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 6 North America wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 7 North America wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 8 North America wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 9 U.S wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 10 U.S wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 11 U.S wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 12 U.S wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 13 U.S wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 14 Canada wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 15 Canada wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 16 Canada wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 17 Canada wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 18 Canada wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 19 Mexico wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 20 Mexico wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 21 Mexico wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 22 Mexico wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 23 Mexico wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 24 Europe wound care market, by country, 2021 - 2033 (USD Million/Billion)
Table 25 Europe wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 26 Europe wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 27 Europe wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 28 Europe wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 29 Europe wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 30 UK wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 31 UK wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 32 UK wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 33 UK wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 34 UK wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 35 Germany wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 36 Germany wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 37 Germany wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 38 Germany wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 39 Germany wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 40 France wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 41 France wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 42 France wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 43 France wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 44 France wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 45 Italy wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 46 Italy wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 47 Italy wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 48 Italy wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 49 Italy wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 50 Spain wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 51 Spain wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 52 Spain wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 53 Spain wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 54 Spain wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 55 Denmark wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 56 Denmark wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 57 Denmark wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 58 Denmark wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 59 Denmark wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 60 Sweden wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 61 Sweden wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 62 Sweden wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 63 Sweden wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 64 Sweden wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 65 Norway wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 66 Norway wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 67 Norway wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 68 Norway wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 69 Norway wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 70 Asia Pacific wound care market, by country, 2021 - 2033 (USD Million/Billion)
Table 71 Asia Pacific wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 72 Asia Pacific wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 73 Asia Pacific wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 74 Asia Pacific wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 75 Asia Pacific wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 76 China wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 77 China wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 78 China wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 79 China wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 80 China wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 81 Japan wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 82 Japan wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 83 Japan wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 84 Japan wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 85 Japan wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 86 India wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 87 India wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 88 India wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 89 India wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 90 India wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 91 South Korea wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 92 South Korea wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 93 South Korea wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 94 South Korea wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 95 South Korea wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 96 Australia wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 97 Australia wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 98 Australia wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 99 Australia wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 100 Australia wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 101 Thailand wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 102 Thailand wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 103 Thailand wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 104 Thailand wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 105 Thailand wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 106 Latin America wound care market, by country, 2021 - 2033 (USD Million/Billion)
Table 107 Latin America wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 108 Latin America wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 109 Latin America wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 110 Latin America wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 111 Latin America wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 112 Brazil wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 113 Brazil wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 114 Brazil wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 115 Brazil wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 116 Brazil wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 117 Mexico wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 118 Mexico wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 119 Mexico wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 120 Mexico wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 121 Mexico wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 122 Argentina wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 123 Argentina wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 124 Argentina wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 125 Argentina wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 126 Argentina wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 127 Middle East & Africa wound care market, by country, 2021 - 2033 (USD Million/Billion)
Table 128 Middle East & Africa wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 129 Middle East & Africa wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 130 Middle East & Africa wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 131 Middle East & Africa wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 132 Middle East & Africa wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 133 South Africa wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 134 South Africa wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 135 South Africa wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 136 South Africa wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 137 South Africa wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 138 Saudi Arabia wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 139 Saudi Arabia wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 140 Saudi Arabia wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 141 Saudi Arabia wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 142 Saudi Arabia wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 143 UAE wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 144 UAE wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 145 UAE wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 146 UAE wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 147 UAE wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)
Table 148 Kuwait wound care market, by product, 2021 - 2033 (USD Million/Billion)
Table 149 Kuwait wound care market, by application, 2021 - 2033 (USD Million/Billion)
Table 150 Kuwait wound care market, by end use, 2021 - 2033 (USD Million/Billion)
Table 151 Kuwait wound care market, by mode of purchase, 2021 - 2033 (USD Million/Billion)
Table 152 Kuwait wound care market, by distribution channel, 2021 - 2033 (USD Million/Billion)List of Figures
Fig. 1 Information Procurement
Fig. 2 Primary Research Pattern
Fig. 3 Market Research Approaches
Fig. 4 Value Chain-Based Sizing & Forecasting
Fig. 5 Market Formulation & Validation
Fig. 6 Wound Care Market, Market Segmentation
Fig. 7 Market Driver Analysis (Current & Future Impact)
Fig. 8 Market Restraint Analysis (Current & Future Impact)
Fig. 9 Market Opportunity Analysis (Current & Future Impact)
Fig. 10 Market Challenge Analysis (Current & Future Impact)
Fig. 11 SWOT Analysis, By Factor (Political & Legal, Economic, and Technological)
Fig. 12 Porter’s Five Forces Analysis
Fig. 13 Regional Marketplace: Key Takeaways
Fig. 14 Global Wound Care Market, for Product, 2021 - 2033 (USD Million/Billion)
Fig. 15 Global Wound Care Market, for Advanced Wound Dressing, 2021 - 2033 (USD Million/Billion)
Fig. 16 Global Wound Care Market, for Moist, 2021 - 2033 (USD Million/Billion)
Fig. 17 Global Wound Care Market, for Foam Dressings, 2021 - 2033 (USD Million/Billion)
Fig. 18 Global Wound Care Market, for Hydrocolloid Dressings, 2021 - 2033 (USD Million/Billion)
Fig. 19 Global Wound Care Market, for Film Dressings, 2021 - 2033 (USD Million/Billion)
Fig. 20 Global Wound Care Market, for Alginate Dressings, 2021 - 2033 (USD Million/Billion)
Fig. 21 Global Wound Care Market, for Hydrogel Dressings, 2021 - 2033 (USD Million/Billion)
Fig. 22 Global Wound Care Market, for Collagen Dressings, 2021 - 2033 (USD Million/Billion)
Fig. 23 Global Wound Care Market, for Other Advanced Dressings, 2021 - 2033 (USD Million/Billion)
Fig. 24 Global Wound Care Market, for Anti-microbial, 2021 - 2033 (USD Million/Billion)
Fig. 25 Global Wound Care Market, for Silver, 2021 - 2033 (USD Million/Billion)
Fig. 26 Global Wound Care Market, for Non-silver, 2021 - 2033 (USD Million/Billion)
Fig. 27 Global Wound Care Market, for Iodine, 2021 - 2033 (USD Million/Billion)
Fig. 28 Global Wound Care Market, for Honey, 2021 - 2033 (USD Million/Billion)
Fig. 29 Global Wound Care Market, for PHMB, 2021 - 2033 (USD Million/Billion)
Fig. 30 Global Wound Care Market, for Chitosan, 2021 - 2033 (USD Million/Billion)
Fig. 31 Global Wound Care Market, for Others, 2021 - 2033 (USD Million/Billion)
Fig. 32 Global Wound Care Market, for Active, 2021 - 2033 (USD Million/Billion)
Fig. 33 Global Wound Care Market, for Biomaterials, 2021 - 2033 (USD Million/Billion)
Fig. 34 Global Wound Care Market, for Skin-substitute, 2021 - 2033 (USD Million/Billion)
Fig. 35 Global Wound Care Market, for Growth Factors, 2021 - 2033 (USD Million/Billion)
Fig. 36 Global Wound Care Market, for Surgical Wound Care, 2021 - 2033 (USD Million/Billion)
Fig. 37 Global Wound Care Market, for Sutures & Staples, 2021 - 2033 (USD Million/Billion)
Fig. 38 Global Wound Care Market, for Tissue Adhesives and Sealants, 2021 - 2033 (USD Million/Billion)
Fig. 39 Global Wound Care Market, for Anti-infective Dressing, 2021 - 2033 (USD Million/Billion)
Fig. 40 Global Wound Care Market, for Traditional Wound Care, 2021 - 2033 (USD Million/Billion)
Fig. 41 Global Wound Care Market, for Medical Tapes, 2021 - 2033 (USD Million/Billion)
Fig. 42 Global Wound Care Market, for Cotton, 2021 - 2033 (USD Million/Billion)
Fig. 43 Global Wound Care Market, for Bandages, 2021 - 2033 (USD Million/Billion)
Fig. 44 Global Wound Care Market, for Gauzes, 2021 - 2033 (USD Million/Billion)
Fig. 45 Global Wound Care Market, for Sponges, 2021 - 2033 (USD Million/Billion)
Fig. 46 Global Wound Care Market, for Cleansing Agents, 2021 - 2033 (USD Million/Billion)
Fig. 47 Global Wound Care Market, for Wound Therapy Devices, 2021 - 2033 (USD Million/Billion)
Fig. 48 Global Wound Care Market, for Negative Pressure Wound Therapy, 2021 - 2033 (USD Million/Billion)
Fig. 49 Global Wound Care Market, for Oxygen and Hyperbaric Oxygen Equipment, 2021 - 2033 (USD Million/Billion)
Fig. 50 Global Wound Care Market, for Electric Stimulation Devices, 2021 - 2033 (USD Million/Billion)
Fig. 51 Global Wound Care Market, for Pressure Relief Devices, 2021 - 2033 (USD Million/Billion)
Fig. 52 Global Wound Care Market, for Others, 2021 - 2033 (USD Million/Billion)
Fig. 53 Global Wound Care Market, for Application, 2021 - 2033 (USD Million/Billion)
Fig. 54 Global Wound Care Market, for Acute Wound, 2021 - 2033 (USD Million/Billion)
Fig. 55 Global Wound Care Market, for Surgical & Traumatic Wounds, 2021 - 2033 (USD Million/Billion)
Fig. 56 Global Wound Care Market, for Burns, 2021 - 2033 (USD Million/Billion)
Fig. 57 Global Wound Care Market, for 1st Degree Burns, 2021 - 2033 (USD Million/Billion)
Fig. 58 Global Wound Care Market, for 2nd Degree Burns, 2021 - 2033 (USD Million/Billion)
Fig. 59 Global Wound Care Market, for 3rd Degree Burns, 2021 - 2033 (USD Million/Billion)
Fig. 60 Global Wound Care Market, for Chronic Wound, 2021 - 2033 (USD Million/Billion)
Fig. 61 Global Wound Care Market, for Diabetic Foot Ulcers, 2021 - 2033 (USD Million/Billion)
Fig. 62 Global Wound Care Market, for Pressure Ulcers, 2021 - 2033 (USD Million/Billion)
Fig. 63 Global Wound Care Market, for Stage 1, 2021 - 2033 (USD Million/Billion)
Fig. 64 Global Wound Care Market, for Stage 2, 2021 - 2033 (USD Million/Billion)
Fig. 65 Global Wound Care Market, for Stage 3, 2021 - 2033 (USD Million/Billion)
Fig. 66 Global Wound Care Market, for Stage 4, 2021 - 2033 (USD Million/Billion)
Fig. 67 Global Wound Care Market, for Deep Tissue Injury, 2021 - 2033 (USD Million/Billion)
Fig. 68 Global Wound Care Market, for Venous Leg Ulcers, 2021 - 2033 (USD Million/Billion)
Fig. 69 Global Wound Care Market, for Others Chronic Wounds, 2021 - 2033 (USD Million/Billion)
Fig. 70 Global Wound Care Market, for End Use, 2021 - 2033 (USD Million/Billion)
Fig. 71 Global Wound Care Market, for Hospitals, 2021 - 2033 (USD Million/Billion)
Fig. 72 Global Wound Care Market, for Specialty Clinics, 2021 - 2033 (USD Million/Billion)
Fig. 73 Global Wound Care Market, for Home Healthcare, 2021 - 2033 (USD Million/Billion)
Fig. 74 Global Wound Care Market, for Physician’s Office, 2021 - 2033 (USD Million/Billion)
Fig. 75 Global Wound Care Market, for Nursing Homes, 2021 - 2033 (USD Million/Billion)
Fig. 76 Global Wound Care Market, for Others, 2021 - 2033 (USD Million/Billion)
Fig. 77 Global Wound Care Market, for Distribution Channel, 2021 - 2033 (USD Million/Billion)
Fig. 78 Global Wound Care Market, for Institutional Sales, 2021 - 2033 (USD Million/Billion)
Fig. 79 Global Wound Care Market, for Retail Sales, 2021 - 2033 (USD Million/Billion)
Fig. 80 Global Wound Care Market, for Mode of Purchase, 2021 - 2033 (USD Million/Billion)
Fig. 81 Global Wound Care Market, for Prescribed, 2021 - 2033 (USD Million/Billion)
Fig. 82 Global Wound Care Market, for Non-prescribed (OTC), 2021 - 2033 (USD Million/Billion)
Fig. 83 Regional Outlook, 2025 & 2033
Fig. 84 North America Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 85 U.S Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 86 Canada Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 87 Mexico Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 88 Europe Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 89 Germany Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 90 UK Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 91 France Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 92 Italy Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 93 Spain Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 94 Denmark Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 95 Sweden Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 96 Norway Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 97 Asia Pacific Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 98 Japan Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 99 China Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 100 India Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 101 Australia Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 102 South Korea Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 103 Thailand Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 104 Latin America Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 105 Brazil Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 106 Argentina Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 107 Middle East and Africa Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 108 South Africa Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 109 Saudi Arabia Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 110 UAE Wound Care Market, 2021 - 2033 (USD Million/Billion)
Fig. 111 Kuwait Wound Care Market, 2021 - 2033 (USD Million/Billion)Research Methodology
The wound care market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each wound care segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Advanced Wound Dressing
Revenue generated from the sale of advanced dressings designed to accelerate wound healing by maintaining a moist wound environment, controlling exudate, preventing infection, and promoting tissue regeneration. This segment includes foam, hydrocolloid, hydrogel, alginate, collagen, antimicrobial, silicone, transparent film, composite, and superabsorbent dressings used for chronic and acute wounds across hospitals, wound care clinics, ambulatory surgical centers, and home healthcare settings.
Surgical Wound Care
Revenue generated from the sale of products used for the prevention, management, and healing of surgical wounds before, during, and after surgical procedures. This segment includes advanced and traditional dressings, surgical incise drapes, wound closure products, tissue adhesives, antimicrobial products, and negative pressure wound therapy (NPWT) used across hospitals, ambulatory surgical centers, and specialty clinics.
Traditional Wound Care
Revenue generated from the sale of conventional wound care products used for the protection and management of acute and minor wounds. This segment includes gauze, adhesive bandages, cotton dressings, wound pads, tapes, and basic absorbent dressings used across hospitals, clinics, ambulatory surgical centers, and home healthcare settings.
Wound Therapy Devices
Revenue generated from the sale of medical devices used to promote wound healing, manage exudate, and improve clinical outcomes. This segment includes negative-pressure wound therapy (NPWT) systems, oxygen and hyperbaric oxygen therapy devices, electrical stimulation devices, ultrasound wound therapy devices, pressure-relief devices, and other advanced wound management equipment used across hospitals, wound care clinics, ambulatory surgical centers, and home healthcare settings.
Estimation Model
Approach
Description
Bottom-Up Patient & Procedure Volume Modeling
Estimates the wound care market by calculating the number of patients receiving wound care across hospitals, wound care clinics, ambulatory surgical centers (ASCs), home healthcare settings, and long-term care facilities. The model incorporates the prevalence and incidence of chronic and acute wounds, including diabetic foot ulcers, pressure ulcers, venous leg ulcers, surgical wounds, burns, and traumatic injuries. Procedure volumes, treatment frequency, product utilization per patient (dressings, NPWT, biologics, wound closure products, and wound care devices), replacement cycles, and average selling prices (ASP) are used to derive the total market value.
Top-Down Revenue Triangulation
Estimates the market by analyzing revenues generated by manufacturers offering advanced wound dressings, traditional dressings, NPWT, biologics & skin substitutes, wound closure products, wound care devices, and infection management solutions. Revenue estimates are segmented by product type, wound type, end user, and geography, and validated using company annual reports, regulatory filings, reimbursement data, procurement trends, distributor networks, hospital purchasing patterns, and expert interviews to ensure comprehensive market coverage while eliminating revenue duplication.
Demand-Side Healthcare Utilization Modeling
Evaluates market demand by assessing the utilization of wound care products and devices across hospitals, wound care centers, ambulatory surgical centers, home healthcare providers, rehabilitation centers, and long-term care facilities. The model considers patient treatment pathways for chronic and acute wounds, clinical practice guidelines, dressing change frequency, adoption rates of advanced wound care technologies, reimbursement availability, healthcare expenditure, and regional treatment patterns to estimate annual product demand, utilization rates, and market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Disease Epidemiology Analysis
Comprehensive analysis of wound disease burden by indication (diabetic foot ulcers, pressure ulcers, venous leg ulcers, surgical wounds, burns, and traumatic wounds), including prevalence, incidence, patient pool, regional trends, and future disease projections.
Enables demand forecasting, identifies high-growth therapeutic segments, supports market sizing assumptions, and assists in regional expansion and investment prioritization.
Product Share Analysis
Detailed market share assessment by product category, including advanced wound dressings, traditional dressings, negative pressure wound therapy (NPWT), biologics & skin substitutes, wound closure products, and wound care devices, with revenue contribution and growth outlook.
Identifies high-revenue product segments, uncovers white space opportunities, supports product portfolio optimization, and informs new product development and commercialization strategies.
Company Share Analysis
Competitive benchmarking of leading and emerging players based on estimated market share, product portfolio, geographic presence, innovation pipeline, strategic initiatives (M&A, partnerships, product launches), and competitive positioning.
Provides actionable competitive intelligence, identifies market leaders and challengers, supports partnership/acquisition decisions, and helps benchmark organizational performance against key competitors.
Frequently Asked Questions About This Report
The global wound care market size was estimated at USD 25.1 billion in 2025 and is expected to reach USD 26.1 billion in 2026.
The global wound care market is expected to grow at a compound annual growth rate of 4.3% from 2026 to 2033 to reach USD 35.1 billion by 2033.
North America dominated with a 46.9% revenue share in 2025.
Some key players operating in the wound care market include Smith+Nephew, Convatec Group PLC, Mölnlycke Health Care AB, Baxter, DeRoyal Industries, Inc, Coloplast Corp, Medtronic, 3M, INTEGRA LIFESCIENCES, MIMEDX Group, Inc., Medline Industries, LP, Johnson & Johnson Services, Inc., B. Braun SE, Cardinal Health, URGO MEDICAL, and Organogenesis Inc
An aging population drives the wound care market, increasing the incidence of chronic diseases such as diabetes, the prevalence of pressure ulcers and venous leg ulcers, and the demand for advanced wound care products and therapies. Technological advancements in wound care products, awareness about wound care management, and favorable reimbursement policies contribute to market growth.
The chronic wounds segment led with a 59.8% revenue share in 2025, while the acute wound segment is expected to grow at a significant CAGR.
The hospital segment led with a 36.4% revenue share in 2025, while the home healthcare segment is anticipated to grow at a significant CAGR.
The institutional sales segment held the largest revenue share in 2025, while the retail sales segment is the fastest-growing.
The advanced wound dressings segment held the largest revenue share in 2025, while the surgical wound care segment is expected to grow at a considerable pace during the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


