
- Home
- »
- Medical Devices
- »
-
Medical Robotic Systems Market Size Report, 2026-2033GVR Report cover

Medical Robotic Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Surgical Robots, Exo-Robots, Cleanroom Robots, Pharma Robots, Medical Service Robots), By Region, And Segment Forecasts
Market Size, 2025
$16.7BMarket Estimate, 2026
$20.3BMarket Forecast, 2033
$55.1BCAGR, 2026–2033
15.3%Medical Robotic Systems Market Summary
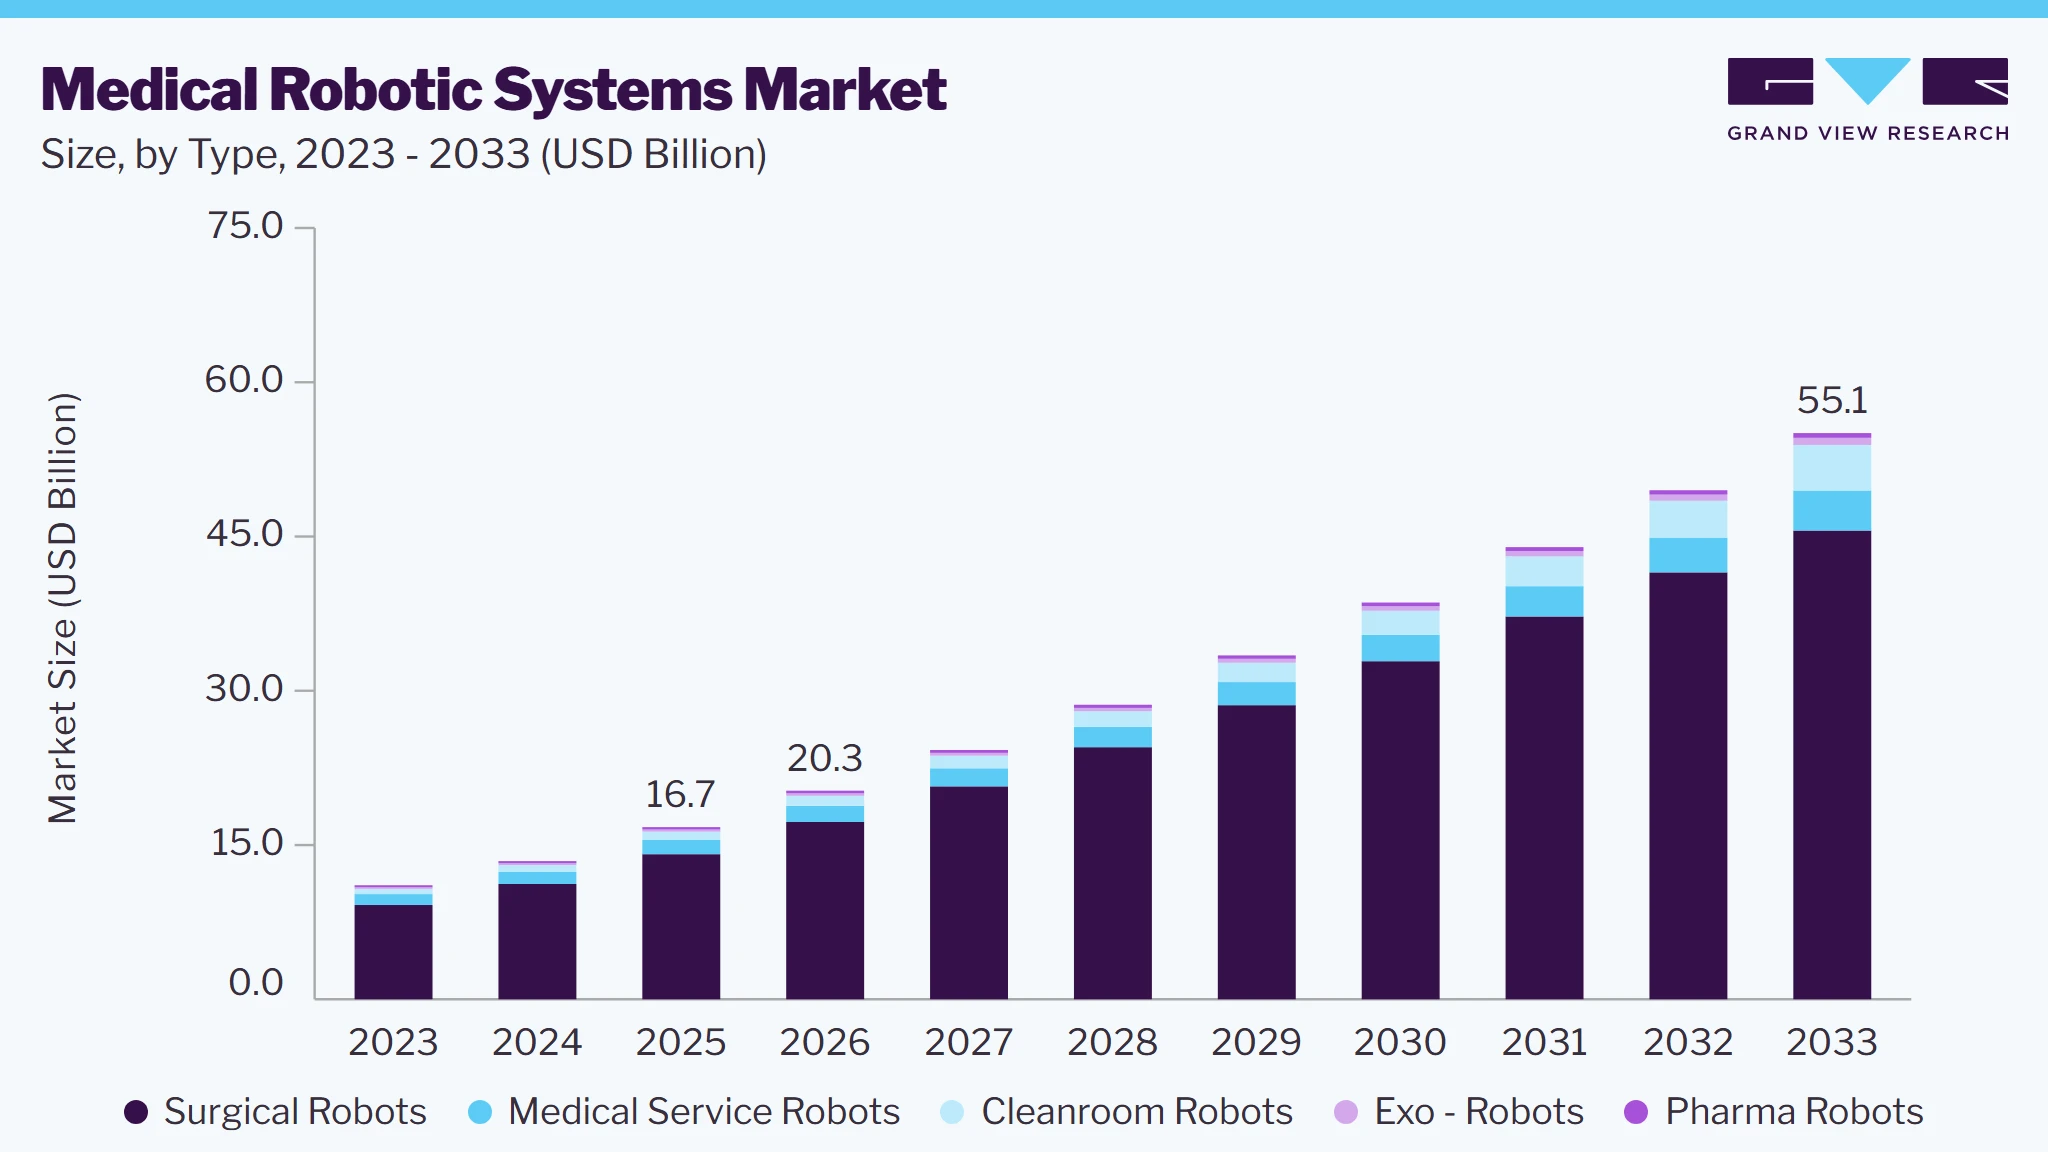
The global medical robotic systems market size was valued at USD 16.7 billion in 2025 and is projected to grow from USD 20.3 billion in 2026 to USD 55.1 billion by 2033, at a CAGR of 15.3% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 46.6% in 2025. The industry is driven by the rising preference for minimally invasive procedures.
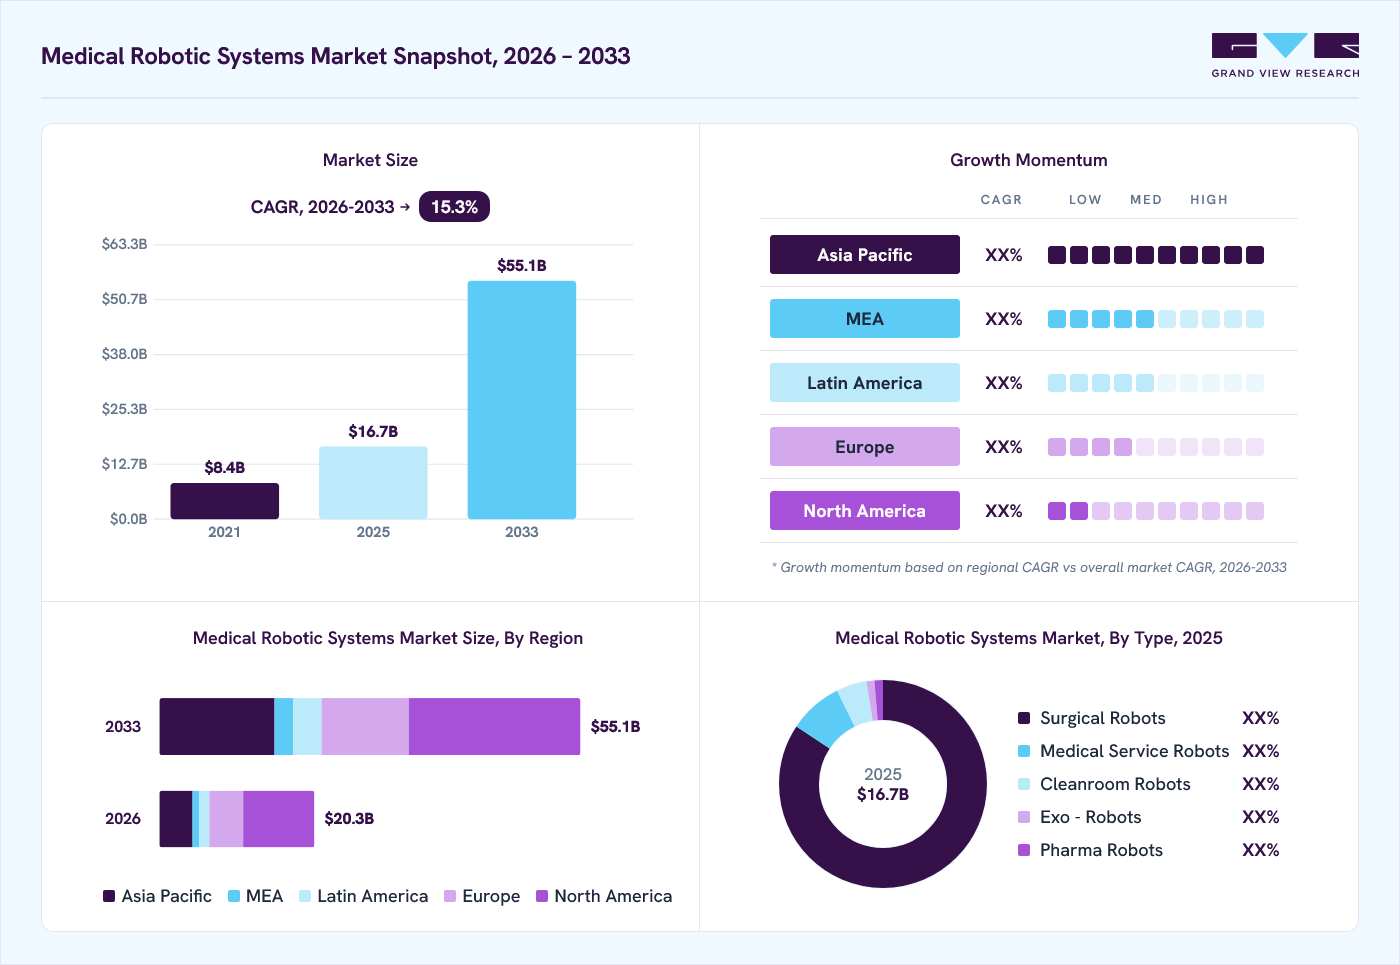 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Surgical robots segment held the largest market share of 84.3% in 2025.
Regional Highlights
- Largest regional market: North America (46.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country:
Market Size & Forecast
- Market Size in 2025: USD 16.7 Billion
- Estimated Market Size in 2026: USD 20.3 Billion
- Projected Market Size by 2033: USD 55.1 Billion
- CAGR (2026-2033): 15.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Market Dynamics
The increasing demand for minimally invasive surgery and clinical precision, advancements in artificial intelligence (AI), imaging, and digital integration, and rising automation in pharmaceutical production and the increasing need for contamination control and compliance are factors contributing to market growth.
1) Increasing Demand for Minimally Invasive Surgery and Clinical Precision
The rising preference for minimally invasive procedures is a primary driver for surgical robots. These systems enable high precision, improved dexterity, and enhanced visualization, allowing surgeons to perform complex procedures with smaller incisions. This results in reduced complications, shorter hospital stays, and faster patient recovery. Hospitals are prioritizing robotic-assisted surgery to improve clinical outcomes while optimizing resource utilization, particularly in high-volume specialties.
Moreover, healthcare systems are integrating robotic-assisted surgery across specialties, including orthopedics, urology, gynecology, and general surgery. Recent examples underscore this trend toward heightened precision and expanded application. For instance, by the end of 2025, customers in the U.S., Korea, Japan, and Europe had installed over 1,200 Intuitive Surgical da Vinci 5 systems, which were used in more than 270,000 procedures.
In addition, in March 2024, Intuitive Surgical received FDA 510(k) clearance for the da Vinci 5, a fifth-generation system featuring "Force Feedback" technology. This innovation allows surgeons to physically feel tissue resistance during a robotic procedure, providing a level of sensory precision previously unavailable on robotic platforms. In addition, in January 2026, the FDA expanded the da Vinci 5 clearance to include complex cardiac procedures, such as mitral valve repair. These advancements demonstrate a market shift toward high-precision medical specialties, in which robotic stability is critical for achieving successful clinical outcomes in delicate anatomical structures.
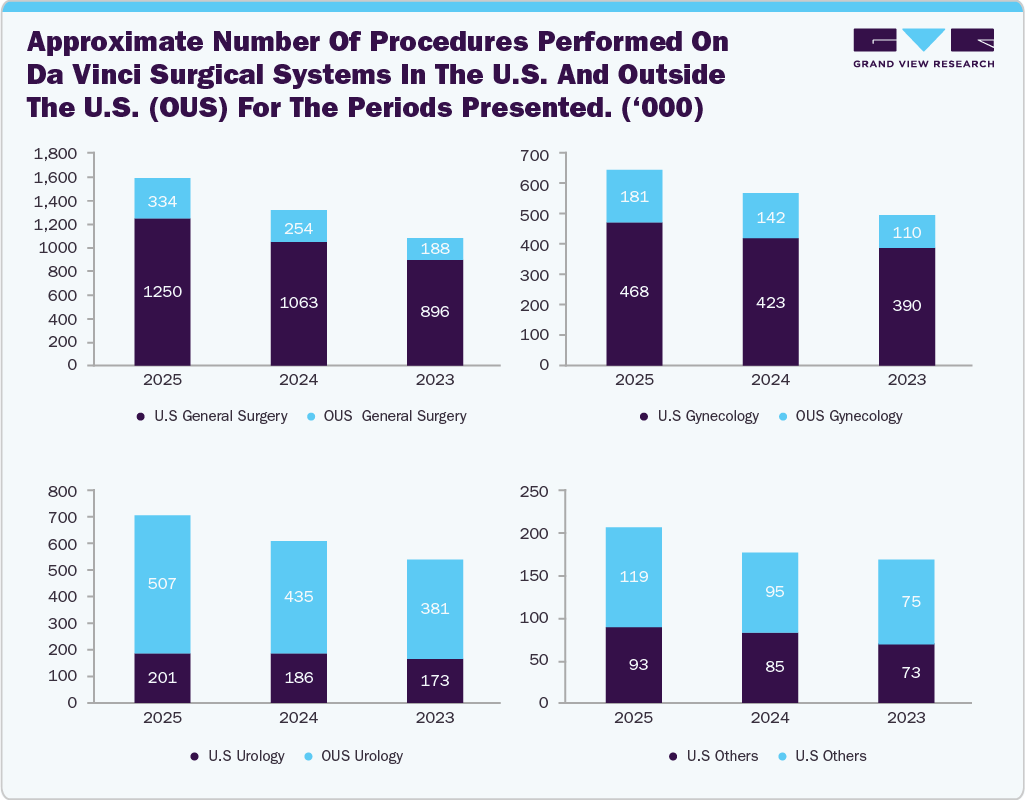
The following is the approximate number of procedures performed on da Vinci surgical systems in the U.S. and outside the U.S. (OUS) for the periods presented. (in Thousand Units)
 To learn more about this report, Download Free Sample Report
2) Rising Automation in Pharmaceutical Production and Increasing Need for Contamination Control and Compliance
Stringent regulatory requirements and the need for contamination-free environments are driving the adoption of cleanroom robots in healthcare and pharmaceutical settings. These robots operate in controlled environments to perform tasks such as material handling, inspection, and packaging with high precision and minimal human intervention. This reduces contamination risks and ensures compliance with GMP and ISO cleanroom standards.
Cleanroom robots are equipped with advanced sensors, vision systems, and sealed designs to operate in sterile environments. They are increasingly used in biologics manufacturing, semiconductor-based medical device production, and laboratory automation. Automation in cleanrooms improves process consistency, reduces error rates, and enhances overall operational efficiency. The growing demand for high-quality, contamination-free products is accelerating adoption. For instance, in March 2025, Stäubli Robotics collaborated with Novo Nordisk to develop Sterimove, a first Grade A/B/C/D-compatible mobile robot for pharmaceutical cleanrooms. Its hygienic design eliminates retention areas, uses H2O2-compatible materials, preserves laminar airflow, and offers modular flexibility with a compact footprint for automated material transport in aseptic production.
The medical robotic systems market faces significant cost-related challenges that are likely to hinder broader adoption, especially in healthcare settings with tight budgets. Surgical robots typically entail substantial upfront costs, as well as expenses for installation, integration, and operating room modifications. Hospitals must also account for recurring costs such as maintenance contracts, software upgrades, and disposable instruments per procedure. In price-sensitive markets and mid-sized healthcare facilities, these costs limit adoption despite clinical benefits.
Similarly, pharma and cleanroom robots require specialized designs, validation processes, and compliance with stringent regulatory standards, increasing initial expenditure. These costs are particularly challenging for small- and mid-sized hospitals, contract manufacturers, and facilities in emerging markets, where budget constraints limit investment in advanced automation technologies. As a result, adoption remains concentrated in large healthcare institutions and well-funded pharmaceutical companies.
Price ranges of medical & healthcare robots (USD)
Robot Model
Manufacturer
Price in USD
Surgical Robots - Minimally invasive, orthopedic, and specialty surgery systems
da Vinci 5
Latest generation, 2024Intuitive Surgical (US)
USD 2,000,000 - USD 2,500,000
Hugo RAS System
Robotic-Assisted SurgeryMedtronic (Ireland / US)
~USD 1,500,000 - USD 2,000,000
Mako SmartRobotics
Orthopedic systemStryker (US)
USD 800,000 - USD 1,400,000
Pharma Robots - GMP-compliant robots for drug manufacturing, packaging, and lab automation
LBR Med / LBR iiwa
Medical-certified cobotKUKA (Germany)
~USD 61,000 - USD 75,000
Stericlean TX2-40 / TX2-60
Pharma-grade 6-axisStäubli (Switzerland)
~USD 80,000 - USD 130,000
Cleanroom Robots - ISO-certified robots for sterile environments in healthcare, medical device & biotech
TX2-60 CR / SCR
ISO Class 2 (SCR) / Class 4 (CR)Stäubli (Switzerland)
~USD 60,000 - USD 120,000
Motoman HC Series (Cleanroom)
Collaborative cleanroom cobotYaskawa Electric (Japan)
~USD 40,000 - USD 60,000
Source: Secondary Research, Grand View Research Analysis
Telesurgery, enabled by 5G and low-latency satellite communication, addresses the global shortage of specialized surgeons and disparities in healthcare access. Specialists can now perform life-saving procedures for patients in rural or underserved areas without travel. Manufacturers are developing modular systems that operate across long distances, decentralizing specialized care and establishing a new service-based economy for remote medical consultation and intervention. For instance, in April 2025, SS Innovations performed robotic cardiac telesurgery using the SSI Mantra 3 system, connecting Gurugram to Aster CMI Hospital in Bengaluru.
Moreover, in November 2025, SS Innovations International introduced MantrAsana, the world’s first portable Tele Surgeon Console, which enables remote procedures without a full operating room. Recent advancements demonstrate that latency and connectivity challenges are being effectively addressed, facilitating the development of commercial Telesurgery Centers that function as hubs for regional and international surgical expertise.
1. Telesurgery in China
China leads in large-scale clinical use of 5G-enabled telesurgery. Its extensive geography and advanced network infrastructure help connect coastal medical centers with inland hospitals.
• Multicenter Randomized Controlled Trial (Dec 2023 - June 2024): A study published in The BMJ in March 2026 reported on 72 patients across five Chinese cities, including Beijing, Harbin, and Urumqi. Surgeons in Beijing performed prostatectomies and nephrectomies on patients up to 2,800 km away using the Edge Medical MP1000 robotic system. The study found that telesurgery matched local surgery in success rates and safety.
• Remote Robotic Eye Surgery (November 2025): Surgeons at Sun Yat-sen University Zhongshan Ophthalmic Center in Guangzhou performed a remote retinal injection on a patient in Urumqi, over 4,000 km away. The procedure, requiring micron-level precision, was completed in under seven minutes using a stable 5G connection.
• Intercontinental Gastrectomy (July 2025): The Chinese University of Hong Kong and Renji Hospital performed an intercontinental tele-robotic gastrectomy over 20,000 km, connecting Hong Kong and London. The locally developed robotic platform demonstrated that ultra-long-distance latency can be managed for complex abdominal surgeries.
Market Concentration & Characteristics
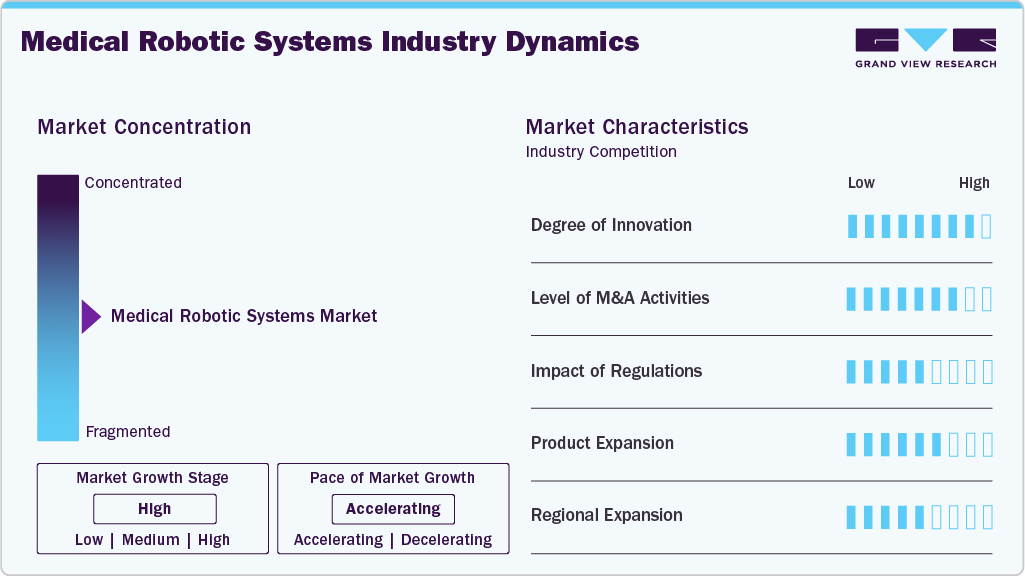
The industry is marked by a high degree of innovation, driven by advancements in artificial intelligence, machine learning, and high-definition imaging technologies. These innovations enhance surgical precision, flexibility, and control, allowing for minimally invasive procedures with improved patient outcomes. Continuous research and development efforts are leading to more sophisticated, user-friendly robotic systems, expanding their application across various surgical specialties and boosting market growth. For instance, in April 2026, UC San Diego Health performed the West Coast's first AI robotic spine surgery using a new platform integrating AI, 3D imaging, patient-specific implants, navigation, and robotic screw delivery.
“This platform fundamentally changes how we think about spine surgery. For the first time, we are bringing together artificial intelligence, data-driven alignment planning, patient-specific implants, navigation, and robotic screw delivery within a single system. That level of precision and coordination allows us to operate more efficiently while significantly enhancing safety for our patients.”
- Joseph Osorio, MD, PhD, neurosurgeon at UC San Diego Health
The industry is witnessing a high level of mergers and acquisitions (M&A) activity. Major healthcare and technology companies are acquiring smaller, innovative firms to enhance their product portfolios and leverage advanced technologies. For instance, in July 2025, Zimmer Biomet announced a definitive agreement to acquire Monogram Technologies for approximately USD 177 million, aiming to expand its robotics portfolio with semi- and fully autonomous surgical technologies and strengthen its position in AI-enabled orthopedic robotics.
 To learn more about this report, Download Free Sample Report
Regulations significantly impact the industry by ensuring safety, efficacy, and quality. Stringent approval processes by regulatory bodies such as the FDA and CE mark requirements can delay market entry, but also build trust and reliability. Compliance with these regulations demands substantial investment in research and development. However, successful navigation of regulatory frameworks enhances market credibility, encourages adoption by healthcare providers, and ultimately drives market growth.
Product expansion involves introducing new and advanced robotic solutions tailored to various surgical specialties. For instance, in April 2026, SS Innovations launched next-generation surgical robotic technologies, including the SSi Vimana Aero drone system and SSi Avtara humanoid platform, highlighting advancements in remote surgery, battlefield care, and mobile robotic operating environments at SMRSC 2026.
“Innovation is in our DNA. Beyond continuously improving our advanced, cost-effective SSi Mantra surgical robotic system and telesurgery capabilities, we strive to pioneer new surgical robotic technologies that will meaningfully improve healthcare for a wider segment of patients in need. SMRSC 2026, our largest conference yet, successfully elevated this important theme.”
- Dr. Sudhir Srivastava, Chairman of the Board and Chief Executive Officer of SS Innovations
Global expansion is driven by increasing adoption in emerging economies, improved healthcare infrastructure, and supportive government policies. Companies are targeting regions like Asia-Pacific, Latin America, and the Middle East, leveraging local partnerships and investments to tap into growing demand and enhance their international market presence. For instance, in January 2026, American Hospital Dubai deployed the da Vinci 5 robotic surgical system, marking the region’s first installation and expanding advanced robotic surgery capabilities, enabling enhanced surgical precision, improved tissue handling, and broader adoption of minimally invasive procedures.
Recent Key Regulatory Approvals in the Medical Robotic Systems Market:
Market players pursue approvals to enhance product capabilities and expand market access.
Key players undergoing strategic initiatives
Companies
Year
Month
Details
CMR Surgical
2026
March
CMR Surgical initiated the U.S. commercial launch of its Versius Plus robotic system following FDA clearance, expanding access to minimally invasive surgery and building on more than 45,000 procedures performed in more than 30 countries worldwide.
CMR Surgical
2026
March
CMR Surgical initiated the U.S. commercial launch of its Versius Plus robotic system following FDA clearance, expanding access to minimally invasive surgery and building on more than 45,000 procedures performed in more than 30 countries worldwide.
Medtronic
2026
February
Medtronic received FDA clearance for its Stealth AXiS surgical system, integrating planning, navigation, and robotics into a single platform for spine surgery, enabling real-time anatomical tracking and improving surgical precision, workflow efficiency, and clinical decision-making.
"The Stealth AXiS system is designed to make advanced technology more usable and clinically meaningful, helping surgeons deliver more predictable, personalized care while laying the foundation for continued innovation."
-said Michael Carter, Senior Vice President and President of Medtronic Cranial & Spinal Technologies.Intuitive Surgical
2026
January
Intuitive Surgical received FDA clearance for its da Vinci 5 system for selected cardiac procedures, expanding minimally invasive surgical capabilities through advanced imaging, data integration, and enhanced robotic precision to improve clinical outcomes and support broader adoption.
“Da Vinci 5 marks the beginning of a global initiative to help transform cardiac care”
- said Intuitive’s global vice president of cardiac, Darla Hutton.Johnson & Johnson
2026
January
Johnson & Johnson submitted its OTTAVA robotic surgical system to the FDA for De Novo classification, supported by IDE clinical study data, marking a significant step toward the commercialization of its next-generation soft-tissue robotic platform.
Zimmer Biomet
2025
November
Zimmer Biomet received FDA clearance for ROSA Knee with OptimiZe, an enhanced robotic-assisted system enabling personalized surgical planning, improved alignment, and reduced variability, supporting more accurate, efficient, and reproducible outcomes in total knee replacement procedures.
Medtronic
2025
December
Medtronic received FDA clearance for its Hugo robotic-assisted surgery system for urologic procedures, enabling expanded access to minimally invasive care through a modular design, integrated digital ecosystem, and enhanced surgical flexibility within U.S. healthcare systems.
"This is an incredibly exciting day for healthcare in the United States. FDA clearance of the Hugo RAS system means there is now a choice for hospitals looking to expand their robotic programs and increase access for patients."
-said Rajit Kamal, vice president and general manager of Robotic Surgical Technologies within the Surgical business of Medtronic.
Analyst Perspective
The industry includes rehabilitation robots, pharmacy automation, cleanroom robots, and autonomous medical service robots. Increasing demand for minimally invasive procedures, healthcare workforce shortages, aging populations, and investments in smart hospitals are accelerating adoption across healthcare settings. Competition is shifting toward integrated robotic ecosystems that combine artificial intelligence, computer vision, autonomous navigation, cloud connectivity, and advanced analytics to improve clinical and operational efficiency. While established companies leverage comprehensive product portfolios, strong regulatory expertise, and global service networks, specialized players are driving innovation through application-specific robotic solutions. Vendors capable of delivering interoperable, AI-enabled platforms supported by robust clinical validation, lifecycle services, and scalable automation technologies are expected to strengthen their competitive position as healthcare providers continue to invest in digital transformation and intelligent automation.
Type Insights
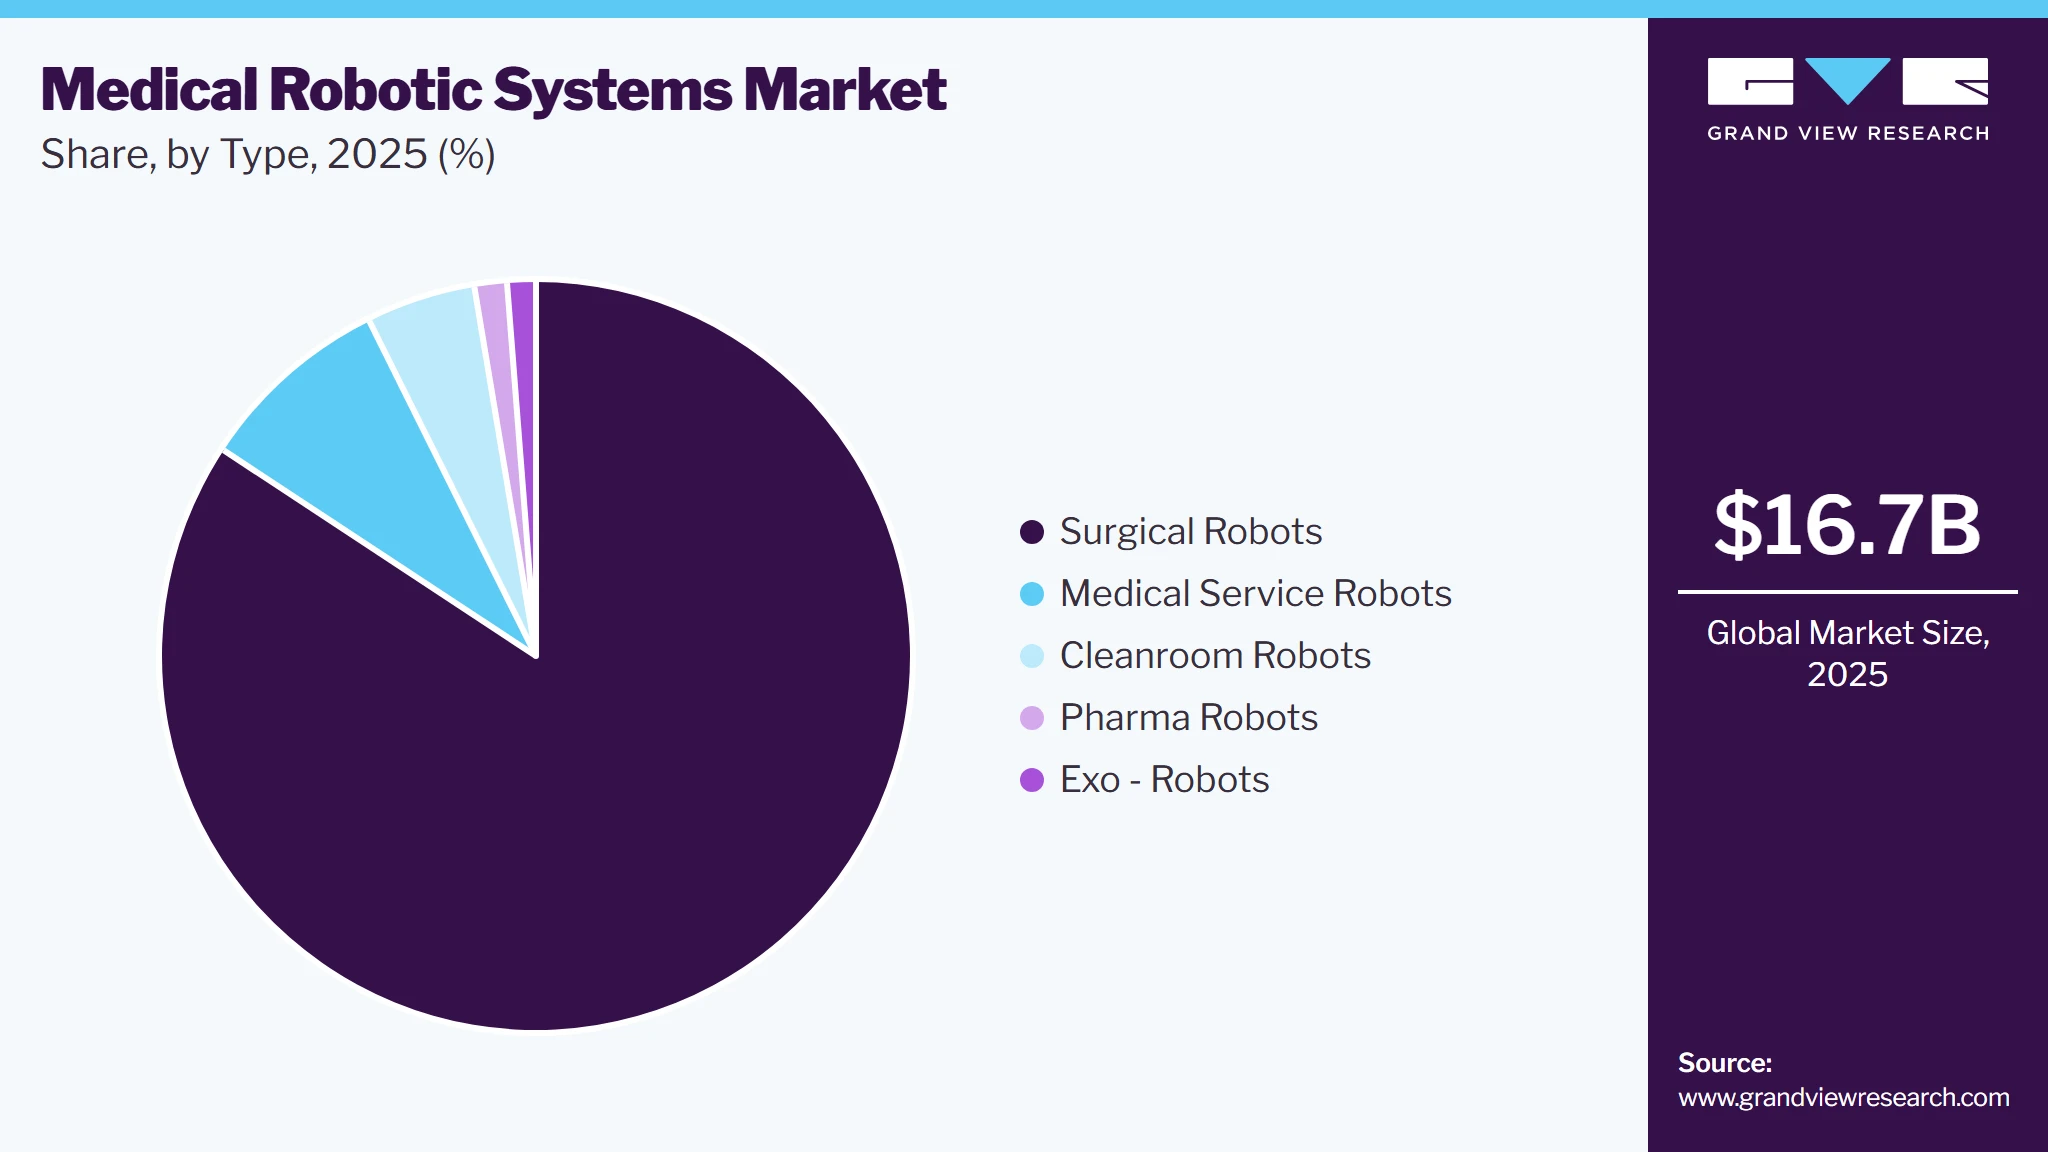
The surgical robots segment held the largest share of 84.3% in 2025. These systems are designed to assist surgeons in performing minimally invasive procedures with enhanced precision, dexterity, and visualization. Robotic platforms integrate advanced imaging, instrument articulation, and real-time controls to improve surgical accuracy.
 To learn more about this report, Download Free Sample Report
Moreover, technological advancements are expanding the capabilities and applications of surgical robots across healthcare settings. Integration of AI, machine learning, and image-guided navigation is improving intraoperative decision-making and workflow efficiency. For instance, in April 2026, Medtronic received CE mark approval for its Stealth AXiS surgical system, an AI-powered platform integrating planning, navigation, and robotics for spine and cranial surgeries, enabling broader access to next-generation surgical technologies across European hospitals.
"The introduction of the Stealth AXiS system to Europe reflects our focus on delivering connected platforms that improve precision, efficiency, and consistency across diverse healthcare systems"
-said Michael Carter, Senior Vice President and President of Cranial & Spinal Technologies at Medtronic
The cleanroom robots segment is projected to grow at the fastest CAGR during the forecast period. Clean-room robots are designed to operate in controlled environments with stringent contamination standards. These systems are widely deployed in pharmaceutical & biopharmaceutical manufacturing, biotechnology labs, and medical device production units where sterility is critical. They support aseptic processing tasks such as vial filling, packaging, and material transfer while minimizing human intervention. Compliance with ISO cleanroom classifications and GMP requirements drives adoption across regulated facilities. Demand is further supported by increasing biologics production and the need for contamination-free workflows.
Regional Insights
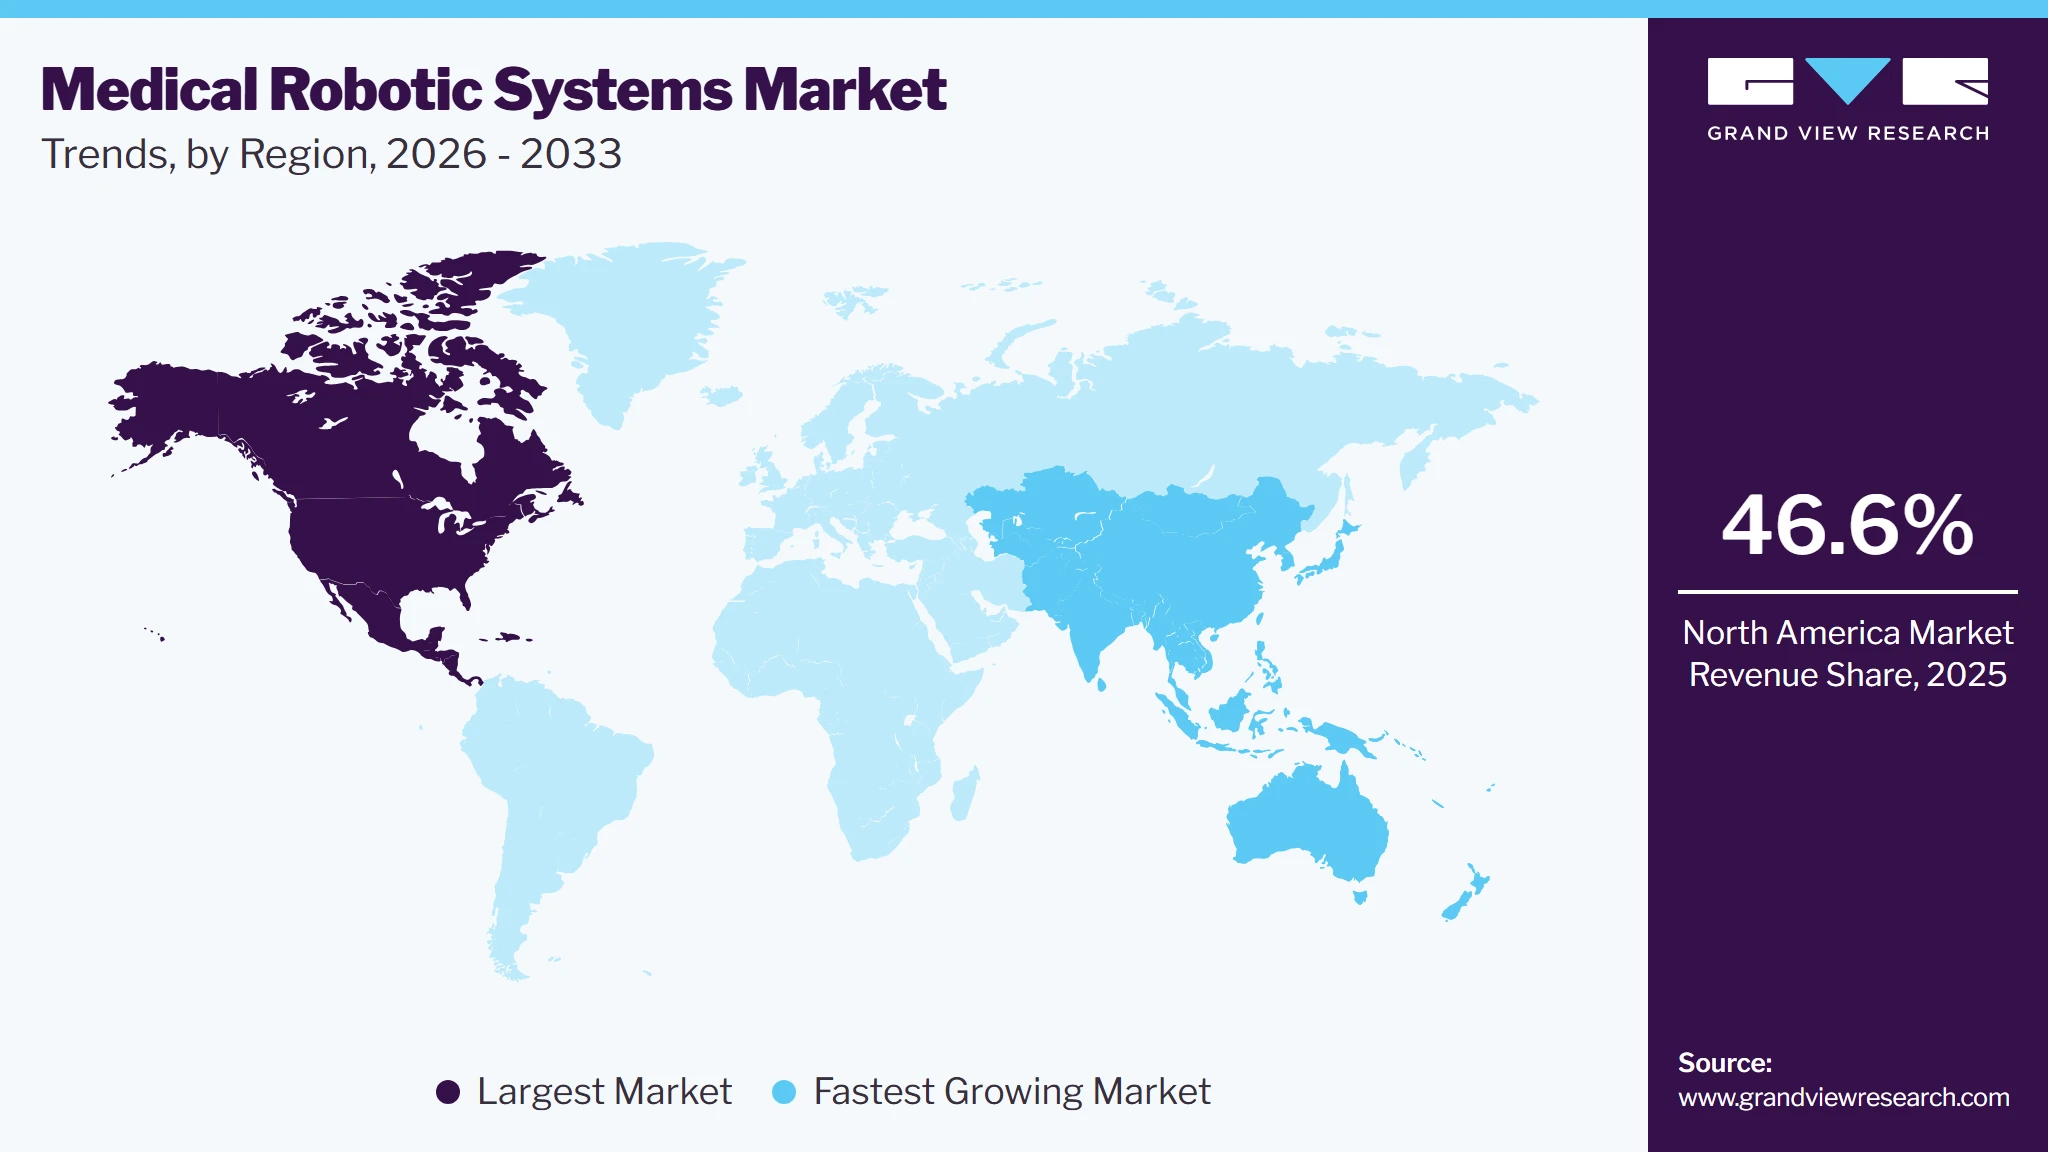
The North America medical robotic systems market held the largest share, at 46.6%, in 2025. High procedural volumes, a growing geriatric population, and a high burden of chronic diseases are primary factors driving the North America medical and healthcare robotics market. The U.S. performs a substantial number of surgical procedures, including orthopedic, neurological, cardiovascular, and oncologic interventions, in which robotic-assisted systems improve precision and reduce complications.
 To learn more about this report, Download Free Sample Report
Canada’s publicly funded healthcare system is expanding minimally invasive surgery programs to manage wait times and improve outcomes, supporting the adoption of surgical robots. In Mexico, rising private healthcare investment and medical tourism are accelerating the uptake of advanced surgical technologies in tertiary hospitals.
U.S. Medical Robotic Systems Market Trends
The medical robotic systems market in the U.S. held a significant share of the North American market in 2025, driven by substantial investments in advanced technologies. High surgical volumes, favorable reimbursement, and strong clinical preference for minimally invasive procedures are driving the adoption of surgical robotics in the U.S. For instance, in March 2026, Golden Valley Memorial Healthcare completed the world's first knee replacement using THINK Surgical's TMINI miniature robotic system with Stryker Triathlon Knee implants. Similarly, in March 2026, Novant Health launched a robotic mitral valve repair program through its Heart & Vascular Institute. This expanded access to minimally invasive heart surgery across the Carolinas at specialized centers improves patient outcomes through advanced robotic precision.
“This program represents a significant step forward for Novant Health and for patients across the Carolinas. Robotic mitral valve repair strengthens our ability to provide leading-edge, minimally invasive heart care. It reinforces our position as a destination for complex cardiac surgery and reflects our ongoing investment in innovation that benefits our patients.”
-Howard L. Haronian, MD, FACC, physician in chief of the Novant Health Heart & Vascular Institute.
Europe Medical Robotic Systems Market Trends
The medical robotic systems market in Europe is growing rapidly, driven by increasing adoption of AI-integrated surgical platforms that combine planning, navigation, and robotic execution to improve surgical precision, efficiency, and patient outcomes. This growth is further supported by the EU Medical Device Regulation (EU MDR), which ensures standardized approval and the safe deployment of advanced robotic systems across diverse healthcare systems. Moreover, the increasing number of regulatory approvals for next-generation robotic systems in Europe is boosting market growth. For instance, in July 2025, Intuitive Surgical received CE mark approval for its da Vinci 5 system in Europe, expanding access to advanced robotic-assisted surgery.
The UK medical robotic systems market is expected to grow significantly over the forecast period. The rapid expansion of robotic systems across the National Health Service, with significant growth in hospital adoption and procedure volumes, is driving market growth by enhancing surgical precision, efficiency, and clinical outcomes. For instance, in February 2026, the National Health Service launched an AI and robotics pilot program for lung cancer diagnosis, combining advanced imaging analysis and robotically guided biopsy to improve diagnostic accuracy, reduce invasive procedures, and enhance early detection capabilities.
The medical robotic systems market in Germany is advancing rapidly with advance technologies. Companies with expertise in precision engineering and robotics are enabling the development of high-performance medical robots. In addition, rising investments in AI-driven surgical decision-support technologies are accelerating the advancement of healthcare robotics in Germany. For instance, in May 2025, Medical Decision Alliance secured USD 3.56 million (Euro 3.3 million) in seed funding to develop AI-powered systems that provide real-time, expert-guided support during surgical procedures. Such innovations enhance the intelligence and clinical capabilities of robotic platforms, enabling improved decision-making, precision, and outcomes. This trend reflects growing investor confidence and is expected to drive the integration of AI with surgical robotics, supporting next-generation smart operating environments in Germany.
Asia Pacific Medical Robotic Systems Market Trends
The medical robotic systems market in the Asia Pacific is expected to grow at the fastest CAGR during the forecast period. The increasing deployment of AI-integrated surgical robotics in emerging Asia Pacific healthcare systems is driving market growth by improving surgical precision, reducing costs, and expanding access to advanced procedures in orthopedics and general surgery. In April 2025, Vinmec Healthcare System introduced a robotic-assisted knee replacement system in Vietnam, enabling cost-effective joint replacement surgery with enhanced precision and faster patient recovery, further driving the growth of robotic systems for precision surgery.
Similarly, in February 2026, King Chulalongkorn Memorial Hospital launched AI-powered medical robots in collaboration with True Digital, enabling advanced patient care, rehabilitation, and treatment support while advancing digital hospital transformation through integrated robotics and artificial intelligence technologies.
The China medical robotic systems market is driven by the accelerating global commercialization of surgical robotics, which is expanding access across both developed and emerging healthcare systems, supported by increased regulatory approvals, international clinical validation, and hospital adoption of remote and AI-assisted surgical platforms. For instance, in October 2025, MicroPort MedBot announced that its Toumai endoscopic surgical robot had achieved over 100 global commercial orders and deployments across more than 60 countries, including landmark installations in the U.S., Europe, the Middle East, Africa, and Asia, with usage in leading hospitals and expansion into remote robotic surgery and multinational training ecosystems.
The medical robotic systems market in Japan is witnessing the launch of technologically advanced products by key players. The convergence of AI, digital twin technology, and industrial robotics is accelerating the evolution of next-generation healthcare and industrial robotics systems by enabling higher adaptability, precision, and automation efficiency through real-time intelligent decision-making and virtual-to-physical deployment. In March 2026, FANUC announced a collaboration with NVIDIA to develop “physical AI”- enabled robotic systems using NVIDIA Jetson, Omniverse, and Isaac Sim platforms, enabling manufacturers to train, simulate, and deploy intelligent robots through digital twins, significantly improving automation flexibility, production efficiency, and operational scalability.
Latin America Medical Robotic Systems Market Trends
The medical robotic systems market in Latin America is expected to grow significantly over the forecast period. Rising investment in healthcare infrastructure and gradual modernization of hospital systems are key drivers in Latin America. Countries such as Brazil and Argentina are expanding private healthcare networks and upgrading surgical capabilities to improve clinical outcomes. Adoption of surgical robots is increasing in large urban hospitals seeking to enhance precision and attract medical tourism. In parallel, pharmaceutical manufacturing in the region is becoming more sophisticated, driving demand for automation and robotics to meet quality and regulatory standards.
Middle East & Africa Medical Robotic Systems Market Trends
The medical robotic systems market in the Middle East & Africa is growing, with healthcare providers adopting advanced robotic technologies to enhance surgical precision, improve patient outcomes, and effectively meet the region's healthcare needs. Countries such as Saudi Arabia, the UAE, and South Africa are investing heavily in advanced medical technologies as part of broader healthcare transformation programs. Moreover, rising focus on healthcare quality, efficiency, and capacity expansion is further accelerating adoption. Governments are promoting digital health and advanced technologies to address the growing disease burden and improve patient outcomes.
Key Medical Robotic Systems Company Insights
The scenario in the medical robotic systems market is highly competitive, with the presence of key players such as Medtronic, Stryker, Smith & Nephew, Johnson & Johnson, Siemens Healthineers, and ABB. These major companies are adopting various strategies, such as product launches, collaborations, acquisitions, mergers, and regional expansion to serve the unmet needs of their customers.
Key Medical Robotic Systems Companies
The following key companies have been profiled for this study on the medical robotic systems market.
-
Intuitive Surgical
-
Medtronic
-
Stryker
-
Zimmer Biomet
-
Smith & Nephew
-
Johnson & Johnson
-
Siemens Healthineers
-
ABB
-
Kawasaki Heavy Industries Ltd.
-
Yaskawa Electric Corporation
-
FANUC America Corporation
-
Denso Corporation
-
Ekso Bionics
-
CMR Surgical
-
Asensus Surgical
-
Distalmotion
-
Vicarious Surgical
-
Wearable Robotics
-
Rehab-Robotics Company Limited
-
ExoAtlet
-
MARSI BIONICS, S.L
-
ABLE Human Motion
-
Bioservo
-
Wandercraft
-
Autonomyo
-
INNOPHYS CO., LTD.
-
Universal Robots A/S
-
Omnicell, Inc.
-
Aethon, Inc.
-
Serve Robotics
-
UVD Robots
-
Hstar Technologies
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Intuitive Surgical, Medtronic, Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Siemens Healthineers, ABB, Kawasaki Heavy Industries Ltd., Yaskawa Electric Corporation, FANUC America Corporation, Denso Corporation, Omnicell, Inc.)
- Expand medical robotics portfolios through strategic acquisitions, continuous product innovation, and partnerships with hospitals, rehabilitation centers, pharmaceutical manufacturers, and healthcare systems. Invest in robotic-assisted surgery, orthopedic robotics, rehabilitation robotics, pharmacy automation, autonomous logistics, cleanroom automation, AI-enabled navigation, computer vision, digital surgery platforms, and smart hospital technologies to strengthen leadership across surgical, pharmaceutical, rehabilitation, and hospital automation applications.
- Strong global market presence, extensive installed base, comprehensive robotics portfolios spanning surgical, rehabilitation, pharmaceutical, and medical service applications, and well-established relationships with healthcare providers. Significant R&D investments, advanced AI and automation capabilities, global manufacturing infrastructure, regulatory expertise, and extensive service networks enable enterprise-scale deployments and recurring revenue through software, consumables, maintenance, and service contracts.
- High capital investment requirements, lengthy regulatory approval processes, and complex implementation may limit adoption among smaller healthcare facilities and resource-constrained markets. Sophisticated robotic platforms require specialized training, infrastructure upgrades, and ongoing maintenance, increasing total cost of ownership and procurement timelines.
Emerging & Specialized Players (Ekso Bionics, CMR Surgical, Asensus Surgical, Distalmotion, Vicarious Surgical, Wearable Robotics, Rehab-Robotics Company Limited, ExoAtlet, MARSI BIONICS, S.L., ABLE Human Motion, Bioservo, Wandercraft, Autonomy, INNOPHYS CO., LTD., Universal Robots A/S, Aethon, Inc., Serve Robotics, UVD Robots, Hstar Technologies)
- Focus on specialized robotic solutions for minimally invasive surgery, rehabilitation, wearable exoskeletons, autonomous hospital logistics, UV disinfection, pharmacy automation support, and collaborative robotics. Leverage AI-enabled automation, modular system architectures, cloud connectivity, human-robot collaboration, lightweight robotic designs, and strategic partnerships with healthcare providers to accelerate adoption across niche clinical and operational applications.
- Greater agility in developing application-specific robotic systems tailored to surgery, rehabilitation, hospital logistics, and patient mobility. The ability to rapidly introduce innovative robotic platforms with flexible deployment models, lower infrastructure requirements, and specialized clinical functionality enables penetration into underserved healthcare segments and outpatient care settings.
- Smaller installed base, limited financial resources, and narrower global commercial and service networks compared with multinational robotics leaders. Limited long-term clinical validation, fewer regulatory approvals, and restricted manufacturing scale may slow adoption by large healthcare systems and multinational procurement organizations.
Recent Developments
-
In March 2026, Stäubli Robotics launched the TX2-60L MedX Ready medical robot, a high-precision six-axis system designed for surgical and clinical applications, offering enhanced safety, reliability, and intuitive manual guidance for advanced medical device integration.
-
In March 2026, Smith & Nephew introduced advancements in handheld robotic systems, including the CORI platform and robotic shoulder arthroplasty solutions, highlighting enhanced surgical precision, personalized pre-operative planning, and improved workflow efficiency across orthopedic procedures at AAOS 2026.
-
In February 2026, Stryker introduced the Mako RPS handheld robotic system for total knee procedures, expanding its Mako robotics portfolio and enabling enhanced surgical precision through an intuitive, robotically guided power tool integrated with its SmartRobotics platform.
-
In February 2026, CritiCare Asia Hospitals launched the CORI Robotic System for joint replacement surgeries, expanding its robotic orthopedics capabilities and enabling enhanced surgical precision, personalized treatment planning, and improved patient recovery outcomes across its hospital network.
-
In January 2026, Serve Robotics acquired Diligent Robotics to expand its autonomy platform into healthcare, enabling the deployment of AI-powered hospital assistant robots, such as Moxi, to improve clinical workflow efficiency and patient support.
-
In September 2025, Swisslog Healthcare, a leading provider of hospital transport and pharmacy automation, announced a strategic alliance with Diligent Robotics to bring autonomous last‑mile delivery robots to U.S. hospitals. The partnership integrated Diligent’s Moxi autonomous mobile manipulation robots with Swisslog’s existing automation, including TransLogic pneumatic tube systems, to create end‑to‑end logistics for medications, supplies, and specimens.
“For our customers who have been asking for reliable, efficient last-mile delivery robots that integrate seamlessly with existing workflows, this cooperative effort with Diligent Robotics allows us to connect them with a proven solution for smarter and safer deliveries that staff and patients trust"
-Ray Castro, Director of Strategic Programs for Transport Automation at Swisslog Healthcare
Medical Robotic Systems Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 16.7 billion
Market size value in 2026
USD 20.3 billion
Revenue forecast in 2033
USD 55.1 billion
Growth rate
CAGR of 15.3% from 2026 to 2033
Actual Data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type; Region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Intuitive Surgical; Medtronic; Stryker; Zimmer Biomet; Smith & Nephew; Johnson & Johnson; Siemens Healthineers; ABB; Kawasaki Heavy Industries Ltd.; Yaskawa Electric Corporation; FANUC America Corporation; Denso Corporation; Ekso Bionics; CMR Surgical; Asensus Surgical; Distalmotion; Vicarious Surgical; Wearable Robotics; Rehab-Robotics Company Limited; ExoAtlet; MARSI BIONICS, S.L; ABLE Human Motion; Bioservo; Wandercraft; Autonomyo; INNOPHYS CO.,LTD.; Universal Robots A/S; Omnicell, Inc.; Aethon, Inc.; Serve Robotics; UVD Robots; Hstar Technologies
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Robotic Systems Market Report Segmentation
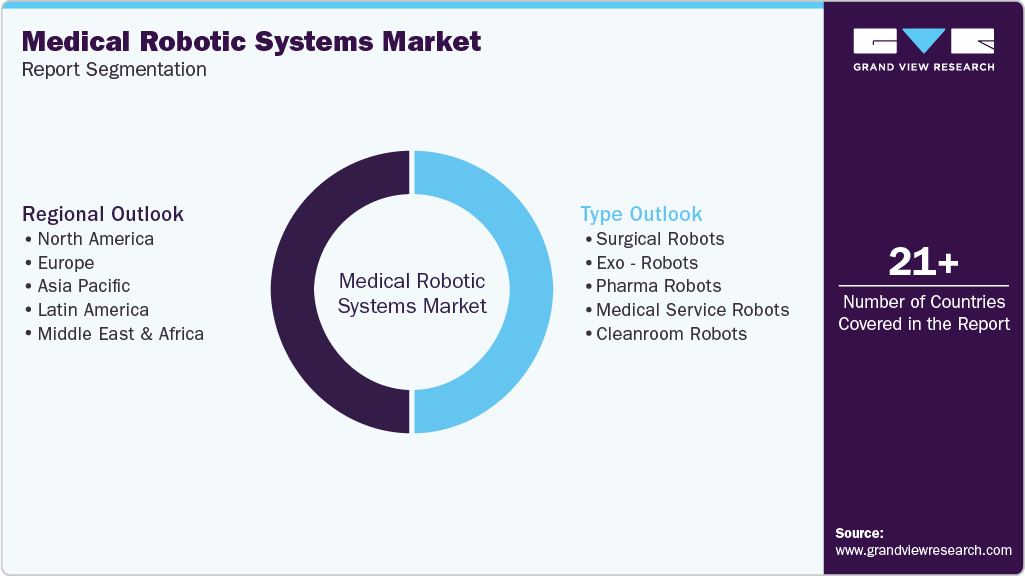
This report forecasts revenue growth at the global, regional & country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical robotic systems market report on the basis of type and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Surgical Robots
-
Surgical Robots, By Application
-
General Surgery
-
Gynecology
-
Urology
-
Orthopedic Surgery
-
Neurosurgery
-
Cardiac Surgery
-
Bariatric
-
Bronchoscopy/Pulmonary
-
Others
-
-
-
Exo-Robots
-
Exo-Robots, By Extremities
-
Upper Body
-
Lower Body
-
Full Body
-
-
-
Pharma Robots
-
Traditional Robots
-
Articulated Robots
-
Delta/Parallel Robots
-
SCARA Robots
-
Dual-Arm Robots
-
Cartesian Robots
-
-
Collaborative Robots
-
-
Medical Service Robots
-
Dispensing Robots
-
Disinfection Robots
-
Delivery Robots
-
Medical Telepresence Robots
-
Robotic Nurse Assistants
-
Others
-
-
Cleanroom Robots
-
Traditional Robots
-
Articulated Robots
-
SCARA Robots
-
Parallel Robots
-
Cartesian Robots
-
-
Collaborative Robots
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
-
Research Methodology
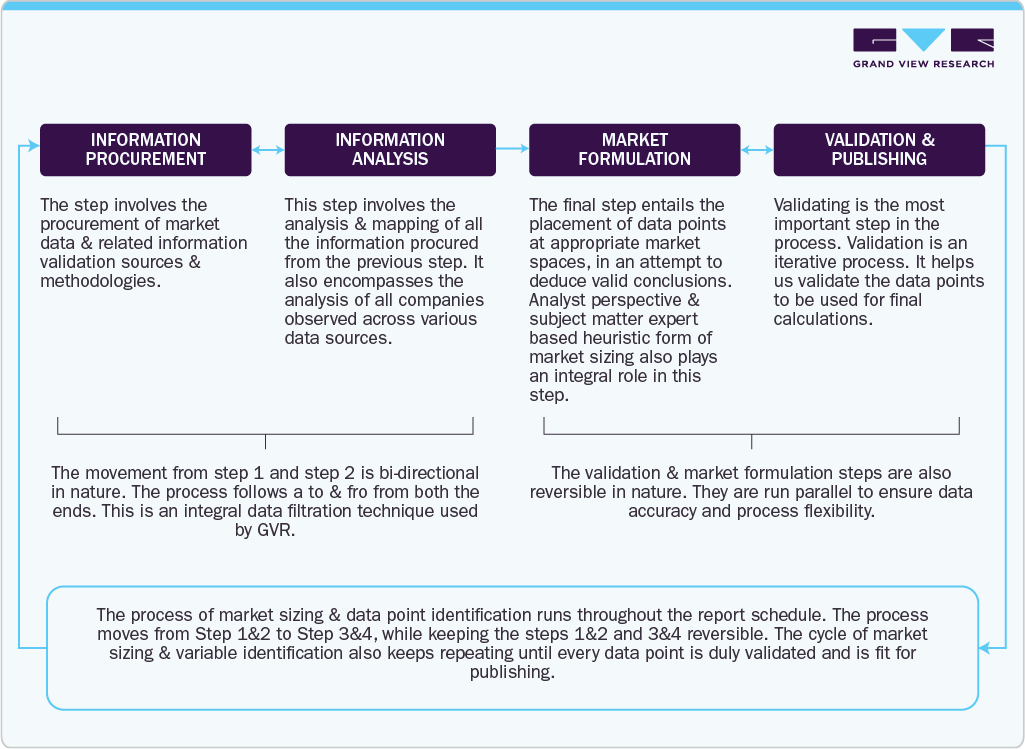
The medical robotic systems market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical robotic systems segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Surgical Robots
Robotic systems designed to assist surgeons in performing minimally invasive and complex surgical procedures with enhanced precision, dexterity, visualization, and control. These systems typically comprise a surgeon console, patient-side robotic arms, imaging systems, and advanced software, and are used across specialties such as general surgery, urology, gynecology, orthopedics, neurosurgery, and cardiothoracic surgery.
Exo-Robots
Wearable robotic exoskeletons developed to augment, assist, or restore human movement and mobility. These robotic systems support gait training, rehabilitation, mobility assistance, and physical therapy for patients with spinal cord injuries, stroke, neurological disorders, musculoskeletal impairments, and age-related mobility limitations in clinical and home care settings.
Pharma Robots
Robotic systems deployed across pharmaceutical research, drug development, manufacturing, laboratory automation, and pharmacy operations. These robots perform tasks such as high-throughput screening, sample preparation, liquid handling, drug dispensing, packaging, labeling, quality inspection, and material handling to improve operational efficiency, precision, and regulatory compliance.
Cleanroom Robots
Robotic systems specifically designed to operate within controlled cleanroom environments while maintaining stringent contamination control standards. These robots are used in pharmaceutical manufacturing, medical device production, biotechnology laboratories, sterile compounding, and cell and gene therapy manufacturing for material handling, aseptic processing, inspection, packaging, and laboratory automation.
Medical Service Robots
Autonomous or semi-autonomous robots that assist healthcare professionals with non-surgical clinical, logistical, and patient support tasks. This segment includes disinfection robots, delivery robots, telepresence robots, robotic nurse assistants, dispensing robots, and other service robots that enhance workflow efficiency, reduce caregiver workload, improve infection control, and support patient care across hospitals, clinics, and long-term care facilities.
Estimation Model
 To learn more about this report, Download Free Sample Report
Market-specific Research Models
Consensus-Based Estimates & Forecasting
The medical robotic systems market presents emerging to dominant opportunities, featuring global key players such as Intuitive Surgical; Medtronic; Stryker; Zimmer Biomet; Smith & Nephew; Johnson & Johnson; Siemens Healthineers; ABB; Kawasaki Heavy Industries Ltd.; Yaskawa Electric Corporation; FANUC America Corporation; Denso Corporation; Ekso Bionics; CMR Surgical; Asensus Surgical; Distalmotion; Vicarious Surgical; Wearable Robotics; Rehab-Robotics Company Limited; ExoAtlet; MARSI BIONICS, S.L; ABLE Human Motion; Bioservo; Wandercraft; autonomy; INNOPHYS CO.,LTD.; Universal Robots A/S; Omnicell, Inc.; Aethon, Inc.; Diligent Robotics (Serve Robotics); UVD Robots; Hstar Technologies. To ensure a holistic approach, the GVR research team adopted a comprehensive methodology, considering multiple companies worldwide and utilizing various variables for data accuracy.
Our methodology included:
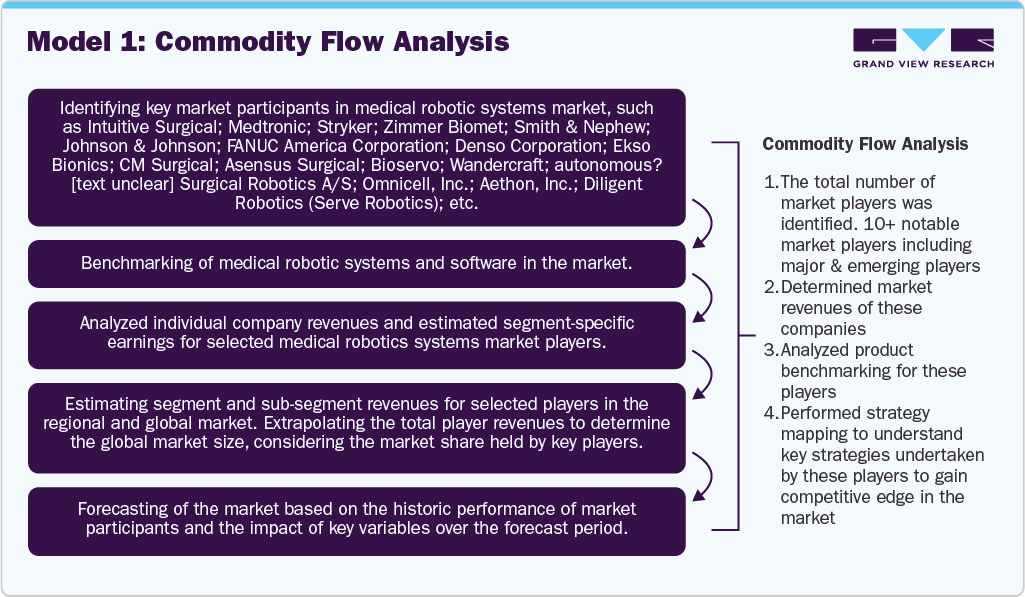
Model 1: Commodity Flow Analysis - For public players, annual reports were referenced. For private players, premium paid data sources such as S&P Global, Crunchbase, ZoomInfo, RocketReach, etc., were used for the latest revenue insights.
Model 2: Parent Market Analysis
Model 3: Country-level Multivariate Analysis Assumptions
Model 4: Segment-level Multivariate Analysis Assumptions
Model 5: Medical Robotic Systems Market CAGR Calculations
 To learn more about this report, Download Free Sample Report
Commodity flow analysis was employed to track the movement of medical robotic systems through the value chain, from technology providers to end users. This analysis provided insights into demand generation points, intermediary roles, and ultimate consumption patterns.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Medical Robotic Systems Adoption & Healthcare Automation Analysis
Developed a tailored analysis of the global medical robotic systems market focused on surgical robots, exoskeleton robots, pharmacy robots, cleanroom robots, and medical service robots. The study assessed adoption trends across hospitals, ambulatory surgical centers (ASCs), rehabilitation centers, pharmacies, long-term care facilities, life sciences manufacturing facilities, and research institutions while evaluating increasing demand for minimally invasive procedures, workforce shortages, healthcare automation, precision medicine, and digital transformation initiatives driving market growth.
Enables stakeholders to understand evolving medical robotics adoption trends, identify high-growth robotic system categories, assess opportunities across clinical and non-clinical healthcare environments, and evaluate the impact of robotic technologies on patient outcomes, operational efficiency, workforce productivity, and long-term market expansion.
Robotics Innovation, AI Integration & Clinical Workflow Assessment
Delivered a customized evaluation of medical robotic systems across robotic-assisted surgery, rehabilitation and mobility assistance, pharmacy automation, aseptic pharmaceutical manufacturing, hospital logistics, disinfection, material handling, and patient support applications. The analysis assessed advancements in artificial intelligence (AI), computer vision, autonomous navigation, robotic arms, collaborative robots (cobots), digital imaging integration, haptic technologies, IoT connectivity, and cloud-based robotic management platforms. Additionally, it evaluated technology innovations, clinical adoption patterns, and product development strategies from leading companies including Intuitive Surgical, Medtronic, Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Siemens Healthineers, ABB, Kawasaki Heavy Industries, Yaskawa Electric, FANUC America, DENSO Corporation, Ekso Bionics, CMR Surgical, Asensus Surgical, Distalmotion, Vicarious Surgical, Wearable Robotics, Rehab-Robotics Company, ExoAtlet, MARSI BIONICS, ABLE Human Motion, Bioservo, Wandercraft, Autonomy, INNOPHYS, Universal Robots, Omnicell, Aethon, Diligent Robotics, UVD Robots, and Hstar Technologies.
Provides actionable insights into commercially attractive robotic segments, emerging automation technologies, evolving healthcare requirements, and growth opportunities associated with precision surgery, rehabilitation, pharmaceutical automation, infection prevention, intelligent logistics, improved workflow efficiency, and next-generation smart healthcare ecosystems.
Medical Robotics Ecosystem, Regulatory Environment & Competitive Landscape Assessment
Conducted a focused assessment of the medical robotic systems ecosystem, including robotic hardware manufacturing, AI software platforms, sensors, control systems, hospital and pharmacy integration, cleanroom automation infrastructure, cybersecurity, regulatory approval pathways, reimbursement frameworks, and competitive positioning. The analysis evaluated implementation challenges, capital investment requirements, interoperability standards, technology adoption barriers, service and maintenance models, strategic collaborations, product innovation initiatives, and competitive differentiation among leading market participants including Intuitive Surgical, Medtronic, Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Siemens Healthineers, ABB, Kawasaki Heavy Industries, Yaskawa Electric, FANUC America, DENSO Corporation, Ekso Bionics, CMR Surgical, Asensus Surgical, Distalmotion, Vicarious Surgical, Wearable Robotics, Rehab-Robotics Company, ExoAtlet, MARSI BIONICS, ABLE Human Motion, Bioservo, Wandercraft, Autonomy, INNOPHYS, Universal Robots, Omnicell, Aethon, Diligent Robotics, UVD Robots, and Hstar Technologies.
Supports strategic planning for robotic platform development, healthcare automation initiatives, manufacturing investments, regulatory compliance, healthcare partnerships, geographic expansion, and market entry strategies by identifying adoption drivers, operational challenges, infrastructure requirements, revenue opportunities, innovation priorities, and competitive advantages across the global medical robotic systems value chain.
Frequently Asked Questions About This Report
North America dominated the medical robotic systems market held the largest share of 46.6% in 2025.
The medical robotic systems market in Asia Pacific is expected to grow at the fastest CAGR during the forecast period.
The global medical robotic systems market size was estimated at USD 16.7 billion in 2025 and is expected to reach USD 20.3 billion in 2026.
Key factors that are driving the medical robotic systems market growth include increasing demand for accurate laparoscopic surgeries, growing need for surgical procedures in the geriatric population, and rising cases of trauma injuries.
The global medical robotic systems market is expected to grow at a compound annual growth rate of 15.3% from 2026 to 2033 to reach USD 55.1 billion by 2033.
The surgical robots segment held the largest share of 84.3% in 2025. Market growth is driven by the rising adoption of robotic-assisted minimally invasive procedures, increasing demand for surgical precision, and growing use of advanced robotic instruments and accessories across hospitals and surgical centers.
Some key players operating in the medical robotic systems market include Intuitive Surgical, Medtronic, Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Siemens Healthineers, ABB, Kawasaki Heavy Industries Ltd., Yaskawa Electric Corporation, FANUC America Corporation, Denso Corporation, Ekso Bionics, CMR Surgical, and Asensus Surgical.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


