
- Home
- »
- Pharmaceuticals
- »
-
Migraine Drugs Market Size & Share Report, 2026-2033GVR Report cover

Migraine Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Treatment (Acute, Preventive), By Therapeutic Class, By Route Of Administration, By Age Group (Pediatric, Adult, Geriatric), By Availability, By Region, And Segment Forecasts
Market Size, 2025
$7.9BMarket Estimate, 2026
$8.9BMarket Forecast, 2033
$16.6BCAGR, 2026–2033
9.2%Migraine Drugs Market Summary
The global migraine drugs market size was valued at USD 7.9 billion in 2025 and is projected to grow from USD 8.9 billion in 2026 to USD 16.6 billion by 2033, growing at a CAGR of 9.2% from 2026 to 2033. North America dominated the global market with the largest revenue share of 40.3% in 2025. Increasing prevalence of migraines is a major factor contributing to the market growth.
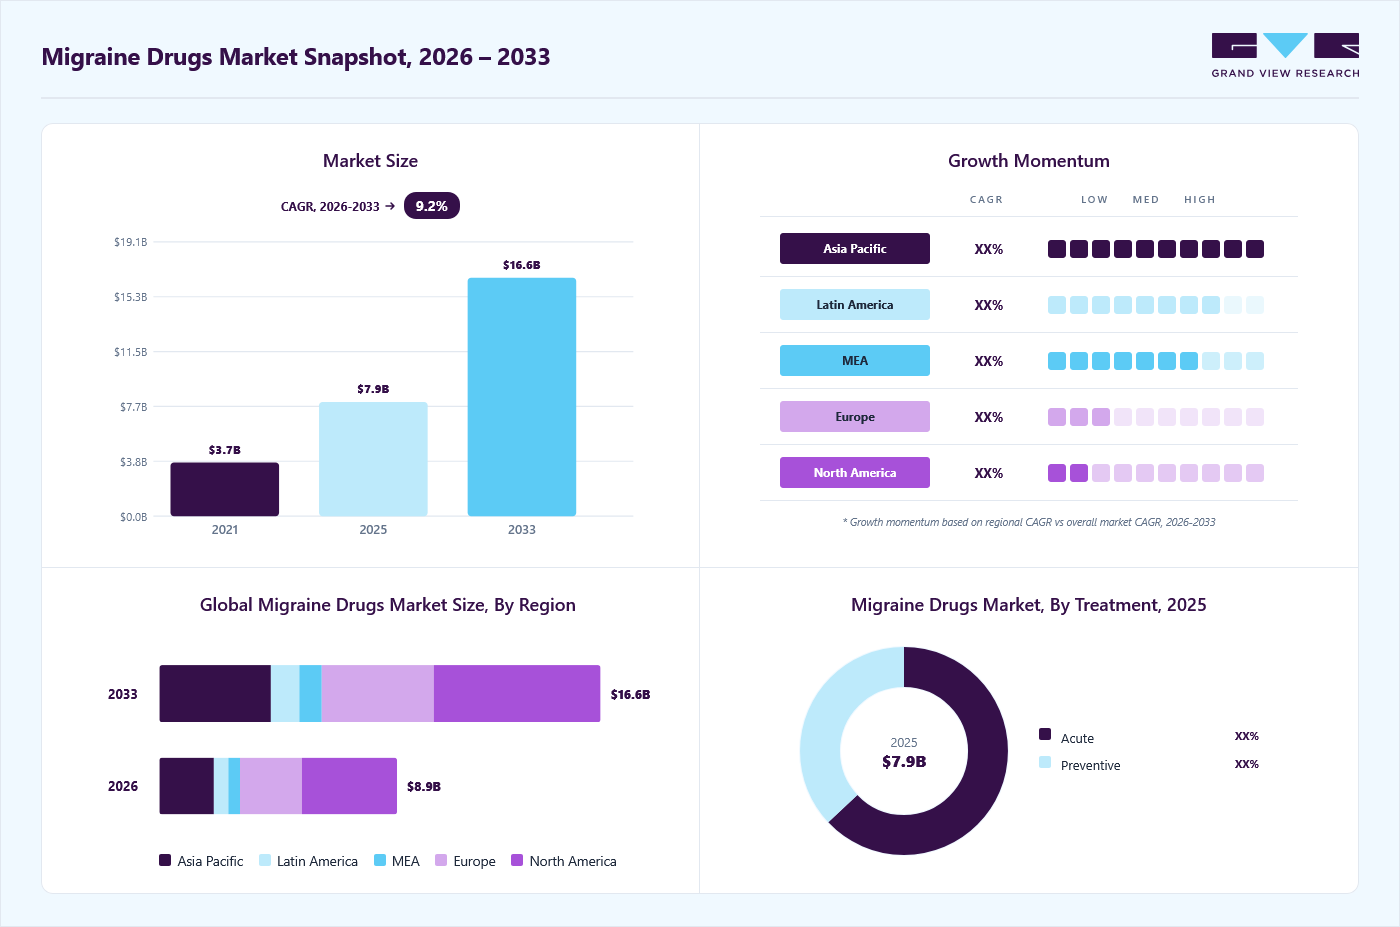 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By therapeutic class: CGRP monoclonal antibodies segment led the market with the largest revenue share of 55.3% in 2025.
- By route of administration: Injectable segment led the market with the largest revenue share of 73.1% in 2025.
- By treatment: Preventive segment led the market with the largest revenue share of 37.1% in 2025.
Regional Highlights
- Largest regional market: North America (40.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.9 Billion
- Estimated market size in 2026: USD 8.9 Billion
- Projected market size by 2033: USD 16.6 Billion
- CAGR (2026-2033): 9.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Migraines are the sixth-leading cause of disability-adjusted life years (DALY) worldwide. According to an article of 2024, NIH migraine ranks as the second leading cause of disability after back pain worldwide. According to an article of National Institute of Neurological Disorders and Stroke published on January 2025, adult females are more likely affected than adult males . Headache disorders consistently rank among the top three most frequent neurological conditions across various age groups, beginning as early as age 5 and maintaining this status until the age of 80. Advancements in drug development and a growing awareness and diagnosis in the market. Moreover, increasing investment by public and private organizations is further propelling growth.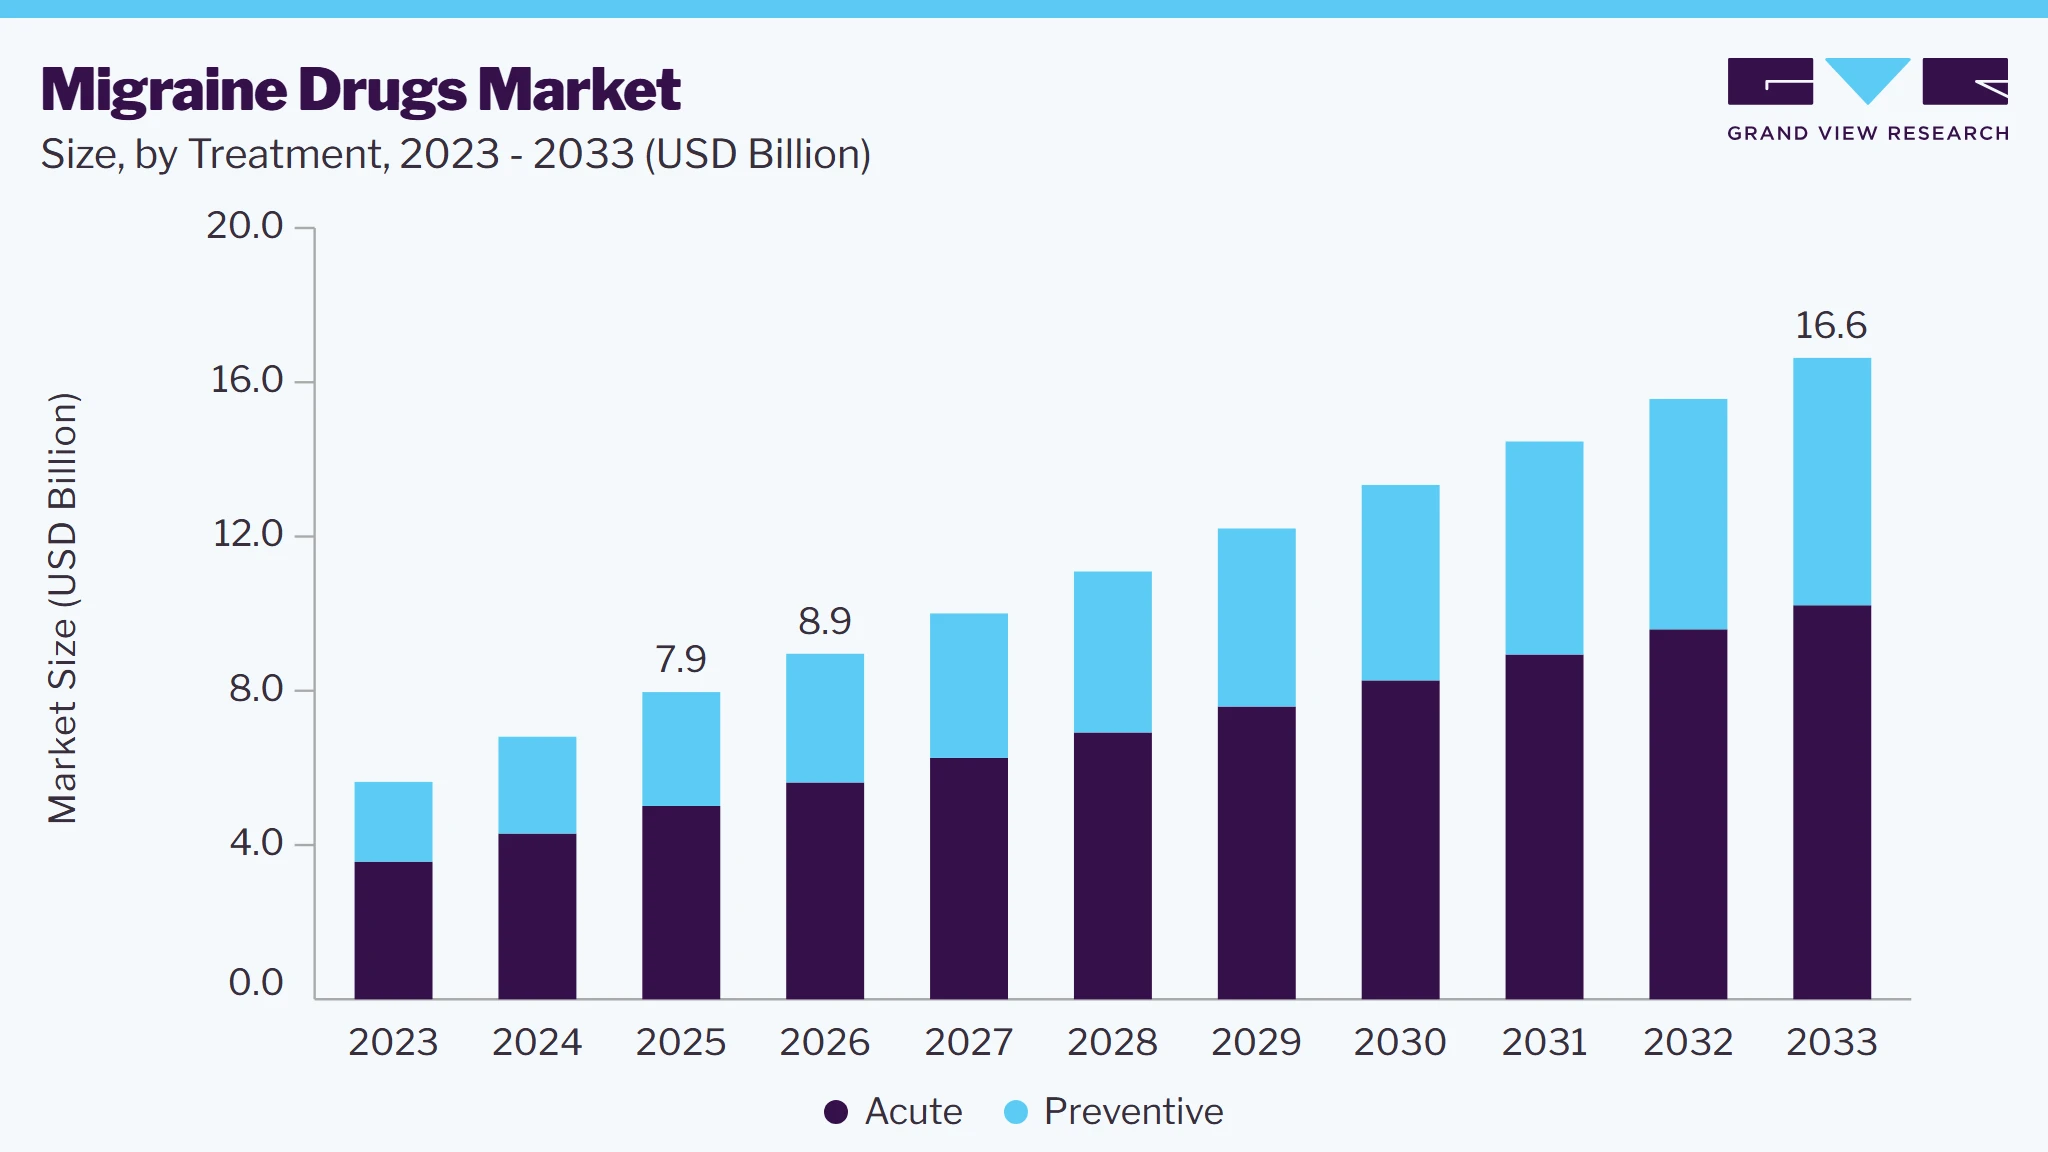 To learn more about this report, Download Free Sample Report
Advancements in drug development fuel the market growth.CGRP monoclonal antibodies, such as fremanezumab (Ajovy), erenumab (Aimovig), and galcanezumab (Emgality), are among the latest preventative drug therapies for migraines. According to the WebMD article published in February 2023, these drugs are administered via self-injection about every month, providing a targeted approach to treating migraines by blocking the release of CGRP, a neuropeptide implicated in migraine pain. Another drug in this class, eptinezumab (Vyepti), is given via intravenous injection every three months. The FDA has granted approval for small molecule CGRP antagonists, such as rimegepant (Nurtec) and atogepant (Qulipta), marking significant advancements in migraine treatment. These approvals represent a breakthrough in the management of migraine, offering new options for both acute and preventive therapy .
Adoption of the small molecule CGRP antagonists. According to the NCBI article published in September 2022, Ubrogepant and rimegepant, colloquially referred to as gepants, have completed phase III studies and are now FDA-approved for the acute treatment of migraine with or without aura. These small-molecule CGRP-receptor inhibitors have shown efficacy and safety, with no signs of hepatic injury. Rimegepant is also approved for the prevention of migraine.
Another inhibitor, atogepant, approved in 2021, is a daily oral medication used for EM prevention. There has been a significant push towards improving the delivery and tolerability of these treatments. This includes the development of intranasal forms for proven treatments and non-invasive neuromodulation techniques. These advancements aim to address the limitations of current therapies, such as adverse events, medication overuse, and intolerance to certain delivery methods or regimens.
Growing awareness and diagnosis of migraine disease requires a comprehensive strategy that encompasses various elements, including education, advocacy, and the establishment of support networks. According to American Migraine Foundation article published in June 2023, during Migraine and Headache Awareness Month, the American Migraine Foundation launched the "GET HEADUCATED" campaign, which underscores the significance of educating both oneself and others about migraine. This initiative is geared towards rallying the community to combat stigma surrounding the condition and to promote understanding of the disease.
Moreover, for instance, in January 2023, the International Classification of Headache Disorders (ICHD-3) offers a thorough framework for the diagnosis of migraine, organizing it into six distinct categories and outlining specific criteria for each classification. This system provides detailed guidelines for healthcare professionals to accurately identify migraine based on symptoms, duration, frequency, and associated features. In addition, tools like the ID Migraine Screener are utilized within this diagnostic framework to assess key migraine-related symptoms such as photophobia, functional impairment, and nausea. These screening tools aid in the efficient and accurate diagnosis, facilitating appropriate management and treatment strategies for individuals affected by this condition.
Market Dynamics
The migraine drugs market is driven by the increasing prevalence of migraine disorders, growing awareness of preventive therapies, and continued investment in targeted treatments. Pharmaceutical companies are focusing on expanding clinical evidence and improving treatment outcomes to increase physician adoption and patient access. An important market dynamic is the shift toward calcitonin gene related peptide based therapies, which are designed specifically for migraine prevention and treatment. To illustrate this trend, pharmaceutical manufacturers are actively investing in comparative clinical studies to demonstrate the value of their products over conventional therapies. For instance, in 2025, AbbVie announced positive Phase 3 clinical trial results for Qulipta (atogepant) in a comparative study against topiramate, a widely used generic migraine preventive therapy. The study showed lower treatment discontinuation rates and higher rates of migraine day reduction among patients receiving Qulipta. Through this initiative, AbbVie strengthened the clinical positioning of its migraine portfolio and supported broader adoption of targeted preventive therapies, which contributes to market expansion. Furthermore, ongoing research activities and increasing investment in innovative migraine treatments are expected to sustain growth across the global migraine drugs market.
The growth of the migraine drugs market is primarily driven by the increasing adoption of calcitonin gene related peptide based therapies for both preventive and acute migraine treatment. These therapies have gained significant attention due to their ability to address migraine specific pathways, offering improved efficacy and tolerability compared to several conventional treatment options. Growing awareness among healthcare professionals regarding the long term benefits of preventive migraine management is further supporting the uptake of targeted therapies. In addition, increasing diagnosis rates and greater patient willingness to seek medical treatment for chronic migraine are contributing to market expansion. Pharmaceutical companies are also investing in clinical research and regulatory activities to strengthen evidence supporting the use of CGRP targeted drugs across broader patient populations. For instance, in 2025, Teva Pharmaceuticals announced that the U.S. Food and Drug Administration approved an expanded indication for AJOVY (fremanezumab vfrm), making it the first anti CGRP preventive treatment approved for pediatric patients aged 6 to 17 years with episodic migraine. The approval expanded access to CGRP based therapies and increased the eligible patient population for targeted migraine prevention, supporting the broader adoption of innovative migraine treatments. As pharmaceutical companies continue to expand indications and improve access to CGRP therapies, demand for targeted migraine drugs is expected to support sustained market growth.
The high cost associated with novel migraine therapies remains a key restraint for the migraine drugs market. While CGRP inhibitors and other targeted treatments have demonstrated clinical benefits, their pricing is substantially higher than conventional therapies such as triptans, nonsteroidal anti inflammatory drugs, and generic preventive medications. This cost difference creates affordability challenges for patients, particularly in developing economies where reimbursement coverage remains limited. In many healthcare systems, access to advanced migraine treatments is subject to strict reimbursement criteria, prior authorization requirements, or step therapy protocols that require patients to fail lower cost therapies before receiving coverage for newer drugs. These barriers can delay treatment initiation and limit overall market penetration. Furthermore, budget constraints faced by public and private healthcare payers often influence prescribing patterns, reducing the adoption of premium priced therapies despite their clinical advantages. The challenge is particularly evident in regions where out of pocket healthcare expenditure remains high. Although manufacturers continue to pursue pricing agreements and patient assistance programs, cost related concerns remain a significant factor affecting treatment accessibility. As a result, the affordability gap between innovative and traditional migraine treatments may continue to limit market growth in certain regions.
The expanding availability of migraine diagnosis and treatment services across emerging markets presents a significant opportunity for the migraine drugs market. Increasing healthcare expenditure, improving healthcare infrastructure, and growing awareness of neurological disorders are encouraging more patients to seek professional treatment for migraine conditions. Many countries in Asia Pacific, Latin America, and the Middle East are strengthening access to specialty care services, creating favorable conditions for the introduction of innovative migraine therapies. In addition, pharmaceutical companies are pursuing market expansion strategies through regulatory approvals, distribution partnerships, and physician education programs aimed at improving treatment adoption. The increasing penetration of digital health platforms is also supporting earlier diagnosis and patient engagement, helping to address historically underserved populations. As awareness of migraine as a treatable neurological condition continues to improve, demand for both preventive and acute treatment options is expected to increase. These factors are likely to create substantial growth opportunities for pharmaceutical companies looking to strengthen their presence in emerging healthcare markets.
Market Concentration & Characteristics
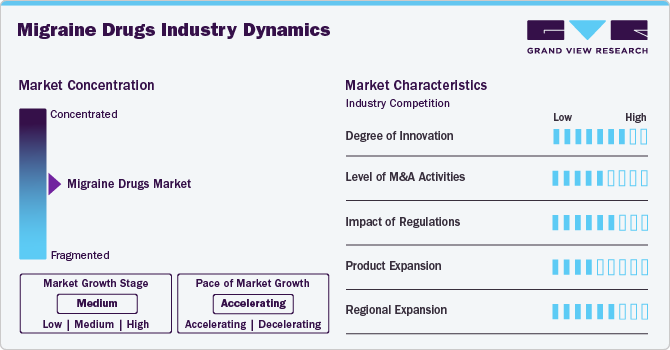
The degree of innovation is high in the market characterized by a growing level of research and development. For example, according to National Institute of Neurological Disorders and Stroke (NINDS) article of 2025, researchers are exploring new medications and treatments, including those targeting the kappa opioid receptor in the brain, which is associated with stress a known trigger for migraine attacks. Researchers are also involved in identifying the biomarkers to predict and explain outcomes of body and medicine collectively work. Also in January 2023 , innovations in migraine drug development have evolved beyond traditional triptans, introducing new medication classes targeting specific migraine triggers. One such advancement is eptinezumab, a humanized IgG1 monoclonal antibody that targets both α and β isoforms of CGRP. Administered quarterly via intravenous infusion, eptinezumab has demonstrated efficacy in reducing days and improving functionality in chronic patients.
Several players engage in mergers & acquisitions to strengthen their market position. This strategy enables companies to increase their capabilities, expand their product portfolios, and improve competency. For instance, in May 2022, Pfizer acquired Biohaven Pharmaceuticals for USD 11.6 billion, securing access to Nurtec, a CGRP inhibitor used to treat acute pain, and zavegepant, a nasal spray migraine drug candidate. This acquisition aligns with Pfizer's strategy to enhance its commercialization capabilities and broaden the availability of migraine treatments.
 To learn more about this report, Download Free Sample Report
Regulations in the migraine drugs industry set standards for safety, efficacy, and accessibility. They govern approval processes, manufacturing standards, labeling, and surveillance. Compliance is vital for companies to introduce and sustain their drugs. Regulations protect patients by minimizing risks and ensuring accurate information. Despite posing challenges, regulations maintain trust and enhance patient outcomes. In February 2025, the American College of Physicians (ACP) released updated guidelines for preventing episodic migraines in non-pregnant adults within outpatient settings. These recommendations are based on systematic reviews of pharmacologic treatments' effectiveness, patient preferences, and economic considerations.
Product substitutes include non-pharmacological treatments, alternative therapies, and lifestyle modifications. These substitutes offer relief without relying solely on medication. For instance[ , biofeedback therapy teaches relaxation techniques to manage migraine symptoms, serving as a substitute for traditional drug treatments.
Regional expansion for migraine drugs involves expanding market reach to new geographical areas beyond current operations. For example: Organon expanded its agreement with Eli Lilly to become the sole distributor and promoter of Emgality (galcanezumab) in 11 additional markets and Europe since February 2024. This expansion strategy aims to tap into previously untapped markets and increase accessibility to migraine treatments. For example, a pharmaceutical company may expand its distribution network to include regions in Asia or South America where the prevalence is high, but access to effective treatments may be limited.
Analyst Perspective
The migraine drugs market is characterized by increasing adoption of targeted therapies, particularly CGRP based treatments, across both acute and preventive migraine management. Market competition is centered on expanding product portfolios, generating clinical evidence, securing regulatory approvals, and increasing patient access across North America, Europe, and selected Asia Pacific countries. Large pharmaceutical companies leverage established commercial infrastructure, broad distribution networks, and strong brand recognition to maintain their market presence, while specialized players focus on differentiated therapies and alternative drug delivery approaches. Ongoing product launches, indication expansions, and geographic expansion activities are expected to strengthen market competition and create opportunities for both established pharmaceutical companies and emerging participants.
Treatment Insights
Based on treatment, the acute segment led the market with the largest revenue share of 62.9% in 2025. Preventive treatment involves medications and strategies aimed at reducing the frequency, severity, and duration of migraine attacks.Recent drug approvals for treatment have highlighted advancements in preventive therapies, offering new options for patients suffering from migraine. For instance in April 2023, Atogepant, an oral medication taken daily, received approval from the US FDA in 2021 for preventing episodic migraines. It marks a novel class of preventive therapy for migraine, presenting an alternative to conventional preventive treatments.
The Acute segment held the second largest market revenue share in 2024. Acute treatment encompasses various medications and strategies designed to alleviate the symptoms experienced during a migraine attack. Advancements in acute treatment have undergone significant evolution, introducing novel options characterized by enhanced efficacy, delivery methods, and tolerability. For instance, Rimegepant and Erenumab were the global first in class drugs CGRP antagonists approved in 2024, where Rimegepant was used for both acute and preventive migraine. There are other treatments including CGRP antibodies, a 5-HT1F receptor agonist, and innovative delivery methods like intranasal formulations and non-invasive neuromodulation. These advancements aim to overcome current treatment limitations such as adverse events, medication overuse, and challenges with certain delivery methods.
Therapeutic Class Insights
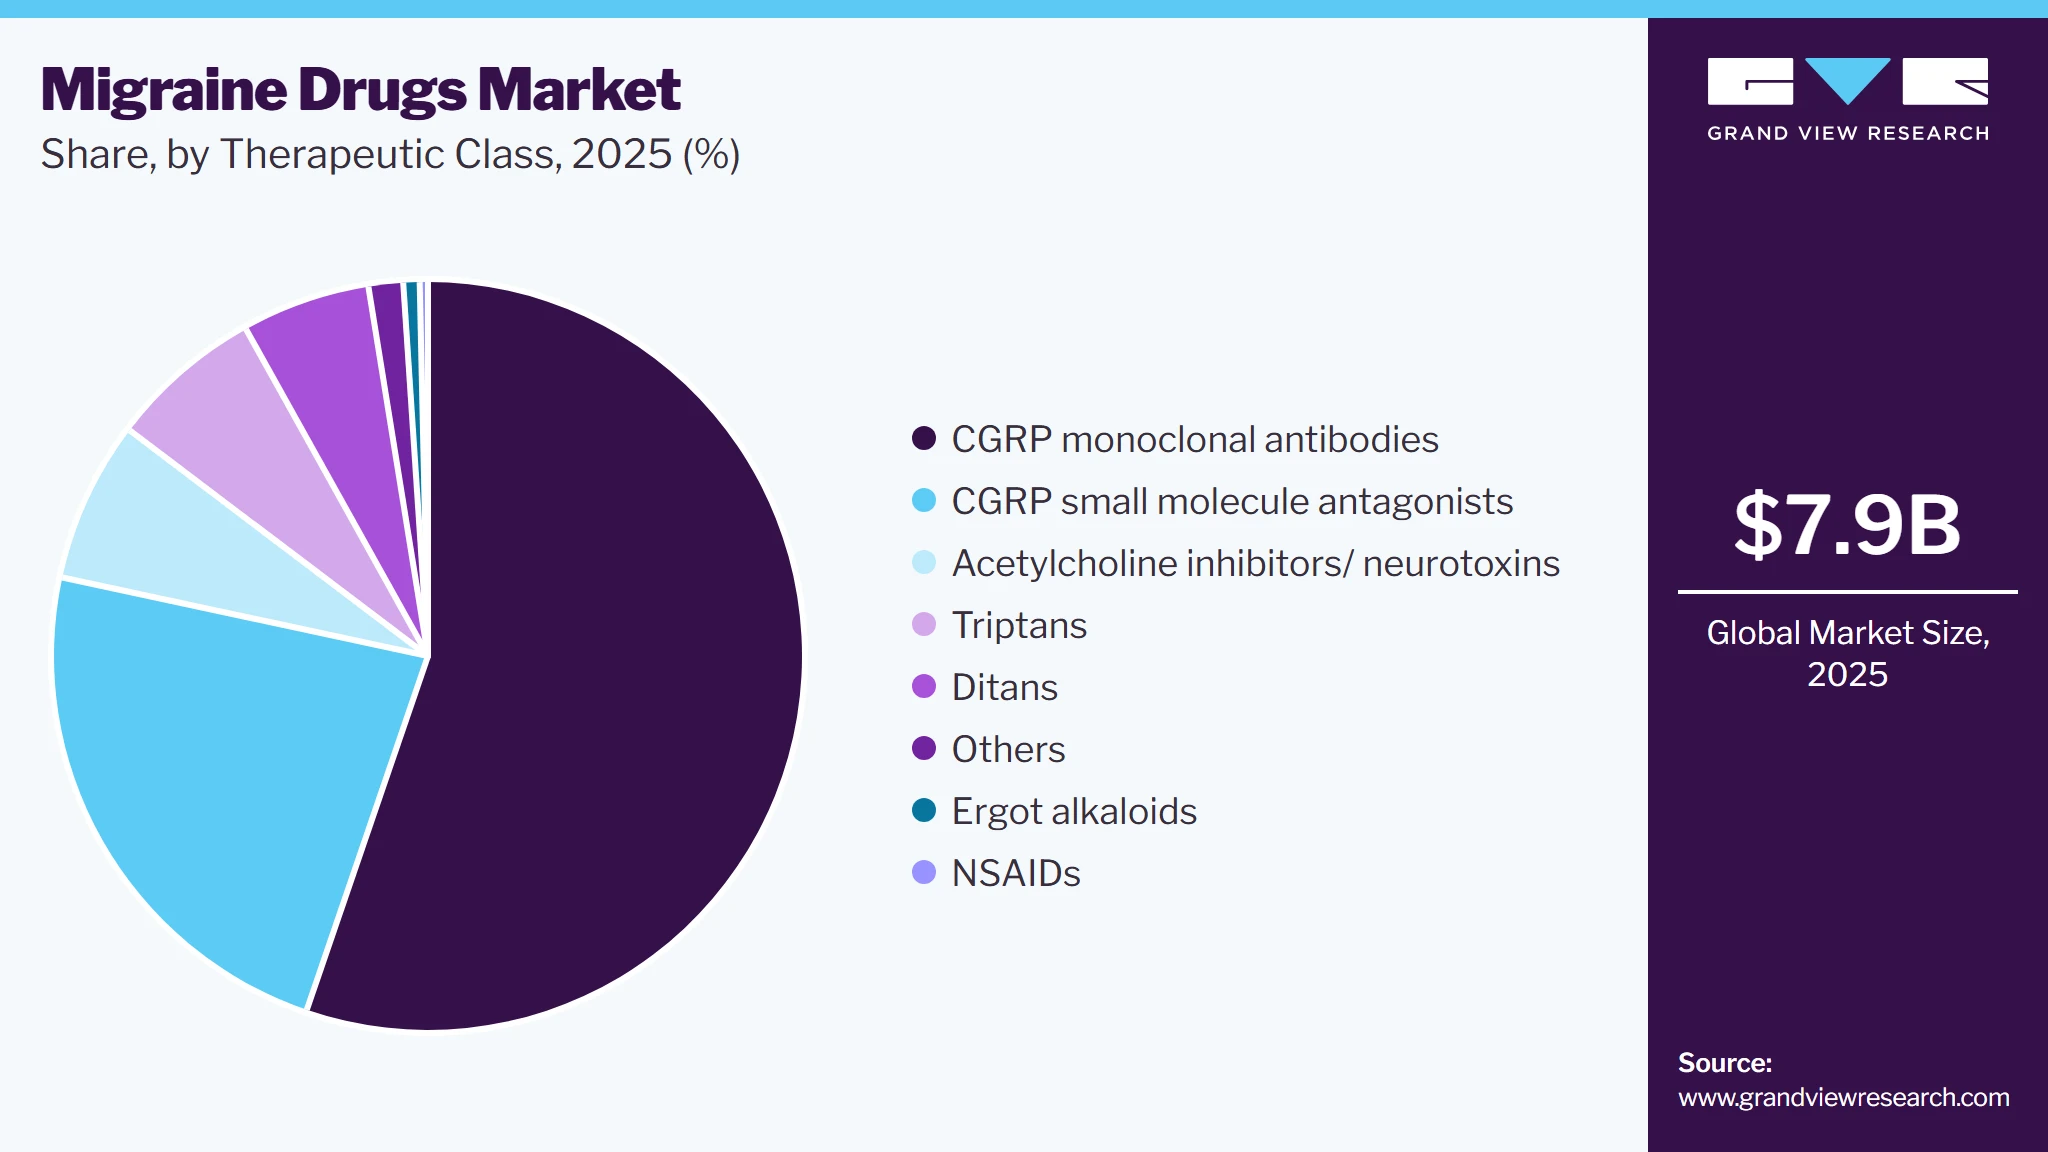
Based on therapeutic class, the CRGP monoclonal antibodies segment led the market with the largest revenue share of 55.3% in 2025. CGRP monoclonal antibodies (mAbs) have proven highly effective in preventing migraine attacks, often demonstrating efficacy rates comparable to or even higher than those of currently used preventive drugs. For instance, in July 2024,Teva Pharmaceutical Industries Ltd. announced positive results from its Phase 3 study, which evaluated the efficacy and safety of AJOVY (fremanezumab) for preventing episodic migraine in children and adolescents aged 6 to 17 years. In December 2024, AbbVie announced that the Canadian Headache Society's (CHS) updated 2024 Migraine Prevention Guideline strongly recommends atogepant for treating both episodic and chronic migraines, and onabotulinumtoxinA for chronic migraine treatment.
 To learn more about this report, Download Free Sample Report
In May 2024, QULIPTA (atogepant) was approved by Health Canada for the preventive treatment of chronic migraine in adults. It is the first and only oral calcitonin gene-related peptide (CGRP) receptor antagonist (gepant) authorized for migraine prevention across all frequencies, including both episodic and chronic migraine . This effectiveness is supported by numerous randomized clinical trials involving large patient populations. Moreover, their excellent tolerability and emerging long-term safety data highlight a remarkable balance between efficacy and adverse effects. Compared to standard prophylactic drugs for prevention, CGRP mAbs offer a more favorable profile, indicating a significant advancement in prevention by effectively reducing attack frequency and severity while minimizing common side effects associated with traditional preventive medications.
Moreover, in January 2023, CGRP monoclonal antibodies (mAbs) are associated with higher costs, yet they offer substantial benefits in terms of increasing migraine-free days and improving health-related quality of life compared to no treatment. These mAbs also lead to reductions in both direct and indirect migraine-related costs. Estimates suggest that each migraine-free day achieved with CGRP mAbs can result in savings ranging from approximately USD 130 to USD 340.
In January 2025, U.S. Food and Drug Administration (FDA) approved Symbravo, an oral combination medication developed by Axsome Therapeutics for the acute treatment of migraines. Symbravo combines meloxicamnonsteroidal anti-inflammatory drug (NSAID), with rizatriptan, a 5-HT1B/1D agonist to provide rapid and sustained relief from migraine pain.
The CGRP small molecule antagonist diagnostics segment is anticipated to grow at the fastest CAGR over the forecast period. CGRP small molecule antagonists are a class of drugs used in migraine treatment. Unlike CGRP monoclonal antibodies, which are large protein molecules administered via injections, small molecule antagonists are orally administered medications. Recent advancements in CGRP small molecule antagonists, known as gepants, for these treatment have been remarkable. For instance, in April 2023, Several drugs have received approval in recent years. Ubrelvy (ubrogepant) was approved on December 23, 2019, followed by Nurtec ODT (rimegepant sulfate) on February 27, 2020. Later, Qulipta (atogepant) received approval on September 28, 2021. Most recently, Zavzpret (zavegepant) in intranasal and oral formulations was approved on March 10, 2023. These approvals mark significant progress in preventive treatment, offering new options for managing these symptoms.
Route Of Administration Insights
Based on route of administration, the injectable segment led the market with the largest revenue share of 73.1% in 2025. Injectable migraine drugs often provide rapid and effective relief from migraine symptoms, making them a preferred choice for individuals experiencing severe or acute attacks.According to an article of NIH 2024, Satsuma Pharmaceuticals and SNBL resubmits the new drug application a new nasal formulation known as STS101, which was accessed for its safety and tolerability for acute treatment of migraine. STS101 is an investigational drug-device combination comprising a dry-powder formulation of dihydroergotamine mesylate (DHE) preloaded into a single-use nasal delivery device. Designed for ease of use, this device requires no assembly or priming and can be stored at room temperature, offering a convenient and portable option for acute migraine treatment .
Injectable medications offer a convenient option for migraine treatment, particularly for individuals who have difficulty swallowing pills or experience nausea and vomiting during migraine attacks. For instance, in February 2022, Sumatriptan injection is a medication used to offer immediate relief from migraines and cluster headache attacks. It serves as a beneficial alternative for individuals who encounter difficulty swallowing pills and can demonstrate its effectiveness in as little as 10 minutes. Available either in a vial or a kit containing all necessary supplies for injection, sumatriptan provides a convenient and rapid treatment option for those experiencing acute or cluster headache symptoms.
According to an article of April 2025, Tonix Pharmaceuticals has introduced TONIX ONE, a comprehensive digital platform aimed at enhancing migraine management. This platform integrates partnerships with UpScript Telemedicine, ProModRx, Blink Health, and a leading migraine diary app to streamline the patient journey from symptom tracking to prescription fulfillment. TONIX ONE offers educational resources on migraine, connects patients with specialists via telehealth, and facilitates e-prescription requests, simplifying and accelerating access to treatment.
The oral segment is projected to witness at a significant CAGR over the forecast period. Oral medications are widely accessible and convenient for patients to use, contributing to their popularity as a preferred treatment option for migraine.Oral drugs have been shown to effectively relieve symptoms for many individuals, providing relief from pain, nausea, and other associated symptoms.There is a wide variety of oral drugs available, including over-the-counter medications such as ibuprofen or acetaminophen, as well as prescription medications such as triptans and preventive medications like beta-blockers or anticonvulsants. For instance, in February 2023 , Rimegepant (Nurtec) and ubrogepant (Ubrelvy) are both CGRP receptor antagonists approved for the acute treatment of migraine with or without aura. These medications function by blocking the CGRP receptor, which plays a role in the sensory nerves supplying the head and neck, thereby preventing these attacks.
Age Group Insights
Based on age group, the adult segment led the market with the largest revenue share of 52.1% in 2025 and is anticipated to grow at a significant CAGR over the forecast period. Modern lifestyles characterized by stress, irregular sleep patterns, poor dietary habits, and sedentary behavior contribute to the exacerbation of migraine symptoms in adults. The need for effective treatment options to manage these symptoms drives the market growth.On November 2024, first USFDA approved, drug-free therapy of Nerivio REN wearable device which proved to transform pediatric migraine as the sole migraine-specific preventive therapy approved for children aged 8 and above. It offers benefits over traditional medications by enhancing accessibility, minimizing classroom disruptions, reducing social stigma, and promoting independence .
In September 2024, Click Therapeutics conducted the ReMMi-D trial to assess the efficacy and safety of CT-132, an investigational prescription digital therapeutic, for preventing episodic migraine in adults aged 18 and older. CT-132 is designed to be used alongside existing acute and preventive migraine treatments.
According to the NCBI article published in February 2024, a meta-analysis involving 23 case-control studies revealed that adults with migraine exhibited higher PSQI scores compared to control groups, indicating poorer sleep quality among migraine sufferers. Furthermore, findings from a randomized controlled trial (RCT) involving 31 adults in the U.S. with chronic migraine and insomnia demonstrated that participants who underwent insomnia cognitive-behavioral therapy experienced a lower frequency of headache events compared to the control group. These results suggest a potential correlation between improving sleep quality and reducing the frequency and intensity of migraine attacks in affected individuals.
The geriatric segment is anticipated to grow at a significant CAGR over the forecast period. There is growing recognition of migraine in the geriatric population, fueled by improved awareness among healthcare providers and older adults themselves. For instance, in April 2021, In older individuals, migraines can manifest differently than in younger people. Headaches associated with migraines are more likely to occur bilaterally and may exhibit less sensitivity to light and sound. In addition, migraine aura, which includes visual disturbances, can occur without the typical headache pain, necessitating careful assessment to rule out stroke, transient ischemic attack, and seizure. The occurrence of aura not including headache can increase from 6% to 16% in individuals after the age of 55. Moreover, migraine attacks in the elderly tend to start more often at night or in the early morning, with up to 60% of cases initiating during these times.
Availability Insights
Based on availability, the prescription drugs segment led the market with the largest revenue share of 77.3% in 2025 and is anticipated to grow at a significant CAGR over the forecast period. The rising prevalence of migraines globally is a significant driver for the growth of prescription drugs. As more people are diagnosed with migraines, there is a higher demand for effective medications. For instance, in February 2023, FDA-approved prophylactic agents for migraine include divalproex sodium, propranolol, topiramate, and timolol. These medications are prescribed to prevent these attacks and are taken daily. Treatment is usually initiated in patients experiencing four or more headaches per month and should be continued for at least two to three months consistently. The primary drug classes used for migraine prophylaxis are beta-blockers, calcium channel blockers, and anticonvulsants.
The Over-the-Counter (OTC) drugs segment is anticipated to grow at the fastest CAGR over the forecast period. OTC drugs are readily available without a prescription, making them convenient for consumers to purchase and use without needing to visit a healthcare provider. This accessibility encourages more people to try OTC options for managing their migraines. For instance, in August 2023, Over-the-Counter (OTC) medications can be effective, particularly when taken early during a moderate migraine attack without nausea. In addition, Sana Pharma Medical has introduced Glitinum, an over-the-counter (OTC) herbal medicine developed for the preventive treatment of migraine in adults. Glitinum contains powdered feverfew (Tanacetum parthenium), a plant traditionally used to reduce the frequency and intensity of migraine attacks .
Studies indicate that NSAIDs (Nonsteroidal Anti-Inflammatory Drugs) are widely used for headache and migraine relief without a prescription. Among them, naproxen, ibuprofen, and acetaminophen have strong evidence supporting their effectiveness in treating acute migraine attacks, especially when taken promptly after onset. In addition, a combination of acetaminophen, aspirin, and caffeine is recognized as highly effective for treating these attacks. These OTC options provide accessible and reliable relief for individuals experiencing migraine symptoms.
Regional Insights
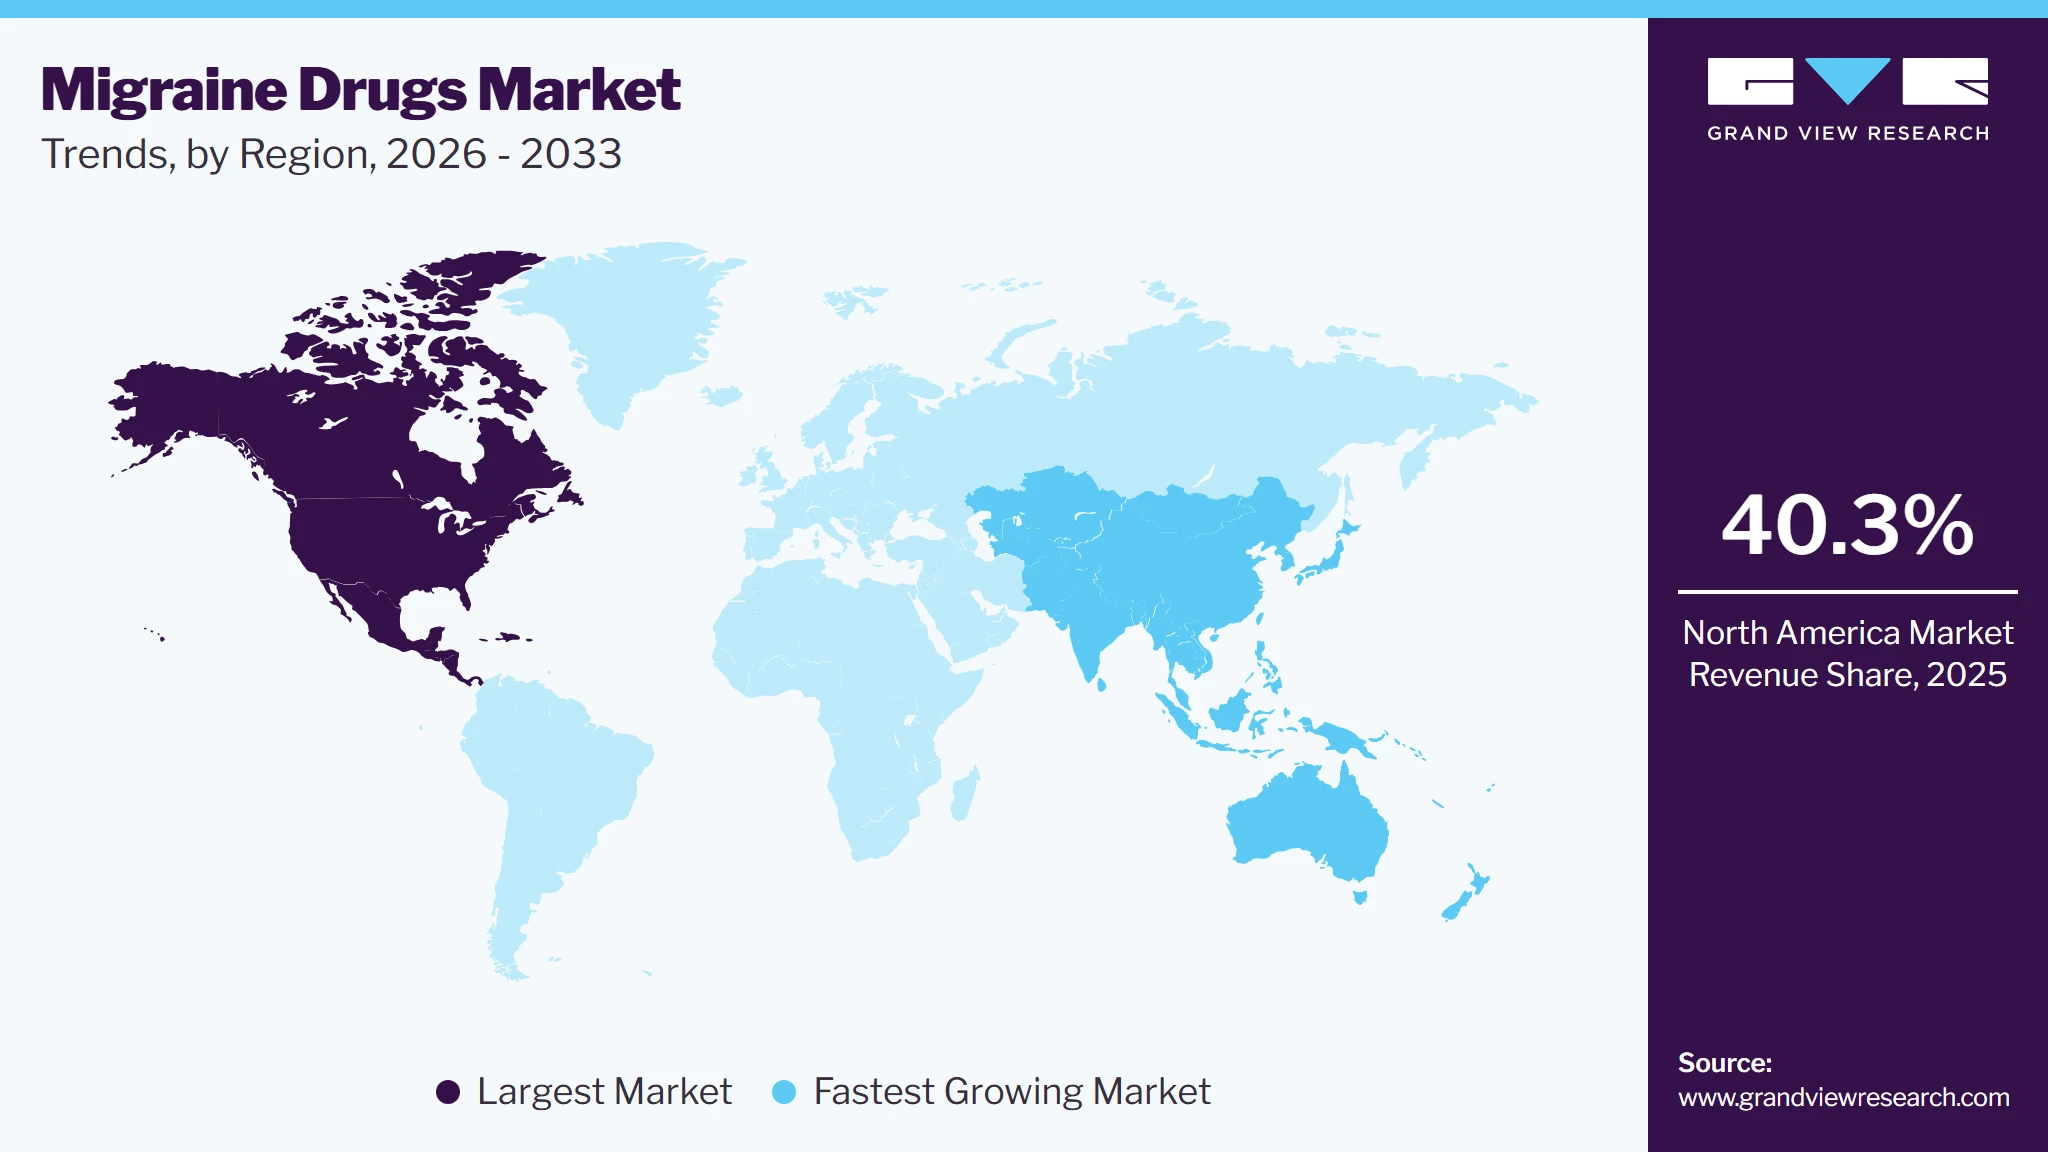
North America dominated the migraine drugs market with the largest revenue share of 40.3% in 2025, owing to migraine is a dominant neurological disorder in North America, affecting millions of people. The rising incidence of these cases in the region contributes to the market growth. For instance, in January 2024 , Migraines affect over 39 million Americans, with women being three times more likely to experience them than men. This high prevalence highlights the significant impact of migraines on the overall health and well-being of the population. The majority of those affected fall within the 35 to 45 age range, and it's estimated that 1 in every 4 American households has a member who suffers from migraines. However, despite the widespread prevalence, only half of Americans experiencing these sought medical attentions for headache-related issues in the previous 12 months. This highlights a gap in healthcare access and emphasizes the need for increased awareness and treatment options.
 To learn more about this report, Download Free Sample Report
U.S. Migraine Drugs Market Trends
The Migraine drugs market in the U.S. held the largest share in the North America region in 2025, due to improved awareness about migraines and their impact on quality of life prompts more individuals to seek medical treatment. In December 2024, Asheville-based Olfax Medical has been advancing its migraine treatment program, Relaspen, with plans to initiate clinical trials in 2025. Relaspen is a self-administered, intra-nasal therapy designed to rapidly alleviate acute migraine or cluster headaches, potentially providing relief in as little as 15 minutes. The company has secured significant funding, including a USD 5.6 million grant from the U.S. Department of Defense, to support the pre-clinical development of this innovative treatment.
Europe Migraine Drugs Market Trends
The migraine drugs market in Europe was identified as a lucrative region in this industry. The growth of the market in the region can be attributed to a significant population affected by migraines, contributing to a substantial market size for these drugs.
The UK migraine drugs market is expected to grow at a significant CAGR over the forecast period due to the presence has a well-developed healthcare infrastructure with access to a wide range of medical services and prescription medications. This facilitates the distribution and availability of migraine drugs, supporting market expansion. According to an article in January 2025, Panadol introduced Panmigrol, a triple-action formulation sub-brand offering tablets designed to provide faster and more effective migraine relief compared to standard ibuprofen tablets This innovation was aimed to be carried out at 10 million people in UK .
The migraine drugs market in France is expected to grow at a substantial CAGR over the forecast period, attributed to the stringent regulatory standards for pharmaceuticals, ensuring the safety and efficacy of drugs on the market.
The Germany migraine drugs market is expected to grow at a significant CAGR over the forecast period due to the rising number aging population, which is more susceptible to chronic conditions like migraines. As the population ages, the demand for drugs is expected to increase, driving market growth.
Asia Pacific Migraine Drugs Market Trends
The migraine drugs market in Asia Pacific is anticipated to witness at the fastest CAGR during the forecast period. Growing prevalence of the Migraine disease contributing to the growth of the market. For instance, in October 2023, across all countries, South Asia reported the highest incidence of migraine, with 12,041,286 cases, along with the highest migraine-associated Disability-Adjusted Life Years (DALYs) at 5,570,590.8. Overall, countries with higher Socio-demographic Index (SDI) values exhibited a greater disease burden of both migraine and Tension-Type Headaches (TTH).
The China migraine drugs market is expected to grow at a significant CAGR over the forecast period. For instance, in August 2023 , Migraine is a significant public health concern in China, impacting approximately 65 million individuals, which constitutes the largest migraine population in the world. This high prevalence highlights the substantial burden of on the population's health and well-being. In January 2025, Teva Pharmaceutical Industries Ltd. announced positive Phase 3 trial results for AJOVY (fremanezumab) in China, demonstrating significant efficacy in reducing monthly migraine days among adult patients. This achievement positions AJOVY to address the substantial unmet need for effective migraine treatments in a market with the largest migraine population worldwide.
In October 2024, CUHK Medical Centre (CUHKMC), FWD Hong Kong, and Pfizer Hong Kong have collaborated to enhance migraine awareness and support in Hong Kong. They have developed a health information platform on FWD's MAX lifestyle experience platform, offering a series of migraine-related resources, including a free online assessment. This initiative aims to encourage early professional consultation and effective management of migraines.
The migraine drugs market in Japan is expected to grow at a substantial CAGR over the forecast period due to the presence of one of the world's most rapidly aging populations. Migraines are more prevalent among older adults, and as the population ages, the demand for drugs is expected to increase, driving market growth. In November 2024, HUTCHMED (China) Limited announced that its partner, Takeda, has launched FRUZAQLA (fruquintinib) in Japan for patients with previously treated metastatic colorectal cancer (CRC). This follows approval by the Japanese Ministry of Health, Labour and Welfare in September 2024. FRUZAQLA is the first novel oral targeted therapy approved for metastatic CRC in Japan in over a decade. HUTCHMED will receive a milestone payment from Takeda in connection with this launch. Fruquintinib has also been approved in regions including the United States, Europe, and China.
Latin America Migraine Drugs Market Trends
The migraine drugs market in Latin America market was identified as a lucrative region in this industry. Advancements in healthcare technology and pharmaceutical innovation. These advancements lead to the introduction of new and improved migraine drugs, meeting the evolving needs of patients and driving market expansion.
The Brazil migraine drugs market is expected to grow at a significant CAGR over the forecast period. Improved awareness about migraines and advancements in diagnostic techniques lead to earlier and more accurate diagnoses in Brazil.
Middle East & Africa Migraine Drugs Market Trends
The migraine drugs market in MEA was identified as a lucrative region in this industry. The prevalence of migraines is increasing in the MEA region, driven by various factors such as lifestyle changes, stress, and genetic predisposition.
The Saudi Arabia migraine drugs market is expected to grow over the forecast period owing availability of health insurance coverage in Saudi Arabia helps increase access to medical treatments, including migraine drugs
Key Migraine Drugs Company Insights
Some of the leading players operating in the migraine drugs industry in include AbbVie Inc., Amgen Inc. and Teva Pharmaceutical Industries Ltd. Key players are using existing customer bases in the region to prioritize maintaining high-quality standards and gain high market size access. This strategy is useful for brands that have already built trust in the market. These players are heavily investing in advanced Therapeutic Class and infrastructure, allowing them to process & analyze a large volume of samples efficiently. Moreover, companies undertake various strategic initiatives with other companies and distributors to strengthen their market presence.
Impel Pharmaceuticals Inc., Tonix Medicines, Inc., Currax Pharmaceuticals LLC. and Lundbeck are some of the emerging market participants in the market. These companies focus on achieving funding support from government bodies and healthcare organizations aided with novel product launches to capitalize on untapped avenues.
Key Migraine Drugs Companies
The following are the leading companies in the migraine drugs market.
-
AbbVie Inc.
-
Amgen Inc.
-
Teva Pharmaceutical Industries Ltd.
-
GSK plc
-
Eli Lilly and Company
-
Pfizer Inc.
-
Bausch Health Companies Inc.
-
Gensco Pharma
-
Impel Pharmaceuticals Inc.
-
Tonix Medicines, Inc.
-
Currax Pharmaceuticals LLC.
-
Lundbeck
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (AbbVie Inc., Amgen Inc., Teva Pharmaceutical Industries Ltd., Eli Lilly and Company, Pfizer Inc., Lundbeck A/S, GSK plc.)
Focus on expanding migraine treatment portfolios through indication expansions, clinical development programs, regulatory approvals, and geographic expansion. Invest in CGRP targeted therapies, preventive migraine treatments, and lifecycle management strategies. Strengthen market presence through physician education initiatives, patient support programs, strategic partnerships, and reimbursement expansion efforts.
Strong research and development capabilities, established commercial infrastructure, extensive global distribution networks, broad regulatory expertise, and strong relationships with healthcare providers and payers. Market leadership is supported by well established migraine brands, robust clinical evidence, and significant financial resources that enable continuous innovation and market penetration.
Exposure to patent expiration risks, increasing pricing pressure from healthcare payers, stringent regulatory requirements, and growing competition from generic products and emerging migraine therapies. Dependence on key branded products may also impact revenue growth as competitive alternatives enter the market.
Emerging and Specialized Players (Bausch Health Companies Inc., Gensco Pharma, Impel Pharmaceuticals Inc., Tonix Medicines, Inc., Currax Pharmaceuticals LLC.)
Focus on developing differentiated migraine therapies, reformulated products, and innovative drug delivery technologies that address unmet patient needs. Pursue targeted commercialization strategies, licensing agreements, strategic collaborations, and niche market expansion opportunities. Emphasize product differentiation through alternative delivery routes, improved patient convenience, and specialized migraine treatment approaches.
Specialized expertise in migraine management, greater operational flexibility, focused product development strategies, and the ability to address specific patient populations. Lean operating structures enable faster decision making and adaptation to changing market conditions. Innovative delivery platforms and targeted product portfolios help create differentiation in a competitive market environment.
Limited global commercial reach, smaller research and development budgets, dependence on a narrow product portfolio, and challenges related to market access and reimbursement negotiations. Growth may also be constrained by limited manufacturing capabilities and reliance on external partnerships for commercialization and distribution activities.
Recent Developments
-
In January 2025, Axsome Therapeutics received FDA approval for Symbravo, its new oral medication for the acute treatment of migraines. Symbravo combines meloxicam, a nonsteroidal anti-inflammatory drug, and rizatriptan, a serotonin receptor agonist, to provide rapid and sustained relief from migraine symptoms. This approval, following earlier regulatory setbacks, marks a significant advancement in Axsome's migraine treatment portfolio.
-
In April 2025, Teva Pharmaceuticals announced that the U.S. Food and Drug Administration (FDA) accepted its supplemental Biologics License Application (sBLA) for AJOVY® (fremanezumab-vfrm), aiming to expand its use for the prevention of episodic migraine in pediatric patients aged 6 to 17 years weighing at least 45 kilograms. If approved, AJOVY would become the first calcitonin gene-related peptide (CGRP) antagonist available for both adult and pediatric migraine prevention. The application is supported by positive results from the Phase 3 SPACE trial, which demonstrated significant reductions in monthly migraine and headache days among pediatric patients, with a safety profile comparable to that observed in adults.
-
In September 2024, Tonix Pharmaceuticals announced the issuance of a U.S. patent covering the subcutaneous delivery of Zembrace® SymTouch®, an FDA-approved medication for the acute treatment of migraines. This patent strengthens Tonix’s intellectual property portfolio and supports the continued development and commercialization of innovative delivery methods for migraine therapeutics, potentially enhancing convenience and efficacy for patients who require rapid symptom relief.
-
In December 2023 , Organon, a global healthcare company specializing in women's health, has entered into an agreement with Eli Lilly and Company (Lilly) to exclusively distribute and promote the migraine medications Emgality (galcanezumab) and RAYVOW (lasmiditan) in Europe.
-
In August 2023, Ajanta Pharma Ltd has obtained final approval from the U.S. Food and Drug Administration (USFDA) to sell topiramate extended-issue capsules in strengths of 25 mg, 50 mg, 100 mg, and 200 mg.
-
In July 2023, the American Heart Association has allocated USD 2.1 million in funding to support seven new scientific research studies focused on investigating the potential link between migraines and the risk of stroke and cardiovascular disease.
Migraine Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.9 billion
Estimated market size in 2026
USD 8.9 billion
Projected market size by 2033
USD 16.6 billion
Growth rate
CAGR of 9.2% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Treatment, therapeutic class, route of administration, age group, availability, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
AbbVie Inc., Amgen Inc., Teva Pharmaceutical Industries Ltd., GSK plc., Eli Lilly and Company, Pfizer Inc., Bausch Health Companies Inc., Gensco Pharma, Impel Pharmaceuticals Inc., Tonix Medicines, Inc., Currax Pharmaceuticals LLC., Lundbeck
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Migraine Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global migraine drugs market report based on treatment, therapeutic class, route of administration,age group, availability, region.
-
Treatment Outlook (Revenue, USD Million, 2021 - 2033)
-
Acute
-
Preventive
-
-
Therapeutic Class Outlook (Revenue, USD Million, 2021 - 2033)
-
CGRP monoclonal antibodies
-
CGRP small molecule antagonists
-
Acetylcholine inhibitors/ neurotoxins
-
Triptans
-
Ditans
-
Ergot alkaloids
-
NSAIDs
-
Others
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral
-
Injectable
-
Others
-
-
Age Group Outlook (Revenue, USD Million, 2021 - 2033)
-
Pediatric
-
Adult
-
Geriatric
-
-
Availability Outlook (Revenue, USD Million, 2021 - 2033)
-
Prescription Drugs
-
Over-the-Counter (OTC) Drugs
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
Research Methodology
Segment Definition
Segment - Treatment
Revenue capture definition
Acute
Includes pharmaceutical products used to treat migraine symptoms during an active migraine attack. Products in this segment include triptans such as sumatriptan, rizatriptan, and zolmitriptan, CGRP antagonists such as rimegepant and zavegepant, ditans such as lasmiditan, ergot derivatives such as dihydroergotamine, and NSAIDs including ibuprofen, naproxen, and diclofenac.
Preventive
Includes pharmaceutical products administered on a regular basis to reduce migraine frequency and severity. Products include CGRP monoclonal antibodies such as erenumab, fremanezumab, galcanezumab, and eptinezumab, neurotoxin therapies such as onabotulinumtoxinA, CGRP antagonists approved for prevention such as atogepant and rimegepant, as well as other preventive agents including beta blockers, anticonvulsants, and antidepressants when prescribed for migraine prevention.
Segment - Therapeutic Class
Revenue capture definition
CGRP Monoclonal Antibodies
Includes biologic therapies that target the calcitonin gene related peptide pathway or its receptor for migraine prevention. Products in this segment are typically administered through subcutaneous or intravenous routes and are indicated for episodic or chronic migraine management.
CGRP Small Molecule Antagonists
Includes oral and intranasal calcitonin gene related peptide receptor antagonists indicated for acute migraine treatment and or preventive migraine therapy. This segment covers prescription small molecule therapies that inhibit CGRP activity to reduce migraine symptoms and attack frequency.
Acetylcholine Inhibitors / Neurotoxins
Includes neurotoxin based pharmaceutical products approved for migraine prevention through the inhibition of neurotransmitter release involved in pain signaling pathways.
Triptans
Includes serotonin receptor agonists indicated for the acute treatment of migraine attacks. Products in this segment are available in oral, injectable, transdermal, and intranasal formulations.
Ditans
Includes selective serotonin receptor agonists indicated for the acute treatment of migraine attacks. These therapies provide migraine relief without significant vasoconstrictive activity and are commonly prescribed for patients with cardiovascular contraindications to triptans.
Ergot Alkaloids
Includes ergot derived pharmaceutical products used for the acute management of migraine attacks. This segment comprises formulations administered through oral, injectable, and intranasal routes.
NSAIDs
Includes nonsteroidal anti inflammatory drugs used for the treatment of mild to moderate migraine attacks. This segment covers both prescription and over the counter products utilized to reduce migraine associated pain and inflammation.
Others
Includes pharmaceutical products used for migraine treatment that are not classified under CGRP monoclonal antibodies, CGRP small molecule antagonists, acetylcholine inhibitors and neurotoxins, triptans, ditans, ergot alkaloids, or NSAIDs. This segment include combination therapies, emerging drug classes, and other prescription or over the counter migraine medications.
Segment - Route of Administration
Revenue capture definition
Oral
Includes migraine drugs administered orally in the form of tablets, capsules, orally disintegrating tablets, and oral solutions. Products in this segment include CGRP antagonists such as Qulipta (atogepant), Nurtec ODT/Vydura (rimegepant), and Ubrelvy (ubrogepant), triptans such as sumatriptan, rizatriptan, and eletriptan, as well as NSAIDs and combination analgesics used for migraine management.
Injectable
Includes migraine drugs administered through subcutaneous, intramuscular, or intravenous injection. Products include CGRP monoclonal antibodies such as Aimovig (erenumab), Ajovy (fremanezumab), Emgality (galcanezumab), and Vyepti (eptinezumab), as well as Botox (onabotulinumtoxinA) for chronic migraine prevention and injectable dihydroergotamine products.
Others
Includes migraine therapies administered through non oral and non injectable routes such as nasal sprays, transdermal systems, and other alternative delivery methods. Products include Zavzpret (zavegepant) nasal spray, Migranal (dihydroergotamine) nasal spray, Trudhesa nasal spray, and sumatriptan nasal formulations.
Segment - Age Group
Revenue capture definition
Pediatric
Includes migraine drugs prescribed for patients below 18 years of age. This segment covers therapies approved or prescribed for pediatric migraine management, including selected triptans, NSAIDs, and recently approved CGRP targeted therapies for pediatric populations.
Adult
Includes migraine drugs prescribed for patients between 18 and 64 years of age. This segment represents the largest patient population and includes all major therapeutic classes such as CGRP monoclonal antibodies, CGRP antagonists, triptans, ditans, neurotoxins, ergot alkaloids, and NSAIDs.
Geriatric
Includes migraine drugs prescribed for patients aged 65 years and above. This segment covers therapies used in older adults, taking into consideration age related comorbidities and medication safety profiles.
Segment - Availability
Revenue capture definition
Prescription Drugs
Includes migraine therapies that require authorization from a licensed healthcare professional for dispensing. Products include CGRP monoclonal antibodies such as Aimovig, Ajovy, Emgality, and Vyepti, CGRP antagonists such as Qulipta, Nurtec ODT/Vydura, Ubrelvy, and Zavzpret, Botox, triptans, ditans, and ergot alkaloids.
Over the Counter (OTC) Drugs
Includes migraine therapies available without a prescription for the management of mild to moderate migraine symptoms. Products include ibuprofen, naproxen sodium, aspirin, acetaminophen based products, and combination analgesics containing acetaminophen, aspirin, and caffeine.
Estimation Model
The market size for the Migraine Drugs Market was estimated through a combination of secondary research, primary interviews, and bottom-up revenue analysis. Initially, revenues generated from migraine-specific pharmaceutical products were collected from annual reports, investor presentations, regulatory filings, company websites, and industry databases of key manufacturers including AbbVie, Amgen, Teva Pharmaceutical Industries, Eli Lilly, Pfizer, Lundbeck, and other market participants. Products were categorized by treatment type (acute and preventive), therapeutic class, route of administration, age group, and availability. Historical sales data, prescription volumes, pricing trends, product approvals, and patent landscapes were analyzed to determine the revenue contribution of each segment. Regional demand patterns, disease prevalence rates, treatment adoption trends, and healthcare expenditure data were also assessed across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa to establish the baseline market value.
Following secondary research, findings were validated through primary interviews with neurologists, headache specialists, hospital pharmacists, pharmaceutical executives, distributors, and healthcare industry experts. A bottom-up modeling approach was then applied, whereby revenues from individual migraine drug categories, including CGRP monoclonal antibodies, CGRP antagonists, triptans, ditans, neurotoxins, ergot alkaloids, NSAIDs, and other therapies, were aggregated to derive regional and global market values. Market forecasts were developed by evaluating factors such as migraine prevalence, diagnosis rates, regulatory approvals, pipeline products, reimbursement coverage, treatment accessibility, and competitive developments. Data triangulation techniques were used to reconcile demand-side and supply-side estimates, ensuring accuracy and consistency across all market segments and geographies. The final market size and forecast were validated through multiple cross-checks using company revenue benchmarks, prescription utilization trends, and regional healthcare statistics.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Migraine Epidemiology & Patient Population Analysis
Assessment of migraine prevalence, chronic and episodic migraine burden, demographic trends, diagnosis rates, and treatment seeking patterns across major countries and regions.
Helps identify high growth patient populations and future demand drivers for migraine therapeutics.
Migraine Treatment Pathway Assessment
Analysis of treatment workflows across acute and preventive care, including diagnosis, first line therapies, CGRP targeted treatments, patient management, and long term disease monitoring practices.
Supports opportunity identification across the migraine treatment continuum and unmet clinical needs.
Novel Drug Adoption & Prescription Trend Analysis
Evaluation of CGRP inhibitors, gepants, ditans, triptans, preventive therapies, and prescription trends across healthcare settings and patient populations.
Tracks the shift toward targeted migraine therapies and evolving prescribing patterns.
Pipeline, Clinical Trials & Innovation Landscape
Assessment of late stage pipeline candidates, clinical development activities, novel mechanisms of action, next generation CGRP therapies, and emerging migraine treatment approaches.
Identifies future product launch opportunities and competitive growth areas.
Reimbursement & Market Access Analysis
Evaluation of payer coverage policies, reimbursement frameworks, pricing trends, treatment accessibility, and formulary positioning of branded and specialty migraine drugs.
Provides insights into commercialization potential and factors influencing therapy adoption.
Frequently Asked Questions About This Report
The global migraine drugs market is expected to grow at a CAGR of 9.2% from 2026 to 2033, reaching USD 16.6 billion by 2033.
North America dominated the migraine drugs market with the largest revenue share of 40.3% in 2025.
Asia Pacific is the fastest-growing regional market and is projected to expand at a CAGR of 10.8% from 2026 to 2033.
The CGRP monoclonal antibodies segment dominated the market, accounting for 55.3% of total revenue in 2025.
The injectable segment held the largest market share, accounting for 73.1% of revenue in 2025.
The global migraine drugs market size was valued at USD 7.9 billion in 2025 and is estimated at USD 8.9 billion in 2026.
Based on treatment, the acute treatment segment led the market with the largest revenue share of 62.9% in 2025.
Key players operating in the migraine drugs market include AbbVie Inc., Amgen Inc., Teva Pharmaceutical Industries Ltd., GSK plc., Eli Lilly and Company, Pfizer Inc., Bausch Health Companies Inc., Gensco Pharma, Impel Pharmaceuticals Inc., Tonix Medicines, Inc., Currax Pharmaceuticals LLC., and Lundbeck.
Key factors include the increasing prevalence of migraine disorders, growing adoption of targeted CGRP-based therapies, rising awareness of preventive migraine treatment, expanding clinical evidence supporting innovative therapies, and continued investment in migraine drug research and development.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


