
- Home
- »
- Automotive & Transportation
- »
-
Military Aerospace And Defense Lifecycle Management Market Report, 2025-2030GVR Report cover

Military Aerospace And Defense Lifecycle Management Market (2025 - 2030)
Size, Share & Trends Analysis Report By Type (Product Lifecycle Management, Service Lifecycle Management), By Region, And Segment Forecasts
Market Size, 2024
$11.0BMarket Estimate, 2026
$13.0BMarket Forecast, 2030
$18.2BCAGR, 2025–2030
8.7%Market Size & Trends
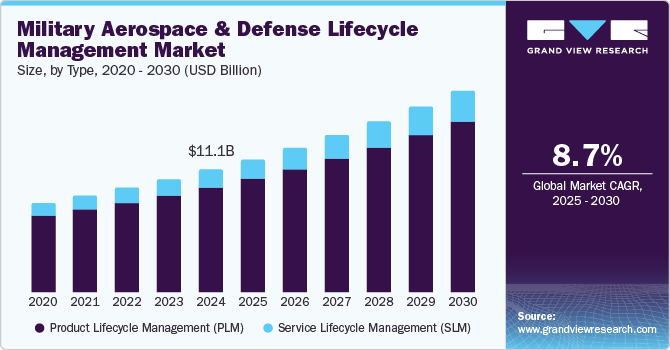
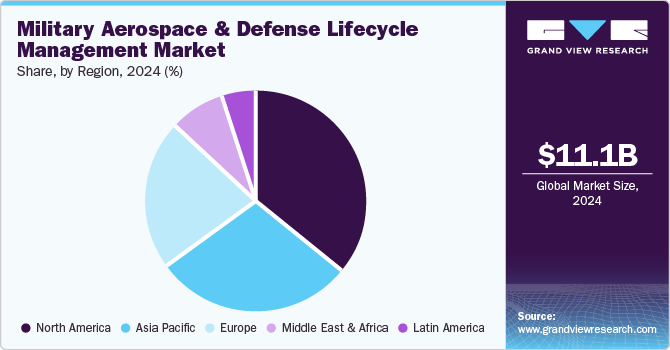
The global military aerospace and defense lifecycle management market size was valued at USD 11.0 billion in 2024 and is projected to grow from USD 13.0 billion in 2026 to USD 18.2 billion by 2030, at a CAGR of 8.7% from 2025 to 2030. North America dominated the market, accounting for a revenue share of 36.0% in 2024. This growth is primarily driven by the increasing complexity of defense systems and the demand for advanced product lifecycle management (PLM) software solutions. As military equipment becomes more sophisticated, manufacturers are compelled to adopt comprehensive lifecycle management strategies that can effectively handle the intricate components and systems involved in modern military operations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The rising need for efficiency in maintenance, repair, and overhaul (MRO) processes is further driving the military aerospace & defense lifecycle management industry. Integrating PLM systems allows manufacturers to optimize these processes, enhancing reliability and extending the operational lifespan of military assets. For instance, the U.S. military's adoption of PLM solutions has enabled better tracking and management of its aging aircraft fleet, ensuring that they remain operationally ready while minimizing costs associated with downtime and repairs. This strategic approach improves equipment performance and supports long-term sustainability goals within defense operations.
Moreover, a significant aspect driving market growth is the increasing emphasis on digital transformation within the defense sector. As organizations embrace digital tools and technologies, the need for effective Service Lifecycle Management (SLM) becomes apparent. The ability to analyze vast amounts of operational data generated by modern defense systems enables organizations to make informed choices regarding maintenance schedules and resource allocation.
Furthermore, geopolitical factors and rising national defense budgets fuel investments in military aerospace and defense lifecycle management solutions. Countries in regions such as Asia Pacific are particularly notable for their rapid modernization efforts, necessitating robust lifecycle management strategies to ensure that new military systems are efficiently integrated into existing frameworks. The ongoing shift toward outsourcing non-core functions to specialized lifecycle management service providers also presents substantial growth opportunities for market players as defense organizations seek to enhance their operational capabilities while focusing on core mission objectives.
Type Insights
The Product lifecycle management (PLM) segment dominated the market with the largest revenue share of 85.5% in 2024, driven by the increasing complexity of defense systems and the need for efficient management throughout their lifecycle. PLM solutions provide comprehensive tools that facilitate the management of intricate components involved in military equipment, ensuring that every phase-from design to disposal-is meticulously handled. For instance, the U.S. Air Force utilizes PLM software to enhance the maintenance processes of its aircraft, such as the F-35 Lightning II, which involves numerous subsystems requiring precise coordination and data management. This capability improves operational readiness and significantly reduces lifecycle costs, thereby underscoring the critical role of PLM in modern defense operations.
The service lifecycle management (SLM) segment is expected to grow at the highest CAGR over the forecast period, driven by the increasing complexity of modern defense systems and the need for efficient maintenance and support services management. As military assets become more sophisticated, equipped with advanced sensors and connectivity features, they generate vast amounts of operational data that require effective analysis and management. This trend drives the adoption of SLM solutions, which enhance predictive maintenance capabilities and optimize asset performance throughout their lifecycle. In addition, the emphasis on sustainability and compliance with environmental regulations further propels the demand for SLM solutions as defense organizations seek to ensure operational readiness while adhering to evolving standards.
Regional Insights
North America military aerospace & defense lifecycle management industry dominated with a revenue share of 36.0% in 2024 due to substantial defense budgets and a strong emphasis on technological innovation. The United States, as a key player in global defense spending, invests heavily in modernizing its military capabilities, which necessitates advanced lifecycle management solutions to optimize maintenance and operational efficiency. For instance, the U.S. Air Force's Integrated Logistics System enhances the maintenance processes for aircraft such as the C-130 Hercules, ensuring high operational readiness while controlling costs. In addition, the aging military equipment fleet in North America drives the need for comprehensive lifecycle strategies to maintain performance and extend asset life.
 To learn more about this report, Download Free Sample Report
U.S. Military Aerospace & Defense Lifecycle Management Market Trends
The U.S. military aerospace & defense lifecycle management market dominated North America in 2024 with the largest revenue share due to significant defense spending and commitment to modernization. The United States allocates a substantial portion of its budget to defense, which enables the adoption of advanced lifecycle management solutions that enhance operational efficiency and asset reliability. For instance, the U.S. Navy's use of predictive maintenance technologies for its fleet, such as the aircraft carrier USS Gerald R. Ford, exemplifies how lifecycle management can optimize maintenance schedules and reduce downtime. In addition, the presence of leading defense contractors and technology firms in the U.S. fosters innovation and the development of integrated systems that address complex military requirements.
Asia Pacific Military Aerospace & Defense Lifecycle Management Market Trends
Asia Pacific military aerospace & defense lifecycle management market is expected to grow at the highest CAGR over the forecast period due to increasing defense budgets and a strong focus on modernization among regional countries. Nations such as India and China are significantly ramping up their military expenditures to enhance their defense capabilities, necessitating effective lifecycle management strategies to ensure operational readiness and efficiency. For instance, India's investment in advanced platforms such as the Rafale fighter jets underscores the need for comprehensive maintenance and support systems to manage these high-value assets throughout their lifecycle. In addition, the rising geopolitical tensions in the region compel governments to prioritize defense procurement, further driving demand for sophisticated lifecycle management solutions that can optimize asset performance and reduce operational costs.
The China military aerospace & defense lifecycle management industry dominated Asia Pacific in 2024 with the largest revenue share due to a significant increase in defense spending and a focused commitment to military modernization. China's defense budget has consistently risen, with a 7.2% increase announced for 2024, totaling approximately CNY 1.66 trillion ($231.4 billion). This financial boost supports the People's Liberation Army's (PLA) efforts to enhance its technological capabilities and operational efficiency, emphasizing the integration of advanced technologies such as artificial intelligence and autonomous systems. For instance, the development of China's stealth fighter jets, such as the Chengdu J-20, necessitates sophisticated lifecycle management practices to ensure optimal performance and maintenance throughout their operational lifespan.
Europe Military Aerospace & Defense Lifecycle Management Market Trends
Europe military aerospace & defense lifecycle management is expected to grow significantly over the forecast period due to escalating defense budgets and a renewed focus on strategic autonomy in response to geopolitical tensions. Germany's commitment to increase its defense budget by 48% between 2014 and 2023 illustrates this trend, as it aims to meet NATO's target of spending 2% of GDP on defense. In addition, initiatives such as the European Defense Fund promote joint procurement and collaborative development among EU member states, fostering innovation and efficiency in defense spending. This combination of increased investment, strategic actions, and an emphasis on modernization prepares Europe for strong growth in the military aerospace and defense lifecycle management market.
Key Military Aerospace And Defense Lifecycle Management Company Insights
Some key companies in the military aerospace & defense lifecycle management industry include Aras Corporation, Infor, PROLIM, Cyient Limited, Siemens AG, and others. These companies in the military aerospace and defense lifecycle management market employ various strategies to maintain a competitive edge, including the development of integrated software solutions that enhance operational efficiency and asset performance. They focus on leveraging advanced technologies such as artificial intelligence and data analytics to optimize maintenance processes and reduce costs throughout the lifecycle of military assets.
-
Dassault Systèmes SE specializes in providing advanced lifecycle management solutions tailored for the military aerospace and defense sector through its 3DEXPERIENCE platform. This platform integrates various applications to enhance collaboration across teams, enabling organizations to manage the entire lifecycle of defense products from design to disposal. By leveraging digital twin technology, Dassault Systèmes allows military operators to simulate and optimize performance, ensuring that defense systems remain mission-ready while adapting to evolving threats.
-
Siemens AG offers comprehensive solutions for military aerospace and defense lifecycle management, focusing on digitalization and automation to enhance operational efficiency. Their software platforms integrate advanced analytics and IoT capabilities, enabling real-time monitoring and predictive maintenance of military assets. Siemens emphasizes the importance of sustainability and compliance in defense operations, providing tools that streamline processes while reducing environmental impact.
Key Military Aerospace And Defense Lifecycle Management Companies:
The following are the leading companies in the military aerospace and defense lifecycle management market. These companies collectively hold the largest market share and dictate industry trends.
- Aras Corporation
- ATS Global B.V.
- Dassault Systèmes SE
- Honeywell International Inc.
- Infor
- PROLIM
- PTC Inc.
- Cyient Limited
- Siemens AG
- Nikon SLM Solutions AG
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2030 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Recent Developments
-
In June 2024, Honeywell announced the acquisition of CAES Systems Holdings LLC. This acquisition aims to enhance Honeywell’s defense technology solutions across sea, air, land, and space by integrating CAES’s high-reliability radio frequency technologies into its portfolio. The deal is expected to bolster Honeywell’s capabilities in electromagnetic defense solutions and expand its established production positions on critical platforms such as the F-35 and Navy Radar (SPY-6).
-
In December 2023, Dassault Aviation announced an extension of its collaboration with Dassault Systèmes to enhance aircraft maintenance, repair, and overhaul (MRO) operations for its Rafale fleet supporting the French Ministry of Armed Forces. Utilizing the 3DEXPERIENCE platform on a sovereign cloud, Dassault Aviation aims to optimize military fleet availability through advanced data analytics and virtual twin technology.
Military Aerospace And Defense Lifecycle Management Market Report Scope
Report Attribute
Details
Market size in 2024
USD 11.0 billion
Estimated market size in 2026
USD 13.0 billion
Projected market size by 2030
USD 18.2 billion
Growth Rate
CAGR of 8.7% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2025 - 2030
Quantitative units
Revenue in USD million and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, region
Regional scope
North America, Europe, Asia Pacific, Latin America, MEA
Country scope
U.S., Canada, Mexico, Germany, UK, France, Russia, China, Japan, India, Australia, South Korea, Brazil, South Africa, Saudi Arabia, UAE
Key companies profiled
Aras Corporation, ATS Global B.V., Dassault Systèmes SE, Honeywell International Inc., Infor, PROLIM, PTC Inc., Cyient Limited, Siemens AG, Nikon SLM Solutions AG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Military Aerospace And Defense Lifecycle Management Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global military aerospace and defense lifecycle management market report based on type, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Product Lifecycle Management (PLM)
-
Service Lifecycle Management (SLM)
-
-
Regional Outlook (Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Russia
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
-
Latin America
-
South Korea
-
Brazil
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
North America dominated the military aerospace & defense lifecycle management market with a share of 36.0% in 2024. This is attributable to the aggressive investments made in strengthening the region's defense capabilities over the past few years.
The global military aerospace & defense lifecycle management market size was valued at USD 11.0 billion in 2024 and is expected to reach USD 13.0 billion in 2026.
The global military aerospace & defense lifecycle management market is expected to grow at a compound annual growth rate of 8.7% from 2025 to 2030 to reach USD 18.2 billion by 2030.
Some key players operating in the military aerospace & defense lifecycle management market include ARAS; ATS Global B.V.; Dassault Systèmes; Honeywell International Inc.; Infor; PROLIM; PTC; Rolls-Royce plc; Siemens AG; and SLM Solutions.
Key factors that are driving the military aerospace & defense lifecycle management market growth include growing demand from defense OEMs for new and innovative approaches that can potentially help in reducing costs and enhancing product quality and evolving need for technologically-advanced solutions that can potentially streamline the core operations.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst -

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


