
- Home
- »
- Clinical Diagnostics
- »
-
Minimal Residual Disease Testing Market Size Report, 2026-2033GVR Report cover

Minimal Residual Disease Testing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Flow Cytometry; Polymerase Chain Reaction (PCR), Next Generation Sequencing (NGS)), By Cancer Type, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$2.6BMarket Estimate, 2026
$3.0BMarket Forecast, 2033
$7.1BCAGR, 2026–2033
13.2%Minimal Residual Disease Testing Market Summary
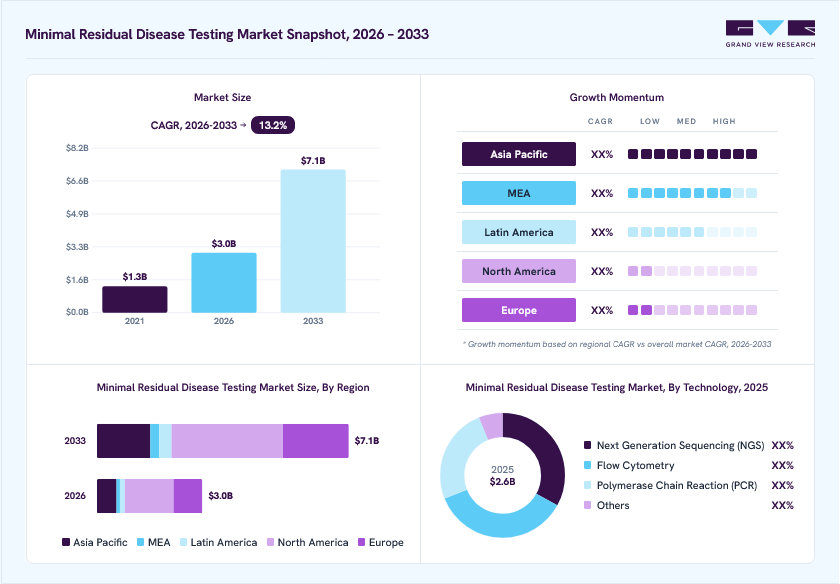
The global minimal residual disease testing market size was valued at USD 2.6 billion in 2025 and is projected to grow from USD 3.0 billion in 2026 to USD 7.1 billion by 2033, at a CAGR of 13.2% from 2026 to 2033. North America dominated the market with the largest revenue share of 46.4% in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Flow cytometry segment held the largest revenue share of 35.9% in 2025.
- By cancer type: Hematological malignancy segment held the largest revenue share of 56.8% in 2025.
- By end use: Hospitals and specialty clinics segment held the largest revenue share of 50.2% in 2025.
Regional Highlights
- Largest regional market: North America (46.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest revenue share of North America in 2025
Market Size & Forecast
- Market size in 2025: USD 2.6 Billion
- Estimated market size in 2026: USD 3.0 Billion
- Projected market size by 2033: USD 7.1 Billion
- CAGR (2026-2033): 13.2%
Prism AI by Grand View Research Free to tryAsk a question about the minimal residual disease testing market✓Every figure cited from GVR research Prefer the report? Download free sample → To learn more about this report, Download Free Sample Report
Market Dynamics
The increasing adoption of minimal residual disease (MRD) testing in oncology care is emerging as a significant driver of market growth. As cancer treatment strategies continue to shift toward precision medicine, healthcare providers are increasingly seeking highly sensitive tools capable of evaluating treatment effectiveness, detecting residual disease, and identifying recurrence at earlier stages than conventional monitoring methods. Traditionally, post-treatment surveillance has relied on imaging techniques, clinical assessments, and biomarker evaluations; however, these approaches may not always detect microscopic disease burden following treatment.
The growing clinical utility of MRD testing has expanded its role beyond research settings into routine patient management across both hematologic malignancies and solid tumors. MRD assessment is increasingly being utilized to evaluate therapeutic effectiveness, guide treatment intensification or de-escalation decisions, support recurrence risk stratification, and facilitate longitudinal disease monitoring. Furthermore, the ability to identify molecular evidence of recurrence before clinical or radiographic progression has strengthened physician confidence in MRD-guided treatment strategies, contributing to broader adoption across healthcare systems.
The lack of standardized testing protocols and variability in clinical adoption continue to present significant challenges to market expansion. MRD testing encompasses a broad range of technologies, including flow cytometry, polymerase chain reaction (PCR), next-generation sequencing (NGS), and circulating tumor DNA (ctDNA)-based assays, each possessing distinct analytical methodologies, sensitivity thresholds, reporting standards, and clinical applications. As a result, differences in testing approaches can create inconsistencies in result interpretation, patient stratification, and treatment decision-making across healthcare institutions.
The absence of universally accepted testing standards remains particularly relevant in the rapidly evolving solid tumor MRD landscape. While MRD assessment has become an established component of disease monitoring in several hematologic malignancies, adoption within solid tumors is still developing. Differences in assay design, testing frequency, biomarker selection, sample collection protocols, and clinical endpoints contribute to variability in how MRD results are utilized across different cancer types and healthcare settings. Consequently, physicians may face challenges when comparing outcomes across studies or integrating MRD findings into routine treatment pathways.
Clinical guideline adoption also varies considerably among regions and oncology specialties. Although increasing evidence supports the prognostic and predictive value of MRD testing, the level of guideline integration differs across cancer indications, healthcare systems, and professional organizations. This variability can influence physician confidence, testing utilization, and reimbursement decisions, thereby affecting overall market penetration. In some settings, MRD testing remains primarily concentrated within academic institutions and specialized oncology centers, while broader adoption in community-based practices continues to evolve.
Technological advancements in circulating tumor DNA (ctDNA)-based liquid biopsy and next-generation sequencing (NGS) platforms are significantly contributing to the growth of the minimal residual disease (MRD) testing market. The ability to detect extremely low levels of residual disease has become increasingly important as oncology treatment strategies move toward earlier intervention, personalized treatment planning, and proactive disease monitoring. Conventional diagnostic techniques, including imaging and standard biomarker testing, often face limitations in detecting microscopic disease burden following treatment. In contrast, modern ctDNA-based MRD assays can identify molecular evidence of residual disease before clinical symptoms or radiographic findings become apparent, enabling earlier and more informed clinical decision-making.
The continuous evolution of NGS technologies has substantially improved analytical sensitivity, specificity, sequencing depth, and bioinformatics capabilities. These advancements have enabled the development of highly personalized tumor-informed and tumor-uninformed MRD assays capable of detecting residual disease at increasingly lower thresholds. Furthermore, improvements in sequencing efficiency, assay design, and computational analysis have expanded the clinical applicability of MRD testing across both hematologic malignancies and solid tumors. As a result, healthcare providers are increasingly adopting advanced molecular testing platforms to support treatment response assessment, recurrence monitoring, and long-term patient surveillance.
Market Concentration & Characteristics
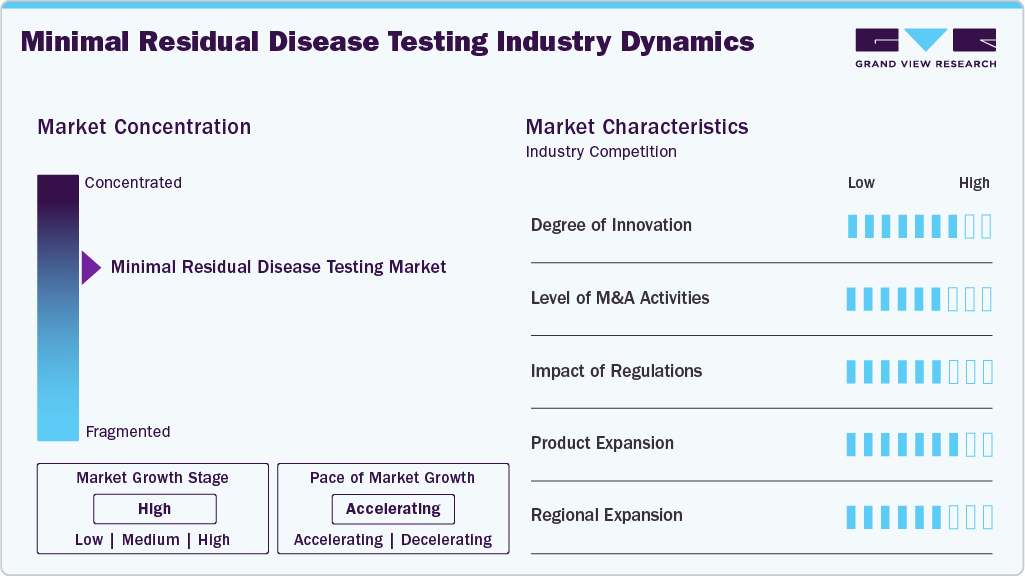
The MRD testing market benefits from continuous innovation, including advanced techniques such as Next-Generation Sequencing, digital PCR, and single-cell analysis. Ongoing R&D efforts focus on automation and integrating AI for enhanced diagnostic capabilities. For instance, in January 2025, Datar Cancer Genetics (DCG) announced the launch of Target-MRD, an advanced minimal residual disease (MRD) monitoring blood test for solid organ cancers. Target-MRD was developed as a blood test based on tumor-agnostic next-generation sequencing (NGS) and a customized, tumor-informed droplet digital PCR (dd-PCR) assay.
The minimal residual disease testing market experiences a high level of mergers and acquisitions (M&A), as companies aim to expand product portfolios and technological capabilities. Strategic partnerships and acquisitions enable rapid access to innovative platforms, broaden market reach, and enhance competitiveness. For example, in April 2025, Hartwig and Ultima Genomics collaborated to reduce costs for whole genome cancer profiling, minimal residual disease testing, and large-scale genetic data generation. Their partnership focused on making advanced genomic technologies more affordable and accessible, aiming to enhance cancer diagnostics and personalized treatment through improved genetic analysis.
 To learn more about this report, Download Free Sample Report
Regulatory approvals are crucial in shaping the MRD testing market. Authorities such as the FDA impose rigorous standards to ensure test accuracy and patient safety. Minimal Residual Disease (MRD) has emerged as an important endpoint for accelerated drug approvals, particularly in hematologic cancers such as multiple myeloma and acute lymphoblastic leukemia (ALL). The FDA's Oncologic Drug Advisory Committee (ODAC) has endorsed MRD as a valid surrogate endpoint for accelerated approval in multiple myeloma as published in article of May 2025. Expanding regulatory recognition of MRD assays in treatment protocols boosts market adoption and reimbursement opportunities.
Manufacturers continuously expand their MRD testing offerings by developing assays for various hematologic malignancies and solid tumors. Innovations focus on enhancing test sensitivity, reducing turnaround time, and enabling multiplexing. For instance, in May 2024, Tempus announced the clinical launch of its MRD testing portfolio xM MRD and NeXT Personal Dx tests. These tests are designed to detect residual disease or early cancer recurrence and to monitor responses to immunotherapy, offering critical insights to guide patient management.
Market players are increasingly targeting emerging regions such as Asia Pacific and Latin America, where rising cancer prevalence and improving healthcare infrastructure create growth opportunities. Localization of products, collaborations with regional healthcare providers, and awareness programs are key strategies to drive MRD testing adoption and expand the global market footprint.
Analyst Perspective
The Minimal Residual Disease (MRD) Testing Market is witnessing robust growth, driven by the increasing adoption of precision oncology, growing prevalence of hematological malignancies, and expanding clinical evidence supporting MRD-guided treatment decisions. Advances in next-generation sequencing (NGS), multiparameter flow cytometry, and PCR-based assays have significantly improved the sensitivity and accuracy of MRD detection, enabling earlier relapse identification and personalized therapy monitoring. The integration of MRD assessment into clinical guidelines, rising use of companion diagnostics, and ongoing development of liquid biopsy-based MRD tests are further strengthening market expansion. In addition, increasing pharmaceutical investments in MRD endpoints for clinical trials, favorable reimbursement in developed markets, and broader access to advanced molecular diagnostics are expected to create sustained growth opportunities throughout the forecast period.
Technology Insights
The flow cytometry segment accounted for largest revenue share of 35.9% in 2025 driven by driven by its rapid and precise detection capabilities. This technology identifies abnormal cells by analyzing multiple cellular markers simultaneously, allowing clinicians to detect residual cancer cells even at very low levels. Its high sensitivity and specificity make it especially valuable in monitoring hematological malignancies such as leukemia and lymphoma. In addition, flow cytometry is widely available in clinical laboratories, offering cost-effective and standardized testing. The ability to provide quick results supports timely treatment decisions, contributing to improved patient outcomes and driving strong demand for flow cytometry-based MRD testing globally.
The polymerase chain reaction (PCR) technology segment is the fastest-growing segment in the minimal residual disease (MRD) testing market. PCR offers exceptional sensitivity and specificity by amplifying targeted DNA or RNA sequences, enabling the detection of even minute amounts of residual cancer cells. Techniques such as quantitative PCR (qPCR) and droplet digital PCR (ddPCR) provide precise quantification of disease markers, making them essential for monitoring treatment response and early relapse detection. PCR-based MRD testing is widely adopted due to its rapid turnaround time and ability to deliver accurate results, supporting timely clinical decisions and personalized treatment strategies in hematologic cancers.
Cancer Type Insights
Hematological malignancy cancer dominated the market with revenue of 56.8% in 2025 and is the fastest-growing segment driven by high prevalence of blood cancers such as leukemia, lymphoma, and multiple myeloma. MRD testing plays a critical role in these cancers by detecting residual malignant cells. Advancements in technologies such as next-generation sequencing (NGS) and droplet digital PCR (ddPCR) have enhanced the sensitivity and accuracy of MRD detection, allowing for earlier detection of residual disease and better monitoring of treatment responses. At the 2025 American Association for Cancer Research (AACR) Annual Meeting, experts highlighted significant advancements in minimal residual disease (MRD) testing for hematologic malignancies, emphasizing the need for standardized methodologies and the integration of novel technologies.
Detecting minimal residual disease (MRD) the small number of cancer cells that remain after treatment is crucial for assessing relapse risk and guiding further therapy. MRD detection enables personalized treatment decisions, including therapy intensification or de-escalation, improving patient outcomes. As MRD becomes an essential biomarker in hematological cancers, its integration into clinical practice supports early intervention and long-term disease monitoring.
End Use Insights
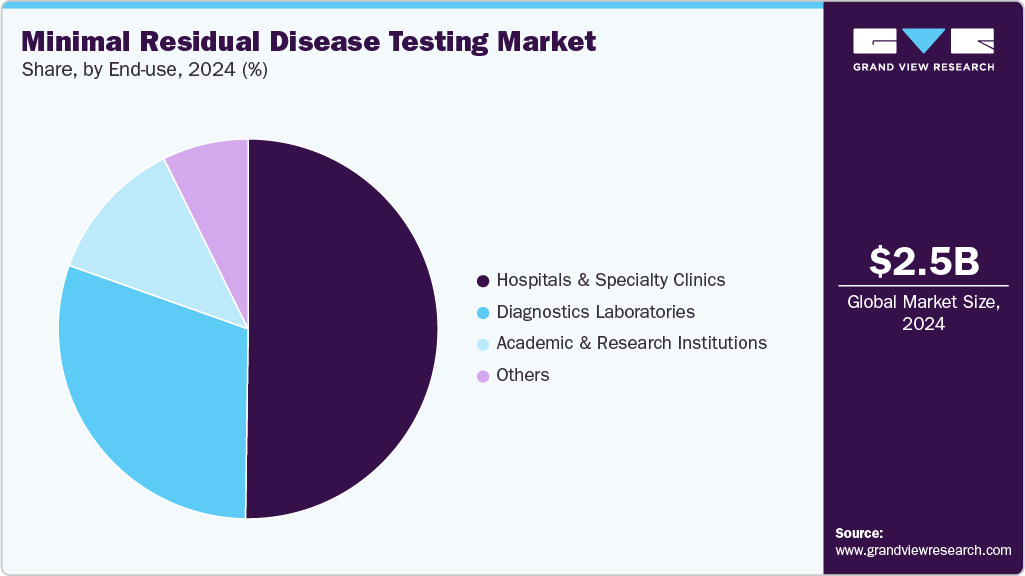
The hospitals and specialty clinics segment accounted the largest share of 50.2% in 2025 due to their advanced diagnostic capabilities and access to specialized healthcare professionals. These facilities are equipped with cutting-edge technologies like flow cytometry, PCR, and next-generation sequencing, enabling precise MRD detection. In addition, hospitals and specialty clinics provide integrated patient care, combining MRD testing with treatment and monitoring, which is crucial for managing hematologic malignancies. Their ability to offer comprehensive services and timely results makes them the preferred choice for MRD testing, driving their dominance and sustained growth in the market.
 To learn more about this report, Download Free Sample Report
The diagnostic laboratories segment is emerging as the fastest-growing segment in the minimal residual disease (MRD) testing market. This growth is driven by increasing demand for high-sensitivity testing, advanced molecular diagnostics, and early relapse detection in hematological malignancies. Diagnostic labs are well-equipped with next-generation sequencing (NGS), digital PCR, and flow cytometry platforms, enabling them to offer precise and standardized MRD assessments. Their scalability, cost-effectiveness, and ability to handle high testing volumes make them ideal partners for hospitals and oncology centers. As precision medicine gains momentum, diagnostic labs are playing a pivotal role in delivering reliable MRD insights for treatment planning.
Regional Insights
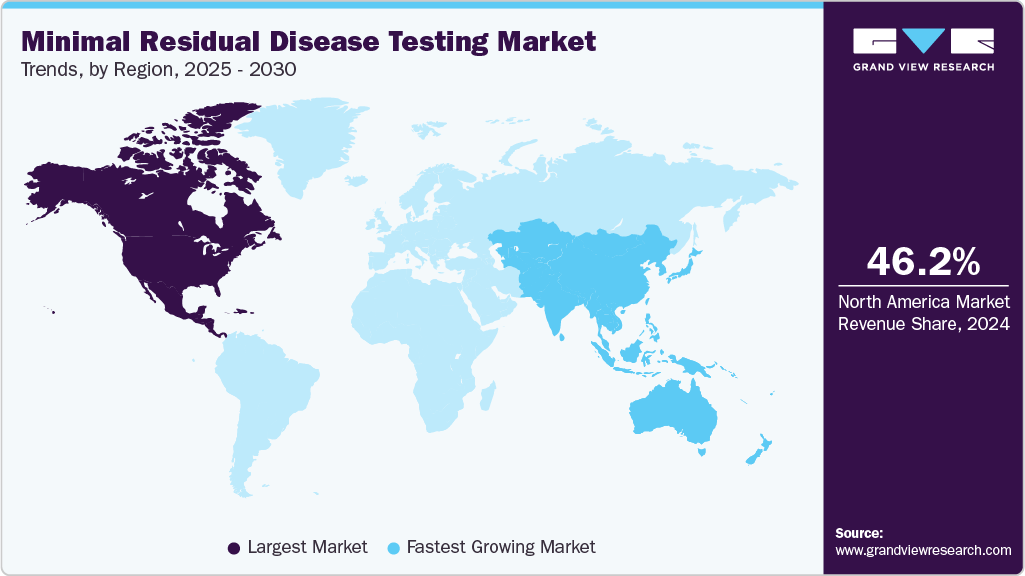
North America dominated the minimal residual disease testing market and accounted for a 46.4% revenue share in 2025. This dominance is attributed to advanced healthcare infrastructure, high adoption of MRD testing technologies, and a strong presence of key industry players. Strategic collaborations such as in December 2024, Personalis and Tempus expanded their collaboration to include the biopharmaceutical sector, enabling Tempus to offer Personalis' ultra-sensitive tumor-informed minimal residual disease (MRD) test, NeXT Personal Dx, to pharmaceutical and biotech companies.
 To learn more about this report, Download Free Sample Report
U.S. Minimal Residual Disease Testing Market Trends
The U.S. leads the minimal residual disease testing market is growing significantly due to rising cancer incidences and growing partnerships and collaborations. For example, in January 2025, Adaptive Biotechnologies and NeoGenomics have partnered to integrate Adaptive's FDA-cleared clonoSEQ MRD test with NeoGenomics' COMPASS and CHART services, enabling comprehensive tracking of minimal residual disease (MRD) in cancers such as multiple myeloma, chronic lymphocytic leukemia, B-cell acute lymphoblastic leukemia, and diffuse large B-cell lymphoma.
Europe Minimal Residual Disease Testing Market Trends
Europe minimal residual market is expanding driven by increased awareness, advancements in diagnostic technologies, and the growing adoption of MRD testing in clinical settings. Countries like Germany, France, and the UK are leading the regional market, with Germany expected to maintain its dominance. Collaborations and partnerships are rising in these areas.
The UK minimal residual disease (MRD) testing market is expanding, driven by advancements in next-generation sequencing (NGS), polymerase chain reaction (PCR), and flow cytometry technologies. These innovations enhance detection sensitivity and monitoring capabilities. The increasing adoption of precision medicine and early cancer detection further propels market growth. As the demand for personalized oncology care rises, the UK's MRD testing market is poised for continued expansion.
Germany's minimal residual disease (MRD) testing market is experiencing significant growth, driven by advancements in next-generation sequencing (NGS), polymerase chain reaction (PCR), and flow cytometry technologies. Collaborations, such as in August 2022, Exact Sciences Corp. announced that it has entered into a collaboration agreement with the West German Study Group (WSG), an international research organization specializing in practice-changing clinical studies in breast cancer streamline clinical workflows.
Asia Pacific Minimal Residual Disease Testing Market Trends
Asia Pacific is the fastest growing segment in minimal residual testing disease market with 15.3% CAGR over the forecast period. Asia Pacific minimal residual disease testing market is anticipated to witness significant growth driven by increasing cancer incidence and technological advancements. Some players include Illumina, Roche, Sysmex, and Natera. Technological innovations, such as multi-parameter flow cytometry and digital PCR, are enhancing test sensitivity and early detection capabilities. Collaborations and strategic partnerships are further accelerating the adoption of MRD testing across the region.
China minimal residual disease testing market held a substantial share in 2025. The market is advancing due to government support for precision medicine. Companies such as Genetron Health, Hotgen Biotech, and Prenetics have presence in China. Innovations in liquid biopsy and digital PCR are enhancing test sensitivity and accessibility. Strategic collaborations and infrastructure development further propel market growth.
Japan’s minimal residual disease testing market is progressing moderately, reflecting a preference for high-precision diagnostic solutions. Innovations in liquid biopsy and digital PCR are enhancing test sensitivity and accessibility. The Japan Society of Clinical Oncology has developed guidelines to standardize MRD testing, promoting its integration into clinical practice.
Latin America Minimal Residual Disease Testing Market Trends
Latin America's minimal residual disease (MRD) testing market is experiencing significant growth, driven rising healthcare investments and improving technologies. Technological advancements such as next-generation sequencing (NGS) and polymerase chain reaction (PCR) are enhancing test sensitivity and early detection capabilities. However, challenges like limited reimbursement and access to advanced diagnostics in certain areas may impact market expansion.
The minimal residual disease (MRD) testing market in Brazil is growing rapidly over he forecast period. Major global players active in Brazil include Roche, Illumina, Exact Sciences, and Qiagen, contributing to a competitive market landscape driven by innovation and personalized medicine trends.
Middle East & Africa Minimal Residual Disease Testing Market Trends
The Middle East and Africa (MEA) minimal residual disease testing market is poised for growth. Advancements in diagnostic technologies and increasing cancer awareness are driving market expansion.
The Saudi Arabia minimal residual disease testing market is experiencing robust growth. Some of the players include Exact Sciences, Illumina, Natera, Guardant Health, Roche, Foundation Medicine, Qiagen, Veracyte, MDxHealth, and Bio-Techne. Technological innovations such as digital PCR and liquid biopsy are enhancing test sensitivity and early detection capabilities. Collaborations and strategic partnerships are further accelerating the adoption of MRD testing in the region.
Key Minimal Residual Disease Testing Company Insights
The minimal residual disease (MRD) testing market is led by key companies such as Exact Sciences Corporation and GRAIL, LLC. Adaptive Biotechnologies dominates with its FDA-approved ClonoSEQ assay, widely used in hematologic cancers. Roche and Thermo Fisher leverage advanced NGS and PCR technologies to maintain significant market shares, supported by their global reach and strong R&D. The market is fragmented but rapidly growing, with NGS-based testing gaining prominence due to higher sensitivity.
Key Minimal Residual Disease Testing Companies
The following key companies have been profiled for this study on the minimal residual disease testing market:
-
Exact Sciences Corporation
-
GRAIL, LLC
-
Veracyte, Inc.
-
Natera, Inc.
-
Guardant Health
-
F. Hoffmann-La Roche Ltd
-
FOUNDATION MEDICINE, INC.
-
QIAGEN
-
mdxhealth.
-
Bio-Techne.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
- Mature Players: Natera,Inc.
- Focus on expanding approved and validated MRD assays across multiple cancer indications, strengthening reimbursement coverage, generating long-term clinical evidence, and integrating MRD testing into routine oncology workflows through strategic collaborations with healthcare providers and pharmaceutical companies.
- Benefit from established commercial infrastructure, extensive clinical validation, strong payer relationships, broad physician adoption, and recognized brand presence, enabling faster market penetration and sustained competitive positioning.
- Face challenges related to higher operating costs, complex organizational structures, and slower adoption of emerging technologies. Maintaining growth requires continuous investment in innovation, clinical studies, and reimbursement expansion.
- Emerging Players: Personalis, Inc.
- Concentrate on developing highly sensitive ctDNA-, NGS-, and AI-enabled MRD platforms targeting unmet clinical needs and niche oncology applications. Their strategies emphasize innovation, focused clinical validation, academic partnerships, and selective commercialization to establish market differentiation.
- Possess greater agility in technology development, enabling rapid innovation, enhanced assay sensitivity, and personalized testing capabilities. Their focused approach allows them to address specific clinical gaps and attract strategic partnerships.
- Operate with limited commercial reach, smaller clinical evidence bases, and evolving reimbursement support. Dependence on external funding, regulatory progress, and successful clinical validation may slow broader market adoption and scalability.
Recent Development
-
In June 2026, Quest Diagnostics has received approval from the New York State Department of Health's Clinical Laboratory Evaluation Program (CLEP) for its Haystack MRD® ctDNA liquid biopsy test, enabling its use in identifying residual or recurrent disease across multiple solid tumor cancers.
-
In June 2025, QIAGEN expanded its oncology diagnostics portfolio through two strategic partnerships aimed at advancing MRD testing in clinical trials. These collaborations—with Tracer Biotechnologies and Foresight Diagnostics—enhance QIAGEN’s presence in the MRD space, supporting companion diagnostic co-development projects across both solid tumors and hematologic cancers
-
In April 2025, Natera, Inc., announced the nationwide availability of its ultra-sensitive Signatera Genome assay for physicians across the U.S. This launch is backed by a major genome-based molecular residual disease (MRD) study, which has been accepted for presentation at the 2025 American Society of Clinical Oncology (ASCO) Annual Meeting.
Minimal Residual Disease Testing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.6 billion
Estimated market size in 2026
USD 3.0 billion
Projected market size by 2033
USD 7.1 billion
Growth rate
CAGR of 13.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Cancer type, technology, end-use, application, clinical application, product, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Exact Sciences Corporation, GRAIL, LLC, Veracyte, Inc., Natera, Inc., Guardant Health, F. Hoffmann-La Roche Ltd, FOUNDATION MEDICINE, INC., QIAGEN, mdxhealth., Bio-Techne
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Minimal Residual Disease Testing Market Report Segmentation
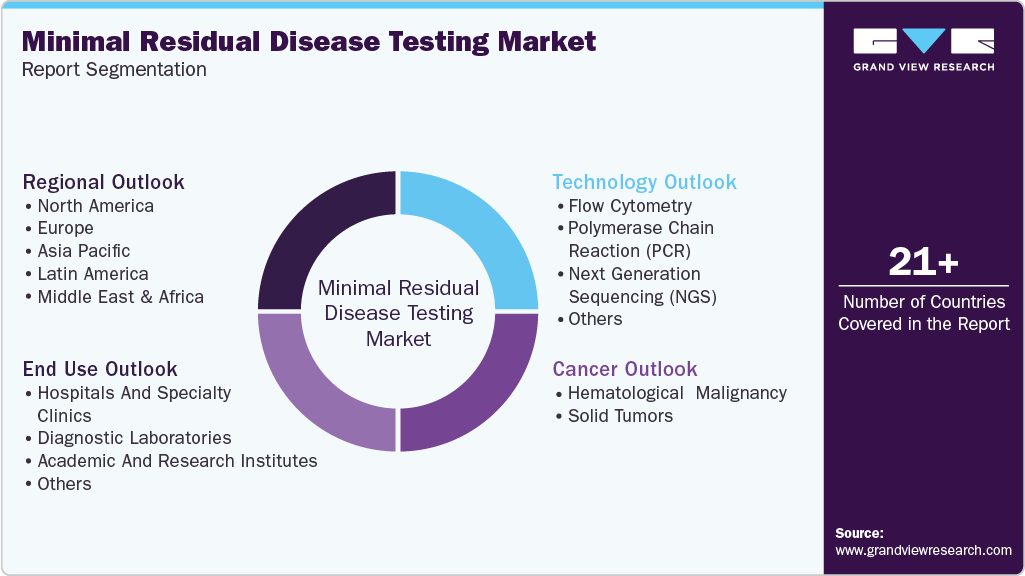
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global minimal residual testing disease market report based on cancer type, technology, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Flow Cytometry
-
Polymerase Chain Reaction (PCR)
-
Next Generation Sequencing (NGS)
-
Others
-
-
Cancer Outlook (Revenue, USD Million, 2021 - 2033)
-
Hematological Malignancy
-
Leukemia
-
Lymphoma
-
-
Solid Tumors
-
-
End use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals and Specialty Clinics
-
Diagnostic Laboratories
-
Academic and Research Institutes
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Spain
-
Italy
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The minimal residual disease testing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each minimal residual disease testing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Technology
Revenue capture definition
Flow Cytometry
Market value is primarily captured through instrument utilization, antibody panels, reagents, software, maintenance services, and laboratory testing volumes.
Polymerase Chain Reaction (PCR)
Revenue flows from assay kits, primers, probes, PCR instruments, consumables, software, and molecular diagnostic testing services.
Next Generation Sequencing (NGS)
Revenue is largely derived from sequencing platforms, library preparation kits, sequencing reagents, bioinformatics software, data analysis services, and laboratory testing.
Others
Market income originates from specialized assays, supporting consumables, dedicated instrumentation, software solutions, maintenance services, and laboratory testing.
Segment - Type
Revenue capture definition
Hematological Malignancy
Includes MRD testing for blood and bone marrow cancers where residual disease is monitored using molecular and cellular diagnostic technologies. Revenue is primarily captured through MRD assay kits, reagents, instruments, laboratory testing, software, and data interpretation services.
Solid Tumors
Covers MRD testing for non-hematological cancers using tissue- and liquid biopsy-based approaches to detect residual disease and recurrence. Revenue flows from sequencing assays, liquid biopsy kits, consumables, laboratory testing, bioinformatics software, and clinical interpretation services.
Segment -End use
Revenue capture definition
Academic and Research Institutes
Includes universities, research centers, and academic medical institutions utilizing MRD testing for translational research, biomarker discovery, and clinical studies. Revenue is primarily captured through research-use assay kits, instruments, reagents, software, and grant-funded testing activities.
Diagnostics Laboratories
Covers independent, reference, and centralized laboratories offering MRD testing as a diagnostic service. Revenue flows from test volumes, assay kits, reagents, instruments, laboratory workflow software, and result interpretation services.
Hospitals and Specialty Clinics
Encompasses hospitals and oncology or hematology specialty clinics performing or outsourcing MRD testing for patient management. Revenue is largely derived from diagnostic testing, assay consumables, instrument utilization, software, and clinical monitoring services.
Others
Includes contract research organizations, pharmaceutical companies, blood banks, and other healthcare facilities using MRD testing. Market income originates from specialized testing services, assay kits, consumables, instruments, and data analysis solutions.
Estimation Model
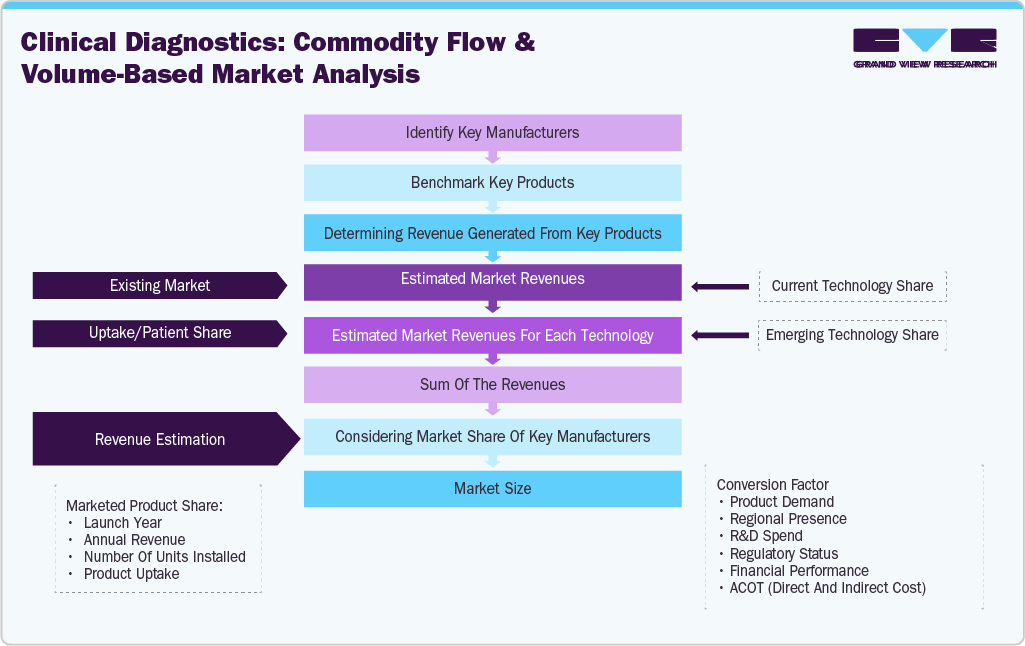
The Minimal Residual Disease (MRD) Testing Market size was estimated using a bottom-up approach by identifying key manufacturers, benchmarking their MRD testing portfolios, and analyzing revenues generated from relevant products and services. Market estimates were further validated by evaluating technology-wise adoption rates, patient uptake, and the market share of leading participants across major regions to derive the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
MRD Market Opportunity and Commercialization Strategy Assessment
Developed a comprehensive assessment of the global MRD testing market, evaluating market size, growth opportunities, competitive landscape, reimbursement trends, regulatory environment, technology adoption, and commercialization strategies across hematologic malignancies and solid tumors.
Enables diagnostic companies, pharmaceutical firms, and investors to identify high-growth market segments, optimize commercialization strategies, prioritize geographic expansion, and capitalize on emerging opportunities in precision oncology.
Precision Oncology and MRD Clinical Adoption Analysis
Delivered an in-depth analysis of MRD testing adoption across clinical settings, including assay utilization, physician adoption trends, treatment monitoring pathways, companion diagnostic opportunities, clinical guideline integration, and patient identification strategies across major cancer indications.
Provides actionable insights to improve market access strategies, strengthen clinical adoption, identify unmet diagnostic needs, and align product development with evolving precision medicine and oncology treatment paradigms.
Competitive Benchmarking and Pipeline Assessment
Conducted a detailed benchmarking of leading and emerging MRD testing companies, evaluating ctDNA- and NGS-based technologies, assay performance, clinical validation, regulatory milestones, strategic partnerships, reimbursement progress, and pipeline innovations across hematologic and solid tumor applications.
Supports strategic decision-making for portfolio expansion, partnership and licensing opportunities, competitive positioning, investment prioritization, and identification of future innovation and revenue-generation opportunities within the MRD testing market.
Frequently Asked Questions About This Report
Some key players operating in the minimal residual disease testing market include Exact Sciences Corporation, GRAIL, LLC, Veracyte, Inc., Natera, Inc., Guardant Health, F. Hoffmann-La Roche Ltd, FOUNDATION MEDICINE, INC., QIAGEN, mdxhealth., and Bio-Techne.
Key factors that are driving the market growth include the increasing prevalence of cancer, increasing consumer awareness for therapy, increasing funding for research with an increasing disposable income in emerging economies.
Asia Pacific is expected to be the fastest-growing segment in the minimal residual testing industry at a CAGR over the forecast period. The market is anticipated to witness significant growth driven by increasing cancer incidence and technological advancements.
The flow cytometry segment accounted for the largest revenue share of 35.9% in 2025, driven by its rapid and precise detection capabilities. This technology identifies abnormal cells by analyzing multiple cellular markers simultaneously, enabling clinicians to detect residual cancer cells even at very low levels.
Hematological malignancy cancer dominated the market with a revenue share in 2025 and is the fastest-growing segment, driven by the high prevalence of blood cancers such as leukemia, lymphoma, and multiple myeloma.
Expanding adoption of personalized oncology and precision medicine is increasing demand for MRD testing to guide treatment selection, monitor therapy response, and detect relapse earlier. Additionally, the growing use of MRD assays in clinical trials and regulatory acceptance as a surrogate endpoint are creating new commercial opportunities for test developers.
The global minimal residual disease testing market size was valued at USD 2.6 billion in 2025 and is estimated at USD 3.0 billion for 2026.
The global minimal residual disease testing market is expected to grow at a CAGR of 13.2% from 2026 to 2033, reaching USD 7.1 billion by 2033.
North America dominated the minimal residual disease testing market with a share of 46.4% in 2024. This is attributable to advanced healthcare infrastructure, high adoption of MRD testing technologies, and a strong presence of key industry players.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


