
- Home
- »
- Drilling & Extraction Equipments
- »
-
Mining Lubricants Market Size & Share Report, 2026-2033GVR Report cover

Mining Lubricants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Mineral Oil, Synthetic, Bio-based), By Application (Coal Mining, Iron Ore Mining, Bauxite Mining, Rare Earth Mineral, Precious Metal Mining), By Region, And Segment Forecasts
Market Size, 2025
$7.4BMarket Estimate, 2026
$7.7BMarket Forecast, 2033
$10.5BCAGR, 2026–2033
4.6%Mining Lubricants Market Summary
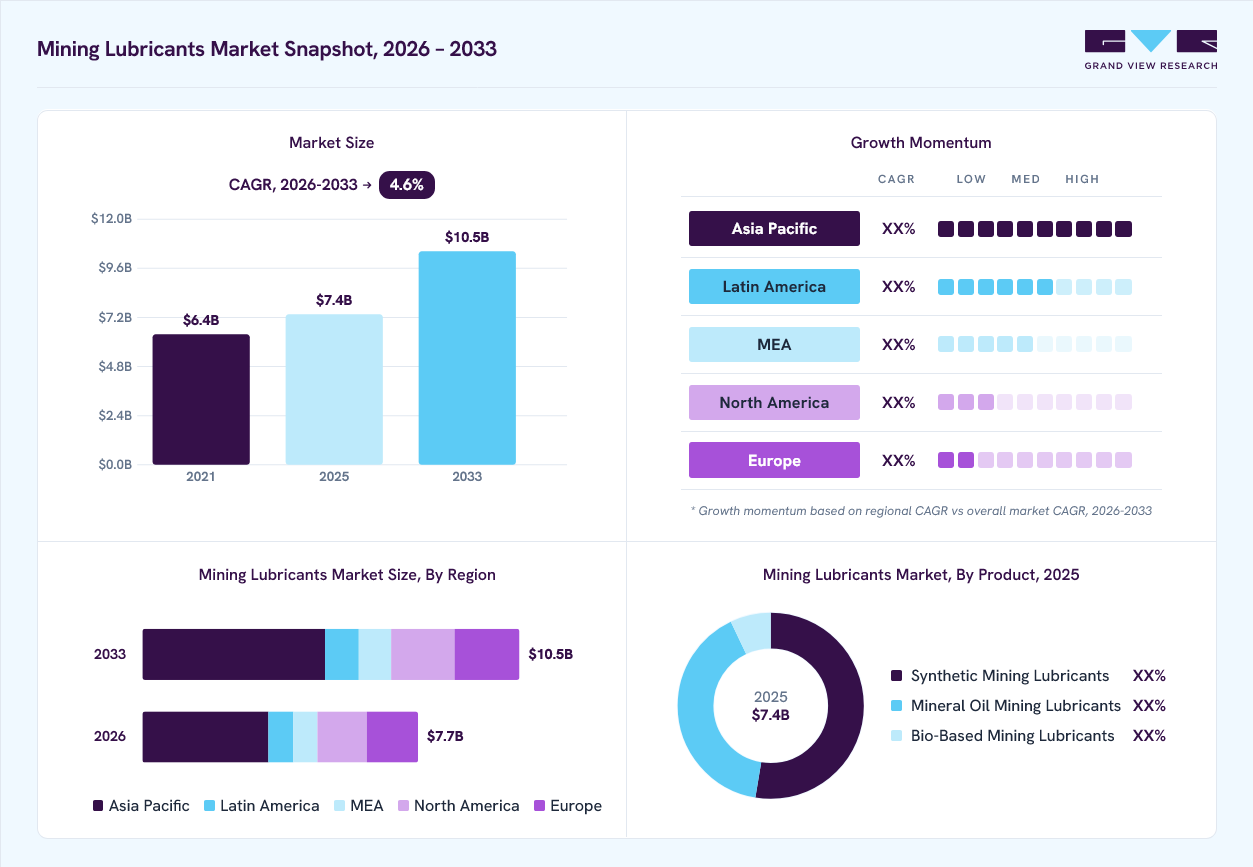
The global mining lubricants market size was valued at USD 7.4 billion in 2025 and is projected to grow from USD 7.7 billion in 2026 to USD 10.5 billion by 2033, at a CAGR of 4.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 45.4% in 2025. This is attributed to the growing demand for products to improve the performance of equipment and machinery in mining operations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product, synthetic mining lubricants held a dominant position, contributing 52.6% of total revenue in 2025.
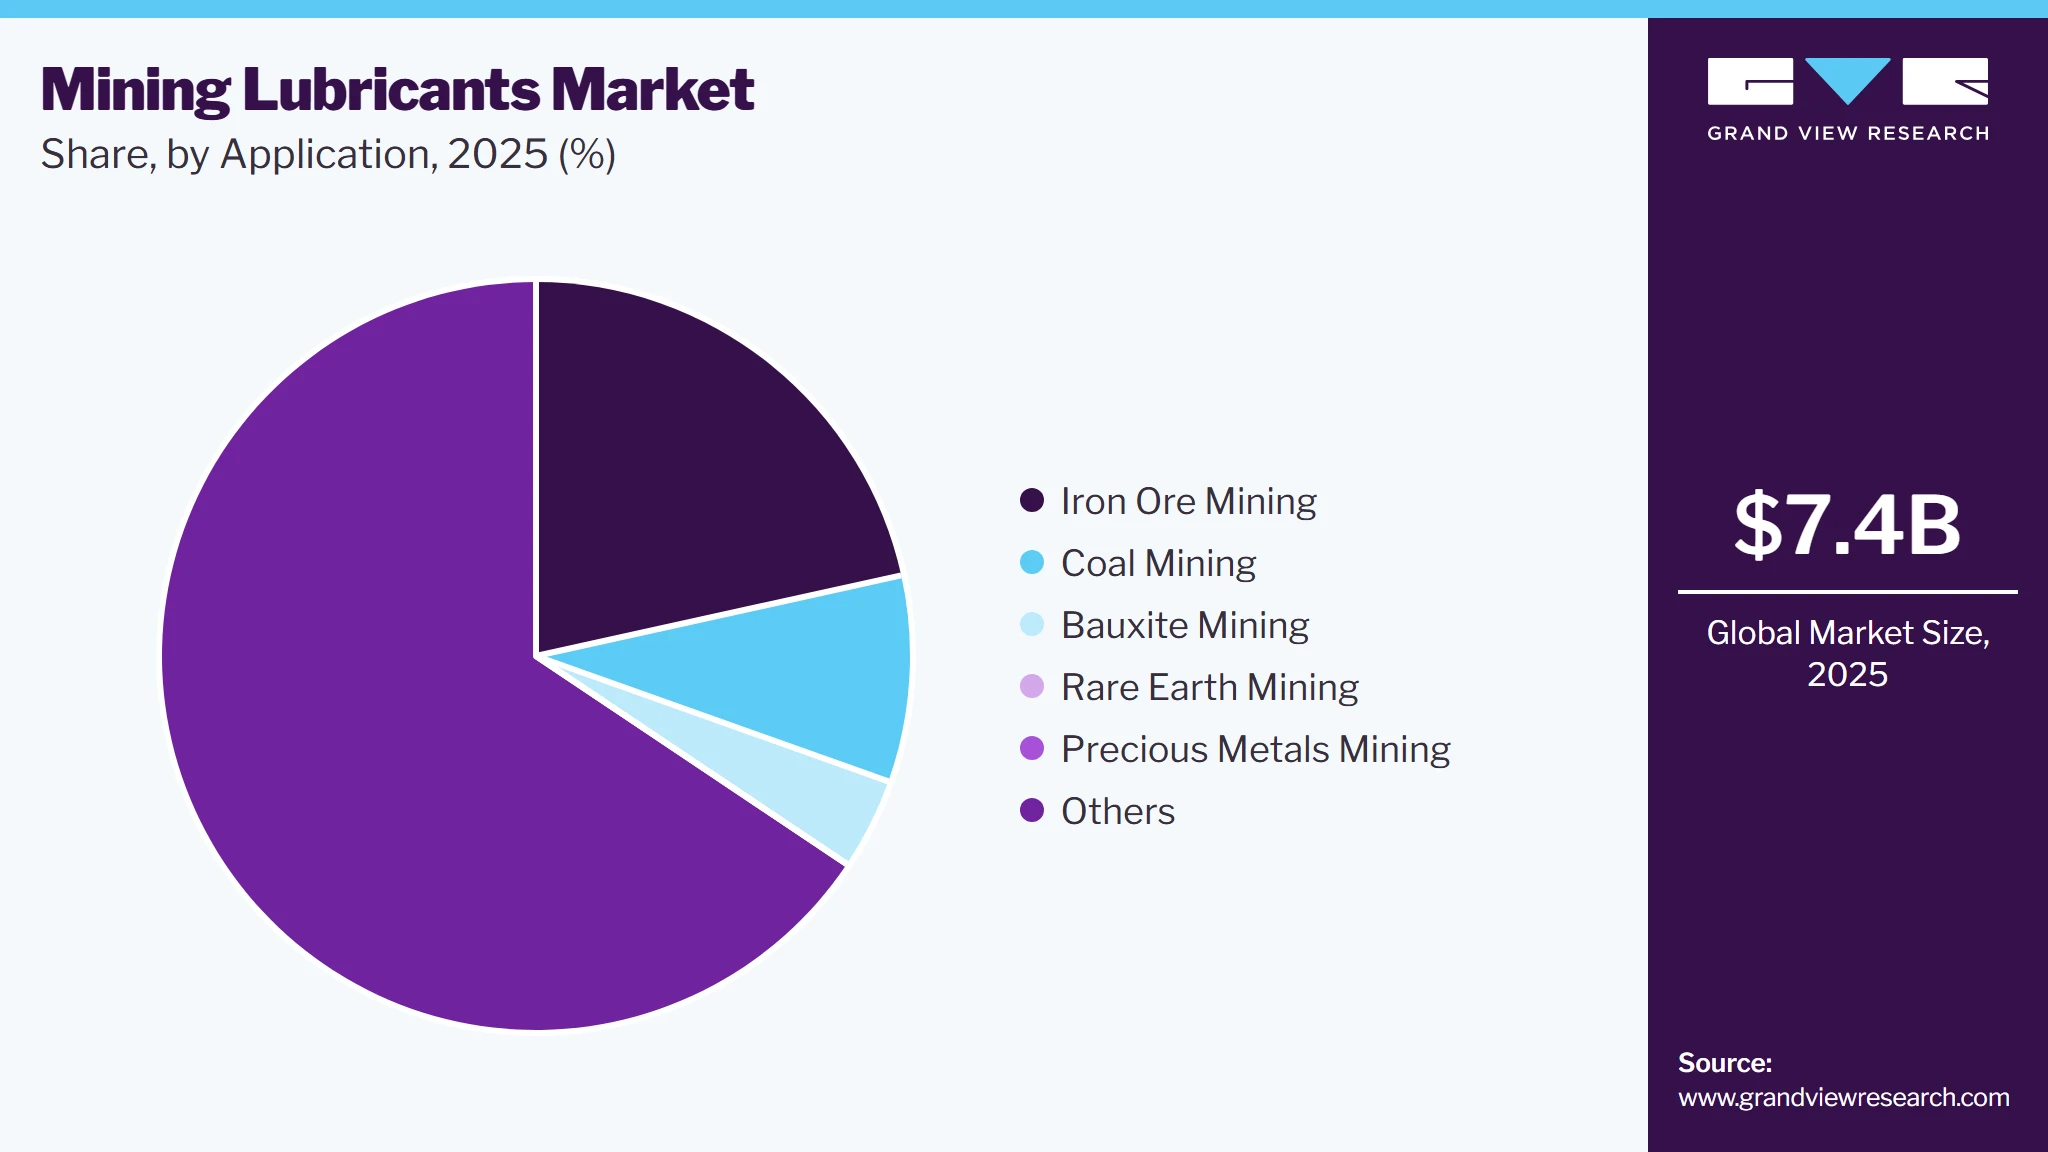
- Iron ore mining segment accounted for the largest revenue of 21.5% in 2025.
Regional Highlights
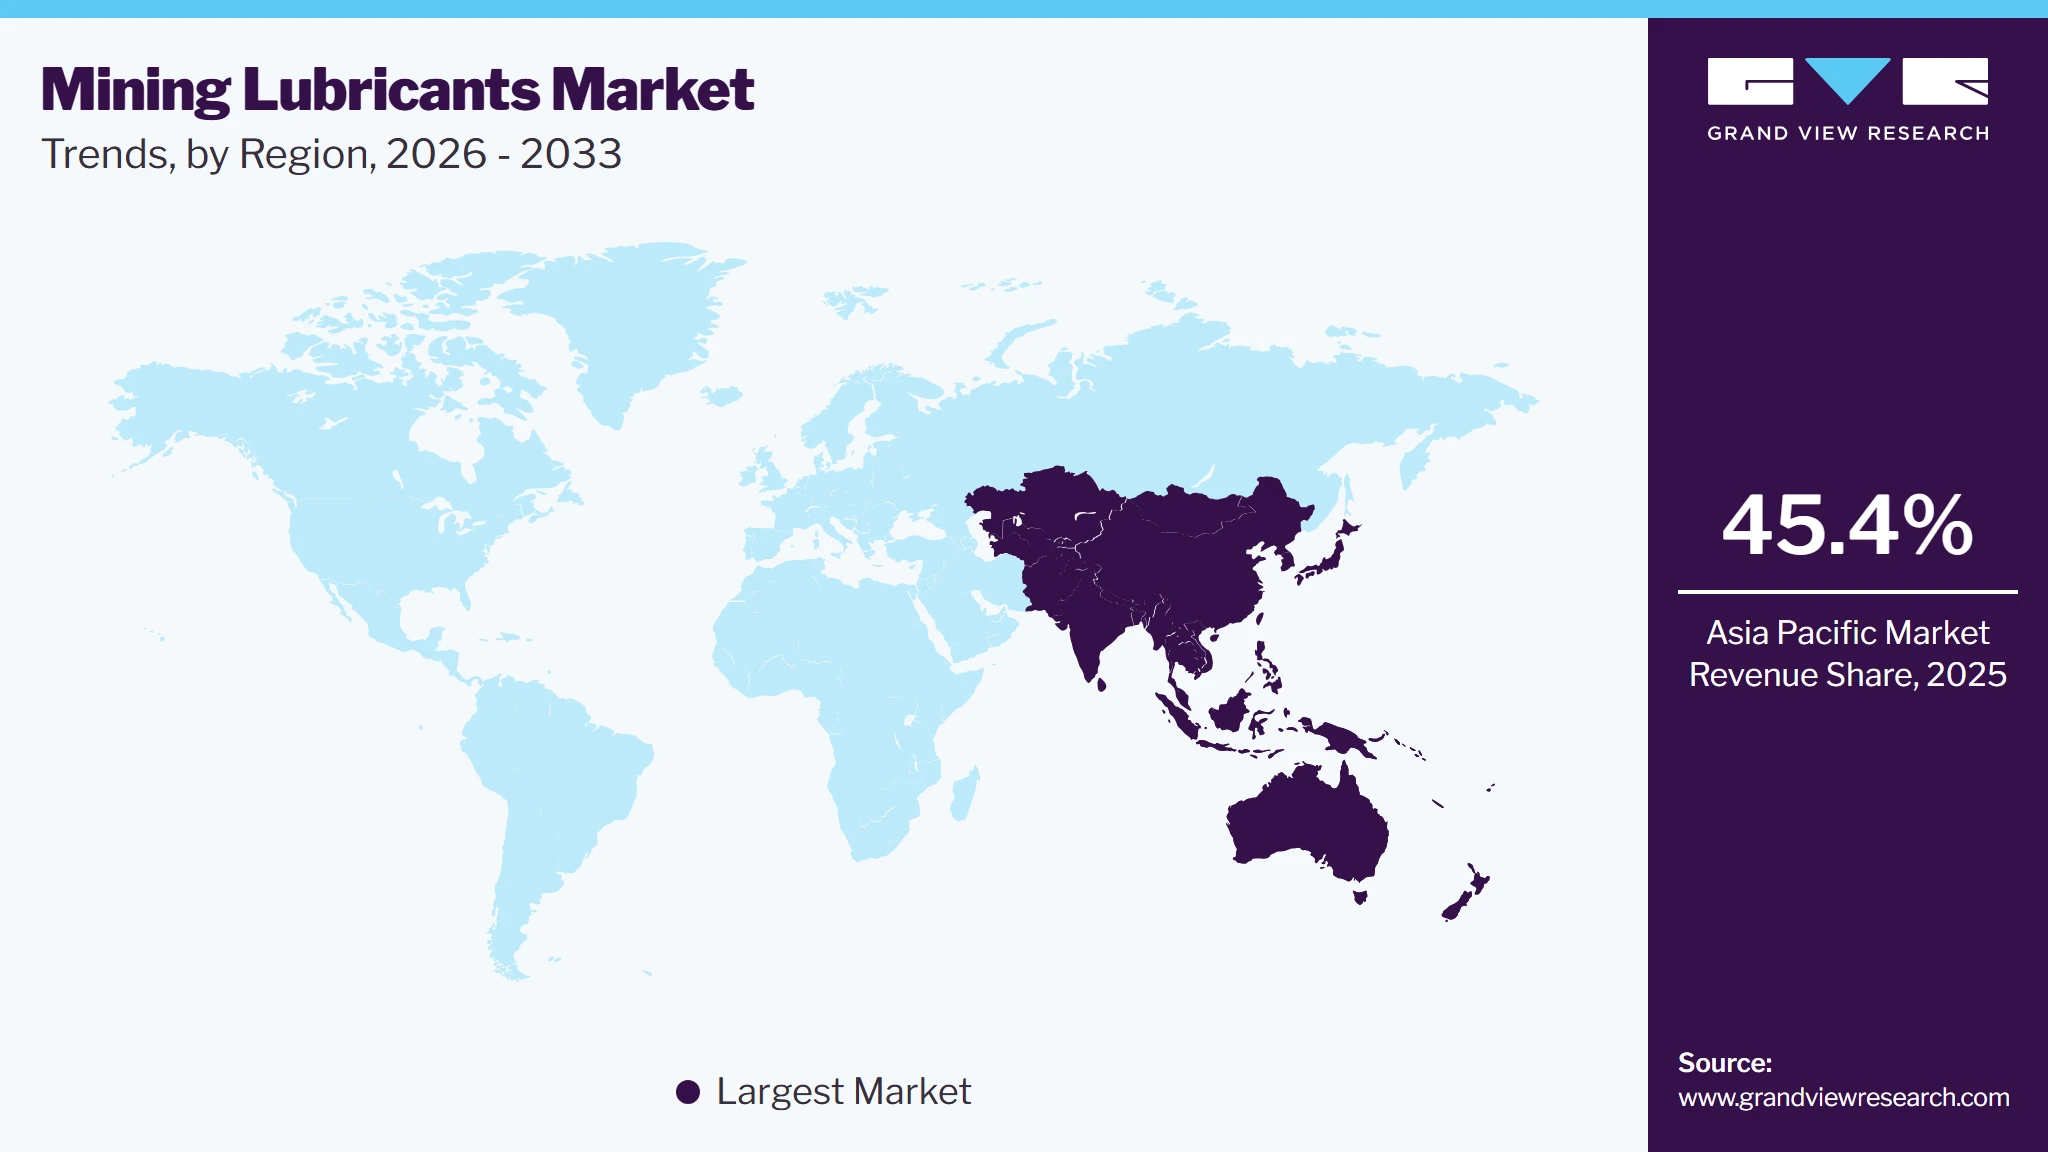
- Largest regional market: Asia Pacific (45.4% revenue share, 2025)
- By country: China held the largest share in 2025.
Market Size & Forecast
- Market Size in 2025: USD 7.4 Billion
- Estimated Market Size in 2026: USD 7.7 Billion
- Projected Market Size by 2033: USD 10.5 Billion
- CAGR (2026-2033): 4.6%
Prism AI by Grand View Research Free to tryAsk a question about the mining lubricants marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The global market continues to expand, due to rising consumer awareness about the advantages of adopting automatic lubrication systems. Major mining companies worldwide are gradually transitioning from inefficient manual lubrication techniques to highly effective automatic lubrication procedures. This switch from manual to automatic lubrication systems remains the primary driver of growth. The industry is undergoing significant changes in terms of production shift from synthetic to bio-based. Although the shift in the sector is gradual, various factors including demand patterns for lubricant oil, government directives, feedstock choices, and products across all major businesses play a vital role in propelling the market.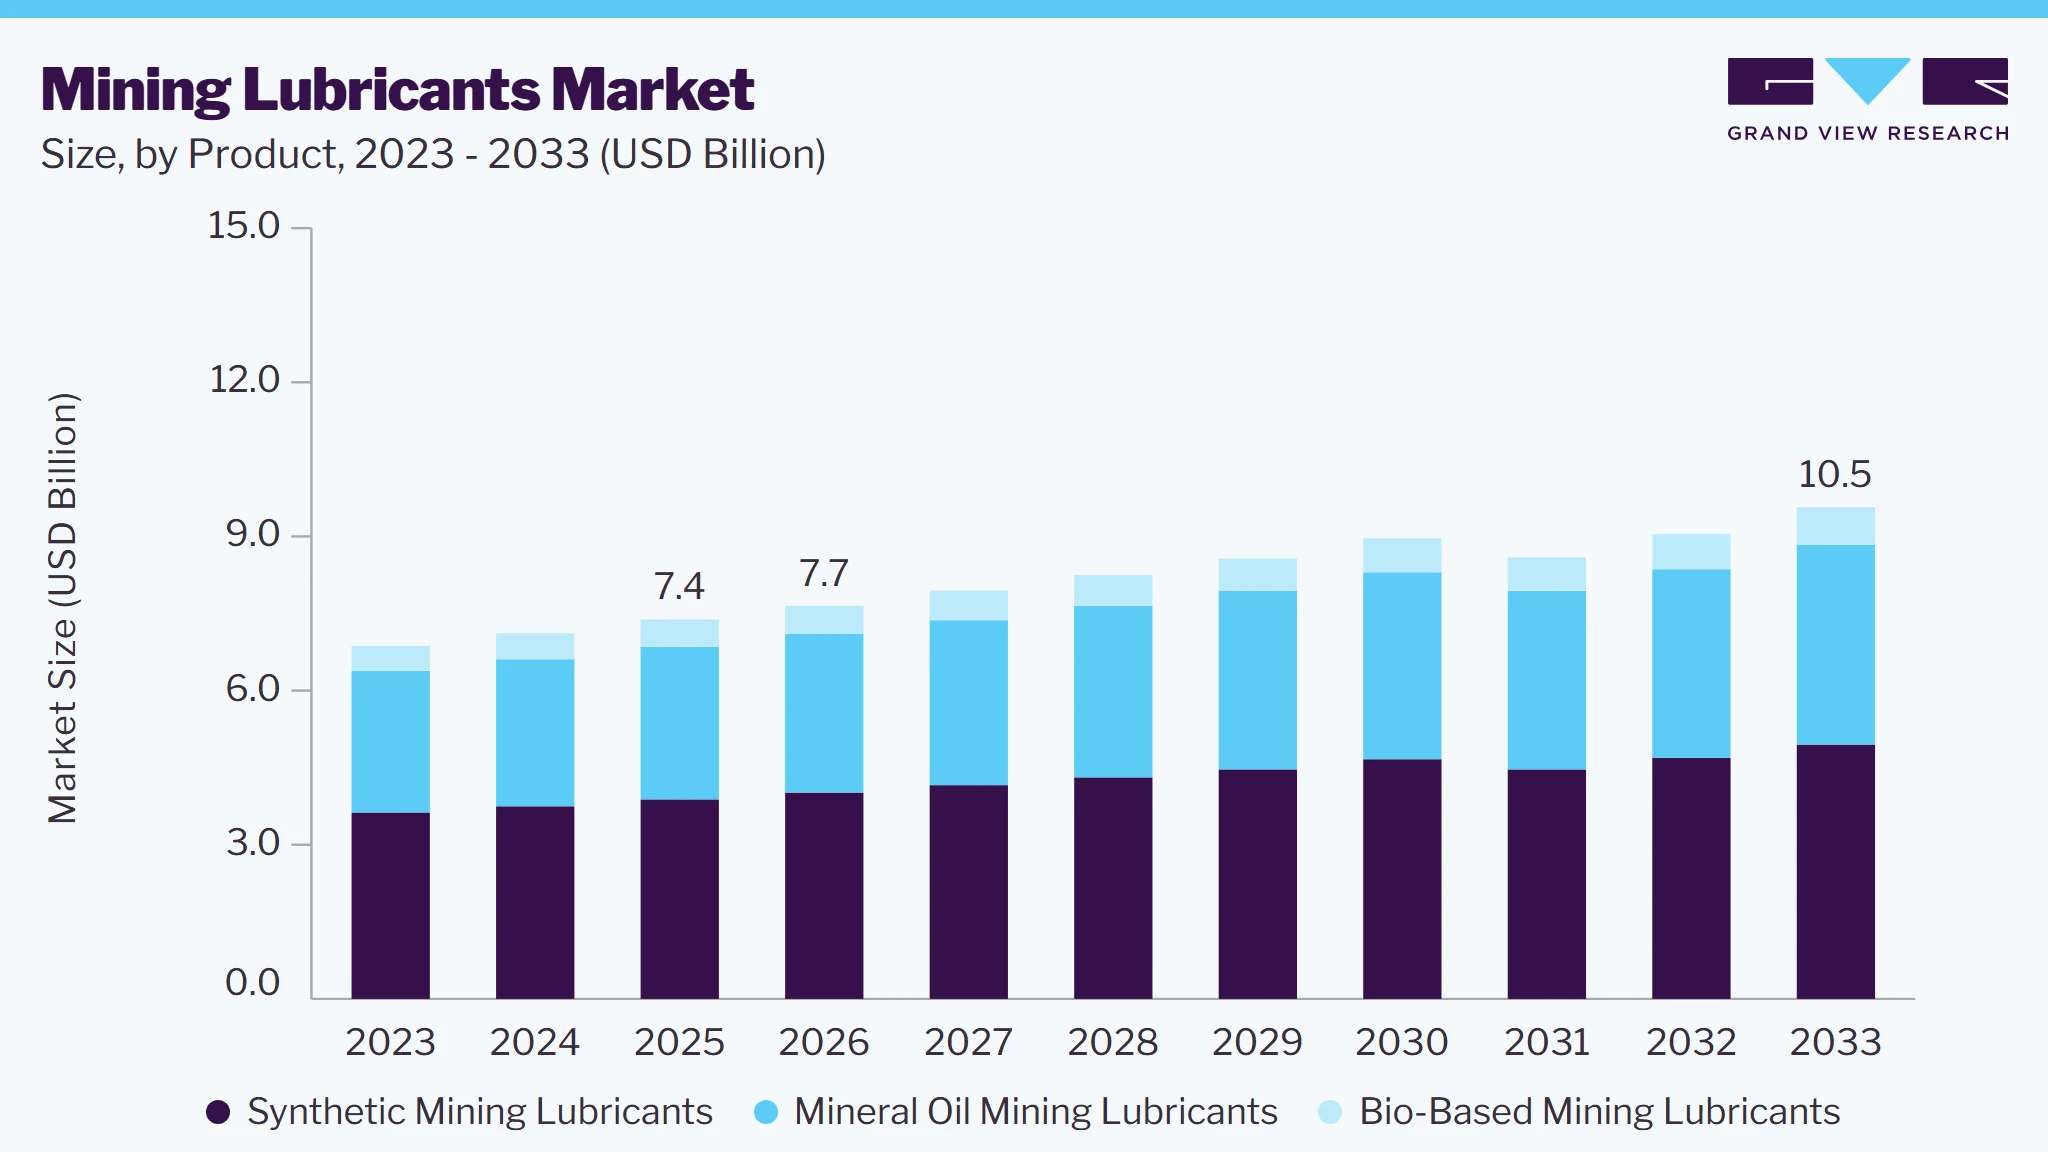 To learn more about this report, Download Free Sample Report
The demand for products with long life, low volatility, and high purity is expected to surge in the near future. The molecular structure of the product continues to undergo major innovation to provide improved lubrication to different machines and equipment. This is anticipated to lead to enhanced product composition and the utilization of improved feedstocks, hydro-processing catalysts, and processes.
Market Dynamics
The global mining lubricants market is driven by increasing mining activities, growing demand for minerals and metals, and the rising adoption of high-performance lubricants to enhance equipment reliability and operational efficiency. The market is further supported by investments in mining infrastructure, automation, and the use of heavy-duty machinery operating under extreme conditions. However, fluctuations in base oil prices and stringent environmental regulations regarding lubricant formulations pose challenges to market growth. At the same time, the development of synthetic and bio-based lubricants, along with the expansion of mining operations in emerging economies, is expected to create significant growth opportunities for industry participants over the forecast period.
The expansion of mining operations to meet the growing global demand for critical minerals, base metals, coal, and industrial minerals is a key factor driving the global mining lubricants market. Increasing investments in new mining projects, capacity expansions, and mineral exploration activities have led to greater deployment of heavy-duty equipment such as excavators, haul trucks, loaders, crushers, and drilling rigs. These machines operate under high loads, extreme temperatures, and harsh environmental conditions, creating sustained demand for specialized lubricants that ensure reliable performance and reduce mechanical wear.
Furthermore, mining companies are placing greater emphasis on maximizing equipment availability while minimizing maintenance costs and unplanned downtime. High-performance mining lubricants enhance component protection, improve fuel efficiency, extend oil drain intervals, and increase the operational life of critical equipment, thereby lowering the total cost of ownership. As mining operators continue to prioritize productivity, operational efficiency, and asset reliability, the adoption of advanced lubricant formulations is expected to remain a significant driver of market growth throughout the forecast period.
Fluctuations in crude oil and base oil prices remain a significant restraint for the global mining lubricants market, as they directly influence the production cost of mineral- and synthetic-based lubricants. Unpredictable raw material prices create pricing uncertainty for lubricant manufacturers and mining operators, making long-term procurement and cost management more challenging. This is particularly impactful for mining companies with large lubricant consumption, where higher input costs can increase overall operating expenses and reduce profit margins.
Frequent price volatility disrupts supply chain planning and may delay purchasing decisions, especially in cost-sensitive mining operations. Although high-performance lubricants deliver long-term operational benefits through reduced maintenance and extended equipment life, the higher upfront costs associated with premium lubricant products may limit their adoption among smaller mining companies and contractors, thereby restraining overall market growth.
The increasing focus on operational efficiency, equipment longevity, and environmental compliance is creating significant opportunities for synthetic and environmentally sustainable mining lubricants. Mining operators are progressively adopting high-performance synthetic lubricants that offer superior thermal stability, oxidation resistance, and extended drain intervals, helping reduce maintenance frequency and improve equipment reliability in demanding operating environments. This shift is particularly evident in large-scale mining operations seeking to optimize lifecycle costs and maximize asset utilization.
Tightening environmental regulations and corporate sustainability initiatives are encouraging the development and adoption of bio-based and low-emission lubricant formulations. Manufacturers are investing in advanced lubricant technologies that enhance performance while minimizing environmental impact, enabling them to meet evolving regulatory standards and customer sustainability goals. As mining companies increasingly prioritize responsible operations, demand for innovative and sustainable lubricant solutions is expected to present substantial growth opportunities for market participants.
Analyst Perspective
The global mining lubricants market is expected to witness steady growth, driven by increasing mining activities, rising demand for critical minerals, and the growing adoption of high-performance lubrication solutions to improve equipment reliability and operational efficiency. While volatility in raw material prices and stringent environmental regulations remain key challenges, continuous advancements in synthetic and bio-based lubricant technologies are creating new growth opportunities. Companies that focus on product innovation, technical support, and sustainable lubricant solutions are expected to strengthen their competitive position as mining operators increasingly prioritize productivity, cost optimization, and equipment lifecycle management.
Product Insights
By product, synthetic mining lubricants held a dominant position, contributing 52.6% of total revenue in 2025. The growth is attributed to the extensive use of synthetic oils. The trend in the industry continues to shift towards higher-performance oils and greases, including synthetics, as the technology in both equipment and lubricants undergoes advancements. This is expected to lead to longer oil drain times, improved energy efficiency, and longer lifespan of components. This is expected to propel the demand for synthetic products over the forecast period.
The mineral oil mining lubricant was the second-largest segment and accounted for a revenue share of 40.0% in 2021. The growth is attributed to its compatibility with various material surfaces including seals, metals, and coatings. Its composition can also be chemically altered to make it semi-synthetic via the distillation process. This is anticipated to propel the demand for mineral oil-based lubricants over the forecast period. The mineral oil mining lubricants are produced by distilling crude. These lubricants can be quickly disposed of and used again due with the help of the existing infrastructure.
Mineral oil mining lubricants are often used for multipurpose lubrication of mechanical components. These include components such as slides, chains, bearings, gears, and other threaded connections, wherein the operating temperatures range from -62.6°F to 302°F
Application Insights
Iron ore mining segment accounted for the largest revenue of 21.5% in 2025. This is attributed to its importance as the crucial raw material for manufacturing steel. Moreover, Steel is indispensable for the preservation of a robust industrial base. Steelmaking uses 98% of the mined iron ore. Around 50 different nations mine iron ore including Australia, China, Brazil, India, and others.
 To learn more about this report, Download Free Sample Report
About three-quarters of the world's production can be traced back to just seven major countries. Furthermore, Australia and Brazil account for nearly one-third of all iron ore exports and dominate the market. With increased production of iron ore in developing countries, the demand for iron ore mining lubricants is anticipated to increase over the forecast period.
Coal mining was the second-largest segment and accounted for a revenue share of over 8.8% in 2021. The growth is attributed to the application of coal for numerous purposes. These include the production of steel, cement, production of thermal energy, and heating. Mining operations are expected to expand as a result of the high demand for coal in chemicals, ceramics, fabrication of various metals, and papers by manufacturing facilities, This would, in turn, boost the demand for mining lubricants in coal mining.
Mining lubricants are also used in heavy machinery, which increases its demand in several key industries heavily reliant on heavy machinery Furthermore, coal mines require high-performance lubricants with high viscosity index, oxidation resistance, and corrosion prevention qualities, making way for continuous product enhancements.
Regional Insights
Asia Pacific dominated the mining lubricants market with the highest revenue share of 45.4% in 2025. It is expected to continue its dominance over the forecast period. This can be attributed to rising steel demand in developing countries, particularly in China and India, thanks to the region's dependence on steel for construction and transportation activities.
 To learn more about this report, Download Free Sample Report
China Mining Lubricants Market Trends
China dominated the Asia Pacific mining lubricants market in 2025. It is the largest producer of coal, gold, and other earth minerals. Increasing foreign investment in Asia Pacific countries, mainly China and India has contributed to the growth. China is home to numerous mines, which are being prepared and developed for operations. The product is extensively utilized in mining machinery and equipment in the country to reduce downtime. This is expected to propel the growth of the market in China during the forecast period.
India is the world's second-largest producer of coal and fourth-largest producer of iron ore. Significant mining activities in the country are expected to promote the utilization of products in India over the forecast period. In addition, liberalized foreign direct investment (FDI), and favorable policies to promote investments in India are anticipated to fuel the growth of the mining industry. This is anticipated to drive strong demand for the product. India has abundant natural reserves of limestone, bauxite, coal, and diamond. It is anticipated that the country's booming mining and mineral processing industries will encourage the use of these products in the area. In the upcoming years, this is anticipated to fuel the growth of the market in Asia Pacific over the forecast period
Europe Mining Lubricants Market Trends
Europe accounted for a revenue share of 19.6% in 2021 and is predicted to grow at a CAGR of more than 2% over the forecast period. Europe remains mature, technologically advanced, and innovative. The region has abundant mineral resources and therefore, mineral extraction plays a pivotal role in the economy. Increasing consumption of metals and minerals in Europe is anticipated to drive the demand for mining lubricants. However, rigid environmental regulations, particularly in relation to the coal industry, are anticipated to promote the development of sustainable products over the forecast period.
Key Mining Lubricants Company Insights
Market players are involved in adopting several strategies including joint ventures business expansions, and new product development to increase their global presence. For instance, in September 2019, Chevron Corporation entered into a three-party collaboration with Schlumberger Limited & Microsoft to accelerate the development of innovative petrotechnical and digital technologies. Some prominent players in the mining lubricants market include:
Key Mining Lubricants Companies
The following key companies have been profiled for this study on the mining lubricants market.
-
Exxon Mobil Corporation
-
Shell plc
-
Quaker Chemical Corporation
-
BASF SE
-
Sinopec Corp.
-
BP P.L.C.
-
FUCHS
-
Total S.A.
-
Kluber Lubrication
-
Chevron Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Exxon Mobil Corporation, Shell plc, BP p.l.c., Chevron Corporation, TotalEnergies (formerly Total S.A.), FUCHS, BASF SE, Sinopec Corp)
- Focus on expanding global production capacity, strengthening long-term supply agreements with mining companies, investing in R&D for high-performance and synthetic lubricants, and leveraging extensive distributor and OEM partnerships to maintain market leadership.
- Strong global brand recognition, comprehensive mining lubricant portfolios, advanced formulation capabilities, integrated refining operations, robust distribution networks, and long-standing relationships with major mining operators worldwide.
- Higher operating costs, exposure to crude oil price fluctuations, and comparatively slower commercialization of niche or customized lubricant solutions due to large organizational structures.
Emerging Players (Quaker Chemical Corporation, Klüber Lubrication)
- Focus on developing specialty and application-specific lubricant solutions, expanding presence through technical service offerings, strategic partnerships, and targeting high-value mining applications requiring premium lubrication performance.
- Strong expertise in specialty lubricants, customized product development, superior technical support, and differentiated solutions for critical mining equipment operating under extreme conditions.
- Smaller global production and distribution footprint compared to major integrated oil companies, lower brand penetration in price-sensitive markets, and limited presence across all mining regions.
Mining Lubricants Market Report Scope
Report Attribute
Details
Market Size in 2025
USD 7.4 billion
Estimated Market Size in 2026
USD 7.7 billion
Projected Market Size by 2033
USD 10.5 billion
Growth rate
CAGR of 4.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million, Volume in kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, Germany, UK, Italy, Spain, China, Japan, India, Brazil, Argentina, Saudi Arabia, South Africa
Key companies profiled
Exxon Mobil Corporation; Shell plc; Quaker Chemical Corporation; BASF SE, Sinopec Corp.; BP P.L.C., FUCHS; Total S.A.; Kluber Lubricantion; Chevron Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Mining Lubricants Market Report Segmentation
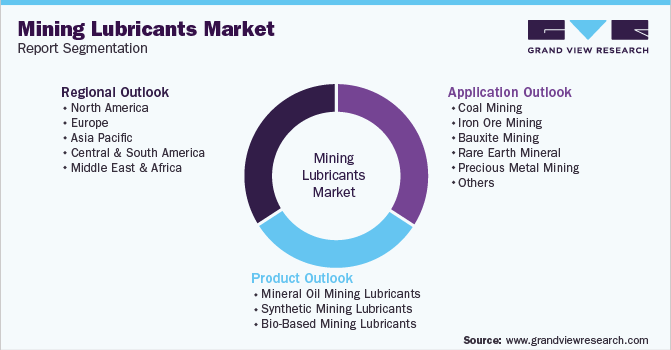
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global mining lubricants market report based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Mineral Oil Mining Lubricants
-
Synthetic Mining Lubricants
-
Bio-Based Mining Lubricants
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Coal Mining
-
Iron Ore Mining
-
Bauxite Mining
-
Rare Earth Mineral
-
Precious Metal Mining
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The mining lubricants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each mining lubricants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Mineral Oil Mining Lubricants
Revenue generated from the sale of mineral oil-based lubricants used in mining equipment, including engine oils, hydraulic oils, gear oils, transmission fluids, greases, and other lubrication products for surface and underground mining operations.
Synthetic Mining Lubricants
Revenue generated from the sale of synthetic lubricants formulated for mining equipment requiring superior thermal stability, oxidation resistance, extended drain intervals, and enhanced performance under extreme operating conditions.
Bio-Based Mining Lubricants
Revenue generated from the sale of bio-based and biodegradable lubricants used in mining operations to support environmental compliance, sustainability objectives, and equipment lubrication in environmentally sensitive areas.
Segment - Application
Revenue capture definition
Coal Mining
Revenue generated from mining lubricants supplied for equipment used in coal extraction, processing, material handling, and transportation across surface and underground mining operations.
Iron Ore Mining
Revenue generated from mining lubricants utilized in iron ore extraction, crushing, beneficiation, hauling, and processing equipment to improve operational efficiency and equipment reliability.
Bauxite Mining
Revenue generated from lubricants consumed in bauxite mining equipment, including excavation, loading, hauling, and ore processing machinery.
Rare Earth Element Mining
Revenue generated from lubricants used in equipment involved in the extraction, processing, and handling of rare earth elements, where reliable equipment performance is essential under demanding operating conditions.
Precious Metal Mining
Revenue generated from mining lubricants used in the extraction and processing of precious metals such as gold, silver, platinum, and related mining activities requiring continuous equipment operation.
Others
Revenue generated from lubricants supplied to mining equipment used in the extraction of other minerals and metals, including copper, nickel, zinc, lead, lithium, phosphate, potash, limestone, and other industrial minerals.
Estimation Model
Layer Name
Key Question
Description
Mining Industry Assessment
What is the size and growth outlook of global mining activities?
Evaluates mining production, mineral demand, active mining projects, and regional mining investments to establish the addressable market for mining lubricants.
Equipment Fleet Analysis
Which mining equipment consumes lubricants?
Assesses the installed base and utilization of mining equipment such as haul trucks, excavators, loaders, drills, crushers, conveyors, and underground machinery across mining operations.
Lubricant Consumption Assessment
How much lubricant is consumed per equipment category?
Estimates lubricant consumption by equipment type, lubricant category, operating hours, maintenance schedules, and replacement intervals to determine volume demand.
Product Mix Analysis
Which lubricant products generate the highest demand?
Analyzes the share of engine oils, hydraulic oils, gear oils, transmission fluids, greases, compressor oils, and other specialty lubricants across mining applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
A comprehensive regional assessment of the mining lubricants market was conducted across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. The study evaluated country-level demand for mineral oil, synthetic, and bio-based mining lubricants while examining lubricant consumption across coal, iron ore, bauxite, rare earth element, precious metal, and other mining operations. Mining production trends, equipment utilization, and regional mining activity were also assessed.
Provides deeper visibility into regional lubricant demand and mining activity across key mineral-producing countries. Supports capacity planning, market prioritization, and regional expansion strategies.
Cross-Segmentation Analysis
The relationship between lubricant type and mining application was assessed to evaluate the adoption of mineral oil, synthetic, and bio-based lubricants across different mining operations. The analysis examined equipment lubrication requirements, operating conditions, and product performance to identify application-specific demand trends across surface and underground mining activities.
Enables identification of high-value product-application combinations and evolving lubricant preferences. Supports portfolio optimization, targeted product development, and commercialization strategies for mining end users.
Opportunity Assessment
Growth opportunities were assessed across bio-based mining lubricants, high-performance synthetic formulations, autonomous mining equipment, and lubrication solutions for critical mineral extraction. The analysis also examined opportunities arising from increasing mining investments, equipment modernization, and sustainability initiatives within the global mining industry.
Enables identification of high-growth product segments and emerging application areas. Supports innovation planning, portfolio expansion, and long-term strategic investment decisions.
Frequently Asked Questions About This Report
By product, synthetic mining lubricants held a dominant position, contributing 52.6% of total revenue in 2025. Growth is driven by the superior performance of synthetic lubricants in reducing equipment wear, improving operational efficiency, extending maintenance intervals, and minimizing downtime in demanding mining environments.
Iron ore mining segment accounted for the largest revenue share of 21.5% in 2025. Growth is driven by rising global iron ore extraction activities, expanding steel production, and increasing demand for advanced mining lubricants that improve equipment efficiency and extend service life under severe operating conditions.
The mining lubricants market is primarily restrained by the volatility in base oil and additive prices, which increases production costs and affects manufacturers' profit margins. In addition, fluctuations in mining activities due to commodity price cycles, along with the high initial cost of premium synthetic lubricants, can limit adoption, particularly among cost-sensitive mining operators.
The market offers significant opportunities through the increasing adoption of synthetic and bio-based lubricants, expansion of mining activities for critical minerals such as lithium, copper, and nickel, and the growing use of predictive maintenance and automated mining equipment. These trends are driving demand for high-performance lubricants that enhance equipment reliability, reduce maintenance costs, and support sustainability objectives.
The global mining lubricants market size was estimated at USD 7.4 billion in 2025 and is projected to grow from USD 7.7 billion in 2026.
The global mining lubricants market is expected to grow at a compound annual growth rate of 4.6% from 2026 to 2033 to reach USD 10.5 billion by 2033.
Asia Pacific dominated the mining lubricants market with a share of 45.4% in 2025. This is attributable to rising steel demand in developing countries, particularly in China and India, as well as the region's dependence on steel for construction and transportation activities.
Some key players operating in the mining lubricants market include Exxon Mobil Corporation, Shell plc, Quaker Chemical Corporation, BASF SE, Sinopec Corp., BP P.L.C., FUCHS, Total S.A., Kluber Lubricantion and Chevron Corporation.
Key factors that are driving the market growth include rising demand for mining equipment and increasing implementation of automatic lubrication systems in mining operations thereby fueling the consumption of mining lubricants used in them.
About the Author(s)
Drilling & Extraction Equipments Research Team
Bulk Chemicals · Drilling & Extraction EquipmentsThis report was authored by the drilling & extraction equipments research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the drilling & extraction equipments segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


