
- Home
- »
- Pharmaceuticals
- »
-
Myasthenia Gravis Treatment Market Size Report, 2026-2033GVR Report cover

Myasthenia Gravis Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Treatment Type (Thymectomy, Cholinesterase Inhibitors, Rapid Immunotherapies), By End-use (Hospitals, Clinics), By Region and Segment Forecasts
Market Size, 2025
$2.8BMarket Estimate, 2026
$3.0BMarket Forecast, 2033
$5.1BCAGR, 2026–2033
7.8%Myasthenia Gravis Treatment Market Summary
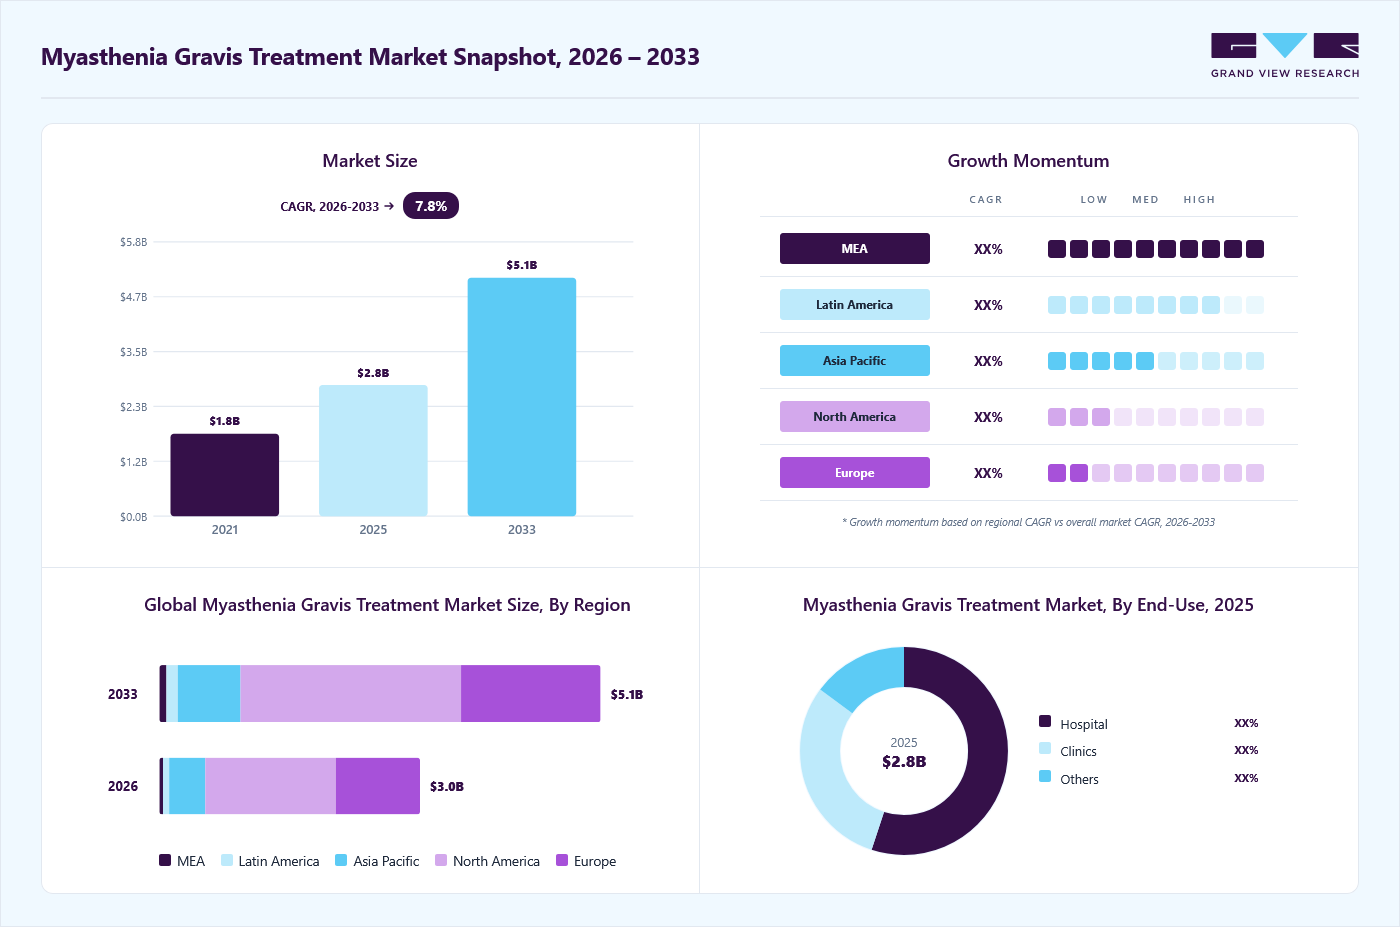
The global myasthenia gravis treatment market size was estimated at USD 2.8 billion in 2025 and is projected to grow from USD 3.0 billion in 2026 to USD 5.1 billion by 2033, growing at a CAGR of 7.8% from 2026 to 2033. The North America market held the largest share of 50.7% of the global market in 2025. The key factors driving this market include the rising adoption of immunotherapies, the approval of promising drugs, the emergence of biologics, and increasing awareness of rare diseases.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By treatment type: The monoclonal antibodies segment led the market with the largest revenue share of 54.8% in 2025.
- By end-use: The hospital segment led the market with the largest revenue share of 55.0% in 2025.
Regional Highlights
- Largest regional market: North America (50.7% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.8 Billion
- Estimated market size in 2026: USD 3.0 Billion
- Projected market size by 2033: USD 5.1 Billion
- CAGR (2026-2033): 7.8%
Prism AI by Grand View Research Free to tryAsk a question about the myasthenia gravis treatment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Myasthenia gravis (MG) is a chronic, progressive, and rare neuromuscular disorder that is characterized by weakness of the head, limb, spinal, eye, and respiratory muscles. In this autoimmune disorder, antibodies are produced against the acetylcholine receptor (AchR) that impedes the normal transmission of electrical signals from nerves to muscles.According to the National Organization for Rare Disorders (NORD), in the U.S., around 14-40 per 100,000 individuals suffer from myasthenia gravis. Reports suggest that the frequency of the disorder is on the rise over the last several decades. This can be attributed to the better identification of patients and the increasing prevalence of autoimmune disorders worldwide.
 To learn more about this report, Download Free Sample Report
Myasthenia gravis occurs more frequently in females than males, and although symptoms may appear at any age, its onset usually peaks in men in their 50s or 60s and women during their 20s or 30s. There is no proven cure for myasthenia gravis; however, patients can be treated with medications and surgery to manage the symptoms.
Currently, research is focused on better understanding the specifics of the autoimmune problems associated with MG and improving their diagnosis and treatment. Additionally, the market is observing a paradigm shift in research from suppressing the immune system to rebalancing it. Another important area of research is the physiology of the neuromuscular junction (NMJ), aimed at improvement in its function regardless of probable immune system attacks.
Market Dynamics
The myasthenia gravis treatment market is evolving as healthcare providers emphasize earlier diagnosis, timely intervention, and improved disease management. Market expansion is supported by increasing awareness among healthcare professionals, growing adoption of targeted therapies, and continued investment in clinical research addressing unmet patient needs. Pharmaceutical companies are developing therapies aimed at improving symptom control, enhancing patient outcomes, and reducing treatment burden. Recent regulatory approvals and expanded treatment options have broadened the therapeutic landscape and created opportunities across major healthcare markets. Market dynamics are influenced by treatment accessibility, reimbursement policies, pricing considerations, and competition between conventional therapies and newer biologic products. The increasing availability of advanced therapies is supporting broader adoption, particularly in regions with established healthcare infrastructure. Ongoing research activity, supportive regulatory pathways, and a growing focus on personalized treatment approaches are expected to contribute to continued market development and sustained innovation within the myasthenia gravis treatment market.
The myasthenia gravis treatment market is being driven by the growing shift toward targeted biologics and the continued progress of clinical development programs focused on immune mediated disease pathways. Traditional treatment approaches such as corticosteroids and immunosuppressants are increasingly being supplemented by biologic therapies that selectively target mechanisms involved in disease activity. This transition is improving treatment options for patients while supporting greater physician adoption of advanced therapies. The increasing focus on FcRn inhibitors, complement inhibitors, and other immune targeted therapies has expanded the therapeutic landscape and encouraged pharmaceutical companies to invest in research and development activities. In April 2025, Johnson & Johnson received FDA approval for IMAAVY (nipocalimab), an FcRn blocking monoclonal antibody indicated for the treatment of generalized myasthenia gravis in adult and pediatric patients aged 12 years and older who are anti acetylcholine receptor or anti muscle specific tyrosine kinase antibody positive. This approval strengthened the availability of targeted biologic therapies and reflected continued advancement in precision based treatment strategies. In addition, ongoing investments in biologic drug development and expanding clinical research activities are supporting the introduction of new treatment options for different patient populations. The growing success of development pipelines is increasing confidence among industry participants and healthcare providers, contributing to broader adoption of innovative therapies. As a result, targeted biologics and pipeline advancements continue to support growth and development within the myasthenia gravis treatment market.
High treatment costs remain a key restraint for the myasthenia gravis treatment market as the use of biologics and targeted therapies continues to increase. While these therapies provide clinical benefits for many patients, their pricing can create access barriers across both developed and emerging healthcare systems. Payers and reimbursement agencies often require substantial clinical and economic evidence before approving coverage, which may delay patient access to newer treatment options. In several regions, patients continue to depend on conventional therapies due to affordability concerns, even when additional treatment choices are available. Healthcare providers must also manage reimbursement procedures, prior authorization requirements, and budget limitations that can affect treatment uptake. The financial burden associated with ongoing therapy may influence treatment adherence and prescribing decisions. Companies operating in the market face the challenge of balancing product development investments with pricing expectations from healthcare systems and payers. In addition, differences in healthcare funding and insurance coverage across regions can contribute to variations in treatment access. As a result, reimbursement policies and cost considerations continue to influence the adoption of newer therapies within the myasthenia gravis treatment market.
The growing emphasis on personalized medicine presents a notable opportunity for the myasthenia gravis treatment market. Advances in diagnostic technologies and biomarker identification are enabling clinicians to better classify patients and select therapies based on specific disease characteristics. This trend is supporting the development of targeted treatments designed for distinct antibody profiles, which can improve therapeutic outcomes and optimize resource utilization. Pharmaceutical companies are increasingly focusing on precision driven drug development strategies that address unmet needs among diverse patient populations. The expansion of antibody testing capabilities and improved disease awareness are expected to facilitate earlier intervention and more individualized treatment selection. Furthermore, healthcare systems are placing greater emphasis on outcome based care models, creating favorable conditions for therapies that demonstrate measurable clinical benefits in defined patient populations. These factors are encouraging continued investment in research programs focused on next generation biologics and immune targeted therapies. In December 2025, Amgen received FDA approval for UPLIZNA (inebilizumab cdon), a CD19 directed monoclonal antibody indicated for the treatment of adults with generalized myasthenia gravis who are anti acetylcholine receptor or anti muscle specific tyrosine kinase antibody positive. This approval highlighted the increasing role of biomarker guided treatment selection and reinforced opportunities for personalized therapeutic approaches targeting defined patient populations within the myasthenia gravis treatment market.
Analyst Perspective
The myasthenia gravis treatment market is undergoing a transition from conventional immunosuppressive therapies toward targeted biologics and precision driven treatment approaches. Recent regulatory approvals of FcRn inhibitors, complement inhibitors, and other immune targeted therapies are expanding treatment options and improving disease management for specific patient populations. Market growth is supported by increasing disease awareness, improved diagnostic capabilities, and ongoing investments in rare disease research. However, high treatment costs and reimbursement challenges may continue to influence adoption rates across healthcare systems. Looking ahead, continued innovation in biologics, antibody specific therapies, and advanced immunomodulatory approaches is expected to shape the competitive landscape and create opportunities for market expansion.
Treatment Type Insights
Medications can dramatically inhibit the immune system and largely manage the associated symptoms. Medications include immunotherapies such as Soliris (eculizumab), corticosteroids, and immunosuppressive drugs such as Prograf (tacrolimus) and Neoral/Sandimmune (cyclosporine). The other major treatment alternative, surgery, is the most invasive and usually involves a thymectomy (thymus removal). The thymus deteriorates with age (thymic involution); however, complete loss of the thymus in such a manner will significantly weaken a patient’s immune system.
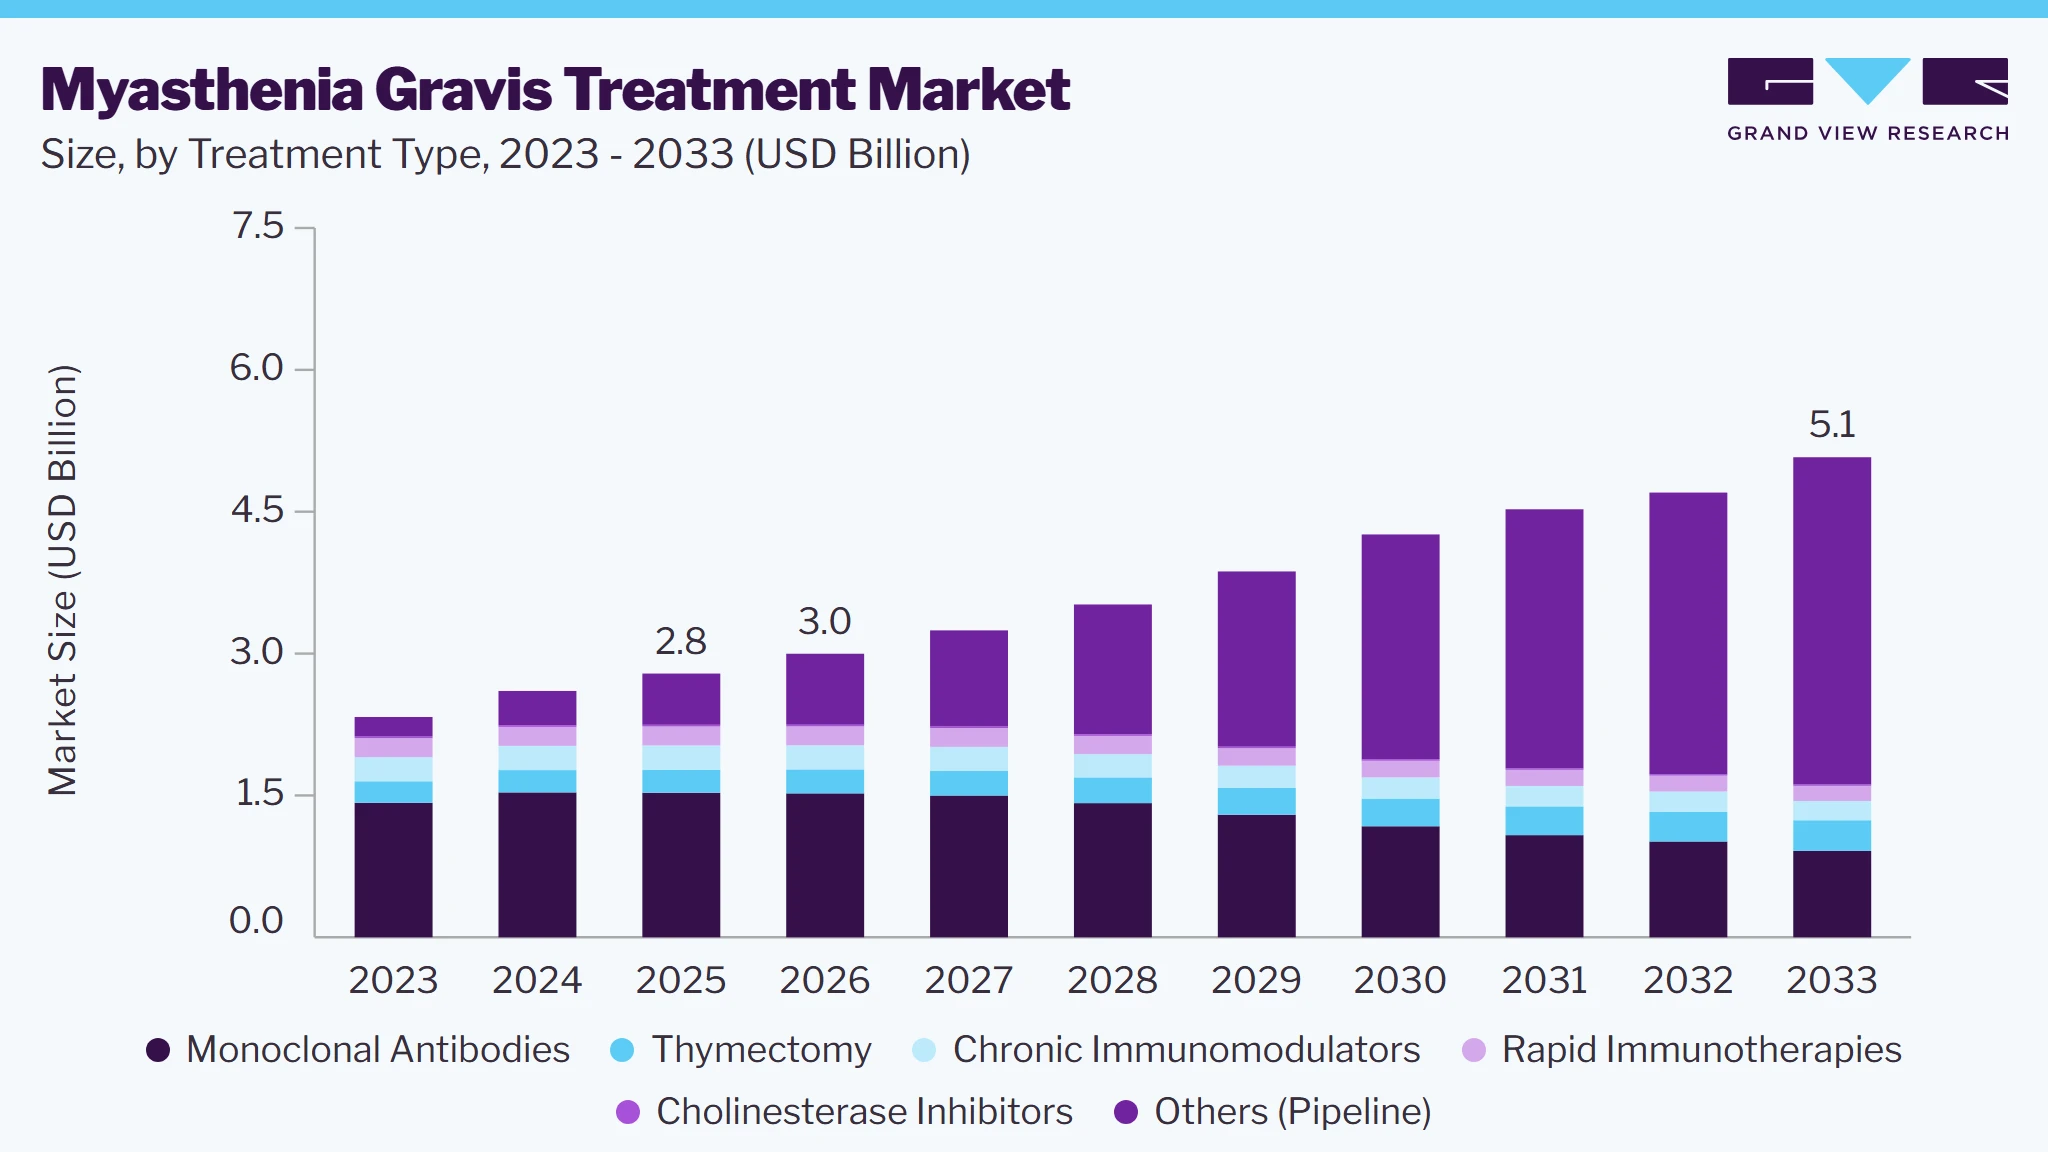
Based on treatment type, the monoclonal antibodies segment led the market with the largest revenue share of 54.8% in 2025, owing to the high precision in treating myasthenia gravis and better efficacy. For instance, Alexion Pharmaceuticals’ eculizumab monoclonal antibodies drug Soliris is used for the treatment of myasthenia gravis. Recently, it received approval from the U.S. Food and Drug Administration (FDA) and the European Commission for treating adult patients with generalized myasthenia gravis who are anti-AchR antibody-positive. Soliris is the first and only complement inhibitor approved for this disorder. The increasing use of monoclonal antibodies and immunosuppressants is aimed at reducing lifelong exposure to corticosteroids and improving long-term results.
The market is witnessing an upsurge in the number of pipeline studies for drug development that is expected to drive the market, resulting in an anticipated fastest growth of 41.8% CAGR in the pipeline studies segment over the forecast period.
End-use Insights
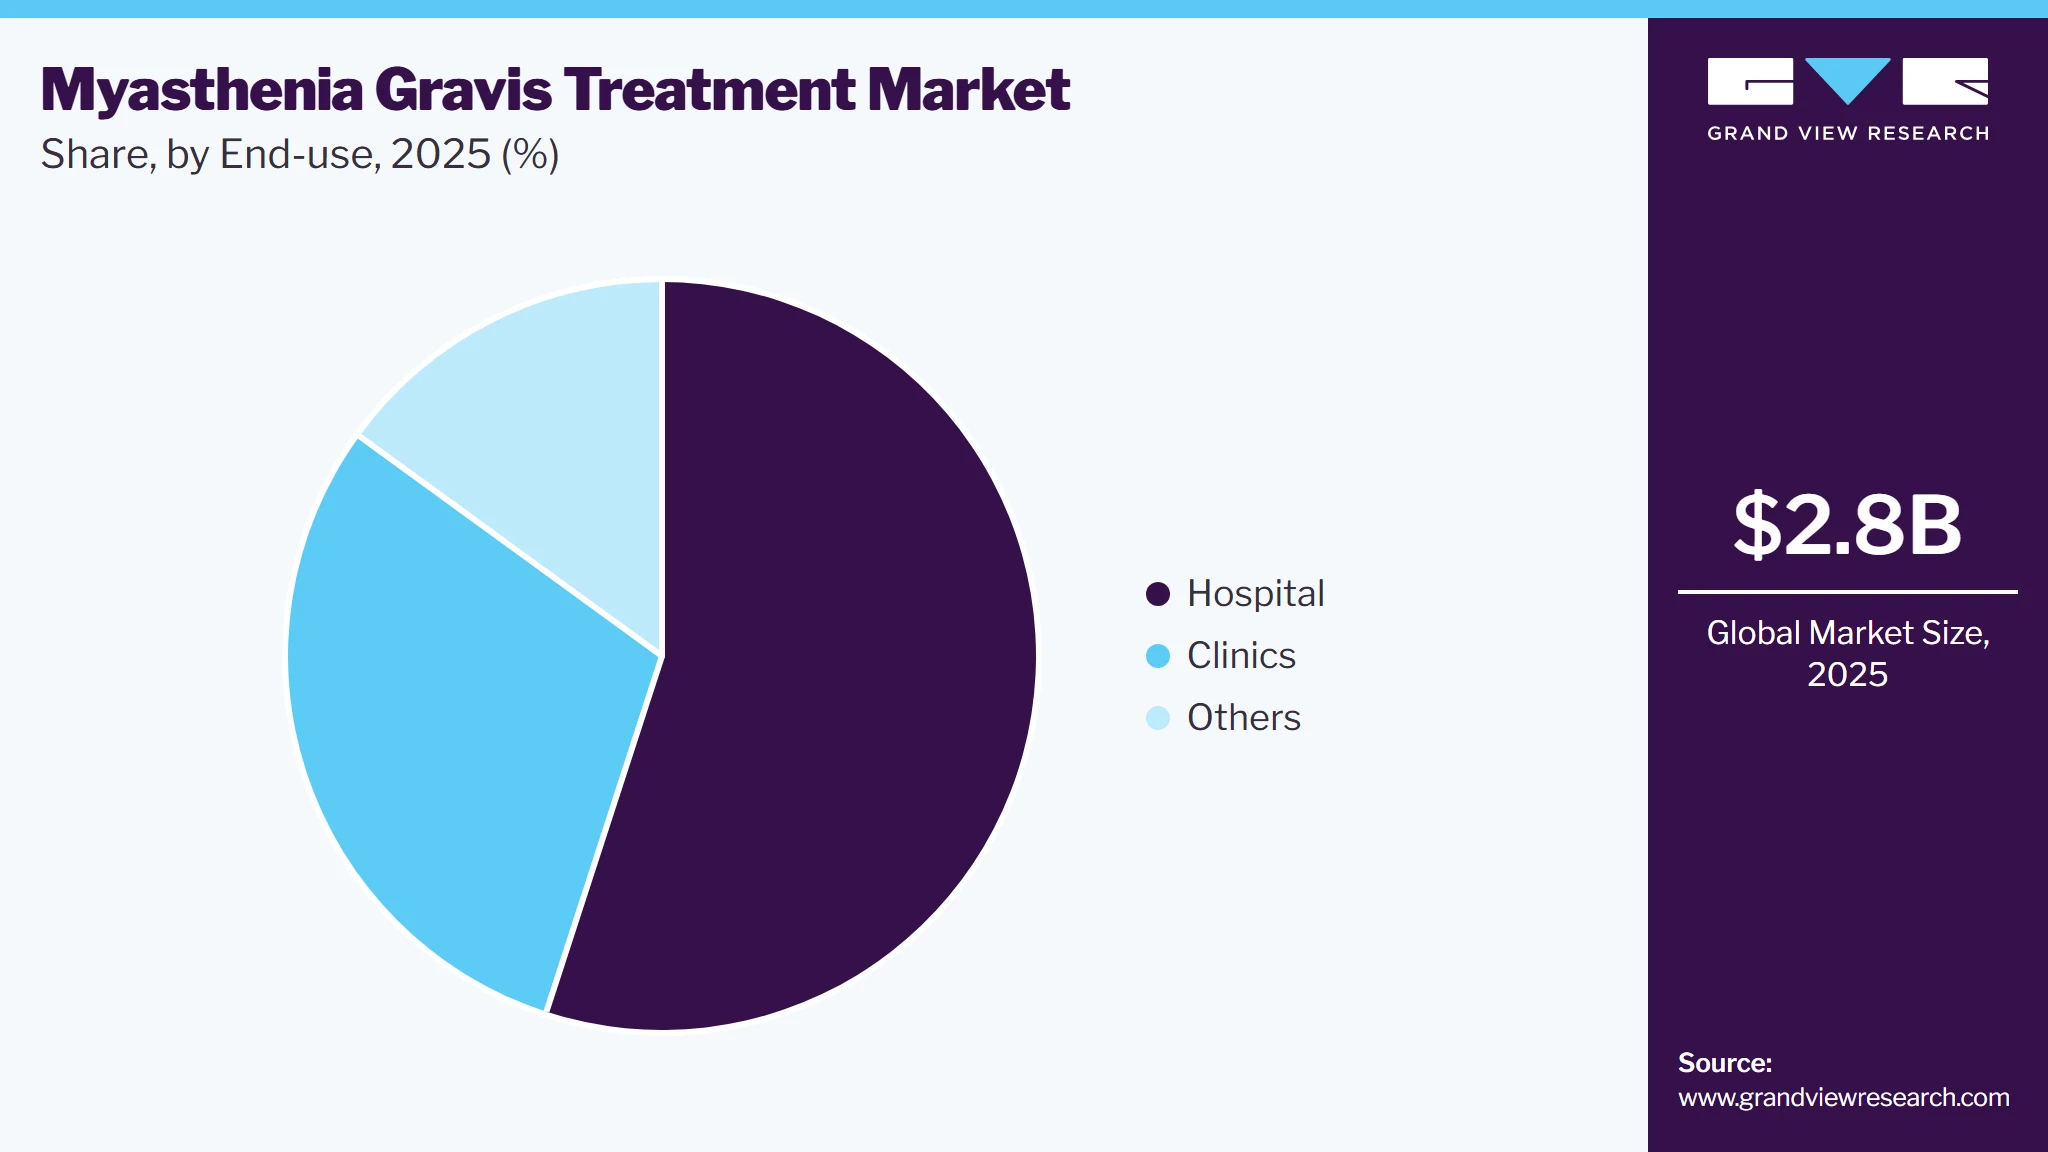
Based on end use, the market has been segmented into hospitals, clinics, and others. The hospital segment led the market with the largest revenue share of 55.0% in 2025 and is expected to grow at a lucrative CAGR of 9.0% over the forecast period. This can be attributed to access to a large patient pool and the high demand for advanced equipment for MG treatment in hospital settings. There has been an increase in patient visits for diagnosis and treatment of MG due to the availability of a broad range of treatment options in such facilities. Furthermore, one of the major factors contributing to its large share is the increased investment in state-of-the-art healthcare infrastructures.
 To learn more about this report, Download Free Sample Report
The clinic segment held the second-largest share of around 30% in 2022 and is expected to retain the position through the forecast period. With the growing need for specialized treatments, many patients prefer specialty clinics for rapid diagnosis and effective MG treatment. A large segment of the end users also depend on eCommerce channels for obtaining therapeutics for myasthenia gravis. These segments are significantly contributing to the growth of the myasthenia gravis treatment market.
Regional Insights
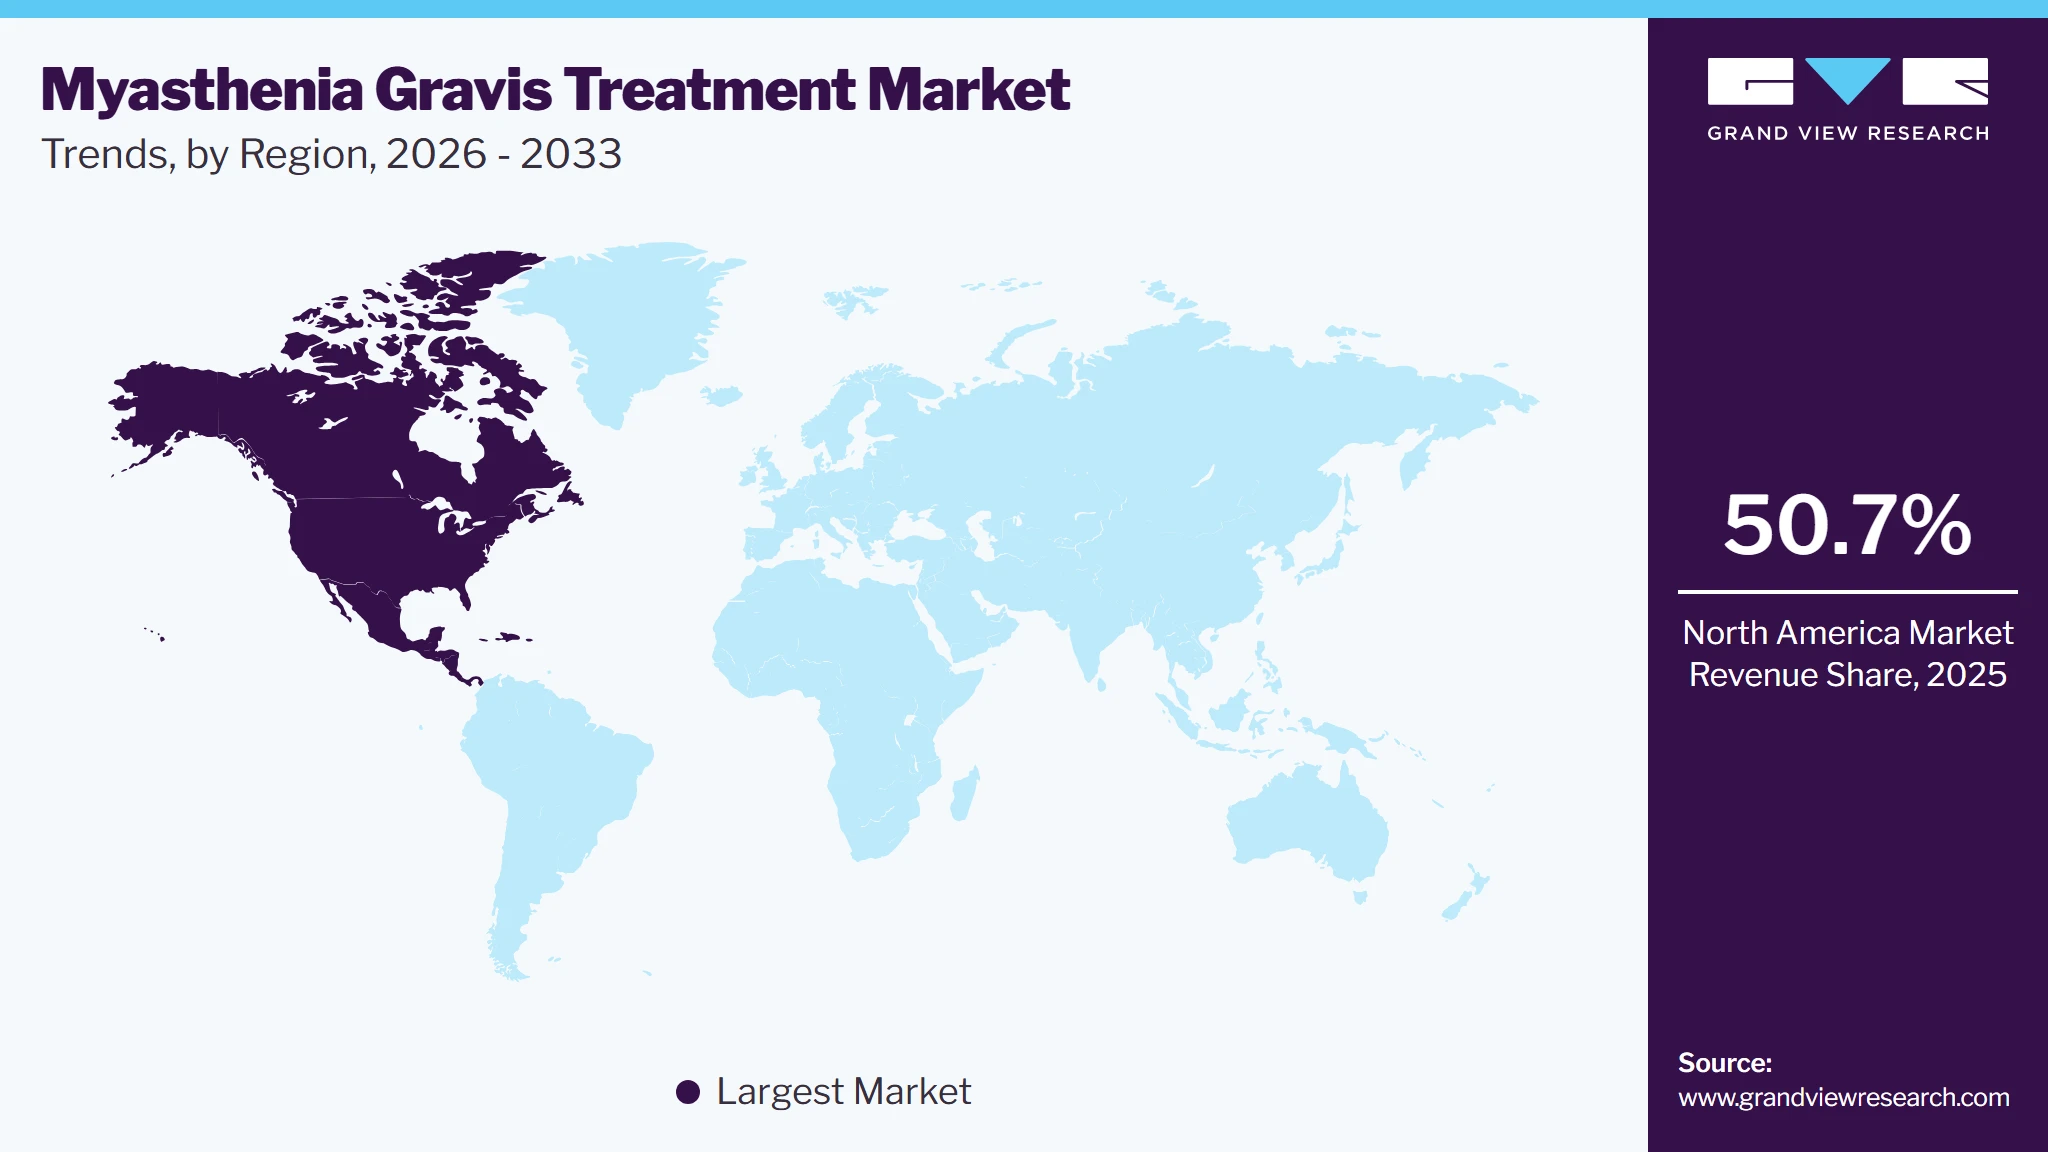
North America dominated the myasthenia gravis treatment market with the largest revenue share of 50.7% in 2025. This can be attributed to the high adoption of immunotherapies and monoclonal antibodies, increasing healthcare expenditure, the presence of established research and development facilities, and favorable reimbursement scenarios.
 To learn more about this report, Download Free Sample Report
U.S. Myasthenia Gravis Treatment Market Trends
The myasthenia gravis treatment marketin the U.S. held the largest share in the North America region in 2025
Middle East and Africa is expected to grow at the fastest CAGR of 14.9% over the forecast period. This can be attributed to the rising prevalence of myasthenia gravis in the region, especially among the elderly population, increasing awareness, availability of advanced diagnostics tools and therapeutic options, and the expansion of healthcare infrastructure.
Asia Pacific is anticipated to grow at a lucrative CAGR through the forecast period due to the increase in revenue generation from medications such as immunosuppressants and monoclonal antibodies in this region. Other factors propelling the growth are the initiatives associated with increasing investments in the healthcare sector by the regional governments and manufacturers.
Key Companies & Market Share Insights
Some of the key companies operating in the market such as Alexion Pharmaceuticals and Astellas Pharma hold the largest market shares due to the strong sales of their flagship products, including Soliris and Prograf.
However, generic competition is a major hindrance to market growth due to the patent loss of several marketed products and the availability of low-priced substitutes to branded drugs in the market. To gain an advantage against competitors, companies are adopting strategies such as expansion in emerging countries, new product development, spreading awareness, and getting into collaborations. For instance, in April 2022, AstraZeneca received approval for Ultomiris (ravulizumab-cwvz) from the FDA for generalized myasthenia gravis. In December 2021, the FDA approved efgartigimod drug Vyvgart, a novel treatment for AChR positive tested generalized myasthenia gravis patients.
Key Myasthenia Gravis Treatment Companies:
The following key companies have been profiled for this study on the myasthenia gravis treatment market.
-
Alexion Pharmaceutical Inc.
-
Grifols SA
-
Avadel Pharmaceuticals, Plc.
-
Novartis
-
Pfizer, Inc.
-
AbbVie Inc.
-
F.Hoffmann-La Roche AG
-
GlaxoSmithKline Plc.
-
Bausch Health Companies Inc.
-
Shire plc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Alexion Pharmaceuticals Inc., Novartis AG, Pfizer Inc., AbbVie Inc., F. Hoffmann La Roche Ltd., GlaxoSmithKline plc)
- Focus on expanding autoimmune and rare disease portfolios through investments in biologics, immunology research, and targeted therapy development. Strengthen market position through clinical trials, regulatory approvals, strategic collaborations, acquisitions, and geographic expansion initiatives. Leverage established commercial infrastructure and physician engagement programs to support treatment adoption across major healthcare markets.
- Strong global brand presence, extensive research and development capabilities, broad regulatory expertise, and substantial financial resources. Established relationships with healthcare providers, payers, and research institutions support market penetration and product commercialization. Diversified therapeutic portfolios and global distribution networks contribute to long term competitive positioning.
- High research and development costs associated with biologics and specialty therapeutics. Exposure to pricing pressures, reimbursement challenges, and patent expiry risks. Intense competition from both established pharmaceutical companies and emerging biotechnology firms developing novel therapies may impact market growth opportunities.
Emerging and Specialized Players (Grifols S.A., Avadel Pharmaceuticals plc, Bausch Health Companies Inc., Shire plc)
- Focus on specialized therapeutic areas, niche treatment segments, and targeted expansion strategies within neurology, immunology, and rare disease markets. Pursue growth through product development, strategic partnerships, licensing agreements, and portfolio optimization initiatives. Emphasize differentiated treatment offerings and selective geographic expansion to strengthen market presence.
- Greater focus on specific therapeutic segments and ability to address targeted patient populations. Operational flexibility enables faster response to evolving market opportunities and emerging treatment trends. Specialized expertise in selected disease areas supports product differentiation and competitive positioning.
- Limited financial resources and commercial scale compared with larger pharmaceutical companies. Dependence on a smaller number of products and therapeutic areas may increase business risk. Challenges related to market access, global expansion, and competition from larger industry participants with broader portfolios and stronger commercial infrastructure.
Myasthenia Gravis Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.8 billion
Estimated market size in 2026
USD 3.0 billion
Projected market size by 2033
USD 5.1 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Treatment Type, End-Use, Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Mexico; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Alexion Pharmaceutical Inc., Grifols SA, Avadel Pharmaceuticals, Plc., Novartis, Pfizer, Inc., abbvie Inc., F.Hoffmann-La Roche AG, glaxosmithkline Plc., Bausch Health Companies Inc., and Shire plc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
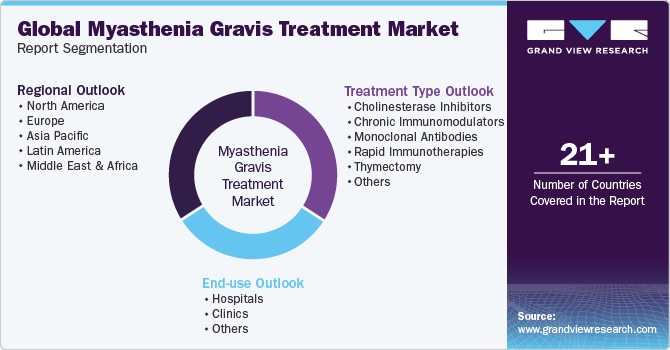
Global Myasthenia Gravis Treatment Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global myasthenia gravis treatment market based on treatment type, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Treatment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Cholinesterase Inhibitors
-
Chronic Immunomodulators
-
Monoclonal Antibodies
-
Rapid Immunotherapies
-
Thymectomy
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The myasthenia gravis treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each myasthenia gravis treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Treatment Type
Revenue capture definition
Cholinesterase Inhibitors
Includes pharmacological therapies that improve neuromuscular transmission by inhibiting the breakdown of acetylcholine at the neuromuscular junction. This segment primarily consists of symptomatic treatments used to improve muscle strength and manage disease symptoms in patients with myasthenia gravis. Revenue is generated from the sale of cholinesterase inhibitor drugs prescribed across various stages of disease management.
Chronic Immunomodulators
Includes long term immunosuppressive and immunomodulatory therapies used to control autoimmune activity associated with myasthenia gravis. This segment comprises corticosteroids, azathioprine, mycophenolate mofetil, tacrolimus, cyclosporine, and other immunosuppressive agents prescribed to reduce autoantibody mediated immune responses and maintain disease control. Revenue is derived from therapies utilized for ongoing disease management and relapse prevention.
Monoclonal Antibodies
Includes biologic therapies that selectively target immune pathways involved in myasthenia gravis pathogenesis. This segment covers complement inhibitors, FcRn inhibitors, CD19 targeted therapies, and other monoclonal antibody based treatments designed to reduce pathogenic autoantibody activity and improve disease outcomes. Revenue is generated from approved biologic therapies administered for generalized myasthenia gravis.
Rapid Immunotherapies
Includes therapies used for rapid symptom control and management of acute disease exacerbations or myasthenic crises. This segment comprises intravenous immunoglobulin therapies and plasma exchange related treatments that provide short term immune modulation and rapid clinical improvement. Revenue is generated from treatments administered in acute care and specialized treatment settings.
Thymectomy
Includes surgical removal of the thymus gland performed as part of disease management in eligible patients with myasthenia gravis. Revenue represents procedural expenditures associated with thymectomy performed in hospital and surgical care settings.
Others
Includes emerging therapeutic approaches, combination regimens, investigational therapies, and supportive treatment modalities that do not fall within the defined treatment categories. This segment captures revenue associated with therapies under limited adoption or specialized clinical use.
Segment - End-Use
Revenue capture definition
Hospitals
Includes public and private hospitals that diagnose, manage, and treat patients with myasthenia gravis. This segment accounts for revenue generated through the administration of pharmacological therapies, biologic treatments, rapid immunotherapies, surgical procedures, and inpatient care services. Hospitals represent the primary treatment setting for patients requiring comprehensive disease management and acute care interventions.
Clinics
Includes neurology clinics, specialty treatment centers, outpatient infusion centers, and physician offices involved in the diagnosis, monitoring, and treatment of myasthenia gravis. Revenue is generated from outpatient consultations, biologic therapy administration, follow up care, and long term disease management services.
Others
Includes ambulatory surgical centers, home healthcare settings, home infusion centers, rehabilitation facilities, academic medical centers, and other healthcare institutions involved in myasthenia gravis treatment and patient support. Revenue is derived from treatment administration, monitoring services, and supportive care activities provided outside traditional hospital and clinic environments.
Estimation Model
The Myasthenia Gravis (MG) Treatment Market size is estimated to use a patient-based epidemiology and revenue modeling approach. The methodology begins with analyzing the total population across major regions and countries, followed by identifying the prevalence and incidence of myasthenia gravis through published epidemiological studies, patient registries, healthcare databases, and scientific literature. The total patient pool is then refined to estimate the diagnosed population by considering disease awareness, access to healthcare services, and diagnostic rates. Subsequently, the treated patient population is assessed based on treatment uptake patterns and access to available therapies. The treated population is further segmented by therapy type, including acetylcholinesterase inhibitors, corticosteroids, immunosuppressants, intravenous immunoglobulin (IVIG), plasma exchange, complement inhibitors, FcRn inhibitors, and other emerging biologic treatments. The average annual cost of each therapy is calculated using drug pricing data, treatment duration, administration costs, reimbursement policies, and regional healthcare expenditure trends. Market revenue is derived by multiplying the number of patients receiving each therapy by the corresponding annual treatment cost and aggregating revenues across all treatment segments and geographies. The final market estimates are validated through primary interviews with neurologists, hospital pharmacists, key opinion leaders, and industry participants, while data triangulation using both top-down and bottom-up approaches ensures the accuracy and reliability of the market size and forecast.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Targeted Therapy Adoption Analysis
Assessment of adoption trends across cholinesterase inhibitors, chronic immunomodulators, monoclonal antibodies, rapid immunotherapies, and emerging targeted therapies used in Myasthenia Gravis treatment.
Helps identify high growth treatment segments and investment opportunities across evolving disease management approaches.
Biologic and Pipeline Landscape Assessment
Analysis of approved biologics, late- stage pipeline candidates, FcRn inhibitors, complement inhibitors, and other immune targeted therapies under development for myasthenia gravis.
Supports opportunity identification across emerging treatment modalities and future commercialization prospects.
Clinical and Treatment Pattern Evaluation
Evaluation of treatment utilization across generalized and ocular myasthenia gravis, including therapy sequencing, biologic adoption trends, immunosuppressive treatment patterns, and acute disease management approaches.
Tracks evolving treatment practices and supports strategic planning for market entry and portfolio expansion.
Personalized Medicine and Innovation Landscape
Assessment of advancements in biomarker guided therapies, antibody specific treatment approaches, precision medicine initiatives, and next generation immunotherapies for Myasthenia Gravis.
Assessment of advancements in biomarker guided therapies, antibody specific treatment approaches, precision medicine initiatives, and next generation immunotherapies for Myasthenia Gravis.
Competitive Benchmarking and Product Portfolio Analysis
Comparative assessment of approved products, pipeline assets, clinical development strategies, regulatory milestones, partnerships, and commercialization initiatives of leading Myasthenia Gravis market participants.
Supports competitive intelligence, partnership evaluation, licensing opportunities, and market positioning decisions.
Frequently Asked Questions About This Report
The global myasthenia gravis treatment market size was estimated at USD 2.8 billion in 2025 and is projected to grow from USD 3.0 billion in 2026
Based on treatment type, the monoclonal antibodies segment led the market with the largest revenue share of 54.8% in 2025..
Some key players operating in the myasthenia gravis treatment market include Alexion Pharmaceutical Inc., Bausch Health Companies Inc., Astellas Pharma Inc., Mitsubishi Tanabe Pharma Co., Grifols SA, Catalyst Pharmaceuticals Inc., CSL Behring, Argenx, UCB S.A., Ra Pharmaceuticals, Inc., and Novartis AG
Key factors that are driving the market growth include rising incidence of autoimmune disorders, increasing research and development activities, and growing awareness about Myasthenia Gravis
North America dominated the myasthenia gravis treatment market with the largest revenue share of 50.7% in 2025. This is attributable to the high adoption of novel therapies, increasing research and development investments, and favorable reimbursement scenarios.
Based on the end-use, the hospital segment led the market with the largest revenue share of 55.0% in 2025.
The global myasthenia gravis treatment market is expected to grow at a compound annual growth rate of 7.8% from 2026 to 2033 to reach USD 5.1 billion by 2033.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


