
- Home
- »
- Clinical Diagnostics
- »
-
Non-alcoholic Steatohepatitis Biomarkers Market Report, 2033GVR Report cover

Non-alcoholic Steatohepatitis Biomarkers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Serum Biomarkers, Hepatic Fibrosis Biomarkers, Apoptosis Biomarkers), By End Use (Pharma & CRO Industry, Hospitals), By Region, And Segment Forecasts
Market Size, 2025
$2.0BMarket Estimate, 2026
$2.5BMarket Forecast, 2033
$9.2BCAGR, 2026–2033
20.4%Non-alcoholic Steatohepatitis Biomarkers Market Summary
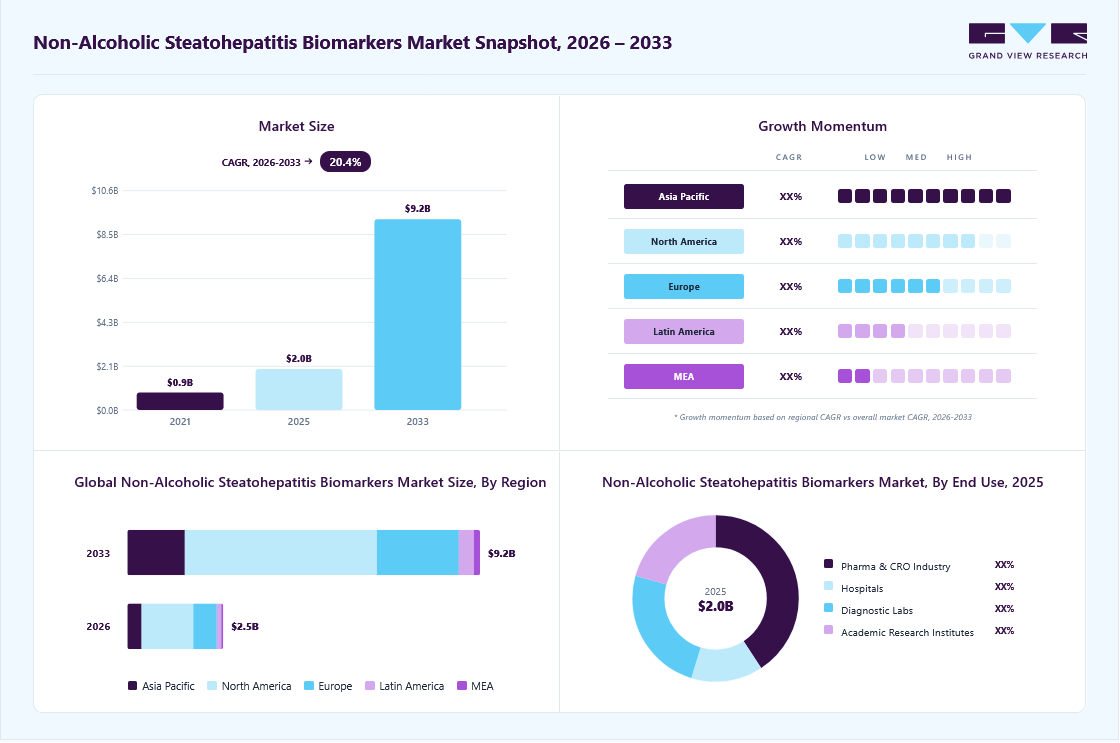
The global non-alcoholic steatohepatitis biomarkers market size was valued at USD 2.0 billion in 2025 and is projected to grow from USD 2.5 billion in 2026 to USD 9.2 billion by 2033, growing at a CAGR of 20.4% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 53.8% in 2025. The increasing prevalence of chronic liver diseases, particularly Non-alcoholic Steatohepatitis (NASH), is significantly expanding the market for NASH biomarkers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Serum biomarker segment held the largest revenue share of 32.7% in 2025.
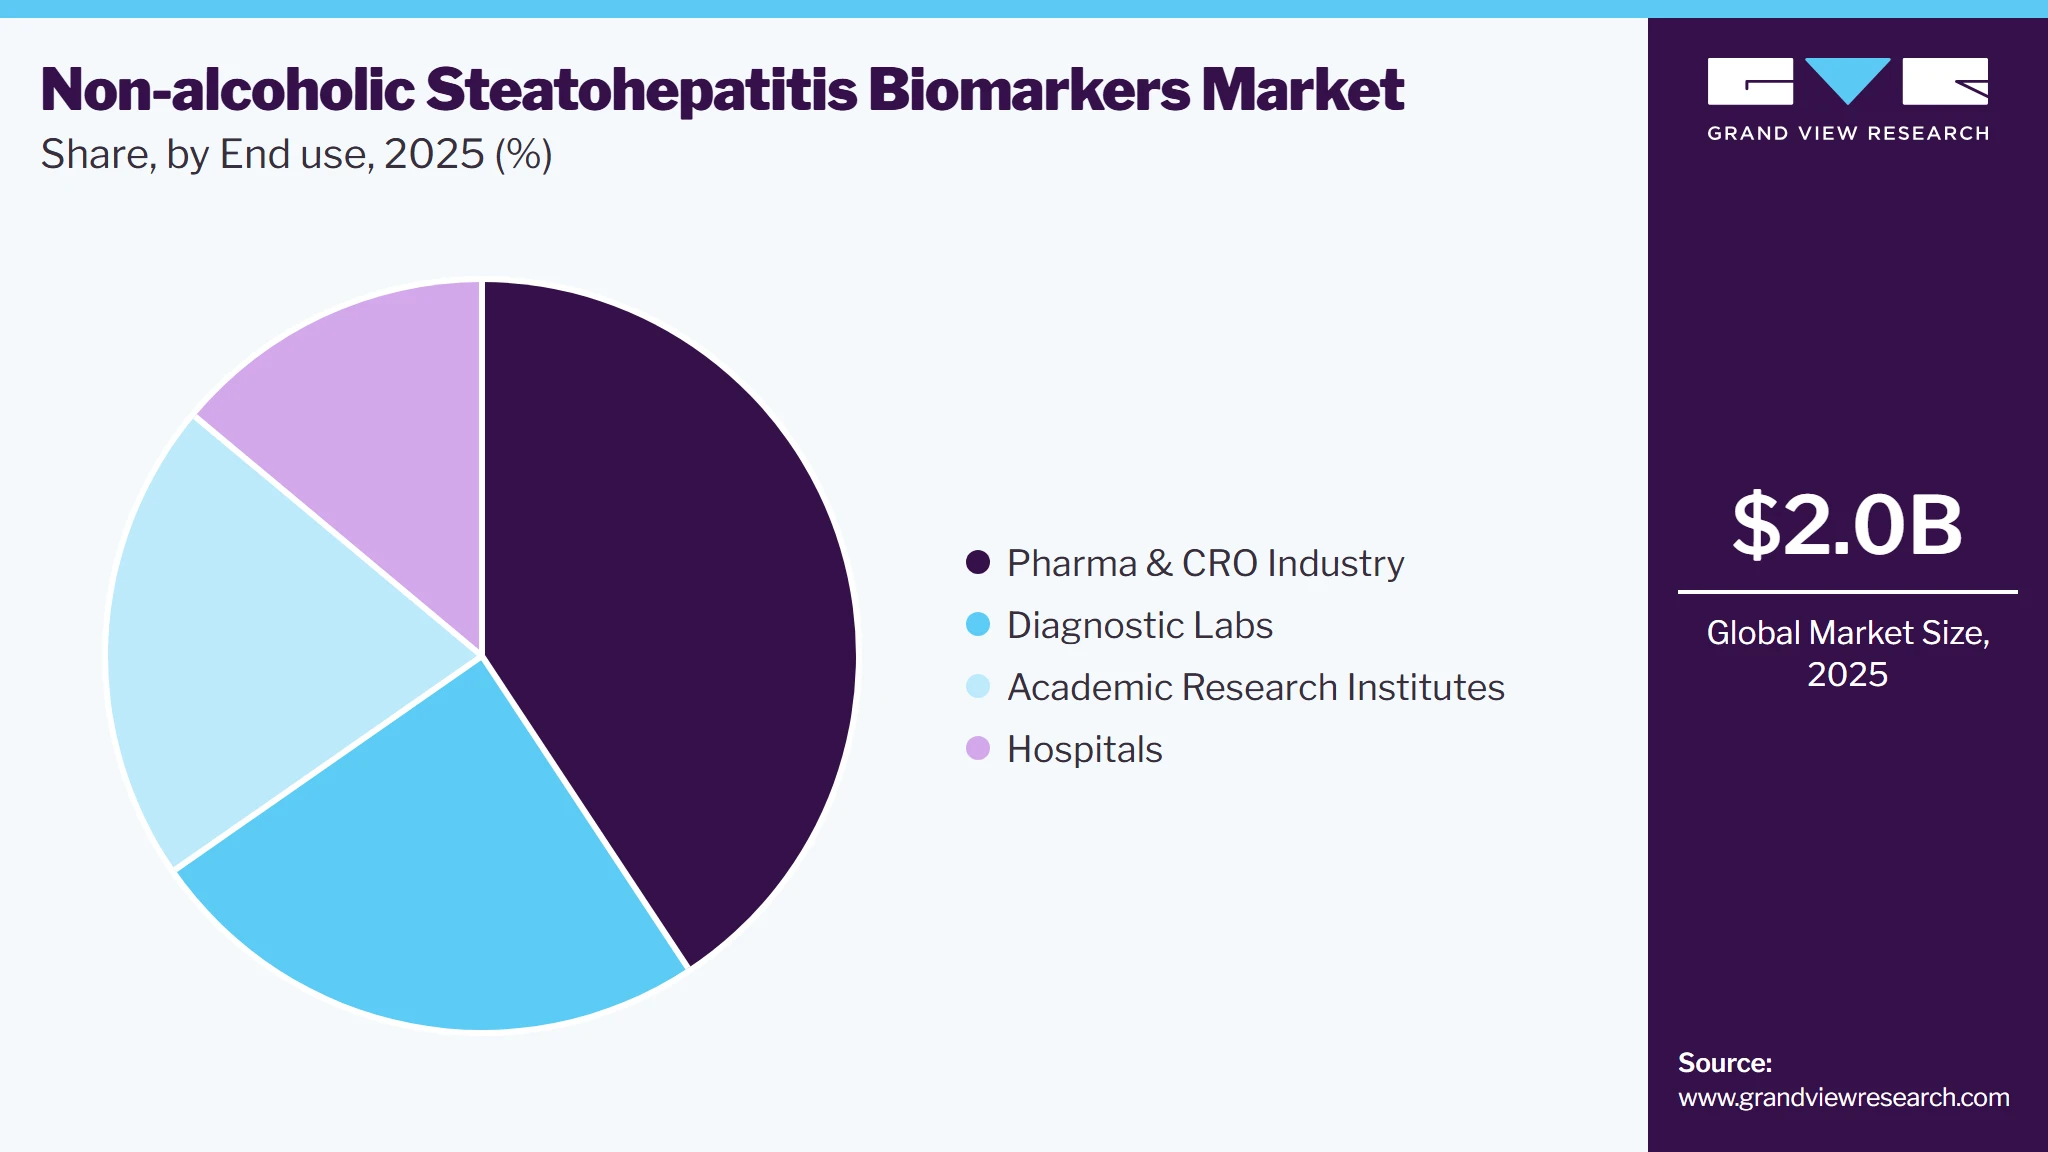
- By end-use: Pharma & CRO industry segment held the largest share of 40.7% in 2025.
Regional Highlights
- Largest regional market: North America (53.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America market in 2025
Market Size & Forecast
- Market size in 2025: USD 2.0 Billion
- Estimated market size in 2026: USD 2.5 Billion
- Projected market size by 2033: USD 9.2 Billion
- CAGR (2026-2033): 20.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing awareness and advancements in diagnostics are the major driving factors encouraging the demand for early detection and better management of the disease. Novel diagnostic tests offer more accurate, noninvasive ways to assess liver damage, thus boosting the adoption of biomarkers for personalized treatment plans. With NASH cases on the rise globally, healthcare providers are increasingly relying on these biomarkers, propelling the market growth and encouraging innovation in diagnostic solutions.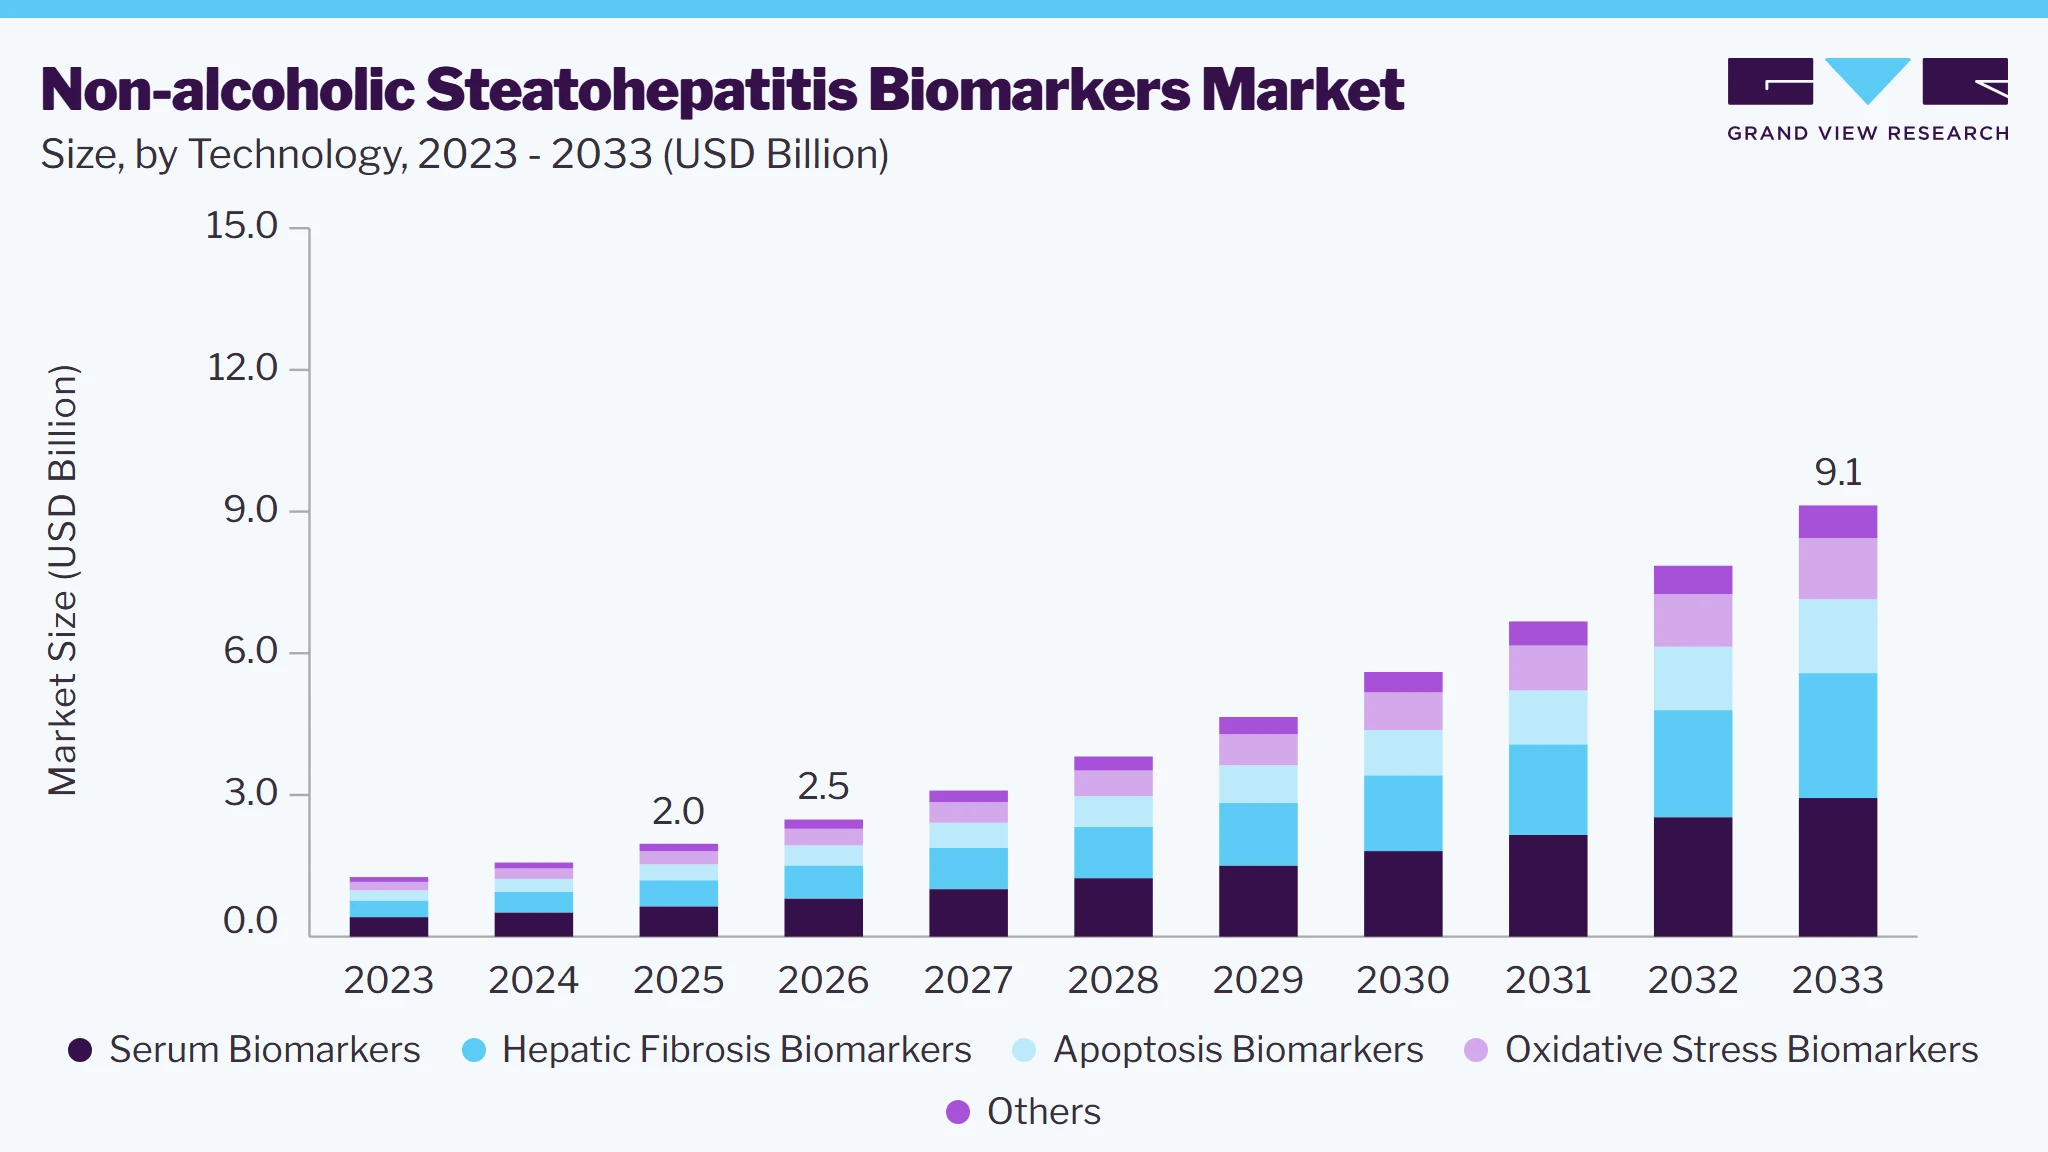 To learn more about this report, Download Free Sample Report
NASH has been one of the most difficult diseases for the diagnostics industry to manage, owing to non-specific or silent symptoms, which resulted in patients being unaware until the late stages of the disease. This hinders the diagnosis of the disease, limiting the overall growth of the market. Studies are being conducted to develop novel functional tests. These tests measure changes in liver function before the condition progresses the fibrosis. In addition, breath tests are being considered the detect molecules and compounds associated with NASH. These tests are projected to provide robust information and compete with biomarker tests.
Market Dynamics
The Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market is driven by the rising prevalence of obesity, type 2 diabetes, and metabolic dysfunction-associated liver disease, increasing demand for non-invasive diagnostic solutions, and growing clinical trial activity for NASH therapeutics. Advancements in serum and imaging biomarkers, as well as multi-omics technologies, are improving early disease detection and patient stratification. Favorable research funding and pharmaceutical partnerships further support market growth. However, regulatory challenges, biomarker validation requirements, and the lack of standardized diagnostic pathways may restrain adoption.
The primary driver of the NASH (now increasingly referred to as MASH) biomarkers market is the rapidly growing patient population at risk of progressive liver disease. Metabolic dysfunction-associated steatotic liver disease (MASLD) affects approximately 1.3 billion people globally, and projections suggest the burden could reach 1.8 billion by 2050, driven largely by obesity, type 2 diabetes, and metabolic syndrome. Since only a subset of MASLD patients progress to NASH/MASH and liver fibrosis, there is a critical need for biomarkers that can identify high-risk patients before irreversible liver damage occurs.
Traditional liver biopsy remains invasive, expensive, and unsuitable for large-scale screening. Consequently, healthcare providers and pharmaceutical companies are increasingly adopting blood-based biomarkers, fibrosis panels, and imaging-derived biomarkers for patient stratification. The growing prevalence of obesity and diabetes, coupled with increased awareness of liver disease screening, is accelerating demand for non-invasive biomarker solutions that can support early diagnosis and disease monitoring.
A major restraint on the NASH biomarkers market is the lack of universally accepted biomarkers that can replace liver biopsy as the diagnostic gold standard. Despite significant advances in serum markers, imaging technologies, and multi-marker algorithms, regulatory authorities and clinicians still rely heavily on histological evidence for definitive disease assessment and treatment decisions. The approval of Rezdiffra (resmetirom), the first FDA-approved NASH therapy, in March 2024 was based on biopsy-confirmed clinical trial data from 888 patients, underscoring the continued importance of histopathology in regulatory pathways.
The lack of standardized cutoffs, inter-laboratory variability, and inconsistent validation across diverse patient populations limits broader clinical adoption of emerging biomarkers. Pharmaceutical companies developing NASH therapies also require highly reliable biomarkers for patient enrollment and endpoint measurement in clinical trials. Until biomarkers achieve greater regulatory acceptance and demonstrate accuracy equivalent to biopsy, market penetration will remain constrained despite technological advancements.
Opportunity: Expansion of NASH therapeutics, creating demand for companion and monitoring biomarkers
The emergence of disease-specific NASH therapies presents a significant opportunity for the biomarkers market. In March 2024, the FDA approved Rezdiffra (resmetirom), the first therapy specifically indicated for adults with non-cirrhotic NASH/MASH and moderate-to-advanced fibrosis. This landmark approval has shifted the clinical landscape from disease identification alone to treatment selection, response monitoring, and longitudinal patient management.
As additional therapies advance through late-stage clinical development, demand for biomarkers is expected to increase substantially. Biomarkers will play a critical role in identifying eligible patients, assessing fibrosis progression, monitoring therapeutic response, and reducing dependence on repeat biopsies. The growing therapeutic pipeline, including positive late-stage data from agents such as semaglutide, further strengthens the need for validated diagnostic and prognostic biomarkers, creating substantial commercial opportunities for diagnostic developers and laboratory service providers.
Analyst Perspective
The Non-Alcoholic Steatohepatitis (NASH), increasingly referred to as Metabolic Dysfunction-Associated Steatohepatitis (MASH) biomarkers market is experiencing strong growth due to the rising prevalence of obesity, type 2 diabetes, and metabolic liver disease. Growing demand for non-invasive alternatives to liver biopsy is accelerating adoption of serum biomarkers, fibrosis markers, metabolomic signatures, and imaging-based diagnostics. Recent approvals of NASH/MASH therapies are further increasing the need for accurate disease identification, staging, and treatment monitoring. Companies are focusing on multi-biomarker panels, AI-enabled diagnostics, and companion diagnostics, supported by collaborations across diagnostic, pharmaceutical, CRO, and academic organizations. Despite regulatory and reimbursement challenges, advances in precision medicine are expected to strengthen the role of biomarkers in liver disease management and drug development.
Type Insights
Based on type, the serum biomarker segment led the market with the largest revenue share of 32.7% in 2025 due to its noninvasive nature and ability to provide critical insights into disease progression. These biomarkers offer convenience and efficiency, enabling early detection and monitoring of NASH without the need for invasive liver biopsies. Furthermore, serum biomarkers are cost-effective and suitable for routine clinical use, driving their adoption among healthcare professionals. Their effectiveness in assessing liver inflammation, fibrosis, and overall metabolic dysfunction further solidifies their dominance in the market.
The hepatic fibrosis biomarkers segment is anticipated to grow at a significant CAGR over the forecast period, attributed to their pivotal role in assessing liver damage and fibrosis progression. These biomarkers enable early identification of advanced fibrosis stages, which is crucial for determining disease severity and treatment options. The growing demand for noninvasive diagnostic tools further boosts their adoption, as they help avoid costly and uncomfortable liver biopsies. Moreover, advancements in biomarker technology and their potential for personalized treatment plans are anticipated to drive significant growth in this segment.
End Use Insights
The pharma & CRO industry segment led the market with the largest revenue share of 40.7% in 2025. Pharmaceutical companies focus on developing therapies for NASH, creating a strong demand for reliable biomarkers to monitor disease progression and treatment responses. CROs contribute by providing specialized services for clinical trials, helping pharmaceutical companies efficiently validate biomarkers. This collaboration accelerates the identification of effective treatments, boosting the market share of the pharma and CRO industries in the NASH biomarker space.
 To learn more about this report, Download Free Sample Report
The diagnostic labs segment is expected to witness a significant CAGR during the forecast period, driven by the growing demand for early detection and personalized treatment of NASH. These labs play a vital role in identifying biomarkers that help diagnose the disease at its onset, enabling more effective management. The rising global prevalence of NASH, coupled with advancements in biomarker testing technologies, drives the demand for diagnostic services. Growing awareness and a shift toward noninvasive diagnostic methods further enhance the segment's potential in the non-alcoholic steatohepatitis biomarkers industry.
Regional Insights
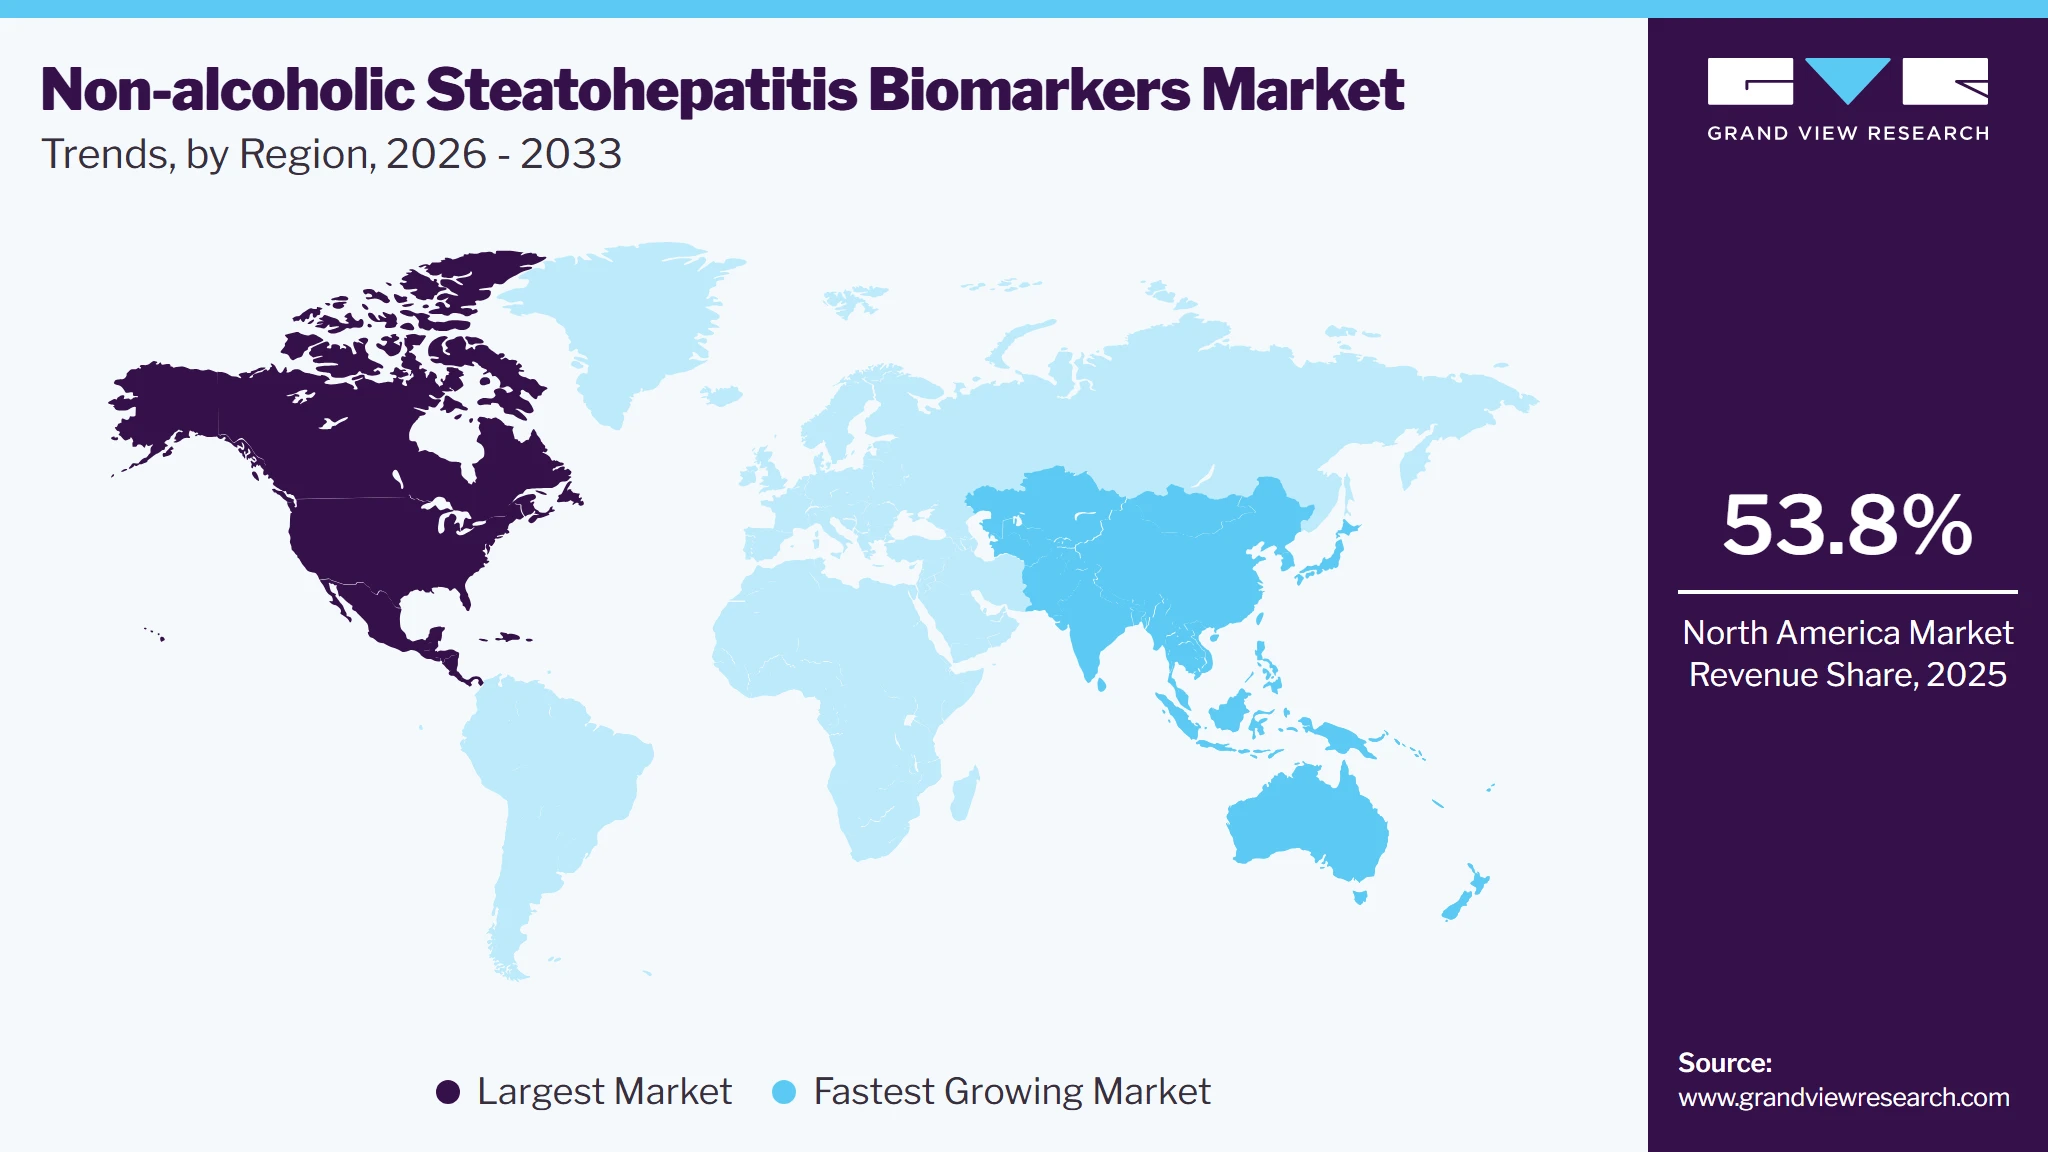
The North America non-alcoholic steatohepatitis biomarkers market accounted for the largest revenue share of 53.8% in 2025. This share is attributable to the increasing diagnosis rate of NASH. Enhanced awareness and better diagnostic technologies aid in the accurate detection of the disease. In addition, the early launch of novel products and biomarkers in the market fosters innovation and improves treatment outcomes. This combination of higher diagnosis rates and the introduction of advanced tools is accelerating the growth of the non-alcoholic steatohepatitis biomarkers industry in North America, driving demand for more effective and tailored diagnostic solutions.
 To learn more about this report, Download Free Sample Report
U.S. Non-alcoholic Steatohepatitis Biomarkers Market Trends
The U.S. held the largest share of NorthAmerica non-alcoholic steatohepatitis biomarkers market in 2025. The growing prevalence of NASH in the U.S., driven by rising obesity and diabetes rates, is significantly boosting the demand for NASH biomarkers. Increased awareness about disease and the need for early detection are compelling healthcare providers to adopt advanced diagnostic methods. Noninvasive testing technologies, including blood biomarkers and imaging techniques, are gaining popularity for their accuracy, safety, and cost-effectiveness, thereby reducing the need for invasive liver biopsies. These innovations fuel market growth and encourage the development of more precise and accessible NASH diagnostic tools.
Europe Non-alcoholic Steatohepatitis Biomarkers Market Trends
Europe non-alcoholic steatohepatitis biomarkers market is anticipated to experience significant expansion over the forecast period. The growing emphasis on early detection and diagnosis of NASH significantly boosts the demand for biomarkers in Europe. Early intervention can improve treatment outcomes, reducing the risk of severe liver damage. Furthermore, the shift toward personalized treatment plans tailored to individual patients' needs is encouraging the development of more precise biomarkers. This dual focus on early detection and customized therapies is expected to drive the growth of the non-alcoholic steatohepatitis biomarkers industry in Europe as healthcare providers seek more accurate and efficient diagnostic tools.
Asia Pacific Non-alcoholic Steatohepatitis Biomarkers Market Trends
Asia Pacific non-alcoholic steatohepatitis biomarkers market is set to be the fastest-growing region over the forecast period, due to expanding healthcare infrastructure and increasing R&D investments by biotech companies. Enhancing regional healthcare facilities enables better diagnostic capabilities and access to advanced biomarkers. Biotech companies are significantly investing in research and development to discover more accurate, noninvasive biomarkers, addressing the rising demand for early-stage NASH detection. This collaborative push toward innovation is expected to accelerate market growth by improving diagnostic accuracy, treatment outcomes, and overall disease management in the region.
India Non-alcoholic Steatohepatitis Biomarkers Market Trends
India non-alcoholic steatohepatitis biomarkers market is projected to grow at the fastest CAGR in the regional market during the forecast period, fueled by the increasing demand for noninvasive diagnostic methods in the country. Patients and healthcare providers prefer noninvasive approaches to avoid the discomfort and risks associated with liver biopsies. Moreover, advancements in biomarker discovery technologies are improving the accuracy and efficiency of diagnosing NASH, leading to better early detection and monitoring of the disease. These factors are expected to significantly expand the market, offering innovative solutions to meet the growing healthcare needs in India.
Key Non-alcoholic Steatohepatitis Biomarkers Company Insights
Some of the key companies in the non-alcoholic steatohepatitis biomarkers industry include Siemens Healthineers AG, AstraZeneca, Labcorp, Pfizer Inc., and Bristol-Myers Squibb Company.
-
Pfizer Inc. provides innovative healthcare solutions, including vaccines, biologics, and prescription medications. Its products target a wide range of conditions, including cancer, cardiovascular diseases, infectious diseases, and immunological disorders, thereby enhancing global health outcomes.
-
Bristol-Myers Squibb Company offers innovative medicines, with a focus on oncology, immunology, cardiology, and fibrosis. Its portfolio includes biologics, small molecules, and cell therapies, aimed at addressing serious diseases and improving patient outcomes globally.
Key Non-alcoholic Steatohepatitis Biomarkers Companies
The following key companies have been profiled for this study on the non-alcoholic steatohepatitis biomarkers market.
-
GENFIT
-
Prometheus Laboratories
-
Siemens Healthineers AG
-
BioPredictive
-
Quest Diagnostics
-
AstraZeneca
-
Exalenz Bioscience Ltd. (Meridian Bioscience; majority-owned by SD Biosensor)
-
Labcorp
-
Pfizer Inc.
-
Bristol-Myers Squibb Company
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well-Established Players (Quest Diagnostics, Labcorp, Mayo Clinic Laboratories, ARUP Laboratories, Siemens Healthineers, Roche Diagnostics, Abbott Laboratories)
- Focus on expanding non-invasive NASH/MASH diagnostic portfolios through serum biomarkers, fibrosis panels, imaging-based biomarkers, and companion diagnostics.
- Emphasize collaborations with pharmaceutical companies, clinical trial support, biomarker validation studies, AI-enabled analytics, and the expansion of global laboratory networks to strengthen market presence.
- Strong brand recognition, extensive laboratory infrastructure, broad customer base, established relationships with healthcare providers and pharmaceutical companies, significant R&D capabilities, and access to large clinical datasets for biomarker development and validation.
- Strong regulatory expertise supports commercialization and market adoption.
- High operating and compliance costs, lengthy biomarker validation timelines, dependence on regulatory approvals and reimbursement policies, and challenges associated with demonstrating clinical utility.
- Large organizational structures may slow innovation and adaptation to emerging biomarker technologies.
Emerging & Specialized Players (OWL Metabolomics, GENFIT, Perspectum, academic spin-offs, and specialty biomarker developers)
- Focus on innovative biomarker discovery, metabolomics, proteomics, genomics, liquid biopsy technologies, and AI-driven disease prediction tools.
- Emphasize partnerships with pharmaceutical companies, academic institutions, and CROs to support clinical trials, patient stratification, and biomarker commercialization.
- Greater flexibility in innovation, specialized expertise in liver disease diagnostics, faster development cycles, and the ability to address unmet needs through differentiated biomarker platforms.
- Strong focus on precision medicine and advanced analytics supports competitive differentiation.
- Limited commercial reach, smaller laboratory and distribution networks, lower brand awareness, and restricted financial resources compared to larger diagnostics companies.
- Dependence on partnerships, clinical validation success, and regulatory acceptance may constrain large-scale market penetration.
Recent Developments
-
In August 2025, the U.S. Food and Drug Administration (FDA) accepted a Letter of Intent proposing liver stiffness measurement by vibration-controlled transient elastography (VCTE) as a reasonably likely surrogate endpoint for all-cause mortality or liver-related events in clinical trials involving adults with non-cirrhotic metabolic dysfunction-associated steatohepatitis (MASH) and moderate-to-advanced liver fibrosis. The proposed biomarker offers a non-invasive approach for assessing liver stiffness and fibrosis severity and may support evaluation of disease progression and treatment response.
-
In July 2024, SomaLogic, a leading protein biomarker discovery and clinical diagnostics company, introduced new biomarkers and provided mechanistic and clinical insights into Acetyl CoA Carboxylase (ACC) for the diagnosis of Non-alcoholic Steatohepatitis (NASH).
Non-alcoholic Steatohepatitis Biomarkers Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 2.0 billion
Market size value in 2026
USD 2.5 billion
Revenue forecast in 2033
USD 9.2 billion
Growth rate
CAGR of 20.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end-use, regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
GENFIT; Prometheus Laboratories; Siemens Healthineers AG; BioPredictive; Quest Diagnostics; AstraZeneca; Exalenz Bioscience Ltd (Meridian Bioscience; majority-owned by SD Biosensor); Labcorp; Pfizer Inc.; Bristol-Myers Squibb Company.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Non-alcoholic Steatohepatitis Biomarkers Market Report Segmentation
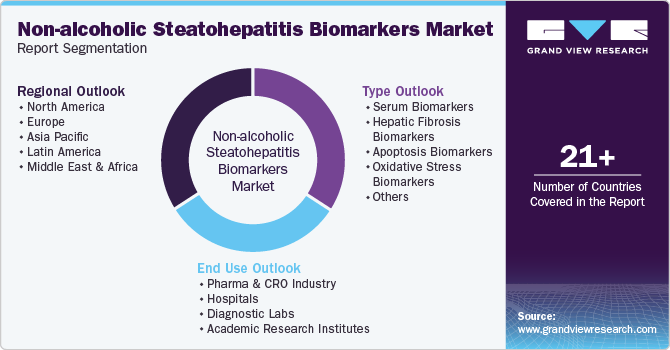
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global non-alcoholic steatohepatitis biomarkers market report on the basis of type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Serum Biomarkers
-
Hepatic Fibrosis Biomarkers
-
Apoptosis Biomarkers
-
Oxidative Stress Biomarkers
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharma & CRO Industry
-
Hospitals
-
Diagnostic Labs
-
Academic Research Institutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
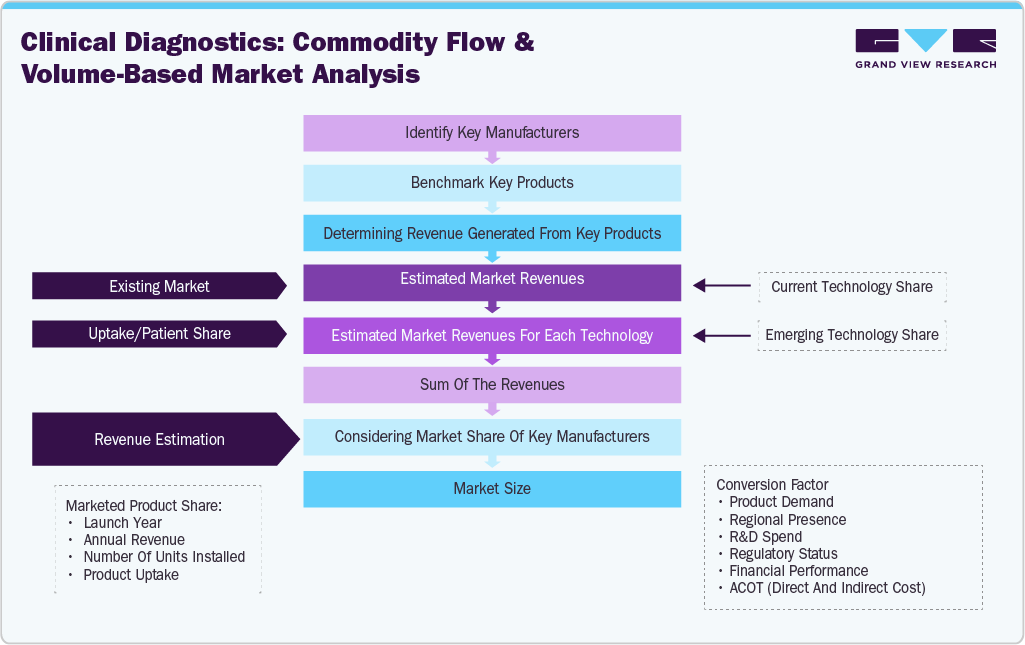
The non-alcoholic steatohepatitis biomarkers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each non-alcoholic steatohepatitis biomarkers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Serum Biomarkers
Revenue is captured from the sale, utilization, and reimbursement of blood-based biomarker assays used to detect, diagnose, stratify, and monitor NASH/MASH patients across clinical and research settings.
Hepatic Fibrosis Biomarkers
Revenue is generated from biomarker tests and diagnostic panels that evaluate liver fibrosis stage, disease progression, and treatment response, including commercial kits, laboratory services, and associated analyses.
Apoptosis Biomarkers
Revenue is captured from assays measuring hepatocyte apoptosis and cell death markers used for disease diagnosis, severity assessment, patient stratification, and monitoring therapeutic outcomes in NASH/MASH.
Oxidative Stress Biomarkers
Revenue is derived from biomarker products and testing services that assess oxidative stress-related liver injury and inflammation, supporting disease detection, prognosis, and progression monitoring.
Others
Revenue includes sales of emerging biomarker technologies, such as inflammatory, genetic, epigenetic, proteomic, and metabolomic assays, as well as multi-marker panels, used in NASH/MASH diagnosis, prognosis, and research applications.
Segment – End Use
Revenue capture definition
Pharma & CRO Industry
Revenue is captured from the use of NASH/MASH biomarker assays and services in drug discovery, clinical trial patient selection, efficacy monitoring, biomarker validation, and regulatory submission activities.
Hospitals
Revenue is generated from biomarker-based diagnostic testing, disease staging, patient monitoring, and treatment decision support services performed within hospital laboratories and specialized hepatology care centers.
Diagnostic Labs
Revenue is derived from routine and specialized NASH/MASH biomarker testing services, including sample processing, fibrosis assessment, disease screening, and longitudinal patient monitoring for healthcare providers.
Academic Research Institutes
Revenue is captured from the procurement and utilization of biomarker assays, reagents, analytical platforms, and research services for studies focused on NASH/MASH pathogenesis, diagnosis, and therapeutics.
Estimation Model
The NASH biomarkers market size is estimated using a combination of top-down and bottom-up approaches. The bottom-up methodology evaluates revenues generated from biomarker assays, diagnostic panels, imaging biomarkers, laboratory services, and research-use products across key end-user segments, including pharmaceutical companies, CROs, hospitals, diagnostic laboratories, and academic institutions. The top-down approach assesses the addressable patient population with MASLD/NASH, biomarker testing rates, adoption of non-invasive diagnostics, and healthcare expenditure trends. Market estimates are validated through analysis of company annual reports, regulatory publications, peer-reviewed journals, clinical trial databases, healthcare statistics, and expert interviews. Data triangulation is applied across product type, biomarker category, end user, and geographic region to ensure accuracy and consistency of market forecasts.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
NASH Biomarkers Competitive Landscape & Technology Assessment
Assessed global NASH biomarker ecosystem across diagnostic modalities, biomarker types (serum, imaging, genetic, multi-omics), stages of development, and applications (diagnosis, prognosis, patient stratification, treatment response). Evaluated key players including biotech, diagnostics companies, academic institutions, and emerging startups.
Enabled benchmarking of leading and emerging biomarkers, identified high-potential biomarkers with strong clinical and commercial potential, assessed white spaces and partnership opportunities, and highlighted innovation hotspots in blood-based and imaging biomarkers.
NASH Biomarkers Regulatory, Compliance & Reimbursement Landscape Assessment
Analyzed evolving regulatory frameworks including FDA biomarker qualification pathways, EMA guidelines, and global regulatory trends. Assessed payer landscape, reimbursement policies, and coverage criteria across key markets (U.S., EU, Japan). Evaluated readiness and evidentiary requirements for biomarker adoption in clinical practice and drug development.
Supported regulatory and reimbursement risk mapping, identified compliance gaps and reimbursement challenges, and highlighted strategies for biomarker qualification, clinical validation, and market access to drive commercialization success.
NASH Biomarkers Innovation & Technology Assessment – Multi-Omics, Imaging, AI & Digital Health Integration
Assessed innovation across multi-omics biomarkers (genomics, proteomics, metabolomics), advanced imaging (MRI-PDFF, elastography), and AI/ML-enabled biomarker discovery and interpretation. Evaluated integration with digital health tools, real-world evidence, and companion diagnostics in NASH biomarker workflows.
Highlighted breakthrough and emerging biomarkers with high growth potential, identified leaders in AI-driven biomarker discovery and digital health integration, and assessed trends in non-invasive and multi-modal biomarker panels for improved accuracy and patient outcomes.
Frequently Asked Questions About This Report
The global non-alcoholic steatohepatitis biomarkers market size was valued at USD 2.0 billion in 2025 and is estimated at USD 2.5 billion in 2026.
The global non-alcoholic steatohepatitis biomarkers market is expected to grow at a compound annual growth rate of 20.4% from 2026 to 2033 to reach USD 9.2 billion by 2033.
Serum biomarkers dominated the non-alcoholic steatohepatitis biomarkers market with a share of 32.7% in 2025. This is attributable to benefits such as the ability to distinguish simple steatosis from NASH and efficient outcomes. These benefits reduce the need for liver biopsy, which is an added advantage compared to other segments.
Key factors that are driving the market growth include the rising prevalence of chronic liver diseases which is projected to increase demand for non-invasive diagnostic tools for NASH detection. Moreover, the market growth is propelled owing to the launch of novel diagnostic tests.
North America non-alcoholic steatohepatitis biomarkers market dominated the global market with the largest revenue share of 53.8% in 2025. This share is attributable to the increasing diagnosis rate of NASH. Enhanced awareness and better diagnostic technologies aid accurate detection of the disease.
The pharma & CRO industry segment held the largest revenue share in 2025, owing to their integral role in drug development and clinical trials. Pharmaceutical companies focus on developing therapies for NASH, creating a strong demand for reliable biomarkers to monitor disease progression and treatment responses.
A major restraint for the NASH biomarkers market is the absence of universally accepted biomarkers capable of replacing liver biopsy as the diagnostic gold standard. Despite significant advances in serum markers, imaging technologies, and multi-marker algorithms, regulatory authorities and clinicians still rely heavily on histological evidence for definitive disease assessment and treatment decisions.
The Asia Pacific non-alcoholic steatohepatitis biomarkers market is poised to be the fastest-growing region, with a CAGR of 20.4% from 2026 to 2033, driven by expanding healthcare infrastructure and increasing R&D investments by biotech companies.
Some key players operating in the non-alcoholic steatohepatitis biomarkers market include GENFIT, Prometheus Laboratories, Siemens Healthineers AG, BioPredictive, Quest Diagnostics, AstraZeneca, Exalenz Bioscience Ltd (Meridian Bioscience), Labcorp, Pfizer Inc., and Bristol-Myers Squibb Company.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


