
- Home
- »
- Medical Devices
- »
-
Non-Magnetic Wheelchair Market Size, Growth Report, 2026-2033GVR Report cover

Non-magnetic Wheelchair Market (2026 - 2033)
Size, Share & Trends Analysis Report By Patient Weight (Below 100 kg, 100 kg To 150 kg, Above 150 kg), By Magnetic Field Strength (Up To 3T, Up To 7T), By End-use (Hospitals, Outpatient Facilities), By Region, And Segment Forecasts
Market Size, 2025
$63.4MMarket Estimate, 2026
$67.8MMarket Forecast, 2033
$108.5MCAGR, 2026–2033
6.9%Non-magnetic Wheelchair Market Trends
The global non-magnetic wheelchair market size was estimated at USD 63.4 million in 2025 and is projected to grow from USD 67.8 million in 2026 to USD 108.5 million by 2033, growing at a CAGR of 6.9% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 34.8% in 2025. Non-magnetic wheelchairs are designed as accessibility equipment without magnetic properties to ensure medical safety and compatibility.
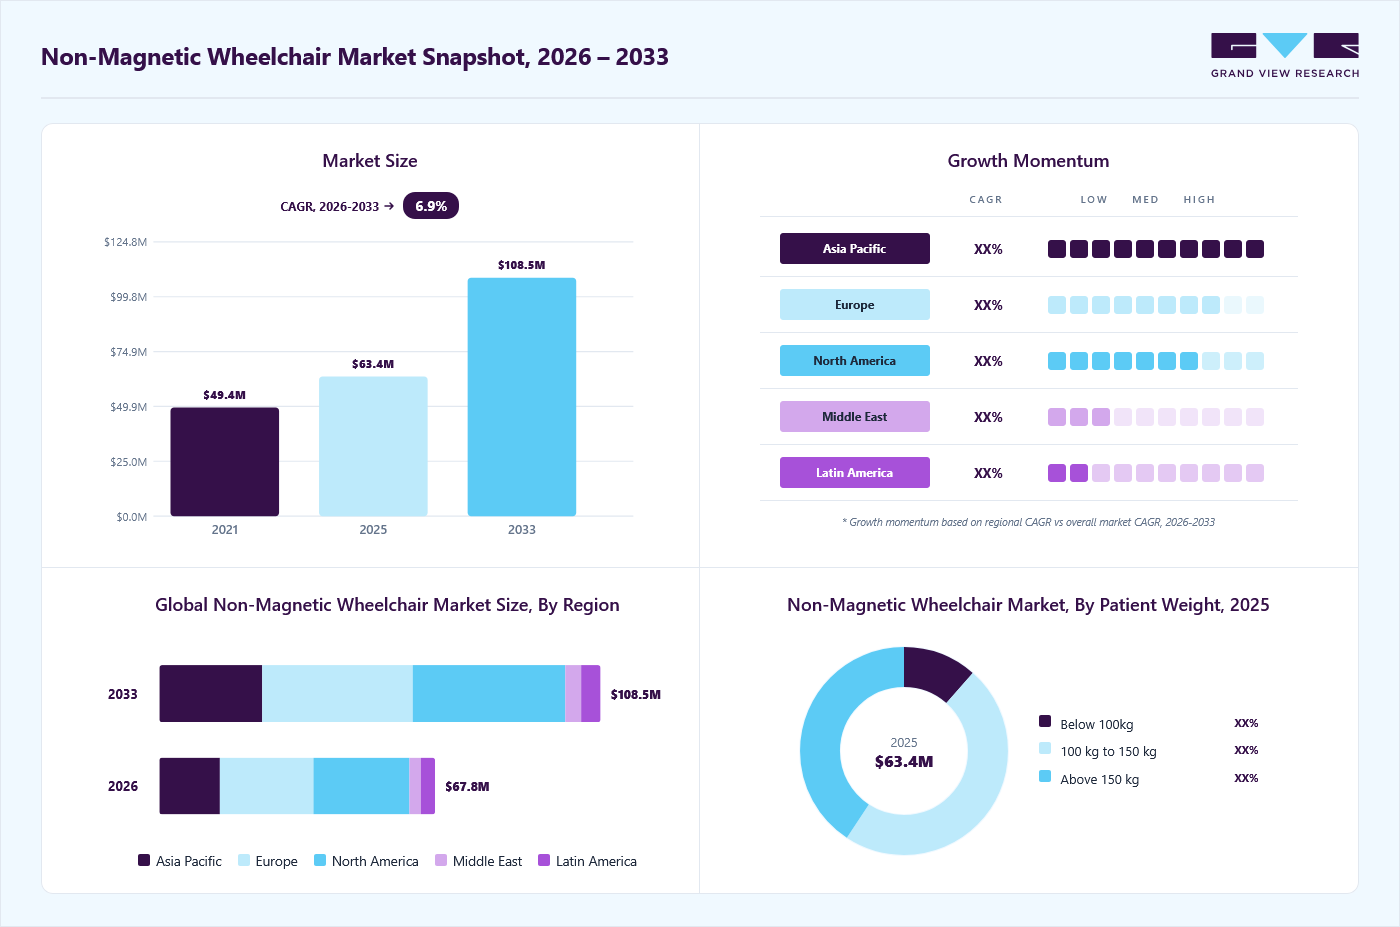 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By patient weight: 100kg to 150kg segment led the market with the largest revenue share of 47.7% in 2025.
- By magnetic field strength: Upto 3T segment led the market with the largest revenue share of 78.5% in 2025.
- Based on end-use: Hospitals segment led the market with the largest revenue share of 51.2% in 2025.
Regional Highlights
- Largest regional market: North America (34.8% revenue share, 2025)
- By country: The U.S non-magnetic wheelchair market is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 63.4 Million
- Estimated market size in 2026: USD 67.8 Million
- Projected market size by 2033: USD 108.5 Million
- CAGR (2026-2033): 6.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is expected to grow due to several factors, such as increasing geriatric population, growing prevalence of physiological and neurological diseases, and increasing installations of imaging modalities such as magnetic resonance imaging (MRI). According to Envision Radiology, nearly 30 million MRI scans are performed in the U.S. each year.The pandemic harmed the non-magnetic wheelchair market. The negative impact was due to stagnancy in MRI scans performed in developing and developed economies. Moreover, journals such as NCBI stated that MRI scans performed in outpatient facilities were majorly affected post-onset of the pandemic in countries such as the U.S. For instance, the average scan volume decreased to 17.3 during the shutdown period, which was estimated at 44.4 during 2019. However, the impact of MRI scans in inpatient settings was affected marginally. Additionally, key market players such as Permobil witnessed a revenue decline of 10.3% in 2020.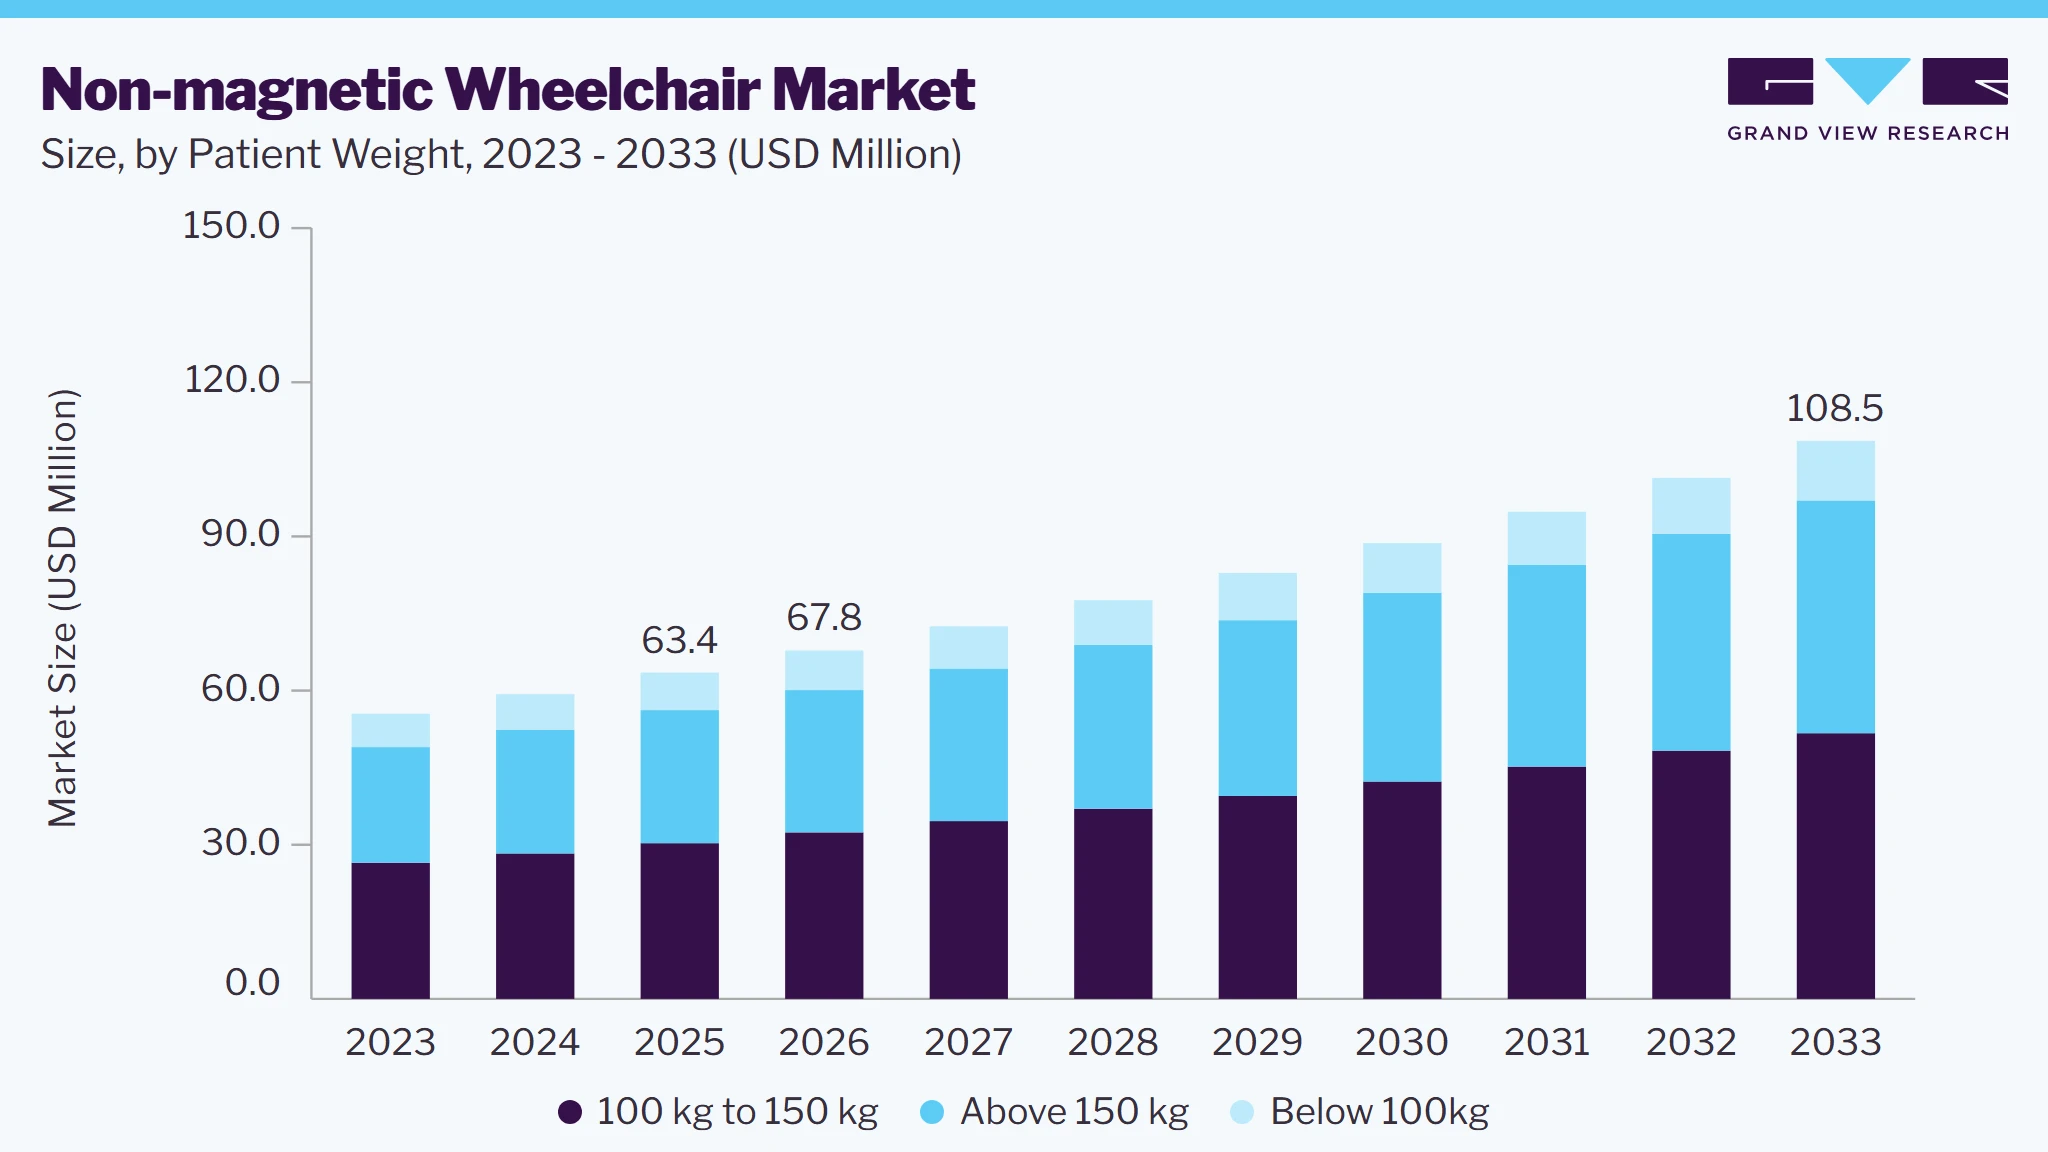 To learn more about this report, Download Free Sample Report
The growing number of physiological and neurological diseases is expected to drive the global market growth during the forecast period. Diseases such as multiple sclerosis (MS), Parkinson's disease (PD), amyotrophic lateral sclerosis (ALS), spinal cord injuries, and stroke lead to mobility impairments, which augments the need for wheelchairs. According to the Parkinson's Foundation, nearly 1 million people in the U.S. suffer from PD, and the incidence of PD is expected to reach 1.2 million by 2030 in the U.S. Furthermore, patients suffering from these diseases require scans to scope the disease progression and nature, thereby, augmenting the demand for non-magnetic wheelchairs.
The growing launch of new imaging centers across economies is expected to drive the market expansion. For instance, in June 2023, McLaren Health Care and MSU Health Care entered a partnership to launch an imaging facility in Michigan within McLaren Greater Lansing Healthcare Campus. In addition, the imaging center will house four MRI machines, along with other technologies. Similarly, in developing countries such as India, government and private bodies are entering into collaboration to build advanced healthcare centers. For instance, in June 2023, an advanced imaging center was opened in Delhi, India, under the public-private partnership (PPP) model, and the center is expected to screen nearly 4,000 to 5,000 patients every month.
Market Dynamics
Non-magnetic wheelchairs are gaining increasing importance as healthcare providers seek safe patient mobility solutions within environments that use strong magnetic fields, particularly Magnetic Resonance Imaging (MRI) suites. These specialized wheelchairs are manufactured using non-ferromagnetic materials such as aluminum, titanium, high-grade plastics, and composite materials, enabling safe patient transport without interfering with MRI imaging quality or creating safety risks. Non-magnetic wheelchairs help hospitals, diagnostic imaging centers, ambulatory care facilities, and specialty clinics improve patient handling efficiency while ensuring compliance with MRI safety standards. As healthcare facilities continue investing in advanced diagnostic imaging infrastructure and patient safety initiatives, demand for MRI-compatible mobility equipment is rising globally. Additionally, growing emphasis on infection control, ergonomic patient transport, lightweight wheelchair designs, and enhanced caregiver convenience is further supporting market expansion.
The increasing adoption of MRI systems worldwide is a major factor driving growth in the non-magnetic wheelchair market. Rising prevalence of neurological disorders, musculoskeletal diseases, cardiovascular conditions, cancer, and sports injuries has significantly increased demand for advanced diagnostic imaging procedures. Healthcare providers are expanding MRI capacity to address growing patient volumes and improve diagnostic accuracy.
As hospitals and imaging centers install additional MRI scanners, the need for MRI-safe patient transport equipment continues to increase. Non-magnetic wheelchairs play a critical role in safely moving patients into MRI environments without creating projectile hazards or affecting imaging outcomes. Furthermore, healthcare facilities are increasingly implementing comprehensive MRI safety protocols, which include the use of MRI-compatible wheelchairs, stretchers, infusion stands, and patient handling equipment.
Despite their safety advantages, the adoption of non-magnetic wheelchairs is constrained by their relatively high acquisition and ownership costs compared with conventional wheelchairs. The use of specialized non-ferromagnetic materials, strict manufacturing requirements, and MRI compatibility testing significantly increases product costs.
Healthcare facilities, particularly smaller hospitals and imaging centers, often face budget constraints when investing in dedicated MRI-compatible mobility equipment. In addition to the initial purchase price, facilities must consider maintenance, periodic safety inspections, replacement parts, and equipment lifecycle management costs.
The gap between standard wheelchair pricing and MRI-compatible alternatives remains a key purchasing challenge. Budget-conscious healthcare providers may delay equipment replacement cycles or limit procurement volumes, especially in emerging markets.
Analyst Perspective
The non-magnetic wheelchair market is experiencing steady growth, driven by the expanding installation of MRI systems, increasing diagnostic imaging volumes, and heightened emphasis on patient safety within magnetic resonance environments. Healthcare providers are increasingly investing in MRI-compatible mobility solutions to comply with stringent safety protocols and improve patient transportation efficiency. Growing prevalence of chronic diseases, neurological disorders, orthopedic conditions, and an aging population is further contributing to demand for specialized patient handling equipment. Additionally, advancements in lightweight non-ferromagnetic materials, ergonomic designs, and durable wheelchair construction are enhancing product performance. As hospitals continue modernizing imaging infrastructure, demand for non-magnetic wheelchairs is expected to remain strong across developed and emerging healthcare markets.
Patient Weight Insights
Based on patient weight, the 100kg to 150kg segment led the market with the largest revenue share of 47.7% in 2025. This is due to factors such as portability, durability, market demand, and product availability. Major manufacturers and distributors of non-magnetic wheelchairs recommend this weight class due to the balance of the product and median patient weight. According to an article by Gallup, Inc., in 2021, the average weight of an adult American man was 91.7 kg.
The above 150 kg segment is estimated to be the fastest-growing, with a CAGR of 7.2% during the forecast period. Factor such as obesity across age groups is expected to be a key driver for the segment’s growth. According to an article by NCBI in May 2023, an estimated 350 million of India’s population suffers from obesity. Similarly, over half of the European adults were marked overweight in 2021. Growing rate of obesity in developing and developed countries is expected to drive the demand for above 150 kg non-magnetic wheelchairs in the forecast period.
Magnetic Field Strength Insights
Based on magnetic field strength, the upto 3T segment led the market with the largest revenue share of 78.5% in 2025. 3T or 3-Tesla MRI machines are commonly used in clinical settings due to their advanced imaging capabilities and accessibility to hospital and healthcare facilities. Furthermore, 3T machines fulfill the regular diagnostic procedure requirements in patients, which supplements the demand for non-magnetic wheelchairs.
However, the 7T segment is estimated to witness the fastest CAGR of 7.7% during the forecast period. 7T or 7-Tesla MRI machines offer higher resolution and detailed imaging capability than 3T machines. Additionally, 7T machines are expected to expand their applications from research to clinical diagnostics, thereby, augmenting demand for compatible non-magnetic wheelchairs. For instance, in August 2020, GE HealthCare launched a 7-Tesla MRI scanner at the International Society for Magnetic Resonance in Medicine.
End-use Insights
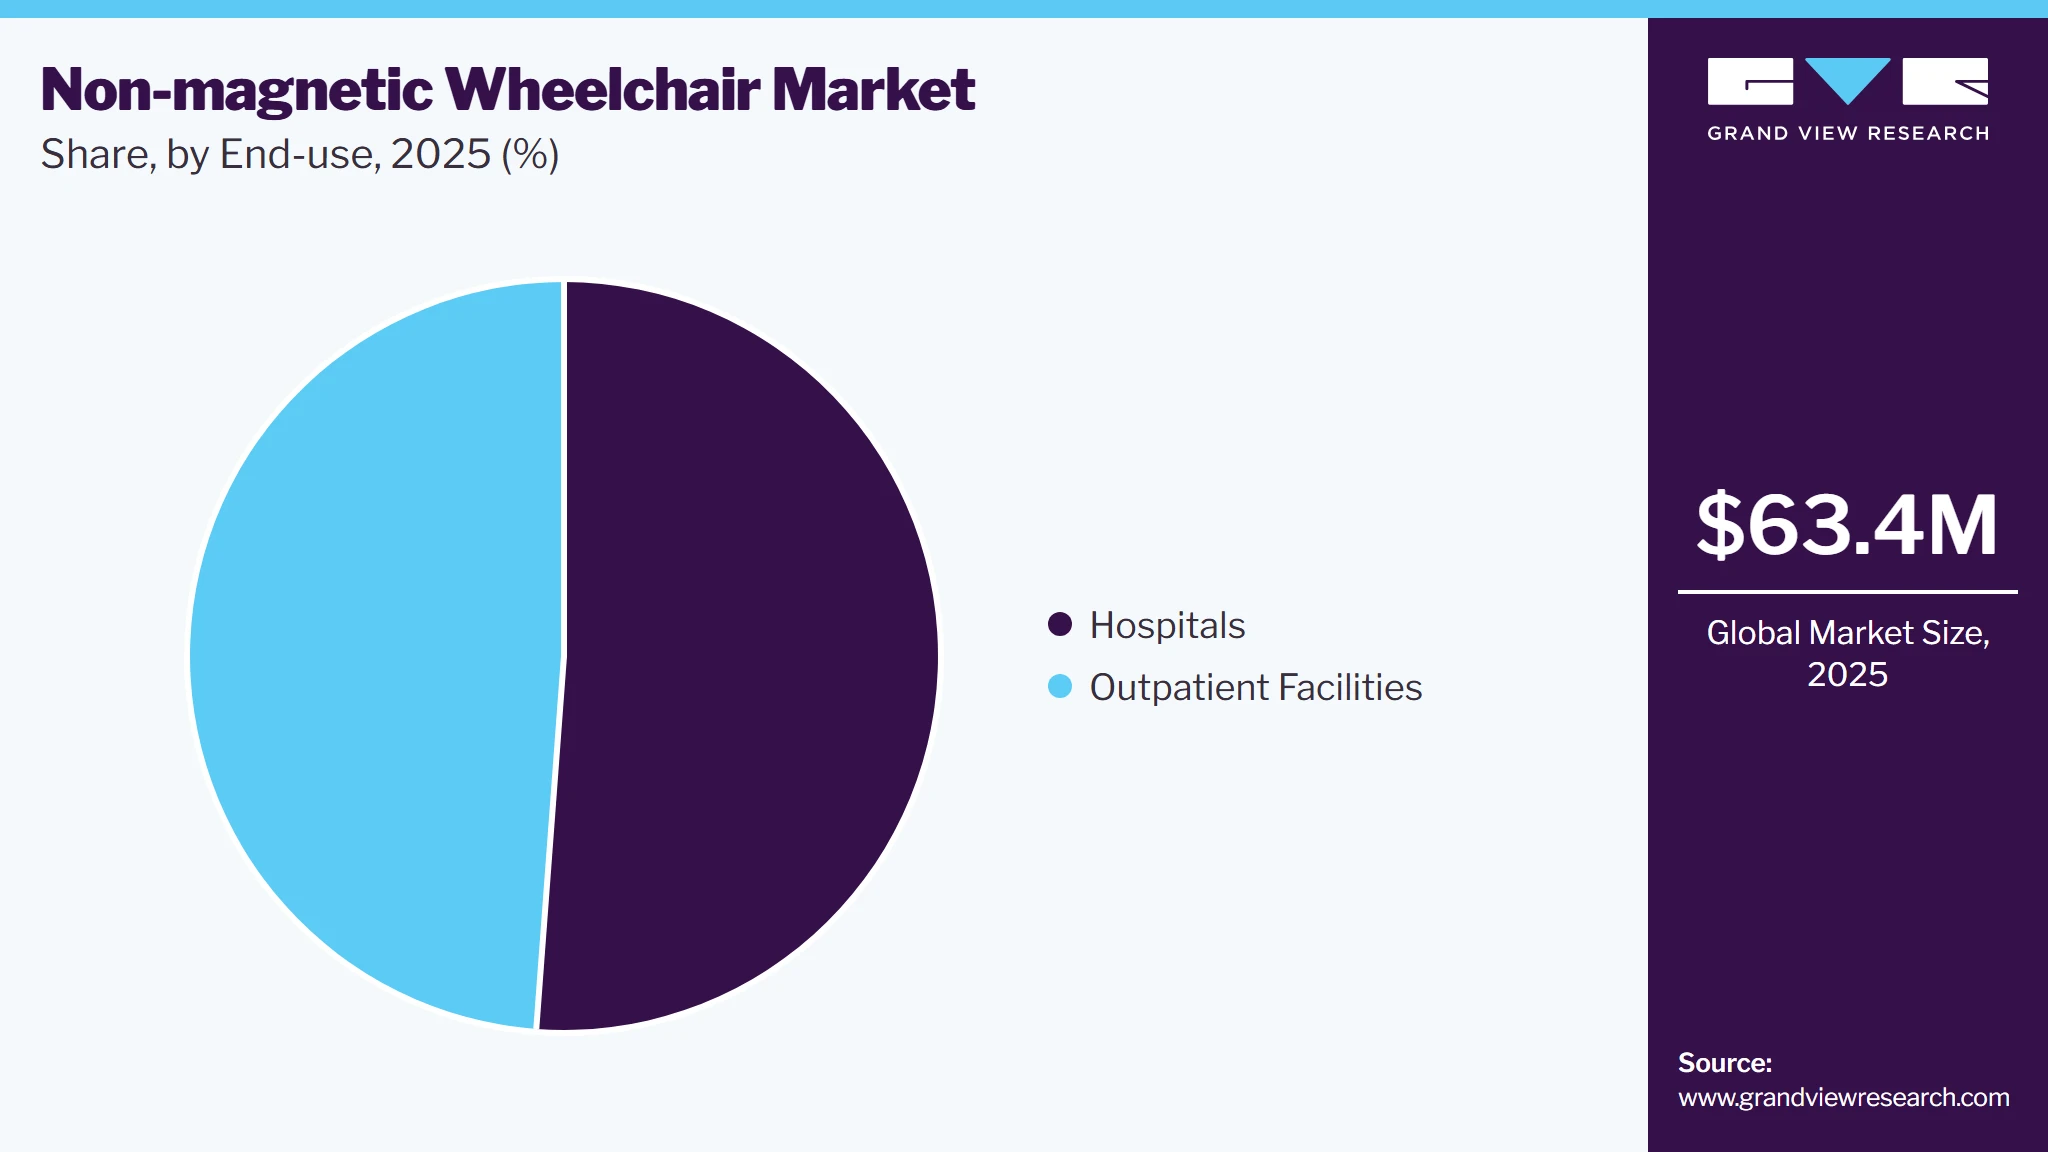
Based on end-use, the hospitals segment led the market with the largest revenue share of 51.2% in 2025. The dominant share is attributed to hospitals as they cater to a diverse patient population, provide a range of diagnostic services, handle complex and specialized cases privy to MRI scans, and have higher financial budgets for technology and equipment such as non-magnetic wheelchairs.
 To learn more about this report, Download Free Sample Report
The outpatient facilities segment is estimated to be the fastest-growing, with a CAGR of 7.3% during the forecast period. Outpatient facilities have started to incorporate a range of imaging services for different medical applications, which is expected to drive demand for non-magnetic wheelchairs. According to an article by AORN Inc. in June 2022, interventional radiology-based medical procedures have started to gain traction in ambulatory surgery centers (ASCs) which are expected to augment growth for imaging services such as MRI and subsequent demand for non-magnetic equipment.
Regional Insights
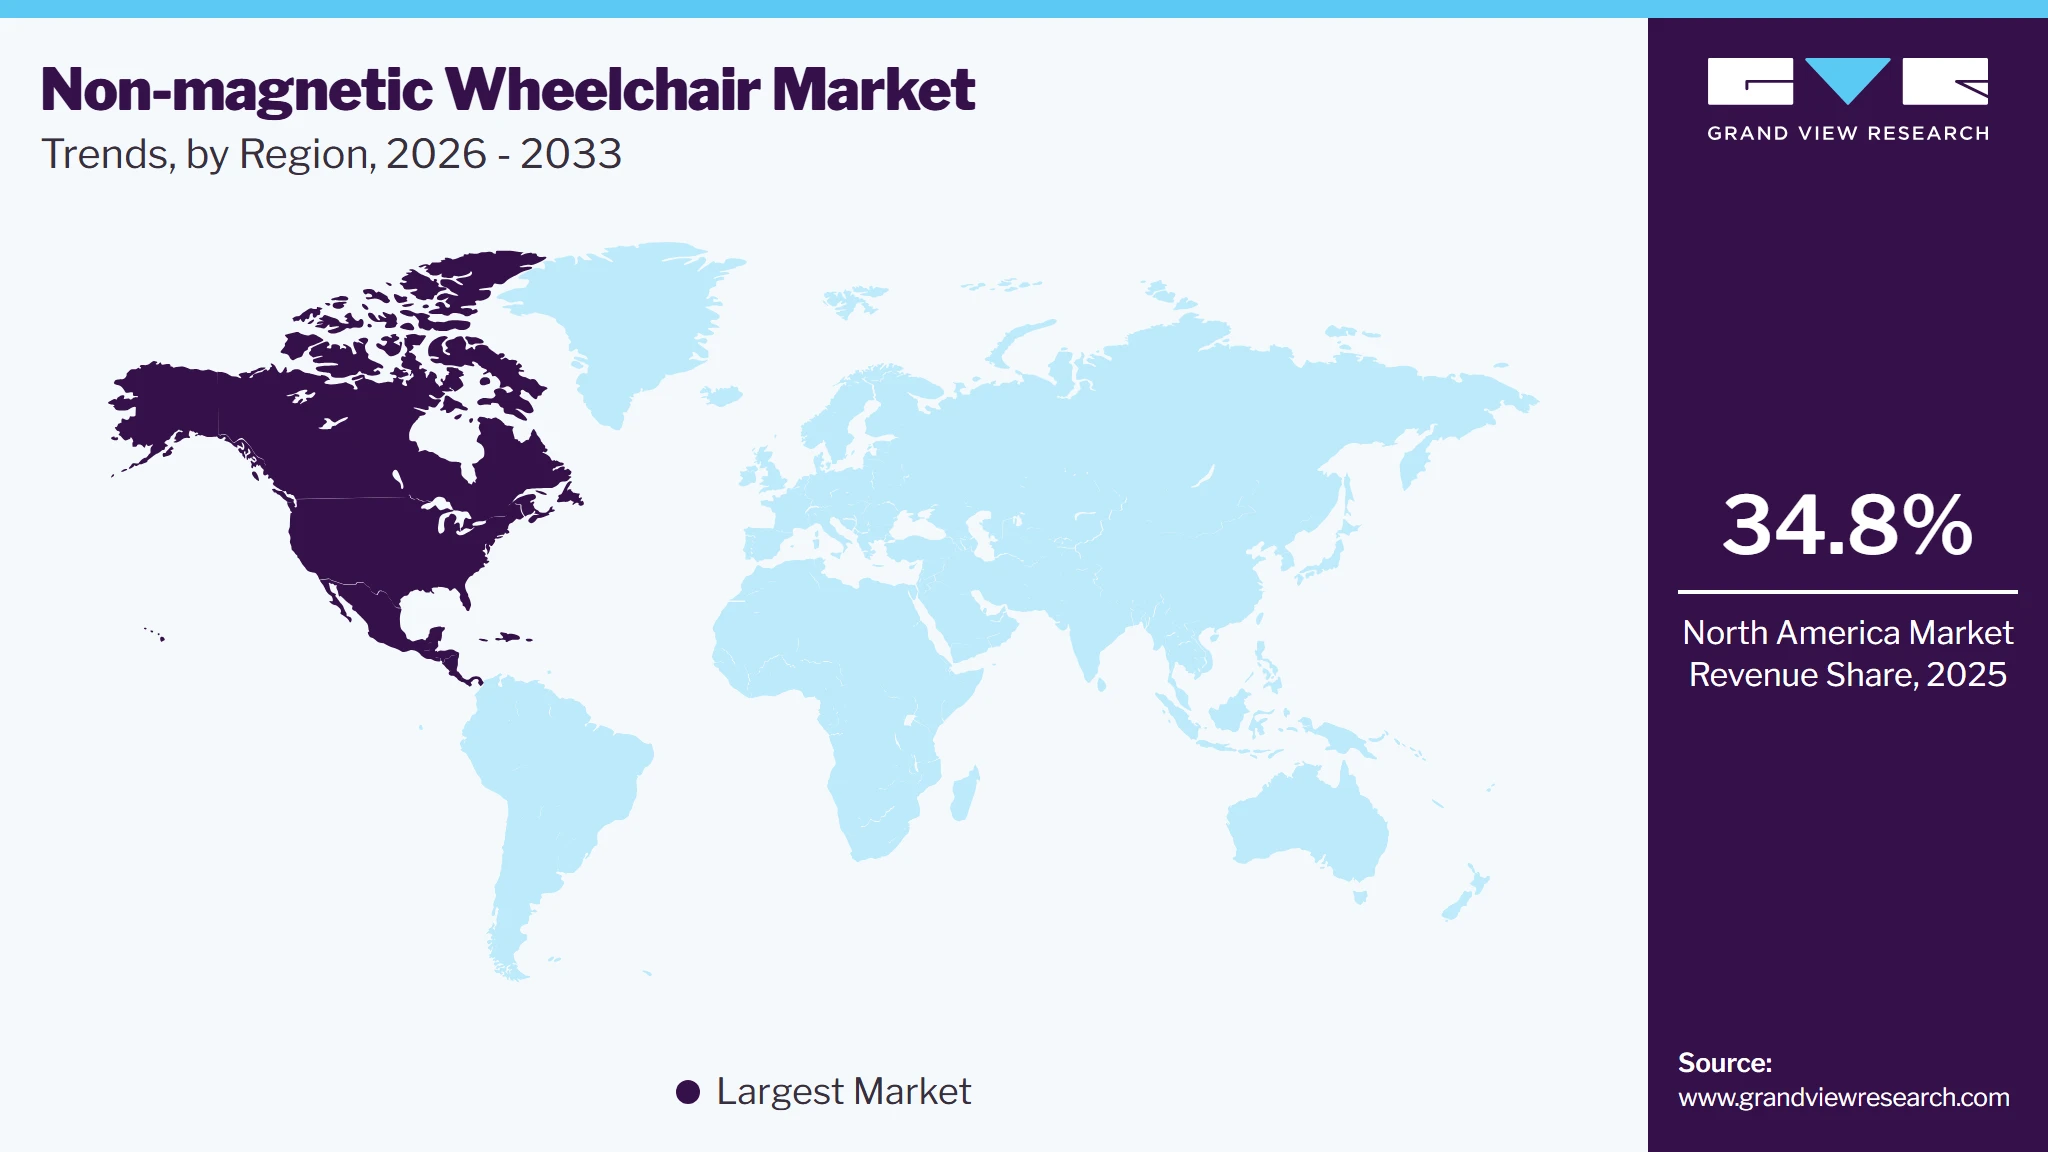
North America dominated the non-magnetic wheelchair market with the largest revenue share of 34.8% in 2025. The share can be attributed to the presence of advanced healthcare technologies, superior healthcare reimbursement policies, and a growing geriatric population susceptible to diseases. Growing sports injuries in Canada and the U.S. supplement the expansion of non-magnetic wheelchairs. According to an article by Springer in September 2022, four sports contributed to nearly 33% of all fatal injuries in Canada, augmenting the need for medical scans and wheelchairs.
 To learn more about this report, Download Free Sample Report
The non-magnetic wheelchair market in the U.S. held the largest share in the North America region in 2025.
Asia Pacific Non-magnetic Wheelchair Market Trends
Asia Pacific is expected to witness the fastest CAGR of 7.9% over the forecast period. The growth can be attributed to the advancements in medical technology, increasing support from government bodies, and public-private partnerships to enhance healthcare services. According to an article by the World Economic Forum in September 2022, India received USD 7.7 billion in 2021 for nearly 25 healthcare projects
India is developing an in-house connected value chain for MRI machines, which is expected to fulfill the deficit of medical imaging machines. For instance, in April 2023, Siemens Healthineers opened its new healthcare imaging manufacturing unit in Bengaluru, India.
Key Company & Market Share Insights
Market is highly competitive, with a large number of manufacturers, and the players are focusing on various strategic initiatives such as new product launches, geographical expansion, mergers and acquisitions, collaboration, product upgradation, and partnerships. For instance, in January 2023, Wheel Freedom Ltd launched an aircraft-grade aluminum wheelchair, Rogue 2.
Key Non-magnetic Wheelchair Companies
The following key companies have been profiled for this study on the non-magnetic wheelchair market.
-
GF Health Products, Inc.
-
Magmedix, Inc.
-
MRIequip.com
-
Newmatic Medical
-
AliMed
-
Innovative Products Unlimited, Inc.
-
Nanning Hhao Technology Co., Ltd
-
Matsunaga
-
Hebei Webian Medical Instrument Co., Ltd
-
Jiangsu Rooe Medical Technology Co., Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (GF Health Products, AliMed, Innovative Products Unlimited, Inc. (IPU), Matsunaga Corporation)
- Focus on expanding MRI-compatible mobility portfolios, including non-magnetic wheelchairs, MRI-safe stretchers, transport chairs, and patient handling equipment.
- Invest in lightweight composite materials, ergonomic wheelchair designs, enhanced patient comfort features, and MRI safety certifications.
- Strengthen distribution partnerships with hospitals, diagnostic imaging centers, and healthcare infrastructure projects globally.
- Expand presence in emerging healthcare markets through direct sales and distributor networks.
- Strong brand recognition within MRI safety and healthcare equipment markets.
- Extensive regulatory compliance experience and established relationships with hospitals, imaging centers, and healthcare procurement organizations.
- Broad MRI-compatible product portfolios enable bundled sales opportunities.
- Proven product reliability, long operating history, and strong after-sales support networks enhance customer retention and market leadership.
- High manufacturing and certification costs associated with MRI-compatible materials and safety testing.
- Dependence on hospital capital expenditure cycles may slow purchasing decisions.
- Longer procurement processes in public healthcare systems can delay revenue realization.
- Increasing competition from lower-cost regional manufacturers may create pricing pressure in developing markets.
Emerging Players (Jiangsu Rooe Medical Technology Co. Ltd, Magmedix Inc., MRIequip.com, Hebei Webian Medical Instrument Co., Ltd.)
- Focus on cost-effective non-magnetic wheelchairs designed for hospitals, outpatient imaging centers, and diagnostic facilities.
- Emphasize lightweight designs, customizable configurations, and competitive pricing strategies to attract budget-conscious healthcare providers.
- Expand into underserved markets with growing MRI installation rates.
- Leverage online sales channels, distributor partnerships, and localized customer support to increase market penetration.
- Greater operational flexibility and faster product customization capabilities.
- Ability to offer competitively priced MRI-compatible wheelchairs tailored to regional healthcare requirements.
- Strong focus on niche MRI safety applications and responsive customer service.
- Lower overhead costs enable quicker adaptation to changing customer demands and procurement trends.
- Limited global brand recognition and smaller installed customer base compared with established competitors.
- Restricted financial resources may constrain R&D investments and international expansion efforts.
- Fewer regulatory approvals and limited clinical validation can affect customer confidence.
- Greater exposure to competitive pricing pressures and procurement challenges in large healthcare systems.
Non-magnetic Wheelchair Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 63.4 million
Market size value in 2026
USD 67.8 million
Revenue forecast in 2033
USD 108.5 million
Growth rate
CAGR of 6.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Patient Weight, Magnetic Field Strength, End-use and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
GF Health Products, Inc.; Magmedix Inc.; MRIequip.com; Newmatic Medical; AliMed; Innovative Products Unlimited, Inc.; Nanning Hhao Technology Co. Ltd; Matsunaga; Hebei Webian Medical Instrument Co. Ltd; Jiangsu Rooe Medical Technology Co. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Non-magnetic Wheelchair Market Report Segmentation
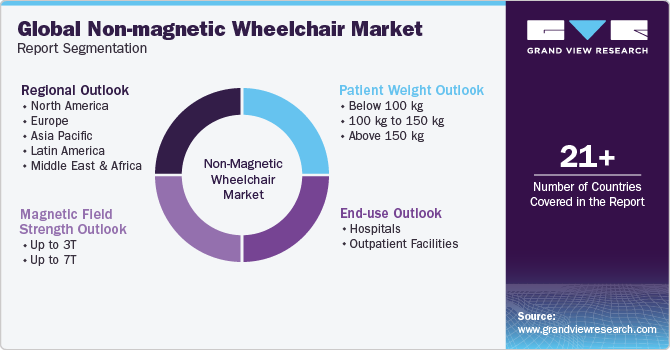
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global non-magnetic wheelchair market report based on patient weight, magnetic field strength, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Patient Weight Outlook (Revenue, USD Million, 2021 - 2033)
-
Below 100 kg
-
100 kg to 150 kg
-
Above 150 kg
-
-
Magnetic Field Strength Outlook (Revenue, USD Million, 2021 - 2033)
-
Up to 3T
-
Up to 7T
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Outpatient Facilities
-
-
Regional Outlook (Revenue, USD Million 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The non-magnetic wheelchair market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each non-magnetic wheelchair segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Patient Weight
Revenue capture definition
Below 100kg
This segment includes non-magnetic wheelchairs designed for patients weighing less than 100 kilograms. These wheelchairs are commonly used in hospitals, diagnostic imaging centers, and outpatient facilities for routine patient transportation within MRI environments. Their lightweight construction improves maneuverability, making them suitable for elderly patients, ambulatory patients requiring assistance, and general diagnostic procedures.
100 kg to 150 kg
This category comprises non-magnetic wheelchairs engineered to safely accommodate patients weighing between 100 kg and 150 kg. These models feature reinforced frames, enhanced seating support, and higher durability while maintaining MRI compatibility. They are widely used in hospitals and imaging centers experiencing increasing numbers of overweight and bariatric patients requiring safe transport during MRI examinations and other diagnostic procedures.
Above 150 kg
This segment includes bariatric non-magnetic wheelchairs specifically designed for patients weighing more than 150 kilograms. These wheelchairs incorporate heavy-duty non-ferromagnetic materials, wider seating dimensions, strengthened structural components, and enhanced stability features. They are primarily utilized in tertiary care hospitals, specialty imaging facilities, and bariatric care centers where safe transportation of high-weight patients into MRI suites is essential while maintaining strict MRI safety compliance.
Segment - Magnetic Field Strength
Revenue capture definition
Upto 3T
This segment includes non-magnetic wheelchairs designed for use in MRI environments with magnetic field strengths of up to 3 Tesla (3T). These wheelchairs are manufactured using non-ferromagnetic materials to ensure patient and staff safety while preventing interference with MRI imaging quality. They are widely utilized in hospitals, diagnostic imaging centers, and outpatient facilities where 1.5T and 3T MRI systems represent the most commonly installed scanners. The segment accounts for a significant share of demand due to the widespread adoption of 3T MRI systems for routine diagnostic imaging across neurology, orthopedics, cardiology, and oncology applications.
Upto 7T
This segment comprises specialized non-magnetic wheelchairs designed for compatibility with ultra-high-field MRI systems operating at magnetic field strengths of up to 7 Tesla (7T). These wheelchairs incorporate advanced non-magnetic materials and stringent safety features to meet the requirements of highly sensitive research and advanced clinical imaging environments. They are primarily used in academic medical centers, research institutions, and specialized hospitals equipped with 7T MRI systems for neurological, musculoskeletal, and advanced diagnostic imaging applications. Growing investments in high-resolution imaging technologies and research infrastructure are supporting demand within this segment.
Segment - End-use
Revenue capture definition
Hospitals
This segment includes revenue generated from non-magnetic wheelchair sales to hospitals, including general hospitals, tertiary care centers, specialty hospitals, and academic medical institutions. Hospitals represent the largest end-user category due to their high patient volumes, extensive MRI infrastructure, and need for safe patient transportation within imaging departments. Demand is driven by increasing MRI procedure volumes, growing focus on patient safety, and the need to accommodate diverse patient populations, including elderly, mobility-impaired, and bariatric patients.
Outpatient Facilities
This segment comprises non-magnetic wheelchairs utilized in outpatient facilities, including standalone diagnostic imaging centers, ambulatory care centers, and specialty clinics offering MRI services. These facilities require MRI-compatible patient transport solutions to ensure safe movement of patients within imaging environments while maintaining operational efficiency. The segment is benefiting from the growing shift toward outpatient diagnostic services, increasing establishment of independent imaging centers, and rising demand for cost-effective healthcare delivery models that reduce hospital burden while maintaining access to advanced imaging procedures.
Estimation Model
Scope Definition
Build the Product Base
Estimate Penetration
Revenue Conversion
What is being sized?
How large is total addressable market?
What portion is transitioning to next-generation smart systems?
How does unit volume become market revenue?
PROCESS STEPS
1. Define non-magnetic wheelchair product categories.
2. Scope end-use environments such as MRI suites, radiology departments, hospitals, diagnostic imaging centers, and ambulatory care facilities.
3. Establish geographic boundaries (Global, North America, Europe, Asia-Pacific, Latin America, and MEA).
4. Align on base year & forecast horizon (2026-2033).
DATA SOURCES: Industry publications, healthcare association reports
PROCESS STEPS
1. Collect MRI installation volumes and healthcare facility counts by region.
2. Estimate installed base of MRI-compatible wheelchairs across hospitals and imaging centers.
3. Map product utilization by facility type and patient volume.
4. Project procurement demand based on healthcare infrastructure expansion and MRI suite growth.
DATA SOURCES: Hospital registries, imaging center databases, healthcare facility records, company filings
PROCESS STEPS
1. Assess adoption rates of MRI-safe mobility solutions across healthcare facilities.
2. Analyze replacement cycles and purchasing patterns for MRI-compatible equipment.
3. Identify premium, standard, and bariatric wheelchair penetration across regions.
4. Validate estimates through hospital procurement interviews and distributor surveys.
DATA SOURCES: Primary interviews, company filings, trade surveys
PROCESS STEPS
1. Collect Average Selling Prices (ASPs).
2. Segment revenue by product type, end user, and geography.
3. Apply replacement cycles and procurement frequency to estimate annual demand.
4. Triangulate and Validate.
DATA SOURCES: Hospital procurement/tender archives, distributor pricing sheets, import/export databases
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Product Innovation and MRI Compatibility Assessment
Conducted a comprehensive assessment of MRI-compatible wheelchair technologies, non-ferrous material innovations, safety standards, and product performance across major manufacturers. The analysis evaluated wheelchair construction materials, weight-bearing capacities, maneuverability, infection-control features, ergonomic designs, and compatibility with high-field MRI environments. The study further assessed advancements in lightweight composite materials, corrosion-resistant frames, and enhanced patient transfer solutions designed specifically for imaging departments.
This analysis enables stakeholders to understand how product innovation is improving patient safety, operational efficiency, and MRI workflow management. It highlights opportunities in advanced material technologies, ergonomic product development, and specialized mobility solutions while identifying key differentiation factors that support procurement decisions and long-term market growth.
Macroeconomic Analysis of the Non-Magnetic Wheelchair Market
Conducted a detailed geographic assessment of the market across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. The study evaluated the impact of healthcare infrastructure investments, MRI installation growth, aging populations, disability prevalence, hospital modernization initiatives, and healthcare spending on market demand. The analysis further examined expansion in diagnostic imaging facilities, outpatient centers, and specialized radiology departments requiring MRI-safe mobility equipment.
This analysis enables stakeholders to evaluate regional growth opportunities, procurement trends, and healthcare infrastructure developments across key markets. It supports strategic planning for market expansion, distributor partnerships, product localization, and investment prioritization in regions experiencing rapid growth in diagnostic imaging services and hospital capacity.
Competitive Landscape Analysis
Conducted a detailed assessment of leading MRI-compatible wheelchair manufacturers and specialized medical mobility equipment providers across major regions. The analysis evaluated product portfolios, pricing strategies, distribution networks, hospital relationships, regulatory compliance, and product certifications. Furthermore, the study assessed competitive differentiation based on material technology, customization capabilities, product durability, safety features, after-sales support, and healthcare facility penetration.
This analysis enables stakeholders to understand competitive positioning, benchmark market shares, identify technology gaps, and evaluate growth opportunities. It supports corporate strategy, partnership development, procurement planning, and product portfolio optimization by uncovering competitor strengths, commercialization strategies, and emerging trends within the MRI-compatible mobility equipment market.
Frequently Asked Questions About This Report
The global non-magnetic wheelchair market size was estimated at USD 63.4 million in 2025 and is expected to reach USD 67.8 million in 2026.
The global non-magnetic wheelchair market is expected to grow at a compound annual growth rate of 6.9% from 2026 to 2033 to reach USD 108.5 million by 2033.
North America dominated the global non-magnetic wheelchair market and accounted for 34.8% of the total market share in 2025. The significant growth of this region's non-magnetic wheelchair market is driven by several factors, including the substantial geriatric population, advanced healthcare infrastructure, and relatively high disposable incomes.
Some of the key players in thenon-magnetic wheelchair market are GF Health Products, Inc., Magmedix Inc., MRIequip.com, Newmatic Medical, AliMed, Innovative Products Unlimited, Inc., Nanning Hhao Technology Co., Ltd, Matsunaga, Hebei Webian Medical Instrument Co., Ltd, and Jiangsu Rooe Medical Technology Co., Ltd.
The non-magnetic wheelchair market is expected to grow due to several factors, such as increasing geriatric population, growing prevalence of physiological and neurological diseases, and increasing installations of imaging modalities such as magnetic resonance imaging (MRI).
By magnetic fielld strength, upto 3T segment led with a 78.5% revenue share in 2025, while upto 7T segment is the fastest-growing.
Asia Pacific is the fastest-growing region over the forecast period.
Above 150 kg held the largest revenue share in 2025 and is the fastest-growing area.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


