
- Home
- »
- Power Generation & Storage
- »
-
Nuclear Power Plant Equipment Market Size Report, 2033GVR Report cover

Nuclear Power Plant Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Carrier (Island Equipment, Auxiliary Equipment), By Reactor (Pressurized Water Reactor, Boiling Water Reactor, Pressurized Heavy Water Reactor), By Region, And Segment Forecasts
Market Size, 2025
$22.2BMarket Estimate, 2026
$23.0BMarket Forecast, 2033
$28.8BCAGR, 2026–2033
3.3%Nuclear Power Plant Equipment Market Summary
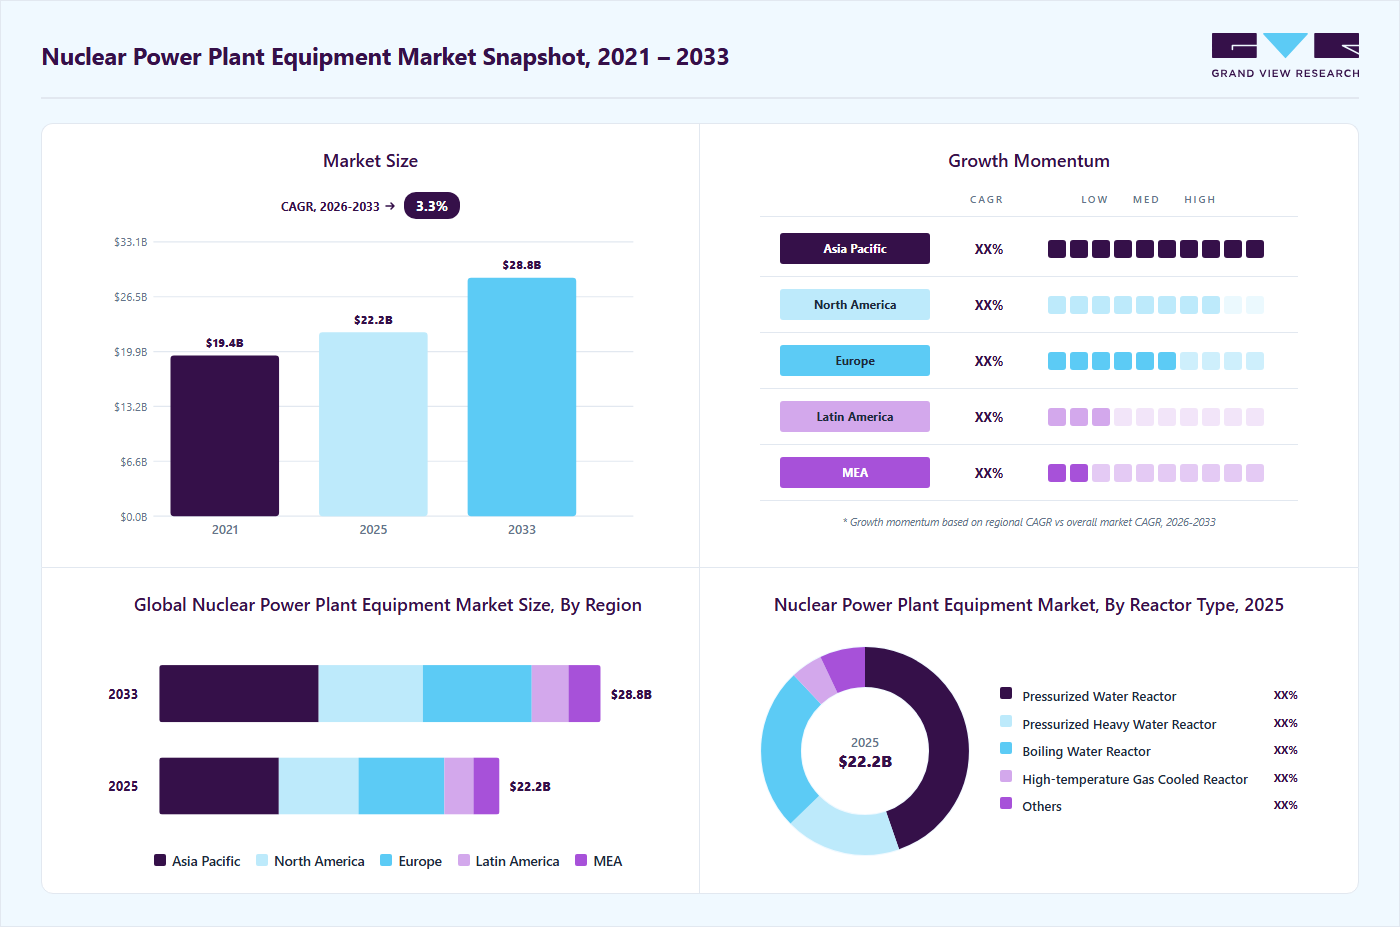
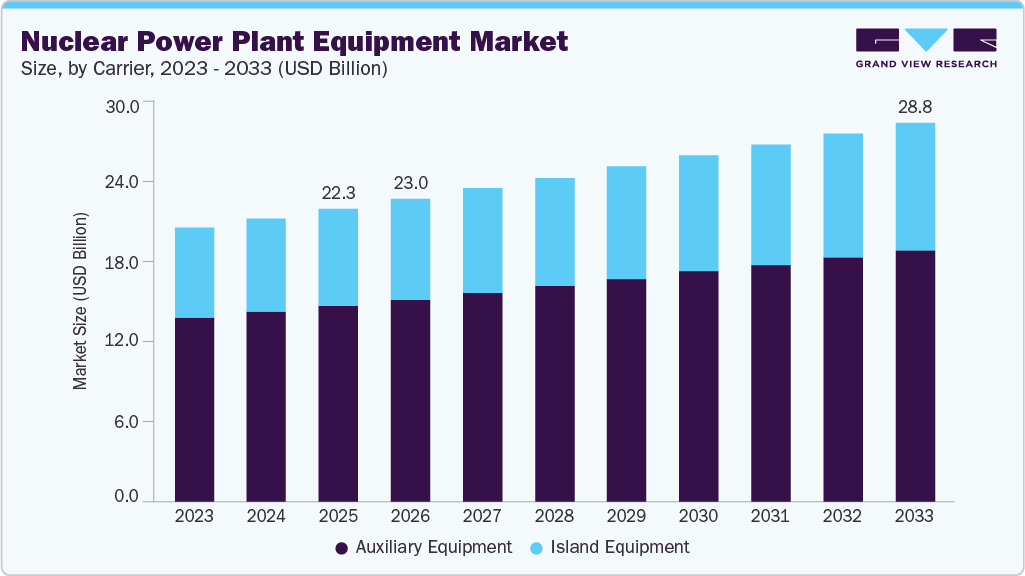
The global nuclear power plant equipment market size was estimated at USD 22.2 billion in 2025 and is projected to grow from USD 23.0 billion in 2026 to USD 28.8 billion by 2033, at a CAGR of 3.3% from 2026 to 2033. Asia Pacific held the largest revenue share of 35.3% of the global market in 2025. Market growth is primarily driven by the revival of nuclear energy programs, rising demand for low-carbon baseload power, and increasing investments in new nuclear power plants, as well as refurbishment and life-extension of existing facilities.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By carrier: Auxiliary Equipment segment held the largest market share of 66.8% in 2025.
- By reactor: Pressurized Water Reactor (PWR) segment held the largest market share in 2025.
- By reactor: Boiling Water Reactor (BWR) segment is expected to register the fastest CAGR of 3.8% over the forecast period.
Regional Highlights
- Largest regional market: Asia Pacific (35.3% market share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR from 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 22.2 Billion
- Market size in 2026: USD 23.0 Billion
- Projected market size by 2033: USD 28.8 Billion
- CAGR (2026-2033): 3.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Governments and utilities are increasingly prioritizing atomic power to meet energy security and decarbonization targets, particularly amid growing electricity demand and volatility in fossil fuel markets. In addition, concerns related to grid stability, energy reliability, and intermittency of renewable energy sources are accelerating investments in nuclear power infrastructure, thereby driving demand for critical plant equipment such as reactor vessels, steam generators, turbines, control systems, pumps, valves, and heat exchangers. Technological advancements in advanced reactor designs, digital instrumentation and control (I&C) systems, improved safety components, and automation technologies are further enhancing the efficiency, safety, and performance of nuclear power plant equipment.
 To learn more about this report, Download Free Sample Report
The market is also gaining momentum due to supportive government policies, nuclear capacity expansion plans, and public-private investments across major economies. Increasing focus on plant safety upgrades, operational efficiency, life-cycle cost optimization, cybersecurity for nuclear facilities, and compliance with stringent regulatory standards, along with growing deployment of small modular reactors (SMRs), is expected to sustain steady market expansion over the forecast period.
Drivers, Opportunities & Restraints
The revival of nuclear power programs primarily drives the global nuclear power plant equipment industry to meet growing electricity demand, energy security requirements, and long-term decarbonization targets. Governments and utilities are increasingly investing in new nuclear power plants, life-extension of existing reactors, and replacement of aging equipment to ensure safe and reliable baseload power generation. In addition, rising concerns around grid stability, intermittency of renewable energy sources, and the need for dependable low-carbon energy are further accelerating investments in nuclear infrastructure and associated equipment.
Opportunities are expanding due to technological advancements in reactor design, digital instrumentation and control (I&C) systems, automation, and advanced safety technologies, which improve plant efficiency, reliability, and operational safety. The growing deployment of small modular reactors (SMRs) and next-generation nuclear technologies is creating new demand for compact, standardized, and factory-manufactured atomic equipment. In addition, increasing focus on plant modernization, life-cycle cost optimization, and retrofitting of safety and monitoring systems, along with government funding and public-private partnerships, is opening new growth avenues across both developed and emerging markets.
However, the market faces restraints such as high capital investment requirements, lengthy construction timelines, and stringent regulatory and licensing processes associated with nuclear power projects. Complexity related to atomic safety compliance, supply chain readiness, and skilled workforce availability can delay equipment deployment. Furthermore, challenges related to nuclear waste management, public perception of nuclear safety, financing constraints, and long approval cycles may limit the pace of market expansion over the forecast period.
Carrier Insights
The auxiliary equipment segment held the largest revenue share of approximately 66.8% in 2025. This dominance is primarily driven by the extensive use of auxiliary systems across all nuclear power plant operations, including cooling systems, pumps, valves, heat exchangers, electrical systems, safety systems, and instrumentation components. These systems are critical for ensuring safe reactor operation, thermal efficiency, regulatory compliance, and continuous power generation, resulting in sustained demand across both new nuclear installations and the refurbishment of existing plants. In addition, ongoing investments in plant modernization, safety upgrades, and life-extension programs for aging atomic facilities continue to support strong demand for auxiliary equipment.
The island equipment segment is expected to register the fastest CAGR of 3.5% over the forecast period, supported by increasing investments in new nuclear power plants and advanced reactor technologies, including small modular reactors (SMRs). Island equipment comprising reactor vessels, steam generators, containment systems, and core components is witnessing rising demand due to growing focus on enhanced safety features, higher thermal efficiency, and standardized reactor designs. Furthermore, advancements in manufacturing techniques, modular construction, and digital monitoring systems, along with government-backed nuclear expansion programs, are expected to drive steady growth in this segment, positioning island equipment as the fastest-growing carrier in the global market.
Reactor Insights
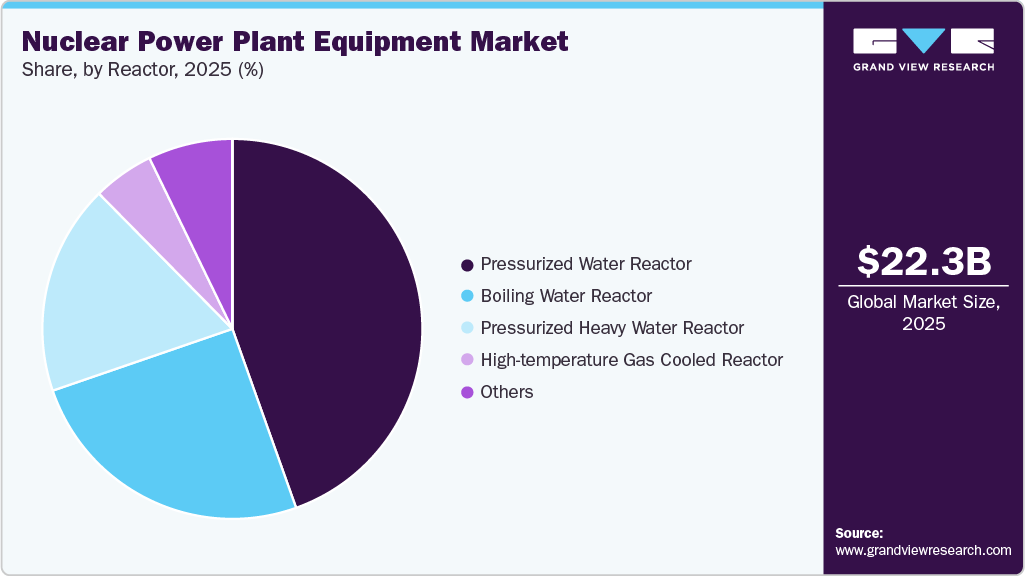
The Pressurized Water Reactor (PWR) segment held the largest revenue share of approximately 44.6% in 2025. This dominance is primarily driven by the widespread deployment of PWR technology across both existing and new nuclear power plants due to its proven operational reliability, enhanced safety features, and standardized design. PWRs require extensive nuclear island and auxiliary equipment, including reactor pressure vessels, steam generators, coolant pumps, and advanced safety systems, which significantly contribute to higher equipment demand. In addition, ongoing investments in life-extension programs, safety upgrades, and refurbishment of aging PWR-based facilities continue to support strong revenue generation for this segment.
 To learn more about this report, Download Free Sample Report
The Boiling Water Reactor (BWR) segment is expected to register the fastest CAGR of 3.8% over the forecast period, driven by renewed interest in modernized BWR designs and upgrades to existing reactor fleets. Increasing focus on improving operational efficiency, simplifying reactor systems, and enhancing safety performance is supporting demand for advanced equipment across BWR-based plants. Furthermore, technological advancements in digital instrumentation and control systems, advanced materials, and modular equipment manufacturing, along with selective new-build projects and plant modernization initiatives, are expected to sustain steady growth in the BWR segment, positioning it as the fastest-growing reactor in the global market.
Regional Insights
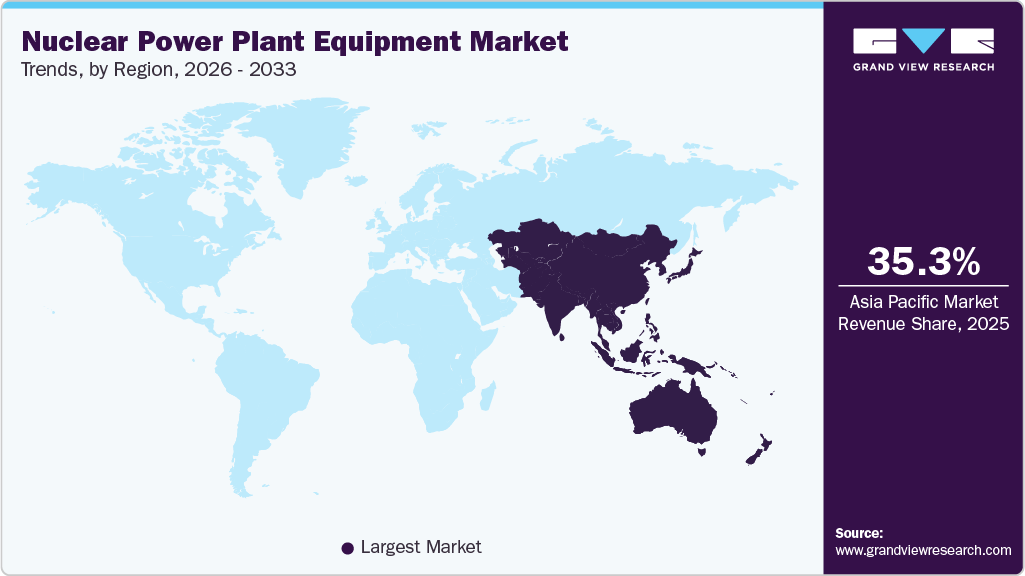
Asia Pacific nuclear power plant equipment industry accounted for approximately 35.3% of the global revenue in 2025, making it the largest regional market. Extensive nuclear power expansion programs, rising electricity demand, and strong government investments in new nuclear reactor construction across countries such as China, India, Japan, and South Korea primarily drive this dominance. The region continues to witness significant deployment of new nuclear power plants, reactor upgrades, and capacity additions, resulting in strong demand for atomic island equipment, auxiliary systems, and safety-related components.
 To learn more about this report, Download Free Sample Report
Asia Pacific is also expected to register the fastest CAGR of 3.6% over the forecast period, supported by ongoing reactor construction projects, refurbishment of aging nuclear facilities, and adoption of advanced reactor technologies. Increasing focus on energy security, decarbonization, and replacement of coal-based power generation, along with localization of nuclear manufacturing supply chains, is expected to sustain steady market growth across the region.
North America Nuclear Power Plant Equipment Market Trends
North America nuclear power plant equipment industry represents a mature yet strategically important market, supported by life-extension programs for existing reactors, safety modernization initiatives, and selective new nuclear investments. The region benefits from advanced nuclear engineering capabilities, strong regulatory frameworks, and continued investments in equipment upgrades, digital instrumentation and control systems, and safety enhancements to maintain long-term plant reliability.
U.S. Nuclear Power Plant Equipment Market Trends
The U.S. nuclear power plant equipment industry remains a major contributor to the North American market, driven by reactor life-extension programs, uprating projects, and replacement of aging plant components. Increasing investments in safety system upgrades, digital control technologies, and operational efficiency improvements, along with federal support for nuclear energy and advanced reactor development, continue to support steady equipment demand across the country.
Europe Nuclear Power Plant Equipment Market
Europe nuclear power plant equipment industry represents a steadily growing market, supported by energy security concerns, decarbonization targets, and renewed interest in nuclear power across several countries. Investments in reactor refurbishment, safety upgrades, and selective new atomic projects in countries such as France, the UK, and Eastern Europe are driving demand for nuclear power plant equipment. Regulatory alignment and long-term nuclear strategies are further supporting regional growth.
Latin America Nuclear Power Plant Equipment Market
The Latin American nuclear power plant equipment industry is witnessing moderate growth, supported by capacity expansion and modernization efforts in countries such as Brazil and Argentina. Increasing focus on energy diversification, grid reliability, and low-carbon baseload generation is expected to drive investments in nuclear equipment across the region gradually.
Middle East & Africa Nuclear Power Plant Equipment Market
The Middle East & Africa nuclear power plant equipment industry is experiencing gradual expansion, driven by new nuclear power projects and long-term energy diversification strategies in countries such as the UAE, Egypt, and South Africa. Government-backed atomic development programs, along with rising power demand and energy security concerns, are expected to support steady growth in nuclear power plant equipment demand across the region.
Key Nuclear Power Plant Equipment Company Insights
Some of the key players operating in the global Nuclear Power Plant Equipment industry include ALSTOM SA, BWX Technologies, Inc., DOOSAN CORPORATION, Dongfang Electric Co., Ltd., and AVEVA, among others. These companies are actively involved in the design, manufacturing, and supply of critical nuclear power plant equipment, including reactor vessels, steam generators, turbines, auxiliary systems, digital control solutions, and safety-related components.
Their strategic focus includes enhancing plant safety, improving operational efficiency, extending reactor lifespans, and supporting new nuclear power plant construction and modernization projects. In addition, increasing investments in advanced reactor technologies, small modular reactors (SMRs), digital instrumentation and control (I&C) systems, and predictive maintenance solutions are helping market participants strengthen reliability, regulatory compliance, and cost efficiency across nuclear power facilities worldwide.
Key Nuclear Power Plant Equipment Companies:
The following key companies have been profiled for this study on the nuclear power plant equipment market.
- ALSTOM SA
- AVEVA
- BWX Technologies, Inc.
- Dongfang Electric Co., Ltd.
- DOOSAN CORPORATION
- EDF
- GE Hitachi Nuclear Energy
- NuScale Power, LLC
- Shanghai Electric
- X Energy
Recent Developments
-
In February 2025, BWX Technologies, Inc. expanded its nuclear equipment manufacturing and services capabilities to support reactor life-extension programs and new nuclear build projects, including the supply of reactor pressure vessels, nuclear fuel systems, and critical auxiliary components. The development also supported the company’s growing involvement in advanced reactor and SMR-related equipment supply.
-
In June 2025, GE Hitachi Nuclear Energy advanced multiple nuclear power plant equipment modernization initiatives, focusing on reactor systems, digital instrumentation and control (I&C) upgrades, and safety-critical equipment enhancements for both existing reactors and new projects. These efforts are aimed at improving operational efficiency, safety performance, and lifecycle cost optimization for nuclear power plant operators.
Nuclear Power Plant Equipment Market Report Scope
Report Attribute
Details
Market Definition
The nuclear power plant equipment industry represents the global revenue generated from the manufacturing, supply, installation, and maintenance of critical equipment and systems used in nuclear power plants, including reactor components, turbines, auxiliary systems, safety equipment, and control technologies.
Market size value in 2025
USD 22.2 billion
Estimated Market size in 2026
USD 23.0 billion
Projected Market size by 2033
USD 28.8 billion
Growth rate
CAGR of 3.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative Units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Carrier, reactor, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; India; Japan; South Korea; Brazil; Saudi Arabia; UAE
Key companies profiled
ALSTOM SA; AVEVA; BWX Technologies, Inc.; Dongfang Electric Co., Ltd.; DOOSAN CORPORATION; EDF; GE Hitachi Nuclear Energy; NuScale Power, LLC; Shanghai Electric; X Energy
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Nuclear Power Plant Equipment Market Report Segmentation
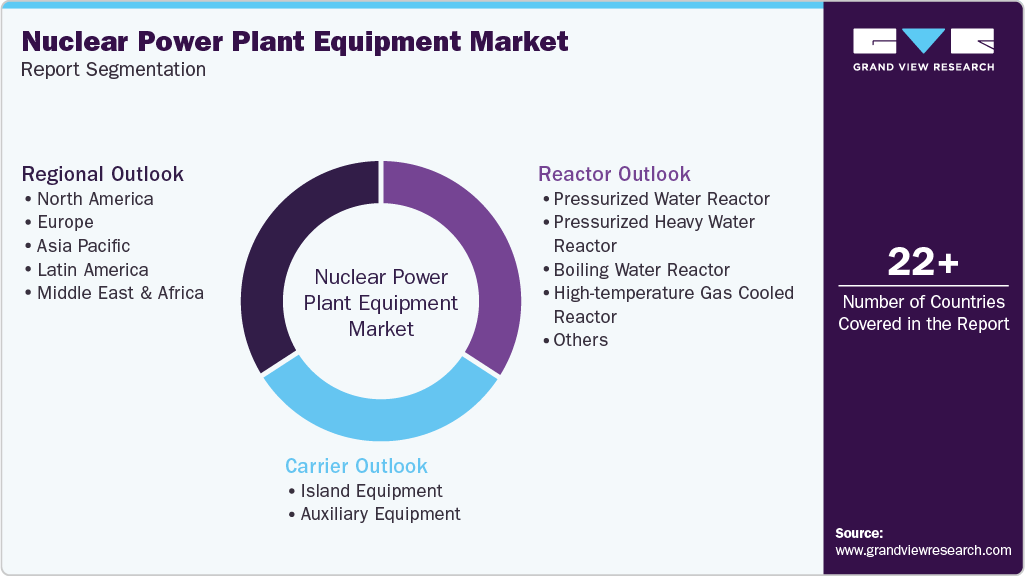
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global nuclear power plant equipment market report based on carrier, reactor, and region.
 To learn more about this report, Download Free Sample Report
-
Carrier Outlook (Revenue, USD Million, 2021 - 2033)
-
Island Equipment
-
Auxiliary Equipment
-
-
Reactor Outlook (Revenue, USD Million, 2021 - 2033)
-
Pressurized Water Reactor
-
Pressurized Heavy Water Reactor
-
Boiling Water Reactor
-
High-temperature Gas Cooled Reactor
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global nuclear power plant equipment market is expected to grow at a compound annual growth rate of 3.3% from 2026 to 2033 to reach USD 28.8 billion by 2033
The global nuclear power plant equipment market size was estimated at USD 22.2 billion in 2025 and is expected to reach USD 23 billion in 2026.
The auxiliary equipment segment held the largest market share of 66.8% in 2025, while the island equipment segment is expected to register the fastest CAGR of 3.5% over the forecast period.
Some of the key players operating in the global nuclear power plant equipment market include ALSTOM SA, BWX Technologies, Inc., DOOSAN CORPORATION, Dongfang Electric Co., Ltd., GE Hitachi Nuclear Energy, Shanghai Electric, EDF, NuScale Power, LLC, X Energy, and AVEVA, among others
The key factors driving the Nuclear Power Plant Equipment market include renewed investments in nuclear power generation to meet energy security and decarbonization goals, increasing electricity demand, and the need for reliable low-carbon baseload power.
Asia Pacific dominated the market with a 35.3% revenue share in 2025.
Asia Pacific is expected to register the fastest growth over the forecast period.
The Pressurized Water Reactor (PWR) segment held the largest revenue share in 2025, while the Boiling Water Reactor (BWR) segment is expected to register the fastest CAGR of 3.8% over the forecast period.
About the Author(s)
Power Generation & Storage Research Team
Energy & Power · Power Generation & StorageThis report was authored by the power generation & storage research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the power generation & storage segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


