
- Home
- »
- Conventional Energy
- »
-
Oil And Gas Analytics Market Size, Growth Report, 2026-2033GVR Report cover

Oil And Gas Analytics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Offering (Hardware, Software, Service), By Deployment, By Application, By End-user, By Region, And Segment Forecasts
Market Size, 2025
$12.0BMarket Estimate, 2026
$14.6BMarket Forecast, 2033
$56.6BCAGR, 2026–2033
21.4%Oil And Gas Analytics Market Summary
The global oil and gas analytics market size was valued at USD 12.0 billion in 2025 and is projected to grow from USD 14.6 billion in 2026 to USD 56.6 billion by 2033, at a CAGR of 21.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.5% in 2025. The major market growth drivers are the escalating demand for energy worldwide and the need for advanced tools to extract valuable insights from vast datasets.
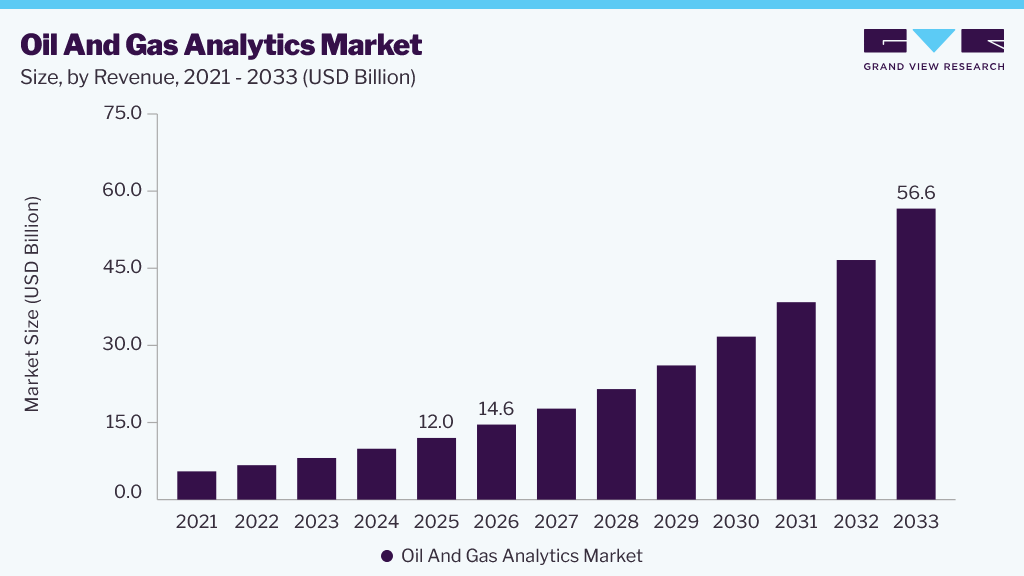 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: The software segment held the largest market share of over 58.5% in 2025.
- By deployment: The cloud segment held the largest market share of over 65.5% in 2025.
- By application: The upstream segment held the largest market share of over 45.0% in 2025.
- By end use: The large enterprises segment held the largest market share of over 72.5% in 2025.
Regional Highlights
- Largest regional market: North America (Over 40.5% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 12.0 Billion
- Estimated market size in 2026: USD 14.6 Billion
- Projected market size by 2033: USD 56.6 Billion
- CAGR (2026-2033): 21.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Companies engaged in the exploration, supply chain, and delivery of hydrocarbons are seeking solutions to reduce operational and maintenance costs, driving the adoption of oil and gas analytics. This technology leverages historical data and recent trends to enhance decision-making, reduce errors, and increase operational efficiency. By integrating workforce and data, analytics enable predictive actions, particularly in upstream applications involving exploration activities.
Despite the market growth facilitated by the increasing energy demand, challenges such as crude oil price volatility and stringent industry regulations act as market restraints. Key players in the market, including Hewlett-Packard, Hitachi, Oracle, and IBM, drive innovation through new product launches and strategic partnerships to enhance operational efficiency and decision-making processes within the oil and gas industry.
The market dynamics are influenced by factors such as the rising demand for oil and gas, increasing competition, financial capital, and public scrutiny. Moreover, adopting analytics-powered programs enables companies to gather valuable insights about exploration activities, production processes, and market trends. The market is witnessing a shift towards integrating AI and ML technologies to navigate uncertainties and streamline operations. As oil and gas companies focus on improving production efficiency, reducing costs, and embracing digital technologies, the oil and gas analytics industry presents significant growth opportunities for enhancing decision-making processes and driving innovation within the sector.
Analyst Perspective
The global oil and gas analytics market is witnessing steady growth due to the transformation, as energy companies are increasingly prioritizing data-driven decision-making to enhance operational efficiency, reduce costs, and improve asset performance. In addition, the integration of artificial intelligence (AI), machine learning (ML), predictive analytics, and IoT is enabling operators to optimize their exploration, production, and logistics activities while mitigating operational risks. However, increased digitization efforts in the upstream, midstream, and downstream sectors are boosting the adoption of the market.
Offering Insights
Based on offering, the market is segregated into hardware, software, and services. The software segment dominated the market and accounted for the largest revenue share of over 58.5% in 2025. The demand for oil & gas analytics software is experiencing a significant upsurge driven by the escalating complexity and scale of operations within the oil and gas industry. Companies involved in hydrocarbon exploration and production are increasingly turning to advanced analytics tools to extract valuable insights from vast datasets, aiming to enhance decision-making, reduce operational costs, and optimize asset performance. The growing integration of artificial intelligence, cloud computing, and predictive analytics into software platforms is enabling operators to monitor assets in real time, identify operational inefficiencies, and improve production planning while minimizing downtime. For instance, in January 2025, Highwood Emissions Management introduced the Emissions Intelligence Platform (EIP), an advanced analytics software designed for oil and gas operators to streamline data-driven emissions management, compliance reporting, and operational decision-making, reflecting the increasing adoption of specialized analytics software across the industry.
Furthermore, the demand for oil & gas analytics hardware is driven by the increasing complexity and scale of operations within the oil and gas industry, necessitating advanced tools to extract valuable insights from vast datasets. Companies in the sector are increasingly adopting sophisticated hardware solutions to enhance operational efficiency, optimize production, and reduce costs. As companies strive to extract meaningful insights from the vast amounts of data generated by connected assets, the demand for cutting-edge hardware tools will continue to rise, enabling the oil and gas sector to operate more efficiently and competitively in the evolving market landscape.
Deployment Insights
Based on deployment, the market has been segmented into on-premises and cloud. The cloud segment dominated the market and held the largest revenue share of over 65.5% in 2025. The demand for cloud-based solutions in the market is experiencing a significant surge due to their ability to streamline operations, enhance scalability, and reduce upfront costs. Cloud deployment allows oil and gas companies to access analytics tools remotely via the internet, eliminating the need for extensive IT infrastructure investments. Cloud services provide improved network management, high application performance, enhanced bandwidth, and lower overhead costs, making them increasingly essential for oil and gas analytics. Furthermore, cloud-based platforms facilitate seamless integration with artificial intelligence, machine learning, and Industrial Internet of Things (IIoT) technologies, enabling real-time monitoring, predictive maintenance, and faster data-driven decision-making across upstream, midstream, and downstream operations. For instance, in September 2024, SLB expanded the capabilities of its Lumi cloud-based data and AI platform, enabling oil and gas operators to integrate and analyze large volumes of operational data in a scalable cloud environment. The development highlights the increasing adoption of cloud-deployed analytics solutions to improve data accessibility, operational efficiency, and enterprise-wide decision-making across the oil and gas value chain.
The rise in cloud-based solutions is reshaping the oil & gas analytics landscape, offering efficient and cost-effective ways to manage data, drive operational efficiency, and navigate the evolving market dynamics. Moreover, the demand for on-premises oil & gas analytics solutions remains significant, offering companies direct control over their data and analytics processes, ensuring high security and compliance standards. This deployment model involves installing analytics software and infrastructure within the organization's premises, providing a tailored approach to data management.
Application Insights
Based on application, the market has been segmented into upstream, midstream, and downstream. Upstream dominated the market and held the largest revenue market share of over 45.0% in 2025. The demand for upstream oil & gas analytics is witnessing substantial growth driven by the industry's focus on optimizing exploration and production activities. Upstream analytics, which encompasses reservoir analysis, drilling optimization, and production forecasting, is pivotal in enhancing operational efficiency and cost-effectiveness for oil and gas companies. For instance, in December 2025, Baker Hughes received a major award from Kuwait Oil Company to deploy its Leucipa automated field production solution and FusionPro intelligent production drive, enabling real-time production analytics, automated optimization, and enhanced recovery across Kuwait's oil fields, highlighting the growing adoption of AI-driven production analytics and automation technologies to optimize upstream oil and gas operations.
The downstream analytics segment is witnessing notable growth trends, emphasizing the importance of analytics in transforming downstream oil and gas operations. As the industry continues to evolve and embrace digital technologies, the demand for downstream oil & gas analytics solutions is expected to rise further, driving operational excellence and efficiency in the downstream sector. For instance, in May 2024, AspenTech expanded its industrial AI, predictive analytics, and digital optimization capabilities for refining operations, enabling downstream operators to leverage real-time data for process optimization, asset performance management, and energy-efficiency improvements. The development underscores the growing role of advanced analytics in enhancing operational excellence and profitability across downstream oil and gas facilities.
End Use Insights
Based on end use, the market has been segmented into small & medium enterprises and large enterprises. Large enterprises dominated the market and accounted for the largest revenue share of 72.5% in 2025. Their dominance is attributed to increasing investments in advanced analytics solutions to optimize operations, reduce costs, and enhance decision-making processes. The significant volume of data generated across these organizations necessitates sophisticated analytics tools to extract valuable insights and drive strategic initiatives. Furthermore, large enterprises increasingly integrate analytics platforms with Industrial Internet of Things (IIoT) devices, digital twins, and enterprise resource planning (ERP) systems to enable predictive maintenance, optimize asset performance, and improve operational resilience across geographically distributed assets. For instance, in March 2025, ADNOC awarded AIQ a USD 340 million contract to deploy the ENERGYai platform across its upstream operations. The enterprise-scale implementation leverages AI, machine learning, and real-time analytics to enhance seismic interpretation, geological modeling, and operational monitoring, demonstrating the significant investments made by large oil and gas companies in advanced analytics solutions to improve efficiency and decision-making.
By embracing analytics, SMEs in the oil & gas sector can streamline operations, enhance decision-making processes, and stay competitive in a rapidly evolving industry. The growth of the oil & gas analytics market presents SMEs with opportunities to leverage advanced technologies and data-driven insights to drive operational excellence and achieve sustainable growth in the dynamic oil and gas landscape.
Regional Insights
The oil and gas analytics industry in North America dominated the market, accounting for a revenue share of 40.5% in 2025. With the evolution of the North American shale sector and the changing dynamics of global energy markets, the demand for analytics tools has surged. Investors seek comprehensive data and insights to understand competition, activity, and the sector's impact on oil and gas supply/demand balances. The market offers a complete workflow solution for investors to assess market conditions, identify opportunities for repositioning, and gain valuable insights for investment strategies. For instance, in June 2026, Chevron signed a 20-year agreement with Microsoft to develop a 2.67 GW energy and data infrastructure project in West Texas to support large-scale cloud and AI operations. The initiative underscores the growing integration of energy production with data-intensive technologies in North America, highlighting the increasing convergence of energy production, cloud computing, and artificial intelligence, which is accelerating the adoption of advanced analytics, digital infrastructure, and data management technologies across North America's oil and gas industry.
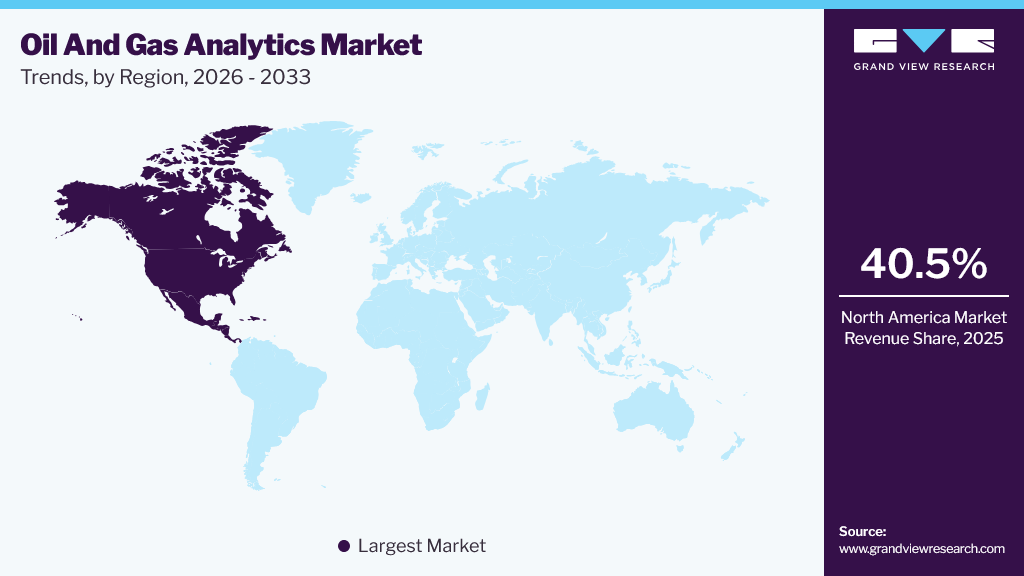 To learn more about this report, Download Free Sample Report
U.S. Oil And Gas Analytics Market Trends
The oil & gas analytics industry in the U.S. accounted for the largest share in North America in 2025. The U.S. is a key market player, with a robust demand driven by the country's significant oil and gas production activities. The adoption of advanced analytics solutions in the U.S. oil and gas sector is propelled by the industry's focus on operational efficiency, cost optimization, and regulatory compliance.
Asia Pacific Oil And Gas Analytics Market Trends
The oil & gas analytics industry in the Asia Pacific is driven by several factors, including the growing demand for data analysis required during the exploration of oil sources, increasing investments in the oil and gas industry, and the rapid adoption of cloud services in the region. The region is also home to many software companies that provide analytics platforms for oil and gas companies, contributing to the market's growth. In addition, the increasing number of oil and gas projects in the region, particularly in countries such as China and India, is also driving the demand for oil and gas analytics. For instance, in December 2023, China National Offshore Oil Corporation (CNOOC) expanded the application of intelligent oilfield technologies, including AI-driven analytics and digital reservoir management systems, to enhance operational efficiency and support carbon-reduction targets. The initiative highlights the increasing demand for advanced analytics solutions in Asia Pacific, particularly in China, where oil and gas companies are leveraging data-driven technologies to address energy security, optimize production, and facilitate the transition toward carbon neutrality.
The China oil and gas analytics industry accounted for the largest share in Asia Pacific. The oil and gas analytics demand in China is on the rise, driven by its significant presence in the global energy market and its focus on operational efficiency and technological advancements. With the increasing demand for oil and gas resources and growing competition and financial influences, the need for advanced analytics solutions is becoming more pronounced in the Chinese market.
The oil and gas analytics industry in South Korea is also expected to grow at a significant CAGR. The oil and gas analytics demand in South Korea is experiencing growth and transformation, driven by increasing energy consumption, government initiatives to enhance energy security, and technological advancements in exploration and production techniques.
Europe Oil And Gas Analytics Market Trends
The Europe oil & gas analytics industry growth is driven by several factors, including the increasing energy demand, the need for improved operational efficiency, and the growing adoption of digital technologies. The market is also influenced by the rising focus on environmental sustainability and the need for companies to reduce their carbon footprint.
The Russia oil and gas analytics industry accounted for the largest share in Europe. The country's vast refining capacity and substantial oil and gas reserves position it as a key supplier in the global market. Russia's role in global energy markets is underscored by its status as one of the top three crude producers worldwide, alongside Saudi Arabia and the U.S.
The oil and gas analytics industry in Norway is also expected to grow at a significant CAGR. The demand for oil and gas analytics in Norway is driven by a dynamic energy market landscape characterized by a mix of traditional oil and gas production and a growing emphasis on alternative energy sources.
Central & South America Oil And Gas Analytics Market Trends
The oil & gas analytics industry in Central and South America is primarily driven by the increasing number of offshore operations in the region, the rising demand for unconventional hydrocarbons like shale gas, and the need for efficient exploration and production activities.
The Brazil oil and gas analytics industry accounted for the largest share in 2025 in Central & South America. Brazil's oil and gas sector is characterized by a competitive landscape, focusing on operational efficiency, exploration activities, and production optimization. The market dynamics are influenced by market needs, competition, regulatory environment, and technological advancements.
Middle East & Africa Oil And Gas Analytics Market Trends
The oil & gas analytics industry in the Middle East & Africa is primarily driven by the region's rich oil and gas deposits, leading to significant opportunities for the industry. The Middle East, in particular, has been home to the majority of the world's refining capacity expansion, with a focus on refining projects.
The Saudi Arabia oil and gas analytics industry accounted for the largest share in 2025 in the Middle East & Africa. The market dynamics are influenced by factors such as OPEC+ production agreements, global oil price fluctuations, and the country's strategic position in the global energy market.
Key Oil And Gas Analytics Market Company Insights
Key companies are adopting several organic and inorganic growth strategies, such as new product development, mergers & acquisitions, and joint ventures, to maintain and expand their market share. Key companies in the market include Essar, Exxon Mobil Corporation, ConocoPhillips, Weatherford, EOG Resources, Inc., and others.
Key Oil And Gas Analytics Companies
The following key companies have been profiled for this study on the oil and gas analytics market .
-
Flywheel Energy
-
Oilmax.in
-
Rockcliff Energy
-
Covey Park Energy
-
Essar
-
Exxon Mobil Corporation
-
ConocoPhillips
-
Weatherford
-
EOG Resources, Inc.
-
Naftogaz
-
DEVON ENERGY CORPORATION
-
National Energy Services Reunited Corp. (NESR)
-
Hunt Oil Company
-
Murphy Oil Corporation
Recent Developments
-
In September 2024, Halliburton introduced the next generation of its LOGIX automation and remote operations platform, combining real-time downhole data, analytics, and autonomous drilling capabilities to enhance drilling performance and well delivery efficiency, reinforcing the increasing role of digital analytics and automation in the oil and gas industry.
-
In May 2024, Exxon Mobil Corporation continued expanding its upstream footprint through the integration of Pioneer Natural Resources following its acquisition, while also deploying advanced digital technologies to optimize production, highlighting the industry's focus on mergers and acquisitions alongside innovation-led growth strategies to strengthen competitive positioning.
-
In January 2024, SLB and Nabors collaborated on automated drilling solutions for oil and gas operators. The collaboration will focus on drilling automation applications and rig operating systems to deliver efficiency.
Oil And Gas Analytics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.0 billion
Estimated market size in 2026
USD 14.6 billion
Projected market size by 2033
USD 56.6 billion
Growth rate
CAGR of 21.4 % from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Offering, deployment, application, end use, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand, South Korea; Brazil; Argentina, South Africa, UAE
Key companies profiled
Flywheel Energy; Oilmax.in; Rockcliff Energy; Covey Park Energy; Essar; Exxon Mobil Corporation; ConocoPhillips; Weatherford; EOG Resources, Inc.; Naftogaz; DEVON ENERGY CORPORATION; National Energy Services Reunited Corp. (NESR); Hunt Oil Company; Murphy Oil Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Oil And Gas Analytics Market Report Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global oil & gas analytics market report based on offering, deployment, application, end use, and region:
-
Offering Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware
-
Software
-
Service
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
On-premises
-
Cloud
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Upstream
-
Midstream
-
Downstream
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small & medium Enterprises
-
Large Enterprises
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Russia
-
Norway
-
UK
-
Italy
-
Turkey
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Indonesia
-
-
Central and South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
Iraq
-
-
Frequently Asked Questions About This Report
Key players in the market include Flywheel Energy; Oilmax.in; Rockcliff Energy; Covey Park Energy; Essar; Exxon Mobil Corporation; ConocoPhillips; Weatherford; EOG Resources, Inc.; Naftogaz; DEVON ENERGY CORPORATION; National Energy Services Reunited Corp. (NESR); Hunt Oil Company; Murphy Oil Corporation, and others
The software segment accounted for the largest revenue share of over 58.5% in 2025.
The global oil and gas analytics market size was valued at USD 12.0 billion in 2025 and is estimated at USD 14.6 billion for 2026.
The global oil and gas analytics market is expected to grow at a CAGR of 21.4% from 2026 to 2033, reaching USD 56.6 billion.
North America dominated with over 40.5% revenue share in 2025.
About the Author(s)
Conventional Energy Research Team
Energy & Power · Conventional EnergyThis report was authored by the conventional energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the conventional energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


