
- Home
- »
- Medical Devices
- »
-
Oral Appliances Market Size, Growth Report, 2026-2033GVR Report cover

Oral Appliances Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Tongue Retaining Devices, Hybrid Devices), By Indication, By End-use, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.6BCAGR, 2026–2033
5.7%Oral Appliances Market Summary
The global oral appliances market was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026 to USD 1.6 billion in 2033, at a CAGR of 5.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 2025. This growth is attributed to the increasing awareness of sleep disorders, rising prevalence of obstructive sleep apnea, and growing demand for non-invasive treatment options.
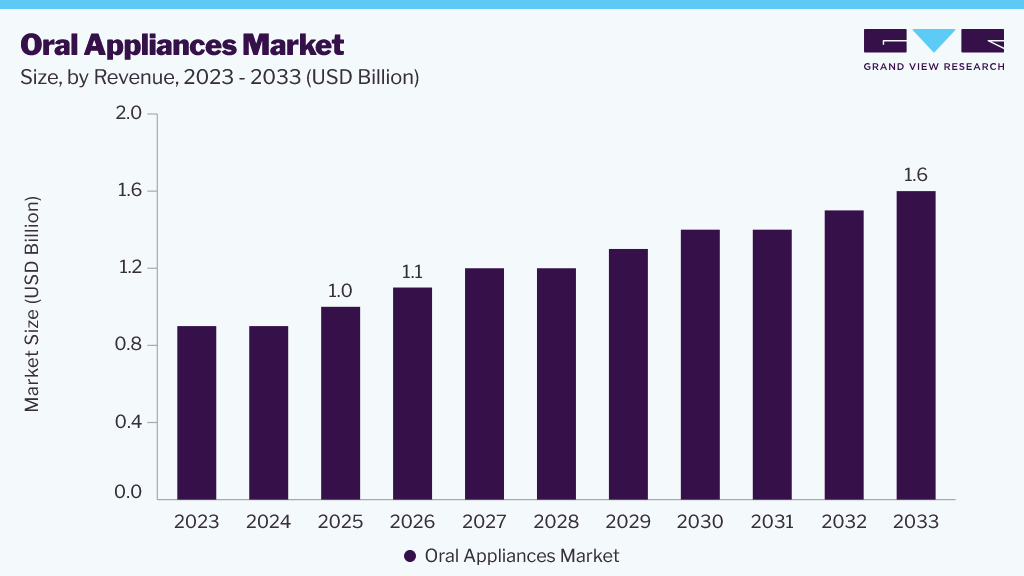 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The mandibular advancement devices (MADs) segment platform segment held the largest market share of over 69.0% in 2025.
- By indication: The mild-to-moderate OSA segment dominated the market with the largest revenue share in 2025.
- By end use: The hospitals & clinics segment dominated the market with the largest revenue share in 2025.
- By distribution channel: The direct-to-consumer (DTC) segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2026: USD 1.1 Billion
- Projected market size by 2033: USD 1.6 Billion
- CAGR (2026-2033): 5.7%
Prism AI by Grand View Research Free to tryAsk a question about the oral appliances marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The market is also bolstered by advancements in technology, improved product designs offering greater comfort, and increased focus on oral health. In addition, favorable reimbursement policies and the presence of key market players contribute to the expansion of this market.
The increasing prevalence of sleep disorders, such as obstructive sleep apnea (OSA), is significantly driving the growth of the market. According to November 2025 report published by National Library of medicine, in accordance with studies conducted in 2024-2025, OSA (Obstructive Sleep Arena) is prevalent in about 80.6-83.7 million adults living in the USA, accounting for about 32% of the adult population, and its global prevalence is projected to be almost 936 million adults, indicating a considerable rise in the burden of the disease from previous figures.
The high prevalence of sleep apnea in an elderly population often goes undiagnosed due to factors like lack of awareness and non-specific symptoms. With the global population aged 60 and above projected to reach 2 billion by 2050 and the elderly population expected to double from 12% to 22%, the incidence of sleep disorders, particularly OSA, is on the rise. OSA affects 13% to 32% of individuals aged 65 and above. The growing geriatric population's vulnerability to sleep apnea is expected to drive the adoption of oral appliances.
Furthermore, as awareness of the health risks associated with untreated sleep disorders rises, more patients are seeking effective treatment options. Oral appliances, known for their convenience and effectiveness in managing sleep apnea, are becoming a preferred choice for both patients and healthcare providers. This surge in demand is further fueled by advancements in oral appliance technology, making these devices more comfortable and accessible. Consequently, the market is experiencing robust growth, propelled by the urgent need to address the widespread issue of sleep disorders.
In addition, the focus on urgent care and the implementation of infection control measures redirected resources and attention away from elective treatments. On the other hand, the pandemic also accelerated the adoption of telehealth and remote consultations, facilitating increased access to diagnosis and management of conditions like obstructive sleep apnea. As the healthcare system adapts to post-pandemic norms, there is a growing emphasis on integrating digital solutions and enhancing patient care through innovative oral appliance technologies.
The transition from PAP devices to oral appliances is driven by a combination of enhanced comfort, ease of use, positive clinical outcomes, and patient satisfaction. Feedback from lapsed PAP users highlights the effectiveness of oral appliances in improving sleep quality and overall user experience. This shift indicates a strong user preference for oral appliances, contributing to their increasing market adoption. These insights provide a solid foundation for understanding the adoption trends and patient preferences in the market.
Analyst Perspective
There are various factors driving growth in the oral appliances market, including the rising prevalence of obstructive sleep apnea (OSA), the growing geriatric population, and increasing awareness regarding alternative treatment options for sleep-related breathing disorders. The shift of patients from continuous positive airway pressure (CPAP) therapy to oral appliances due to their greater comfort, portability, and higher patient compliance is another key factor supporting market growth. Furthermore, advancements in digital dentistry, such as CAD/CAM technology and 3D printing, are enabling the development of customized oral appliances with improved fit, effectiveness, and patient comfort. Growing collaborations between sleep physicians and dental professionals, along with expanding reimbursement support in developed countries, are also contributing to increased adoption.
Product Insights
The Mandibular Advancement Devices (MADs) segment dominated the market with the largest revenue share of over 69.0% in 2025. This growth is primarily driven by increasing regulatory approvals and clearances, which enhance the credibility and market reach of these devices. For instance, in June 2025, ProSomnus Sleep Technologies Sleep Technologies launched EVO Guided, a precision oral device for obstructive sleep apnea that has received FDA clearance. The personalized mandibular advancement appliance is designed to enhance upper airway expansion, boosting treatment effectiveness and promoting innovation in the oral devices industry.
Furthermore, rising FDA regulations are also fueling market growth. For instance, in January 2024, SnoreLessNow announced that the FDA granted 510(k) clearance for its OTC mandibular advancement device, known as SomniFit-S in Europe. The Anti-Snore Mouth Guard+ reduces snoring by gently advancing the jaw, thereby eliminating airway obstruction and enhancing airflow without the need for masks, hoses, or electronics.
The Tongue-Retaining Devices (TRDs) segment is expected to grow significantly over the forecast period. Increasing awareness of sleep-related disorders, particularly obstructive sleep apnea (OSA), has led to greater demand for noninvasive treatment options. TRDs are favored for their effectiveness in preventing airway obstruction during sleep by maintaining the tongue's position. Technological advancements in these devices improved the comfort and efficacy of TRDs, enhancing patient compliance.
Indication Insights
The mild-to-moderate OSA segment dominated the market with the largest revenue share in 2025. This growth can be attributed to the increasing awareness of the condition, advancements in diagnostic technologies, and the rising prevalence of obesity, a major risk factor for OSA. In addition, the demand for non-invasive treatment options and growing recognition of the long-term health impacts of untreated OSA are driving more individuals to seek diagnosis and treatment. This expanding patient base, coupled with innovations in therapy devices, is propelling the segment growth.
The severe OSA segment is expected to grow significantly during the forecast period. Oral appliances serve as a viable alternative for patients who cannot tolerate CPAP therapy, offering a more comfortable and user-friendly option. With approximately 39 million adults in the U.S. and an estimated 936 million globally affected by mild to severe OSA, rising awareness of the health risks associated with severe OSA and advancements in appliance technology that improve efficacy and comfort are key factors contributing to the segment's dominance.
Distribution Channel Insights
The Direct-to-Consumer (DTC) segment dominated the market with the largest revenue share in 2025. The increasing consumer preference for convenient and accessible healthcare solutions has led to a surge in demand for at-home treatments. The rise of e-commerce platforms has made it easier for consumers to purchase oral appliances online, offering a seamless shopping experience with a wide range of products available at their fingertips. In addition, the growing awareness of the importance of sleep health and the prevalence of conditions such as obstructive sleep apnea has fueled consumer interest in non-invasive treatment options like oral appliances.
The availability of detailed product information, customer reviews, and virtual consultation services online has also empowered consumers to make informed purchasing decisions. Offline channels, such as retail stores and specialty clinics, continue to play a crucial role by providing hands-on product demonstrations and personalized consultations, further enhancing consumer confidence. Together, these factors contribute to the robust growth of the DTC segment in the market.
The hospitals & clinics distribution channel segment held a substantial market share in 2025. The growth is due to their central role in diagnosing and treating sleep disorders. These facilities provide comprehensive care, including assessing and managing OSA, making them primary venues for prescribing and fitting oral appliances. The extensive reach and integrated care provided by hospitals and clinics, coupled with their access to advanced diagnostic tools and specialists, drive the segment's prominence in the market.
End Use Insights
The hospitals & clinics segment dominated the market with the largest revenue share in 2025, owing to their central role in diagnosing and managing sleep disorders such as OSA. These healthcare facilities are equipped with advanced diagnostic tools and have the expertise to accurately prescribe and fit oral appliances. Hospitals and clinics often have established referral networks and patient bases that drive demand for oral appliances. Their comprehensive care, including follow-up and adjustments, ensures higher adoption rates and contributes to the segment's market leadership.
The homecare segment is expected to grow significantly during the forecast period. With a growing preference for convenient at-home treatment options that offer flexibility and comfort, more patients are seeking non-invasive solutions for conditions like obstructive sleep apnea. Oral appliances are emerging as a practical alternative to in-clinic therapies, prompting market players to expand their homecare offerings.
Regional Insights
North America oral appliances market held the dominant global revenue share in 2025. This large share is attributed to the increasing prevalence of sleep apnea and the growing need to diagnose these disorders. Furthermore, the increasing number of FDA approvals for sleep apnea conditions would likely drive market growth in the region. For instance, in April 2026 ProSomnus Sleep Technologies Sleep Technologies won FDA Class II clearance for its RPMO₂ OSA Device, which is an advanced mandibular advancement oral device that integrates pulse and oxygen saturation measurement. It will be used to help clinicians provide sleep apnea therapy to patients, increasing use in US sleep clinics and dental sleep medicine programs.
U.S. Oral Appliances Market Trends
The oral appliances market in the U.S. accounted for the largest market share in 2025. One of the key factors driving the market is growing innovation. In June 2025, ProSomnus Sleep Technologies developed EVO Guided that is a totally customized oral appliance approved by the FDA for patients with obstructive sleep apnea. The oral appliance is expected to make the life of the patient more comfortable while undergoing treatment.
Europe Oral Appliances Market Trends
The oral appliances market in Europe is expected to grow significantly during the forecast period, driven by increasing awareness of sleep disorders such as OSA and growing demand for non-invasive treatment options. Moreover, advances in technology, such as custom 3D printing and smart devices, enhance oral appliances' effectiveness and comfort. Supportive regulatory frameworks and an aging population seeking alternatives to CPAP therapy contribute to market growth.
The oral appliances market in the UK had a substantial share in 2025, owing to the increasing awareness of sleep disorders such as obstructive sleep apnea, the rising prevalence of snoring, and the growing preference for non-invasive treatment options. In addition, advancements in dental technology and increased focus on patient comfort are further driving market expansion.
The Germany oral appliances market held a substantial market share in 2025. The market growth in Germany is driven by increasing awareness of sleep disorders such as obstructive sleep apnea (OSA) and the growing emphasis on preventive dental care. Technological advances, including developing customizable and comfortable oral devices, also contribute to market growth. In addition, supportive healthcare policies and reimbursement options enhance the accessibility and adoption of oral appliances.
Asia Pacific Oral Appliances Market Trends
The oral appliances market in Asia Pacific is expected to grow significantly during the forecast period due to various factors. For instance, in April 2024, IDEM Singapore 2024, a leading dental event in the Asia-Pacific region, showcased the latest advancements in dentistry, drawing industry leaders, innovators, and practitioners. Smartee's involvement highlighted mandibular repositioning technology, showcasing its commitment to advancing orthodontic services through advanced technologies and innovative clear aligner solutions, driving growth in the oral appliance market in the region.
The Australia oral appliances market held a significant market share in the Asia Pacific region in 2025. The growth is attributed to market players undertaking initiatives to obtain regulatory approvals for innovative oral appliance therapies. In addition, the increasing prevalence of obstructive sleep apnea (OSA), growing awareness regarding the health risks associated with untreated sleep disorders, and the rising preference for non-invasive treatment options are supporting market expansion. The presence of well-established dental care infrastructure, increasing adoption of dental sleep medicine, and collaborations between dental professionals and sleep physicians are further contributing to the demand for oral appliances across the country.
The oral appliances market in India is expected to grow significantly during the forecast period. The growth is due to the increasing awareness of sleep disorders and their treatment, rising healthcare spending, and advancements in dental technology. The growing prevalence of OSA and related conditions also contributes to higher demand for effective oral appliance solutions. In addition, expanding access to dental care services and improved patient education drive the market growth.
Key Oral Appliances Company Insights
The oral appliances industry is expanding with the presence of many companies. Intense competition among market players can be attributed to the growing demand for oral appliances, such as MADs and Tongue Retaining Devices (TRDs).
Key Oral Appliances Companies
The following key companies have been profiled for this study on the oral appliances market.
-
ResMed Inc.
-
ProSomnus Sleep Technologies
-
Vivos Inc
-
SomnoMed.com
-
Glidewell
-
Airway Management (TAP)
-
Mitsui Chemicals, Inc. (Whole You)
-
Achaemenid, LLC
-
Apnea Sciences
-
Signifier Medical Technologies
Recent Developments
-
In May 2024, Glidewell launched a new Digital Silent Nite 3D Sleep Appliance. It is a mandibular advancement device developed from Glidewell’s Silent Nite Sleep Appliance. Made from durable light-cured resin, it effectively treats mild to moderate obstructive sleep apnea (OSA) & snoring.
-
In February 2024, Sleep Doctor partnered with Airway Management to offer the myTAP Oral Appliance. This device, holding FDA clearance for snoring and obstructive sleep apnea (OSA), provides a cost-effective and convenient solution for same-day treatment.
-
In January 2024, ProSomnus Sleep Technologies, Inc. announced adopting UnitedHealth care’s updated medical policy (#2024T0525NN) for Obstructive and Central Sleep Apnea, effective March 1, 2024. The revised policy mandates oral appliance therapy (OAT), including ProSomnus Sleep Technologies's Precision OAT devices, as a prerequisite for implantable hypoglossal nerve stimulation in adult patients with moderate to severe obstructive sleep apnea (OSA). The policy specifies a "failure of adequate trial of Oral Appliance therapy" as the new requirement.
Oral Appliances Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 billion
Estimated market size in 2026
USD 1.1 billion
Projected market size by 2033
USD 1.6 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, indication, end use, distribution channel, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; UK; Germany; Spain; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
ResMed Inc.; ProSomnus Sleep Technologies; Vivos Inc; SomnoMed.com; Glidewell; Airway Management (TAP); Mitsui Chemicals, Inc. (Whole You); Achaemenid, LLC; Apnea Sciences; Signifier Medical Technologies
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Oral Appliances Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global oral appliances market report based on product, indication, end use, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Mandibular Advancement Devices (MADs)
-
Tongue Retaining Devices (TRDs)
-
Hybrid Devices
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Mild to Moderate Obstructive Sleep Apnea (OSA)
-
Severe Obstructive Sleep Apnea (OSA)
-
Snoring
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Homecare
-
Hospitals & Clinics
-
Others (Sleep Laboratories, etc.)
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Direct-to-Consumer (Online and Offline)
-
Hospitals & Clinics
-
Others (Dental Clinics, etc.)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global oral appliances market size was estimated at USD 908.7 million in 2023 and is expected to reach USD 970.7 million in 2024.
The global oral appliances market is expected to grow at a compound annual growth rate of 5.7% from 2024 to 2030 to reach USD 1.4 billion by 2030.
North America held the dominant revenue share in 2023. This growth is attributed to the increasing prevalence of sleep apnea and the growing need to diagnose these disorders. Furthermore, the increasing number of FDA approvals for sleep apnea conditions would likely drive market growth in the region.
Some key players operating in the oral appliances market include ResMed Inc.; ProSomnus; Vivos; SomnoMed.com; Glidewell; Airway Management (TAP); Mitsui Chemicals, Inc. (Whole You); Achaemenid, LLC; Apnea Sciences; Signifier Medical Technologies
Key factors that are driving the market growth include increasing awareness of sleep disorders, rising prevalence of obstructive sleep apnea, and growing demand for non-invasive treatment options. The market is also bolstered by advancements in technology, improved product designs offering greater comfort, and increased focus on oral health. In addition, favorable reimbursement policies and the presence of key market players contribute to the expansion of this market.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


