
- Home
- »
- HVAC & Construction
- »
-
Outdoor Power Equipment Market Size Report, 2026-2033GVR Report cover

Outdoor Power Equipment Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Power Source (Gasoline, Battery), By End-use (Residential, Commercial/Government), By Type, By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$56.3BMarket Estimate, 2026
$59.7BMarket Forecast, 2033
$93.4BCAGR, 2026–2033
6.6%Outdoor Power Equipment Market Summary
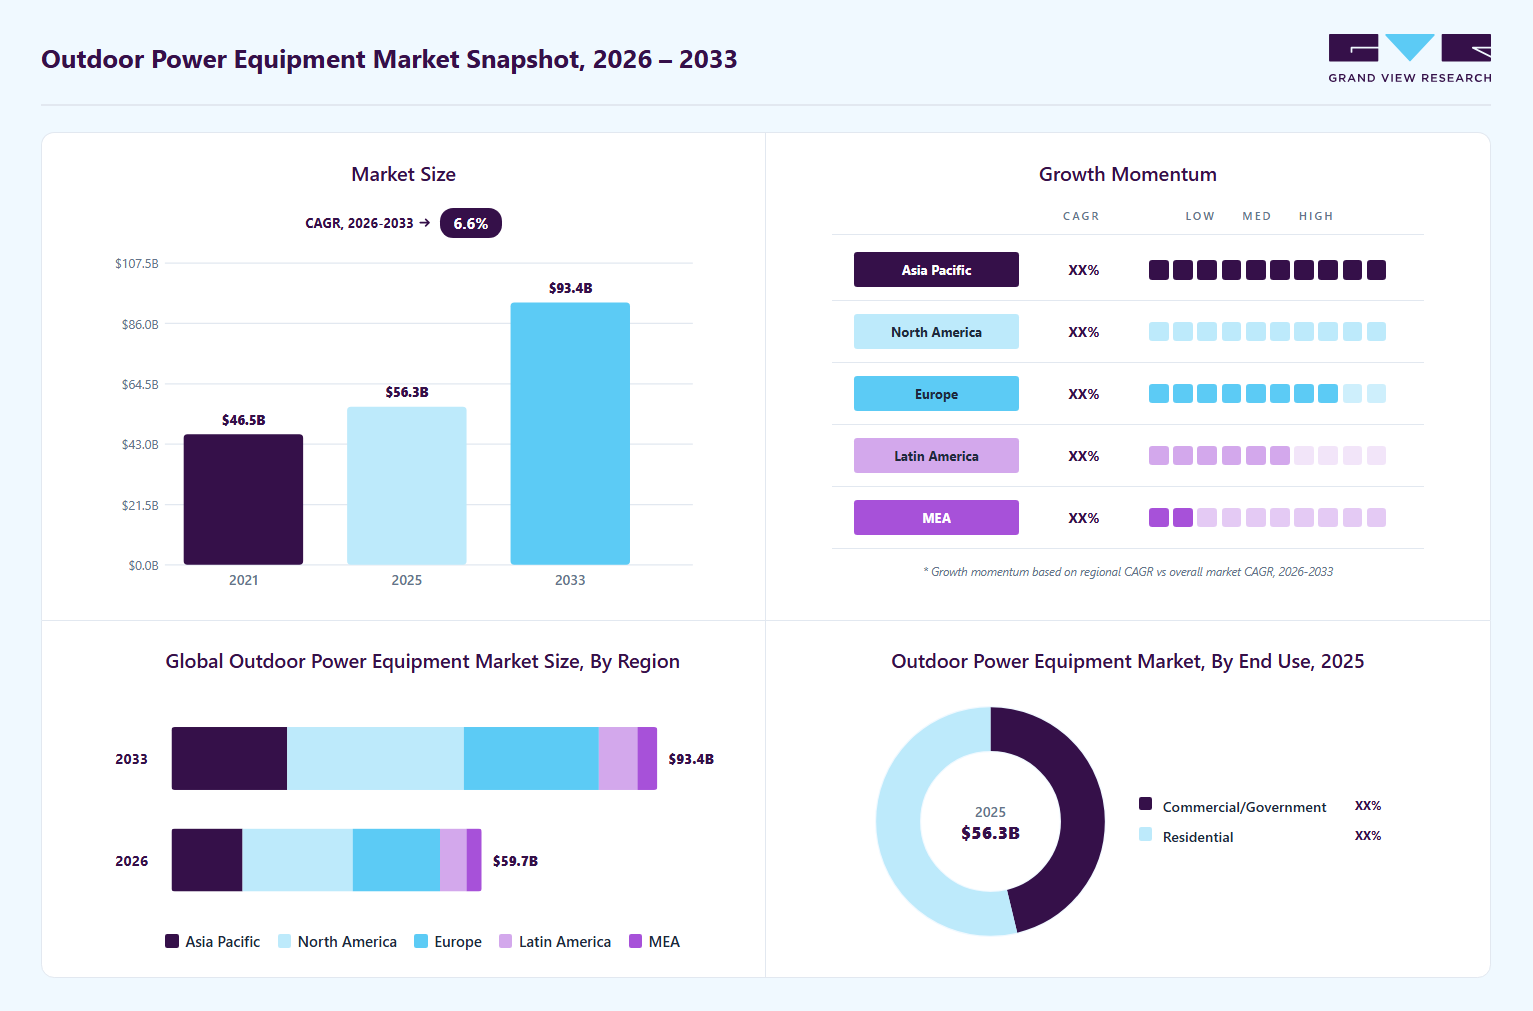
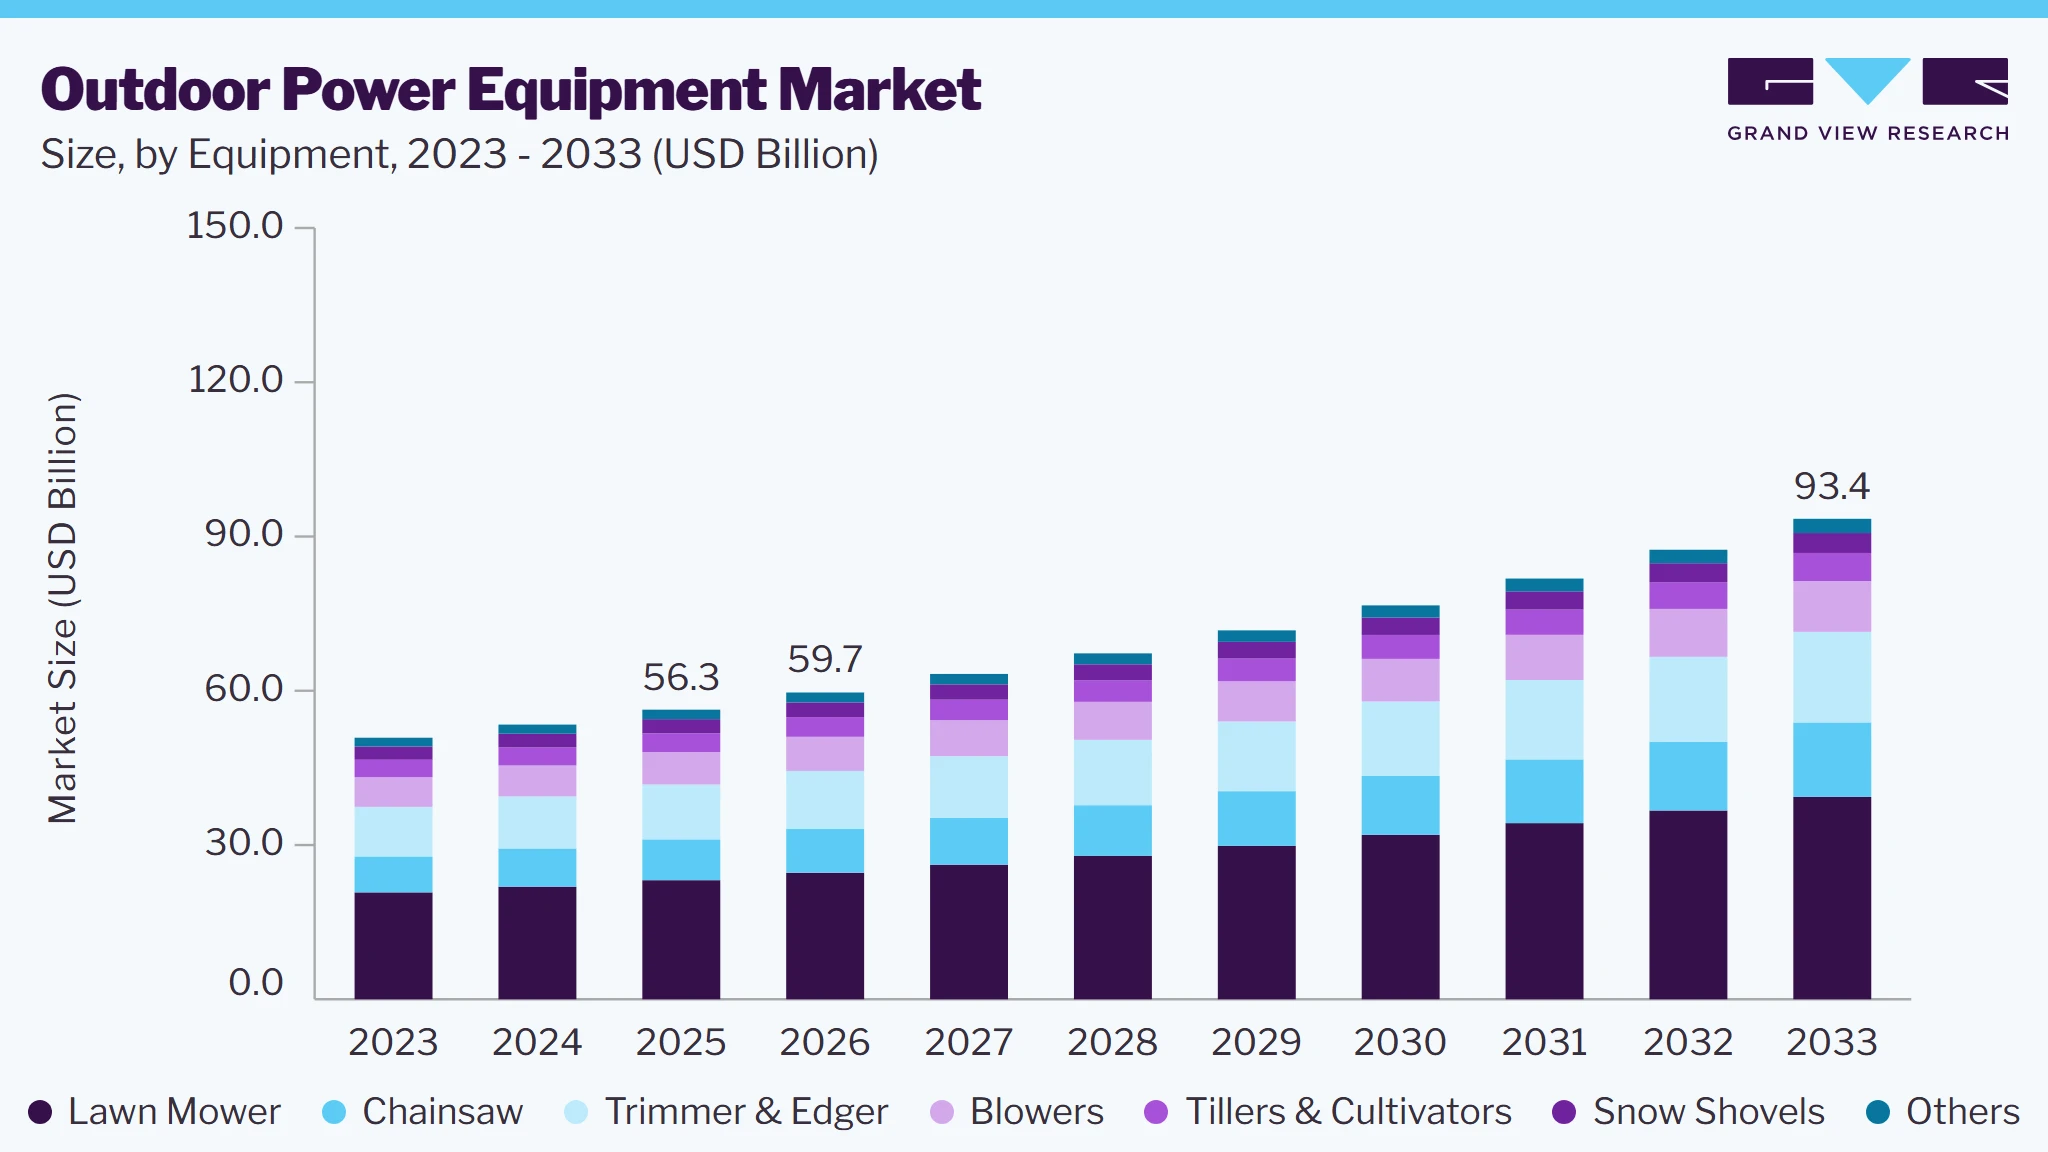
The global outdoor power equipment market size was valued at USD 56.3 billion in 2025 and is projected to grow from USD 59.7 billion in 2026 to USD 93.4 billion by 2033, at a CAGR of 6.6% from 2026 to 2033. North America dominated the outdoor power equipment market with the largest revenue share of 35.4% in 2025. Furthermore, several companies’ technological advancements in outdoor power equipment are also expected to drive market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By power source: Gasoline segment led the market with the largest revenue share of 56.1% in 2025.
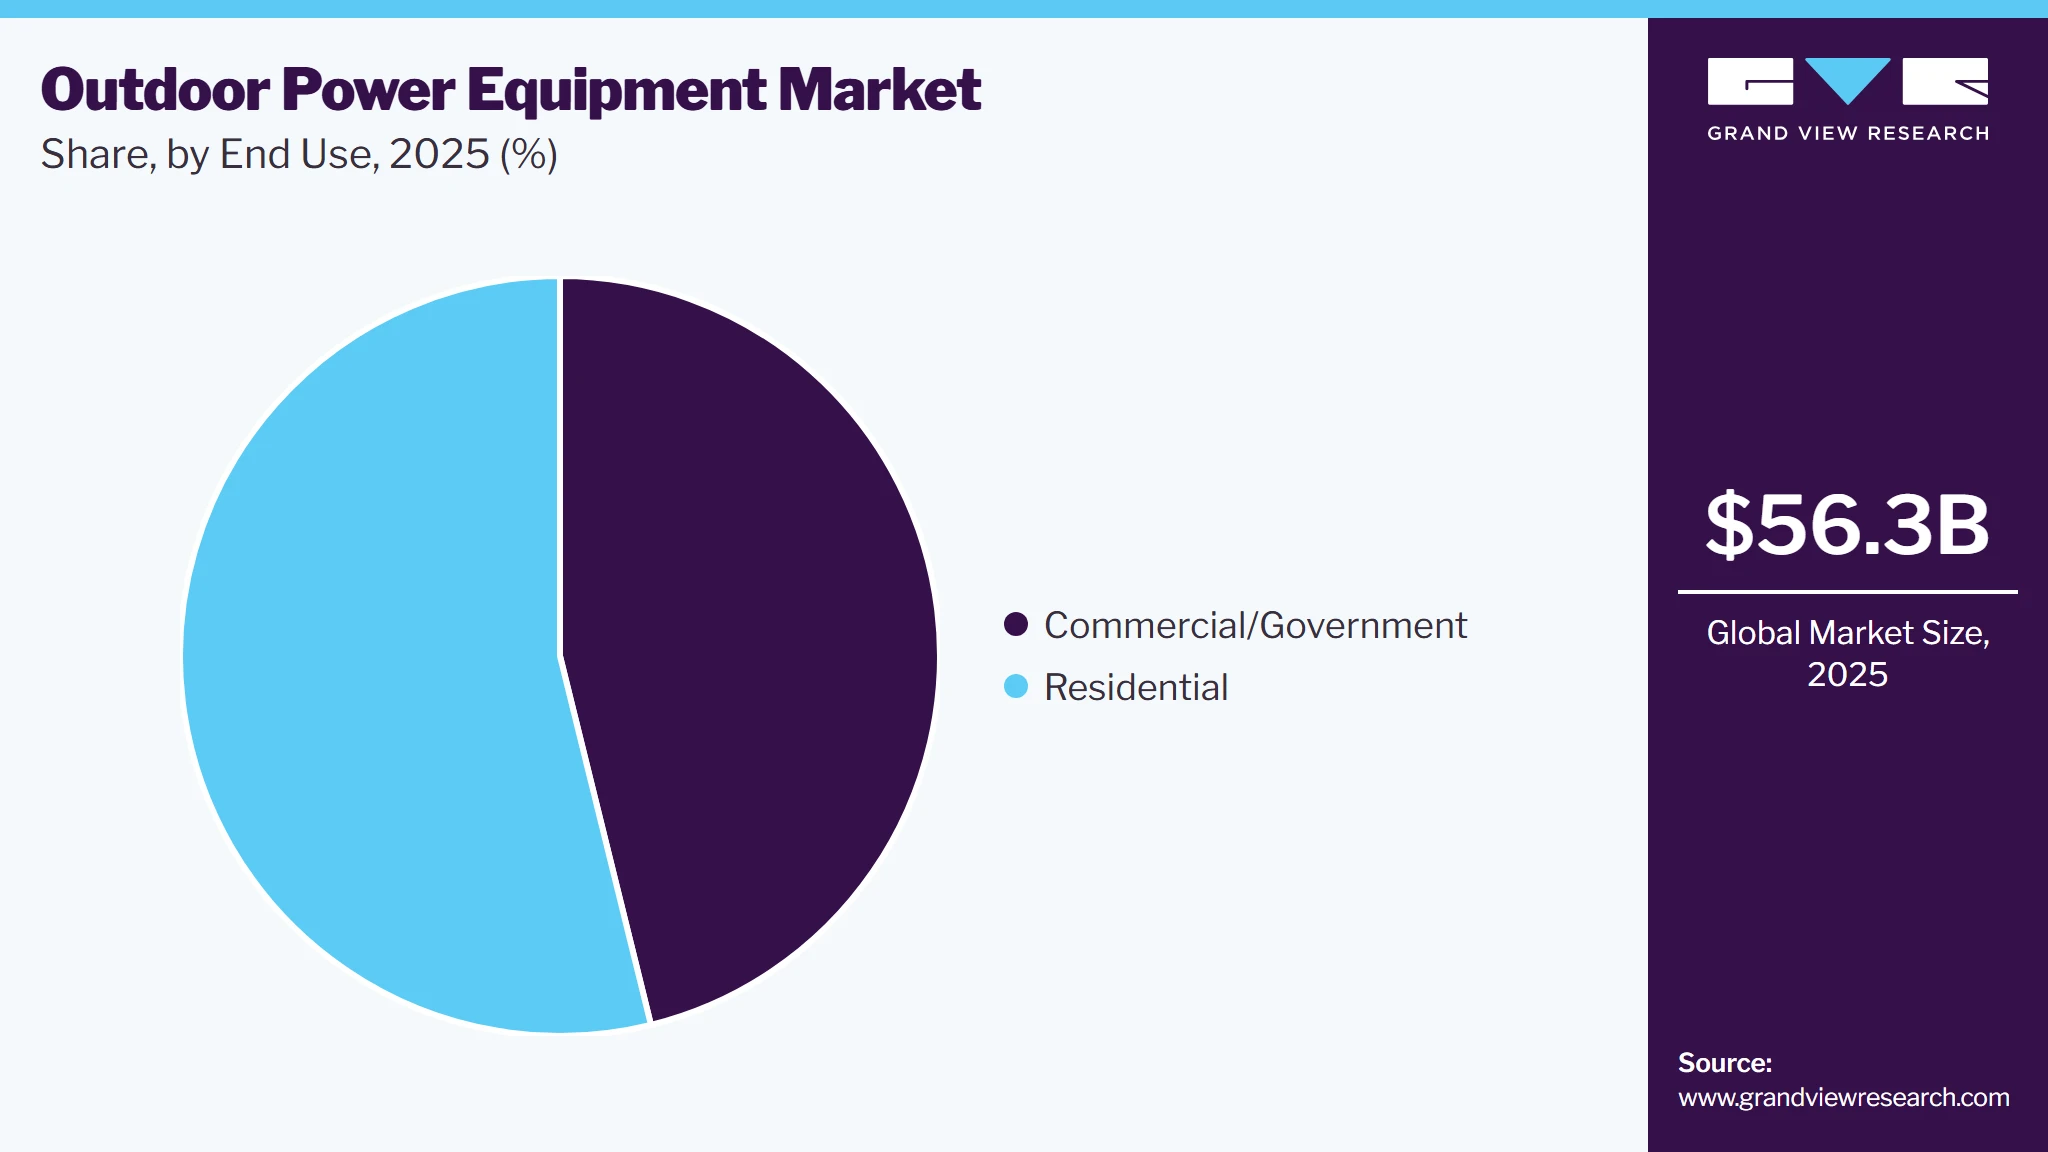
- By end use: Residential segment led the market with the largest revenue share of 53.8% in 2025.
- By type: Lawn mower segment led the market with the largest revenue share of 41.1% in 2025.
Regional Highlights
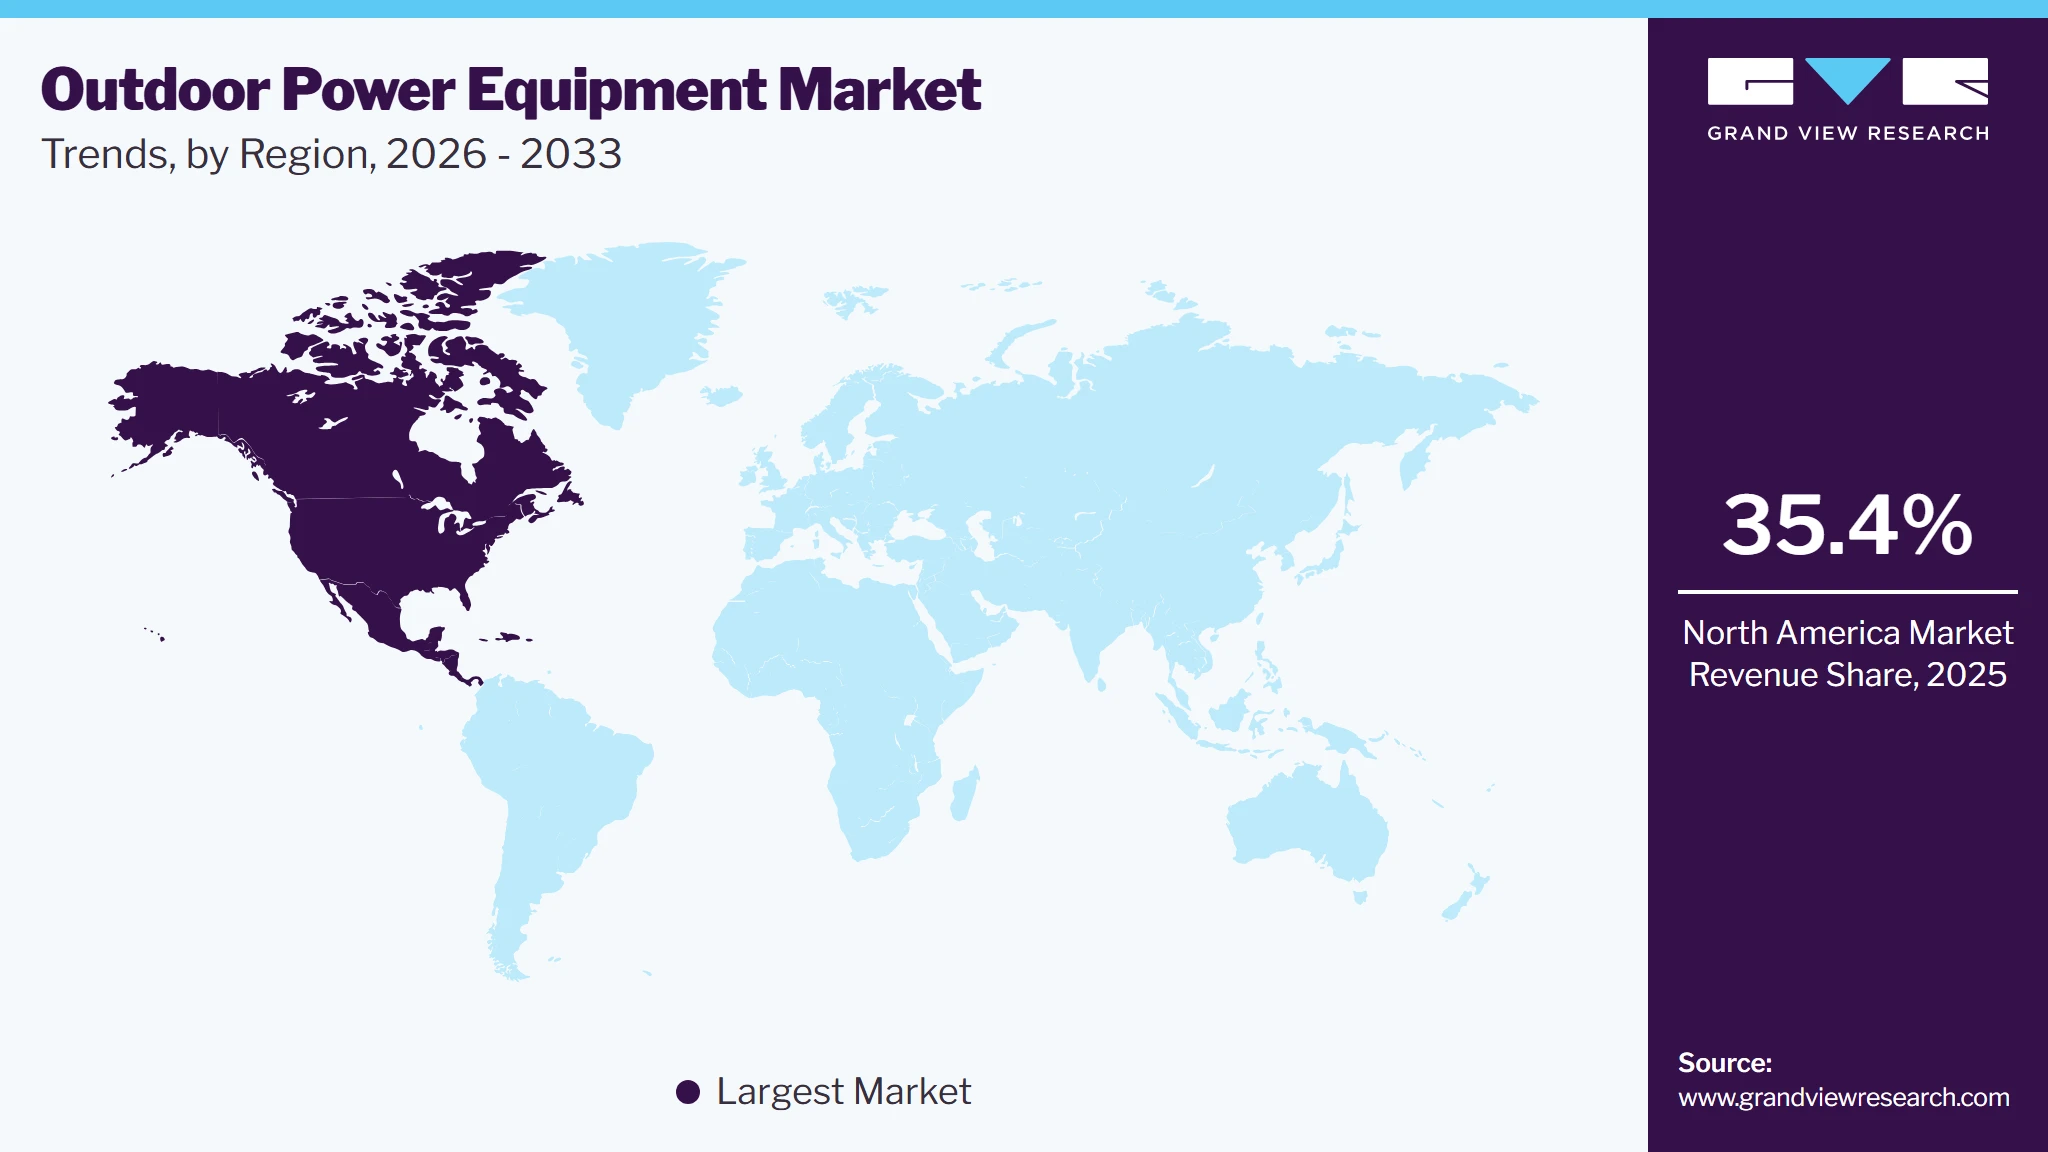
- Largest regional market: North America (35.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 56.3 Billion
- Estimated market size in 2026: USD 59.7 Billion
- Projected market size by 2033: USD 93.4 Billion
- CAGR (2026-2033): 6.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
For instance, in February 2020, Robert Bosch GmbH launched Indego M 700 and Indego M+ 700, two autonomous lawn mowers. These two connected lawn mowers feature 18 V lithium batteries with brushless DC motors that can cut grass from medium-sized gardens up to 700 square meters on a single charge.The rising urbanization, disposable income, and infrastructure activities coupled with rising demand for landscaping services are expected to augment the growth of the outdoor power equipment industry. Furthermore, growing awareness of environmental issues leads to increasing adoption of outdoor power equipment using lithium-ion batteries as they are environment friendly and maximize energy output. Several companies are focused on innovation in lithium-ion batteries. For instance, in 2021, Techtronic's Industries started using red lithium-ion batteries for its cordless power tools, as they work faster and deliver more than expected from the battery's life.
 To learn more about this report, Download Free Sample Report
The gardening trend has increased rapidly, mainly among younger generations. Most young people are inclined toward growing vegetables, fruits, and herbs. As young people are more likely to live in smaller yard lots, the type of equipment, plant, and tools they require should work in tighter spaces. The gardening and lawn industry is changing to adapt to various consumer requirements by launching equipment that is lighter in weight and makes work comfortable. Furthermore, the growing popularity of home improvement projects bodes well for the growth of the outdoor power equipment and garden tools market over the forecast period. Companies such as The Toro Company, Husqvarna, ANDREAS STIHL AG & Co. KG, and others gained profits from the stay-at-home trend due to the pandemic, which has extended the gardening season.
The pandemic in 2020 did cast a gloomy outlook on almost all industries worldwide. The outbreak of COVID-19 impacted market growth during the initial few months of 2020. However, in later months, demand for various outdoor power equipment has witnessed strong growth with the resumption of operations in multiple industries. A considerable increase in the market for Do-it-yourself (DIY) equipment and do-it-for-me (DIFM) services in the commercial and residential segments is expected to drive market growth. For instance, according to the Outdoor December forecast report in 2021, the commercial lawn mower grew by over 15 % in 2020, with shipping of nearly 7.7 billion units. Furthermore, rising concern about gasoline fumes and engine noise due to the COVID-19 pandemic has also increased the demand for energy-efficient outdoor power equipment.
Although the prospects look promising, the industry is still faced with several challenges regarding high maintenance costs. For accurate operations, one must inspect outdoor power equipment at various intervals. The factors to be reviewed regularly include inspecting cords, checking for damaged switches, sharpening, oiling, and other repairs needed for properly working the equipment. Hence, the maintenance cost of outdoor power equipment is relatively high, which is expected to hamper the market’s growth.
Market Dynamics
The outdoor power equipment market is experiencing steady growth driven by increasing landscaping activities, technological advancements in battery-powered equipment, and rising residential and commercial demand for lawn and garden maintenance. However, the market also faces challenges related to high equipment costs and operational limitations of battery-powered systems in heavy-duty applications. At the same time, emerging trends such as smart connected equipment and expansion in developing economies are creating new growth avenues for manufacturers. Innovation, sustainability initiatives, and changing consumer preferences toward environmentally friendly products continue to reshape the competitive landscape of the industry.
Technological innovation in battery-powered and electric outdoor power equipment is accelerating market growth. Manufacturers are increasingly introducing cordless, lightweight, and low-noise equipment equipped with lithium-ion battery technology, improved runtime, and fast-charging capabilities. Consumers are shifting toward electric alternatives due to environmental concerns, reduced maintenance requirements, and stricter emission regulations targeting gasoline-powered engines. Smart features such as digital monitoring, automated controls, and connected device integration are also enhancing user convenience and operational efficiency.
Continuous product development is helping manufacturers improve power output and performance levels comparable to traditional fuel-based equipment. These advancements are driving widespread adoption across both residential and professional applications. For instance, in July 2025, Honda introduced four new lithium-ion battery-powered lawn mower models in Canada, Honda HRN-BV, Honda HRX-BV, Honda HRX-BE, and Honda HRC-BE. These residential and commercial walk-behind lawn mowers are being made available in North America for the first time. The lineup offers high quality, durability, reliability, and professional-grade performance associated with Honda’s premium gasoline-powered lawn mowers, while incorporating advanced battery-powered technology.
The relatively high purchase cost of advanced outdoor power equipment is a key restraint for market growth. Battery-powered, robotic, and technologically enhanced equipment often requires substantial upfront investment compared to conventional alternatives. Small businesses, budget-conscious consumers, and users in price-sensitive markets may hesitate to adopt premium products due to affordability concerns. In addition to acquisition costs, equipment maintenance, battery replacement, repairs, and spare part expenses can increase total ownership costs. Professional-grade equipment used in commercial applications may involve even higher servicing requirements and operational expenditures. These cost-related challenges can limit adoption rates, particularly in emerging markets.
Emerging economies offer substantial growth opportunities for the outdoor power equipment market due to rapid urbanization, rising middle-class populations, and increasing investment in infrastructure development. Governments across developing regions are investing in smart cities, public parks, recreational areas, and urban green infrastructure projects, driving demand for landscaping and maintenance equipment.
Expanding residential housing developments and commercial real estate projects are also supporting equipment adoption. Growing awareness regarding lawn care, gardening, and outdoor aesthetics is gradually influencing consumer purchasing behavior in these markets. In addition, increasing penetration of modern retail channels and e-commerce platforms is improving product accessibility. These factors position emerging economies as important future growth markets for outdoor power equipment manufacturers.
Analyst Perspective
The outdoor power equipment market is evolving rapidly due to technological advancements, sustainability initiatives, and changing consumer preferences. Demand is increasingly shifting from gasoline-powered equipment toward battery-powered, electric, and smart-enabled solutions driven by the need for low-emission, low-noise, and easy-to-maintain products. Rising investments in residential landscaping, commercial maintenance, and green infrastructure projects are expected to support market growth. While manufacturers continue to focus on innovation and expanding cordless product portfolios, challenges such as high equipment costs and battery performance limitations may restrain adoption. Nevertheless, ongoing developments in battery technology, automation, and connected equipment are expected to create strong growth opportunities over the forecast period.
Power Source Insights
Based on power source, the gasoline segment led the market with the largest revenue share of 56.1% in 2025 and is expected to witness a drop in demand because of gas fumes and noise produced. Various government regulations have been enacted to address gasoline-powered sources' environmental issues. For instance, California implemented laws banning gas-powered chainsaws, lawnmowers, and leaf blowers, which were anticipated to be in effect as early as 2024.
Meanwhile, the battery power source segment is estimated to grow at a significant CAGR over the forecast period. The battery-powered source segment is expanding owing to lower shipping costs, lighter than gasoline alternatives, and is more affordably purchased online. Furthermore, various online retailers are adjusting their inventory to optimize new government rules and regulations for developing electric outdoor power equipment products.
End-use Insights
Based on end use, the residential segment led the market with the largest revenue share of 53.8% in 2025. The growing inclination of residential users towards investing more time in gardening and outdoor is expected to drive the demand for outdoor power equipment. Furthermore, the rising sales of DIY outdoor power equipment due to the pandemic are likely to drive the segment growth.
The commercial segment is expected to grow at a significant CAGR over the forecast period. The rising number of smart cities owing to increasing urbanization is expected to drive segment growth. According to a report published by World Urbanization Prospects in 2019 by the UN Department of Economic and Social Affairs (UN DESA), the recent urban population, which is 55.7%, is anticipated to increase to 68.4% in 2050 globally. Furthermore, with the rising number of golf players coupled with a growing number of golf club facilities, the demand for various outdoor power equipment is expected to increase for the commercial segment.
Type Insights
Based on type, the lawn mower segment led the market with the largest revenue share of 41.1%in 2025. The chainsaw segment is estimated to grow at a significant CAGR over the forecast period. A chainsaw is a handheld, portable mechanical device mainly used to cut wood and wood-related products. The increasing deforestation rate for various infrastructure activities is expected to drive market growth. Furthermore, the rising demand for interior décors such as wood-based flooring, roofing, panels, and more are augmenting the use of chainsaws in various furniture applications.
 To learn more about this report, Download Free Sample Report
The lawn mower segment captured the largest market share and is expected to grow at a significant CAGR over the forecast period. Several companies are focused on introducing various robotic mowers due to the rising demand for technologically advanced mowers. Furthermore, the latest automated lawn mowers are equipped with GPS tracking and remote control, making it easier for the user to operate, monitor, and track the mower. In addition, changing consumer behavior in its spending power and aesthetic appeal for their gardening space is also expected to boost the market's growth.
Regional Insights
North America dominated the outdoor power equipment market with the largest revenue share of 35.4% in 2025. The regional market’s growth is attributed to North America’s larger geographical area compared to its population, which leads to more gardens and lawns in the region. This has led to increased demand for outdoor power equipment in the region. Furthermore, rising investment by the government in infrastructure is expected to drive the region’s growth. For instance, in 2022, the Canadian government provided USD 1.5 billion for the Canada Mortgage and Housing Corporation to expand the rapid housing initiative of building houses.
 To learn more about this report, Download Free Sample Report
U.S. Outdoor Power Equipment Market Trends
The outdoor power equipment market in the U.S. held the largest share in the North America region in 2025. The U.S. market is driven by high consumer spending on lawn and garden care, rising demand for battery-powered tools due to sustainability trends, extensive landscaping in residential and commercial properties, and stringent emissions regulations accelerating electric equipment adoption.
Europe Outdoor Power Equipment Market Trends
The outdoor power equipment industry in Europe is expected to grow at a significant CAGR. Europe market is driven by strict environmental regulations promoting low-emission and electric equipment, increasing urban green spaces, strong government support for sustainable landscaping, high adoption of robotic lawnmowers, and a well-established culture of gardening and outdoor leisure activities.
The UK outdoor power equipment industry is driven by a strong gardening culture, rising popularity of allotments and urban green projects, increasing demand for electric and battery-powered tools due to strict emission laws, and growing investments in smart, automated lawn care solutions.
Germany's outdoor power equipment industry is driven by a strong DIY and home improvement culture, high adoption of precision-engineered tools, stringent environmental laws favoring electric models, increasing demand for robotic lawn mowers, and a growing emphasis on sustainable landscaping in urban planning initiatives.
Asia Pacific Outdoor Power Equipment Market Trends
The Asia Pacific outdoor power equipment industry is expected to register a fastest CAGR during the forecast period. The significant growth rate of the region is due to rising disposable income and changing lifestyles in various developing countries such as India and China. Furthermore, increasing annual events such as the Indian Premier League (IPL), World Baseball Classic, Asian Games, and various other sports activities are expected to boost the requirement for outdoor power equipment to enhance sports stadiums and fields.
Japan's outdoor power equipment industry is driven by the increasing adoption of compact and precision-engineered tools for small gardens, high demand for automated and robotic equipment due to labor shortages, government support for urban greening, and strong consumer preference for high-tech, low-noise solutions.
China's outdoor power equipment industry is driven by rapid urbanization fueling demand for landscaping tools, increasing government initiatives for green infrastructure, rising disposable income boosting consumer spending on garden maintenance, and growing local manufacturing capabilities supporting cost-effective and technologically advanced equipment production.
Key Outdoor Power Equipment Company Insights
Some of the key companies in the outdoor power equipment industry include Husqvarna Group, Makita Corporation, Honda Motor Co., Ltd., Briggs & Stratton, and others. Organizations are focusing on integrating advanced technologies into their offerings to maintain competitive advantages. Therefore, key players are taking several strategic initiatives, such as new product launches, mergers and acquisitions, and partnerships, among others.
-
Makita Corporation is a key player in the global outdoor power equipment industry, known for its high-performance cordless and electric tools. The company leverages advanced battery technology, strong R&D, and a global distribution network to meet the rising demand for eco-friendly and durable equipment.
-
Briggs & Stratton is a manufacturer in the global outdoor power equipment industry, specializing in gasoline engines and battery-powered solutions. The company focuses on innovation, durability, and expanding its electrification portfolio to meet the growing demand for sustainable and high-performance equipment worldwide.
Key Outdoor Power Equipment Companies
The following key companies have been profiled for this study on the outdoor power equipment market.
-
Makita Corporation
-
Honda Motor Co., Ltd.
-
Briggs & Stratton
-
MTD Inc
-
Stanley Black & Decker, Inc.
-
ANDREAS STIHL AG & Co. KG
-
CHERVON (China) Trading Co., Ltd.
-
Techtronic Industries Co. Ltd.
-
YAMABIKO Corporation
-
Robert Bosch GmbH
-
AL-KO GmbH
-
AriensCo
-
The Toro Company
-
Deere & Company
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Husqvarna, Deere & Company, The Toro Company, Honda Power Equipment)
- These companies primarily focus on expanding their market presence through continuous product innovation, advanced outdoor power equipment launches, and portfolio enhancement.
- They emphasize maintaining leadership positions by integrating improved performance, durability, and technologically advanced features into their offerings.
- These players strengthen their competitive positioning through strategic initiatives such as product launches, partnerships, acquisitions, and investments in research & development.
- Their established brand recognition, extensive distribution networks, and strong innovation capabilities provide a significant advantage in the market.
- Despite strong brand equity and substantial market share, these companies operate in a highly competitive and moderately consolidated market environment.
- Sustaining leadership requires continuous innovation, pricing optimization, and adaptation to evolving customer expectations and regulatory requirements.
Emerging Players (Greenworks Tools, EGO, Techtronic Industries (TTI), Positec Group, Worx)
- Emerging companies are increasingly focusing on launching cost-competitive products equipped with advanced features comparable to premium offerings.
- They aim to strengthen their market footprint by expanding product portfolios, improving accessibility, and targeting value-driven customer segments.
- These players compete through strategic activities such as new product development, collaborations, partnerships, and innovation-led differentiation.
- Their focus on affordability, sustainability, and compliance with evolving industry standards helps them remain competitive in the market.
- Emerging companies may face challenges in expanding market share due to the strong presence of well-established global and regional competitors.
- Limited brand recognition, distribution reach, and resource constraints may also impact their ability to compete at scale.
Recent Developments
-
In October 2024, Husqvarna Group introduced four new robotic lawnmowers-580L EPOS, 580 EPOS, 560 EPOS, and an upgraded 535 AWD EPOS-expanding its boundary wire-free lineup for professional turf management. Available globally from March 2025, these advanced models feature precision GPS navigation and customizable cutting patterns, enhancing efficiency, sustainability, and cost-effectiveness for commercial users.
-
In January 2022, Robert Bosch GmbH launched Keo, a cordless garden saw. Keo is one of the products of 18V Power for All System, the alliance formed with Husqvarna Group. The product is acquainted with a powerful interchangeable battery pack with replaceable saw blades designed for DIY applications.
Outdoor Power Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 56.3 billion
Estimated Market size in 2026
USD 59.7 billion
Projected Market size by 2033
USD 93.4 billion
Growth rate
CAGR of 6.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, Volume in ‘000 units, and CAGR from 2026 to 2033
Report coverage
Revenue and volume forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Power source, end-use, type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; South Korea; Australia; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
Makita Corporation, Husqvarna Group, Honda Motor Co., Ltd., Briggs & Stratton, Stanley Black & Decker, Inc., ANDREAS STIHL AG & Co. KG, Robert Bosch GmbH, AriensCo, The Toro Company, Deere & Company
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Outdoor Power Equipment Market Report Segmentation
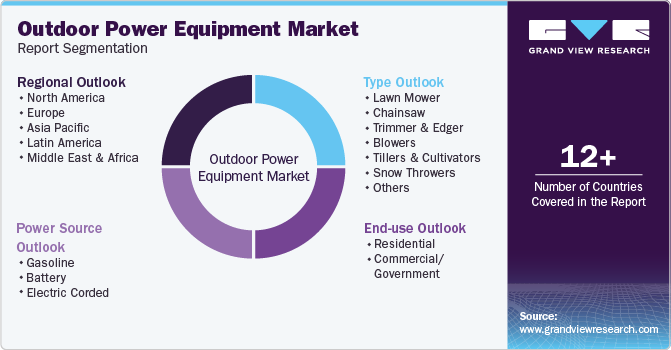
This report forecasts revenue growth at the global, regional, and country levels and analyzes the latest industry trends from 2021 to 2033 in each sub-segment. For this study, Grand View Research has segmented the global outdoor power equipment market report based on power source, end-use, type, and region:
 To learn more about this report, Download Free Sample Report
-
Power Source Outlook (Revenue, USD Million, 2021 - 2033)
-
Gasoline
-
Battery
-
Electric Corded
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Residential
-
Commercial/ Government
-
-
Type Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
Lawn Mower
-
Walk-Behind Lawn Mowers
-
Ride-on Lawn Mowers
-
Robotic Lawn Mowers
-
Zero -Turn Mowers
-
-
Chainsaw
-
Trimmer & Edger
-
Trimmers & Brush Cutter
-
Hedge Trimmers
-
Walk-Behind Edgers & Trimmers
-
-
Blowers
-
Snow
-
Leaf
-
-
Tillers & Cultivators
-
Snow Throwers
-
Others
-
-
Regional Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Netherlands
-
Denmark
-
Finland
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Singapore
-
Australia
-
New Zealand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
Segment Definition
Segment - Power Source
Revenue capture definition
Gasoline
Revenue is generated from outdoor power equipment powered by internal combustion engines using gasoline fuel. It includes equipment preferred for high-power, heavy-duty, and extended-duration applications across residential, commercial, and professional landscaping operations.
Battery
This segment includes revenue derived from outdoor power equipment operated using rechargeable battery technologies, primarily lithium-ion batteries. It covers cordless products offering portability, reduced emissions, lower noise levels, and minimal maintenance requirements.
Electric Corded
This segment accounts for revenue from outdoor power equipment powered through direct electrical connection using power cords. These products are commonly used in residential settings where access to a continuous electricity supply is available.
Segment - End Use
Revenue capture definition
Residential
This segment captures revenue generated from outdoor power equipment purchased and used by homeowners and individual consumers for lawn care, gardening, landscaping, and outdoor maintenance activities. It includes products designed for small to medium-sized properties with a focus on ease of use, affordability, and convenience.
Commercial/ Government
This segment includes revenue from outdoor power equipment utilized by professional landscapers, contractors, municipalities, government agencies, parks departments, and institutional facilities. The equipment in this segment is typically designed for heavy-duty, large-scale, and frequent operational requirements.
Segment - Type
Revenue capture definition
Lawn Mower
This segment captures revenue generated from equipment used for cutting and maintaining grass and lawn surfaces in residential, commercial, and institutional environments. It includes multiple mower categories based on operational design, mobility, and automation level.
- Walk-Behind Lawn Mowers: This segment includes revenue from a self-propelled or manually operated machine used for cutting grass on lawns, yards, or other outdoor areas. These are commonly used for residential lawn maintenance.
- Ride-on Lawn Mowers: This segment captures revenue from lawn mowing equipment that allows operators to sit and drive the machine while mowing.
- Robotic Lawn Mowers: This segment includes revenue generated from autonomous lawn mowers that operate with minimal human intervention using programmed routes, sensors, and smart navigation systems.
- Zero-Turn Mowers: This segment captures revenue from high-performance lawn mowers equipped with zero-turn steering capability for enhanced maneuverability and faster mowing operations.
Chainsaw
This segment includes revenue generated from handheld cutting equipment designed for tree cutting, pruning, logging, wood processing, and land clearing activities.
Trimmer & Edger
This segment captures revenue from handheld or wheeled devices designed for cutting and trimming grass, weeds, and other vegetations in areas that are difficult to reach with a lawn mower.
- Trimmers & Brush Cutter: This segment includes revenue generated from heavy-duty tools designed to cut through thicker vegetation, including small trees, bushes, and dense undergrowth.
- Hedge Trimmers: This segment captures revenue from equipment designed for trimming, shaping, and maintaining hedges, shrubs, and ornamental plants.
- Walk-Behind Edgers & Trimmers: This segment includes revenue generated from wheeled, walk-behind equipment used for edging and trimming lawns, sidewalks, driveways, and landscape borders.
Blowers
This segment captures revenue generated from equipment designed to move debris, leaves, grass clippings, dust, and snow using high-speed airflow.
- Snow: This segment includes revenue derived from outdoor power equipment specifically used for snow management, snow removal, and winter maintenance applications.
- Leaf: This segment captures revenue from equipment used to clear fallen leaves and debris from lawns, driveways, and sidewalks. It is available in various configurations, including handheld, backpack-mounted, and walk-behind models.
Tillers & Cultivators
This segment includes revenue generated from equipment used for soil preparation, aeration, cultivation, and garden bed maintenance.
Snow Shovels
This segment captures revenue from mechanized snow removal equipment designed to collect and discharge snow from driveways, walkways, roads, and outdoor surfaces.
Others
This segment captures revenue from other type of outdoor power equipment including aerators, augers, and pressure washer.
Estimation Model
Name
Key Question
Description
Installed Base / Demand Layer
Who owns or operates the equipment today?
Establish the total potential demand by identifying all users, facilities, assets, or entities that currently own, operate, or could require the equipment. This serves as the foundation for market sizing before any market-specific filters are applied.
Addressable Market Layer
Who can realistically be reached and served?
Refine the total universe into the realistically serviceable market by applying geographic, industry, infrastructure, regulatory, and operational filters. This helps determine the portion of the installed base that can actually purchase or adopt the equipment.
Purchase & Replacement Layer
Who is actively purchasing, replacing, or upgrading equipment?
Estimate the annual demand generation by evaluating replacement cycles, equipment aging, fleet expansion, new installations, technology upgrades, and adoption trends. This converts the addressable installed base into yearly purchasing demand.
Monetisation Layer
How much revenue is generated from this demand?
Convert equipment demand into market revenue by applying average selling prices (ASP), product mix, aftermarket sales, maintenance contracts, spare parts, consumables, software, and other recurring revenue streams where applicable.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Customer Purchasing Behavior & Buyer Trends
Delivered analysis of customer purchasing behavior across residential users, landscaping contractors, municipalities, and commercial users.
Assessment of buying preferences, replacement cycles, and brand loyalty factors.
Evaluation of seasonal demand patterns and purchasing drivers.
Improved customer segmentation and targeting strategies.
Supported development of customer-centric sales models.
Enhanced understanding of buyer decision-making trends.
Region Opportunity & Demand Assessment
Delivered region-wise market sizing, forecasts, and trend analysis across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Assessment of regional landscaping demand, urbanization trends, and infrastructure development.
Identification of high-growth regional markets and demand hotspots.
Supported regional expansion and investment planning.
Enabled targeted go-to-market strategies.
Assisted in identifying emerging growth opportunities.
Competitive Benchmarking & Product Portfolio Analysis
Delivered comparative benchmarking of key market participants based on product portfolio, technology offerings, pricing, innovation, and regional presence.
Analysis of strategic initiatives, product launches, and distribution capabilities.
Evaluation of competitive strengths and market positioning.
Supported competitive intelligence and strategic decision-making.
Enabled identification of market gaps and growth opportunities.
Assisted in strengthening product differentiation strategies.
Frequently Asked Questions About This Report
Asia Pacific is expected to emerge as the fastest-growing regional market for outdoor power equipment through 2033. The significant growth rate of the region is due to rising disposable income and changing lifestyles in various developing countries such as India and China.
Key factors that are increasing demand for cordless outdoor power equipment as people are more inclining toward greater flexibility and portability, rising demand for landscaping services, and growing awareness of environmental issues leads to increasing adoption of outdoor power equipment using lithium-ion batteries.
The global outdoor power equipment market size was estimated at USD 56.3 billion in 2025 and is expected to reach USD 59.7 billion in 2026.
The global outdoor power equipment market is expected to grow at a compound annual growth rate of 6.6% from 2026 to 2033 to reach USD 93.4 billion by 2033.
The lawn mower segment dominated the type outdoor power equipment market and accounted for 41.1% of the global revenue share in 2025, while the chainsaw is the fastest growing segment.
Some key players operating in the outdoor power equipment market include Makita Corporation, Husqvarna Group, Honda Motor Co., Ltd., Briggs & Stratton, Stanley Black & Decker, Inc., ANDREAS STIHL AG & Co. KG, Robert Bosch GmbH, AriensCo, The Toro Company, Deere & Company
North America dominated the outdoor power equipment market with the largest revenue share of 35.4% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Based on end use, the residential segment led the market with the largest revenue share of 53.8% in 2025 and is the fastest-growing end use segment.
About the Author(s)
HVAC & Construction Research Team
Technology · HVAC & ConstructionThis report was authored by the hvac & construction research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the hvac & construction segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


