
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Packaging Coatings Market Size & Share Report, 2026-2033GVR Report cover

Packaging Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By Resin (Epoxy, Acrylics, Polyurethane), By Packaging Type (Rigid Packaging, Flexible Packaging),By End use, By Region, And Segment Forecasts
Market Size, 2025
$4.0BMarket Estimate, 2026
$4.1BMarket Forecast, 2033
$5.2BCAGR, 2026–2033
3.4%Packaging Coatings Market Summary
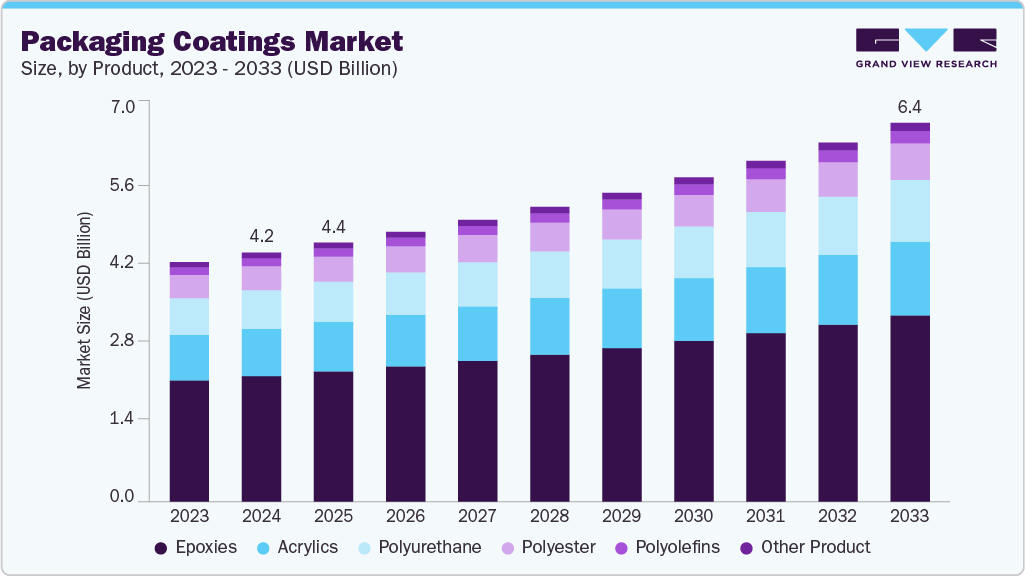
The global packaging coatings market size was valued at USD 4.0 billion in 2025 and is projected to grow from USD 4.1 billion in 2026 to USD 5.2 billion by 2033, at a CAGR of 3.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 35.9% in 2025. The market demand for packaging coatings is increasing for their application in flexible packaging coatings.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By resin: Acrylic segment held the largest revenue share of 36.3% in 2025.
- By packaging type: Rigid segment dominated the market, with a revenue share of 58.5% in 2025.
- By end use: Food & Beverage segment held the largest market share of 45.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.9% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.0 Billion
- Estimated market size in 2026: USD 4.1 Billion
- Projected market size by 2033: USD 5.2 Billion
- CAGR (2026-2033): 3.4%
Prism AI by Grand View Research Free to tryAsk a question about the packaging coatings marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
These products offer enhanced adhesion, durability, and resistance properties, making them ideal for various industries, including food and beverage packaging. The rise of the e-commerce industry is another significant driving factor. With the growth of online shopping, there is a higher demand for protective coatings for packaging materials to ensure the safe delivery of products. In addition, the increased demand for sustainable packaging solutions has also played a role in driving the market growth. Companies are focusing on developing eco-friendly alternatives to meet regulatory requirements and consumer preferences.Technological advancement and extensive research and development activities have contributed to market growth as well. These efforts aim to develop more effective and sustainable coating for various consumer goods products. Furthermore, global industrialization and urbanization have created a higher demand for packaged products, which in turn drives the market growth of the products.
 To learn more about this report, Download Free Sample Report
Regulatory considerations also impact on the market for products. Increasing regulations related to harmful chemicals, such as volatile organic compounds (VOCs), can affect the market. However, companies have quickly adapted to various eco-friendly alternatives to comply with these regulations.
Market Dynamics
Technological innovation, evolving food safety regulations, and sustainability initiatives continue to influence the development of the packaging coatings market. Manufacturers are focusing on improving coating performance through enhanced corrosion resistance, chemical stability, adhesion, flexibility, and barrier properties while simultaneously reducing environmental impact. Increasing adoption of BPA-NI technologies, waterborne formulations, and recyclable packaging materials is transforming product portfolios across the industry. Furthermore, continuous advancements in coating chemistry and application technologies are enabling packaging manufacturers to improve operational efficiency while meeting increasingly stringent regulatory and consumer requirements.
The packaging industry is undergoing a significant transition toward sustainable materials and environmentally compliant coating systems, creating substantial growth opportunities for advanced packaging coatings. Regulatory restrictions on bisphenol A (BPA), volatile organic compounds (VOCs), and hazardous substances have accelerated investments in BPA-NI coatings, waterborne technologies, powder coatings, and bio-based resin systems. Brand owners and packaging manufacturers are increasingly adopting coatings that improve recyclability while maintaining high levels of product protection and processing efficiency.
Simultaneously, sustainability commitments by food & beverage companies, consumer goods manufacturers, and packaging converters are encouraging the development of innovative coating formulations with lower environmental impact. Continued investment in circular economy initiatives, recyclable metal packaging, and lightweight packaging solutions is expected to drive demand for next-generation packaging coatings over the forecast period.
Fluctuating raw material prices and increasingly stringent environmental regulations remain significant challenges for packaging coating manufacturers. The industry relies heavily on petrochemical-based resins, pigments, additives, and specialty chemicals, making production costs highly sensitive to volatility in crude oil prices and global supply chain disruptions. At the same time, regulatory restrictions concerning BPA, VOC emissions, hazardous substances, and food-contact materials require continuous product reformulation and significant investment in research and development, increasing compliance costs and extending product commercialization timelines.
Growing investments in sustainable packaging and the increasing adoption of recyclable metal and flexible packaging present significant opportunities for the packaging coatings market. Rising demand for BPA-NI, bio-based, low-VOC, and high-performance coating technologies is encouraging manufacturers to develop innovative formulations that comply with evolving environmental regulations while maintaining superior packaging performance. Emerging applications in pharmaceutical packaging, premium food packaging, e-commerce packaging, and specialty industrial packaging, combined with increasing packaging consumption across Asia Pacific, Latin America, and the Middle East, are expected to create attractive long-term growth opportunities for coating manufacturers.
Market Concentration & Characteristics
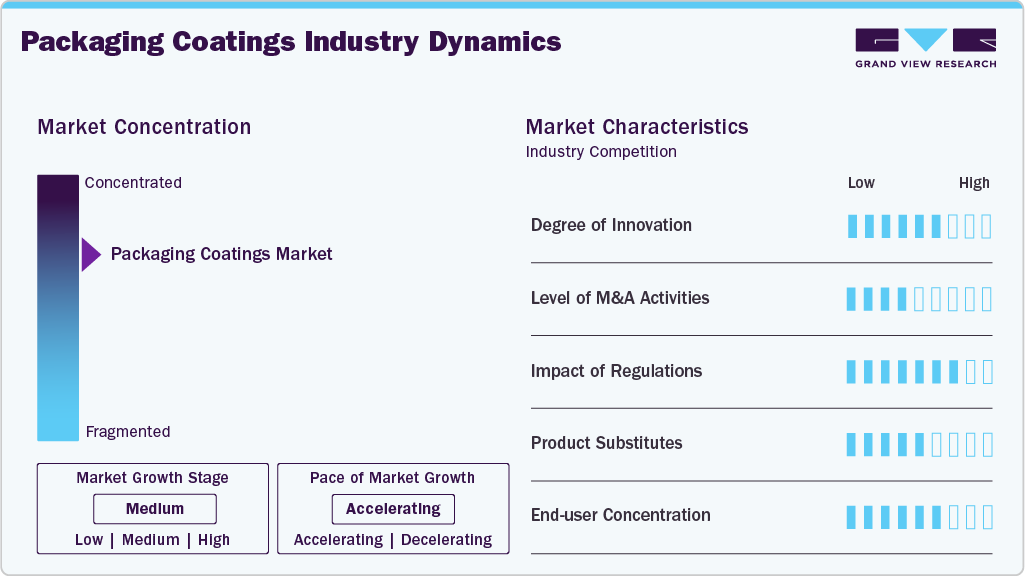
The market exhibits characteristics of a moderately concentrated market. In the case of packaging coatings, a handful of key companies dominate the market, leading to a concentrated competitive landscape. These companies have established strong brand recognition, extensive distribution networks, and advanced technological capabilities, which act as barriers to entry for new players.
The competitive market landscape is characterized by intense rivalry among the major players. These companies compete based on factors such as product quality, innovation, pricing strategies, and customer service. Competition drives continuous improvement and innovation in products, benefiting consumers with a wider range of options and improved product performance.
 To learn more about this report, Download Free Sample Report
Regulatory factors also play a significant role in shaping the market. Governments and regulatory bodies impose various regulations and standards to ensure the safety and sustainability of packaging materials. Compliance with these regulations is crucial for companies operating in the market. In addition, environmental concerns and the growing demand for sustainable packaging solutions have led to the development of eco-friendly coatings that meet regulatory requirements and consumer preferences.
Other factors that influence the product market include technological advancements and research and development activities. Companies invest in research and development to enhance the performance and functionality of coatings, such as improving barrier properties, adhesion, and durability. Technological advancements also enable the development of innovative coatings that cater to specific packaging requirements, such as temperature-sensitive products or high-barrier applications.
Analyst Perspective
The packaging coatings market is witnessing steady expansion, supported by rising global consumption of packaged food, beverages, pharmaceuticals, personal care products, and industrial goods. Manufacturers are increasingly investing in advanced coating technologies that provide superior corrosion resistance, product protection, and regulatory compliance while addressing growing sustainability requirements. The transition toward BPA-non-intent (BPA-NI), low-VOC, and recyclable packaging solutions is reshaping product development strategies across the industry. Companies with strong formulation expertise, integrated supply chains, and the ability to develop environmentally compliant coating systems are expected to strengthen their competitive position as packaging performance and sustainability become key purchasing criteria.
Resin Insights
Based on resin, the acrylic segment accounted for the highest market share, representing 36.3% of total revenue in 2025, due to their strong adhesion, chemical resistance, and durability properties. Epoxy products have been used in food packaging to provide a protective layer that separates the food or drink from the metal used to make cans. This helps prevent corrosion and maintains the safety, freshness, and nutritional value of the contents. Epoxy products also contribute to the longer shelf life of canned food, allowing consumers to store food for extended periods. In addition, epoxies are used in glass packaging to protect metal lids from corrosion.
Polyurethane packaging coatings segments are expected to grow fastest with a CAGR of 5.6% from 2025 to 2033, for their excellent flexibility, chemical resistance, and moisture resistance. They are used in products to provide a protective and durable layer that can withstand various environmental conditions. Polyurethane coatings offer good adhesion, impact resistance, and weather ability, making them suitable for applications such as food packaging, beverage cans, and Other Application materials.
Packaging Type Insights
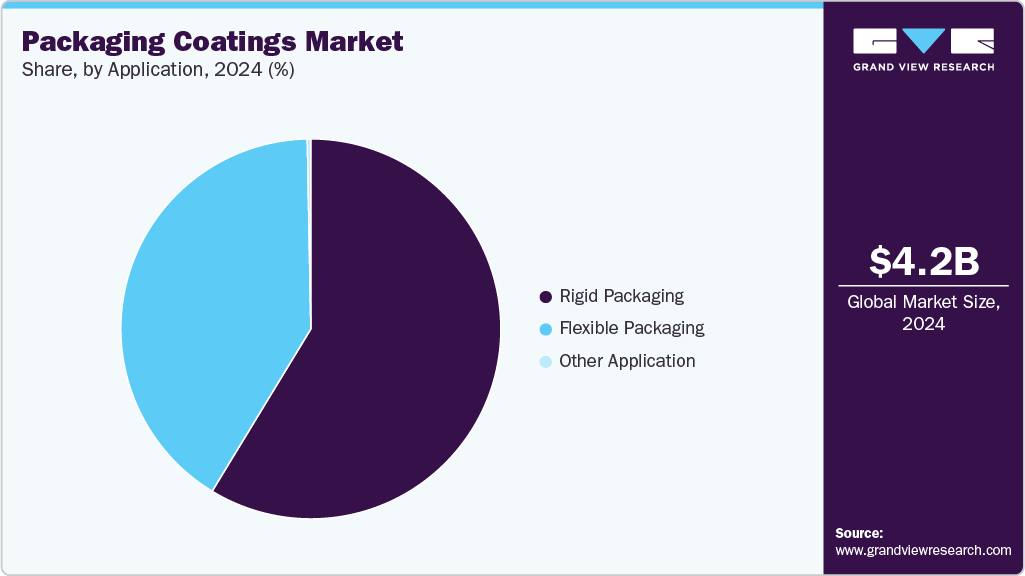
Based on packaging type, the rigid segment accounted for the highest market share, representing 58.5% of total revenue in 2025. attributed to its preference for products that require strong protection and a higher perceived value. It is commonly used for high-end beverages, spirits, perfumes, and specific beauty and health products. Glass packaging, in particular, is associated with a premium image and is favored for certain products. Rigid packaging also offers excellent barrier properties, ensuring the preservation and freshness of the contents. The global rigid packaging market is predicted to reach a significant value by 2024, indicating its continued importance in the consumer-packaged goods (CPG) industry.
 To learn more about this report, Download Free Sample Report
Flexible packaging applications of packaging coatings are expected to grow fastest at a CAGR of 5.2% from 2025 to 2033, due to their lower cost and environmental impact compared to rigid packaging. Flexible pouches, for example, have become increasingly popular for food packaging due to their resealable nature, low environmental impact, and cost-effectiveness. They are commonly used for packaging products like granola, energy drinks, coffee, soups, snacks, and various other food items. The demand for flexible packaging is driven by factors such as convenience, lightweight design, and the ability to extend the shelf life of products.
End Use Insights
By end use, food & beverage held a dominant position, contributing 45.4% of total revenue in 2025, driven by the extensive use of coated metal cans, beverage containers, and food packaging materials to protect products from corrosion, moisture, and external contamination. Increasing demand for packaged and processed foods, ready-to-drink beverages, and packaging solutions that preserve product quality and shelf life continues to support the adoption of specialized coatings. In addition, stringent food-contact safety requirements and the need for durable, high-performance coatings are encouraging manufacturers to develop formulations that meet regulatory standards while maintaining packaging integrity.
Consumer electronic segment is expected to grow the fastest with a CAGR of 3.8%, during the forecast period, driven by rising demand for protective and functional packaging for smartphones, laptops, televisions, home appliances, and other electronic devices. Packaging coatings help improve resistance to moisture, abrasion, and surface damage while supporting the durability and appearance of packaging materials during storage and transportation. Increasing shipments of electronic products, shorter product replacement cycles, and the need for reliable packaging across e-commerce and distribution networks are expected to support demand for coatings used in protective packaging components
Regional Insights
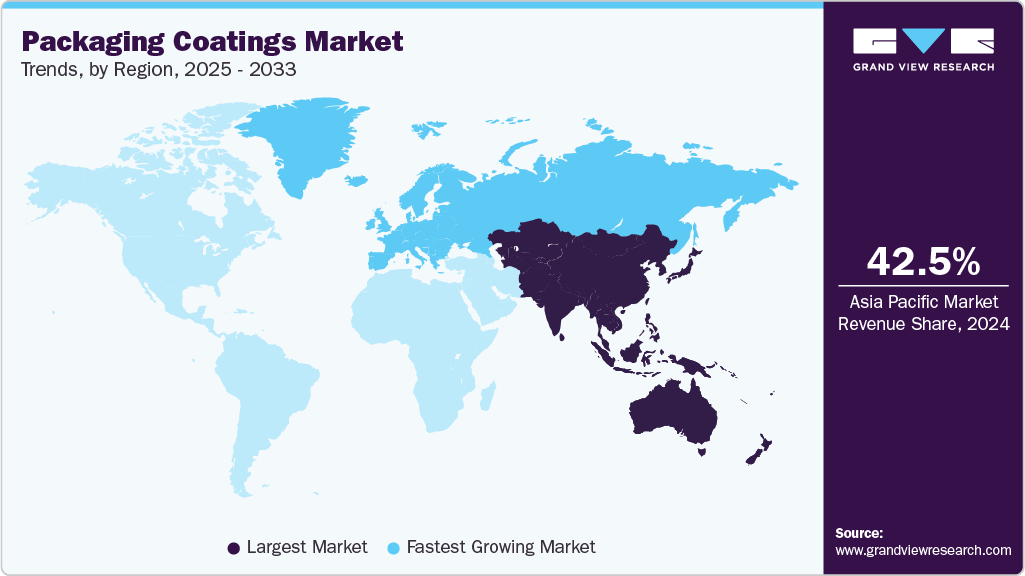
Asia Pacific dominated the packaging coatings market with the highest revenue share of 35.9% in 2025. This high share of this segment can be attributed to the demand for packaging coatings in the Asia Pacific region is robust, driven by several key factors that contribute to its dominance in the global market. The region's market dominance is evident through its largest consumption and demand for packaging coatings. This demand is primarily fueled by the increasing need for flexible packaging coatings, particularly in the food and beverage packaging sector. In addition, the surge in demand for packaged food & beverage and consumer goods has significantly contributed to the high adoption of the products in the region.
 To learn more about this report, Download Free Sample Report
China dominated the Asia Pacific packaging coatings market in 2025, driven by the increasing demand for flexible packaging coatings and the rising demand for food and beverage packaging. However, it is important to note that increasing regulations are expected to hinder the market's growth. Nevertheless, the swiftly shifting market towards eco-friendly coatings is likely to act as an opportunity in the future.
North America Packaging Coatings Market Trends
The North America packaging coatings market secured 24.9% of the revenue share in 2024, owing to the increasing demand for flexible packaging coatings and rising food and beverage packaging. However, the market is also witnessing fast growth owing to the region's fast-paced economy, changing lifestyles, and consumer inclination toward packaged food and beverages.
U.S. Packaging Coatings Market Trends
The U.S. packaging coatings market remains a vital segment of the coatings industry, supported by strong demand from food, beverage, pharmaceutical, and personal care sectors. These coatings enhance packaging performance by providing chemical resistance, corrosion protection, and improved shelf life. With growing consumer awareness and regulatory pressure, there is a marked shift toward sustainable solutions, such as BPA-free, water-based, and low-VOC coatings.
Leading companies like PPG Industries, Axalta, Sherwin-Williams, and Michelman are investing heavily in R&D to create innovative, eco-friendly products. The rise in e-commerce and convenience packaging has also accelerated the need for functional barrier coatings that ensure product safety and integrity. While the market is mature, it continues to evolve through technological advancement and sustainability-driven demand, ensuring a stable growth outlook for the foreseeable future.
Europe Packaging Coatings Market Trends
The Europe packaging coatings market held 20.0% of the global revenue share in 2024. This demand is driven by increasing consumer preference for sustainable and recyclable packaging materials, strict EU regulations promoting low VOC and BPA-free coatings, and rising demand from the food & beverage and personal care industries. Additionally, the expansion of e-commerce and advancements in coating technologies, such as water-based and UV-curable coatings, further boost the market. Growing emphasis on product shelf-life enhancement, visual appeal, and barrier properties also contributes significantly to the demand for high-performance packaging coatings across the region.
Middle East & Africa Packaging Coatings Market Trends
The Middle East & African packaging coatings market is experiencing strong growth, driven by increasing demand for food and beverage packaging. As urbanization, population growth, and changing consumption patterns fuel the demand for packaged foods and beverages, manufacturers in the region are increasingly adopting advanced coating technologies to enhance product shelf life, safety, and visual appeal.
Packaging coatings, particularly epoxy, acrylic, and polyester-based types, are gaining traction for their ability to provide effective barrier properties, corrosion resistance, and chemical stability, essential for maintaining product integrity during transport and storage in the region’s often harsh climatic conditions. Countries like the UAE, Saudi Arabia, and South Africa are experiencing rising investments in food processing and packaging infrastructure, partly due to growing tourism and a shift toward convenience and ready-to-eat products. This, in turn, is driving the adoption of high-performance packaging coatings that comply with international food safety standards.
Latin America Packaging Coatings Market Trends
The Latin American packaging coatings market is witnessing steady growth, largely driven by demand for advanced materials that enhance product shelf life, aesthetic appeal, and regulatory compliance. Packaging coatings serve critical roles as barrier layers, primers, and protective finishes, resisting moisture, oxygen, chemicals, and mechanical damage.
A prominent example is the adoption of water-based and BPA-free epoxy coatings in Brazil’s canned food industry, where manufacturers aim to meet both health standards and export quality benchmarks. As regional packaging converters and brand owners increasingly seek durable, safe, and compliant coating technologies, the demand for multifunctional packaging coatings continues to rise, reinforcing their pivotal role in Latin America’s packaging evolution.
Key Packaging Coatings Company Insights
Some key players operating in the packaging coatings market include Akzo Nobel NV, BASF SE, Arkema Group, Berger Paints India Limited, and Clariant, among others.
-
Akzo Nobel N.V., headquartered in Amsterdam, Netherlands, is a global leader in the packaging coatings market. It is recognized for its strong heritage in coatings technology, sustainability leadership, and innovation-driven growth. The company offers a comprehensive portfolio of high-performance packaging coatings designed to meet rigorous food safety standards and evolving environmental regulations. These coatings deliver critical functionalities such as corrosion resistance, flexibility, adhesion, chemical inertness, and aesthetics, making them highly suitable for food and beverage cans, aerosol containers, closures, and industrial packaging. Akzo Nobel develops next-generation waterborne, BPA-NI (Bisphenol A non-intent), and solvent-free coatings aligned with global sustainability trends. Its coatings are tailored to comply with stringent international standards, including FDA, EU Framework Regulation, and Swiss Ordinance requirements, ensuring safety and regulatory compliance across global markets.
Chugoku Marine Paints Ltd, HEMPEL A/S, Jotun, and Kansai Paint Co. Ltd. are emerging market participants in the packaging coatings market.
-
Jotun, headquartered in Norway, is an emerging and agile player in the global packaging coatings market. It is renowned for its advanced coating technologies and commitment to sustainability, performance, and aesthetics. With a strong legacy in decorative paints and marine, protective, and powder coatings, Jotun steadily expanded its footprint in metal packaging coatings tailored for food, beverage, and general industrial packaging applications. The company emphasizes innovative, BPA-NI (Bisphenol A non-intent) solutions, corrosion resistance, and superior adhesion to meet the evolving regulatory and consumer demands for safe, durable, and eco-friendly coatings. Leveraging its robust R&D capabilities, global production facilities, and localized technical support teams, Jotun delivers high-performance solutions with consistent quality across Europe, Asia-Pacific, the Middle East, and emerging markets. Its integrated supply chain, sustainability focus, and deep industry expertise position Jotun as a trusted partner for brand owners, converters, and packaging manufacturers in the dynamic global packaging coatings landscape.
Key Packaging Coatings Companies
The following key companies have been profiled for this study on the packaging coatings market.
-
Akzo Nobel NV
-
Axalta Coatings
-
BASF SE
-
Arkema Group
-
Berger Paints India Limited
-
Chemetall
-
Chugoku Marine Paints Ltd
-
DowDuPont
-
Evonik Industries AG
-
HEMPEL A/S
-
Henkel AG & Co. KGaA
-
Jotun
-
Kansai Paint Co. Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Akzo Nobel NV, BASF SE, Axalta Coatings, DowDuPont, Evonik Industries AG, HEMPEL A/S, Jotun, Kansai Paint Co. Ltd.)
- Expand sustainable and BPA-NI packaging coating portfolios to comply with evolving food-contact regulations.
- Strengthen global manufacturing and distribution networks through strategic investments and acquisitions.
- Invest in advanced coating technologies offering improved corrosion protection, barrier performance, and sustainability.
- Establish long-term partnerships with packaging manufacturers, food & beverage companies, and brand owners.
- Large-scale Broad product portfolios serving diverse packaging applications.
- Strong global manufacturing footprint and distribution capabilities.
- Advanced R&D supporting continuous innovation and regulatory compliance.
- Long-standing relationships with multinational packaging manufacturers and consumer goods companies.
- High dependence on petrochemical-derived raw materials and associated price volatility.
- Increasing regulatory compliance costs related to food-contact materials and environmental standards.
- High capital investment required for product innovation and manufacturing upgrades.
- Exposure to fluctuations in global packaging and consumer goods demand.
Emerging Players (Arkema Group, Berger Paints India Limited, Chemetall, Chugoku Marine Paints Ltd., Henkel AG & Co. KGaA)
- Focus on specialty packaging coating solutions and application-specific product development.
- Expand regional manufacturing capabilities and customer support networks.
- Develop environmentally friendly and low-VOC coating technologies to strengthen market presence.
- Collaborate with regional packaging manufacturers to deliver customized coating solutions.
- Greater flexibility in developing customer-specific formulations.
- Strong regional market presence and technical support capabilities.
- Faster response to changing customer requirements.
- Competitive positioning in niche packaging coating applications
- Smaller global manufacturing footprint compared with multinational competitors.
- Limited product portfolios across certain coating technologies.
- Lower investment capacity for large-scale R&D and international expansion.
- Greater dependence on regional packaging demand and customer concentration
Recent Developments
-
In June 2025, In response to the growing global demand for electric vehicles (EVs) and energy storage systems (ESS), Jotun launched advanced powder coating technologies specifically designed to enhance battery packaging. These coatings offer electrical insulation, thermal management, fire resistance, and corrosion protection, which are key to ensuring battery packs' safety, longevity, and efficiency. Traditionally, battery insulation relied on plastics and liquid paints, but Jotun’s powder coatings provide a more stable, solvent-free, and cost-effective alternative. These are applied to various battery components and enclosures to prevent thermal runaway, corrosion, mechanical damage, and critical battery performance risks.
-
In November 2023, AkzoNobel reinforced its position as a leader in the packaging coatings sector by introducing its Accelstyle line, specifically developed for the exterior of aluminum beverage cans and formulated without bisphenols, styrene, or PFAS. This launch builds on the previous debut of Accelshield 700, a BPx-NI (bisphenol non-intent) internal coating for can ends that meet both FDA and EU regulatory standards. In addition, AkzoNobel is investing significantly in a new environmentally efficient facility in Vilafranca, Spain, which will manufacture bisphenol-free coatings for the EMEA market. Set to become operational by mid-2025, this plant will increase the production of safer, lower-carbon packaging coatings and help drive the industry’s transition away from materials of concern.
Packaging Coatings Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.0 billion
Estimated market size in 2026
USD 4.1 billion
Projected market size by 2033
USD 5.2 billion
Growth rate
CAGR of 3.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Resin, packaging type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America Middle East & Africa
Country scope
U.S.; Canada; Mexico, UK; Germany; Italy; France, Spain, China; India; Japan, South Korea, Brazil, Argentina, Saudi Arabia, South Africa
Key companies profiled
Axalta Coatings; Akzo Nobel NV; BASF SE; Arkema Group; Berger Paints India Limited; Chemetall; Chugoku Marine Paints Ltd; DowDuPont; Evonik Industries AG; HEMPEL A/S; Henkel AG & Co. KGaA; Jotun; Kansai Paint Co. Ltd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
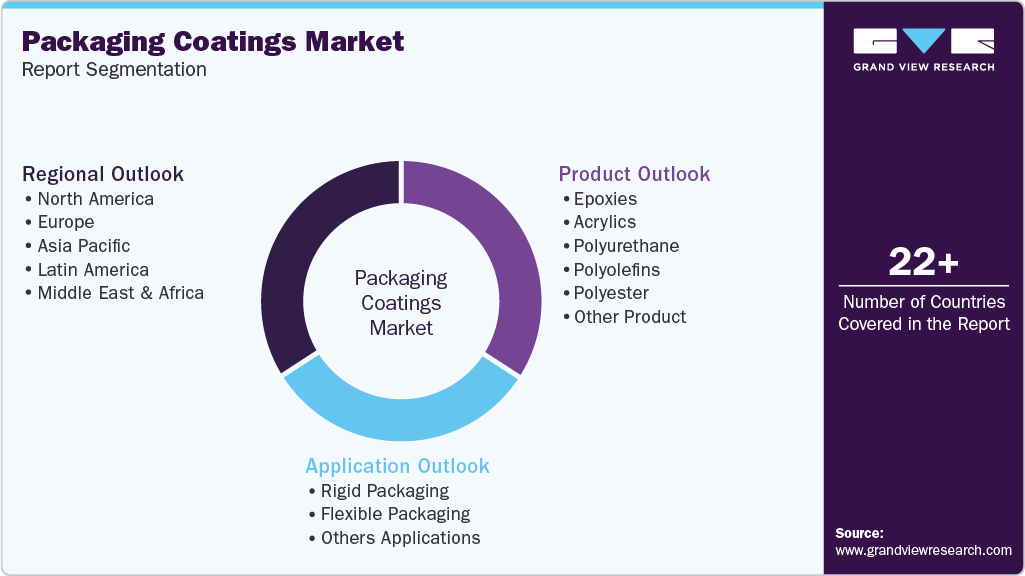
Global Packaging Coatings Market Report SegmentationThis report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global packaging coatings market report based on product, application, and region
 To learn more about this report, Download Free Sample Report
-
Resin Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Epoxies
-
Acrylics
-
Polyurethane
-
Polyolefins
-
Polyester
-
Other Product
-
-
Packaging Type Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Rigid Packaging
-
Flexible Packaging
-
Others Applications
-
-
End Use Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Food & Beverage
-
Cosmetics
-
Pharmaceuticals
-
Consumer Electronics
-
Other End Uses
-
-
Regional Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
The packaging coatings market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each packaging coatings segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Resin
Revenue capture definition
Epoxy
Revenue is generated from epoxy-based packaging coatings utilized in food and beverage cans, metal containers, closures, aerosol cans, and industrial packaging applications. Market growth is supported by excellent chemical resistance, corrosion protection, adhesion properties, and the ability to preserve product integrity throughout storage and transportation
Acrylic
Revenue is generated from acrylic packaging coatings used in metal packaging, beverage cans, closures, flexible packaging, and specialty containers. Increasing demand for coatings offering superior gloss, UV resistance, weatherability, and regulatory compliance for food-contact applications continues to support market expansion.
Polyurethane
Revenue is generated from polyurethane packaging coatings utilized in flexible packaging, metal packaging, industrial containers, and specialty packaging applications requiring high abrasion resistance, flexibility, impact strength, and chemical durability. Rising demand for premium packaging solutions and protective coatings supports market growth
Polyolefins
Revenue is generated from polyolefin-based packaging coatings used across flexible packaging films, food packaging, pharmaceutical packaging, and industrial packaging applications. Demand is supported by increasing consumption of lightweight packaging materials, moisture barrier requirements, and cost-effective packaging solutions
Polyester
Revenue is generated from polyester packaging coatings utilized in beverage cans, food containers, metal packaging, and specialty industrial packaging requiring excellent corrosion resistance, mechanical performance, and compliance with food safety regulations. Growing adoption of BPA-free coating technologies continues to drive product demand
Other Products
Revenue is generated from fluoropolymer, vinyl, alkyd, silicone, and other specialty packaging coatings utilized across food packaging, pharmaceutical packaging, industrial containers, aerosol packaging, and high-performance protective packaging applications requiring customized functional properties.
Packaging Type
Revenue capture definition
Rigid
Revenue is generated from packaging coatings applied to metal cans, beverage containers, food cans, aerosol cans, closures, drums, industrial containers, and rigid plastic packaging. Demand is supported by increasing consumption of packaged food, beverages, chemicals, paints, and pharmaceutical products requiring corrosion resistance, product protection, and extended shelf life.
Flexible
Revenue is generated from packaging coatings utilized in flexible packaging films, pouches, laminates, sachets, wraps, and multilayer packaging structures. Market growth is driven by increasing demand for lightweight packaging, improved barrier performance, product differentiation, and sustainable flexible packaging solutions across food, pharmaceutical, and consumer goods industries
End Use
Revenue capture definition
Food & Beverage
Revenue is generated from packaging coatings utilized in beverage cans, food containers, metal closures, bottle caps, and processed food packaging requiring corrosion resistance, food safety compliance, product preservation, and extended shelf life. Rising consumption of packaged food and beverages continues to support market growth
Cosmetics
Revenue is generated from packaging coatings applied to cosmetic containers, aerosol packaging, personal care bottles, jars, tubes, and premium beauty packaging requiring decorative appearance, chemical resistance, and product compatibility. Increasing demand for premium cosmetic packaging continues to drive coating consumption.
Pharmaceuticals
Revenue is generated from packaging coatings used in pharmaceutical bottles, blister packaging, aerosol containers, medical packaging, closures, and specialty healthcare packaging requiring stringent regulatory compliance, chemical resistance, and contamination protection. Growing pharmaceutical manufacturing supports market expansion
Consumer Electronics
Revenue is generated from protective packaging coatings utilized in electronic component packaging, specialty containers, transport packaging, and moisture-resistant packaging solutions designed to protect sensitive electronic products during storage and distribution
Other End Use
Revenue is generated from packaging coatings utilized across industrial chemicals, paints & coatings, lubricants, agrochemicals, household products, automotive fluids, and specialty industrial packaging requiring enhanced corrosion protection, durability, and chemical resistance
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Raw Material & Production Layer
What forms the supply base?
Assess global packaging coating production based on the availability of epoxy resins, acrylic resins, polyurethane resins, polyester resins, polyolefins, pigments, additives, curing agents, solvents, and specialty coating materials. The assessment evaluates manufacturing capacities, raw material sourcing, production technologies, formulation capabilities, and regional manufacturing hubs supporting global packaging coating supply
02
Application Adoption Layer
Where are packaging coatings consumed?
Evaluate packaging coating adoption across major packaging applications including food & beverage packaging, pharmaceutical packaging, cosmetic packaging, industrial packaging, consumer goods packaging, and specialty packaging solutions. Adoption is influenced by food safety regulations, sustainability initiatives, corrosion protection requirements, barrier performance, product aesthetics, and packaging innovation
03
Consumption Intensity Layer
How much packaging coatings is utilized?
Analyze packaging coating consumption intensity by evaluating coating loading per packaging unit, packaging production volumes, substrate types, coating technologies, product specifications, packaging formats, and end-use industry demand across global markets
04
Revenue Layer
How is market revenue generated?
Market revenue is generated through the production and commercialization of epoxy, acrylic, polyurethane, polyester, polyolefin, and specialty packaging coatings supplied to packaging manufacturers, can producers, converters, and brand owners. Revenue growth is supported by increasing demand for packaged consumer goods, sustainable packaging solutions, BPA-free coatings, food safety regulations, premium packaging, and technological advancements in coating formulations
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study provides comprehensive country-level analysis across major packaging coatings markets, evaluating production and consumption trends, manufacturing footprint, raw material availability, regulatory landscape, import-export dynamics, pricing outlook, and demand across key packaging applications including food & beverages, pharmaceuticals, personal care & cosmetics, industrial packaging, and consumer goods.
Enables stakeholders to identify high-growth regional markets, assess supply-demand dynamics, evaluate manufacturing competitiveness, optimize sourcing strategies, and prioritize expansion opportunities based on regional demand patterns and regulatory requirements.
Opportunity-Assessment
The study evaluates emerging growth opportunities driven by sustainable and BPA-NI coatings, water-based and UV-curable technologies, recyclable and mono-material packaging, food-contact compliant coatings, high-performance barrier coatings, and increasing demand from food & beverage, pharmaceutical, and personal care packaging applications. It also assesses opportunities arising from evolving environmental regulations and advancements in coating technologies.
Assists companies in identifying high-growth application areas, aligning product development with evolving regulatory and sustainability requirements, prioritizing investment opportunities, and strengthening long-term competitive advantage.
Competitive Benchmarking
The study benchmarks leading packaging coating manufacturers based on product portfolio, geographic presence, manufacturing capabilities, technology offerings, sustainability initiatives, strategic developments, and key end-use industry focus. It also evaluates competitive positioning across major regional markets.
Supports competitive intelligence by identifying market leaders, benchmarking product differentiation, evaluating strategic initiatives, and assisting companies in strengthening their competitive positioning and market expansion strategies.
Frequently Asked Questions About This Report
The Asia Pacific dominated the packaging coatings market with a revenue share of 35.9%, in 2025.
The growth is attributed to packaging coatings increasing for its application for flexible packaging coatings.
The acrylic resin segment dominated the packaging coatings market with a revenue share of 36.3% in 2025.
Food & beverage held a dominant position, contributing 45.4% of total revenue in 2025 and consumer electronic segment is expected to be the fastest-growing market.
The global packaging coatings market size was valued at USD 4.0 billion in 2025 and is estimated at USD 4.1 billion for 2026.
The global packaging coatings market is expected to grow at a CAGR of 3.4% from 2026 to 2033, reaching USD 5.2 million by 2033.
The rigid packaging coatings segment led the market and accounted for the largest revenue share of 58.5% in 2025, attributed to its preference for products that require strong protection and a higher perceived value.
Some of the key players operating in the Packaging Coatings Market include Axalta Coatings, Akzo Nobel NV, BASF SE, Arkema Group, Berger Paints India Limited, Chemetall, Chugoku Marine Paints Ltd, DowDuPont, Evonik Industries AG, HEMPEL A/S, Henkel AG & Co. KGaA, Jotun, Kansai Paint Co. Ltd.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


