
- Home
- »
- Animal Health
- »
-
Pet Dental Health Market Size And Share Report, 2026-2033GVR Report cover

Pet Dental Health Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal Type (Dogs, Cats), By Type (Products, Services), By Indication (Gum Diseases, Endodontic Diseases, Dental Calculus, Oral Tumor), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
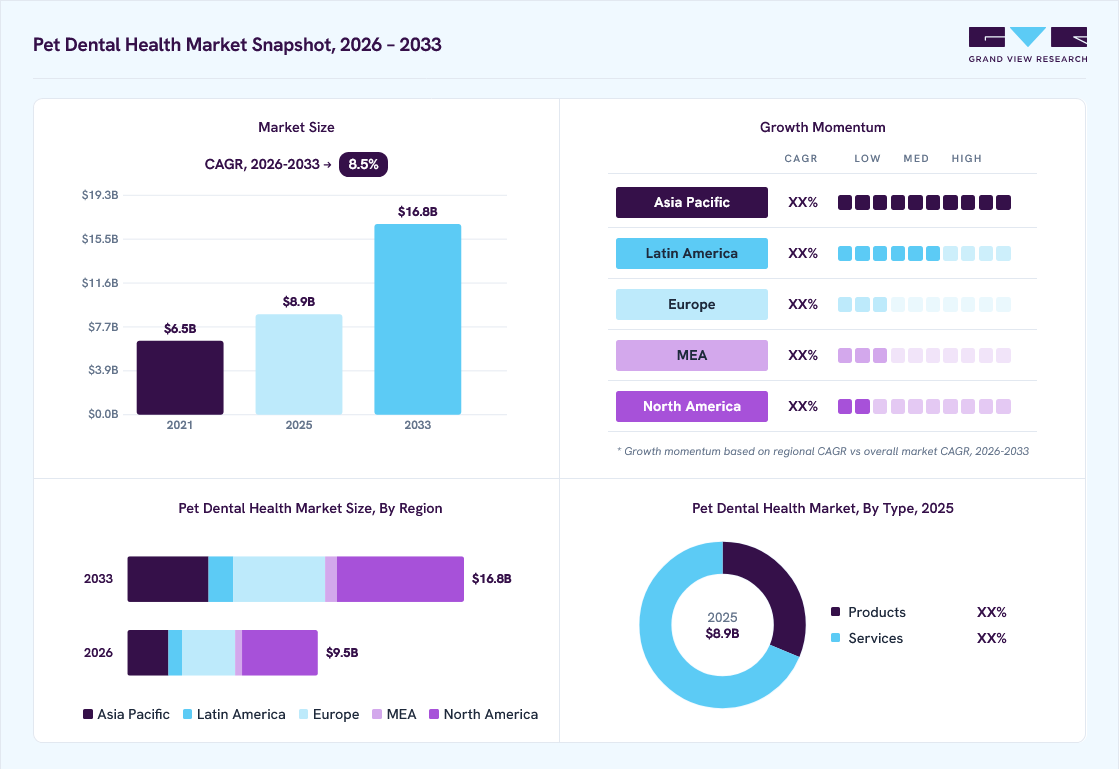
$8.9BMarket Estimate, 2026
$9.5BMarket Forecast, 2033
$16.8BCAGR, 2026–2033
8.5%Pet Dental Health Market Summary
The global pet dental health market size was valued at USD 8.9 billion in 2025 and is projected to grow from USD 9.5 billion in 2026 to USD 16.8 billion by 2033, at a CAGR of 8.5% from 2026 to 2033. North America dominated the pet dental health market with the largest revenue share of 40.1% in 2025. The market growth is driven by rising pet ownership, with increased humanization of pets and growing awareness among owners and veterinarians about the importance of oral hygiene.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal: Dogs segment held the largest market share of 58.6% in 2025.
- By type: Services segment held the largest market share of 68.7% in 2025.
- By indication: Gum diseases segment held the largest market share of 37.3% in 2025.
- By distribution channel: Veterinary hospitals segment held the largest market share of 41.3% in 2025.
Regional Highlights
- Largest regional market: North America (40.1% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 8.9 Billion
- Estimated market size in 2026: USD 9.5 Billion
- Projected market size by 2033: USD 16.8 Billion
- CAGR (2026-2033): 8.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Additionally, advancements in veterinary dental products and preventive care are fueling market growth. For instance, in January 2025, Saint Roch Veterinary launched GingiGuard, a novel, non-systemic topical treatment that effectively reduces canine periodontal disease by restoring oral microbiome balance and delaying plaque buildup for over four weeks. Field trials demonstrated strong clinical efficacy and safety. Its microbiome-focused approach may set a new standard in veterinary dental care, driving innovation and attracting joint ventures. Pet owners concerned about their pet's health are more likely to prioritize dental health and be willing to invest in products & services that support it. They need products that are effective in maintaining their pet's dental health. They are likely to be more willing to purchase products with proven effectiveness, such as those endorsed by veterinarians. Safety is a key concern for pet owners, especially when it comes to oral care products that their pets will ingest. Hence, pet owners have an increasing preference for products with natural ingredients, which has prompted market players to launch several natural ingredients-based products.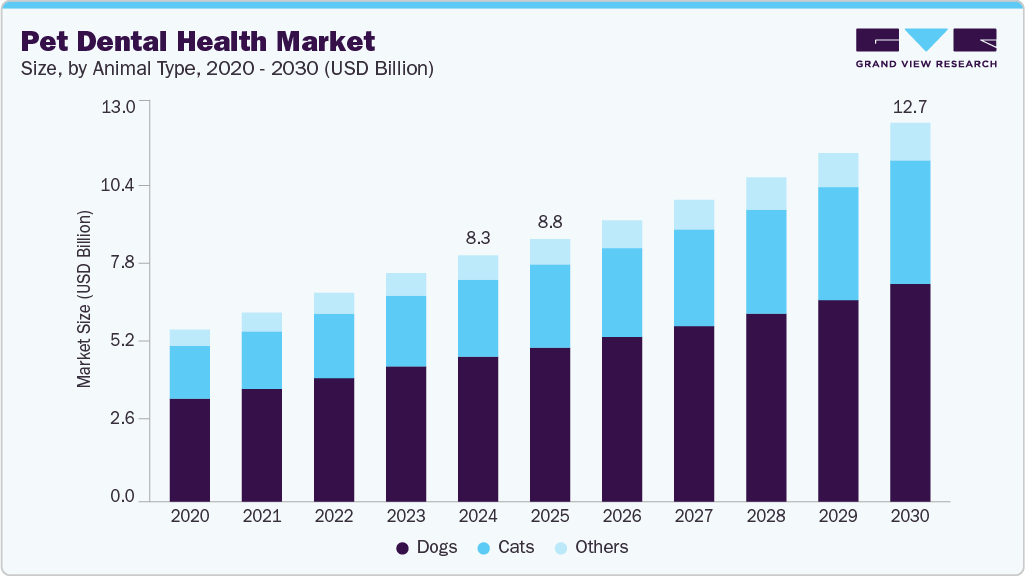 To learn more about this report, Download Free Sample Report
Dental diseases are common in companion animals such as dogs and cats. According to the Banfield Pet Hospital report, over 70% of dogs and 60% of cats seen in 2023 had dental diseases, with small breeds and certain states showing the highest prevalence. The findings underscore links between oral and systemic health and stress the need for responsible veterinary dental care. Small dog breeds like Beagles, Chihuahuas, and Dachshunds showed the highest rates of periodontal disease, which is linked to severe conditions like kidney and heart disease. This data highlights a widespread need for preventive dental care and advanced treatment options, driving demand for effective, breed-specific, and regionally tailored solutions. It also encourages innovation in antimicrobial stewardship and supports growth in the pet dental services and product markets.
Similarly, dental conditions such as periodontitis are the leading causes of tooth loss in equine species, with disease prevalence ranging from 35% to 85% of the horse population. Furthermore, proactive animals such as dogs, horses, and cats are commonly prone to a variety of traumatic dental injuries, leading to fractured teeth (prevalence 10%-27%) and tooth loss. Most of these dental indications are reversible at early stages with timely treatments, so the requirement for dental care products and dental treatment services is growing. These factors are driving the growth of the pet dental health industry.
The pet population has been significantly rising over the years in various regions. Most common pet animals, such as dogs and cats, are valued for providing companionship to humans. Pets have become a part of each household due to their various benefits, such as psychological comfort, stress reduction & depression among adults, and helping overcome anxiety in humans. Such factors have increased pet ownership and pet humanization in various countries. A 2023-2024 survey report published by the American Pet Products Association estimated that 65.1 million households in the U.S. own dogs and 46.5 million households own cats. The FEDIAF 2024 report suggested that the region had 129 million cats and 106 million dogs as of 2024. Thus, the constantly rising pet population and growing adoption of dogs & cats are among the key drivers of market growth.
Market Dynamics
The pet dental health market is experiencing significant growth, driven by increasing pet ownership, rising awareness of companion animal oral health, and growing expenditure on preventive veterinary care. The high prevalence of periodontal disease, gingivitis, dental calculus, and tooth loss among dogs and cats is encouraging routine dental checkups and greater adoption of oral care products, professional cleaning services, and advanced dental procedures. In addition, technological advancements in veterinary dentistry, including digital dental radiography, minimally invasive dental equipment, laser dentistry, and specialized oral care formulations, are improving diagnostic accuracy and treatment outcomes. For instance, Mars Pet Nutrition is advancing pet oral healthcare through microbiome-based formulations, AI-powered dental assessment tools such as GREENIES Canine Dental Check, and science-supported dental chews, promoting early disease detection, preventive care, and improved owner awareness of periodontal health.
The market is also witnessing expanding availability of premium dental chews, enzymatic toothpastes, water additives, and veterinarian-recommended preventive products is supporting its growth. However, limited pet owner awareness in developing regions, high costs associated with advanced dental procedures, and low compliance with routine oral hygiene remain key challenges. However, increasing humanization of pets and expanding veterinary dental services are expected to create substantial growth opportunities throughout the forecast period.
Increasing awareness of preventive pet oral healthcare is a major driver of the pet dental health market. Veterinary organizations and animal health companies are actively educating pet owners about the importance of maintaining oral hygiene to prevent periodontal disease, gingivitis, tooth loss, and other systemic health complications. For instance, in February 2026, Tartar Shield launched the "Second Smile" initiative in partnership with the Humane Society of Tampa Bay, providing preventive dental care products, lifetime oral health support, and adoption resources to over 120 shelter dogs, promoting early preventive dentistry and improving long-term canine oral health outcomes.
As dental disease is among the most common conditions affecting companion animals, routine dental examinations, professional cleanings, and daily oral care practices are becoming integral components of preventive veterinary medicine. In addition, growing pet humanization has encouraged owners to invest in premium dental products such as enzymatic toothpastes, dental chews, oral rinses, water additives, and dental diets that promote long-term oral health. Furthermore, advancements in veterinary dentistry, increasing availability of specialized dental services, and AI-enabled oral health assessment tools are improving early disease detection and treatment outcomes. These factors are driving greater adoption of preventive dental care products and services, supporting sustained market growth globally.
The high cost of advanced veterinary dental procedures is a significant restraint limiting growth in the pet dental health market. Some of the treatments such as professional dental cleaning, dental radiography, root canal therapy, periodontal surgery, and tooth extractions often require specialized equipment, trained veterinary dentists, anesthesia, and post-operative care, substantially increasing overall treatment costs. in addition, many pet owners, particularly those without pet insurance or with limited disposable income, postpone or decline recommended dental procedures due to affordability concerns. As a result, oral diseases frequently progress to advanced stages, requiring more complex and expensive interventions. Smaller veterinary clinics may also hesitate to invest in advanced dental equipment because of high capital costs and uncertain patient volumes. Although the availability of pet insurance and wellness plans is gradually improving access to dental care, cost remains a major barrier to routine preventive dentistry and advanced oral treatments, restricting wider market penetration and delaying timely management of companion animal dental diseases.
The market is witnessing continuous innovation in pet dental technologies represents a significant growth opportunity. Some of the manufacturers are introducing AI-powered oral health assessment tools, microbiome-based dental formulations, advanced dental imaging systems, laser dentistry, and next-generation preventive oral care products to improve early diagnosis and treatment outcomes. In addition, smart digital platforms that enable pet owners to monitor oral health remotely are enhancing preventive care and increasing veterinary consultations. For instance, in June 2026, Prodogi launched the first slow-dissolving oral health strip for dogs, using liposomal controlled-release technology to deliver full-mouth coverage, significantly reducing oral bacteria, plaque, and bad breath while improving periodontal disease prevention compared to conventional dental supplements.
Furthermore, companies are also investing in scientifically formulated dental chews, water additives, enzymatic toothpastes, and postbiotic-based oral care products that target plaque, tartar, and periodontal disease more effectively. These innovations improve treatment accessibility while encouraging routine oral hygiene practices among pet owners. As veterinary clinics continue adopting advanced dental equipment and manufacturers launch clinically validated oral healthcare solutions, technology-driven product development is expected to expand market penetration, improve patient outcomes, and create new revenue opportunities for companies operating in the global pet dental health market.
Market Concentration & Characteristics
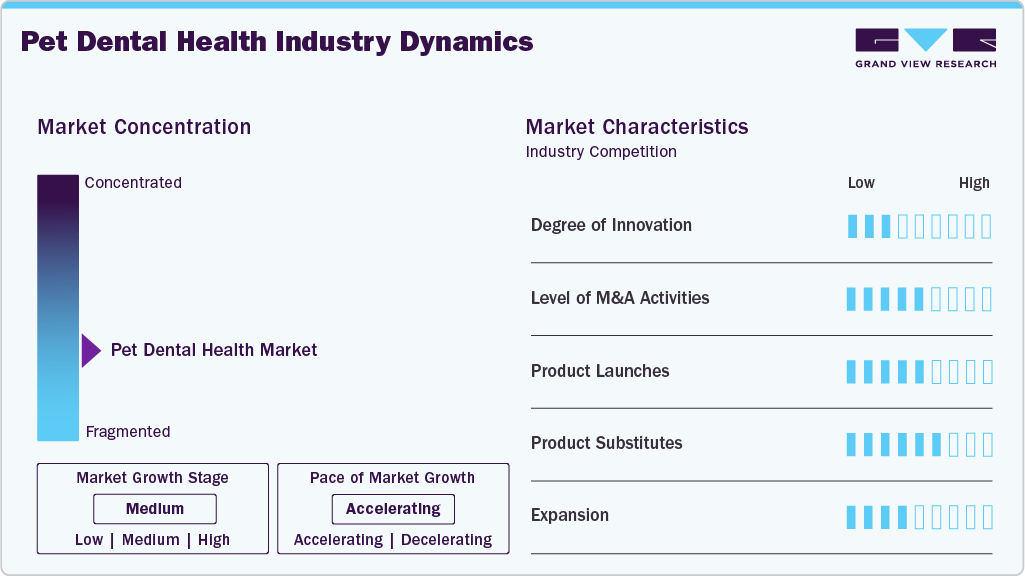
The pet dental health market is highly concentrated. The market is in a moderate growth stage, and the rate of expansion is rapidly increasing. Industry leaders like Colgate-Palmolive Company, Dechra Pharmaceuticals plc, Nestlé Purina Pet Care, Vetoquinol SA, Ceva Sante Animale, Heska Corporation (Mars Inc.), Merrick Pet Care, BarkBox, etc. are undertaking strategies, such as the launch of new products, partnerships, and mergers and acquisitions to gain a greater share of the market. For instance, in March 2024, Purina DentaLife launched its new Puppy Teething Chews by hosting the Puppy Smiles Gallery in New York City. The event highlighted the importance of early dental care for puppies, with DentaLife offering free samples of its teething chews designed to support healthy brain, tooth, and bone development. This initiative emphasizes the growing focus on pet dental health within the pet care market.
The pet dental health industry is experiencing a high degree of innovation, with brands continuously developing advanced products to address common oral health issues in pets. Innovations include dental chews with unique textures and shapes designed to effectively clean teeth and gums, natural ingredients that target plaque and tartar, and enhanced formulations incorporating herbs and postbiotics for improved breath and oral microbiome balance. This focus on innovation is driven by the increasing awareness of pet oral health and the demand for convenient, practical solutions. For instance, in March 2024, NPIC launched Flossta by N-Bone, a dental chew for dogs with a floss-like structure to clean teeth and gums in difficult-to-reach areas. It is formulated with natural herbs like parsley and fennel and is available in chicken, beef liver, and mint flavors. This product reflects NPIC's commitment to innovative pet care solutions, enhancing oral health with a unique design and natural ingredients, contributing to the market growth.
 To learn more about this report, Download Free Sample Report
The market is also characterized by a strategy to acquire resources such as facilities, capabilities, labor, equipment, or product/service portfolios to boost their market position & revenue. These initiatives may be implemented to expand regionally or widen the global network to reach more customers. For instance, in February 2024, Targeted PetCare (TPC) acquired Pet Brands, enhancing its pet treat portfolio with new sourcing, design, and packaging capabilities. This acquisition strengthens TPC's position in the pet consumables market, particularly in natural dog and cat treats, including dental chews, reflecting the growing focus on pet dental health within the industry.
The market is price-sensitive, and companies offer customers the right balance of quality and affordability to increase sales. Although established manufacturers such as Virbac, Dechra Pharmaceuticals, Colgate, and Nestlé Purina have a strong customer base and portfolio, the emergence of new and niche players poses significant competition. The availability of cheaper alternatives from manufacturers and traders in countries including China & India increases the competition with existing market players.
Product launches in the pet dental health market drive growth by introducing innovative solutions catering to rising consumer demand for effective and convenient dental care products. New products, such as dental chews, powders, and treats, help in preventing common issues like plaque, tartar buildup, and periodontal disease, which are prevalent concerns among pet owners. These launches also enhance market competition, leading to further advancements in product formulations, ingredients, and delivery methods, ultimately expanding the market's scope and reach. For instance, in February 2024, Stella & Chewy's introduced Dental Delights, a new line of dental treats designed to help control plaque and tartar while providing an engaging and fun experience for dogs. Similarly, in February 2024, Blue Buffalo introduced a new dental chew for dogs, featuring a patented design with 50 ridges and grooves that help clean teeth, support gum health, and freshen breath. Made with natural ingredients, including real chicken and spearmint flavor, these chews are designed to prevent periodontal disease, reflecting the growing demand for effective pet dental health solutions.
The increase in product expansions within the pet dental health industry significantly drives market growth. New product launches, such as size-specific dental treats and innovative formulations, address diverse consumer needs and enhance oral care for pets of various sizes. This expansion broadens product offerings and caters to rising consumer awareness about the importance of dental health in pets, leading to increased adoption and market penetration. For instance, in March 2024, PetIQ, Inc. expanded its Minties dental treats line by introducing a new option specifically for large-sized dogs. These veterinarian-recommended treats are designed to freshen breath and promote oral health with natural ingredients like alfalfa and peppermint. The expansion reflects the growing demand for effective, affordable solutions for different dog sizes in the market.
Analyst Perspective
The pet dental health market is experiencing steady growth, driven by rising pet humanization and growing awareness of oral hygiene and overall animal wellness. Increasing veterinary emphasis on preventive dental care, along with the prevalence of periodontal disease in cats and dogs, is driving demand for dental chews, enzymatic toothpaste, water additives, and specialized diets. Premium and natural formulations are gaining traction, while e-commerce and subscription models are improving accessibility. Growing veterinary recommendations, pet insurance coverage, and disposable incomes are further supporting demand. Competitive intensity is also increasing as established companies and startups invest in R&D to improve product efficacy, palatability, and long-term compliance.
Animal type Insights
Based on animal, the dogs segment led the market with the largest revenue share of 58.6% in 2025. This is attributed to the growing preference for dogs as companion animals. According to the 2024 APPA National Pet Owners Survey, 82 million U.S. households own a pet. Among them, 58 households have at least one dog, making dogs the most popular pet in the U.S. By 2030, this number is projected to exceed 100 million. Thus, the increasing population of pet dogs in several key countries is expected to contribute to the demand for pet dental health products and services.
As pet owners become more aware of the importance of dental care for their dogs, the demand for products and services that support oral hygiene continues to increase. For instance, there has been an increase in demand for professional dental cleaning services. Veterinary clinics and pet dental specialists offer more dental services, including cleanings, X-rays, and oral surgery. Pet owners are also becoming more aware of the link between good dental health and overall health in dogs, which is estimated to propel the market in the coming years.
Type Insights
Based on type, the services segment led the market with the largest revenue share of 68.7% in 2025. This is due to the wide-scale availability of multiple dental care, diagnosis, and treatment alternatives offered by veterinary clinics. Since oral health significantly impacts a pet's overall health and behavior, routine annual dental exams for pets are crucial. The key to controlling dental issues is prevention; therefore, it is essential to consistently brush and clean the pet's teeth to prevent plaque development. The American Animal Hospital Association advises routine oral checkups and dental cleanings to reduce tartar & prevent gum diseases.
The increasing frequency of veterinary dental checkups and procedures performed in response to increased dental illness in companion animals is predicted to fuel this segment. Root canal therapy typically preserves the dog's tooth for life and is less invasive than extraction. A tooth with strong periodontal support can also be extracted as a different alternative. In addition, surgery is the recommended course of action for pet dental care to remove growths, fix jaw fractures, and remove oral tumors.
The need for canine tooth extractions is relatively common and may arise for various reasons. Sometimes a fractured tooth suffers permanent damage. In other situations, it could be necessary to extract a tooth with severe decay to stop infections and further dental decay. Once an affected tooth is extracted and the surrounding area is cleaned of infectious debris, the dog should be free of infection.
Indication Insights
Based on indication, the gum diseases segment led the market with the largest revenue share of 37.3% in 2025. The most common condition in cats and dogs is gum disease. It is a progressive, cyclical inflammatory disorder of dental structural supports that causes dental disease & premature tooth loss. Furthermore, these disorders may result in major health problems if left untreated, such as organ failure. According to the AVMA, about 70% of cats and 80% of dogs experience some form of periodontal disease by the age of 3 years. The rising incidence of various oral health-related illnesses has been identified as the primary factor promoting market growth.
The dental calculus segment has the fastest CAGR during the forecast period. Calculus and gingivitis are the most common dental problems in pets. According to the DSM pet owner study, only 16% of dog owners brush their pets' teeth daily. As a result, pet products that give a comprehensive approach to oral care, such as breath fresheners, water additives, dental treats, and dental wipes, are in high demand. A pet's oral health can also be improved by regular veterinary examinations and preventative treatment given at home. As a result, the key driver of market growth has been identified as the rising prevalence of various conditions associated with oral health.
Distribution Channel Insights
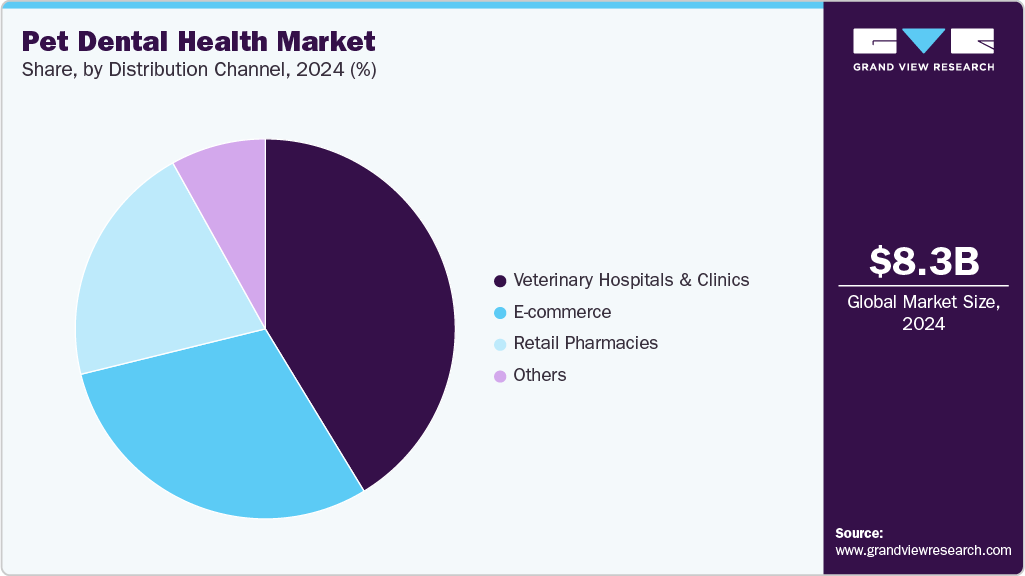
Based on distribution channel, the veterinary hospitals segment led the market with the largest revenue share of 41.3% in 2025. This is attributed to the increase in veterinary hospitals and clinics with innovative infrastructures worldwide. Veterinary clinics and hospitals are crucial for the appropriate care of a pet's teeth since they provide expert dental services to qualified veterinary dentists. The increasing number of veterinary experts is another factor driving the segment. The AVMA estimated that 127,131 veterinarians operated in the U.S. in 2023. Furthermore, according to the Canadian Veterinary Medical Association, there were approximately 15,459 veterinarians in Canada in 2023, with approximately 3,825 of them working in clinical practice. This increases demand for veterinary services, such as preventative care, medical treatment, surgery, etc.
 To learn more about this report, Download Free Sample Report
Changing customer shopping behaviors, specifically the shifting trend toward online shopping due to the COVID-19 pandemic & digitalization, have altered nearly all products, including pet dental health services & products. It is accepted and commonly discussed that retail stores undertake fewer retail transactions for goods and pharmaceuticals than they previously did. For instance, for dogs, cats, and other pets, specialty foods & other dental foods, in general, were purchased by a high percentage of animal owners at a physical store. Several E-commerce websites are widely contributing to the growth of the market. With an increasing number of families having companion animals, there is a greater demand for easy access to pet oral care supplies. Numerous brands of dental care diets, toothbrushes, chews, wipes, snacks, rinses, oral care water additives, pastes, and other products are available for use in pet dental care.
Regional Insights
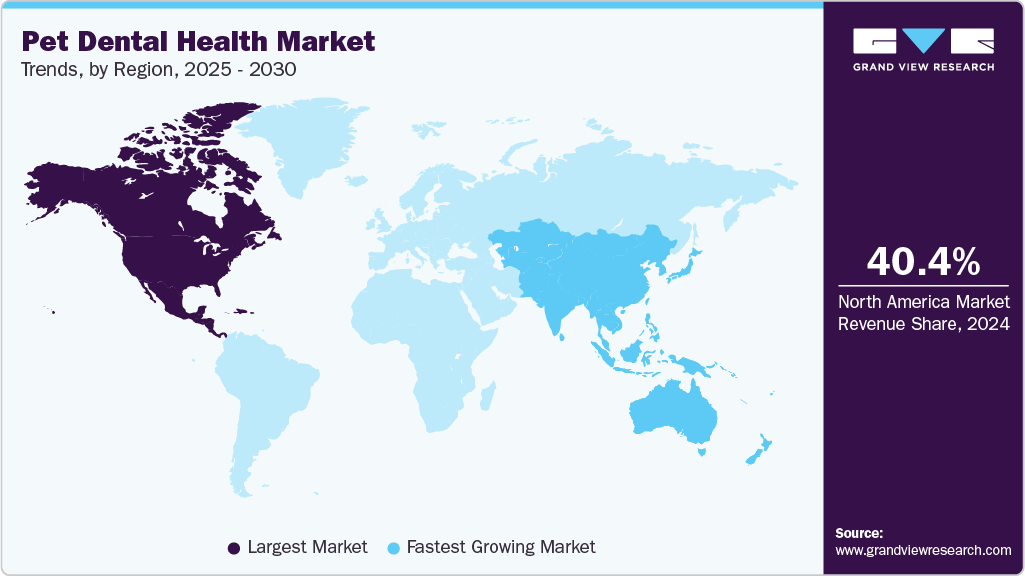
North America dominated the pet dental health market with the largest revenue share of 40.1% in 2025. The increased prevalence of a variety of oral health-related disorders has been highlighted as a significant driver of market growth. The American Pet Product Association (APPA) estimates that in 2023-24, the number of households that owned a pet was 65.1 million in the U.S. Furthermore, pet owners' increased knowledge of pet health and an increase in the number of dental operations are driving the market growth. In addition, the COVID-19 pandemic led to a surge in pet adoptions and ownership, further boosting the market growth. With more people spending time at home and seeking companionship, the demand for pets increased.
 To learn more about this report, Download Free Sample Report
U.S. Pet Dental Health Market Trends
The pet dental health market in the U.S. held the largest share in the North America region in 2025, due to the growing need to mitigate unexpected veterinary costs, the penetration of pet insurance, and the increasing medicalization rate. For instance, as per the North American Pet Health Insurance Association, about 5.7 million pets were insured in the U.S. in 2023. Leading insurance companies, such as Trupanion, announced in February 2023 that pet insurance enrollments in their organization reached 1.54 million as of December 31, 2022. This represented a growth of 31% over the previous year. Pet owners are adopting insurance facilities to reduce their out-of-pocket expenditure for various dental diseases and their respective medications. For instance, in the case of pet dental insurance, companies such as ASPCA, Trupanion, Nationwide, Lemonade, Healthy Paws, Embrace, Petplan, and Fetch by the Dodo cover both dental illnesses & dental accidents for companion animals.
Europe Pet Dental Health Market Trends
The Europe pet dental health industry is experiencing significant growth driven by increasing awareness among pet owners about the importance of oral hygiene for pets. Key trends include the rising demand for specialized dental products, such as toothbrushes, dental chews, and water additives. Opportunities are emerging in the development of innovative, vet-approved dental care solutions and the expansion of services like professional dental cleanings at veterinary clinics. Additionally, there is growing interest in natural and eco-friendly dental products, reflecting broader consumer preferences.
In Europe, pet dental disease is highly prevalent, with studies revealing significant concerns across various countries. In the UK, 12.5% of dogs suffer from dental disease, with breeds like Greyhounds and King Charles Spaniels being the most affected. In the Czech Republic, 85.3% of dogs at a private veterinary hospital exhibited dental issues, including periodontitis and missing teeth. In Spain, 30.9% of cats at a veterinary teaching hospital were diagnosed with periodontal disease. This widespread prevalence underscores the urgent need for effective pet dental health products and services across Europe.
The Germany pet dental health market held the largest share of Europe in 2024. Germany has a vast number of companion animals in Europe. A recent report by the Central Association of Zoological Specialist Companies (ZZF) stated that in 2023, 45% of German households owned at least one pet. Cats remained the most popular pets, residing in 25% of homes, and dogs followed closely with 21% of households. Based on a survey of 5,000 households conducted by Skopos for the Pet Supplies Industry Association (IVH) eV and ZZF, the report indicated that pets are a significant part of German life. Additionally, the prevalence of pet dental diseases in Germany is a significant concern. According to various studies, around 70% to 85% of dogs and 60% to 70% of cats above the age of 3 years have active gum disease. This indicates the country's potential need for pet dental health products.
The pet dental health market in the UK is expected to grow rapidly due to increased awareness among pet owners about pet dental health and a growing number of veterinary experts in the country. According to new claims data from Co-op Insurance, untreated pet dental diseases can cost UK pet owners up to £962 (USD 1,261.6) in vet expenses, demonstrating the financial effect of poor canine dental hygiene. Over 42% of dog and cat owners list dental difficulties as one of the most common causes for vet appointments, while roughly 19% have postponed care due to growing prices. Popular breeds, such as Cocker Spaniels and Labradors, are the most susceptible to dental claims. Thus, increasing awareness of costly dental problems is driving the market growth, with a focus on preventive care and products like dental chews. Furthermore, due to the rising incidence of dental disease, veterinary clinics have started offering comprehensive dental care services such as regular checkups and professional cleanings. For example, The London Cat Clinic uses modern diagnostic and treatment strategies to address the rising prevalence of feline dental diseases in the UK. This increase in initiatives by veterinary care providers in the UK is likely to drive market growth.
Asia Pacific Pet Dental Health Market Trends
The Asia Pacific pet dental health industry is anticipated to witness significant growth during the forecast period. The growing demand for pet care in developed and emerging countries in the Asia Pacific is expected to drive the overall market during the forecast period. Market players adopt various strategic initiatives such as new product launches, partnerships, acquisitions, mergers, and collaborations to improve their market positions. For instance, the new Pedigree Dentastix chewy chunk from Mars Petcare was introduced to stop plaque buildup throughout the day. The company also plans to provide the same product in beef and chicken tastes with a maxi or mini choice for bigger & smaller dogs.
The pet dental health market in India is witnessing notable growth due to increasing awareness among pet owners to preserve their pets’ oral health. This increased knowledge is driving demand for pet dental care products in India. Companies are introducing creative and advanced goods, like dental chews, sprays, and wipes, to cater to pet owners who are concerned about their pets' oral health. As an example of the growing demand for pet dental care products in the region, Virbac Animal Health India recently launched a new range of dental chews and oral hygiene products for dogs and cats. This launch is indicative of the increasing efforts of companies to cater to the growing demand for pet dental care products in the country.
Latin America Pet Dental Health Market Trends
The Latin America pet dental health industry is growing steadily, driven by increasing pet ownership and rising awareness of pet health and wellness. More pet owners are recognizing the importance of dental care, leading to higher demand for dental products like toothbrushes, dental chews, and oral rinses. Veterinary clinics are also expanding their dental care services, further contributing to market growth. The market is poised for continued expansion as education on the impact of dental health on overall pet well-being spreads throughout the region.
Middle East & Africa Pet Dental Health Market Trends
The Middle East & Africa pet dental health industry is witnessing gradual growth, driven by increasing pet ownership and a growing focus on pet health. Key trends include rising demand for pet dental care products, such as dental chews and specialized toothpaste, particularly among urban pet owners. Veterinary clinics are expanding their services to include dental care, reflecting a broader awareness of the importance of oral hygiene in pets. However, the market is still in the early stages of development, with opportunities for growth in education and the availability of advanced dental care products.
The Saudi Arabia pet dental health market is expected to grow over the forecast period. The pet population in Saudi Arabia is growing rapidly, driven by factors such as increasing pet humanization, rising disposable income, and raising awareness about animal health. Pet owners in Saudi Arabia are becoming more aware of the importance of dental health in their pets, leading to an increase in demand for pet dental care products and services.
Key Pet Dental Health Company Insights
Key players in the pet dental health market are actively engaged in highly competitive market dynamics. Companies focus on innovation, introducing advanced dental products like enzymatic toothpaste, dental wipes, and chew toys with dual-action cleaning features.
Key Pet Dental Health Companies:
The following key companies have been profiled for this study on the pet dental health market.
-
Virbac
-
Colgate-Palmolive Company
-
Dechra Pharmaceuticals plc
-
Petzlife Products
-
imrex
-
Nestlé Purina Pet Care
-
Vetoquinol SA
-
Ceva Sane Animale
-
TropiClean Pet Products
-
Basepaws, Inc (Zoetis)
-
Dentalaire, International.
-
Midmark Corporation.
-
Heska Corporation (Mars Inc.)
-
Merial (Boehringer sub)
-
BarkBox
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Virbac, Colgate-Palmolive Company, Dechra Pharmaceuticals plc)
- Mature players strengthen their market position by offering comprehensive pet dental health portfolios comprising oral care products, dental equipment, medicines, and professional services. They invest in product innovation, veterinary partnerships, clinical validation, and consumer education to promote preventive oral care. Strategic acquisitions, geographic expansion, omnichannel distribution, and premium product positioning enable wider market penetration, while continuous research and development supports long-term competitiveness and sustained revenue growth.
- Mature companies benefit from strong brand recognition, extensive distribution networks, diversified product portfolios, and established relationships with veterinarians and pet care providers. Significant investments in research, product innovation, regulatory compliance, and marketing enable consistent product quality and customer trust. Global manufacturing capabilities, robust supply chains, and comprehensive after-sales support further strengthen their position across preventive and therapeutic pet dental health segments.
- Mature players often face slower innovation cycles due to complex organizational structures and extensive regulatory processes. Premium pricing strategies may limit adoption in price-sensitive markets, while maintaining broad product portfolios increases operational complexity and costs.
Emerging Players (BarkBox, TropiClean Pet Products, and other regional pet hygiene brands)
- Emerging players focus on introducing innovative, affordable, and easy-to-use pet dental care products tailored to companion animal owners. They leverage e-commerce platforms, direct-to-consumer sales, subscription models, and partnerships with veterinary clinics to expand market reach. Investments in natural ingredients, veterinarian-endorsed formulations, sustainable packaging, and consumer education campaigns help strengthen brand awareness, improve customer engagement, and establish credibility in the competitive pet oral healthcare market.
- Emerging companies gain a competitive advantage through product innovation, niche formulations, premium natural ingredients, and digitally driven marketing strategies. Their agility enables faster product development, customization for breed-specific or age-specific needs, and rapid response to evolving consumer preferences. Strong online presence, personalized customer experiences, subscription services, and competitive pricing further differentiate emerging brands, allowing them to capture market share despite competition from established veterinary healthcare companies.
- Emerging players often face challenges including limited brand recognition, constrained financial resources, smaller distribution networks, and lower customer trust compared with established pet healthcare brands.
Recent Developments
-
In January 2025, Saint Roch Veterinary launched GingiGuard, a novel, non-systemic topical treatment that effectively reduces canine periodontal disease by restoring oral microbiome balance and delaying plaque buildup for over four weeks. Field trials demonstrated strong clinical efficacy and safety.
-
In July 2024, Pet Honesty launched Fresh Breath Dental Powder, a meal-time supplement designed to improve dogs' oral health by freshening breath, reducing plaque, and supporting gum health. This innovative product, featuring natural ingredients and postbiotics, reflects the growing demand for effective and convenient dental care solutions.
-
In May 2023, Virbac, a global animal health company, acquired a distributor in the Czech Republic and Slovakia. This acquisition will allow Virbac to expand its presence and strengthen its position in the Central European market.
Pet Dental Health Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.9 billion
Estimated market size in 2026
USD 9.5 billion
Projected market size by 2033
USD 16.8 billion
Growth rate
CAGR of 8.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Animal, type, indication, distribution channel and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
Virbac; Colgate-Palmolive Company; Dechra Pharmaceuticals plc; Petzlife Products; Imrex; Nestlé Purina Pet Care; Vetoquinol SA; Ceva Sane Animale; TropiClean Pet Products; Basepaws, Inc. (Zoetis); Dentalaire; International; Midmark Corporation; Heska Corporation (Mars Inc.); Merial (Boehringer sub); BarkBox
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pet Dental Health Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pet dental health market report based on animal type, type, indication, distribution channel, and region:
-
Animal type Outlook (Revenue, USD Million, 2021 - 2033)
-
Dogs
-
Cats
-
Others
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Products
-
Oral Care Products
-
Toothpastes & brushes
-
Oral care solutions
-
Dental Treats
-
Dental Chews
-
Dental Powder
-
Others
-
-
Medicines
-
Equipment
-
-
Services
-
Diagnosis
-
Treatment
-
Dental Cleaning
-
Surgery
-
Root Canal Therapy
-
Others
-
-
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Gum Diseases
-
Endodontic Diseases
-
Dental Calculus
-
Oral Tumor
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Retail Pharmacies
-
E-commerce
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
Rest of EU
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
Rest of APAC
-
-
Latin America
-
Brazil
-
Argentina
-
Rest of LA
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Rest of MEA
-
-
Research Methodology
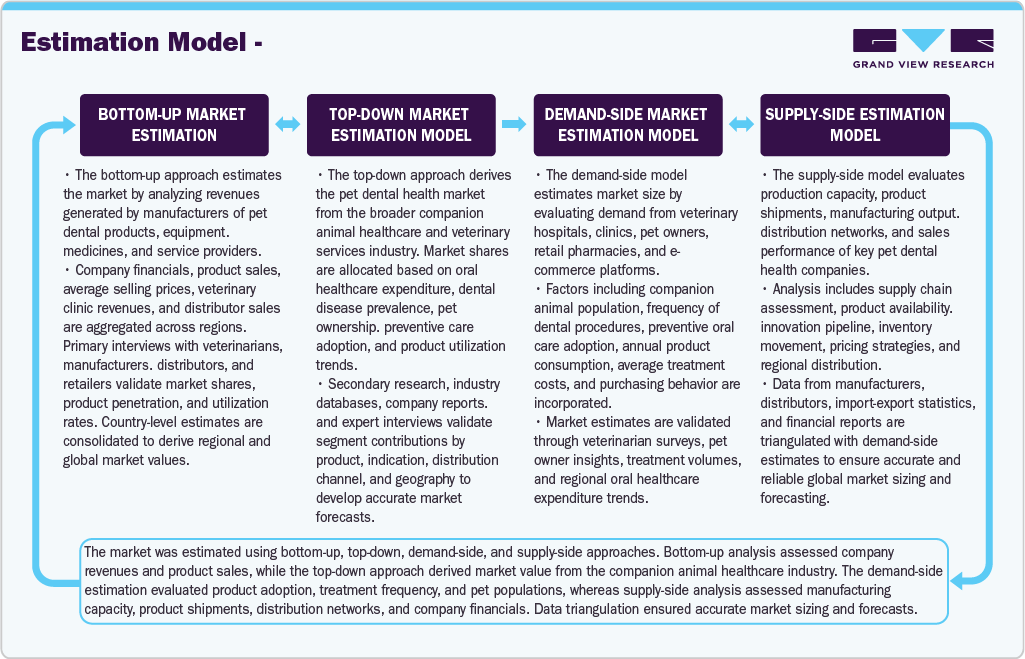
The pet dental health market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pet dental health segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Animal
Revenue Capture Definition
Dogs
Includes canine dental health products, diagnostics, treatments, and preventive care addressing periodontal disease, plaque accumulation, tooth fractures, oral infections, and routine dental maintenance throughout all life stages.
Cats
Covers feline oral healthcare products and veterinary services focused on managing periodontal disease, gingivitis, tooth resorption, dental calculus, oral infections, and preventive oral hygiene for companion cats.
Others
Includes rabbits, ferrets, rodents, birds, and exotic companion animals receiving specialized dental healthcare products and veterinary dental treatments for species-specific oral conditions and preventive care.
Segment - Type
Revenue Capture Definition
Products
Includes preventive oral healthcare products such as toothpastes, toothbrushes, dental chews, oral rinses, powders, and other formulations designed to maintain oral hygiene and reduce dental disease.
Oral Care Products
Comprises daily oral hygiene products formulated to prevent plaque, tartar, gingivitis, bad breath, and periodontal disease while promoting long-term dental health in companion animals.
Toothpastes & Brushes
Includes pet-specific toothbrushes and enzymatic toothpastes designed for routine plaque removal, tartar prevention, gum protection, and maintaining optimal oral hygiene through regular home-based dental care.
Oral Care Solutions
Covers liquid rinses, water additives, gels, sprays, and antimicrobial solutions formulated to reduce oral bacteria, improve breath freshness, and support daily dental hygiene in companion animals.
Dental Treats
Includes edible treats formulated with ingredients and textures that mechanically reduce plaque and tartar buildup while promoting healthier gums and supporting routine preventive oral care.
Dental Chews
Comprises chewable products designed to mechanically clean teeth, reduce plaque accumulation, strengthen gums, freshen breath, and encourage daily dental maintenance through natural chewing behavior.
Dental Powder
Includes powdered oral care formulations added to pet food to reduce plaque, tartar, and oral bacteria while improving breath freshness and supporting routine preventive dental care.
Others
Includes dental wipes, oral gels, dental toys, finger brushes, mouth sprays, and innovative oral hygiene products designed to support comprehensive preventive dental care for companion animals.
Medicines
Covers prescription and over-the-counter pharmaceuticals including antibiotics, anti-inflammatory drugs, pain management medications, and antimicrobial agents used to treat dental infections and oral diseases.
Equipment
Includes veterinary dental equipment such as ultrasonic scalers, dental radiography systems, polishing units, anesthesia equipment, extraction instruments, and surgical tools supporting advanced veterinary dentistry procedures.
Services
Comprises professional veterinary dental services including diagnosis, preventive cleaning, periodontal therapy, oral surgery, restorative procedures, and specialized treatment of companion animal dental disorders.
Diagnosis
Includes oral examinations, dental radiography, periodontal assessments, imaging, and diagnostic procedures performed to identify dental diseases, structural abnormalities, infections, and treatment requirements in pets.
Treatment
Covers therapeutic interventions addressing periodontal disease, infections, fractured teeth, oral pain, and other dental disorders through medical, restorative, and surgical veterinary procedures.
Dental Cleaning
Involves professional scaling, polishing, plaque removal, tartar elimination, and preventive periodontal care performed under veterinary supervision to maintain optimal oral health and prevent disease progression.
Surgery
Includes tooth extractions, periodontal surgery, oral tumor removal, jaw reconstruction, and other surgical procedures performed to treat advanced dental and oral diseases in companion animals.
Root Canal Therapy
Refers to endodontic procedures preserving damaged teeth by removing infected pulp, disinfecting root canals, and restoring tooth function while avoiding unnecessary extractions in companion animals.
Others
Includes orthodontic procedures, restorative dentistry, prosthodontics, laser dentistry, oral rehabilitation, and specialized veterinary dental treatments addressing complex oral health conditions.
Segment - Indication
Revenue Capture Definition
Gum Diseases
Includes gingivitis and periodontal diseases affecting gums and supporting tooth structures, requiring preventive care, professional cleaning, medication, and surgical treatment to preserve oral health.
Endodontic Diseases
Covers diseases affecting tooth pulp and root canals, including pulpitis, infections, fractures, and abscesses requiring root canal therapy, extraction, or restorative veterinary dental procedures.
Dental Calculus
Refers to hardened plaque deposits accumulating on teeth, increasing the risk of periodontal disease, gingivitis, bad breath, and requiring professional scaling and preventive oral hygiene management.
Oral Tumor
Includes benign and malignant tumors affecting oral tissues, gums, tongue, or jaw, requiring diagnostic evaluation, biopsy, surgical removal, and supportive veterinary oncology management.
Others
Covers tooth fractures, malocclusion, oral trauma, stomatitis, developmental abnormalities, retained deciduous teeth, and miscellaneous dental disorders requiring veterinary diagnosis and treatment.
Segment - Distribution Channel
Revenue Capture Definition
Veterinary Hospitals & Clinics
Includes veterinary practices providing professional dental diagnosis, treatment, preventive care, surgical services, and dispensing oral healthcare products and prescription medications for companion animals.
Retail Pharmacies
Covers brick-and-mortar pharmacies and pet specialty retailers offering over-the-counter oral care products, dental treats, supplements, hygiene solutions, and prescribed veterinary dental medications.
E-commerce
Includes online platforms selling pet dental care products, medicines, preventive solutions, and accessories through digital channels offering convenience, product variety, subscription services, and home delivery.
Others
Includes supermarkets, pet stores, distributors, wholesalers, animal shelters, veterinary universities, and alternative sales channels supplying pet dental healthcare products and related services.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Detailed Market Segmentation & End-user Adoption Analysis
Conducted an in-depth assessment of the pet dental health ecosystem covering oral care product manufacturers, veterinary dental equipment suppliers, veterinary hospitals, specialty dental clinics, retail pharmacies, e-commerce platforms, distributors, and pet care organizations. Evaluated the market by animal type, product category, indication, treatment preferences, consumer purchasing behavior, pricing trends, preventive care adoption, and regional demand across major markets.
Delivers comprehensive insights into the pet dental healthcare industry, enabling stakeholders to identify high-growth segments, evolving consumer preferences, preventive care trends, product innovation opportunities, and attractive investment areas for long-term business expansion.
Competitive Benchmarking & Brand Positioning Assessment
Performed benchmarking of leading pet dental health companies based on product portfolio, veterinary recommendations, ingredient innovation, oral care efficacy, pricing strategies, retail penetration, digital presence, customer reviews, brand positioning, distribution capabilities, and regional expansion initiatives. Assessed competitive differentiation across preventive products, medicines, equipment, and dental services.
Enables companies to identify competitive advantages, benchmark product performance, refine branding strategies, strengthen channel presence, evaluate innovation pipelines, and uncover strategic partnership, acquisition, or geographic expansion opportunities within the pet oral healthcare market.
Consumer Behavior & Distribution Channel Opportunity Assessment
Evaluated purchasing behavior by analyzing pet ownership demographics, preventive oral healthcare awareness, frequency of dental product usage, veterinary recommendations, e-commerce adoption, subscription purchasing models, retailer performance, pricing sensitivity, and regional demand patterns. Identified priority customer segments and recommended optimized distribution strategies.
Supports informed decision-making for channel expansion, customer targeting, product launch planning, pricing optimization, retail partnerships, and long-term revenue growth by identifying attractive consumer segments and commercialization opportunities across multiple distribution channels.
Frequently Asked Questions About This Report
The global pet dental health market size was estimated at USD 8.9 billion in 2025 and is expected to reach USD 9.5 billion in 2026.
The global pet dental health market is expected to grow at a compound annual growth rate (CAGR) of 8.5% from 2026 to 2033 to reach USD 16.8 billion by 2033.
North America dominated the pet dental health market with a share of over 40.1% in 2025.
Some key players operating in the pet dental health market include Virbac; Colgate- Palmolive Company; Dechra Pharmaceuticals plc; Nestlé Purina Pet Care; Vetoquinol SA; Nylabone (Central Garden & Pet Company); Barkbox; imRex Inc.; Basepaws, Inc.; Animal Microbiome Analytics, Inc.; Dentalaire, International.; Pedigree (Mars Incorporate); PetIQ, LLC.; Animal Dental Clinic; Petzlife UK.
Key factors that are driving the pet dental health market growth include the growing prevalence of numerous pet dental diseases, such as periodontitis, and rising awareness among pet parents coupled with the increasing number of routine veterinary dental check-ups and treatments.
Asia Pacific is the fastest-growing region over the forecast period.
The dogs segment led with a 58.6% revenue share in 2025, while the cats is the fastest-growing segment.
The services segment led with a 68.7% revenue share in 2025, while the products is the fastest-growing segment.
The gum diseases segment led with a 37.3% revenue share in 2025, while the dental calculus is the fastest-growing segment.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


