
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Photoinitiator Market Size And Share Report, 2025-2030GVR Report cover

Photoinitiator Market (2025 - 2030)
Size, Share & Trends Analysis Report By Type (Free Radical, Cationic), By End Use (Adhesives, Ink, Coating), By Region (North America, Europe, APAC, CSA, Latin America), And Segment Forecasts
Market Size, 2024
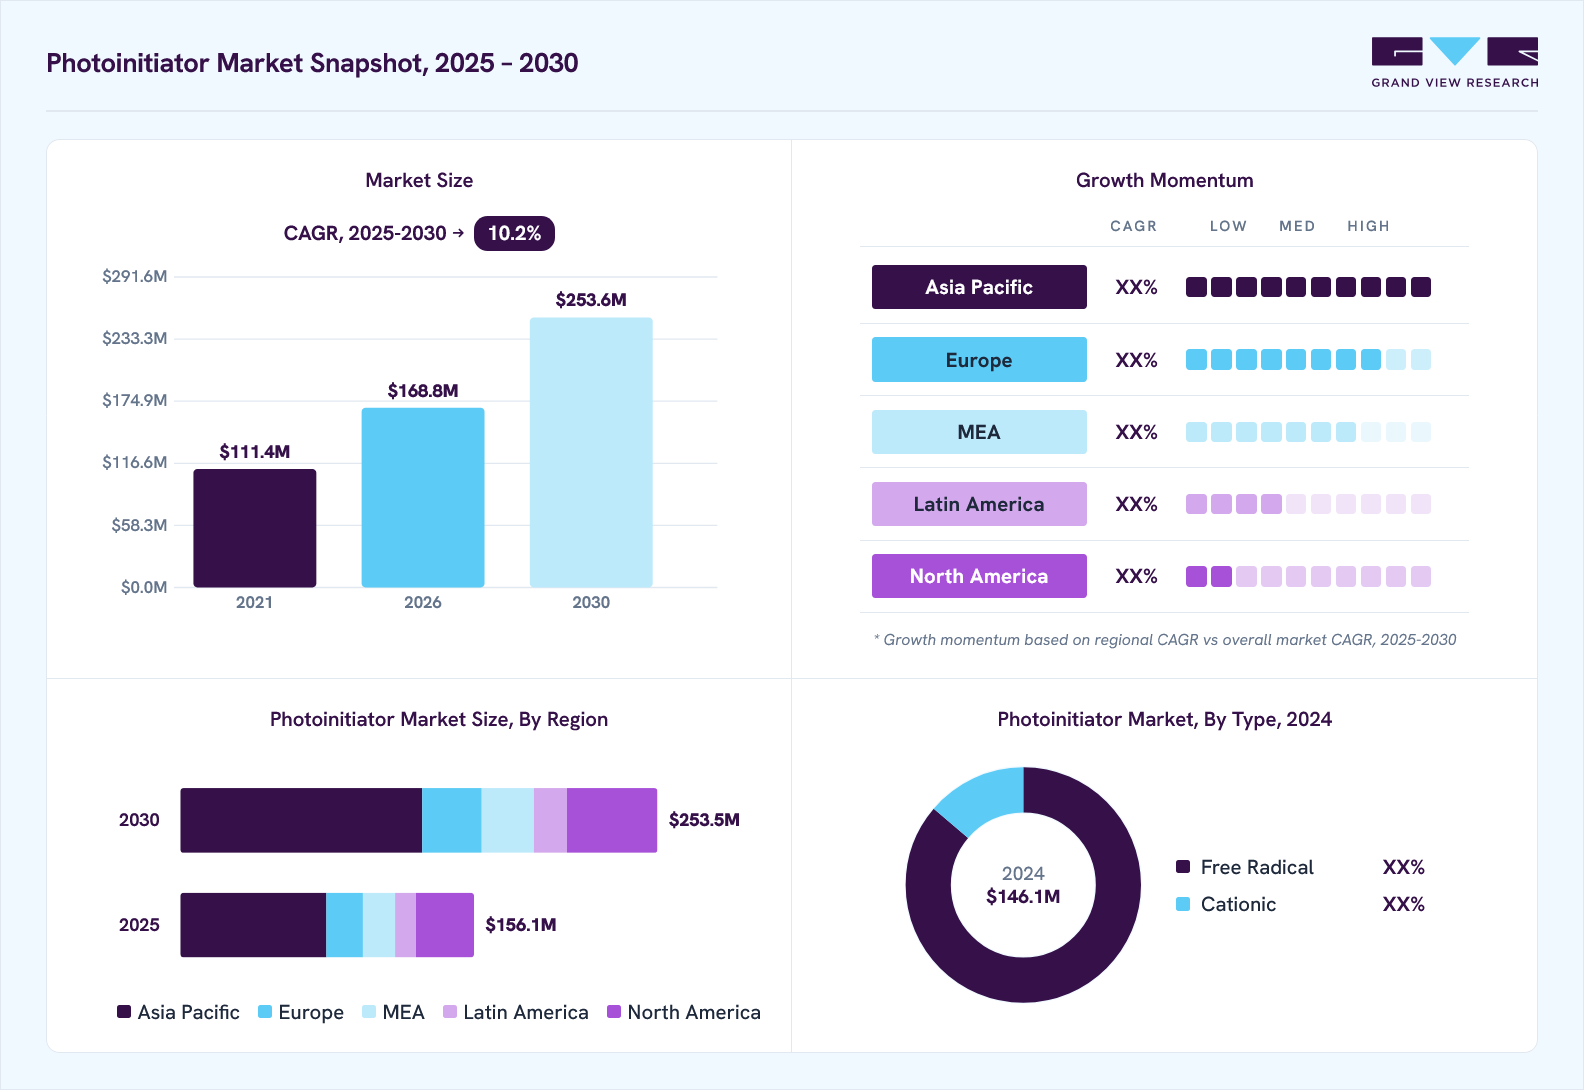
$146.1MMarket Estimate, 2026
$168.8MMarket Forecast, 2030
$253.6MCAGR, 2025–2030
10.2%Photoinitiator Market Summary
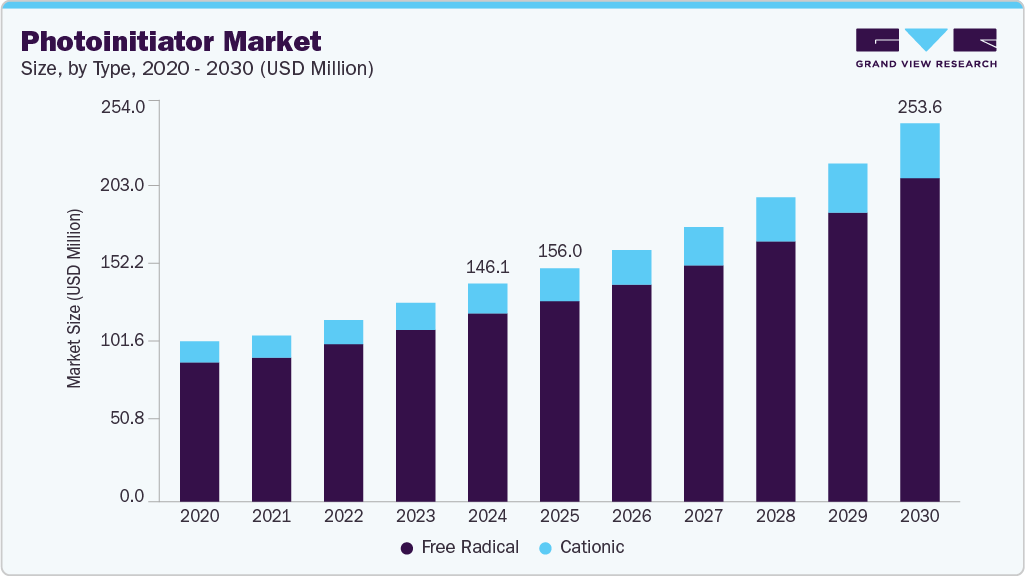
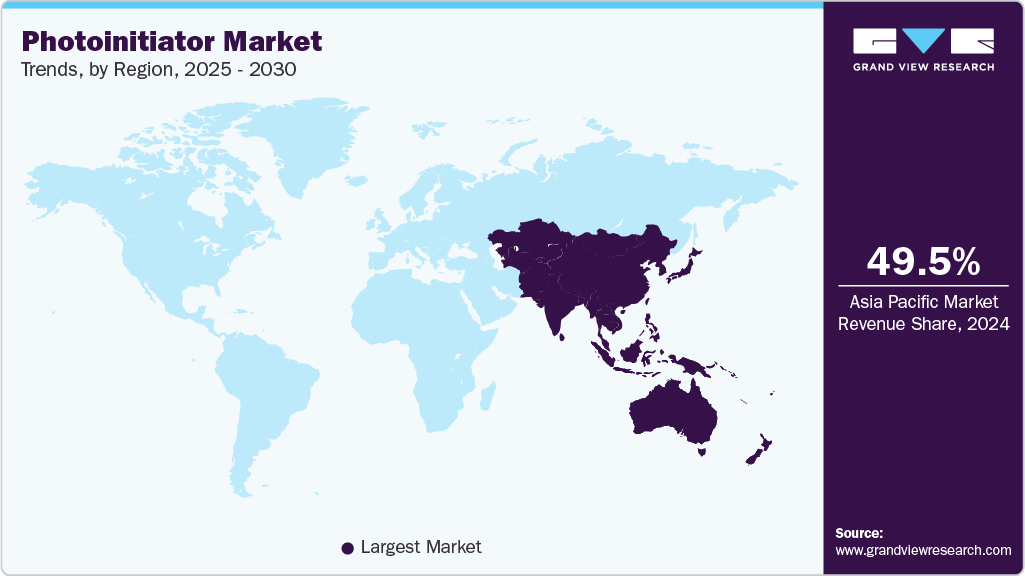
The global photoinitiator market size was valued at USD 146.1 million in 2024 and is projected to grow from USD 168.8 million in 2026 to USD 253.6 million by 2030, at a CAGR of 10.2% from 2025 to 2030. Asia Pacific dominated the market, accounting for a revenue share of 49.5% in 2024. Photoinitiators are crucial compounds in UV-curable systems, widely adopted across inks, adhesives, and coatings due to their role in initiating polymerization upon UV light exposure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- The photoinitiator market in the U.S. is among the most established globally, contributing over 85% of North America's total demand in 2024.
- By type, the free radical segment accounted for over 73.5% of the market in 2024.
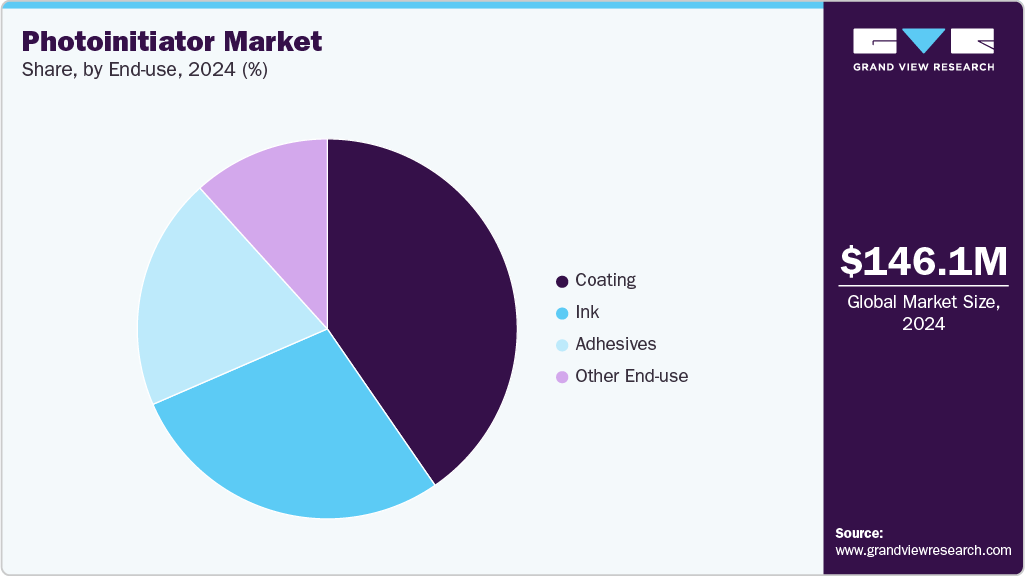
- By end use, the coatings segment led the global market with a revenue share of 37.2% in 2024.
Market Size & Forecast
- 2024 Market Size: USD 146.1 Million
- 2030 Projected Market Size: USD 253.6 Million
- CAGR (2025-2030): 10.2%
- Asia Pacific: Largest market in 2024
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2030 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Market growth is driven by the rising demand for environmentally friendly, low-VOC formulations in industrial and consumer applications. The evolution of photoinitiator chemistry, such as free radical and cationic initiators, has expanded application breadth into 3D printing resins, electronics encapsulation, dental composites, and flexible packaging. In addition, global shifts toward sustainability and energy efficiency promote the use of UV-curable materials, thereby fueling photoinitiator consumption.Ongoing R&D in water-compatible and visible-light-sensitive photoinitiators is shaping the market landscape. These developments cater to demand in biomedical devices and food-grade coatings. Market participants strategically collaborate with resin formulators and equipment manufacturers to optimize curing performance and speed, particularly in fast-turnaround printing and industrial coating lines.
 To learn more about this report, Download Free Sample Report
Global manufacturers also respond to regional regulatory frameworks such as REACH and FDA approvals by innovating lower-toxicity and non-migratory photoinitiators. The rise in high-resolution printing, medical device miniaturization, and sustainable packaging solutions is expected to support long-term demand.
Market Concentration & Characteristics
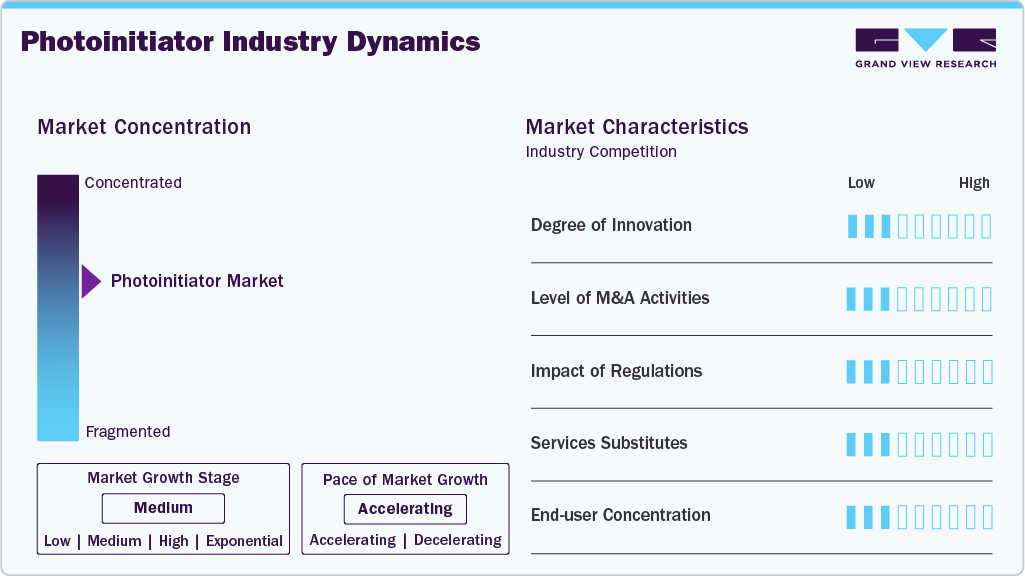
The photoinitiator industry is moderately consolidated, with key multinational players holding significant intellectual property in high-performance initiator systems. Companies such as IGM Resins, Lambson Ltd, and Arkema dominate through diverse product portfolios and global supply networks.
Strategic integration across the supply chain-from photoinitiator synthesis to UV resin formulation-offers competitive advantages in terms of pricing, innovation, and end-user customization. Meanwhile, Asian regional manufacturers increasingly focus on cost-effective bulk initiators for commodity applications like flooring and automotive topcoats.
 To learn more about this report, Download Free Sample Report
Regulatory compliance and product stewardship are critical market differentiators. Initiators used in food packaging, medical devices, and cosmetics require adherence to strict migration and toxicity limits. Players investing in REACH registrations and ISO-certified production are better positioned to supply premium segments.
Digital printing, inkjet, and 3D printing are emerging high-growth application areas, where niche suppliers offering high-absorption or low-yellowing initiators are carving out specialized roles. Product innovation, speed of curing, and global technical support are shaping competitive positioning.
Type Insights
The free radical photoinitiators accounted for over 73.5% of the market in 2024 and are expected to maintain dominance due to their broad compatibility with acrylate resins and widespread use in coatings, adhesives, and inks. Products like benzoin ethers, α-hydroxyketones, and acyl phosphine oxides are commonly utilized.
Cationic photoinitiators, though smaller in market share, are witnessing faster growth. Applications are expanding in epoxy-based systems for electronics, automotive components, and high-performance coatings. Their ability to cure in ambient conditions without oxygen inhibition makes them suitable for specific industrial uses.
Adopting dual-cure systems, combining radical and cationic initiators, is also gaining momentum in 3D printing and dental applications, where controlled depth cure and mechanical strength are essential. Hybrid initiator systems are projected to open new performance benchmarks for formulators.
End Use Insights
The coatings segment led the global market with a revenue share of 37.2% in 2024. Rapid UV curing, solvent-free formulation compatibility, and superior mechanical properties have led to the usage of photoinitiators in wood coatings, automotive topcoats, metal protection, and plastic finishes.
The inks segment is expanding steadily with the digitalization of commercial and packaging printing. UV-curable inks offer low energy consumption, fast drying, and resistance to abrasion and chemicals, critical for applications like labels, shrink sleeves, and flexible packaging.
 To learn more about this report, Download Free Sample Report
Adhesives account for a smaller but stable share, with adoption in medical tapes, optical bonding, electronics assembly, and pressure-sensitive labels. In recent years, the trend toward miniaturization and biocompatible adhesives has promoted R&D in low-extractable, odorless photoinitiators.
Emerging applications include 3D printing resins, dental composites, and bio-based UV formulations, where custom photoinitiator systems tailored for performance, safety, and light wavelength compatibility are in high demand. These advanced systems often require low-yellowing, deep-curing, and low-migration characteristics to meet next-generation materials' stringent mechanical, aesthetic, and biocompatibility standards.
Regional Insights
North America accounted for an estimated 34.7% revenue share in 2024, led by strong adoption in digital printing, industrial coatings, and medical device adhesives. The U.S. is the primary consumer, backed by an advanced graphics industry, strict VOC regulations favoring UV-curable systems, and robust R&D ecosystems. High demand from the packaging and electronics sectors drives innovations in high-performance and low-migration photoinitiators.
U.S. Photoinitiator Market Trends
The photoinitiator market in the U.S. is among the most established globally, contributing over 85% of North America's total demand in 2024. Growth is supported by widespread use in high-performance coatings, digital UV inks, and medical-grade adhesives. The country has rapidly adopted UV-curable systems across the packaging, electronics, and healthcare sectors, driven by stringent environmental regulations favoring low-VOC solutions.
Asia Pacific Photoinitiator Market Trends
The photoinitiator market in Asia Pacific is expected to grow significantly as China leads in both production and consumption, driven by expanding electronics, automotive, and packaging industries. Japan and South Korea are key innovation hubs for semiconductor and display-related UV applications. The region benefits from cost-efficient manufacturing and growing domestic demand for 3D printing and UV-curable products.
 To learn more about this report, Download Free Sample Report
Europe Photoinitiator Market Trends
The photoinitiator market in Europe is growing steadily because countries like Germany, France, and the UK have well-established manufacturing bases for industrial coatings, inks, and adhesives. EU REACH compliance has prompted the development and substitution of traditional photoinitiators with safer, non-toxic alternatives. There is also strong penetration in wood coatings and label printing segments.
Latin America Photoinitiator Market Trends
The photoinitiator market in Latin America is an emerging market that is increasingly adopting UV-curable inks and coatings in the packaging, flooring, and furniture sectors. Brazil and Mexico are the major contributors, where demand is supported by modernization in commercial printing and consumer goods packaging. Market growth is modest but improving with technology transfers from North American and European players.
Middle East & Africa Photoinitiator Market Trends
The photoinitiator market in the MEA is still nascent but gaining traction in segments like automotive refinishing, electronics encapsulation, and label printing. GCC countries are investing in industrial infrastructure where UV-curing is considered an energy-efficient and sustainable solution. Imports dominate the region’s supply, but growing awareness and infrastructure investments may enhance future regional value addition.
Key Photoinitiator Company Insights
Some of the key players operating in the market include IGM Resins, Lambson Ltd, Arkema S.A., BASF SE, Tronly New Electronic Materials Co., Ltd., Tianjin Jiuri New Materials Co., Ltd., ADEKA Corporation, Evonik Industries AG, Rahul Photoinitiators Pvt. Ltd., Eutec Chemical Co., Ltd.
-
IGM Resins leads the global market with its extensive range of free radical and cationic initiators, supported by regional manufacturing units in Europe, North America, and Asia. The company has also invested in visible-light photoinitiator R&D and maintains technical partnerships with coating and ink manufacturers.
-
BASF SE is a prominent player offering high-performance initiator systems under its specialty chemicals divisions. Both companies serve critical applications in medical, electronic, and automotive coatings with products that meet REACH and FDA compliance.
Key Photoinitiator Companies:
The following are the leading companies in the photoinitiator market. These companies collectively hold the largest market share and dictate industry trends.
- IGM Resins
- Lambson Ltd (part of Aditya Birla Group)
- Arkema S.A.
- BASF SE
- Tronly New Electronic Materials Co., Ltd.
- Tianjin Jiuri New Materials Co., Ltd.
- ADEKA Corporation
- Evonik Industries AG
- Rahul Photoinitiators Pvt. Ltd.
- Eutec Chemical Co., Ltd.
Recent Developments
-
In April 2025, IGM Resins opened a new R&D center in Waalwijk, Netherlands, focusing on visible-light and low-migration photoinitiators for food and healthcare packaging. This facility focuses on creating visible-light and low-migration photoinitiators, addressing the industry's demand for safer and more efficient UV-curable solutions. The center also emphasizes the development of polymeric photoinitiators, which are designed to minimize migration into packaged goods, ensuring compliance with stringent food safety regulations.
-
In January 2025, Tianjin Jiuri New Materials expanded its photoinitiator production capacity in China by 20,000 tons/year to meet rising global demand, especially from Europe and Southeast Asia. This expansion is part of the company's strategic initiative to enhance its global supply capabilities and strengthen its position in the UV-curing materials market.
Photoinitiator Market Report Scope
Report Attribute
Details
Market size in 2024
USD 146.1 million
Estimated Market size in 2026
USD 168.8 million
Projected Market size by 2030
USD 253.6 million
Growth rate
CAGR of 10.2% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2025 - 2030
Quantitative units
Volume in kilotons, revenue in USD million, and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea
Key companies profiled
IGM Resins; Lambson Ltd (part of Aditya Birla Group); Arkema S.A.; BASF SE; Tronly New Electronic Materials Co., Ltd.; Tianjin Jiuri New Materials Co., Ltd.; ADEKA Corporation; Evonik Industries AG; Rahul Photoinitiators Pvt. Ltd.; Eutec Chemical Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Photoinitiator Market Report Segmentation
This report forecasts volume & revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global photoinitiator market report based on type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Free Radical
-
Cationic
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Adhesives
-
Ink
-
Coating
-
Other End Use
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Middle East & Africa
-
Frequently Asked Questions About This Report
The global photoinitiator market size was valued at USD 146.1 million in 2024 and is estimated at USD 168.8 million for 2026.
The global photoinitiator market is expected to grow at a CAGR of 10.2% from 2025 to 2030, reaching USD 253.6 million by 2030.
North America accounted for an estimated 34.7% revenue share in 2024, led by strong adoption in digital printing, industrial coatings, and medical device adhesives.
IGM Resins, Lambson Ltd, Arkema S.A., BASF SE, Tronly New Electronic Materials Co., Ltd., Tianjin Jiuri New Materials Co., Ltd., ADEKA Corporation, Evonik Industries AG, Rahul Photoinitiators Pvt. Ltd., Eutec Chemical Co., Ltd.
Market growth is driven by the rising demand for environmentally friendly, low-VOC formulations in industrial and consumer applications.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


