
- Home
- »
- Advanced Interior Materials
- »
-
Physical Vapor Deposition Market Size, Industry Report 2033GVR Report cover

Physical Vapor Deposition Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Thermal Evaporation, Sputter Deposition, Arc Vapor Deposition), By Application (Semiconductor & Electronics, Solar Products, Cutting Tools), By Region, And Segment Forecasts
Market Size, 2025
$3.4BMarket Estimate, 2026
$3.6BMarket Forecast, 2033
$6.1BCAGR, 2026–2033
7.6%Physical Vapor Deposition Market Summary
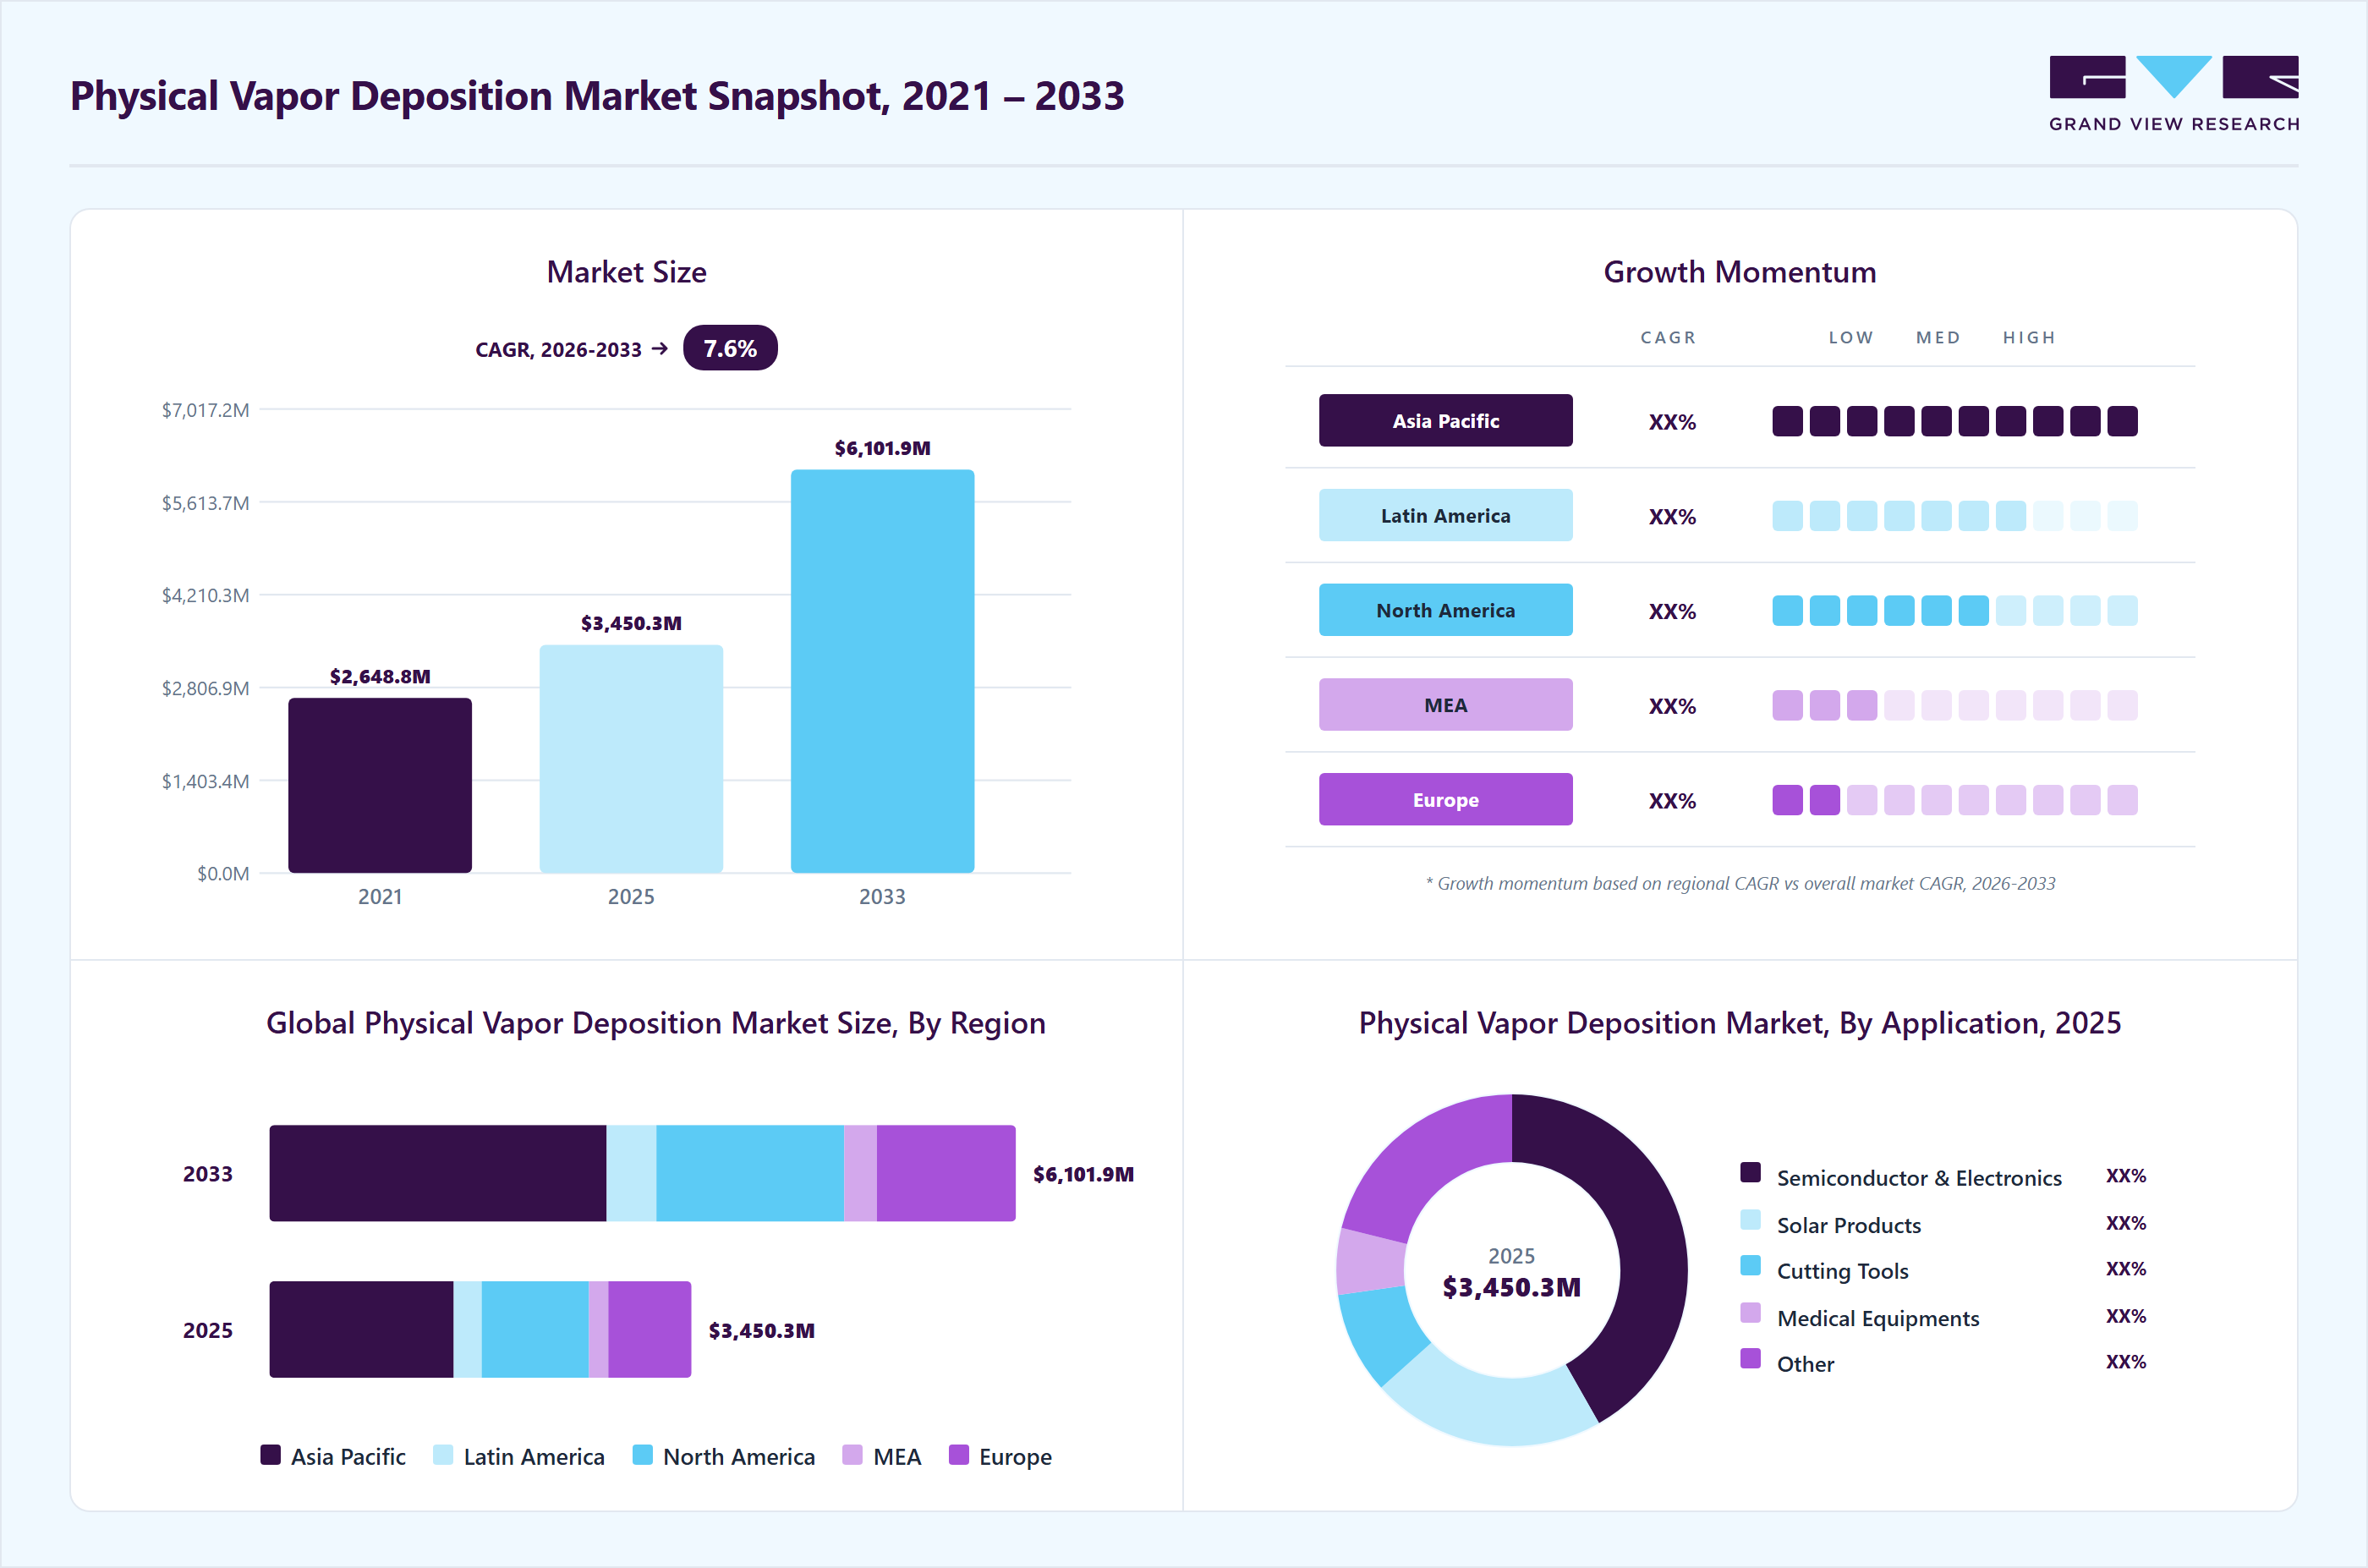
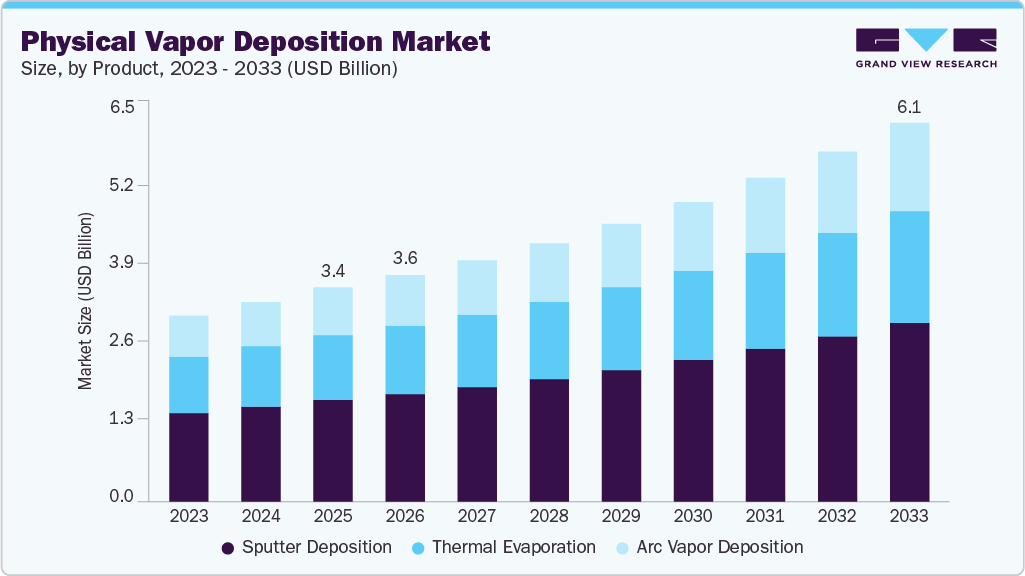
The global physical vapor deposition market size was valued at USD 3.4 billion in 2025 and is projected to grow from USD 3.6 billion in 2026 to USD 6.1 billion by 2033, at a CAGR of 7.6% from 2026 to 2033. Asia Pacific dominated the global physical vapor deposition market with the largest revenue share of 43.7% in 2025. The physical vapor deposition market is primarily driven by the increasing demand for advanced coating technologies across industries such as automotive, aerospace, medical devices, and cutting tools.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Sputter deposition segment dominated the market with revenue share of 47.5% in 2025.
- By product: Arc vapor deposition is expected to be the fastest-growing segment during the forecast period at CAGR of 8.3%
- By application: Solar products segment is expected to register strong growth, with a projected CAGR of 8.1% from 2026 to 2033 in terms of revenue.
Regional Highlights
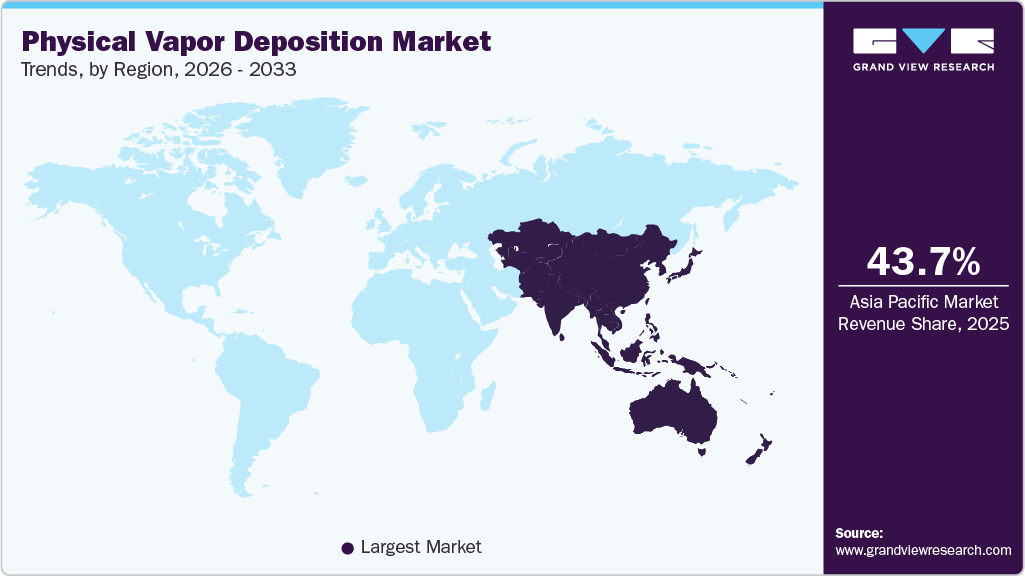
- Largest regional market: Asia Pacific (43.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.4 Billion
- Estimated market size in 2026: USD 3.6 Billion
- Projected market size by 2033: USD 6.1 Billion
- CAGR (2026-2033): 7.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
PVD coatings are widely adopted for their ability to enhance surface properties, including hardness, wear resistance, and corrosion protection, thereby improving product durability and performance. The semiconductor industry continues to be a major growth engine for the PVD market, given its reliance on thin-film deposition technologies for chip fabrication.
 To learn more about this report, Download Free Sample Report
According to the Semiconductor Industry Association (SIA), global semiconductor sales reached USD 82.5 billion in January 2026, marking a 3.7% increase from December 2025 and a substantial 46.1% growth compared to January 2025. These shows strong momentum in global chip demand. As PVD is essential for producing high-precision coatings used in integrated circuits and electronic components, this rapid growth in semiconductor sales is expected to significantly drive the adoption of PVD technologies over the forecast period.
Market Dynamics
The demand for semiconductors is increasing significantly worldwide. This is because the design of integrated circuits (ICs) is becoming increasingly complex and advanced to support enhanced services in electronic devices, resulting in the consumption of a large number of semiconductors. The semiconductors help minimize the production cost of ICs, reduce the time required for their mass production, and enhance the value of final products in terms of operations. PVD equipment is used in semiconductor fabrication for the deposition of thin film on semiconductor substrates. The rising demand for semiconductor fabrication is likely to increase the demand for PVD services over the forecast period.
Moreover, the rise in the global demand for consumer electronics can be attributed to the increasing per capita disposable income and high demand for advanced electronics. The surging adoption of electronic products for workplaces, daily use, and entertainment is expected to increase the global demand for semiconductors. This is expected to drive the demand for PVD equipment and services for the semiconductor fabrication process.
The high capital limits the global market growth of physical vapor deposition coating technology. The high upfront cost of the PVD equipment and the expensive coating process act as a barrier for small and medium-scale manufacturers. Moreover, the maintenance of PVD equipment parts is expensive. The capital cost includes the cost of raw materials, equipment, and labor employed to operate the complex machinery.
Market Concentration & Characteristics
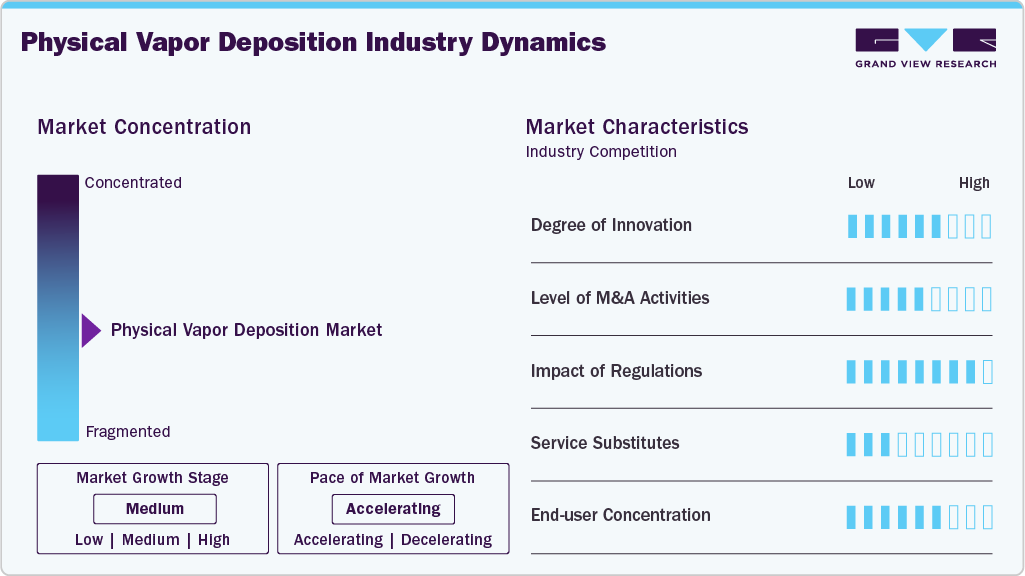
The Physical Vapor Deposition (PVD) market is slightly fragmented, with the presence of numerous regional and local service providers alongside a few established global players. While companies such as Oerlikon Balzers and IHI Corporation (through its coating division) hold notable positions, a large share of the market is distributed among smaller firms offering specialized and customized coating services. The service-based nature of the market lowers entry barriers compared to equipment manufacturing, allowing niche players to compete based on application expertise, turnaround time, and customer-specific solutions.
The physical vapor deposition (PVD) market is strongly driven by innovation, with continuous improvements in coating performance, process efficiency, and material capabilities. Companies are focusing on developing advanced systems that deliver better coating uniformity, higher productivity, and lower operational costs. For example, in September 2024, Oerlikon Balzers launched the INVENTA PVD system with Advanced Arc Technology (AAT), designed to improve coating quality, expand material flexibility, and enhance overall efficiency. Such developments highlight the industry’s shift toward more precise, scalable, and cost-effective coating solutions.
 To learn more about this report, Download Free Sample Report
Regulations play an increasingly important role in shaping the PVD market, especially in regions with strict environmental and safety standards. PVD is gaining preference over conventional coating methods because it generates minimal hazardous waste and reduces the use of harmful chemicals. This aligns well with tightening environmental norms across industries such as automotive, aerospace, and healthcare. In addition, stringent requirements related to product reliability, safety, and biocompatibility are further encouraging the adoption of advanced coating technologies like PVD.
The market shows a relatively concentrated end-user base, with demand largely coming from a few major industries. The semiconductor and electronics sector accounts for a significant share due to its heavy reliance on thin-film deposition processes. At the same time, industries such as cutting tools, automotive, and medical equipment also contribute notably to demand. As a result, overall market growth is closely linked to investment trends and technological advancements within these core sectors.
Product Insights
Sputter deposition segment dominated the physical vapor deposition market in 2025 due to its simplicity, cost-effectiveness, and wide applicability across basic coating requirements. The process is well-established and widely used in applications such as optics, displays, and simple electronic components where ultra-high precision is not always required. Its ability to deliver consistent coatings with relatively lower equipment and operating costs makes it a preferred choice, especially in high-volume and cost-sensitive manufacturing environments.
Arc vapor deposition is expected to be the fastest-growing segment during the forecast period at CAGR of 8.3%, driven by its ability to produce extremely hard, dense, and wear-resistant coatings. This technology is increasingly adopted in cutting tools, automotive components, and industrial machinery where superior surface performance is critical. The growing demand for high-durability coatings, along with advancements in arc-based technologies that improve coating quality and efficiency, is supporting its rapid growth across industrial applications.
Application Insights
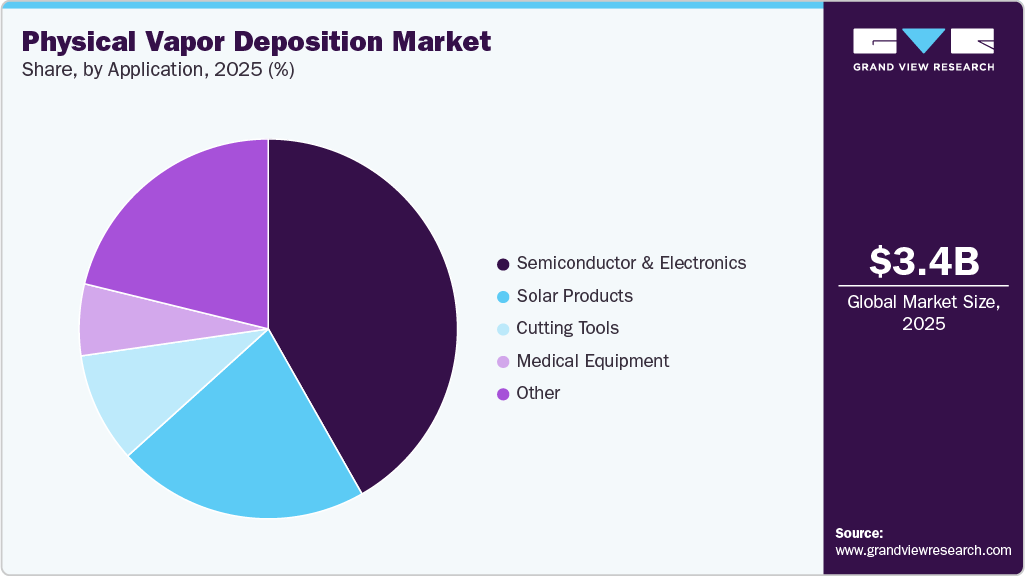
Semiconductor & electronics dominated the physical vapor deposition market and accounted for 41.8% share in 2025, driven by the strong demand for advanced chips, integrated circuits, and electronic components. PVD is widely used in this sector for depositing thin films with high precision and uniformity, which are essential for modern microelectronics and display technologies. The continued growth in areas such as consumer electronics, data centers, and communication technologies further strengthens the demand for PVD in semiconductor manufacturing.
 To learn more about this report, Download Free Sample Report
Solar products are expected to be the fastest-growing application segment during the forecast period, supported by rising investments in renewable energy and increasing adoption of solar power worldwide. PVD plays a key role in the production of thin-film solar cells by enabling efficient and durable coatings that enhance energy conversion efficiency. As governments and industries focus more on clean energy solutions and sustainability, the demand for PVD technologies in solar applications is projected to grow rapidly over the forecast period.
Regional Insights
North America holds a significant share of the market, driven by advanced semiconductor research, strong presence of leading technology companies, and high adoption of precision coating solutions in aerospace and medical sectors. The region benefits from continuous innovation and early adoption of advanced manufacturing technologies, along with increasing investments in domestic semiconductor production and clean energy initiatives.
U.S. Physical Vapor Deposition Market Trends
U.S. dominated the North American physical vapor deposition market, supported by strong semiconductor production, advanced manufacturing, and high adoption of precision coating technologies. According to the Solar Energy Industries Association, the U.S. installed 43.2 GWdc of solar capacity in 2025, accounting for 54% of new electricity generation capacity, boosting demand for thin-film coatings. In addition, the National Association of Manufacturers reported manufacturing value-added output rising from USD 2.7 trillion in Q2 2025 to USD 2.9 trillion in Q3 2025, reflecting strong industrial growth that supports increased adoption of PVD technologies.
Mexico is expected to witness notable growth during the forecast period, driven by expanding manufacturing activities and increasing integration into global electronics and automotive supply chains. The country is emerging as a cost-effective production hub, attracting investments in industrial and electronic component manufacturing where PVD coatings are used to enhance product durability and performance.
Europe Physical Vapor Deposition Market Trends
Europe is characterized by strong demand from automotive, aerospace, and industrial tooling industries. The region emphasizes high-quality, sustainable manufacturing practices, which supports the adoption of environmentally friendly coating technologies like PVD. Countries such as Germany and France are key contributors, with a focus on precision engineering and advanced surface treatment solutions.
Germany dominated the Europe physical vapor deposition market, supported by its strong industrial base, particularly in automotive, precision engineering, and medical device manufacturing. The country’s focus on high-quality production and advanced surface treatment technologies drives consistent demand for PVD coatings. According to the International Trade Administration, Germany’s medical device market is among the largest globally, generating around USD 44 billion (EUR 38 billion) annually and accounting for 26.5% of the European market, further supporting the adoption of high-performance coating solutions.
France is expected to witness steady growth during the forecast period, driven by increasing investments in aerospace, healthcare, and advanced manufacturing sectors. The country is gradually expanding its capabilities in precision engineering and surface coating technologies, creating demand for PVD in applications requiring durability and performance. In addition, supportive government initiatives and a growing focus on sustainable and high-value manufacturing are contributing to the rising adoption of PVD technologies in France.
Asia Pacific Physical Vapor Deposition Market Trends
Asia Pacific dominated the physical vapor deposition market with 43.7% share in 2025 and is also expected to be the fastest-growing region during the forecast period at CAGR of 8.1%. This growth is supported by the strong presence of semiconductor manufacturing hubs in countries such as China, Taiwan, Japan, and India along with expanding electronics production and industrial base. Increasing investments in renewable energy, particularly solar panel manufacturing, and the rapid growth of automotive and tooling industries further strengthen regional demand for PVD technologies.
 To learn more about this report, Download Free Sample Report
China dominated the Asia Pacific physical vapor deposition market, supported by its large electronics manufacturing base, strong semiconductor production, and widespread industrial activity. The country continues to invest heavily in chip fabrication, display panels, and solar technologies, all of which require advanced thin-film coatings. Its integrated supply chain and policy support for high-tech manufacturing sustain strong demand for PVD systems across key industries.
India is expected to be one of the fastest-growing markets, driven by increasing focus on semiconductor manufacturing and electronics production. As per the India Semiconductor Mission 2.0, the domestic semiconductor market was valued at about USD 38 billion in 2023 and is projected to reach USD 100-110 billion by 2030. This growth trajectory, supported by national programs like Make in India and Make for the World, is expected to accelerate the adoption of PVD technologies across the country.
Latin America Physical Vapor Deposition Market Trends
Latin America is witnessing gradual growth in the PVD market, supported by expanding industrial activities and increasing demand for durable coatings in automotive and manufacturing sectors. While the region is still developing in terms of advanced coating technologies, rising investments and improving industrial infrastructure are expected to create growth opportunities over the forecast period.
Brazil leads the physical vapor deposition market in Latin America, supported by its relatively large industrial base and growing manufacturing sector. Demand for PVD technologies is increasing across automotive, machinery, and tooling applications, where enhanced durability and surface performance are critical. The country is also seeing gradual adoption of advanced coating solutions in medical devices and electronics, driven by improving industrial capabilities.
Middle East & Africa Physical Vapor Deposition Market Trends
Middle East & Africa is emerging as a potential market, driven by growing industrialization and diversification efforts beyond oil-dependent economies. Demand for PVD is increasing in sectors such as construction, energy, and healthcare, where durable and high-performance coatings are required. Although adoption is at an early stage, ongoing infrastructure development and investment in advanced technologies are expected to support steady market growth.
UAE is emerging as a key market for physical vapor deposition technologies in the region, supported by its focus on industrial diversification and advanced manufacturing. The country is investing in sectors such as aerospace, construction, and energy, where high-performance and decorative coatings are widely used. Growing demand for durable, corrosion-resistant materials in infrastructure and oil & gas applications is also contributing to the adoption of PVD.
Key Physical Vapor Deposition Company Insights
Some of the key players operating in the physical vapor deposition market include Oerlikon Balzers, ULVAC, Inc, and Veeco Instruments Inc.
-
Oerlikon Balzers specializes in surface engineering technologies that enhance the performance and lifespan of components used in industries such as aerospace, automotive, semiconductors, and healthcare. The company offers a combination of coating systems, materials, and related services designed to improve wear resistance, efficiency, and overall functionality. Its strength lies in integrating advanced materials science with coating solutions to support precision-driven manufacturing while also aligning with more sustainable production practices.
-
ULVAC, Inc. develops and supplies vacuum technologies used in industries such as semiconductors, electronics, display manufacturing, and solar energy. Its offerings include sputtering and deposition systems, vacuum pumps, analytical equipment, and related materials like sputtering targets. The company supports various stages of the production process by combining equipment and materials expertise, enabling precise thin-film formation and other vacuum-based manufacturing applications essential for advanced technologies.
Key Physical Vapor Deposition Companies:
The following key companies have been profiled for this study on the physical vapor deposition market.
- Oerlikon Balzers
- Angstrom Engineering Inc.
- Kurt J. Lesker Company
- voestalpine High Performance Metals International GmbH
- Nissin Electric Vietnam Co., Ltd.
- IHI HAUZER TECHNO COATING B.V.
- HEF Groupe
- KOBE STEEL, LTD
- Lafer S.p.A.
- INORCOAT
- Applied Materials, Inc.
- ULVAC, Inc
- Veeco Instruments Inc
- Denton Vacuum
- Mustang Vacuum Systems
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Oerlikon Balzers; Kurt J. Lesker Company; voestalpine High Performance Metals International GmbH; IHI HAUZER TECHNO COATING B.V.; HEF Groupe
- Focused on expanding advanced thin-film coating and vacuum deposition technologies for semiconductors, cutting tools, automotive, aerospace, medical devices, and industrial manufacturing applications
- Invested heavily in high-performance sputtering systems, vacuum coating technologies, automation integration, and next-generation surface engineering solutions
- Strengthened global service capabilities, R&D infrastructure, and long-term partnerships with semiconductor and industrial manufacturing companies
- Strong global brand recognition and extensive expertise in vacuum coating and thin-film deposition technologies
- Advanced engineering capabilities for high-precision and high-performance coating applications
- Large installed customer base across semiconductor, electronics, aerospace, and industrial tooling sectors
- Strong R&D capabilities supporting coating innovation, process optimization, and production scalability
- High equipment and maintenance costs compared to conventional separation technologies
- High equipment and installation costs compared to conventional coating technologies
- Dependence on semiconductor, electronics, and industrial capital expenditure cycles
- Complex process control and maintenance requirements for vacuum systems
Emerging Players: Angstrom Engineering Inc.; Nissin Electric Vietnam Co., Ltd.; Lafer S.p.A.; INORCOAT; Denton Vacuum
- Focused on customized and application-specific PVD coating systems for research laboratories, industrial coating, electronics, and niche manufacturing applications
- Increased emphasis on compact system designs, flexible coating capabilities, and cost-effective vacuum deposition solutions
- Expanded offerings for regional industrial markets and mid-scale manufacturing facilities
- Competitive flexibility and strong responsiveness to specialized coating requirements
- Growing adoption in research institutions, specialty manufacturing, and localized industrial applications
- Ability to provide customized coating solutions for niche thin-film deposition processes
- Comparatively lower global market penetration and brand visibility
- Limited financial scale for large international expansion and advanced R&D investments
- Lower diversification compared to multinational coating equipment providers
Recent Developments
-
In July 2025, Kurt J. Lesker Company introduced a roll-to-roll module for its PVD 200 system to enable continuous coating of flexible materials. The setup supports controlled thin-film deposition on moving substrates, improving scalability. It is suited for transitioning from research to pilot production, especially in flexible electronics. The module enhances throughput while maintaining coating precision.
-
In December 2024, ULVAC, Inc. launched the ENTRON-EXX deposition system for semiconductor manufacturing. The system improves efficiency through enhanced data monitoring and real-time process control. Its modular design allows flexibility to meet changing production requirements. This development highlights ULVAC’s focus on advancing semiconductor fabrication technologies.
Physical Vapor Deposition Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.4 billion
Estimated market size in 2026
USD 3.6 billion
Projected market size by 2033
USD 6.1 billion
Growth rate
CAGR of 7.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Product, application, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; France; Italy; UK; China; Japan; India; Australia; Brazil; Argentina; South Africa; UAE
Key companies profiled
Oerlikon Balzers; Angstrom Engineering Inc.; Kurt J. Lesker Company; voestalpine High Performance Metals International GmbH; Nissin Electric Vietnam Co., Ltd.; IHI HAUZER TECHNO COATING B.V.; HEF Groupe; KOBE STEEL, LTD; Lafer S.p.A.; INORCOAT; Applied Materials, Inc.; ULVAC, Inc.; Veeco Instruments Inc.; Denton Vacuum; Mustang Vacuum Systems
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Physical Vapor Deposition Market Report Segmentation
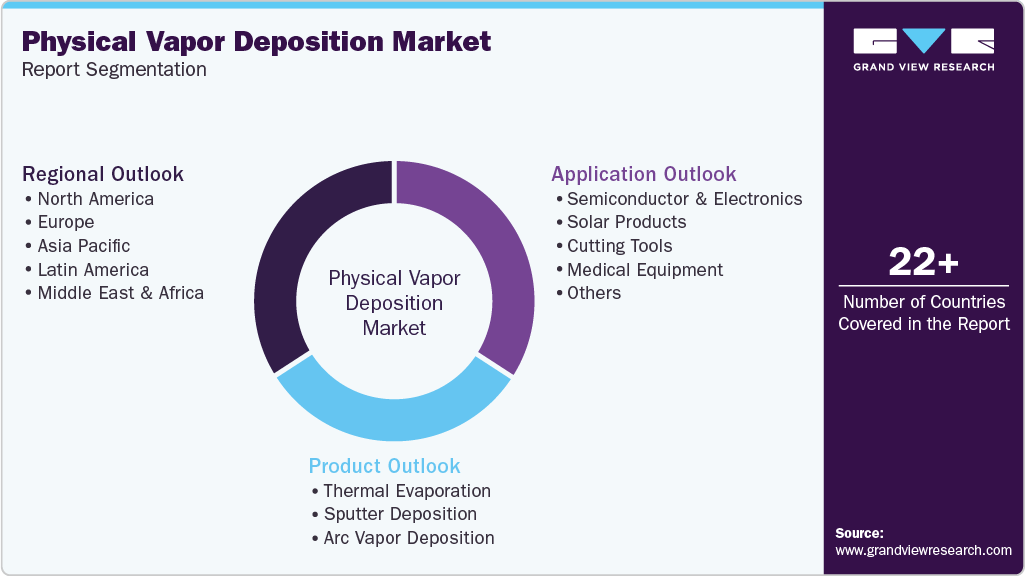
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the physical vapor deposition market on the basis of product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Thermal Evaporation
-
Sputter Deposition
-
Arc Vapor Deposition
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Semiconductor & Electronics
-
Solar Products
-
Cutting Tools
-
Medical Equipment
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
Delivered detailed market sizing, historical analysis, and forecast assessment for the physical vapor deposition market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Country-level demand trends were analyzed across semiconductor manufacturing, automotive, aerospace, medical devices, electronics, and industrial tooling industries.
Enabled identification of high-growth manufacturing hubs, regional investment pockets, and future expansion opportunities.
Opportunity assessment
Identified and evaluated emerging growth opportunities driven by semiconductor fabrication expansion, electric vehicle production growth, increasing adoption of advanced medical coatings, rising demand for high-performance cutting tools, and the transition toward environmentally sustainable coating technologies.
Enabled stakeholders to prioritize future investment areas, innovation initiatives, and untapped industrial applications.
Competitive benchmarking
Delivered comprehensive benchmarking of leading PVD equipment manufacturers based on product offerings, innovation intensity, regional footprint, and strategic initiatives.
Provided clear visibility into competitor strengths, technology leadership, and market positioning.
Frequently Asked Questions About This Report
The global physical vapor deposition market size was estimated at USD 3.4 billion in 2025 and is expected to reach USD 3.6 billion in 2026.
The global physical vapor deposition market, in terms of revenue, is expected to grow at a compound annual growth rate of 7.6% from 2026 to 2033 to reach USD 6.1 billion by 2033.
Asia Pacific dominated the physical vapor deposition market in 2025 and is also expected to be the fastest-growing region during the forecast period at CAGR of 8.1%.
Some of the key players operating in the physical vapor deposition market include Oerlikon Balzers; Angstrom Engineering Inc.; Kurt J. Lesker Company; voestalpine High Performance Metals International GmbH; Nissin Electric Vietnam Co., Ltd.; IHI HAUZER TECHNO COATING B.V.; HEF Groupe; KOBE STEEL, LTD; Lafer S.p.A.; INORCOAT; Applied Materials, Inc.; ULVAC, Inc; Veeco Instruments Inc; Denton Vacuum; and Mustang Vacuum Systems.
The physical vapor deposition market is driven by growing demand from the semiconductor and electronics industries, where thin-film coatings are essential for advanced device manufacturing. Increasing need for durable, wear-resistant coatings across automotive, aerospace, and industrial applications, along with rising adoption of clean energy technologies, further supports market growth.
The semiconductor & electronics segment led with a 41.8% revenue share in 2025, while solar products is expected to be the fastest-growing segment.
Sputter deposition held the largest revenue share in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


