
- Home
- »
- Advanced Interior Materials
- »
-
Pipe Welding Rotator Market Size, Share Report, 2026-2033GVR Report cover

Pipe Welding Rotator Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Conventional Rotators, Self-aligning Rotators), By Operation Mode, By End Use (Construction, Shipbuilding & Marine, Automotive, Power Generation), By Region, And Segment Forecasts
Market Size, 2025
$1.1BMarket Estimate, 2026
$1.2BMarket Forecast, 2033
$2.0BCAGR, 2026–2033
7.3%Pipe Welding Rotator Market Summary
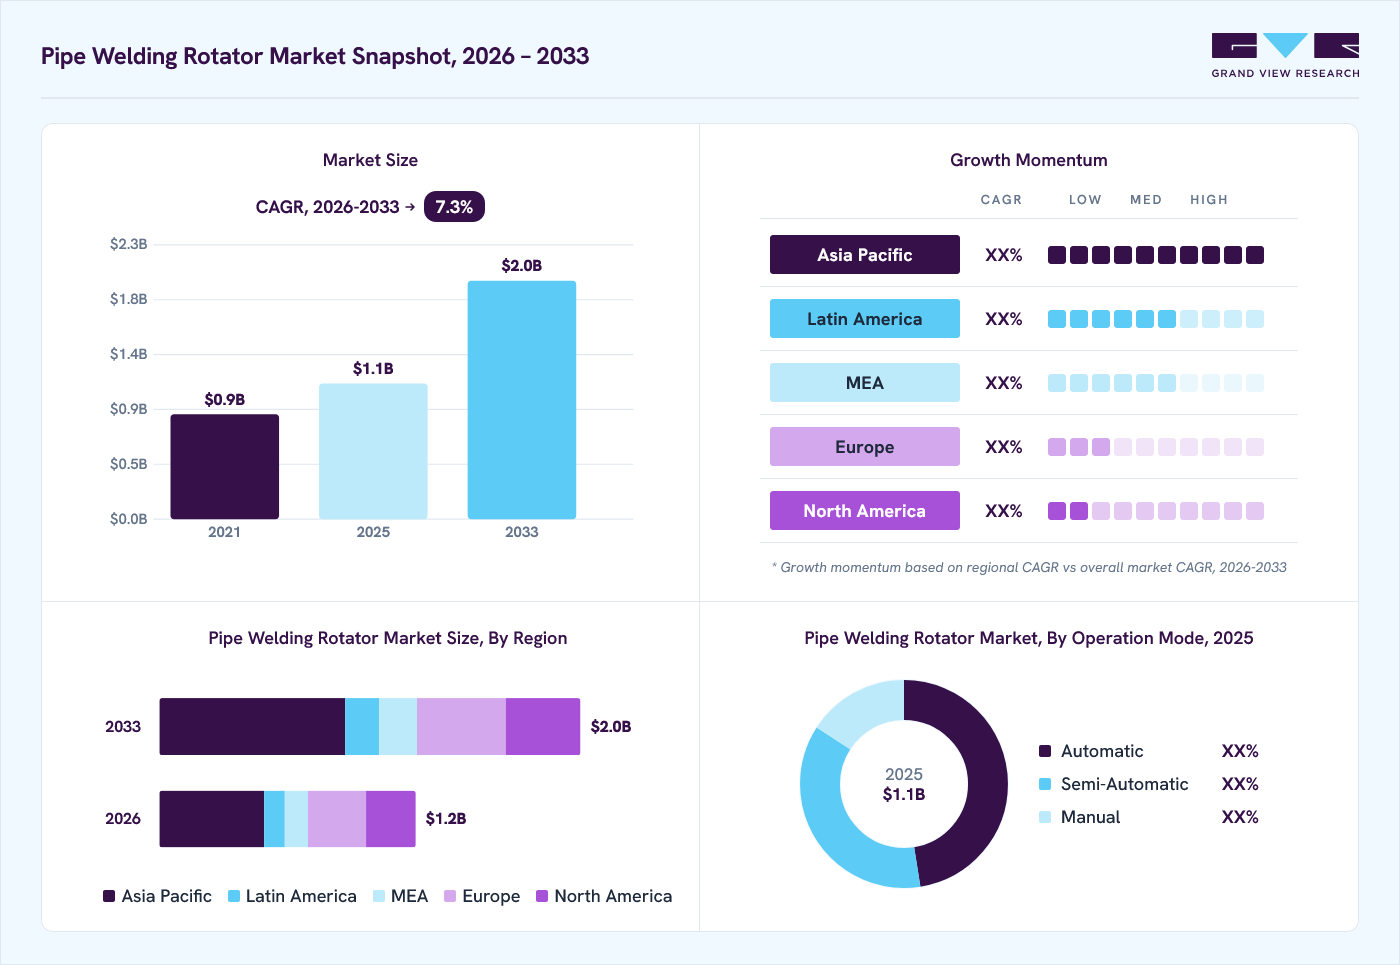
The global pipe welding rotator market size was valued at USD 1.1 billion in 2025 and is projected to grow from USD 1.2 billion in 2026 to USD 2.0 billion by 2033, growing at a CAGR of 7.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 40.4% in 2025. The expansion of large-scale pipe fabrication and welding activities is driving demand for pipe welding rotators across heavy fabrication facilities.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Self-aligning rotators segment led the market with a revenue share of 34.2% in 2025.
- By operation mode: Automatic segment led the market with a revenue share of 47.4% in 2025.
- By end use: Oil & gas segment led the market with a revenue share of 31.5% in 2025.
Regional Highlights
- Largest Regional Market: Asia Pacific (40.4% revenue share, 2025).
- By Country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.1 Billion
- Estimated Market size in 2025: USD 1.2 Billion
- Projected market size by 2033: USD 2.0 Billion
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing construction of pipelines, pressure vessels, storage tanks, marine structures, power-generation equipment, and other cylindrical components is increasing the need for controlled workpiece positioning. Rotators enable stable and uniform rotation during welding, helping fabricators achieve consistent weld quality while reducing handling time and operator movement. The adoption of higher-capacity systems is also gaining traction as manufacturers increasingly work with larger and heavier components.
 To learn more about this report, Download Free Sample Report
Rising adoption of automated welding technologies is further supporting market growth. Fabricators are integrating rotators with welding manipulators, robotic systems, sensors, and programmable controls to improve production consistency and throughput. Automatic and self-aligning models can reduce setup requirements while maintaining controlled rotation speeds, making them suitable for repetitive fabrication tasks. As manufacturers focus on reducing production cycle times, improving workplace efficiency, and addressing skilled labor constraints, investment in mechanized welding-positioning equipment is expected to increase.
Market Dynamics
The pipe welding rotator industry is shaped by increasing demand for efficient fabrication of large cylindrical work pieces, rising adoption of mechanized welding, and growing preference for accurate and repeatable production processes. Demand varies according to infrastructure development, fabrication capacity, shipbuilding activity, energy projects, and investments in automated welding cells. At the same time, high equipment costs, varying workpiece dimensions, and the need for skilled operators can influence purchasing decisions. Technological advancements in self-aligning, hydraulic, and automated systems are gradually shifting the market toward more sophisticated equipment.
The growing use of robotic and mechanized welding is creating stronger demand for compatible pipe welding rotators. Automated welding cells require precise and controlled workpiece movement to maintain consistent welding speed, positioning, and heat application. Rotators equipped with variable-speed controls, programmable operation, and automated alignment can support these requirements while reducing manual intervention.
The shift toward automation is particularly relevant for fabrication facilities handling repetitive welding jobs and large cylindrical components. Integrating rotators with welding manipulators, robotic arms, and digital control systems can improve production throughput and dimensional consistency. This trend is encouraging users to replace basic positioning equipment with more advanced systems capable of supporting semi-automated and fully automated workflows.
The relatively high purchase cost of advanced pipe welding rotators can limit adoption, particularly among small and medium-sized fabrication businesses. High-capacity systems require stronger structural components, precision drive mechanisms, specialized controls, and safety features, increasing the overall investment. Additional expenses associated with installation, integration, and operator training can further raise the initial expenditure.
Growing fabrication of oversized pipes, pressure vessels, storage structures, and other heavy cylindrical components is creating opportunities for customized rotator solutions. Users increasingly require equipment tailored to specific load capacities, pipe diameters, rotation speeds, and production layouts rather than standardized systems alone. This is encouraging manufacturers to develop modular and application-specific designs.
The integration of hydraulic fit-up mechanisms, anti-creep features, automatic alignment, and remote controls provides further opportunities for product differentiation. Suppliers capable of combining high load-bearing capacity with automation and precise positioning can address specialized fabrication requirements and expand their presence in large-scale production facilities.
Market Concentration & Characteristics
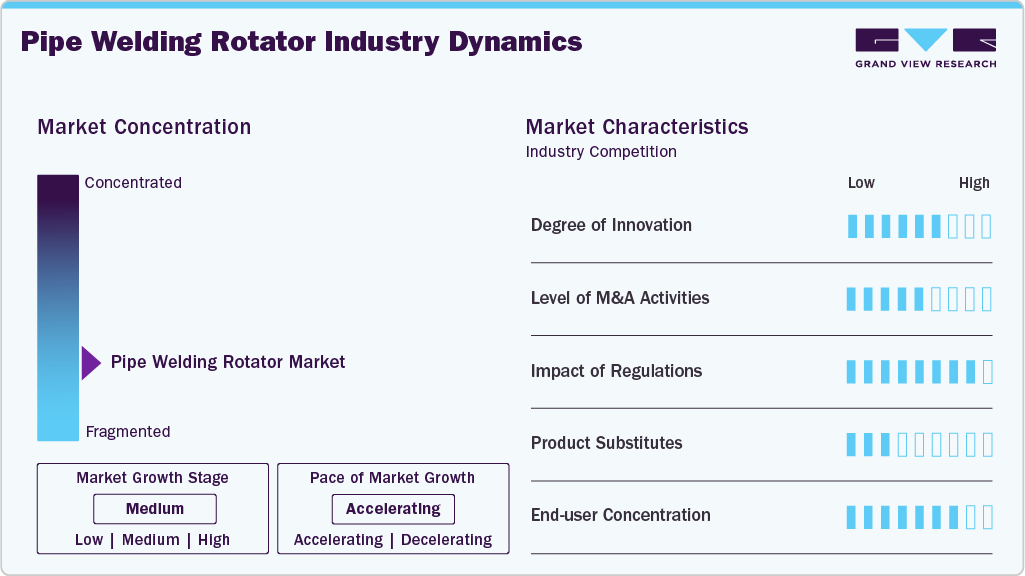
The pipe welding rotator industry is moderately fragmented, with competition spread across global welding-equipment manufacturers, specialized rotator producers, and regional fabricators. Market participants differentiate through load capacity, rotation accuracy, automation level, customization, and compatibility with different pipe dimensions. The presence of numerous suppliers serving specific geographic and application requirements limits overall consolidation, while established manufacturers benefit from engineering capabilities, advanced automation, product reliability, and broader distribution networks.
 To learn more about this report, Download Free Sample Report
The pipe welding rotator industry is experiencing a moderate-to-high degree of innovation, driven by the integration of automation, variable-speed drives, digital controls, and sensor-based positioning. Manufacturers are developing self-aligning, anti-creep, and hydraulic systems that improve workpiece stability and reduce setup requirements. Integration with robotic welding equipment is also increasing, particularly in facilities seeking higher throughput and consistent weld execution.
Regulatory requirements have a moderate impact on the market, primarily through standards for workplace safety, equipment reliability, electrical protection, and welding quality. Fabrication facilities must comply with applicable occupational safety requirements while equipment used in critical applications may need to meet relevant technical and certification standards. These requirements encourage users to select rotators with appropriate load ratings, guarding, emergency controls, and reliable operating mechanisms.
End user concentration is moderate, as demand comes from a diverse group of fabrication-intensive industries rather than a single customer segment. Large fabrication yards and infrastructure projects can generate substantial orders for high-capacity systems, while smaller workshops typically purchase standard or lower-capacity models. This mix creates opportunities across different customer sizes and applications, although major projects can cause periodic fluctuations in equipment demand.
Analyst Perspective
The market is moving toward higher automation, greater handling capacity, and more precise workpiece control as fabrication facilities seek to improve welding consistency and production efficiency. Self-aligning systems currently benefit from their flexibility across different pipe diameters, while anti-creep and semi-automatic solutions are gaining attention for applications involving long and heavy workpieces. Demand from energy infrastructure, power-generation projects, shipbuilding, construction, and automotive fabrication is creating a diverse customer base, with Asia Pacific offering significant expansion potential. Integration with robotic welding systems, hydraulic fit-up mechanisms, and digitally controlled rotation is expected to remain an important direction for product development, while customized equipment for specialized load and dimensional requirements provides additional scope for manufacturers.
Product Insights
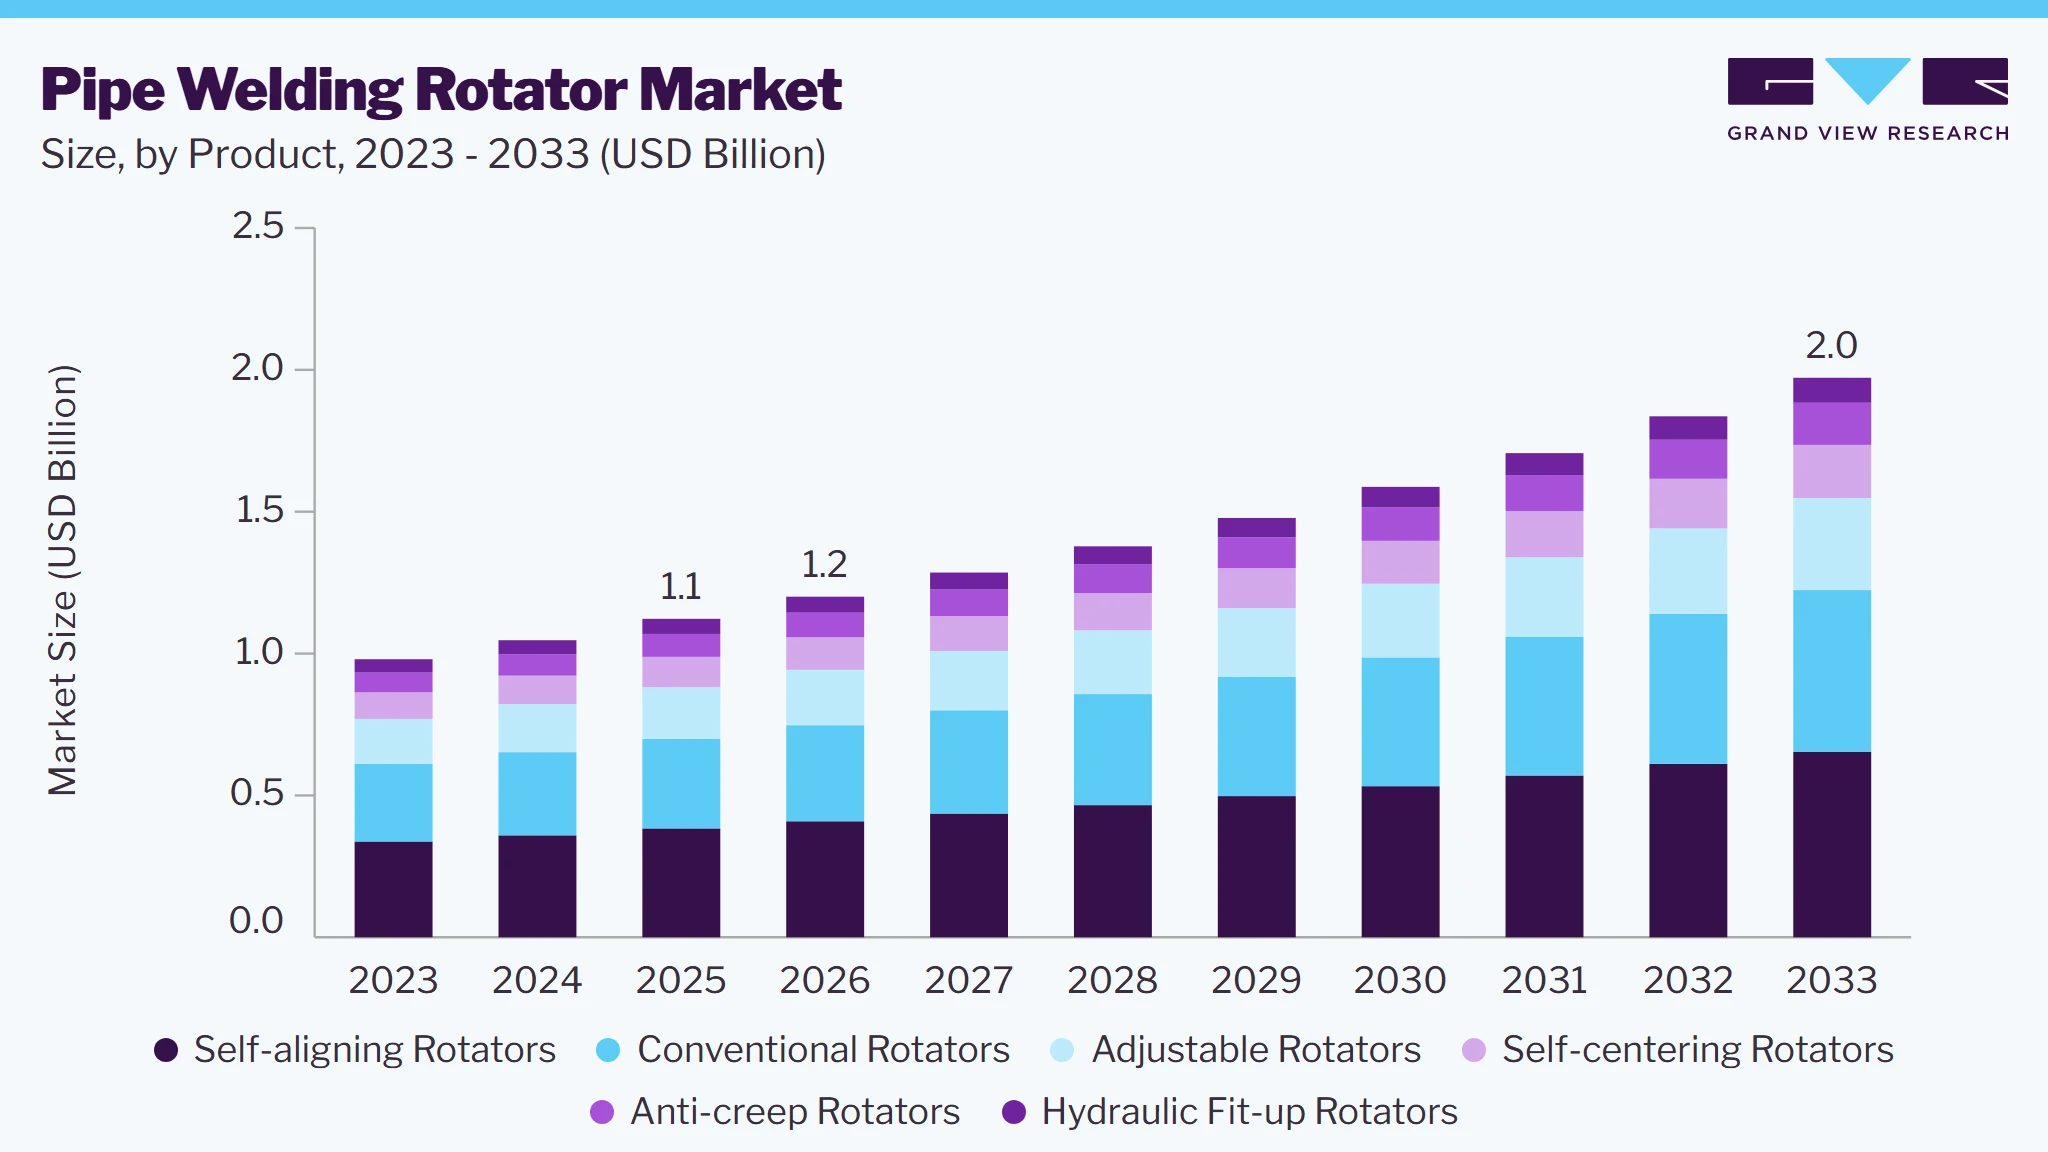
The self-aligning rotators segment dominated the market in 2025, supported by their ability to accommodate different pipe diameters with limited manual adjustment. These systems automatically position their rollers around the workpiece, reducing setup time and improving stability during rotation. Their versatility makes them suitable for fabrication facilities handling varying pipe sizes and heavy cylindrical components, where consistent positioning is important for maintaining welding accuracy and productivity.
The anti-creep rotators segment is expected to register the fastest growth over the forecast period at CAGR of 8.0%, driven by increasing demand for stable handling of long and heavy workpieces during welding. These systems help minimize axial movement of the pipe while it rotates, supporting accurate weld positioning and reducing interruptions during fabrication. Growing use in large-scale fabrication projects and automated welding setups is likely to encourage adoption of anti-creep designs, particularly where dimensional accuracy and continuous operation are important.
Operation Mode Insights
The automatic segment dominated the market in 2025, driven by the increasing adoption of mechanized and robotic welding systems in fabrication facilities. Automatic rotators provide controlled rotation speed, precise workpiece movement, and consistent positioning, which supports repeatable welding operations and higher production throughput. Their ability to integrate with welding manipulators, robotic arms, and programmable controls makes them well suited for large-scale and repetitive fabrication activities.
The semi-automatic segment is expected to witness strong growth at CAGR of 7.2% over the forecast period, as fabricators seek to improve productivity without making the higher investment required for fully automated welding cells. These systems reduce manual handling while allowing operators to retain control over key welding activities, offering a practical balance between automation and flexibility. Their suitability for facilities with varied production volumes and workpiece specifications is expected to support wider adoption.
End Use Insights
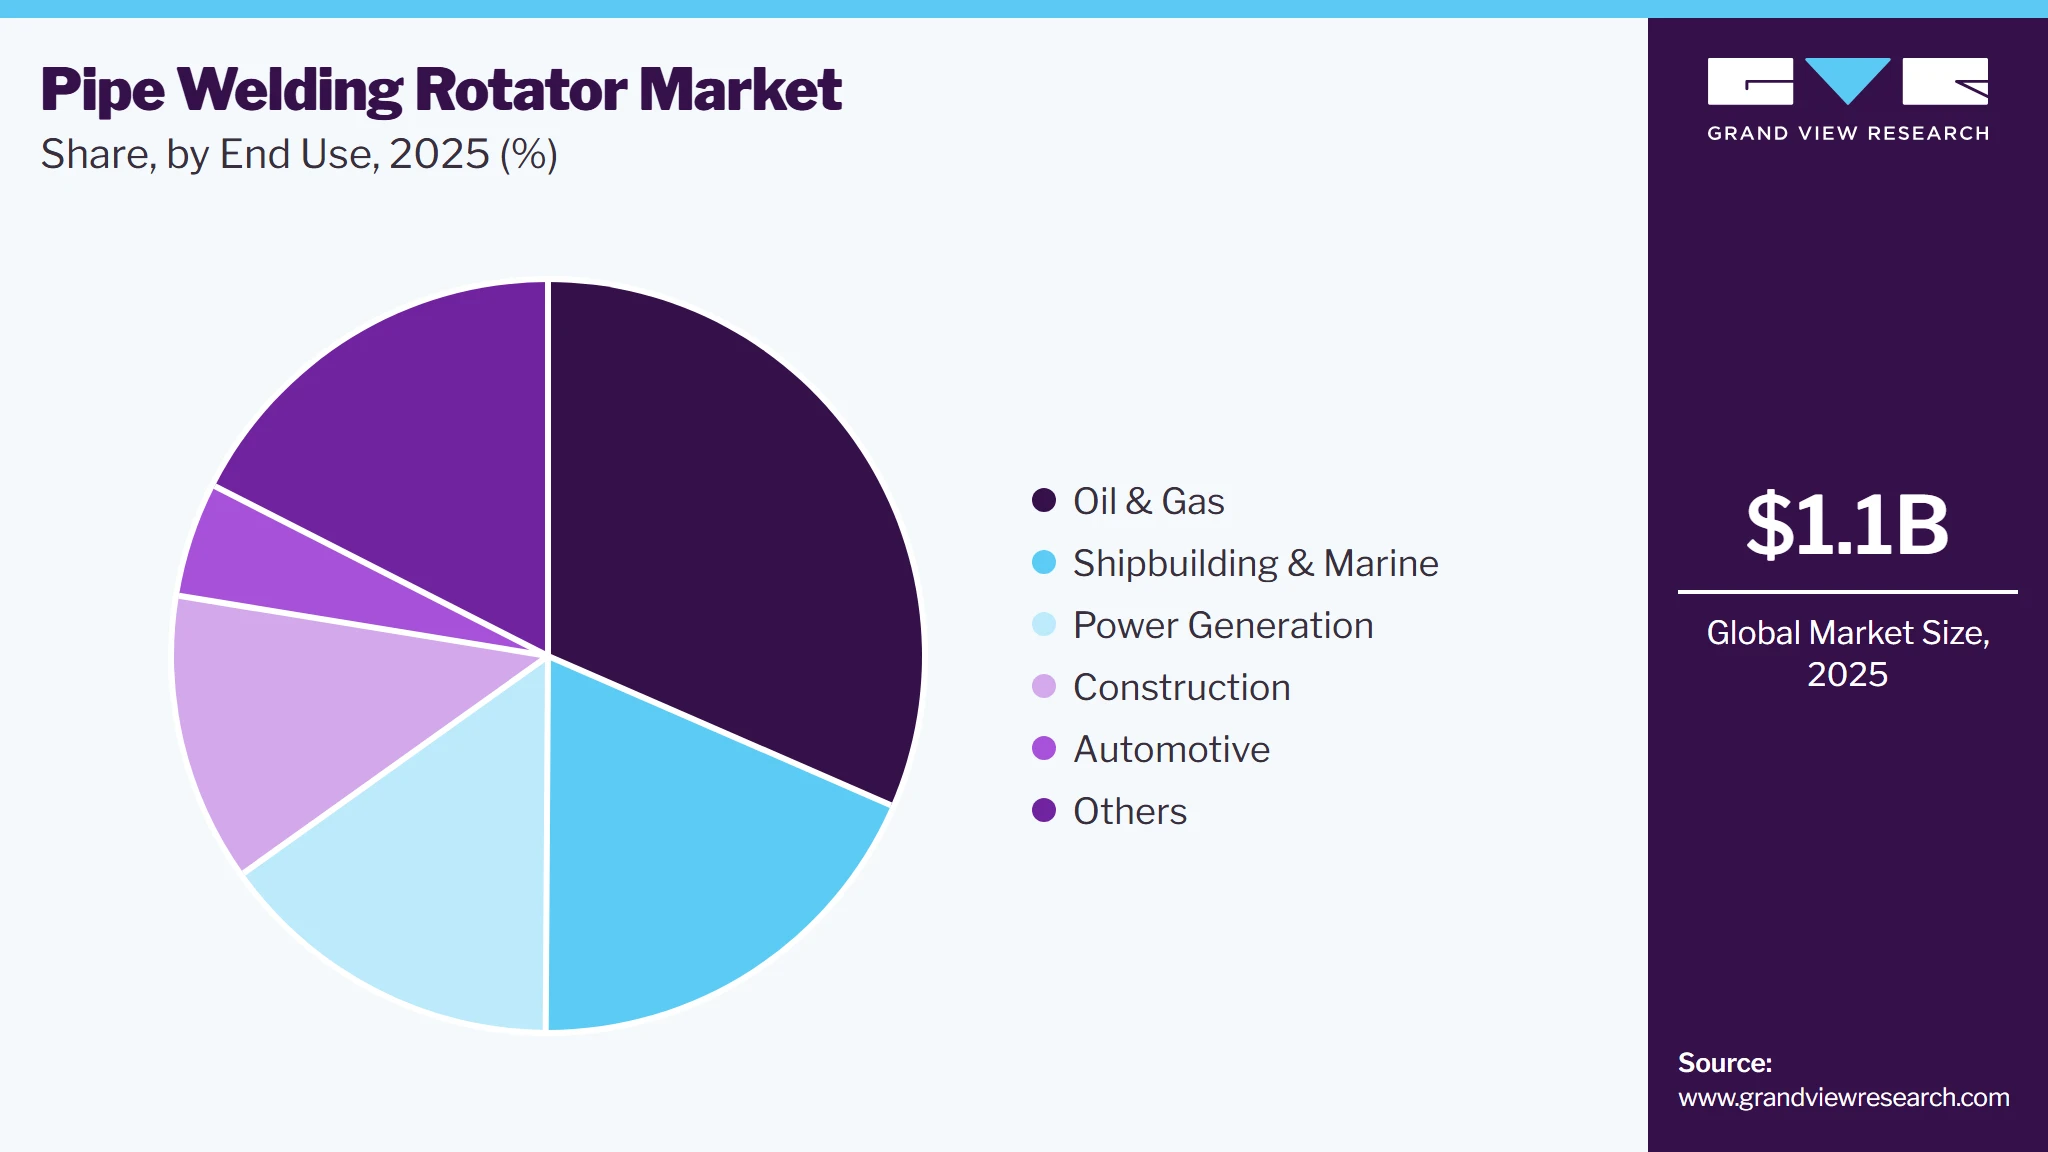
The oil & gas segment dominated the market, supported by extensive fabrication of pipelines, pressure vessels, storage tanks, and large-diameter tubular components. These applications often involve heavy and lengthy workpieces that require controlled rotation for efficient circumferential welding. The continued development and upgrading of pipeline networks, processing facilities, and related infrastructure increases the need for reliable positioning equipment across fabrication operations.
 To learn more about this report, Download Free Sample Report
The power generation segment is expected to register the fastest growth at CAGR of 8.1% over the forecast period, driven by investments in new generating capacity, equipment upgrades, and fabrication of large boilers, pressure vessels, piping assemblies, and other cylindrical components. Increasing emphasis on weld consistency and fabrication efficiency is encouraging the use of mechanized positioning systems in power equipment production. The expansion of conventional and renewable power infrastructure, along with modernization of existing facilities, is expected to create additional demand for advanced rotators.
Regional Insights
Asia Pacific Pipe Welding Rotator Market Trends
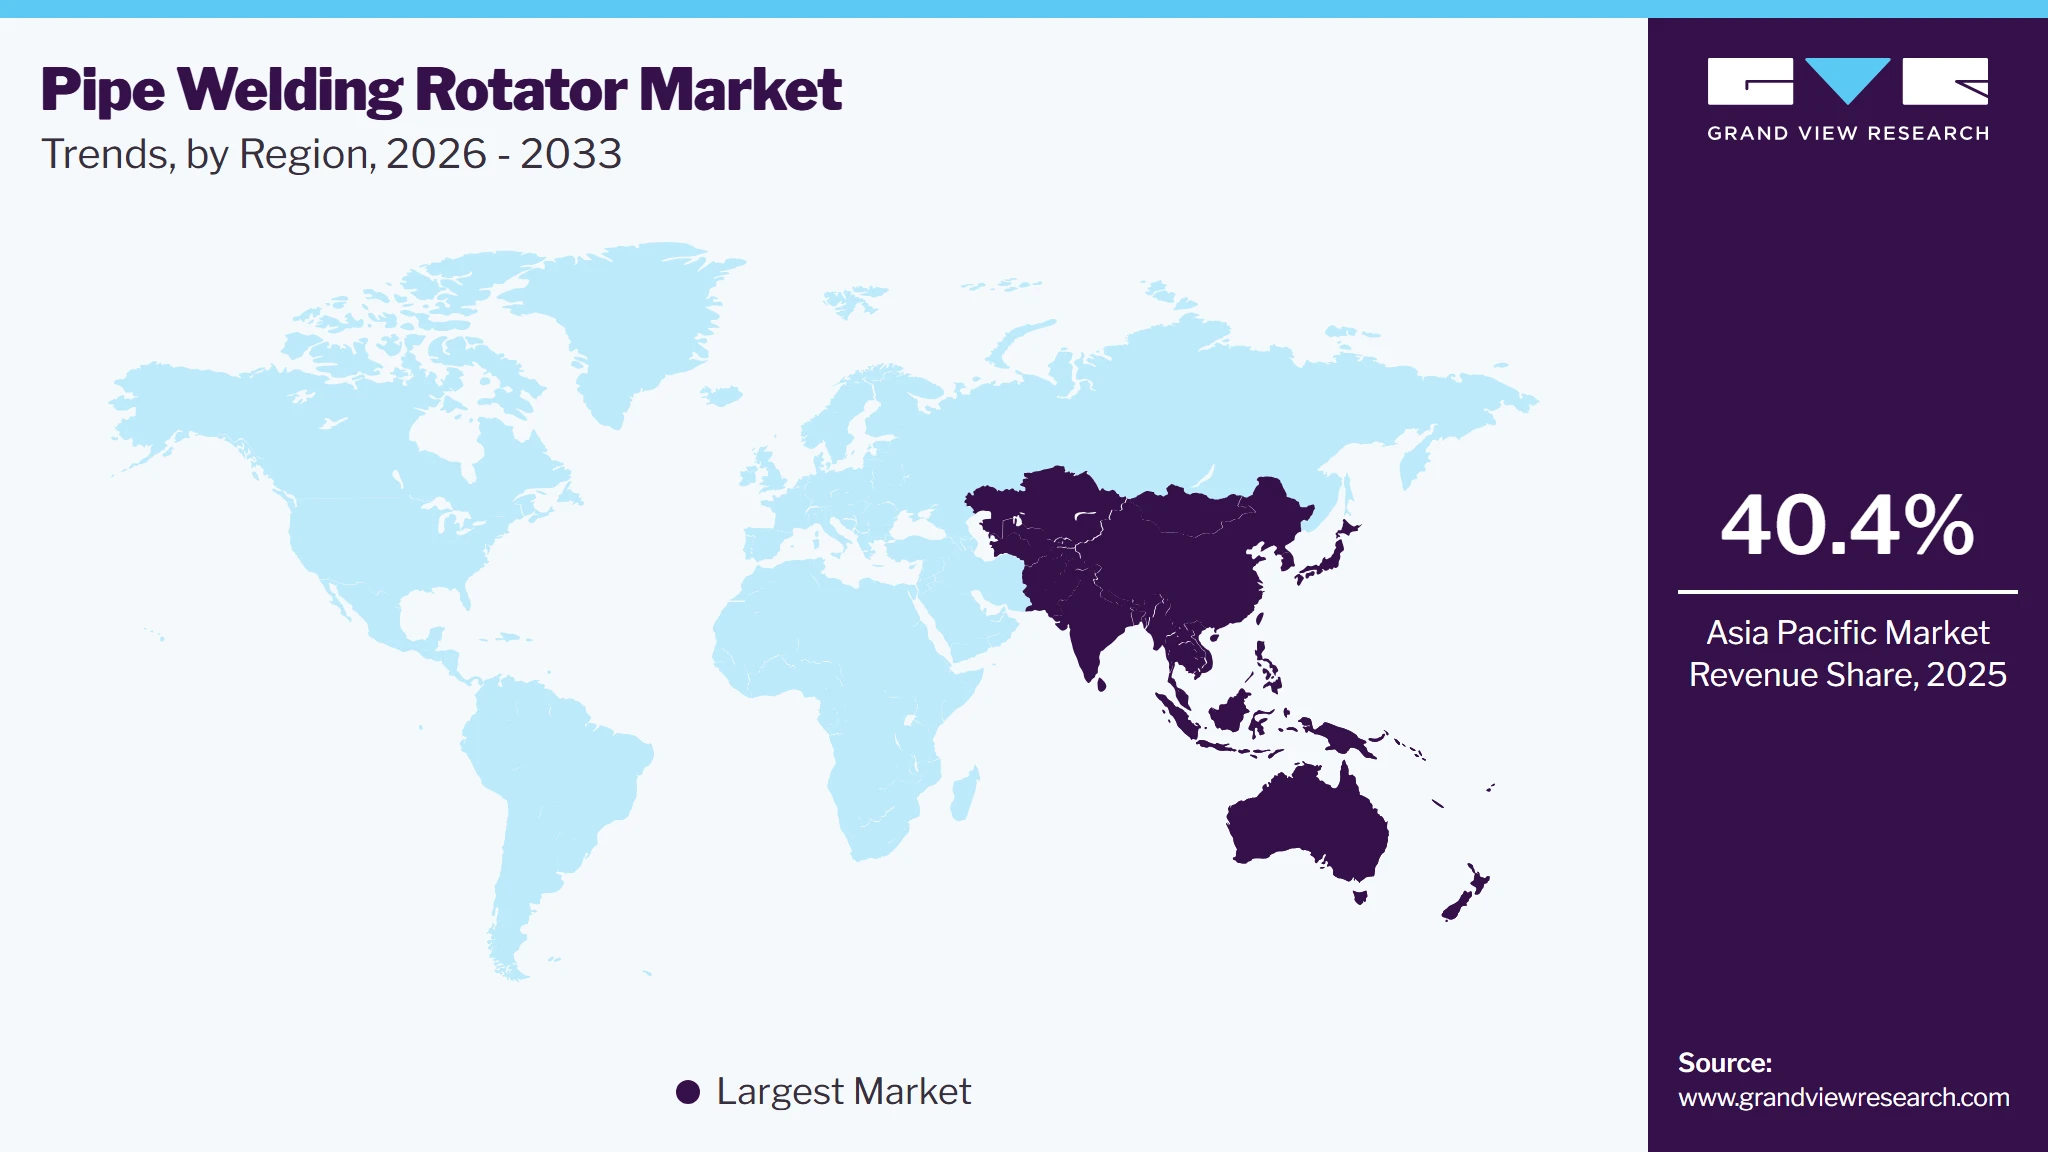
Asia Pacific dominated the market with a share of 40.4% in 2025. Asia Pacific is expected to remain the fastest-growing region projected to grow at 8.5% over the forecast period, supported by extensive fabrication capacity, infrastructure expansion, and rising investments in shipyards, power facilities, and pipeline networks. Strong manufacturing activity across China, India, Japan, and South Korea is creating sustained demand for equipment that can improve welding productivity and handling of large cylindrical components. Increasing adoption of automated fabrication technologies is further strengthening regional demand.
 To learn more about this report, Download Free Sample Report
China pipe welding rotator industry dominated the Asia Pacific market, supported by its extensive manufacturing capacity, large-scale infrastructure development, and strong fabrication ecosystem. The country has substantial activity across shipbuilding, machinery production, power equipment, transportation infrastructure, and large structural fabrication, creating broad demand for equipment used to handle and weld cylindrical components. Increasing investment in automated production systems and advanced welding technologies is further encouraging the adoption of self-aligning, automatic, and high-capacity rotators across fabrication facilities.
The pipe welding rotator industry in India is poised for strong growth in the market, supported by the expansion of its automotive manufacturing and broader fabrication activities. Data from the Society of Indian Automobile Manufacturers (SIAM) indicates that total vehicle production reached 34.7 million units in FY2025-26, comprising 5.5 million passenger vehicles and 1.2 million commercial vehicles. Passenger vehicle output rose from 5.1 million units in FY2024-25 to 5.5 million units, while commercial vehicle production increased from 1.0 million to 1.2 million units. The rising scale of vehicle manufacturing, combined with ongoing industrial and infrastructure development, is encouraging manufacturers to invest in mechanized welding and workpiece-positioning equipment, creating further opportunities for pipe welding rotators in India.
North America Pipe Welding Rotator Market Trends
The pipe welding rotator industry in North America is experiencing gradual expansion as manufacturers increase automation across welding and metal fabrication operations. Investments in energy infrastructure, shipbuilding, industrial facilities, and large-scale construction projects are supporting the need for reliable workpiece positioning equipment. Labor availability challenges and efforts to improve production consistency are also encouraging fabrication companies to integrate rotators with robotic and mechanized welding systems.
U.S. Pipe Welding Rotator Market Trends
The pipe welding rotator industry in the U.S. dominated the North American market, supported by its extensive construction, manufacturing, energy, and pipeline infrastructure. According to the U.S. Census Bureau, total construction spending reached an annualized USD 2.2 trillion in July 2026, with nonresidential construction accounting for a substantial portion of activity. The U.S. Energy Information Administration reported that natural-gas pipeline projects completed in 2025 added approximately 6.3 billion cubic feet per day (Bcf/d) of capacity, with 85% of the additions serving the South Central region. These large-scale infrastructure and fabrication requirements support demand for equipment used to position and rotate pipes, vessels, and other cylindrical components during welding. Increasing investment in automated fabrication processes is also creating opportunities for advanced rotators with controlled movement and integration capabilities.
Europe Pipe Welding Rotator Market Trends
The pipe welding rotator industry in Europe is witnessing steady market growth, supported by modernization of fabrication facilities, advanced engineering capabilities, and continued investments in marine, energy, and industrial infrastructure. The region has a strong emphasis on production efficiency, worker safety, and precision welding, encouraging the replacement of basic positioning equipment with automated and digitally controlled systems. Demand is also supported by specialized fabrication requirements for complex and high-value components.
Germany pipe welding rotator industry dominated the Europe market, supported by its strong automotive manufacturing and engineering base. According to the German Association of the Automotive Industry (VDA), 4.15 million passenger cars were produced domestically in 2025, up 2% from 2024. Electric passenger-car production reached 1.67 million units, increasing 23% year over year, while electric vehicles represented around 40% of total domestic passenger-car production. The country's extensive vehicle production, machinery manufacturing, and metal fabrication activities create demand for accurate workpiece positioning and mechanized welding equipment. Continued automation and the shift toward electric-vehicle production are also supporting investment in advanced fabrication systems, including rotators used for cylindrical components and welded assemblies.
The pipe welding rotator industry in Italy is expected to witness notable growth in the market, driven by its well-established machinery, metalworking, shipbuilding, and industrial equipment sectors. The presence of numerous fabrication facilities creates demand for flexible positioning systems capable of handling different workpiece sizes and production requirements. Growing emphasis on manufacturing efficiency and automation is further supporting the transition toward semi-automatic and automatic rotator solutions.
Middle East & Africa Pipe Welding Rotator Market Trends
The pipe welding rotator industry in Middle East & Africa is developing alongside investments in energy infrastructure, construction, industrial facilities, and large-scale fabrication projects. Major infrastructure programs and expansion of processing and utility capacity are generating demand for equipment capable of handling heavy cylindrical structures efficiently. Adoption of automated welding and positioning technologies is gradually increasing as fabricators seek improved productivity, consistent weld execution, and reduced dependence on manual handling.
Saudi Arabia pipe welding rotator industry dominated the Middle East & Africa market, supported by extensive energy infrastructure, large-scale construction programs, and ongoing development of industrial and fabrication facilities. The country's continued investment in pipelines, storage infrastructure, power projects, and major construction developments creates demand for equipment capable of handling large and heavy cylindrical components. Increasing emphasis on project execution efficiency and mechanized welding is also encouraging the adoption of advanced rotators across fabrication operations.
Latin America Pipe Welding Rotator Market Trends
The pipe welding rotator industry in Latin America is registering growing demand as infrastructure development and industrial investment stimulate fabrication activities across several countries. Expansion of energy projects, transportation infrastructure, marine facilities, and heavy equipment production is creating requirements for systems capable of handling large tubular structures. Greater interest in productivity-enhancing machinery is also encouraging workshops to move from manually positioned workpieces toward mechanized rotation solutions.
Brazil pipe welding rotator industry represents a significant market in Latin America, supported by its established steel fabrication, shipbuilding, energy, infrastructure, and machinery industries. Development of pipelines, industrial facilities, power infrastructure, and large fabricated structures creates demand for equipment capable of safely positioning and rotating heavy cylindrical workpieces during welding. Growing efforts to improve fabrication efficiency and to expand mechanized production are also encouraging the use of self-aligning and automated rotator systems.
Key Pipe Welding Rotator Company Insights
Some of the key players operating in the market include Pemamek, Koike Aronson, Inc., and LJ Welding.
-
Pemamek is a Finland based provider of welding automation and production technology, serving heavy fabrication industries worldwide. The company develops a broad range of equipment, including welding positioners, roller beds, robotic welding systems, and column-and-boom solutions, along with integrated production lines. Its roller bed systems are relevant to pipe welding applications, where they support controlled rotation and positioning of pipes, tubes, and other cylindrical workpieces during fabrication. Pemamek serves sectors such as shipbuilding, power generation, offshore, wind energy, process equipment, and heavy machinery, with its solutions deployed across international markets.
-
Koike Aronson is a U.S. based manufacturer of cutting, positioning, and welding equipment, with manufacturing operations in Arcade. The company offers a range of turning rolls and pipe rolls designed to support and rotate cylindrical workpieces such as pipes, tanks, and pressure vessels. Its portfolio includes adjustable pipe rolls, Aronson and Ransome turning rolls, anti-drift systems, and powered fit-up rolls, with solutions available for applications requiring different workpiece sizes and load capacities. The company also provides welding manipulators and other positioning equipment that can be integrated with turning rolls for mechanized and automated fabrication.
Key Pipe Welding Rotator Companies
The following key companies have been profiled for this study on the pipe welding rotator market.
-
Pemamek
-
Koike Aronson, Inc.
-
LJ Welding
-
Gullco International, Inc.
-
F. Bode & Sons Ltd. Welding Positioners
-
SENLISWELD
-
Wuxi OLIVET Machinery Equipment Co., Ltd.
-
Carmac Pvt Limited
-
Key Plant Automation Ltd.
-
Mogra Engineering Pvt. Ltd.
-
DUMETA B.V.
-
Wuxi Fengwei Mechanical Equipment Co., Ltd.
-
ProArc Welding & Cutting Systems Co., Ltd.
-
Huaheng Automation Pvt. Ltd.
-
Wuxi ABK Machinery Co., Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Pemamek; Koike Aronson, Inc.; Gullco International, Inc.; F. Bode & Sons Ltd. Welding Positioners; DUMETA B.V.)
- Focus on high-capacity and customized rotators for large-scale fabrication applications.
- Integrate rotators with welding manipulators, robotic systems, and automated production lines.
- Expand global distribution and technical support to serve large industrial customers.
- Extensive experience in welding automation and workpiece-positioning technologies.
- Broad product portfolios covering self-aligning, conventional, anti-creep, and automated rotator systems.
- Strong engineering capabilities and established relationships with major fabrication companies.
- Higher equipment and integration costs can restrict adoption among smaller fabrication workshops.
- Advanced systems often require specialized installation, programming, and operator training.
- Complex product configurations may result in longer lead times for highly customized orders.
Emerging & Regional Players (e.g., ENLISWELD; Wuxi OLIVET Machinery Equipment Co., Ltd.; Carmac Pvt Limited; Key Plant Automation Ltd.; Mogra Engineering Pvt. Ltd.; Wuxi Fengwei Mechanical Equipment Co., Ltd.; ProArc Welding & Cutting Systems Co., Ltd.; Huaheng Automation Pvt. Ltd.)
- Offer cost-effective rotators tailored to regional fabrication requirements and specific pipe dimensions.
- Target small and medium-sized workshops requiring flexible and customized positioning equipment.
- Gradually expand portfolios toward self-aligning, hydraulic, semi-automatic, and automated rotator solutions.
- Competitive pricing helps address customers with limited equipment budgets.
- Greater flexibility allows customization based on load capacity, pipe diameter, and workshop requirements.
- Regional presence enables faster customer response and closer relationships with local fabricators.
- Limited international distribution networks can restrict access to large overseas projects.
- Smaller R&D capabilities may slow development of advanced automation and control technologies.
- Lower brand recognition compared with established global welding-equipment manufacturers can affect large-project opportunities.
Recent Developments
-
In June 2026, Pemamek acquired Mach Machines' business operations to strengthen its North American presence and expand its robotic welding automation capabilities. The deal increases its ability to provide integrated, automated welding solutions that complement rotators and positioning equipment.
-
In April 2025, Pemamek expanded its welding automation capabilities through its collaboration with Mach Machines, strengthening its position in automated fabrication solutions. The development supports the integration of advanced welding technologies for heavy fabrication applications and complements Pemamek’s existing portfolio of welding positioners, roller beds, and automated welding systems.
-
In April 2025, Pemamek secured an order for three PEMA WS2 welding automation stations for offshore wind-tower production. The companies are also developing a long-term technical roadmap for welding processes, supporting broader automation adoption in heavy cylindrical fabrication.
Global Pipe Welding Rotator Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.1 billion
Estimated market size in 2026
USD 1.2 billion
Revenue forecast in 2033
USD 2.0 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, operation mode, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; China; Japan; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Pemamek; Koike Aronson, Inc.; LJ Welding; Gullco International, Inc.; F. Bode & Sons Ltd. Welding Positioners; SENLISWELD; Wuxi OLIVET Machinery Equipment Co., Ltd.; Carmac Pvt Limited; Key Plant Automation Ltd.; Mogra Engineering Pvt. Ltd.; DUMETA B.V.; Wuxi Fengwei Mechanical Equipment Co., Ltd.; ProArc Welding & Cutting Systems Co., Ltd.; Huaheng Automation Pvt. Ltd.; Wuxi ABK Machinery Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pipe Welding Rotator Market Report Segmentation
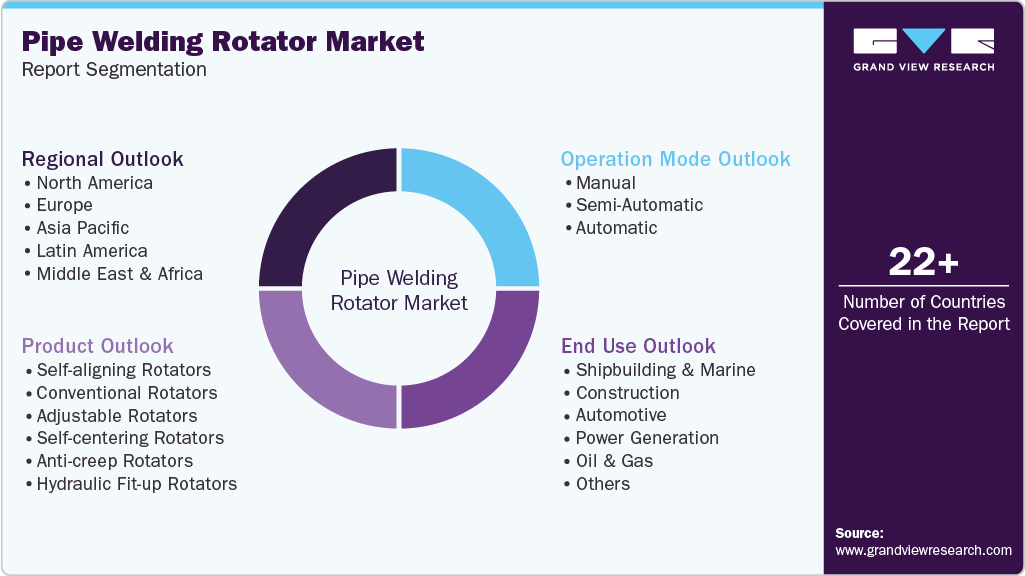
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pipe welding rotator market report based on product, operation mode, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Self-aligning Rotators
-
Conventional Rotators
-
Adjustable Rotators
-
Self-centering Rotators
-
Anti-creep Rotators
-
Hydraulic Fit-up Rotators
-
-
Operation Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Manual
-
Semi-Automatic
-
Automatic
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Shipbuilding & Marine
-
Construction
-
Automotive
-
Power Generation
-
Oil & Gas
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The pipe welding rotator market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pipe welding rotator segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
Self-aligning Rotators
Revenue generated from the sale of self-aligning welding rotators that automatically adjust the roller position according to the diameter of the workpiece. Revenue includes standard and customized units used to rotate pipes, tanks, pressure vessels, and other cylindrical components during welding and fabrication.
Conventional Rotators
Revenue generated from conventional turning-roll systems in which roller positioning is fixed or requires manual adjustment before operation. This includes equipment used for supporting and rotating cylindrical workpieces during welding, assembly, coating, and related fabrication processes.
Adjustable Rotators
Revenue generated from rotators featuring adjustable roller spacing or configuration to accommodate different workpiece diameters. The segment covers equipment sold to fabrication facilities requiring flexibility across multiple pipe sizes and cylindrical components.
Self-centering Rotators
Revenue generated from rotators designed to automatically maintain the workpiece in a central position between the supporting rollers. Revenue includes systems used where stable positioning and consistent rotation are required for accurate welding and fabrication.
Anti-creep Rotators
Revenue generated from rotators equipped with anti-creep or anti-drift mechanisms that minimize unwanted axial movement of the workpiece during rotation. This includes systems designed for long, heavy, or large-diameter components requiring stable positioning throughout welding operations.
Hydraulic Fit-up Rotators
Revenue generated from hydraulic rotator systems that combine workpiece rotation with hydraulic lifting, positioning, or fit-up functions. The segment includes equipment used for aligning and preparing large or heavy cylindrical sections before and during welding.
Operation Mode
Revenue Capture Definition
Manual
Revenue generated from manually operated welding rotators where operators control positioning, adjustment, rotation, or operating parameters. This includes basic and mechanically adjusted systems primarily used in fabrication workshops and applications with lower automation requirements.
Semi-Automatic
Revenue generated from welding rotators that automate selected functions such as rotation speed or movement while requiring operator involvement for loading, alignment, welding, or process control. The segment includes equipment offering a balance between manual operation and full automation.
Automatic
Revenue generated from fully automated rotator systems capable of programmed rotation, speed regulation, positioning, and process synchronization. Revenue includes systems integrated with robotic welding equipment, welding manipulators, sensors, and computerized controls for repetitive production.
End Use
Revenue Capture Definition
Shipbuilding & Marine
Revenue generated from rotators supplied for manufacturing and welding ship sections, marine pipelines, shafts, tanks, tubular structures, and other cylindrical components. This includes equipment used in shipyards and marine fabrication facilities for handling large workpieces.
Construction
Revenue generated from rotators used in the fabrication of structural pipes, steel columns, tubular assemblies, infrastructure components, and other cylindrical structures associated with construction projects.
Automotive
Revenue generated from rotators used for welding and positioning cylindrical automotive components, shafts, exhaust assemblies, structural parts, and other fabricated vehicle components. The segment covers equipment supplied to vehicle and component manufacturing facilities.
Power Generation
Revenue generated from rotators used in manufacturing and assembling boilers, pressure vessels, piping systems, turbine-related components, and other large cylindrical equipment for power-generation facilities.
Oil & Gas
Revenue generated from rotators used for fabricating pipelines, pressure vessels, storage tanks, process piping, and other tubular or cylindrical equipment across petroleum and natural-gas infrastructure. Revenue includes systems supplied for both project-based fabrication and dedicated production facilities.
Others
Revenue generated from rotators used across applications outside the defined end-use categories, including heavy machinery, industrial equipment, general metal fabrication, specialized engineering, and other cylindrical workpiece applications.
Estimation Model
Layer Name
Key Question
Description
Industry Demand Assessment
What is the overall demand for pipe welding rotators?
Assess demand based on pipe fabrication activity, welding requirements, infrastructure development, industrial production, and investments across major end-use sectors and regions.
Equipment Adoption Analysis
How widely are pipe welding rotators being adopted?
Estimate adoption by evaluating fabrication facilities, welding automation penetration, replacement demand, equipment capacity requirements, and preference for manual, semi-automatic, and automatic systems.
Segment & Regional Allocation
How is demand distributed across products, operation modes, end uses, and regions?
Allocate the addressable market across self-aligning, conventional, adjustable, self-centering, anti-creep, and hydraulic fit-up rotators; operating modes; end-use industries; and key geographic markets.
Revenue Estimation
What is the total market revenue generated from pipe welding rotators?
Calculate market revenue by combining estimated equipment volumes with applicable selling values across product categories, operating modes, end uses, and regions, followed by aggregation to determine the overall market size.
Customization Table
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered a comprehensive regional and country-level assessment covering North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The analysis further identified key countries within each region and evaluated their market position based on fabrication activity, infrastructure development, industrial production, and relevant end-use demand.
Provides a clear understanding of geographic demand patterns, regional growth opportunities, and country-specific factors influencing the pipe welding rotator market.
Competitive Benchmarking
Delivered a detailed competitive landscape covering major established, emerging, and regional manufacturers. The report evaluates product portfolios, welding rotator capabilities, operating strategies, competitive advantages, limitations, and recent developments such as product launches, partnerships, acquisitions, and expansion activities.
Enables stakeholders to understand the competitive structure, differentiate suppliers based on capabilities, and identify areas of competitive positioning within the market.
Opportunity Assessment
Delivered an opportunity assessment covering high-growth product categories, operation modes, end-use industries, regional markets, automation adoption, and emerging demand areas. The analysis also highlights opportunities arising from increased mechanization, robotic welding integration, customized equipment requirements, and demand for high-capacity rotators.
Helps identify commercially attractive areas for expansion, product development, investment, and market entry while supporting strategic planning and prioritization of growth opportunities.
Frequently Asked Questions About This Report
The global pipe welding rotator market size was estimated at USD 1.1 billion in 2025 and is expected to be USD 1.2 billion in 2026.
The global pipe welding rotator market, in terms of revenue, is expected to grow at a compound annual growth rate of 7.3% from 2026 to 2033 to reach USD 2.0 billion by 2033.
Asia Pacific was the largest regional market, accounting for 40.4% of global revenue in 2025. Its leading position is supported by extensive manufacturing and fabrication capacity, infrastructure development, shipbuilding activity, and increasing adoption of automated welding technologies.
China held the largest country-level share of the global pipe welding rotator market in 2025. Its strong manufacturing base, large-scale infrastructure projects, shipbuilding capacity, machinery production, and extensive fabrication activities provide a substantial customer base for pipe welding and positioning equipment.
The self-aligning rotators segment dominated the market, accounting for 34.2% of global revenue in 2025. Their ability to automatically accommodate different workpiece diameters while maintaining stable roller contact makes them suitable for diverse fabrication requirements and reduces manual setup time.
The automatic segment led the market with a 47.4% revenue share in 2025. Increasing integration of rotators with robotic welding systems, welding manipulators, programmable controls, and automated production lines is supporting their adoption across high-volume fabrication environments.
The oil & gas segment represented the largest end-use category, with a 31.5% revenue share in 2025. Extensive fabrication of pipelines, pressure vessels, storage tanks, and large tubular components creates significant demand for equipment capable of safely rotating and positioning heavy workpieces during welding.
Some of the key players operating in the global pipe welding rotator market include Pemamek; Koike Aronson, Inc.; LJ Welding; Gullco International, Inc.; F. Bode & Sons Ltd. Welding Positioners; SENLISWELD; Wuxi OLIVET Machinery Equipment Co., Ltd.; Carmac Pvt Limited; Key Plant Automation Ltd.; Mogra Engineering Pvt. Ltd.; DUMETA B.V.; Wuxi Fengwei Mechanical Equipment Co., Ltd.; ProArc Welding & Cutting Systems Co., Ltd.; Huaheng Automation Pvt. Ltd.; Wuxi ABK Machinery Co., Ltd.
The market is primarily driven by increasing fabrication of large and heavy cylindrical components, rising adoption of automated and robotic welding systems, and the need for consistent weld quality and higher production efficiency. Growing investments in energy infrastructure, shipbuilding, construction, power-generation facilities, and advanced manufacturing are further increasing demand for controlled workpiece positioning and rotation equipment.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


