
- Home
- »
- Medical Devices
- »
-
Point Of Care CT Imaging Market Size Report, 2026-2033GVR Report cover

Point Of Care CT Imaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Compact CT Scanner, Full-sized CT Scanner), By Application (Neurology, Respiratory), By End-use (Hospitals, ASCs), By Region, And Segment Forecasts
Market Size, 2025
$249.0MMarket Estimate, 2026
$262.3MMarket Forecast, 2033
$392.0MCAGR, 2026–2033
5.9%Point Of Care CT Imaging Market Trends
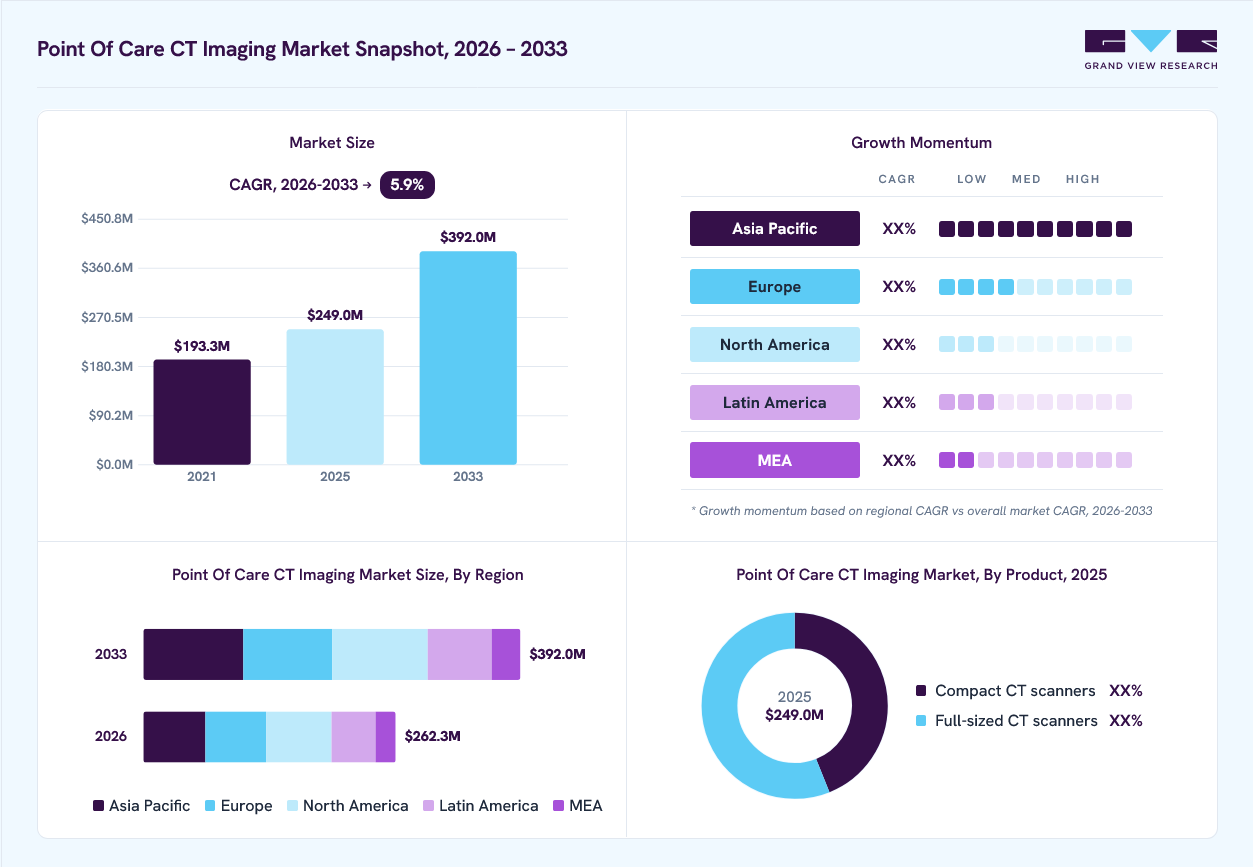
The global point of care CT imaging market size was valued at USD 249.0 million in 2025 and is projected to grow from USD 262.3 million in 2026 to USD 392.0 million by 2033, at a CAGR of 5.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 26.0% in 2025. Increasing prevalence of chronic disorders, technological advancements, growing emphasis on early diagnosis and treatment and the growing aging population are the major factors contributing to the market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Full-sized CT scanners segment led the market with the largest revenue share of 56.1% in 2025.
- By application: Neurology segment led the market with the largest revenue share of 29.2% in 2025.
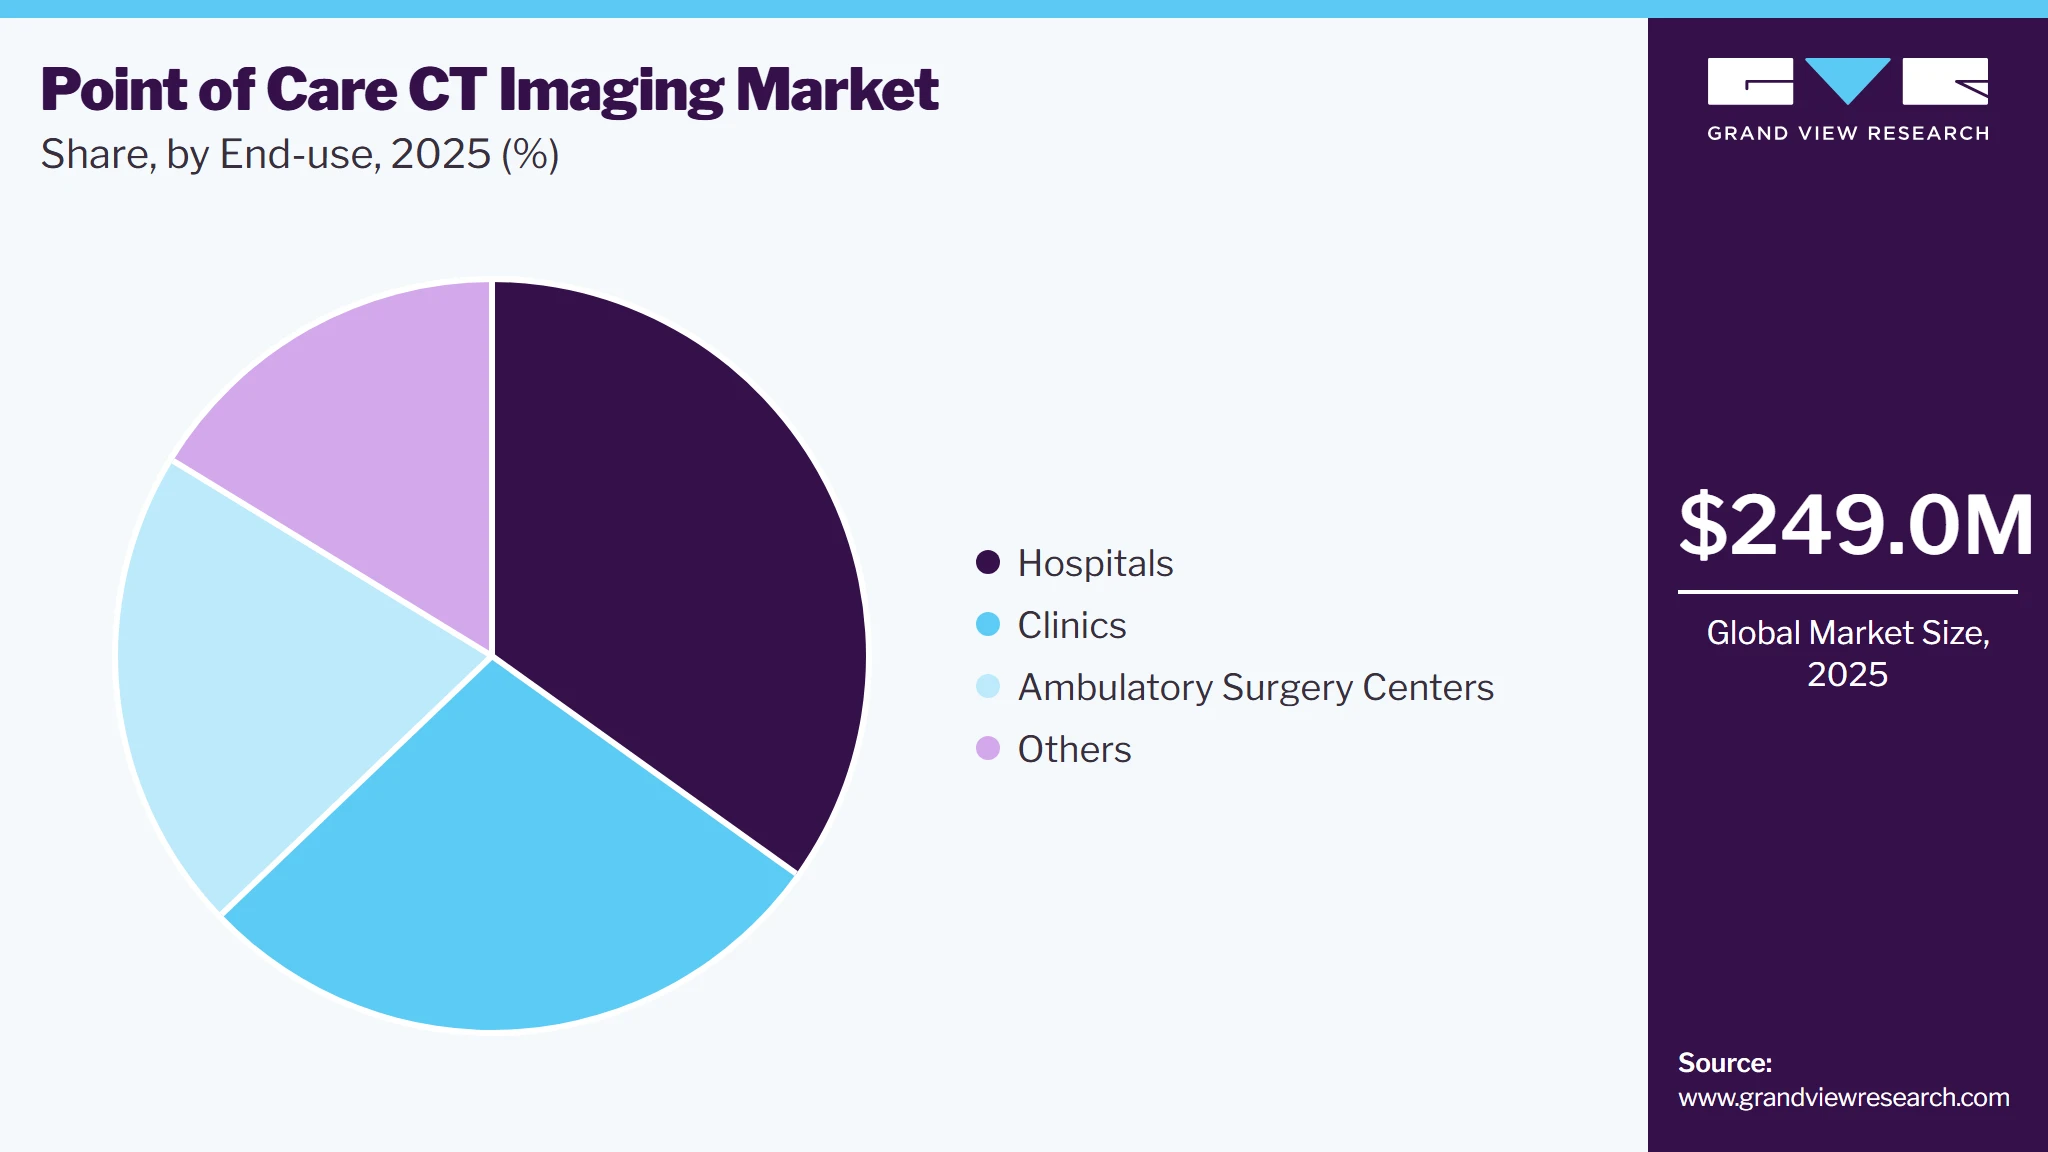
- By end use: Hospital segment led the market with the largest revenue share of 34.9% in 2025.
Regional Highlights
- Largest regional market: North America (26.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 249.0 Million
- Estimated market size in 2026: USD 262.3 Million
- Projected market size by 2033: USD 392.0 Million
- CAGR (2026-2033): 5.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
For instance, according to data published by the Economic and Social Commission for Asia and the Pacific (ESCAP) in 2023, there are approximately 697 million older persons (aged 60 and over) living in Asia and the Pacific. This figure represents about 60 percent of the global elderly population. Technological advancements are expected to have a significant impact on market growth, primarily through the development of portable and compact CT imaging devices. These innovations have made it possible to adopt CT imaging in various healthcare settings. For instance, in emergency rooms, these portable devices allow for immediate imaging of critical patients, facilitating rapid diagnosis and treatment decisions without the need to transfer patients to imaging department. In intensive care units, compact CT scanners enable continuous monitoring of patients with severe conditions, allowing for timely interventions. Furthermore, the portability of these devices is also beneficial in remote or rural locations, where access to advanced imaging facilities is often limited.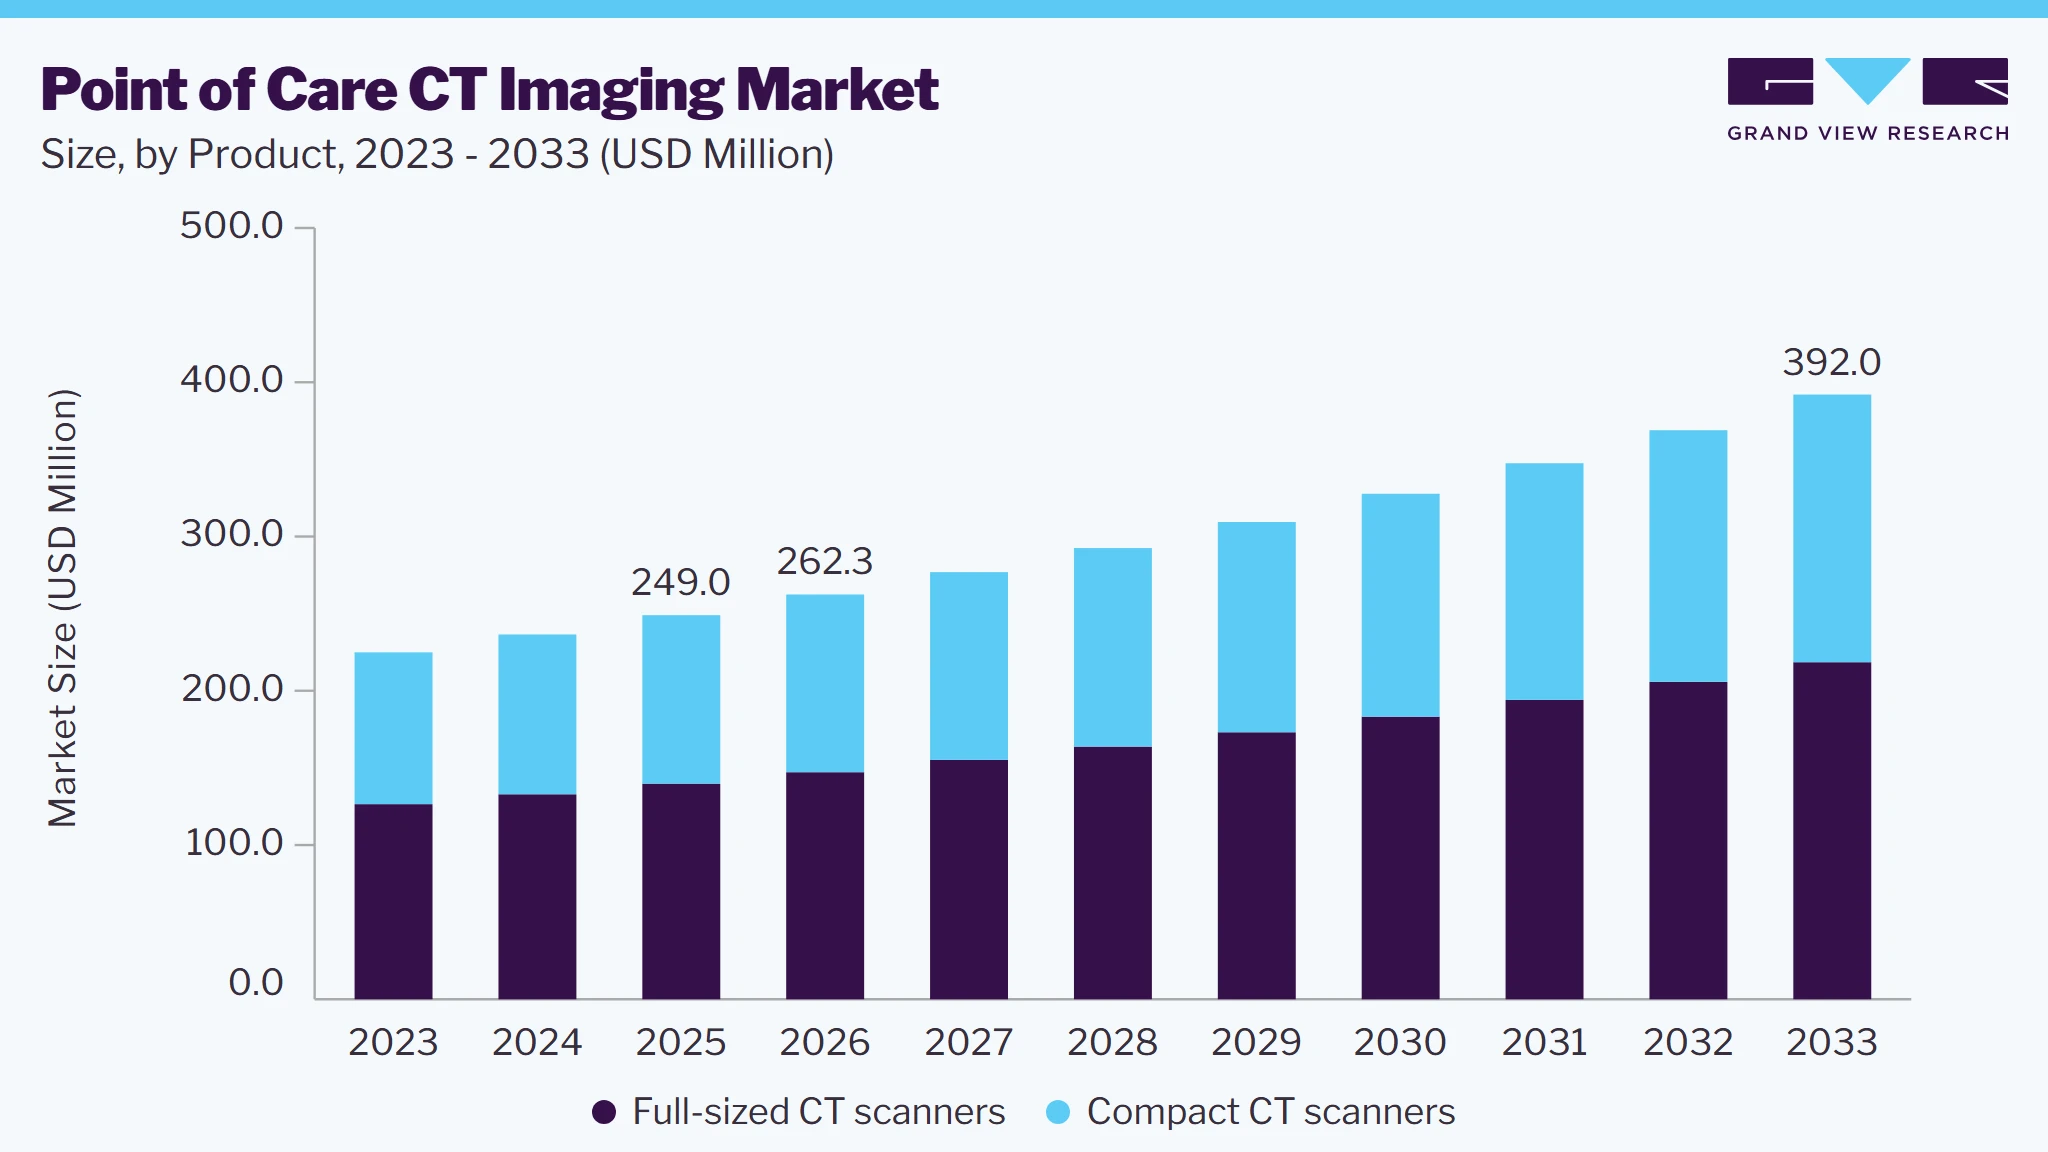 To learn more about this report, Download Free Sample Report
The growing initiatives undertaken by companies in the global market to secure a substantial market share are anticipated to further drive market growth. For instance, in 2022, Philips partnered with Roswell Park Comprehensive Cancer Center (Buffalo, New York, U.S.) to develop truck-based mobile CT lung cancer screening units.These units, equipped with Philips’ advanced Incisive CT scanners, are already supporting Roswell Park’s Project Eddy (Early Detection Driven to You) by facilitating increased lung cancer screenings within the community.
“For more than a decade, the incidence of lung cancer has been higher in the city of Buffalo than in the rest of the state of New York,”
-Dr. Mary Reid, Chief of Cancer Screening, Survivorship and Mentorship at Roswell Park Comprehensive Cancer Center (Buffalo, New York, USA).
“Since partnering with Project Eddy, we actually brought screening to our firehouses in Buffalo and caught cancers, and people are now healthy and able to return to work,”
-Chris Whelan, Trustee for Buffalo Professional Firefighters Local 282
Chronic diseases such as cardiovascular disease, cancer, diabetes, and respiratory disorders are on the rise globally, leading to an increased demand for diagnostic imaging to monitor and manage these conditions effectively. PoC CT imaging offers the advantage of immediate and accurate diagnostic capabilities at the patient’s location, enabling prompt decision-making and treatment. In addition, the aging population is expanding rapidly. Older adults are more prone to suffer from multiple chronic conditions that require frequent medical attention and medical imaging investigations. As the number of elderly individuals grows, so does the need for convenient, accessible, and rapid diagnostic solutions that can be provided without the need for transport to specialized facilities. PoC CT imaging meets this need by offering portable, high-quality imaging that can be utilized in various settings, including nursing homes, assisted living facilities, and at home.
Market Dynamics
The point-of-care CT imaging market is experiencing significant growth, driven by the increasing demand for rapid diagnostic imaging, rising incidence of stroke, traumatic brain injuries, and other neurological emergencies, as well as the growing need for immediate clinical decision-making in emergency and critical care settings. The market is further supported by continuous technological advancements in compact and portable computed tomography systems, increasing adoption of mobile imaging solutions in intensive care units (ICUs), emergency departments, and operating rooms, and the expanding focus on improving patient outcomes through faster diagnosis while reducing the need for patient transport. The growing geriatric population, increasing prevalence of chronic neurological and cardiovascular diseases, and rising investments in advanced healthcare infrastructure are also contributing to market expansion. Point-of-care CT imaging systems enable hospitals, emergency departments, intensive care units, trauma centers, ambulatory surgical centers, and specialized healthcare facilities to perform high-quality diagnostic imaging directly at or near the patient's bedside. These systems facilitate timely clinical assessment, reduce delays associated with conventional radiology workflows, minimize risks related to transporting critically ill patients, and support faster treatment decisions in acute care environments.
The increasing demand for point-of-care (POC) diagnostics is a major driver accelerating the growth of the global point-of-care CT imaging market. Healthcare systems worldwide are increasingly prioritizing rapid, decentralized diagnostic solutions that enable timely clinical decision-making, reduce patient transfer requirements, and improve treatment outcomes. Point-of-care CT imaging systems provide immediate high-quality diagnostic images at the patient's bedside or in emergency settings, allowing clinicians to quickly identify conditions such as acute stroke, traumatic brain injury, intracranial hemorrhage, hydrocephalus, and other neurological emergencies without transporting critically ill patients to centralized radiology departments. This capability significantly reduces diagnosis-to-treatment time, enhances workflow efficiency, and supports faster clinical interventions, particularly in emergency departments, intensive care units (ICUs), operating rooms, and trauma centers. The growing emphasis on value-based healthcare, increasing patient volumes in emergency and critical care settings, and the need to optimize hospital resources are further driving the adoption of bedside imaging technologies. In addition, advances in portable CT scanner design, artificial intelligence-assisted image reconstruction, low-dose radiation technologies, and wireless connectivity have improved image quality, operational efficiency, and ease of use, making point-of-care CT systems increasingly attractive for healthcare providers.
The high cost of point-of-care (POC) CT imaging systems remains a significant restraint to the growth of the global point-of-care CT imaging market. These systems require substantial upfront capital investment due to advanced detector technologies, compact engineering, AI-enabled imaging software, and integrated mobility features. In addition to acquisition costs, healthcare providers must bear installation expenses, infrastructure modifications, software licensing fees, routine calibration, preventive maintenance, service contracts, and periodic hardware upgrades, significantly increasing the total cost of ownership. The financial burden is particularly challenging for small hospitals, ambulatory care centers, rural healthcare facilities, and providers in emerging economies with limited healthcare budgets. As a result, many institutions delay procurement decisions or continue relying on conventional centralized CT systems that offer higher patient throughput and better return on investment. Furthermore, uncertain reimbursement policies for advanced imaging procedures in several countries reduce the economic viability of adopting portable CT technologies. These cost-related barriers limit widespread deployment, especially in resource-constrained settings, thereby slowing the overall adoption and growth of the point-of-care CT imaging market despite the technology's significant clinical advantages.
Market Concentration & Characteristics
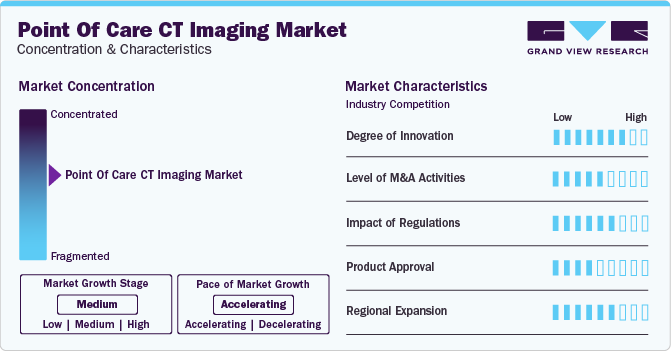
The industry growth stage is moderate. The point of care (PoC) CT imaging industry has seen significant innovation, characterized by the development of advanced, portable CT imaging devices that can be easily transported and utilized in a variety of healthcare settings. These innovations include compact designs, and high-resolution scans. In addition, these devices are also equipped with enhanced connectivity features, enabling seamless integration with hospital information systems and electronic health records for efficient data sharing and patient management.
To expand their customer base and capture a larger industry share, major players in the industry are consistently improving their product offerings. This includes upgrading their current products with advanced technologies, pursuing strategic acquisitions to enhance their capabilities and presence, and securing necessary government approvals to ensure compliance and facilitate industry entry. For instance, in October 2022, NeuroLogica obtained CE marking for all Elite Mobile Computed Tomography Systems by complying with the new EU Medical Device Regulation (MDR 2017/745).
 To learn more about this report, Download Free Sample Report
Point of care CT imaging has achieved a high degree of innovation due to remarkable technological advancements, such as the development of portable and high-resolution devices. These innovations have enabled immediate and accurate diagnostic capabilities in diverse healthcare settings, from emergency rooms to remote locations. For instance, in November 2023, Canon Medical Systems announced the integration of its Advanced intelligent Clear-IQ Engine (AiCE) Deep Learning Technology across all segments of its CT business, aiming to provide high-quality imaging at low doses for all patients.
Manufacturers of point of care CT imaging devices are undertaking partnership and collaboration activities. For instance, in January 2023, NeuroLogica Corp., a subsidiary of Samsung Electronics Co. Ltd., announced a collaboration with The University of Dundee in Scotland, United Kingdom, to conduct research using the OmniTom Elite with Photon Counting Detector (PCD) CT imaging technology.
“By utilizing the state-of-the-art equipment alongside the University of Dundee’s unique research and clinical expertise, together we can work to modernize the future of patient care.”
-Professor Grunwald, and executive member of SINAPSE
Regulations significantly impact point of care CT imaging by ensuring safety, efficacy, and quality standards. Compliance with regulatory requirements such as FDA approvals or CE marking is essential for industry entry and product usage. These regulations influence device design, manufacturing processes, and clinical practices, ultimately safeguarding patient well-being and increasing innovation in the field.
Industry participants are actively pursuing product approvals to maintain competitiveness. For instance, in November 2022, NeuroLogica Corp. announced that its comprehensive trauma imaging solution, the BodyTom 64 Point-of-Care Mobile Computed Tomography (CT) Scanner, received FDA clearance for commercial utilization in the U.S.
The geographical expansion of point of care CT imaging has been increasing moderately too significantly due to population growth, rising healthcare spending, and regulatory conditions.
Analyst Perspective
The global point-of-care CT imaging market is positioned at the intersection of several transformative healthcare trends, including the growing demand for rapid diagnostic imaging, increasing prevalence of neurological and traumatic conditions, rising adoption of decentralized healthcare delivery models, and continuous advancements in portable imaging technologies. The increasing incidence of acute conditions such as stroke, traumatic brain injury, intracranial hemorrhage, neurovascular disorders, spinal injuries, and other critical emergencies is creating substantial growth opportunities for medical device manufacturers, hospitals, emergency departments, intensive care units (ICUs), ambulatory care centers, military healthcare facilities, and mobile healthcare providers. The market is further supported by the expanding geriatric population, rising burden of chronic diseases, increasing emergency care admissions, and the growing need for timely diagnosis and treatment in critical care settings. The expansion of the point-of-care CT imaging market is accelerating as healthcare providers increasingly adopt compact and mobile CT systems capable of delivering advanced diagnostic imaging directly at the patient's bedside.
Product Insights
Based on product, the full-sized CT scanners segment led the market with the largest revenue share of 56.1% in 2025. Full-sized PoC CT scanners provide a wider range of imaging capabilities and high throughput, making them ideal for a variety of clinical applications. They are mostly preferred in larger healthcare facilities such as hospitals and imaging centers where there is a higher patient volume and the need for detailed diagnostic study. In addition, advancements in technology have led to improvements in full-sized PoC CT scanners, such as high imaging resolution, faster scan time, and reduced radiation dose, thus boosting the segment growth.
The compact CT scanner segment is expected to grow at a fastest CAGR from 2025 to 2030. This can be attributed to various factors, such as its portability, versatility, and convenience, allowing for their use in a wide range of clinical settings, including smaller healthcare facilities, outpatient clinics, and ambulatory care centers. In addition, the growing emphasis on point-of-care diagnostics and personalized medicine is driving the demand for compact CT scanners, as they enable immediate imaging and quick decision-making at the patient's bedside. Furthermore, the rising prevalence of chronic diseases and the aging population are fueling the need for accessible and efficient diagnostic solutions, further driving the adoption of compact CT scanners.
Application Insights
Based on application, the neurology segment led the market with the largest revenue share of 29.2% in 2025. The rising prevalence of neurological disorders, coupled with an aging population, has led to growing awareness for efficient diagnostic solutions in neurology. This device holds the ability to conduct immediate imaging at the patient's bedside or within neurocritical care units is crucial for facilitating timely diagnosis and treatment decisions, particularly in acute neurological emergencies such as strokes or traumatic brain injuries. Point-of-care CT scanners offer the advantage of rapid imaging acquisition, enabling healthcare providers to quickly assess patients' neurological status and determine the most appropriate course of action.
The respiratory segment is expected to grow at the fastest CAGR over the forecast period. The growing prevalence of respiratory disorders worldwide such as pneumonia, chronic obstructive pulmonary disease (COPD), and lung cancer, are major contributing factors to segment growth. For instance, according to the International Agency for Research on Cancer in 2022, Lung cancer cases ranked first among all other cancers, and about 2,480,675 lung cancer cases were reported worldwide.
Point-of-care CT scanners offer a crucial diagnostic tool for assessing respiratory health, enabling healthcare providers to promptly detect and evaluate pulmonary abnormalities, monitor disease progression, and guide treatment decisions. Furthermore, the increasing emphasis on early detection and management of respiratory diseases, is expected to boost the segment growth.
End-use Insights
Based on end use, the hospital segment led the market with the largest revenue share of 34.9% in 2025. The growing adoption of this technology by hospitals is a major factor contributing to the segment growth. For instance, in May 2024, Surrey and Sussex Healthcare NHS Trust introduced a new mobile CT scanner at Crawley Hospital to enhance the capacity for outpatient diagnostic appointments for the local community. In addition, factors like high patient volume, availability of advanced medical devices, specialized staff, and the need for rapid on-site diagnostic imaging make hospitals a preferred choice for medical diagnosis.
 To learn more about this report, Download Free Sample Report
“We are delighted to have this opportunity to start putting into practice the principles of Community Diagnostic Centres offering responsive high-quality diagnostics where patients can easily access them - reducing waiting times for all our patients and ensuring our hospital imaging facilities are able to respond to the needs of our most acutely unwell patients.”
- Dr Tony Newman-Sanders, consultant radiologist and chief of cancer and diagnostics at the Trust
The ambulatory surgery centers (ASCs) segment is expected to grow at the fastest CAGR during the forecast period. The growing development of compact point of care CT imaging devices to be incorporated in outpatient settings such as ASCs is expected to drive the segment. Moreover, patients opt for ASCs to avoid the extra cost associated with the hospital stay. This cost-efficiency, coupled with the convenience and shorter recovery times of outpatient care, contributes to the rising patient preference for ASCs. Thus, the aforementioned factors are expected to contribute to the market growth.
Regional Insights
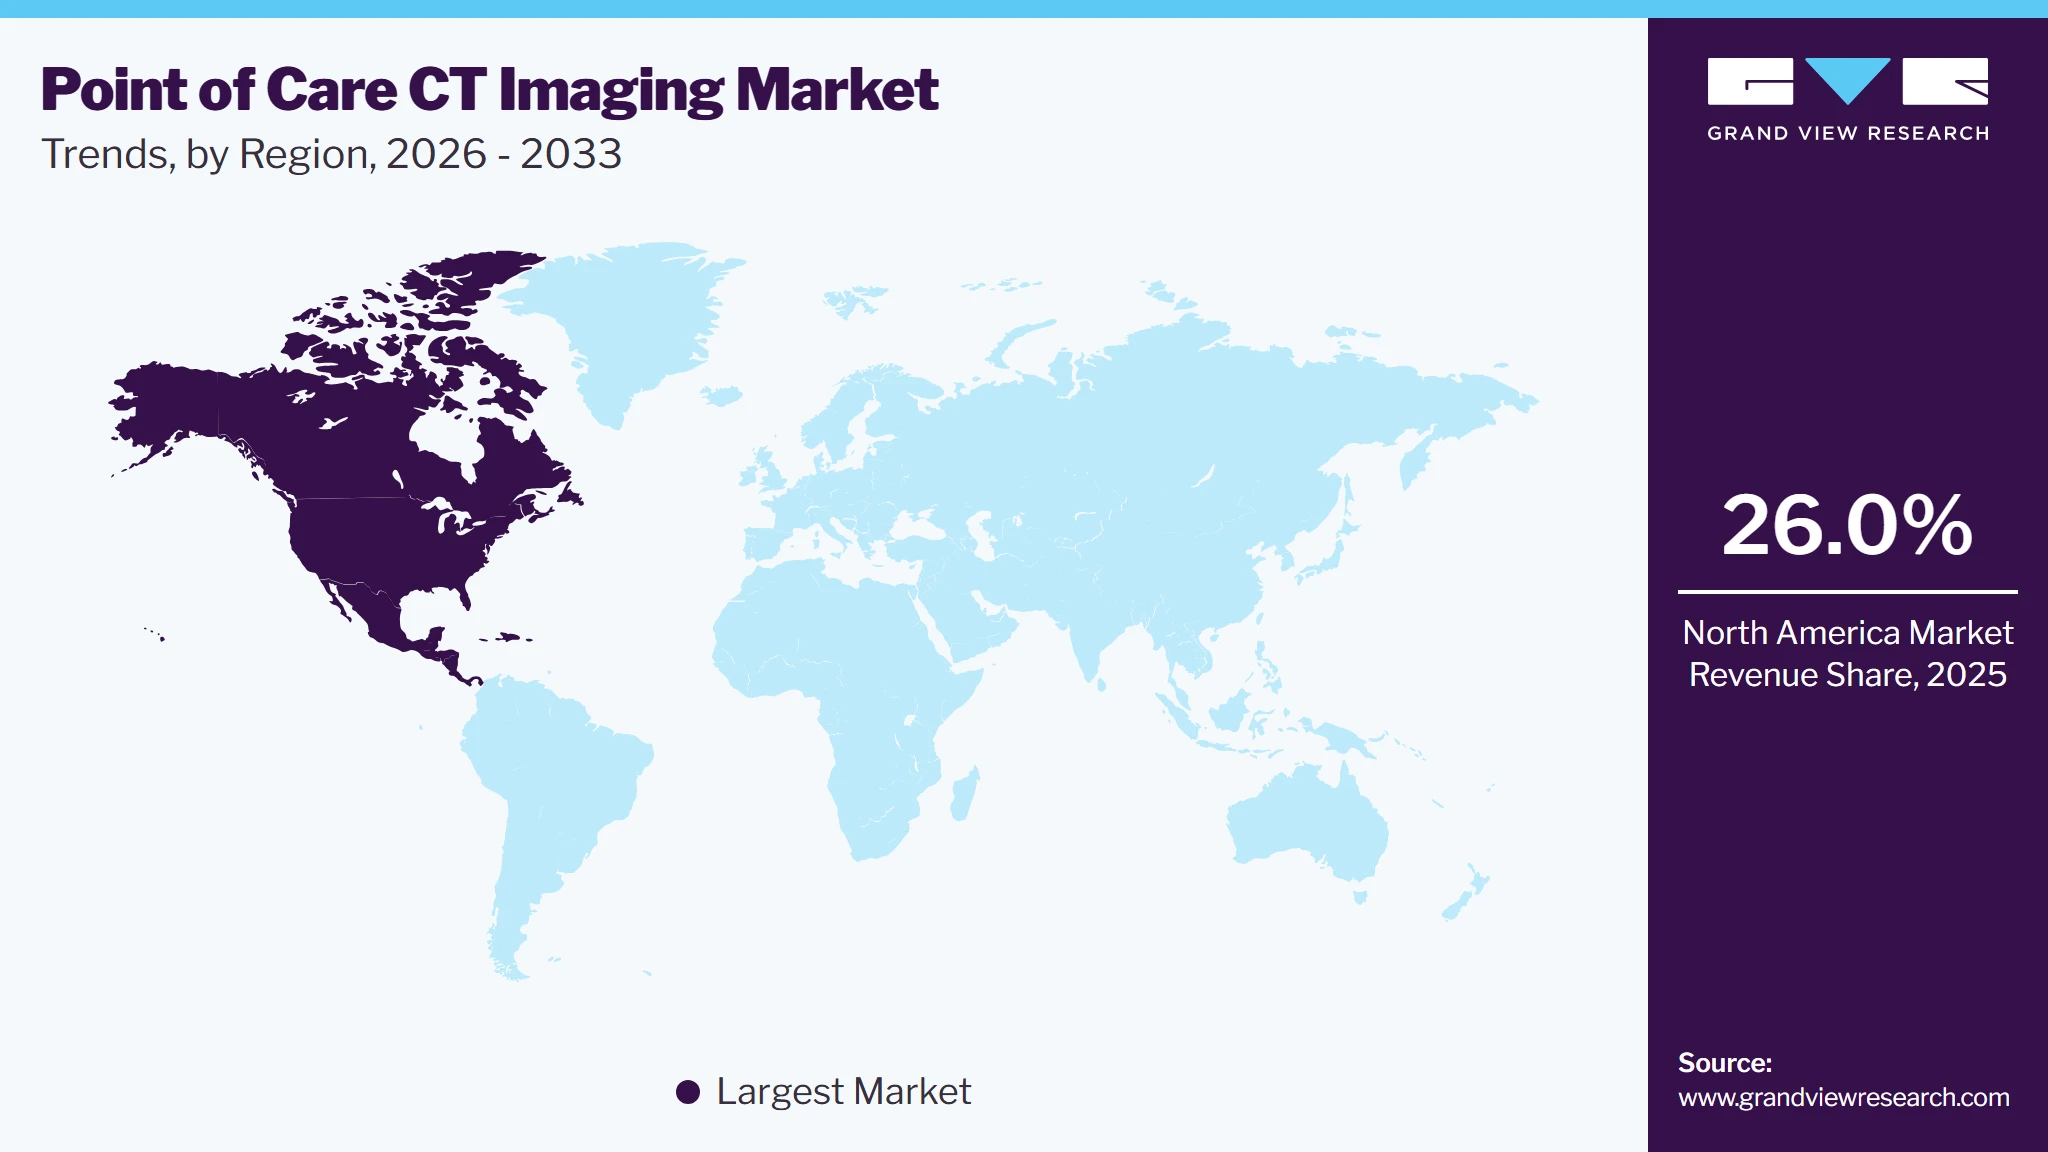
North America dominated the point-of-care CT imaging market with the largest revenue share of 26.0% in 2025. Several factors contribute to this trend, such as highly advanced healthcare infrastructure, presence of leading market players in this region, adoption of advanced imaging technologies and the growing prevalence of chronic disorders.
 To learn more about this report, Download Free Sample Report
U.S. Point Of Care CT Imaging Market Trends
The point-of-care CT imaging market in the U.S. held the largest share in the North America region in 2025. The country has a high incidence of chronic diseases and a significant number of emergency and critical care situations that demand rapid and precise diagnostic tools, further boosting the demand for PoC CT imaging. For instance, according to data published by the American Hospital Association, 133 million Americans, nearly half the population, suffer from at least one chronic illness, such as hypertension, heart disease, or arthritis.
Europe Point Of Care CT Imaging Market Trends
The point of care CT imaging market in Europe held a significant market share in 2024. European countries have strong healthcare funding and reimbursement policies which support the acquisition and utilization of advanced imaging technologies. In addition, the increasing prevalence of chronic disorders, such as cancer, is expected to drive the adoption of these devices. For instance, according to the International Agency for Research on Cancer in 2022, about 4,471,422 new cancer cases were reported in this region.
The UK point of care CT imaging marketis expected to grow at the fastest CAGR over the forecast period, owing to the rising awareness and adoption of medical imaging coupled with increasing government initiatives in the country. For instance, in March 2024, Planning permission has been granted for the new Plymouth Community Diagnostic Centre (PCDC) to be constructed in the West End. Plymouth City Council has approved the plans for this new facility, which will offer over 91,600 imaging tests at its location in Colin Campbell Court. Patients will be able to visit the PCDC for various tests, including MRI, CT, X-ray, lung cancer screening, ultrasound, audiology, ECG, point of care testing, and blood tests.
The point of care CT imaging market in France is expected to grow at the substantial CAGR over the forecast period. In June 2021, the government announced the Health Innovation 2030 plan, with a budget of 7.5 billion euros. This initiative aims to increase innovation and advancements in the healthcare sector over the next decade.
The Germany point of care CT imaging market is expected to grow at the significant CAGR over the forecast period, due to the rapid aging of the population, leading to a higher incidence of chronic disorders. PoC CT imaging provides convenient and effective solutions for diagnosing and managing these conditions, offering precise results that facilitate timely treatment decisions.
Asia Pacific Point Of Care CT Imaging Market Trends
The point of care CT imaging market in Asia Pacific is estimated to witness at the fastest CAGR during the forecast period. This can be attributed to the growing adoption of this technology in this region. For instance, in December 2022, NeuroLogica Corp., announced the installation of its SmartMSU with OmniTom Elite for head imaging - in the Asia-Pacific region.
The China point of care CT imaging market is expected to grow at the substantial CAGR over the forecast period, this expansion is primarily driven by the presence of leading market players within the country, each employing various strategies to hold a prominent market share.
The point of care CT imaging market in Japan is expected to grow at the significant CAGR over the forecast period. This expansion is primarily attributed to the country's focus on technological innovation and the widespread adoption of advanced medical technology.
The India point of care CT imaging market is expected to grow at a rapid CAGR over the forecast period. This expansion is primarily due to adoption of advanced imaging technology and the growing prevalence of chronic disorders in the country.
Latin America Point Of Care CT Imaging Market Trends
The point of care CT imaging in the Latin America market is anticipated to grow at a moderate CAGR throughout the forecast period. This growth is fueled by increasing demand for PoC CT imaging systems due to the increasing prevalence of chronic diseases and the necessity for effective diagnostic tools. In addition, the growth is also supported by government initiatives and investments in healthcare infrastructure in this region.
Middle East & Africa Point Of Care CT Imaging Market Trends
Thepoint of care CT imaging in Middle East & Africa is expected to grow at the fastest CAGR during the forecast period, owing to the robust economies and significant investments in healthcare infrastructure. Countries like the UAE and Saudi Arabia are leading the adoption of advanced medical technologies. Thus, there is a rising focus on integrating PoC CT imaging systems into their healthcare systems to address the need for efficient and rapid diagnostic solutions. Moreover, governmental support for expanding healthcare services in these countries is expected to contribute to the increasing demand for PoC CT imaging.
Key Point Of Care CT Imaging Company Insights
The major as well as emerging players in this industry are actively pursuing various initiatives to secure a significant share of the market. These initiatives involve different strategies aimed at strengthening their market position and competitiveness. Established companies use their existing resources, brand reputation, and market presence to grow their offerings. Whereas emerging players concentrate on specialized markets or innovative technologies to establish themselves in the industry. For instance, as a key technology partner in the Australian Stroke Alliance, Micro-X is in the process of developing a CT scanner that is lightweight and can be integrated into any ambulance.
Key Point Of Care CT Imaging Companies
The following key companies have been profiled for this study on the point of care CT imaging market.
-
Xoran Technologies, LLC
-
CurveBeam
-
Planmed
-
NeuroLogica Corp.
-
Siemens Healthcare GmbH
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Xoran Technologies, LLC, CurveBeam, Siemens Healthcare GmbH)
- Focus on expanding portable and compact CT imaging systems for emergency departments, ICUs, ambulances, and military healthcare settings.
- Invest in AI-enabled image reconstruction, advanced visualization software, low-dose imaging technologies, and workflow automation to improve diagnostic accuracy.
- Strong global brand recognition, extensive clinical validation, and established customer relationships enable higher adoption of advanced point-of-care CT solutions.
- Comprehensive product portfolios integrating AI, cloud connectivity, PACS compatibility, and remote diagnostics provide superior clinical workflow efficiency.
- High development and manufacturing costs, along with stringent FDA, CE, and other regulatory requirements, increase commercialization timelines.
- Large organizations often experience slower product innovation due to complex organizational structures and lengthy validation processes.
Emerging Players (NeuroLogica Corp., Planmed)
- Focus on developing lightweight, battery-powered, and highly portable CT systems designed for bedside imaging, emergency medicine, stroke care, and critical care applications.
- Prioritize AI-based image enhancement, cloud-enabled image sharing, tele-radiology integration, and compact system designs to improve accessibility.
- Faster product development cycles allow rapid adoption of emerging technologies such as AI-assisted diagnostics and portable imaging platforms.
- Greater flexibility in designing specialized solutions for niche applications including neuroimaging, trauma care, and rural healthcare settings.
- Limited financial resources and smaller sales and service networks restrict large-scale commercial expansion.
- Lower brand recognition and limited clinical evidence compared with established manufacturers reduce physician confidence and procurement opportunities.
Recent Developments
-
In January 2024, Varian, a Siemens Healthineers company, has entered into a 10-year, $175 million CAD (approximately $131 million USD) multi-disciplinary oncology partnership (MDOP) with Nova Scotia Health. This collaboration aims to enhance the patient journey across the Nova Scotia Health system, accelerating progress from screening to survivorship in oncology care
-
In December 2023, OU Health collaborates with Siemens Healthineers to enhance healthcare in Oklahoma, promote research, and innovation. The 10-year Value Partnership encompasses imaging and laboratory equipment
-
In September 2022, CurveBeam, LLC and StraxCorp Pty Ltd announced a merger agreement resulting in the establishment of CurveBeam AI Limited. This merger enables CurveBeam AI to broaden CurveBeam's economically sustainable point-of-care imaging solutions into the realm of bone health, while also serving as a platform for the development of artificial intelligence (AI) driven applications for weight-bearing CT (WBCT) imaging
Point of Care CT Imaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 249.0 million
Estimated market size in 2026
USD 262.3 million
Projected market size by 2033
USD 392.0 million
Growth rate
CAGR of 5.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Xoran Technologies, LLC; CurveBeam; Planmed; NeuroLogica Corp.; Siemens Healthcare GmbH
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Point Of Care CT Imaging Market Report Segmentation
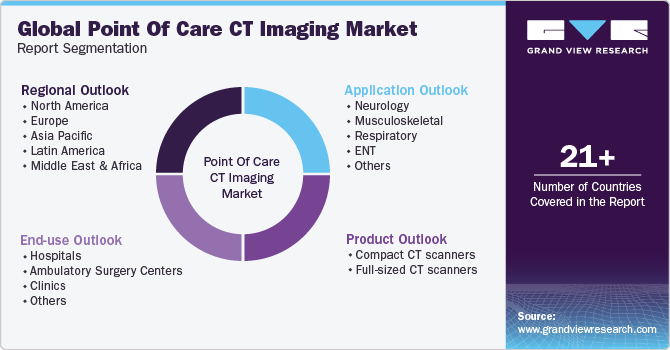
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global point of care CT imaging market report on the basis of product, application, end-use and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Compact CT scanners
-
Full-sized CT scanners
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Neurology
-
Musculoskeletal
-
Respiratory
-
ENT
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgery Centers
-
Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The point of care CT imaging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each point of care CT imaging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Compact CT scanners
Revenue is derived from the commercialization of lightweight, highly mobile, and specialized computed tomography systems engineered for rapid, bedside deployment. Manufacturers generate substantial revenue from upfront hardware purchases by specialty clinics and emergency departments, which are supplemented by recurring income from modular system components, multi-year protection plans, and specialized software licenses for real-time 3-D image reconstruction at the point of care.
Full-sized CT scanners
Revenue is captured through the procurement of heavy-duty, high-slice, yet mobile or transportable full-body CT imaging arrays designed for intensive care units (ICUs) and operating rooms. Medtech companies secure high-value capital revenue via initial institutional sales, complemented by predictable long-term revenue streams from post-warranty service agreements, hardware calibration contracts, tube replacements, and premium artificial intelligence (AI) diagnostic integration upgrades.
Segment - Application
Revenue capture definition
Neurology
Revenue is generated through the deployment of scanners optimized for ultra-fast head and neck imaging to evaluate acute conditions such as ischemic strokes, intracranial hemorrhages, and traumatic brain injuries (TBIs). Income is heavily driven by institutional demand for immediate, near-patient diagnostic workflows in stroke centers and emergency departments, accelerating clinical decision-making and reducing time-to-treatment.
Musculoskeletal
Revenue flows from the clinical use of point-of-care scanners configured to capture high-contrast bone and joint structures, particularly for complex orthopedic trauma, extremity fractures, and intraoperative spinal assessments. Market participants capture revenue through specialized extremity-specific positioning accessories, specialized software modules, and integration pipelines with surgical navigation systems.
Respiratory
Revenue is captured through specialized low-dose thoracic scanning configurations designed for swift pulmonary assessments, acute pneumonia evaluation, and critical-care lung tracking. Income is driven by high-frequency diagnostic throughput in intensive care settings, which pulls through recurring value via system optimization, cloud-based data storage, and PACS network connectivity fees.
ENT
Revenue is derived from high-resolution, low-dose maxillofacial and sinus imaging systems tailored for otolaryngology clinics. Manufacturers monetize this application through direct-to-practice sales of compact scanners, generating high profit margins on specialized software for stereotactic sinus surgery planning and recurring maintenance packages for dedicated head/neck stabilizers.
Others
Revenue encompasses expanding or multi-specialty clinical domains, including point-of-care dental/maxillofacial imaging, veterinary-specific diagnostics, and mobile or military field hospital screening deployments.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated through structured, large-scale capital budget allocations, public-private medical tenders, and long-term group purchasing organization (GPO) network contracts. Manufacturers capture bulk revenue through multi-unit institutional shipments to emergency rooms, trauma centers, and ICUs, alongside lucrative, multi-year comprehensive service contracts that guarantee maximum equipment uptime.
Ambulatory Surgery Centers
Revenue flows from targeted commercial sales of compact and highly efficient point-of-care systems optimized for outpatient surgical workflows. Income is driven by outpatient procurement structures that value small machine footprints, fast patient turnaround times, and immediate intraoperative scanning capabilities to verify surgical outcomes before discharge.
Clinics
Revenue is captured via direct commercial sales channels supplying private multi-specialty practices, orthopedic clinics, and ENT groups. Device providers capture high-margin revenue by offering specialized leasing structures, flexible financing, and bundled software packages that allow small-to-medium-sized practices to offer on-site diagnostic services and capture local diagnostic fees.
Others
Revenue is derived from alternative or specialized care points, including mobile stroke units (specialized ambulances), remote or rural health outposts, research laboratories, and military field medicine applications.
Estimation Model
01. Scope Definition
02. Build the Product Base
03. Estimate Penetration
04. Revenue Conversion
What is being measured in the Point-of-Care CT Imaging Market?
What is the total addressable market for Point-of-Care CT imaging systems?
What is the current and expected adoption rate of Point-of-Care CT imaging systems?
How is the Point-of-Care CT Imaging Market revenue estimated and validated?
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
Define the scope of point-of-care CT imaging systems
Analyze the installed base of CT scanners and identify healthcare facilities with potential demand for bedside and portable CT imaging solutions.
Assess the adoption of point-of-care CT imaging across healthcare settings.
Collect average selling prices (ASP) of portable and bedside CT imaging systems across different regions and manufacturers.
Segment the market by product, application, end user, and geography.
Estimate the addressable customer base by evaluating hospitals, ambulatory surgical centers, and clinics.
Evaluate technology adoption trends by comparing portable CT systems with conventional fixed CT scanners for acute care imaging.
Estimate annual unit shipments and installed base by product type, application, and geography.
Identify key end-user categories
Assess disease burden and procedure volumes for conditions requiring rapid CT diagnosis.
Analyze the impact of technological advancements, AI-assisted image reconstruction, and lower radiation dose technologies.
Calculate market revenues using unit sales, replacement cycles, software upgrades, service contracts, maintenance revenues, and installation services.
Establish geographic scope and align on base year & forecast horizon (2026-2033)
Forecast future demand based on healthcare infrastructure expansion, increasing emergency admissions, and investments in decentralized diagnostic imaging.
Evaluate regional adoption patterns based on healthcare infrastructure, reimbursement policies, regulatory approvals, and hospital capital investments.
Validate mar
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Porters Analysis
Conducted a comprehensive Porter's Five Forces analysis of the global point-of-care CT imaging market to evaluate the competitive intensity and long-term market attractiveness. The assessment examined supplier bargaining power across CT component manufacturers, detector technology providers, software developers, and imaging system integrators, along with buyer bargaining power among hospitals, emergency departments, trauma centers, intensive care units, ambulatory surgical centers, and military healthcare facilities. The study further evaluated the threat of new entrants considering regulatory compliance, capital investment requirements, technological expertise, and intellectual property barriers. Additionally, it assessed the threat of substitute diagnostic imaging modalities, competitive rivalry among leading manufacturers, product innovation trends, pricing strategies, strategic partnerships, mergers & acquisitions, distribution networks, and regional competitive dynamics shaping the point-of-care CT imaging industry.
Enables stakeholders to understand the competitive landscape, market entry barriers, supplier and buyer influence, substitution risks, and competitive positioning within the global point-of-care CT imaging market. The analysis supports strategic decision-making related to product differentiation, pricing strategies, partnership development, regional expansion, investment prioritization, and competitive benchmarking while identifying opportunities for sustainable growth and long-term market leadership.
Market Growth Driver Analysis
Conducted a detailed assessment of the major growth drivers influencing the global point-of-care CT imaging market. The analysis evaluated the impact of continuous technological advancements, including AI-enabled image reconstruction, portable CT systems, low-dose imaging technologies, wireless connectivity, and cloud-based image management solutions. The study further examined the increasing demand for rapid point-of-care diagnostics in emergency medicine, critical care, stroke management, and trauma care, where immediate imaging significantly improves clinical decision-making. Additionally, the assessment analyzed the growing aging population requiring frequent diagnostic imaging, along with the rising prevalence of chronic diseases such as cardiovascular disorders, neurological diseases, cancer, and respiratory conditions that necessitate timely imaging at the point of care. The study also evaluated healthcare infrastructure modernization, expanding emergency care services, and increasing investments in decentralized diagnostic technologies supporting market expansion.
Enables stakeholders to identify the primary factors accelerating market growth and evaluate their long-term commercial impact. The analysis supports strategic planning by highlighting high-growth application areas, emerging technology opportunities, evolving healthcare delivery models, and unmet clinical needs. It also assists manufacturers in prioritizing R&D investments, optimizing product portfolios, strengthening commercialization strategies, and targeting high-potential end-user segments and regional markets.
Macroeconomic Analysis
Conducted a comprehensive macroeconomic assessment of factors influencing the global point-of-care CT imaging market. The study evaluated healthcare expenditure trends, government investments in medical infrastructure, inflationary pressures, reimbursement policies, public and private funding for diagnostic imaging, medical device manufacturing costs, semiconductor and electronic component supply chains, international trade policies, currency fluctuations, and regulatory environments impacting production and commercialization. The analysis further examined demographic shifts, urbanization, aging populations, increasing prevalence of chronic diseases, expansion of emergency and critical care infrastructure, healthcare digitalization initiatives, and investments in decentralized healthcare delivery models that influence demand for portable CT imaging systems across developed and emerging markets.
Enables stakeholders to assess macroeconomic opportunities and risks influencing market growth, investment potential, and regional demand patterns. The study provides actionable insights for pricing optimization, manufacturing strategy, supply chain resilience, geographic expansion, and market prioritization while helping organizations anticipate the impact of healthcare spending, economic fluctuations, regulatory changes, and infrastructure investments on future demand for point-of-care CT imaging systems.
Frequently Asked Questions About This Report
Some key players operating in the point of care CT imaging market include Xoran Technologies, LLC, CurveBeam, Planmed, NeuroLogica Corp., and Siemens Healthcare GmbH.
By product, the full-sized CT scanners segment held a leading market share of 56.1% in 2025.
Key factors that are driving the point of care CT imaging market growth include the increasing prevalence of chronic disorders, technological advancements, growing emphasis on early diagnosis and treatment and the growing aging population.
North America dominated the point of care CT imaging market with a share of 26.0% in 2025. This is attributable to the presence of major market players such as Xoran Technologies, and CURVEBEAM.
Asia Pacific is the fastest-growing region over the forecast period.
By application, the respiratory segment expected to witness fastest CAGR over the forecast period.
The global point of care CT imaging market size was valued at USD 249.0 million in 2025 and is estimated at USD 262.3 million for 2026.
The global point of care CT imaging market is expected to grow at a CAGR of 5.9% from 2026 to 2033, reaching USD 392.0 million by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


