
- Home
- »
- Advanced Interior Materials
- »
-
Point of Use Water Treatment Systems Market Report, 2033GVR Report cover

Point Of Use Water Treatment Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology, By Device, By Application (Residential, Commercial, Industrial, Offices, Hotels, Restaurants, Café, Hospitals, Schools), By Region, And Segment Forecasts
Market Size, 2025
$34.5BMarket Estimate, 2026
$37.4BMarket Forecast, 2033
$67.8BCAGR, 2026–2033
8.9%Point Of Use Water Treatment Systems Market Summary
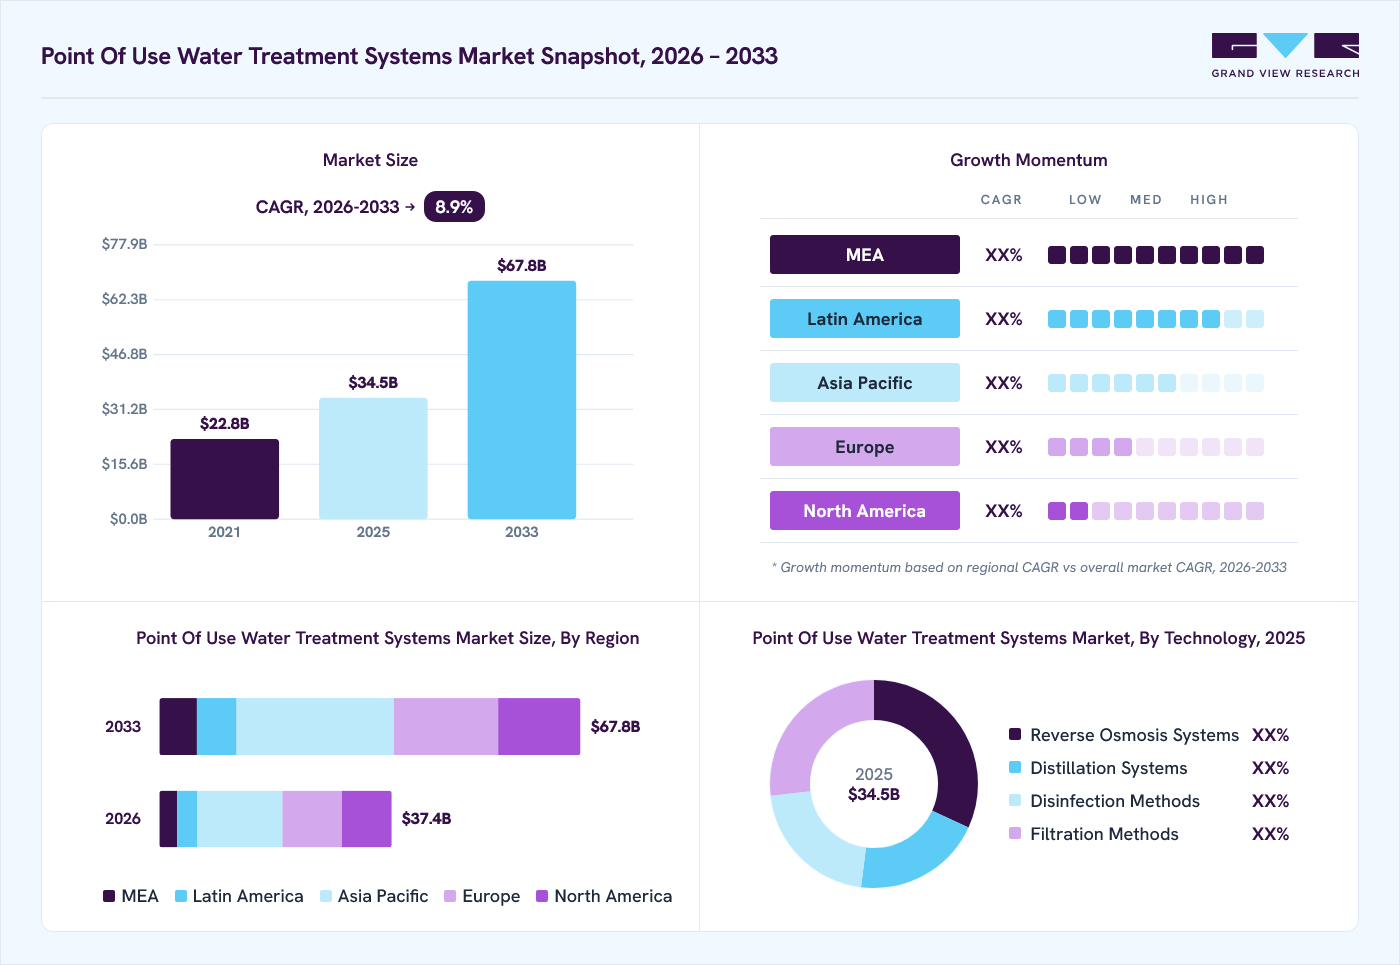
The global point of use water treatment systems market size was valued at USD 34.5 billion in 2025 and is projected to grow from USD 37.4 billion in 2026 to USD 67.8 billion by 2033, at a CAGR of 8.9% from 2026 to 2033. Asia Pacific dominated the point of use water treatment systems market with the largest revenue share of 36.4% in 2025. Rising concerns over different waterborne infections, such as E. coli and cholera, have boosted the popularity and demand for point of use water treatment systems globally.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Reverse osmosis systems segment held the largest market share of 31.8% in 2025.
- By device: Tabletop pitchers segment held the largest market share of 34.8% in 2025.
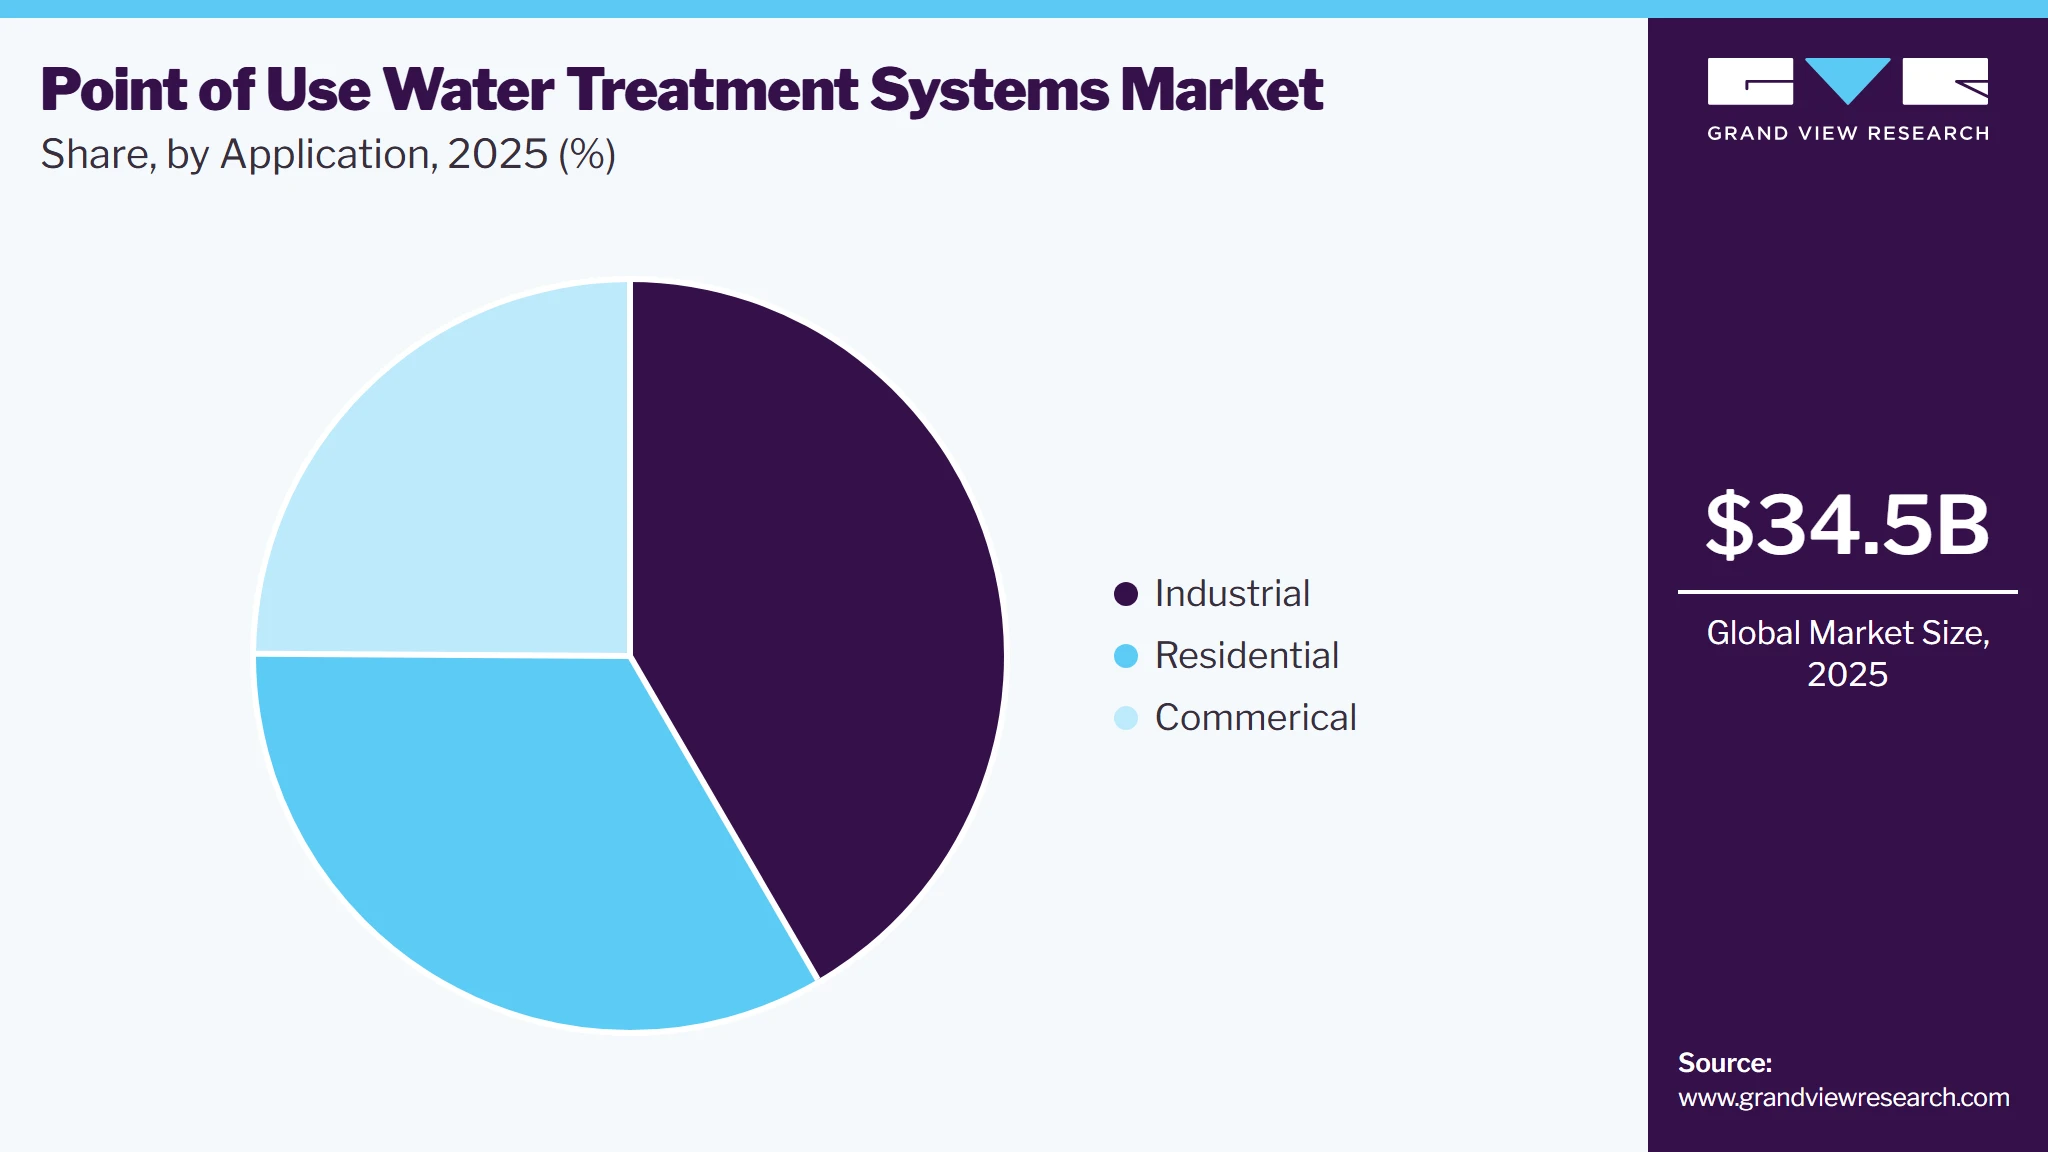
- By application: Industrial segment held the largest market share of 41.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (36.4% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 34.5 Billion
- Estimated market size in 2026: USD 37.4 Billion
- Projected market size by 2033: USD 67.8 Billion
- CAGR (2026-2033): 8.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to a report by EBSCO, in 2024, around 2 billion people worldwide lack access to safe drinking water service in their households. The waterborne diseases account for 4% of the global disease burden. Each year, around 2 million people worldwide die due to waterborne diarrheal illnesses. In addition, around 1.3 to 4 million cases of cholera are caused by the bacteria Vibrio cholerae each year, resulting in an estimated 21,000 to 143,000 deaths. The Safe Drinking Water Act, of 1974, the Environment Protection Agency (EPA) has set standards for the quality of drinking water supply, and along with its partners, the agency implements numerous financial and technical programs to safeguard drinking water quality. Furthermore, The Clean Water Act establishes the fundamental framework for controlling the discharge of pollutants into waters and for regulating surface water quality standards.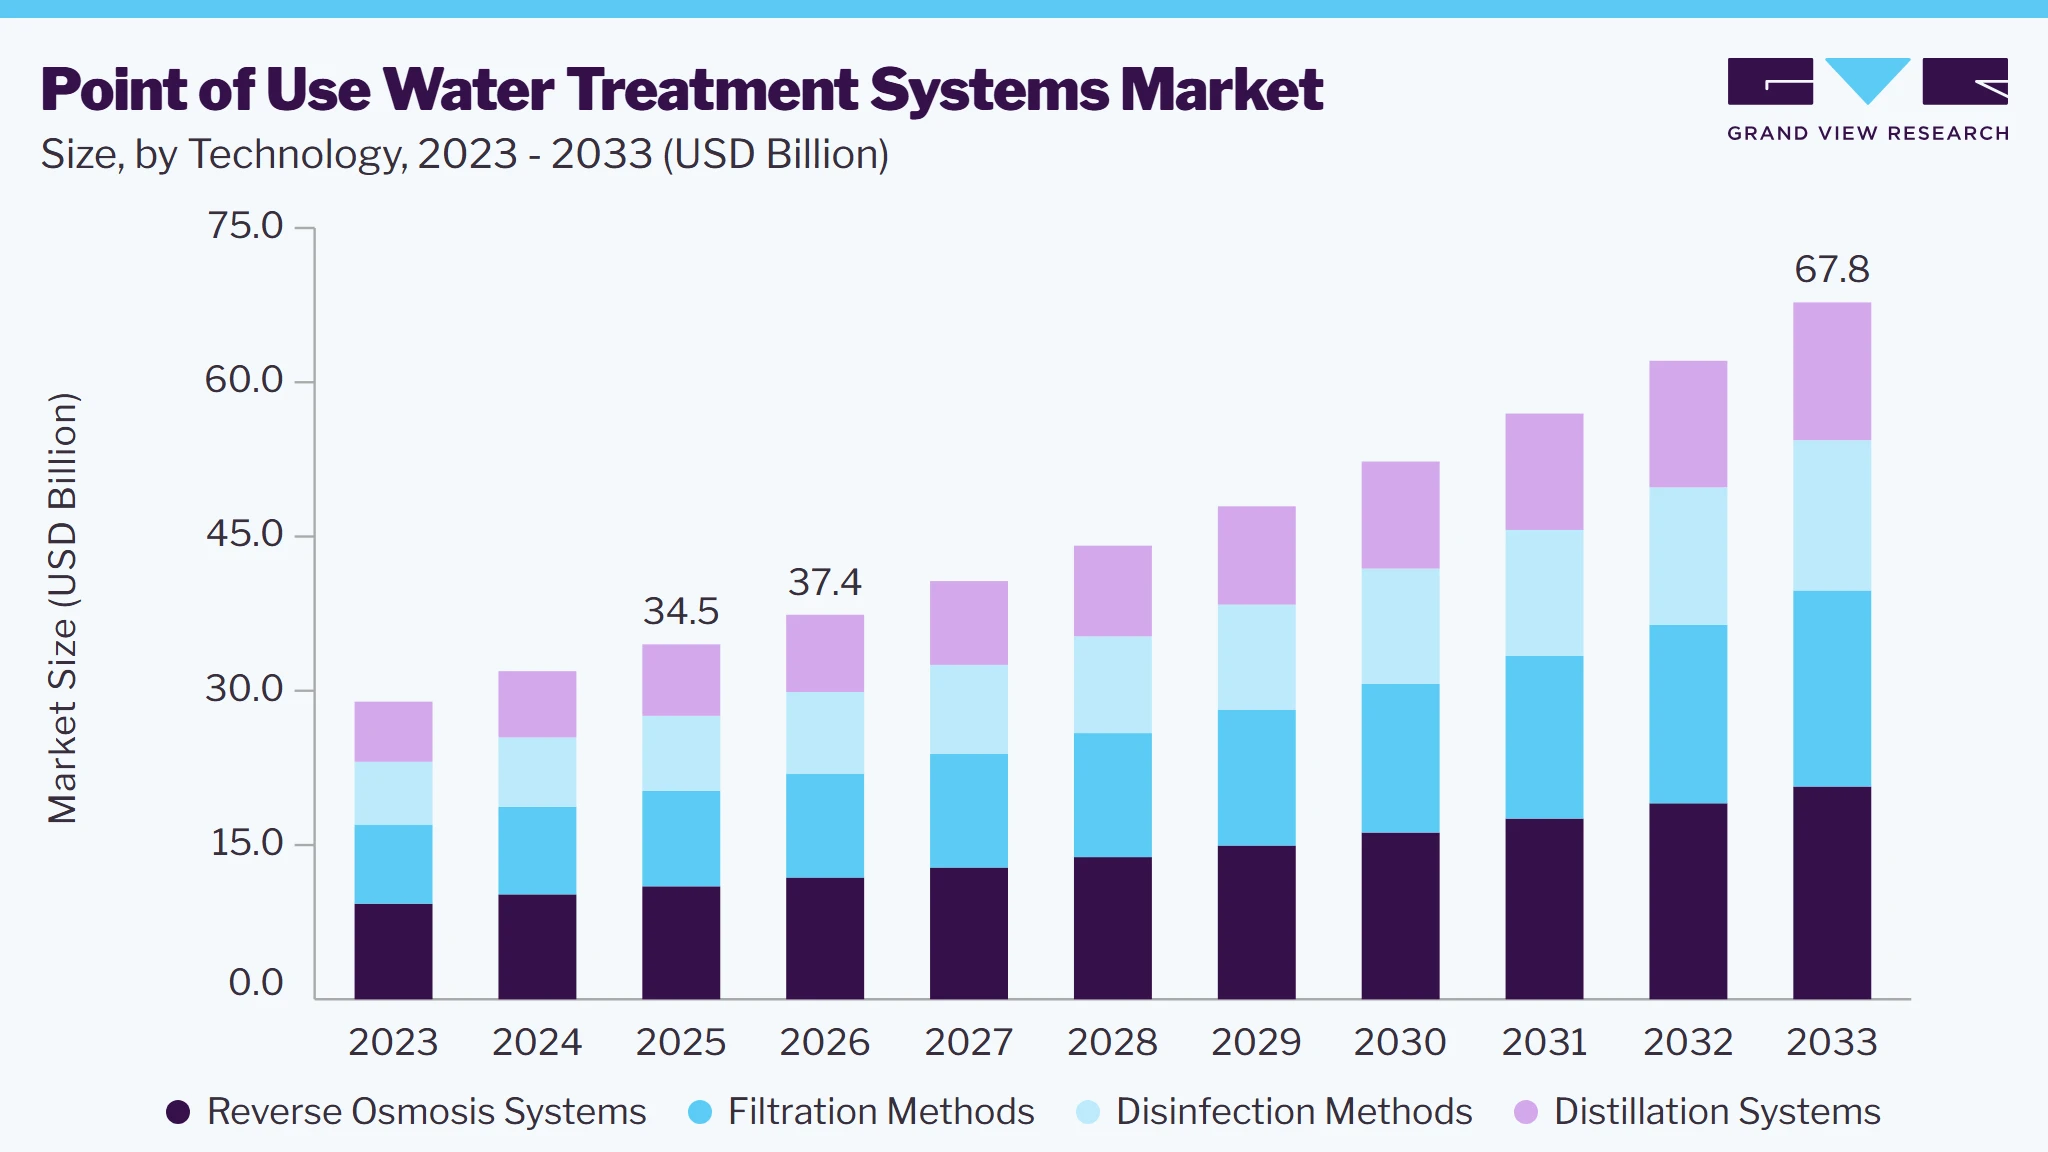 To learn more about this report, Download Free Sample Report
Growing emphasis on the quality of water will drive the market for point of use water treatment systems in the U.S. In addition, to encourage investments in upgrading current domestic water purification facilities and establishing new ones, the U.S. passed a new Public-Private Partnership (PPP) law. Over the forecast period, the favorable initiative to encourage domestic investments in the point of use water treatment systems industry is anticipated to positively affect market growth.
The growing industrial activities and commercial agricultural practices are releasing new pollutants into the water and affecting the health of individuals. This is considerably driving the demand for the point of use water treatment systems. In addition, increasing the motility rates due to unsafe drinking water is raising the demand for point of use water treatment systems. For instance, according to WHO’s 2023 report, about 1 million people are estimated to die from diarrhea each year due to contaminated drinking water. The demand for point of use water treatment systems is significantly influenced by the grade of water quality.
Market Dynamics
The point-of-use water treatment systems market is experiencing steady growth due to increasing concerns over drinking water contamination, rising health awareness, and the growing need for reliable water purification at the point of consumption. Consumers across residential, commercial, and institutional sectors are increasingly investing in compact treatment systems that provide immediate access to safe drinking water while reducing dependence on bottled water. Technological advancements in filtration and purification technologies, combined with stricter water quality standards and urbanization, continue to support market expansion. However, high upfront costs of advanced systems and the need for periodic filter replacement remain key challenges affecting wider adoption.
Increasing contamination of water sources by heavy metals, industrial pollutants, microorganisms, pesticides, and emerging contaminants has significantly increased the demand for point-of-use water treatment systems. Consumers are becoming more aware of the health risks associated with untreated drinking water, prompting households, offices, restaurants, hospitals, and educational institutions to install purification systems that ensure safe and clean water at the point of consumption. Growing public awareness campaigns and stricter drinking water regulations are further encouraging the adoption of advanced filtration technologies.
In addition, rapid urbanization and aging municipal water infrastructure in many countries have increased concerns about water quality even after municipal treatment. This has accelerated the adoption of reverse osmosis, ultraviolet (UV), activated carbon, and multi-stage filtration systems that provide an additional layer of protection. Continuous product innovations, including smart monitoring features, improved membrane efficiency, and compact designs, are making these systems more accessible and attractive to a wider consumer base, supporting long-term market growth.
Although demand for clean drinking water continues to rise, the relatively high initial cost of advanced point-of-use water treatment systems, particularly reverse osmosis and multi-stage purification units, remains a significant barrier to adoption. In addition to installation expenses, consumers must bear recurring costs for filter replacements, membrane maintenance, and periodic servicing to maintain system performance. These ongoing expenditures discourage price-sensitive households and small businesses, particularly in developing regions where affordable water treatment alternatives are often preferred.
The increasing integration of digital technologies into household appliances presents a strong growth opportunity for the point-of-use water treatment systems market. Manufacturers are introducing smart purification systems equipped with IoT connectivity, real-time water quality monitoring, predictive filter replacement alerts, mobile application control, and automated performance diagnostics. These advanced features improve user convenience, enhance system efficiency, and encourage preventive maintenance. As smart homes and connected buildings become more common, demand for intelligent water treatment solutions is expected to create new revenue opportunities for manufacturers and technology providers.
Market Concentration & Characteristics
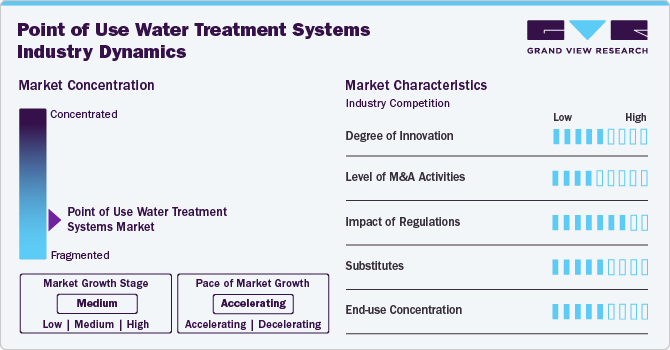
Market growth stage is medium, and pace of the market growth is accelerating. The market is characterized by a high degree of innovation in water filters, UV water disinfection technology, integration of more technologies, and increasing innovative product launches. In February 2025, Culligan Water Quench acquired Stonybrook Water a premium supplier of point of use (POU) water to expand its presence and enhance its offerings in POU water systems.
The market is also characterized by a moderate to high level of product launches and innovation activity by the leading players. This is due to several factors, including the desire to gain improved water treatment capabilities and removal of emerging pollutants from water source for safe use at residential, commercial, and industrial settings. As well as increasing product launches likely to help acquire new customers and increase existing customer engagement.
 To learn more about this report, Download Free Sample Report
The global market is also subject to increasing regulatory compliance. In public assemblies, educational institutions, health & fitness facilities, and others these regulations play a vital role in the increasing demand for point of use water treatment systems for safe drinking water. According to a December 2024 report by the U.S. Environmental Protection Agency (EPA), the Safe Drinking Water Act (SDWA) primarily regulates municipal drinking water systems to safeguard public health. The EPA also acknowledges the significance of point-of-use (PoU) water treatment devices, particularly in areas without access to centralized water treatment.
There are a limited number of direct product substitutes for point of use water treatment systems. Indirect product substitutes or methods used for the treatment of water before using them include traditional methods such as boiling water, alum treatment, and others.
End use concentration is a significant factor in the global market. A number of residential, commercial, and industrial end users that are driving demand for point of use water treatment systems solutions. The increasing awareness among residential customers and strict compliance among the commercial and industrial applications are also expected to increase the end use concentration.
Analyst Perspective
The point-of-use water treatment systems market is expected to witness sustained growth over the forecast period, driven by increasing concerns over drinking water quality, stricter water safety regulations, and rising consumer awareness of health and hygiene. Growing urbanization, aging water infrastructure, and the increasing presence of contaminants such as heavy metals, microorganisms, and emerging pollutants are encouraging households and commercial establishments to adopt advanced point-of-use purification solutions. Technological advancements, including smart connected systems, energy-efficient reverse osmosis technologies, and multi-stage filtration solutions, are further enhancing product performance and user convenience. Looking ahead, manufacturers that focus on innovation, cost-effective designs, sustainability, and expansion in emerging markets are expected to strengthen their competitive position and capitalize on the growing global demand for safe and reliable drinking water solutions.
Technology Insights
Based on technology, reverse osmosis systems segment led the market with the largest revenue share of 31.8% in 2025. The driving factors for the adoption of reverse osmosis point of use water treatment systems include their effectiveness in removing contaminants, energy efficiency, compact design, and versatility in treating various water sources. The technology's ability to address specific contaminants like bacteria, viruses, and dissolved solids further enhances its appeal, making it a preferred choice for households and communities aiming to ensure access to clean and potable water. A point of use reverse osmosis system is a type of water filtration device linked to a specific fixture, like beneath the kitchen sink. RO (reverse osmosis) systems are capable of potentially eliminating various water contaminants, including Volatile Organic Compounds (VOCs), lead, arsenic, PFAS, and others.
Furthermore, product innovations and newly added features in reverse osmosis systems are facilitating the demand for new installations for effective water treatment at the point of use. For instance, in October 2024, Toray Industries, Inc., developed a highly durable reverse osmosis (RO) membrane. This innovation offers long-term provision of high-quality water by desalinating river water and seawater, producing drinking water, and reusing wastewater as a technology to ensure sustainable water sources.
The filtration methods segment is expected to grow significantly over the forecast period. Rising water contamination and health concerns are expected to drive the growth of the point of use water treatment industry. Furthermore, technological advancements in filtration technologies, such as the development of materials capable of removing toxic chemicals, are expected to enhance the effectiveness of POU water treatment systems. For instance, according to a report by the National Technology Alliance in January 2025, Researchers at the Massachusetts Institute of Technology (MIT) have created a new filtration material. It is highly efficient in eliminating PFAS and heavy metals from water.
Device Insights
Based on device, tabletop pitchers segment led the market with the largest revenue share of 34.8% in 2025. This is attributable to the growing adoption of tabletop pitchers owing to their attractive features and characteristics. Tabletop pitchers are compact household water purification devices that sit on tables, providing a convenient and portable solution for treating water at the point of consumption. The ease of use and portability of tabletop pitchers make them a popular choice.
The under-the-sink filters segment is expected to register a significant CAGR during the forecast period. These systems are designed to purify water at the point of use, providing a dedicated solution for enhancing the quality of drinking and cooking water within a specific faucet. Under-the-sink filters are known for their ability to provide comprehensive filtration, targeting a wide range of contaminants such as sediments, chlorine, heavy metals, and various impurities. This level of filtration ensures that users have access to clean and safe drinking water directly from their kitchen faucet. One driving factor is the utilization of space beneath the sink. As these filtration systems are installed discreetly, they don't occupy valuable counter space, which makes them a suitable choice for those who prioritize a clutter-free kitchen.
Application Insights
Based on application, industrial segment led the market with the largest revenue share of 41.6% in 2025. The market demand for point of use water treatment systems in the industrial segment is anticipated to be driven by stringent government regulation and to address contaminants such as polyfluoroalkyl substances (PFAS). Furthermore, smart and connected devices such as Internet of Things (IoT) technologies can be integrated into water treatment systems, which can be remotely accessible. For instance, WaterTDS Inc.’s TDS Bot, a smart IoT device, provides a real-time monitoring solution in the water treatment systems designed for industrial applications. It enhances the reliability and efficacy of various water treatment systems.
 To learn more about this report, Download Free Sample Report
The commercial sector is projected to grow at the fastest CAGR over the forecast period. Point of use water treatment systems for commercial applications are designed to provide localized purification at specific water outlets. These systems ensure that water used for various purposes, such as drinking, cooking, or cleaning, meets quality standards. Common technologies include reverse osmosis, UV disinfection, and filtration. They offer convenience and targeted treatment and can be tailored to specific contaminants present in the water source, making them suitable for non-residential settings with diverse water needs. The demand for point of use water treatment systems in hotels has been on the rise, driven by various factors that cater to both guest satisfaction and operational efficiency. These systems play a crucial role in ensuring the quality and safety of the water supply within hotel establishments. According to HotelTechReport, approximately 81% of hoteliers anticipate that the use of think technology is crucial for the hotel businesses over the next five years.
Regional Insights
North America region has a gradual growth in the point of use water treatment system industry. This is due to stringent government regulations, advancement, and awareness of water contamination issues are driving the point of use water treatment systems industry. Increasing concerns over “forever chemicals” in drinking water, companies are investing in technologies to eliminate polyfluoroalkyl substances (PFAS) from drinking water. According to an article published by Financial Times in July 2024, Companies such as Veolia and Clean Harbor are investing in providing safe drinking water.
U.S. Point of Use Water Treatment Systems Market Trends
The U.S. dominates the North America point of use water treatment systems industry with largest revenue share and is expected to grow at fastest growth rate. The market is driven by the water contamination crises such as Flint and Michigan water crises has raised public awareness about lead poising, PFAS, and other chemicals in water. For instance, according to a report by WaterSense on December 2024, The U.S. Environmental Protection Agency (EPA) enforces the Safe Drinking Water Act, which sets legal limit over 90 contaminants in drinking water. However, this has raised the demand for point of use water treatment systems to improve water quality.
Europe Point of Use Water Treatment Systems Market Trends
The Europe point of use water treatment systems is expected to grow at significantly over the forecast period. The stringent regulations of the government regarding the quality of water are rising the demand for the water treatment industry. According to an article by European Commission on December 2023, The Water Framework Directive (WFD) law which requires member states to restore and protect water bodies to prevent contamination. This initiative has increased the demand for advanced water treatment systems.
Asia Pacific Point of Use Water Treatment Systems Market Trends
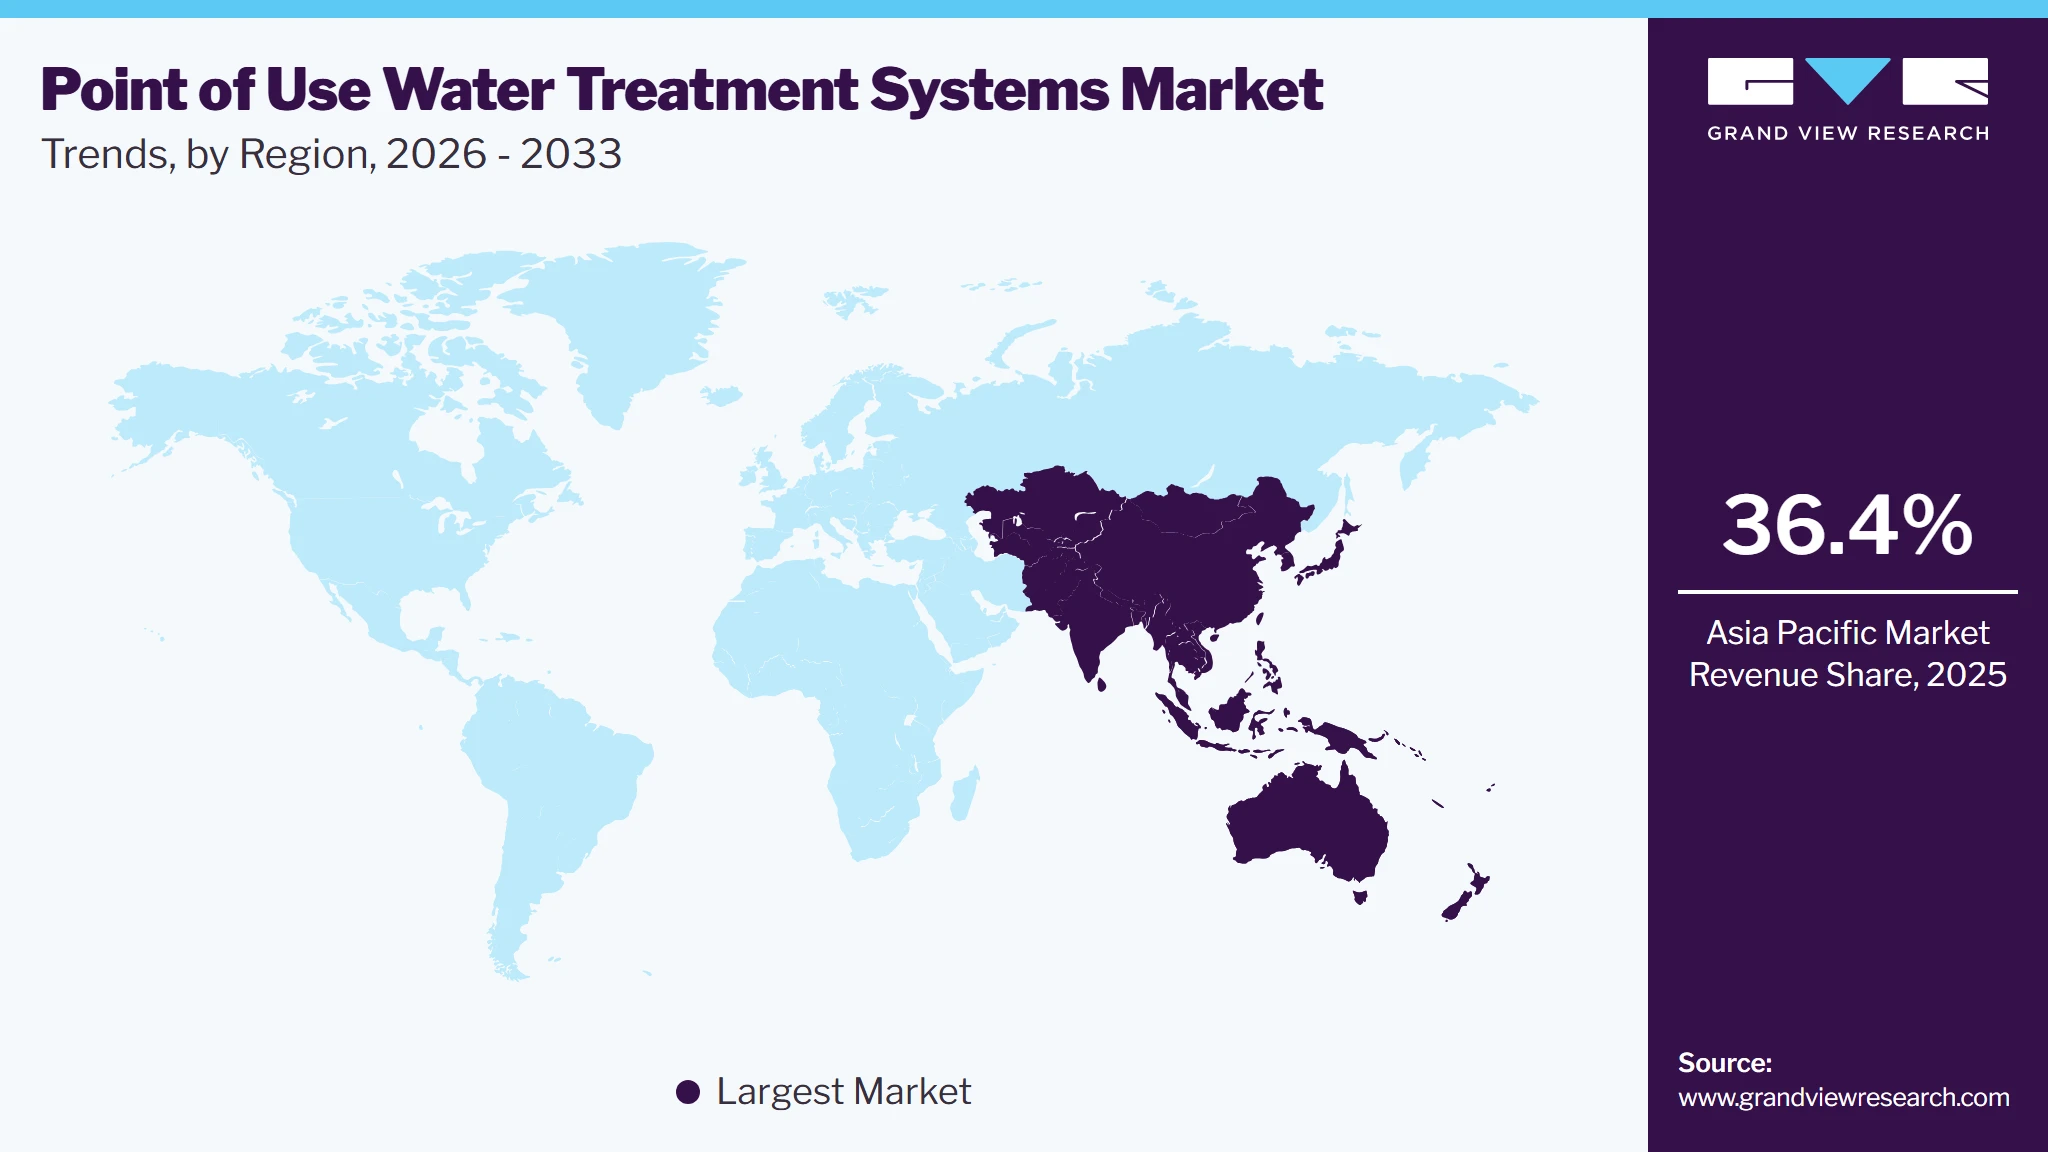
Asia Pacific dominated the point of use water treatment systems market with the largest revenue share of 36.4% in 2025. The region is experiencing rapid urbanization, population growth and economic development in the region middle class has also led to the expansion of urban middle class. However, increase in the disposable income and health awareness the population is more inclined to invest in point of use water treatment system to ensure the quality and safety of drinking water.
 To learn more about this report, Download Free Sample Report
The point of use water treatment systems market in the China held the largest share in the Asia Pacific region in 2025. The stringent water regulations in the country such as on March 2024, China issued regulation on Water Conservation by the State Council of China. The regulation specifies legal responsibilities for illegal acts such as outdated water-intensive technologies, products and equipment banned by the government. In addition, companies are required to adopt advanced and applicable water saving process, technologies and equipment aimed for wastewater treatment, water recycling and reuse.
Middle East & Africa Point of Use Water Treatment Systems Market Trends
Middle East & Africa is anticipated to witness significant growth in the market. The increasing pace of globalization and exposure to global health standards have influenced consumer preferences toward safer and cleaner water sources in the region. Evolving lifestyles and preferences, coupled with a growing understanding of the importance of clean water for overall well-being, contribute to the demand for point of use water treatment systems. Point of use water treatment systems cater to this demand by providing a more direct and individualized solution for ensuring water safety.
Saudi Arabia point of use water treatment system market is expected to register significant growth during the forecast period. Government initiatives and efforts for sustainability drive the market. According to a report by the Arab Gulf States Institute in April 2025, Saudi Arabia’s Vision 2030 highlights sustainable water management solutions. This vision includes promoting water reuse and recycling, indirectly supporting the demand for efficient water purification systems. In addition, evolving consumer preferences regarding safe drinking water and technological advancements in water treatment systems drive the demand for POU water treatment systems in Saudi Arabia.
Key Point of Use Water Treatment Systems Company Insights
Some of the key players operating in the market include 3M, Pentair, LG Electronics, A. O. Smith. Key players are taking several strategic initiatives, such as product launches, geographical expansions, mergers and acquisitions, and others in emerging and economically favorable regions.
-
3M offers range of point of use water treatment systems such as under-the-sink filtration, reverse osmosis systems providing consistent high quality water for commercial applications.
-
LG Electronics offers water purifiers such as faucet mounted filters and tabletop pitchers designed with energy efficient characteristics.
Key Point of Use Water Treatment Systems Companies
The following key companies have been profiled for this study on the point of use water treatment systems market.
-
3M
-
Koninklijke Philips N.V.
-
Pentair
-
Panasonic Corporation
-
Unilever
-
LG Electronics
-
EcoWater
-
A.O. Smith
-
Culligan Water
-
Kinetico Incorporated
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., 3M; Koninklijke Philips N.V.; Pentair; Panasonic Corporation; Unilever; LG Electronics; A.O. Smith; Culligan Water)
- Strong focus on advanced filtration technologies, smart purification systems, and energy-efficient water treatment solutions.
- Expansion of residential and commercial distribution networks across developed and emerging markets.
- Increasing investments in RO, UV, ultrafiltration, and IoT-enabled purification technologies.
- Strong global brand recognition and diversified product portfolios.
- Advanced R&D capabilities and technological expertise in water purification systems.
- Extensive dealer, retail, and aftermarket service networks.
- Premium pricing compared to regional and local manufacturers.
- High dependence on replacement filter and service revenue.
- Exposure to raw material and electronic component price fluctuations.
Emerging & Regional Players (e.g., EcoWater; Kinetico Incorporated)
- Focus on specialized water softening and customized point-of-use water treatment solutions.
- Expansion through dealer-based sales channels and regional partnerships.
- Increasing emphasis on energy-efficient and low-maintenance purification systems.
- Strong expertise in residential water treatment and softening technologies.
- Flexible product offerings tailored to specific water quality conditions.
- Growing customer loyalty in niche and regional markets.
- Comparatively lower global market penetration and brand visibility.
- Limited product diversification compared to multinational players.
- Lower financial scale for large-scale R&D and marketing investments.
Recent Developments
-
In June 2024, Grundfos expanded its presence in the European water treatment market by acquiring Culligan’s Commercial & Industrial division in Italy, France, and the UK. This acquisition strengthens Grundfos's portfolio and regional footprint, complementing its previous acquisitions of EUROWATER and MECO.
-
In June 2024, CIWI and Brabant Water collaborated and launched a pilot project in Zevenbergen to test new technology developed with Delft University of Technology. This technology aims to produce alternatives to metal salts on-site for water purification. This innovation is expected to make water treatment plants more sustainable and robust, advancing environmentally friendly and efficient water purification processes.
-
In 2024, Walker Corporation invested $150 million to accelerate the delivery of drinking and wastewater infrastructure for new developments in Appin, southwest Sydney. This initiative, in partnership with Sydney Water and coNEXA, aims to fast-track the construction of over 12,000 homes by delivering the necessary infrastructure up to a decade earlier than planned
-
In July 2023, Hindustan Unilever, a subsidiary of Unilever, launched the Pureit Revito range of water purifiers. The newly launched purifiers save up to 70% of the water and enrich it with essential minerals like magnesium and calcium. Moreover, it comes with additional features, such as an improved external sediment filter and UV-in-tank sterilization.
Point Of Use Water Treatment Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 34.5 billion
Estimated market size in 2026
USD 37.4 billion
Projected market size by 2033
USD 67.8 billion
Growth rate
CAGR of 8.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, device, application, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; U.K.; Spain; Italy; China; Japan; South Korea; India; Australia; Brazil; Argentina; Saudi Arabia; UAE
Key companies profiled
3M; Koninklijke Philips N. V.; Pentair; Panasonic Holdings Corporation; Unilever; LG Electronics; EcoWater Systems LLC; A. O. Smith; Culligan Water; Kinetico Incorporated
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Point of Use Water Treatment Systems Market Report Segmentation
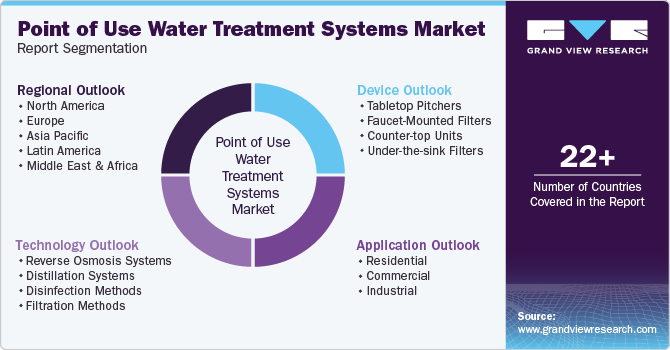
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global point of use water treatment systems industry report based on technology, device, application, and region.
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Reverse Osmosis Systems
-
Distillation Systems
-
Disinfection Methods
-
Filtration Methods
-
-
Device Outlook (Revenue, USD Million, 2021 - 2033)
-
Tabletop Pitchers
-
Faucet-Mounted Filters
-
Counter-top Units
-
Under-the-sink Filters
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Residential
-
Commercial
-
Offices
-
Hotels
-
Restaurants
-
Café
-
Hospitals
-
Schools
-
Others
-
Industrial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
UAE
-
Saudi Arabia
-
-
Research Methodology
The point of use water treatment systems market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each point of use water treatment systems segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Application
Revenue Capture Definition
Reverse Osmosis Systems
Revenue captured from the sale of reverse osmosis-based point-of-use water treatment systems designed to remove dissolved solids, heavy metals, microorganisms, and other contaminants from drinking water.
Distillation Systems
Revenue captured from the sale of point-of-use water distillation systems that purify water through evaporation and condensation for residential and commercial applications.
Disinfection Methods
Revenue captured from the sale of ultraviolet (UV), ozone, and other disinfection-based point-of-use water treatment systems used to eliminate bacteria, viruses, and other harmful microorganisms.
Filtration Methods
Revenue captured from the sale of activated carbon, ceramic, sediment, and other filtration-based point-of-use water treatment systems that improve water quality by removing impurities, odors, chlorine, and suspended particles.
Device
Revenue Capture Definition
Tabletop Pitchers
Revenue captured from the sale of tabletop water filter pitchers that provide portable and convenient drinking water purification for households and small offices.
Faucet-Mounted Filters
Revenue captured from the sale of faucet-mounted water filtration systems that are directly attached to taps to provide instant access to filtered drinking water.
Counter-top Units
Revenue captured from the sale of counter-top point-of-use water purification systems designed for easy installation without requiring major plumbing modifications.
Under-the-sink Filters
Revenue captured from the sale of under-the-sink water treatment systems that offer high-capacity, multi-stage purification for residential and commercial kitchens.
Application
Revenue Capture Definition
Residential
Revenue captured from the sale of point-of-use water treatment systems installed in households to provide safe and clean drinking water for daily consumption.
Commercial
Revenue captured from the sale of point-of-use water treatment systems used across commercial establishments, including offices, hotels, restaurants, cafés, hospitals, schools, and other institutional facilities, to provide high-quality drinking water for employees, customers, patients, students, and visitors.
Industrial
Revenue captured from the sale of point-of-use water treatment systems used in industrial facilities to supply purified water for specific production processes, laboratories, and employee drinking water needs.
Estimation Model
Layer Name
Key Question
Description
Addressable Consumer Base
Who are the primary buyers of point-of-use water treatment systems?
Estimates the potential customer base across residential, commercial, and industrial sectors by evaluating households, commercial establishments, institutions, industrial facilities, water quality concerns, and access to safe drinking water.
Product & Technology Adoption
Which devices and treatment technologies are being adopted?
Assesses the adoption of reverse osmosis, filtration, distillation, and disinfection technologies across tabletop pitchers, faucet-mounted filters, countertop units, and under-the-sink systems based on consumer preferences, regulations, and water quality requirements.
Deployment & Replacement Demand
What factors influence system installations and replacement demand?
Evaluates new installations, replacement of existing systems, filter replacement cycles, infrastructure development, consumer awareness, and demand across residential, commercial, and industrial applications to estimate market penetration.
Revenue Estimation
What is the total market revenue generated?
Calculates the total market revenue by combining technology adoption, device demand, installation trends, replacement demand, and application-wise consumption across key regions to estimate the overall market size and forecast.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered a comprehensive regional analysis covering North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, along with detailed country-level insights for key markets. The report includes market size, growth forecasts, demand trends, regulatory landscape, technology adoption, and competitive presence across each region to help identify regional growth patterns and investment priorities.
Enables clients to identify high-growth regions, prioritize market entry strategies, evaluate regional demand drivers, and make informed decisions on expansion, distribution, and investment opportunities based on localized market intelligence.
Competitive Benchmarking
Delivered a detailed competitive assessment of major industry participants, including company profiles, product portfolios, technology offerings, strategic initiatives, recent developments, mergers & acquisitions, partnerships, and competitive positioning. The report also benchmarks key players based on product innovation, market presence, and business strategies.
Helps clients understand the competitive landscape, identify market leaders and emerging competitors, evaluate differentiation strategies, benchmark their own offerings, and develop effective competitive and partnership strategies.
Opportunity Assessment
Delivered an in-depth evaluation of current and emerging market opportunities by analyzing technology advancements, evolving customer preferences, regulatory developments, untapped application areas, and high-growth end-use sectors. The assessment also highlights future investment hotspots and potential revenue-generating opportunities throughout the forecast period.
Supports strategic decision-making by identifying attractive investment areas, new product development opportunities, expansion potential, and long-term growth prospects, enabling clients to capitalize on emerging market trends and maximize returns.
Frequently Asked Questions About This Report
The global point of use water treatment systems market size was estimated at USD 34.5 billion in 2025 and is projected to grow from USD 37.4 billion in 2026.
The reverse osmosis (RO) systems segment accounted for the largest revenue share of 31.8% in 2025. Its leadership is driven by superior purification performance, the ability to remove dissolved solids, heavy metals, microorganisms, and other contaminants, along with increasing consumer demand for high-quality drinking water in residential, commercial, and industrial applications.
The tabletop pitchers segment held the largest revenue share of 34.8% in 2025. The segment's growth is supported by its affordability, portability, ease of use, and growing consumer preference for simple water filtration solutions that require no installation, particularly among households and renters.
The industrial segment dominated the market with the largest revenue share of 41.6% in 2025. Increasing demand for purified water in manufacturing facilities, laboratories, pharmaceuticals, food & beverage processing, and electronics production, along with stringent water quality standards, has driven widespread adoption of point-of-use water treatment systems across industrial settings.
Asia Pacific is projected to be the fastest-growing regional market during the forecast period. Rapid urbanization, expanding industrialization, rising investments in water infrastructure, increasing concerns over water contamination, and growing awareness of safe drinking water are key factors accelerating market growth.
The global point of use water treatment systems market, in terms of revenue, is expected to grow at a compound annual growth rate of 8.9% from 2026 to 2033 to reach USD 67.8 billion by 2033.
Asia Pacific region dominated the market and accounted for 36.4% share in 2025. The region has been experiencing a surge in demand for safe drinking water, driven by factors such as population growth, rising health awareness, and increasing disposable income.
Some of the key players operating in the point of use water treatment systems market include 3M; Koninklijke Philips N. V.; Pentair; Panasonic Holdings Corporation; Unilever; LG Electronics; EcoWater Systems LLC; A. O. Smith; Culligan Water;Kinetico Incorporated.
The market is primarily driven by rising concerns over drinking water contamination, increasing health awareness, stringent water quality regulations, growing adoption of advanced filtration technologies, rapid urbanization, aging water infrastructure, and increasing demand for convenient and sustainable water purification solutions across residential, commercial, and industrial sectors.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


