
- Home
- »
- Medical Devices
- »
-
Poly-L-lactic Acid Filler Market Size Report, 2026-2033GVR Report cover

Poly-L-lactic Acid Filler Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Face, Neck, Abdomen, Knees, Thighs), By End Use (Medspas, Cosmetic Surgery Centers/Dermatology Clinics), By Region (North America, Europe, MEA), And Segment Forecasts
Market Size, 2025
$214.6MMarket Estimate, 2026
$234.4MMarket Forecast, 2033
$432.0MCAGR, 2026–2033
9.1%Poly-L-lactic Acid Filler Market Summary
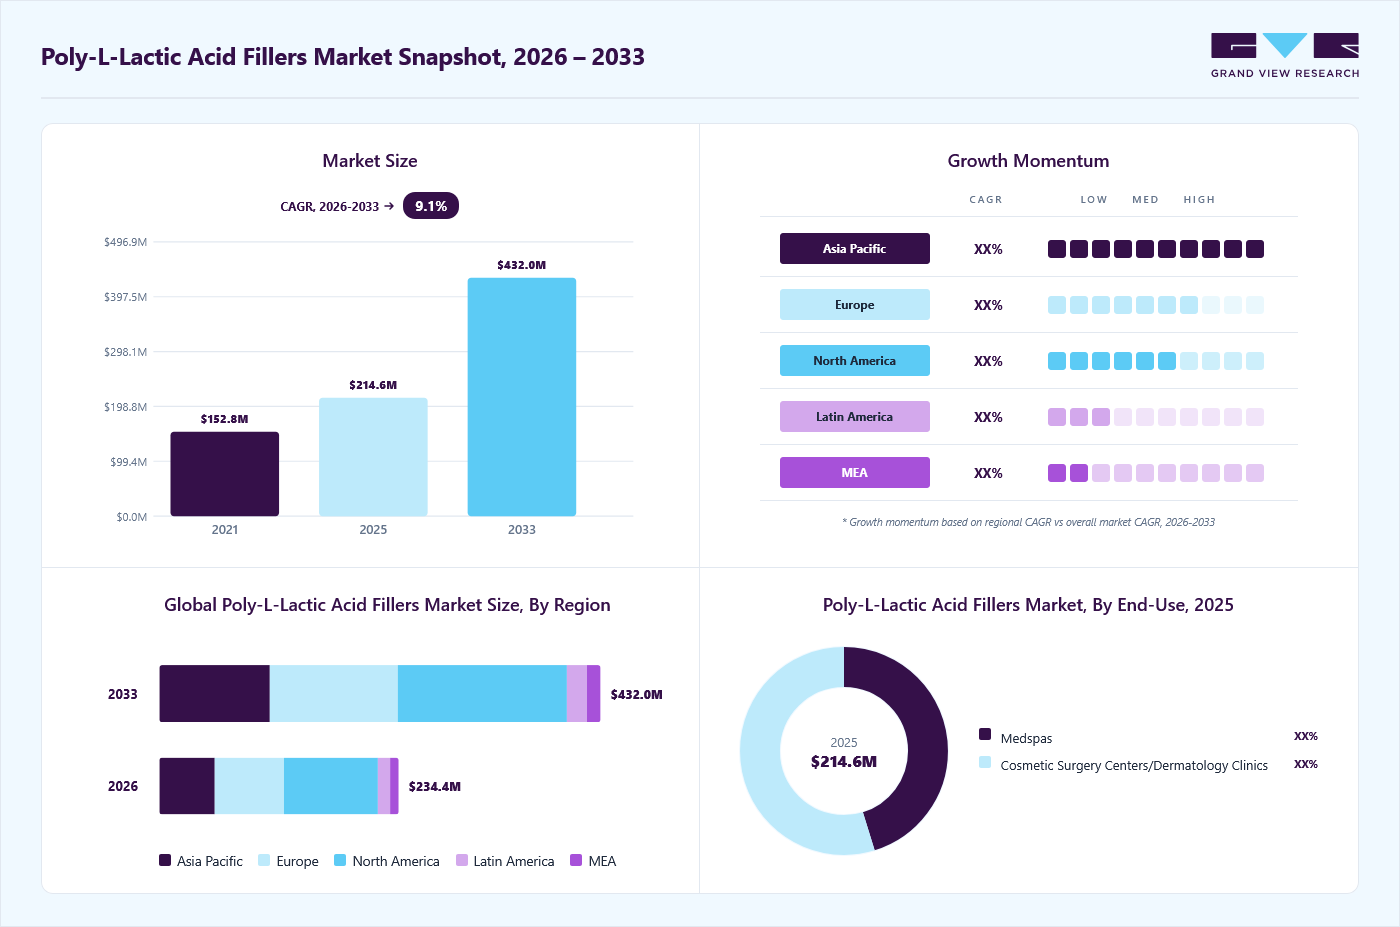
The global Poly-L-lactic acid filler market size was estimated at USD 214.6 million in 2025 and is projected to grow from USD 234.4 million in 2026 to USD 432.0 million by 2033, growing at a CAGR of 9.1% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 39.3% in 2025. Increasing demand for minimally invasive cosmetic procedures is a major factor boosting market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Face segment led the market with the largest revenue share of 44.5% in 2025.
- By end use: Cosmetic surgery centers/dermatology clinics segment led the market with the largest revenue share of 54.8%in 2025.
Regional Highlights
- Largest regional market: North America (39.3% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 214.6 Million
- Estimated market size in 2026: USD 234.4 Million
- Projected market size by 2033: USD 432.0 Million
- CAGR (2026-2033): 9.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the American Society of Plastic Surgeons (ASPS) report published in 2024, in America, 28,243,407 minimally invasive cosmetic procedures were performed. Among these procedures, non-HA fillers such as Radiesse, Sculptra, and Bellafill accounted for 932,861 treatments. This data highlights the significant use of poly-lactic acid (PLLA) filler in aesthetic treatments to restore facial volume and reduce wrinkles. Aging population, rising focus on anti-aging solutions, technological advancements, product innovations, and the growing awareness and acceptance of cosmetic enhancements are the drivers boosting the market's growth.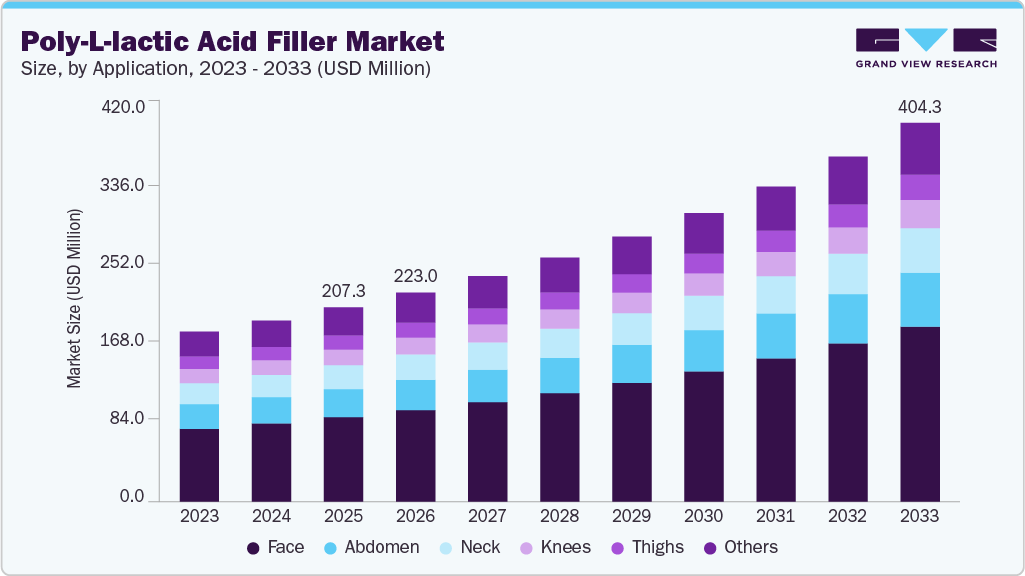 To learn more about this report, Download Free Sample Report
An aging population and a rising focus on anti-aging solutions are boosting the market's growth. According to the United Nations Fund for Population Activities (UNFPA), the global proportion of individuals aged 65 and older is increasing more rapidly than the younger population. This demographic is expected to grow from 5.5% in 1974 to 10.3% in 2024. According to United Nations projections, this figure is expected to double again, reaching 20.7% by 2074. Additionally, the number of people aged 80 and above is set to more than triple over the same period, highlighting the growing demand for aesthetic solutions like Poly-L-lactic Acid (PLLA) fillers to address age-related volume loss and skin rejuvenation. In 2023, ASPS surgeons performed 369,614 cosmetic procedures using non-hyaluronic acid fillers on individuals aged 55 to 69, the highest number among all age groups. This reflects a widespread acknowledgment of PLLA fillers' effectiveness in anti-aging treatments, meeting the demands of aging populations globally.
Technological advancements and product innovations drive the growth of the market as companies continue to explore innovative treatment approaches. In January 2025, Galderma announced promising initial results from a groundbreaking clinical trial assessing the combined use of Restylane Lyft or Contour with Sculptra in patients experiencing medication-induced weight loss and facial volume depletion. The three-month interim data from this first-of-its-kind study demonstrated significant improvements in facial aesthetics, along with high patient satisfaction. These findings, set to be presented at the 43rd Annual J.P. Morgan Healthcare Conference, highlight the growing potential of PLLA-based fillers in advanced aesthetic treatments.
Growing awareness and acceptance of cosmetic enhancements are among the major factors driving the poly-l-lactic acid (PLLA) filler market. According to an NCBI article published in March 2024, several clinical trials and studies have confirmed the safety and efficacy of PLLA in skin rejuvenation. PLLA treatments have been shown to notably increase skin thickness and improve texture, particularly in refining static wrinkles. For instance, a study involving 54 patients in the U.S. demonstrated a 54.9% increase in skin thickness after 12 months of PLLA treatment. Other research has indicated that repeated PLLA treatments can effectively address contour defects and enhance overall skin quality.
Market Dynamics
Poly-L-Lactic Acid (PLLA) fillers are gaining significant traction as they enable aesthetic practitioners and dermatology specialists to effectively restore facial volume, improve skin quality, and address age-related soft tissue loss through long-term collagen biostimulation. These advanced injectable treatments help aesthetic clinics, dermatology centers, medical spas, and cosmetic surgery practices meet the growing demand for minimally invasive facial rejuvenation procedures by providing gradual, natural-looking aesthetic enhancements across diverse patient populations, particularly individuals seeking correction of facial volume depletion, skin laxity, deep wrinkles, and contour deficiencies associated with aging. PLLA fillers support improved aesthetic outcomes, prolonged treatment durability, enhanced patient satisfaction, and reduced reliance on invasive surgical procedures through sustained stimulation of endogenous collagen production. Unlike conventional dermal fillers that primarily provide immediate volumization, PLLA-based formulations promote progressive tissue regeneration and structural support, resulting in long-lasting facial rejuvenation and skin revitalization.
The growing demand for minimally invasive cosmetic procedures is a major factor driving the growth of the PLLA fillers market. Consumers are increasingly seeking aesthetic treatments that provide natural-looking facial rejuvenation, volume restoration, and wrinkle correction without the risks, downtime, and costs associated with traditional surgical interventions such as facelifts and fat grafting procedures. PLLA fillers have emerged as a preferred solution due to their ability to stimulate natural collagen production, offering gradual and long-lasting aesthetic improvements while maintaining a natural facial appearance. The rising influence of social media, increasing awareness of anti-aging treatments, and growing acceptance of aesthetic procedures among both younger and aging populations have further accelerated demand for injectable biostimulatory fillers. Additionally, advancements in injection techniques, improved safety profiles, and expanding availability of treatments across dermatology clinics, aesthetic centers, and medical spas are encouraging greater patient adoption.
Stringent regulatory policies represent a significant restraint to the growth of the PLLA fillers market. As PLLA fillers are injectable medical aesthetic products intended for soft tissue augmentation and collagen stimulation, manufacturers must comply with rigorous regulatory requirements related to product safety, efficacy, biocompatibility, manufacturing quality, and post-market surveillance before obtaining commercialization approvals. Regulatory agencies across major markets, including the U.S., Europe, China, Japan, and other regions, require extensive clinical evidence and long-term safety data to evaluate potential adverse events such as nodule formation, granulomas, inflammatory reactions, product migration, and injection-related complications. The approval process often involves substantial investments in clinical trials, regulatory documentation, quality assurance systems, and ongoing compliance activities, increasing both development timelines and operational costs for market participants.
Market Concentration & Characteristics
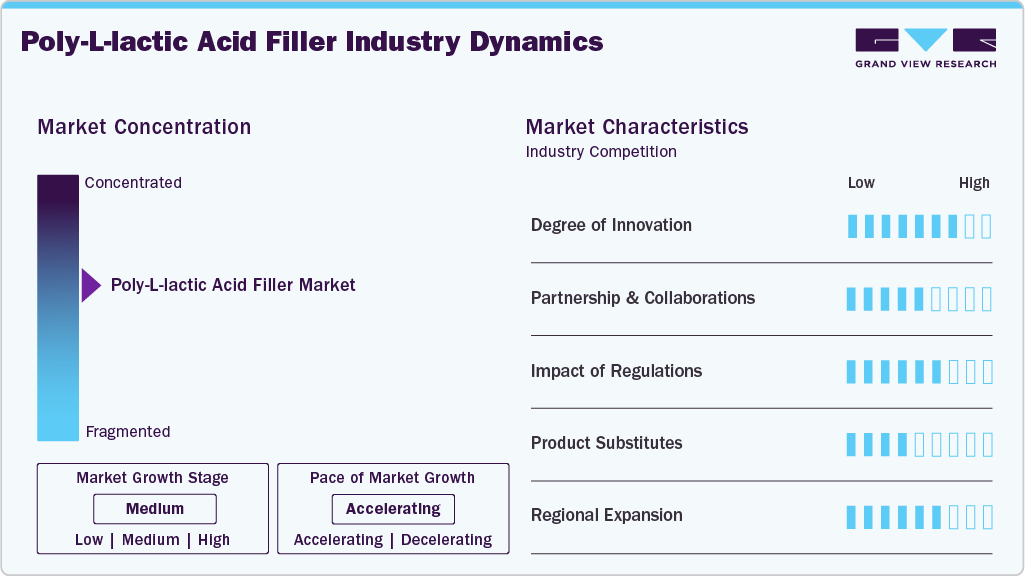
The PLLA fillers industry is moderately concentrated, with leading companies such as Galderma, Sinclair Pharma, GANA R&D Co., Ltd., and PRP Life Science Co., Ltd holding significant shares of the market. These players offer advanced collagen-stimulating injectable fillers designed to restore facial volume, improve skin texture, and reduce wrinkles through gradual collagen regeneration. Their product portfolios include well-known PLLA-based aesthetic injectables such as Sculptra and AestheFill, which are widely used for facial rejuvenation and long-lasting anti-aging treatments. The market continues to evolve due to advancements in biostimulatory dermal filler technologies, improved formulation stability, and innovations in injection techniques that enhance safety and treatment outcomes. In addition, the rising demand for minimally invasive aesthetic procedures, increasing consumer focus on natural-looking anti-aging solutions, and the growing acceptance of cosmetic dermatology treatments are supporting market growth.
The industry is experiencing significant innovation due to advancements in regenerative aesthetic technologies and collagen-stimulating injectable formulations. PLLA fillers function as biostimulatory agents that gradually stimulate collagen production, enabling long-lasting improvements in skin structure, facial volume, and wrinkle reduction. Recent clinical research has focused on improving injection protocols, dilution techniques, and treatment combinations to enhance safety and treatment outcomes. For instance, a 2024 clinical review published in the journal Plastic and Reconstructive Surgery - Global Open highlighted advances in PLLA injection techniques and expanded aesthetic indications, including facial rejuvenation, skin tightening, and body contouring applications. These innovations improve treatment precision and patient outcomes while supporting the growing adoption of collagen-stimulating dermal fillers in aesthetic medicine. Such technological and clinical advancements are expected to drive the growth of the PLLA fillers market during the forecast period.
 To learn more about this report, Download Free Sample Report
Partnerships and collaborations play a crucial role in the poly-L-lactic acid (PLLA) fillers industry, enabling companies to expand their aesthetic portfolios, strengthen distribution networks, and improve clinical adoption of collagen-stimulating injectable treatments. Strategic alliances between pharmaceutical companies, aesthetic clinics, and dermatology organizations help accelerate product availability and training for advanced injection techniques. These collaborations also support knowledge sharing through clinical workshops, medical conferences, and certification programs for dermatologists and aesthetic practitioners, which help improve treatment outcomes and patient satisfaction.
Regulatory approval plays a critical role in shaping the industry by ensuring that injectable aesthetic products meet stringent safety, efficacy, and quality standards before they are introduced to the market. Regulatory authorities such as the U.S. Food and Drug Administration, the European Medicines Agency, and the National Medical Products Administration in China regulate dermal fillers as medical devices or injectable aesthetic products. Manufacturers must provide comprehensive clinical data demonstrating biocompatibility, sterility, long-term safety, and effectiveness in stimulating collagen production and improving facial volume. Compliance with these regulatory frameworks enhances confidence among dermatologists, plastic surgeons, and aesthetic practitioners while supporting broader adoption of PLLA-based fillers in cosmetic procedures.
Product substitutes in the industry include other dermal filler materials and non-surgical aesthetic treatments that are widely used for facial rejuvenation and anti-aging procedures. Common alternatives include hyaluronic acid (HA) fillers, calcium hydroxylapatite (CaHA) fillers, polymethylmethacrylate (PMMA) fillers, as well as energy-based aesthetic treatments such as laser skin resurfacing, radiofrequency skin tightening, chemical peels, and botulinum toxin injections. These treatments are often preferred for addressing mild to moderate wrinkles, fine lines, and skin texture improvements due to their quicker treatment time and immediate results. For instance, HA-based fillers such as Juvederm and Restylane are widely used alternatives because they provide instant volume restoration and are reversible. Similarly, calcium hydroxylapatite fillers such as Radiesse and PMMA fillers like Bellafill are used for long-lasting facial contouring and wrinkle correction.
Regional expansion in the industry is gaining momentum across key global regions, driven by the increasing demand for minimally invasive aesthetic procedures, growing aging populations, and rising awareness of cosmetic dermatology treatments. Companies are actively broadening their geographical presence through strategic partnerships with local distributors, collaborations with aesthetic clinics, and targeted product registrations to enhance market access. These regional expansion strategies enable companies to capture new customer segments, strengthen brand recognition, and support the overall growth of the PLLA fillers industry.
Analyst Perspective
The PLLA fillers market is positioned at the intersection of several long-term aesthetic medicine and healthy aging trends, including the growing global demand for minimally invasive cosmetic procedures, increasing consumer preference for natural-looking aesthetic outcomes, and rising awareness of collagen biostimulation therapies. As aging populations continue to expand and aesthetic consciousness increases among both younger and older demographics, demand for advanced facial rejuvenation solutions that address volume loss, skin laxity, and age-related structural changes is expected to accelerate. PLLA fillers are gaining significant traction due to their unique ability to stimulate endogenous collagen production, providing gradual, long-lasting, and natural-looking aesthetic improvements compared to conventional volumizing fillers. The market is further benefiting from the growing shift toward regenerative aesthetics, where treatment approaches focus on restoring underlying tissue quality rather than simply correcting visible signs of aging. Increasing adoption of collagen stimulators by dermatologists, plastic surgeons, and aesthetic practitioners is creating new growth opportunities across facial rejuvenation, body contouring, skin quality enhancement, and combination aesthetic treatment protocols. Additionally, continuous advancements in PLLA particle technology, injection techniques, product formulation, and treatment customization are improving clinical outcomes, safety profiles, and patient satisfaction rates.
Application Insights
Based on application, the face segment led the market with the largest revenue share of 44.5% in 2025, owing to the rising popularity of facial rejuvenation procedures, technological advancements in fillers, and the expanding middle-aged and elderly population. Recent advancements in PLLA filler technology aimed to develop more refined formulations. For example, Devolux Injectable Filler employs advanced granular technology to produce ultra-fine particle sizes (3-5µm), enabling faster dissolution and dispersion within five minutes. This improvement minimizes the risk of post-treatment issues like nodules and papules, resulting in a smoother and safer treatment experience. These advancements contribute to the growing popularity and trust in PLLA treatments for facial applications. The American Academy of Facial Plastic and Reconstructive Surgery (AAFPRS) released new statistics highlighting key trends in facial plastic surgery, reporting that patients aged 35-55 now account for about 32% of facelift procedures, up from 26% in previous years. With a rising number of younger patients (ages 35-55) opting for facial procedures, the need for non-surgical alternatives like PLLA fillers is expanding.
The abdomen segment is driven by the increasing demand for non-invasive skin rejuvenation and tightening solutions. Abdominal skin laxity commonly occurs due to aging, pregnancy, and significant weight loss, leading many individuals to seek aesthetic treatments to restore skin firmness and elasticity. Individuals with mild-to-moderate skin laxity or those unwilling to undergo surgery turn to PLLA-based stimulatory collagen activators as a safer and more convenient alternative. Research supports the effectiveness of PLLA-SCA in improving sagging, wrinkling, dimpling, and cellulite, with long-lasting results and minimal side effects. The introduction of advanced formulations, such as Lanluma, has further expanded the application of PLLA fillers beyond traditional facial treatments, positioning them as a versatile solution for abdominal rejuvenation. As consumer awareness grows and technology advances, the market for PLLA fillers in abdominal treatments is expected to experience significant expansion, catering to the rising demand for minimally invasive body contouring solutions.
End-use Insights
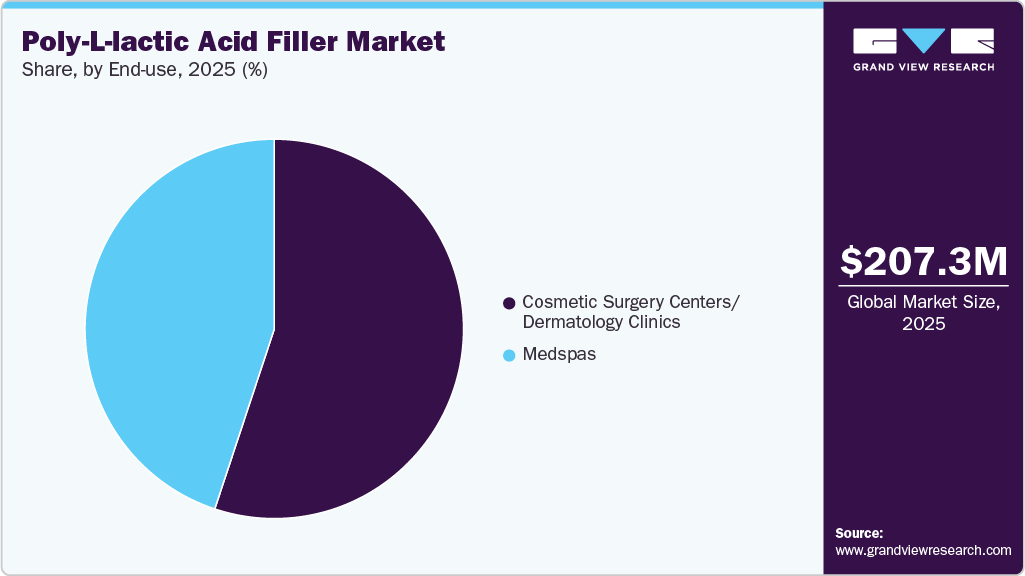
Based on end use, the cosmetic surgery centers/dermatology clinics segment led the market with the largest revenue share of 54.8%in 2025, due to an increasing patient base seeking minimally invasive alternatives to traditional surgical procedures. Cosmetic surgery centers are well-equipped with advanced technologies and skilled professionals who can effectively administer PLLA fillers. Moreover, the integration of PLLA fillers into the treatment protocols at cosmetic surgery centers is supported by continuous advancements in product formulations and injection techniques. These innovations improve the safety, efficacy, and patient satisfaction of PLLA filler treatments, making them a reliable option for practitioners and patients. In addition, the growing strategic initiatives adopted by key players are anticipated to fuel segment growth over the forecast period. For instance, in January 2024, The Waldorf Center for Plastic Surgery partnered with Forefront Dermatology Group, a well-established dermatology organization. Such collaborations underscore the growing integration of cosmetic surgery and dermatology services. In February 2023, Athenix, a leading plastic surgery practice in the U.S., acquired Marina Plastic Surgery and Medspa, a renowned cosmetic surgery center in California, the U.S. By this acquisition, Athenix would operate from six locations in the U.S. Similarly, in June 2023, Kortesis Bharti Management Group, LLC acquired Lowcountry Plastic Surgery Center. Post-acquisition, the latter company’s name will be H/K/B Mount Pleasant.
 To learn more about this report, Download Free Sample Report
The medspas segment is expected to show lucrative growth during the forecast period due to increasing consumer confidence in the safety and efficacy of non-invasive treatments offered in these settings, supported by stringent regulatory oversight and advancements in injection techniques. Moreover, medspas are strategically positioned to offer consumers who value personalized care and a complete approach to beauty and wellness. Medspas, which combine medical expertise with a spa-like environment, offer a range of non-surgical cosmetic procedures that appeal to a broad demographic seeking rejuvenation and enhancement without the downtime associated with surgical options. In 2024, the American Med Spa Association reported that over 10,488 Med spas were operational in the U.S., representing a 15.2% increase in recent years. According to the American Med Spa Association’s 2024 Medical Spa State of the Industry Report, an average medical spa generates more than USD 1.4 million annually.
Regional Insights
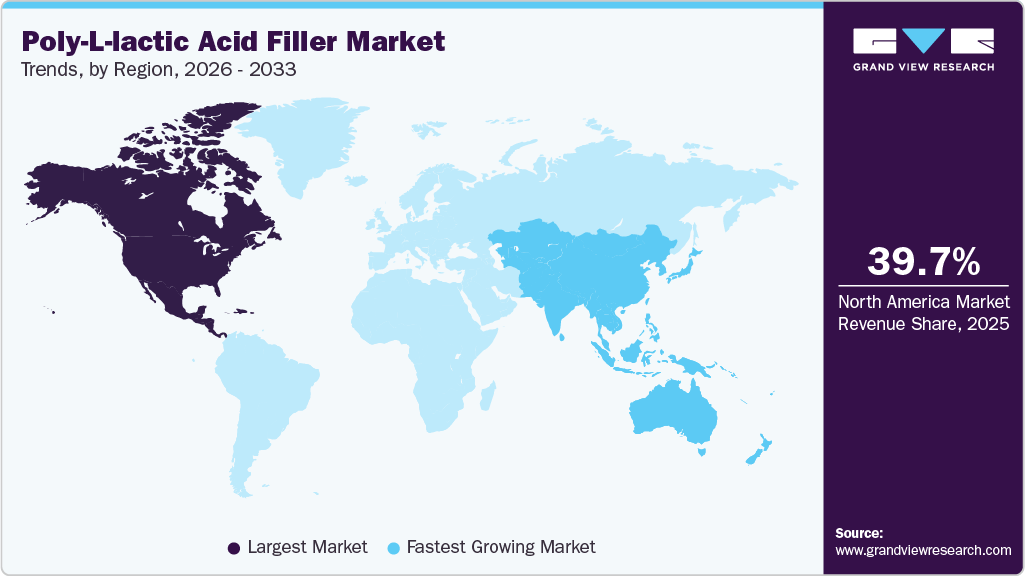
North America dominated the poly-l-lactic acid (PLLA) filler market with the largest revenue share of 39.3%in 2025, owing to advanced healthcare infrastructure, increasing adoption of aesthetic procedures, huge research and development activities, continuous technological advancements in cosmetic treatments, growing geriatric population and a strong presence of key market players. The growing geriatric population in the U.S., susceptible to skin imperfections or diseases, is expected to increase the demand for cosmetic procedures, thereby significantly contributing to the market growth over the forecast period. Moreover, according to a U.S. Census Bureau article published in May 2023, the geriatric population in the region is about 1 in 6 people above 65. Furthermore, the country has the most plastic surgeons, fueling market growth. Furthermore, the country has the highest number of plastic surgeons, expected to boost market growth.
 To learn more about this report, Download Free Sample Report
U.S. Poly-L-lactic Acid Filler Market Trends
The poly-l-lactic acid (PLLA) filler market in the U.S. held the largest share in the North America region in 2025. This dominance can be attributed to several key factors, including a highly developed healthcare infrastructure and the advanced cosmetic industry, which facilitate widespread availability and adoption of PLLA fillers among consumers and healthcare providers. Moreover, the economy and high disposable incomes enable greater affordability and accessibility to aesthetic treatments like PLLA fillers, and technological advancements boost the market's growth. According to the American Society of Plastic Surgeons 2024 Procedural Statistics Report, nearly 1.6 million cosmetic surgical procedures and over 28.5 million minimally invasive aesthetic procedures were performed in the U.S. in 2024. Injectable treatments remained highly popular, with around 5,331,426 hyaluronic acid filler procedures conducted during the year, reflecting strong consumer demand for minimally invasive facial rejuvenation treatments.
Europe Poly-L-lactic Acid Filler Market Trends
The poly-l-lactic acid (PLLA) filler market in Europe held a significant share in 2025 due to the presence of skilled professionals and the rise in the geriatric population. Rising demand for advanced treatment tools in Europe is a major factor anticipated to propel the market growth. The region’s growing geriatric population has led to an increased demand for anti-aging and facial rejuvenation treatments, particularly long-lasting, collagen-stimulating fillers such as PLLA-based products. Rising awareness and acceptance of minimally invasive cosmetic procedures among middle-aged and elderly populations have further fueled market growth.
Germany poly-l-lactic acid (PLLA) filler market dominated Europe with the highest revenue share of 24.6% in 2025. Various factors, such as an increase in the popularity of cosmetic procedures, an aging population, technological advancements, and a rise in beauty consciousness, are driving the market. The aging population's interest in maintaining a youthful appearance drives market growth as individuals seek nonsurgical solutions like dermal fillers, emphasizing the relevance & potential growth within the market in Germany. According to AARP, the prevalence of individuals aged 65 and above is expected to increase by 41%, reaching 24 million by 2050, which will make up nearly one-third of the total population, and is a significant growth driver for the poly-l-lactic acid (PLLA) filler market.
The poly-l-lactic acid filler market in the UK held the second largest regional share in 2025. The country's growing number of nonsurgical procedures is expected to boost the market over the forecast period. According to the ISAPS 2023 report, nearly 22,526 nonsurgical procedures were performed nationwide. Moreover, it was estimated that nearly 729 surgeons were registered in the country. Moreover, the country is rapidly changing its regulations for poly-l-lactic acid (PLLA) filler due to practitioner malpractices. For instance, in September 2023, a government consultation program was launched to improve the clinical practices related to dermal fillers and Botox procedures.
France poly-l-lactic acid (PLLA) filler market is anticipated to witness a significant CAGR of 9.0% during the forecast period. Increased awareness among customers about the potential benefits of aesthetic procedures and the growing adoption of minimally invasive procedures are boosting the market in France. Furthermore, rising purchasing power, growing involvement of international players, increasing spending on cosmetics and personal care, & rising number of beauty clinics are among the factors fueling the market growth in France.
Asia Pacific Poly-L-lactic Acid Filler Market Trends
The poly-l-lactic acid (PLLA) filler market in Asia Pacific is expected to grow at the fastest rate during the forecast period. This can be attributed to the rising medical tourism industry, especially in Southeast Asia where high-quality cosmetic procedures are available at more affordable rates compared to Western nations. In addition, the growing middle-class population, increasing disposable income, and rising awareness of non-surgical aesthetic treatments are fueling demand for minimally invasive procedures such as PLLA, CaHA, and hyaluronic acid-based fillers. Social media influence and cultural trends emphasizing youthful appearance further encourage consumers, especially in urban areas, to seek facial rejuvenation treatments.
China poly-l-lactic acid (PLLA) filler market accounted for the largest share of the Asia Pacific region in 2025 due to increasing demand for antiaging procedures. According to the WHO, 28% of the country’s population is projected to be above 65 by 2040, which in turn is expected to boost the adoption of noninvasive aesthetic treatments. Moreover, according to the ISAPS in 2024, China has a surgical workforce of 5,000 surgeons, constituting 8.5% of the total number of surgeons.
The poly-l-lactic acid (PLLA) filler market in Japan held the second largest market share in the Asia Pacific region. Japan is one of the most rapidly aging countries in the world. The National Institute of Population and Social Security Research projects that by 2040, individuals aged 65 & older will make up 34.8% of Japan's total population. The rapidly aging population in the country is also anticipated to boost the market demand, as the geriatric population is more susceptible to fine lines, wrinkles, saggy skin, and other signs of aging.
The India poly-l-lactic acid (PLLA) filler market is experiencing significant growth, driven by increasing affordability of aesthetic procedures along with growing disposable income & awareness about these procedures. Moreover, lower treatment costs in the country are expected to contribute to the growing medical tourism. According to the Times of India article published in May 2023, India witnesses an annual arrival of around 800,000 to 1 million cosmetic procedure patients, 10% of whom come from foreign countries. This positions India as the sixth most favored global destination for medical tourism in cosmetic procedures.
Latin America Poly-L-lactic Acid Filler Market Trends
The poly-L-lactic acid (PLLA) filler market in Latin America is growing due to several factors. These countries are preferred for medical tourism due to the availability of treatments at a lower cost (30% to 70% discount) compared to North American and European countries. In addition, a stronger emphasis on physical beauty coupled with extensive acceptance of facial surgeries has led to the high demand for poly-l-lactic acid filler in Brazil.
Brazil poly-l-lactic acid filler market is expanding due to several distinct growth drivers. Brazil has a strong culture of beauty & aesthetics, emphasizing youthful appearances and physical attractiveness. This cultural focus on beauty has contributed to the widespread acceptance and use of poly-l-lactic acid filler to enhance or maintain one's appearance. According to the ISAPS report in 2024, 2,354,513 surgical procedures were conducted in Brazil, alongside 769,245 nonsurgical procedures.
MEA Poly-L-lactic Acid Filler Market Trends
The poly-l-lactic acid filler market in the Middle East & Africa is expected to grow at the lucrative rate. The MEA region is witnessing a rising preference among consumers for non-surgical cosmetic treatments, driven by increasing disposable incomes and a growing awareness of aesthetic procedures. Moreover, MEA countries invest in healthcare infrastructure and adopt advanced aesthetic technologies, facilitating greater accessibility to cosmetic procedures, including PLLA fillers.
South Africa poly-l-lactic acid (PLLA) filler market held the 17.2% share in the MEA region. The growing demand for hyaluronic acid-based dermal fillers from the geriatric population is expected to boost market growth. According to the UNFPA Statistics, in 2024, nearly 6% of the total country’s population was aged over 65. The market is further supported by the presence of advanced dermatology clinics and aesthetic centers in urban areas, particularly in Johannesburg, Cape Town, and Durban, where consumers have better access to aesthetic procedures. Rising disposable incomes, urbanization, and the growing influence of social media and beauty trends have also encouraged consumers to opt for minimally invasive treatments over surgical alternatives.
Key Poly-L-lactic Acid Filler Company Insights
Some of the key players operating in the industry include Galderma, GANA RND and Sinclair Pharma. Companies’ key strategies include understanding the strengths and weaknesses of major market participants, anticipating future market trends, opportunities, and challenges, and making proactive decisions based on insights into emerging technologies and changing consumer preferences. For instance, PRP Science and Laboratories Hyamed SA are some of the emerging players in the poly-l-lactic acid (PLLA) filler. These industry players continuously focused on leveraging specialized technologies to differentiate themselves.
Key Poly-L-lactic Acid Filler Companies
The following key companies have been profiled for this study on the poly-l-lactic acid filler market.
-
Galderma
-
Sinclair Pharma
-
GANA RND
-
PRP Life Science Co., Ltd
-
Laboratories Hyamed SA
-
Dermax Co., Ltd
-
Rimless Industry Co., Ltd.
-
Hangzhou Singclean Medical Products Co.,Ltd
-
LINKUS GLOBAL Co., Ltd.
 To learn more about this report, Download Free Sample Report
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Galderma, Sinclair Pharma, GANA RND)
- Focus on expanding global distribution networks and strengthening presence in high-growth aesthetic markets.
- Invest heavily in clinical studies, physician training programs, and scientific evidence supporting collagen biostimulation benefits.
- Strong brand recognition and extensive physician trust developed through long-term clinical performance.
- Robust regulatory approvals and established safety profiles across multiple geographies.
- High dependence on regulatory approvals and compliance requirements across multiple regions.
- Premium product pricing may limit adoption in price-sensitive markets.
Emerging Players (Rimless Industry Co., Ltd., Hangzhou Singclean Medical Products Co.,Ltd, LINKUS GLOBAL Co., Ltd.)
- Focus on regional expansion and targeted commercialization in emerging aesthetic markets.
- Develop cost-competitive PLLA formulations to address unmet demand in mid-tier clinics and medical spas.
- Greater operational flexibility and faster response to evolving market trends.
- Ability to develop customized products tailored to local regulatory and physician requirements.
- Restricted financial resources for large-scale clinical trials and global expansion initiatives.
- Greater vulnerability to regulatory changes and reimbursement limitations.
Recent Developments
-
In December 2025, Galderma announced that Sculptra, a PLLA-based regenerative biostimulator, received EU Medical Device Regulation (MDR) certification along with expanded indications for body contouring treatments. The certification strengthens the company’s regulatory standing and supports wider adoption of PLLA fillers across European aesthetic markets.
-
In January 2025, South Korean aesthetics company Hugel Inc. announced plans to pursue mergers and acquisitions involving PLA- and collagen-based injectable products as part of its strategy to expand in the global dermal filler market. The move reflects increasing demand for collagen-stimulating fillers such as PLLA in medical aesthetics.
-
In January 2025, Alpha Aesthetics Partners announced its strategic collaboration with Flawless Medspa & Wellness, a reputed aesthetic-care center in Mexico and abroad. This partnership would expand the business in body contouring, dermal fillers, and other aesthetic treatments by combining expertise from both the companies.
-
In February 2024, Praj Industries revealed that its polylactic acid (PLA) pilot plant was nearing completion and would convert to operation by April 2024. The facility, designed to manufacture bioplastics, was part of the company’s R&D push to develop renewable chemicals like biodegradable polymers using feedstocks.
-
In April 2023, Galderma revealed that the U.S. FDA had launched Sculptra (injectable poly-L-lactic acid) for treating fine lines and wrinkles in the cheek area. Sculptra, the first FDA-launched PLLA collagen stimulator, enhances collagen production to smooth wrinkles and improve skin firmness and glow, with effects lasting up to 2 years.
Poly-L-lactic Acid (PLLA) Filler Market Report Scope
Report Attribute
Details
Market size in 2025
USD 214.6 million
Estimated market size in 2026
USD 234.4 million
Projected market size by 2033
USD 432.0 million
Growth rate
CAGR of 9.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Galderma; Sinclair Pharma; GANA RND; PRP Life Science Co., Ltd; Laboratories Hyamed SA; Dermax Co., Ltd; Rimless Industry Co., Ltd.; Hangzhou Singclean Medical Products Co., Ltd; LINKUS GLOBAL Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Poly-L-lactic Acid Filler Market Report Segmentation
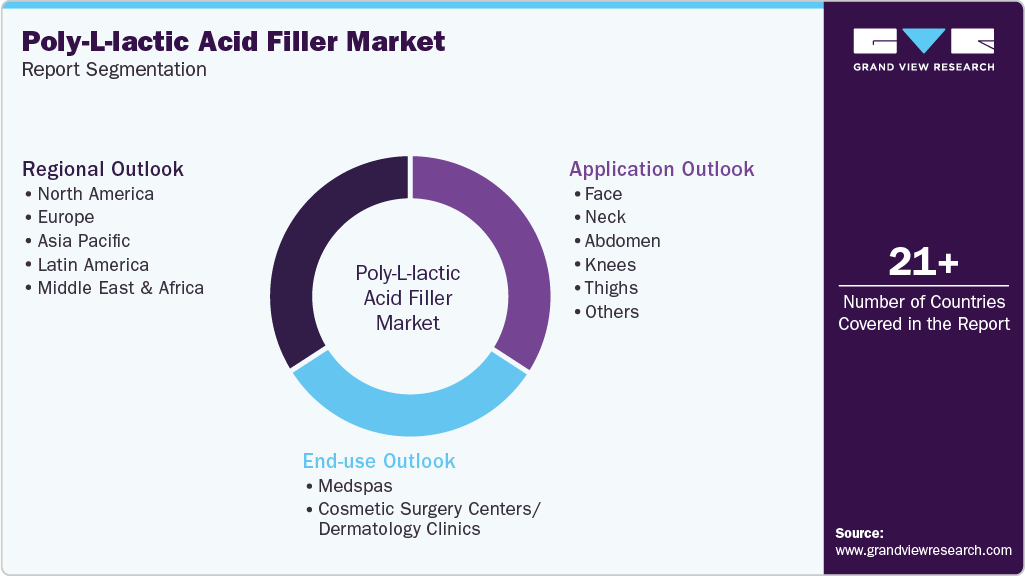
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global poly-l-lactic acid filler market report on the basis of application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Face
-
Neck
-
Abdomen
-
Knees
-
Thighs
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Medspas
-
Cosmetic Surgery Centers/Dermatology Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The poly-l-lactic acid filler market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each poly-l-lactic acid filler segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Face
Revenue is generated through the sale of PLLA injectable vials engineered for facial structural rejuvenation, addressing midfacial volume loss, temporal hollowing, nasolabial folds, and deep static wrinkles. Manufacturers derive high-volume, premium revenue streams from multi-vial treatment series per patient, fueled by cosmetic injectors purchasing replenishment inventory to satisfy consumer demand for gradual, long-lasting facial collagen neogenesis.
Neck
Revenue flows from the commercialization of PLLA microsphere formulations applied to the submental and cervical regions to correct skin laxity, horizontal neck bands, and structural crepiness. Value is captured via hyper-diluted vial sales optimized specifically for superficial dermal placement, driving incremental ordering volumes beyond traditional facial anti-aging portfolios.
Abdomen
Revenue is derived from the procurement of high-volume or specialized thick-cut PLLA filler configurations indicated for body contouring and the treatment of post-pregnancy or post-weight-loss abdominal skin laxity. Manufacturers capture revenue through multi-vial bundle shipments required to treat larger body surface areas, operating on high-unit-volume transaction profiles.
Knees
Revenue is captured through the supply of PLLA biostimulatory injectables targeted at resolving suprapatellar wrinkling, sagging tissue, and skin thinning around the knee joints. Revenue streams are driven by specialized, niche aesthetic product positioning, allowing manufacturers to leverage targeted marketing to certified practitioners specializing in localized body-skincare restoration.
Thighs
Revenue flows from the distribution of PLLA formulations utilized for large-scale body contouring, targeting outer/inner thigh skin laxity, dimpling, and structural cellulite correction. Market participants generate significant revenue from high-volume, bulk vial purchasing agreements with top-tier aesthetic accounts due to the extensive product volumes demanded by multi-session thigh tissue reconstruction protocols.
Others
Revenue is generated by the commercialization of PLLA products across secondary and emerging anatomical zones, including gluteal augmentation (buttock lifts), hand rejuvenation, and decolletage structural smoothing. Income is captured through specialty kits, off-label clinical supply contracts, and expanding therapeutic expansion applications.
Segment - End Use
Revenue capture definition
Medspas
Revenue is captured through direct manufacturing sales, commercial distribution contracts, and recurring wholesale vial purchasing agreements with medical spa franchises, localized boutique wellness clinics, and corporate aesthetic chains. This segment drives substantial, steady capital inflows characterized by fast re-order cycles, group-account volume discounts, and aggressive promotional product bundling tied to consumer-facing retail cosmetic marketing.
Cosmetic Surgery Centers/Dermatology Clinics
Revenue is generated from product procurement by specialized physician-led practices, board-certified plastic surgery centers, and core dermatological medical networks. Value is captured through premium, single-account direct sourcing, advanced clinical training certification kits (e.g., specialized reconstitution protocols), and institutional loyalty programs tailored to high-tier aesthetic professionals managing complex facial and body-contouring patient cases.
Estimation Model
Phase
Key Question
Process Steps
Data Sources
Scope Definition
What is being studied?
1. Define PLLA filler products and forms.
2. Establish geographic coverage and countries under analysis.
3. Determine forecast period and base year.
4. Align on base year and forecast horizon (2026–2033).
GAPs, ASPs, regulatory body product registries
Build the Product Base
How large is the addressable patient population?
1. Collect annual aesthetic procedure demographics.
2. Identify the proportion of patients opting for injectables.
3. Segment consumers by age and treatment target.
4. Forecast consumer base growth.
Commercially available aesthetic medical association databases, demographic/lifestyle surveys
Estimate Penetration
What proportion chooses PLLA over other injectables and receives treatment?
1. Estimate PLLA market share among dermal injectables.
2. Segment by treatment application indication.
3. Assess treatment access and provider certification rates.
4. Validate penetration and treatment rates.
Conference presentations, physician interviews, medical literature reviews, key opinion leader (KOL) interviews
Revenue Conversion
How does patient volume translate into market revenue?
1. Estimate PLLA market share among dermal injectables.
2. Segment by treatment application indication.
3. Assess treatment access and provider certification rates.
4. Validate penetration and treatment rates.
Company annual reports, product pricing databases, distributor data
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request Customization Delivered
Value Adds
Growing Awareness and Acceptance of Cosmetic Enhancements Conducted a comprehensive assessment of the clinical, technological, and commercial developments shaping the PLLA fillers market, with a particular focus on the increasing adoption of collagen biostimulation-based aesthetic procedures for facial rejuvenation and body contouring applications. The study evaluated evolving treatment protocols involving PLLA fillers for mid-face volume restoration, jawline enhancement, temple correction, skin quality improvement, and non-surgical body rejuvenation. Additionally, the analysis examined emerging trends including AI-enabled facial assessment platforms, advanced injection planning technologies, ultrasound-guided aesthetic procedures, personalized treatment approaches, and next-generation PLLA formulations designed to improve product longevity, optimize collagen stimulation, and enhance patient satisfaction. The research further assessed changing consumer preferences toward minimally invasive aesthetic treatments and the growing role of preventive and regenerative aesthetics in expanding the addressable patient population.
This analysis enables stakeholders to understand the impact of increasing aesthetic awareness, social media influence, and technological innovation on the adoption of PLLA fillers globally. It helps identify high-growth treatment indications, emerging consumer segments, and innovation opportunities in regenerative aesthetics. The study supports strategic decision-making related to product development, market expansion, physician education initiatives, and competitive positioning while highlighting future opportunities in personalized aesthetic medicine, advanced collagen biostimulation technologies, and long-duration facial rejuvenation solutions.
Geographic Analysis Conducted a detailed assessment of regional and country-level factors influencing the PLLA fillers market across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The study evaluated the impact of healthcare expenditure, disposable income growth, aesthetic procedure volumes, demographic trends, regulatory frameworks, and physician availability on market development. It analyzed regional differences in consumer preferences, adoption rates of collagen-stimulating injectables, medical tourism flows, reimbursement environments, and regulatory approval pathways. Additionally, the analysis examined the influence of urbanization, increasing beauty consciousness, expanding medical spa networks, and rising demand for minimally invasive cosmetic procedures on market penetration across both mature and emerging economies. The study also assessed country-specific growth opportunities, competitive intensity, and evolving distribution strategies supporting regional market expansion.
This analysis enables stakeholders to evaluate regional growth potential, prioritize market entry and expansion strategies, and optimize resource allocation across key geographies. It supports long-term business planning by identifying high-opportunity markets, assessing regulatory and commercial risks, and understanding country-specific adoption dynamics. The study further assists organizations in developing effective pricing and commercialization strategies while highlighting emerging growth hubs, medical tourism destinations, and underserved aesthetic markets with significant future demand potential.
Competitive Landscape Analysis Conducted a comprehensive assessment of leading multinational aesthetic companies, dermatology-focused manufacturers, and emerging biopharmaceutical organizations operating within the PLLA fillers market. The analysis evaluated company market positioning, product portfolios, regulatory approvals, innovation pipelines, geographic presence, and strategic initiatives including partnerships, acquisitions, and product launches. Furthermore, the study examined competitive differentiation based on clinical performance, treatment longevity, safety profiles, physician training programs, brand recognition, distribution capabilities, and pricing strategies. The research also assessed ongoing investments in next-generation collagen biostimulators, combination treatment approaches, advanced formulation technologies, and digital aesthetic platforms that are shaping future market competition. In addition, benchmarking of key participants was conducted to identify market leaders, emerging challengers, and innovation-focused companies driving industry transformation.
This analysis enables stakeholders to understand competitive intensity, benchmark leading manufacturers, and identify strategic growth opportunities within the PLLA fillers market. It supports portfolio optimization, partnership evaluation, acquisition targeting, and competitive positioning initiatives by providing actionable insights into market share dynamics and product differentiation strategies. The study further helps organizations anticipate future industry developments, monitor innovation trends, evaluate pipeline competitiveness, and identify potential areas for expansion across emerging treatment indications and geographic markets.
Frequently Asked Questions About This Report
The primary factors driving the market are the rising demand for minimally invasive cosmetic procedures, the growing aging population, and technological advancements.
The global poly-l-lactic acid filler market size was valued at USD 214.6 million in 2025 and is expected to reach USD 234.4 million in 2026.
North America dominated the poly-lactic acid (PLLA) filler market with a share of 39.3% in 2025, owing to advanced healthcare infrastructure, increasing adoption of aesthetic procedures, huge research and development activities, and continuous technological advancements in cosmetic treatments.
Asia Pacific is the fastest-growing region over the forecast period.
Cosmetic surgery clinics/dermatology clinics held the largest revenue share in 2025, while medspas are the fastest-growing area.
The global poly-l-lactic acid filler market is expected to grow at a compound annual growth rate of 9.1% from 2026 to 2033, reaching USD 432.0 million by 2033.
By application, the face application segment led the poly-l-lactic acid filler market with a 44.5% revenue share in 2025 and is the fastest-growing segment.
Some key players operating in the poly-l-lactic acid filler market include Galderma, Sinclair Pharma, GANA RND, PRP Life Science Co., Ltd, Laboratories Hyamed SA, Dermax Co., Ltd, Rimless Industry Co., Ltd., Hangzhou Singclean Medical Products Co., Ltd., and LINKUS GLOBAL Co., Ltd.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


