
- Home
- »
- Medical Devices
- »
-
Portable Medical Devices Market Size & Share Report, 2033GVR Report cover

Portable Medical Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Diagnostic, Monitoring, Therapeutics, Smart Wearable Devices), By Application (Gynecology, Cardiology, Gastrointestinal), By Region (North America, Asia Pacific), And Segment Forecast
Market Size, 2025
$85.7BMarket Estimate, 2026
$95.4BMarket Forecast, 2033
$201.9BCAGR, 2026–2033
11.3%Portable Medical Devices Market Summary
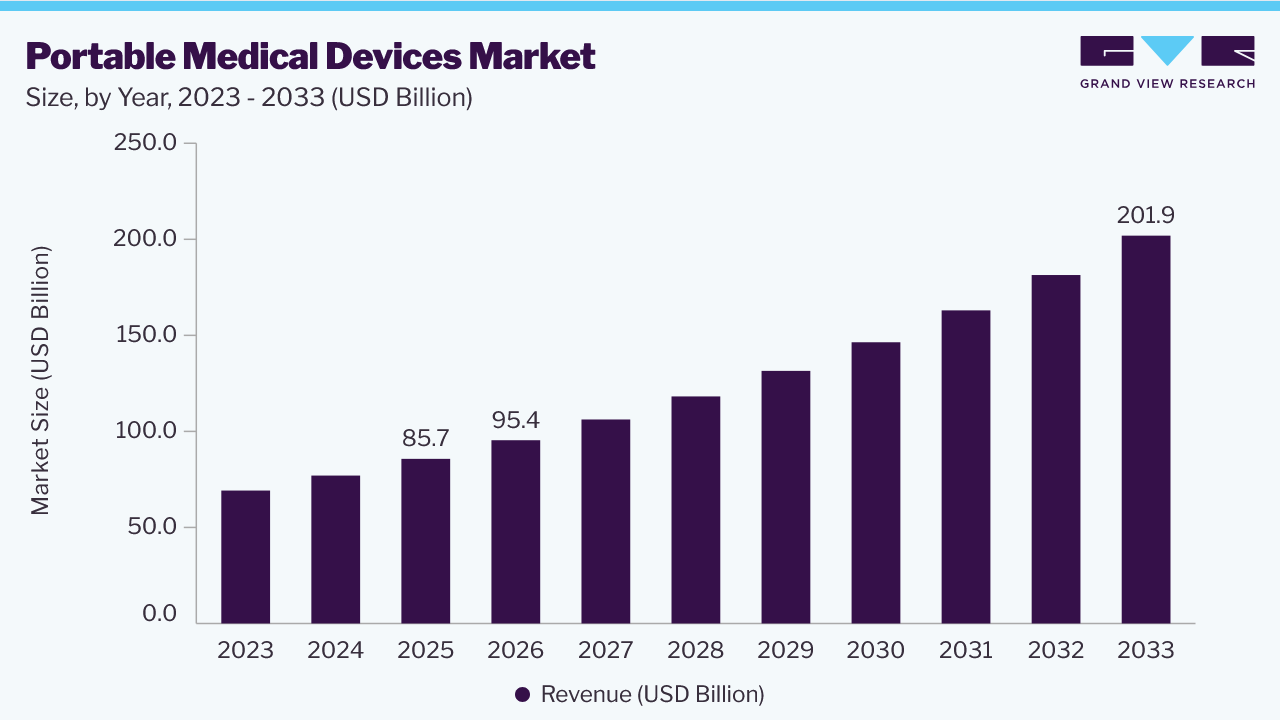
The global portable medical devices market size was valued at USD 85.7 billion in 2025 and is projected to grow from USD 95.4 billion in 2026 to USD 201.9 billion by 2033, growing at a CAGR of 11.3% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 40.0% in 2025. An increase in chronic diseases due to changing lifestyles, a preference for home healthcare, and an aging population is anticipated to positively impact market growth in the coming years.
Key Market Trends & Insights
- By product type: The monitoring devices segment dominated the market, with a revenue share of more than 48.5% in 2025.
- By application: The others segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 85.7 Billion
- Estimated market size in 2026: USD 95.4 Billion
- Projected market size by 2033: USD 201.9 Billion
- CAGR (2026-2033): 11.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, the growing demand for wearable electronics and wireless medical devices is among the key factors for the market growth. Rising awareness among the population regarding the benefits of portable devices and the proliferation of smart technologies is also contributing to the adoption of portable medical devices in hospitals and healthcare settings. In addition, the increasing aging populations, the growing prevalence of chronic diseases, and the rising demand for home-based monitoring equipment continue to support market expansion.The rising emphasis on health and fitness among adults worldwide and the focus of healthcare agencies on preventive monitoring have significantly boosted demand for fitness trackers and wearable devices. Wearables help evaluate physiological parameters, activity levels, and overall wellness. According to the International Data Corporation (IDC), global shipments of wearable devices exceeded 537.9 million units in 2024, driven by strong demand for smartwatches, fitness bands, and health-monitoring wearables. Growing adoption among professional athletes and health-conscious consumers is expected to drive market expansion.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Furthermore, the growing adoption of remote patient monitoring (RPM) solutions and decentralized healthcare delivery models is a key driver of the portable medical devices market. Healthcare providers are increasingly utilizing portable diagnostic, monitoring, and therapeutic devices to improve patient outcomes, reduce hospital visits, and enhance access to care in both urban and rural settings. Portable medical devices enable continuous monitoring of vital signs and disease conditions outside traditional healthcare facilities, supporting timely interventions and reducing healthcare costs. Furthermore, advancements in wireless connectivity, cloud-based health platforms, and digital health ecosystems are improving the efficiency and reliability of portable devices, encouraging their wider adoption across various healthcare applications.
Analyst Perspective
The portable medical devices market is witnessing steady growth, driven by the rising prevalence of chronic diseases, aging populations, and increasing demand for home healthcare. Growing adoption of remote patient monitoring is accelerating the use of portable diagnostic, therapeutic, and monitoring devices. Advances in wireless connectivity, miniaturized sensors, AI, and wearable technologies are improving device accuracy and usability. The shift toward decentralized and preventive healthcare is expected to further support long-term market growth.
Product Type Insights
By product type, the monitoring devices segment dominated the market with a share of more than 48.5% in 2025. This is attributable to the growing adoption in healthcare centers. Technological advancements, advantages such as mobility and compact design, and new product approvals are some other factors driving the market. For instance, in October 2024, Garmin launched the Lily 2 Active smartwatch featuring enhanced health monitoring capabilities, including heart rate tracking, sleep monitoring, stress management, and fitness analytics, reflecting the growing integration of advanced physiological monitoring features into wearable devices.
The diagnostics segment held the second-largest market share in terms of revenue in 2025, owing to the increasing adoption of X-ray, CT scans, handheld ultrasound systems, and endoscopes among other systems in healthcare settings. The development of smaller, technologically advanced imaging platforms and subsequent product approvals are other factors boosting the market. For instance, in April 2024, GE HealthCare introduced the Vscan Air SL, a wireless handheld ultrasound imaging system designed to provide high-quality imaging across a broad range of clinical applications, enabling greater accessibility to point-of-care diagnostics in diverse healthcare settings.
The smart wearable devices segment is expected to witness the fastest CAGR during the forecast period. This can be attributed to the rising demand for fitness and wristbands for long-term continuous health monitoring. Focus on preventive healthcare and the growing adoption of technologically advanced products are also expected to contribute to the growth of the portable medical devices market.For instance, in September 2024, Apple launched the Apple Watch Series 10 with enhanced health-monitoring capabilities, faster charging, including new sleep apnea notifications, water depth and temperature sensing, along with new health and fitness insights and intelligence.
Application Insights
The others application segment, which consists of oncology, musculoskeletal, thoracic, vascular, and metabolic applications, accounted for the largest market share in terms of revenue in 2025. The growing prevalence of cancer, coupled with rising usage of diagnostic imaging and image-guided therapy systems, is one of the key factors attributed to this growth. Moreover, the increasing prevalence of diabetes and the adoption of advanced, portable glucose monitoring technologies are further driving market expansion. According to the 11th Edition of the International Diabetes Federation (IDF) Diabetes Atlas published in 2025, approximately 589 million adults aged 20-79 years were living with diabetes globally in 2024, representing 11.1% of the global adult population. These trends are expected to sustain demand for portable diagnostic and monitoring devices across a broad range of clinical applications, thereby supporting the continued growth of the segment over the forecast period.
Cardiology held the second most prominent position in the market. This can be attributed to technological advancements and new product development in cardiology. In addition, technologies available in clinical settings, such as ECG monitors, heart rhythm trackers, and blood pressure monitors, are increasingly becoming accessible through portable and consumer-facing devices, thereby boosting product demand. For instance, in January 2025, AliveCor announced that the Centers for Medicare & Medicaid Services (CMS) approved reimbursement for its AI-powered Kardia 12L ECG System under the 2025 Hospital Outpatient Prospective Payment System. This highlights the growing clinical acceptance and accessibility of portable cardiac monitoring technologies.
Gynecology is expected to register the maximum growth during the forecast period. The segment growth can be attributed to the growing prevalence of gynecological disorders, including Polycystic Ovary Syndrome (PCOS), endometriosis, uterine fibroids, and adenomyosis, along with growing awareness regarding women's health. As per the World Health Organization (WHO), endometriosis affects approximately 10% of women and girls of reproductive age globally, representing nearly 190 million individuals worldwide. The growing disease burden is expected to increase demand for portable diagnostic and monitoring technologies in gynecological care.
Regional Insights
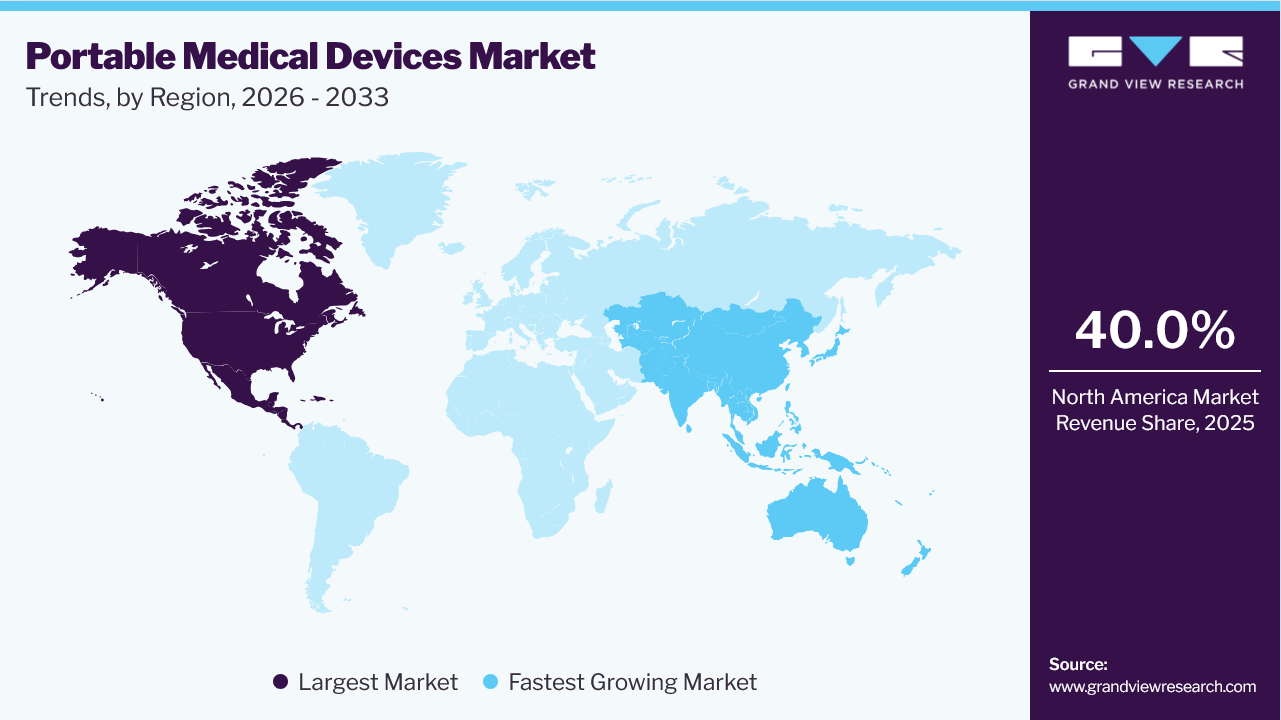
North America dominated the market with a share of around 40.0% in 2025. Major factors contributing to the growth of this region include high penetration of diagnostic, therapeutic, and monitoring portable medical devices for disease management. The rising burden of chronic diseases, increasing adoption of remote patient monitoring solutions, favorable reimbursement policies, and a growing geriatric population are also driving market growth. According to the American Hospital Association, approximately 76% of hospitals in the U.S. have implemented telehealth and remote patient monitoring capabilities, reflecting the increasing integration of connected and portable medical technologies into healthcare delivery. This trend is expected to continue supporting demand for portable medical devices across the region.
 To learn more about this report, Download Free Sample Report
Europe Portable Medical Devices Market Trends
Europe held the second-largest revenue share of the global market. The UK, France, Germany, Italy, and Spain are the main markets in this region. The increasing geriatric population in developed countries, such as the UK, Germany, Italy, & France, and the presence of high unmet needs in Eastern Europe are among the factors anticipated to drive growth over the forecast period.Furthermore, favorable healthcare infrastructure, increasing healthcare expenditure, and the expanding use of remote patient monitoring solutions are supporting the adoption of portable medical devices across the region. According to Eurostat, individuals aged 65 years and above accounted for approximately 22.0% of the European Union's total population in 2024. As the elderly population is more susceptible to chronic conditions such as diabetes, cardiovascular diseases, and respiratory disorders that require continuous monitoring and disease management, the demand for portable medical devices, including wearable monitors, blood glucose meters, portable ECG devices, and remote patient monitoring systems, is expected to increase significantly across Europe.
Asia Pacific Portable Medical Devices Market Trends
Asia Pacific is expected to attain a significant CAGR in the forecast period. Rise in the geriatric population, the growing prevalence of diabetes, escalating incidences of heart diseases, along with the adoption of smart wearables, are attributed to the regional market growth. Moreover, rising disposable incomes and increasing consumer awareness regarding preventive healthcare are accelerating the adoption of smart wearable devices and remote patient monitoring solutions. According to the United Nations Population Fund (UNFPA) the number of older persons aged 60 years and above in the Asia-Pacific region is projected to nearly double from around 630 million in 2020 to approximately 1.3 billion by 2050. These factors are expected to drive sustained demand for portable monitoring, diagnostic, and therapeutic devices.
Key Portable Medical Devices Market Company Insights
The portable medical devices market is highly fragmented, with numerous manufacturers offering handheld diagnostic devices, portable monitoring systems, wearable medical technologies, and mobile healthcare solutions. Market participants are actively pursuing strategic initiatives such as product launches, technological advancements, partnerships, and acquisitions to strengthen their competitive positions and expand their product portfolios.
Key Portable Medical Devices Companies
The following key companies have been profiled for this study on the portable medical devices market:
-
GE HealthCare.
-
OMRON Corporation
-
Samsung Electronics Co., Ltd.
-
Koninklijke Philips N.V.
-
Medtronic
-
F. Hoffmann-La Roche Ltd
-
Nox Medical
-
Masimo.
-
ResMed.
-
Baxter.
Recent Developments
-
In June 2026, Philips collaborated with Bajaj Integrated Health System (BIHS) to establish a digitally connected healthcare network across India, supporting remote patient monitoring, connected care delivery, and broader deployment of portable healthcare technologies.
-
In July 2024, F. Hoffmann-La Roche Ltd completed the acquisition of LumiraDx’s Point of Care technology platform, strengthening its portfolio of decentralized and portable diagnostic solutions and expanding access to near-patient testing across primary and community care settings.
Portable Medical Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 85.7 billion
Estimated Market size in 2026
USD 95.4 billion
Projected Market size by 2033
USD 201.9 billion
Growth rate
CAGR of 11.3% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Product type, application, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; Spain; France; Italy; Sweden; Norway; Denmark; Japan; China; India; Australia; Thailand; South Korea; New Zealand; Brazil; Mexico; Argentina; South Africa; UAE; Saudi Arabia; Kuwait
Key companies profiled
GE HealthCare; OMRON Corporation; Samsung Electronics Co., Ltd.; Koninklijke Philips N.V.; Medtronic; F. Hoffmann-La Roche Ltd; Nox Medical; Masimo.; ResMed.; Baxter.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Portable Medical Devices Market Segmentation
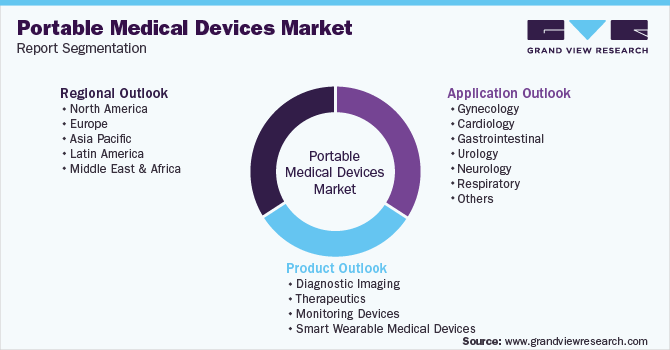
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global portable medical devices market based on product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Diagnostic Imaging
-
CT
-
X-ray
-
Ultrasound
-
Endoscope
-
-
Therapeutics
-
Insulin Pump
-
Nebulizer
-
Oxygen Concentrator
-
Image-guided Therapy Systems
-
-
Monitoring Devices
-
Cardiac Monitoring
-
Holter Monitors
-
Resting ECG System
-
Stress ECG Monitors
-
Event Monitoring Systems
-
ECG Management Systems
-
-
Neuromonitoring
-
EEG Machines
-
EMG Machines
-
ICP Monitors
-
MEG Machines
-
Cerebral Oximeters
-
-
Respiratory Monitoring
-
Capnographs
-
Spirometers
-
Peak Flow Meters
-
-
Fetal Monitoring
-
Neonatal Monitoring
-
Hemodynamic Monitoring Systems
-
Vital Sign Monitors
-
-
Smart Wearable Medical Devices
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Gynecology
-
Cardiology
-
Gastrointestinal
-
Urology
-
Neurology
-
Respiratory
-
Orthopedics
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
New Zealand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
Some key players operating in the portable medical devices market include Koninklijke Philips N.V, General Electric Company, Medtronic, OMRON Corporation, Samsung, and F. Hoffmann-La Roche Ltd.
The monitoring devices segment accounted for the largest revenue share of more than 48.5% in 2025.
The global portable medical devices market is expected to grow at a CAGR of 11.3% from 2026 to 2033, reaching USD 201.9 billion.
The global portable medical devices market size was valued at USD 85.7 billion in 2025 and is estimated at USD 95.4 billion for 2026.
North America dominated with around 40.0% revenue share in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


