
- Home
- »
- Medical Devices
- »
-
Preclinical Medical Device Testing Services Market Report, 2033GVR Report cover

Preclinical Medical Device Testing Services Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (Biocompatibility Testing Services, Chemistry Testing Service) By Testing Model, By Device Class, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$3.4BMarket Estimate, 2026
$3.7BMarket Forecast, 2033
$6.7BCAGR, 2026–2033
8.9%Preclinical Medical Device Testing Services Market Summary
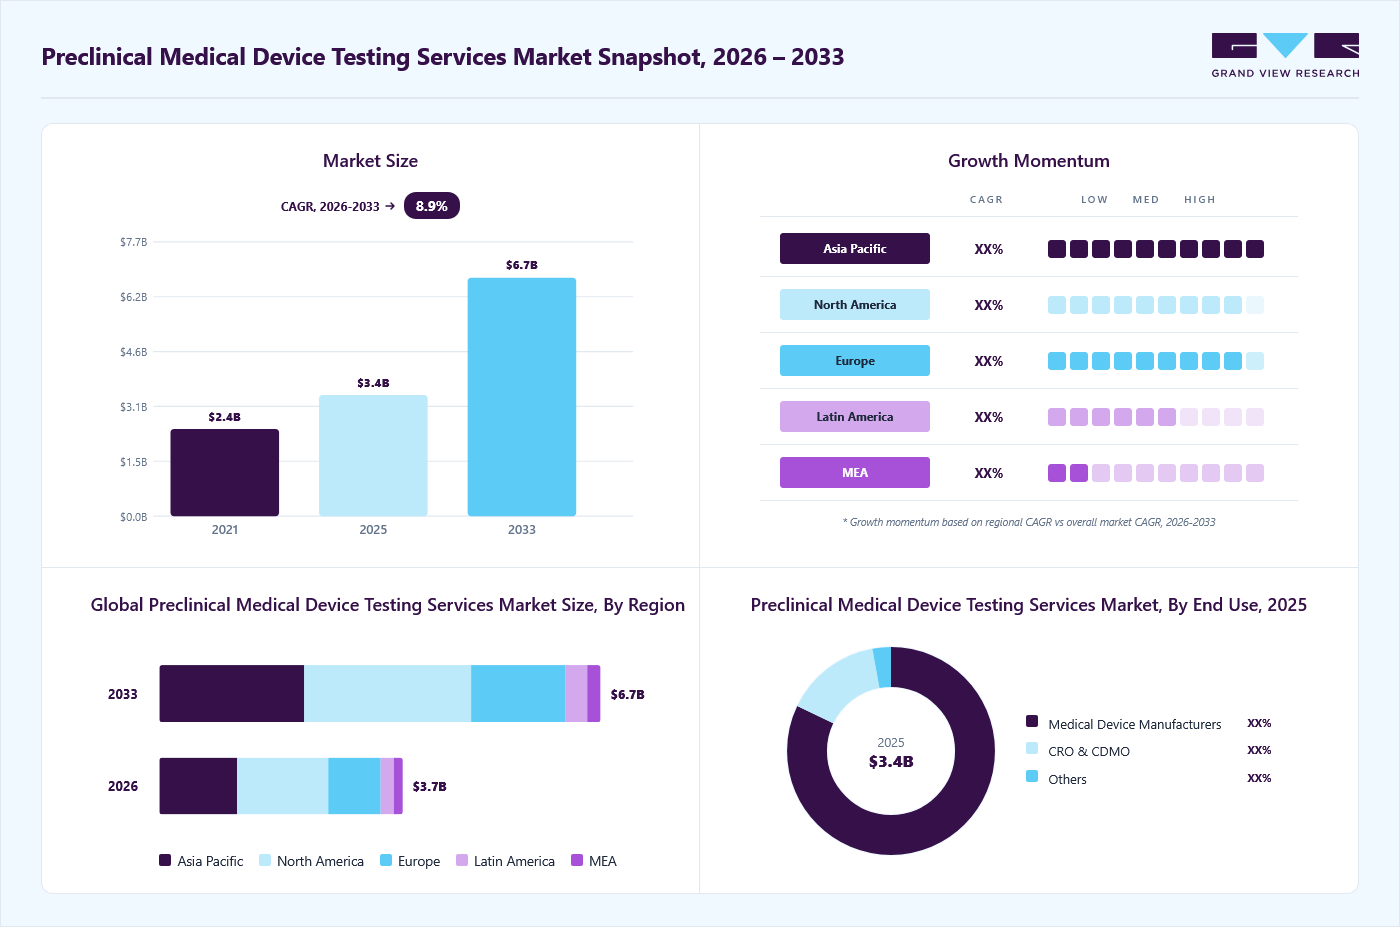
The global preclinical medical device testing services market size was valued at USD 3.4 billion in 2025 and is projected to grow from USD 3.7 billion in 2026 to USD 6.7 billion by 2033, at a CAGR of 8.9% from 2026 to 2033. North America dominated the market, accounting for the largest share of 37.4% in 2025. The market growth is driven by an increasing number of new drug launches, a rise in pharmaceutical R&D activities, growing demand to reduce costs associated with in-house sales, rising complexity in drug commercialization, increasing regulatory oversight, and the ongoing need for cost optimization.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Biocompatibility testing services held the largest revenue share of 57.5% in 2025
- By testing model: In vivo testing held the largest revenue share of 54.6% in 2025
- By device class: Class II held the largest revenue share of 44.3% in 2025
- By industry application: Cardiovascular devices held the largest revenue share of 23.9% in 2025
- By end use: Medical device manufacturers held the largest revenue share of 82.1% in 2025
Regional Highlights
- Largest regional market: North America (37.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share in 2025
Market Size & Forecast
- Market Size in 2025: USD 3.4 Billion
- Estimated Market Size in 2026: USD 3.7 Billion
- Projected Market Size by 2033: USD 6.7 Billion
- CAGR: 8.9% (2026-2033)
Prism AI by Grand View Research Free to tryAsk a question about the preclinical medical device testing services market✓Every figure cited from GVR research Prefer the report? Download free sample →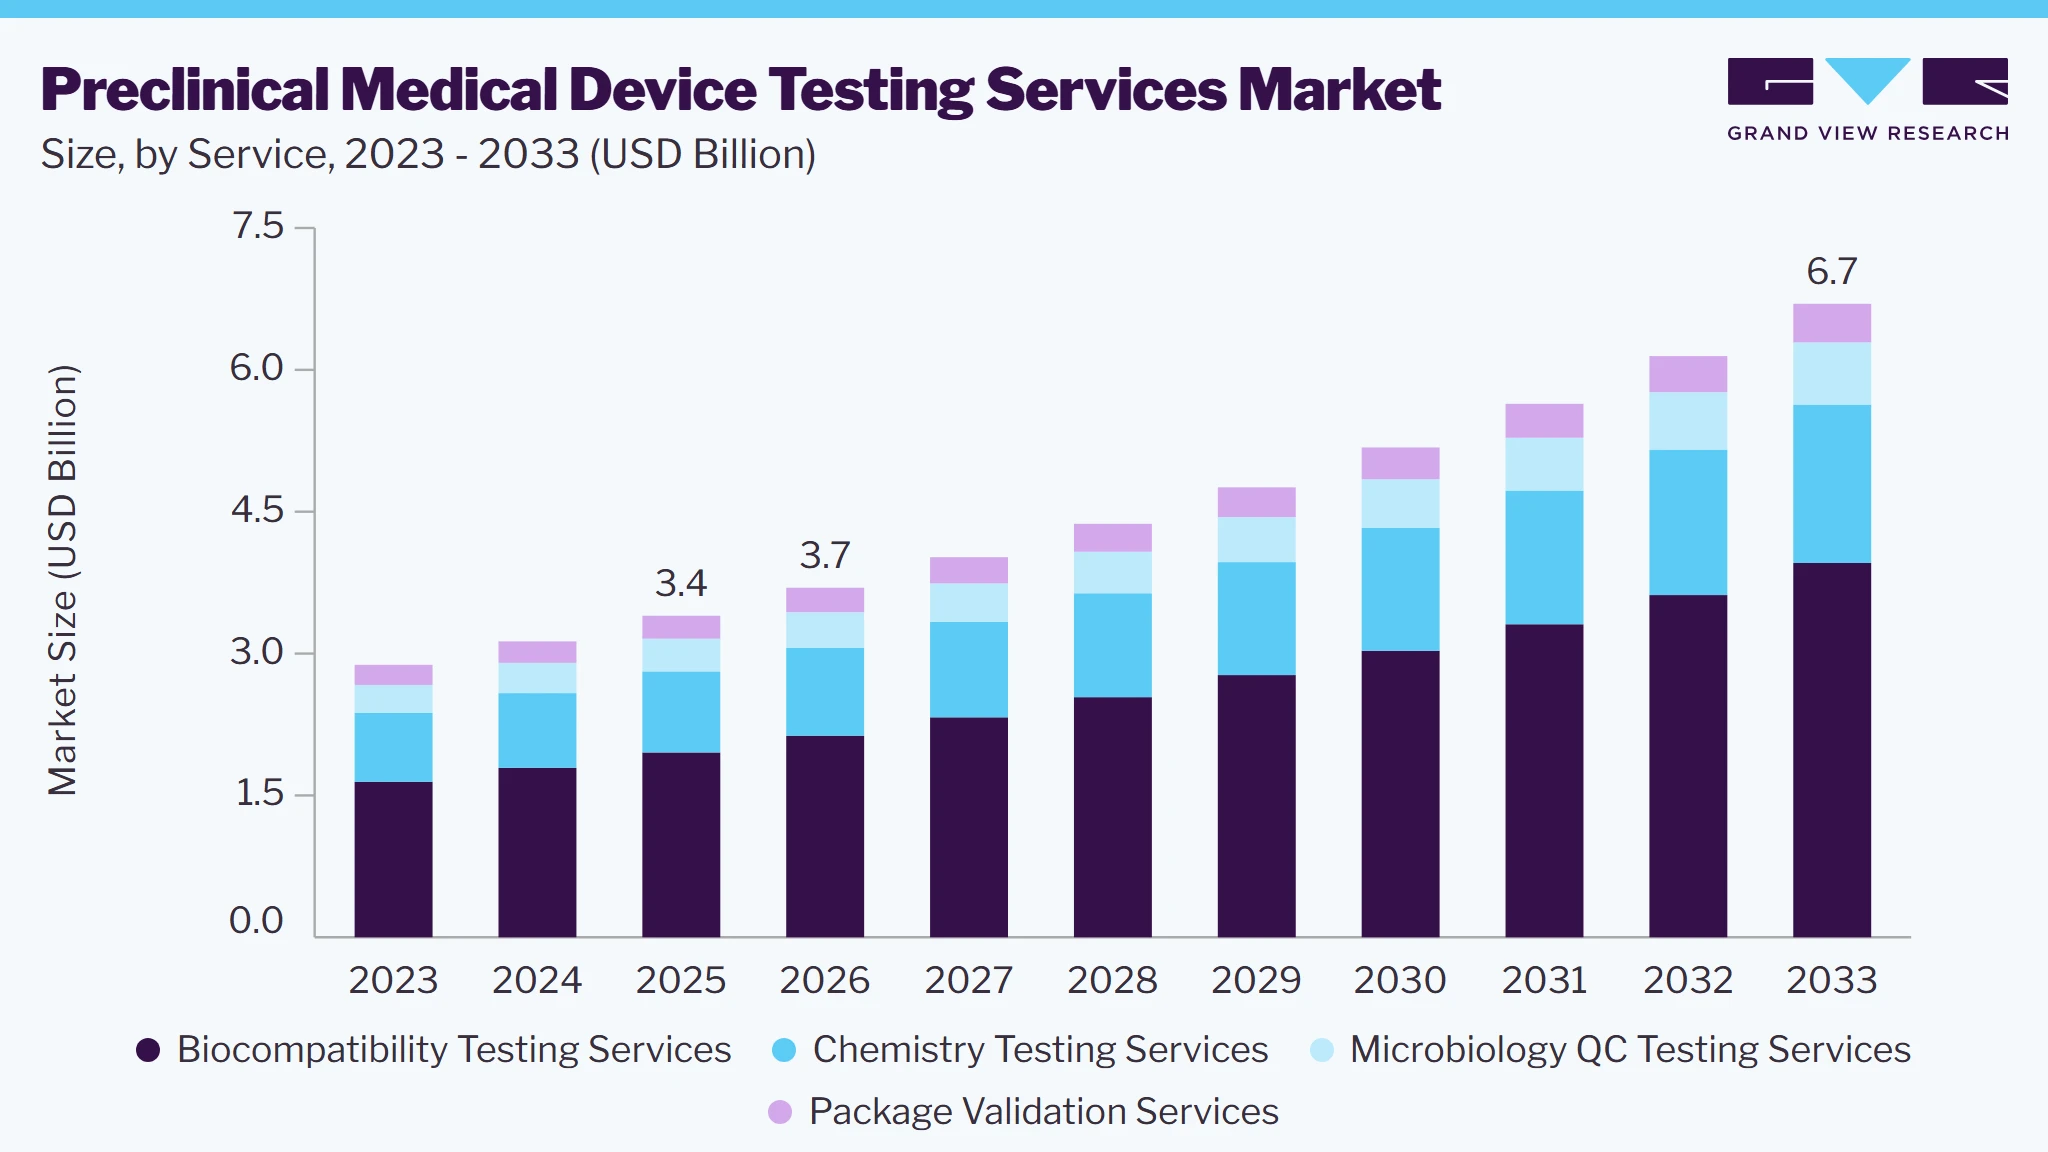 To learn more about this report, Download Free Sample Report
Market Dynamics
The preclinical medical device testing services market is experiencing strong growth, driven by the increasing development of innovative medical devices to address the rising prevalence of chronic diseases and complex clinical conditions. As devices become more sophisticated with the integration of technologies such as artificial intelligence (AI), the Internet of Things (IoT), robotics, and connected health solutions, comprehensive preclinical testing has become essential to ensure safety, functionality, and regulatory compliance. In addition, many medical device manufacturers lack the specialized infrastructure, technical expertise, and laboratory capabilities required to perform extensive in-house testing, leading to greater reliance on outsourced testing service providers. In addition, a substantial share of research and development expenditure is allocated to preclinical evaluation to minimize regulatory risks and accelerate product approvals. Furthermore, growing regulatory scrutiny, increasing demand for biocompatibility, mechanical, and electrical safety testing, and continuous innovation in next-generation medical devices are further driving the adoption of specialized preclinical medical device testing services worldwide.
The increasing development of breakthrough therapies for oncology, rare diseases, and other complex conditions is driving demand for advanced medical devices, thereby supporting the growth of the preclinical medical device testing services market. In addition, novel therapeutic approaches, including targeted therapies, immunotherapies, and regenerative medicine, require highly specialized delivery systems, implantable devices, diagnostic platforms, and combination products that must undergo rigorous preclinical evaluation before clinical use.
As manufacturers introduce sophisticated devices integrated with digital technologies, ensuring their safety, biocompatibility, mechanical performance, and functional reliability has become critical. This has increased the need for specialized preclinical testing services capable of evaluating device performance in accordance with stringent regulatory standards. Furthermore, pharmaceutical and medical device companies are investing heavily in innovation to accelerate product development and improve patient outcomes, creating sustained demand for outsourced testing expertise. Thus, the growing pipeline of advanced therapies and supporting medical technologies continues to expand opportunities for preclinical medical device testing service providers worldwide.
Stringent regulatory requirements governing pharmaceutical promotion and interactions with healthcare professionals significantly restrain the preclinical medical device testing services market growth. The CSOs must comply with evolving regulations related to promotional practices, transparency reporting, data privacy, anti-bribery laws, and scientific communication across multiple jurisdictions. In addition, frequent regulatory updates require continuous training, compliance monitoring, and investment in digital governance systems, increasing operational costs. Any non-compliance can result in financial penalties, reputational damage, and contract losses for both CSOs and their pharmaceutical clients. Moreover, varying country-specific promotional regulations limit standardized commercial strategies, making multinational sales operations more complex and resource-intensive, thereby slowing market expansion and reducing operational efficiency.
The rapid adoption of artificial intelligence (AI)-enabled, Internet of Things (IoT)-connected, and software-integrated medical devices presents a significant opportunity for the preclinical medical device testing services market. These next-generation devices require comprehensive preclinical assessments to evaluate safety, cybersecurity, software validation, interoperability, electrical performance, and functional reliability before clinical trials and commercialization. As healthcare providers increasingly adopt smart implants, wearable monitoring devices, robotic surgical systems, and digital diagnostics, manufacturers are seeking specialized testing partners with advanced technical capabilities and regulatory expertise.
In addition, evolving global regulatory frameworks for software as a medical device (SaMD) and AI-based medical technologies are increasing the complexity of product validation, that are driving demand for outsourced testing services. The testing providers that invest in digital validation platforms, simulation technologies, cybersecurity assessment, and AI-specific performance testing will be well-positioned to support innovation, accelerate regulatory approvals, and capitalize on the expanding pipeline of intelligent medical devices worldwide.
Impact of U.S. Tariffs on Preclinical Medical Device Testing Services Market
The U.S. tariffs on imported medical devices, electronic components, and raw materials are influencing the preclinical medical device testing services market by increasing development and manufacturing costs for device manufacturers. Rising costs encourage companies to optimize research and development expenditures while ensuring regulatory compliance, leading to greater reliance on specialized outsourced preclinical testing providers. These tariffs are also prompting manufacturers to diversify supply chains, localize production, and redesign products using alternative materials, creating additional demand for biocompatibility, performance, mechanical, and safety testing before commercialization.
However, higher production costs and supply chain disruptions may delay early-stage device development and reduce R&D budgets, particularly among small- and mid-sized manufacturers, thereby slowing testing volumes in the short term. Despite these challenges, the shift toward domestic manufacturing and increased regulatory scrutiny for redesigned devices is expected to generate sustained demand for preclinical testing services, supporting long-term market growth through expanded validation, verification, and compliance activities.
Technological Advancements
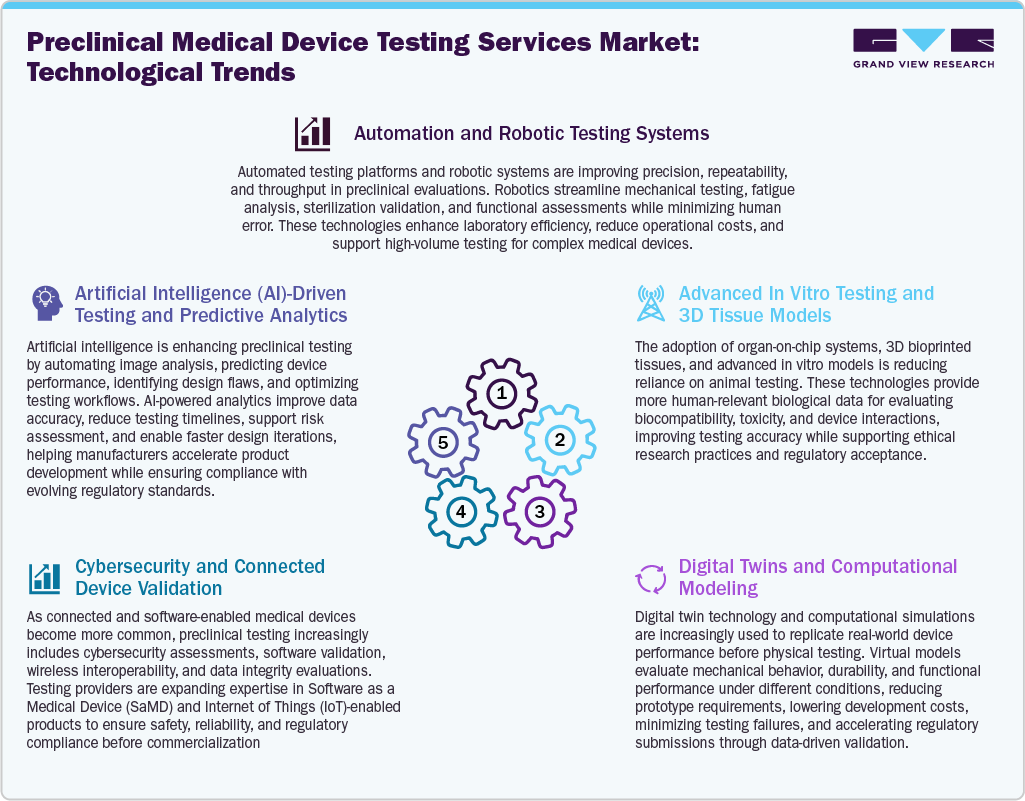
The market is advancing due to technological advancements that are transforming the preclinical medical device testing services market by improving testing accuracy, efficiency, and regulatory compliance. Artificial intelligence (AI) and machine learning are increasingly used for predictive analytics, automated image analysis, and risk assessment, enabling faster identification of design flaws and optimization of testing protocols. In addition, digital twin technology and computational modeling allow manufacturers to simulate device performance under various conditions, reducing prototype development costs and accelerating validation. In addition, advanced in vitro models, including organ-on-chip platforms and 3D bioprinted tissues, are improving the evaluation of biocompatibility and toxicity while reducing dependence on animal testing.
 To learn more about this report, Download Free Sample Report
Furthermore, automation and robotic testing systems enhance precision, repeatability, and throughput across mechanical, electrical, and functional testing processes, minimizing human error and improving laboratory productivity. Moreover, the rapid adoption of AI-enabled, connected, and software-based medical devices has increased demand for cybersecurity validation, software verification, and interoperability testing, enabling service providers to support the development of next-generation medical technologies while meeting evolving global regulatory requirements.
Pricing Model Analysis
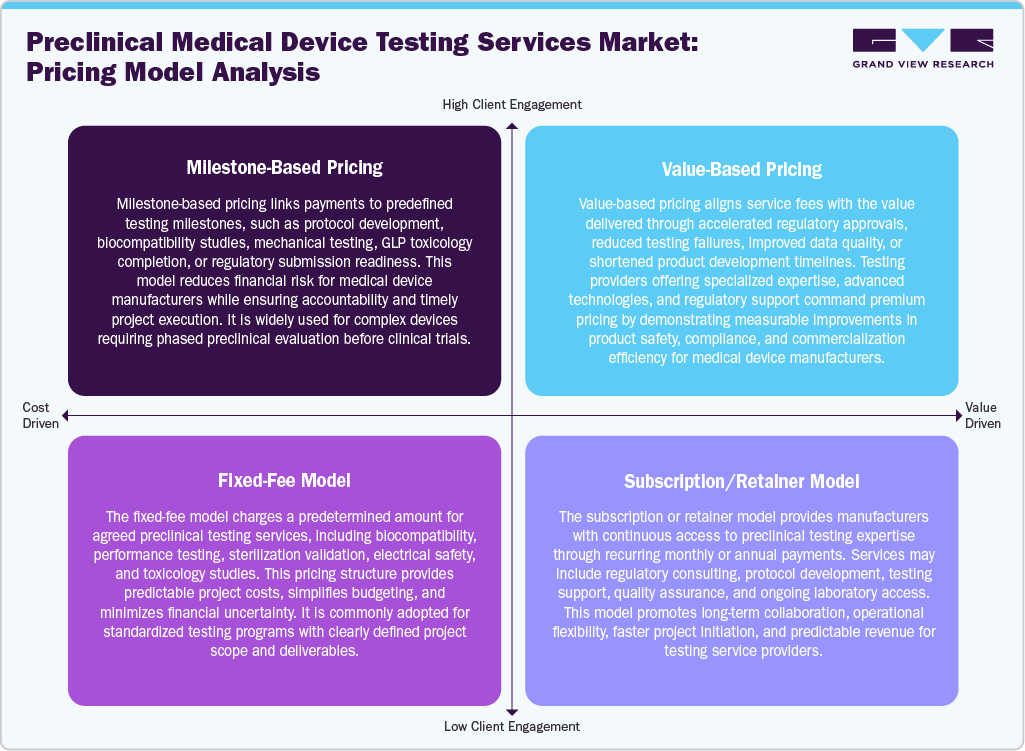
The market adopts multiple pricing models to accommodate varying project complexities, regulatory requirements, and client budgets. Milestone-based pricing ties payments to predefined project stages, such as protocol development, biocompatibility testing, mechanical evaluation, or regulatory submission readiness, ensuring accountability and reducing financial risk. Value-based pricing aligns service fees with measurable outcomes, including accelerated regulatory approvals, improved testing efficiency, and reduced development timelines. The fixed-fee model offers a predetermined price for clearly defined testing services, enabling predictable budgeting and effective cost control for manufacturers.
 To learn more about this report, Download Free Sample Report
Meanwhile, the subscription or retainer model provides continuous access to testing expertise, regulatory consulting, laboratory support, and quality assurance through recurring payments. These flexible pricing approaches allow medical device manufacturers to optimize research and development expenditures, efficiently manage testing programs, accelerate product validation, and select commercial arrangements that best align with device complexity, development stage, regulatory strategy, and long-term commercialization objectives.
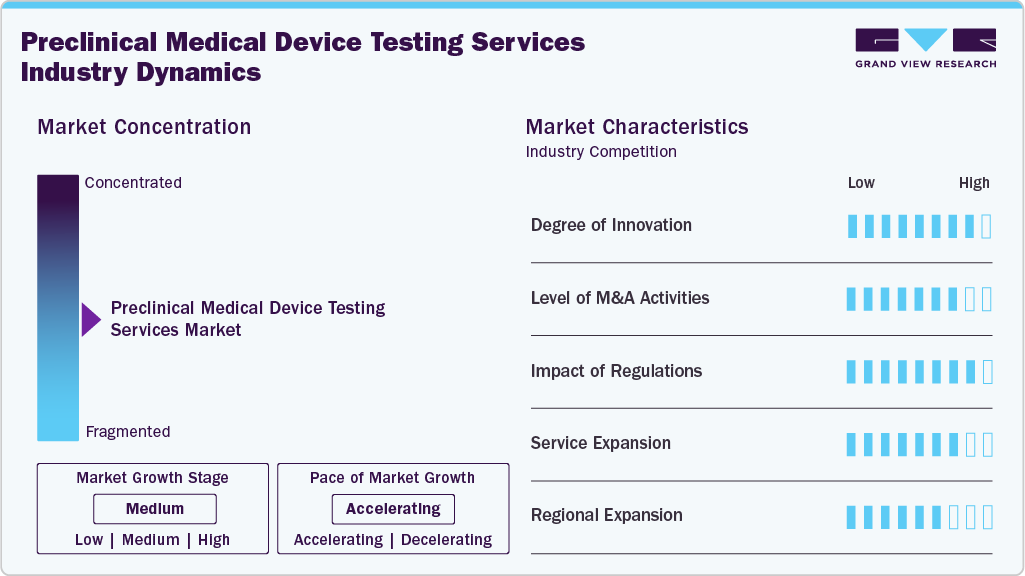
Market Concentration & Characteristics
The preclinical medical device testing services industry is characterized by stringent regulatory compliance, high technical expertise, growing outsourcing of testing activities, adoption of advanced testing technologies, and increasing demand for specialized laboratories. The industry is driven by innovation in medical devices, expanding R&D investments, quality-focused validation processes, and long-term partnerships between manufacturers and testing providers.
The growth of the preclinical medical device testing services market is accelerating through the adoption of innovative technologies such as artificial intelligence (AI), digital twins, computational modeling, organ-on-chip platforms, and automated testing systems. In addition, service providers are expanding their capabilities in advanced biocompatibility, cybersecurity, software validation, and performance testing to support increasingly sophisticated medical devices.
 To learn more about this report, Download Free Sample Report
The market is witnessing rising M&A activity as testing organizations seek to expand their laboratory networks, technical expertise, and specialized testing capabilities. Companies are acquiring niche testing laboratories and regulatory consulting firms to strengthen end-to-end service portfolios, enhance geographic presence, and support complex medical devices, including AI-enabled, implantable, and combination products across global regulatory markets.
Stringent regulations from the FDA, MDR, IVDR, ISO 10993, and other international standards significantly shape the market. The testing providers continuously invest in laboratory accreditation, quality systems, skilled personnel, and regulatory expertise to meet evolving compliance requirements. Increasing scrutiny for software-enabled and AI-based devices is further expanding demand for comprehensive preclinical validation and documentation services.
Testing providers are broadening their service portfolios beyond traditional biocompatibility and toxicology studies to include cybersecurity assessments, software validation, usability testing, digital health evaluations, sterilization validation, human factors engineering, and regulatory consulting. Integrated service offerings enable manufacturers to streamline product development, reduce vendor complexity, accelerate regulatory submissions, and improve commercialization timelines.
Some of the key preclinical testing providers are expanding laboratory facilities and regulatory support services across Asia Pacific, Europe, and North America to meet rising global demand. Regional expansion enables faster testing turnaround, localized regulatory expertise, and improved access for multinational medical device manufacturers. In addition, growing healthcare investments and medical device innovation in emerging economies further support international market growth.
Analyst Perspective
The preclinical medical device testing services market is expanding as medical device manufacturers increasingly prioritize rigorous safety and efficacy evaluations before regulatory submission and commercialization. In addition, the rising complexity of medical devices, growing adoption of combination products, and stringent regulatory requirements from the FDA, EMA, and other agencies are driving demand for specialized preclinical testing services. Furthermore, increasing outsourcing to contract research organizations, growing focus on biocompatibility and performance testing, and rising investments in innovative device development further strengthen market growth across established and emerging medical device manufacturing hubs globally.
Service Insights
The biocompatibility testing services segment dominated the preclinical medical device testing services industry, accounting for the largest share of 57.5% in 2025. This can be attributed to the mandatory regulatory requirements for evaluating the biological safety of medical devices before clinical use. The segment is driven by the increasing development of implantable cardiovascular, orthopedic, and neurological devices that require comprehensive assessments, including cytotoxicity, sensitization, irritation, systemic toxicity, hemocompatibility, and implantation testing. In addition, compliance with ISO 10993 standards and stringent FDA and MDR regulations strengthens the dominance of this segment, making it an essential step in medical device commercialization.
The chemistry testing services segment is projected to grow at the second-fastest CAGR during the forecast period, driven by increasing regulatory emphasis on material characterization, extractables and leachables studies, residual contaminant analysis, and stability assessments. The growing use of advanced polymers, coatings, drug-device combination products, and additive manufacturing materials has increased the need for comprehensive analytical chemistry evaluations. In addition, evolving global regulatory requirements and rising demand for risk-based safety assessments are accelerating the adoption of specialized chemistry testing services across medical device development.
Testing Model Insights
The in vivo testing segment dominated the preclinical medical device testing services market, accounting for the largest share of 54.6% in 2025, due to its critical role in evaluating the biological safety, functional performance, and long-term tissue response of medical devices under physiological conditions. The regulatory authorities continue to require in vivo studies for high-risk implantable and Class III devices to assess systemic toxicity, implantation, and hemocompatibility. In addition, the ongoing development of cardiovascular, orthopedic, neurological, and combined devices further sustains demand for comprehensive in vivo preclinical evaluations prior to clinical trials.
The in vitro testing is projected to grow at the fastest CAGR over the forecast period, driven by advancements in cell-based assays, organ-on-chip technologies, 3D tissue models, and high-throughput screening platforms. Increasing emphasis on reducing animal testing, improving testing efficiency, and generating reproducible biological data is accelerating adoption. Furthermore, evolving regulatory acceptance of alternative testing methods and growing investments in predictive laboratory models are expanding the use of in vitro testing across diverse medical device applications.
Device Class Insights
The class II devices dominated the preclinical medical device testing services industry, accounting for the largest share of 44.3% in 2025, owing to their broad adoption across diagnostic, monitoring, surgical, and therapeutic applications. These moderate-risk devices require comprehensive preclinical evaluations, including biocompatibility, performance, microbiological, and package validation testing to meet stringent regulatory requirements. The large volume of Class II product launches, increasing technological advancements, and continuous innovation in minimally invasive and digital medical devices continue to drive sustained demand for specialized preclinical testing services.
The Class I devices segment is projected to grow at the fastest CAGR during the forecast period, driven by increasing production of disposable medical products, home healthcare devices, and wearable monitoring technologies. Although regulatory requirements are comparatively less stringent, manufacturers increasingly conduct preclinical evaluations to strengthen product quality, ensure material safety, and support global commercialization. Rising healthcare demand, expanding preventive care, and growing adoption of cost-effective medical devices are further accelerating testing requirements for Class I products.
Application Insights
The cardiovascular devices segment dominated the market, with the largest share of 23.9% in 2025, driven by the high prevalence of cardiovascular diseases and ongoing innovation in implantable and interventional technologies. Some of the products, such as stents, heart valves, vascular grafts, catheters, and cardiac rhythm management devices, require extensive preclinical evaluation for biocompatibility, durability, mechanical performance, and long-term safety. Stringent regulatory requirements and increasing investments in advanced cardiovascular technologies continue to drive demand for specialized preclinical testing services.
The aesthetic & cosmetic devices are projected to grow at the fastest CAGR over the forecast period, driven by rising consumer demand for minimally invasive cosmetic procedures and continuous innovation in laser, skin resurfacing, body contouring, and energy-based devices. Manufacturers are increasingly investing in preclinical safety, performance, and biocompatibility evaluations to meet evolving regulatory requirements and accelerate commercialization. Growing medical tourism, rising disposable incomes, and expanding adoption of aesthetic treatments further support rapid market growth.
End Use Insights
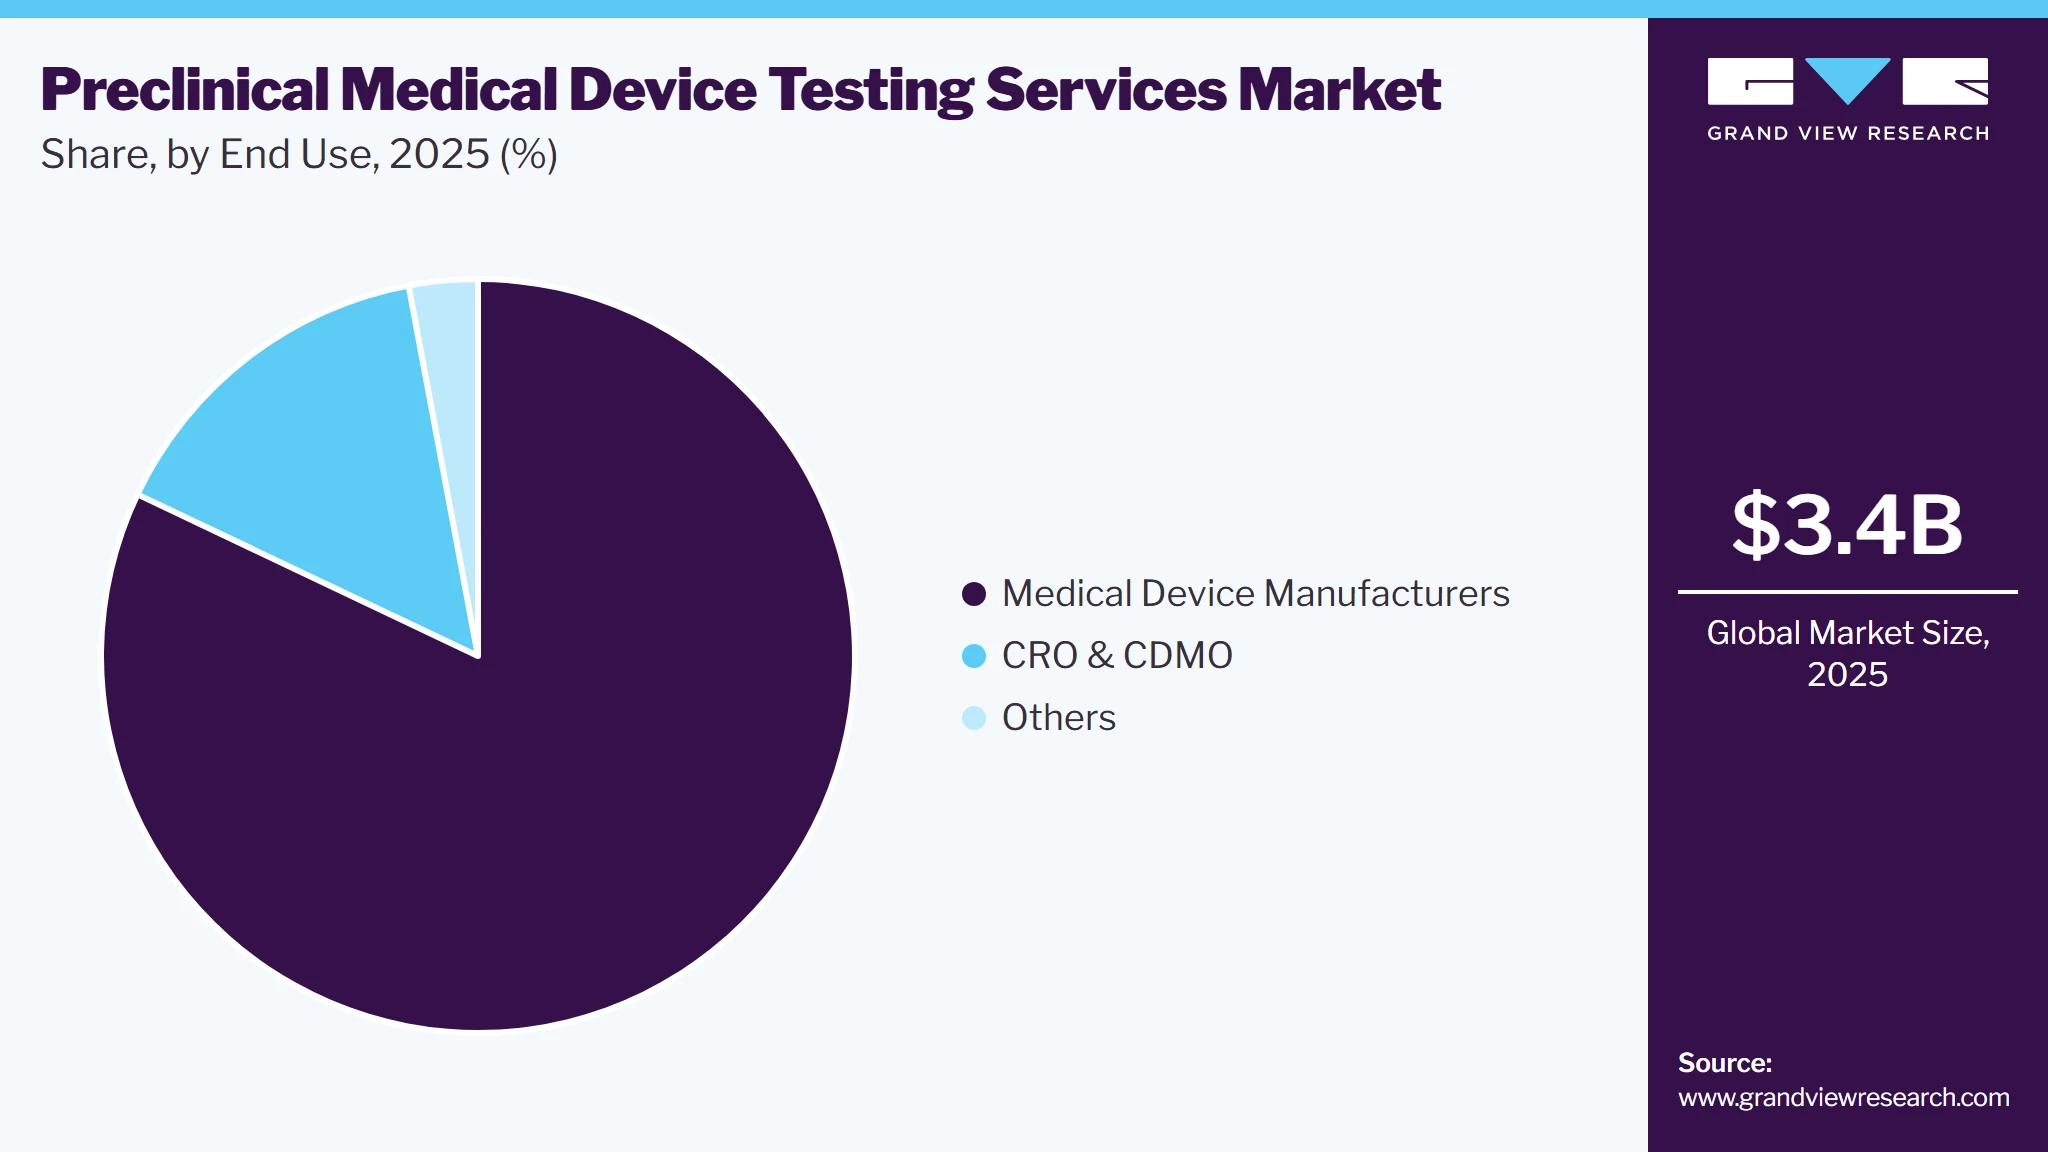
The medical device manufacturers segment dominated the preclinical medical device testing services industry, accounting for the largest share of 82.1% in 2025. This can be attributed to increasing product innovation, stringent regulatory approval requirements, and growing outsourcing of specialized testing activities. Some of the manufacturers rely on external testing providers for biocompatibility, chemistry, microbiology, and package validation to accelerate product development while ensuring compliance with FDA, MDR, and ISO standards. Rising investment in advanced medical technologies and an expanding device pipeline continue to strengthen demand for comprehensive preclinical testing services.
 To learn more about this report, Download Free Sample Report
The CROs & CDMOs segment is expected to register a significant CAGR over the study period, driven by increasing outsourcing of research, testing, and regulatory activities by medical device manufacturers seeking greater operational efficiency and faster commercialization. These organizations offer integrated development, validation, quality assurance, and regulatory support under a single platform, reducing development timelines and costs. in addition, growing demand for end-to-end outsourcing, expanding laboratory capabilities, and strategic collaborations with device innovators are accelerating segment growth.
Regional Insights
North America dominated the preclinical medical device testing services market with the largest revenue share of 37.4% in 2025. This can be attributed to the growth of the medical device industries in the U.S. and Canada. In addition, market players are increasingly focusing on expanding their product portfolios, enabling them to advance the development of technologically advanced medical devices. In addition, outsourcing preclinical testing services for medical devices enables companies to focus on their core capabilities, share associated risks, and improve device delivery, helping them gain competitive advantages.
 To learn more about this report, Download Free Sample Report
U.S. Preclinical Medical Device Testing Services Market Trends
The U.S. preclinical medical device testing services industry held the largest share of North America in 2025. The country is home to numerous medical device companies that outsource parts of their R&D to service providers, thereby contributing to the market growth. The high cost of R&D is a significant challenge, prompting medical device companies in the region to outsource functions to third parties with deep expertise in the field. In addition, medical device companies are committed to expanding their services with the innovations of new device development for patients, which has led to a rise in the requirement for preclinical medical device testing services in the country.
The preclinical medical device testing services market in Canada is driven by high demand for efficient healthcare, increased commitment to providing high-quality medical device services, and the growing need for outsourcing that addresses medical device manufacturers' manufacturing and regulatory compliance requirements. In addition, the innovation of medical devices with new technologies to meet patients' requirements due to the growing aging population, increased life expectancy & chronic diseases is expected to drive the market.
Europe Preclinical Medical Device Testing Services Market Trends
The Europe preclinical medical device testing industry’s growth is driven by the increasing demand for a range of medical devices and a growing number of clinical trials for different infectious diseases. Besides, medical device companies mostly prefer to outsource their preclinical trials in EU member states, as they can access a larger market and reduce costs by complying with the regulatory framework prevalent across the EU. In addition, the rising expansion of new facilities and emerging R&D activities are changing market scenarios rapidly. Such factors are expected to drive the region's growth.
The UK preclinical medical device testing services market held a significant revenue share in 2025. The country’s market growth is due to the increasing trend of outsourcing among medical device companies; technological advancements and expanding innovation among medical device companies and outsourcing companies have benefited the market growth. Also, the presence of major early-stage development outsourcing companies, R&D spending, and the increasing number of preclinical trials in the UK fuels the market.
The preclinical medical device testing services market in Germanyis anticipated to grow significantly over the forecast period. The country’s growth is due to the country's growing number of clinical trials and rising R&D investment for new technology-based medical device products. In addition, rising demand for outsourcing services and emerging research and development activities are reshaping the market landscape in Germany, further fueling growth.
Asia Pacific Preclinical Medical Device Testing Services Market Trends
The Asia Pacific preclinical medical device testing services industry is expected to grow at the fastest CAGR during the forecast period, owing to the cost-effectiveness of outsourcing medical device testing services and rising R&D costs. In addition, the presence of multinational medical device companies in the region and an increasing number of collaborative partnerships & strategic alliances are creating growth opportunities in the market. Moreover, the rising disease burden, the growing demand for advanced medical devices, and government initiatives such as tax exemptions and regulatory policy reforms fuel market growth.
The preclinical medical device testing services market in China is expected to grow over the forecast period. The growth of the market is driven by an increasing burden of disease, a growing number of clinical trials, low costs, a large pool of technical expertise, and an increasing focus on assessing medical device safety in the discovery process. Besides, the availability of technology for the innovation of medical devices is further boosting growth in the Asia-Pacific market. Additionally, the country offers low-cost services, a large pool of technical expertise, and high manufacturing capabilities for generic drugs. In addition, the outsourcing trend is expected to support medical device product innovation by ensuring compliance with relevant regulations & standards.
The Japan preclinical medical device testing services marketis witnessing significant growth over the forecast period. The growth of the market is due to the increasing adoption of outsourcing models and growing strategic alliances among medical device companies and outsourcing companies. The country is one of the major markets for clinical trials due to well-established clinical development knowledge, clinical investigational sites with well-trained site staff, & regulatory processes. In addition, increasing demand for preclinical medical device testing services to evaluate the safety of new medical devices is anticipated to drive the market.
The preclinical medical device testing services market in Indiais witnessing considerable growth due to the increasing presence of medical device companies in the country. The country has become one of the preferred sites for clinical trials due to its cost competitiveness, increasing patient pool, developing healthcare sector, and highly educated physicians. Besides, growing investment in research and development is expected to support market growth over the projected period.
Latin America Preclinical Medical Device Testing Services Market Trends
The Latin America preclinical medical device testing services industry is growing due to expanding medical device manufacturing, increasing healthcare investments, and rising adoption of advanced diagnostic and therapeutic technologies. Countries are strengthening regulatory frameworks and attracting multinational device manufacturers for regional product development. The competitive landscape is evolving with global testing providers expanding local laboratory capabilities through partnerships and acquisitions, while regional contract research organizations enhance specialized testing services to support regulatory compliance and accelerate product commercialization.
The preclinical medical device testing services market in Brazil is expected to grow over the forecast period. The growth is due to expanding domestic medical device manufacturing, increasing investment in healthcare innovation, and stronger adoption of internationally harmonized quality standards. For instance, in July 2026, the introduction of ANVISA's enhanced technovigilance framework has encouraged manufacturers to strengthen product validation, risk assessment, and lifecycle documentation prior to commercialization. These developments are increasing demand for accredited preclinical testing providers that offer biocompatibility, performance, and safety evaluations, thereby supporting faster regulatory preparedness and global market access.
Middle East and Africa Preclinical Medical Device Testing Services Market Trends
The MEA preclinical medical device testing services industry accounted for a significant revenue share in 2025. The growth is driven by increasing investments in medical technology and growing localization of medical device manufacturing in countries such as Saudi Arabia, the UAE, and South Africa. The competitive landscape is developing as international testing laboratories establish regional collaborations and local providers enhance specialized testing capabilities, regulatory consulting, and quality assurance services to support compliance with global standards and facilitate faster market entry for innovative medical devices.
The South Africa Preclinical Medical Device Testing Services Market is witnessing growth due to rising manufacturing and R&D investments, increasing government initiatives to strengthen healthcare and regulatory infrastructure, and growing adoption of international quality standards for device approvals. In addition, expanding partnerships with global medical device companies, increasing focus on local clinical and preclinical research capabilities, and the rising prevalence of chronic diseases requiring advanced medical devices are boosting market growth.
The preclinical medical device testing services market in Saudi Arabia is growing, driven by increasing government investments in healthcare infrastructure under Vision 2030, rising local medical device manufacturing initiatives, and growing focus on reducing import dependency through domestic production. In addition, the increasing adoption of advanced diagnostic devices and supportive regulatory alignment with global quality standards are encouraging manufacturers to invest in comprehensive safety, biocompatibility, and performance testing prior to commercialization.
Key Preclinical Medical Device Testing Services Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. Companies are investing in AI-enabled testing, biocompatibility assessment, digital validation, and strategic acquisitions to strengthen their global presence. Long-term partnerships with medical device manufacturers and compliance with international quality standards remain key competitive differentiators.
Key Preclinical Medical Device Testing Services Companies
The following key companies have been profiled for this study of the preclinical medical device testing services market.
-
SGS SA
-
Eurofins Scientific
-
Pace Analytical Services LLC
-
Intertek Group Plc
-
WUXI APPTEC
-
TÜV SÜD AG
-
Sterigenics International LLC (Nelson Labs)
-
North American Science Associates, Inc.
-
Charles River Laboratories International, Inc.
-
Labcorp Drug Development
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: SGS SA
- Mature players focus on expanding accredited laboratory networks, investing in AI-enabled testing platforms, automation, and digital simulation technologies.
- Continuous investment in GLP-compliant infrastructure, specialized testing services, and global quality certifications enables end-to-end support from product development through regulatory approval and commercialization.
- Established companies benefit from extensive regulatory expertise, globally accredited laboratories, comprehensive testing portfolios, and long-standing relationships with medical device manufacturers.
- Their ability to deliver integrated biocompatibility, toxicology, mechanical, microbiological, and software validation services under one platform ensures faster project execution, high-quality data, global regulatory acceptance, and strong customer retention.
- Mature providers often face high operational and infrastructure costs associated with maintaining advanced laboratories, regulatory compliance, and specialized personnel.
Emerging Players: Intertek Group Plc
- Emerging players focus on niche preclinical testing services, rapid turnaround times, and cost-effective solutions to compete with established laboratories.
- They invest in advanced technologies such as AI-assisted testing, digital pathology, and in vitro models while forming strategic partnerships with medical device manufacturers, CROs, and research institutes. Expanding ISO/GLP-certified facilities and regulatory consulting capabilities also strengthens market positioning.
- Emerging companies offer greater operational flexibility, customized testing protocols, and faster project execution than larger competitors.
- Their ability to rapidly adopt innovative testing technologies, provide personalized client support, and specialize in high-growth segments such as AI-enabled devices, digital health, and combination products enables differentiation.
- Emerging players often face limited laboratory capacity, restricted geographic presence, and lower brand recognition compared with established global testing providers. High capital requirements for accredited facilities, advanced equipment, and skilled personnel constrain expansion.
Recent Developments
- In January 2025, WuXi AppTec signed a definitive agreement to sell its U.S. medical device testing facilities in Minnesota and Georgia to NAMSA, enabling WuXi to strengthen its pharmaceutical CRDMO focus while optimizing its business portfolio. Such an acquisition strengthens NAMSA's leadership in preclinical medical device testing by expanding laboratory capacity, technical expertise, and regulatory capabilities, while intensifying competition among global testing service providers.
Preclinical Medical Device Testing Services Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.4 billion
Estimated market size in 2026
USD 3.7 billion
Projected market size by 2033
USD 6.7 billion
Growth rate
CAGR of 8.9% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, testing model, device class, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar
Key companies profiled
SGS SA; Eurofins Scientific; Pace Analytical Services LLC; Intertek Group Plc; WUXI APPTEC; TÜV SÜD AG; Sterigenics International LLC (Nelson Labs); North American Science Associates, Inc.; Charles River Laboratories International, Inc.; Labcorp Drug Development
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Preclinical Medical Device Testing Services Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global preclinical medical device testing services market report based on service, testing model, device class, application, end use, and region:
-
Service Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Biocompatibility Testing Services
-
Material / Chemical Characterization
-
Cytotoxicity Testing
-
Sensitization Testing
-
Irritation & Reactivity Testing
-
Systemic Toxicity Testing
-
Hemocompatibility Testing
-
Implantation Testing
-
Pyrogenicity Testing
-
Others
-
-
Chemistry Testing Services
-
Residuals & Contaminant Analysis
-
Analytical Method Development & Validation
-
Stability & Degradation Studies
-
Other Analytical Chemistry Services
-
-
Microbiology QC Testing Services
-
Sterility Testing & Validation
-
Bioburden Determination
-
Bacterial Endotoxin Testing
-
Others
-
-
Package Validation Services
-
-
Testing Model Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
In Vivo Testing
-
In Vitro Testing
-
Ex Vivo Testing
-
-
Device Class Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Class I
-
Class II
-
Class III
-
-
Application Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Cardiovascular Devices
-
Orthopedic Devices
-
Dental Devices
-
Neurological Devices
-
Ophthalmic Devices
-
General Surgical Devices
-
Aesthetic & Cosmetic Devices
-
Others
-
-
End Use Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Medical Device Manufacturers
-
CRO & CDMO
-
Others
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Oman
-
Qatar
-
-
Research Methodology
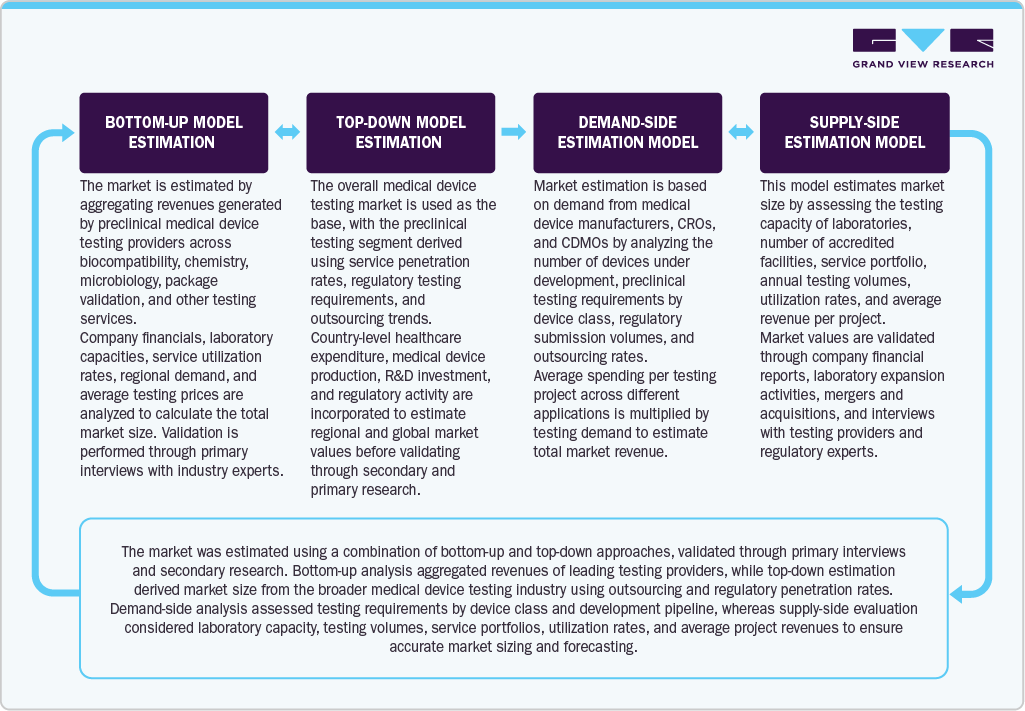
The preclinical medical device testing services market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each preclinical medical device testing services segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service
Revenue capture definition
Biocompatibility Testing Services
Revenue is generated from biological safety evaluations assessing material compatibility, toxicity, irritation, sensitization, and tissue response, ensuring medical devices comply with ISO 10993 and regulatory approval requirements.
Material / Chemical Characterization
Revenue includes chemical composition analysis, extractables and leachables studies, impurity profiling, and material identification to verify device material safety, consistency, and regulatory compliance.
Cytotoxicity Testing
Revenue is generated from laboratory evaluations measuring cellular toxicity of medical device materials to confirm biological safety before clinical use and regulatory submission.
Sensitization Testing
Revenue includes testing that evaluates allergic or immune responses caused by medical device materials, supporting compliance with international biocompatibility standards and regulatory approvals.
Irritation & Reactivity Testing
Revenue is derived from assessments measuring local tissue irritation and inflammatory responses following contact with medical device materials, supporting product safety validation.
Systemic Toxicity Testing
Revenue includes short-term and long-term toxicity studies evaluating adverse systemic effects caused by device materials or extracts before commercialization.
Hemocompatibility Testing
Revenue is generated from evaluating interactions between blood-contacting medical devices and blood components, including coagulation, hemolysis, thrombogenicity, and platelet activation assessments.
Implantation Testing
Revenue includes animal implantation studies assessing tissue compatibility, healing response, inflammation, degradation, and long-term safety of implantable medical devices.
Pyrogenicity Testing
Revenue is generated from detecting fever-inducing contaminants in medical devices using validated testing methods to ensure patient safety and regulatory compliance.
Others (Biocompatibility)
Revenue comprises specialized biological evaluations, genotoxicity, carcinogenicity, reproductive toxicity, and customized testing supporting unique medical device applications and regulatory requirements.
Chemistry Testing Services
Revenue is generated from analytical chemistry evaluations supporting material characterization, contamination analysis, stability testing, method validation, and regulatory compliance for medical devices.
Residuals & Contaminant Analysis
Revenue includes testing for manufacturing residues, cleaning agents, processing chemicals, heavy metals, and contaminants to ensure product safety and regulatory compliance.
Analytical Method Development & Validation
Revenue is generated from developing, validating, and optimizing analytical methods ensuring reliable chemical testing, reproducibility, and regulatory acceptance throughout product development.
Stability & Degradation Studies
Revenue includes accelerated and real-time stability testing evaluating material integrity, degradation products, shelf life, and packaging compatibility under controlled environmental conditions.
Other Analytical Chemistry Services
Revenue comprises customized analytical testing, impurity identification, material comparison, elemental analysis, and chemical investigations supporting medical device development and quality assurance.
Microbiology QC Testing Services
Revenue is generated from microbiological quality control testing ensuring sterile, contamination-free medical devices through validated laboratory testing and regulatory compliance services.
Sterility Testing & Validation
Revenue includes validated sterility testing, process validation, media fills, and contamination assessments confirming sterile medical devices before commercial distribution.
Bioburden Determination
Revenue is generated from quantifying microbial contamination present before sterilization, supporting sterilization process validation and microbiological quality assurance.
Bacterial Endotoxin Testing
Revenue includes endotoxin detection using validated methods to ensure injectable and implantable devices meet established pyrogen safety limits before commercialization.
Others (Microbiology QC)
Revenue comprises environmental monitoring, microbial identification, antimicrobial effectiveness testing, disinfectant validation, and customized microbiological quality control services.
Segment – Testing Model
Revenue capture definition
In Vivo Testing
Revenue includes animal studies evaluating biological safety, functional performance, tissue response, and long-term implantation characteristics supporting regulatory approval and clinical readiness.
In Vitro Testing
Revenue is generated from laboratory-based evaluations using cell cultures and advanced tissue models to assess device safety, toxicity, and biological compatibility without animal use.
Ex Vivo Testing
Revenue includes testing using isolated tissues or organs to evaluate device functionality, performance, and tissue interaction under controlled laboratory conditions.
Segment – Device Class
Revenue capture definition
Class I
Revenue is generated from testing low-risk medical devices requiring limited biological evaluation, material verification, and regulatory documentation before commercialization.
Class II
Revenue includes comprehensive preclinical testing for moderate-risk devices involving performance validation, biocompatibility, electrical safety, and regulatory compliance assessments.
Class III
Revenue is derived from extensive testing of high-risk implantable and life-supporting devices requiring rigorous safety, toxicology, durability, and functional validation.
Segment – Application
Revenue capture definition
Cardiovascular Devices
Revenue includes testing heart valves, vascular grafts, stents, catheters, and related devices requiring comprehensive biological, mechanical, and performance evaluations.
Orthopedic Devices
Revenue is generated from testing implants, fixation systems, prosthetics, and spinal devices for strength, durability, wear resistance, and biocompatibility.
Dental Devices
Revenue includes evaluation of dental implants, restorative materials, orthodontic products, and surgical instruments for safety, durability, and biological compatibility.
Neurological Devices
Revenue is generated from testing neurostimulators, spinal implants, brain-computer interfaces, and neurosurgical devices for safety, functionality, and tissue compatibility.
Ophthalmic Devices
Revenue includes preclinical testing of intraocular lenses, retinal implants, ophthalmic instruments, and vision correction devices for optical performance and biological safety.
General Surgical Devices
Revenue is generated from evaluating surgical instruments, staplers, electrosurgical devices, and minimally invasive systems for safety, functionality, and sterilization compatibility.
Aesthetic & Cosmetic Devices
Revenue includes testing laser systems, skin treatment equipment, body contouring devices, and cosmetic technologies for performance, safety, and regulatory compliance.
Others (Applications)
Revenue comprises testing respiratory, gastrointestinal, urology, wound care, diagnostic, and other specialized medical devices requiring customized preclinical evaluations.
Segment – End Use
Revenue capture definition
Medical Device Manufacturers
Revenue is generated from manufacturers outsourcing comprehensive preclinical testing, regulatory validation, and safety assessments to accelerate product approvals and commercialization.
CRO & CDMO
Revenue includes outsourced testing services supporting contract research and manufacturing organizations requiring integrated preclinical validation for client medical device development projects.
Others (End Use)
Revenue is derived from academic institutions, government agencies, research organizations, and healthcare innovators requiring specialized testing, validation, and regulatory consulting services.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Technology & Regulatory Landscape Analysis
Delivered in-depth assessment of AI-driven testing, digital twins, organ-on-chip models, automation, cybersecurity validation, and evolving FDA, MDR, ISO 10993, and regional regulatory requirements influencing testing services.
Supports informed investment decisions, technology adoption strategies, regulatory preparedness, and product development planning while reducing compliance risks and accelerating medical device commercialization.
Competitive Benchmarking & Company Profiling
Provided detailed profiles of leading and emerging testing service providers, including service portfolios, strategic developments, mergers & acquisitions, laboratory capabilities, technology adoption, and competitive positioning across global markets.
This helps clients benchmark competitors, identify partnership or acquisition opportunities, understand market concentration, and formulate effective competitive strategies for strengthening market presence and service differentiation.
Regional Market Assessment
Delivered a comprehensive evaluation of North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, highlighting country-level drivers, regulatory developments, competitive landscape, and growth opportunities for preclinical medical device testing services.
This enables clients to identify high-growth regions, prioritize expansion strategies, optimize resource allocation, and develop region-specific market entry plans based on regulatory maturity, healthcare investments, and medical device innovation trends.
Frequently Asked Questions About This Report
The global preclinical medical device testing services market size was estimated at USD 3.4 billion in 2025 and is expected to reach USD 3.7 billion in 2026.
The global preclinical medical device testing services market is expected to grow at a compound annual growth rate of 8.9% from 2026 to 2033 to reach USD 6.7 billion by 2033.
Based on device class, the class II segment held the largest market share of 44.3% in 2025, while class I are the fastest-growing segment.
Based on application, the cardiovascular devices segment held the largest market share of 23.9% in 2025, while neurological devices are the fastest-growing segment.
Based on end use, the medical device manufacturers segment held the largest market share of 82.1% in 2025.
North America preclinical medical device testing services market held the largest share of 37.4% of the global market in 2025.
Key players include SGS SA, Eurofins Scientific, Pace Analytical Services LLC, Intertek Group Plc, WUXI APPTEC, TÜV SÜD AG, Sterigenics, International LLC (Nelson Labs), North American Science Associates, Inc., Charles River Laboratories International, Inc., Labcorp Drug Development
Based on testing model, in vivo testing segment held the largest market share of 54.6% in 2025, while in vitro testing are the fastest-growing segment.
Some of the major factors driving the market include complexity in the product design, strict approval norms, intense competition in the medical device industry, and an increase in the number of small medical devices lacking in-house testing capabilities.
Based on service, the biocompatibility testing services segment held the largest market share of 57.5% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


