
- Home
- »
- Advanced Interior Materials
- »
-
Pressure Reducing Valve Market Size Report, 2026-2033GVR Report cover

Pressure Reducing Valve Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Direct Acting, Pilot Operated), By Media (Water And Other Liquids, Air And Industrial Gases), By End Use (Oil And Gas, Water And Wastewater), By Region, And Segment Forecasts
Market Size, 2025
$3.5BMarket Estimate, 2026
$3.6BMarket Forecast, 2033
$4.8BCAGR, 2026–2033
4.3%Pressure Reducing Valve Market Summary
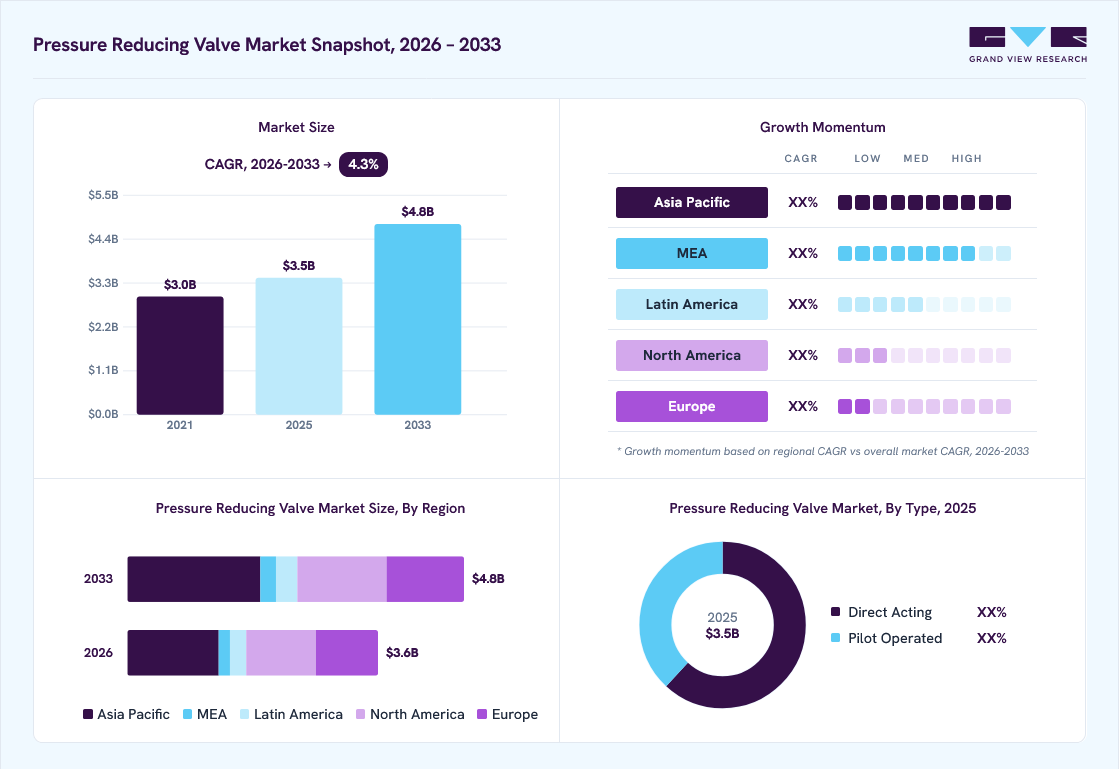
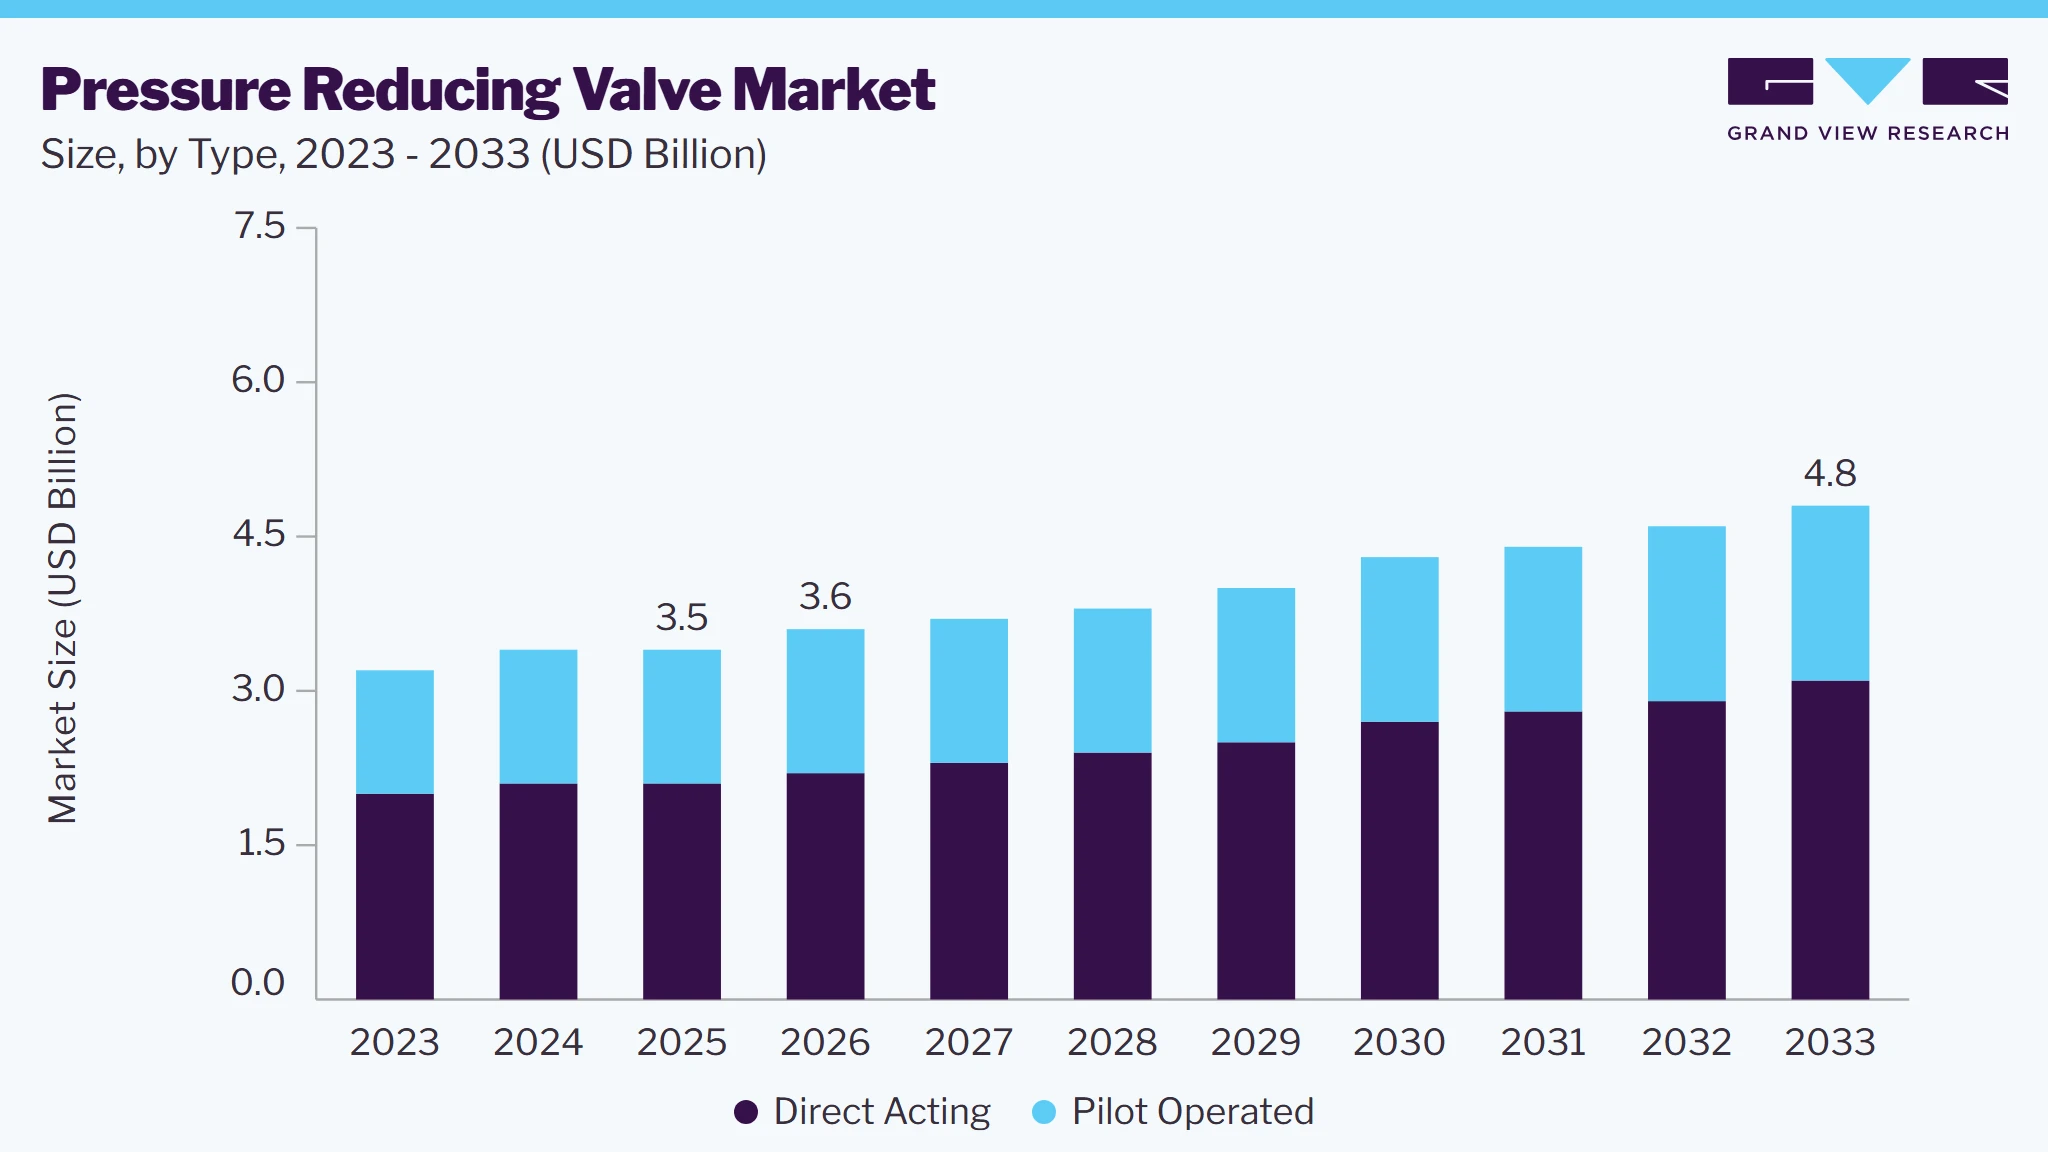
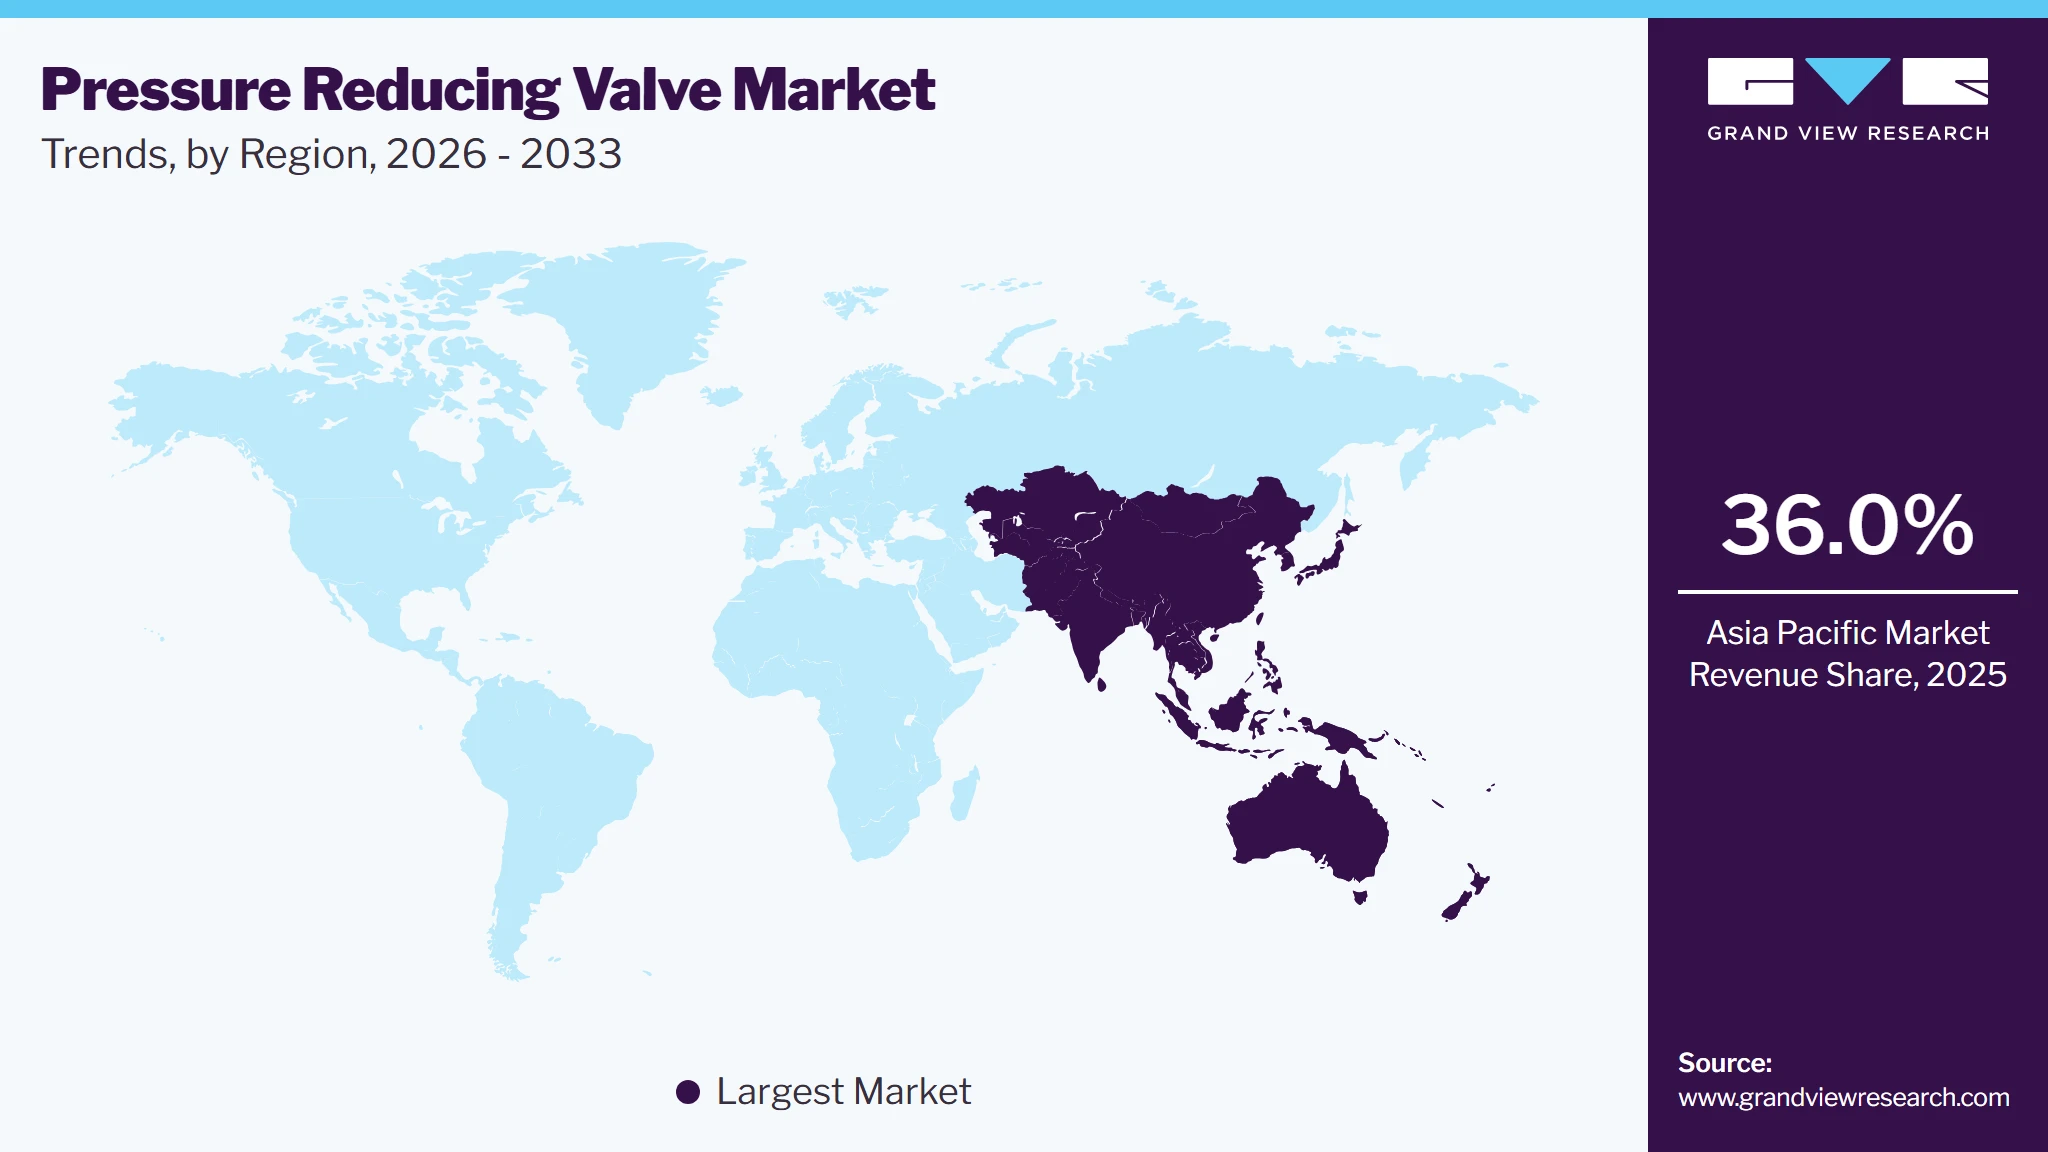
The global pressure reducing valve market size was valued at USD 3.5 billion in 2025 and is projected to grow from USD 3.6 billion in 2026 to USD 4.8 billion by 2033, at a CAGR of 4.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 36.0% in 2025. The market is driven by investments in water distribution, wastewater treatment, industrial processing, and energy infrastructure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Direct acting segment held the largest share of 61.9% in 2025.
- By media: Water and other liquids segment led the market in 2025, with a share of 48.6%.
- By end use: Water and wastewater segment is expected to grow at the fastest CAGR of 5.3% from 2026 to 2033.
Regional Highlights
- Largest regional market: Asia Pacific (36.0% revenue share, 2025)
- By country: China dominated the APAC market in 2025.
Market Size & Forecast
- Market Size in 2025: USD 3.5 Billion
- Estimated Market Size in 2026: USD 3.6 Billion
- Projected Market Size by 2033: USD 4.8 Billion
- CAGR (2026-2033): 4.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, the market is witnessing growth due to the expansion of pipelines, treatment facilities, manufacturing plants, chemical facilities, and power projects, which are increasing the need for controlled downstream pressure to protect equipment and maintain system stability. Replacement of aging pressure-control equipment and modernization of existing networks further contribute to demand.
 To learn more about this report, Download Free Sample Report
In addition, the adoption of automated pressure-management systems is increasing demand for pressure reducing valves with improved regulation accuracy and monitoring capabilities. Integration with sensors and electronic controls enables real-time pressure monitoring and more responsive system management. Product development focused on higher flow capacity, durable materials, and application-specific configurations is further broadening their use across water, industrial, and utility systems.
Market Dynamics
The global pressure reducing valve market is influenced by investments in water distribution, industrial processing, energy infrastructure, and fluid-handling systems. Market demand varies according to pressure-control requirements, operating conditions, media characteristics, and system configuration. Product selection is increasingly shaped by requirements for stable downstream pressure, equipment protection, operating reliability, and compatibility with automated monitoring and control systems. Development of compact, higher-capacity, and application-specific valve designs is also influencing product offerings across industrial and infrastructure applications.
Development and rehabilitation of water distribution networks, treatment facilities, and industrial infrastructure are creating requirements for pressure reducing valves. In water systems, these valves control pressure across different network zones and limit excessive pressure reaching downstream pipelines and equipment. Industrial facilities also require pressure reduction within process and utility circuits, creating demand across manufacturing, chemicals, power generation, oil and gas, and other fluid-handling applications.
Pressure reducing valve selection requires careful consideration of inlet pressure, required downstream pressure, flow rate, temperature, media properties, valve size, and material compatibility. Variations in operating conditions can require application-specific configurations and engineering assessment, increasing procurement complexity. In industrial installations, additional requirements related to testing, certification, installation, and maintenance can increase the overall implementation burden and influence purchasing decisions.
Digitalization of water networks and industrial fluid systems is creating opportunities for pressure reducing valves with monitoring and control capabilities. Integration with sensors, electronic controllers, and remote monitoring platforms can provide real-time information on pressure conditions and valve performance. Such capabilities can assist operators in identifying abnormal pressure conditions, improving maintenance planning, and optimizing system operation, creating scope for manufacturers to develop connected pressure-control solutions.
Market Concentration & Characteristics
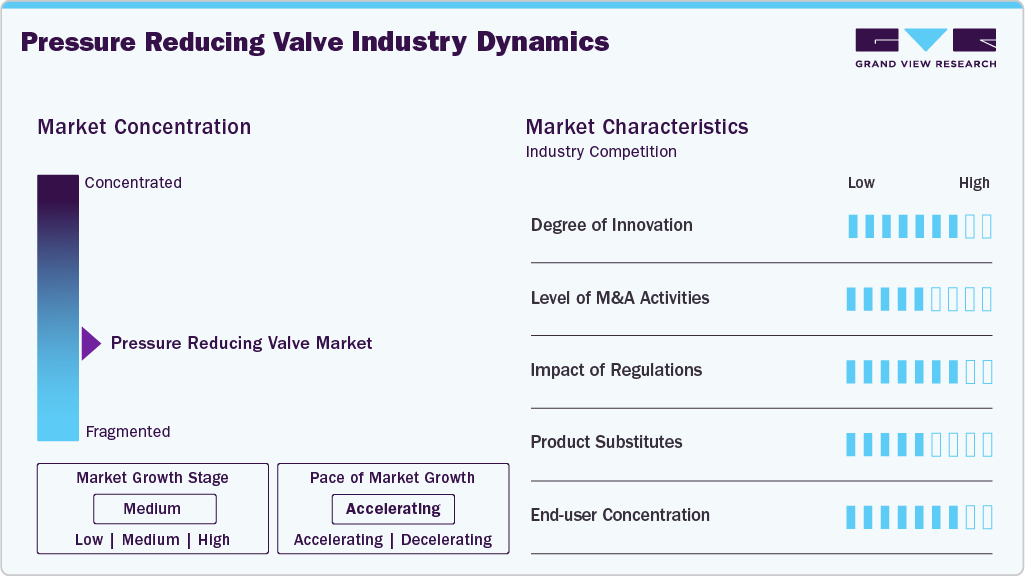
The global pressure reducing valve market comprises manufacturers with varying degrees of product specialization, ranging from broad valve portfolios to dedicated pressure-control solutions. Competitive positioning is influenced by valve configuration, pressure and flow capacity, material selection, media compatibility, certifications, manufacturing capabilities, and application expertise. Suppliers serve requirements across municipal water systems, industrial processes, steam networks, gas distribution, and utility applications.
Product offerings are differentiated primarily by pressure-control mechanism and operating requirements. Direct-acting pressure reducing valves provide a relatively simple configuration for applications with moderate flow and pressure-control requirements, while pilot-operated pressure reducing valves are designed for higher flow rates and applications requiring tighter downstream pressure regulation. Product selection also considers inlet and outlet pressure, flow capacity, temperature, media compatibility, valve size, body and trim materials, connection type, and installation conditions.
 To learn more about this report, Download Free Sample Report
The market includes standardized valve models as well as engineered configurations developed for specific operating environments. Manufacturers are differentiating through improved pressure stability, broader operating ranges, corrosion-resistant construction, compact designs, easier maintenance, and integration with automated monitoring and control systems. Demand is generated through new infrastructure and industrial projects as well as replacement of installed valves, while application-specific requirements create opportunities for suppliers with specialized engineering and customization capabilities.
Analyst Perspective
The pressure reducing valve market is characterized by demand from both infrastructure and industrial applications, with water distribution, wastewater, manufacturing, chemicals, oil and gas, power generation, and industrial utilities forming important areas of use. Replacement of installed valves remains relevant alongside demand generated by new infrastructure and plant development. Product competitiveness is increasingly influenced by pressure regulation accuracy, operating range, material selection, service life, maintenance requirements, and compatibility with automated control systems. Manufacturers with application-specific product portfolios and capabilities in pressure management, system integration, and technical support can address a broader range of operating requirements across municipal and industrial installations.
Type Insights
The direct acting segment held the largest revenue share of 61.9% in 2025. Its relatively simple design, rapid pressure response, and ease of installation make it suitable for applications requiring reliable downstream pressure regulation across water systems, industrial utilities, and process installations. These characteristics support its broad adoption across applications with straightforward pressure-control requirements.
The pilot operated segment is projected to register a significant CAGR during the forecast period. Its ability to provide precise downstream pressure regulation and handle higher flow rates makes it suitable for industrial and infrastructure applications with variable operating conditions. Increasing demand for stable pressure control across water distribution, process industries, power generation, and other fluid-handling systems is contributing to its growth.
Media Insights
The water and other liquids segment held the largest revenue share of 48.6% in 2025, reflecting the broad application of pressure reducing valves across municipal water distribution, wastewater systems, industrial water circuits, and liquid-handling processes. These valves regulate downstream pressure and protect pipelines, equipment, and connected systems from excessive pressure, making them suitable for diverse liquid-handling requirements.
The air and industrial gases segment is projected to register the fastest CAGR of 4.9% during the forecast period. Pressure reducing valves are widely used in compressed-air networks and industrial gas systems to maintain stable downstream pressure across manufacturing, processing, and utility applications. Increasing requirements for controlled gas pressure and reliable operation across industrial systems are contributing to the segment’s growth.
End Use Insights
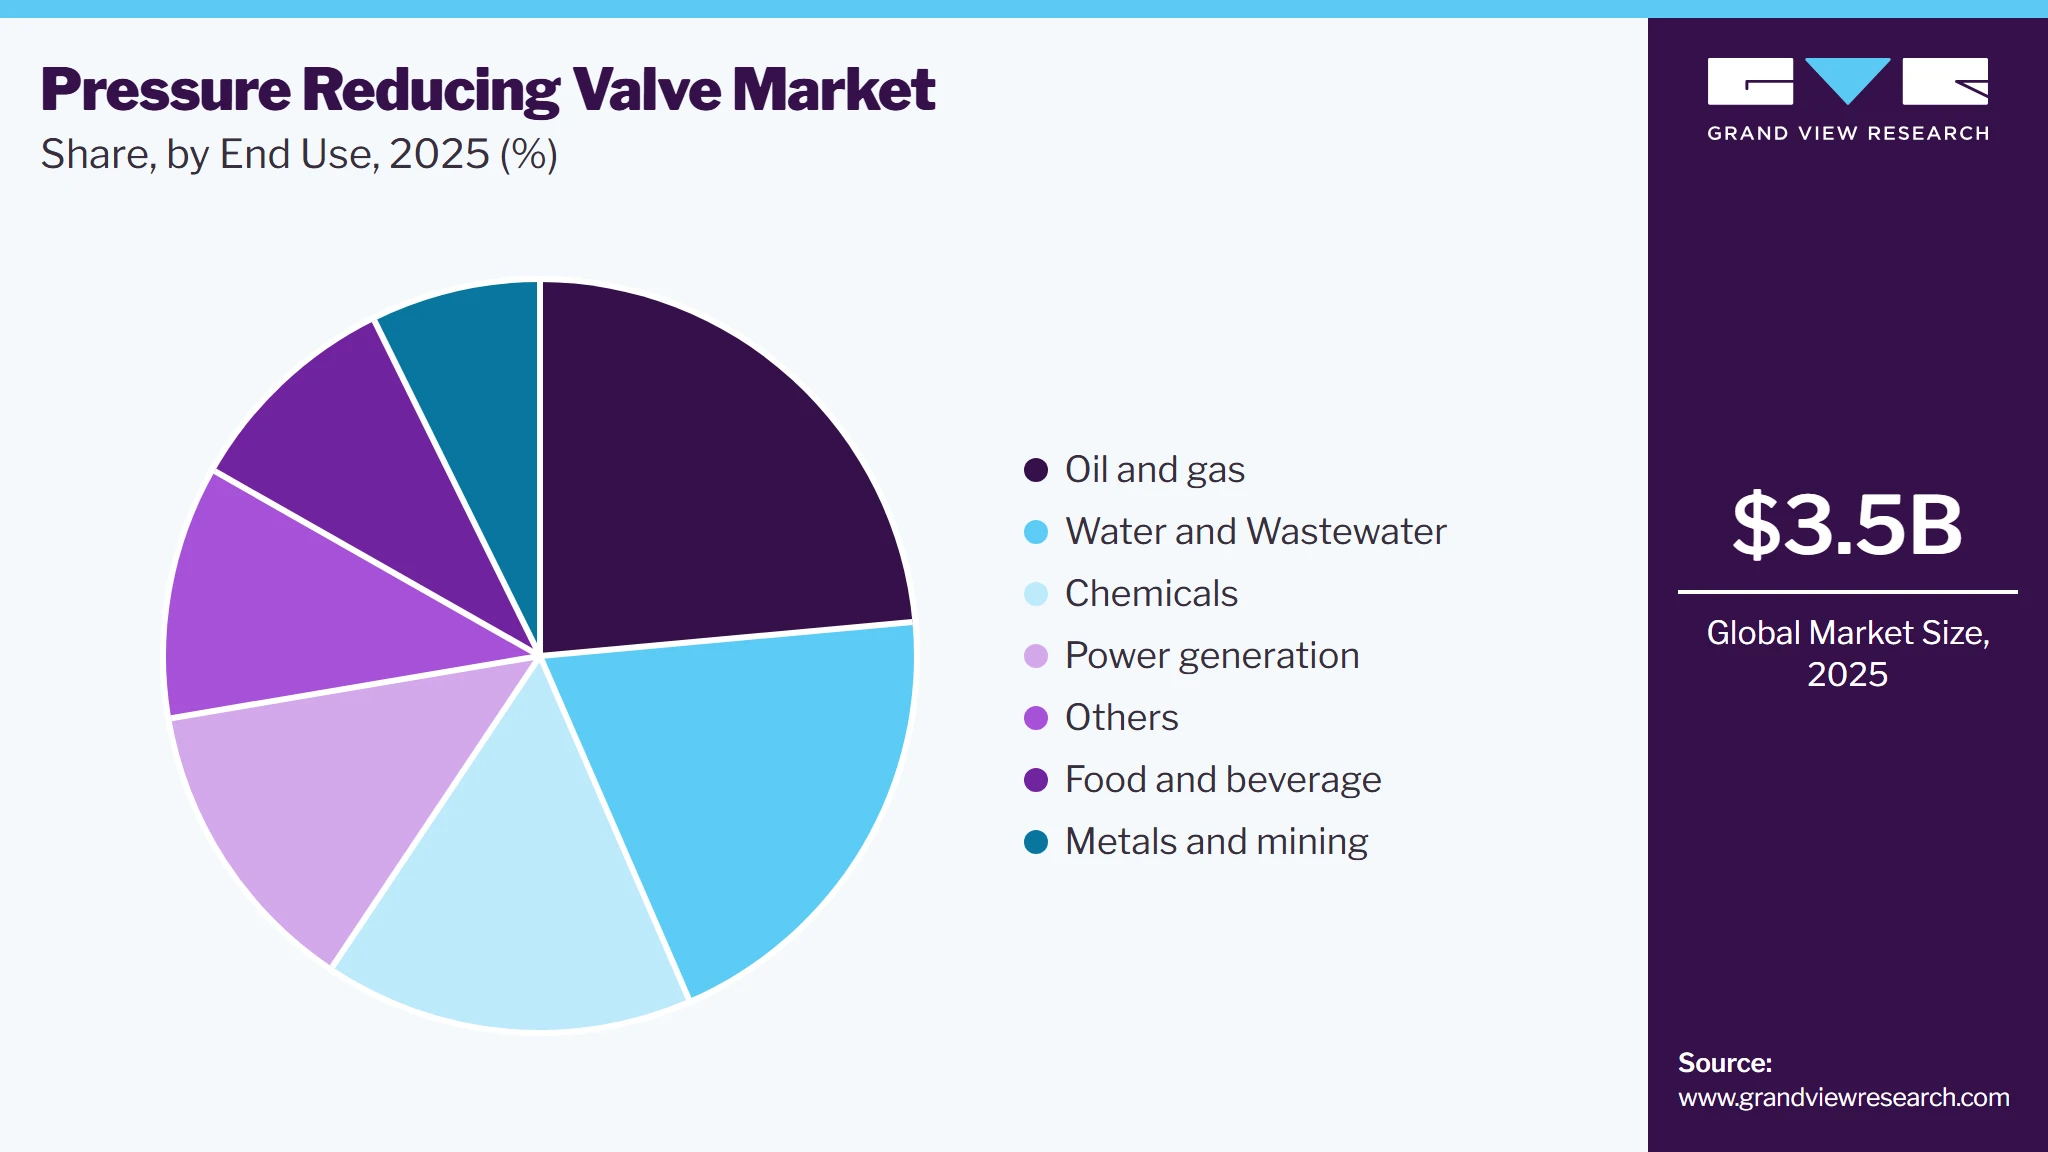
The oil and gas segment held the largest revenue share of 23.5% in 2025. Pressure reducing valves are widely used across upstream, midstream, and downstream operations to regulate pressure within pipelines, processing systems, and utility networks. Their ability to maintain controlled downstream pressure and protect connected equipment makes them suitable for demanding oil and gas applications involving high-pressure and variable-flow conditions.
 To learn more about this report, Download Free Sample Report
The water and wastewater segment is projected to register the fastest CAGR during the forecast period. Expansion and modernization of water distribution networks, treatment facilities, and wastewater infrastructure are creating demand for pressure reducing valves to maintain stable pressure and protect pipelines, pumps, and other downstream equipment. Increasing requirements for efficient pressure management across municipal and industrial water systems are further contributing to segment growth.
Regional Insights
Asia Pacific pressure reducing valve market presents growth opportunities across municipal water systems, manufacturing facilities, chemical processing, power generation, oil and gas, and industrial utilities. Industrial capacity expansion and development of water and wastewater infrastructure are creating requirements for controlled downstream pressure and protection of connected equipment. Demand also arises from replacement of existing valves and modernization of fluid-handling systems.
 To learn more about this report, Download Free Sample Report
Pressure reducing valve market in China has a broad application base for pressure reducing valves across chemical processing, petrochemicals, power generation, manufacturing, and municipal water networks. Industrial facilities require pressure-control solutions for process fluids, steam, water, and utility systems. Upgrades to production facilities and continued investment in fluid-handling infrastructure create opportunities for new and replacement pressure reducing valve installations.
India pressure reducing valve market is witnessing demand for pressure reducing valves through investments in water distribution, wastewater treatment, manufacturing facilities, power projects, and industrial infrastructure. Municipal applications require pressure management across transmission and distribution networks, while pharmaceutical, chemical, food processing, and general manufacturing facilities use pressure reducing valves across process and utility systems. Expansion of industrial capacity is creating additional requirements for pressure-control equipment.
North America Pressure Reducing Valve Market Trends
North America has an established pressure reducing valve market supported by a substantial installed base across municipal, commercial, and industrial applications. Demand is associated with water distribution, commercial plumbing, oil and gas, chemical processing, power generation, manufacturing, compressed-air systems, and steam networks. Infrastructure rehabilitation, equipment replacement, and modernization of pressure-control systems contribute to ongoing valve demand.
U.S. Pressure Reducing Valve Market Trends
The U.S. has diverse pressure reducing valve applications across water utilities, commercial buildings, manufacturing plants, chemical facilities, and energy infrastructure. Pressure reducing valves are used to maintain suitable downstream pressure and protect piping and connected equipment across these systems. Industrial facility upgrades and replacement of aging pressure-control equipment continue to create opportunities for pressure reducing valve suppliers.
Pressure reducing valve market in Canada is experiencing demand across water infrastructure, mining, energy, and industrial processing applications. Mining and resource-related facilities require pressure-control equipment for water and process-fluid systems operating under demanding conditions. Maintenance of municipal networks and upgrades to industrial facilities also generate requirements for the replacement and installation of new pressure-reducing valves.
Europe Pressure Reducing Valve Market Trends
Europe has an established market for pressure reducing valves across water distribution, steam systems, chemical processing, manufacturing, power generation, and commercial infrastructure. Demand is influenced by industrial modernization, pressure-control requirements, energy efficiency initiatives, and replacement of existing equipment. Industrial users require pressure-control solutions that provide stable operation and compatibility with automated systems.
Pressure reducing valve market in Germany has demand for pressure reducing valves across chemical manufacturing, machinery production, power generation, industrial utilities, and water systems. Applications include steam distribution, compressed-air networks, process fluids, and industrial water circuits. Modernization of production facilities and upgrades to utility systems provide opportunities for valves offering precise pressure regulation and durable construction.
France pressure reducing valve market serves demand across municipal water services, energy facilities, chemical processing, food and beverage plants, and commercial infrastructure. Water pressure management forms an important application area, while industrial facilities use pressure reducing valves in steam and utility systems. Rehabilitation of existing networks and modernization of industrial installations support replacement and new equipment requirements.
Middle East & Africa Pressure Reducing Valve Market Trends
Middle East & Africa offers pressure reducing valve opportunities across water infrastructure, desalination, oil and gas, petrochemical processing, power generation, and industrial utilities. Water treatment and transmission projects require pressure regulation across interconnected fluid-handling systems, while hydrocarbon processing facilities use pressure reducing valves in process and utility applications. Industrial diversification and infrastructure development are broadening the range of applications.
Pressure reducing valve market in Saudi Arabia is experiencing demand associated with desalination, water transmission, oil and gas, power generation, and industrial facilities. Water infrastructure requires pressure management across treatment and distribution systems, while refineries and petrochemical facilities use pressure-control equipment in process and utility networks. Development of industrial and utility infrastructure is creating requirements for new pressure-control installations.
Latin America Pressure Reducing Valve Market Trends
Latin America presents pressure reducing valve opportunities across municipal water systems, mining, oil and gas, chemicals, food processing, energy, and manufacturing. Demand varies across countries according to industrial activity, infrastructure conditions, and investment levels. Expansion of processing facilities and rehabilitation of water networks are creating requirements for pressure regulation and replacement of existing valves.
Pressure reducing valve market in Brazil serves demad across water infrastructure and industrial sectors such as mining, chemicals, pulp and paper, food processing, energy, and manufacturing. Pressure-control equipment is used across process and utility systems to maintain operating conditions and protect downstream components. Investment in water infrastructure and industrial facility modernization provides opportunities for both new installations and replacement demand.
Key Pressure Reducing Valve Company Insights
Some of the key players operating in the market include Spirax Sarco, Yoshitake, among others.
-
Spirax Sarco is a global provider of steam and thermal energy management solutions, with a strong focus on pressure control and fluid management systems. The company offers an extensive range of pressure reducing valves, including direct-acting and pilot-operated configurations, serving steam and industrial-fluid applications. Its portfolio includes BRV, DP, DRV, LRV, and SRV series, covering different pressure, temperature, and flow requirements.
-
Yoshitake Inc. is a Japan-based valve manufacturer specializing in fluid-control products for industrial, building, and mechanical systems. The company maintains a dedicated pressure reducing valve portfolio covering applications across steam, water, air, and other fluids, with product offerings spanning direct-acting and pilot-operated designs. Its integrated manufacturing capabilities extend from casting through final product completion, enabling control over product quality and configuration. Yoshitake also operates through an international group network, supporting product supply and technical services across multiple markets.
Key Pressure Reducing Valve Companies
The following key companies have been profiled for this study on the pressure reducing valve market.
-
Spirax Sarco
-
Yoshitake
-
Watts Water Technologies
-
BERMAD
-
CLA-VAL
-
Emerson (Fisher)
-
SAMSON
-
TLV
-
Honeywell
-
Goetze KG
-
Cashco
-
Jordan Valve
-
Kane Kogyo
-
Hyperr Valves
-
Flowcen
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Spirax Sarco; Yoshitake; Watts Water Technologies; BERMAD; CLA-VAL; SAMSON; Emerson (Fisher))
Expand PRV offerings across direct-acting and pilot-operated configurations, pressure ranges, and media services.
Invest in product engineering, manufacturing capabilities, certifications, global distribution, and aftermarket services.
Established brands, extensive installed bases, and broad customer relationships across industrial and infrastructure applications.
Strong manufacturing scale, pressure-control expertise, and global sales and service networks.
Higher costs associated with manufacturing, product development, certification, and global service operations.
Larger organizational structures can increase development complexity for specialized or low-volume PRV configurations.
Emerging & Regional Players (e.g., TLV; Goetze KG; Cashco; Jordan Valve; Kane Kogyo; Hyperr Valves, Flowcen)
Focus on specialized PRV configurations, customized pressure-control solutions, and targeted media or end-use applications.
Strengthen regional presence through application engineering, distributor partnerships, responsive customer support, and aftermarket services.
Greater flexibility in addressing application-specific pressure, temperature, flow, and media requirements.
Focused product development and closer customer engagement can support faster responses to niche market requirements.
Smaller manufacturing scale and geographic reach can restrict participation in large multinational projects.
Limited resources may constrain international expansion, certification programs, and development of broader PRV portfolios.
Recent Developments
-
In July 2026: Parker Hannifin launched the PE06M proportional pressure reducing valve series for hydraulic pressure-control applications. The direct-operated valve is designed to regulate downstream pressure with rapid response and low hysteresis. It supports flow rates of up to 40 L/min and inlet pressures of up to 350 bar, with multiple coil and connector configurations. The valve is intended for applications including force and torque control, secondary pressure circuits, and hydraulic braking systems.
-
In June 2026: Genebre launched a new diaphragm pressure reducing valve designed for residential, commercial, and industrial water systems. The valve regulates downstream pressure under varying inlet conditions and features an adjustable handwheel with an integrated pressure indicator, removable cartridge, and stainless-steel filter. Available in sizes from ½ inch to 2 inches and pressure ratings up to PN25, the product expands Genebre’s pressure-control portfolio for water applications.
Pressure Reducing Valve Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.5 billion
Estimated market size in 2026
USD 3.6 billion
Projected market size by 2033
USD 4.8 billion
Growth rate
CAGR of 4.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Type, media, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; UK; Italy; Spain; France; China; Japan; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Spirax Sarco; Yoshitake; Watts Water Technologies; BERMAD; CLA-VAL; Emerson (Fisher); SAMSON; TLV; Honeywell; Goetze KG; Cashco; Jordan Valve; Kane Kogyo; Hyperr Valves; Flowcen
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pressure Reducing Valve Market Report Segmentation
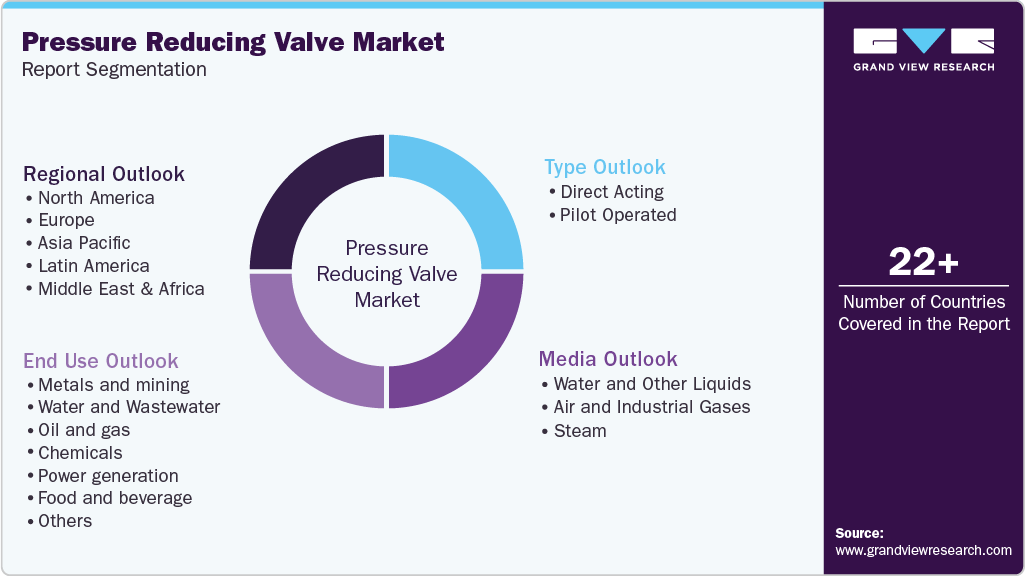
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the pressure reducing valve market based on type, media, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Direct Acting
-
Pilot Operated
-
-
Media Outlook (Revenue, USD Billion, 2021 - 2033)
-
Water and Other Liquids
-
Air and Industrial Gases
-
Steam
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Metals and mining
-
Water and Wastewater
-
Oil and gas
-
Chemicals
-
Power generation
-
Food and beverage
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The pressure reducing valve market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pressure reducing valve segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue Capture Definition
Direct Acting
Revenue generated from the sale of direct-acting pressure reducing valves, including complete valve units and assemblies supplied for pressure regulation applications.
Pilot Operated
Revenue generated from the sale of pilot-operated pressure reducing valves, including valves equipped with pilot control mechanisms and associated components.
Media
Revenue Capture Definition
Water and Other Liquids
Revenue generated from the sale of pressure reducing valves designed and supplied for water and other liquid media, including process liquids and compatible fluids.
Air and Industrial Gases
Revenue generated from the sale of pressure reducing valves designed and supplied for compressed air and industrial gas services, including nitrogen, oxygen, and other industrial gases.
Steam
Revenue generated from the sale of pressure reducing valves designed and supplied for steam-service applications in industrial and process systems.
End Use
Revenue Capture Definition
Metals and Mining
Revenue generated from the sale of pressure reducing valves to metals processing, mining, mineral processing, and related facilities.
Water and Wastewater
Revenue generated from the sale of pressure reducing valves to municipal and industrial water distribution, treatment, and wastewater facilities.
Oil and Gas
Revenue generated from the sale of pressure reducing valves to upstream, midstream, refining, processing, and other oil and gas industry facilities.
Chemicals
Revenue generated from the sale of pressure reducing valves to chemical manufacturing and processing facilities for process and utility systems.
Power Generation
Revenue generated from the sale of pressure reducing valves to power generation facilities, including thermal, nuclear, renewable, and other power plants.
Food and Beverage
Revenue generated from the sale of pressure reducing valves to food and beverage processing and manufacturing facilities.
Others
Revenue generated from the sale of pressure reducing valves to other industries, including pharmaceuticals, pulp and paper, textiles, general manufacturing, and commercial facilities.
Estimation Model
Layer Name
Key Question
Description
Pressure Control Demand Layer
Where are pressure reducing valves required?
Analyze demand for pressure reducing valves across water and other liquids, air and industrial gases, and steam systems. Evaluate pressure regulation requirements for fluid distribution, process operations, utility systems, equipment protection, and downstream pressure stabilization to establish the addressable demand for PRVs.
Industrial & Infrastructure Capacity Layer
Where is new PRV demand being created?
Assess investments in new industrial facilities, production capacity expansions, water and wastewater infrastructure, processing facilities, power plants, and other pressure-control systems. Evaluate new installations, plant expansions, system modernization, maintenance, and replacement of existing valves to determine incremental PRV demand.
Segment Adoption Layer
How is demand distributed across the market segments?
Analyze market demand across the three defined segmentation dimensions: type, media, and end use. For type, assess direct-acting and pilot-operated adoption based on flow, pressure-control requirements, and system complexity. For media, evaluate water and other liquids, air and industrial gases, and steam, while end-use adoption is assessed across metals and mining, water and wastewater, oil and gas, chemicals, power generation, food and beverage, and other industries.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual sales of new and replacement pressure reducing valves across type, media, end use, and region. Convert estimated valve demand into revenue using product-specific selling prices, valve size, pressure rating, material, configuration, flow capacity, and technical specifications. Validate estimates using manufacturer revenues, product portfolios, shipment volumes, distributor sales, and project activity.
Customization Table
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
A competitive benchmarking analysis was conducted by evaluating leading pressure reducing valve manufacturers based on product portfolio, direct-acting and pilot-operated offerings, pressure and flow ranges, valve sizes, materials, media compatibility, control capabilities, application coverage, customization capabilities, manufacturing footprint, aftermarket services, strategic initiatives, and market positioning.
The benchmarking provided a clear understanding of competitive strengths, product differentiation, pressure-control technologies, portfolio breadth, innovation trends, and supplier positioning, enabling stakeholders to evaluate competitors and formulate effective product and market strategies.
Regional Segmentation
A comprehensive regional assessment was provided across key markets, analyzing pressure reducing valve demand across water and other liquids, air and industrial gases, and steam. The analysis considered industrial capacity additions, water and wastewater infrastructure, oil and gas and chemical processing activity, power generation investments, manufacturing expansion, replacement requirements, and regional adoption patterns influencing PRV sales.
The regional analysis helped stakeholders identify high-potential markets, evaluate regional PRV sales opportunities, prioritize geographic expansion, and align product portfolios with regional pressure-control requirements and industry demand.
Opportunity Assessment
A detailed opportunity assessment was conducted by evaluating demand across direct-acting and pilot-operated valves, water and liquid, air and industrial gas, and steam services, along with metals and mining, water and wastewater, oil and gas, chemicals, power generation, food and beverage, and other end uses. The assessment considered new installations, capacity additions, modernization, replacement demand, and adoption of advanced pressure-control solutions.
The assessment enabled stakeholders to prioritize attractive product, media, and end-use segments, identify emerging PRV sales opportunities, support investment planning, and align product development and commercialization strategies with evolving pressure-control requirements.
Frequently Asked Questions About This Report
Asia Pacific dominated the global pressure reducing valve market with a revenue share of 36.0% in 2025, driven by industrial expansion and infrastructure development across water, manufacturing, energy, chemical, and oil and gas applications.
The water and other liquids segment dominated the market with a revenue share of 48.6% in 2025, reflecting broad use across water distribution, wastewater, and industrial liquid-handling systems.
The oil and gas segment held the largest revenue share in 2025, reflecting pressure regulation requirements across pipelines, processing facilities, and utility systems.
Market growth is driven by investments in water and wastewater infrastructure, industrial processing facilities, energy projects, and fluid-handling systems, along with the need for controlled downstream pressure, equipment protection, and reliable system operation.
Key companies include Spirax Sarco, Yoshitake, Watts Water Technologies, BERMAD, CLA-VAL, Emerson (Fisher), SAMSON, TLV, Honeywell, Goetze KG, Cashco, Jordan Valve, Kane Kogyo, Hyperr Valves, and Flowcen.
The global pressure reducing valve market size was valued at USD 3.5 billion in 2025 and is projected to reach USD 3.6 billion in 2026.
The global pressure reducing valve market is projected to grow at a CAGR of 4.3% from 2026 to 2033, reaching USD 4.8 billion by 2033.
The pilot operated segment is projected to grow at a CAGR of 3.6% during the forecast period, driven by its suitability for applications requiring precise pressure regulation and higher flow-handling capacity.
The water and other liquids segment dominated the market with a revenue share of 48.6% in 2025, reflecting broad use across water distribution, wastewater, and industrial liquid-handling systems.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


