
- Home
- »
- Plastics, Polymers & Resins
- »
-
PVC Additives Market Size & Share Report, 2026-2033GVR Report cover

PVC Additives Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Stabilizers, Impact Modifiers, Processing Aids, Lubricants, Plasticizers), By End-use (Building & Construction, Transportation, Packaging), By Region, And Segment Forecasts
Market Size, 2025
$7.2BMarket Estimate, 2026
$7.6BMarket Forecast, 2033
$10.6BCAGR, 2026–2033
4.9%PVC Additives Market Summary
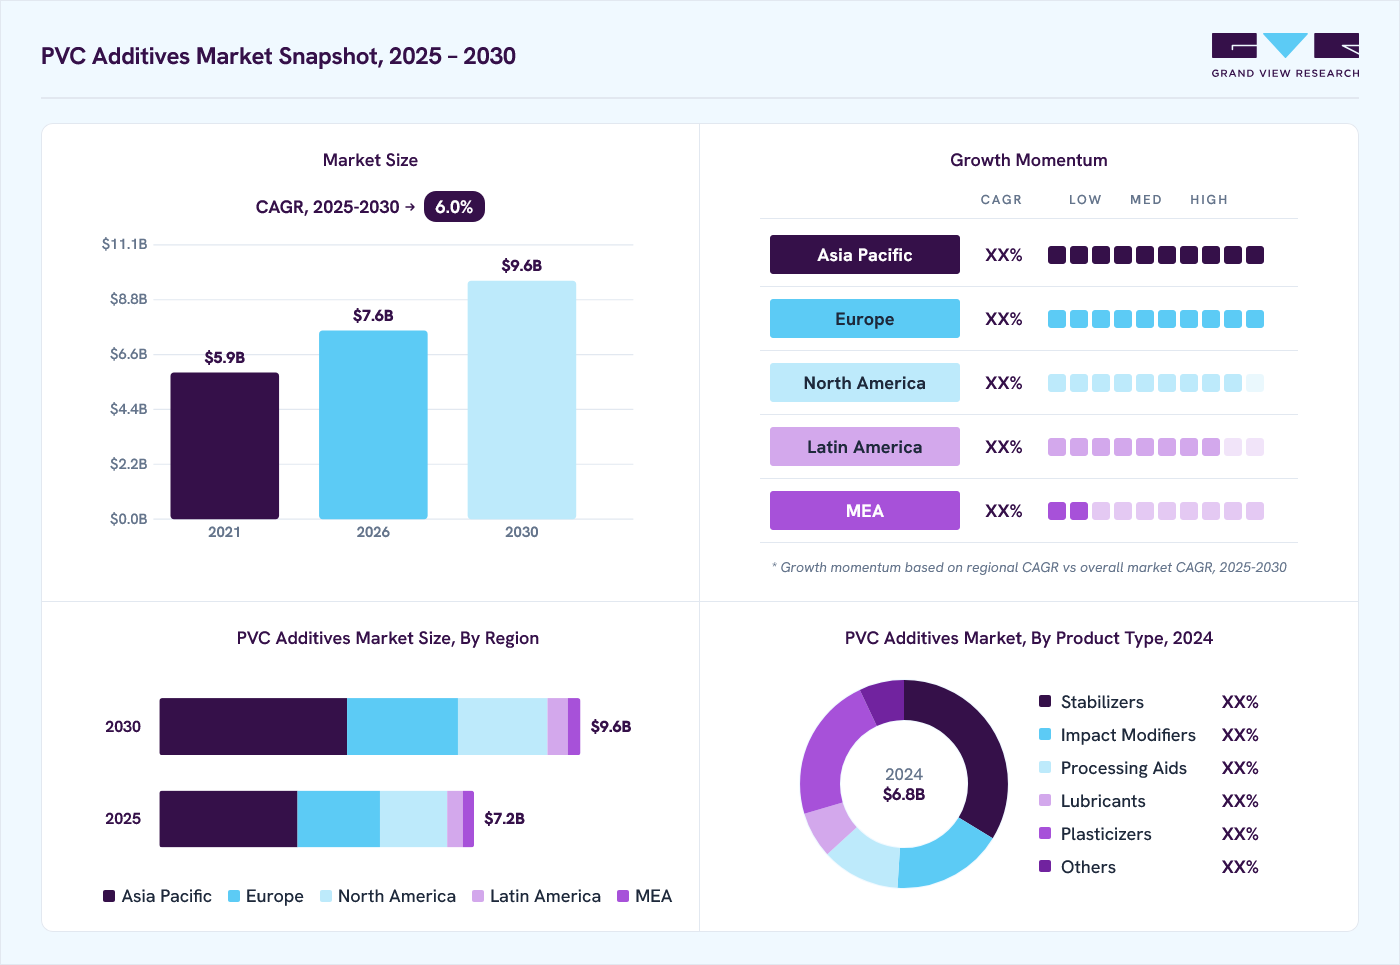
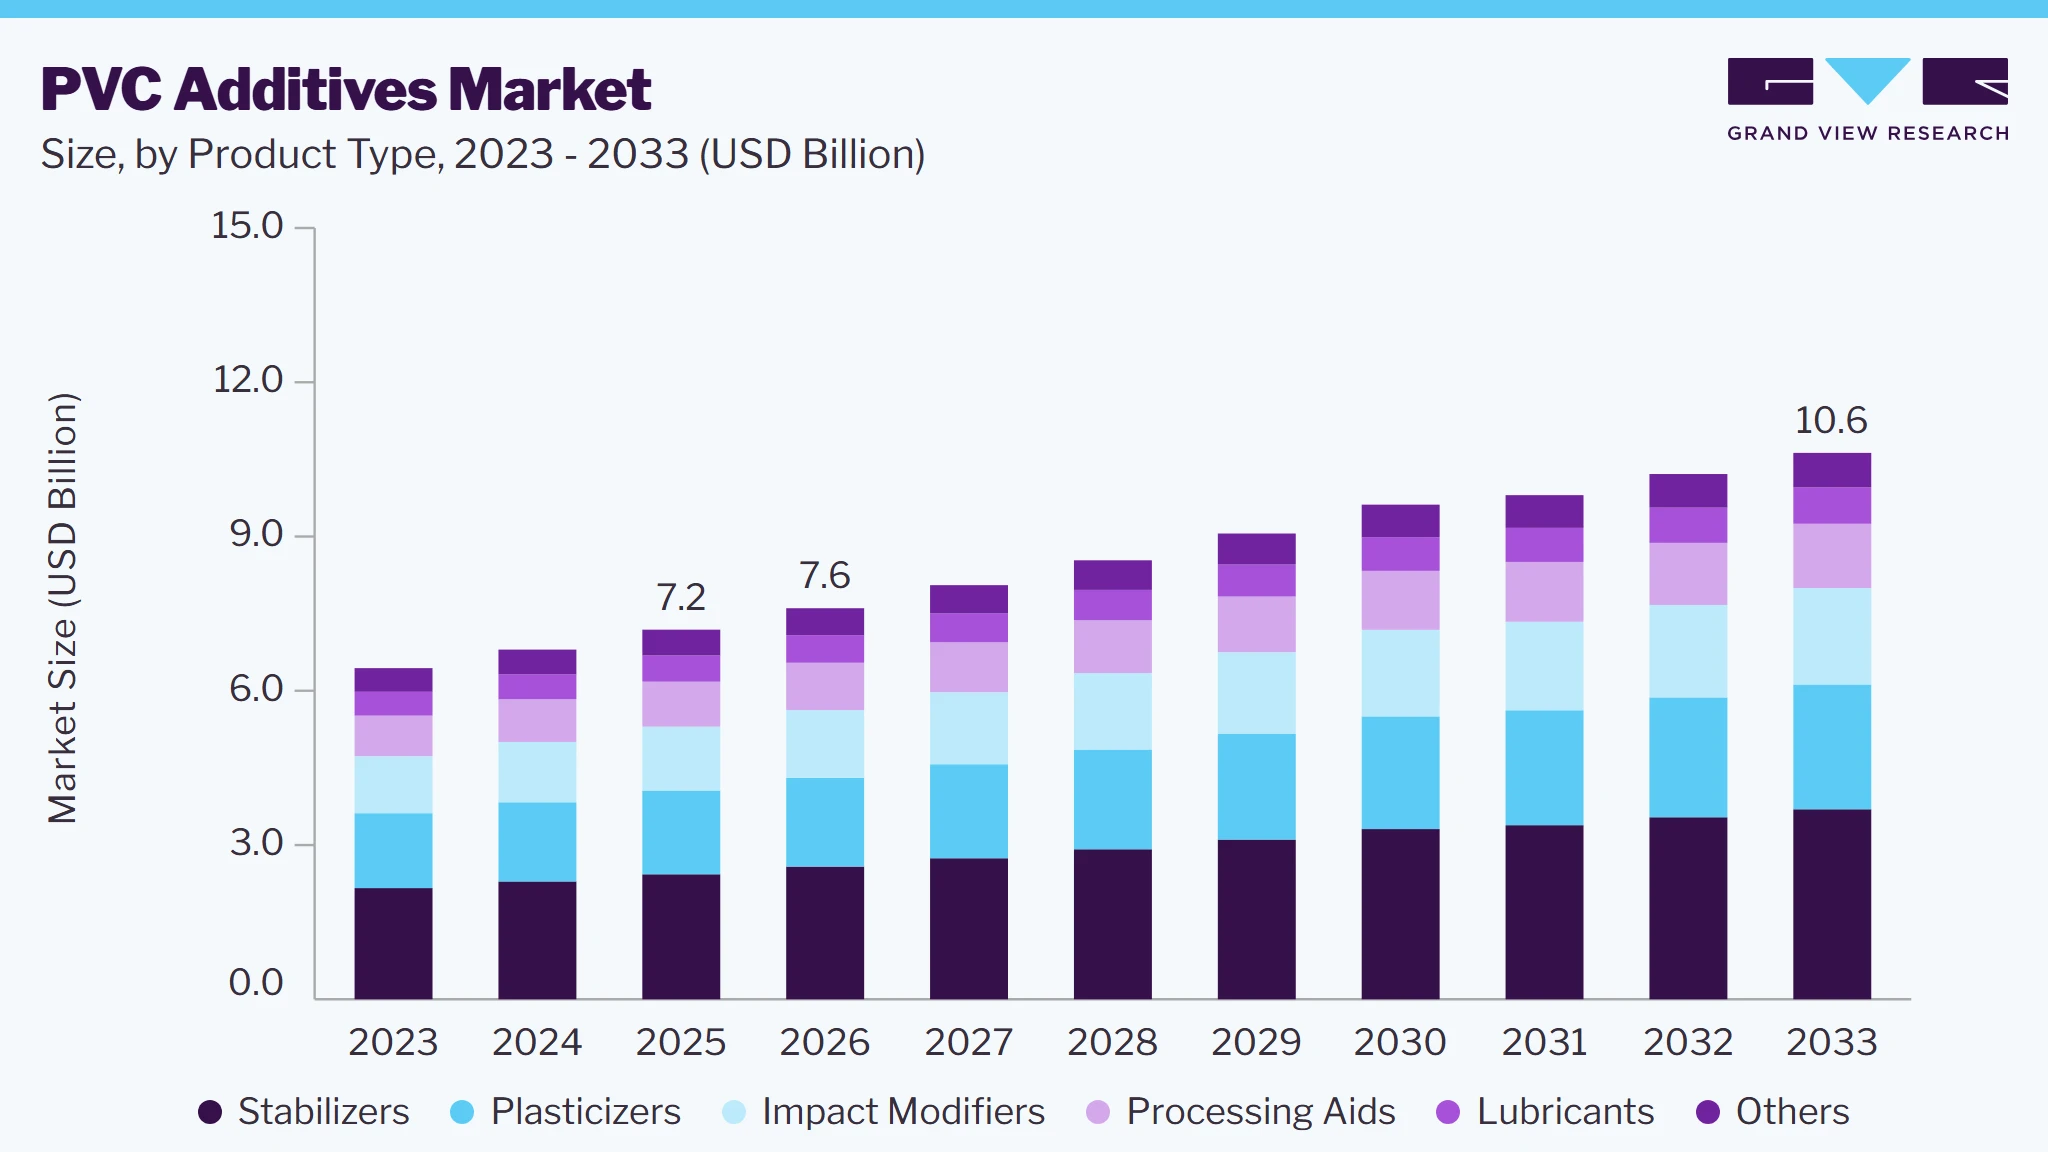
The global PVC additives market size was valued at USD 7.2 billion in 2025 and is projected to grow from USD 7.6 billion in 2026 to USD 10.6 billion by 2033, at a CAGR of 4.9% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 43.9% in 2025. Growing demand from construction, infrastructure, packaging, healthcare, and consumer goods industries, together with tightening environmental regulations and increasing preference for recyclable, high-performance PVC formulations, is accelerating PVC additives adoption.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Stabilizers PVC additives segment led the market with the largest revenue share of 33.8% in 2025.
- By end use: Building and construction PVC additives segment led the market with the largest revenue share of 38.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (43.9% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.2 Billion
- Estimated market size in 2026: USD 7.6 Billion
- Projected market size by 2033: USD 10.6 Billion
- CAGR (2026-2033): 4.9%
Prism AI by Grand View Research Free to tryAsk a question about the PVC additives marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Continuous advancements in stabilizer, plasticizer, and processing aid technologies, expanding sustainable additive portfolios, and rising investments in recyclable and low-emission PVC solutions are further strengthening demand for durable, weather-resistant, and application-specific PVC products across developed and emerging markets As urbanization accelerates in emerging economies-particularly in regions like Asia Pacific, Africa, and Latin America-there is an increasing need for affordable, durable, and versatile building materials. PVC, being cost-effective, lightweight, and durable, is a preferred material in End Uses like pipes, window profiles, flooring, roofing, and siding. PVC, when combined with stabilizers, impact modifiers, and other additives, offers enhanced performance in terms of UV stability, durability, and weather resistance. This makes it an ideal material for construction projects that require longevity and reduced maintenance
 To learn more about this report, Download Free Sample Report
The growing demand for high-performance, long-lasting construction materials means that additives such as stabilizers, impact modifiers, and lubricants are becoming more important to enhance the performance of PVC products. For instance, stabilizers improve the resistance of PVC to UV degradation, allowing it to withstand harsh outdoor conditions for longer periods, a key feature in construction projects.
Globally, the packaging industry remains a significant consumer of PVC additives. PVC is widely used in both rigid and flexible packaging end uses, including food and beverage packaging, medical packaging, and consumer goods packaging. Additives like plasticizers, stabilizers, and lubricants play a key role in improving the flexibility, clarity, durability, and processability of PVC films, sheets, and containers. The increasing demand for high-quality packaging materials that provide safety, protection, and aesthetic appeal is driving the market for PVC additives.
With growing consumer concerns over product safety, shelf life, and environmental sustainability, PVC packaging solutions are becoming increasingly popular. Additives that improve the recyclability of PVC, or reduce toxic emissions during manufacturing and disposal, are in demand, particularly in developed regions where environmental regulations are stricter. The rise in e-commerce and packaged food consumption, especially in regions like North America and Europe, is contributing to the growing demand for PVC additives in packaging.
Additionally, the rise of sustainable packaging materials, combined with technological innovations to create more eco-friendly and efficient packaging solutions, has made PVC additives essential to improve the performance of PVC-based packaging. This trend is expected to continue as global brands aim to reduce their environmental footprint.
Advances in PVC additive formulations are enabling manufacturers to tailor additives for specific End Uses across different industries. The customization of PVC additives to meet the performance requirements of various sectors-such as automotive, medical devices, and electronics-has expanded the use of PVC in diverse markets. Innovations in additives are also improving the processing efficiency of PVC, enabling manufacturers to produce more durable and cost-effective products.
As governments around the world implement stricter environmental regulations, industries are seeking safer and more sustainable materials. The growing focus on the environmental impact of PVC, particularly regarding plasticizers and stabilizers, has led to the development of additives that improve the recyclability of PVC and reduce harmful emissions during production. This trend toward sustainability is helping to drive the demand for more eco-friendly PVC additives that comply with global environmental standards.
With the global push for a circular economy, PVC’s ability to be recycled has become an important factor in its adoption. Additives that improve PVC recyclability, such as those that reduce the release of toxic substances during the recycling process, are becoming increasingly important. As industries move toward more sustainable and recyclable solutions, the demand for additives that support these efforts is rising.
Market Dynamics
PVC additive demand is anchored by construction-led PVC consumption, especially in pipes, window profiles, flooring, siding, roofing, and electrical conduit. Asia Pacific remains the largest demand center, while North America and Europe show strong specification-led demand tied to energy-efficient building materials and stricter compliance needs. The market is commercially concentrated around large suppliers that combine formulation know-how, regional manufacturing, and customer qualification support. Stabilizers hold the leading role because they protect PVC from heat, UV, and weathering, while product development is increasingly shaped by recyclability, low-emission chemistry, and application-specific performance.
The most important driver is the sustained use of PVC in construction systems that require long service life and low maintenance. Pipes, profiles, siding, roofing, flooring, and conduits all depend on additives to deliver thermal stability, impact strength, processability, and outdoor durability. As residential, commercial, and infrastructure spending expands, stabilizers and impact modifiers gain higher content intensity because PVC must perform reliably in heat, UV exposure, and moisture-prone settings. This keeps additive loading closely tied to project specifications rather than simple resin consumption.
Demand is further reinforced by urbanization in emerging economies and the shift toward lighter, more affordable building materials. The report also highlights rising demand for eco-friendly additives as customers and regulators favor lower-emission, recyclable PVC systems. That combination supports higher-value formulations rather than commodity grades, especially where compliance, weather resistance, and recycling performance are central purchase criteria. Europe and North America are likely to remain the lead markets for premium grades because sustainability rules are tightening qualification standards. Suppliers with safer chemistry and technical service will capture the upgrade cycle.
The main restraint is the cost and time required to reformulate away from legacy additive systems while maintaining mechanical performance. Environmental and health scrutiny around plasticizers and stabilizers is tightening in Europe and North America, forcing suppliers to invest in testing, approvals, and customer requalification. At the same time, PVC converters remain highly price sensitive and often resist premium additive upgrades unless performance gains are immediate and measurable. This creates a narrow commercial window for suppliers and keeps margins vulnerable when feedstock costs, compliance costs, or substitution pressure rise. Reformulation risk is especially high in applications that already meet minimum specifications.
The clearest opportunity lies in additive systems that improve PVC recyclability, reduce toxic emissions, and support circular construction and packaging uses. Suppliers that can deliver low-migration, low-VOC, and durable formulations for green building materials and recyclable packaging can capture higher-margin demand. This is especially relevant in Europe and other regulated markets where sustainability credentials increasingly influence specification and vendor selection.
Analyst Perspective
PVC additives is moving from a volume-led market to a value-led market shaped by performance, compliance, and sustainability. Construction and infrastructure will remain the core demand base, but packaging, transportation, and medical uses will steadily raise the need for application-specific formulations, especially low-emission and recyclable systems. Over the next 5 to 10 years, the strongest suppliers will be those that combine integrated production, regional formulation support, and regulatory depth with credible sustainability programs and technical partnerships. The market will reward companies that can prove compatibility with recycling streams, reduce toxic chemistry exposure, and tailor performance to local building and safety standards. Pricing pressure, raw material volatility, and requalification costs will continue to challenge margins, but leaders with broad portfolios, strong approvals, and geographic reach should be best positioned to convert compliance and circularity into durable growth.
Product Type Insights
Based on product type, the stabilizers PVC additives segment led the market with the largest revenue share of 33.8% in 2025. One of the primary factors for the growing demand for stabilizers in the PVC additives market is their role in improving the durability and longevity of PVC products. PVC is highly susceptible to degradation when exposed to UV radiation, heat, and oxygen over time. This degradation can lead to discoloration, brittleness, and a reduction in the material’s overall strength. Stabilizers help mitigate these issues by protecting PVC from thermal and UV degradation.
Stabilizers prevent the breakdown of PVC at high temperatures during manufacturing, ensuring that the material retains its mechanical properties after the production process. This is particularly important in industries such as construction, automotive, and electrical wiring, where PVC components need to maintain their performance in high-temperature environments.
Another key factor driving the demand for stabilizers in PVC additives is the growing emphasis on regulatory compliance and safety standards. Various industries, particularly construction and medical End Uses, are subject to strict regulatory guidelines regarding the materials used in their products. PVC, being a synthetic polymer, can release harmful substances when it degrades or during manufacturing processes. This has led to increased demand for stabilizers that ensure PVC remains safe, stable, and compliant with environmental and health regulations.
Stringent regulations in the automotive and medical sectors require PVC to be free from harmful substances and to meet high-performance standards. As a result, manufacturers are increasingly relying on stabilizers to ensure their PVC products comply with these regulations. The demand for stabilizers that enable PVC to meet these stringent standards is growing, particularly in developed regions with strict regulatory frameworks such as Europe and North America.
End-use Insights
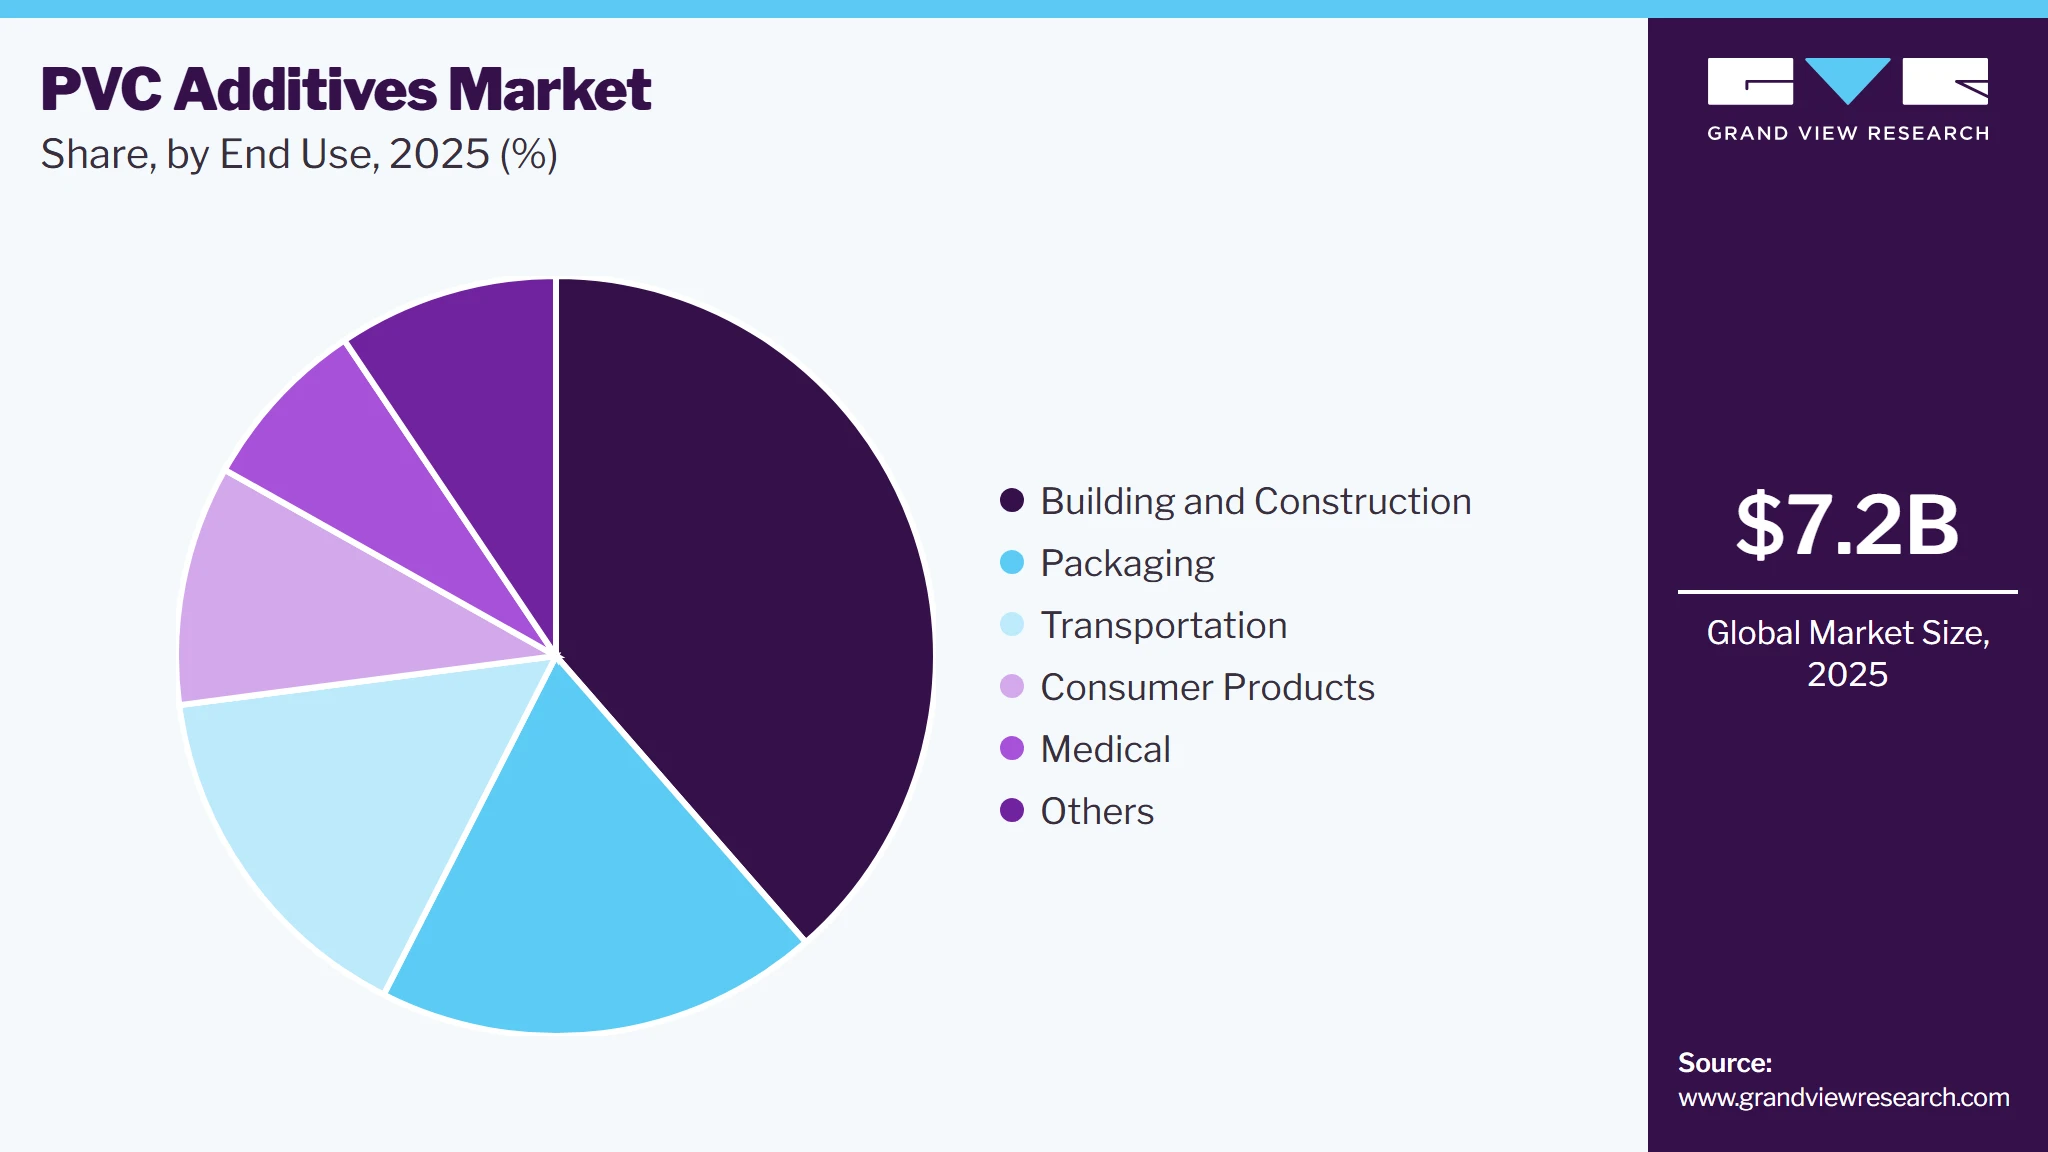
Based on end use, the building and construction PVC additives segment led the market with the largest revenue share of 38.6% in 2025. The demand for PVC stabilizers in the building and construction industry is growing significantly due to a combination of factors related to performance, durability, sustainability, and regulatory compliance. PVC (polyvinyl chloride) is widely used in various construction End Uses such as pipes, window profiles, siding, flooring, roofing, and electrical conduits due to its versatility, cost-effectiveness, and long service life. Stabilizers play a crucial role in enhancing these properties, making them essential for the continued growth of PVC in construction.
 To learn more about this report, Download Free Sample Report
Another key driver for the growing demand for stabilizers in the building and construction industry is the need for PVC to resist weathering and perform optimally in various environmental conditions. PVC is frequently used in outdoor End Uses, such as piping, window profiles, siding, and roofing, where it is exposed to elements like moisture, temperature fluctuations, and pollutants. Additionally, PVC is inherently resistant to water, making it ideal for use in pipes and siding. However, without proper stabilization, moisture over time can still impact the material's surface, leading to discoloration and surface degradation. Stabilizers help to maintain the material's resistance to moisture and prevent damage caused by prolonged exposure to wet conditions.
Furthermore, governments and regulatory bodies worldwide have implemented stringent fire safety standards for building materials. For example, the EU and North America have regulations that require construction materials to pass specific fire performance tests. Stabilizers that enhance fire resistance are essential for ensuring PVC products meet these standards. As fire safety regulations become stricter, demand for flame-retardant stabilizers in PVC products used in construction End Uses is growing.
PVC is one of the most cost-effective materials used in construction, and its widespread use is driven by its affordability compared to other materials such as metal or wood. However, PVC needs to meet certain performance criteria to be competitive in the construction sector. Stabilizers are essential in achieving the desired performance attributes of PVC, such as flexibility, impact resistance, and processability.
Region Insights
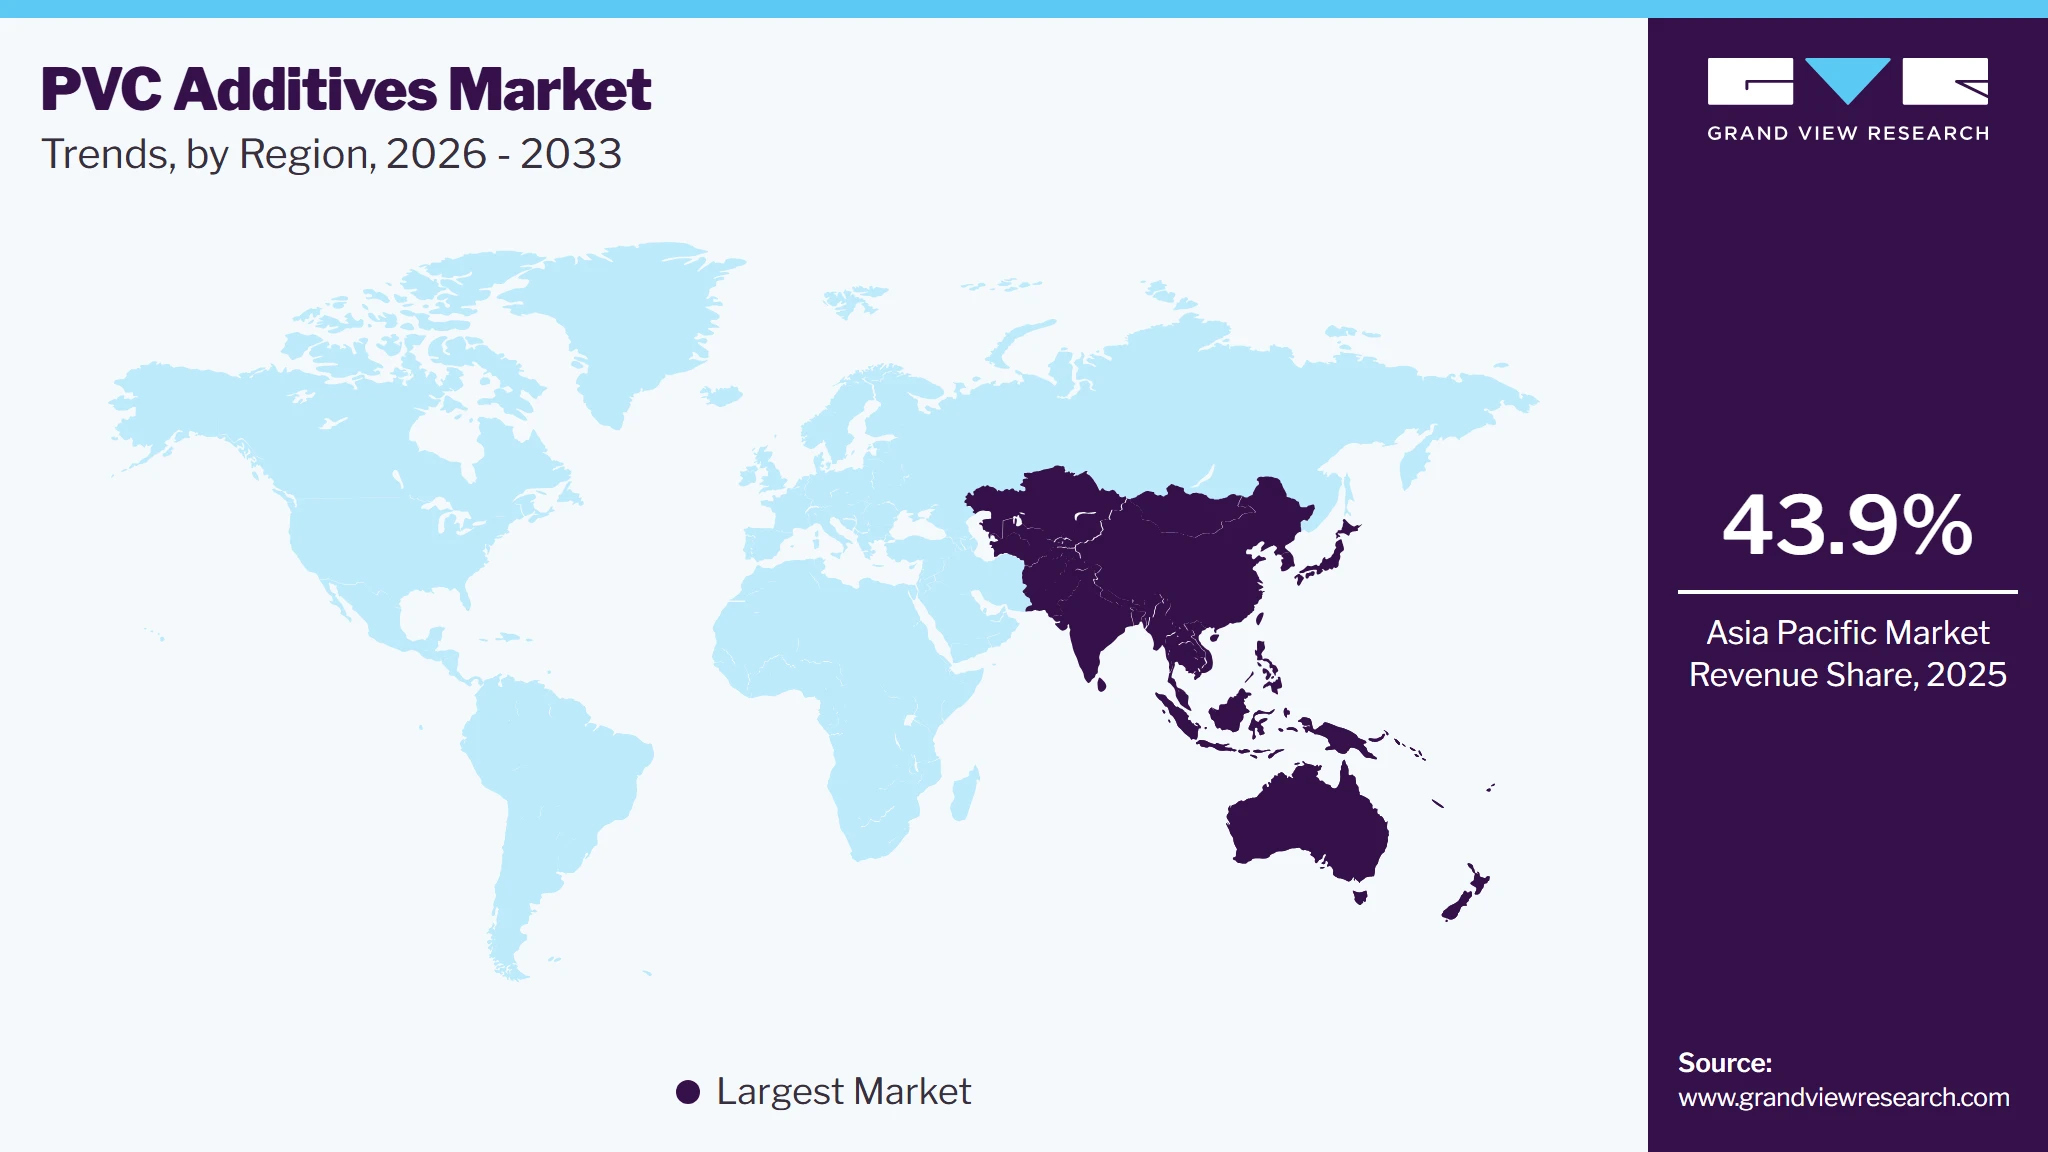
Asia Pacific dominated the PVC additives market with the largest revenue share of 43.9% in 2025. This region has dominated the global market due to a combination of factors including strong industrial growth, increasing urbanization, the presence of leading manufacturing hubs, and the expanding demand from various end use industries. The APAC region, comprising countries like China, India, Japan, South Korea, and Southeast Asia, has witnessed tremendous economic growth over the past few decades, which has made it a key player in the market.
 To learn more about this report, Download Free Sample Report
China PVC Additives Market Trends
The PVC additives market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China's PVC additives marketgrowthis primarily driven by the major global manufacturing hubs, producing a wide range of PVC products. The availability of cheap labor, favorable government policies, and robust infrastructure have led to the expansion of manufacturing facilities. As PVC is used in a variety of industries, such as electrical cables, pipes, flooring, and window profiles, the demand for PVC additives that improve the performance of these products is high. Additionally, the increasing disposable income of the middle class in countries like China and India is also fueling the demand for better housing, infrastructure, and consumer goods. This translates into a higher demand for PVC-based products, such as pipes, flooring, and insulation materials. The demand for high-quality, long-lasting PVC products, which rely on additives for enhanced properties, continues to grow.
North America PVC Additives Market Trends
In North America, the demand for PVC additives is growing due to the robust construction and infrastructure development, alongside advancements in manufacturing processes. With the region's focus on sustainable building materials and improved energy efficiency, the demand for high-performance PVC products, such as pipes, window profiles, and flooring, is increasing. Additionally, stricter environmental regulations are encouraging the use of eco-friendly PVC additives, driving innovation and higher adoption rates within industries like construction, automotive, and packaging.
The PVC additives industry in the U.S. is driven by the growth of the construction and housing markets, where PVC is favored for its durability, cost-effectiveness, and versatility. With an increasing emphasis on infrastructure modernization and the expansion of residential and commercial buildings, the need for high-performance PVC products is rising. Additionally, the shift toward sustainable building materials, supported by green construction initiatives and government policies, is pushing the demand for eco-friendly PVC additives, making them crucial for meeting regulatory standards and achieving energy-efficient construction goals.
Europe PVC Additives Market Trends
In Europe, the demand for PVC additives is expanding as a result of stringent environmental regulations and a growing emphasis on sustainability. The region's commitment to green building standards and reducing carbon footprints has led to increased demand for eco-friendly PVC products in the construction and infrastructure sectors. Additionally, the automotive industry's shift toward lightweight and durable materials, combined with innovations in the packaging industry, is pushing the need for additives that enhance PVC's performance. Europe's focus on recycling and circular economy practices also drives demand for additives that improve the recyclability and environmental footprint of PVC materials.
PVC Additives market in Germany is boosted by the country’s strong automotive and construction sectors, where high-performance materials are required to meet stringent regulations and quality standards. The automotive industry in Germany relies on PVC for lightweight and durable components, and additives are crucial for ensuring the material's functionality in this context. Furthermore, Germany's commitment to environmental sustainability and the circular economy has led to a greater focus on recycling, with additives playing a key role in improving the recyclability and eco-friendliness of PVC products, particularly in the construction and packaging industries.
Key PVC Additives Company Insights
The competitive landscape of the PVC additives industry is characterized by the presence of several key global and regional players that dominate the production and supply of various additives such as stabilizers, plasticizers, impact modifiers, lubricants, and processing aids. Major companies are prominent in the market, offering a wide range of high-performance products to meet the diverse needs of industries like construction, automotive, packaging, and healthcare. These players focus on innovation, expanding product portfolios, and developing eco-friendly and sustainable additives to comply with growing environmental regulations.
Additionally, regional players are actively investing in production facilities to strengthen their market position and expand their geographic reach. Strategic partnerships, acquisitions, and collaborations are common as companies seek to enhance their technological capabilities, enter new markets, and cater to evolving customer demands for high-quality and environmentally friendly PVC additives. As the demand for PVC additives grows, particularly in emerging economies, competition is intensifying, with companies focusing on differentiation through R&D, sustainability initiatives, and product customization to maintain a competitive edge in the global market.
-
In September 2023, BASF SE launched the industry’s first biomass balance offerings for plastic additives. This new range of plastic additives contributes to the replacement of fossil feedstock with renewable raw materials according to a certified biomass balance approach.
-
In October 2022, Clariant launched new additives at K 2022 to support plastics sustainable evolution. This anti-scratch additive for PP & TPO formulations boosts reuse potential of plastics used in consumer End Uses.
Key PVC Additives Companies
The following key companies have been profiled for this study on the PVC additives market.
-
AkzoNobel
-
Clariant
-
SABIC
-
Solvay
-
LyondellBasell
-
Formosa Plastics
-
Ineos
-
BASF
-
Lanxess
-
DuPont
-
LG Chem
-
Mitsubishi Chemical
-
Chevron Phillips Chemical
-
Dow
-
Evonik
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players ( Clariant, SABIC, Solvay, LyondellBasell, Formosa Plastics, Ineos, BASF, DuPont, LG Chem, Mitsubishi Chemical, Chevron Phillips Chemical, Dow, Evonik)
- Expand integrated additive systems linked to upstream petrochemicals and downstream compounder support.
- Protect key accounts through formulation customization, compliance support, and local technical service.
- Invest in low-emission, recyclable, and high-stability chemistries for construction and packaging.
- Scale and global supply continuity.
- Broad regulatory and formulation expertise.
- Strong customer qualification and brand trust.
- Higher legacy portfolio exposure.
- Slower changeover to niche formulations.
- Margin pressure in commoditized grades.
Emerging Players (AkzoNobel, Lanxess)
- Target specialty or application-specific additives where technical service matters more than scale.
- Use partnerships, distributors, and tolling to extend reach without heavy capital outlay.
- Focus on differentiated, compliance-friendly products for selective end uses.
- Faster product adaptation.
- Leaner decision making and shorter commercialization cycles.
- Strong specialty chemical capabilities.
- Smaller installed customer base.
- Less feedstock integration and pricing leverage.
- Greater dependence on partners for scale and market access.
PVC Additives Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.2 billion
Estimated market size in 2026
USD 7.6 billion
Projected market size by 2033
USD 10.6 billion
Growth rate
CAGR of 4.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, end use, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, France, Italy, UK, China, Japan, India, Australia, Brazil, Argentina, Colombia, Saudi Arabia, UAE, and South Africa
Key companies profiled
AkzoNobel; Clariant; SABIC; Solvay; LyondellBasell; Formosa Plastics; Ineos; BASF; Lanxess; DuPont; LG Chem; Mitsubishi Chemical; Chevron Phillips Chemical; Dow; Evonik
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase—addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global PVC Additives Market Report Segmentation
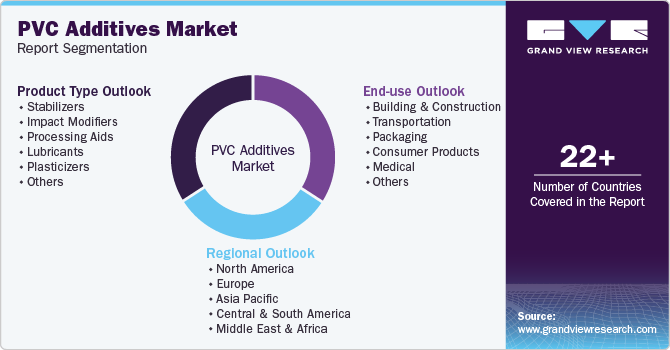
This report forecasts revenue growth at a global level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global PVC additives market report based on product type, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Stabilizers
-
Impact Modifiers
-
Processing Aids
-
Lubricants
-
Plasticizers
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Building and Construction
-
Transportation
-
Packaging
-
Consumer Products
-
Medical
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The PVC additives market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each PVC additives segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Product Type
Revenue capture definition
Stabilizers
Revenue is captured through heat, UV, and weather stabilization packages sold to compounders and converters for pipes, profiles, wiring, and outdoor PVC products.
Impact Modifiers
Revenue is generated from modifiers that improve toughness, crack resistance, and impact tolerance in rigid PVC used in construction and molded parts.
Processing Aids
Revenue comes from additives that improve melt flow, fusion, surface finish, and extrusion stability during compounding, calendaring, and molding.
Lubricants
Revenue is earned through internal and external lubricant systems that control friction, release, and die build-up in PVC processing lines.
Plasticizers
Revenue is captured from flexible PVC formulations where plasticizers are specified for cables, films, flooring, medical products, and soft goods.
Others
Revenue includes specialty chemistries such as flame retardants, antioxidants, and niche formulation packages sold for application-specific performance needs.
Segment – End Use
Revenue capture definition
Building and Construction
Revenue is captured through additives used in pipes, profiles, siding, flooring, roofing, conduits, and other long-life building systems.
Transportation
Revenue comes from additives specified into interior trim, wire and cable, sealing, and other transportation parts that require durability and flexibility.
Packaging
Revenue is generated from additive demand in rigid and flexible films, sheets, trays, and containers where clarity, processability, and shelf-life matter.
Consumer Products
Revenue is earned from household goods, furniture, toys, appliances, and molded consumer items that require appearance, color stability, and handling performance.
Medical
Revenue is captured through additives used in medical tubing, bags, and devices where purity, flexibility, and regulatory conformity are essential.
Others
Revenue covers electrical, industrial, agricultural, and specialty uses that require tailored PVC formulations not covered by the core end-use groups.
Estimation Model
Layer No.
Layer Name
Key Question
Description
1
Demand Layer
Where does demand originate?
It captures additive consumption across pipes, profiles, films, and molded goods, linking revenue directly to PVC end-use intensity.
2
Formulation Layer
How is value created?
It translates application requirements into stabilizer, modifier, plasticizer, and lubricant demand, reflecting value capture inside the compound.
3
Regional Layer
Which regions drive demand?
It weights demand by Asia Pacific, Europe, and North America, where regulation, construction spend, and qualification standards differ.
4
Supplier Layer
Who captures market revenue?
It reconciles company shares through integrated capacity, distribution reach, and customer approvals, avoiding double counting across channels.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-level regional coverage
Expanded the regional view into country-level demand commentary, with focus on construction, packaging, and transportation uses, while reflecting the different regulatory and supply chain conditions across mature and emerging PVC markets.
Improves localization and supports market entry prioritization.
Segment-level revenue logic
Added segment definitions for product type and end-use that explain where revenue is captured, how additives are specified into PVC formulations, and why each segment commands distinct commercial value.
Clarifies monetization and strengthens segmentation analysis.
Supplier competitive lens
Inserted a mature versus emerging player view with operating strategies, competitive edge, and weaknesses so the market structure can be read alongside supplier positioning and differentiation.
Helps benchmark competitive intensity and supplier readiness.
Frequently Asked Questions About This Report
The Asia Pacific PVC Additives market accounted for the largest share of 43.9% market size in 2025.
China was the leading PVC Additives market and is expected to grow at a compound annual growth rate of 5.5%.
Based on end use, the building and construction segment accounted for the largest share of 38.6% market size in 2025. Growing demand for residential, commercial, and infrastructure construction, increasing investments in urban development, and rising preference for durable, low-maintenance building materials, together with advances in heat stabilization technologies and high-performance PVC additive formulations, are accelerating PVC additives adoption for pipes, window profiles, roofing, siding, flooring, electrical conduits, and long-life construction applications.
The medical segment, based on end use, is expected to grow at a CAGR of 5.8% for the forecast period.
The stabilizers PVC additives industry led the PVC additives product type market in 2025 with a 33.8% share. Growing demand from pipes, window profiles, siding, roofing, wire and cable, and flooring applications, coupled with stricter environmental regulations, increasing adoption of calcium-zinc and organic stabilizer systems, and advances in heat and UV stabilization technologies, is accelerating stabilizer adoption for durable, weather-resistant, recyclable, and high-performance PVC formulations across construction, electrical, packaging, and consumer goods industries.
The global PVC additives market was estimated at around USD 7.2 billion in the year 2025 and is expected to reach around USD 7.6 billion in 2026.
The global PVC additives market is expected to grow at a compound annual growth rate of 4.9% from 2026 to 2033 to reach around USD 10.6 billion by 2033.
The key players in the PVC additives market include AkzoNobel, Clariant, SABIC, Solvay, LyondellBasell, Formosa Plastics, Ineos, BASF, Lanxess, DuPont, LG Chem, Mitsubishi Chemical, Chevron Phillips Chemical, Dow, and Evonik Industries.
The global PVC Additives market is driven by flourishing construction on a global level. As urbanization accelerates in emerging economies—particularly in regions like Asia-Pacific, Africa, and Latin America—there is an increasing need for affordable, durable, and versatile building materials.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


