
- Home
- »
- Next Generation Technologies
- »
-
Radar Market Size, Share And Trends Report, 2026-2033GVR Report cover

Radar Market (2026 - 2033)
Size, Share & Trends Analysis Report By Platform, By Offering (Components, Service), By Frequency Band, By Range, By End Use (Automotive, Military And Defense), By Region, And Segment Forecasts
Market Size, 2025
$43.3BMarket Estimate, 2026
$46.5BMarket Forecast, 2033
$70.5BCAGR, 2026–2033
6.1%Radar Market Summary
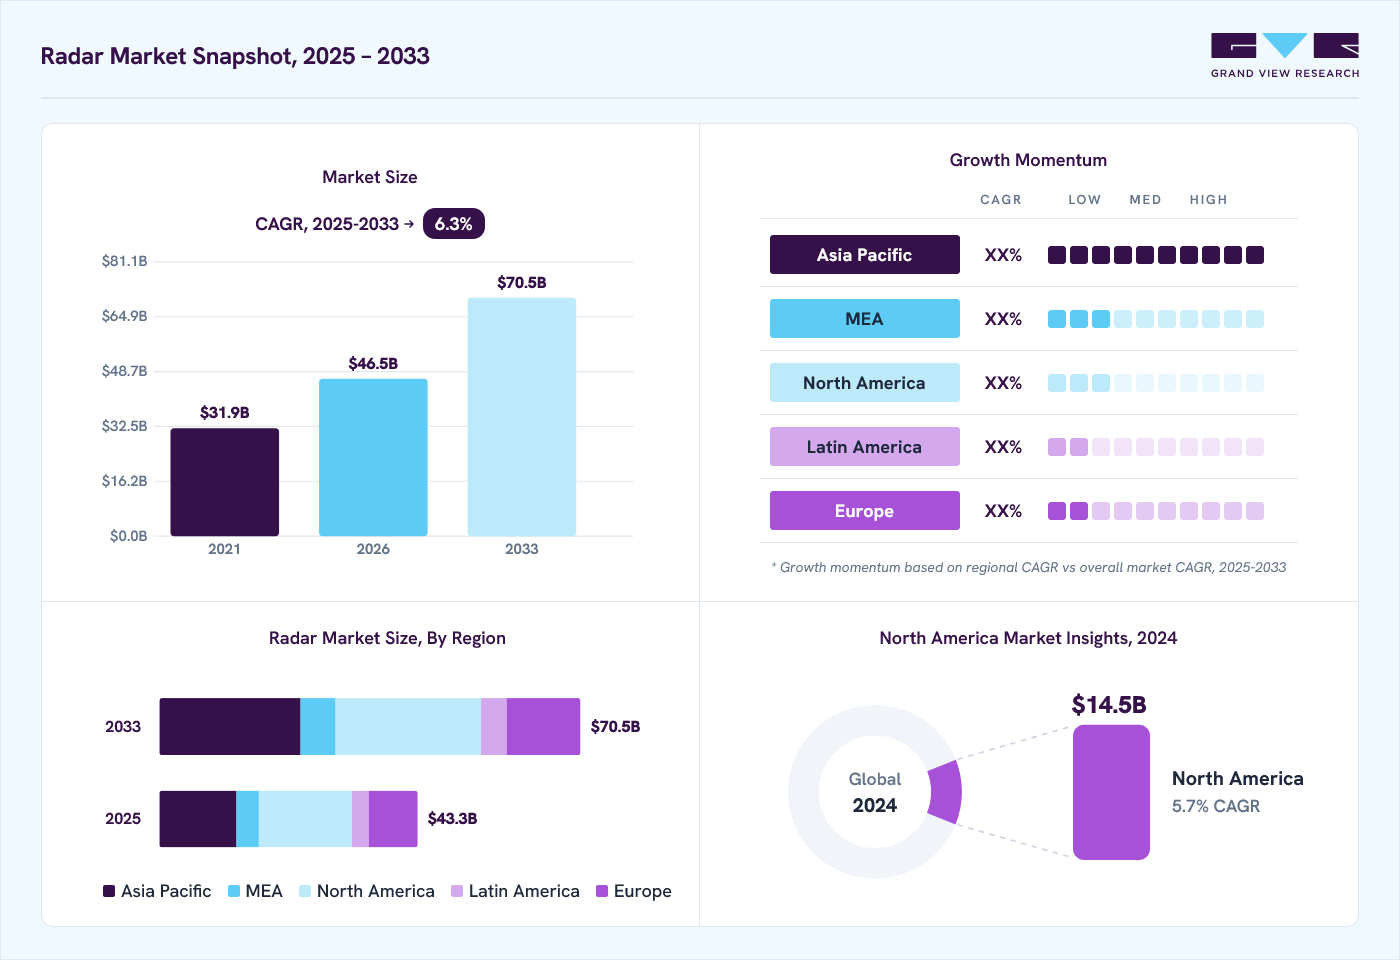
The global radar market size was valued at USD 43.3 billion in 2025 and is projected to grow from USD 46.5 billion in 2026 to USD 70.5 billion by 2033, at a CAGR of 6.1% from 2026 to 2033. North America dominated the global market with the largest revenue share of 37.9% in 2025. The radar market is driven by increasing demand for advanced surveillance and threat detection systems, growing investment in defense modernization programs, and rising adoption of radar technologies across the military, aerospace, automotive, and industrial sectors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By platform: Ground-based segment dominated the market, with a share of 44.4% in 2025.
- By offering: Components segment accounted for the largest market share of 72.8% in 2025.
- By frequency band: S-band segment dominated the market with a revenue share of 28.4% in 2025.
- By range: Long range segment held the largest market share in 2025.
- By end use: Military and defense segment accounted for the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (37.9% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 43.3 Billion
- Estimated market size in 2026: USD 46.5 Billion
- Projected market size by 2033: USD 70.5 Billion
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The expanding deployment of radar systems for air and missile defense, border surveillance, weather monitoring, air traffic management, autonomous vehicles, and maritime navigation is significantly accelerating market growth. The increasing demand for integrated air and missile defense solutions is accelerating the deployment of multi-mission radar platforms across global armed forces. Nations are prioritizing radar systems that offer long-range detection, electronic warfare resistance, and real-time situational awareness to counter evolving aerial threats. Major defense modernization programs are now focusing on ground-based and airborne radar capable of supporting joint-force operations. This surge is being driven by rising geopolitical tensions and the need for national security autonomy. To learn more about this report, Download Free Sample Report
The growing demand for radar-enabled safety and automation features in vehicles is reshaping the automotive radar landscape. As ADAS and autonomous driving functions become mainstream, OEMs are integrating short-, mid-, and long-range radar to enable features such as adaptive cruise control, emergency breaking, and parking assist. Radar’s reliability in poor weather and low-light conditions gives it a competitive edge over other sensing technologies. This trend is positioning automotive radar as a core enabler of next-generation mobility.
The radar industry is undergoing transformation such as AI, machine learning, and software-defined architectures drive innovation in detection, tracking, and target classification. Defense and commercial users alike are adopting radar systems capable of real-time analytics, autonomous decision-making, and adaptive threat response. This evolution is reducing operator dependency while increasing radar system agility and mission versatility. As a result, vendors are focusing on scalable, modular radar designs to stay competitive in a rapidly evolving landscape.
The expansion of satellite constellations and space surveillance operations is driving demand for advanced radar systems capable of earth observation, climate monitoring, and space debris tracking. Agencies and private firms are deploying SAR (Synthetic Aperture Radar) in LEO and GEO orbits to enhance imaging precision and revisit rates. Miniaturization and lightweight radar payloads are becoming essential for commercial satellite operators. This trend is fostering growth in Ka-band and X-band radar systems with high-frequency, high-resolution capabilities.
Market Dynamics
The radar market is experiencing strong growth, driven by rising investments in integrated air and missile defense, border security, weather monitoring, air traffic management, autonomous mobility, and critical infrastructure protection are accelerating the deployment of radar systems for enhanced situational awareness and operational efficiency. The growing use of active electronically scanned array (AESA) radars, digital beamforming, gallium nitride (GaN)-based transmitters, multi-function radar systems, and advanced signal processing technologies is improving detection accuracy and operational performance. The integration of artificial intelligence, machine learning, sensor fusion, real-time target tracking, edge computing, and network-centric defense architectures enables faster threat identification, enhanced decision-making, improved mission effectiveness, reduced operational complexity, and superior system reliability, creating significant long-term growth opportunities for the global radar market.
Governments across major economies are significantly increasing investments in defense modernization to strengthen national security, improve border protection, and enhance multi-domain surveillance capabilities. This has accelerated the procurement of advanced radar systems capable of detecting aircraft, missiles, unmanned aerial vehicles, naval platforms, and other emerging threats across complex operational environments. As geopolitical tensions continue to rise, defense agencies are prioritizing next-generation radar technologies to improve situational awareness and operational readiness.
The adoption of active electronically scanned array (AESA) radar, digital beamforming, gallium nitride (GaN)-based transmitters, and multi-function radar architectures is transforming surveillance performance across defense platforms. These technologies provide greater detection range, higher target tracking accuracy, faster response times, and improved resistance to electronic warfare. Continuous investments in integrated air defense networks, missile defense systems, and command-control infrastructure are further strengthening demand for advanced radar solutions worldwide.
The deployment of advanced radar systems requires substantial capital investment due to sophisticated hardware, high-performance electronic components, specialized software, and complex system integration requirements. Procurement expenses are further increased by installation, calibration, maintenance, workforce training, and lifecycle support costs. These financial requirements often delay modernization programs, particularly for organizations operating under constrained defense or infrastructure budgets.
In addition to acquisition costs, advanced radar platforms require continuous upgrades to address evolving threats, regulatory requirements, and technological advancements. Maintaining compatibility with legacy command systems, communication networks, and sensor platforms further increases implementation complexity and ownership costs. These financial and operational challenges may limit the widespread adoption of these technologies among smaller defense organizations, commercial operators, and developing economies.
The increasing integration of artificial intelligence, machine learning, and sensor fusion technologies is creating new opportunities for next-generation radar systems across defense, aviation, maritime, weather monitoring, and autonomous mobility applications. Intelligent radar platforms can process vast amounts of data in real time, automatically classify targets, reduce false alarms, and improve decision-making under highly dynamic operational conditions.
Modern radar systems are increasingly being integrated with electro-optical sensors, infrared imaging, satellite intelligence, unmanned platforms, and command-control networks to deliver comprehensive situational awareness. AI-powered analytics enable predictive threat assessment, automated tracking, adaptive beam management, and faster mission execution while improving operational efficiency. These advancements are expanding radar applications across both military and civilian environments, enabling more reliable surveillance and monitoring.
Market Concentration & Characteristics
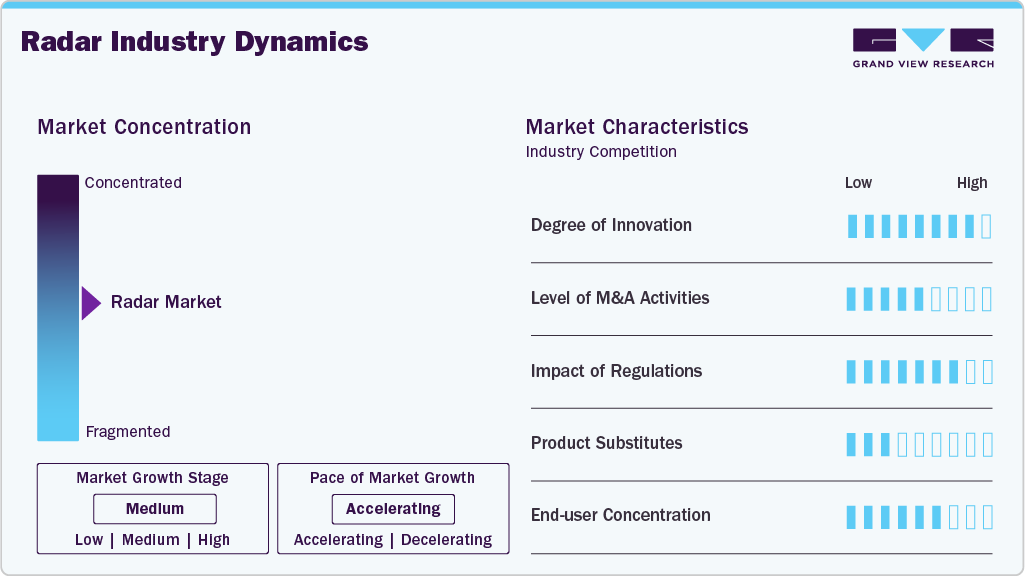
The radar market is moderately concentrated, with leading defense contractors, aerospace companies, radar system manufacturers, semiconductor suppliers, and sensor technology providers competing across military surveillance, air and missile defense, air traffic management, maritime navigation, weather monitoring, automotive safety, and critical infrastructure security applications. Rising investments in defense modernization, increasing deployment of integrated surveillance networks, and growing demand for high-performance detection systems are driving market expansion. Companies are strengthening their competitive positions through strategic partnerships, technology collaborations, product innovations, and continuous investments in active electronically scanned array (AESA) radar, gallium nitride (GaN)-based systems, digital beamforming, and AI-enabled signal processing technologies.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, supported by rapid advancements in AI-powered target recognition, software-defined radar, digital beamforming, multi-function radar architectures, gallium nitride (GaN) semiconductor technology, and sensor fusion capabilities. Merger and acquisition activity remains moderate as companies expand radar portfolios and strengthen defense and commercial technology capabilities. Regulatory impact is significant due to defense procurement standards, spectrum allocation policies, export control regulations, cybersecurity requirements, and aviation safety certifications. The threat of substitutes remains low because alternative sensing technologies cannot consistently provide the long-range detection, all-weather operation, high target accuracy, and real-time situational awareness that advanced radar systems deliver in critical applications.
Analyst Perspective
The radar market is experiencing significant expansion, driven by rising investments in defense modernization programs, rapid advances in radar sensing technologies, and the growing adoption of AI-enabled surveillance systems, active electronically scanned array (AESA) radars, and multi-function detection platforms across diverse applications. The expanding implementation of digital beamforming, gallium nitride (GaN)-based transmitters, software-defined radar architectures, sensor fusion technologies, and real-time signal processing is improving detection accuracy, operational efficiency, situational awareness, and system reliability. Organizations increasingly prioritize advanced threat detection, continuous surveillance, and resilient monitoring capabilities to meet evolving requirements across defense, aviation, maritime, automotive, and weather forecasting. Technology providers are positioned to capitalize on emerging opportunities, thereby reinforcing long-term market expansion and sustainable revenue generation across the global radar ecosystem.
Platform Insights
Based on platform, the ground-based segment led the market with the largest revenue share of 44.4% in 2025 and is expected to grow at a considerable CAGR over the forecast period. primarily driven by rising defense modernization initiatives and increased cross-border threat perception. Governments across developed and emerging economies are prioritizing the deployment of advanced ground-based radar systems for air defense, missile tracking, and early warning capabilities. These systems offer extensive coverage and superior target discrimination, making them essential components of modern military infrastructure. Moreover, ongoing territorial tensions are further accelerating investments in long-range ground radar platforms.
The airborne segment is expected to register the fastest CAGR of 6.8% from 2025-2033, driven by the growing demand for multi-mission radar systems across both military and commercial aviation sectors. Defense forces worldwide are investing heavily in airborne surveillance, reconnaissance, and targeting radars to strengthen situational awareness and electronic warfare capabilities. These radar systems are now being integrated into a wide range of platforms, including fighter jets, UAVs, helicopters, and large reconnaissance aircraft. Furthermore, the expansion of unmanned aerial vehicles (UAVs) for ISR (Intelligence, Surveillance, and Reconnaissance) missions is reinforcing the need for lightweight, high-resolution radar systems.
Offering Insights
Based on offering, the components segment dominated the market with the largest revenue share of 72.8% in 2025, owing to the rising deployment of radar systems across defense, automotive, and industrial sectors, the demand for high-performance and scalable components has seen significant growth. The Components segment, including antennas, transmitters, receivers, and signal processors, forms the backbone of modern radar architectures. Manufacturers are prioritizing modularity, miniaturization, and improved thermal efficiency to support evolving platform requirements. This is particularly critical in applications with SWaP (Size, Weight, and Power) constraints such as UAVs and autonomous vehicles.
The service segment is expected to grow at the fastest CAGR in the coming years, driven by the increasing deployment of advanced radar systems across military, aviation, and commercial sectors, the demand for expert installation and integration services is accelerating. As radar technologies become more complex, seamless implementation and system calibration are critical to achieving operational effectiveness. Vendors are expanding service portfolios to include end-to-end setup, customization, and interoperability support. This growing reliance on specialized technical services is fostering long-term partnerships between radar manufacturers and end users.
Frequency Band Insights
Based on frequency band, the S-Band segment accounted for the largest market share of 28.4% in 2025, the increasing demand for long-range, all-weather surveillance and tracking capabilities is propelling growth in the S-band radar industry segment. Known for its optimal balance between range and resolution, the S-band is widely adopted in air traffic control, weather monitoring, and naval surveillance systems. Governments and defense agencies are deploying S-band radars to enhance early warning systems, missile detection, and battlefield awareness. Its ability to perform reliably in harsh environments makes it a preferred choice for mission-critical applications.
The Ka-band segment is expected to grow at the fastest CAGR in the coming years, primarily driven by the growing need for high-resolution imaging and precision targeting, the Ka-Band segment is gaining significant traction across defense and aerospace applications. The Ka-band's shorter wavelength allows for enhanced resolution, making it ideal for synthetic aperture radar (SAR), drone surveillance, and satellite-based radar systems. Defense agencies are increasingly adopting Ka-band radar for its ability to detect small or low-observable targets at extended ranges. Its frequency agility and compact size also support integration into advanced airborne and space-based platforms.
Range Insights
Based on range, the long range segment dominated the market with the largest revenue share of 40.7% in 2025, driven by the surge in demand for radar-based safety systems across automotive, industrial, and security sectors, the Short Range radar industry is experiencing rapid growth. These systems are increasingly used for applications such as collision avoidance, blind spot detection, perimeter surveillance, and industrial automation due to their precision in confined spaces. Technological advancements are enabling miniaturized, low-power, and cost-effective short-range radar modules suitable for mass deployment. In addition, the rise of smart cities and autonomous vehicles is further accelerating adoption, positioning the segment as a key enabler of real-time situational awareness in dense and dynamic environments.
The long range segment is expected to grow at the significant CAGR in the coming years, the increasing growth of cross-border threats, missile proliferation, and geopolitical tensions is fueling demand for Long Range radar systems worldwide. These radars are critical for airspace surveillance, early warning, and missile defense, offering extended detection ranges and high-resolution target tracking. Governments and defense organizations are investing in next-generation long-range radar technologies with enhanced electronic scanning and real-time data fusion. As nations prioritize strategic defense infrastructure, the Long Range segment continues to gain traction as a vital component of national security frameworks.
End Use Insights
Based on end use, the military and defense segment dominated the market with a revenue share of 49.9% in 2025, the increasing growth of advanced driver-assistance systems (ADAS) and autonomous driving technologies is driving rapid adoption of automotive radar systems. Radar sensors particularly short- and mid-range are now essential for applications such as adaptive cruise control, lane-keeping assistance, blind spot detection, and emergency braking. Automakers are integrating multi-mode radar units to achieve 360-degree situational awareness and enhance vehicle safety standards. As electric and autonomous vehicle development accelerates globally, the automotive segment is expected to be one of the fastest-growing verticals in the radar industry.
 To learn more about this report, Download Free Sample Report
The telecommunications segment is expected to grow at significant CAGR in the coming years, driven by the rapid densification of 5G infrastructure and the widespread deployment of small cells, radar is being explored to improve site planning, interference mitigation, and real-time environmental monitoring. Telecom operators are using radar-based sensing to understand movement patterns and physical obstructions in urban landscapes. This data helps optimize antenna placement, reduce blind spots, and enhance end user coverage. As networks become more dynamic, radar supports more responsive and self-healing architectures.
Regional Insights
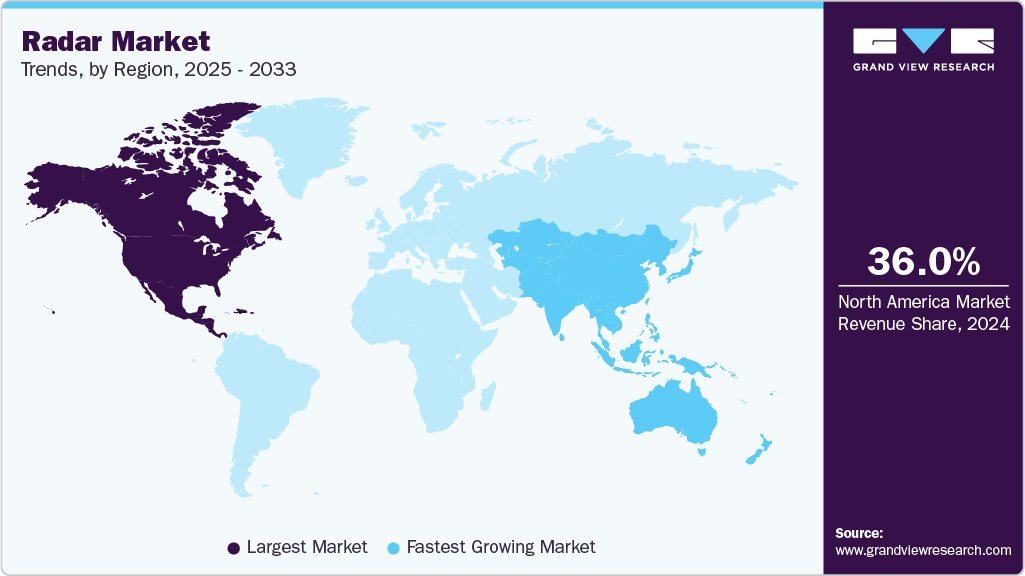
North America dominated the radar market with the largest revenue share of 37.9% in 2025, increased integration of radar with AI and sensor fusion technologies to enhance target detection accuracy and reduce false positives. There is a growing emphasis on multi-domain operations, leading to investment in interoperable radar systems across air, land, sea, and space. The commercial aviation sector is also driving demand for weather radar upgrades to improve safety. Furthermore, private aerospace and satellite firms are contributing to innovation in compact and space-borne radar systems.
 To learn more about this report, Download Free Sample Report
U.S. Radar Market Trends
The radar market in the U.S. held the largest share in the North America region in 2025, as technology is advancing rapidly through major defense contracts and innovation in space-based and ground-based radar systems. The Department of Defense is prioritizing the development of scalable and software-defined radar for next-generation platforms. There's also strong growth in automotive radar driven by ADAS and autonomous driving technologies.
Europe Radar Market Trends
The Europe radar market is expanding its radar capabilities in both civil and military sectors, particularly for weather monitoring, air traffic control, and defense readiness. Pan-European collaborations are advancing radar system standardization and interoperability, especially under NATO initiatives. The rise of electric and autonomous vehicles is also pushing radar sensor demand in transportation. Moreover, investment in dual-use radar applications for environmental monitoring and disaster management is gaining momentum.
The Germany radar market is advancing radar systems with enhanced signal processing, digital beamforming, and stealth target detection for national defense. The country is also exploring radar integration in smart logistics systems for real-time tracking and object recognition. The automotive sector is heavily investing in radar modules for driver monitoring, blind-spot detection, and traffic jam assist features. Additionally, research institutions in Germany are contributing to innovations in THz radar for non-destructive testing and biomedical applications.
The UK radar market is investing in radar solutions that support maritime situational awareness and cyber-resilient battlefield operations. Local firms are developing software-defined radar systems for easier upgrades and mission reconfigurations. There is growing interest in radar for railways, coastal monitoring, and autonomous drone navigation. The UK government is also funding early-stage radar startups focused on miniaturization and export-grade systems.
Asia Pacific Radar Market Trends
Asia Pacific radar market is expected to grow at the fastest CAGR of 7.8% from 2025 to 2033, owing to the need for reduced import dependence and enhanced defense sovereignty, countries are scaling up indigenous radar production. Coastal surveillance radar is witnessing growing demand to tackle challenges such as illegal fishing, piracy, and territorial intrusions. Urban development initiatives are accelerating the deployment of radar-based systems for smart traffic management and flood monitoring.
The China radar market is focusing on high-resolution radar imaging for both military intelligence and civilian disaster management. It is deploying ground-based radar systems along contested borders and in artificial island installations for surveillance. The country is also pushing forward with commercial radar satellite constellations for earth observation. Meanwhile, Chinese electric vehicle makers are embedding compact radar sensors for lane change, parking assist, and collision warning systems.
The Japan radar market is refining its radar capabilities to detect advanced aerial threats including stealth aircraft and hypersonic missiles. Its automotive sector is innovating with radar sensors that enable 360-degree perception for autonomous vehicles. The country is also exploring underwater radar technologies for maritime security and anti-submarine warfare. In the public sector, radar-based earthquake detection and infrastructure health monitoring are gaining importance.
Key Radar Company Insights
Some of the key players operating in the market include Lockheed Martin Corporation and RTX corporation and among others.
-
RTX Corporation, formerly Raytheon Technologies, is one of the leading defense contractors globally, with a dominant presence in the radar systems market. It specializes in next-generation radar technologies like the AN/SPY-6 (AMDR) for the U.S. Navy and ground-based Patriot radar systems. RTX’s radar solutions are widely adopted across airborne, naval, and missile defense platforms, with strong focus on scalability and integration. The company continues to innovate with software-defined radar and digital beamforming technologies.
-
Lockheed Martin Corporation is a global aerospace and defense giant, specializing in advanced radar systems for air, ground, and naval platforms. It is known for producing long-range missile defense radars such as the AN/TPY-2 and SPY-7, which are integral to U.S. and allied defense systems. The company heavily invests in multi-mission radar technologies with capabilities in ballistic missile tracking, threat detection, and integrated air and missile defense. Lockheed Martin’s radar offerings support both military surveillance and precision targeting applications.
Elbit Systems Ltd. and Infineon Technologies AG are some of the emerging market participants in the radar market.
-
Elbit Systems is an Israeli defense technology company making strides in the radar space with integrated and compact systems. It specializes in multi-mission tactical radars, border surveillance radar, and UAV-mounted radar systems. The company emphasizes modular radar solutions that can adapt to various terrains and mission requirements. Elbit is increasingly focusing on export markets, offering lightweight, high-performance radar for homeland security and defense applications.
-
Infineon Technologies is a semiconductor company carving a niche in the automotive radar segment, particularly in short- and mid-range applications. It specializes in 77 GHz radar chipsets used for driver-assistance systems such as adaptive cruise control, lane-keeping, and collision avoidance. The company provides compact radar sensors that integrate seamlessly with modern vehicle electronics. Infineon is driving innovation in radar-on-chip design, low power consumption, and mass-market scalability for autonomous driving.
Key Radar Companies
The following key companies have been profiled for this study on the radar market.
-
Lockheed Martin Corporation
-
NXP Semiconductors
-
RTX
-
Thales Group
-
Northrop Grumman
-
BAE Systems
-
Leonardo S.p.A.
-
AIRBUS
-
L3Harris Technologies, Inc.
-
Infineon Technologies AG
-
Robert Bosch GmbH
-
ASELSAN A.Ş.
-
General Dynamics Corporation
-
Elbit Systems Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Lockheed Martin Corporation, Northrop Grumman, Thales Group)
- Focus on expanding integrated radar portfolios through defense contracts, technology partnerships, and platform modernization programs.
- Invest heavily in R&D to develop AI-enabled, AESA, multi-function, and software-defined radar systems.
- Strong global presence, established government relationships, and extensive expertise in advanced radar technologies.
- Ability to deliver integrated, high-performance radar solutions for complex defense and civilian surveillance applications.
- Dependence on lengthy government procurement cycles can delay revenue realization and business expansion.
- Large organizational structures may reduce flexibility against agile radar technology specialists and emerging competitors.
Emerging Players (Elbit Systems Ltd., Infineon Technologies AG, ASELSAN A.Ş.)
- Emerging players focus on developing AI-enabled radar solutions through specialized technology partnerships and niche application expertise.
- Invest in agile R&D to deliver compact, software-defined, and cost-effective radar platforms.
- Strong innovation capabilities enable rapid development of advanced radar technologies for emerging applications.
- Ability to deliver flexible, customized radar solutions with faster product development and deployment cycles.
- Limited manufacturing scale and customer base restrict participation in large defense procurement programs.
- Lower financial resources may constrain global expansion and long-term investment in advanced radar technologies.
Recent Developments
-
In May 2025, Scopic acquired ZoomRadar, a provider of real-time weather data and radar visualization tools. The acquisition aims to enhance ZoomRadar’s platform using Scopic’s expertise in AI and cloud technologies. This move strengthens Scopic’s position in delivering advanced weather intelligence solutions across various industries.
-
In March 2025, indie Semiconductor collaborated with GlobalFoundries to accelerate the development of high-performance radar SoCs for automotive applications. The partnership focuses on 77 GHz and 120 GHz radar solutions built on GF’s 22FDX platform. These compact and cost-efficient chips are designed to support a wide range of safety features, including collision avoidance and in-cabin monitoring.
-
In January 2025, Arbe partnered with NVIDIA to integrate its high-resolution MIMO radar with NVIDIA’s DRIVE AGX platform. The collaboration enables real-time free-space mapping and detection of small obstacles under all conditions. This joint solution aims to advance safety and performance in ADAS and autonomous driving systems.
Radar Market Report Scope
Report Attribute
Details
Market size in 2025
USD 43.3 Billion
Estimated market size in 2026
USD 46.5 Billion
Projected market size by 2033
USD 70.5 Billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Platform, offering, frequency band, range, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
Lockheed Martin Corporation; NXP Semiconductors; RTX; Thales Group; Northrop Grumman; BAE Systems; Leonardo S.p.A.; AIRBUS; L3Harris Technologies, Inc.; Infineon Technologies AG; Robert Bosch GmbH; ASELSAN A.Ş.; General Dynamics Corporation; Elbit Systems Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Radar Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global radar market report based on platform, offering, frequency band, range, end use, and region.
-
Platform Outlook (Revenue, USD Million, 2021 - 2033)
-
Ground-based
-
Naval
-
Airborne
-
Space based
-
-
Offering Outlook (Revenue, USD Million, 2021 - 2033)
-
Components
-
Antenna
-
Transmitter
-
Receiver
-
Others
-
-
Service
-
Installation/ Integration
-
Support & Maintenance
-
Training & Consulting
-
-
-
Frequency Band Outlook (Revenue, USD Million, 2021 - 2033)
-
L-Band
-
S-Band
-
C-Band
-
X-Band
-
Ku-Band
-
Ka-Band
-
Others
-
-
Range Outlook (Revenue, USD Million, 2021 - 2033)
-
Long Range
-
Medium Range
-
Short Range
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Military and Defense
-
Aviation
-
Weather Forecasting and Monitoring
-
Telecommunications
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The radar market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each radar segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Platform
Revenue capture definition
Ground-based
Revenue is generated through ground-based radar systems deployed for air surveillance, border security, missile detection, weather monitoring, air traffic control, and critical infrastructure protection. This segment is driven by increasing investments in national defense modernization, integrated surveillance networks, and advanced situational awareness capabilities.
Naval
Revenue is captured through radar systems installed on naval vessels for maritime surveillance, navigation, target tracking, coastal security, and anti-submarine operations. This segment is supported by growing naval modernization programs, expanding maritime security initiatives, and increasing demand for enhanced fleet protection technologies.
Airborne
Revenue is generated through airborne radar systems integrated into fighter aircraft, helicopters, unmanned aerial vehicles, surveillance aircraft, and early warning platforms. This segment is driven by rising demand for long-range target detection, airborne intelligence, battlefield awareness, and advanced reconnaissance capabilities.
Space based
Revenue is generated through space-based radar systems supporting Earth observation, military reconnaissance, environmental monitoring, disaster management, and maritime surveillance. This segment is propelled by increasing satellite deployments, demand for persistent global monitoring, and advancements in synthetic aperture radar technologies.
Offering
Revenue capture definition
Components
Revenue is generated through radar hardware components including antennas, transmitters, receivers, power amplifiers, processors, waveguides, and signal processing modules. This segment is driven by continuous technological advancements, increasing radar production, and modernization of surveillance and defense infrastructure.
Service
Revenue is captured through radar installation, integration, calibration, maintenance, software upgrades, system testing, training, and lifecycle support services. This segment is supported by growing demand for operational reliability, system optimization, and long-term maintenance of mission-critical radar platforms.
Frequency Band
Revenue capture definition
L-Band
Revenue is generated through L-Band radar systems used for long-range surveillance, air traffic management, weather observation, and military detection applications. This segment is driven by reliable long-distance performance and superior operation under challenging atmospheric conditions.
S-Band
Revenue is captured through S-Band radar systems supporting weather forecasting, maritime surveillance, airport monitoring, and defense operations. This segment is fueled by increasing deployment in air defense systems and meteorological observation networks.
C-Band
Revenue is generated through C-Band radar systems utilized for weather monitoring, precision tracking, satellite communications, and industrial sensing applications. This segment benefits from balanced performance, reliable target detection, and broad commercial and defense adoption.
X-Band
Revenue is generated through X-Band radar systems deployed for missile guidance, fire control, naval surveillance, airborne reconnaissance, and security applications. This segment is driven by demand for high-resolution imaging, precise target tracking, and advanced battlefield awareness.
Ku-Band
Revenue is captured through Ku-Band radar systems supporting airborne surveillance, satellite communications, maritime navigation, and remote sensing applications. This segment is supported by increasing adoption of high-frequency radar for enhanced imaging and communication performance.
Ka-Band
Revenue is generated through Ka-Band radar systems used for high-resolution imaging, satellite observation, advanced military surveillance, and next-generation aerospace applications. This segment is driven by technological advancements requiring higher bandwidth and improved detection precision.
Others
Revenue is generated through radar systems operating across additional frequency bands for specialized defense, industrial automation, scientific research, and security applications. This segment is supported by expanding use cases requiring customized radar performance and operational flexibility.
Range
Revenue capture definition
Long Range
Revenue is generated through long-range radar systems designed for missile defense, strategic surveillance, airspace monitoring, maritime security, and early warning applications. This segment is driven by increasing investments in national security and long-distance threat detection capabilities.
Medium Range
Revenue is captured through medium-range radar systems supporting air defense, border monitoring, coastal surveillance, weather observation, and aviation safety. This segment is fueled by growing demand for balanced detection performance across military and civilian operations.
Short Range
Revenue is generated through short-range radar systems deployed for automotive safety, industrial automation, perimeter security, collision avoidance, and drone detection. This segment is driven by rising adoption of autonomous technologies and intelligent sensing solutions.
End Use
Revenue capture definition
Automotive
Revenue is generated through radar systems integrated into advanced driver assistance systems, autonomous vehicles, collision avoidance, adaptive cruise control, blind-spot detection, and parking assistance. This segment is driven by increasing vehicle automation and stringent road safety regulations.
Military and Defense
Revenue is captured through radar systems supporting air defense, missile detection, battlefield surveillance, target acquisition, electronic warfare, border security, and naval operations. This segment is propelled by rising defense spending and continuous military modernization initiatives.
Aviation
Revenue is generated through radar systems used for air traffic management, aircraft navigation, weather detection, airport surveillance, and collision avoidance. This segment is supported by increasing air traffic volumes and modernization of aviation infrastructure.
Weather Forecasting and Monitoring
Revenue is generated through radar systems deployed for precipitation tracking, storm detection, climate observation, flood monitoring, and severe weather forecasting. This segment is driven by growing investments in meteorological infrastructure and disaster preparedness programs.
Telecommunications
Revenue is captured through radar technologies supporting spectrum monitoring, satellite communications, wireless infrastructure management, and network performance analysis. This segment is fueled by expanding communication networks and increasing deployment of advanced wireless technologies.
Others
Revenue is generated from radar systems used in industrial automation, critical infrastructure protection, mining, transportation, scientific research, law enforcement, and public safety. This segment is supported by the expanding adoption of radar technologies across diverse commercial and government operations.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Radar System Adoption Layer
Who are the potential adopters?
Identifies organizations adopting radar systems, including defense agencies, aviation authorities, maritime operators, automotive manufacturers, weather agencies, industrial enterprises, and public safety organizations requiring surveillance, navigation, target detection, monitoring, and situational awareness capabilities.
02
Radar Technology Enablement Layer
Who can deploy radar solutions?
Deployment depends on advanced radar hardware, antennas, transmitters, receivers, AI-enabled signal processing, GaN semiconductors, software platforms, integration expertise, skilled professionals, and reliable communication infrastructure supporting accurate detection, tracking, and operational performance.
03
Operational Application Layer
Where are radar solutions actively utilized?
Radar solutions are utilized across military surveillance, air traffic management, maritime navigation, weather forecasting, border security, autonomous vehicles, industrial monitoring, disaster management, and infrastructure protection, requiring reliable real-time detection and tracking capabilities.
04
Revenue Generation Layer
How is revenue generated?
Revenue is generated through radar system manufacturing, component sales, software licensing, system integration, installation, maintenance, modernization, training, consulting, lifecycle support, and recurring service contracts across defense, commercial, aviation, and industrial applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Defense Radar Modernization & Surveillance Capability Assessment
Conducted detailed evaluation of ground-based, airborne, naval, and space-based radar systems across air defense, border security, missile detection, and battlefield surveillance, integrating AESA technology, AI-enabled target recognition, sensor fusion, and digital beamforming to improve operational effectiveness.
Improves threat detection, enhances situational awareness, strengthens defense readiness, and supports mission-critical surveillance operations.
Multi-Domain Radar Deployment & Integrated Sensor Network Strategy
Assessed deployment of radar systems across military, aviation, maritime, automotive, and weather monitoring applications, integrating command-and-control platforms, sensor fusion, software-defined radar architectures, and real-time data processing to improve detection coverage and operational coordination.
Enhances detection coverage, improves operational coordination, increases mission efficiency, and strengthens multi-domain surveillance capabilities.
AI-Enabled Radar Analytics & Advanced Detection Performance Assessment
Evaluated implementation of artificial intelligence-powered signal processing, automated target classification, predictive analytics, multi-function radar architectures, and edge computing frameworks to improve tracking accuracy, threat identification, operational reliability, and decision-making across critical surveillance environments.
Enables intelligent surveillance, improves tracking accuracy, enhances operational reliability, and supports faster tactical decision-making.
Frequently Asked Questions About This Report
Some key players operating in the radar market include Lockheed Martin Corporation; Collins Aerospace; Saab AB; Honeywell International Inc.; General Dynamics Corporation; BAE Systems; Northrop Grumman Corporation; Raytheon Company; and Thales Group.
Key factors that are driving the radar market growth continued emphasis on enhancing border surveillance & security and growing demand for continuous weather monitoring systems.
The global radar market size was valued at USD 43.3 billion in 2025 and is estimated at USD 46.5 billion for 2026.
The global radar market is expected to grow at a CAGR of 6.1% from 2026 to 2033, reaching USD 70.5 billion by 2033.
North America dominated with a 37.9% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The ground-based segment dominated with a 44.4% revenue share in 2025 while airborne segment is segment is expected to be the fastest-growing market.
The components segment dominated the market with a share of 72.8% in 2025, owing to the rising deployment of radar systems across defense, automotive, and industrial sectors, the demand for high-performance and scalable components has seen significant growth.
The military and defense segment accounted for the largest share, with 49.9% of revenue in 2025 and telecommunications segment is second fastest growing market
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


