
- Home
- »
- Healthcare IT
- »
-
Radiology As A Service Market Size, Growth Report, 2026-2033GVR Report cover

Radiology As A Service Market (2026 - 2033)
Size, Share & Trends Analysis Report By Location (In-house, Off-shore, In-shore), By Service, By Modality, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$5.2BMarket Estimate, 2026
$5.9BMarket Forecast, 2033
$15.8BCAGR, 2026–2033
15.2%Radiology As A Service Market Summary
The global radiology as a service market was valued at USD 5.2 billion in 2025 and is projected to grow from USD 5.9 billion in 2026 to USD 15.8 billion in 2033, at a CAGR of 15.2% from 2026 to 2033. The North America region dominated the global market, accounting for around 35.0% of revenue in 2025. The increasing demand for low-cost, advanced, cloud-based medical imaging services is the key driver of market growth.
Key Market Trends & Insights
- By service: The tele radiology reading platform segment held the largest market share of over 30.0% in 2025.
- By location: The inshore segment held the largest market share of around 40.0% in 2025.
- By end-use: The hospital segment held the largest market share of over 50.0% in 2025.
Regional Highlights
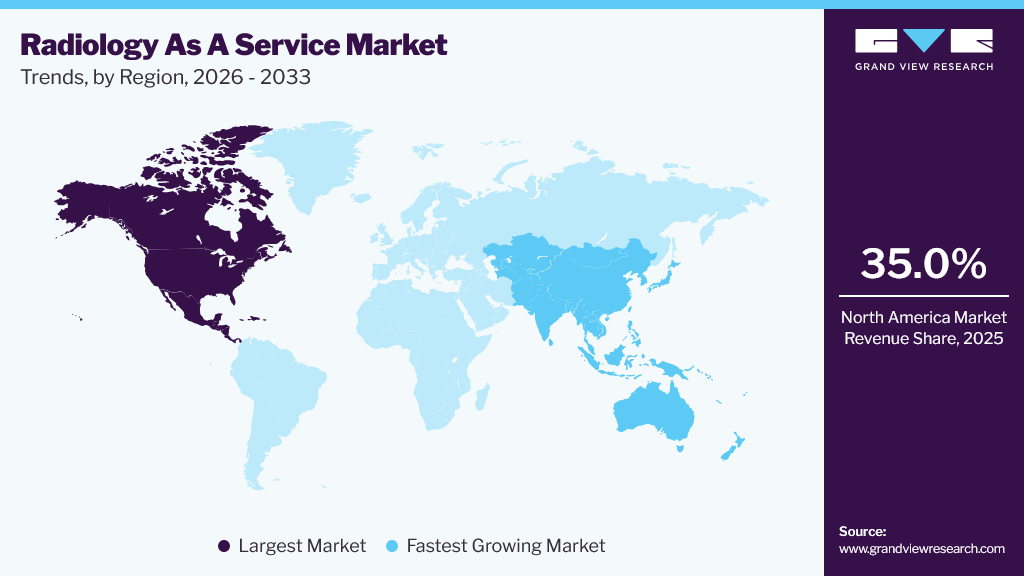
- Largest regional market: North America (Approximately 35.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 5.2 Billion
- Estimated market size in 2026: USD 5.9 Billion
- Projected market size by 2033: USD 15.8 Billion
- CAGR (2026-2033): 15.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
A global shortage of skilled radiologists is fueling the growth of medical imaging. This shortage, combined with the ability to access advanced technologies with limited investment, is expected to drive demand for radiology services. According to the Association of American Medical Colleges (AAMC), the U.S. could face a shortage of between 17,100 and 41,900 radiologists in the coming years.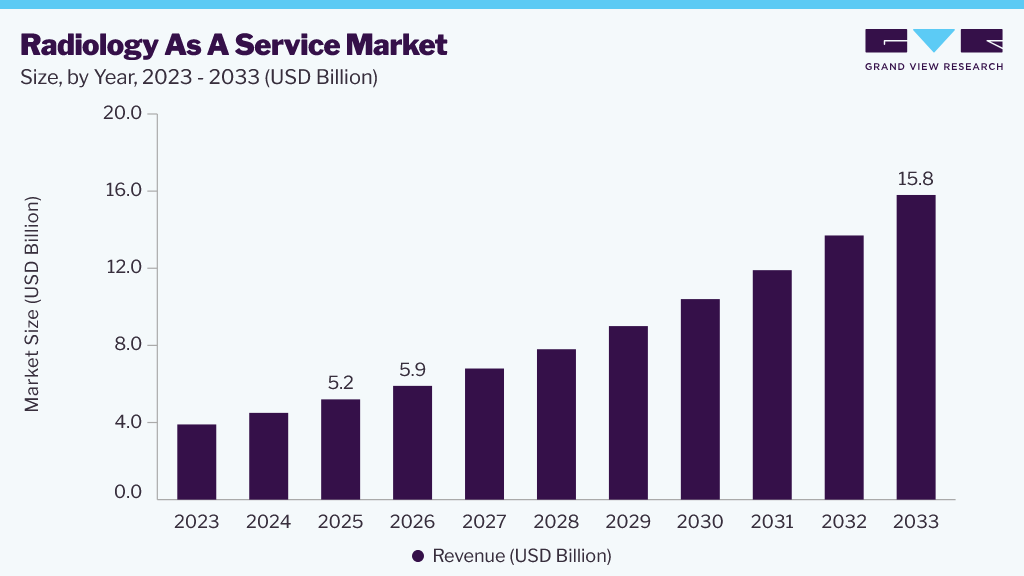 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Additionally, the increasing prevalence of targeted diseases like cancer, cardiovascular diseases, pneumonia, and Chronic Obstructive Pulmonary Disease (COPD) is boosting the need for radiology services. Breast cancer, for instance, is the most common cancer among women in the U.S., as reported by the American Cancer Society. Aging is another significant risk factor for degenerative joint disorders such as osteoporosis and osteoarthritis, both of which are prevalent among individuals over 70. The CDC estimates that around 58.5 million people in the U.S. have arthritis.
The radiology-as-a-service model allows healthcare providers to access advanced medical imaging technologies without making substantial investments. Providers are increasingly adopting these service models to meet the rising demand for better diagnostics at affordable prices while ensuring their long-term sustainability. By implementing such a model, healthcare providers eliminate the need to purchase costly imaging equipment. Instead, they can collaborate with suppliers who provide the necessary tools and services in exchange for regular payments or a pay-per-use arrangement. This approach significantly reduces the upfront capital required, easing the financial burden on healthcare providers, especially those with constrained budgets.
Analyst Perspective
The radiology-as-a-service market is evolving as healthcare providers increasingly seek flexible, cost-efficient ways to manage growing imaging volumes and radiologist shortages. Hospitals and diagnostic centers are shifting from traditional in-house models to outsourced, technology-enabled radiology services that improve reporting efficiency and access to specialist expertise. Companies with strong clinical networks, reliable turnaround times, and advanced workflow integration capabilities are likely to strengthen their market position. As healthcare systems place greater emphasis on operational efficiency and remote care delivery, demand is expected to favor providers that can combine imaging expertise with scalable digital infrastructure. Over time, service quality, data integration, and the ability to support faster clinical decision-making will become key competitive differentiators.
Service Insights
Based on service, tele-radiology reading platform services held the largest share at over 35.0% in 2025, driven by growing demand for medical imaging due to the rising prevalence of chronic diseases such as cancer, cardiovascular diseases, and brain injuries. Remote imaging solutions are tele-radiology reading platform services that enable radiologists to perform remote readings and deliver high-quality patient care. For instance, in January 2025, VSee Health, Inc., a leader in telehealth solutions, announced its expansion by partnering with one of the U.S. leading post-acute care hospital networks for tele-radiology services.
The other IT services segment is expected to witness the fastest growth during the forecast period, owing to the increasing demand for solutions in patient scheduling, revenue management, staffing, and billing to optimize workflow, improve efficiency, & decrease the number of denials. Other IT services include patient booking & scheduling, documentation, and billing services. Service providers in the market offer various solutions that aid in scheduling patient appointments and enabling a hassle-free documentation & billing process.
Location Insights
The inshore segment dominated the industry, accounting for around 40.0% of revenue in 2025, due to the uneven distribution of radiologists and an increasing number of physicians/referrers unwilling to make a diagnosis without confirmation from diagnostic radiology. Moreover, owing to late working hours in radiology departments and the increased demand for reporting imaging cases in the emergency department with a turnaround time of fewer than 4 hours, the need for onshore tele-radiology services has increased.
The offshore segment is expected to grow at the fastest CAGR over the forecast period. Factors such as the shortage of radiologists in various countries, the availability of radiologists during the night shift, and the high demand for low reporting costs are propelling segment growth. Moreover, the growing number of foreign-trained and certified radiologists in developing countries such as India and Australia is further propelling segment growth. In addition, radiologists need not travel to access images, as they can be transferred anywhere. It eliminates the overhead costs of printing images or reports. Thus, these factors are anticipated to propel segment growth.
Modality Insights
In 2025, the X-ray segment accounted for the largest revenue share, exceeding 25.0%, owing to the growing burden of chronic diseases and rising awareness of early disease diagnosis. Continuous technological advancements, such as improvements in image quality, acquisition time, portability, detector form, and software, are further boosting demand for X-ray systems. The inclusion of Artificial Intelligence (AI) in medical imaging is creating new growth opportunities for market players. Key players are investing heavily in R&D to provide AI across different imaging modalities.
The CT segment is expected to witness the fastest growth during the forecast period. This can be attributed to the growing incidence of chronic conditions such as orthopedic conditions, cancer, cardiovascular diseases, and neurological disorders. It is highly useful in emergencies, as internal injuries can be detected early, saving lives. Thus, the growing adoption of advanced assessment tools in emergency departments and the rising percentage of ambulatory emergency care units are other key factors positively impacting market growth. For instance, in March 2025, GE HealthCare, a global medical technology and digital solutions provider, launched its new advanced CT platform, the Revolution Vibe CT system. It is designed for cardiology, oncology, emergency, and general diagnostic imaging.
End-use Insights
By end use, the hospital segment dominated the market with around 50.0% share in 2025. Advancements in healthcare infrastructure and government initiatives are expanding healthcare facilities even in remote areas. Furthermore, hospitals generally have substantial funding, which helps them develop specialized radiology departments equipped with the most advanced systems and solutions, thereby helping them retain patients through improved patient care. Moreover, a growing shortage of radiologists leads to outsourcing for diagnosis and reporting. Various healthcare facilities also deploy advanced technological solutions for enhancing workflow.
However, medical imaging centers are expected to achieve the fastest CAGR during the forecast period. The growth is majorly attributed to the growing geriatric population, as they are more prone to chronic conditions, which increases the adoption rate of imaging devices for diagnosis and treatment planning. The government also promotes early disease diagnosis to reduce the burden of chronic conditions in the region, which further positively impacts segment growth.
Regional Insights
North America had the largest revenue share at around 35.0% as of 2025. The increasing target population, coupled with the rising prevalence of target chronic diseases, such as cancer and bone impairments, and the presence of major players & developed healthcare IT infrastructure, are among the key factors contributing to the region's largest revenue share. Technological advancements and high healthcare expenditure are key factors driving market growth. Technological upgradation is estimated to support market growth in the region in the coming years.
 To learn more about this report, Download Free Sample Report
Asia Pacific Radiology As A Service Market Trends
Asia Pacific is anticipated to register the fastest growth rate over the forthcoming years. Various factors, such as high unmet medical needs due to the growing prevalence of target chronic diseases, such as cancer & cardiac diseases, & hypertension, as well as rising demand for medical imaging, are driving growth in the region. In addition, global market players are expanding their footprints in the Asia-Pacific region. The presence of various manufacturing companies specializing in diagnostic imaging in this region is further driving market growth. The growing demand for data-driven healthcare services and the shortage of skilled nursing personnel are among the factors expected to drive market growth in the coming years.
Key Radiology As A Service Company Insights
The radiology-as-a-service market is highly fragmented, with a few major players and large local players holding the majority of the share. Key players are focusing on various growth strategies to expand their market reach and increase market share. Moreover, these players are developing technologically advanced solutions to meet consumer demand. For instance, in July 2025, Radiology Partners, a U.S.-based technology-enabled radiology services provider, announced the launch of its new technology services division, Mosaic Clinical Technologies and MosaicOS. They are a radiologist-driven platform that is designed to address emergent challenges.
Key Radiology As A Service Companies
The following key companies have been profiled for this study on the radiology as a service market:
-
The Radiology Group
-
Within Health
-
AbbaDox IDS
-
Siemens Healthineers
-
CodaMetrix
-
Coreline Soft
-
DeepHealth, Inc.
-
DeepTek Inc.
-
Enlitic Inc.
-
Koninklijke Philips N.V.
-
GE HealthCare
-
TeleRay
-
Everlight Radiology
-
Medica Group
-
Teleconsult Europe
-
Vesta Teleradiology
-
Real Rads
-
deepc
-
Teleradiology Solutions
-
Ambra Health (Intelerad)
-
RamSoft Inc.
-
OnRad Inc.
-
Nanox Imaging LTD.
-
USARAD
-
TeleDiagnosys Services Pvt. Ltd
-
Telediagnostic Solutions
-
vRad
-
Telemedicine Clinic U.K.
-
Fovia AI, Inc. (Subsidiary of Fovia, Inc.)
-
HealthLevel, Inc.
-
Riverain Technologies
-
Vista.ai
-
Imalogix
-
IONIC Health
-
Lucid Health, Inc.
-
medQ, Inc.
-
medSR
-
openDoctor
-
OpenRad
-
Paragon Consulting Partners, LLC
-
Qure.ai
-
RadNet, Inc.
Recent Developments
- In June 2026, DeepHealth, a subsidiary of RadNet, Inc., launched Reporting Pro, an A.I. powered platform intended to automate and accelerate Radiologists workflows. The solution offers a new reporting paradigm that integrates speech recognition, AI-derived findings, measurements, impressions, quality control, and structured reports into a unified workflow, enabling radiology service providers to improve efficiency and produce more precise reports.
- . In November 2025, vRad, a prominent tele-radiology services provider, announced The vRad Platform, an end-to-end A.I.-driven technology and support solution that provides an all-inclusive tool for radiology practices to enhance radiologist productivity and deliver real-time analytics throughout their organizations.
Radiology as A Service Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.2 Billion
Estimated market size in 2026
USD 5.9 Billion
Projected market size by 2033
USD 15.8 Billion
Growth rate
CAGR of 15.2% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, location, modality, end-use, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand, South Korea; Brazil; Argentina, South Africa, UAE
Key companies profiled
The Radiology Group; Within Health; AbbaDox IDS; Siemens Healthineers; CodaMetrix; Coreline Soft; DeepHealth, Inc.; DeepTek Inc.; Enlitic Inc.; Koninklijke Philips N.V.; GE HealthCare; TeleRay; Everlight Radiology; Medica Group; Teleconsult Europe; Vesta Teleradiology; Real Rads; deepc; Teleradiology Solutions; Ambra Health (Intelerad); RamSoft Inc.; OnRad Inc.; Nanox Imaging LTD.; USARAD; TeleDiagnosys Services Pvt. Ltd; Telediagnostic Solutions; vRad; Telemedicine Clinic U.K.; Fovia AI, Inc. (Subsidiary of Fovia, Inc.); HealthLevel, Inc.; Riverain Technologies; Vista.ai; Imalogix; IONIC Health; Lucid Health, Inc.; medQ, Inc.; medSR; openDoctor; OpenRad; Paragon Consulting Partners, LLC; Qure.ai; RadNet, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Radiology As A Service Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global radiology as a Service market report based on service, location, modality, end-use, and region:
- Service Outlook (Revenue, USD Million, 2021 - 2033)
- Tele-radiology Reading Platform Services
- Cloud-based Reading Platform Services
- Web-based Reading Platform Services
- 3D Lab Imaging Services
- Remote Scanning Services
- Consulting Services
- Staffing Services
- Staffing Services for Radiologists
- Staffing Services for Radiographers
- Other IT Services
- Patient Booking & Scheduling
- Patient Arrival and Registration
- Workflow Scheduling and Data Entry
- Documentation
- Image Acquisition
- Diagnosis and Reporting
- Information Exchange
- Billing services
- Coding, Billing, And Working Denials
- Reimbursement from Payers
- Patient Booking & Scheduling
- Tele-radiology Reading Platform Services
- Location Outlook (Revenue, USD Million, 2021 - 2033)
- Inshore
- Offshore
- In-house
- Modality Outlook (Revenue, USD Million, 2021 - 2033)
- X-ray
- CT
- MRI
- Ultrasound
- Mammography
- PET-CT
- End-use Outlook (Revenue, USD Million, 2021 - 2033)
- Hospitals
- Diagnostic Imaging Centers
- Radiology Clinics
- Physician Offices
- Nursing Homes
- Regional Outlook (Revenue, USD Million, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- UK
- Germany
- France
- Spain
- Italy
- Sweden
- Norway
- Denmark
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- MEA
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The global radiology as a service market size was valued at USD 5.2 billion in 2025 and is estimated at USD 5.9 billion for 2026
The global radiology as a service market is expected to grow at a CAGR of 15.2% from 2026 to 2033, reaching USD 15.8 billion.
The tele radiology reading segment accounted for the largest revenue share of over 30.0% in 2025.
North America dominated with an approximately 35.0% revenue share in 2025
Key players in the market include The Radiology Group; Within Health; AbbaDox IDS; CodaMetrix; Coreline Soft; DeepHealth; Inc.; DeepTek Inc.; Enlitic Inc.; Koninklijke Philips N.V.; GE Healthcare, and others
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


