
- Home
- »
- Advanced Interior Materials
- »
-
Rapid Thermal Processing Equipment Market Report, 2033GVR Report cover

Rapid Thermal Processing Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Equipment (Batch/Multiple-Substrate RTP Systems, Single-Wafer RTP/RTA Systems), By Technology (Lamp-based RTP, Laser-based RTP), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$870.4MMarket Estimate, 2026
$927.5MMarket Forecast, 2033
$1,484.3MCAGR, 2026–2033
6.9%Rapid Thermal Processing Equipment Market Summary
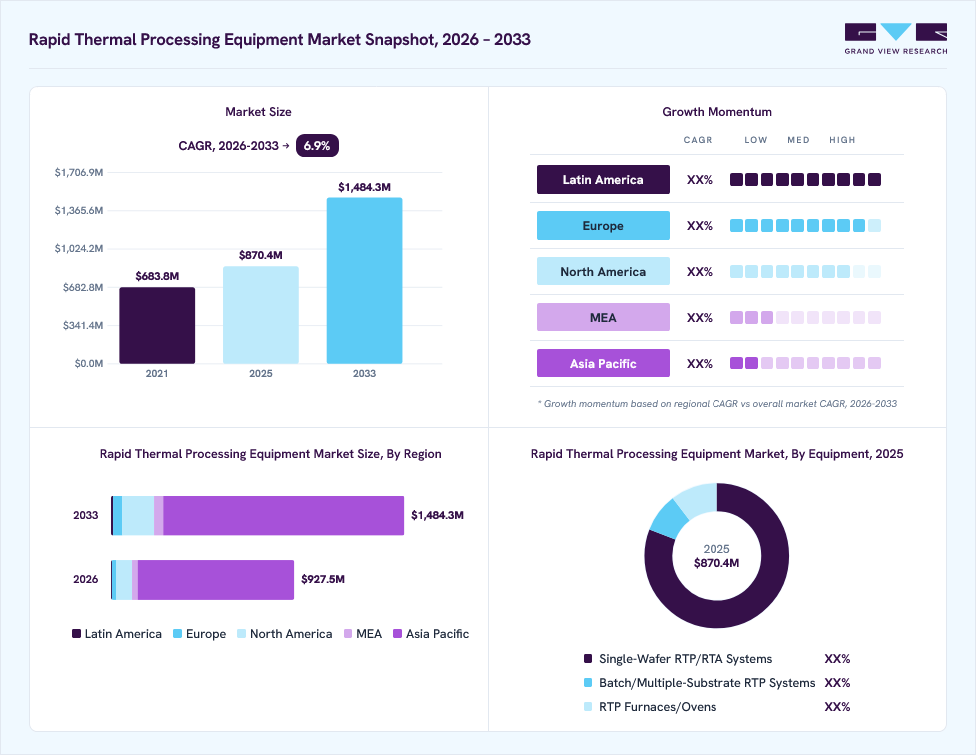
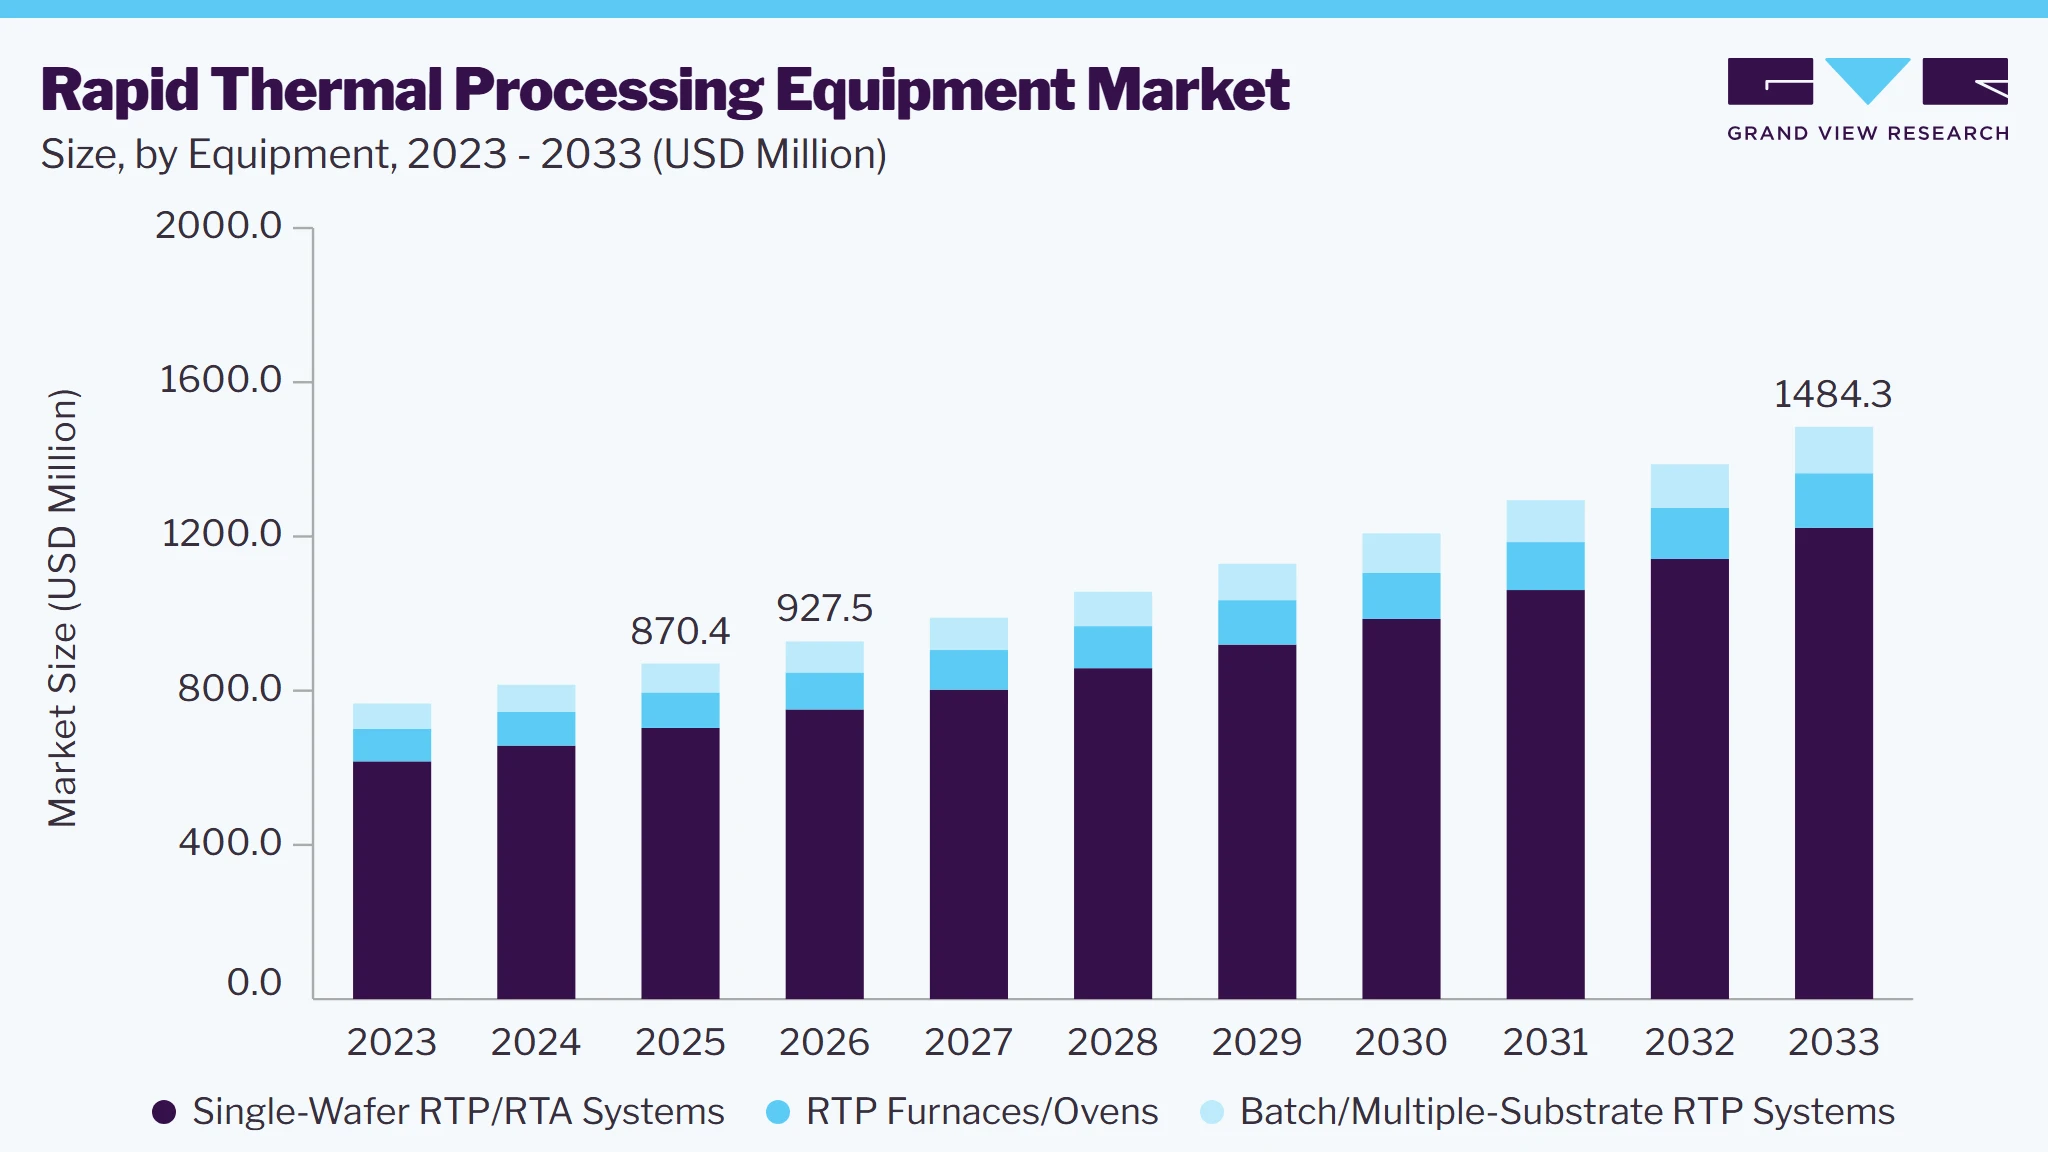
The global rapid thermal processing equipment market size was valued at USD 870.4 million in 2025 and is projected to grow from USD 927.5 million in 2026 to USD 1,484.3 million by 2033, at a CAGR of 6.9% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 86.6% in 2025. The growing demand for advanced semiconductor devices is a major driver of the global rapid thermal processing (RTP) equipment market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By equipment: Single-wafer RTP/RTA systems segment led the market with a revenue share of 80.8% in 2025.
- By technology: Lamp-based RTP segment led the market with a revenue share of 79.7% in 2025.
- By end use: Semiconductor manufacturing segment led the market with a revenue share of 76.8% in 2025.
Regional Highlights
- Largest Regional Market: Asia Pacific (86.6% revenue share, 2025).
- Fastest-growing regional market: Latin America (highest CAGR, 2026-2033)
- By Country: Taiwan held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 870.4 Million
- Estimated market size in 2026: USD 927.5 Million
- Projected market size by 2033: USD 1,484.3 Million
- CAGR (2026-2033): 6.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As chip architectures become more compact and process integration becomes more complex, manufacturers require highly controlled thermal cycles to activate dopants, anneal implanted wafers, modify thin films, and improve material interfaces. RTP systems enable rapid heating and cooling with tight temperature uniformity, helping reduce unwanted dopant diffusion and maintain the integrity of nanoscale structures.
 To learn more about this report, Download Free Sample Report
Increasing adoption of advanced materials and emerging electronic technologies is also creating opportunities for RTP equipment suppliers. Semiconductor manufacturers are incorporating materials such as silicon carbide, gallium nitride, advanced dielectric layers, and other engineered films that require carefully optimized thermal treatment. At the same time, growing production of automotive electronics, high-performance computing components, sensors, and other sophisticated devices is increasing the need for precise process control. Improvements in lamp-based, laser-based, and resistive heating technologies are further expanding RTP capabilities by enabling faster thermal cycles, localized treatment, and greater flexibility across different substrate and process requirements.
Market Dynamics
The rapid thermal processing (RTP) equipment industry is shaped by the increasing need for precise thermal treatment across semiconductor fabrication, microelectronics, MEMS, research, and photovoltaic applications. Demand is influenced by semiconductor process miniaturization, growing wafer-processing capacity, adoption of advanced materials, and the transition toward more sophisticated device architectures. At the same time, high equipment costs, complex integration requirements, lengthy qualification procedures, and the technical expertise needed for operation can moderate purchasing activity. Technological progress in rapid heating, temperature uniformity, process automation, and energy-efficient thermal cycles continues to create new avenues for market expansion.
The increasing complexity of semiconductor devices is driving demand for RTP systems capable of delivering highly controlled thermal cycles. Modern fabrication processes require precise treatment of wafers to activate dopants, repair implantation-related defects, modify thin films, and optimize material interfaces while limiting excessive thermal exposure. Rapid heating and cooling allow manufacturers to achieve targeted material changes within tightly controlled process windows, supporting the fabrication of smaller and more complex device structures.
Expansion of semiconductor production capacity is further strengthening equipment demand. Investments in new fabrication facilities and upgrades to existing production lines are increasing the demand for advanced wafer-processing tools, particularly as manufacturers move toward higher-performance logic, memory, power, and specialty semiconductor technologies. The growing adoption of compound semiconductor materials and advanced process technologies is also creating requirements for thermal systems with greater flexibility, temperature accuracy, and process repeatability.
The substantial capital investment required for RTP equipment can limit adoption, particularly among smaller manufacturers, research facilities, and organizations operating with constrained equipment budgets. Advanced systems incorporate sophisticated heating sources, temperature-monitoring components, process-control systems, automation, and specialized chambers, resulting in considerable acquisition and maintenance expenses. In addition to the initial purchase price, installation, facility integration, calibration, servicing, and operator training can add to the overall cost of ownership. Lengthy equipment qualification and process validation requirements may further delay deployment in production environments.
The development of laser-based, millisecond, and other highly localized thermal-processing technologies presents significant opportunities for market participants. These approaches can provide shorter thermal cycles and greater control over localized energy delivery, making them suitable for advanced device structures and temperature-sensitive material stacks. Improvements in sensing, automation, software-based process control, and real-time temperature monitoring can further enhance process consistency while reducing energy consumption and production losses.
Additional opportunities are emerging from the expansion of specialty semiconductor manufacturing, compound semiconductor devices, MEMS, and next-generation photovoltaic technologies. These applications often require customized thermal profiles rather than standardized furnace-based treatment, creating demand for flexible equipment capable of handling different substrates, materials, temperatures, and processing conditions. As manufacturers diversify their material platforms and device designs, suppliers with adaptable RTP architectures and application-specific process capabilities can address a wider range of thermal-processing requirements.
Market Concentration & Characteristics
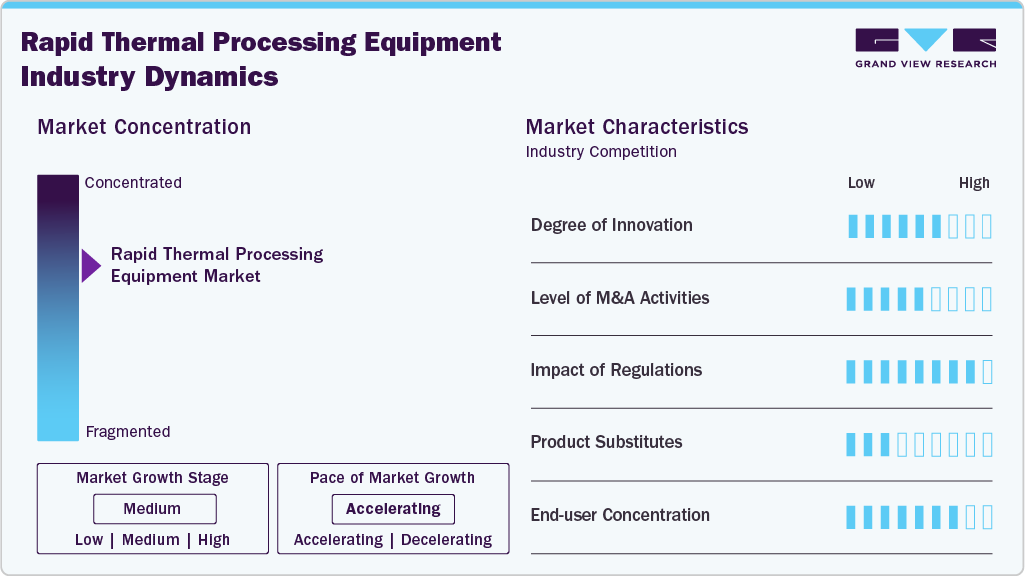
The rapid thermal processing equipment industry is concentrated, with a limited number of established manufacturers holding substantial shares, particularly in advanced wafer-processing applications. High entry barriers, significant R&D requirements, specialized engineering capabilities, established customer relationships, and extensive technical support networks strengthen the position of leading suppliers. However, the presence of smaller specialized manufacturers serving research, specialty semiconductor, photovoltaic, and other niche applications adds competitive diversity.
 To learn more about this report, Download Free Sample Report
The market has a high degree of innovation, driven by the continuous evolution of semiconductor manufacturing and the need for tighter process control. Equipment development is increasingly focused on faster heating and cooling rates, improved temperature uniformity, precise thermal-cycle control, reduced energy consumption, and compatibility with advanced wafer materials and device architectures. Innovations in lamp, laser, and resistive heating technologies are also enabling more localized and shorter-duration thermal treatments, while advanced sensors, automation, and process-control software are improving repeatability and production efficiency.
Regulatory influence on the RTP equipment market is moderate, with requirements primarily affecting equipment safety, energy efficiency, emissions, chemical handling, and manufacturing-environment standards. Thermal-processing systems used in semiconductor and photovoltaic facilities must comply with applicable electrical, mechanical, workplace-safety, environmental, and facility regulations. Increasing emphasis on energy consumption and sustainable manufacturing is encouraging equipment developers to improve thermal efficiency and reduce operating requirements. Compliance with industry standards can increase development and certification costs, but it also promotes greater reliability, operational safety, and environmental performance.
The market has a relatively high end user concentration, as a substantial share of demand originates from large-scale semiconductor manufacturers and advanced electronics producers with significant fabrication capacity. These customers typically require sophisticated systems, stringent process specifications, high uptime, and long-term technical support, resulting in lengthy qualification and procurement cycles. At the same time, research institutions, MEMS manufacturers, specialty-device producers, and photovoltaic facilities broaden the customer base and create opportunities for equipment suppliers offering flexible and application-specific systems.
Analyst Perspective
The market is expected to maintain steady growth as semiconductor manufacturers increase investments in advanced wafer fabrication and require faster, more precise thermal treatment with lower thermal budgets. Single-wafer RTP/RTA systems and lamp-based technologies currently benefit from their established use in high-volume production, while laser-based processing is gaining attention for next-generation device structures and increasingly demanding annealing requirements. Asia Pacific remains the primary demand center due to its strong semiconductor manufacturing ecosystem, while opportunities are also expanding across microelectronics, MEMS, photovoltaics, and research applications. Overall, market competition is likely to remain technology-driven, with equipment precision, process flexibility, automation, and compatibility with advanced manufacturing nodes becoming important factors for supplier differentiation.
Equipment Insights
The single-wafer RTP/RTA systems dominated the market with a revenue share of 80.8% in 2025, supported by their ability to provide precise temperature control, rapid heating and cooling, and consistent processing at the individual wafer level. These capabilities are particularly important for advanced semiconductor fabrication, where tight thermal budgets and increasingly complex device structures require accurate control over short process cycles. Single-wafer systems also enable manufacturers to optimize recipes for specific process steps, minimize unwanted dopant diffusion, and maintain high process uniformity. Rising investment in advanced logic, memory, power semiconductor, and specialty-device production continues to support demand for these systems.
Batch/Multiple-Substrate RTP Systems are expected to register significant growth at a CAGR of 5.9%, primarily because they can process several wafers or substrates within a single thermal cycle, improving throughput and equipment utilization. Their productivity advantages make them attractive for applications where processing volumes are high and wafer-by-wafer customization is less critical. Increasing manufacturing capacity in photovoltaics, specialty semiconductors, research facilities, and other substrate-based applications is creating additional opportunities for batch configurations. Ongoing improvements in temperature uniformity, process monitoring, and automated handling are also enhancing their suitability for higher-volume operations.
Technology Insights
Lamp-based RTP dominated the market with a revenue share of 79.7% in 2025, owing to its established position in high-temperature wafer processing and its ability to deliver rapid, uniform heating across the substrate. High-intensity lamps enable fast temperature ramping and precise control over short thermal cycles, making the technology suitable for annealing, dopant activation, oxidation, and thin-film treatment. Its proven performance, compatibility with established semiconductor production processes, and broad adoption across fabrication facilities have supported its leading position. In addition, mature system designs and process know-how help manufacturers integrate lamp-based platforms into existing production environments.
Laser-based RTP is expected to be the fastest-growing technology over the forecast period at CAGR of 7.6%, driven by the increasing need for highly localized and ultra-fast thermal treatment in advanced semiconductor applications. Laser energy can be precisely directed toward targeted areas, enabling very short processing durations while limiting heat transfer to surrounding structures. This capability is particularly relevant for sophisticated device architectures, temperature-sensitive materials, and applications requiring reduced thermal budgets. Continued development of laser sources, beam-control systems, real-time monitoring, and millisecond-scale processing is expected to broaden adoption as semiconductor manufacturing moves toward increasingly demanding process requirements.
End Use Insights
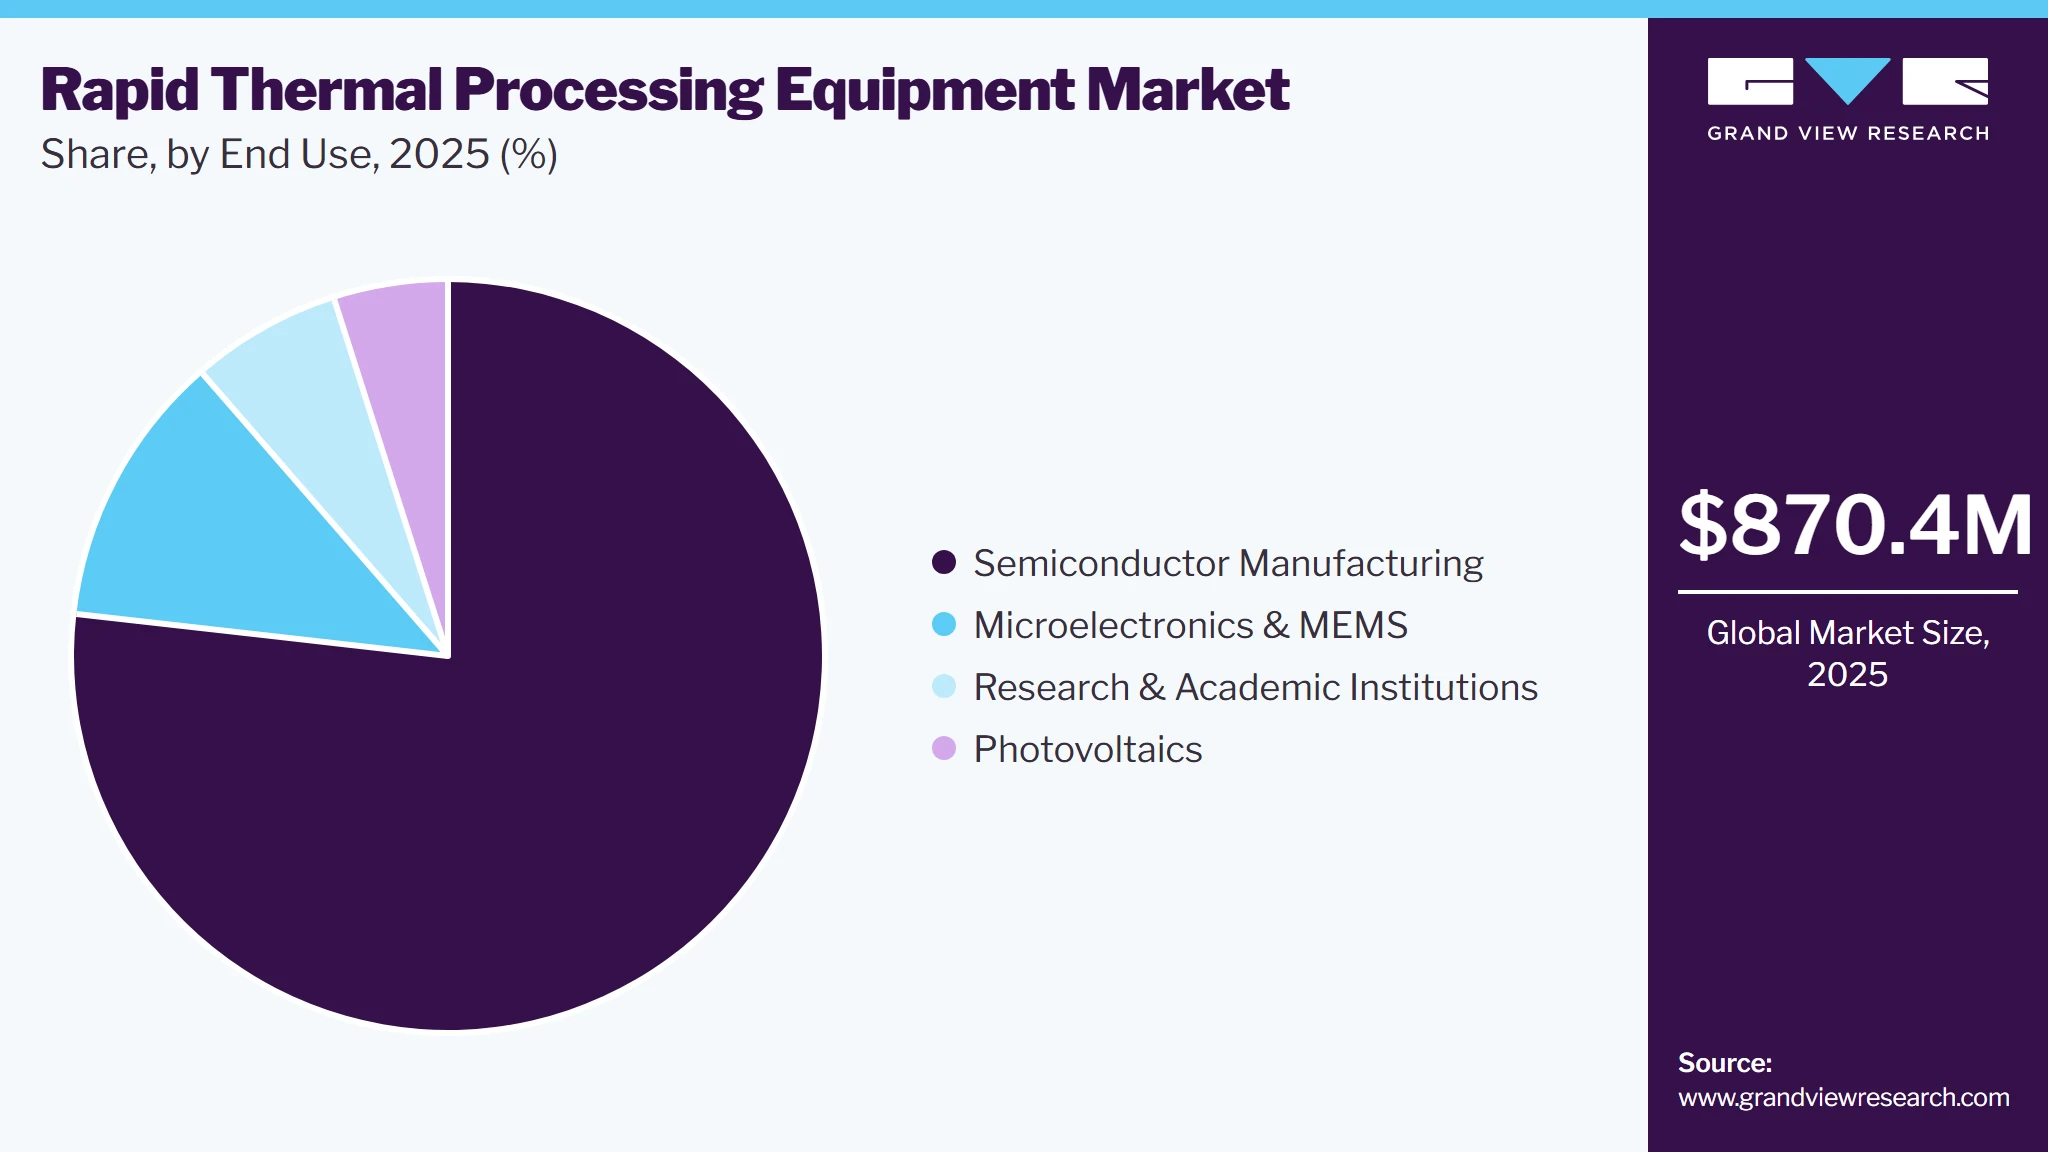
Semiconductor manufacturing dominated the market with a revenue share of 76.8% in 2025, driven by the extensive use of rapid thermal processing across critical wafer-fabrication steps. RTP systems are required for applications such as dopant activation, implant damage repair, oxidation, thin-film modification, and contact formation, where precise thermal exposure is essential for maintaining device performance and process consistency. Increasing semiconductor production capacity, continued device miniaturization, and the adoption of advanced process architectures are sustaining demand for high-precision thermal-processing systems across fabrication facilities.
 To learn more about this report, Download Free Sample Report
Microelectronics & MEMS is expected to be the fastest-growing end-use segment at a CAGR of 7.7%, supported by rising production of sensors, accelerometers, gyroscopes, microphones, actuators, and other miniaturized electronic components. These applications often involve delicate structures and diverse material combinations that require tightly controlled thermal treatment to prevent deformation, material degradation, or unwanted property changes. Growing demand for sensing technologies in automotive electronics, consumer devices, industrial systems, and connected equipment is further encouraging investment in specialized thermal-processing capabilities for microelectronics and MEMS fabrication.
Regional Insights
Asia Pacific Rapid Thermal Processing Equipment Market Trends
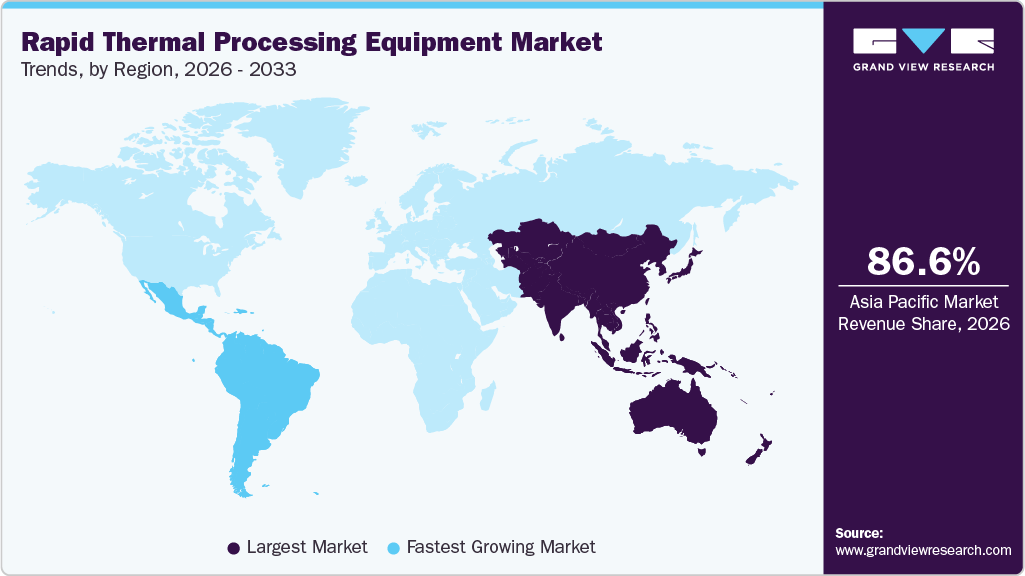
The rapid thermal processing equipment industry in Asia Pacific dominated the market with revenue share of 86.6% in 2025, supported by its extensive semiconductor and electronics manufacturing ecosystem. The region benefits from substantial wafer-fabrication capacity, established supply chains, expanding foundry operations, and strong production of memory, logic, power devices, and consumer electronics. Ongoing investments in fabrication facilities, particularly across major semiconductor-producing economies, are generating demand for advanced thermal-processing systems. The presence of equipment manufacturers, component suppliers, and technology-development centers within the region further strengthens its position.
 To learn more about this report, Download Free Sample Report
Taiwan rapid thermal processing equipment industry dominated the Asia Pacific market, supported by its highly developed semiconductor manufacturing ecosystem and continued investment in advanced wafer fabrication. Taiwan’s Ministry of Economic Affairs reported that integrated-circuit industry output increased 29.0% year-on-year in Q1 2026, driven by strong demand for AI and high-performance computing and increased 12-inch wafer foundry production. In the same quarter, output of computer, electronics, and optical products increased by 143.7%, reflecting strong investment in semiconductor equipment. Taiwan's real GDP also grew 8.7% in 2025, with manufacturing expansion led largely by semiconductors, computers, electronics, and optical products. This strong fabrication activity supports sustained requirements for precise thermal-processing equipment used in advanced wafer manufacturing.
The rapid thermal processing equipment industry in China is expected to witness strong growth in the market, supported by expanding domestic semiconductor production and broader electronics manufacturing capacity. According to China's National Bureau of Statistics, integrated-circuit production reached 484.3 billion units in 2025, increasing 10.9% year-on-year, while the value of integrated-circuit production among designated-size industrial enterprises increased 27.4%. The Ministry of Industry and Information Technology also reported that China's electronic information manufacturing sector increased its value-added output by 10.6% in 2025, while major companies generated USD 2.5 trillion in operating revenue. Increasing domestic wafer production and semiconductor equipment investment are creating additional demand for RTP and other thermal-processing systems.
North America Rapid Thermal Processing Equipment Market Trends
The rapid thermal processing equipment industry in North America is expected to witness steady growth, primarily due to renewed investment in domestic semiconductor manufacturing and the expansion of advanced fabrication capabilities. Government-backed initiatives, private-sector capital expenditure, and efforts to strengthen regional semiconductor supply chains are encouraging the development and modernization of wafer-production facilities. Demand for high-precision thermal equipment is also supported by research into advanced materials, compound semiconductors, power electronics, and next-generation device technologies, particularly through collaboration between manufacturers, research laboratories, and technology institutions.
U.S. Rapid Thermal Processing Equipment Market Trends
The rapid thermal processing equipment industry in the U.S. dominated the North American market, supported by its expanding semiconductor manufacturing base, advanced R&D infrastructure, and substantial investment in domestic chip production. According to the U.S. Department of Commerce, the CHIPS Program Office had awarded approximately USD 34 billion in semiconductor incentives across 22 states, while planned semiconductor and electronics investments had reached nearly USD 450 billion. In addition, major fabrication projects are expanding domestic wafer-production capacity, including more than USD 18 billion of planned investment by Texas Instruments, nearly USD 90 billion of expected U.S. investment by Intel through the end of the decade, and more than USD 37 billion planned by Samsung for leading-edge chip production and R&D in Texas. These developments are supporting demand for advanced wafer-processing equipment, including RTP and RTA systems, as new and upgraded fabrication facilities increase their equipment requirements.
Europe Rapid Thermal Processing Equipment Market Trends
The rapid thermal processing equipment industry in Europe is projected to experience consistent expansion, supported by its established automotive electronics, industrial technology, power semiconductor, and specialty-device industries. The region has a strong focus on developing advanced semiconductor capabilities for applications such as electric mobility, energy systems, industrial automation, and connected technologies. Investments in semiconductor production and research infrastructure are creating opportunities for RTP suppliers, while Europe's emphasis on energy efficiency and sustainable manufacturing is encouraging demand for thermal systems with improved process control and lower resource consumption.
Germany rapid thermal processing equipment industry dominated the Europe market, supported by its substantial semiconductor manufacturing capacity. The German Federal Government states that the country accounts for 30% of EU wafer capacity, making it the largest microelectronics location in the European Union. Germany is also expanding domestic production capacity, with an approximately USD 4.0 billion semiconductor investment in Dresden supported by up to USD 1.1 billion in public funding. The combination of significant wafer capacity and ongoing fab expansion supports demand for advanced thermal-processing systems used during semiconductor fabrication.
The rapid thermal processing equipment industry in the UK is expected to witness growing demand for RTP equipment, supported by expansion across its semiconductor ecosystem and manufacturing capabilities. The UK Government's 2026 semiconductor sector study identified 703 semiconductor companies, including 295 dedicated semiconductor companies, while dedicated firms generated an estimated approximately USD 14.1 billion in revenue in 2025, and USD 10.0 billion in GVA. The sector also employed approximately 16,350 people directly, while grants and fundraising among companies covered by the study reached approximately USD 2.3 billion. These figures indicate a strengthening semiconductor base that can support greater adoption of specialized wafer-processing and thermal-treatment equipment.
Middle East & Africa Rapid Thermal Processing Equipment Market Trends
The rapid thermal processing equipment industry in Middle East & Africa is anticipated to grow gradually, supported by diversification of industrial economies, rising investments in advanced manufacturing, renewable-energy infrastructure, and technology-oriented development programs. Photovoltaic projects represent an important area of potential demand, while emerging electronics and semiconductor initiatives could create additional applications for thermal-processing systems. Although the region currently has a smaller semiconductor fabrication base than the major production centers, expanding research capabilities, industrial localization efforts, and investments in high-technology infrastructure are expected to gradually widen the market opportunity.
Israel rapid thermal processing equipment industry dominated the Middle East & Africa market, supported by its well-established semiconductor, microelectronics, and advanced technology ecosystem. The country has strong capabilities in chip design, specialty semiconductor production, MEMS, and research-driven electronics, creating demand for precise thermal-processing technologies. Its concentration of technology companies, fabrication facilities, universities, and research centers supports the adoption of RTP systems for wafer annealing, material modification, and process development. Ongoing development of advanced electronics and semiconductor technologies is expected to sustain the need for sophisticated thermal-processing equipment across the country.
Latin America Rapid Thermal Processing Equipment Market Trends
The rapid thermal processing equipment industry in Latin America is expected to register the fastest growth, albeit from a comparatively smaller installed base. Increasing electronics manufacturing, semiconductor-related assembly activities, photovoltaic deployment, and investment in industrial technology are gradually expanding the addressable market for thermal-processing equipment. Efforts to develop local manufacturing capabilities and diversify supply chains are also creating opportunities for advanced processing technologies. Growth in research infrastructure and specialized production applications could further support adoption as regional industries move toward higher-value electronic and energy technologies.
Brazil rapid thermal processing equipment industry is emerging as a key market for RTP equipment in Latin America, supported by its growing electronics, semiconductor, photovoltaic, and research ecosystem. The country has been strengthening domestic capabilities in microelectronics and advanced technology through investments in semiconductor research, component production, and technology infrastructure. Expansion of electronics manufacturing and increasing deployment of photovoltaic technologies are creating additional applications for controlled thermal-processing systems. Government initiatives aimed at developing local semiconductor capabilities and reducing dependence on imported technologies are also expected to encourage adoption of specialized wafer-processing equipment.
Key Rapid Thermal Processing Equipment Company Insights
Some of the key players operating in the market include Applied Materials, Inc., Tokyo Electron Limited, and Mattson Technology.
-
Applied Materials is a global provider of equipment and materials engineering technologies for semiconductor and advanced electronics production. Its portfolio supports critical manufacturing processes used to develop sophisticated chips and electronic components. The company invests substantially in research and development to advance semiconductor manufacturing capabilities and serves customers across major technology markets worldwide. Its broad technical expertise and extensive global presence position it as an important supplier of advanced wafer-processing equipment, including solutions used for thermal processing applications.
-
Mattson Technology develops semiconductor manufacturing equipment designed for critical wafer-processing applications. Its technology portfolio includes rapid thermal processing and annealing solutions, along with plasma-based systems used in the production of memory, logic, and foundry devices. The company focuses on improving process precision, productivity, and wafer performance for advanced fabrication environments. Its specialized thermal-processing capabilities make it a relevant participant in the global rapid thermal processing equipment industry.
Key Rapid Thermal Processing Equipment Companies:
The following key companies have been profiled for this study on the rapid thermal processing equipment market
-
Applied Materials, Inc.
-
Tokyo Electron Limited
-
Mattson Technology
-
Veeco Instruments Inc.
-
Annealsys
-
JTEKT Thermo Systems Corporation
-
Centrotherm
-
ECM Group
-
CVD Equipment Corporation
-
SemiTEq JSC
-
SCREEN Semiconductor Solutions Co., Ltd.
-
HQ-Dielectrics GmbH
-
Plasma-Therm
-
ADVANCE RIKO, Inc.
-
Anarghya Innovations and Technology
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Applied Materials, Inc.; Tokyo Electron Limited; Mattson Technology; Veeco Instruments Inc.; JTEKT Thermo Systems Corporation)
- Expand advanced RTP/RTA equipment to support next-generation semiconductor nodes and high-volume wafer processing.
- Invest in process automation, thermal uniformity, and real-time monitoring to improve manufacturing precision.
- Strengthen global customer support and integration capabilities across major semiconductor manufacturing hubs.
- Strong installed base and established relationships with major semiconductor manufacturers.
- Broad technology capabilities covering rapid annealing, thermal processing, and advanced wafer treatment.
- High R&D investment supports development of solutions for increasingly demanding process requirements.
- High equipment costs can limit adoption among smaller fabs, research facilities, and cost-sensitive customers.
- Dependence on semiconductor capital expenditure cycles can create fluctuations in equipment demand.
- Complex product portfolios and integration requirements may increase implementation time.
Emerging & Regional Players (e.g., Annealsys; Centrotherm; ECM Group; CVD Equipment Corporation; SemiTEq JSC)
- Focus on specialized RTP systems for MEMS, power devices, photovoltaics, and research applications.
- Offer customized thermal-processing equipment based on specific temperature, wafer size, and process requirements.
- Expand market reach through regional partnerships and targeted applications.
- Greater flexibility in developing application-specific RTP solutions.
- Strong positioning in niche thermal-processing applications requiring customized configurations.
- Ability to respond quickly to specialized customer requirements and smaller production volumes.
- Smaller installed bases and lower brand visibility compared with established equipment suppliers.
- Limited financial resources may restrict large-scale R&D and global expansion.
- Greater dependence on niche applications and regional semiconductor investment cycles.
Recent Developments
- In June 2026, Applied Materials strengthened its presence in Singapore with the launch of a new USD 500 million manufacturing and R&D facility in Tampines. The expansion increases the company’s advanced cleanroom capacity and supports rising demand for semiconductor production equipment, particularly from AI-related chip manufacturing.
-
In February 2026, Veeco Instruments received shareholder approval for its planned merger with Axcelis Technologies. The transaction, which is expected to close in the second half of 2026 subject to regulatory and other closing conditions, will bring the two semiconductor equipment businesses together.
Global Rapid Thermal Processing Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 870.4 million
Estimated Market size in 2026
USD 927.5 million
Revenue forecast in 2033
USD 1,484.3 million
Growth rate
CAGR of 6.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Equipment, technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; China; Japan; India; Taiwan; South Korea; Brazil; Israel; South Africa
Key companies profiled
Applied Materials, Inc.; Tokyo Electron Limited; Mattson Technology; Veeco Instruments Inc.; Annealsys; JTEKT Thermo Systems Corporation; Centrotherm; ECM Group; CVD Equipment Corporation; SemiTEq JSC; SCREEN Semiconductor Solutions Co., Ltd.; HQ-Dielectrics GmbH; Plasma-Therm; ADVANCE RIKO, Inc.; Anarghya Innovations and Technology
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Rapid Thermal Processing Equipment Market Report Segmentation
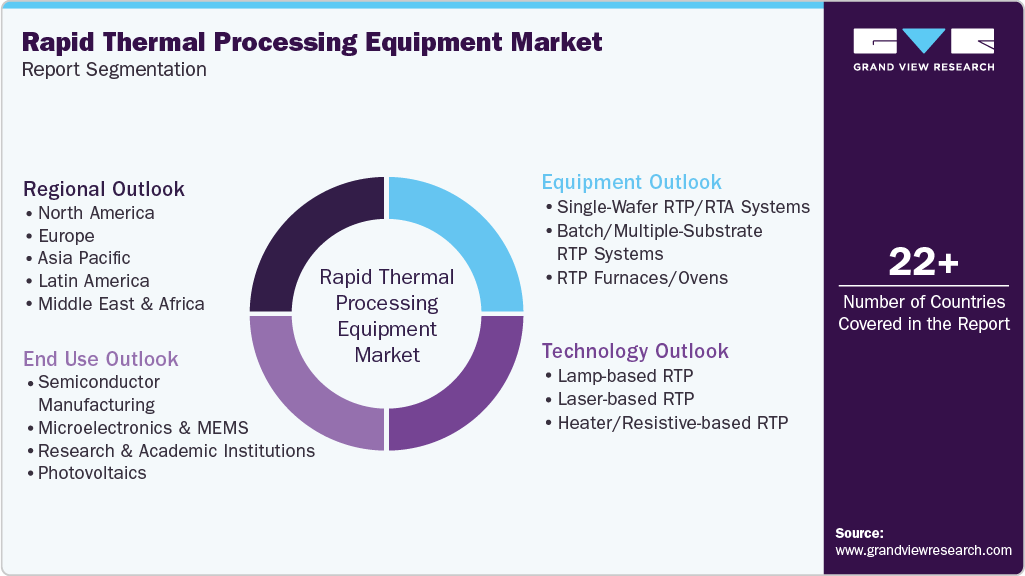
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global rapid thermal processing equipment market report based on equipment, technology, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Equipment Outlook (Revenue, USD Million, 2021 - 2033)
-
Single-Wafer RTP/RTA Systems
-
Batch/Multiple-Substrate RTP Systems
-
RTP Furnaces/Ovens
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Lamp-based RTP
-
Laser-based RTP
-
Heater/Resistive-based RTP
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Semiconductor Manufacturing
-
Microelectronics & MEMS
-
Research & Academic Institutions
-
Photovoltaics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
-
Asia Pacific
-
-
China
-
India
-
Japan
-
South Korea
-
Taiwan
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Israel
-
South Africa
-
-
Research Methodology
The rapid thermal processing equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each rapid thermal processing (RTP) equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Equipment
Revenue Capture Definition
Single-Wafer RTP/RTA Systems
Revenue generated from the sale of systems designed to thermally process individual semiconductor wafers through rapid heating, annealing, and controlled cooling cycles.
Batch/Multiple-Substrate RTP Systems
Revenue generated from equipment capable of processing multiple wafers or substrates simultaneously within a controlled thermal environment.
RTP Furnaces/Ovens
Revenue generated from rapid thermal furnaces and ovens used for controlled heating, annealing, oxidation, curing, and related substrate-processing applications.
Technology
Revenue Capture Definition
Lamp-based RTP
Revenue attributable to RTP systems that use high-intensity lamps or infrared radiation as the primary heat source for rapid substrate processing.
Laser-based RTP
Revenue generated from thermal-processing systems using laser energy for highly localized, rapid, or ultra-short-duration heating and annealing applications.
Heater/Resistive-based RTP
Revenue generated from RTP equipment that uses electrically powered resistive heating elements to achieve controlled substrate temperatures.
End Use
Revenue Capture Definition
Semiconductor Manufacturing
Revenue derived from RTP equipment supplied to semiconductor fabrication facilities for wafer-processing steps such as dopant activation, annealing, oxidation, and thin-film treatment.
Microelectronics & MEMS
Revenue generated from RTP systems used in the production of MEMS, sensors, microelectronic components, and other miniaturized electronic devices.
Research & Academic Institutions
Revenue from RTP equipment purchased by universities, research centers, government laboratories, and R&D facilities for material studies, process development, and experimental wafer processing.
Photovoltaics
Revenue generated from RTP systems used in solar-cell and photovoltaic manufacturing processes, including annealing, dopant activation, film treatment, and contact-related thermal processing.
Estimation Model
Layer Name
Key Question
Description
Market Size
What is the overall addressable market?
Identify the global demand for semiconductor and substrate thermal-processing equipment, including applications where rapid heating, annealing, and controlled cooling are required.
Equipment & Technology Scope
What portion relates specifically to RTP equipment?
Determine the share attributable to Single-Wafer RTP/RTA Systems, Batch/Multiple-Substrate RTP Systems, and RTP Furnaces/Ovens, further segmented by lamp-based, laser-based, and heater/resistive technologies.
End-Use & Regional Allocation
Where is RTP equipment purchased and deployed?
Allocate equipment demand across semiconductor manufacturing, microelectronics & MEMS, research & academic institutions, and photovoltaics, followed by country and regional deployment patterns.
Revenue
What is the resulting market revenue?
Calculate total RTP equipment revenue by aggregating equipment sales across technologies, end-use applications, and geographic markets, using manufacturer revenues, shipment volumes, pricing information, and validated market estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The report provided a detailed regional and country-level assessment of the Rapid Thermal Processing Equipment Market, covering North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, along with key country-level market trends and growth factors.
Enabled the client to identify regional demand centers, understand geographic growth patterns, and assess expansion opportunities across established and emerging semiconductor manufacturing hubs.
Competitive Benchmarking
The report included a comprehensive competitive assessment of major RTP equipment manufacturers, covering company positioning, product portfolios, operating strategies, competitive advantages, weaknesses, and market participant categorization into established and emerging players.
Provided a structured view of the competitive landscape, helping the client understand supplier capabilities, differentiation areas, technology strengths, and competitive positioning within the RTP equipment market.
Opportunity Assessment
The report evaluated key market drivers, restraints, technology developments, end-use trends, regional opportunities, and emerging applications, with specific focus on advanced semiconductor manufacturing, laser-based processing, and growing microelectronics & MEMS demand.
Helped identify high-potential application areas, technology shifts, and geographic opportunities that can support strategic planning, investment decisions, and future market expansion.
Frequently Asked Questions About This Report
Latin America is the fastest-growing region over the forecast period.
Semiconductor manufacturing dominated the market with a 76.8% revenue share in 2025, driven by the growing need for rapid annealing, dopant activation, oxidation, and other thermal processes in wafer fabrication.
Some of the key players operating in the global rapid thermal processing equipment market include Applied Materials, Inc.; Tokyo Electron Limited; Mattson Technology; Veeco Instruments Inc.; Annealsys; JTEKT Thermo Systems Corporation; Centrotherm; ECM Group; CVD Equipment Corporation; SemiTEq JSC; SCREEN Semiconductor Solutions Co., Ltd.; HQ-Dielectrics GmbH; Plasma-Therm; ADVANCE RIKO, Inc.; Anarghya Innovations and Technology.
Rising semiconductor fabrication capacity, increasing demand for advanced and miniaturized chips, greater adoption of precise low-thermal-budget processing, and continued investments in foundries and advanced wafer manufacturing are driving market growth. Expanding applications in MEMS, microelectronics, power devices, and photovoltaics also support demand.
The global rapid thermal processing equipment market size was valued at USD 870.4 million in 2025 and is estimated at USD 927.5 million in 2026.
The global rapid thermal processing equipment market, in terms of revenue, is expected to grow at a compound annual growth rate of 6.9% from 2026 to 2033, reaching USD 1,484.3 million by 2033.
Asia Pacific was the largest regional market, accounting for 86.6% of global revenue in 2025.
Single-wafer RTP/RTA systems led the market, accounting for 80.8% of global revenue in 2025 while batch/multiple-substrate RTP systems is expected to be the fastest-growing market.
Lamp-based RTP held the largest share, representing 79.7% of market revenue in 2025 while Laser-based RTP is expected to be the fastest-growing market.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


