
- Home
- »
- Plastics, Polymers & Resins
- »
-
Refillable Packaging Market Size & Share Report, 2026-2033GVR Report cover

Refillable Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Pallets & Crates, Bottles & Containers), By End-use (Food & Beverage, Cosmetics & Personal Care, Household Care, Chemicals), By Region, And Segment Forecasts
Market Size, 2025
$47.5BMarket Estimate, 2026
$49.7BMarket Forecast, 2033
$78.2BCAGR, 2026–2033
6.7%Refillable Packaging Market Summary
The global refillable packaging market size was valued at USD 47.5 billion in 2025 and is projected to grow from USD 49.7 billion in 2026 to USD 78.2 billion by 2033, at a CAGR of 6.7% from 2026 to 2033. Asia Pacific market dominated, with a revenue share of 46.4% in 2025. One of the primary drivers of the refillable packaging industry is the growing consumer awareness of environmental issues, particularly related to plastic pollution and waste generation.
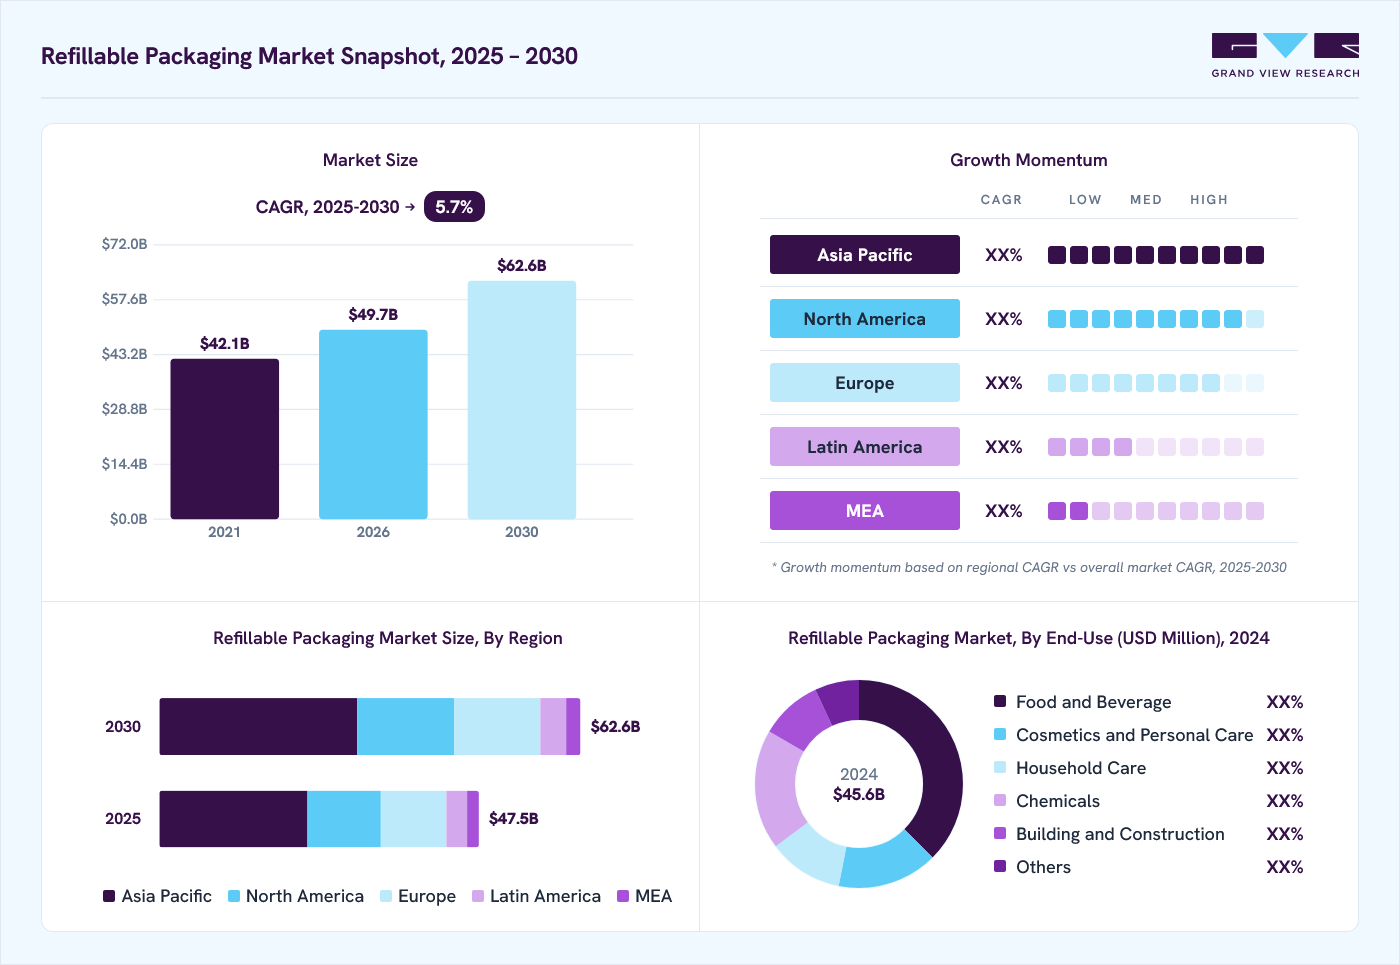 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Pallets and crates segment led the market with the largest revenue share of 32.4% in 2025.
- By end-use: Food & beverage segment led the market with the largest revenue share of 37.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (46.4% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 47.5 Billion
- Estimated market size in 2026: USD 49.7 Billion
- Projected market size by 2033: USD 78.2Billion
- CAGR (2026-2033): 6.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Consumers are actively seeking eco-friendly alternatives to traditional single-use packaging, leading brands and retailers to adopt refillable packaging models as a sustainable solution. With the rise of conscious consumerism, people are making purchasing decisions based on packaging sustainability, recyclability, and reusability. This shift in consumer behavior is driving the demand for refill stations, refillable bottles, and refill pouches, particularly in sectors such as personal care, household cleaning, and food & beverage.
Many governments and organizations are also conducting awareness campaigns to educate consumers about the benefits of refillable and refillable packaging, further encouraging adoption. In addition, refill-on-the-go stations in supermarkets, retail stores, and specialty stores are gaining popularity, allowing customers to reuse their existing packaging instead of purchasing new plastic containers, which significantly reduces waste generation and carbon footprints.
The personal care, beauty, and household cleaning industries are at the forefront of the refillable packaging revolution, with major brands transitioning to refillable and refillable solutions. Consumers are increasingly drawn to products that offer sustainability without compromising convenience, making refillable models highly attractive. Leading beauty and skincare companies like L’Oréal, Unilever, and P&G have introduced refill stations, refillable aluminum bottles, and compostable refills for products such as shampoo, conditioner, body wash, and facial creams.
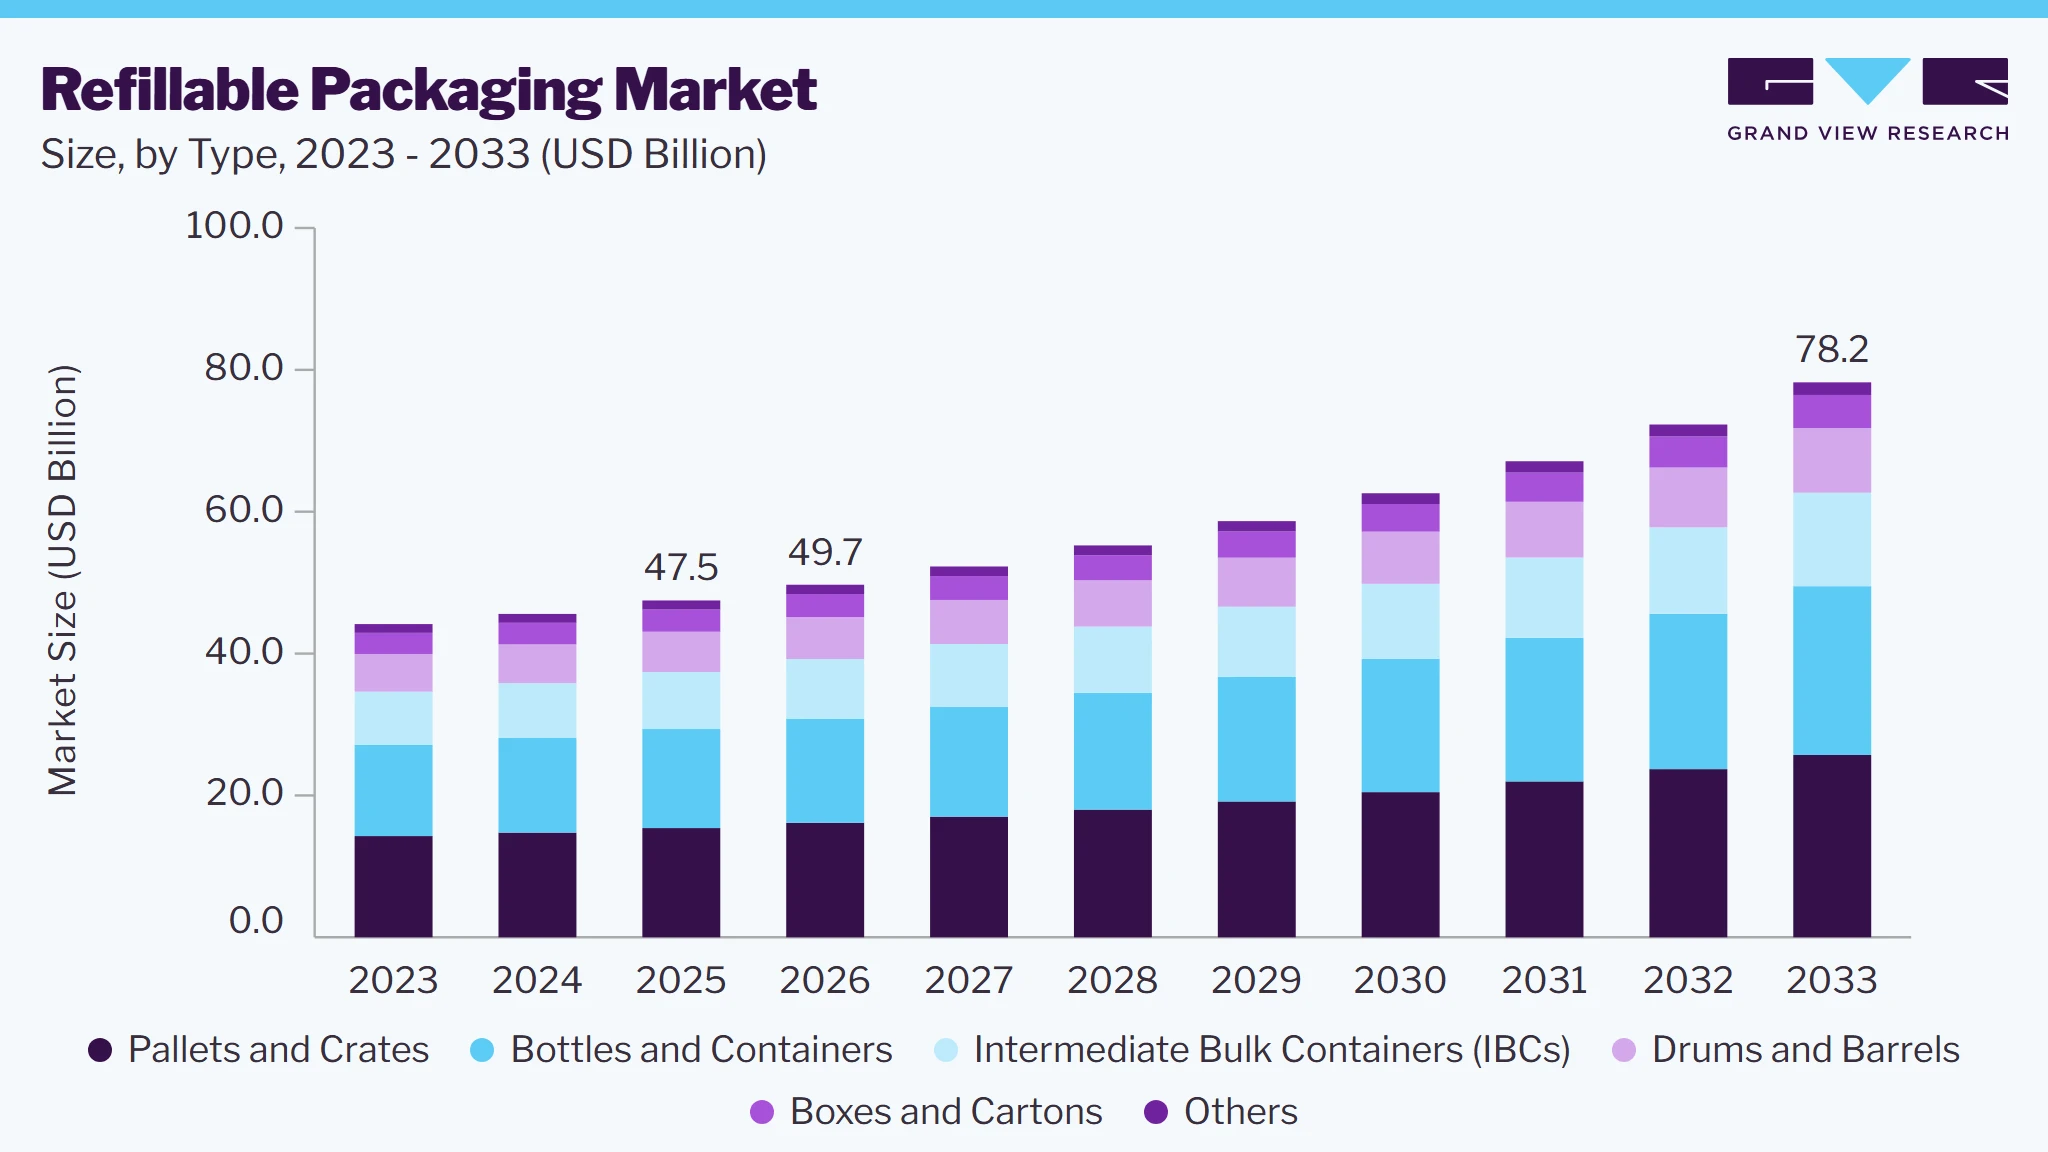 To learn more about this report, Download Free Sample Report
Similarly, in the household cleaning segment, brands are launching concentrated refill pods and refill pouches that significantly reduce plastic waste compared to conventional single-use bottles. Products like dishwashing liquids, detergents, and surface cleaners are now available in waterless or concentrated formats, allowing consumers to reuse their original containers multiple times, thereby cutting down on plastic production and disposal. This shift toward refillable household and personal care products is expected to continue growing as consumers demand more environmentally friendly options from manufacturers.
Governments worldwide are enforcing strict regulations and sustainability initiatives to curb plastic waste and promote circular economy models. Several countries have introduced bans or restrictions on single-use plastics, driving industries to adopt alternative packaging solutions such as refillable containers, refillable glass bottles, and compostable packaging. For instance, Europe’s Single-Use Plastics Directive (SUPD) and Extended Producer Responsibility (EPR) programs encourage businesses to switch to eco-friendly packaging formats and invest in closed-loop refill systems. Similarly, in the United States and Canada, many states and provinces have introduced plastic waste reduction policies, urging companies to offer refillable or refillable packaging to meet regulatory compliance.
In Asia-Pacific, countries like Japan, China, and India are also witnessing growing governmental pressure to reduce plastic consumption and encourage sustainable alternatives. Several brands in these regions are launching refillable packaging solutions to align with the United Nations’ Sustainable Development Goals (SDGs) and regional waste management policies. As regulations continue to tighten, businesses across various industries are investing in refill stations, bulk dispensers, and durable packaging materials to comply with these mandates and maintain market competitiveness.
Market Dynamics
The refillable packaging market is growing steadily, driven by increasing demand for sustainable packaging, stricter regulations on single-use plastics, and rising adoption of circular economy practices. Expanding refill and reuse programs across personal care, home care, food & beverage, and healthcare sectors, along with advancements in durable packaging materials and dispensing technologies, are supporting market growth. However, higher upfront costs, reverse logistics challenges, and the need for greater consumer participation continue to influence market adoption.
The growing emphasis on sustainability is the primary driver of the refillable packaging market. Consumers are increasingly choosing reusable and refillable packaging options to reduce plastic waste and minimize environmental impact. At the same time, governments worldwide are implementing stricter regulations on single-use plastics and promoting circular economy practices, encouraging brands to adopt refillable packaging solutions. This shift is particularly evident across the personal care, home care, food & beverage, and household products sectors.
In response, leading consumer goods companies and retailers are expanding refill and reuse programs while investing in durable, recyclable packaging designs and refill infrastructure. Innovations such as in-store refill stations, refill pouches, and smart dispensing systems are improving convenience and encouraging consumer participation. As sustainability commitments become a core business priority, the adoption of refillable packaging is expected to accelerate across both developed and emerging markets.
A significant restraint for the refillable packaging market is the high initial investment required for durable packaging, refill infrastructure, and reverse logistics systems. Implementing collection, cleaning, sanitization, and redistribution processes increases operational complexity and costs for manufacturers and retailers. Furthermore, inconsistent consumer participation in returning packaging and limited refill infrastructure in many regions can reduce the efficiency and scalability of refill programs, slowing broader market adoption.
The expansion of refill infrastructure and retail partnerships presents a significant opportunity for the refillable packaging market. Increasing investments in in-store refill stations, automated dispensing systems, and e-commerce refill subscription models are making refillable packaging more accessible and convenient for consumers. As retailers and consumer goods companies strengthen collaborations to support circular economy initiatives and reduce packaging waste, the adoption of refillable packaging is expected to expand across personal care, home care, food & beverage, and healthcare applications.
Analyst Perspective
The refillable packaging market is expected to grow steadily, driven by increasing demand for sustainable packaging, rising adoption of circular economy practices, and stricter regulations on single-use plastics. Expanding refill and reuse programs across food & beverage, cosmetics & personal care, household care, and chemical industries are supporting market growth. Furthermore, advancements in durable packaging materials and refill infrastructure are expected to strengthen market adoption and competitiveness.
Type Insights
Based on type, the pallets and crates segment led the market with the largest revenue share of 32.4% in 2025. Pallets and crates are essential components of global supply chains, playing a crucial role in the transportation, storage, and distribution of goods across various industries. As global trade and e-commerce continue to expand, the demand for efficient, durable, and refillable packaging solutions has surged, with pallets and crates emerging as the preferred choice due to their high load-bearing capacity, easy handling, and compatibility with automated logistics systems. These packaging types facilitate bulk shipping and optimized space utilization, making them indispensable for warehousing, freight transport, and cargo management.
Unlike other types of packaging, such as bottles or cartons, pallets and crates allow for the safe stacking and efficient movement of heavy and oversized goods, significantly reducing handling time and transportation costs. The rise of automated warehouses and conveyor-based logistics systems has further fueled the demand for standardized, refillable pallets and crates that integrate seamlessly with forklifts, automated guided vehicles (AGVs), and robotic picking systems. This growing reliance on efficient and sustainable transport solutions has cemented the dominance of pallets and crates in the global refillable packaging industry.
Moreover, pallets and crates provide a cost-effective and long-term packaging solution compared to single-use alternatives such as boxes, cartons, or shrink-wrapped packages. Wooden and plastic pallets can withstand multiple reuse cycles, significantly reducing packaging costs over time for industries that handle large volumes of shipments. Unlike Intermediate Bulk Containers (IBCs) or barrels, which are primarily used for liquid and chemical storage, pallets and crates are versatile and can be used across multiple industries, from retail to automotive and pharmaceuticals.
End Use Type Insights
Based on end-use, the food & beverage segment led the market with the largest revenue share of 37.5% in 2025, and is forecasted to grow at a rapid CAGR over the forecast period. The Food & Beverage (F&B) industry is the largest end-use segment in the global refillable packaging industry due to its high demand for durable, cost-effective, and hygienic packaging solutions. Refillable packaging such as crates, pallets, trays, and bulk containers plays a crucial role in food distribution, processing, and retail supply chains, ensuring efficient handling and transportation of perishable goods.
Supermarkets, grocery stores, and food distributors are increasingly adopting returnable plastic crates (RPCs), wooden pallets, and bulk bins to enhance the efficiency of their supply chains while minimizing single-use packaging waste. These packaging formats provide better protection for fresh produce, dairy, meat, and baked goods, ensuring extended shelf life and reduced spoilage. Unlike disposable cardboard boxes, refillable food crates offer superior ventilation and stackability, making them a preferred choice for farm-to-retail logistics.
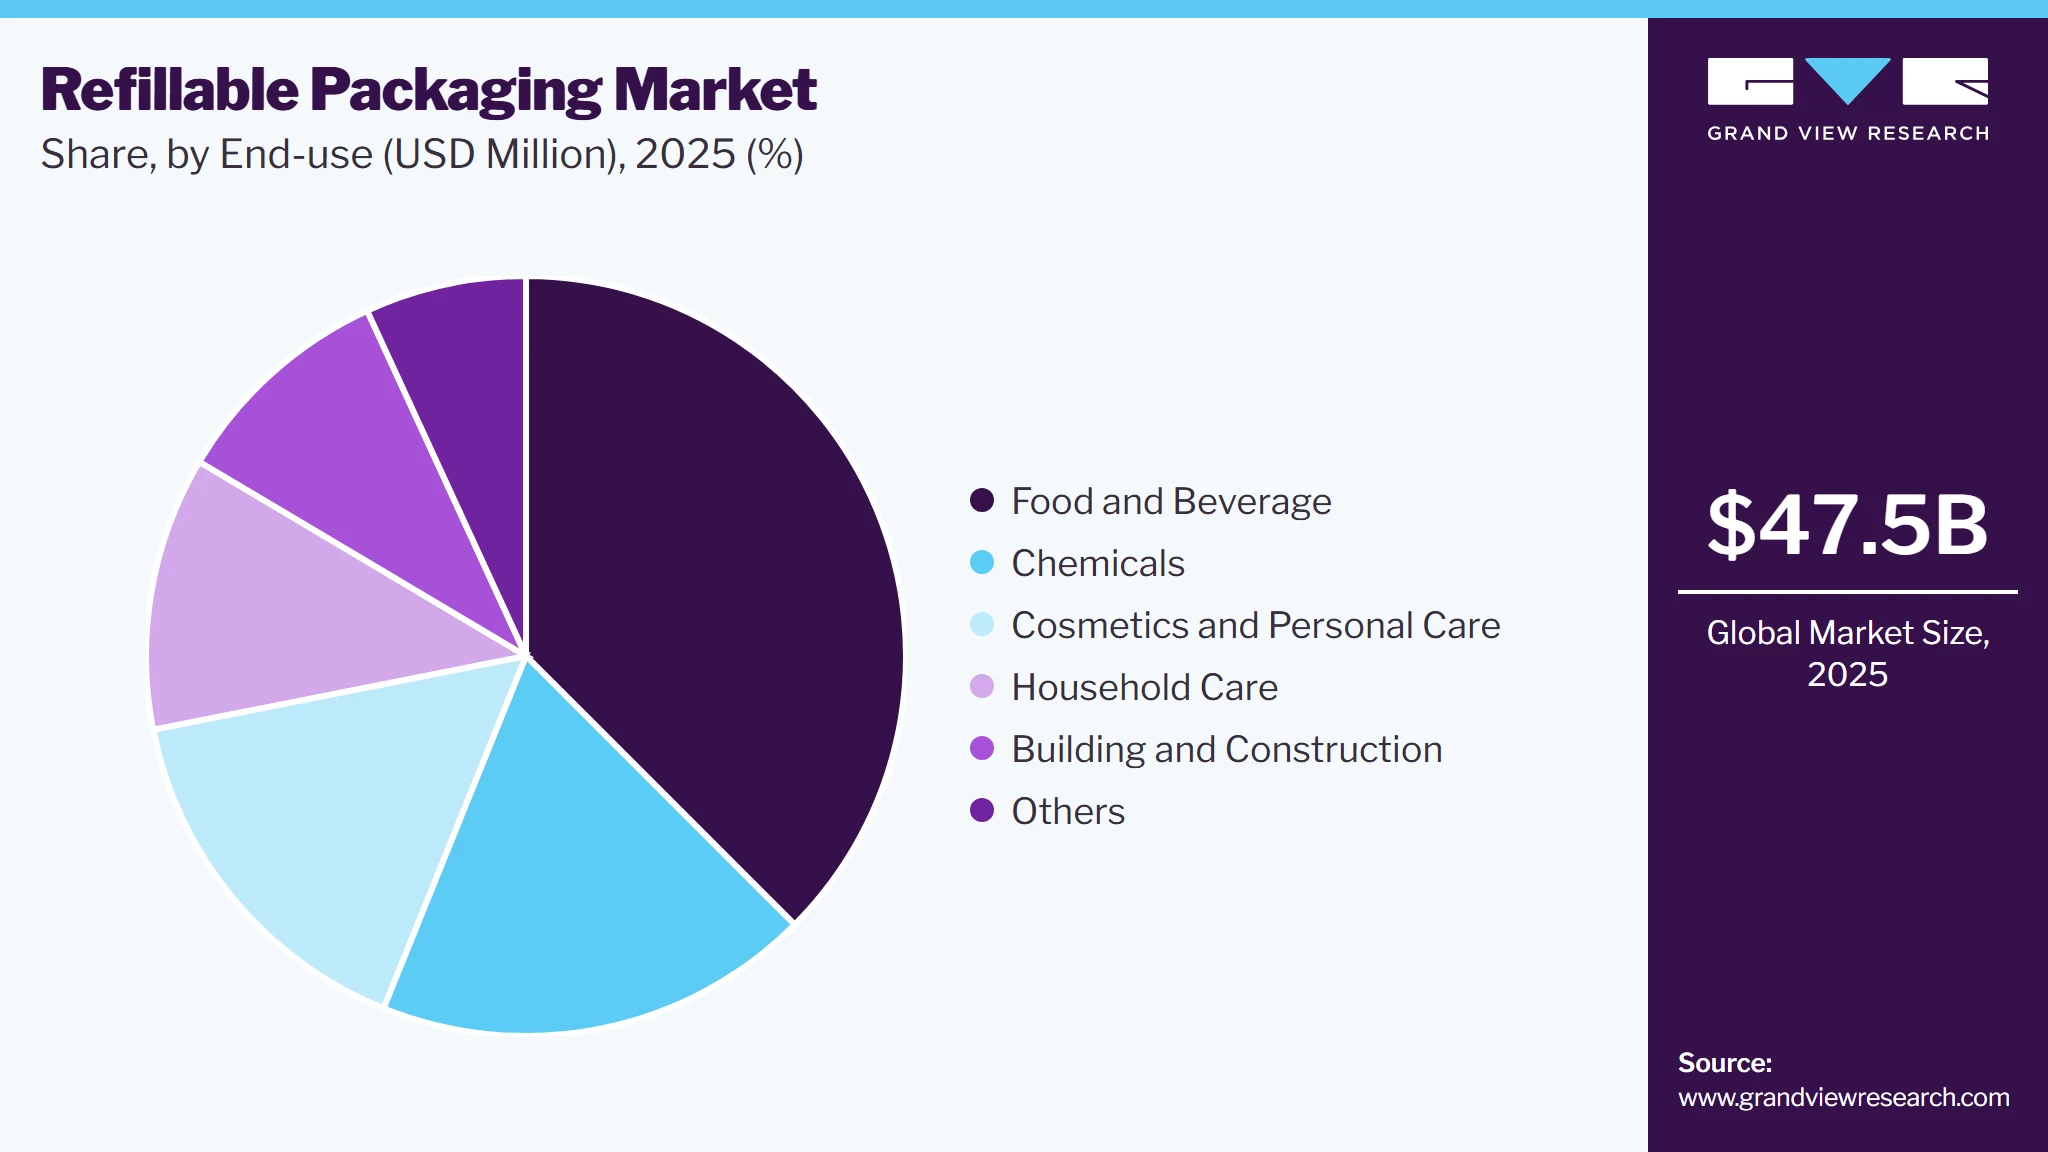 To learn more about this report, Download Free Sample Report
Furthermore, sustainability concerns are driving the transition from single-use to refillable packaging in the food & beverage sector. Governments worldwide are implementing strict regulations on single-use plastics, encouraging businesses to switch to recyclable and refillable alternatives. Companies are increasingly investing in circular packaging systems, where refillable containers, bottles, and crates are collected, sanitized, and reintroduced into the supply chain, reducing overall waste and carbon emissions.
For instance, many beverage brands are reintroducing refillable glass bottles and aluminum cans, reducing reliance on disposable plastic bottles. Similarly, the rise of zero-waste grocery stores and bulk refill stations is further propelling demand for returnable packaging formats, including stainless steel, glass, and refillable plastic containers. As sustainability continues to be a top priority for food and beverage brands, the dominance of this segment in the refillable packaging industry is expected to persist.
Region Insights
The refillable packaging market in North America is growing due to the rise of e-commerce, increasing corporate sustainability goals, and consumer-driven preferences for eco-friendly alternatives. Major retail and FMCG brands are investing in closed-loop packaging systems and sustainable supply chains to meet environmental commitments. The expansion of bulk refill stations in grocery stores, along with the adoption of returnable transport packaging (RTP) in logistics and warehousing, is contributing to market growth. In addition, industries like automotive, agriculture, and pharmaceuticals are increasingly shifting toward durable, refillable containers and bulk bins to optimize efficiency and reduce waste.
U.S. Refillable Packaging Market Trends
The refillable packaging market in the U.S.demand is primarily driven by regulatory pressures, corporate sustainability initiatives, and consumer demand for waste reduction. Many states, such as California, New York, and Oregon, have implemented plastic bans and extended producer responsibility (EPR) laws, encouraging businesses to transition to refillable, returnable, and recyclable packaging models. The growth of sustainable e-commerce packaging solutions, along with the increasing popularity of subscription-based refill programs, has fueled demand in sectors like food & beverage, cosmetics, and household care. In addition, logistics and retail giants such as Amazon and Walmart are exploring refillable pallet pooling systems and collapsible bulk containers to enhance supply chain efficiency while minimizing environmental impact.
Asia Pacific Refillable Packaging Market Trends
Asia Pacific dominated the refillable packaging market with the largest revenue share of 46.4% in 2025 and is anticipated to grow at the fastest CAGR of 6.0% over the forecast period. The demand for refillable packaging in Asia Pacific is growing rapidly due to urbanization, e-commerce expansion, and increasing government initiatives to reduce plastic waste. With rising industrial activity and global trade, businesses in the region are prioritizing cost-effective and sustainable packaging solutions, particularly in logistics, food & beverage, and consumer goods. Countries like India, Japan, and South Korea are implementing stricter regulations on single-use plastics, encouraging the use of returnable crates, pallets, and bulk transport packaging. In addition, the increasing penetration of e-commerce platforms and automated supply chains is driving the adoption of durable, refillable packaging formats that ensure efficient storage, transportation, and reduced environmental impact.
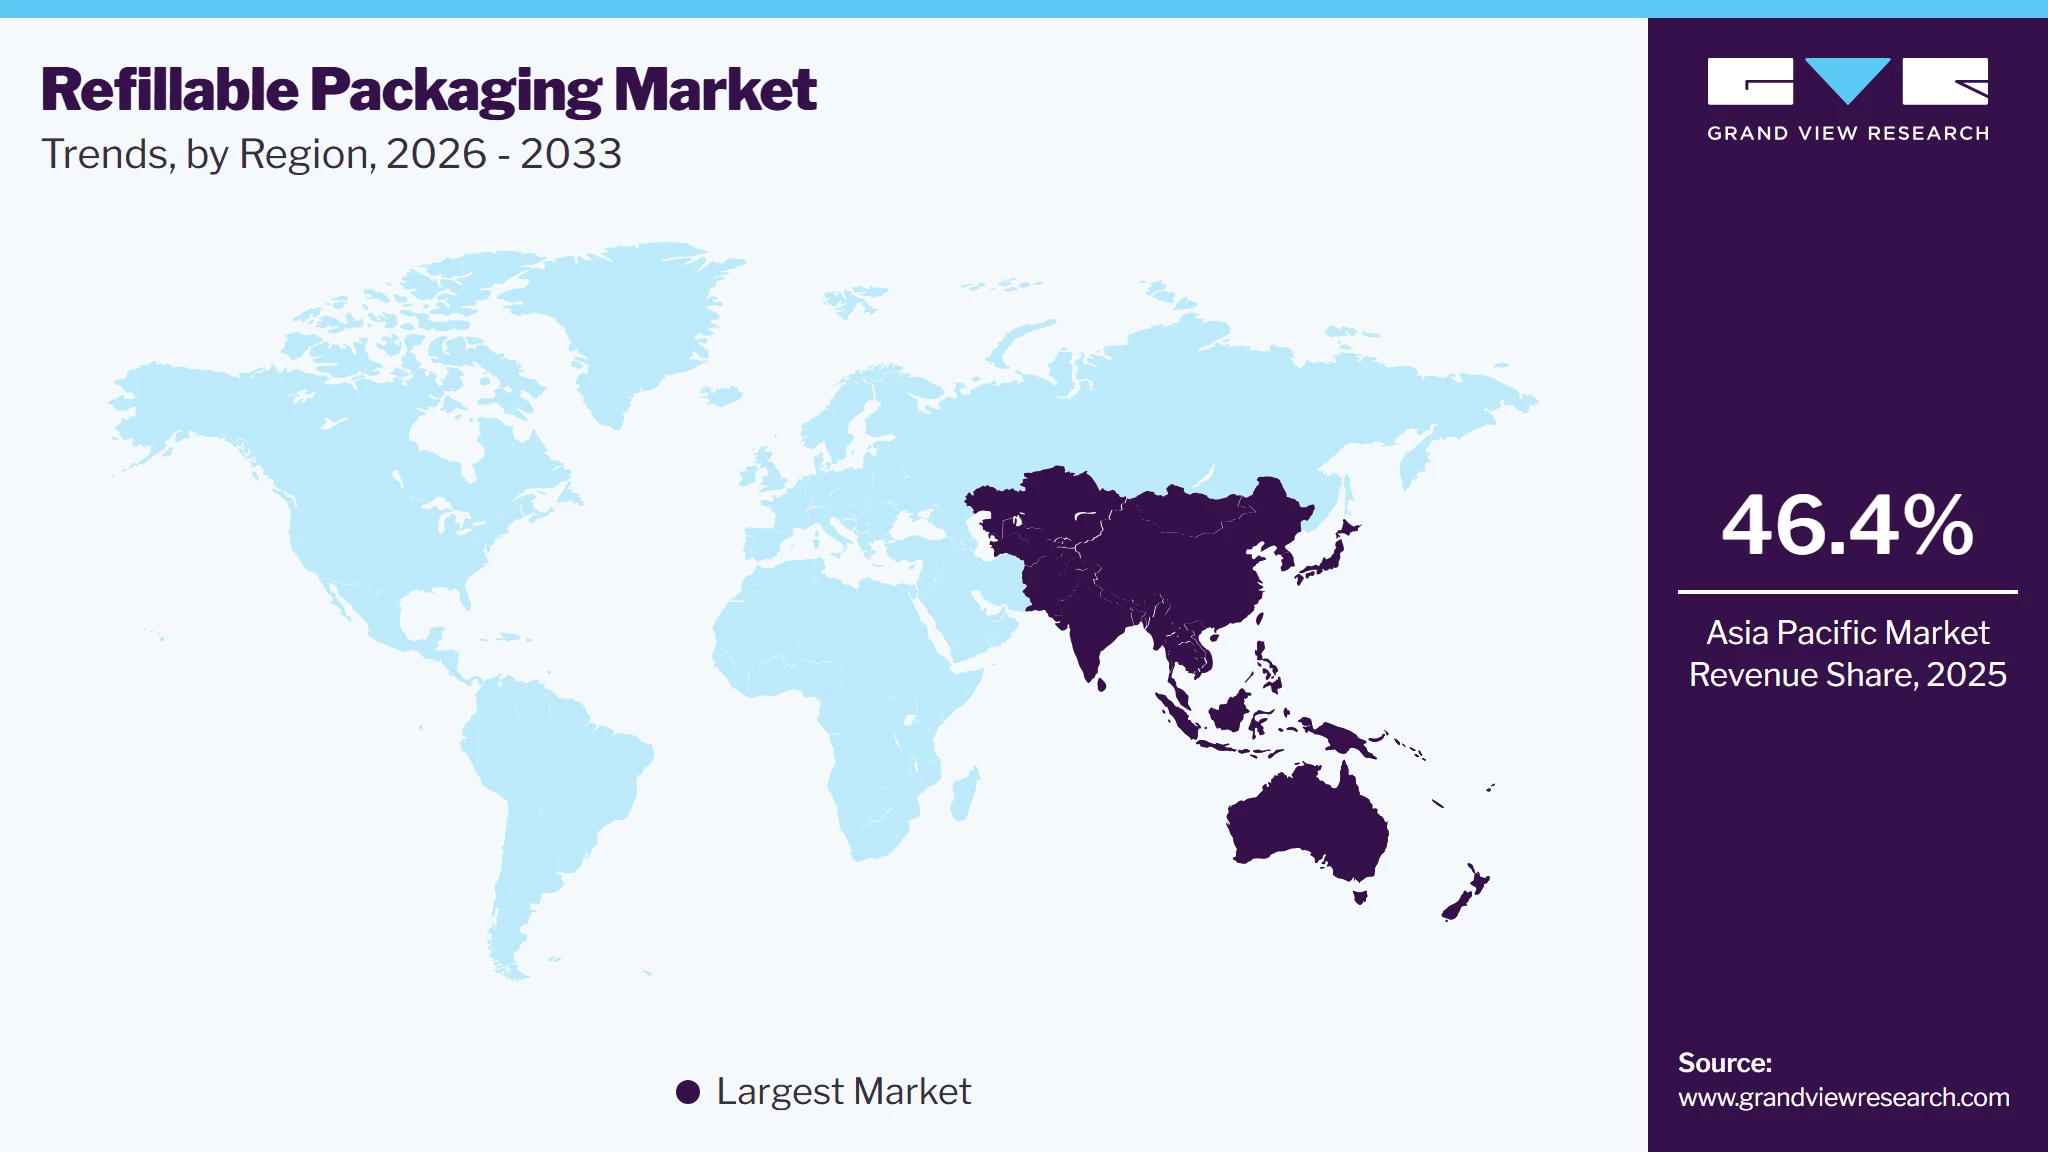 To learn more about this report, Download Free Sample Report
The refillable packaging market in China held the largest share in the Asia Pacific region in 2025. The refillable packaging market in Chinagrowth can be attributed to the production sector in the country. As the largest manufacturing and consumer market in Asia Pacific, China is leading the shift toward refillable packaging through strict waste management policies, rapid industrialization, and corporate sustainability commitments. The government's ban on single-use plastics and emphasis on a circular economy have pushed industries—especially food & beverage, retail, and logistics—toward refillable alternatives like pallets, crates, and refillable bottles. In addition, China's booming e-commerce sector, dominated by giants like Alibaba and JD.com, is investing heavily in returnable transport packaging (RTP) and smart logistics systems that prioritize durability and reusability. The large-scale adoption of refillable industrial packaging in automotive and electronics manufacturing further contributes to the growing market demand.
Europe Refillable Packaging Market Trends
The refillable packaging market in Europe has been at the forefront of refillable packaging adoption due to strict sustainability regulations and increasing consumer awareness about environmental impact. The European Union's Circular Economy Action Plan (CEAP) and Single-Use Plastics Directive have placed significant restrictions on disposable packaging, encouraging industries to shift towards refillable and returnable solutions. Many European companies, especially in the food, beverage, and cosmetics sectors, have adopted deposit-return schemes (DRS), bulk dispensing models, and refillable packaging pools to comply with regulatory mandates and meet sustainability goals. Moreover, retailers and e-commerce platforms are promoting zero-waste shopping experiences, further driving the demand for refillable bags, containers, and secondary packaging materials.
The Germany refillable packaging market is driven by sustainability and packaging innovation. The country has well-established deposit-return schemes (DRS) for beverage packaging, significantly increasing the use of refillable glass and PET bottles. In addition, Germany’s strict waste disposal laws and emphasis on circular economy practices have encouraged businesses across industries to invest in refillable transport and bulk packaging solutions. Large retailers and supermarket chains have introduced refill stations for household and personal care products, while industrial sectors such as automotive and logistics are expanding their use of returnable crates, pallets, and collapsible bulk containers to optimize costs and environmental impact.
Key Refillable Packaging Company Insights
The global refillable packaging industry is highly competitive, with key players focusing on innovation, material advancements, and sustainability-driven solutions to gain a competitive edge. Key players operating in the industry include Amcor, Sem Plastik, Double H Plastics, Greiner Packaging, Tek Pak, RPC Group, Reynolds Group, ORBIS Corporation, Sanpaca, and Plastipak Industries Inc.
These companies leverage advanced material technology, automation, and smart tracking systems to enhance the efficiency and lifespan of refillable packaging. The market is also witnessing increased strategic partnerships, mergers & acquisitions, and investments in circular economy models to strengthen market positioning. Regional players and emerging companies are focusing on customized, industry-specific refillable packaging to cater to the growing demand for sustainability, while e-commerce giants and FMCG brands are adopting closed-loop packaging systems and refill models to align with global sustainability goals. Regulatory policies, shifting consumer preferences, and advancements in smart packaging technologies are key factors intensifying competition, making innovation and scalability critical for market leadership.
Key Refillable Packaging Companies
The following key companies have been profiled for this study on the refillable packaging market.
-
Amcor plc
-
Sem Plastik
-
Double H Plastics
-
Greiner Packaging
-
Tek Pak
-
RPC Group
-
Reynolds Group
-
ORBIS Corporation
-
Sanpaca
-
Plastipak Industries Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Amcor plc, Greiner Packaging, RPC Group, Reynolds Group, ORBIS Corporation, and Plastipak Industries Inc.)
Invest in advanced refillable packaging technologies, automation, and circular economy initiatives to enhance production efficiency and sustainability.
Strengthen long-term partnerships with multinational brand owners and retailers while expanding manufacturing and collection networks across key regions.
Broad product portfolios, global manufacturing footprints, and strong financial capabilities enable them to serve diverse end-use industries at scale.
Well-established R&D capabilities and regulatory expertise facilitate the development of innovative, durable, and compliant refillable packaging solutions.
Large operational structures and extensive manufacturing networks result in higher fixed costs and slower response to rapidly changing customer requirements.
Dependence on mature markets and complex supply chains can limit flexibility and affect profitability during economic or raw material price fluctuations.
Emerging Players (Sem Plastik, Double H Plastics, Tek Pak, and Sanpaca)
Focus on customized refillable packaging solutions for regional customers and niche applications, emphasizing flexibility and shorter production lead times.
Expand market presence through strategic collaborations, product innovation, and investments in sustainable manufacturing capabilities.
Agile organizational structures enable faster product customization and quicker adaptation to evolving customer and sustainability requirements.
Strong regional market knowledge and close customer engagement support tailored solutions and responsive technical service.
Limited financial resources and manufacturing capacity restrict large-scale expansion and investments in advanced production technologies.
Lower global brand recognition and narrower distribution networks make it challenging to compete with established multinational packaging companies for large contracts.
Recent Development
-
In December 2022, PepsiCo declared a global packaging objective to increase from 10% to 20% by 2033 the proportion of beverage servings it sells that are supplied in refillable models. This goal is a component of PepsiCo Positive (pep+), the company's end-to-end, strategic business transformation that centers on people and sustainability as the primary means of generating growth and value. In order to radically change the way that people drink beverages, it will be necessary to provide refillable and refillable solutions that are widely available and easy for customers.
-
In February 2023, An international pioneer in creating and manufacturing environmentally friendly packaging solutions invested $250,000 in the third Lift-Off initiative winner from Amcor, circulation, a smart refillable food packaging start-up. Launched in April 2022, Amcor Lift-Off seeks breakthrough, state-of-the-art solutions that will further advance Amcor's objective to make the future of packaging more sustainable.
Refillable Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 47.5 billion
Estimated market size in 2026
USD 49.7 billion
Projected market size by 2033
USD 78.2 billion
Growth rate
CAGR of 6.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Amcor; Sem Plastik; Double H Plastics; Greiner Packaging; Tek Pak; RPC Group; Reynolds Group; ORBIS Corporation; Sanpaca and Plastipak Industries Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Refillable Packaging Market Report Segmentation
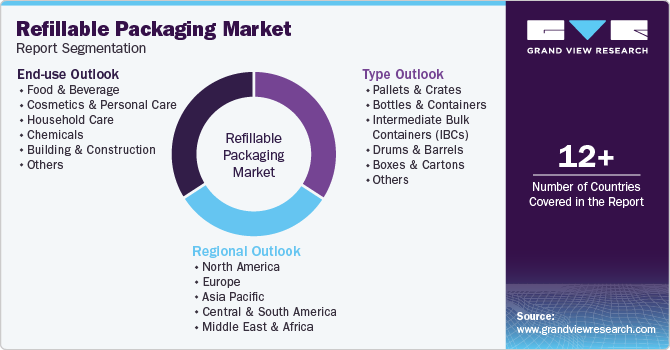
This report forecasts revenue growth at a global level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global refillable packaging market report based on type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Pallets and Crates
-
Bottles and Containers
-
Intermediate Bulk Containers (IBCs)
-
Drums and Barrels
-
Boxes and Cartons
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Food and Beverage
-
Cosmetics and Personal Care
-
Household Care
-
Chemicals
-
Building and Construction
-
Others
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The refillable packaging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each refillable packaging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Pallets and Crates
Revenue generated from the sale of refillable pallets and crates designed for repeated handling, storage, and transportation of goods. This segment includes reusable plastic, metal, and wooden pallets and crates used across food & beverage, retail, logistics, agriculture, and industrial supply chains.
Bottles and Containers
Revenue generated from the sale of refillable bottles and containers intended for multiple use cycles. This segment includes reusable packaging for beverages, personal care, household care, food products, and pharmaceutical applications made from materials such as glass, plastic, and metal.
Intermediate Bulk
Containers (IBCs)
Revenue generated from the sale of refillable intermediate bulk containers designed for the bulk storage and transportation of liquids and semi-liquids. This segment includes reusable IBCs used in chemical, food & beverage, pharmaceutical, and industrial applications.
Drums and Barrels
Revenue generated from the sale of refillable drums and barrels used for the repeated storage and transportation of liquids, powders, and hazardous materials. This segment includes reusable steel, plastic, and fiber drums utilized in chemicals, food processing, lubricants, and industrial sectors.
Boxes and Cartons
Revenue generated from the sale of refillable boxes and cartons designed for multiple distribution and return cycles. This segment includes reusable corrugated, plastic, and foldable boxes used in retail, e-commerce, food distribution, and logistics applications.
Others
Revenue generated from the sale of other refillable packaging formats, including pails, totes, kegs, canisters, jars, and specialized reusable transport packaging designed for repeated use across various end-use industries.
Segment - End Use
Revenue capture definition
Food and Beverage
Revenue generated from the sale of refillable packaging used for food, dairy, beverages, and other consumable products. This segment includes reusable bottles, containers, crates, kegs, and transport packaging designed to support circular packaging systems.
Chemicals
Revenue generated from the sale of refillable packaging used for storing and transporting industrial and specialty chemicals. This segment includes reusable drums, IBCs, containers, and other durable packaging designed to safely handle hazardous and non-hazardous chemicals.
Cosmetics and Personal Care
Revenue generated from the sale of refillable packaging for cosmetics, skincare, haircare, fragrances, and personal hygiene products. This segment includes reusable bottles, jars, dispensers, and refill systems that reduce single-use packaging waste.
Household Care
Revenue generated from the sale of refillable packaging for household cleaning and maintenance products. This segment includes reusable bottles, containers, dispensers, and refill packs used for detergents, surface cleaners, and related products.
Building and Construction
Revenue generated from the sale of refillable packaging used for paints, coatings, adhesives, sealants, and construction chemicals. This segment includes reusable pails, drums, containers, and bulk packaging designed for repeated industrial use.
Others
Revenue generated from the sale of refillable packaging used across additional industries, including healthcare, agriculture, automotive, retail, and industrial manufacturing, where durable reusable packaging supports efficient logistics and sustainability initiatives.
Estimation Model
Layer Name
Key Question
Description
Reusable Packaging Demand Base Layer
What forms the demand base?
Identify global demand for refillable packaging across major end-use industries, including food & beverage, chemicals, cosmetics & personal care, household care, building & construction, healthcare, and industrial applications. This layer establishes the total addressable demand driven by sustainability initiatives, circular economy adoption, and reusable packaging programs.
Refill & Reuse Adoption Layer
Where is refillable packaging utilized?
Estimate the penetration of refillable packaging across different packaging formats and end-use industries. Assess adoption levels of reusable bottles, containers, pallets, crates, drums, IBCs, and boxes across developed and emerging markets, considering regulatory support, consumer acceptance, and retailer participation in refill and return systems.
Packaging Circulation & Supply Chain Layer
How much refillable packaging is circulated?
Analyze the number of refill and reuse cycles, return rates, collection efficiency, cleaning and sanitization capacity, reverse logistics infrastructure, and inventory turnover. Packaging circulation intensity is influenced by product durability, transportation networks, end-use requirements, and regional recycling and reuse ecosystems.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale, leasing, and lifecycle management of refillable packaging solutions, including pallets, crates, bottles, containers, IBCs, drums, barrels, and boxes. Revenue is generated from recurring demand for durable reusable packaging, refill systems, reverse logistics services, packaging maintenance, cleaning and sanitization, and replacement across consumer and industrial end-use industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation Analysis
Delivered detailed market size, forecasts, and demand analysis for North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa, along with country-level insights for key refillable packaging markets.
Enabled identification of regional growth opportunities, evolving sustainability regulations, refill infrastructure development, and end-use demand trends across mature and emerging markets.
Cross-Segmentation Analysis
Provided detailed cross-analysis of the market across Type (Pallets and Crates, Bottles and Containers, Intermediate Bulk Containers (IBCs), Drums and Barrels, Boxes and Cartons, Others) and End-use (Food and Beverage, Chemicals, Cosmetics and Personal Care, Household Care, Building and Construction, Others) to evaluate product adoption, application trends, and growth potential.
Helped identify high-growth product-end-use combinations, customer demand patterns, and targeted expansion opportunities across diverse industrial sectors.
Competitive Benchmarking
Benchmarked leading refillable packaging manufacturers based on product portfolio by packaging type, geographic presence, manufacturing capabilities, sustainability initiatives, reusable packaging solutions, strategic partnerships, innovation pipeline, and recent developments.
Supported competitive positioning, product portfolio evaluation, partnership decisions, and identification of differentiation opportunities within the refillable packaging market.
Frequently Asked Questions About This Report
Key players in the refillable packaging market include Amcor; Sem Plastik; Double H Plastics; Greiner Packaging; Tek Pak; RPC Group; Reynolds Group; ORBIS Corporation; Sanpaca and Plastipak Industries Inc.
Key factors driving the refillable packaging market include rising demand for sustainable packaging, stricter regulations on single-use plastics, growing adoption of refill and reuse models, increasing consumer environmental awareness, and advancements in durable packaging materials and refill systems.
The global refillable packaging market is expected to grow at a CAGR of 6.7% from 2026 to 2033, reaching USD 78.2 billion by 2033.
Pallets and crates segment led the market with the largest revenue share of 32.4% in 2025.
The global refillable packaging market size was valued at USD 47.5 billion in 2025 and is estimated at USD 49.7 billion for 2026.
Food & beverage segment led the market with the largest revenue share of 37.5% in 2025.
Asia Pacific market dominated, with a revenue share of 46.4% in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


