
- Home
- »
- Catalysts & Enzymes
- »
-
Refinery Catalyst Market Size, Share & Trends Report, 2033GVR Report cover

Refinery Catalysts Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Zeolite, Metallic, Chemical Compounds), By Application (FCC Catalyst, Alkylation Catalysts, Catalytic Reforming, Hydrocracking Catalysts), By Region, And Segment Forecasts
Market Size, 2025
$10.1BMarket Estimate, 2026
$10.6BMarket Forecast, 2033
$14.2BCAGR, 2026–2033
4.3%Refinery Catalysts Market Summary
The global refinery catalyst market size was valued at USD 10.1 billion in 2025 and is projected to grow from USD 10.6 billion in 2026 to USD 14.2 billion by 2033, at a CAGR of 4.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 32.5% in 2025. The market growth is driven by a convergence of structural shifts in the refining industry, evolving fuel regulations, and the push toward cleaner, higher-value product streams.
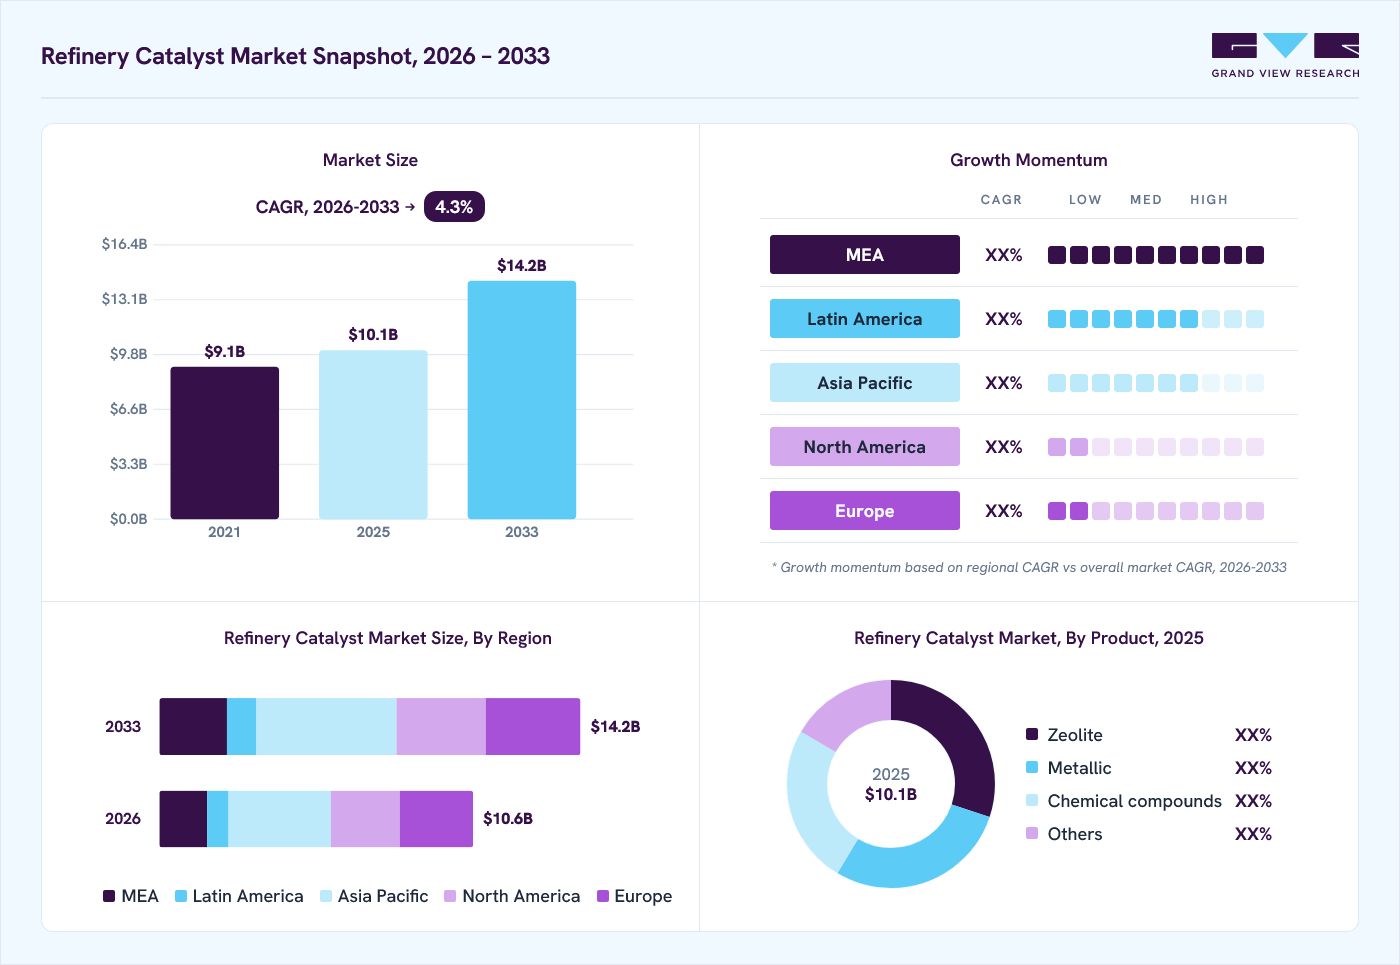 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Zeolite segment accounted for the highest market share, representing 30.1% of total revenue in 2025.
- By application: FCC catalysts held a dominant position, contributing 45.1% of total revenue in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (32.5% revenue share, 2025)
- Fastest-growing regional market: MEA (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 10.1 Billion
- Estimated market size in 2026: USD 10.6 Billion
- Projected market size by 2033: USD 14.2 Billion
- CAGR (2026-2033): 4.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
One of the strongest drivers for the growth of the refinery catalyst industry is the tightening of fuel-quality standards across major markets. Ultra-low sulfur diesel (ULSD), low-sulfur gasoline, and IMO 2020 marine fuel standards continue to elevate demand for hydrotreating, hydrodesulfurization (HDS), and hydrocracking catalysts. As refiners optimize operations to reduce sulfur, nitrogen, aromatics, and other impurities, catalyst consumption increases both in volume and complexity.Another major driver is the industry’s transition toward higher conversion and higher-value product yields. As fuel demand patterns shift-especially with the rise of petrochemical integration-refiners are investing in FCC, reforming, and alkylation catalysts to maximize propylene, aromatics, and high-octane components. This is reinforced by the global trend of processing heavier, sourer, and opportunity crudes, which require more sophisticated catalysts to maintain throughput and unit reliability.
 To learn more about this report, Download Free Sample Report
Additionally, the growing emphasis on energy efficiency and emissions reduction is pushing refiners toward catalysts that offer longer cycles, lower coke formation, reduced CO₂ footprint, and overall better unit economics. Emerging demand for renewable fuels, such as renewable diesel and sustainable aviation fuel (SAF), is also creating new opportunities for hydrotreating and isomerization catalysts tailored to bio-feedstocks.
Stringent regulations, coupled with increasing demand for petroleum and petroleum-derived products/chemicals, are likely to steer market growth. Refinery catalysts are used in the petroleum refining industry to enhance the operational efficiency of petroleum.
In addition, the increasing demand for high-octane fuel, particularly in countries such as the U.S., Japan, Germany, the UK, and India, due to stringent regulations, is expected to positively influence the growth of the market for refinery catalysts positively. Furthermore, the shift towards renewable energy sources has prompted oil refineries to optimize their operations and improve their efficiency, leading to an increased demand for advanced refinery catalysts. The market is also expected to benefit from the growing adoption of new and advanced technologies in the refining industry, which require specialized catalysts to ensure optimal performance.
Refinery catalysts are widely used to counter issues such as metal contamination and heat balance effects in tight oil processing. The increasing production of tight oil in the U.S., Russia, China, and Argentina is expected to drive market growth over the forecast period. Stringent government regulations, including those related to Ultra-Low Sulfur Diesel (ULSD) and strict emission standards in mature economies, are anticipated to remain the major factors steering demand for refinery catalysts in the petroleum refining sector. The availability of alternative fuels such as biofuels, coupled with the adoption of “Go Green” campaigns and environmental policies by several nations, is expected to restrain the market growth for refinery catalysts.
Different types of materials used in the manufacturing of refinery catalysts include zeolites, chemical compounds, and metals. These materials, when used in various compositions or in combination with other chemicals, enable manufacturers to produce fluid catalytic cracking refinery catalysts, alkylation refinery catalysts, hydrotreating refinery catalysts, and hydrocracking refinery catalysts.
Global manufacturers of refinery catalysts are highly focused on designing catalysts that can handle a wide range of feedstocks and ensure stable, reliable, easy, and profitable hydrotreating and hydrocracking applications. For the same reason, the adoption of superior process designs, proprietary equipment, and innovation of performance refinery catalysts has helped the manufacturers gain a competitive edge over others. Furthermore, a combination of technical expertise and sustainable production approaches is increasingly being adopted by manufacturers.
The global refinery catalysts market has witnessed a significant growth rate over the past few years, owing to the benefits it has received from high-value product segments. For instance, the application of catalysts in an automobile reduces carbon emissions that are harmful to the environment, and thus, their application is highly promoted by governments globally. Favorable government regulations have, in turn, increased the demand for catalysts in the automotive industry across regions.
Market Dynamics
The refinery catalyst market is influenced by evolving fuel quality regulations, changing crude oil processing requirements, and continuous investments in refinery modernization. Growing demand for cleaner transportation fuels has encouraged refiners to adopt advanced catalyst formulations that improve sulfur removal, enhance conversion efficiency, and maximize the production of high-value products from heavier crude feedstocks. Technological advancements in catalyst design, including improved activity, selectivity, and regeneration capabilities, continue to strengthen market growth by enabling longer operating cycles and reducing operational costs. At the same time, fluctuations in crude oil prices and high catalyst development costs can affect capital investment decisions and replacement cycles, creating challenges for market participants. Rising global energy consumption, expanding refining capacities in developing economies, and increasing adoption of residue upgrading technologies present significant growth opportunities.
The implementation of increasingly stringent fuel quality regulations across major economies is a key driver of the refinery catalyst market. Governments and regulatory authorities continue to impose tighter limits on sulfur, nitrogen, and particulate emissions from transportation fuels to improve air quality and reduce environmental impact. As a result, refineries are investing in high-performance catalysts that enable efficient hydrotreating, hydrocracking, and fluid catalytic cracking processes while meeting evolving product specifications. These catalysts enhance contaminant removal, improve conversion rates, and support the production of cleaner gasoline, diesel, and other refined products without requiring extensive modifications to existing refining infrastructure.
The growing complexity of crude oil feedstocks further reinforces the need for advanced catalyst technologies capable of maintaining operational efficiency under demanding processing conditions. Modern refinery catalysts help maximize yields of high-value fuels, improve catalyst longevity, and reduce energy consumption during refining operations. Continuous innovation in catalyst formulations is allowing refiners to comply with environmental standards while optimizing profitability, making regulatory-driven catalyst adoption a fundamental growth driver for the market.
The refinery catalyst market faces a significant restraint in the form of high research, development, and manufacturing costs associated with advanced catalyst technologies. Developing catalysts with improved activity, selectivity, thermal stability, and resistance to contaminants requires extensive scientific research, specialized raw materials, and rigorous performance testing, resulting in substantial investment requirements for manufacturers. For refinery operators, catalyst procurement and replacement represent considerable operational expenditures, particularly for large-scale refining units where shutdowns for catalyst replacement can lead to production losses and increased maintenance costs. The long operational life of many refinery catalysts reduces replacement frequency, limiting recurring sales opportunities for suppliers. Combined with fluctuations in refinery margins and uncertainty in capital expenditure during periods of volatile crude oil prices, these factors may delay catalyst upgrades and slow the adoption of newly developed technologies, thereby restraining overall market growth.
Ongoing refinery modernization projects and the increasing utilization of heavier and more challenging crude feedstocks present a significant opportunity for the refinery catalyst market. Many refineries are upgrading their processing units to improve operational flexibility, increase production efficiency, and maximize the recovery of valuable transportation fuels from lower-cost crude sources. These modernization initiatives require advanced catalysts capable of delivering higher conversion efficiency, greater selectivity, and improved resistance to catalyst deactivation under severe operating conditions. Emerging economies are also expanding refining capacity to meet rising domestic fuel demand and reduce dependence on imported petroleum products. These investments create sustained demand for innovative catalyst technologies that enhance refinery performance while supporting compliance with evolving environmental standards.
Analyst Perspective
The refinery catalyst market is expected to grow, supported by increasing investments in refinery modernization and the production of cleaner transportation fuels. Rising processing of heavier crude feedstocks is accelerating demand for high-performance catalysts with improved conversion efficiency and contaminant removal capabilities. Continuous advancements in catalyst formulations are enabling refiners to enhance operational performance while complying with stringent environmental regulations. Although fluctuating refining margins and high catalyst development costs may pose challenges, expanding refining capacities in emerging economies continue to create growth opportunities. Companies focused on innovation, customized catalyst solutions, and technical support are likely to strengthen their competitive position over the forecast period.
Product Insights
Based on product, the zeolite segment accounted for the highest market share, representing 30.1% of total revenue in 2025 and is expected to continue to dominate the industry over the forecast period. This is attributed to their widespread usage as adsorbents and catalysts owing to their porosity and large surface area. The porous structure of zeolites accommodates a variety of cations, including potassium (K+), sodium (Na+), calcium (Ca2+), and magnesium (Mg2+). Naturally, zeolites are formed by the reaction of volcanic rocks and ash layers with alkaline water. Natural zeolites are impure owing to the presence of other minerals, metals, and quartz. On the contrary, zeolites are commercially manufactured through the slow crystallization of silica-alumina gel, with multiple other atoms incorporated to enhance activity and performance in a particular process.
The growing demand for noble and other metals in emerging economies of Chile, China, and South Africa, on account of favorable regulatory support for FDI in mineral production, is expected to ensure a robust raw material supply for the manufacturers of metal catalysts. However, the growing demand for these metals in other applications is expected to put additional pressure on raw material supply. It may create obstacles to the growth of the refinery catalyst industry over the forecast period.
Application Insights
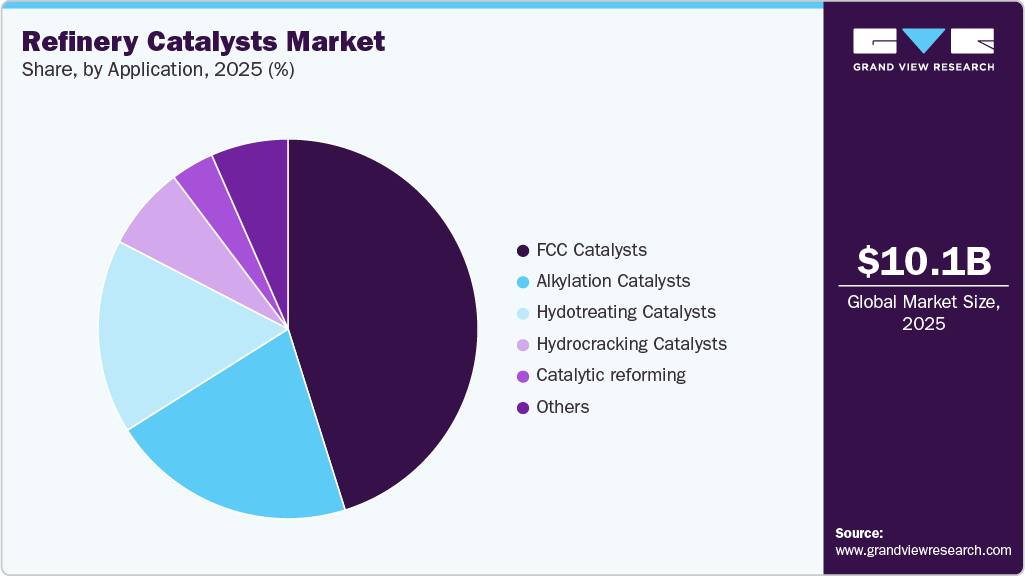
By application, FCC catalysts held a dominant position, contributing 45.1% of total revenue in 2025. The growth in this segment can be attributed to the growing demand for gasoline as a fuel for its use in automotive vehicles across the globe. Other application-based segments include fluid catalytic cracking (FCC) catalysts, hydrotreating catalysts, hydrocracking catalysts, and catalytic reforming.
Fluid catalytic cracking is the most preferred method used by refineries to convert heavy and high-boiling hydrocarbons into lower-value fractions. Gasoline is the primary material obtained from the process, along with other fractions such as diesel and C3 and C4 gaseous fractions. This process helps produce an additional quantity of gasoline to cater to the robust demand for automotive vehicles. The lighter fractions formed during the process are fed to the alkylation unit to produce a high-octane gasoline component called alkylate. The heavier fractions are used as a blender and an additive in diesel.
 To learn more about this report, Download Free Sample Report
The hydrotreating segment is expected to grow at the fastest CAGR of 4.7% from 2026 to 2033. The hydrotreating process, also known as the hydrodesulfurization process, is used to separate chemically bound sulfur compounds from various petrochemical materials. This is done using a variety of refinery catalysts that are selected based on the feed. The process also aids in the removal of other impurities such as metals, oxygen, and nitrogen. This unit is used at multiple stages in the refinery for hydrotreating various products, including jet fuel, pyrolysis gas, catalytic feed, reformer feed, and other distillates.
Hydrotreating is carried out before processes such as catalytic reforming to avoid the contamination of the catalyst by crude feedstock. Additionally, hydrocracking is employed before catalytic cracking to reduce sulfur content, enhance yields, and increase the production of middle distillate petroleum fractions, which are used in heating fuel oil, kerosene, and diesel fuel.
Regional Insights
The refinery catalysts market in North America is mature and technologically advanced, driven by stringent environmental regulations and the need for high-efficiency fuel refining. Key applications include fluid catalytic cracking (FCC), hydrocracking, and hydrotreating, which reduce the sulfur and nitrogen content in fuels. The growing demand for cleaner transportation fuels and shale oil processing is driving catalyst innovation and adoption. The region benefits from strong R&D capabilities and the presence of major catalyst producers like Albemarle, BASF, and W.R. Grace.
U.S. Refinery Catalysts Market Trends
The U.S. refinery catalysts industry led North America, with the largest revenue share of 77.7% in 2025, backed by its large refining capacity, complex refineries, and significant shale oil output. Regulations by the EPA and Department of Energy continue to push refiners to adopt advanced catalyst systems to meet Tier 3 and ultra-low sulfur fuel standards. Innovation in FCC and hydrotreating catalysts is particularly prominent, with a focus on improving fuel yield and reducing emissions. The presence of global catalyst manufacturers and strategic R&D investment further strengthens the U.S. market.
Asia Pacific Refinery Catalysts Market Trends
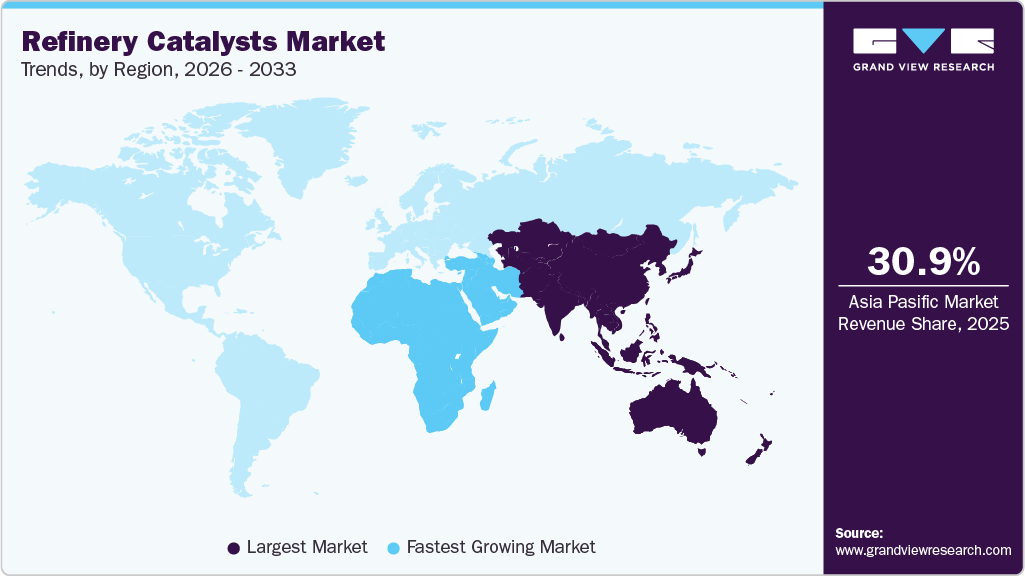
Asia Pacific dominated the refinery catalyst market with the highest revenue share of 32.5% in 2025. An increasing number of private sector companies play a crucial role in promoting the refining industry in the aforementioned countries, especially in India. The Reliance-operated Jamnagar refinery complex in Gujarat had a capacity of 1.2 million barrels per day in 2019, making it the largest refinery in the world. The government of India has approved the Petroleum, Chemicals, and Petrochemicals Investment Region (PCPIR) policy for promoting FDI investments in the oil and gas sector. This regulatory move is expected to accelerate the petrochemicals and polymer production in India, thus contributing to the demand for refinery catalysts over the forecast period.
 To learn more about this report, Download Free Sample Report
China accounted for 47.2% of the Asia Pacific refinery catalyst market in 2025. In China, the presence of substantial oil reserves is likely to contribute to the growth of the Asia Pacific market. As a result, key market players are focusing their efforts on expanding capacity in the Asia Pacific region and meeting the growing demand across regions.
Europe Refinery Catalysts Market Trends
The refinery catalysts industry in Europe is anticipated to grow at a CAGR of 3.7% during the forecast period. Refineries in Europe are struggling with low margins due to high manufacturing costs and stringent environmental regulations. This regulatory move in Russia is expected to fuel demand for catalysts in refining applications. In addition, technological developments related to enhanced oil recovery and the deployment of hydraulic fracturing activities in countries such as Russia and Ukraine are expected to lead to an increase in the availability of tight oil and shale gas. The increasing availability of shale gas and tight oil is expected to facilitate access to raw materials for refineries operating in Germany, France, and Italy. This is likely to have a positive impact on the European market.
Key Refinery Catalysts Company Insights
Some of the key players operating in the market include Dow and Linde Plc.
- BASF SE is a chemical manufacturing company with a presence across Asia Pacific, North America, Central & South America, Europe, and the Middle East & Africa. The company operates through six business segments, namely chemical, material, industrial solutions, surface technologies, agricultural solutions, and nutrition & care. The chemical segment encompasses petrochemicals and their intermediates. The material segment comprises performance polymers and monomers. The Solutions segment includes performance chemicals and dispersions, as well as pigments. The agricultural solution segment includes products for farming, landscape management, and pest control. The Nutrition & Care segment is further sub-segmented into Nutrition & Health and Care. The company provides a wide range of surfactants for textile, paint & coatings, homecare, and food processing industries.
Key Refinery Catalysts Companies:
The following key companies have been profiled for this study on the refinery catalysts market.
- Albemarle Corporation
- BASF SE
- Johnson Matthey Plc
- W. R. Grace
- Clariant International Ltd.
- Arkema
- Zeolyst International
- Chevron Corporation
- Exxon Mobil Corporation
- Evonik Industries AG
- DuPont
- Haldor Topsoe A/S
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Albemarle Corporation, BASF SE, Johnson Matthey Plc, W. R. Grace, Clariant International Ltd., Chevron Corporation, Exxon Mobil Corporation, Evonik Industries AG, DuPont)
- Invest heavily in research and development to introduce advanced catalyst formulations.
- Establish long-term supply agreements with major refinery operators worldwide.
- Expand manufacturing capabilities and technical service networks to support global customers.
- Focus on continuous catalyst performance improvement through process optimization and digital monitoring solutions.
- Strong global brand recognition and extensive customer relationships across the refining industry.
- Broad product portfolios covering multiple refining processes and catalyst technologies.
- Significant financial resources to support innovation, acquisitions, and capacity expansion.
- Comprehensive technical expertise and after-sales support that enhances customer retention
- High operating and research costs can reduce flexibility during market downturns.
- Large organizational structures may slow product development and decision-making.
- Greater exposure to fluctuations in global refining investments and crude oil market cycles.
- Dependence on stringent environmental and regulatory compliance increases operational complexity.
Emerging Players (Arkema, Zeolyst International, Haldor Topsoe A/S)
- Concentrate on specialized catalyst technologies for targeted refinery applications.
- Collaborate with technology providers and research institutions to accelerate product innovation.
- Strengthen regional distribution channels to expand market presence.
- Develop customized catalyst solutions to address specific refinery processing requirements.
- Greater operational agility enables faster response to evolving customer needs.
- Specialized expertise allows differentiation in niche catalyst applications.
- Flexible manufacturing approaches support tailored product development.
- Ability to capitalize on emerging opportunities in refinery modernization and process optimization.
- Limited global manufacturing footprint compared with established competitors.
- Lower investment capacity for large-scale research, production expansion, and acquisitions.
- Smaller customer base may constrain long-term revenue stability.
- Reduced brand visibility can make it challenging to secure contracts with major international refineries.
Recent Developments
-
In May 2025, Johnson Matthey agreed to sell its “Catalyst Technologies” business to Honeywell for £1.8 billion (cash and debt-free basis). The deal enables Honeywell to integrate JM’s catalyst technologies with its existing Energy & Sustainability Solutions (ESS) business, broadening its offerings in refining and petrochemical catalysts - including those for lower-emission fuels, sustainable aviation fuel (SAF), blue hydrogen, and ammonia.
-
In August 2024, BASF launched Fourtiva, a new fluidized catalytic cracking (FCC) catalyst designed to enhance the production of high-octane gasoline blending components. The catalyst leverages BASF’s latest Advanced Innovative Matrix (AIM) and Multiple Frameworks Topology (MFT) technologies to deliver a tailored solution that prioritizes higher butylene output, improved naphtha octane, and increased LPG olefinicity, while reducing the formation of coke and dry gas. This advanced formulation enables refiners to boost the yield of high-value products, enhance overall profitability, and lower the FCC unit's environmental impact.
Refinery Catalysts Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.1 billion
Estimated market size in 2026
USD 10.6 billion
Projected market size by 2033
USD 14.2 billion
Growth rate
CAGR of 4.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/billion, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Russia; China; India; Japan; South Korea; Indonesia; Australia; Brazil; South Africa; Saudi Arabia
Key companies profiled
Albemarle Corporation; BASF SE; Johnson Matthey Plc; W. R. Grace; Clariant International Ltd.; Arkema; Zeolyst International; Chevron Corporation; Exxon Mobil Corporation; Evonik Industries AG; DuPont; Haldor Topsoe A/S
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Refinery Catalysts Market Report Segmentation
This report forecasts volume & revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global refinery catalysts market report based on product, application, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Zeolite
-
Metallic
-
Chemical Compounds
-
Other Products
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
FCC Catalysts
-
Alkylation Catalysts
-
Hydrotreating Catalysts
-
Hydrocracking Catalysts
-
Catalytic Reforming
-
Other Applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Indonesia
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The refinery catalysts market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each refinery catalysts segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Zeolite
Commercial gains are supported by the widespread deployment of zeolite-based catalysts in fluid catalytic cracking units, where they improve conversion efficiency and increase gasoline and light olefin output. Their indispensable role in large-scale refining operations ensures stable market demand.
Metallic
Revenue streams are strengthened through metallic catalyst systems containing active metals such as nickel, cobalt, molybdenum, and platinum for hydrotreating and hydrocracking applications. Their superior performance in impurity removal and fuel upgrading supports premium pricing.
Chemical Compounds
Market proceeds are derived from catalyst formulations incorporating alumina, silica, phosphates, and other compounds that enhance durability, selectivity, and process stability. Broad integration across refinery units contributes to consistent purchasing activity.
Other Products
Financial returns are achieved through specialty catalysts, performance additives, and customized formulations developed for residue conversion, catalyst enhancement, and process optimization. Their application-specific capabilities expand commercial opportunities across diverse refining operations.
Segment - Application
Revenue capture definition
FCC Catalysts
Business value is captured through catalyst consumption in fluid catalytic cracking units that transform heavy hydrocarbons into gasoline, LPG, and petrochemical feedstocks. Continuous catalyst replenishment and high refinery throughput underpin this segment's contribution.
Alkylation Catalysts
Income potential is supported by catalyst use in alkylation processes that produce high-octane gasoline blending components with improved environmental performance. Expanding demand for cleaner transportation fuels reinforces long-term growth prospects.
Hydrotreating Catalysts
Commercial performance is driven by catalysts that eliminate sulfur, nitrogen, and other contaminants from petroleum streams, enabling compliance with increasingly stringent fuel quality standards. Ongoing refinery operations sustain procurement across global markets.
Hydrocracking Catalysts
Economic value is realized from catalyst deployment in hydrocracking units that convert heavier feedstocks into premium diesel, jet fuel, and naphtha with higher conversion efficiency. Greater reliance on lower-quality crude oils continues to strengthen adoption.
Other Applications
Growth opportunities are supported by catalyst utilization in reforming, isomerization, residue upgrading, and other specialized refining processes that improve operational flexibility and product quality. Continued investments in refinery upgrades foster sustained commercial demand.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Analyze the manufacturing ecosystem for refinery catalysts, focusing on the sourcing of zeolites, alumina, silica, rare earth elements, and active metals such as nickel, cobalt, molybdenum, platinum, and palladium. Evaluate catalyst formulation technologies, impregnation and calcination processes, production capacities, raw material availability, integrated manufacturing facilities, international trade, and major production hubs that support reliable supply to global refining operations.
Application Adoption Layer
Where is refinery catalyst consumed?
Assess catalyst deployment across refining processes including fluid catalytic cracking (FCC), hydrotreating, hydrocracking, alkylation, catalytic reforming, and residue upgrading. Adoption patterns are influenced by refinery modernization, processing of heavier crude feedstocks, compliance with fuel quality regulations, demand for cleaner transportation fuels, and investments in conversion efficiency and operational optimization.
Consumption Intensity Layer
How much refinery catalyst is utilized?
Measure catalyst requirements across refining units by evaluating refinery throughput, catalyst replacement cycles, feedstock characteristics, process severity, operating conditions, and regeneration practices. The analysis considers consumption volumes associated with FCC, hydrotreating, hydrocracking, alkylation, and other catalytic processes to estimate annual demand across regional refining markets.
Revenue Layer
How is market revenue generated?
Market valuation is supported by the supply of standardized and customized catalyst solutions to petroleum refineries for conversion, upgrading, and purification processes. Commercial performance depends on catalyst formulation, processing efficiency, long-term supply contracts, replacement frequency, refinery operating rates, technological advancements, regulatory requirements, and investments in refining capacity and process upgrades across global energy markets.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study delivers detailed country-level assessment across major refinery catalyst production and consumption markets. It analyzes refining capacity, refinery modernization initiatives, crude processing trends, catalyst demand, regulatory frameworks, trade dynamics, and investments in FCC, hydrotreating, hydrocracking, and alkylation technologies across key regions.
Supports expansion planning by identifying high-growth refining markets, evaluating regional demand patterns, assessing investment potential, and recognizing opportunities arising from refinery upgrades and capacity additions.
Competitive Benchmarking
The study provides an in-depth comparison of leading refinery catalyst manufacturers based on product portfolio, technological capabilities, manufacturing footprint, refinery partnerships, innovation pipeline, pricing approach, regional presence, strategic initiatives, and recent business developments. It further assesses each company's position across major catalyst applications and end markets.
Helps stakeholders benchmark industry participants, identify competitive advantages, evaluate market positioning, recognize collaboration prospects, and formulate effective business growth and differentiation strategies.
Opportunity Assessment
The study identifies emerging opportunities driven by refinery modernization, processing of heavier crude feedstocks, production of cleaner transportation fuels, catalyst regeneration technologies, residue upgrading, and capacity expansion projects. It also evaluates growth potential associated with advanced catalyst formulations and evolving environmental compliance requirements.
Assists organizations in prioritizing high-potential investment areas, strengthening product development strategies, aligning with evolving refining requirements, and capturing long-term opportunities across the global refinery catalyst value chain.
Frequently Asked Questions About This Report
Some key players operating in the refinery catalyst market include Albemarle Corporation; BASF SE; Johnson Matthey Plc; W. R. Grace; Clariant International Ltd.; Arkema; Zeolyst International; Chevron Corporation; Exxon Mobil Corporation; Evonik Industries AG; DuPont; Haldor Topsoe A/S
The global refinery catalysts market size was valued at USD 10.1 billion in 2025 and is expected to reach USD 10.6 billion in 2026.
FCC catalysts held a dominant position, contributing 45.1% of total revenue in 2025.
The global refinery catalysts market is expected to grow at a CAGR of 4.3% from 2026 to 2033, reaching USD 14.2 billion by 2033.
Middle East & Africa is the fastest-growing region over the forecast period.
The refinery catalyst market is primarily driven by stringent environmental regulations requiring the production of cleaner transportation fuels and the growing need to process heavier crude oil feedstocks efficiently.
Based on product, the zeolite segment accounted for the highest market share, representing 30.1% of total revenue in 2025. The segment's leadership is supported by the superior cracking efficiency, high thermal stability, and exceptional selectivity of zeolite catalysts, making them the preferred choice for fluid catalytic cracking (FCC) applications in modern refineries.
Asia Pacific dominated the refinery catalyst market with the highest revenue share of 32.5% in 2025. The region's leadership was driven by its extensive refining capacity, ongoing refinery modernization projects, and rising demand for cleaner transportation fuels across major economies such as China and India.
About the Author(s)
Catalysts & Enzymes Research Team
Specialty & Chemicals · Catalysts & EnzymesThis report was authored by the catalysts & enzymes research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the catalysts & enzymes segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


