
- Home
- »
- Medical Devices
- »
-
Saudi Arabia Diabetes Devices Market Size Report, 2033GVR Report cover

Saudi Arabia Diabetes Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Blood Glucose Monitoring Devices, Insulin Delivery Devices), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies), By End Use (Hospitals, Diagnostic Centers), And Segment Forecasts
Market Size, 2025
$215.1MMarket Estimate, 2026
$232.6MMarket Forecast, 2033
$405.8MCAGR, 2026–2033
8.3%Saudi Arabia Diabetes Devices Market Summary
The Saudi Arabia diabetes devices market size was valued at USD 215.1 million in 2025 and is projected to grow from USD 232.6 million in 2026 to USD 405.8 million in 2033, at a CAGR of 8.3% from 2026 to 2033. The market is witnessing steady growth, driven by the rising prevalence of diabetes, rapid advances in connected diabetes management technologies, and supportive government policies aimed at improving healthcare accessibility, strengthening preventive care programs, and accelerating the adoption of innovative medical devices across Saudi Arabia.
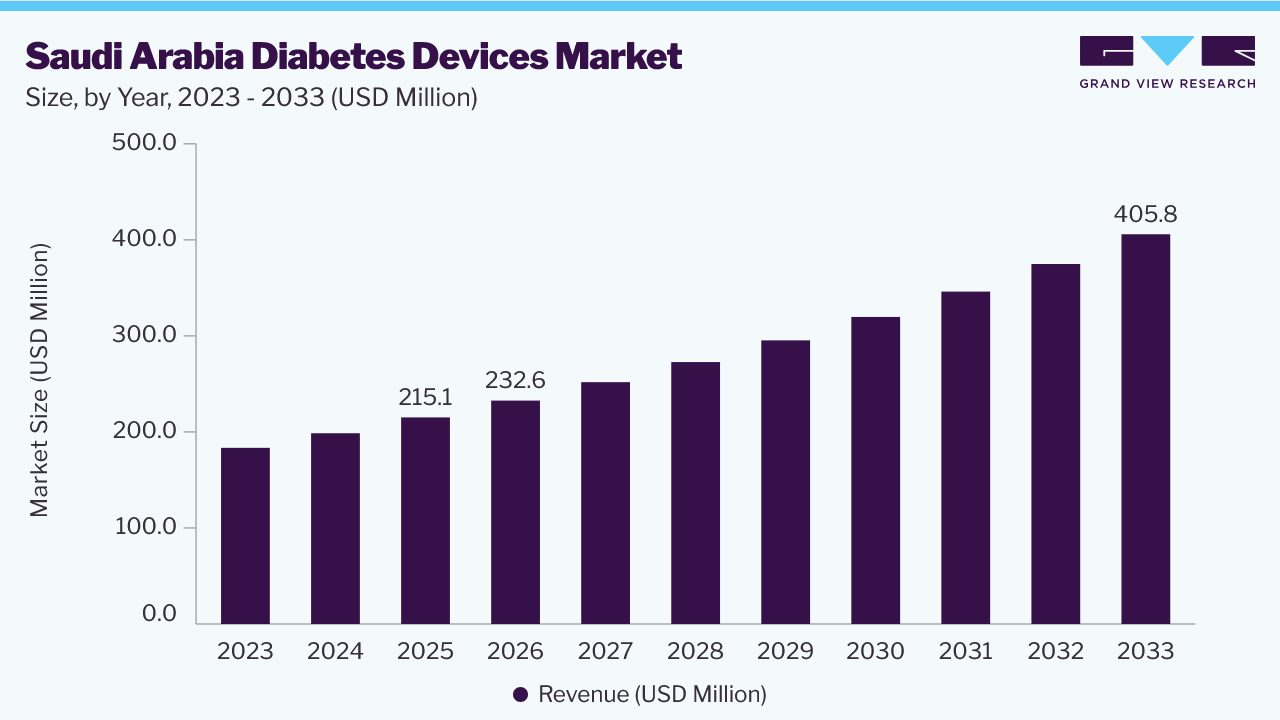 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Insulin delivery segment held a market share of around 55.0% in 2025.
- By distribution channel: Hospital pharmacies held the largest revenue share of over 50.0% in 2025.
- By end use: Hospital segment held the largest revenue share of around 40.0% in 2025.
Market Size & Forecast
- Market size in 2025: USD 215.1 Million
- Estimated market size in 2026: USD 232.6 Million
- Projected market size by 2033: USD 405.8 Million
- CAGR (2026-2033): 8.3%
Prism AI by Grand View Research Free to tryAsk a question about the saudi arabia diabetes devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Saudi Arabia's ongoing healthcare transformation is creating a favorable environment for the adoption of advanced diabetes management technologies. Under the Vision 2030 Health Sector Transformation Program, the government continues to modernize the healthcare ecosystem by expanding private sector participation, accelerating digital health adoption, strengthening integrated care networks, and enhancing preventive healthcare services. These initiatives, supported by significant investments in healthcare infrastructure and a target to increase private sector participation to 65% by 2030, are expected to improve access to advanced diabetes devices, including continuous glucose monitoring (CGM) systems and insulin delivery technologies.
The rising burden of diabetes remains one of the strongest drivers for the Saudi Arabia diabetes devices industry. According to the International Diabetes Federation (IDF) Diabetes Atlas, 11th Edition (2025), approximately 5.34 million adults aged 20–79 years were living with diabetes in Saudi Arabia in 2024, with the number projected to reach 9.54 million by 2050. The country reported an adult diabetes prevalence of 23.1%, placing it among the nations with the highest diabetes burden globally. Increasing urbanization, sedentary lifestyles, unhealthy dietary habits, and rising obesity rates continue to contribute to the growing prevalence of diabetes, strengthening the need for advanced glucose monitoring and insulin delivery solutions.
Government-led awareness and digital health initiatives are further supporting market expansion. National screening programs and public awareness campaigns are encouraging early diagnosis, timely intervention, and better disease management, while healthcare providers are increasingly adopting connected diabetes technologies to improve patient outcomes. Reflecting this trend, Saudi Arabia launched the world's first Digital Diabetes Command Center in October 2025, integrating connected diabetes devices with real-time patient monitoring to support wider adoption of CGM systems and insulin pumps across the Kingdom. Such initiatives, combined with increasing investments in medical technology and digital healthcare infrastructure, are expected to accelerate the adoption of next-generation diabetes management solutions over the forecast period.
Analyst Perspective
Saudi Arabia's diabetes devices market is evolving rapidly, driven by increasing emphasis on early diagnosis, continuous disease management, and improved patient outcomes. The growing adoption of continuous glucose monitoring systems, insulin delivery devices, and digital health technologies is driving the shift toward personalized diabetes care. Government initiatives under Vision 2030, alongside healthcare infrastructure investments and digital transformation, will further accelerate market growth. Companies offering clinically proven devices, localized support, and integration with digital health platforms are well-positioned to expand. Rising home-based monitoring and patient awareness will strengthen demand for connected, user-friendly solutions. Long-term market growth will depend on innovation, affordability, and improved treatment adherence and chronic disease management.
Type Insights
The insulin delivery segment dominated the Saudi Arabia diabetes devices industry, accounting for a revenue share of around 55.0% in 2025, and is expected to grow at the fastest CAGR over the forecast period. These devices offer several advantages over traditional methods of insulin administration, providing patients with greater flexibility, precision, and convenience in managing diabetes. Insulin delivery devices, such as insulin pens and insulin pumps, simplify the administration of insulin injections. They eliminate the need for manual drawing and measuring of insulin doses, thereby reducing the risk of dosing errors and enhancing treatment accuracy. For instance, in February 2026, Insulet Corporation launched the Omnipod 5 Automated Insulin Delivery System in the Middle East, including Saudi Arabia, along with the Omnipod Discover data management.
The presence of several market players in the country, along with various strategic initiatives undertaken by them, is expected to drive market expansion. For instance, in February 2025, Sanofi announced the transfer of its global insulin manufacturing expertise to Saudi Arabia through its partnership with Sudair Pharma Company (SPC) and NUPCO. The initiative will establish a state-of-the-art local insulin production facility capable of manufacturing, assembling, and packaging approximately 15 million SoloStar insulin pens annually, meeting the needs of around 500,000 patients and covering nearly 70% of insulin users in the Kingdom. This development is expected to strengthen local diabetes care and improve access to insulin therapies in Saudi Arabia. Consequently, this is expected to increase insulin production within the country, potentially also increasing the production of insulin delivery devices.
The blood glucose monitoring devices segment is expected to witness the fastest CAGR over the forecast period, driven by the rising prevalence of diabetes and increasing awareness of routine glucose monitoring. In addition, the growing adoption of self-monitoring devices and continuous glucose monitoring technologies, as well as government initiatives to improve diabetes management, is supporting segment growth. Furthermore, increasing healthcare expenditure and expanding access to advanced diagnostic devices are expected to drive sustained demand.
Distribution Channel Insights
The hospital pharmacies segment led the Saudi Arabia diabetes devices market, accounting for a revenue share of more than 50.0% in 2025. This is attributed to the critical role hospital pharmacies play as primary access points for patients receiving diabetes care within healthcare facilities. Given the complexity of diabetes management and the need for specialized medical guidance, hospitals are the primary settings where patients receive diagnosis, treatment, and ongoing support for their condition. Moreover, hospital pharmacies adhere to regulatory standards and quality control measures to ensure the safety, efficacy, and reliability of the diabetes devices they dispense.
The retail pharmacy segment is expected to grow at the fastest CAGR from 2026 to 2033, as they serve as a convenient and accessible point of purchase for individuals seeking diabetes devices and related supplies. With their widespread presence in local communities and urban areas, retail pharmacies offer patients the convenience of obtaining diabetes devices closer to home, reducing travel time and logistical barriers to accessing care. Diabetes care products offered by retail pharmacies to patients include medications, self-monitoring glucose supplies (glucose meter, test strips, lancets), insulin delivery equipment, and OTC products.
End Use Insights
The hospital segment dominated the Saudi Arabia diabetes devices industry, accounting for over 40.0% revenue share in 2025. The rising number of hospital admissions among patients with diabetes is boosting demand in the segment. Diabetes patients have a threefold chance of hospitalization compared with those without diabetes. Diabetes technology has evolved rapidly in the past few years. Most of these technologies aim to improve diabetes care in hospitals and clinics. These technological advancements have increased the use of diabetes devices in hospitals and clinics.
The diagnostic centers segment is expected to grow at a significant CAGR from 2026 to 2033. Diabetes devices are being increasingly used in various healthcare settings, such as diagnostic centers. Patients with diabetes prefer to have their glucose levels checked at diagnostic centers because these centers provide instant results without long waiting times. SMBG devices are widely used in these diagnostic centers. Thus, increasing demand for diabetes devices is expected to propel segment growth.
Key Saudi Arabia Diabetes Devices Company Insights
The Saudi Arabia diabetes devices industry features a range of global, regional, and local players, making it a competitive market. The world’s leading companies are using partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share. Saudi Arabia diabetes device manufacturers are investing heavily in product enhancements and new product development.
Key Saudi Arabia Diabetes Devices Companies
The following key companies have been profiled for this study of the Saudi Arabia diabetes devices market.
-
Medtronic plc
-
Abbott Laboratories
-
F. Hoffmann-La Roche Ltd
-
Bayer AG
-
Lifescan, Inc.
-
B Braun Melsungen AG
-
Dexcom Inc.
-
Insulet Corporation
-
Sanofi
-
Novo Nordisk A/S
-
Becton, Dickinson and Company
Recent Developments
- In January 2025, the Saudi Food and Drug Authority (SFDA) issued its first license for a medical software manufacturing facility to commercialize an AI-powered device for the diagnosis of diabetic foot. The device has been developed with thermal imaging and advanced image analysis, and it supports the early detection of diabetic foot complications. This development highlights Saudi Arabia's growing focus on locally developed digital diabetes care solutions under Vision 2030.
Saudi Arabia Diabetes Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 215.1 million
Estimated market size in 2026
USD 232.6 million
Projected market size by 2033
USD 405.8 million
Growth rate
CAGR of 8.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, distribution channel, and end use
Country scope
Saudi Arabia
Key companies profiled
Medtronic plc; Abbott Laboratories; F. Hoffmann-La Roche Ltd; Bayer AG; Lifescan, Inc.; B Braun Melsungen AG; Dexcom Inc.; Insulet Corporation; Sanofi; Novo Nordisk A/S; Becton, Dickinson and Company
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Saudi Arabia Diabetes Devices Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Saudi Arabia diabetes devices market report based on type, distribution channel, and end use:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Blood Glucose Monitoring Devices
-
Self-monitoring Devices
-
Blood Glucose Meters
-
Testing Strips
-
Lancets
-
-
Continuous Glucose Monitoring Devices
-
Sensors
-
Transmitters
-
Receiver
-
-
-
Insulin Delivery Devices
-
Insulin Pumps
-
Insulin Pens
-
Insulin Syringes
-
Insulin Jet Injectors
-
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Diabetes Clinics/Centers
-
Online Pharmacies
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Homecare
-
Diagnostic Centers
-
Frequently Asked Questions About This Report
The Saudi Arabia diabetes devices market size was valued at USD 215.1 million in 2025 and is estimated at USD 232.6 million for 2026.
The Saudi Arabia diabetes devices market is expected to grow at a CAGR of 8.3% from 2026 to 2033, reaching USD 405.8 million.
The insulin delivery Saudi Arabia diabetes devices segment accounted for the largest revenue share of approximately 55.0% in 2025.
Key players in the market include Medtronic plc; Abbott Laboratories; F. Hoffmann-La Roche Ltd; Bayer AG; Lifescan, Inc.; B Braun Melsungen AG; Dexcom Inc.; Insulet Corporation; Sanofi; Novo Nordisk A/S; and Becton, Dickinson and Company.
The hospital pharmacies segment led the Saudi Arabia diabetes devices market, accounting for a revenue share of more than 50.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


