
- Home
- »
- Pharmaceuticals
- »
-
Semaglutide Market Size, Share & Trends Report, 2026-2035GVR Report cover

Semaglutide Market (2026 - 2035)
Size, Share & Trends Analysis Report By Product (Ozempic, Wegovy, Rybelsus), By Application (Type 2 Diabetes Mellitus, Obesity), By Route Of Administration, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$34.6BMarket Estimate, 2026
$40.5BMarket Forecast, 2035
$93.6BCAGR, 2026–2035
9.8%Semaglutide Market Summary
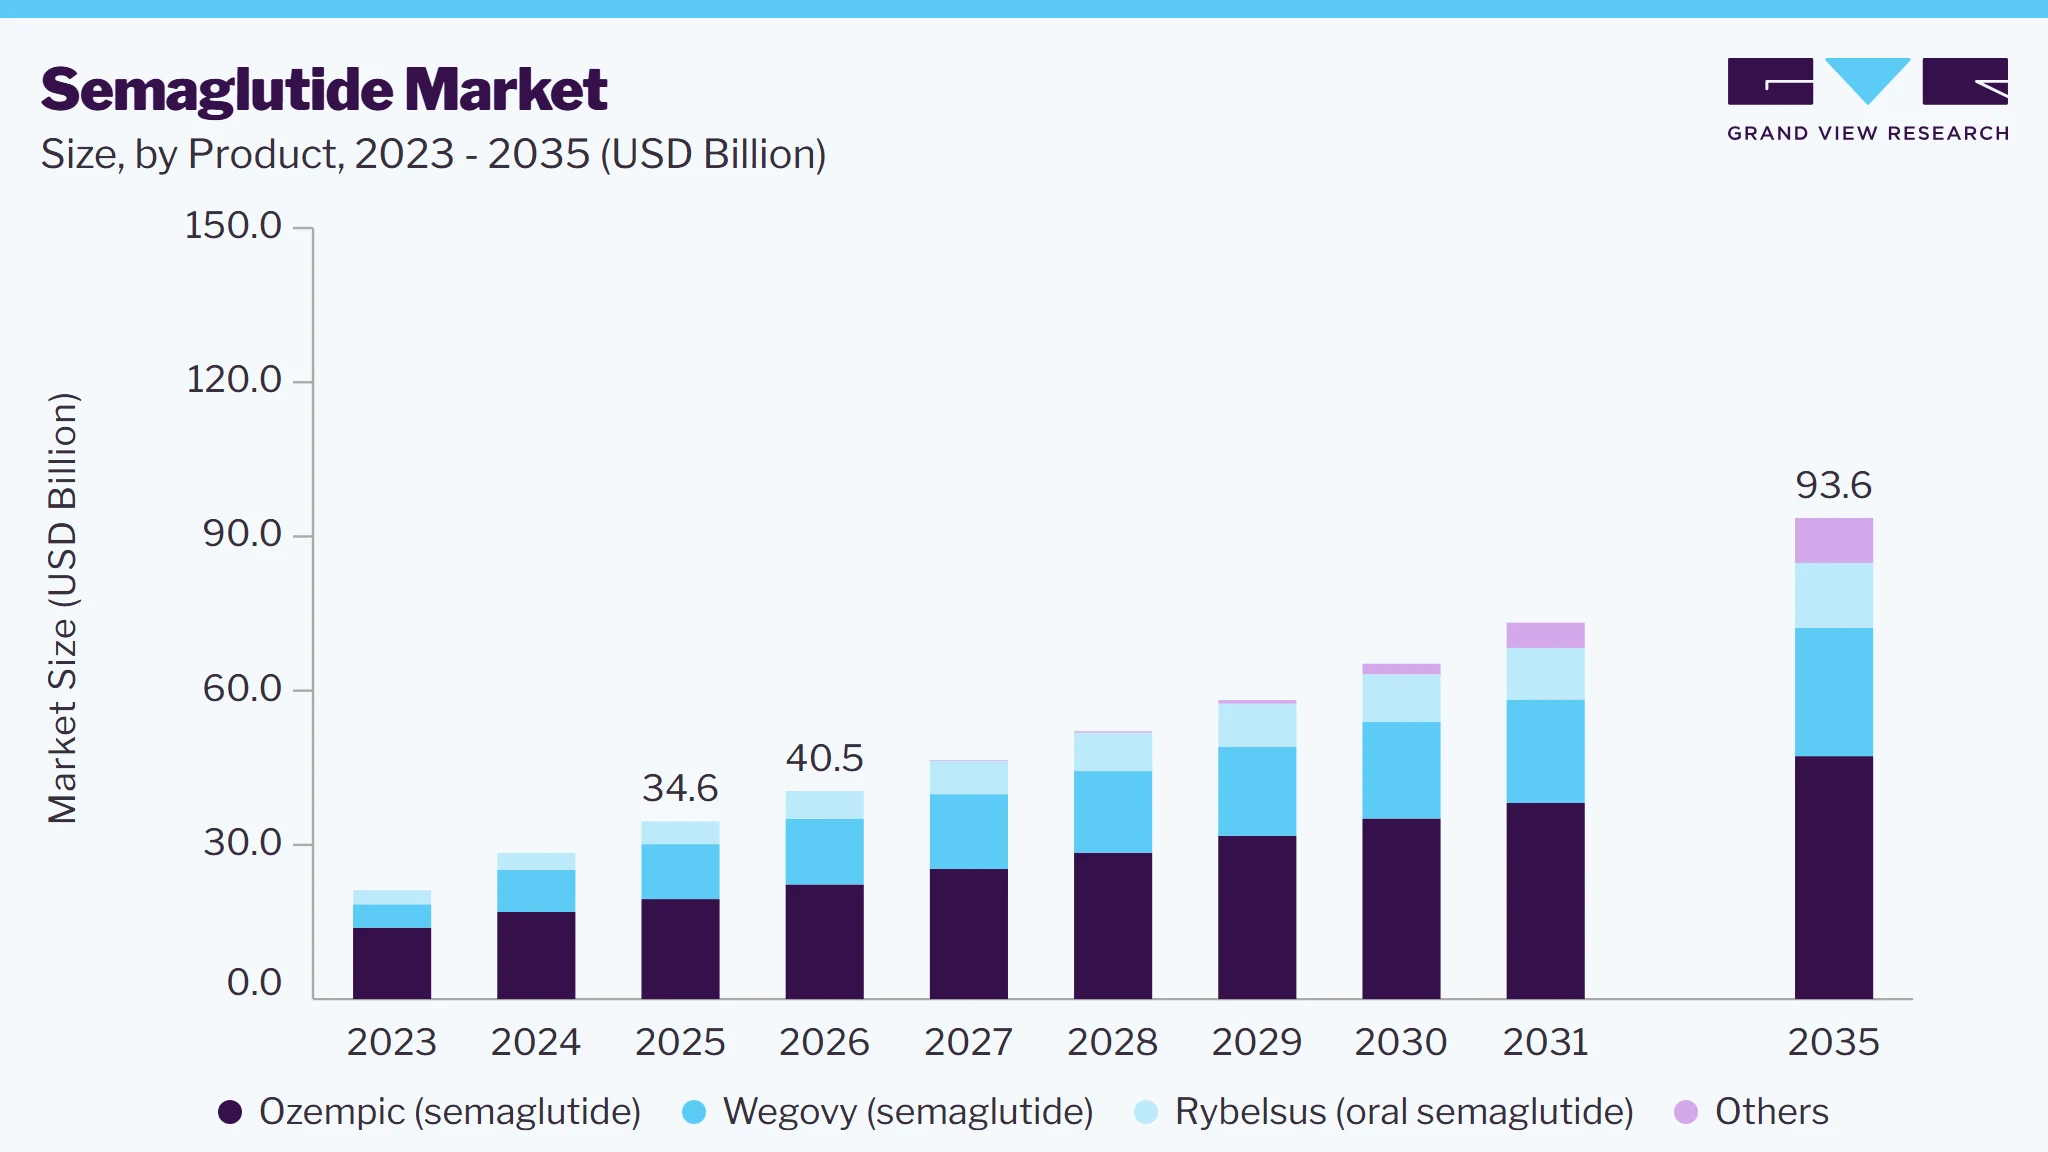
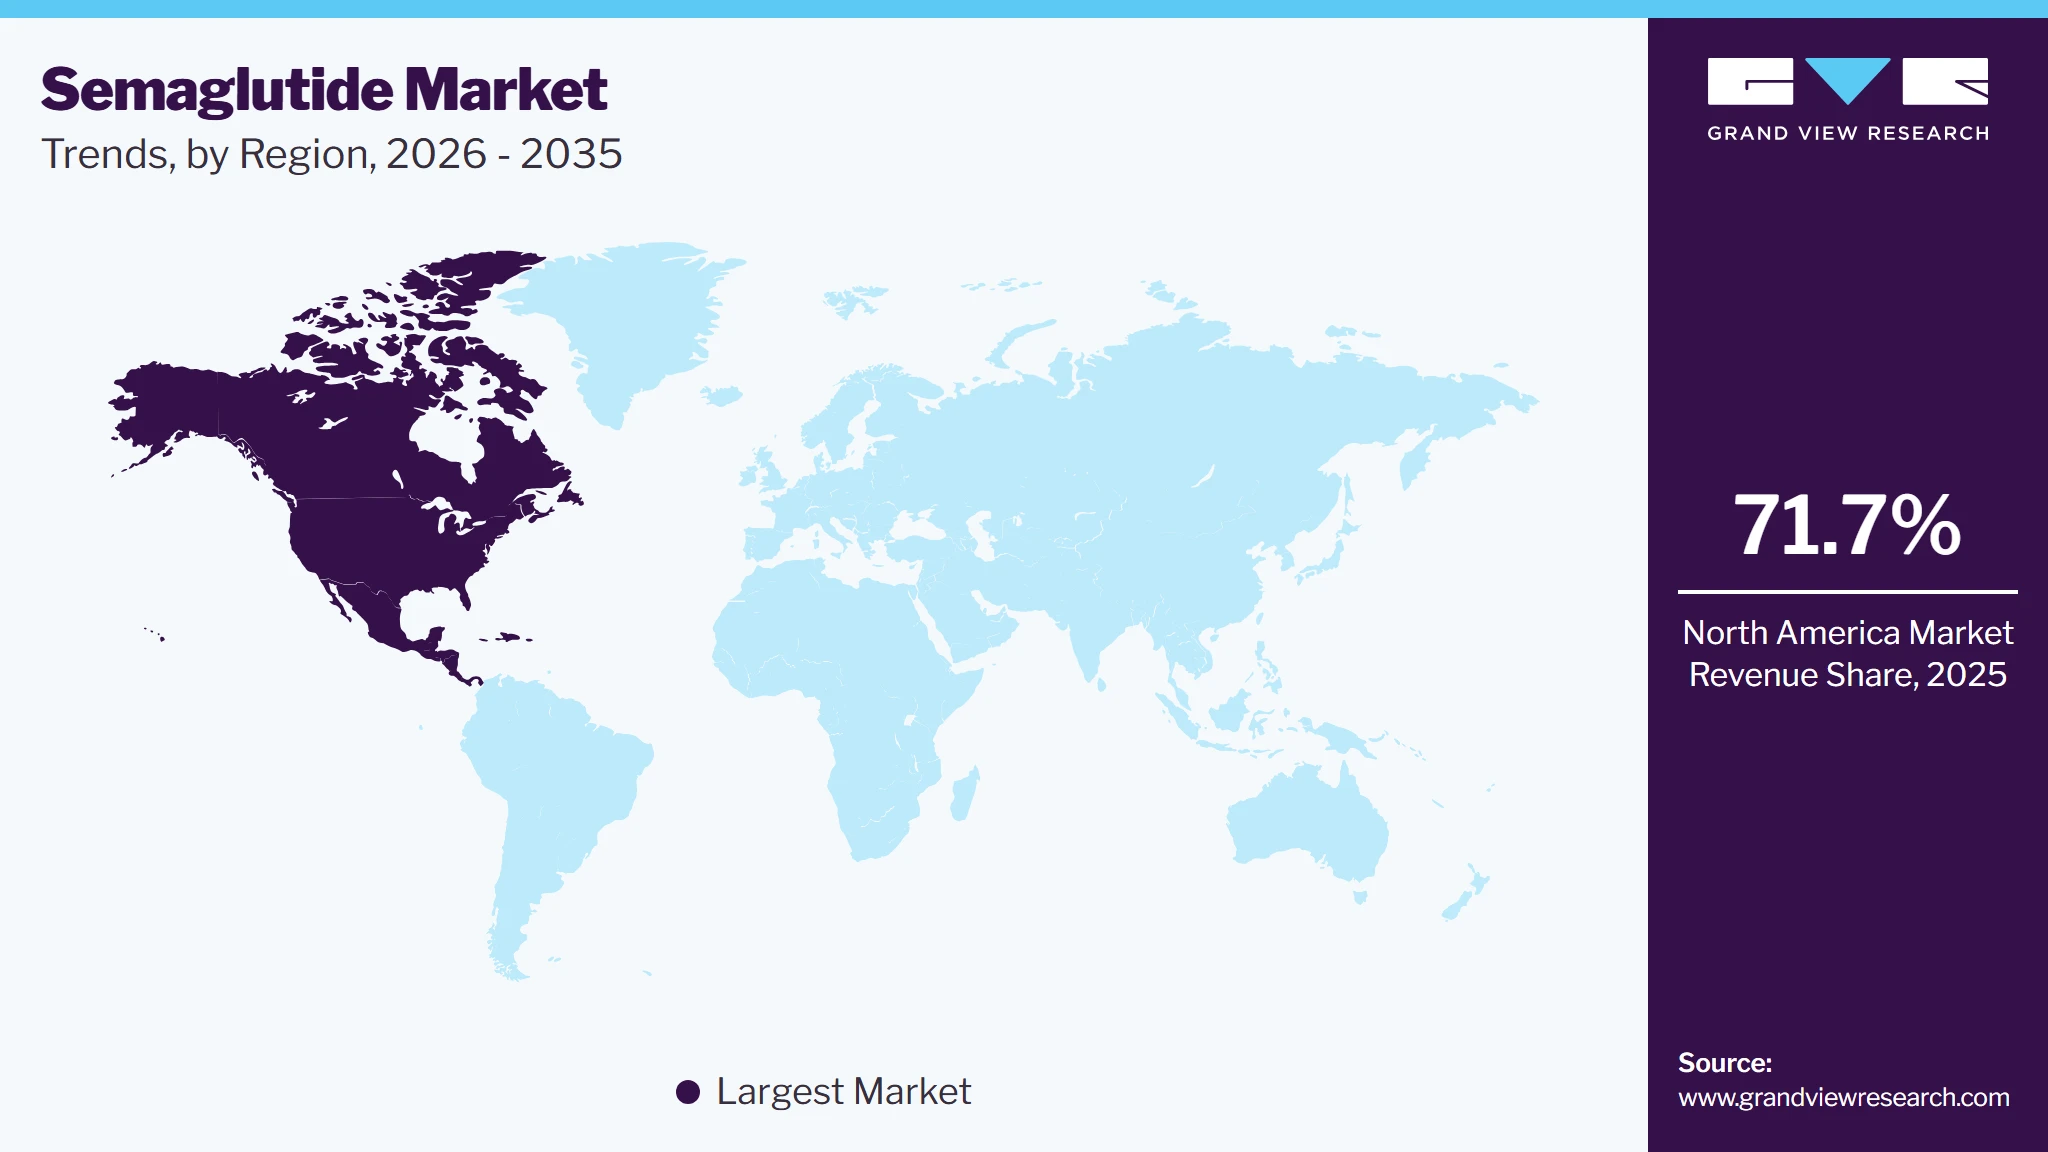
The global semaglutide market size was valued at USD 34.6 billion in 2025 and is projected to grow from USD 40.5 billion in 2026 to USD 93.6 billion by 2035, at a CAGR of 9.8% from 2026 to 2035. North America dominated the market, accounting for the largest global share of 71.7% in 2025. The global semaglutide industry is driven by the increasing prevalence of type 2 diabetes and obesity, rising demand for GLP-1 receptor agonists, and growing adoption of weight management treatments.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Ozempic segment led the market with the largest revenue share of 56.3% in 2025.
- By application: Type 2 diabetes mellitus segment held the largest revenue share of 67.9% in 2025.
- By route of administration: Parenteral segment held the largest revenue share of 87.2% in 2025.
- By distribution channel: Retail pharmacies segment held the largest revenue share of 55.4% in 2025.
Regional Highlights
- Largest regional market: North America (71.7% revenue share, 2025)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 34.6 Billion
- Estimated market size in 2026: USD 40.5 Billion
- Projected market size by 2035: USD 93.6 Billion
- CAGR (2026-2035): 9.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2035 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Expanding clinical applications, regulatory approvals, and strong sales performance further support market growth. Key players invest in R&D, while favorable reimbursement policies and patient preference for once-weekly dosing contribute to market expansion. Pharmaceutical collaborations and geographic expansion strategies also influence market dynamics.The rising global obesity rate is a key driver for the semaglutide market growth, particularly for Wegovy. WHO data (March 2024) reports 890 million obese adults, with associated healthcare costs projected to exceed USD 18 trillion by 2060. Obesity-related conditions, including type 2 diabetes and cardiovascular diseases, are increasing demand for effective pharmacological interventions. Wegovy, a GLP-1 receptor agonist, addresses obesity by regulating appetite and caloric intake. Regulatory support and clinical evidence further accelerate adoption. With obesity’s growing burden on healthcare systems and economies, the market is expanding, positioning Wegovy as a leading solution in medical weight management.
 To learn more about this report, Download Free Sample Report
The rising diabetes burden is a key driver for the semaglutide industry, particularly for Ozempic and Rybelsus. The IDF Diabetes Atlas (2021) reports 537 million adults (20-79 years) living with diabetes, projected to rise to 643 million by 2030 and 783 million by 2045. Over 90% have type 2 diabetes, driven by urbanization, aging populations, and obesity. Nearly 240 million remain undiagnosed, increasing demand for effective treatments. Semaglutide-based therapies, including Ozempic (injectable) and Rybelsus (oral), improve glycemic control and cardiovascular outcomes, positioning them as critical solutions amid the growing diabetes epidemic and rising healthcare expenditure.
Novo Nordisk has made substantial strides in expanding its diabetes and obesity care product reach, with a 6% increase in the number of patients treated with diabetes products, reaching 43 million in 2024. The growth in obesity treatments was particularly notable, with the number of patients reaching 2.2 million in 2024, a 100% increase driven by the expanded launch of Wegovy in additional countries. However, the number of vulnerable patients treated with Diabetes care products decreased by 5%, primarily due to reduced access through affordability initiatives. The Changing Diabetes in Children program also showed strong progress, reaching 64,743 children by the end of 2024, toward a target of 100,000 by 2030.
The willingness to pay for semaglutide influences market expansion, pricing strategy, and adoption. Patients, healthcare providers, and payers recognize its clinical outcomes in weight management, type 2 diabetes, and cardiovascular risk reduction, supporting its pricing. Despite the treatment cost, patients seeking long-term health outcomes choose to pay out-of-pocket, particularly in markets with limited reimbursement.
Healthcare systems and insurers assess the cost-effectiveness of semaglutide in reducing obesity-related complications, which affects healthcare expenditures. This assessment leads to reimbursement approvals and access initiatives, supporting adoption. The cost-benefit profile of semaglutide, in comparison to existing therapies, sustains demand and revenue growth.
Market Dynamics
The semaglutide market is evolving from a diabetes-focused market into a broader metabolic disease market, supported by increasing use in obesity management and the expanding clinical focus on reducing long-term cardiometabolic complications. Demand is concentrated around branded products, as semaglutide remains protected by intellectual property in major markets and no widely available generic versions are currently commercialized. The market is characterized by strong prescription growth, increasing physician confidence, and rising treatment persistence due to proven clinical outcomes in glycemic control, weight reduction, and cardiovascular risk reduction. Healthcare systems are also expanding the use of semaglutide through updated clinical guidelines and broader patient eligibility, although reimbursement policies continue to vary by indication and country. At the same time, manufacturing scale-up, active pharmaceutical ingredient production capacity, and supply management remain important competitive factors as demand continues to exceed supply in several markets. Ongoing clinical studies evaluating semaglutide in chronic kidney disease, metabolic dysfunction-associated steatohepatitis (MASH), and other metabolic disorders are further expanding its commercial potential and strengthening its position within the GLP-1 receptor agonist market.
Driver: Expanding Clinical Use of Semaglutide Across Diabetes, Obesity, and Cardiometabolic Diseases
The increasing use of semaglutide across multiple chronic metabolic conditions is a major driver of market growth. Initially adopted for glycemic control in type 2 diabetes, semaglutide is now widely prescribed for chronic weight management and cardiovascular risk reduction in eligible patients. Clinical guidelines are increasingly recognizing glucagon-like peptide-1 (GLP-1) receptor agonists as an important treatment option because they provide sustained reductions in blood glucose levels, body weight, and cardiovascular events. This broader clinical acceptance has expanded the eligible patient population and increased physician confidence in prescribing semaglutide earlier in disease management. The growing prevalence of obesity and type 2 diabetes continues to support long-term demand, while healthcare providers are placing greater emphasis on therapies that address multiple cardiometabolic risk factors through a single treatment. In addition, ongoing label expansions are increasing the clinical utility of semaglutide across different disease areas, supporting wider adoption in hospitals, specialty clinics, and outpatient settings. For instance, in October 2025, Novo Nordisk received U.S. FDA approval for Rybelsus (oral semaglutide) to reduce the risk of major adverse cardiovascular events in adults with type 2 diabetes who were at high cardiovascular risk. Oral semaglutide 14 mg reduced the risk of major adverse cardiovascular events by 14% compared with placebo. This approval expanded the approved use of oral semaglutide beyond glycemic control, increased physician prescribing opportunities, and strengthened the adoption of semaglutide across the broader cardiometabolic treatment market.
Despite strong clinical demand, the semaglutide market continues to face challenges related to treatment affordability and product availability. Branded semaglutide products remain expensive in many countries, limiting access for patients without comprehensive insurance coverage or reimbursement support. Coverage for obesity treatment also differs across healthcare systems, resulting in unequal patient access even where the medicine is approved. In addition, manufacturing semaglutide requires specialized peptide production capacity, complex fill-finish operations, and strict quality controls, making rapid expansion of supply difficult. Demand has exceeded production capacity in several markets, leading to periodic shortages and delayed treatment initiation for new patients. Healthcare providers have also implemented prescribing prioritization during supply shortages to maintain treatment continuity for existing patients. Furthermore, increasing demand from both diabetes and obesity indications places additional pressure on global manufacturing networks. These factors can slow market penetration, particularly in price-sensitive regions where long-term therapy costs remain a concern. While manufacturers continue to invest in production expansion, balancing global demand with stable supply remains an important operational challenge for the semaglutide market.
The evaluation of semaglutide in additional chronic diseases presents a significant opportunity for market expansion beyond diabetes and obesity. Clinical research has demonstrated that the mechanism of glucagon-like peptide-1 (GLP-1) receptor agonists may provide benefits across several metabolic and organ-specific disorders, encouraging companies to pursue broader regulatory approvals. Positive clinical outcomes in areas such as metabolic dysfunction-associated steatohepatitis (MASH), chronic kidney disease, and cardiovascular disease are creating opportunities to expand the addressable patient population. These additional indications also strengthen product lifecycle management and increase prescribing opportunities across multiple medical specialties, including endocrinology, hepatology, nephrology, and cardiology. As regulatory agencies continue to review new clinical evidence, expanded indications are improving treatment adoption and increasing the role of semaglutide in long-term chronic disease management. For instance, in August 2025, Novo Nordisk received U.S. FDA approval for Wegovy (semaglutide 2.4 mg) for the treatment of noncirrhotic metabolic dysfunction-associated steatohepatitis (MASH) in adults with moderate to advanced liver fibrosis (F2-F3). In the supporting study, 36.8% of patients receiving Wegovy achieved improvement in liver fibrosis without worsening steatohepatitis compared with 22.4% receiving placebo after 72 weeks. The approval expanded semaglutide into a new therapeutic indication, increased its addressable patient population, and created additional growth opportunities for the semaglutide market beyond diabetes and obesity.
Market Concentration & Characteristics
The market is advancing with innovations in drug formulations, delivery mechanisms, and combination therapies. Extended-release formulations, oral versions, and novel co-therapies are improving patient adherence and therapeutic outcomes. Innovations focus on optimizing bioavailability, reducing gastrointestinal side effects, and expanding indications beyond diabetes and obesity to cardiovascular and neurodegenerative disorders.
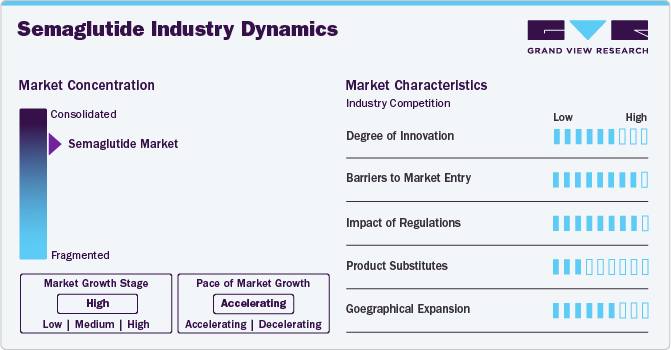
The market has high entry barriers due to strict regulatory requirements, significant R&D investments, and Novo Nordisk’s strong intellectual property protections. The complexity of peptide-based drug development, specialized manufacturing processes, and the need for extensive clinical trials further restrict potential competitors. Additionally, Novo Nordisk’s established market presence and control over global supply chains reinforce its dominance.
 To learn more about this report, Download Free Sample Report
Regulatory agencies, including the FDA and EMA, impose stringent guidelines on semaglutide products, requiring extensive clinical trials to establish long-term safety and efficacy. Pricing and reimbursement policies significantly influence market access, as high treatment costs necessitate favorable insurance coverage. Regulatory harmonization across regions is essential for global adoption, particularly in emerging markets.
Semaglutide competes with other GLP-1 receptor agonists, DPP-4 inhibitors, SGLT2 inhibitors, and insulin therapies. Non-pharmacological approaches, including bariatric surgery and lifestyle modifications, also serve as alternatives. However, semaglutide’s efficacy in weight management, cardiovascular benefits, and patient preference for less frequent dosing contribute to its market expansion.
Novo Nordisk is expanding its semaglutide portfolio into high-growth markets such as Asia-Pacific, Latin America, and the Middle East, driven by rising diabetes and obesity prevalence and improving healthcare infrastructure. The company focuses on securing regulatory approvals, optimizing pricing strategies, and strengthening reimbursement frameworks to enhance patient access. Strategic partnerships with healthcare providers and government initiatives support market penetration, while investments in local manufacturing and distribution networks address supply chain challenges.
Analyst Perspective
The semaglutide market is evolving from a diabetes-focused market into a broader metabolic disease market, supported by expanding clinical use in obesity, cardiovascular disease, and other chronic metabolic conditions. The market is becoming increasingly concentrated around companies with established glucagon-like peptide-1 (GLP-1) receptor agonist development capabilities, manufacturing capacity, and global commercial operations. Novo Nordisk continues to maintain its leadership through its Ozempic, Wegovy, and Rybelsus portfolios, while Eli Lilly is strengthening competition through its incretin-based therapies and continued investment in obesity treatment. At the same time, companies such as Viking Therapeutics, AstraZeneca, Lexicon Pharmaceuticals, and Biocon are expanding research activities and strategic collaborations, contributing to the continued development of the metabolic therapeutics market.
Semaglutide Clinical Trials - Pipeline Analysis
The pipeline for semaglutide-based interventions highlights a broad spectrum of indications beyond diabetes and obesity, areas where approved drugs like Ozempic and Wegovy already dominate. Key ongoing trials focus on conditions such as Alzheimer's disease, non-alcoholic steatohepatitis (NASH), cardiovascular disease, and chronic kidney disease, addressing unmet needs in these therapeutic areas. While diabetes and obesity remain central, with several studies in advanced phases (Phase 3 and 4), the exploration of semaglutide for conditions like early Alzheimer's and liver diseases opens avenues for market expansion. The focus on novel combinations and specialized treatments for these additional indications could significantly enhance the clinical profile of semaglutide, potentially broadening its therapeutic impact and driving growth in emerging treatment areas.
Table: Notable clinical trials for semaglutide - Pipeline Analysis
NCT Number
Study Title
Conditions
Sponsor
Phases & Completion Date
Market Impact
NCT06739044
Efficacy and Safety of Semaglutide Injection Vs Ozempic in Patients with Type 2 Diabetes
Type 2 Diabetes
Hangzhou Zhongmei Huadong Pharmaceutical Co., Ltd.
PHASE3
2/10/2025Potential expansion in diabetic treatment market, especially with biosimilars.
NCT04777409
A Research Study Investigating Semaglutide in People With Early Alzheimer's Disease (EVOKE Plus)
Early Alzheimer's Disease
Novo Nordisk A/S
PHASE3
10/6/2026Could establish semaglutide as a novel treatment for Alzheimer’s disease, opening new revenue streams.
NCT06604624
Semaglutide in Treatment of Obesity
Weight Management
CSPC Baike (Shandong) Biopharmaceutical Co., Ltd.
PHASE3
3/1/2026Increased market penetration for weight management therapies.
NCT04822181
Research Study on Whether Semaglutide Works in People With Non-alcoholic Steatohepatitis (NASH)
Non-alcoholic Steatohepatitis
Novo Nordisk A/S
PHASE3
4/25/2029Significant market potential if approved for NASH treatment, an unmet medical need.
NCT04596631
A Research Study to Compare a New Medicine Oral Semaglutide to a Dummy Medicine in Children and Teenagers With Type 2 Diabetes
Type 2 Diabetes
Novo Nordisk A/S
PHASE3
2/4/2026Expansion of market scope to pediatric diabetes management.
NCT05669755
REDEFINE 3: A Research Study to See the Effects of CagriSema in People Living With Diseases in the Heart and Blood Vessels
Cardiovascular Disease
Novo Nordisk A/S
PHASE3
10/13/2027Broadens semaglutide’s application for cardiovascular disease treatment.
NCT06269107
A Research Study to See How Well New Weekly Medicine IcoSema Controls Blood Sugar Levels in People With Type 2 Diabetes (T2D), Compared to Daily Insulin Glargine (COMBINE 4)
Type 2 Diabetes
Novo Nordisk A/S
PHASE3
6/30/2025If successful, could challenge existing insulin treatments with improved efficacy.
NCT05726227
A Research Study on How Well Semaglutide Helps Children and Teenagers With Excess Body Weight Lose Weight
Obesity
Novo Nordisk A/S
PHASE3
12/7/2026Potential to establish semaglutide as a pediatric weight management treatment.
Growth Scenarios for the Global Semaglutide Market (2035) - Opportunity Analysis
To provide a comprehensive understanding of the future growth potential of the semaglutide industry, we have conducted a detailed market size analysis considering multiple growth scenarios. This analysis aims to offer strategic insights into how various factors-such as regulatory developments, adoption rates, reimbursement policies, and market expansion into new therapeutic indications-might influence the market's trajectory over the next decade.
Market size projections for the global market for semaglutide vary based on different growth scenarios, each accounting for factors such as regulatory developments, adoption rates, reimbursement policies, and market expansion into new indications. These projections provide a strategic outlook on potential market trajectories and the variables influencing overall growth.
 To learn more about this report, Download Free Sample Report
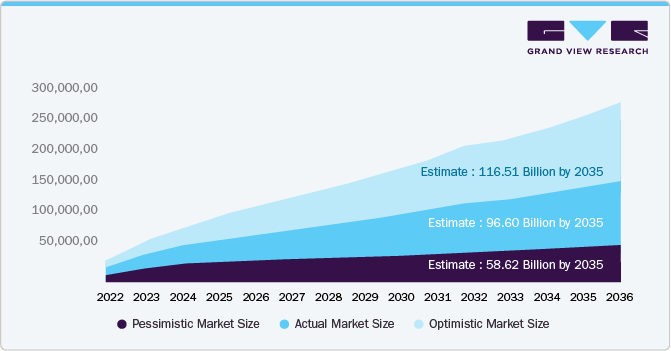
The pessimistic market size represents the lower-end estimate, assuming regulatory hurdles, slower adoption rates, and market saturation. Under this scenario, the market is projected to reach approximately USD 58.6 billion by 2035. Factors such as pricing pressures, supply constraints, competition from alternative therapies, and restrictive reimbursement policies could contribute to slower market growth.
The actual market size reflects the most likely scenario, incorporating current market trends, demand projections, and sustained commercial investments. The market is expected to reach approximately USD 93.60 billion by 2035, driven by expanding therapeutic applications, increasing patient adoption, and continued investment in research and development. This scenario assumes stable regulatory support and steady market expansion.
The optimistic market size represents the higher-end estimate, assuming accelerated adoption, favorable reimbursement policies, and expansion beyond diabetes management into new indications. Under this scenario, the semaglutide market could grow to approximately USD 116.5 billion by 2035. Factors such as wider global accessibility, expanded indications in obesity and cardiovascular diseases, and further clinical advancements would support this level of growth.
Regulatory landscapes, supply chain dynamics, innovation, and accessibility strategies will shape the semaglutide industry trajectory. Continuous investment in research, pricing strategies, and market expansion initiatives will determine the final market size, influencing the long-term commercial success of semaglutide-based therapies.
Off-Label Use and Counterfeit Semaglutide: Regulatory and Market Implications
The FDA has raised concerns over the off-label use of unapproved and compounded semaglutide, citing risks such as dosing errors, safety concerns, and over 455 adverse event reports as of February 2025. The growing demand for GLP-1 receptor agonists in weight management has led to an influx of illegally marketed and counterfeit versions, including counterfeit Ozempic. The FDA warns that compounded semaglutide, especially in salt forms, lacks regulatory oversight, raising concerns over efficacy and safety.
Regulatory actions targeting compounded and counterfeit semaglutide could disrupt supply chains, impact prescribing trends, and increase scrutiny over off-label use. As more patients turn to semaglutide for weight loss-despite its primary FDA approvals for diabetes-these developments could influence market availability and healthcare provider decisions. The FDA’s recent investigations into counterfeit Ozempic reflect a broader effort to curb unauthorized versions of the drug.
As of December 2023, the FDA has seized thousands of units of counterfeit Ozempic and issued warnings for products labeled with lot number NAR0074 and serial number 430834149057. These counterfeit versions contain unverified ingredients and non-sterile needles, increasing the risk of infections. While five adverse events have been reported, none were classified as severe. The FDA advises pharmacies to source Ozempic only from authorized distributors and urges patients to verify their prescriptions.
With the semaglutide shortage now resolved, the FDA has clarified compounding policies. As of February 21, 2025, state-licensed pharmacies and physicians (503A facilities) can compound semaglutide until April 22, 2025, while outsourcing facilities (503B) can continue until May 22, 2025, or pending a court ruling in Outsourcing Facilities Association (OFA) v. FDA. However, the FDA may take action against substandard or unsafe compounded products. These regulatory updates and ongoing legal challenges could reshape compounding policies and market competition in the GLP-1 receptor agonist space, affecting both diabetes management and weight-loss treatments.
Patent Expiry Outlook and Market Implications
The patent loss for Ozempic, Rybelsus, and Wegovy, all under the semaglutide market, presents significant opportunities and challenges. As patents expire between 2026 and 2032, generic competition will likely intensify, potentially reducing market share and pricing power. However, this opens pathways for biosimilars and alternatives, potentially boosting patient access and driving market growth. Companies will need to focus on differentiation, innovation, and extended indications to maintain a competitive edge. Additionally, the expiration of patents may shift the focus toward next-generation therapies, further impacting the market landscape.
Product
U.S.
China
Japan
Europe
Ozempic
2032
2026
2031
2031
Rybelsus
2032
2026
2031
2031
Wegovy
2032
2026
2031
2031
Pricing Dynamics and Affordability Impact for Semaglutide-Based Treatments
The cost of semaglutide-based treatments, including Ozempic, Wegovy, and Rybelsus, is a significant factor influencing their market dynamics. These medications are positioned within a specialized segment targeting diabetes and obesity, where accessibility and affordability are key to broad adoption. The impact of insurance coverage, discounts, and patient assistance programs on out-of-pocket costs is substantial, allowing for greater patient access and adherence. For patients without insurance or with limited coverage, the availability of savings programs can significantly reduce financial barriers, ensuring continued demand. Moreover, as competition grows in the weight management and diabetes treatment sectors, pricing strategies and cost transparency will be critical in maintaining market share. The ongoing adjustments to pricing structures and cost-saving measures directly influence both patient outcomes and long-term market growth, as the affordability of such treatments remains central to addressing the increasing global burden of these chronic conditions.
Product
Dosage
List Price (USD)
Wegovy
1 package
1349.02
Ozempic
0.25 or 0.5 mg (1 x 1.5-mL pen)
997.58
1 mg (1 x 3-mL pen)
997.58
2 mg (1 x 3-mL pen)
997.58
RYBELSUS
3 mg (1 package)
997.58
7 mg (1 package)
997.58
14 mg (1 package)
997.58
Product Insights
Based on product, the ozempic (semaglutide) segment led the market with the largest revenue share of 56.3% in 2025, driven by strong clinical efficacy, broad regulatory approvals, and increasing adoption for type 2 diabetes. Novo Nordisk’s extensive distribution network, favorable reimbursement policies, and ongoing clinical trials reinforced its leadership. The drug’s once-weekly dosing, cardiovascular benefits, and expanding indications fueled growth. Strong sales in North America and Europe, along with market expansion in Asia-Pacific and Latin America, solidified its position. Continued R&D, supply chain optimization, and strategic pricing sustained Ozempic’s dominance despite demand pressures.
A study published in Diabetes Care, "Economic Costs of Diabetes in the U.S. in 2022," analyzed diabetes' financial burden on the U.S. economy. The total cost of diagnosed diabetes in 2022 was USD 412.9 billion, with USD 306.6 billion in direct medical expenses and USD 106.3 billion in indirect costs. The report highlights a rising economic burden, with hospital inpatient care, prescription medications, and diabetes supplies as major contributors. Indirect costs include productivity loss, absenteeism, and disability. The study underscores the urgent need for improved prevention and management strategies to curb escalating costs.
Wegovy is projected to grow at a significant CAGR over the forecast period, driven by rising demand for GLP-1 receptor agonists in weight management. Increasing obesity rates, expanding insurance coverage, and strong clinical outcomes support market expansion. Novo Nordisk’s production scale-up and regulatory approvals in multiple regions further enhance growth prospects. Competition from Eli Lilly’s Zepbound and regulatory scrutiny on off-label semaglutide use may influence market dynamics. However, with sustained consumer interest and physician adoption, Wegovy is expected to maintain strong momentum, reinforcing its position in the obesity treatment market. Future sales growth will depend on supply stability and pricing strategies.
Application Insights
Based on application, the type 2 diabetes mellitus segment led the market with the largest revenue share of 67.9% in 2025, driven by its rising global prevalence and increasing adoption of advanced therapies. The growing use of GLP-1 receptor agonists, including semaglutide (Ozempic, Wegovy), has significantly influenced treatment trends. Expanding healthcare access, favorable reimbursement policies, and continued innovation in insulin formulations further support market growth. While Type 1 Diabetes treatments remain essential, Type 2 Diabetes accounts for the majority of diagnosed cases, reinforcing its market leadership. Pharmaceutical investments and regulatory approvals will shape competitive dynamics and treatment accessibility in 2024.
The obesity segment is expected to witness the significant CAGR during the forecast period, driven by increasing demand for GLP-1 receptor agonists like Wegovy for weight management. Rising obesity prevalence, expanding insurance coverage, and growing physician acceptance of pharmacological interventions contribute to market expansion. Regulatory approvals and clinical evidence supporting semaglutide’s efficacy in weight loss further accelerate adoption. As consumer awareness increases and supply constraints ease, the obesity segment will outpace other applications, positioning semaglutide as a key driver in the evolving weight management market.
Route of Administration Insights
Based on route of administration, the parenteral segment led the market with the largest revenue share of 87.2% in 2025, driven by the widespread adoption of Ozempic and Wegovy, both available as injectable formulations. The strong efficacy and established usage of these GLP-1 receptor agonists in diabetes and obesity management contributed to market leadership. Although an oral formulation of semaglutide is in development for both Ozempic and Wegovy, the injectable form remains the standard due to proven patient adherence and efficacy. Continued innovation in drug delivery may influence future market dynamics, but parenteral administration currently holds the majority share.
The oral route of administration is projected to experience the fastest CAGR over the forecast period, driven by the development of non-injectable alternatives. Novo Nordisk is advancing oral formulations of Ozempic (semaglutide) and Wegovy (semaglutide), which are currently in the pipeline. These developments aim to improve patient compliance and expand market accessibility. While injectable formulations remain dominant, increasing preference for convenient oral options and advancements in drug delivery technology is expected to accelerate market adoption, positioning oral semaglutide as a key growth driver in the coming years.
Distribution Channel Insights
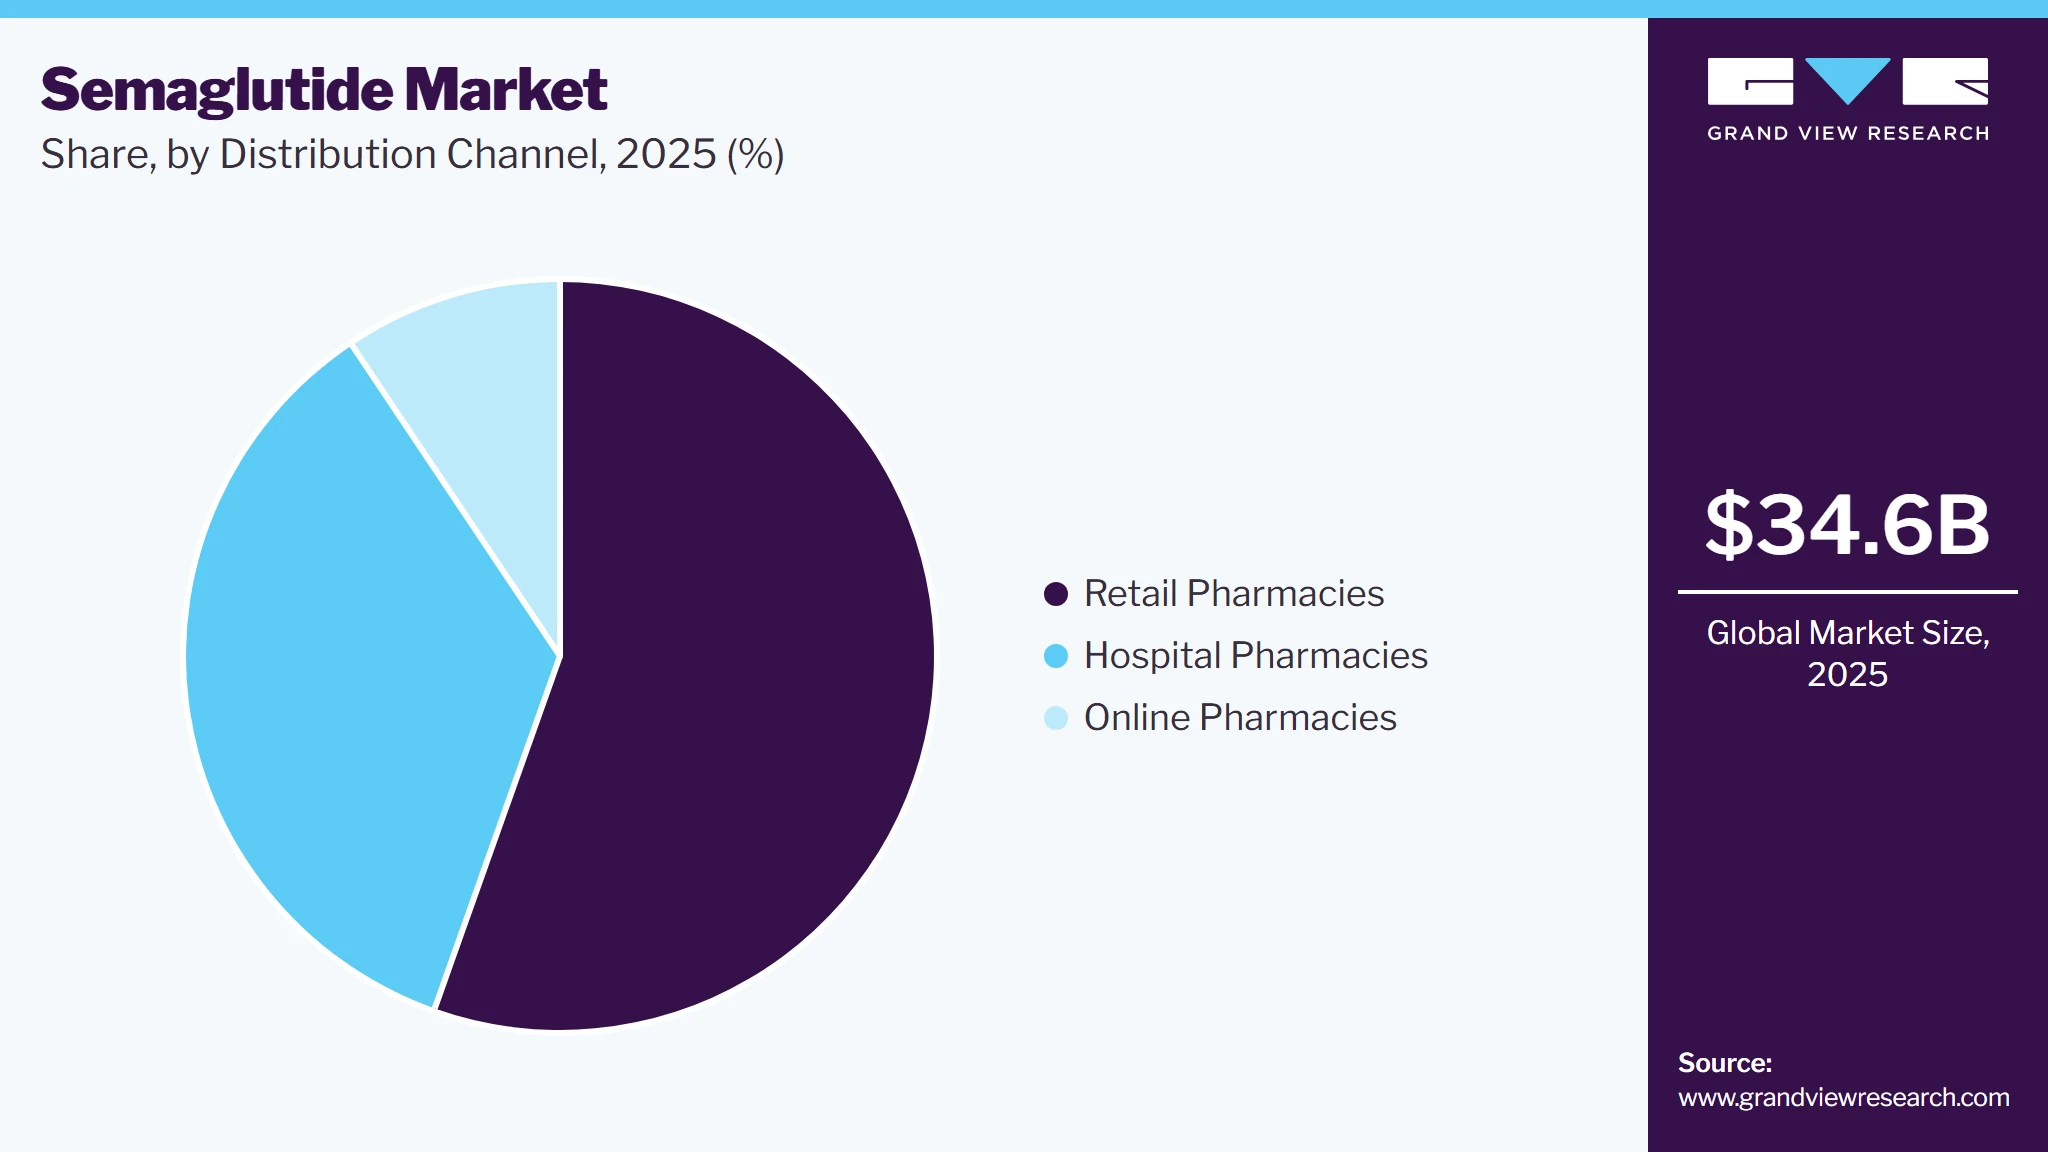
Based on distribution channel, the retail pharmacies segment led the market with the largest revenue share of 55.4% in 2025, driven by increasing consumer demand for GLP-1 receptor agonists like Ozempic and Wegovy. The accessibility of these medications through retail chains enhanced patient convenience, contributing to higher sales volumes. Expanded insurance coverage and direct patient purchases further supported dominance in this segment. While hospital and online pharmacies also play significant roles, retail pharmacies benefited from widespread distribution networks and pharmacist-driven patient engagement, solidifying their position as the primary distribution channel for semaglutide-based therapies.
 To learn more about this report, Download Free Sample Report
The online pharmacies segment is expected to grow at the fastest CAGR during the forecast period, due to increasing consumer preference for digital healthcare solutions. The rising demand for Ozempic and Wegovy, coupled with home delivery convenience, drives this expansion. Enhanced telemedicine services and direct-to-consumer sales models have further accelerated adoption. Regulatory approvals for online prescription fulfillment and expanding insurance coverage contribute to market penetration. While retail pharmacies remain dominant, online platforms benefit from accessibility, competitive pricing, and discreet purchasing options, positioning them as the fastest-growing distribution channel for semaglutide-based therapies.
Regional Insights
North America dominated the semaglutide market with the largest revenue share of 71.7% in 2025, driven by high obesity and diabetes prevalence, strong healthcare infrastructure, and widespread adoption of GLP-1 receptor agonists like Ozempic and Wegovy. The region benefits from favorable reimbursement policies, increasing weight management awareness, and rising prescriptions for off-label use. The U.S. dominates due to robust pharmaceutical regulations, active patient engagement, and significant investments in obesity therapeutics. Additionally, market growth is fueled by ongoing clinical advancements, including oral semaglutide formulations. With continuous regulatory oversight and expanding treatment accessibility, North America remains the largest market for semaglutide-based therapies.
 To learn more about this report, Download Free Sample Report
U.S. Semaglutide Market Trends
The semaglutide market in the U.S. held the largest share in the North America region in 2025. The U.S. dominates the North America semaglutide industry, driven by increasing demand for GLP-1 receptor agonists in diabetes and obesity management. Early regulatory approvals, and extensive R&D activities contribute to market expansion. The rising adoption of semaglutide for weight loss, despite its primary approval for diabetes, is reshaping prescribing trends. Retail pharmacies are the dominant distribution channel, with online pharmacies gaining traction due to convenience and direct-to-consumer models.
Europe Semaglutide Market Trends
Europe exhibits steady semaglutide industry growth, led by Germany, France, and the UK. The region benefits from strong clinical research infrastructure, government initiatives for obesity and diabetes management, and increasing prescriptions of GLP-1 receptor agonists. Regulatory policies supporting obesity therapeutics further drive adoption.
The UK semaglutide market growth is propelled by increasing funding for diabetes and obesity treatments, along with growing demand for personalized medicine. Expanding weight management programs and clinical trials evaluating new formulations contribute to market expansion. Retail pharmacies play a crucial role in semaglutide accessibility, complementing traditional hospital pharmacy channels.
Semaglutide market in Germany is expected to grow during the forecast period. Germany leads the Europe market due to its advanced biopharmaceutical manufacturing and robust healthcare system. Increasing adoption of GLP-1 receptor agonists for metabolic disorders and obesity fuels growth. Hospital pharmacies dominate the distribution landscape, with online pharmacy expansion improving patient access to semaglutide-based therapies.
France semaglutide market benefits from strong regulatory support and public healthcare initiatives aimed at diabetes and obesity management. Increased awareness and reimbursement policies for GLP-1 receptor agonists contribute to higher adoption rates. Hospital pharmacies remain the primary distribution channel, with retail and online pharmacies gradually gaining presence.
Asia Pacific Semaglutide Market Trends
The Asia Pacific semaglutide industry is witnessing rapid expansion, driven by rising obesity and diabetes prevalence, increasing healthcare investments, and regulatory approvals for GLP-1 therapies. China, Japan, and India lead the market, supported by domestic pharmaceutical manufacturing and growing patient awareness. The region is experiencing increasing adoption of semaglutide in both hospital and retail pharmacy settings.
Japan’s semaglutide market is expanding due to government-backed initiatives for diabetes and obesity management. The aging population and increasing prevalence of obesity contribute to demand. Retail pharmacies dominate semaglutide distribution, with hospital pharmacies enhancing disease management strategies.
Semaglutide market in China is growing rapidly, supported by government policies promoting healthcare modernization and local biopharma expansion. Increasing demand for diabetes and obesity treatments, coupled with the rise of online pharmacies, is transforming market accessibility. The country is seeing significant investments in GLP-1 receptor agonist research and manufacturing.
Latin America Semaglutide Market Trends
Latin America is experiencing moderate growth in the semaglutide industry, led by Brazil and Argentina. Increasing healthcare expenditures and rising awareness of obesity treatments are driving market penetration. Expanding government programs for diabetes management support semaglutide adoption in the region.
Brazil’s semaglutide market is growing due to high obesity rates and increasing government efforts to improve healthcare access. Investments in local biopharmaceutical production and partnerships with international firms contribute to expanding semaglutide availability. Retail pharmacies are playing a key role in making GLP-1 therapies more accessible.
Middle East & Africa Semaglutide Market Trends
Middle East and Africa is experiencing growing demand for semaglutide, particularly in Saudi Arabia and the UAE. Government healthcare initiatives and increasing obesity rates are key drivers. The market is expanding as healthcare infrastructure improves and semaglutide accessibility increases through both hospital and retail pharmacies.
Saudi Arabia’s semaglutide market is expanding, driven by healthcare reforms and rising obesity-related complications. Government investments in biotechnology and chronic disease management support semaglutide adoption. Retail and hospital pharmacies are key distribution channels, with growing online pharmacy penetration enhancing patient access.
Key Semaglutide Company Insights
Novo Nordisk dominates the semaglutide market, holding a leading position due to its exclusive development, manufacturing, and commercialization of Ozempic, Wegovy, and Rybelsus. The company's strong market presence is supported by continuous product innovation, global regulatory approvals, and expanding production capacity to meet rising demand. Novo Nordisk’s strategic investments in supply chain expansion and ongoing research in oral semaglutide formulations further strengthen its leadership. With no direct competitors for branded semaglutide, the company maintains control over market dynamics, pricing strategies, and distribution channels, ensuring sustained growth in the GLP-1 receptor agonist segment. However, as the drug approaches patent expiration, the market landscape is expected to shift, with biosimilar competition and alternative GLP-1 receptor agonists or combination therapies challenging its dominance
Competitive Landscape & Emerging Players
-
Lexicon Pharmaceuticals: Lexicon licensed LX9851 to Novo Nordisk for obesity treatment, exploring combination with semaglutide, with up to USD 1 billion in payments.
-
Viking Therapeutics: Viking Therapeutics' VK2735, a dual GLP-1/GIP agonist, showed significant weight loss efficacy in Phase 1/2 trials, competing with semaglutide.
-
Eli Lilly and Company: Lilly's Zepbound outperformed Wegovy in weight loss (20.2% vs. 13.7%) in SURMOUNT-5 trial, demonstrating superior efficacy in obesity management without diabetes.
-
Upcoming Biosimilars: As semaglutide’s patent nears expiration, biosimilar manufacturers, including major generic and biotech firms, are preparing to enter the market. Companies are exploring biosimilar versions, which could reshape the market landscape post-2032.
Key Semaglutide Companies
The following key companies have been profiled for this study on the semaglutide market.
-
Novo Nordisk
-
Eli Lilly
-
Viking Therapeutics
-
Lexicon Pharmaceuticals
-
Biocon
-
AstraZeneca
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Novo Nordisk, Eli Lilly, AstraZeneca)
- Focus on expanding metabolic disease portfolios through new product indications, lifecycle management, and investments in manufacturing capacity. Strengthen market presence through regulatory approvals, global product launches, strategic collaborations, and expansion across diabetes, obesity, cardiovascular, and metabolic disease treatment.
- Strong product portfolios supported by established brands, extensive clinical evidence, and broad regulatory approvals. Wide commercial presence, established manufacturing capabilities, and long-standing relationships with healthcare providers, payers, and distribution partners support sustained market position.
- High manufacturing costs associated with peptide-based therapies and continued investment requirements for production expansion. Dependence on large-scale manufacturing capacity and global supply chain operations may affect product availability during periods of strong demand.
Emerging Players (Viking Therapeutics, Lexicon Pharmaceuticals, Biocon)
- Focus on expanding their presence through development of next-generation metabolic therapies, strategic licensing agreements, partnerships, and biosimilar development. Target unmet clinical needs by advancing differentiated treatment options and increasing participation in obesity and diabetes care.
- Ability to develop differentiated products, flexible research strategies, and focused development programs. Strategic collaborations and cost-efficient development models support entry into selected therapeutic segments and regional markets.
- Limited commercial infrastructure and smaller product portfolios compared with established market participants. Dependence on successful regulatory approvals, partnership agreements, and manufacturing scale-up may delay broader market expansion.
Recent Developments
-
In February 2025, Novo Nordisk announced the FDA has declared the Wegovy and Ozempic shortage over, confirming U.S. supply meets demand. The company invested USD 6.5 billion to expand production and launched the AI-powered Find My Meds app. Novo Nordisk warns against counterfeit drugs and emphasizes responsible use of its FDA-approved semaglutide medicines.
-
In January 2025, Novo Nordisk announced that semaglutide 7.2 mg achieved 20.7% weight loss in the STEP UP trial, surpassing semaglutide 2.4 mg and placebo. The trial confirmed safety and tolerability. Another phase 3 trial, STEP UP T2D, is ongoing. Results reinforce semaglutide’s role in obesity treatment alongside Wegovy’s cardiovascular benefits.
-
In June 2024, Novo Nordisk’s Phase 3 FLOW trial showed Ozempic (semaglutide) 1 mg reduced kidney disease-related events by 24% in type 2 diabetes patients with CKD. The FDA is reviewing a label extension, with a decision expected in January 2025. Results were published in NEJM and presented at ADA 2024.
Semaglutide Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 34.6 billion
Market size value in 2026
USD 40.5 billion
Revenue forecast in 2035
USD 93.6 billion
Growth rate
CAGR of 9.8% from 2026 to 2035
Historical data
2021 - 2024
Forecast period
2026 - 2035
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Novo Nordisk; Eli Lilly; Viking Therapeutics; Lexicon Pharmaceuticals; Biocon; AstraZeneca
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Semaglutide Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2035. For this study, Grand View Research has segmented the global semaglutide market report based on product, application, route of administration, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2035)
-
Ozempic
-
Wegovy
-
Rybelsus
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2035)
-
Type 2 Diabetes Mellitus
-
Obesity
-
Others
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2035)
-
Parenteral
-
Oral
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2035)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The semaglutide market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each semaglutide segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Ozempic
Includes all commercially marketed Ozempic products containing semaglutide. The segment captures demand generated from approved injectable formulations prescribed for labeled indications under the Ozempic brand.
Wegovy
Includes all commercially marketed Wegovy products containing semaglutide. The segment captures demand generated from approved injectable formulations marketed under the Wegovy brand for all labeled therapeutic uses.
Rybelsus
Includes all commercially marketed Rybelsus products containing semaglutide. The segment captures demand generated from approved oral tablet formulations marketed under the Rybelsus brand across approved indications.
Others
Includes semaglutide products marketed under brands other than Ozempic, Wegovy, and Rybelsus, including regional brands and new branded formulations introduced during the forecast period.
Segment-Application
Revenue capture definition
Type 2 Diabetes Mellitus
Includes semaglutide prescribed for the treatment of adults with type 2 diabetes mellitus, including approved use for glycemic management and cardiovascular risk reduction within the indicated patient population.
Obesity
Includes semaglutide prescribed for chronic weight management in adults and adolescents with obesity or overweight according to approved prescribing information. The segment captures demand associated with weight management indications only.
Others
Includes semaglutide prescribed for approved therapeutic indications other than type 2 diabetes mellitus and obesity, including additional metabolic or chronic disease indications approved during the forecast period.
Segment - Route of Administration
Revenue capture definition
Parenteral
Includes all commercially marketed semaglutide formulations administered by subcutaneous injection. The segment captures demand for injectable presentations across approved brands and therapeutic indications.
Oral
Includes all commercially marketed semaglutide formulations administered as oral tablets. The segment captures demand for oral presentations across approved brands and labeled therapeutic indications.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes semaglutide products dispensed through hospital-based pharmacies for inpatient and outpatient treatment. The segment captures products supplied directly by hospitals and affiliated healthcare institutions.
Retail Pharmacies
Includes semaglutide products dispensed through community pharmacies, chain pharmacies, independent pharmacies, and supermarket pharmacy outlets for outpatient use under valid prescriptions.
Online Pharmacies
Includes semaglutide products dispensed through licensed online pharmacy platforms that process prescription orders and deliver products directly to patients through digital sales channels.
Estimation Model
 To learn more about this report, Download Free Sample Report
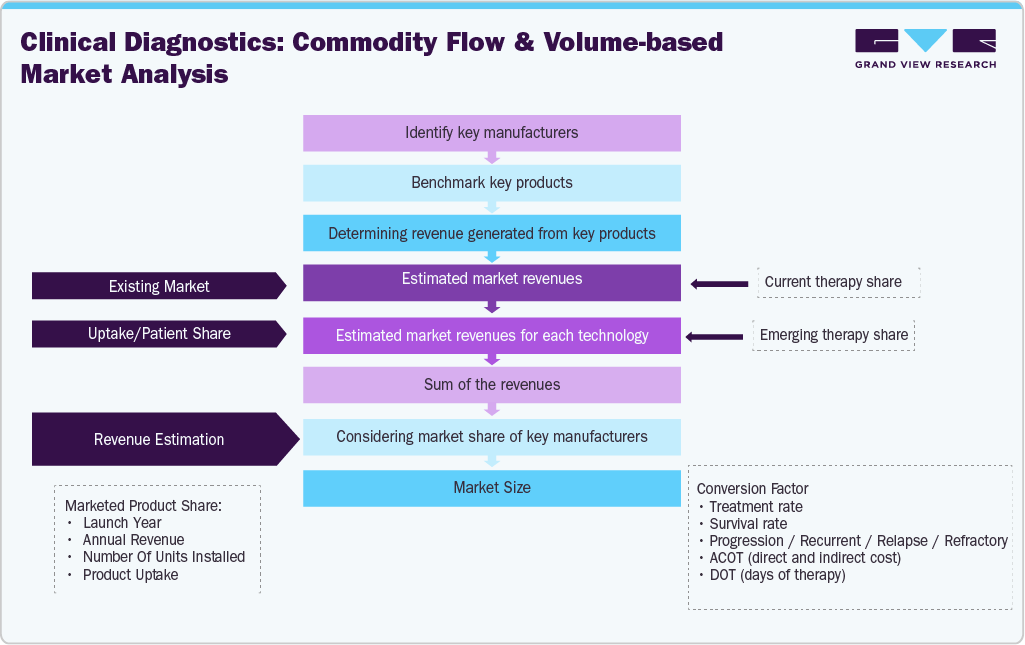
The Semaglutide Market was estimated using a commodity flow market analysis based on revenues generated from commercially available semaglutide products. Key manufacturers were identified, followed by benchmarking marketed products, including Ozempic, Wegovy, and Rybelsus, across major regions. Product-level revenues were evaluated using company annual reports, quarterly financial results, investor presentations, regulatory filings, and official company press releases. Revenue contribution was allocated by region based on product availability, regulatory approvals, prescription trends, distribution network, and geographic sales presence. Market estimates were further segmented by product, application, route of administration, and distribution channel using prescription patterns, treatment utilization, and product positioning. The aggregated product revenues were validated through company market presence, manufacturing capacity, pricing trends, and secondary healthcare databases. Final market estimates were verified through primary interviews with industry participants and triangulated using multiple data sources to ensure consistency and accuracy.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Semaglutide Competitive Landscape & Pipeline Assessment
Conducted a detailed assessment of the global semaglutide market, evaluating approved products, pipeline therapies, lifecycle management strategies, regulatory progress, and competitive positioning. The study analyzed key participants including Novo Nordisk, Eli Lilly, Viking Therapeutics, Lexicon Pharmaceuticals, Biocon, and AstraZeneca, along with emerging therapies targeting obesity, type 2 diabetes, and other metabolic disorders.
Helped the client identify key market participants, evaluate pipeline competition, benchmark product differentiation, and assess licensing, partnership, and acquisition opportunities across the metabolic therapeutics market.
Semaglutide Product & Clinical Benchmarking Study
Delivered a comprehensive benchmarking analysis of marketed semaglutide products and pipeline candidates, focusing on product positioning, dosage forms, route of administration, approved indications, clinical evidence, regulatory status, and lifecycle management strategies. The assessment compared product differentiation, indication expansion, manufacturing capabilities, and geographic availability across leading market participants.
Enabled the client to assess product competitiveness, identify gaps in therapeutic positioning, evaluate future indication opportunities, and support portfolio planning based on clinical and commercial developments within the semaglutide market.
Semaglutide Manufacturing & Supply Chain Feasibility Assessment
Conducted a strategic assessment of the semaglutide manufacturing ecosystem, evaluating active pharmaceutical ingredient production, peptide manufacturing capabilities, fill-finish operations, supply chain capacity, regulatory compliance requirements, and contract manufacturing opportunities. The study assessed manufacturing scalability, regional production capabilities, and supply continuity supporting commercial distribution across global markets.
Supported manufacturing planning by identifying production capabilities, evaluating supply chain risks, assessing outsourcing opportunities, and strengthening long-term manufacturing capacity planning to support growing demand for semaglutide products across global markets.
Frequently Asked Questions About This Report
The global semaglutide market size was valued at USD 34.6 billion in 2025 and is estimated at USD 40.5 billion in 2026.
The global semaglutide market is expected to grow at a CAGR of 9.8% from 2026 to 2035, reaching USD 93.6 billion by 2035.
North America dominated the semaglutide market with a 71.7% revenue share in 2025.
Asia Pacific is the fastest-growing regional market over the forecast period.
The Ozempic (semaglutide) segment led the market with a 56.3% revenue share in 2025.
The type 2 diabetes mellitus segment held the largest revenue share of 67.9% in 2025.
The retail pharmacies segment held the largest revenue share of 55.4% in 2025.
Key players include Novo Nordisk, Eli Lilly, Viking Therapeutics, Lexicon Pharmaceuticals, Biocon, and AstraZeneca.
Key factors include expanding clinical use across type 2 diabetes, obesity, and cardiometabolic diseases, increasing physician confidence, growing prevalence of obesity and diabetes, expanding regulatory approvals for new indications, and ongoing investments in manufacturing capacity and supply expansion.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


