
- Home
- »
- Distribution & Utilities
- »
-
Shunt Reactor Market Size, Share & Growth Report, 2033GVR Report cover

Shunt Reactor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Oil-Immersed Shunt Reactor, Air-Core Shunt Reactor), By Phase (Single Phase, Three Phase), By Application, By Region, And Segment Forecasts
Market Size, 2025
$2.8BMarket Estimate, 2026
$3.0BMarket Forecast, 2033
$4.9BCAGR, 2026–2033
7.2%Shunt Reactor Market Summary
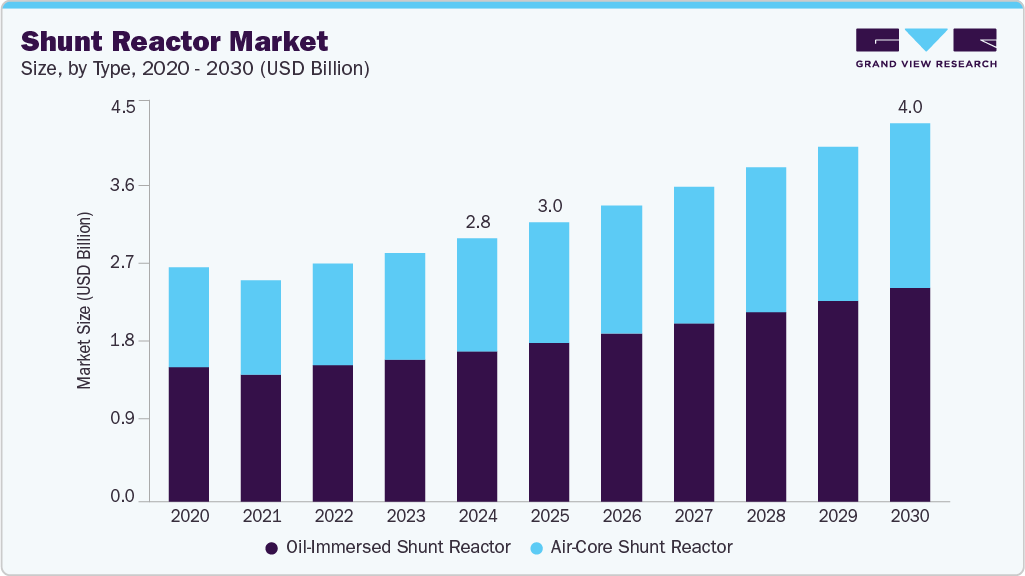
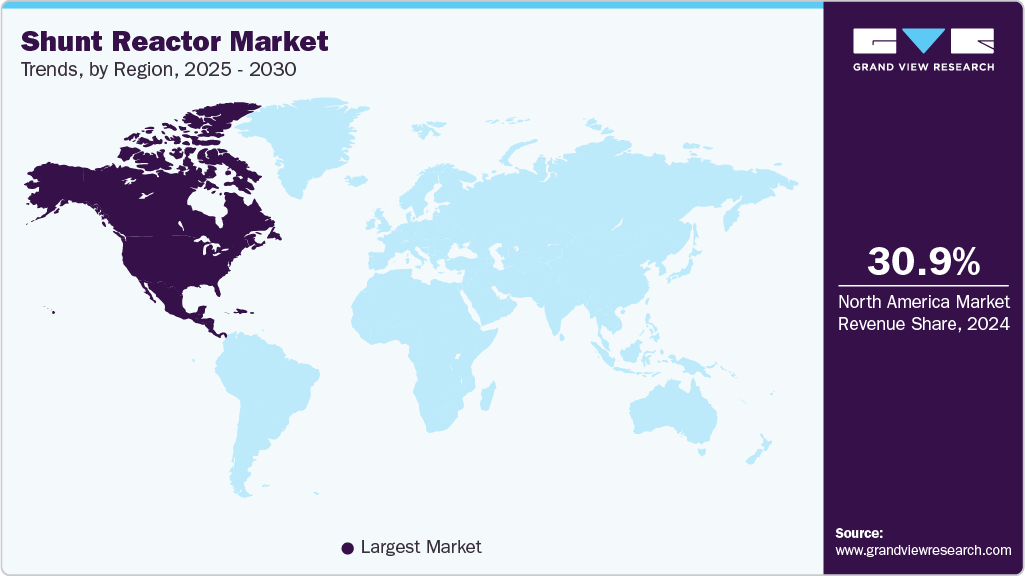
The global shunt reactor market size was valued at USD 2.8 billion in 2025 and is projected to grow from USD 3.0 billion in 2026 to USD 4.9 billion by 2033, at a CAGR of 7.2% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 42.8% in 2025. This growth is driven by rising demand across various applications, particularly in power transmission and distribution systems.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Oil-immersed shunt reactor segment held the largest market share of 84.2% in 2025.
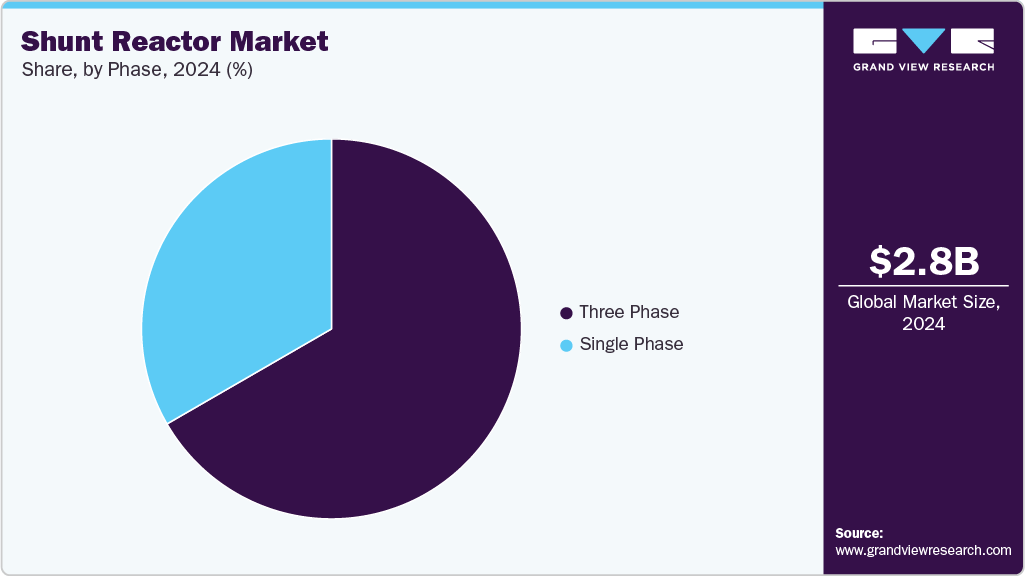
- By phase: Three phase segment held the largest market share of 66.4% in 2025.
- By application: Fixed segment held the largest market share of 81.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (42.8% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.8 Billion
- Estimated market size in 2026: USD 3.0 Billion
- Projected market size by 2033: USD 4.9 Billion
- CAGR (2026-2033): 7.2%
Prism AI by Grand View Research Free to tryAsk a question about the shunt reactor marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The surge is supported by increasing global electricity consumption, fueled by industrialization, urbanization, and infrastructure development. As the adoption of renewable energy sources, such as solar and wind power, increases, their inherently variable nature introduces volatility into the system. Shunt reactors are essential for maintaining grid stability and ensuring a reliable power supply by managing voltage fluctuations. In high-voltage transmission networks, they play a key role in voltage regulation under varying load conditions. These reactors are strategically engaged and disengaged to provide necessary reactive power compensation, in alignment with the prevailing voltage demands.Environmental considerations and strict government regulations promoting energy efficiency are driving the adoption of shunt reactors in power networks. A growing emphasis on reducing carbon emissions and enhancing grid reliability is prompting utilities to embrace supportive technologies. In 2023, the Australian government emphasized the importance of integrating renewable energy sources into the grid without compromising environmental integrity, as outlined by the Environment Protection and Biodiversity Conservation Act. This legislation ensures that new energy initiatives, including those involving shunt reactors, meet stringent environmental criteria, fostering technology adoption for improved grid stability and efficiency.
 To learn more about this report, Download Free Sample Report
Advancements in grid infrastructure and integrating renewable energy sources are expected to drive market expansion. As renewable energy generation grows, reactive power compensation becomes essential for maintaining voltage levels and ensuring system stability. The U.S. EPA has also underscored the role of advanced technologies in enhancing grid resilience and reliability, which is crucial as more intermittent renewable energy sources, such as wind and solar, are incorporated into the energy mix.
Rising demand for grid stability and reliability, as well as the increase in the adoption of electric vehicle (EV), are anticipated to propel the growth of the shunt reactor industry. The growing number of EVs places added pressure on power grids, especially with increased charging needs, highlighting the importance of maintaining voltage stability. Shunt reactors are critical in regulating voltage and mitigating overvoltage issues, ensuring smooth grid operations. With grids becoming more complex and EVs expanding, the demand for efficient power distribution solutions, including shunt reactors, is expected to rise.
Market Dynamics
The shunt reactor market is driven by the growing expansion of high-voltage transmission networks, increasing integration of renewable energy sources, and rising investments in grid modernization to maintain voltage stability and improve power quality. Utilities are increasingly deploying shunt reactors to manage reactive power and ensure reliable electricity transmission across long-distance power lines. The market is also benefiting from the replacement of aging grid infrastructure and the development of smart grids, particularly in emerging economies. However, high installation costs and the complexity of integrating shunt reactors into existing power systems remain key challenges, while advancements in digital monitoring and eco-friendly insulation technologies present significant growth opportunities.
The increasing integration of renewable energy sources into power grids is a major driver of the shunt reactor market. Wind and solar power generation are inherently variable, causing voltage fluctuations and excess reactive power, particularly across long-distance transmission networks. Shunt reactors play a critical role in absorbing reactive power and maintaining voltage stability, enabling grid operators to integrate renewable electricity without compromising system reliability. As countries accelerate renewable capacity additions and strengthen interregional transmission infrastructure, demand for shunt reactors continues to rise to support stable and efficient grid operations.
In May 2025, GE Vernova secured an order from Power Grid Corporation of India (POWERGRID) to supply more than 70 units of 765 kV extra-high-voltage transformers and shunt reactors for renewable energy transmission corridors. The equipment will support multiple transmission projects designed to evacuate electricity from large-scale renewable energy installations under India's Tariff-Based Competitive Bidding (TBCB) framework, with deliveries beginning in 2026. The project highlights the increasing deployment of shunt reactors to maintain voltage stability and enable reliable integration of renewable power into national transmission networks.
The high upfront capital investment required for shunt reactors is a significant restraint on market growth. These systems are engineered for high-voltage transmission networks and require specialized core materials, advanced insulation systems, cooling mechanisms, and extensive testing to ensure reliable operation. In addition to equipment costs, utilities must invest in installation, commissioning, civil infrastructure, and long-term maintenance, increasing the overall project expenditure. These high initial costs can discourage adoption, particularly among smaller utilities and power operators in developing economies with constrained infrastructure budgets.
The increasing deployment of Variable Shunt Reactors (VSRs) presents a significant growth opportunity for the shunt reactor market. Unlike fixed shunt reactors, VSRs continuously adjust reactive power output in real time, enabling grid operators to manage voltage fluctuations caused by the intermittent nature of renewable energy sources such as wind and solar. As utilities modernize transmission networks and adopt smart grid technologies, the demand for flexible voltage regulation solutions is expected to rise. Their ability to improve grid stability, reduce transmission losses, and support dynamic power flows makes VSRs particularly attractive for high-renewable and ultra-high-voltage transmission systems.
Analyst Perspective
The shunt reactor market is experiencing steady growth as utilities invest in expanding transmission networks and integrating renewable energy into the grid. Rising deployment of high-voltage AC transmission lines and the modernization of aging grid infrastructure are creating sustained demand for shunt reactors that improve voltage stability and reduce transmission losses. A key market trend is the increasing adoption of digitally monitored and smart shunt reactors that enable real-time condition monitoring and predictive maintenance, helping utilities improve grid reliability while reducing operating costs.
Type Insights
Based on type, the oil-immersed shunt reactor segment led the market with the largest revenue share of 84.2% in 2025, fueled by its exceptional performance and reliability. These reactors use mineral oil as a coolant and an insulating medium, providing excellent heat dissipation and insulation qualities that make them well-suited for continuous operation in large-scale power grid applications. Their robust design and low maintenance requirements enhance long-term efficiency, especially under fluctuating load conditions.
The air-core shunt reactor segment is anticipated to be the fastest-growing segment, with a CAGR of 9.2% over the forecast period, driven by advancements in high-voltage direct current transmission and renewable energy projects that demand superior performance in voltage control and stability. Unlike oil-immersed reactors, air-core reactors use air as the core material, reducing energy losses and environmental impact. Their lightweight construction and reduced footprint make them suitable for installation in compact spaces, such as urban substations and offshore wind farms.
Phase Insights
Based on phase, the three phase segment led the market with the largest revenue share of 66.4% in 2025, propelled by its widespread application in high-voltage transmission systems, where it effectively manages reactive power and enhances voltage stability. Its ability to handle large amounts of reactive power compensation is essential for maintaining grid reliability, especially with the increasing integration of renewable energy sources. Furthermore, major players like Siemens and ABB have developed advanced three-phase shunt reactors to cater to the growing demand for efficient power transmission, further solidifying their market dominance.
 To learn more about this report, Download Free Sample Report
The single phase segment is expected to grow at the fastest CAGR from 2026 to 2033, owing to their suitability for lower voltage applications and ease of installation in urban environments with space limitations. The increasing demand for localized reactive power compensation in distribution networks has driven the surge in one-phase shunt reactor adoption. For instance, in 2023, Hitachi Energy introduced compact one-phase shunt reactors designed specifically for urban areas, addressing space constraints while providing effective voltage regulation.
Application Insights
Based on application, the fixed segment led the market with the largest revenue share of 81.1% in 2025, propelled by expanding applications in traditional power transmission networks and industrial installations where steady-state voltage control is paramount. These reactors have a fixed number of tapping points or fixed impedance values designed to provide consistent reactive power compensation under normal operating conditions. They are essential for maintaining grid stability and power quality in large-scale transmission lines and substations.
The variable segment is expected to grow at the fastest CAGR from 2026 to 2033, due to its flexibility in adjusting reactive power compensation based on dynamic grid conditions and varying loads. These reactors feature adjustable tapping points or electronically controlled switching mechanisms that precisely regulate voltage levels in response to fluctuating demand or grid disturbances. Their ability to dynamically manage reactive power ensures optimal grid stability and efficiency, particularly in networks facing variable operational conditions or integrating renewable energy sources.
Regional Insights
North America's shunt reactor market account for the significant revenue share of 21.7% in 2025, driven by robust investments in upgrading aging grid infrastructure and integrating renewable energy sources. The U.S. leads the market, supported by stringent regulatory frameworks and the growing need for a reliable electricity supply. In addition, government initiatives such as the U.S. Department of Energy's "Building a Better Grid" program are catalyzing investments in high-voltage transmission facilities and grid modernization.
U.S. Shunt Reactor Market Trends
The U.S. shunt reactor market held the largest share in 2025, driven by increasing demand for energy efficiency and the modernization of aging power infrastructure. Key trends include a heightened focus on environmentally sustainable solutions, with manufacturers like Hitachi Energy introducing variable shunt reactors that enhance voltage stability while minimizing environmental impact.
Europe Shunt Reactor Market Trends
The European shunt reactor market is anticipated to experience significant expansion during the forecast period, fueled by the region's focus on enhancing grid reliability and reducing transmission losses. Europe’s ambitious renewable energy targets and the need for stable integration of renewable power sources are creating strong demand for shunt reactors.
Asia Pacific Shunt Reactor Market Trends
Asia Pacific dominated the shunt reactor market with the largest revenue share of 42.8% in 2025, attributed to rapid industrialization and urbanization in countries like China and India. The region's expanding power generation capacities and investments in renewable energy sources and smart grid technologies are key drivers of market growth.
 To learn more about this report, Download Free Sample Report
The shunt reactor market in China held the largest share in the Asia Pacific region in 2025. China's shunt reactor market is projected to grow significantly during the forecast period due to rapid industrialization, urbanization, and increasing energy demands. As the country invests heavily in renewable energy sources, smart grid technologies, and high-voltage transmission infrastructure, stable and efficient power distribution becomes critical. Shunt reactors play a key role in regulating voltage and ensuring grid stability.
Key Shunt Reactor Company Insights
Some of the key companies in the shunt reactor industry include ABB; General Electric Company; Siemens; TOSHIBA CORPORATION; Fuji Electric Co., Ltd.; Mitsubishi Electric Corporation; and Hitachi Energy Ltd.
-
ABB, headquartered in Switzerland, is a global leader in power and automation technologies, offering advanced shunt reactor solutions designed for voltage regulation and stability in transmission networks. With a strong commitment to sustainability and innovation, ABB continues to expand its market presence through strategic partnerships and technological advancements.
-
Siemens, based in Germany, is a key player in the energy sector, providing comprehensive shunt reactor solutions aimed at optimizing grid performance and efficiency. Leveraging its extensive expertise in power transmission and distribution, Siemens delivers reliable and scalable shunt reactor systems that meet the evolving needs of utilities worldwide.
Key Shunt Reactor Companies:
The following key companies have been profiled for this study on the shunt reactor market.
-
ABB
-
General Electric Company
-
Siemens
-
Crompton Greaves Consumer Electricals Limited
-
TOSHIBA CORPORATION
-
Fuji Electric Co., Ltd.
-
Mitsubishi Electric Corporation
-
NISSIN ELECTRIC Co., Ltd.
-
Trench Group
-
Hilkar
-
TBEA
-
Hitachi Energy Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ABB, General Electric Company, Siemens Energy, CG Power & Industrial Solutions Ltd., TOSHIBA CORPORATION, Fuji Electric Co., Ltd., Mitsubishi Electric Corporation, NISSIN ELECTRIC Co.,Ltd., Hitachi Energy Ltd)
- Focus on expanding global manufacturing capacity and strengthening localized production to meet utility and grid modernization demand.
- Invest continuously in R&D to develop high-efficiency shunt reactors with lower losses, reduced noise levels, and enhanced operational reliability.
- Strengthen market presence through turnkey EPC capabilities, long-term utility contracts, and partnerships with transmission system operators.
- Strong global brand recognition and long-standing relationships with utilities, EPC contractors, and transmission operators.
- Comprehensive product portfolios covering fixed, variable, oil-immersed, and air-core shunt reactors for diverse voltage levels.
- Extensive manufacturing capabilities, advanced engineering expertise, and proven execution of large-scale transmission projects.
- Higher manufacturing and operational costs compared to regional competitors.
- Longer product development and approval cycles due to complex organizational structures.
- Greater dependence on utility capital expenditure cycles and large infrastructure investments.
Emerging Players (Trench Group, Hilkar)
- Focus on niche applications, customized reactor designs, and regional transmission projects to establish market presence.
- Expand through strategic partnerships with EPC contractors, transformer manufacturers, and local utilities.
- Invest selectively in manufacturing upgrades and engineering capabilities to improve product quality and competitiveness.
- Greater flexibility in delivering customized solutions for specific voltage ratings and project requirements.
- Lower operating costs and competitive pricing for regional utility and industrial projects.
- Faster decision-making and shorter lead times due to lean organizational structures.
- Limited global brand recognition and smaller installed base compared to established manufacturers.
- Lower R&D budgets, restricting the development of advanced digital monitoring and next-generation reactor technologies.
- Limited manufacturing scale, resulting in lower economies of scale for large-volume orders.
Recent Developments
-
In April 2024, Hitachi Energy announced plans to invest over USD 100 million to upgrade its power transformer factory in Quebec, Canada. The investment aims to enhance manufacturing capabilities to meet the growing demand for advanced power transmission technologies, such as shunt reactors.
-
In September 2023, Hitachi Energy announced a strategic partnership with TenneT to supply transformers and shunt reactors as part of TenneT’s transmission grid development program in Germany. By providing advanced shunt reactors, Hitachi Energy aims to improve reactive power compensation and voltage regulation within TenneT’s infrastructure, supporting the shift to a more sustainable energy system.
Shunt Reactor Market Report Scope
Report Attribute
Details
Market Definition
The shunt reactor market comprises the sales of oil-immersed and air-core shunt reactors in single-phase and three-phase configurations used to maintain voltage stability in high-voltage power transmission networks.
Market size in 2025
USD 2.8 billion
Estimated market size in 2026
USD 3.0 billion
Projected market size by 2033
USD 4.9 billion
Growth rate
CAGR of 7.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, Phase, Application, Region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, U.K., Spain, France, Italy, China, India, Japan, South Korea, Brazil, Argentina, Saudi Arabia, UAE, and South Africa.
Key companies profiled
ABB, General Electric Company, Siemens Energy, CG Power & Industrial Solutions Ltd., TOSHIBA CORPORATION, Fuji Electric Co., Ltd., Mitsubishi Electric Corporation, NISSIN ELECTRIC Co.,Ltd., Hilkar, Trench Group, Hitachi Energy Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Shunt Reactor Market Report Segmentation
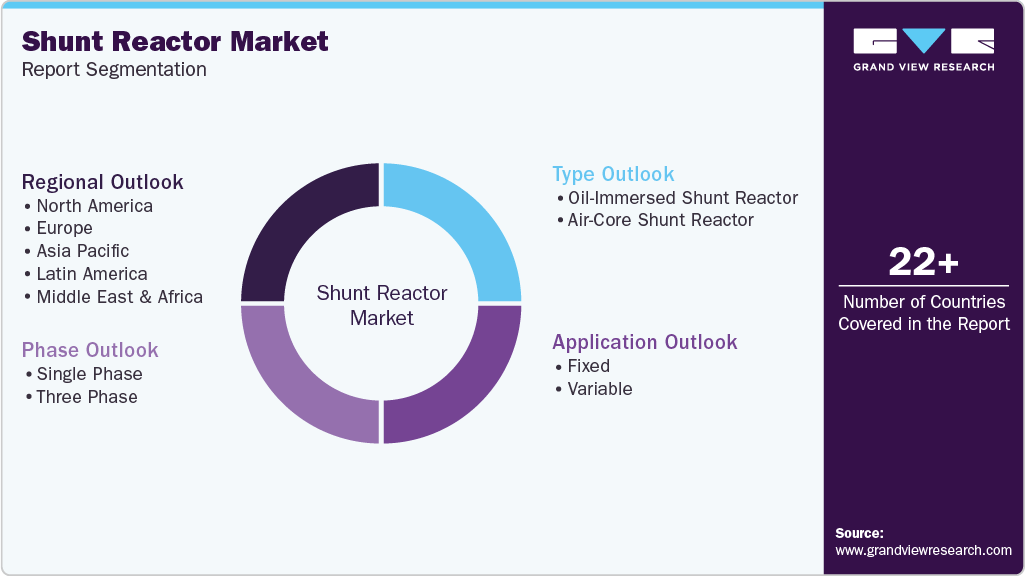
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global shunt reactor market report based on type, phase, application, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oil-Immersed Shunt Reactor
-
Air-Core Shunt Reactor
-
-
Phase Outlook (Revenue, USD Billion, 2021 - 2033)
-
Single Phase
-
Three Phase
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Fixed
-
Variable
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
Spain
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The shunt reactor market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each shunt reactor segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Oil-Immersed Shunt Reactor
Captures revenue from the sale of oil-immersed shunt reactors used for reactive power compensation and voltage regulation in high-voltage transmission and substation applications.
Air-Core Shunt Reactor
Includes revenue from air-core shunt reactors deployed for voltage stabilization and reactive power compensation in transmission networks and industrial power systems.
Segment - Phase
Revenue capture definition
Single Phase
Consists of sales of single-phase shunt reactors used in high-voltage transmission systems and substations requiring individual phase operation.
Three Phase
Comprises sales of three-phase shunt reactors designed for integrated voltage regulation and reactive power compensation in power transmission networks.
Segment - Application
Revenue capture definition
Fixed
Accounts for sales of fixed shunt reactors that provide continuous reactive power compensation under stable grid operating conditions.
Variable
Represents sales of variable shunt reactors that dynamically regulate reactive power to maintain voltage stability under changing grid conditions.
Estimation Model
Layer Name
Key Question
Description
Shunt Reactor Demand Layer
What drives the demand for shunt reactors?
Identify the key demand drivers for shunt reactors, including expansion of high-voltage transmission networks, increasing renewable energy integration, rising investments in grid modernization, reactive power compensation requirements, cross-border interconnections, and replacement of aging transmission infrastructure. Assess the impact of grid stability requirements and growing electricity demand on market growth.
Shunt Reactor Type & Phase Layer
What types and configurations are used?
Analyze market adoption based on type (oil-immersed and air-core) and phase configuration (single-phase and three-phase). Assess preferences based on voltage level, installation environment, maintenance requirements, cooling performance, system flexibility, and utility network specifications.
Shunt Reactor Application Layer
How are shunt reactors deployed?
Evaluate demand across fixed and variable shunt reactor applications. Assess adoption based on grid operating conditions, reactive power compensation needs, renewable energy integration, transmission system flexibility, and voltage regulation requirements in modern power networks.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sales of oil-immersed and air-core shunt reactors across single-phase and three-phase configurations for fixed and variable applications. The overall market value is determined by revenue generated from shunt reactors supplied for transmission substations, utility grid expansion, and grid modernization projects.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
A detailed analysis was conducted to evaluate the adoption of Oil-Immersed Shunt Reactors across Fixed and Variable applications by assessing technical suitability, grid voltage regulation requirements, installation environment, operational flexibility, maintenance needs, and regional deployment trends.
Identified high-growth product-application combinations, technology adoption trends, application-specific advantages, and revenue opportunities across different shunt reactor configurations.
Competitive Benchmarking
Key shunt reactor manufacturers were benchmarked based on product portfolio (oil-immersed and air-core shunt reactors), phase offerings (single-phase and three-phase), voltage range, manufacturing capabilities, digital monitoring features, R&D investments, global presence, utility and EPC partnerships, service network, and recent strategic developments.
Provided insights into competitive positioning, product differentiation, technological capabilities, expansion strategies, and key opportunities for partnerships and market entry.
Application-Level Opportunity Analysis
A comprehensive assessment of Fixed and Variable shunt reactor applications was conducted by analyzing transmission network expansion, renewable energy integration, long-distance power transmission projects, voltage regulation requirements, grid modernization initiatives, utility investment trends, and regional demand patterns.
Identified the most attractive application segments, emerging growth opportunities, investment hotspots, and key demand drivers supporting future market expansion.
Frequently Asked Questions About This Report
The Asia Pacific region dominated the shunt reactor market with a revenue share of 42.8% in 2025.
China dominated the Asia Pacific region market with a revenue share of 47.5% in 2025.
Middle East & Africa is anticipated to register the second fastest CAGR of 8.0% over the forecast period.
Based on type, the oil-immersed shunt reactor segment accounted for the largest revenue share of 84.2% in 2025.
The key factors driving the shunt reactor market include rising investments in transmission infrastructure, increasing renewable energy integration, growing deployment of high-voltage power networks, and ongoing grid modernization initiatives.
The global shunt reactor market size was valued at USD 2.8 billion in 2025 and is estimated at USD 3.0 billion for 2026.
The global shunt reactor market is expected to grow at a CAGR of 7.2% from 2026 to 2033, reaching USD 4.9 billion by 2033.
Based on application, the fixed segment accounted for the largest revenue share of 81.1% in 2025.
The key players operating in the shunt reactor market are ABB, General Electric Company, Siemens Energy, CG Power & Industrial Solutions Ltd., TOSHIBA CORPORATION, Fuji Electric Co., Ltd., Mitsubishi Electric Corporation, NISSIN ELECTRIC Co.,Ltd., Hilkar, Trench Group, Hitachi Energy Ltd.
About the Author(s)
Distribution & Utilities Research Team
Energy & Power · Distribution & UtilitiesThis report was authored by the distribution & utilities research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the distribution & utilities segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


