
- Home
- »
- Agrochemicals & Fertilizers
- »
-
Soil Conditioners Market Size And Share Report, 2026-2033GVR Report cover

Soil Conditioners Market (2026 - 2033)
Size, Share & Trends Analysis Report Product (Natural, Synthetic), By Solubility (Water Soluble, Hydrogels), By Soil Type (Sand, Peat, Clay, Loam), By Crop Type (Cereals & Grains, Oilseeds & Pulses), By Region, And Segment Forecasts
Market Size, 2025
$7.9BMarket Estimate, 2026
$8.5BMarket Forecast, 2033
$13.9BCAGR, 2026–2033
7.2%Soil Conditioners Market Summary
The global soil conditioners market size was valued at USD 7.9 billion in 2025 and is projected to grow from USD 8.5 billion in 2026 to USD 13.9 billion by 2033, at a CAGR of 7.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 37.8% in 2025. Market demand is supported by the shift toward sustainable and regenerative farming systems, where soil conditioners play a crucial role in enhancing soil structure, improving moisture retention, and optimizing nutrient efficiency, while also aligning with regulatory and environmental sustainability objectives.
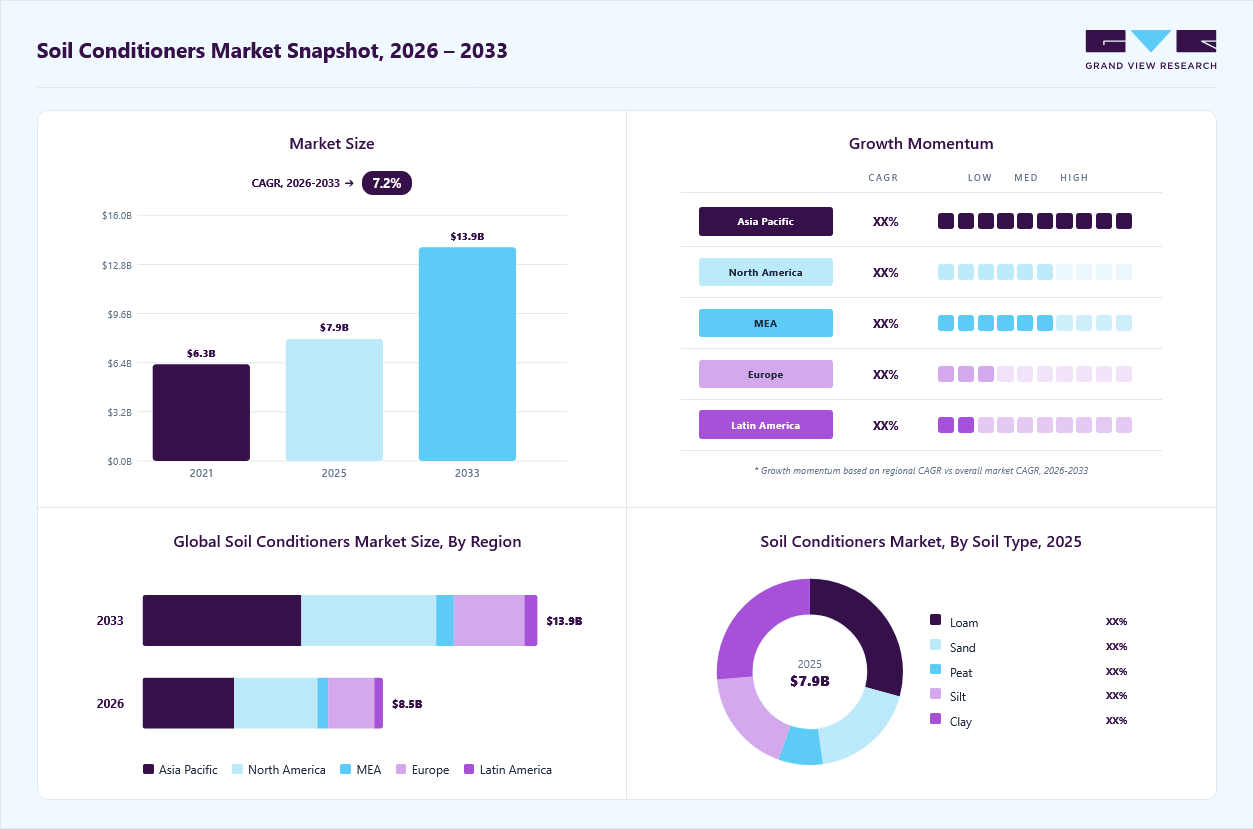 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Natural held a dominant position, contributing 64.9% of total revenue in 2025.
- By solubility: Water-soluble segment accounted for the largest revenue share of 62.0% in 2025.
- By soil type: Loam segment dominated the soil conditioners market, capturing a revenue share of 29.2% in 2025.
- By crop type: Cereals & grain segment captured the largest revenue share of 43.2% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.8% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.9 Billion
- Estimated market size in 2026: USD 8.5 Billion
- Projected market size by 2033: USD 13.9 Billion
- CAGR (2026-2033): 7.2%
Prism AI by Grand View Research Free to tryAsk a question about the soil conditioners marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
With limited availability of arable land and rising global food demand, growers are prioritizing solutions that improve yield performance and resource utilization. Soil conditioners support this need by optimizing root development, improving nutrient uptake, and enhancing water-use efficiency, making them an increasingly essential component in high-intensity and precision-driven agricultural production systems.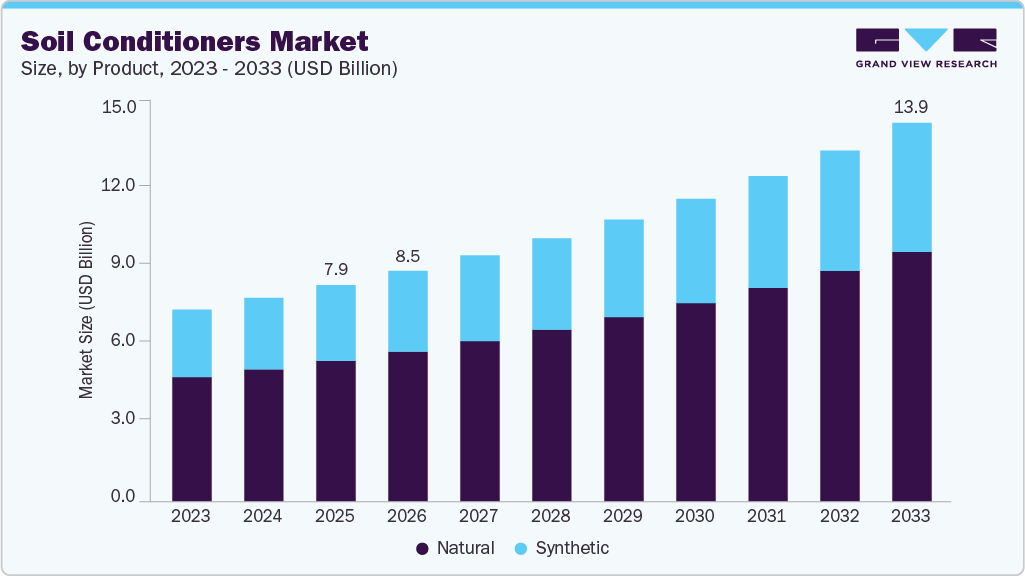 To learn more about this report, Download Free Sample Report
The growing adoption of organic farming and biologically based agricultural inputs presents a significant growth opportunity for the soil conditioners industry. Rising demand for eco-friendly solutions, coupled with increasing regulatory support for reduced chemical usage, is encouraging manufacturers to invest in microbial, humic, and bio-based soil conditioners. This shift enables companies to differentiate their portfolios, capture premium pricing, and expand penetration in high-growth regions focused on sustainable agriculture.
Market Dynamics
The soil conditioners market is driven by the growing need to improve soil fertility, enhance water retention, and increase agricultural productivity amid declining arable land quality. Rising adoption of sustainable farming practices, precision agriculture, and organic cultivation is accelerating demand for both organic and inorganic soil conditioning products. Government initiatives promoting soil health management and balanced nutrient application further support market growth. However, high product costs, limited farmer awareness in developing regions, and inconsistent adoption across small-scale farms may restrain market expansion. Increasing investments in bio-based soil amendments, regenerative agriculture, and climate-resilient farming practices are expected to create significant growth opportunities, while advancements in soil health technologies and customized conditioning solutions continue to strengthen the market's long-term outlook.
The increasing emphasis on sustainable agriculture is a key driver of the soil conditioners market. Farmers are increasingly adopting soil conditioners to improve soil structure, enhance nutrient availability, increase water retention, and restore degraded farmland. Growing concerns over declining soil fertility, intensive farming practices, and climate-related stress are encouraging the use of both organic and inorganic soil conditioning solutions to improve crop productivity and long-term land sustainability.
Government-led soil health initiatives, expanding organic farming activities, and the adoption of precision agriculture are supporting market growth. Agricultural producers are investing in soil management solutions that optimize input efficiency, improve crop resilience, and reduce environmental impact. As the focus shifts toward regenerative farming and sustainable food production, demand for advanced soil conditioners is expected to strengthen across both developed and emerging agricultural markets.
The widespread adoption of soil conditioners is constrained by the relatively high cost of advanced and specialty soil conditioning products, particularly bio-based and customized formulations. Small and medium-scale farmers, especially in price-sensitive agricultural markets, often prioritize conventional fertilizers over soil conditioners due to immediate cost considerations, limiting market penetration.
The benefits of soil conditioners are typically realized over multiple cultivation cycles rather than delivering immediate yield improvements. This longer return on investment, coupled with limited awareness of long-term soil health benefits in certain regions, discourages adoption and slows the expansion of the soil conditioners market.
The growing adoption of regenerative agriculture presents a significant opportunity for the soil conditioners market. Farmers are increasingly incorporating bio-based soil conditioners, compost-derived amendments, and microbial products to improve soil organic matter, enhance carbon sequestration, and restore long-term soil productivity. This transition toward sustainable land management is creating strong demand for environmentally friendly soil conditioning solutions.
Rising investments in biological agricultural inputs, supported by favorable government policies and sustainability commitments from the food and agriculture value chain, are accelerating product innovation. Manufacturers are developing advanced organic and microbial soil conditioners tailored to specific soil types and crop requirements, enabling higher productivity while supporting environmental conservation and resource-efficient farming practices.
Market Concentration & Characteristics
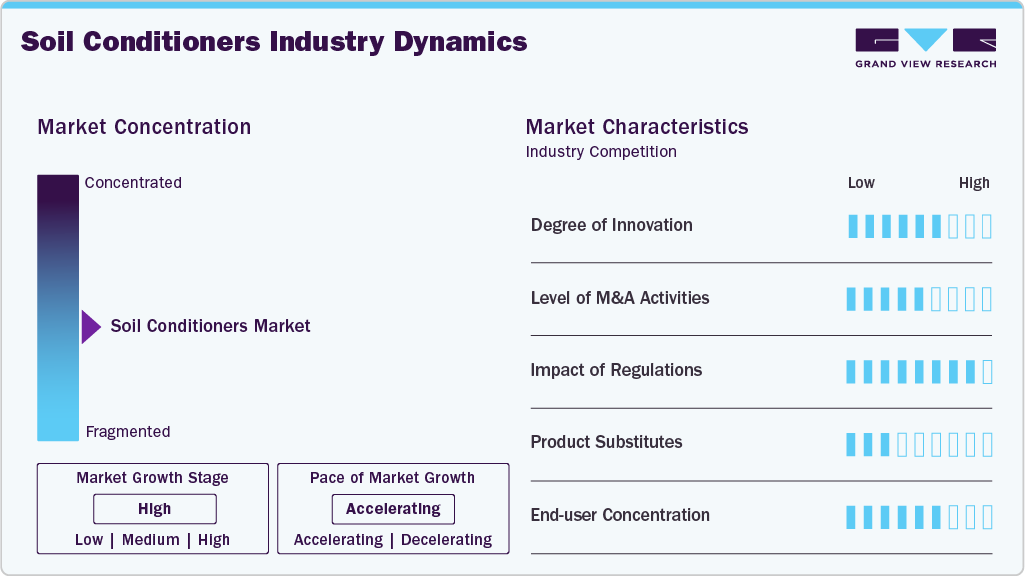
The soil conditioners industry is moderately fragmented, with global agribusiness leaders competing alongside regional and specialty manufacturers. Large players benefit from strong R&D, established brands, and wide distribution networks, while smaller companies focus on niche and organic solutions.
 To learn more about this report, Download Free Sample Report
The soil conditioners industry features a broad mix of organic, inorganic, and polymer-based products driven by soil health improvement and sustainable farming needs. Demand is influenced by crop cycles, regulatory support, and the growing adoption of precision and resource-efficient agriculture.
Analyst Perspective
The soil conditioners market is expected to witness steady growth as agricultural stakeholders increasingly prioritize soil health improvement, sustainable farming practices, and resource-efficient crop production. Established players are leveraging strong R&D capabilities and global distribution networks to introduce advanced soil amendment solutions, while emerging companies are gaining traction through cost-effective, region-specific, and customized products. Growing adoption of regenerative agriculture, organic farming, and water management solutions is likely to create new opportunities, although market expansion will depend on improving farmer awareness and addressing affordability challenges in developing regions.
Product Insights
By product, natural held a dominant position, contributing 64.9% of total revenue in 2025, due to growing adoption of sustainable and organic farming practices. Increasing awareness of soil health, regulatory support for eco-friendly inputs, and rising demand for organic food are driving the use of compost, humic substances, and bio-based conditioners that improve soil structure and fertility while minimizing environmental impact.
The synthetic segment is expected to grow at the fastest CAGR of 6.9% from 2026 to 2033, driven by the need for immediate and consistent soil performance in high-intensity farming systems. These products offer precise control over soil properties such as water retention and nutrient availability, making them highly suitable for large-scale commercial agriculture and regions facing water stress and declining soil productivity.
Solubility Insights
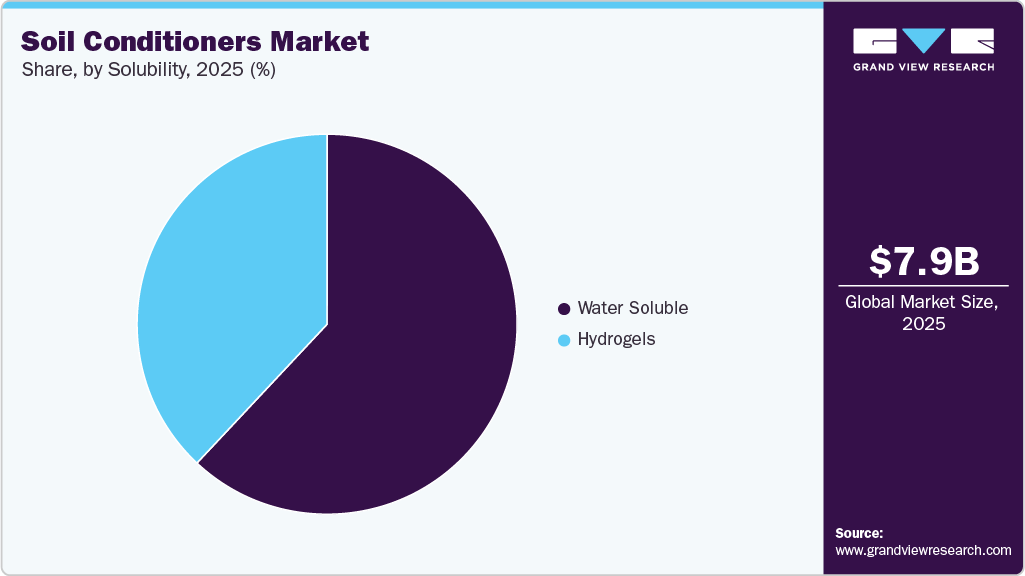
Water soluble segment accounted for the largest revenue of 62.0% in 2025, due to its ease of application and rapid effectiveness in improving nutrient availability and soil structure. These products are widely adopted in conventional and precision agriculture as they integrate seamlessly with irrigation and fertigation systems, enabling uniform distribution and immediate soil performance benefits.
 To learn more about this report, Download Free Sample Report
The hydrogels segment led the market with the largest revenue share of CAGR of 7.4% during the forecast period, driven by increasing water scarcity and the need for improved moisture management in agriculture. Their high water-retention capacity helps reduce irrigation frequency and enhances crop resilience under drought conditions, making them increasingly attractive in arid and semi-arid regions that focus on efficient water use and sustainable farming practices.
Soil Type Insights
The loam segment dominated the soil conditioners market, capturing a revenue share of 29.2% in 2025, due to its widespread use in agriculture and high suitability for diverse crops. Farmers commonly apply soil conditioners in loam soils to maintain optimal structure, enhance nutrient retention, and sustain long-term productivity, driving consistent demand across major agricultural regions.
The clay segment is anticipated to grow at the fastest CAGR of 7.6% during the forecast period, driven by the need to address poor drainage, compaction, and limited root penetration associated with heavy soils. Increasing adoption of soil conditioners to improve aeration, water movement, and workability in clay-rich soils is supporting rapid growth, particularly in intensive farming and infrastructure-driven agricultural areas.
Crop Type Insights
In 2025, the cereals & grain segment captured the largest revenue share of 43.2% in the market, due to their large cultivation area and their role as staple food crops globally. High demand for yield stability and soil fertility management in crops such as wheat, rice, and maize drives consistent use of soil conditioners to enhance nutrient efficiency and maintain soil productivity.
The oilseeds & pulses segment is anticipated to grow at the fastest CAGR of 9.2% during the forecast period, supported by rising global demand for edible oils and plant-based protein. Increased focus on improving soil health, nitrogen efficiency, and root development in crops such as soybean, sunflower, and pulses is accelerating the adoption of soil conditioners in this segment.
Regional Insights
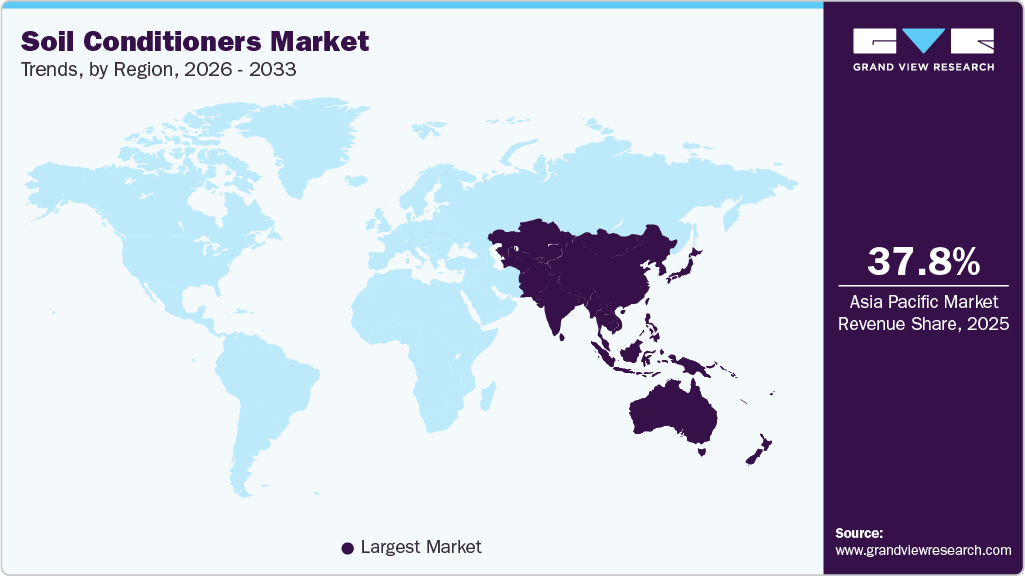
Asia Pacific dominated the soil conditioners market with the highest revenue share of 37.8% in 2025 and is projected to grow at the fastest CAGR during the forecast period, supported by rapid agricultural intensification and declining soil quality, prompting increased use of soil conditioners to improve yield performance and soil resilience in high-cropping-frequency farming systems.
 To learn more about this report, Download Free Sample Report
China Soil Conditioners Market Trends
China dominated the Asia Pacific soil conditioners market in 2025. China’s market growth is driven by government-led initiatives focused on soil remediation and sustainable farming practices to restore degraded farmland and improve agricultural efficiency.
North America Soil Conditioners Market Trends
The soil conditioners market in North America held second-largest revenue share of 34.7% in 2025, driven by the widespread adoption of precision agriculture and advanced farm input technologies, where soil conditioners are used to enhance input efficiency, manage soil variability, and support high-value crop production across large-scale commercial farms.
The soil conditioners market in the U.S. is driven by large-scale mechanized farming and high adoption of soil health management practices, where soil conditioners are increasingly used to optimize yields, improve soil structure, and support long-term farm productivity.
Europe Soil Conditioners Market Trends
The soil conditioners market in Europe is driven by strict environmental regulations and strong policy support for sustainable agriculture, encouraging the adoption of soil conditioners that improve soil health while reducing chemical fertilizer dependence.
The Germany soil conditioners market is anticipated to grow at a significant CAGR during the forecast period. The demand is driven by advanced agronomic practices and strong emphasis on environmentally responsible farming, supporting the use of soil conditioners that align with sustainable and organic agriculture standards.
Latin America Soil Conditioners Market Trends
The soil conditioners market in Latin America is driven by expansion of commercial agriculture and export-oriented crop production, particularly in oilseeds and cereals, increasing the need for soil conditioners to maintain long-term soil productivity.
Middle East & Africa Soil Conditioners Market Trends
The soil conditioners market in Middle East & Africa is growing rapidly. Rising water scarcity and poor soil conditions are key drivers in the Middle East & Africa, boosting demand for soil conditioners that enhance water retention and improve crop performance in arid and semi-arid environments.
Key Soil Conditioners Company Insights
Key players, such as BASF SE, Syngenta AG, Novozymes A/S, Eastman Chemical Company, Aquatrols Corporation of America, Solvay S.A., Rallis India Limited, GreenBest Ltd., and Grow More Inc., are dominating the market.
-
BASF leverages its global chemical expertise to provide advanced soil conditioner solutions that enhance soil structure, water retention, and nutrient efficiency. The company focuses on innovative formulations, including humic and polymer-based conditioners, catering to both conventional and sustainable agriculture, strengthening its position as a market leader in improving soil health and crop productivity worldwide.
-
Syngenta integrates crop protection with soil health strategies, offering a range of biological and chemical soil conditioners that optimize soil fertility and plant growth. Its solutions emphasize sustainable agriculture and precision farming, supporting farmers in enhancing yield, soil resilience, and long‑term land productivity, reinforcing Syngenta’s role as a key player in the soil conditioners industry.
Key Soil Conditioners Companies
The following key companies have been profiled for this study on the soil conditioners market.
-
BASF SE
-
Syngenta AG
-
Novozymes A/S
-
Eastman Chemical Company
-
Aquatrols Corporation of America
-
Solvay S.A.
-
Rallis India Limited
-
GreenBest Ltd.
-
Grow More Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, Syngenta AG, Novozymes A/S, Eastman Chemical Company, Solvay S.A.)
- Focus on product portfolio expansion, strategic partnerships, R&D investments, and development of advanced soil health solutions, including biological amendments, water management products, and sustainable agricultural inputs. These companies leverage global distribution networks and collaborations with agricultural stakeholders to strengthen market presence.
- Strong brand recognition, extensive geographic reach, established farmer networks, advanced R&D capabilities, and diversified product portfolios across agriculture and specialty chemicals enable these players to serve large-scale farming operations.
- Higher product pricing compared with regional suppliers, complex organizational structures, and slower customization of products for specific local soil conditions may limit penetration in price-sensitive markets.
Emerging Players (Aquatrols Corporation of America, Rallis India Limited, GreenBest Ltd., Grow More Inc.)
- Concentrate on niche product development, regional market expansion, cost-effective formulations, and customized soil conditioning solutions. These companies primarily target specific agricultural segments by offering specialized products addressing soil moisture management, organic farming, and crop productivity improvement.
- Greater flexibility in product customization, strong regional market understanding, competitive pricing, and faster response to local farmer requirements provide an advantage in emerging agricultural markets.
- Limited global distribution networks, lower brand visibility, comparatively smaller R&D investments, and dependence on regional markets can restrict large-scale expansion and competitive positioning.
Recent Developments
-
In 2024, UPL Corp has unveiled NIMAXXA, a new triple‑strain bionematicide seed treatment registered by the U.S. EPA that offers season‑long protection for soybeans (and corn) against major nematodes including soybean cyst, root‑knot, and reniform nematodes by combining three biological strains that attack nematode eggs and juveniles, form a protective zone around roots, and stimulate root growth to enhance crop resilience for the 2025 season.
Soil Conditioners Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.9 billion
Estimated market size in 2026
USD 8.5 billion
Projected market size by 2033
USD 13.9 billion
Growth rate
CAGR of 7.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Volume, Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, solubility, soil type, crop type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; China; India; Japan; Saudi Arabia; Brazil; Argentina
Key companies profiled
BASF SE; Syngenta AG; Novozymes A/S; Eastman Chemical Company; Aquatrols Corporation of America; Solvay S.A.; Rallis India Limited; GreenBest Ltd.; Grow More Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Soil Conditioners Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global soil conditioners market report based on product, solubility, soil type, crop type and region:
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Natural
-
Polysaccharides Derivatives
-
Others
-
Compost
-
Sewage Sludge
-
Animal Manure
-
-
-
Synthetic
-
Polymers
-
Minerals
-
Gypsum
-
-
-
Solubility Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Water Soluble
-
Hydrogels
-
-
Soil Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Loam
-
Sand
-
Peat
-
Silt
-
Clay
-
-
Crop Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Cereals & Grains
-
Oilseeds & Pulses
-
Fruits & Vegetables
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Middle East & Africa
-
Saudi Arabia
-
Latin America
-
Brazil
-
Argentina
-
-
Research Methodology
The soil conditioners market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each soil conditioners segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Product
Revenue capture definition
Natural
Revenue generated from the sale of naturally derived soil conditioners, including compost, manure, biochar, peat, gypsum, humic substances, and other organic amendments used to improve soil fertility, structure, moisture retention, and microbial activity.
Synthetic
Revenue generated from the sale of chemically formulated soil conditioners, including synthetic polymers, mineral-based conditioners, and engineered products designed to enhance soil structure, water retention, aeration, and nutrient availability.
Segment – Solubility
Revenue capture definition
Water Soluble
Revenue generated from water-soluble soil conditioners that dissolve or disperse in water for application through irrigation systems, fertigation, or direct soil treatment to improve nutrient uptake and soil performance.
Hydrogels
Revenue generated from hydrogel-based soil conditioners that absorb and retain large volumes of water, improving soil moisture availability, reducing irrigation frequency, and enhancing crop performance under water-stressed conditions.
Segment – Soil Type
Revenue capture definition
Loam
Revenue generated from soil conditioners formulated or marketed for loam soils to enhance soil fertility, maintain optimal structure, and improve moisture and nutrient management.
Sand
Revenue generated from soil conditioners used in sandy soils to increase water-holding capacity, reduce nutrient leaching, and improve overall soil productivity.
Peat
Revenue generated from soil conditioners applied to peat soils to optimize soil pH, improve nutrient balance, and support sustainable crop production.
Silt
Revenue generated from soil conditioners designed for silt soils to improve aggregation, drainage, aeration, and resistance to compaction.
Clay
Revenue generated from soil conditioners used in clay soils to improve soil structure, reduce compaction, enhance drainage, and facilitate root development.
Segment – Crop Type
Revenue capture definition
Cereals & Grains
Revenue generated from soil conditioners used in the cultivation of cereals and grains, including wheat, rice, maize, barley, oats, sorghum, and similar field crops.
Oilseeds & Pulses
Revenue generated from soil conditioners used in the cultivation of oilseed and pulse crops, including soybean, canola, sunflower, groundnut, chickpea, lentil, pea, and other leguminous crops.
Fruit & Vegetables
Revenue generated from soil conditioners applied in fruit and vegetable cultivation to improve soil quality, nutrient availability, water retention, and crop yield and quality.
Others
Revenue generated from soil conditioners used across other agricultural and horticultural applications, including plantation crops, turf and landscaping, floriculture, forage crops, and specialty crops.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Parent Market Identification
What is the size of the global agricultural inputs and soil health management market?
Identify the broader market encompassing soil conditioners and assess its historical and forecast growth to establish the market boundary.
02
Product Segmentation
How is revenue distributed across natural and synthetic soil conditioners?
Segment the market by product type based on commercial adoption, product availability, pricing, and application across agricultural sectors.
03
Solubility Analysis
What is the revenue contribution of water-soluble and hydrogel soil conditioners?
Evaluate demand by formulation type considering irrigation practices, moisture management requirements, and product performance characteristics.
04
Company Revenue Mapping
Which manufacturers generate revenue from soil conditioner products?
Analyze revenues of leading manufacturers based on product portfolios, geographic presence, production capacity, and sales mix attributable to soil conditioners.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
The relationship between soil conditioner type, solubility characteristics, soil type, and crop application was assessed to understand product adoption across different agricultural conditions. The analysis examined the suitability of water-soluble conditioners, hydrogels, organic amendments, and mineral-based products across loam, sandy, peat, silt, and clay soils, along with their usage across cereals & grains, oilseeds & pulses, fruits & vegetables, and other crops.
Enables identification of high-potential product-application combinations and specific agricultural requirements. Supports product development strategies, targeted marketing approaches, and optimization of soil conditioner portfolios.
Competitive Benchmarking
Key soil conditioner manufacturers were benchmarked based on product portfolio, organic and synthetic solution capabilities, raw material sourcing, application expertise, distribution networks, sustainability initiatives, and presence across agricultural regions. Competitive strategies related to bio-based formulations, water retention technologies, and soil health solutions were also evaluated.
Helps identify competitive advantages, innovation capabilities, and market positioning gaps. Facilitates strategic differentiation, partnership evaluation, and development of customer-focused soil improvement solutions.
Opportunity Assessment
Emerging opportunities in sustainable agriculture, regenerative farming practices, water-efficient crop production, and organic soil improvement solutions were assessed. The analysis examined increasing adoption of bio-based conditioners, moisture retention technologies, and soil restoration products driven by declining soil quality and changing agricultural requirements.
Enables identification of high-growth application areas and future investment opportunities. Supports innovation planning, sustainable product development, and long-term growth strategies within the agricultural inputs sector.
Frequently Asked Questions About This Report
Market demand is supported by the shift toward sustainable and regenerative farming systems, where soil conditioners play a critical role in improving soil structure, moisture retention, and nutrient efficiency, while also aligning with regulatory and environmental sustainability objectives.
Asia Pacific dominated with a 37.8% revenue share in 2025.
Natural segment led with a 64.9% revenue share in 2025, while synthetic is the fastest-growing segment.
Water soluble segment led with a 62.0% revenue share in 2025.
Loam segment led with a 29.2% revenue share in 2025, while clay is the fastest-growing area.
Cereals & grain segment led with a 43.2% revenue share in 2025.
The global soil conditioners market size was valued at USD 8.0 billion in 2025 and is estimated at USD 8.5 billion for 2026.
The global soil conditioners market is expected to grow at a CAGR of 7.2% from 2026 to 2033, reaching USD 13.9 billion by 2033.
Key players include BASF SE, Syngenta AG, Novozymes A/S, Eastman Chemical Company, Aquatrols Corporation of America, Solvay S.A., Rallis India Limited, GreenBest Ltd., Grow More Inc., are dominating the market.
About the Author(s)
Agrochemicals & Fertilizers Research Team
Bulk Chemicals · Agrochemicals & FertilizersThis report was authored by the agrochemicals & fertilizers research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the agrochemicals & fertilizers segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


