
- Home
- »
- Pharmaceuticals
- »
-
Stomach Cancer Treatment Market Size Report, 2025-2030GVR Report cover

Stomach Cancer Treatment Market (2025 - 2030) Size, Share & Trends Analysis Report By Treatment Type (Standard Chemotherapy), By Disease Indication, By Route Of Administration, By Drug Class, By Region, And Segment Forecasts
Market Size, 2024
$5.4BMarket Estimate, 2026
$7.3BMarket Forecast, 2030
$11.2BCAGR, 2025–2030
12.5%Stomach Cancer Treatment Market Summary
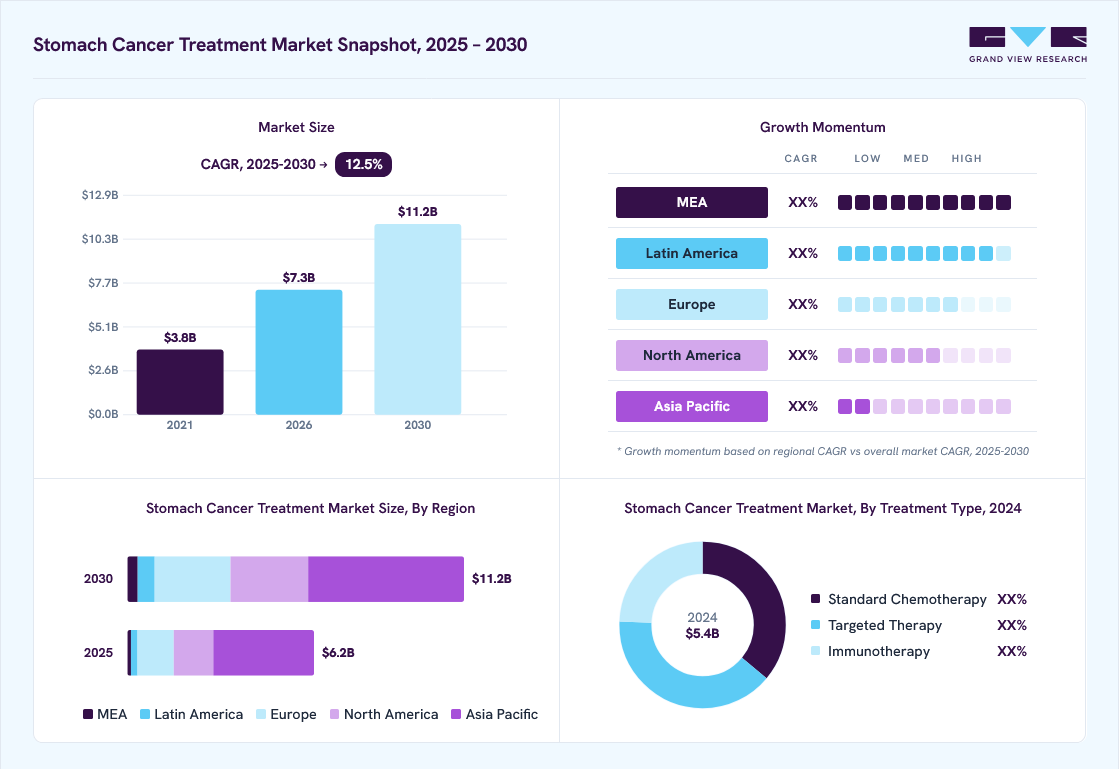
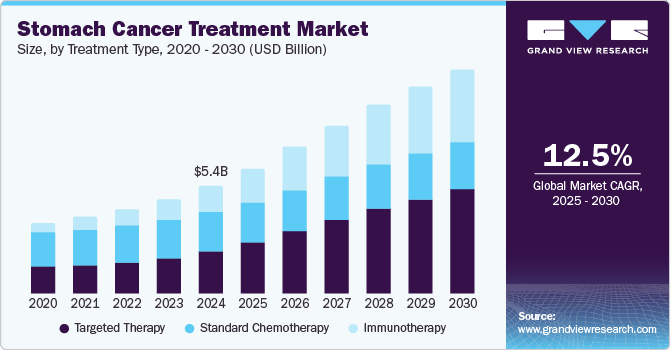
The global stomach cancer treatment market size was valued at USD 5.4 billion in 2024 and is projected to grow from USD 7.3 billion in 2026 to USD 11.2 billion by 2030, at a CAGR of 12.5% from 2025 to 2030. Asia Pacific dominated the market, accounting for a revenue share of 55.6% in 2024. The World Cancer Research Fund estimated the incidence of over 1.1 million new cases in 2023, showing an alarming rise in the incidence of stomach cancer worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- The stomach cancer treatment market in China dominated the Asia Pacific stomach cancer treatment market with a revenue share of 27.1% in 2024.
- By treatment type, targeted therapy segment dominated the market and accounted for a share of 39.6% in 2024..
- By disease indication,gastric cancer/gastroesophageal junction segment led the market with a revenue share of 84.7% in 2024.
Market Size & Forecast
- 2024 Market Size: USD 5.4 Billion
- 2030 Projected Market Size: USD 11.2 Billion
- CAGR (2025-2030): 12.5%
- Asia Pacific: Largest market in 2024
Prism AI by Grand View Research Free to tryAsk a question about the stomach cancer treatment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →With gastric cancer ranked as the fifth most common cancer worldwide, the regional disparities, particularly in high-incidence areas such as Mongolia and China, indicate a critical need for targeted treatment solutions. The correlation between lifestyle factors, healthcare access, and rising diagnosis rates further amplifies the urgency for market expansion in this sector.
 To learn more about this report, Download Free Sample Report
Advancements in treatment modalities are central to improving patient outcomes and positioning the market for rapid evolution. The introduction of immunotherapies and targeted therapies, exemplified by agents such as Opdivo (nivolumab) and Keytruda (pembrolizumab), has transformed the therapeutic landscape for advanced gastric cancer. These advancements reflect a growing recognition of gastric cancer as a complex disease that necessitates personalized treatment strategies. As treatments become increasingly sophisticated and aligned with the biological profiles of tumors, the market is expected to attract investment and demand.
Investment in research and development (R&D) is instrumental in driving innovation within the stomach cancer treatment landscape. Pharmaceutical companies are dedicating resources to unravel the molecular mechanisms underlying gastric cancer, with early 2024 witnessing numerous clinical trials exploring the effectiveness of combination therapies. This focus on novel therapeutic approaches enhances the treatment arsenal available to healthcare providers and positions companies favorably within an evolving regulatory environment, which is incentivizing rapid therapeutic approvals.
Demographic trends further bolster the market’s expansion prospects, particularly as the geriatric population continues to grow. With the median age at diagnosis hovering around 70 years, the aging population is a significant contributing factor to the increasing prevalence of stomach cancer. Regulatory bodies responding with expedited reviews for new therapies are critical for ensuring patients can access innovative treatment options swiftly. As support policies and healthcare strategies evolve, addressing regional disparities and enhancing early detection capabilities will be vital in aligning market offerings with the urgent needs of diverse patient populations.
Treatment Type Insights
Targeted therapy dominated the market and accounted for a share of 39.6% in 2024. Targeted therapy offers precision targeting cancer cells while minimizing harm to adjacent healthy tissues. This specific approach enhances treatment effectiveness and reduces associated side effects. Furthermore, the rise of personalized medicine and the introduction and approval of novel targeted agents have further galvanized interest and adoption among healthcare professionals and patients.
Immunotherapy is expected to grow at the fastest CAGR of 17.0% over the forecast period, owing to its innovative mechanism, which amplifies the body’s immune response toward cancer cells. PD-1/PD-L1 inhibitors, in particular, have demonstrated remarkable clinical trial outcomes, correlating with improved survival rates in patients with advanced stomach cancer. The increasing acknowledgment of immunotherapy as a standard treatment underscores its effectiveness and potential for sustained management of gastric cancer.
Disease Indication Insights
Gastric cancer/gastroesophageal junction led the market with a revenue share of 84.7% in 2024, fueled by its considerable prevalence and associated mortality rates worldwide. There is an urgent requirement for effective therapies. The intricacies of these cancers, often diagnosed at advanced stages, elevate the focus on advanced treatment options and targeted therapies within clinical practices.
Gastrointestinal stromal tumors are expected to register significant growth over the forecast period. Gastrointestinal stromal tumors (GISTs) have distinct biological properties and responsiveness to targeted therapies such as imatinib. Growing recognition of GISTs and available treatment modalities has led to more effective diagnoses and interventions. Their unique nature demands specialized therapeutic strategies, emphasizing their significance within the stomach cancer treatment spectrum.
Drug Class Insights
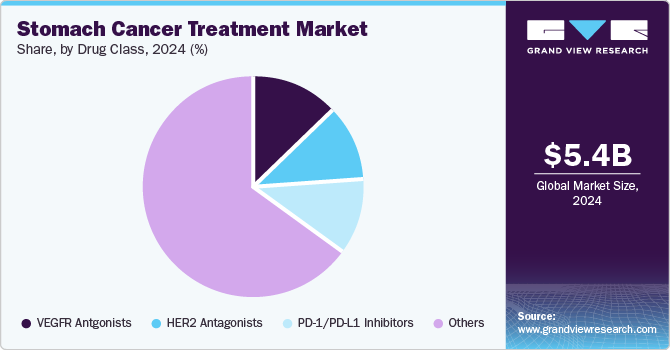
VEGFR antagonists held a substantial share in 2024 due to their critical role in inhibiting tumor angiogenesis, a vital process for tumor growth and metastasis. These agents have shown significant effectiveness in clinical settings for advanced gastric cancer, leading to improved patient outcomes. Ongoing research into combination therapies featuring VEGFR antagonists further solidifies their prominence in contemporary treatment regimens for stomach cancer.
 To learn more about this report, Download Free Sample Report
PD-1/PD-L1 inhibitors are projected to grow at the fastest CAGR of 19.9% over the forecast period, supported by their capacity to enhance the immune response against cancer cells. Clinical evidence highlighting their efficacy in advanced gastric cancer has facilitated their widespread adoption among oncologists. Promising results from ongoing trials continue to stimulate interest, establishing these inhibitors as fundamental components of modern immunotherapeutic approaches in managing stomach cancer.
Route of Administration Insights
Injectable treatment held the largest revenue share of 89.0% in 2024, aided by their rapid therapeutic action and effectiveness in administering chemotherapy and targeted therapies directly into the bloodstream. This delivery method is advantageous for patients who struggle with oral medications or require an immediate therapeutic response. The practicality and efficacy of injectable formulations position them as a favored option among healthcare providers for managing stomach cancer.
Oral treatment is expected to grow at the fastest rate of 18.8% over the forecast period. Oral medications allow for treatment at home, reducing the necessity for hospital visits and facilitating better patient adherence. The introduction of new oral therapies with favorable safety profiles further enhances accessibility, particularly for those with advanced stomach cancer preferring less invasive treatments.
Regional Insights
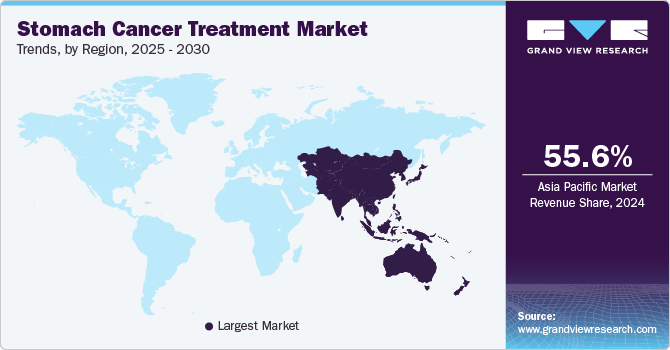
Asia Pacific stomach cancer treatment market dominated the global market with a revenue share of 55.6% in 2024. Countries such as China and Japan report some of the highest global gastric cancer cases. Growing awareness around gastric cancer and advancements in healthcare access are driving demand for effective treatment solutions, positioning this region as a key focal point for market growth.
 To learn more about this report, Download Free Sample Report
China Stomach Cancer Treatment Market Trends
The stomach cancer treatment market in China dominated the Asia Pacific stomach cancer treatment market with a revenue share of 27.1% in 2024. Alarming incidence rates of stomach cancer, with approximately 478,000 new cases reported annually, act as primary market drivers in the country. The country’s healthcare reforms have improved access to advanced treatments, including targeted therapies and immunotherapy. Furthermore, increased investments in cancer research and ongoing clinical trials are expanding treatment options for patients.
North America Stomach Cancer Treatment Market Trends
North America stomach cancer treatment market is expected to register significant growth over the forecast period. North America houses advanced healthcare infrastructure and rapid adoption of innovative therapies. The region hosts numerous clinical trials and research initiatives, leading to swifter drug approvals. Moreover, heightened awareness of stomach cancer, coupled with an anticipated 26,500 new cases in 2023, drives the demand for effective treatment options.
The stomach cancer treatment market in the U.S. dominated the North America market with a revenue share of 90.5% in 2024. The country’s strong pharmaceutical sector and significant investments in research and development. The availability of advanced therapies, including immunotherapy and targeted treatments, contributes to improved patient outcomes. With an estimated 27,510 new stomach cancer cases projected for 2023 by the American Cancer Society, there exists a critical need for effective treatment options in the country.
Europe Stomach Cancer Treatment Market Trends
Europe stomach cancer treatment market held substantial market share in 2024 due to rising incidence rates and a strong focus on early detection and innovative therapies. The region enjoys comprehensive healthcare coverage and access to advanced treatment modalities. Furthermore, collaborative research efforts and ongoing clinical trials are facilitating the development of new treatments, positioning Europe as a vital player in effectively addressing stomach cancer.
Middle East & Africa Stomach Cancer Treatment Market Trends
Middle East & Africa stomach cancer treatment market is expected to register the fastest CAGR of 23.2% in the forecast period. As awareness of gastric cancer rises and healthcare infrastructure improves, the region is experiencing heightened demand for stomach cancer treatment alternatives. Increasing lifestyle-related risk factors have increased incidence rates, necessitating effective treatment solutions. Moreover, international collaborations and investments from pharmaceutical companies are enhancing access to innovative therapies, thereby improving overall patient care in this diverse region.
Key Stomach Cancer Treatment Company Insights
Some key companies operating in the market include Novartis AG; Pfizer Inc.; Mylan N.V.; F. Hoffmann-La Roche Ltd; among others. The market features substantial investments in research and development, fostering innovative therapies. Key players prioritize strategic collaborations, portfolio expansion, and the approval of novel treatments, enhancing competition and market dynamics.
-
Pfizer Inc. actively engages in the stomach cancer treatment sector through the development of immunotherapies and targeted therapies. In collaboration with Merck KGaA, the company has initiated Phase III clinical trials for avelumab, which targets advanced gastric and gastroesophageal junction cancers.
-
F. Hoffmann-La Roche Ltd (Roche) significantly contributes to stomach cancer treatment with targeted therapies such as Herceptin (trastuzumab) for HER2-positive gastric cancer and conducts clinical trials to assess immunotherapy efficacy alongside chemotherapy for advanced gastric cancers.
Key Stomach Cancer Treatment Companies:
The following are the leading companies in the stomach cancer treatment market. These companies collectively hold the largest market share and dictate industry trends.
- Novartis AG
- Pfizer Inc.
- Mylan N.V.
- F. Hoffmann-La Roche Ltd
- Eli Lilly and Company
- Merck & Co., Inc.
- Teva Pharmaceutical Industries Ltd.
- CELLTRION INC.
- Samsung Bioepis
- Bristol-Myers Squibb Company
Recent Developments
-
In October 2024, Roche obtained FDA approval for the VENTANA CLDN18 (43-14A) RxDx Assay, the inaugural companion diagnostic for identifying gastric and GEJ cancer patients eligible for Astellas’ VYLOY therapy.
-
In May 2024, Merck announced that the Phase 3 KEYNOTE-811 trial met its dual primary endpoint of overall survival for KEYTRUDA combined with trastuzumab and chemotherapy in HER2-positive gastric or GEJ adenocarcinoma.
-
In January 2024, Novartis announced that Lutathera significantly reduced disease progression or death risk by 72% in advanced gastroenteropancreatic neuroendocrine tumors, highlighting the effectiveness of radioligand therapy as first-line treatment.
Stomach Cancer Treatment Market Report Scope
Report Attribute
Details
Market size in 2024
USD 5.4 billion
Estimated market size in 2026
USD 7.3 billion
Projected market size by 2030
USD 11.2 billion
Growth rate
CAGR of 12.5% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2025 - 2030
Quantitative units
Revenue in USD million/billion and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Treatment type, disease indication, route of administration, drug class, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Novartis AG; Pfizer Inc.; Mylan N.V.; F. Hoffmann-La Roche Ltd; Eli Lilly and Company; Merck & Co., Inc.; Teva Pharmaceutical Industries Ltd.; CELLTRION INC.; Samsung Bioepis; Bristol-Myers Squibb Company
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Stomach Cancer Treatment Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global stomach cancer treatment market report based on treatment type, disease indication, route of administration, drug class, and region:
-
Treatment Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Standard Chemotherapy
-
Targeted Therapy
-
Immunotherapy
-
-
Disease Indication Outlook (Revenue, USD Million, 2018 - 2030)
-
Gastric Cancer/Gastroesophageal Junction cancer
-
Gastrointestinal Stromal Tumors
-
-
Route of Administration Outlook (Revenue, USD Million, 2018 - 2030)
-
Oral
-
Injectable
-
-
Drug Class Outlook (Revenue, USD Million, 2018 - 2030)
-
PD-1/PD-L1 Inhibitors
-
HER2 Antagonists
-
VEGFR Antgonists
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global stomach cancer treatment market size was valued at USD 5.4 billion in 2024 and is estimated at USD 7.3 billion for 2026.
Based on disease indication, the gastric cancer & gastroesophageal junction cancer segment held the largest share of 85.47% in 2021 owing to high prevalence of the disease.
Some key players operating in the stomach cancer treatment market include Novartis AG; Pfizer, Inc.; Mylan N.V.; F. Hoffmann La Roche Ltd.; Eli Lilly and Company; Merck & Co., Inc.; Teva Pharmaceutical Industries Ltd.; Celltrion Inc.; Samsung Bioepis; and Bristol Myers Squibb Company.
The major factors driving the market growth are the rising incidence of stomach cancer and the launch & adoption of targeted and immunotherapy drugs for the treatment of stomach cancer.
The global stomach cancer treatment market is expected to grow at a CAGR of 12.5% from 2025 to 2030, reaching USD 11.2 billion by 2030.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


