
- Home
- »
- Medical Devices
- »
-
Surgical Helmet Market Size And Share Report, 2026-2033GVR Report cover

Surgical Helmet Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Surgical Helmet, Accessories, Disposable Consumables), By End Use (Hospitals, Ambulatory Surgical Centers, Specialty Clinics), By Distribution Channel (Online, Offline) By Region, And Forecasts
Market Size, 2025
$549.7MMarket Estimate, 2026
$589.0MMarket Forecast, 2033
$967.8MCAGR, 2026–2033
7.4%Surgical Helmet Market Summary
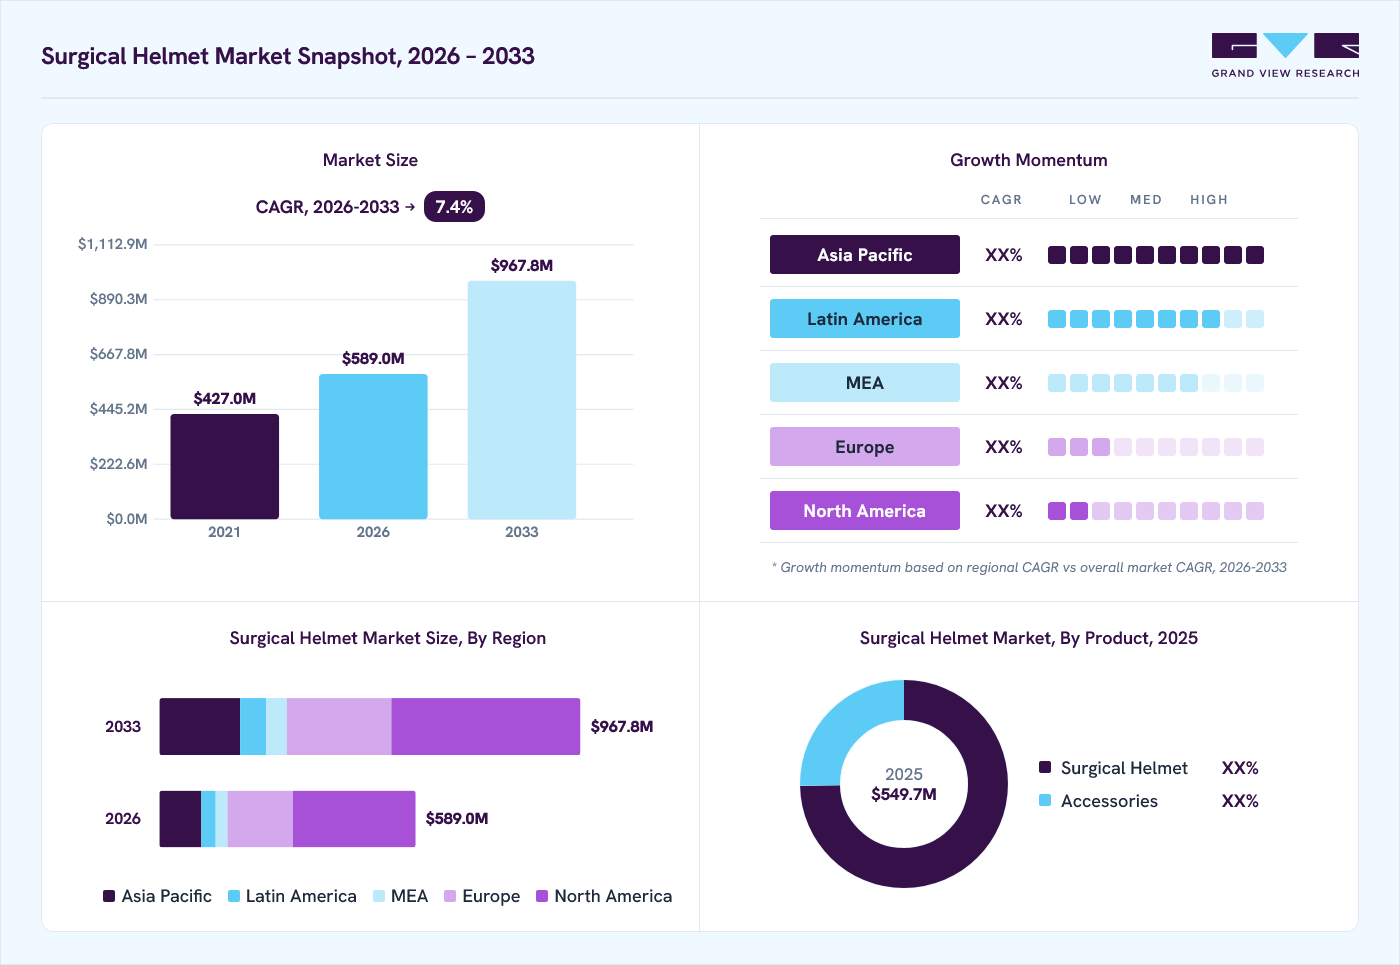
The global surgical helmet market size was valued at USD 549.7 million in 2025 and is projected to grow from USD 589.0 million in 2026 to USD 967.8 million by 2033, at a CAGR of 7.4% from 2026 to 2033. North America dominated the market with the largest revenue share of 48.2% in 2025. The growing focus on operating room safety, infection prevention, and the protection of healthcare professionals during surgical procedures is driving the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Disposable consumables segment led the market with the largest revenue share in 2025.
- By end use: Hospitals segment led the market with the largest revenue share in 2025.
- By distribution channel: Offline segment led the market with the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (48.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 549.7 Million
- Estimated market size in 2026: USD 589.0 Million
- Projected market size by 2033: USD 967.8 Million
- CAGR (2026-2033): 7.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rising surgical volumes, particularly in orthopedics, trauma, and other complex procedures requiring prolonged operating times, are prompting hospitals and surgical centers to adopt advanced protective solutions to reduce the risk of contamination and improve surgeon comfort. Growing awareness of surgical site infections and the need to maintain sterile surgical environments are further supporting the adoption of powered air ventilation and helmet-based protection systems. Technological advancements, including lightweight designs, improved airflow systems, enhanced visibility, anti-fog features, and ergonomic improvements, are contributing to greater acceptance among surgeons. To learn more about this report, Download Free Sample Report
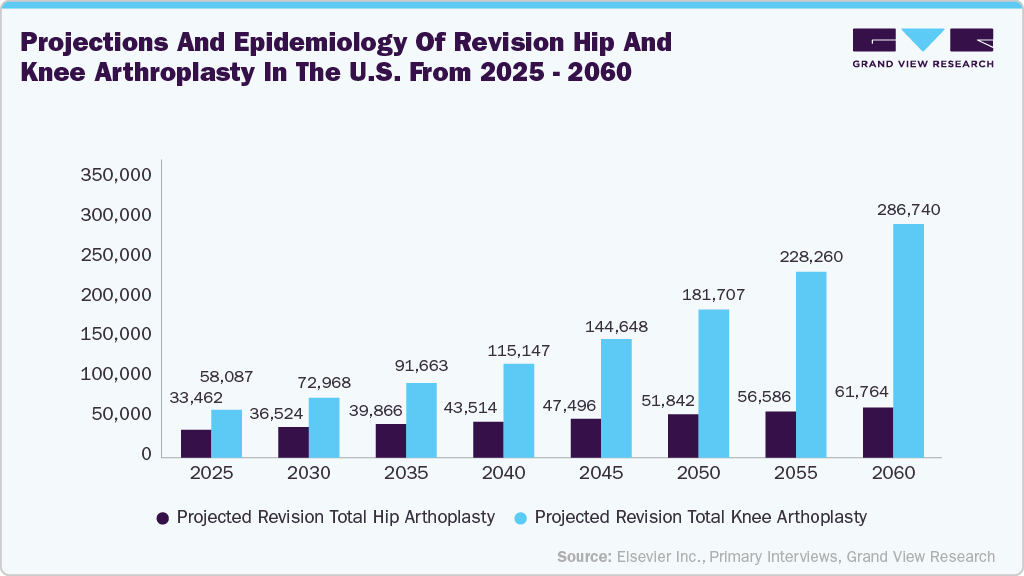
The rising number of orthopedic surgeries is a key market driver. Orthopedic procedures, including total knee replacements, hip replacements, spinal surgeries, fracture fixation, and trauma reconstruction, are among the most frequently performed operations and require extended operating times under highly sterile conditions. These procedures involve the use of power tools, such as drills, saws, and reamers, which can generate bone particles, tissue debris, and fluid splashes in the operating room. As the volume of orthopedic surgeries continues to increase globally, hospitals and surgical centers are placing greater emphasis on protecting surgeons and operating room personnel through advanced surgical helmet systems. These helmets provide continuous airflow, improve surgeon comfort during lengthy procedures, and support adherence to operating room safety protocols. The increasing demand for orthopedic interventions, driven by a higher incidence of fractures, sports injuries, degenerative joint conditions, and trauma cases, is leading healthcare facilities to invest in specialized surgical protective equipment.
 To learn more about this report, Download Free Sample Report
The growing focus on preventing surgical site infections (SSIs) and other hospital-acquired infections (HAIs) is a major market driver. Healthcare providers are placing greater emphasis on infection-control measures to improve patient outcomes, reduce postoperative complications, and lower the costs associated with prolonged hospital stays and revision surgeries. During surgical procedures, operating room personnel can contribute to contamination by shedding skin particles, hair, and microorganisms into the sterile field. Surgical helmet systems, when used with compatible sterile hoods, provide an additional protective barrier, improve surgeon comfort during lengthy procedures, and support established infection-control protocols.
As hospitals continue to strengthen sterile operating room practices, particularly for complex and implant-based procedures, the adoption of advanced protective equipment has increased. The growing implementation of infection prevention programs, stricter hospital safety standards, and ongoing investments in operating room safety are encouraging healthcare facilities to incorporate surgical helmet systems into routine surgical practice. For instance, in November 2024, a WHO report on infection prevention and control highlighted the need for sustained investment in these programs. IPC guidelines emphasize standard precautions to prevent the transmission of diseases in healthcare settings. Thus, these guidelines and the rising focus on infection control and prevention are anticipated to drive demand for surgical helmets.
“WHO is committed to supporting countries to ensure that by 2030, everyone accessing and providing health care is safe from HAIs. Fulfilling all IPC minimum requirements at the national and healthcare-facility levels should be a priority for all countries, to protect patients and health-care workers, and prevent unnecessary suffering,” said Dr. Bruce Aylward, WHO Assistant Director-General, Universal Health Coverage, Life Course.
Market Dynamics
Increasing numbers of orthopedic, trauma, and other long-duration surgeries are creating demand for advanced protective systems that help maintain sterile conditions and improve surgeon comfort. The rising focus on reducing surgical site infections and hospital-acquired infections is encouraging healthcare facilities to adopt enhanced personal protective equipment, including helmet systems with integrated airflow and protective barriers. Technological advancements such as lightweight designs, improved ventilation, better ergonomics, and enhanced visibility are further supporting market adoption by addressing the challenges associated with prolonged use of conventional protective equipment.
The rising prevalence of trauma and sports-related injuries requiring surgical intervention is a significant market driver. Increasing participation in recreational and professional sports, higher rates of road traffic accidents, workplace injuries, and an aging yet physically active population have contributed to a growing volume of orthopedic trauma procedures, including fracture fixation, ligament reconstruction, joint repair, and complex reconstructive surgeries. These procedures involve prolonged operative times and the use of power instruments that generate aerosols of blood, bone, and tissue, increasing the risk of contamination in the operating room. Thus, surgeons and operating room personnel are adopting surgical helmet systems with integrated ventilation and face protection to maintain a sterile environment and reduce exposure to airborne particles and bodily fluids. Trauma surgeries are frequently performed under emergency conditions, where maintaining high standards of infection prevention and personal protection is critical.
For instance, data published by AIWH 2026, the reported number of sports injury hospitalizations was compared against the estimated number of participants aged 15 and over from AusPlay (ASC 2025). In 2024-25, rugby (which includes both rugby league and rugby union) had the highest rate of sports injury hospitalization based on participation rate (nearly 1,500 hospitalizations per 100,000 participants), followed by wheeled motor sports (about 1,100 hospitalizations per 100,000 participants) and Australian rules football (just under 750 hospitalizations per 100,000 participants).
Limited adoption in small and budget-constrained hospitals is a significant restraint on market growth. Powered surgical helmet systems require substantial upfront investment and recurring expenditures for disposable hoods, face shields, batteries, filters, and routine maintenance. For smaller hospitals, community healthcare facilities, and rural surgical centers operating under limited capital budgets, these costs are difficult to justify, particularly when surgical volumes are relatively low. Thus, healthcare providers tend to prioritize investments in essential surgical equipment, imaging systems, and patient monitoring technologies over specialized personal protective equipment. In many cases, these facilities continue to rely on conventional surgical masks, face shields, and standard protective gowns that offer lower procurement costs.
The development of lightweight, ergonomic, and surgeon-friendly helmet systems is driving significant market growth by improving user comfort, safety, and overall surgical performance. Traditional surgical helmet systems have been associated with issues such as neck fatigue, heat buildup, noise, and restricted mobility during lengthy procedures. In response, manufacturers are focusing on designing helmets with reduced weight, improved weight distribution, enhanced airflow, quieter ventilation systems, and adjustable head supports to minimize physical strain on surgeons. Innovations such as anti-fog visors, integrated LED lighting, wider fields of vision, and optimized battery performance further enhance visibility and operational efficiency in the operating room. These advancements enable surgeons to perform complex orthopedic, trauma, and joint replacement procedures with greater comfort and precision, encouraging wider adoption across hospitals and ambulatory surgical centers.
For instance, February 2024 - MAXAIR Systems introduced the CAPR SHS Advanced Surgical Helmet System at the 2024 AORN Global Surgical Conference & Expo. The system features NIOSH-approved filtration, a sterile hood designed to enhance breathability and reduce CO₂ recirculation, and ergonomic features to improve surgeon comfort while providing advanced protection against airborne particles, fluids, and microorganisms in the operating room.
Market Concentration & Characteristics
The surgical helmet industry is characterized by increasing adoption across orthopedic, trauma, and joint replacement surgeries, where maintaining a sterile operating environment and protecting surgical teams are critical priorities. The market is driven by continuous product innovation, with manufacturers focusing on lightweight, ergonomic helmet systems that offer improved airflow, anti-fog visors, quieter ventilation, longer battery life, and enhanced wearer comfort during prolonged procedures. Hospitals and ambulatory surgical centers are the primary end users, with purchasing decisions influenced by clinical performance, infection-prevention capabilities, product durability, and overall lifecycle costs. The market also benefits from recurring revenue generated through disposable hoods, face shields, batteries, filters, and replacement accessories.
The surgical helmet industry is experiencing continuous technological advancements focused on improving surgeon protection, comfort, and operating room efficiency. Manufacturers are investing in developing advanced helmet systems featuring lightweight materials, ergonomic designs, improved ventilation, enhanced filtration, and optimized weight distribution to reduce physical strain during lengthy surgical procedures. Innovations such as anti-fog visors, integrated lighting systems, improved battery performance, and quieter airflow systems are enhancing visibility, mobility, and user experience for surgical teams. In addition, companies are focusing on improving disposable components, including sterile hoods and face shields, to provide a better fit, greater protection, and easier use. The integration of smart features, communication capabilities, and design improvements further supports product differentiation among manufacturers.
 To learn more about this report, Download Free Sample Report
For instance, in December 2025, 4LifeLAB announced the first real-time transmission of robotic spine surgery via its surgical helmet, which integrates cameras, Augmented Reality (AR) glasses, and 5G connectivity. The technology enabled live broadcasting of a robotic spine procedure between ULS São João in Porto and ULS Nordeste in Macedo de Cavaleiros, Portugal. Using NOS’s 5G mobile network, the surgical helmet captured high-quality, surgeon point-of-view images and transmitted them in real time to support professional training.
The surgical helmet industry has seen merger and acquisition activity as companies aim to strengthen their presence in the surgical safety, personal protective equipment, and operating room technology segments. These activities primarily focus on expanding product portfolios, acquiring advanced respiratory protection technologies, and enhancing capabilities in infection-prevention solutions. Companies are pursuing acquisitions and partnerships to integrate complementary technologies such as powered air-purifying respirators, advanced filtration systems, ergonomic designs, and reusable surgical protection platforms into their offerings. M&A activities also support geographic expansion by enabling companies to access established distribution networks and healthcare customer bases across different regions.
Regulatory standards established by bodies such as the U.S. Food and Drug Administration (FDA), National Institute for Occupational Safety and Health (NIOSH), European Medicines Agency (EMA), European regulatory authorities under the Medical Device Regulation (MDR), and other national healthcare regulatory agencies significantly influence the development and adoption of surgical helmet systems. These regulations ensure that surgical helmets meet required standards for safety, filtration efficiency, airflow performance, material quality, electrical safety, and protection against biological and airborne hazards. Manufacturers are required to undergo product testing, quality assessments, and certification processes to demonstrate compliance, which influences product development strategies and market entry timelines.
The surgical helmet industry is experiencing significant regional expansion, driven by growing awareness of surgical site infection prevention, regulatory mandates, and rising volumes of orthopedic and other high-risk surgeries. In North America and Europe, mature healthcare systems and stringent occupational safety standards have led to the widespread adoption of surgical helmets, especially in orthopedic and trauma surgeries.
For instance, in June 2024, RevelAi Health and Zimmer Biomet Holdings, Inc. announced a multi-year co-marketing agreement. This partnership aims to combine RevelAi Health’s innovative solutions with Zimmer Biomet’s extensive global reach to enhance the delivery and adoption of advanced medical technologies, improving patient outcomes across multiple therapeutic areas.
Analyst Perspective
The market is moderately competitive and evolving, driven by growing emphasis on operating room safety and infection prevention, as well as the adoption of advanced protective solutions in surgical environments. Established players such as Zimmer Biomet, Stryker, THI Total Healthcare Innovation GmbH, and MAXAIR Systems compete by offering product innovation, ergonomic designs, improved ventilation systems, and enhanced protective features tailored for long-duration surgical procedures. These companies benefit from strong relationships with healthcare institutions, established distribution channels, and broader medical technology portfolios. Emerging manufacturers are focusing on developing cost-effective surgical helmet systems and expanding accessibility across price-sensitive markets, particularly through customized solutions and regional distribution networks.
Product Insights
The disposable consumables segment dominated the market, accounting for the largest revenue share of 82.9% in 2025, due to their critical importance in maintaining sterility and infection control within operating theatres. These consumables include disposable helmet covers, hoods, togas, and face shields, all designed for single use to prevent cross-contamination between surgical procedures. Their dominance is due to the increasing global focus on hospital-acquired infection prevention, which has become a top priority for healthcare institutions. Hospitals and surgical centers adopt disposable components as part of stringent PPE protocols to ensure maximum patient and staff safety. In addition, disposable consumables eliminate the time-consuming, costly decontamination processes associated with reusable components, thereby offering greater operational efficiency.
Surgical helmets are expected to grow at a significant CAGR over the forecast period, driven by rising demand for comprehensive infection-control solutions in operating rooms. These systems include an integrated helmet, a powered air-purifying respirator or ventilation unit, and a full-body gown or hood offering head-to-toe protection for surgical staff. The growth is primarily fueled by increasing awareness of occupational hazards in high-risk surgeries such as orthopedic, trauma, and joint replacement procedures, where blood splatter and aerosolized particles are common. Hospitals and surgical centers prioritize helmet systems as they offer enhanced safety, comfort, and regulatory compliance compared to individually sourced components.
End Use Insights
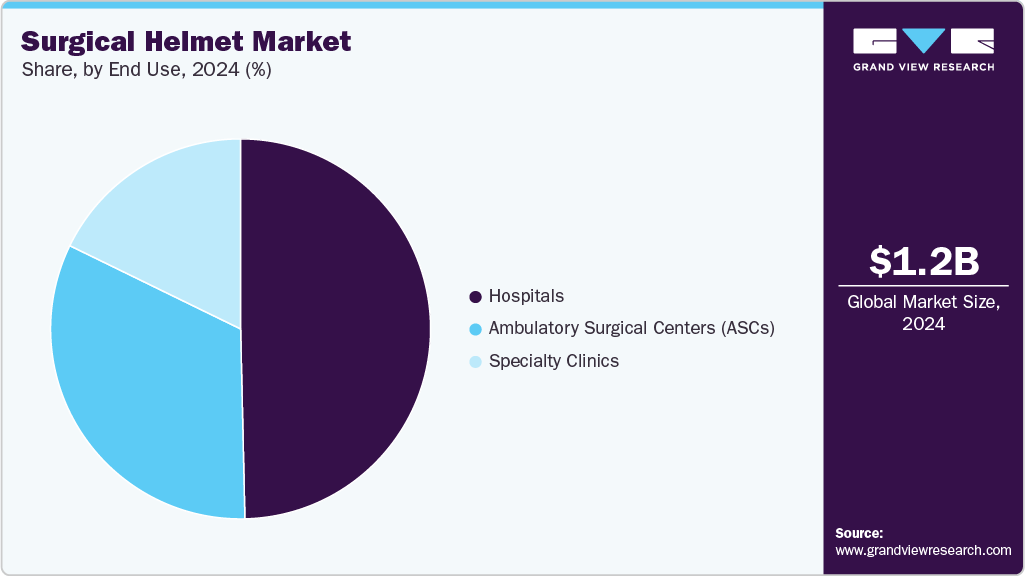
The hospitals segment dominated the market, accounting for the largest revenue share of 50.0% in 2025. Large hospitals possess advanced operating room infrastructure, dedicated infection-prevention protocols, and higher procurement budgets, enabling investment in complete surgical helmet systems and disposable consumables. Stringent hospital policies focused on reducing surgical site infections, protecting operating room personnel from splashes of blood and other fluids, and complying with occupational safety standards further supported product adoption. In addition, the presence of specialized orthopedic departments, experienced surgical teams, and centralized purchasing agreements has made hospitals the primary consumers of surgical helmet systems worldwide.
Ambulatory Surgical Centers (ASCs) are expected to see significant market growth as more orthopedic and minimally invasive procedures shift from hospitals to outpatient settings. Advances in surgical techniques, anesthesia, and postoperative care have enabled ASCs to perform a wider range of joint replacement and sports medicine procedures while maintaining high safety standards. These facilities are adopting surgical helmet systems to enhance infection control, protect staff, and meet quality accreditation requirements. Furthermore, the emphasis on cost-efficient healthcare delivery, shorter patient stays, faster recovery, and expanding investments in outpatient surgical infrastructure are accelerating the adoption of surgical helmets across ASCs.
Distribution Channel Insights
The offline segment is expected to dominate the market, accounting for the largest revenue share of 75.6% in 2025. Surgical helmet systems are high-value products that require product demonstrations, technical consultations, installation support, user training, and reliable after-sales service, making offline procurement the preferred purchasing channel. Long-term supply agreements, institutional contracts, and bulk purchasing arrangements further strengthen offline distribution's dominance. In addition, healthcare providers rely on established distributor networks to ensure consistent availability of disposable consumables, timely maintenance, and regulatory compliance, supporting the continued leadership of the offline channel.
 To learn more about this report, Download Free Sample Report
The online segment is witnessing significant growth as healthcare providers utilize digital procurement platforms to streamline purchasing processes and improve supply chain efficiency. Hospitals and ambulatory surgical centers are adopting online channels for ordering disposable consumables, replacement accessories, and standardized surgical equipment due to greater product availability, transparent pricing, and faster order processing. The expansion of manufacturer-owned e-commerce platforms and business-to-business (B2B) medical procurement portals has further accelerated online sales. In addition, the increasing digitalization of healthcare procurement, improved inventory management systems, and the growing preference for convenient, data-driven purchasing are driving rapid growth in the online distribution channel.
Regional Insights
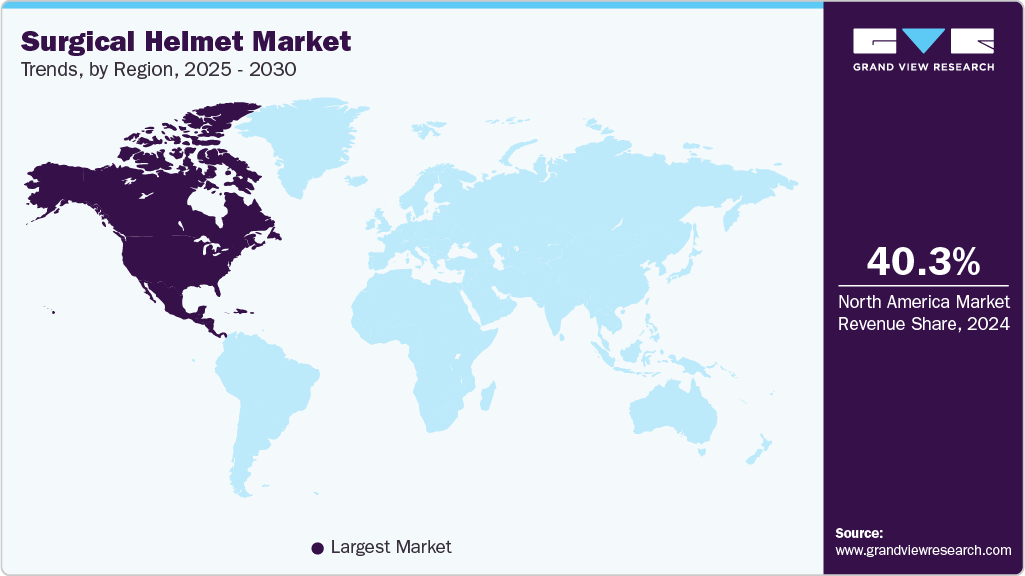
North America dominated the surgical helmet market with the largest revenue share of 48.2% in 2025. The market in North America is growing due to the increasing volume of orthopedic, trauma, and joint replacement procedures, as well as a greater emphasis on operating room safety and infection prevention practices. The region benefits from a well-developed healthcare infrastructure, high adoption of advanced surgical technologies, and strong purchasing capacity among hospitals and ambulatory surgical centers. The growing focus on protecting healthcare professionals from exposure to surgical aerosols, blood splashes, and airborne contaminants is driving the adoption of powered surgical helmet systems with advanced filtration and ventilation features. In addition, the presence of leading medical device manufacturers and continuous product innovations, including lightweight designs, improved ergonomics, enhanced airflow systems, and integrated protective features, is supporting market expansion.
 To learn more about this report, Download Free Sample Report
U.S. Surgical Helmet Market Trends
The surgical helmet market in the U.S. is growing due to the rising number of hip and knee replacement surgeries, which is driving demand for advanced protective solutions in orthopedic operating rooms. Total joint replacement procedures are complex surgeries that require strict infection prevention measures due to the risk of surgical site infections, which can lead to prolonged hospital stays, revision procedures, and increased healthcare costs. As the volume of primary and revision hip and knee arthroplasty procedures continues to rise due to an aging population, increasing prevalence of osteoarthritis, and growing demand for improved mobility and quality of life, hospitals and orthopedic centers are adopting enhanced protective equipment for surgical teams. For instance, according to data published by the American College of Rheumatology in 2025, about 790,000 total knee replacements and 544,000 hip replacements are performed every year in the U.S. This number continues to grow as our population ages. Total joint replacement is one of the safest and most reliable treatments in any area of medicine. A hip or knee replacement can last for 20 or more years. In fact, for most patients, total joint replacement surgery is a lifelong solution for arthritis of the hip or knee.
The expansion of ambulatory surgical centers in the U.S. is driving market growth by increasing demand for advanced operating room safety solutions outside traditional hospital settings. ASCs are performing a wide range of orthopedic procedures, including arthroscopic surgeries, joint interventions, and other elective procedures that require strict infection prevention protocols and efficient surgical workflows. As these facilities focus on maintaining high standards of patient safety while improving procedural efficiency and reducing healthcare costs, adoption of protective equipment, such as surgical helmet systems, is increasing. Surgical helmets provide enhanced protection against blood splashes, fluid exposure, and airborne contaminants while supporting a controlled surgical environment through integrated ventilation and filtration technologies.
Number of ASCs per State in the U.S. in 2025
State / U.S. Territory
Number of Ambulatory Surgical Centers (ASCs)
Alabama
51
Alaska
18
Arizona
239
Arkansas
84
California
896
Colorado
132
Connecticut
54
Delaware
22
District of Columbia
2
Florida
517
Georgia
423
Guam
2
Hawaii
24
Idaho
61
Illinois
136
Indiana
Upgrade the report license to gain access to the complete analysis.
Iowa
Kansas
Kentucky
Louisiana
Maine
Maryland
Massachusetts
Michigan
Minnesota
Mississippi
Missouri
Montana
Nebraska
Nevada
New Hampshire
New Jersey
New Mexico
New York
North Carolina
North Dakota
Ohio
Oklahoma
Oregon
Pennsylvania
Puerto Rico
Rhode Island
South Carolina
South Dakota
Tennessee
Texas
Utah
Vermont
Virgin Islands
Virginia
Washington
West Virginia
Wisconsin
Wyoming
Source: Ambulatory Surgery Center Association 2025
Europe Surgical Helmet Market Trends
The surgical helmet market in Europe is growing due to increasing adoption of advanced infection-prevention measures, rising orthopedic and trauma surgeries, and a growing emphasis on healthcare worker safety in operating rooms. The region has a well-established healthcare infrastructure, strong regulatory standards, and high awareness regarding the prevention of surgical site infections, which is encouraging hospitals and surgical centers to invest in advanced protective equipment. The increasing number of joint replacement procedures, sports injury treatments, and complex surgical interventions is driving demand for surgical helmet systems that provide enhanced protection against fluid exposure, airborne particles, and contamination. In addition, European hospitals are focusing on improving operating room standards, surgeon comfort, and occupational safety, thereby supporting demand for lightweight, ergonomically designed helmet systems with improved ventilation and filtration capabilities.
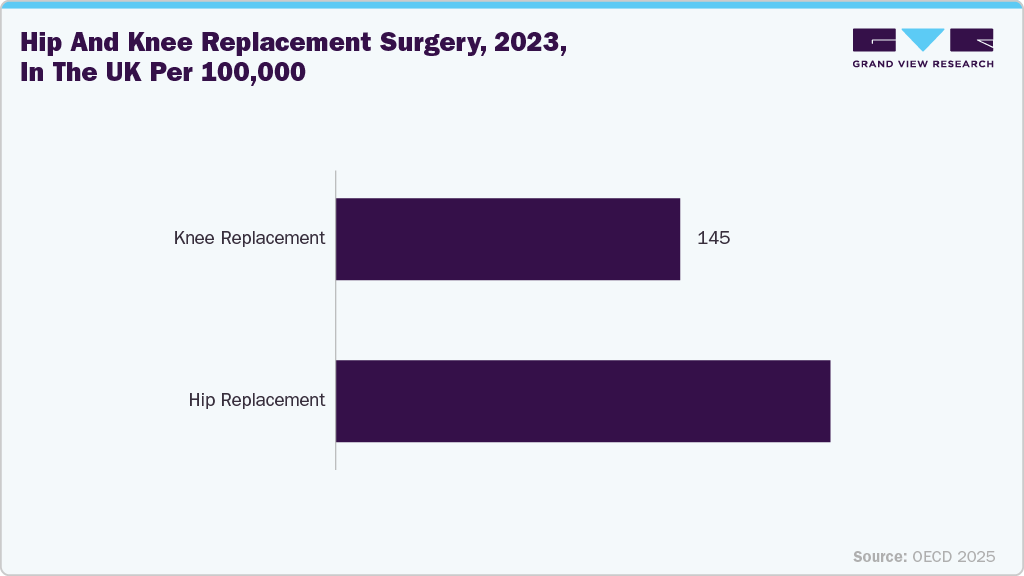
The UK surgical helmet market is rising due to several hip and knee replacement surgeries, driving growth by increasing demand for enhanced infection-prevention and protective solutions in orthopedic operating environments. Hip and knee arthroplasty procedures require stringent sterile conditions due to the risk of surgical site infections, which can lead to implant complications, revision surgeries, and higher healthcare costs. The rising burden of osteoarthritis, an aging population, and growing demand for mobility-restoring procedures have contributed to a higher volume of joint replacement surgeries across the UK. As hospitals and orthopedic centers perform more complex primary and revision joint replacement procedures, the adoption of surgical helmet systems is increasing to provide surgeons and operating room staff with improved protection against fluid exposure, airborne particles, and contamination.
 To learn more about this report, Download Free Sample Report
The surgical helmet market in Germany is growing due to the country’s advanced healthcare infrastructure, high volume of complex surgical procedures, and strong focus on maintaining stringent operating room safety standards. Germany has a well-established orthopedic and trauma care ecosystem, with numerous specialized hospitals and surgical centers performing procedures such as joint reconstruction, fracture repair, and implant surgeries that require enhanced protection against contamination risks. The increasing emphasis on reducing healthcare-associated infections and improving occupational safety for surgical teams is encouraging healthcare facilities to adopt advanced protective solutions, including powered surgical helmet systems. In addition, Germany’s strong medical technology sector supports continuous innovation in surgical equipment, with manufacturers focusing on improving helmet ergonomics, ventilation efficiency, filtration performance, and user comfort.
Asia Pacific Surgical Helmet Market Trends
The surgical helmet market in the Asia Pacific is growing due to increased focus on operating room safety and infection prevention, as well as the adoption of advanced protective equipment in healthcare facilities. The rising number of complex surgical procedures, including orthopedic, trauma, and other long-duration surgeries, is creating demand for surgical helmet systems that provide enhanced protection, ventilation, and surgeon comfort. Hospitals and surgical centers are strengthening infection control protocols to reduce the risk of surgical site infections, supporting the adoption of powered surgical helmet solutions. In addition, the expansion of healthcare infrastructure, modernization of operating rooms, and increasing investments in advanced medical technologies are encouraging healthcare providers to integrate improved surgical protection systems.
India surgical helmet market is growing due to the rapid expansion of healthcare infrastructure, increasing surgical capacity, and rising adoption of advanced operating room safety solutions. The growing number of orthopedic procedures, trauma surgeries, and complex surgical interventions is creating demand for protective systems that enhance surgeon safety and comfort during prolonged operations. Hospitals are focusing on improving infection-prevention measures and maintaining sterile surgical environments, which is driving the integration of powered surgical helmets with filtration and ventilation features. In addition, the expansion of private hospitals, multispecialty healthcare facilities, and ambulatory surgical centers is increasing access to advanced surgical equipment beyond major medical institutions.
The surgical helmet market in Japan is growing due to the country’s rapidly aging population, which is increasing the demand for orthopedic and other complex surgical procedures. The growing elderly demographic is associated with a higher prevalence of age-related conditions such as joint degeneration, fractures, and musculoskeletal disorders, leading to an increased volume of hip and knee replacement surgeries and other orthopedic interventions. As these procedures involve extended operating times and require strict infection-prevention measures, healthcare providers are adopting advanced protective solutions, such as surgical helmet systems, to enhance surgeon safety and maintain a controlled surgical environment.
For instance, in 2025, according to the World Economic Forum, Japan's Ministry of Internal Affairs and Communications reported that, as of 2024, the country had a record 36.25 million people aged 65 and over, accounting for 29.3% of the total population. This share is projected to rise to 34.8% in 2040 and 36.3% in 2045. Japan's proportion of elderly residents is already far higher than second-ranked Martinique (25.3%), making it the world's most aged society.
Middle East & Africa Surgical Helmet Market Trends
The surgical helmet market in MEA is expanding as healthcare systems across the region continue to improve surgical capabilities and adopt advanced technologies to enhance operating room standards. Increasing investment in tertiary care hospitals, specialized surgical facilities, and medical infrastructure is creating opportunities to adopt surgeon protection systems. The rising prevalence of chronic diseases, the growing number of orthopedic procedures, and the increasing demand for complex surgeries are encouraging healthcare providers to implement solutions that support longer and safer surgical procedures. In addition, the growing emphasis on healthcare quality accreditation and adherence to international infection control practices is driving awareness about protective equipment that minimizes contamination risks in operating environments.
Latin America Surgical Helmet Market Trends
The surgical helmet market in Latin America is growing, driven by the shift toward more advanced surgical environments and the need for enhanced protection for operating room personnel. The rising adoption of modern surgical practices and the growing availability of technologically advanced healthcare equipment are encouraging hospitals to upgrade their operating room capabilities. The region is experiencing increased demand for orthopedic and reconstructive procedures due to changing demographics, rising trauma cases, and greater access to specialized care, creating opportunities for surgical helmet systems. In addition, healthcare institutions are becoming more focused on improving surgical workflow efficiency, reducing surgeon discomfort during prolonged procedures, and enhancing overall operating room performance.
Key Surgical Helmet Company Insights
The market is characterized by established medical device companies and specialized manufacturers that develop advanced head protection systems for surgical teams. Key companies are competing by offering product innovation, improved ergonomics, enhanced ventilation technologies, improved filtration efficiency, and solutions designed to support long-duration surgical procedures. Market participants are focusing on expanding their product portfolios, strengthening distribution networks, and improving their presence across hospitals, ambulatory surgical centers, and specialty healthcare facilities. Companies with strong brand recognition, regulatory approvals, and established relationships with healthcare providers hold a competitive advantage due to higher adoption among surgical professionals.
Key Surgical Helmet Companies
The following key companies have been profiled for this study on the surgical helmet market.
-
Zimmer Biomet
-
Stryker
-
Beijing ZKSK Technology Co., Ltd.
-
Kaiser Technology Co., Ltd.
-
THI Total Healthcare Innovation GmbH
-
MAXAIR Systems
-
AresAir (Netia Design and Health Solutions Ltd.)
-
Regal Healthcare
-
Vizbl Brand Products (Prodancy Pvt. Ltd.)
-
Apex Hygiene Products
-
YuHoTa
-
Maharani Medicare Pvt. Ltd.
-
4LifeLAB
-
Dexup (Codex Healthcare Pvt. Ltd.)
-
StubMed
Product-Level Value Capture Framework
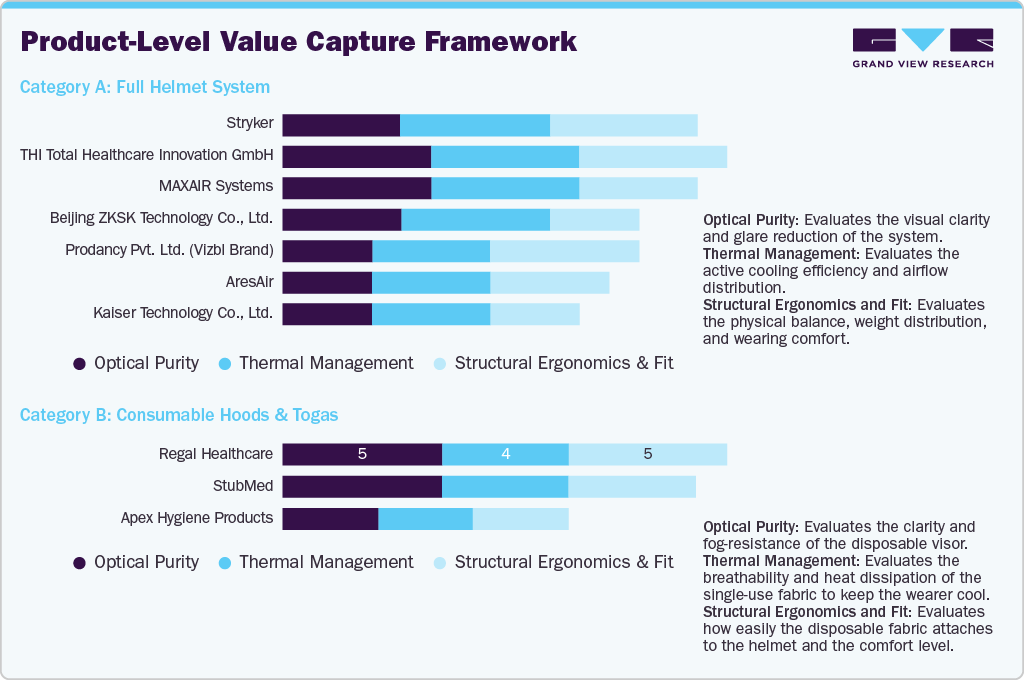
The product-level value capture framework provides a comparative assessment of key manufacturers in the market by evaluating their products across three critical value dimensions: optical purity, thermal management, and structural ergonomics & fit. The framework is divided into two product categories: Category A: Full Helmet Systems and Category B: Consumable Hoods & Togas, to distinguish the performance characteristics of helmet platforms from those of their disposable protective components. Each company is assigned a score based on the extent to which its products deliver value across these functional attributes, enabling a standardized comparison of competitive positioning. The analysis highlights differences in product design, material selection, airflow, thermal management capabilities, visor performance, and ergonomic comfort. The framework illustrates how manufacturers differentiate their offerings through technology and product innovation, identifies areas of competitive strength and potential improvement, and provides insights into the value proposition delivered by participants across the surgical helmet ecosystem.
 To learn more about this report, Download Free Sample Report
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Zimmer Biomet, Stryker, THI Total Healthcare Innovation GmbH, MAXAIR Systems, Kaiser Technology Co., Ltd.)
- Focus on continuous product innovation by integrating ergonomic designs, enhanced airflow systems, and advanced visor technologies to improve surgical performance.
- Expand market presence through strategic distributor partnerships, hospital collaborations, and comprehensive after-sales support to strengthen customer relationships and global reach.
- Strong brand recognition and extensive clinical adoption enable established companies to maintain customer trust and secure long-term procurement agreements with hospitals.
- Broad product portfolios that combine reusable helmet systems with compatible disposable consumables generate recurring revenue and strengthen customer retention.
- Premium product pricing may limit adoption among cost-sensitive healthcare facilities and emerging markets with constrained procurement budgets and reimbursement challenges.
- Dependence on proprietary consumables and replacement components can increase ownership costs and encourage customers to evaluate lower-cost alternative suppliers.
Emerging Players (Beijing ZKSK Technology Co., Ltd., AresAir (Netia Design and Health Solutions Ltd.), Regal Healthcare, Vizbl Brand Products (Prodancy Pvt. Ltd.), Apex Hygiene Products, Maharani Medicare Pvt. Ltd.)
- Focus on developing cost-effective surgical helmet systems and consumables that meet essential performance requirements while reducing costs for healthcare providers.
- Expand market presence through regional distributors, OEM partnerships, and targeted product customization to strengthen penetration across domestic and international healthcare markets.
- Competitive pricing and flexible manufacturing capabilities enable emerging companies to respond quickly to customer requirements and evolving market demands.
- A strong emphasis on niche product innovation, customized designs, and rapid product development enables differentiation from larger, well-established competitors.
- Limited global brand recognition and smaller distribution networks may restrict access to large hospital systems and international procurement opportunities.
- A comparatively lower investment in research, clinical validation, and marketing can slow product adoption and reduce competitiveness relative to established industry leaders.
Recent Developments
-
In June 2025, THI Total Healthcare Innovation GmbH announced the launch of the ViVi 25 Surgical Helmet, describing it as its latest innovation in surgical personal protection systems. According to the company, the helmet features a multi-layer, high-impact-resistant shell, breathable, ergonomic inner padding, a smart ventilation system for improved airflow during extended use, and a modern, lightweight design. THI states that the Vivi 25 is designed to provide enhanced safety, comfort, and performance for healthcare professionals in demanding surgical environments.
-
In June 2025, MAXAIR Systems highlighted the CAPR Bonnet System, designed to securely attach to the MAXAIR CAPR Helmet for use in high-risk healthcare environments. According to the company, the system features superior filtration with an integrated PAPR100-N filter, whisper-quiet operation, balanced weight distribution, adjustable cooling airflow, a heads-up display for real-time battery and airflow monitoring, and a streamlined design that eliminates the need for fit testing while simplifying training, procurement, stocking, and distribution.
-
In March 2025, Stryker introduced its latest personal protective equipment, the Steri-Shield 8 personal protection system. This innovative system was developed over years of research, testing, and collaboration with field users.
Surgical Helmet Market Report Scope
Report Attribute
Details
Market size in 2025
USD 549.7 million
Estimated market size in 2026
USD 589.0 million
Projected market size by 2033
USD 967.8 million
Growth rate
CAGR of 7.4% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Zimmer Biomet; Stryker; Beijing ZKSK Technology Co., Ltd.; Kaiser Technology Co., Ltd.; THI Total Healthcare Innovation GmbH; MAXAIR Systems; AresAir (Netia Design and Health Solutions Ltd.); Regal Healthcare; Vizbl Brand Products (Prodancy Pvt. Ltd.); Apex Hygiene Products; YuHoTa; Maharani Medicare Pvt. Ltd.; 4LifeLAB; Dexup (Codex Healthcare Pvt. Ltd.); StubMed
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Surgical Helmet Market Report Segmentation
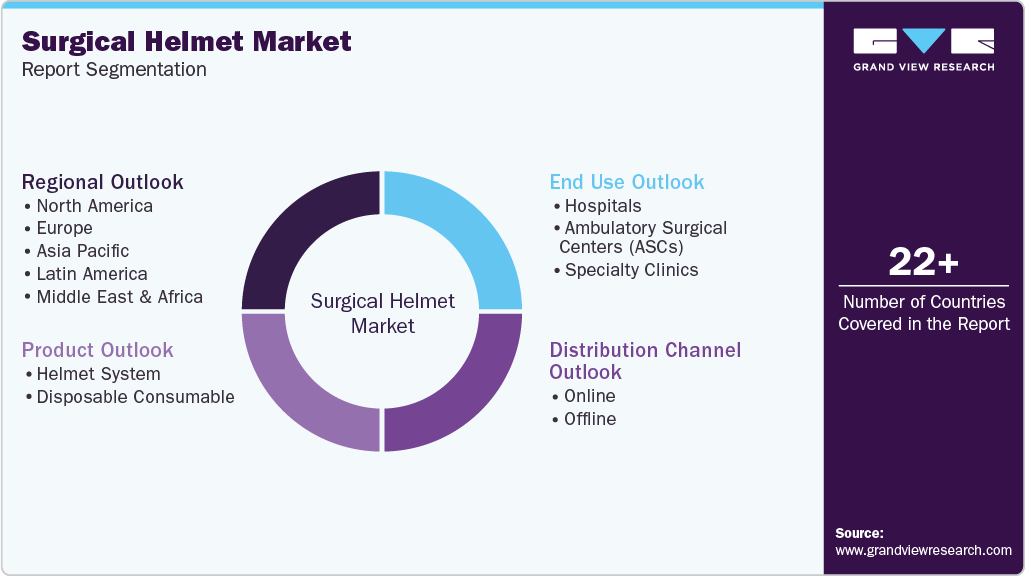
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global surgical helmet market report based on product, end use, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume in Units; Revenue, USD Million, 2021 - 2033)
-
Surgical Helmet
-
Complete surgical helmet systems
-
Powered surgical helmets
-
-
Disposable Consumables
-
Complete Surgical Helmet Disposables
-
Hoods
-
By Technology
-
Peel-away
-
Non-peel (standard visor)
-
Advanced (anti-fog / anti-reflective)
-
-
Togas
-
Other Disposable Consumables
-
-
Powered Surgical Helmet Disposables
-
Hoods
-
By Technology
-
Peel-away
-
Non-peel (standard visor)
-
Advanced (anti-fog / anti-reflective)
-
-
Togas
-
Other Disposable Consumables
-
-
-
Accessories
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers (ASCs)
-
Specialty Clinics
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Online
-
Offline
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The surgical helmet market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each surgical helmet segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Surgical Helmet
Surgical helmet market revenue capture includes the total monetary value generated from direct sales and leasing of reusable capital hardware, such as helmet units, built-in cooling fans, LED illumination systems, and power heads. It accounts for primary equipment acquisitions by hospitals and ambulatory surgical centers globally.
Disposable Consumables
Surgical helmet market revenue capture includes the ongoing sales of single-use, sterile protective barriers, such as disposable hoods, surgical togas, face shields, and replacement air filters. It covers recurring, high-volume purchases by healthcare facilities to prevent cross-contamination and maintain sterility in the operating room during surgical procedures.
Accessories
Financial value in this segment is realized through sales of auxiliary support hardware, such as rechargeable lithium-ion battery packs, multi-dock charging stations, power adapters, wall brackets, and protective carrying cases. It captures secondary purchases necessary for day-to-day operational uptime and system maintenance.
Estimation Model
Bottom-Up Epidemiological Modeling
Top-Down Revenue Triangulation
Demand-Side Care-Setting Modeling
Supply-Side Capacity & Utilization Modeling
Data Triangulation & Market Reconciliation
Estimating the target patient population requiring surgical helmets using epidemiological data on procedures such as orthopedic, neurosurgical, trauma, ENT, and maxillofacial surgeries. Country-level hospital records, surgical registries, published literature, and procedure databases across major procedure volumes are multiplied by the average usage rate of surgical helmets to estimate unit demand.
Analyzing total revenue reported by key surgical helmet manufacturers and medical device companies in annual reports, investor presentations, and financial disclosures. Company revenues are segmented by product category, region, and application, and used to estimate the overall market value and validate bottom-up findings.
Assessing demand across care settings including hospitals, ambulatory surgical centers, and specialty clinics. Procedure volumes are mapped by care setting, combined with average selling prices (ASP) and replacement frequency (typically 3–5 years) to estimate current demand and forecast market size.
Evaluating installed manufacturing capacity and production output of surgical helmet manufacturers, capacity utilization rates, and supply chain constraints. This includes analysis of raw material availability, lead times, and distribution networks to assess achievable supply and potential bottlenecks.
Combining outputs from bottom-up, top-down, demand-side, and supply-side models to reconcile market estimates. Differences are analyzed, and final market size is validated using expert interviews, regulatory approvals, import-export data, and industry publications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
ASP and volume analysis (historical and forecast)
Comprehensive ASP (Average Selling Price) and volume analysis for surgical helmet systems and consumables (hoods, togas, face shields, filters, batteries, and accessories) across 2021–2033, segmented by product type, end use, distribution channel and geography. Includes historical pricing trends, procurement contracts, replacement cycles, reusable vs. disposable component mix, utilization rates, and forward-looking forecasts based on orthopedic procedure volumes, hospital infrastructure expansion, infection prevention initiatives, and adoption of advanced surgical helmet technologies.
Enables long-term revenue forecasting, pricing strategy optimization, procurement planning, identification of premium product opportunities, evaluation of replacement demand, and regional adoption trends to support commercialization, investment, and product lifecycle management decisions.
Procedure volume and patient population analysis
Detailed assessment of surgical procedures requiring surgical helmet systems, including joint replacement surgeries (hip, knee, shoulder), trauma fixation, spine surgery, orthopedic oncology, revision surgeries, and selected high-risk surgical procedures. Includes segmentation by hospitals, ambulatory surgical centers, specialty orthopedic centers, procedure volumes, surgeon adoption rates, operating room utilization, replacement frequency of consumables, and regional healthcare infrastructure across major markets.
Supports accurate demand forecasting, estimation of addressable procedure volumes, identification of high-growth clinical segments, healthcare resource planning, consumables demand estimation, and long-term market sizing based on surgical activity and infection control practices.
Competitive benchmarking and market share analysis
Comprehensive competitive assessment of leading surgical helmet manufacturers, including product portfolio benchmarking, ASP comparison, regional market share analysis, distribution channel assessment, regulatory approvals, technological comparison (airflow systems, filtration efficiency, battery technology, comfort, ergonomics, and visibility), innovation pipeline evaluation, strategic initiatives, partnerships, mergers & acquisitions, and product positioning across global markets.
Enables competitive positioning, identification of market gaps, pricing strategy optimization, partnership and acquisition evaluation, product differentiation, innovation benchmarking, geographic expansion planning, and strategic decision-making for new product launches and portfolio expansion.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The disposable consumables segment led with an 82.9% revenue share in 2025 and is the fastest-growing segment.
The Hospitals segment led with a 50.0% revenue share in 2025, and it is the fastest-growing segment.
The global surgical helmet market size was valued at USD 549.7 million in 2025 and is estimated at USD 589.0 million in 2026.
The global surgical helmet market is expected to grow at a CAGR of 7.4% from 2026 to 2033, reaching USD 967.8 million by 2033.
North America dominated with a revenue share of 48.2% in 2025.
Some key players operating in the surgical helmets market include Zimmer Biomet, Stryker, Beijing ZKSK Technology Co., Ltd., Kaiser Technology Co., Ltd., THI Total Healthcare Innovation GmbH, MAXAIR Systems, AresAir (Netia Design and Health Solutions Ltd.), Regal Healthcare, Vizbl Brand Products (Prodancy Pvt. Ltd.), Apex Hygiene Products, YuHoTa, Maharani Medicare Pvt. Ltd., 4LifeLAB, Dexup (Codex Healthcare Pvt. Ltd.), StubMed, among others.
Key factors driving the market growth include the high volume of surgical procedures, the growing focus on infection control and prevention, and the increasing number of road and sports accidents.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


