
- Home
- »
- Medical Devices
- »
-
Surgical Laser Rental Market Size Report, 2025-2033GVR Report cover

Surgical Laser Rental Market (2025 - 2033) Size, Share & Trends Analysis Report By Type (Solid State Lasers, Diode Laser System), By Application (Dentistry, Ophthalmology), By Rental Offering, By End Use, By Region, And Segment Forecasts
Market Size, 2024
$10.3BMarket Estimate, 2026
$11.9BMarket Forecast, 2033
$19.5BCAGR, 2025–2033
7.3%Surgical Laser Rental Market Summary
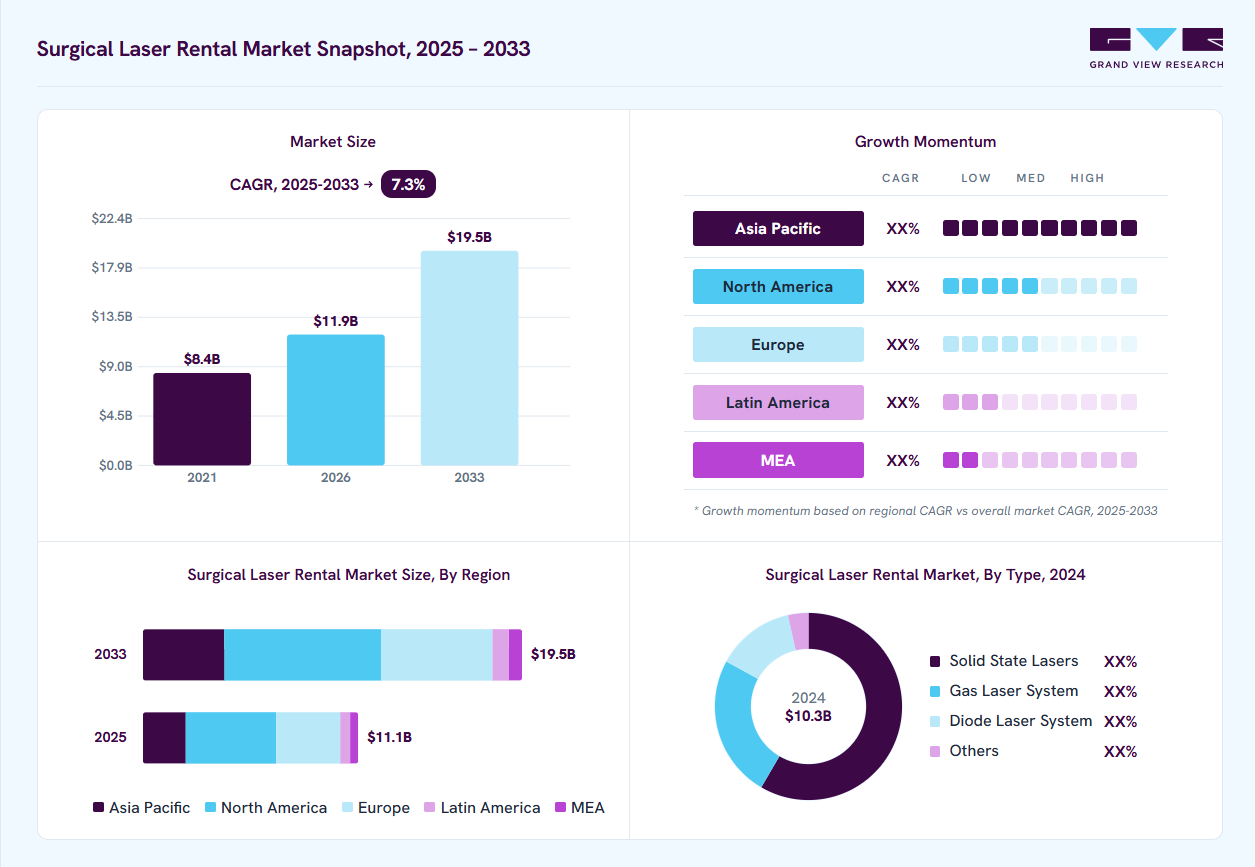
The global surgical laser rental market size was valued at USD 10.3 billion in 2024 and is projected to grow from USD 11.9 billion in 2026 to USD 19.5 billion by 2033, at a CAGR of 7.3% from 2025 to 2033. North America dominated the market, accounting for a revenue share of 41.9% in 2024. The market's expansion is fueled by the increasing preference for minimally invasive surgeries, rising procedure volumes, and the high upfront cost of laser systems, encouraging facilities to choose rental options.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- The surgical laser rental market in the U.S. accounted for the largest market revenue share of 90.3% in North America in 2024.
- Based on type, the solid-state lasers segment led the market with the largest revenue share of 58.4% in 2024.
- Based on applications, the surgical segment led the market with the largest revenue share of 71.7% in 2024.
- By rental offering, the long-term rentals segment led the market with the largest revenue share of 55.2% in 2024.
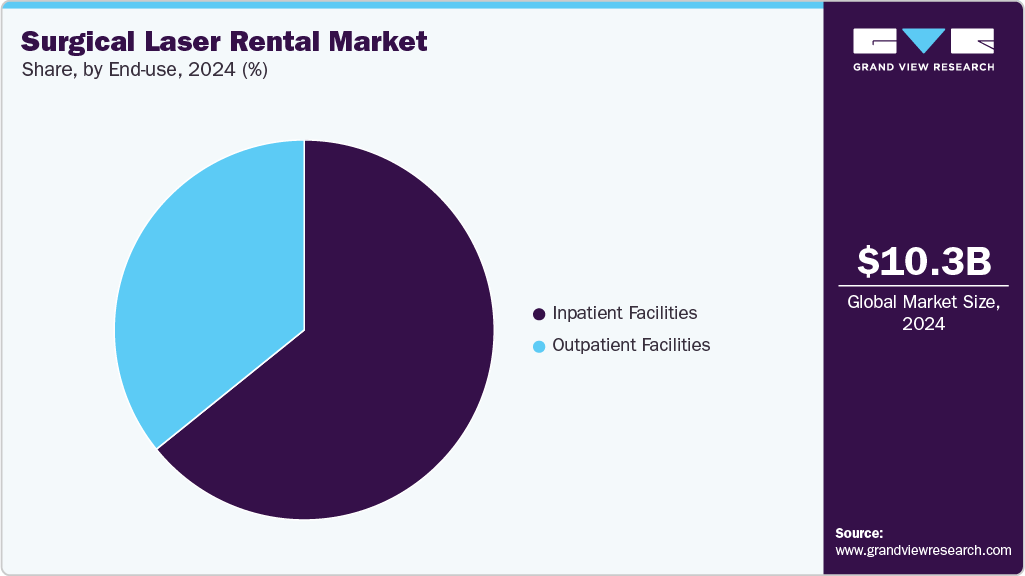
- By end-use, the inpatient facilities segment led the market with the largest revenue share of 64.2% in 2024.
Market Size & Forecast
- 2024 Market Size: USD 10.3 Billion
- 2030 Projected Market Size: USD 19.5 Billion
- CAGR (2025-2030): 7.3%
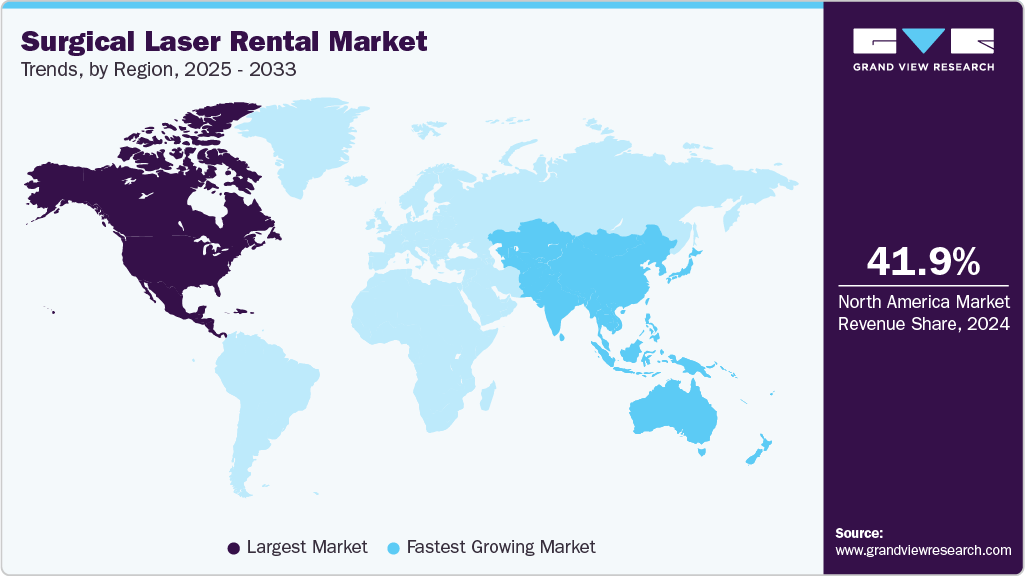
- North America: Largest market in 2024
- Asia Pacific: Fastest growing market
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2033 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Technological advancements in diode and CO₂ lasers and the shift toward outpatient and ASC-based surgeries further boost demand. Flexible rental solutions that include maintenance, training, and compliance services improve accessibility and efficiency. Notably, 123 of 216 countries (56.9%) classified by income levels reported surgical volume by 2023, reflecting a 70.8% rise in reporting nations since 2016 indicating heightened global surgical activity that supports broader market growth.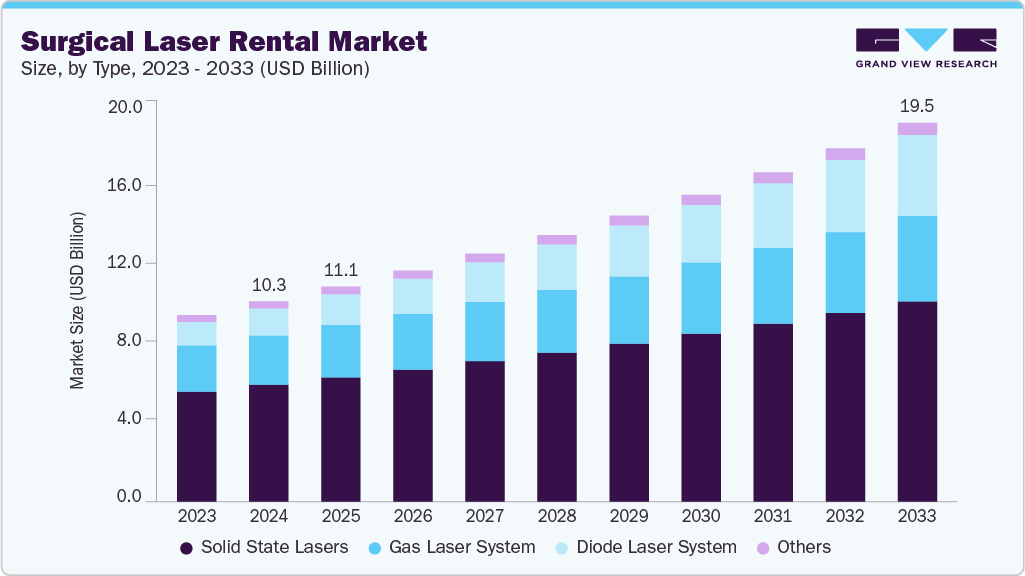 To learn more about this report, Download Free Sample Report
The market is experiencing strong growth, fueled by the rising demand for non-invasive cosmetic procedures. Laser systems are increasingly utilized in aesthetic treatments like skin resurfacing, laser hair removal, and tattoo removal, owing to their high precision and minimal downtime. In 2023, minimally invasive cosmetic procedures grew by 7%, outpacing surgical ones by 2%. Procedures such as laser hair removal rose by 9% to over 800,000, while laser skin resurfacing increased by 4%, exceeding 1 million treatments. According to the American Society of Plastic Surgeons (ASPS), the total number of minimally invasive cosmetic procedures reached 25.4 million in 2023, with laser-based treatments contributing significantly to this upward trend.
The Growing Demand for Non-Invasive Cosmetic Procedures:
Procedure
Volume (2023)
% Increase from 2022
Neuromodulator injections (e.g., Botox)
9,480,949
9%
Hyaluronic acid (HA) fillers
5,294,603
8%
Skin resurfacing (e.g., lasers, peels)
3,501,696
5%
Laser-based skin treatments (e.g., hair removal, tattoo removal, IPL)
3,101,772
6%
Lip augmentation (injectables)
1,439,291
4%
Source: American Society of Plastic Surgeons, Grand View Research Analysis
The market is witnessing robust growth, bolstered by technological advancements and increasing demand for precision-driven, minimally invasive procedures. Alcon’s planned USD 430 million acquisition of Lensar marks a significant milestone, aiming to enhance the affordability and efficiency of femtosecond laser-assisted cataract surgery (FLACS). Lensar’s ALLY system, a next-generation dual-pulsed femtosecond laser, is designed to reduce procedure time by up to two-thirds while improving surgical outcomes through robotic operation, advanced astigmatism tools, and enhanced imaging. By leveraging Alcon’s global network, the acquisition is set to expand the reach of advanced FLACS systems to a broader base of surgeons worldwide. With Lensar’s market share already reaching 20% in the U.S. and 170,000 procedures performed in 2024 alone, the merger positions Alcon to further penetrate the estimated 32 million annual global cataract surgeries.
Meanwhile, innovation in cosmetic surgical lasers is also accelerating market momentum. The introduction of LightScalpel 4020, a carbon dioxide laser engineered for both aesthetic and surgical use, is redefining facial rejuvenation and soft tissue surgeries. Designed for optimal skin resurfacing and wrinkle removal, the 4020 operates at a 10,600 nm wavelength and offers unmatched precision by vaporizing superficial skin layers to stimulate new collagen formation. Its fiberoptic delivery system enhances surgical control, while the device’s ability to perform bloodless procedures translates to better visibility, reduced bruising, and faster recovery. Surgeons like Dr. Laverson praise it as a transformative tool in plastic surgery for applications ranging from facial aesthetics to laser labiaplasty.
Together, these developments reflect a growing shift toward high-performance, flexible laser systems that meet the rising demand for outpatient, non-invasive, and cost-effective surgical solutions. As hospitals and ASCs seek access to cutting-edge technologies without high capital expenditure, surgical laser rentals are becoming a preferred model. Rental providers benefit from partnerships with manufacturers, delivering advanced devices like the ALLY system or the LightScalpel 4020 to end-users with bundled support, maintenance, and training. This model ensures consistent access to innovation while supporting clinicians’ goals of improved precision, patient outcomes, and workflow efficiency. The expanding ecosystem of high-tech laser solutions, coupled with strategic mergers and product rollouts, is expected to keep fueling the global growth of the surgical laser rental market through 2033.
Market Concentration & Characteristics
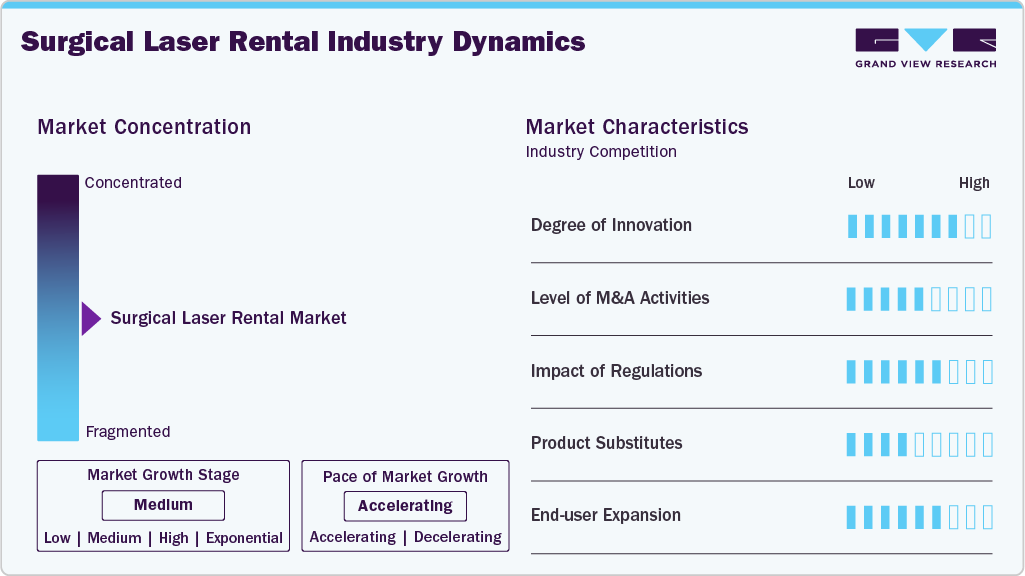
The industry shows moderate to high industry concentration, with key players like HealthTronics, Inc. and Advanced Surgical Technologies dominating regional markets. These companies maintain large inventories, offer 24/7 service, and provide specialized lasers for urology, dermatology, ophthalmology, and gynecology. The industry is characterized by flexible rental models, rapid technological adoption, and a focus on maintenance, training, and regulatory compliance. High entry barriers include equipment cost, technical expertise, and certification requirements. Competitive differentiation is based on service reliability, geographic coverage, and access to next-generation laser systems, contributing to a consolidated market structure in urban and high-demand healthcare regions.
Market Characteristics
The surgical laser rental industry exhibits a high degree of innovation, driven by advancements in femtosecond, CO₂, and diode laser technologies. Devices like Lensar’s ALLY system and LightScalpel 4020 demonstrate cutting-edge features such as dual-pulsed lasers, robotic precision, and fiberoptic delivery. These innovations enhance surgical accuracy, reduce procedure times, and improve patient outcomes. Rental models enable broader access to such technologies without the burden of ownership costs, supporting hospitals and ASCs in adopting the latest equipment. Continuous improvements in ergonomics, imaging, and safety protocols further underscore the industry's commitment to delivering flexible, next-generation solutions for a range of procedures.
Regulations significantly influence the surgical laser rental industry by ensuring safety, quality, and compliance in clinical environments. Providers must meet standards like ISO 13485:2016 for medical device quality management and adhere to FDA requirements for device safety and effectiveness. These regulations shape equipment design, sterilization protocols, and maintenance practices. Rental companies must also comply with state licensing, facility accreditation standards, and data privacy laws when integrating laser systems with patient records. While regulatory compliance ensures trust and patient safety, it can increase operational costs and limit flexibility, especially for smaller providers. However, strong adherence enhances credibility and market acceptance.
 To learn more about this report, Download Free Sample Report
The surgical laser rental industry is witnessing increasing merger and acquisition (M&A) activity, reflecting strategic consolidation and innovation. A notable example is the formation of the MedTech Laser Group in 2024, through Afinum’s acquisition of shares in A.R.C. Laser GmbH and neoLaser Ltd. These firms specialize in ophthalmic and proctology laser technologies, respectively. This M&A move underscores the growing investor interest in high-precision, minimally invasive laser systems and reflects the sector's global integration. As companies seek to enhance their portfolios and expand geographical reach, such acquisitions are reshaping the competitive landscape, promoting R&D synergies, and boosting service and rental capabilities.
In the surgical laser rental industry, key product substitutes include traditional surgical tools such as scalpels, electrosurgical units, cryosurgical devices, and radiofrequency ablation systems. These alternatives may be preferred due to lower upfront costs or familiarity among surgeons. Additionally, advanced energy-based devices and robotic surgical systems offer different therapeutic approaches, depending on the procedure. However, surgical lasers remain superior for precision, minimal invasiveness, reduced blood loss, and faster healing times. Substitution risk is moderate, as laser systems are increasingly essential in dermatology, urology, ophthalmology, and cosmetic surgery areas where precision and tissue conservation are critical to successful outcomes and patient satisfaction.
End-user concentration in the surgical laser rental industry is relatively high, with hospitals, ambulatory surgical centers (ASCs), and specialty clinics representing the core clientele. Large hospitals dominate demand due to higher surgical volumes and complex procedures requiring advanced laser systems. ASCs are rapidly increasing their share, especially for outpatient dermatology, ophthalmology, and gynecology procedures, driven by cost-efficiency and patient preferences. This concentration allows rental companies to build long-term contracts and offer tailored services.
Type Insights
The solid-state lasers segment dominated the market and accounted for the largest revenue share of around 58.4% in 2024. This dominance is attributed to their high precision, reliability, and versatility across various surgical applications, including urology, ophthalmology, and ENT procedures. Solid-state lasers, such as Nd:YAG and Holmium:YAG, are favored for their effective tissue interaction and minimal thermal damage.
The diode laser system segment is expected to witness the fastest growth during the forecast period due to its compact design, energy efficiency, and versatility across multiple surgical specialties, including dermatology, dentistry, urology, and vascular procedures. These lasers offer precise tissue targeting minimal damage, making them ideal for minimally invasive surgeries. Their lower cost compared to other laser types enhances affordability, especially in outpatient and ambulatory surgical settings. Technological advancements and increasing demand for cosmetic procedures further support their adoption.
Application Insights
The surgical segment dominated the market and accounted for the largest revenue share in 2024 and is expected to exhibit the fastest growth during the forecast period. Laser systems enhance surgical precision, reduce recovery time, and minimize complications, making them highly preferred by healthcare providers. The rental model enables broader access to advanced surgical lasers without the burden of high capital investment. As surgical procedures shift to outpatient settings and technological advancements continue, the segment is expected to experience the fastest growth throughout the forecast period.
The dentistry segment in the surgical laser rental market is expected to grow steadily due to rising demand for minimally invasive dental procedures and increasing adoption of advanced laser technologies in practices. Lasers are used for soft tissue surgeries, periodontal treatments, cavity preparations, and teeth whitening, offering greater precision and patient comfort. According to the American Dental Association, over 200,000 dentists were practicing in the U.S. as of 2023, with a growing number integrating lasers into routine care. The rental model allows clinics to access costly laser systems without significant upfront investment, driving consistent growth in this segment.
Rental Offering Insights
The long-term rentals segment dominated the market and accounted for the largest revenue in 2024. This dominance is attributed to hospitals and large healthcare facilities opting for extended rental agreements to ensure consistent access to advanced laser systems without capital expenditure. Long-term rentals offer cost-effectiveness, maintenance support, and uninterrupted usage for high-volume procedures. They also provide flexibility in equipment upgrades and compliance with regulatory standards. As surgical demand rises and facilities prioritize operational efficiency, the preference for long-term rental contracts continues to grow, making this segment a key driver of sustained market expansion in the coming years.
The short-term rental segment is projected to grow at the fastest rate in the surgical laser rental market during the forecast period. This growth is driven by increasing demand from outpatient facilities, dermatology clinics, and ambulatory surgical centers (ASCs) that require flexible access to advanced laser systems for specific procedures. Short-term rentals offer cost savings, reduced commitment, and quick access to the latest technologies without long-term contracts. They are ideal for facilities with variable caseloads or seasonal demand. The convenience and scalability of short-term rentals make them an attractive option, fueling rapid adoption and segment growth in the evolving healthcare landscape.
End-use Insights
The inpatient facilities, such as hospitals, dominated the market and accounted for the largest revenue share in 2024. This leadership is driven by hospitals' high surgical volumes, advanced infrastructure, and need for versatile, high-performance laser systems across various specialties such as urology, gynecology, ENT, and oncology. Hospitals prefer long-term rentals to access cutting-edge technologies without the burden of capital investment, ensuring uninterrupted surgical services. The inclusion of maintenance, compliance, and training in rental agreements further supports adoption. As hospitals continue to handle complex and high-risk procedures, their reliance on surgical laser rentals remains a key market driver.
 To learn more about this report, Download Free Sample Report
The outpatient facilities, such as ambulatory centers & specialty clinics segment is expected to grow steadily in the surgical laser rental market due to the increasing shift toward minimally invasive, cost-effective treatments performed outside traditional hospital settings. These facilities benefit from laser rentals, which provide access to advanced technologies without significant capital investment. The rise in same-day procedures in dermatology, urology, ophthalmology, and gynecology supports this trend.
Regional Insights
North America surgical laser rental market dominated the global industry with the largest revenue share of 41.9% in 2024, driven by its advanced healthcare infrastructure and strong uptake of innovative medical technologies. The region’s well-developed healthcare system, combined with growing use of surgical lasers in hospitals and ambulatory centers, supports this dominance. Increasing awareness among both clinicians and patients about the advantages of laser-assisted procedures is also contributing significantly to market expansion.
 To learn more about this report, Download Free Sample Report
U.S. Surgical Laser Rental Market Trends
The surgical laser rental market in the U.S. held the largest share of the North American market in 2024. This leadership is strengthened by innovations such as the FDA 510(k) clearance of Medency’s RAPIDO ENT BLUE laser system, now available across the country. Designed for precision in ENT surgeries, the system reduces thermal damage and enhances surgical accuracy. Utilizing blue laser light, it offers improved outcomes compared to traditional tools like scalpels and KTP lasers. The rising popularity of minimally invasive procedures, supported by faster recovery and reduced discomfort, continues to drive demand. In 2020, over 15.6 million cosmetic procedures reflected this growing trend.
Europe Surgical Laser Rental Market Trends
The surgical laser rental market in Europe is experiencing significant growth, primarily due to the rising prevalence of eye disorders, especially in countries like Germany and the UK. According to the European Society of Cataract and Refractive Surgeons (ESCRS), the use of laser-assisted cataract surgeries is increasing, offering faster recovery and fewer complications than traditional techniques. Studies also indicate a strong preference for procedures that reduce discomfort and promote quicker healing. Additionally, initiatives like ERN-EYE, focusing on rare eye diseases, are enhancing awareness and access. This increasing shift toward laser-assisted surgeries is driving greater demand for surgical lasers across Europe.
The UK surgical laser rental market is advancing steadily, supported by strong domestic manufacturers like Lynton, the UK’s top laser and IPL device producer. Founded in 1994 through University of Manchester research, Lynton has earned NHS Supply Chain recognition and leads in medical-grade aesthetic laser systems. Their rental offerings empower clinics with award-winning, scientifically backed equipment and extensive support services. Lynton’s commitment to clinical excellence and training has positioned it as a trusted partner across both private and NHS clinics.
The surgical laser rental market in Germany is expanding due to its growing elderly population, which contributes to higher rates of chronic conditions like diabetes and heart disease. According to the Federal Statistical Office, the proportion of those aged 65 and above is set to increase significantly, intensifying the need for laser-assisted surgical procedures. This demographic trend underscores the demand for minimally invasive and efficient treatment methods, encouraging hospitals and clinics to opt for rental solutions that offer advanced laser technologies. As a result, the aging population continues to be a key driver of market growth in the country.
Asia Pacific Surgical Laser Rental Market Trends
The surgical laser rental market in Asia Pacific is expected to show the fastest CAGR, driven by rising healthcare investments, expanding medical tourism, and increasing demand for minimally invasive procedures. Countries like China, India, Japan, and South Korea are witnessing rapid adoption of advanced laser technologies in fields such as dermatology, ophthalmology, and gynecology. A growing middle-class population, higher awareness of aesthetic procedures, and favorable government initiatives are further fueling this trend. Additionally, the cost-effectiveness and flexibility of renting over purchasing surgical lasers make it an attractive option for hospitals and outpatient centers across the region, accelerating market expansion.
China’s surgical laser rental market is witnessing robust growth due to demographic changes, particularly the rise in its elderly population. In 2023, around 297 million people in China were aged 60 or older, representing 21.1% of the population. The World Health Organization projects this figure to climb to 28% by 2040.
Latin America Surgical Laser Rental Market Trends
The surgical laser rental market in Latin America is growing steadily due to rising demand for minimally invasive procedures and increasing healthcare investments. Countries like Brazil and Argentina are witnessing a surge in cosmetic and ophthalmic laser surgeries. Public and private healthcare institutions are adopting laser technologies for cost-effective treatment solutions without full equipment ownership. The growing medical tourism industry, particularly in Brazil, further supports market growth. Additionally, the region’s increasing geriatric population and chronic disease burden are driving demand for advanced surgical solutions, with laser rentals offering flexible, budget-conscious alternatives for healthcare providers seeking modern technologies.
Middle East Africa Surgical Laser Rental Market Trends
The surgical laser rental market in the Middle East and Africa is growing rapidly due to rising chronic disease rates, increased demand for aesthetic procedures, and expanding healthcare investments. Countries like the UAE, Kuwait, Saudi Arabia, and South Africa are embracing advanced technologies like surgical lasers. For instance, in May 2024, Saudi German Hospital Aseer successfully used MALDI-TOF laser technology to rapidly diagnose and treat a complex mitral valve infection, showcasing the region’s commitment to innovation. Such cases highlight the value of minimally invasive laser solutions. As healthcare systems evolve and medical tourism thrives, surgical laser rentals offer a cost-effective, flexible alternative to permanent equipment investments.
Key Surgical Laser Rental Company Insights
Key players operating in the surgical laser rental market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Surgical Laser Rental Companies:
The following are the leading companies in the surgical laser rental market. These companies collectively hold the largest market share and dictate industry trends.
- HealthTronics, Inc.
- Advanced Surgical Technologies
- LASErent
- Southland Surgical Laser Rental
- Southeast Laser Systems, Inc.
- Mobile Med Surgical Inc.
- Laser Surgical of Florida, Inc.
- Lynton Surgical
- Phoxton
- Laser 2000 GmbH
Recent Developments
-
In May 2025, Laser 2000 launched a new subsidiary in Bolzano, Italy, to enhance regional support and responsiveness across Europe. This expansion reflects its decentralized strategy, boosting customer proximity, agility, and innovation. The move, including offices in Sweden and Italy, strengthens one of Europe’s most experienced photonics distribution networks for tailored, application-specific solutions.
-
In May 2025, U.S. Med-Equip opened a new Tucson branch to expand medical equipment rental services across Arizona and New Mexico. The facility offers hospitals quick access to critical care devices like ventilators and monitors, enabling faster response to patient needs while controlling costs. It supports 24/7 operations and is actively hiring locally.
Surgical Laser Rental Market Report Scope
Report Attribute
Details
Market size in 2024
USD 10.3 billion
Estimated market size in 2026
USD 11.9 billion
Projected market size by 2033
USD 19.5 billion
Growth rate
CAGR of 7.3% from 2025 to 2033
Base year for estimation
2024
Historical data
2021 - 2024
Forecast period
2025 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2025 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, rental offering, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; and Middle East & Africa (MEA)
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; Kuwait; UAE
Key companies profiled
HealthTronics, Inc.; Advanced Surgical Technologies; LASErent; Southland Surgical Laser Rental; Southeast Laser Systems, Inc.; Mobile Med Surgical Inc.; Laser Surgical of Florida, Inc.; Lynton Surgical; Phoxton; Laser 2000 GmbH
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Surgical Laser Rental Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global surgical laser rental market report on the basis of type, application, rental offering, end-use and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Solid State Lasers
-
Thulium Fiber Lasers (TFLs)
-
Holium:YAG (Ho:YAG) Lasers
-
Neodymium Yttrium Aluminum Garnet (Nd: YAG Lasers)
-
Erbium Yttrium Aluminum Garnet (Er: YAG Lasers)
-
Ruby Laser Systems
-
Others
-
-
Gas Laser System
-
CO2
-
Excimer
-
Helium
-
Others
-
-
Diode Laser System
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Surgical
-
Urology Surgery
-
Gynecology Surgery
-
ENT/Otolaryngology
-
General Surgery
-
Others
-
-
Dentistry
-
Ophthalmology
-
-
Rental Offering Outlook (Revenue, USD Million, 2021 - 2033)
-
Short Term Rentals
-
Long Term Rentals
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Inpatient Facilities
-
Outpatient Facilities
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
Frequently Asked Questions About This Report
Key factors that are driving the surgical laser rental market growth include increasing preference for minimally invasive surgeries, rising procedure volumes, and the high upfront cost of laser systems, encouraging facilities to choose rental options.
The global surgical laser rental market size was valued at USD 10.3 billion in 2024 and is estimated at USD 11.9 billion for 2026.
The solid state lasers segment held the largest share of 58.4% in the surgical laser rental market in 2024. This dominance is driven by their high precision, compact design, and reliability across various surgical procedures. Additionally, their cost-effectiveness and lower maintenance make them ideal for rental services.
Some key players operating in the surgical laser rental market include HealthTronics, Inc., Advanced Surgical Technologies, LASErent, Southland Surgical Laser Rental, Southeast Laser Systems, Inc., Mobile Med Surgical Inc., Laser Surgical of Florida, Inc., Lynton Surgical, Phoxton, Laser 2000 GmbH
The global surgical laser rental market is expected to grow at a CAGR of 7.3% from 2025 to 2033, reaching USD 19.5 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


