
- Home
- »
- Medical Devices
- »
-
Surgical Wound Care Market Size, Share Report, 2027-2035GVR Report cover

Surgical Wound Care Market (2027 - 2035)
Size, Share & Trends Analysis Report By Product (Wound Closure Products, Tissue Sealants, Surgical Wound Dressings, Negative Pressure Wound Therapy (NPWT)), By Surgery Type, By End Use, By Region And Segment Forecasts
Market Size, 2026
$5.4BMarket Estimate, 2027
$5.6BMarket Forecast, 2035
$8.0BCAGR, 2027–2035
4.5%Surgical Wound Care Market Summary
The global surgical wound care market size was valued at USD 5.4 billion in 2026 and is projected to grow from USD 5.6 billion in 2027 to USD 8.0 billion by 2035, at a CAGR of 4.5% from 2027 to 2035. North America dominated the market, accounting for a revenue share of 38.3% in 2025. The market is primarily driven by the rising number of surgical procedures worldwide, the increasing prevalence of chronic diseases, and the growing demand for effective surgical site infection prevention. In addition, advancements in wound dressing technologies, increasing adoption of advanced wound care products, and growing emphasis on faster wound healing and reduced hospital stays are supporting market growth.
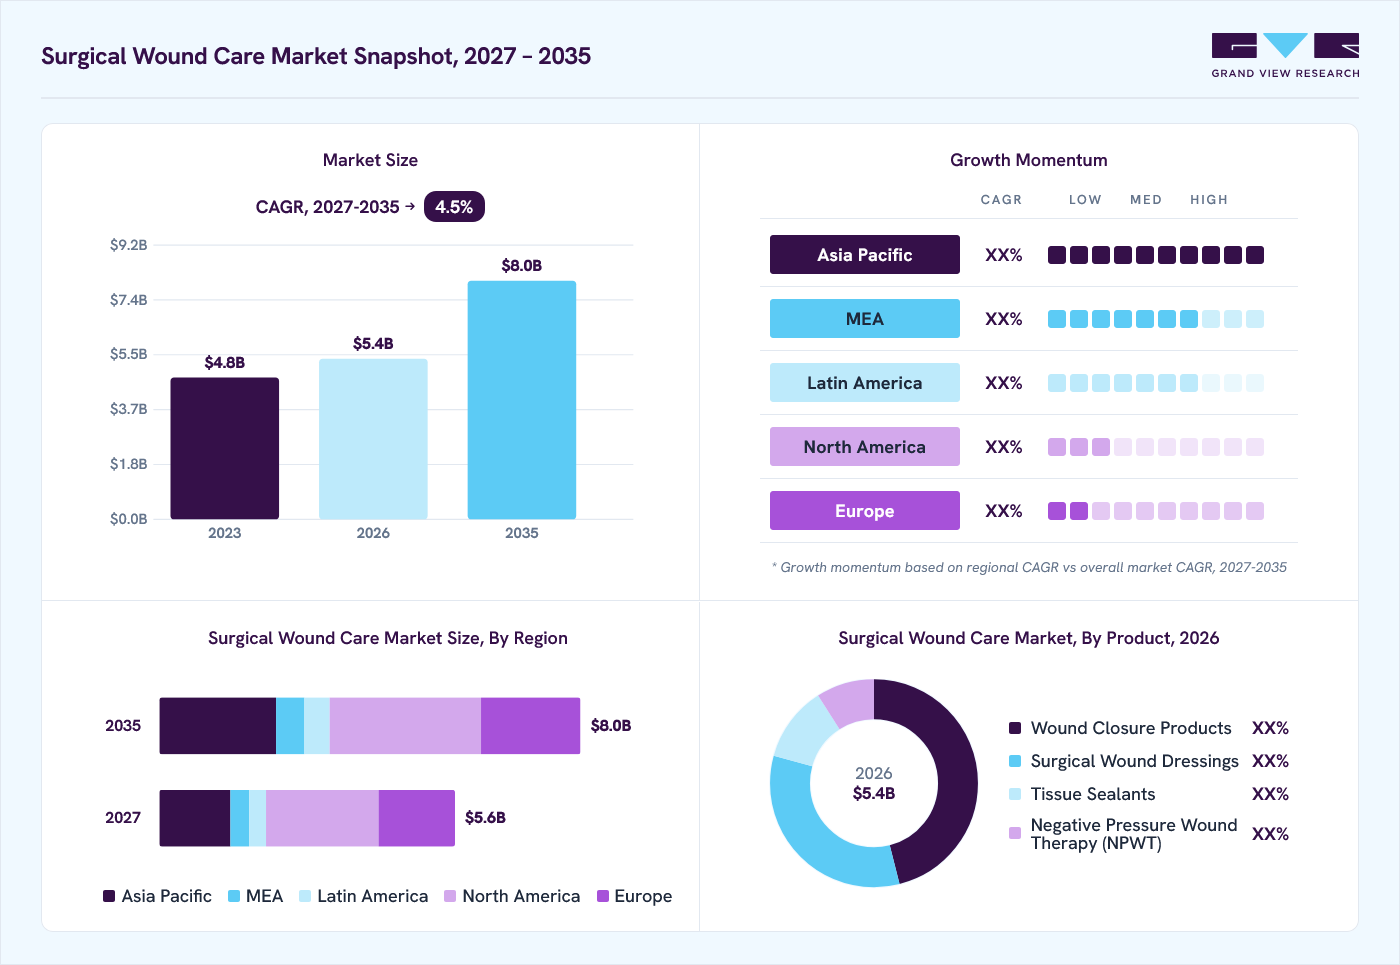 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Wound closure products segment dominated the market, with a revenue share of 46.0% in 2026.
- By surgery type: General surgeries segment held the largest market share of 29.5% in 2026.
- By end use: Hospitals segment accounted for the largest share of 57.3% in 2026.
Regional Highlights
- Largest regional market: North America (38.3% revenue share, 2026)
- Fastest growing market: Asia Pacific (highest CAGR, 2027-2035)
- By country: The U.S. held the largest share in the North America region in 2026.
Market Size & Forecast
- Market Size in 2026: USD 5.4 Billion
- Estimated Market Size in 2027: USD 5.6 Billion
- Projected Market Size by 2035: USD 8.0 Billion
- CAGR (2027-2035): 4.5%
Prism AI by Grand View Research Free to tryAsk a question about the surgical wound care marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →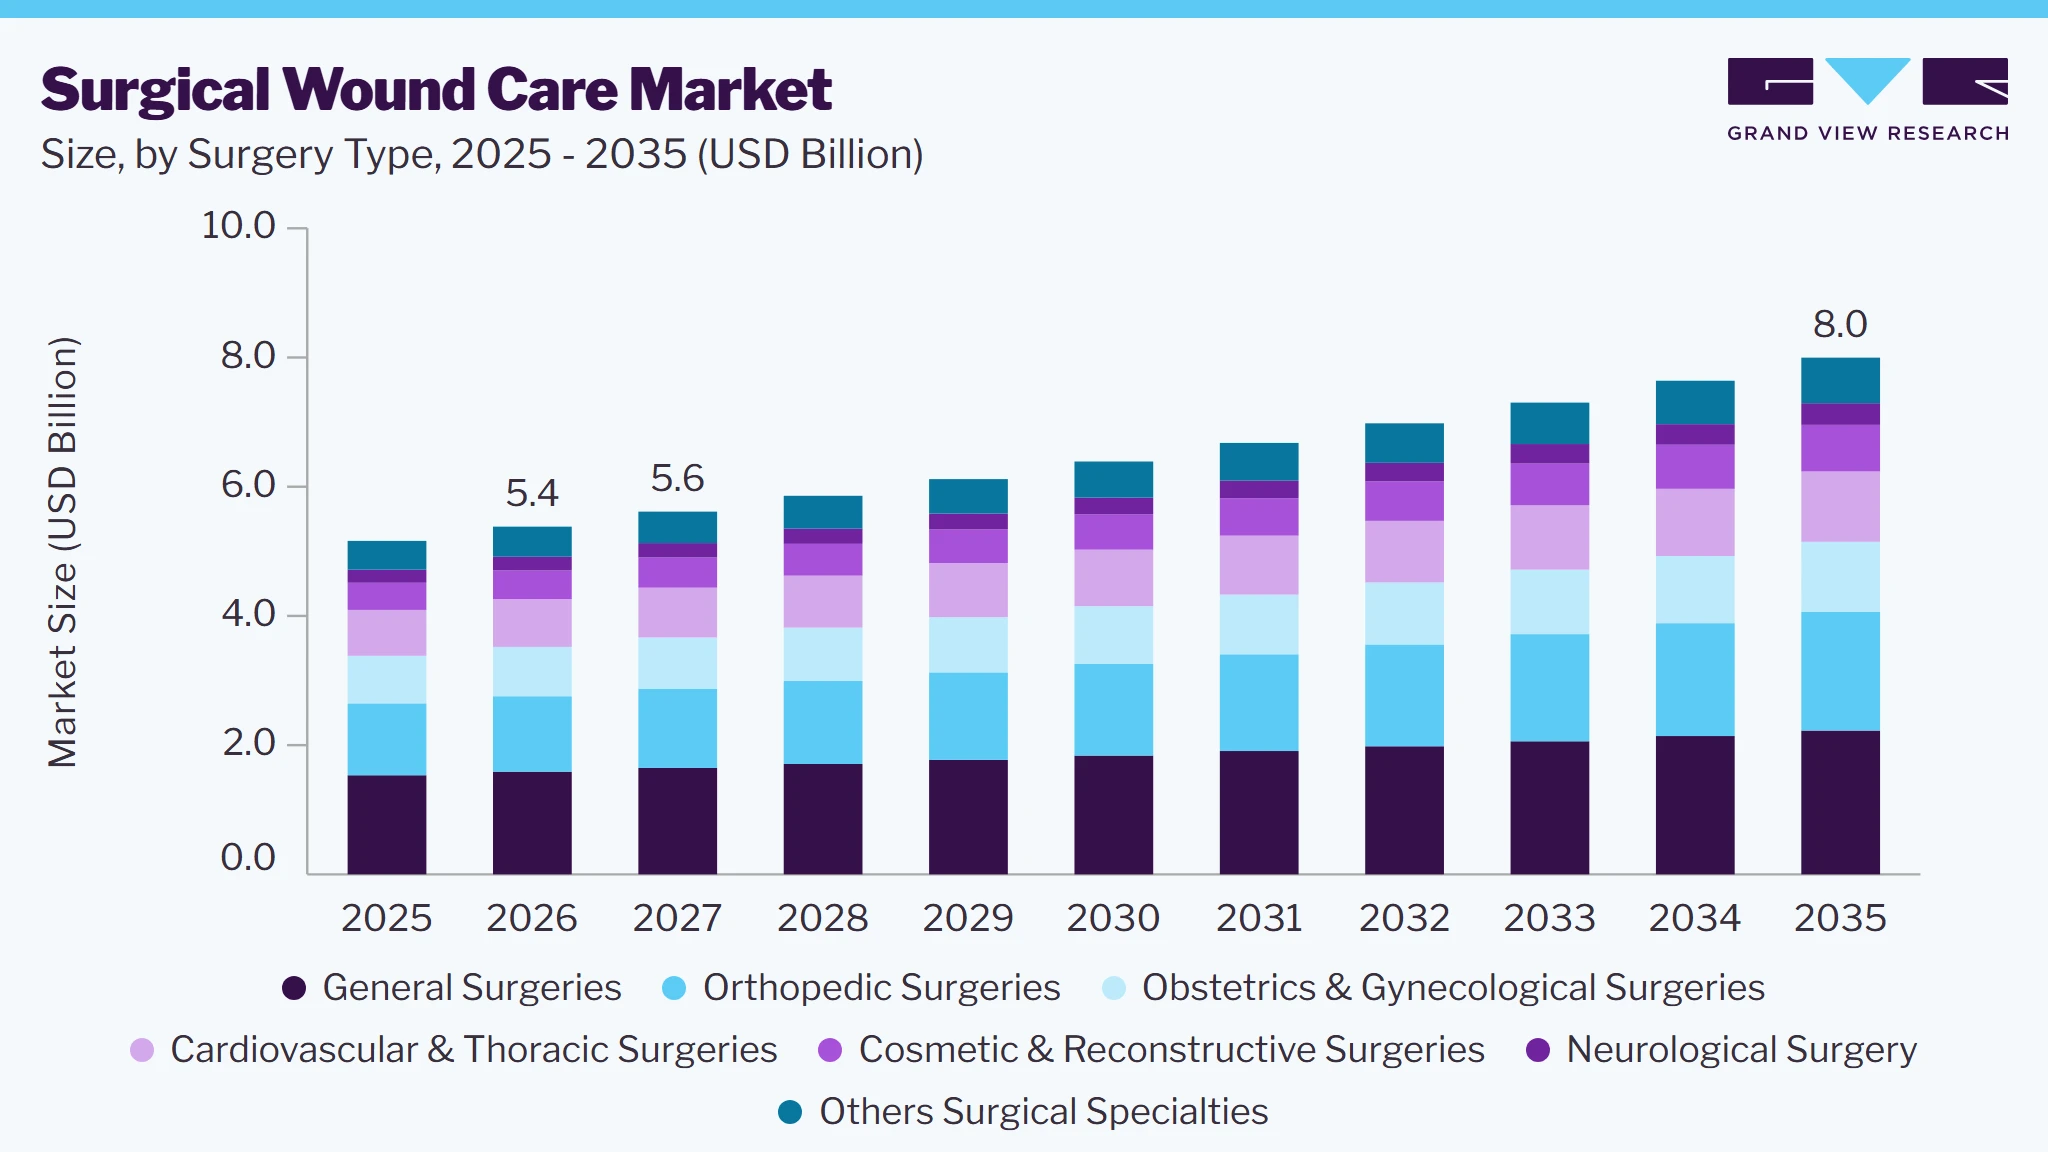 To learn more about this report, Download Free Sample Report
The increasing number of surgical procedures worldwide is driving demand for surgical wound care products, including sutures, surgical dressings, wound closure devices, and advanced wound management solutions. The growing prevalence of chronic diseases, rising geriatric population, expanding access to healthcare services, and advancements in minimally invasive and complex surgical techniques are contributing to higher surgical volumes. As a result, hospitals and surgical centers require effective wound management solutions to promote faster healing, prevent surgical site infections (SSIs), and minimize postoperative complications, thereby supporting the growth of the surgical wound care market.
 To learn more about this report, Download Free Sample Report
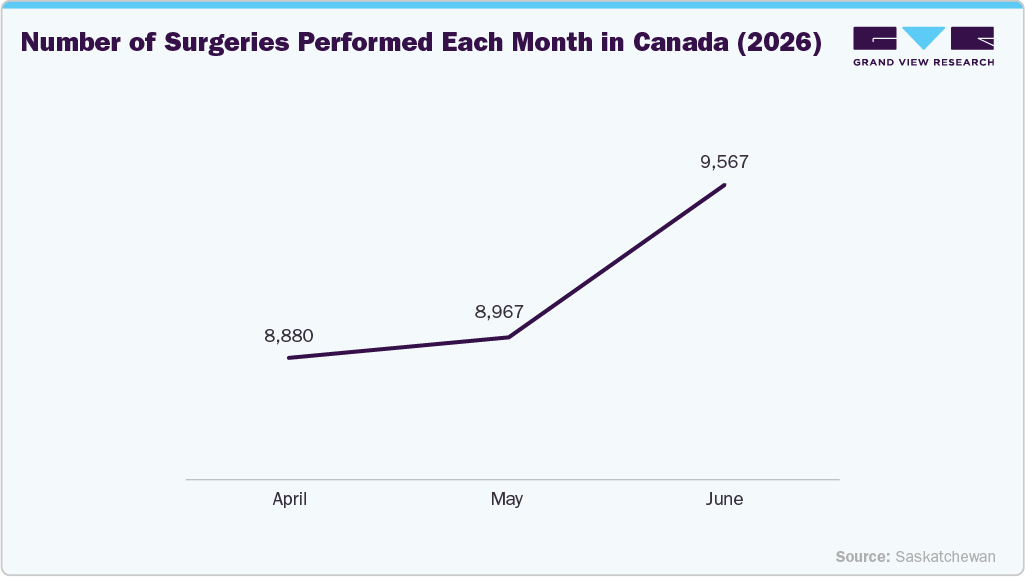
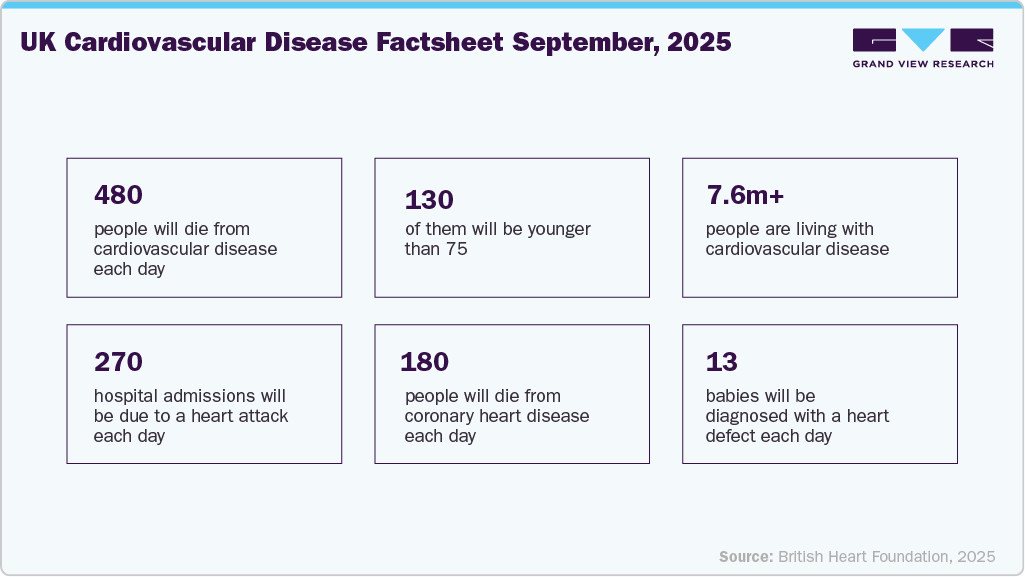
The rising prevalence of cardiovascular diseases is increasing the number of surgical interventions, including coronary artery bypass grafting, heart valve replacement, and other cardiac procedures. This is driving demand for surgical wound care products to manage post-operative incisions, prevent surgical site infections, and promote effective wound healing.
 To learn more about this report, Download Free Sample Report
The growing emphasis on preventing surgical site infections (SSIs) is driving the adoption of advanced surgical wound care products, including antimicrobial dressings, wound closure devices, and infection-control solutions. Healthcare providers are prioritizing effective postoperative wound management to reduce infection risks, minimize hospital readmissions, shorten recovery periods, and improve patient outcomes, thereby supporting the growth of the surgical wound care market. For instance, in July 2026, the European Center for Disease Prevention and Control (ECDC) reported 6,254 surgical site infections (SSIs) across 421,397 surgical procedures monitored in 12 EU Member States and one EEA country during 2023. SSI rates ranged from 0.4% for laminectomy procedures to 10.2% for open colon surgery, highlighting the continued need for effective surgical wound infection prevention and management solutions.
Surgical Site Infection (SSI) Statistics Across EU Member States and EEA Countries, 2023
Parameter
Statistics / Findings
Countries Reporting
12 EU Member States and 1 EEA country
Total Number of SSIs Reported
6,254
Total Surgical Procedures Monitored
421,397
Types of Surgical Procedures Covered
9
Lowest SSI Rate
0.4% for laminectomy procedures
Highest SSI Rate
10.2% for open colon surgery
In-Hospital SSI Incidence Density
0.1-5.7 SSIs per 1,000 postoperative patient-days
Source: European Centre for Disease Prevention and Control (ECDC) 2026
Market Dynamics
The surgical wound care market is influenced by the growing volume of surgical procedures, rising incidence of surgical site infections, and increasing demand for advanced wound management solutions. Technological advancements in antimicrobial dressings, hydrocolloids, foam dressings, and smart wound care products are creating new growth opportunities. However, high costs of advanced wound care products, pricing pressures, and stringent regulatory requirements may restrict market expansion. Increasing focus on infection prevention, faster wound healing, and improved patient outcomes continue to shape the competitive landscape.
The rising volume of surgical procedures across major specialties, including cardiovascular, orthopedic, general, and oncology surgeries, is driving demand for surgical wound care products. Increasing surgical interventions are creating a greater need for effective wound dressings, antimicrobial solutions, and post-operative wound management to prevent infections and promote faster healing. In addition, the growing number of elective and minimally invasive procedures is supporting the adoption of advanced surgical wound care solutions.
The high cost of advanced surgical dressings and incision management products, including antimicrobial dressings, negative pressure wound therapy (NPWT) systems, and silver- or silicone-based dressings, acts as a significant restraint on market growth. These products often involve higher acquisition and treatment costs compared with conventional gauze dressings, limiting their adoption in cost-sensitive healthcare settings and developing markets. In addition, budget constraints, limited reimbursement coverage, and the need for frequent dressing replacements can increase overall treatment expenditure, restricting widespread adoption of advanced surgical wound care solutions.
The development of smart surgical dressings with real-time incision monitoring presents a significant growth opportunity in the surgical wound care market. Integration of advanced sensors, wireless connectivity, and digital monitoring technologies enables continuous tracking of wound parameters such as temperature, moisture, pH levels, and signs of infection. These innovations can facilitate early detection of post-operative complications, reduce surgical site infection risks, and support timely clinical interventions. Growing adoption of digital healthcare solutions and remote patient monitoring is expected to create opportunities for manufacturers to develop differentiated, technology-enabled surgical wound care products.
For instance, in March 2026,
• Researchers at RMIT University (Australia) developed a smart hydrogel dressing incorporating multifunctional carbon dots.
• The technology combines wound monitoring and therapeutic delivery within a single dressing platform, supporting infection monitoring and wound healing.
• This development demonstrates opportunities for multifunctional surgical dressings that combine treatment with real-time wound assessment.
Furthermore,
• Researchers at Pennsylvania State University (U.S.) developed a sensor-based wound monitoring system capable of detecting multiple biomarkers associated with infection and inflammation.
• The system measures pH, uric acid, phenazine-1-carboxylic acid, and interleukin-6 (IL-6).
• Wireless data transmission to a mobile application enables real-time monitoring and may support early identification of post-operative wound complications.
Market Concentration & Characteristics
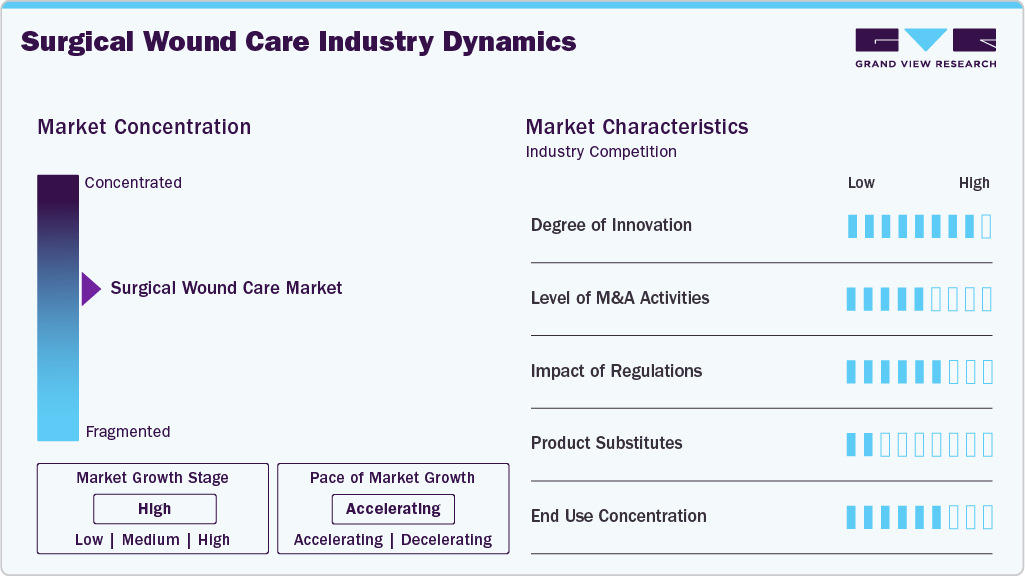
The surgical wound care market demonstrates moderate to high innovation, driven by advancements in antimicrobial dressings, NPWT, silicone-based materials, and smart wound monitoring technologies. Manufacturers are increasingly developing multifunctional dressings with biosensors, bioactive materials, and moisture-management capabilities to improve infection prevention, wound healing, and post-operative patient outcomes. For instance, in July 2026, BRIJ Medical announced the commercial launch of BRIJ-SEAL, an advanced wound closure device designed to address the growing need for simple and efficient post-operative incision management. The product utilizes hypoallergenic adhesive technology to provide effective coverage and protection of surgical incisions.
"Surgeons have been clear about what they want: a solution that's fast, easy to apply, effectively covers and protects the incision, and doesn't compromise patient comfort with adhesive-related skin reactions," said Tim Gleeson, CEO of BRIJ Medical.
 To learn more about this report, Download Free Sample Report
The market experiences moderate to high M&A activity, driven by companies seeking to expand product portfolios, acquire innovative wound care technologies, and strengthen geographical presence. Strategic acquisitions are enabling manufacturers to enhance capabilities in antimicrobial dressings, regenerative materials, and advanced incision management while strengthening their competitive positioning. For instance, in June 2025, Gentell announced the acquisition of Casex, a leading Latin American manufacturer of ostomy and wound care products. Following the acquisition, Casex was rebranded as Gentell, with its products distributed under the Gentell brand name, strengthening the company's presence in the Latin American wound care market.
"Gentell's acquisition of Casex facilitates and enhances our growth in South America by taking advantage of existing relationships and product registrations, while at the same time enabling opportunities in the U.S. to expand our ostomy product line." said David Navazio, Gentell President & CEO.
Regulations have a moderate to high impact on the surgical wound care market, as manufacturers must meet stringent safety, efficacy, quality, and clinical validation requirements before commercializing products. FDA clearance, EU MDR compliance, and medical device registration requirements influence product development costs, approval timelines, and market entry. While regulatory compliance can increase operational expenses and delay product launches, it also ensures product safety, improves clinical confidence, and encourages the development of high-quality surgical wound care solutions.
The surgical wound care market exhibits high end-use concentration in hospitals, as these facilities account for a significant share of surgical procedures, including cardiovascular, orthopedic, general, and oncology surgeries. Ambulatory surgical centers (ASCs) are also gaining importance due to the increasing shift toward outpatient and minimally invasive procedures. In addition, specialty clinics and home healthcare settings contribute to market demand through post-operative wound management, dressing changes, and incision monitoring.
Analyst Perspective
The surgical wound care market is expected to witness significant growth, driven by increasing surgical procedure volumes, rising emphasis on surgical site infection prevention, and growing adoption of advanced wound management solutions. The market is gradually shifting from conventional gauze dressings toward antimicrobial dressings, advanced incision management products, and closed-incision negative pressure wound therapy (ciNPWT). Continuous innovation in smart dressings, bioactive materials, and skin-friendly wound closure technologies is expected to create new growth opportunities. Competition will increasingly depend on product differentiation, clinical evidence, pricing strategies, and strong hospital distribution networks.
Product Insights
The wound closure products segment dominated the surgical wound care market with a market revenue share of 46.0% in 2026, supported by the essential role of sutures, surgical staples, tissue adhesives, and sealants across various surgical procedures. Their widespread use in approximating tissue edges, securing incisions, and supporting post-operative healing sustains demand across hospitals and ambulatory surgical centers. The established clinical use of these products and their applicability across multiple surgical specialties continue to support segment dominance.
The tissue sealants segment is expected to register the fastest growth in the surgical wound care market during the forecast period, driven by increasing adoption of fibrin sealants, synthetic adhesives, and other advanced sealing technologies across surgical specialties. These products support tissue adhesion, control bleeding, and minimize fluid leakage, offering alternatives or complements to conventional sutures and staples. Growing demand for minimally invasive procedures, faster surgical closure, and improved post-operative wound management is expected to accelerate segment growth.
Surgery Type Insights
The general surgeries segment dominated the surgical wound care market with a market revenue share of 29.5% in 2026, driven by the high volume of procedures such as appendectomies, hernia repairs, laparotomies, and gastrointestinal surgeries. These procedures frequently require effective incision closure, post-operative dressings, and infection prevention solutions to support wound healing. Increasing demand for surgical interventions and the widespread use of wound closure products and advanced dressings across general surgical procedures continue to support the segment's leading position.
The cosmetic and reconstructive surgeries segment is expected to register the fastest growth in the surgical wound care market during the forecast period, driven by increasing demand for aesthetic procedures, breast reconstruction, scar revision, and post-traumatic tissue repair. Growing adoption of advanced surgical techniques and rising patient preference for improved aesthetic outcomes are increasing the need for specialized wound closure products and advanced dressings. Additionally, the increasing volume of reconstructive procedures following cancer treatment, burns, and traumatic injuries is expected to support segment growth. According to the American Society of Plastic Surgeons, more than 1 million reconstructive procedures were performed in the U.S. in 2024.
End Use Insights
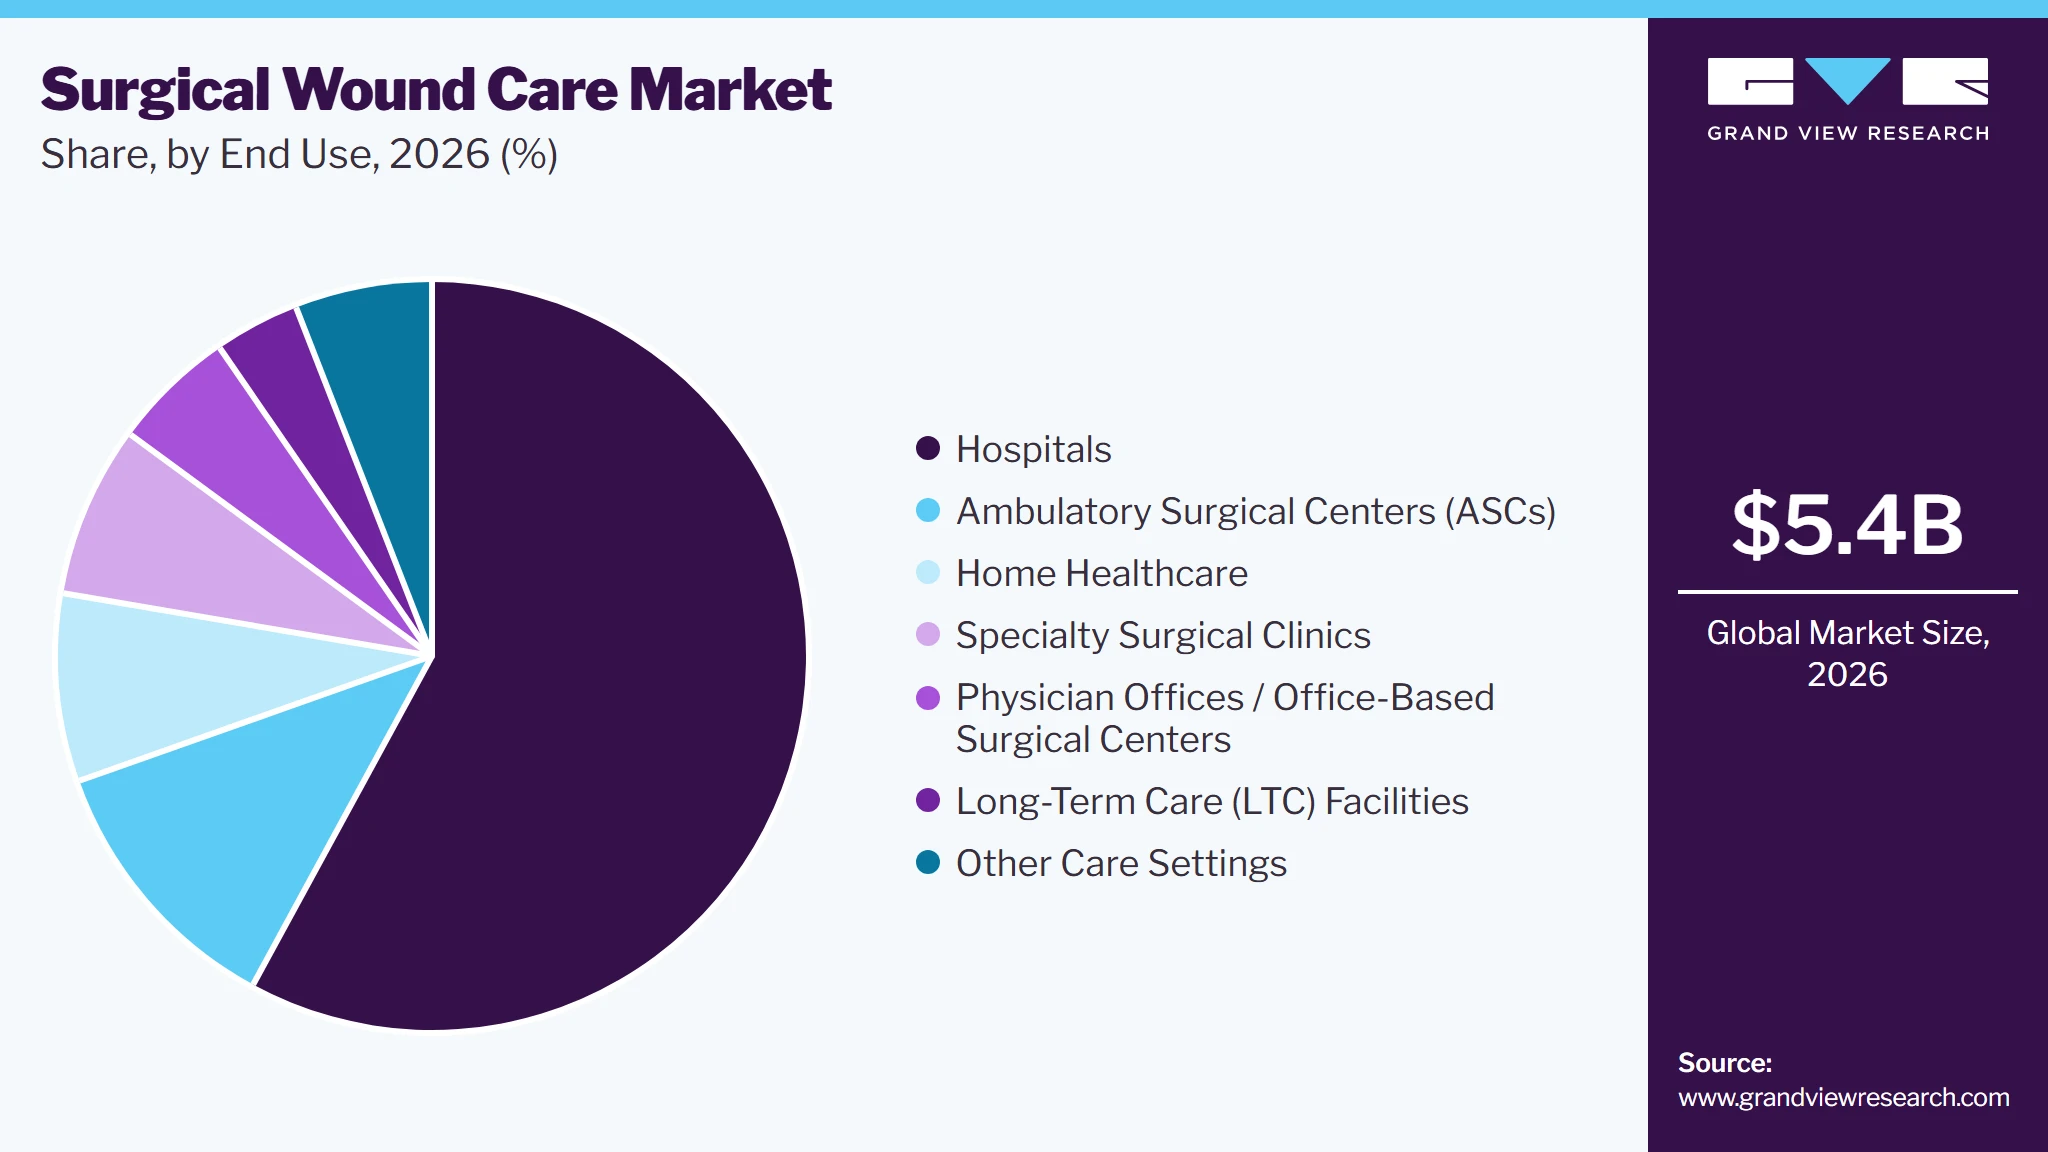
The hospitals segment dominated the surgical wound care market with a market share of 57.9% in 2026, driven by the high concentration of complex, emergency, and elective surgical procedures performed in hospital settings. Hospitals require substantial volumes of wound closure products, advanced dressings, antimicrobial solutions, and incision management systems for post-operative care. In addition, the availability of specialized surgical teams, operating facilities, and post-operative monitoring services supports hospitals' leading position in end-use demand.
 To learn more about this report, Download Free Sample Report
The home healthcare segment is expected to register the fastest growth in the surgical wound care market during the forecast period, driven by the increasing shift toward post-operative care and wound management at home. Growing preference for early hospital discharge, cost-effective treatment, and personalized nursing services is increasing demand for surgical dressings, wound closure products, and infection prevention solutions in home settings. In addition, advancements in remote wound monitoring and home-based healthcare services are expected to accelerate segment growth.
Regional Insights
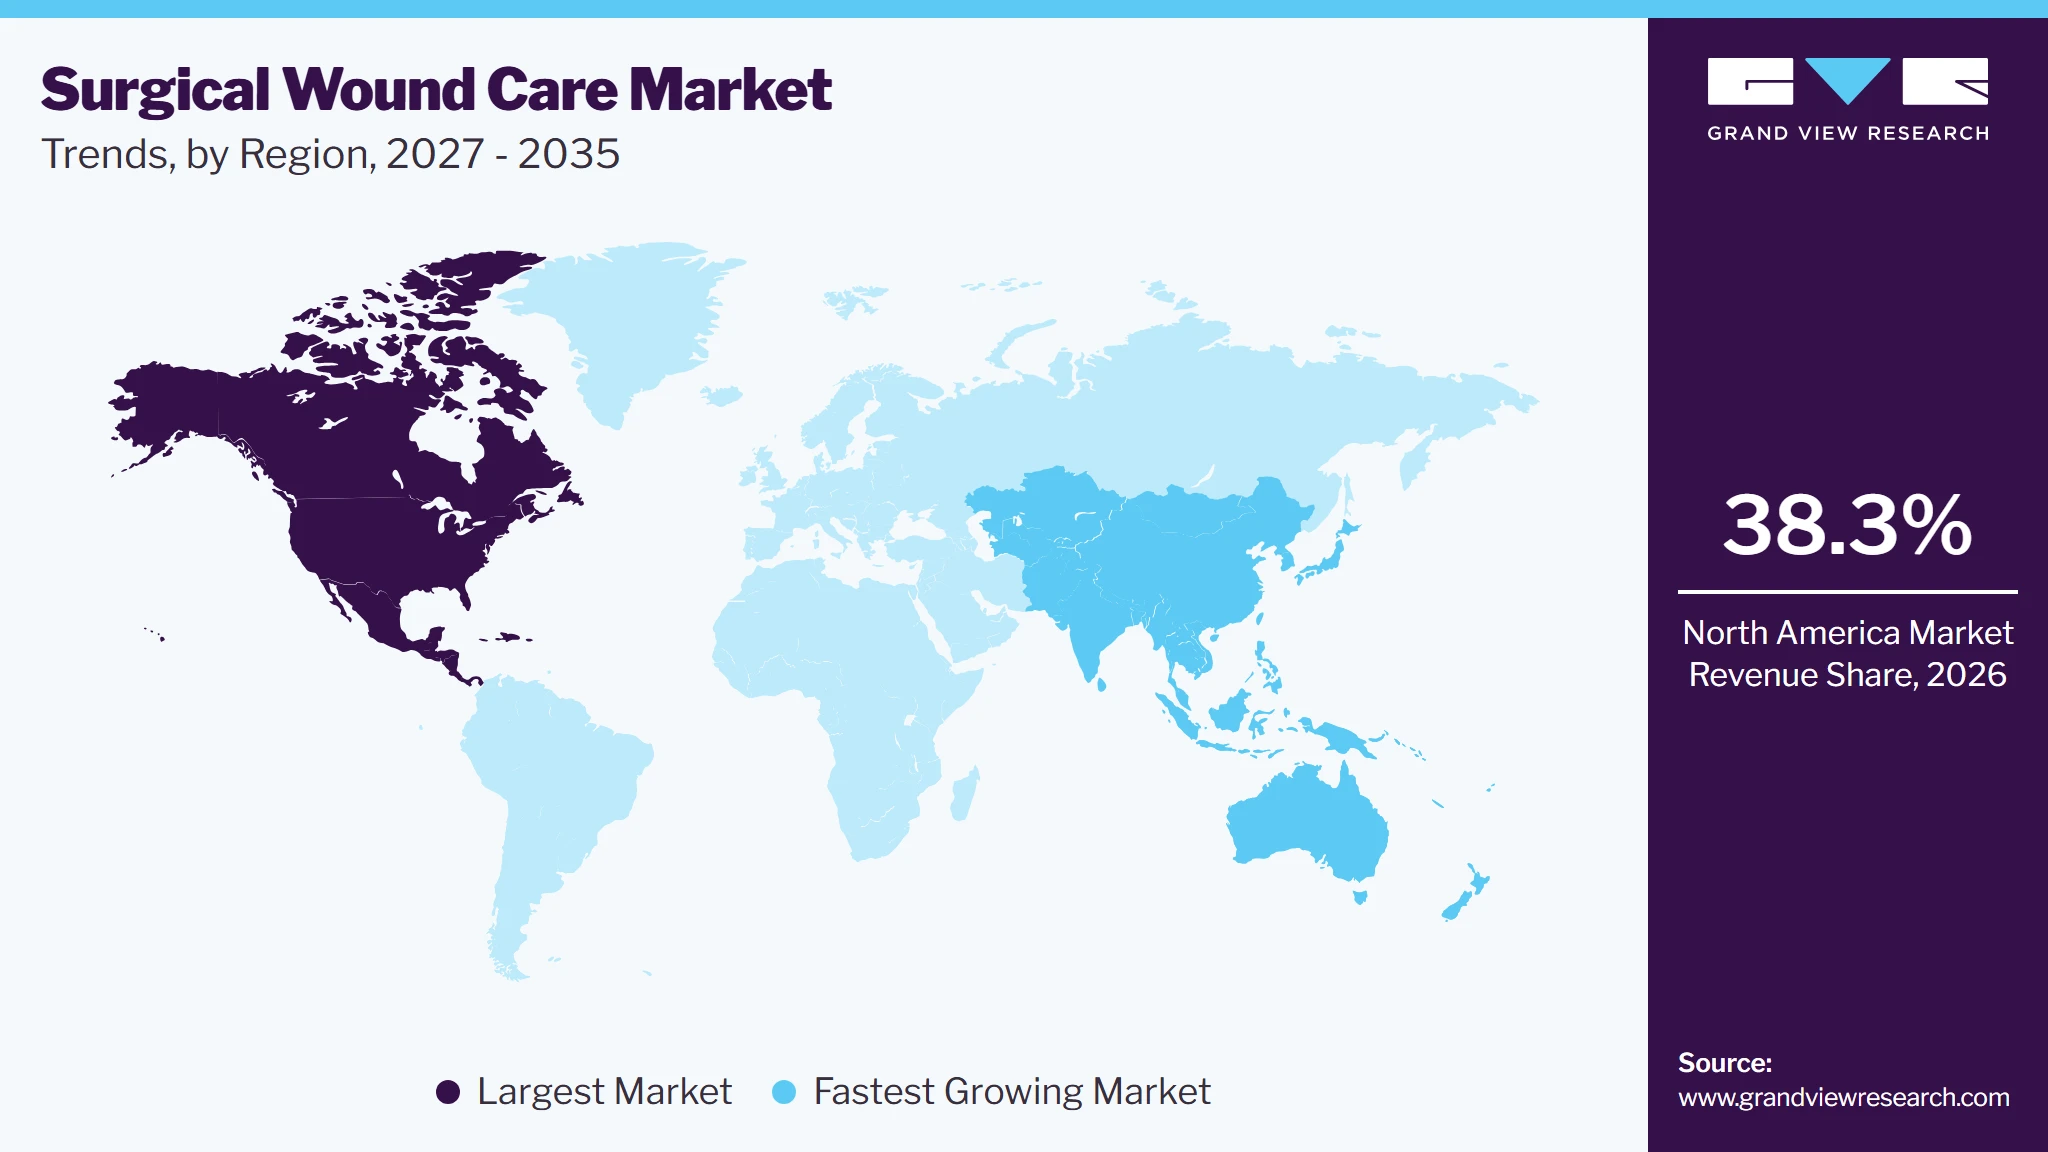
North America dominated the surgical wound care market with the largest revenue share of 38.3% in 2026. The market is witnessing strong growth driven by advanced healthcare infrastructure, high surgical volumes, and widespread adoption of advanced wound management products. The U.S. CDC’s 2024 National Healthcare-Associated Infections Progress Report, released in July 2026, reported a 4% decline in surgical site infections following colon surgery, while abdominal hysterectomy-associated infections increased by 8% compared with 2023. This continued focus on infection prevention supports demand for antimicrobial dressings and advanced incision management solutions.
 To learn more about this report, Download Free Sample Report
U.S. Surgical Wound Care Market Trends
The U.S. surgical wound care market is driven by high surgical activity, established reimbursement infrastructure, and increasing emphasis on post-operative infection prevention. According to the CDC, approximately 518,000 healthcare-associated infections occurred in U.S. acute care hospitals in 2023, with surgical site infections among the most common categories. This creates demand for antimicrobial dressings, surgical sealants, wound closure products, and advanced incision protection technologies.
Europe Surgical Wound Care Market Trends
Europe represents an established market for surgical wound care, supported by well-developed hospital infrastructure, increasing adoption of minimally invasive procedures, and stringent infection prevention standards. According to Eurostat, approximately 5.01 million cataract surgeries were performed across the EU in 2023, while 791,000 knee replacements and 455,500 appendectomies were also recorded. These procedure volumes support demand for surgical dressings, wound closure products, and post-operative incision management solutions.
The UK surgical wound care market is supported by NHS surgical capacity expansion, growing elective procedure volumes, and increasing focus on reducing hospital waiting lists. According to NHS England, healthcare providers delivered a record 18.4 million treatments and operations in 2025, compared with 18 million in 2024. The expansion of surgical hubs and outpatient procedures is expected to support demand for surgical dressings, tissue adhesives, and advanced wound closure products.
The French surgical wound care market benefits from an established hospital network, increasing surgical activity, and the growing adoption of outpatient surgical procedures. Publicly sourced French healthcare activity data indicate that approximately 6.96 million surgical stays were recorded in 2025, representing a 12.5% increase compared with 2021, with ambulatory procedures accounting for 65.1%. This shift toward outpatient surgery supports demand for convenient incision protection, advanced dressings, and home-based post-operative wound management.
Asia Pacific Surgical Wound Care Market Trends
The Asia Pacific surgical wound care market is expected to experience fastest growth, driven by expanding healthcare infrastructure, rising surgical volumes, increasing medical tourism, and improving access to healthcare services in China, India, and Japan. Government-supported healthcare initiatives and investments in hospital infrastructure are increasing access to surgical interventions. In India, the Ministry of Health’s 2025-26 reporting highlighted the expansion of surgical services under the Ayushman Bharat and national healthcare initiatives, supporting the long-term demand for surgical wound management products.
The Japan surgical wound care market is supported by an aging population, advanced surgical infrastructure, and widespread adoption of advanced surgical technologies. According to the Japan Surgical Society’s 2024 National Clinical Database report, the registry covered more than 95% of surgeries performed in Japan, with participation expanding to 5,802 institutions by 2025. The substantial surgical database and increasing focus on clinical quality support demand for advanced wound closure, infection prevention, and post-operative wound management solutions.
Latin America Surgical Wound Care Market Trends
The Latin American surgical wound care market is witnessing increasing opportunities due to expanding public healthcare programs, rising surgical accessibility, and investments in hospital infrastructure. Brazil’s Ministry of Health reported a record 14.9 million elective surgeries in 2025 under its public healthcare system (SUS), reflecting increased access to surgical treatment. This expansion is expected to support demand for conventional and advanced surgical dressings, sutures, tissue sealants, and infection prevention products across the region.
MEA Surgical Wound Care Market Trends
The MEA surgical wound care market is gradually expanding, supported by healthcare infrastructure development, increasing hospital capacity, and government-led healthcare modernization initiatives. Saudi Arabia’s Ministry of Health reported that surgical capacity across health clusters increased from an average of 6,000 procedures per week to 12,000 in 2025, while 90% of surgeries were performed within standard timeframes. These developments are creating opportunities for surgical wound dressings, advanced closure systems, and post-operative infection management products.
Key Surgical Wound Care Company Insights
The Surgical Wound Care Market is moderately fragmented, with key players such as 3M, Smith+Nephew, Mölnlycke Health Care, ConvaTec, Solventum, and Johnson & Johnson competing through broad product portfolios and technological innovation. No single manufacturer dominates the overall market, as market shares are distributed across multinational companies and specialized wound care manufacturers, with competition driven by product differentiation, clinical performance, and distribution reach.
Key Surgical Wound Care Companies
The following key companies have been profiled for this study on the surgical wound care market.
-
Solventum
-
Smith & Nephew plc
-
Mölnlycke Health Care
-
Johnson & Johnson (Ethicon)
-
Baxter International
-
Medtronic
-
Cardinal Health
-
Coloplast
-
Convatec Group plc
-
B. Braun SE
-
Essity
-
Paul Hartmann AG
-
Integra LifeSciences
-
URGO Medical
-
Medline Industries
-
DeRoyal Industries
-
Advanced Medical Solutions Group
-
Winner Medical Co., Ltd.
-
Lohmann & Rauscher (L&R)
-
Hollister Incorporated
Recent Developments
-
In September 2026, Mölnlycke announced its intention to separate its Operating Room Solutions (ORS) and Gloves businesses into a new standalone entity, Mölnlycke Surgical. The strategic separation aims to enable both businesses to strengthen their operational focus, unlock growth opportunities, and drive long-term value creation.
-
In March 2026, Smith+Nephew, a global medical technology company, announced the launch of its ALLEVYN COMPLETE CARE Foam Dressing, incorporating proprietary technologies and supported by scientific data and clinical evidence to enhance wound management and patient care.
-
In July 2026, BRIJ Medical announced the commercial launch of BRIJ-SEAL, an advanced wound closure device designed to provide a simple and efficient solution for post-operative incision management. The product incorporates hypoallergenic adhesive technology to effectively cover and protect surgical incisions.
Surgical Wound Care Market Report Scope
Report Attribute
Details
Market size in 2026
USD 5.4 billion
Estimated market size in 2027
USD 5.6 billion
Projected market size by 2035
USD 8.0 billion
Growth rate
CAGR of 4.5% from 2027 to 2035
Historical data
2023 - 2025
Forecast period
2027 - 2035
Quantitative units
Revenue in USD million/billion and CAGR from 2027 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, surgery type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Solventum, Smith & Nephew plc, Mölnlycke Health Care, Johnson & Johnson (Ethicon), Baxter International, Medtronic, Cardinal Health, Coloplast, Convatec Group plc, B. Braun SE, Essity, Paul Hartmann AG, Integra LifeSciences, URGO Medical, Medline Industries, DeRoyal Industries, Advanced Medical Solutions Group, Winner Medical Co., Ltd., Lohmann & Rauscher (L&R), Hollister Incorporated
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Surgical Wound Care Market Report Segmentation
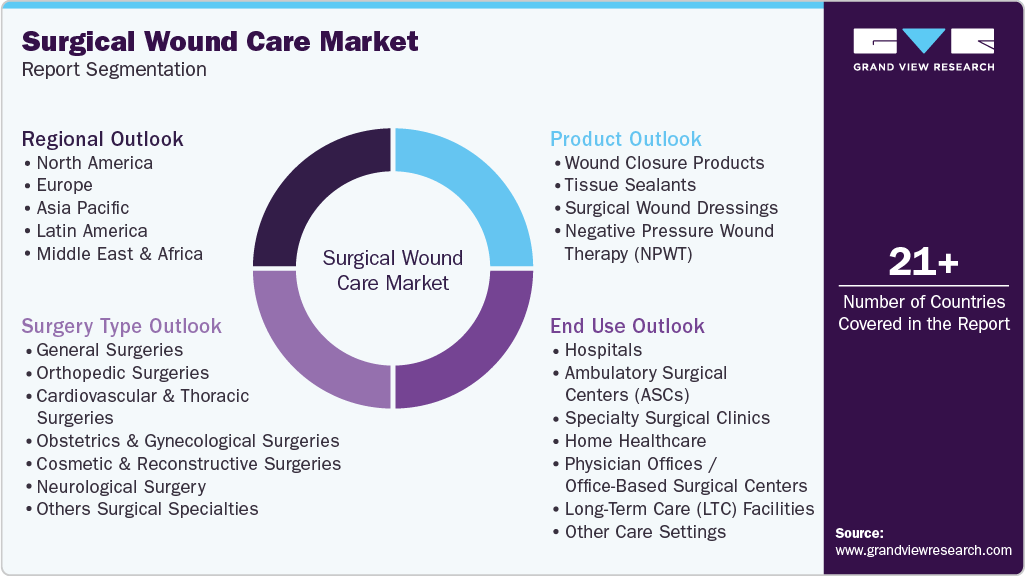
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on the latest industry trends in each of the sub-segments from 2023 to 2035. For the purpose of this study, Grand View Research has segmented the global surgical wound care market report on the basis of product, surgery type, end use and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2023 - 2035)
-
Wound Closure Products
-
Sutures
-
Absorbable Sutures
-
Non-Absorbable Sutures
-
-
Surgical Staples
-
Wound Closure Strips
-
Tissue Adhesives (Cyanoacrylate-Based)
-
-
Tissue Sealants
-
Fibrin-Based Sealants
-
PEG-Based Sealants
-
Collagen-Based Sealants
-
Other Tissue Sealants
-
-
Surgical Wound Dressings
-
Traditional Gauze & Basic Dressings
-
Foam Dressings
-
Hydrocolloid Dressings
-
Alginate & Hydrogel Dressings
-
Antimicrobial / Anti-infective Dressings
-
Silver-Based Dressings
-
PHMB-Based Dressings
-
Iodine-Based Dressings
-
DACC-Coated Dressings
-
Other Antimicrobial Dressings
-
-
Other Advanced Surgical Dressings
-
-
Negative Pressure Wound Therapy (NPWT)
-
Traditional NPWT Systems
-
Single-Use / Disposable NPWT Systems
-
-
-
Surgery Type Outlook (Revenue, USD Million, 2023 - 2035)
-
General Surgeries
-
Orthopedic Surgeries
-
Cardiovascular & Thoracic Surgeries
-
Obstetrics & Gynecological Surgeries
-
Cosmetic & Reconstructive Surgeries
-
Neurological Surgery
-
Others Surgical Specialties
-
-
End Use Outlook (Revenue, USD Million; 2023 - 2035)
-
Hospitals
-
Ambulatory Surgical Centers (ASCs)
-
Specialty Surgical Clinics
-
Home Healthcare
-
Physician Offices / Office-Based Surgical Centers
-
Long-Term Care (LTC) Facilities
-
Other Care Settings
-
-
Regional Outlook (Revenue, USD Million, 2023 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The surgical wound care market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each surgical wound care segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Wound Closure Products
Revenue generated from the sale of products used to approximate and close surgical incisions, including sutures, surgical staples, skin closure strips, and tissue adhesives specifically used for wound closure.
Tissue Sealants
Revenue generated from the sale of surgical sealants used to seal tissue, prevent fluid or air leakage, achieve hemostasis, and reinforce surgical closures. This includes fibrin sealants, synthetic sealants, and other bio-based tissue sealants.
Surgical Wound Dressings
Revenue generated from the sale of dressings specifically designed to protect surgical incisions, absorb postoperative exudate, maintain a suitable wound environment, and prevent external contamination. This includes gauze, film, foam, hydrocolloid, alginate, silicone, and antimicrobial surgical dressings.
Negative Pressure Wound Therapy (NPWT)
Revenue generated from the sale of NPWT systems and associated consumables used for managing surgical wounds and closed surgical incisions. This includes NPWT pumps, wound dressings, foam or gauze fillers, canisters, tubing, and other disposable accessories used in surgical wound management.
Estimation Model
01
02
03
Bottom-Up Procedure Volume Modeling
Top-Down Revenue Triangulation
Demand-Side Care-Setting Modeling
Estimates the total addressable market by assessing annual surgical procedure volumes across major specialties, including orthopedic, cardiovascular, general, gastrointestinal, plastic, and oncological surgeries. The model evaluates the number of surgical incisions, wound closure requirements, dressing utilization, tissue sealant adoption, and NPWT usage per procedure. Average selling prices (ASPs) of products, consumption rates, and regional procedure volumes are incorporated to estimate market revenue across product segments and geographies.
Aggregates supplier-side revenues from leading surgical wound care manufacturers through annual reports, financial disclosures, product portfolios, regulatory filings, investor presentations, and distribution data. Revenue estimates are validated using company-specific market participation, product-level sales contributions, geographic presence, pricing trends, and competitive positioning. The analysis accounts for wound closure products, tissue sealants, surgical wound dressings, and negative pressure wound therapy (NPWT) to derive overall market size.
Evaluates demand across hospitals, ambulatory surgical centers (ASCs), specialty surgical centers, and outpatient facilities by assessing surgical procedure volumes, procurement patterns, product adoption rates, and average consumption per procedure. The model further examines demand across surgical specialties, postoperative wound management practices, antimicrobial dressing adoption, and closed-incision NPWT utilization. Regional healthcare infrastructure, reimbursement policies, and purchasing trends are considered to validate market estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Detailed assessment of surgical wound care product categories and their revenue contribution
Segmented the market into wound closure products, tissue sealants, surgical wound dressings, and negative pressure wound therapy (NPWT), with product-level revenue assessment.
Enabled identification of high-revenue product categories and evaluation of segment-level growth opportunities.
Assessment of epidemiological trends influencing surgical wound care demand
Evaluated the prevalence and incidence of diabetes, obesity, cardiovascular diseases, and other chronic conditions, along with surgical procedure volumes and surgical site infection (SSI) rates across key regions.
Established the relationship between disease burden, surgical interventions, postoperative complications, and demand for surgical wound care products..
Competitive benchmarking of established manufacturers and emerging technology developers
Evaluated company portfolios, product innovations, operating strategies, competitive positioning, and technological developments across surgical wound closure, antimicrobial dressings, and ciNPWT.
Identified competitive gaps, innovation opportunities, and potential areas for product differentiation and strategic expansion.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


