
- Home
- »
- Communications Infrastructure
- »
-
ROADM WSS Component Market Size, Share Report, 2033GVR Report cover

ROADM WSS Component Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Blocker-based, Edge ROADMs, PLC-based, Wavelength Selective Switches), By Node (Two-node, Multi-node), By Application (Long Haul, Metro), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$1.1BMarket Estimate, 2026
$1.2BMarket Forecast, 2033
$2.7BCAGR, 2026–2033
12.2%ROADM WSS Component Market Summary
The global ROADM WSS component market size was valued at USD 1.1 billion in 2025 and is projected to grow from USD 1.2 billion in 2026 to USD 2.7 billion in 2033, at a CAGR of 12.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of approximately 32.5% in 2025. The increasing data traffic, widespread adoption of 5G networks, need for data center interconnectivity, and rising demand for network virtualization are some factors highlighting the importance of these solutions.
Key Market Trends & Insights
- By type: The wavelength selective switches (WSS) segment held the largest market share of 44.0% in 2025.
- By node: The multi-node segment held the largest market share of approximately 67.0% in 2025.
- By application: The metro segment held the largest market share of approximately 57.0% in 2025.
- By end-use: The communication segment held the largest market share of approximately 80.0% in 2025.
Regional Highlights
- Largest regional market: North America (Approximately 32.5% revenue share, 2025)
- Fastest-growing regional market: Latin America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.1 Billion
- Estimated market size in 2026: USD 1.2 Billion
- Projected market size by 2033: USD 2.7 Billion
- CAGR (2026-2033): 12.2%
Prism AI by Grand View Research Free to tryAsk a question about the ROADM WSS component marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
ROADM WSS stands for Reconfigurable Optical Add/Drop Multiplexer Wavelength Selective Switch. It allows for the precise selection and management of individual wavelengths in an optical fiber, providing network operators with precise control over data transmission. The steadily increasing data transmission volumes across the world require large network bandwidth. ROADM WSS facilitates network flexibility and efficiency, which accounts for its heightened demand, leading to market growth.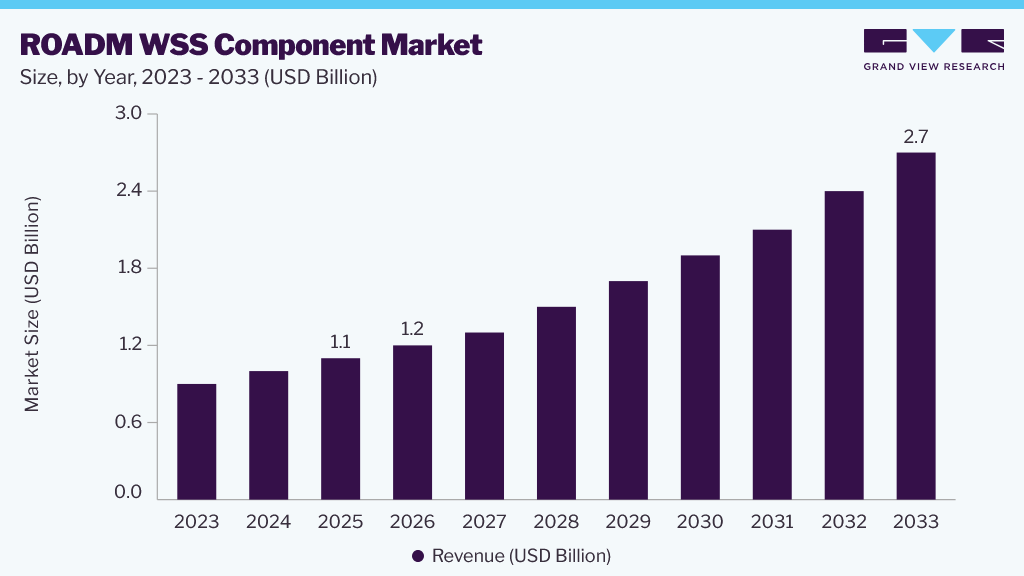 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The exponential increase in data consumption driven by cloud computing, video streaming, extensive use of social media platforms, and IoT applications has necessitated the presence of high-capacity, efficient, and flexible optical networks. As per the Digital 2026 Global Overview Report, currently more than 6 billion people have access to internet. Also, GSMA Intelligence report that 73.2% of the population worldwide are online. Rising digital transformation and smartphone adoption by consumers in developing countries have fueled the demand for better internet connectivity. ROADM WSS components are essential for efficiently managing this expanding data traffic, leading to steady market expansion.
As data centers expand and interconnect, the requirement for high-speed, low-latency optical networks becomes paramount. ROADM WSS components play a pivotal role in optimizing data center connectivity. Additionally, the widespread adoption of 5G technology demands robust and agile infrastructure. ROADM WSS solutions offer the required flexibility to support the dynamic nature of 5G networks. Ongoing research and innovations in WSS technology, such as the development of more compact and cost-effective components, are preferred by consumers, which help in driving market expansion.
Analyst Perspective
The ROADM WSS market is poised for sustained growth, driven by the rapid rise in global data traffic owing to adoption of cloud computing, video streaming, IoT, and growing internet penetration. The increasing deployment of hyperscale data centers and 5G networks is accelerating demand for flexible, high-capacity optical transport solutions capable of supporting dynamic bandwidth requirements. WSS-enabled ROADMs are becoming critical components for improving network scalability, reducing latency, and optimizing wavelength management in modern optical infrastructures. Furthermore, ongoing advancements in compact, cost-efficient, and high-performance WSS technologies are expected to enhance deployment across telecom and data center applications. As network operators continue investing in next-generation optical networks, vendors focused on innovation and programmable optical switching are likely to gain a competitive advantage.
Type Insights
The wavelength selective switches (WSS) segment dominated the global ROADM WSS component industry, accounting for a revenue share of approximately 44.0% in 2025. WSS components are the fundamental building blocks for controlling and routing optical signals based on their wavelengths. This precise control is essential for optimizing network performance and resource utilization. Moreover, continuous innovations in WSS technology, such as increased port density, improved switching speeds, and reduced power consumption have solidified their position as the preferred choice for network operators, leading to dominance of this segment in the market.
The PLC-based segment is expected to grow at the fastest CAGR of approximately 14.0% over the forecast period. PLC technology is considered to be a scalable and cost-efficient manufacturing process, resulting in lower component prices compared to traditional technologies. This economic advantage has stimulated wider adoption and accelerated market penetration of the components. Furthermore, PLC-based components offer greater design flexibility, enabling the creation of customized solutions to meet specific network requirements. This extensive adaptability has contributed to their widespread adoption across various network architectures and topologies.
Node Insights
The multi-node segment dominated the ROADM WSS component market, accounting for a revenue share of approximately 67.0% in 2025. Multi-node ROADM configurations offer greater flexibility in managing and controlling wavelength flow across multiple network nodes. This attribute is crucial in accommodating the dynamic and evolving demands of modern communication networks. Additionally, the segment is well-positioned to support emerging network trends such as data center interconnectivity, 5G deployment, and the proliferation of cloud services, which require high-capacity, flexibility, and scalable optical infrastructure.
The two-node segment is expected to grow at a significant CAGR over the forecast period. The two-node configuration offers core network backbone architecture. For instance, optical networks rely on a hub-and-spoke topology, where core network nodes are interconnected through point-to-point links. This architecture requires the deployment of two-node ROADM systems to efficiently manage optical signal routing and wavelength assignment between these core network locations. This attribute, along with lower costs of deployment, presents two-node configuration as a cost-effective alternative to multi-node configuration, accounting for its notable share in this market.
Application Insights
The metro segment led the ROADM WSS component market, accounting for 57.0% of the revenue share in 2025. Metro networks are characterized by high network density and a substantial number of data centers, enterprises, and residential areas. This requires frequent network reconfigurations to accommodate evolving traffic patterns and service demands. ROADM WSS components provide the necessary flexibility to adapt to these dynamic conditions. While the metro segment is characterized by high network density, the shorter distances involved compared to long-haul networks allow for the deployment of more cost-effective ROADM WSS solutions. These factors of flexibility and affordability fuel market growth in this segment.
The long-haul segment is expected to witness a significant CAGR during the forecast period. Long-haul networks travel across vast geographical areas and require high-capacity and low-loss optical transmission. ROADM WSS components are instrumental in optimizing wavelength management and network efficiency over these extended distances. As data traffic continues to rise, network operators are compelled to upgrade their long-haul infrastructure, which has helped ensure consistent segment growth.
End-use Insights
The communication segment dominated the ROADM WSS component industry, accounting for a revenue share of approximately 80.0% in 2025. The telecommunication sector has played a pivotal role in data transmission globally. Telecommunications companies are increasingly being compelled to adapt to the digital age, driven by growing data usage, a surge in the use of connected devices, and the need for quicker services. To meet these demands, continuous technological upgradation is required. For instance, the demand for 5G technology is rising, and telecom companies are investing significant resources in building the necessary infrastructure.
The other end-uses segment is expected to grow at a rapid CAGR during the forecast period. Rapid advancements in technology are leading to new applications for optical networks, such as data center interconnects, metro and access networks, and submarine cable systems. These emerging areas are expected to contribute significantly to the increasing market share of other end-uses of ROADM WSS. Furthermore, specialized applications requiring tailored ROADM WSS components highlight the need for smaller and niche manufacturers in this industry.
Regional Insights
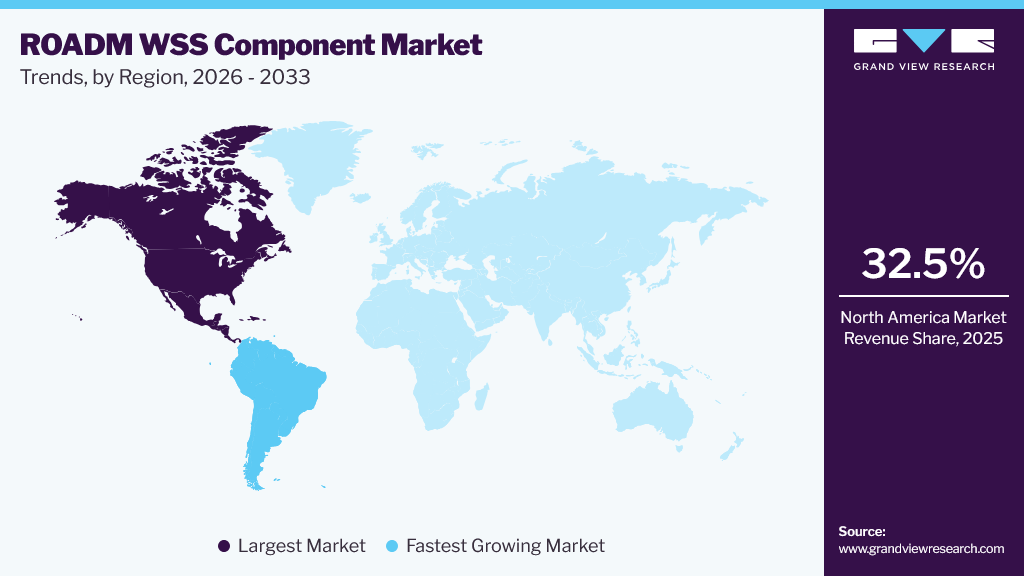
The North America ROADM WSS component held the largest global revenue share of approximately 32.5% in the market in 2025. This region has witnessed several technological advancements in the telecommunications sector, fostering a conducive environment for the development and deployment of innovative solutions such as ROADM WSS. These factors are accompanied by a well-established and extensive telecommunications infrastructure, creating a substantial demand for network upgrades and expansions, thereby driving the adoption of ROADM WSS components.
 To learn more about this report, Download Free Sample Report
U.S. ROADM WSS Component Market Trends
The U.S. held a dominant share in the regional market in 2025. Several prominent telecommunication equipment manufacturers and service providers such as Cisco Systems, Inc., Agiltron Inc., and AC Photonics, Inc. have their headquarters in the country, which has stimulated the growth of the ROADM WSS component ecosystem. Furthermore, substantial investments in research and development activities in the U.S. have contributed to the development of advanced ROADM WSS technologies and components.
Europe ROADM WSS Component Market Trends
The Europe ROADM WSS component industry accounted for a considerable revenue share in 2025. Europe's early and substantial investments in broadband networks and digital infrastructure have created an expanding demand for high-capacity, flexible optical networks. ROADM WSS components are essential enablers for such networks, driving their uptake in the region. Moreover, the stringent regulatory environment and emphasis on data privacy have accelerated the deployment of secure and resilient optical networks. ROADM WSS components play a crucial role in enhancing network security and reliability, thereby contributing to their widespread adoption in Europe.
The UK ROADM WSS component market is expected to grow over the forecast period. The UK is among the earliest economies where telecommunication infrastructure was established successfully. As a result, the presence of such a mature ecosystem of telecommunications equipment manufacturers, research institutions, and service providers in the country has nurtured a collaborative environment for the development and commercialization of ROADM WSS components. This ecosystem has been instrumental in driving technological advancements and market growth.
Latin America ROADM WSS Component Market Trends
The Latin America ROADM WSS component industry is expected to grow at the fastest CAGR of approximately 14.0% from 2026 to 2033. The region is undergoing a swift transition towards digital economies, characterized by increasing internet penetration, urbanization, and the proliferation of data-intensive applications. In 2025, mobile technologies and services contributed approximately USD 600 billion to Latin America's economy, equivalent to 8.6% of the region's GDP, highlighting the mobile industry's significant role in economic growth and digital transformation. This surge in digital activity requires robust and scalable telecommunications infrastructure, driving demand for advanced components such as ROADM WSS. Additionally, a cost-competitive environment for telecommunications infrastructure development has attracted investments in network expansion and modernization, driving market growth.
The Brazil ROADM WSS component market is expected to grow during the forecast period. According to DataReportal, currently, there are 217 million active cellular connections in the country representing 102% of the total population. Also, 183 million individuals are using internet in Brazil in 2025 accounting for approximately 86.2% of the total population. The increasing adoption of smartphones and other mobile devices has led to a surge in mobile data traffic, demanding efficient and flexible network solutions. ROADM WSS components play a crucial role in enabling internet service providers and mobile network operators in the country to meet the growing bandwidth requirements and improve network performance.
Key ROADM WSS Component Companies Insights
Some key companies involved in the ROADM WSS component market include Ciena Corporation, Adtran, and AC Photonics, Inc.
-
Ciena Corporation is a U.S.-based networking systems and software services company. Ciena specializes in creating and selling solutions for telecommunications companies and major cloud providers. Their offerings include hardware, software, and support services to handle and manage voice and data communication across networks. The company offers various equipment for network infrastructure such as the 6500 family of Packet-optical platforms which includes the 6500 D/S-Series, 6500-T Series, and 6500 Reconfigurable Line System (RLS). It further provides Navigator Network Control Suite (NCS) for optimization of multi-layer performance.
-
AC Photonics, Inc. is an American fiber optics product supplier. The company serves different industries such as aerospace, defense, communication, and healthcare through its services in photonic solutions. AC Photonics offers components for Dense Wavelength-Division Multiplexing (DWDM) with channel spacing of 200, 100, and 50 GHz for transmitting signals in many wavelengths through a single optical fiber. In the OADM component segment, AC Photonics offers single and dual-channel OADMs with 100/200 GHz ITU channel spacing.
Key ROADM WSS Component Companies
The following key companies have been profiled for this study on the ROADM WSS component market:
-
AC Photonics, Inc.
-
Agiltron Inc.
-
Cisco Systems, Inc.
-
Coherent Corp.
-
Fujitsu
-
Adtran
-
Corning Incorporated
-
Ciena Corporation
-
Molex
-
Lumentum Operations LLC
Recent Developments
-
In March 2024, Adtran announced that it had successfully completed the first-ever trial in Europe for optical transport within a live research network, in partnership with BT Group. This trial leveraged Adtran’s Coherent 100ZR pluggable transceiver, showcasing its high spectral efficiency level and low power consumption.
-
In March 2024, Coherent Corp. introduced a new optical circuit switch that leverages the company’s field-tested and highly reliable Datacenter Lightwave Cross-Connect (DLX) technology. The solution has been optimized for deployment in artificial intelligence data centers.
ROADM WSS Component Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.1 billion
Estimated market size in 2026
USD 1.2 billion
Projected market size by 2033
USD 2.7 billion
Growth rate
CAGR of 12.2% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, node, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Japan; India; China; Australia; South Korea; Brazil; South Africa; Saudi Arabia; UAE
Key companies profiled
AC Photonics, Inc.; Agiltron Inc.; Cisco Systems, Inc.; Coherent Corp.; Fujitsu; Adtran; Corning Incorporated; Ciena Corporation; Molex; Lumentum Operations LLC
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global ROADM WSS Component Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ROADM WSS component market report based on type, node, application, end-use, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Blocker-based
-
Edge ROADMs
-
PLC-based
-
Wavelength Selective Switches (WSS)
-
-
Node Outlook (Revenue, USD Billion, 2021 - 2033)
-
Two-node
-
Multi-node
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Long Haul
- Metro
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Communication
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
India
-
China
-
Australia
-
South Korea
-
-
Latin America
- Brazil
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
North America dominated with approximately 32.5% revenue share in 2025.
Key players in the market include AC Photonics, Inc.; Agiltron Inc.; Cisco Systems, Inc.; Coherent Corp.; Fujitsu; Adtran; Corning Incorporated; Ciena Corporation; Molex; and Lumentum Operations LLC.
The wavelength selective switches (WSS) segment accounted for the largest revenue share of approximately 44.0% in 2025.
The global ROADM WSS component market size was valued at USD 1.1 billion in 2025 and is estimated at USD 1.2 billion for 2026.
The global ROADM WSS component market is expected to grow at a CAGR of 12.2% from 2026 to 2033, reaching USD 2.7 billion.
About the Author(s)
Communications Infrastructure Research Team
Technology · Communications InfrastructureThis report was authored by the communications infrastructure research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communications infrastructure segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


