
- Home
- »
- Medical Devices
- »
-
Transdermal Skin Patches Market Size Report, 2026-2033GVR Report cover

Transdermal Skin Patches Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Multi-layer Drug-in-Adhesive), By Application (Pain Relief), By Distribution Channel (Hospital Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$6.6BMarket Estimate, 2026
$7.1BMarket Forecast, 2033
$12.0BCAGR, 2026–2033
7.8%Transdermal Skin Patches Market Summary
The global transdermal skin patches market size was valued at USD 6.6 billion in 2025 and is projected to grow from USD 7.1 billion in 2026 to USD 12.0 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. North America dominated the market with the largest revenue share of 39.5% in 2025. The market is increasing due to the growing incidence of chronic diseases such as cardiovascular disease, diabetes, chronic pain, etc., the enhanced preference of consumers for less-invasive treatment options, an aging population worldwide, and the technological advancement in transdermal drug delivery methods.
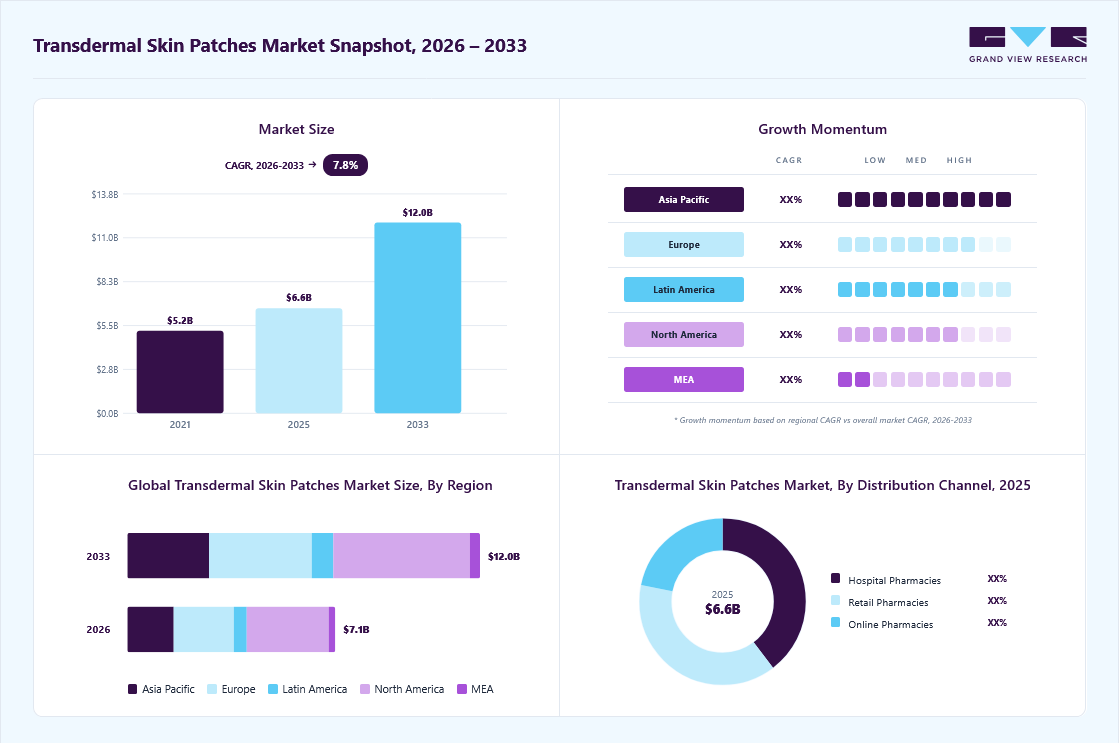 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Multi-layer drug-in-adhesive segment dominated the market, with a revenue share of 36.7% in 2025.
- By application: Pain relief segment held the largest market share of 22.9% in 2025.
- By distribution channel: Hospital pharmacies segment held the largest revenue share of 39.6% in 2025.
Regional Highlights
- Largest regional market: North America (39.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.6 Billion
- Estimated market size in 2026: USD 7.1 Billion
- Projected market size by 2033: USD 12.0 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Transdermal patches offer a non-invasive and convenient approach to managing drugs through oral and injectable formulations; therefore, patients are more likely to take their medications as prescribed and experience lower gastrointestinal side effects than oral medications. Due to their ease of use and consistent drug-release rates over long periods, transdermal patches are especially appealing in chronic disease state management. To learn more about this report, Download Free Sample Report
The industry is experiencing notable growth because of the rise of chronic diseases across the globe. In February 2024, the Centers for Disease Control and Prevention (CDC) estimates there are 129 million people in the United States with at least one key chronic disease, such as cancer, heart disease, obesity, diabetes, and hypertension. The most common treatment for chronic pain is to have the patient take pain relief medication daily, which is not only tedious, but oral or injectable forms often have bothersome side effects and burdensome frequency of administration. Transdermal patches can show efficacy in these scenarios as they improve adherence to medication therapy through regulated medication delivery over a longer period. For example, fentanyl transdermal patches have been approved for chronic pain management and will continuously release fentanyl over 72 hours, providing low-dose relief and reducing the frequency of administration.
Innovations like microneedles, iontophoresis, and permeation enhancers have broadened the transdermal drug delivery landscape, creating new possibilities for administering large molecules and biologics. Microneedle patches generate tiny channels to the skin to enhance the delivery of large-molecule drugs that are too large to administer transdermally. For instance, a microneedle patch containing insulin allows for a pain-free way of taking insulin rather than daily needles, which may optimize control of glycemic levels. Iontophoresis is a newer, innovative delivery strategy that utilizes a small electric charge to help push drugs through the skin.
The industry is driven by increasing consumer preference for less invasive options. Patients and healthcare providers opt for these patches because of decreased pain, less risk for developing an infection, and reduced side effects compared to oral or injected medications. For example, hormone replacement therapy patches, such as Estraderm Mx Patch by Biochemie Novartis, provide continuous release of hormones to avoid the side effects of the fluctuating hormone levels associated with oral HRT. Patches for smoking cessation, pain, and neurological disorders offer non-invasive, discreet, and convenient drug delivery to patients. These non-invasive routes improve patient comfort and compliance to treatment, which translates to growth in the market as consumers become more familiar with the potential benefits.
Market Dynamics
Transdermal skin patches are gaining significant traction as they enable hospitals, retail pharmacies, and outpatient clinics alongside the rapidly expanding homecare and over-the-counter (OTC) consumer wellness sectors to administer, manage, and optimize systemic drug delivery and localized therapeutic treatments through advanced membrane and matrix-based platforms. These solutions integrate cutting-edge technologies such as single- and multi-layer drug-in-adhesive systems, controlled-release polymer matrices, bio-absorbable microneedle arrays, smart sensor-enabled electronic patches, and digital patient compliance tracking software to provide real-time control over permeation kinetics, steady plasma drug concentrations, precise membrane transport, and overall treatment tolerance. Transdermal patch platforms help pharmaceutical companies and healthcare providers address the rising global demand for non-invasive, pain-free drug administration by supporting personalized chronic disease management plans, long-acting pain and addiction therapies, automated or continuous hormone replacement delivery, and proactive outpatient health optimization. This approach successfully eliminates the gastrointestinal irritation and first-pass hepatic metabolism commonly associated with oral dosage forms while providing a highly compliant, non-invasive alternative to traditional needle injections.
The rising global burden of chronic conditions such as cardiovascular diseases, central nervous system (CNS) disorders, diabetes, and severe chronic pain stands as the primary macro-level driver accelerating the growth of the transdermal skin patches market. Managing long-term conditions requires sustained drug release kinetics to maintain constant plasma concentrations and avoid the hazardous peaks and troughs associated with traditional oral dosing. Transdermal patches effectively satisfy this clinical requirement by facilitating controlled, continuous drug absorption directly through the skin barrier. This non-invasive administration route circumvents the gastrointestinal tract, bypassing first-pass hepatic metabolism and mitigating systemic side effects. Furthermore, because chronic illnesses disproportionately affect elderly populations who often suffer from dysphagia or cognitive decline, the simple, discreet wear profile of a transdermal system drastically enhances long-term patient therapy adherence and reduces hospital readmissions. The critical role of transdermal patches in managing progressive chronic conditions is heavily supported by prominent clinical advancements and real-world commercial instances. In neurological care where consistent medication delivery is vital to minimize cognitive and motor fluctuations, pharmaceutical companies are expanding their biostimulatory patch pipelines.
The incidence of localized skin irritation and severe allergic reactions stands as a major clinical restraint restricting the growth and widespread adoption of the transdermal skin patches market. Because transdermal systems require prolonged, continuous contact with the skin to ensure steady drug diffusion, the underlying tissue is frequently subjected to prolonged occlusion, mechanical friction, and sweat accumulation. This environment highly predisposes patients to Irritant Contact Dermatitis (ICD) and Allergic Contact Dermatitis (ACD), which typically manifest as severe erythema (redness), localized edema (swelling), pruritus (itching), or painful blistering at the application site. These adverse cutaneous responses can be triggered not only by the active pharmaceutical ingredient (API) itself but also by essential patch components, such as synthetic polymer matrices, permeation-enhancing chemicals, or structural pressure-sensitive adhesives (PSAs). When a patient experiences significant discomfort or noticeable skin breakdown, it frequently leads to premature patch removal, poor therapy adherence, and absolute treatment discontinuation. This dynamic ultimately forces clinicians to switch patients back to traditional oral or injectable therapies, which directly limits the addressable market expansion for transdermal therapeutics.
Market Concentration & Characteristics
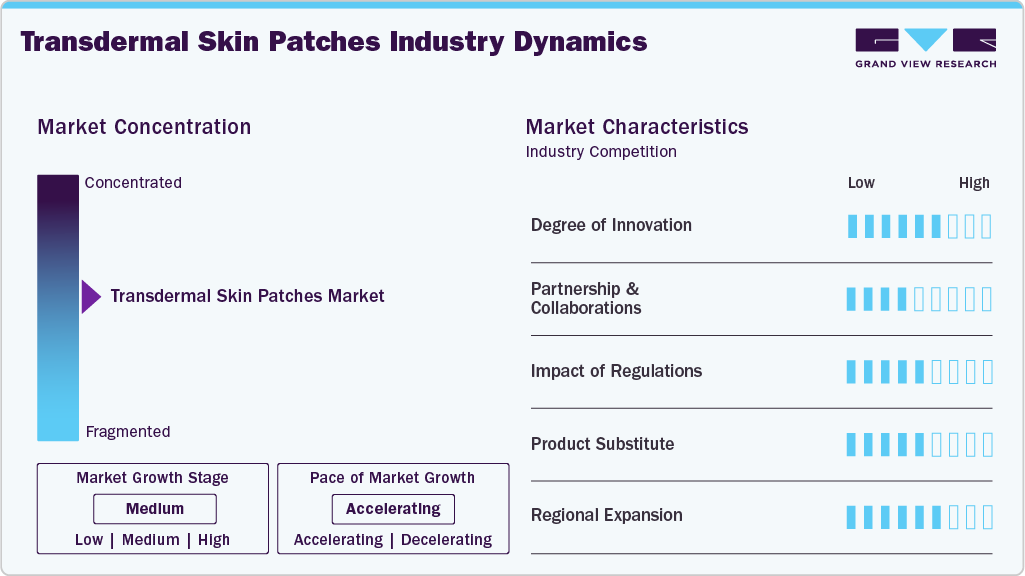
The industry is experiencing steady and balanced growth, fueled by innovations in smart and microneedle technologies that improve drug delivery and patient adherence. Leading companies like Teva Pharmaceuticals, Transdermal Therapeutics, Inc., Novartis AG, and Medherant sustain robust market positions through ongoing R&D efforts and international expansion.
Recent improvements within transdermal drug delivery, such as microneedles, iontophoresis, and permeation enhancers, have broadened the types of medications that can now be administered, including large molecules and biologics. These methods provide more precise and pain-free drug delivery, and progress in patch technology and controlled-release systems ensures effectiveness and patient outcomes. The transdermal drug delivery field is progressing rapidly and improving patient or resident care.
 To learn more about this report, Download Free Sample Report
Partnerships and collaborations accelerate advancement by introducing innovative drug delivery solutions in the transdermal patch market. Collaborations like Medherant’s with Bayer focus on developing new transdermal patches, combining expertise to improve efficiency and patient outcomes. Similarly, in January 2024, LTS Lohmann Therapie-Systeme AG and Micron have partnered to commercialize Micro Array Patch (MAP) technology, supporting scale-up and global distribution. These collaborations allow companies to leverage technical expertise to develop innovative therapies, expand production capabilities, and accelerate the availability of innovative treatments. Strategic partnerships enhance technological development and market growth in the transdermal drug delivery sector.
Transdermal skin patches are strictly regulated to safeguard against risks and ensure safety, effectiveness, and quality. In the U.S., the FDA regulates patches as combination drugs that are assigned a Primary Mode of Action (PMOA) that determines whether the FDA drug branch under the Center for Drug Evaluation and Research (CDER) or the device branch under the Center for Devices and Radiological Health (CDRH) will review the patch, while following cGMP and design controls. In the European Union, transdermal patches are regulated under the Medical Device Regulation (MDR) or the Medicinal Products Directive, depending on the primary function of the patch. In India, the CDSCO will evaluate a patch case-by-case basis, ensuring it is approved under frameworks including drug and device components.
Tablets and therapeutic injections are effective alternatives to transdermal skin patches. Tablets provide accurate dosing, a long shelf life, easy-to-use formats, and controlled or sustained-release options. Therapeutic injections allow for rapid, targeted, and precise drug delivery. Together, tablets and therapeutic injections provide flexible, patient-friendly, and effective solutions for various treatments.
The industry is a result of strong growth across the different regional markets, paired with improved access to sophisticated drug delivery technologies. Given vast healthcare expenditures, R&D capacity, and healthcare infrastructure support, North America and Europe lead the transdermal skin patches market. The Asia-Pacific region is accelerating due to the increasing prevalence of chronic diseases and awareness of new health care opportunities. The consolidation of prime factors during this time will continue to drive growth, including the government's continued efforts, improved drug delivery technology, and pharmaceutical agreement partnerships across all targeted markets.
Analyst Perspective
The transdermal skin patches market is positioned at the intersection of several long-term healthcare, pharmaceutical drug delivery, and patient-centric treatment trends, including the growing demand for non-invasive drug administration, increasing emphasis on improving medication adherence, and continuous advancements in transdermal delivery technologies. Rising prevalence of chronic conditions such as pain disorders, cardiovascular diseases, neurological disorders, hormonal imbalances, and smoking addiction is creating significant opportunities for transdermal patch manufacturers and pharmaceutical companies as healthcare providers seek convenient, controlled, and sustained drug delivery solutions that can enhance therapeutic outcomes while minimizing systemic side effects associated with conventional oral and injectable therapies. Furthermore, ongoing innovations in patch design, adhesive technologies, permeation enhancers, microneedle-assisted transdermal systems, and smart drug delivery platforms are fundamentally transforming the market landscape. These advancements enable precise dosing, extended drug release profiles, improved bioavailability, and enhanced patient comfort, making transdermal patches an increasingly attractive alternative to traditional dosage forms. The ability of transdermal systems to bypass gastrointestinal degradation and first-pass hepatic metabolism further contributes to their growing clinical acceptance across multiple therapeutic areas.
Type Insights
Based on type, the multi-layer drug-in-adhesive segment led the market with the largest revenue share of 36.7% in 2025, driven by their superior drug delivery efficiency and versatility across various applications. These innovative patches consist of several adhesive layers containing the active pharmaceutical ingredient (API), allowing for slow and sustained drug diffusion over time. This protects against dose dumping while also establishing a sustained therapeutic effect instead. For instance, the fentanyl transdermal patch, utilized for chronic pain management, is a multi-layer patch whose active principle provides continuous pain relief over a duration of 72 hours. It improves patient comfort and adherence to treatment more than oral painkillers, which need to be dosed regularly throughout the day. The long-lasting medication with less frequent dosing appropriate for these patches is often more suitable for patients managing chronic diseases.
The matrix segment is expected to witness significant growth at a CAGR of 8.1% during the forecast period. This expansion has been facilitated by improved formulation flexibility and greater cost-effectiveness of manufacturing. A matrix patch mixes the active pharmaceutical ingredient (API) within the polymer matrix to achieve a consistent dispersion and predictable release. The matrix design provides considerable formulation flexibility with respect to a range of APIs, such that it is possible to create patches that can be used therapeutically, like the Nicotine transdermal patch, which is a commonly used product to aid smoking cessation. For example, Nicoderm CQ is a matrix patch product that achieves a steady-state release of nicotine, reducing withdrawal symptoms and cravings, thereby significantly enhancing participants’ likelihood of successfully quitting smoking through nicotine replacement therapy.
Application Insights
Based on application, the pain relief segment led the market with the largest revenue share of 22.9% in 2025 due to the increasing prevalence of chronic pain conditions. Chronic pain, stemming from conditions like arthritis, fibromyalgia, and lower back pain, affects millions globally, driving demand for effective and manageable pain relief solutions. For instance, the Institute for Health Metrics and Evaluation published a report in August 2023, which predicts that 1 billion people will be affected by osteoarthritis by 2050, with 15% of individuals aged 30 and older currently experiencing it. Transdermal patches provide a continuous and controlled release of analgesics, ensuring sustained pain relief without the peaks and troughs associated with oral medications. They eliminate the need for multiple daily doses, injections, or complex medication regimens, making them particularly suitable for patients with chronic pain who require long-term treatment. These patches' discreet nature and ease of application further contribute to their popularity among patients and healthcare providers.
The smoking reduction segment is expected to witness significant growth at a CAGR of 9.2% in the transdermal skin patches market, driven by the increasing awareness of the health risks associated with smoking. As reported by the World Health Organization (WHO) in July 2023, smoking tobacco results in visits to more than 8 million people worldwide every year. Public health campaigns and resulting tighter restrictions around tobacco use have created a heightened level of awareness around the negative consequences of smoking, including lung cancer, heart disease, and respiratory disease. Nicotine transdermal patches provide evidence-based, non-invasive treatment of smoking cessation, as they adhere to the skin and gradually deliver an alleviation of withdrawal symptoms and cravings in a controlled dose of nicotine. For example, in April 2023, Rusan Pharma commenced a campaign to support smoking cessation with their brand '2baconil', which is a nicotine transdermal patch serving a 24-hour dose.
Distribution Channel Insights
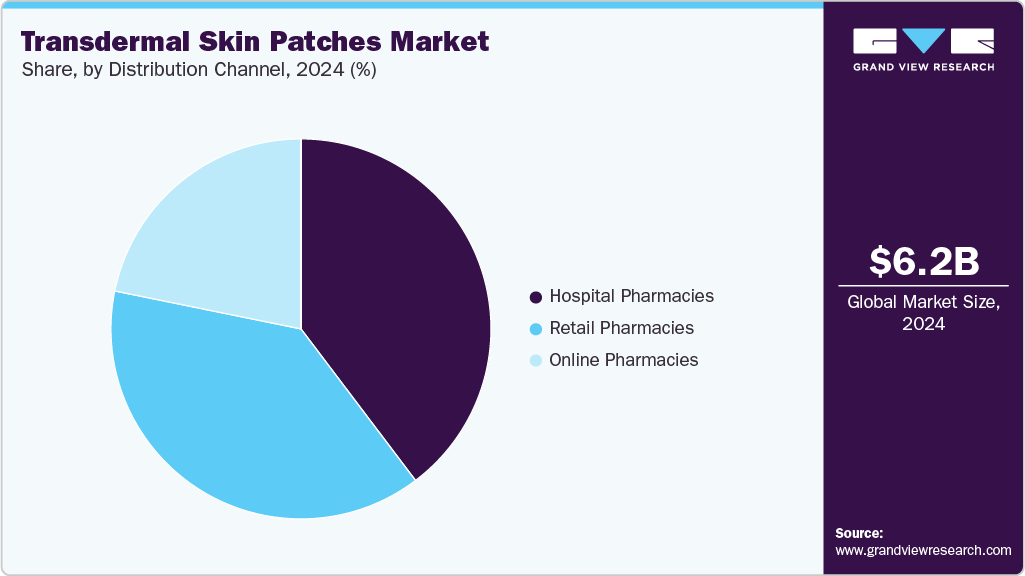
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 39.6% in 2025. Hospitals cater to many patients daily, providing a steady demand for various medications, including transdermal patches. Patients often rely on hospital pharmacies for their prescriptions following hospital visits or stays, ensuring a consistent and reliable distribution channel for these products. Moreover, hospital pharmacists' professional guidance and support are crucial in educating patients about the correct use of transdermal patches, their benefits, and potential side effects. This expert advice is particularly important for first-time users or for those using patches for complex treatments, such as hormone replacement therapy or pain management.
 To learn more about this report, Download Free Sample Report
Online pharmacies are expected to grow at the fastest CAGR of 8.1% during the forecast period. The increasing adoption of e-commerce and online shopping has significantly broadened the availability of healthcare products, including transdermal patches. Platforms like Amazon and Walgreens offer a diverse range of transdermal patches, catering to patients managing chronic conditions with enhanced convenience and accessibility.
Regional Insights
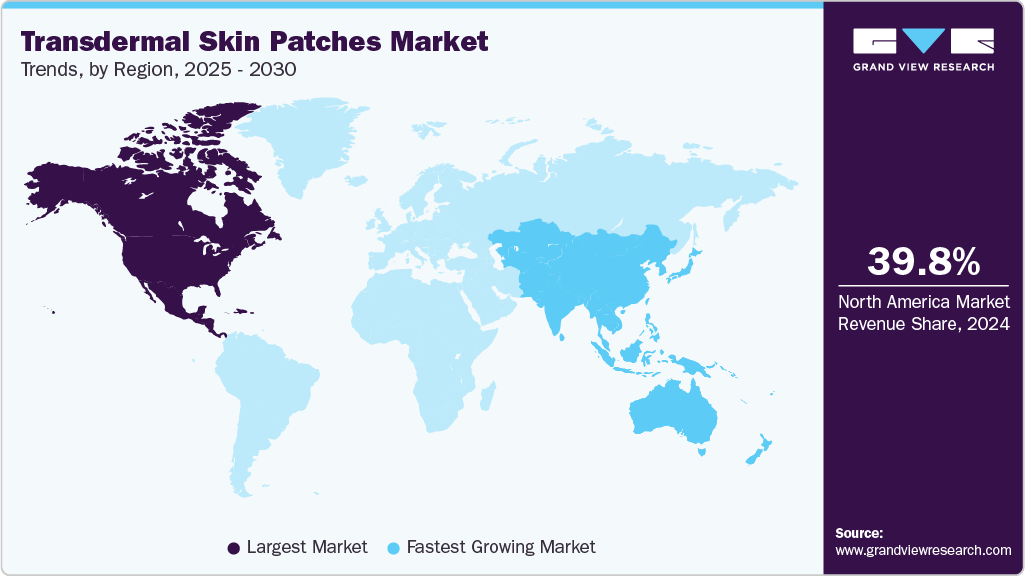
North America dominated the transdermal skin patches market with the largest revenue share of 39.5% in 2025 due to the advanced healthcare infrastructure and regulatory frameworks that facilitate developing and approving innovative transdermal patch technologies. In addition, the high rates of chronic illnesses, including diabetes, cardiovascular disease, and chronic pain conditions, in North America contribute to the need for convenient and effective treatment options such as transdermal patches. According to CDC data, cigarette smoking is the leading preventable cause of disease, disability, and death in the United States, accounting for more than 480,000 deaths each year.
 To learn more about this report, Download Free Sample Report
U.S. Transdermal Skin Patches Market Trends
The transdermal skin patches market in the U.S. held the largest share in the North America region in 2025. The transdermal skin patches market in the U.S is witnessing strong growth, driven by the rising prevalence of chronic diseases and the growing need for advanced and innovative drug delivery solutions. Additionally, stringent regulatory guidelines are important to the market's growth. In the U.S., the FDA considers transdermal patches to be combination products that must satisfy requirements for both therapeutic products and medical devices. Regulators review each patch's life cycle to ensure safety, efficacy, and quality. As chronic diseases become more prevalent, the demand for Transdermal Skin Patches that provide efficient, reliable, controlled, and minimally invasive drug delivery is expected to increase.
Europe Transdermal Skin Patches Market Trends
The transdermal skin patches market in Europe is characterized by stringent regulations, high disease prevalence driving demand, a focus on innovation, and increasing acceptance of non-invasive treatment options. Authorities like the European Medicines Agency (EMA) are essential for ensuring these products receive approval and that patients can trust that these agencies also have an ongoing surveillance and monitoring function. Medicine manufacturers and research organizations based in countries including Germany, the UK, and France are leading the way in innovating transdermal drug delivery systems, studying new types of materials, formulations, and/or delivery technologies to achieve improved therapeutic outcomes and patient convenience.
The UK transdermal skin patches market is witnessing rapid growth. This growth is driven by noninvasive and pain-free drug administration, which increases patient comfort and adherence. The rising prevalence of chronic diseases is also a key driver for the rise in the market, boosting the demand for convenient and effective medication delivery methods.
The market for transdermal skin patches in Germany is expanding progressively because of the growing attention towards chronic disease management and technological advancements. Developments in microneedle patches for better delivery penetration and single-layer and multi-layer drug-in-adhesive patches for improved treatment effectiveness and patient comfort continue contributing to the growing demand. These innovative concepts increase the precision, efficacy, and ease of use in drug delivery, further solidifying Germany's status as a global leader in innovative health care solutions.
Asia Pacific Transdermal Skin Patches Market Trends
The transdermal skin patches market in Asia Pacific is anticipated to witness fastest growth over the forecast period owing to the region's large and rapidly growing population, rising disposable incomes and urbanization, and increasing healthcare spending and demand for advanced medical treatments. As awareness of chronic diseases such as diabetes, cardiovascular disorders, and pain management grows, there is a corresponding rise in demand for effective and convenient drug delivery systems like transdermal patches. According to the report published by the Shanghai Municipal People's Government in July 2023, China's elderly population, comprising 190 million, faces a significant public health issue due to chronic diseases. The National Health Commission reports that 75% of those over 60 have one chronic disease and 43% have at least two. Chronic diseases are the leading cause of death for Chinese people, accounting for 86.6% of all deaths.
Japan's transdermal skin patches market is witnessing significant growth, driven by an aging population; in 2025, there were over 36.25 million 65+ citizens, almost one-third of the population. Non-invasive and pain-free patch delivery, offering easier and more comfortable treatment, becomes especially attractive in this demographic. Additionally, increasing rates of chronic disease in older individuals make convenient drug delivery even more attractive.
The transdermal skin patches market in China is growing steadily, driven by the increased number of chronic diseases. A study published by ScienceDirect in 2023 reported that the national prevalence of chronic diseases among adults age 60 and above is 81.1%, while 36.3% of this population experiences cardiovascular disease. This prevalent condition underscores the increasing demand for effective health care options and access to care. Noninvasive and simple-to-use transdermal patches are becoming a convenient and effective option to discontinue oral and injectable medications. Convenient, simple-to-use and effective transdermal patches are especially vital for the aging population managing chronic health conditions.
Latin America Transdermal Skin Patches Market Trends
The transdermal skin patches market in Latin America is anticipated to grow because of improvements in healthcare infrastructure and a growing demand for advanced drug delivery systems. Countries like Brazil, Mexico, and Argentina are increasing healthcare service access and improving the quality of care, leading to the adoption of new therapies. There is a rising interest in using advanced drug delivery systems, such as transdermal patches, as a noninvasive and patient-friendly alternative to traditional medication routes.
Brazil's transdermal skin patches market is expanding gradually because of the increasing incidence of chronic illnesses, particularly in the older population. Transdermal systems provide a non-invasive, convenient, and patient-friendly option compared to oral medications and injections. Transdermal systems are easy to use, provide consistent drug delivery, and are suitable for long-term therapy; thereby, they are becoming more appealing for treating chronic diseases. Due to the increasing burden of chronic diseases, the demand for novel and efficient drug delivery systems is expected to increase in Brazil.
Middle East & Africa Transdermal Skin Patches Market Trends
The transdermal skin patches market in the Middle East & Africa is witnessing a rise in chronic diseases, driven by an aging population and evolving lifestyle factors. The estimated prevalence of multimorbidity in the region is 21.8%, with hypertension, diabetes, and cardiovascular disease being the leading conditions. This demographic shift places increased pressure on healthcare systems, necessitating new and efficient treatment approaches.
Saudi Arabia transdermal skin patches market is expanding as chronic disease cases and the aging population continue to rise. The rise in multimorbidity is becoming increasingly common, increasing the necessity of patient-friendly and efficient treatment options. Transdermal patches offer non-invasive, continuous, and patient-friendly drug delivery for treating chronic diseases.
The transdermal skin patches market in Kuwait is growing because of the rise of chronic diseases and an aging population. Multimorbidity is very common among the elderly, particularly women and Kuwaiti nationals. Elderly individuals report higher incidences of chronic disease, including heart disease, diabetes, and hypertension. Transdermal pharmaceutical patches provide advantages to patients as a non-invasive, tractable, and decentralized way to administer therapeutics or to manage chronic disease conditions, aligning with the growing demand for effective and accessible healthcare solutions.
Key Transdermal Skin Patches Company Insights
Key players operating in the transdermal skin patches market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Transdermal Skin Patches Companies:
The following key companies have been profiled for this study on the transdermal skin patches market.
-
Teva Pharmaceutical Industries Ltd
-
Novartis AG
-
Teikoku Pharma USA Inc.
-
Viatris Inc.
-
Johnson & Johnson
-
Luye Pharma Group
-
Purdue Pharma Manufacturing LP
-
Henan Lingrui Pharmaceutical Ltd
-
Samyang Biopharmaceuticals Corp.
-
Hisamitsu Pharmaceutical Co, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Teva Pharmaceutical Industries Ltd, Novartis AG, Teikoku Pharma USA Inc.)
- They focus on lifecycle management of approved patch products, geographic expansion, strategic licensing agreements, formulation optimization, and investment in next-generation patch technologies to maintain market leadership.
- Their strategies emphasize large-scale commercialization, supply chain efficiency, and long-term revenue generation across pain management, smoking cessation, hormone replacement therapy, neurological disorders, and cardiovascular applications.
- Company’s established relationships with healthcare providers, pharmacies, hospitals, and payers facilitate broad market access and product adoption.
- Their ability to invest in advanced adhesive technologies, controlled-release formulations, and large clinical programs enables sustained competitive positioning and portfolio expansion.
- Their large operational footprints can reduce agility in responding to emerging technologies, novel drug-delivery platforms, and evolving patient preferences.
- Maintaining compliance across multiple jurisdictions increases operational complexity and cost burdens.
Emerging Players (Henan Lingrui Pharmaceutical Ltd, Samyang Biopharmaceuticals Corp., Hisamitsu Pharmaceutical Co, Inc.)
- Emerging players prioritize research and development of advanced transdermal drug delivery systems, microneedle-enabled patches, smart wearable patches, and enhanced permeation technologies.
- Their focus is often on addressing unmet therapeutic needs, improving patient adherence, and enabling delivery of complex molecules that are difficult to administer through conventional transdermal systems.
- Emerging player’s flexibility allows rapid adoption of novel materials, digital health integration, connected monitoring features, and patient-centric delivery platforms.
- Many target niche therapeutic segments and specialized applications where large pharmaceutical companies have limited presence, enabling them to establish early market positions and create disruptive growth opportunities.
- Emerging players often face limitations related to funding availability, smaller commercialization infrastructures, limited manufacturing scale, and comparatively less regulatory experience.
- Clinical validation requirements, reimbursement uncertainties, and lengthy approval timelines can delay market entry.
Recent Developments
-
In August 2024, Zydus Lifesciences received final approval from the U.S. Food and Drug Administration (FDA) to market its Scopolamine Transdermal System (1 mg/3 days).
-
In September 2023, Corium, LLC, a biopharmaceutical company, released data confirming the success of its donepezil transdermal system, ADLARITY, in a placebo-controlled trial with healthy volunteers. It is the first U.S. FDA-approved donepezil transdermal system for patients with mild, moderate, and severe Alzheimer's dementia.
-
In September 2023, Zydus Lifesciences Ltd announced the final approval from the U.S. Food and Drug Administration (USFDA) for its Norelgestromin and Ethinyl Estradiol Transdermal System. This skin patch delivers a combination of hormone medications designed to prevent pregnancy effectively.
-
In August 2023, Yaral Pharma, the U.S. generics subsidiary of IBSA, introduced the Lidocaine Patch 5%, positioned as an AB-rated equivalent to Lidoderm. This prescription-strength lidocaine patch is a significant addition to Yaral Pharma's lineup of non-opioid prescription products designed to alleviate pain and inflammation effectively.
Transdermal Skin Patches Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.6 billion
Estimated market size in 2026
USD 7.1 billion
Projected market size by 2033
USD 12.0 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Teva Pharmaceutical Industries Ltd; Novartis AG; Teikoku Pharma USA Inc.; Viatris Inc.; Johnson & Johnson; Luye Pharma Group; Purdue Pharma Manufacturing LP; Henan Lingrui Pharmaceutical Ltd; Samyang Biopharmaceuticals Corp.; Hisamitsu Pharmaceutical Co, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Transdermal Skin Patches Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and analyzes the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global transdermal skin patches market report by type, application, distribution channel, and region:
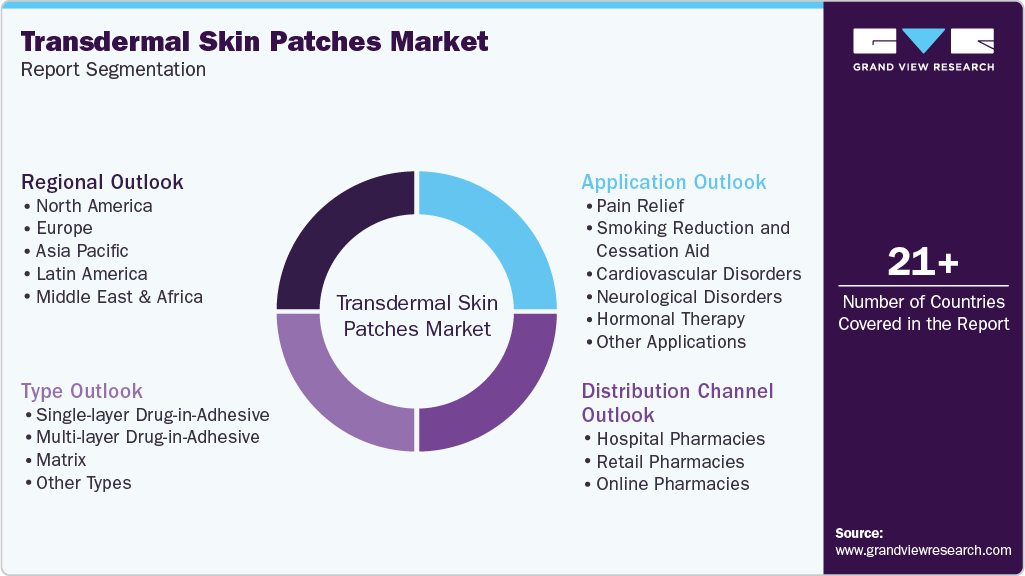 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Unit, 2021 - 2033)
-
Single-layer Drug-in-Adhesive
-
Multi-layer Drug-in-Adhesive
-
Matrix
-
Other Types
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pain Relief
-
Smoking Reduction and Cessation Aid
-
Cardiovascular Disorders
-
Neurological Disorders
-
Hormonal Therapy
-
Other Applications
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The transdermal skin patches market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each transdermal skin patches segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Single-layer Drug-in-Adhesive
Revenue is generated through the commercialization of thin, low-profile patches where the Active Pharmaceutical Ingredient (API) is directly formulated into a single skin-contact adhesive layer. Manufacturers earn revenue primarily from high-volume sales of cost-effective over-the-counter (OTC) and prescription patches, leveraging simplified, single-pass manufacturing processes that lower production costs.
Multi-layer Drug-in-Adhesive
Revenue flows from advanced patch systems featuring multiple adhesive layers infused with varying drug concentrations or multiple APIs. Companies capture revenue by targeting complex therapeutic needs, offering distinct pricing structures for patches engineered for multi-day, phased, or immediate-versus-sustained drug release, thereby capturing value through extended treatment cycles and improved patient adherence.
Matrix
Revenue is derived from patches where the drug is uniformly dispersed within a solid or semi-solid polymer matrix layer, distinct from the primary skin adhesive. Manufacturers generate income through premium pricing for highly stable, abuse-deterrent prescription formulations. This design reduces the risk of accidental dose dumping and ensures highly predictable pharmacokinetic release profiles over extended wear times.
Others
Revenue is captured through innovative, emerging transdermal delivery platforms, including reservoir systems and advanced microneedle patches. Monetization models involve premium product pricing, strategic out-licensing of intellectual property, and co-development partnerships aimed at delivering complex macromolecules and biologics that cannot pass through the skin barrier traditionally.
Segment - Application
Revenue capture definition
Pain Relief
Revenue is driven by continuous consumer and clinical demand for non-invasive management of chronic, acute, and neuropathic pain. Manufacturers earn sustained revenue through high-volume sales of prescription narcotic patches, localized lidocaine patches, and over-the-counter anti-inflammatory patches.
Smoking Reduction and Cessation Aid
Revenue flows through the highly commercialized Nicotine Replacement Therapy (NRT) market. Market participants capture revenue through multi-step, structured step-down treatment kits, driving high recurring consumer purchases across both mass retail and pharmacy channels.
Cardiovascular Disorders
Revenue is generated through specialized prescription patches designed to treat chronic conditions like hypertension and angina. Income is derived from long-term, highly loyal patient cohorts requiring consistent, daily-to-weekly systemic medication adherence to prevent acute cardiovascular events.
Neurological Disorders
Revenue is derived from specialized central nervous system (CNS) therapies, such as patches for Parkinson’s disease and Alzheimer’s disease. Manufacturers command high premium pricing due to the therapeutic benefit of avoiding GI side effects and providing steady drug plasma levels in highly sensitive, elderly, or dysphagic patient populations.
Hormonal Therapy
Revenue is captured through systemic hormone delivery systems, including estrogen/progesterone patches for menopause management and female contraception, as well as testosterone patches. Income is driven by consistent, multi-week or monthly subscription-style prescription refills required for ongoing endocrine balance.
Other Applications
Revenue flows from a diversified mix of niche therapeutic areas, including patches for overactive bladder, motion sickness, and emerging cosmetic/wellness patches. Income is generated through a mix of prescription insurance reimbursements and direct-to-consumer premium retail pricing.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Revenue is captured via large-scale, institutional B2B procurement contracts and bulk purchasing agreements. Revenue is tightly linked to inpatient clinical care, post-surgical pain management protocols, and direct integration into acute hospital electronic health record (EHR) and formulary systems.
Retail Pharmacies
Revenue is driven by high-volume, steady cash flows from localized brick-and-mortar chain pharmacies and independent drugstores. Income is generated through a balanced split of commercial insurance prescription copays and high-margin, immediate out-of-pocket consumer sales for OTC patches.
Online Pharmacies
Revenue flows through digital e-commerce platforms, mail-order pharmacy networks, and automated chronic medication prescription delivery services. Providers capitalize on convenience-driven consumer behaviors, capturing steady revenue streams through automated monthly auto-ship refills, subscription models for smoking cessation kits, and digital telehealth prescribing partnerships.
Estimation Model
Phase Title
Key Question
Process Steps
Data Sources
Scope Definition
What is being studied?
1. Define Patch & Matrix Technology Categories 2. Scope Type & Application Segments 3. Set Geographic Boundaries (Global / Regional) 4. Align on Data Format & Forecast Horizon (2021-2031)
FDA, EMA, Global health agencies
Build the Product Base
How large is the total addressable market?
1. Gather Prescription & Retail Volume Data 2. Estimate Patient Treatment Base 3. Apply Patch Type & Formulation Price Splits 4. Project Volume Trajectories
Industry databases, healthcare associations, company annual reports, primary interviews
Estimate Penetration
What penetration rate must be achieved considering forward forecasts?
1. Survey Advancements & Adoption Rates 2. Map Adhesion & Matrix Design Utilization 3. Identify Small/Connected System Mix 4. Triangulate With Vendor Shipment Data & Product Launches
Primary interviews, company filings, distributor feedback
Revenue Conversion
How does volume become revenue?
1. Gather Formulation Cost Metrics 2. Segment by Revenue Streams 3. Apply Distribution Channel Share 4. Cross-Check with Import/Export Data
Industry databases, government publications, company annual reports, primary interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
CompetitiClient Requestve Landscape Analysis Conducted a comprehensive competitive landscape assessment for the global transdermal skin patches market, covering major manufacturers of prescription (Rx) and over-the-counter (OTC) patch formulations across multi-specialty hospital pharmacies, institutional clinics, and retail commercial distribution channels. The study evaluated corporate market positioning, multi-technology drug delivery portfolios, strategic contract manufacturing (CMO) alliances, and key therapeutic pipelines. Additionally, the analysis tracked international regulatory approval pathways, bioequivalence studies, proprietary chemical permeation-enhancer innovations, and physician-targeted clinical marketing strategies adopted by leading multinational pharmaceutical corporations and emerging biotechnology market participants. Enables stakeholders to understand the competitive dynamics, technological positioning, and strategic corporate initiatives shaping the global transdermal skin patches market. The study supports informed decision-making related to cross-enterprise partnerships, generic versus branded product differentiation, R&D pipeline prioritization, and global commercialization planning. It also helps drug developers and device engineers identify formulation gaps, benchmark regulatory approval timelines, and strengthen commercial market penetration across hospital formulary networks and large-scale pharmaceutical retail distribution channels. Macroeconomic Analysis Conducted a detailed macroeconomic assessment of the primary global forces shaping the transdermal skin patches market. The study evaluated the impact of international healthcare expenditures, public vs. private medical insurance reimbursement models, and stringent regulatory compliance frameworks on manufacturing overhead and pricing structures of transdermal drug delivery systems. It analyzed the financial implications of shifting active pharmaceutical ingredient (API) supply chain dynamics, regional manufacturing localization policies, and fluctuating raw material costs. Enables stakeholders to navigate geographic financial volatility, mitigate international trade and regulatory compliance risks, and strategically optimize global tier-pricing and product positioning structures. It provides corporate leadership with actionable financial insights to support long-term investment planning, manage supply chain disruptions, and isolate high-margin geographic markets where robust medical reimbursement frameworks actively offset the premium cost of sophisticated, multi-day transdermal drug formulations. Key Market Drivers Analysis Conducted an in-depth driver analysis focused on the increasing global demand for non-invasive, pain-free drug administration, the rising worldwide prevalence of chronic conditions requiring long-term treatment adherence, and continuous technological advancements in transdermal delivery matrices. The study evaluated clinical trends driving the adoption of patch solutions, including aging global demographic profiles, higher acceptance of digital and cognitive decline, where simple, discreet patch delivery drastically improves therapy compliance. Enables stakeholders to understand the core clinical, demographic, and technological factors driving volume and value expansion within the global transdermal skin patches market. The study supports data-driven strategic forecasting, therapeutic pipeline prioritization, and market entry mapping by identifying how evolving practitioner prescribing habits and patient-centric care models align with next-generation pharmaceutical formulations and long-acting transdermal technologies. Frequently Asked Questions About This Report
Some key players operating in the transdermal skin patches market include Teva Pharmaceutical Industries Ltd; Novartis AG; Teikoku Pharma USA Inc.; Viatris Inc.; Johnson & Johnson; Luye Pharma Group; Purdue Pharma Manufacturing LP; Henan Lingrui Pharmaceutical Ltd; Samyang Biopharmaceuticals Corp.; Hisamitsu Pharmaceutical Co, Inc.
Key factors that are driving the market growth include increasing prevalence of chronic diseases, where conventional drug delivery systems, such as oral drugs have lower potency due to the hepatic first-pass metabolism.
North America dominated with a share of 39.5% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Pain relief segment held the largest revenue share of 22.9% in 2025, while smoking reduction is the fastest-growing area.
Hospital pharmacies held the largest revenue share of 39.6% in 2025, while online pharmacies is the fastest-growing segment.
The global transdermal skin patches market size was estimated at USD 6.6 billion in 2025 and is expected to reach USD 7.1 billion in 2026.
The global transdermal skin patches market is expected to grow at a compound annual growth rate of 7.8% from 2026 to 2033 to reach USD 12.0 billion by 2033.
By type, the multi-layer drug-in-adhesive segment led with a 36.7% revenue share in 2025, while the matrix segment is the fastest-growing segment.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


