
- Home
- »
- Clinical Diagnostics
- »
-
UAE D2C Clinical Laboratory Diagnostics Market Report 2033GVR Report cover

UAE D2C Clinical Laboratory Diagnostics Market (2026 - 2033)
Sizing, Policy, And Future Trends (Macro Trends, Market And Innovation Trends)
Market Size, 2025
$71.2MMarket Estimate, 2026
$79.3MMarket Forecast, 2033
$175.3MCAGR, 2026–2033
11.9%UAE D2C Clinical Laboratory Diagnostics Market Summary
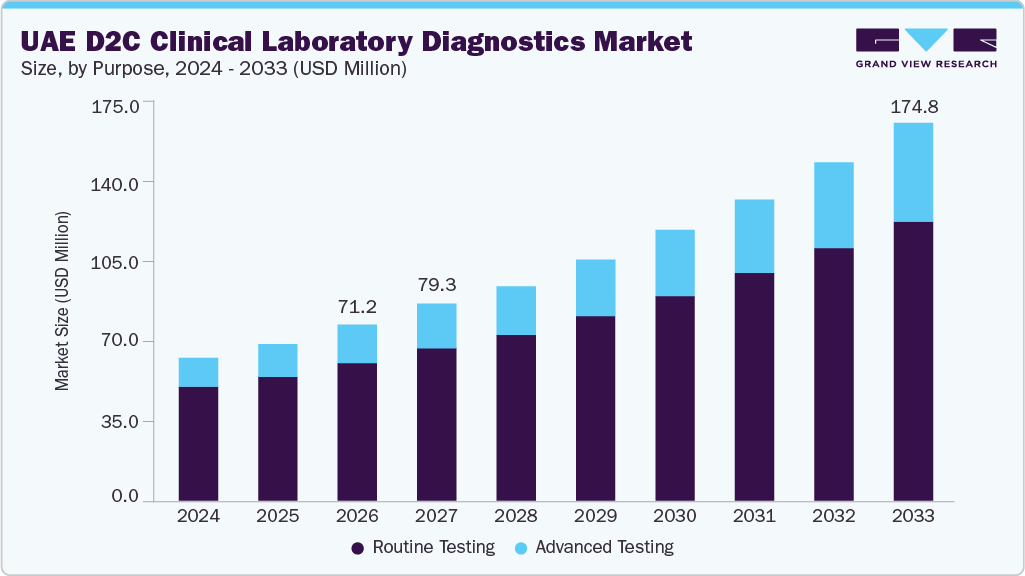
The UAE D2C clinical laboratory diagnostics market size was valued at USD 71.2 million in 2025 and is projected to grow from USD 79.3 million in 2026 to USD 175.3 million by 2033, at a CAGR of 11.9% from 2026 to 2033. The market is driven by increasing digital health adoption, growing consumer preference for preventive and personalized testing, expanding home-based sample collection services, and continued investments in AI-enabled diagnostics and integrated digital healthcare infrastructure.
Key Market Trends & Insights
- The Abu Dhabi D2C clinical laboratory diagnostics market accounted for the largest revenue share in the UAE in 2025.
- Based on purpose: Routine testing segment led the market with the largest revenue share of 78.4% in 2025.
- Based on channel: Home collection segment led the market with the largest revenue share of 59.8% in 2025.
- Based on willingness: Corporate wellness and employee health programs segment led the market with the largest revenue share of 65.5% in 2025.
- Based on specialty: Diabetes & metabolic health segment led the market with the largest revenue share of 18.2% in 2025.
Market Size & Forecast
- Market size in 2025: USD 71.2 Million
- Estimated market size in 2026: USD 79.3 Million
- Projected market size by 2033: USD 175.3 Million
- CAGR (2026-2033): 11.9%
Prism AI by Grand View Research Free to tryAsk a question about the UAE D2C clinical laboratory diagnostics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →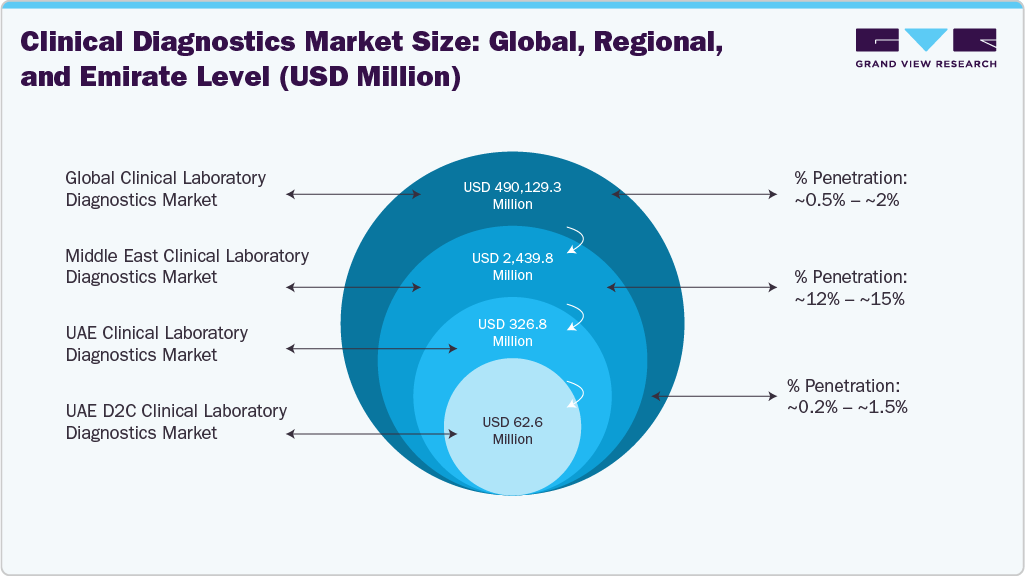 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The growing emphasis on preventive healthcare is accelerating the adoption of D2C clinical laboratory diagnostics across the UAE. Rising consumer demand for early disease detection, routine health assessments, and wellness-focused diagnostic services is driving greater utilization of direct-to-consumer testing. In response, healthcare providers are expanding preventive diagnostic offerings through home-based sample collection, employer-sponsored wellness programs, and digitally enabled service models. This shift from reactive disease management to proactive health monitoring is increasing testing volumes, broadening consumer access to diagnostic services, and supporting the sustained expansion of the UAE D2C clinical laboratory diagnostics market.
 To learn more about this report, Download Free Sample Report
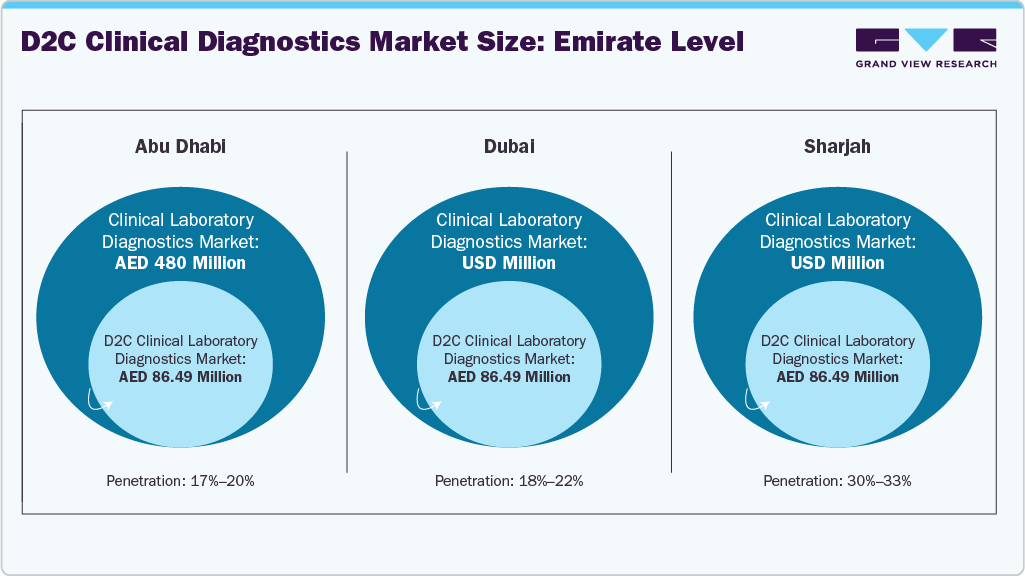
The UAE D2C clinical laboratory diagnostics market remains in the early stages of development, with significant growth potential driven by increasing preventive healthcare adoption and digital health readiness. While Dubai and Abu Dhabi account for the largest market share, Sharjah demonstrates comparatively higher D2C penetration, reflecting stronger consumer adoption of direct-to-consumer testing. Although physician-led diagnostics and limited insurance coverage continue to influence market penetration, evolving consumer preferences and expanding digital healthcare infrastructure are expected to support sustained market growth.
Abu Dhabi and Dubai account for the largest share of the UAE D2C clinical laboratory diagnostics market, supported by strong healthcare infrastructure, preventive health initiatives, and high digital adoption. Abu Dhabi leads through government-backed screening programs, while Dubai benefits from medical tourism and digital-first healthcare services. Sharjah, although smaller in market size, demonstrates strong demand for affordable routine diagnostics, highlighting the importance of accessibility and cost-effective testing in expanding D2C adoption across the UAE.
 To learn more about this report, Download Free Sample Report
Industry Standards and Regulatory Evolution
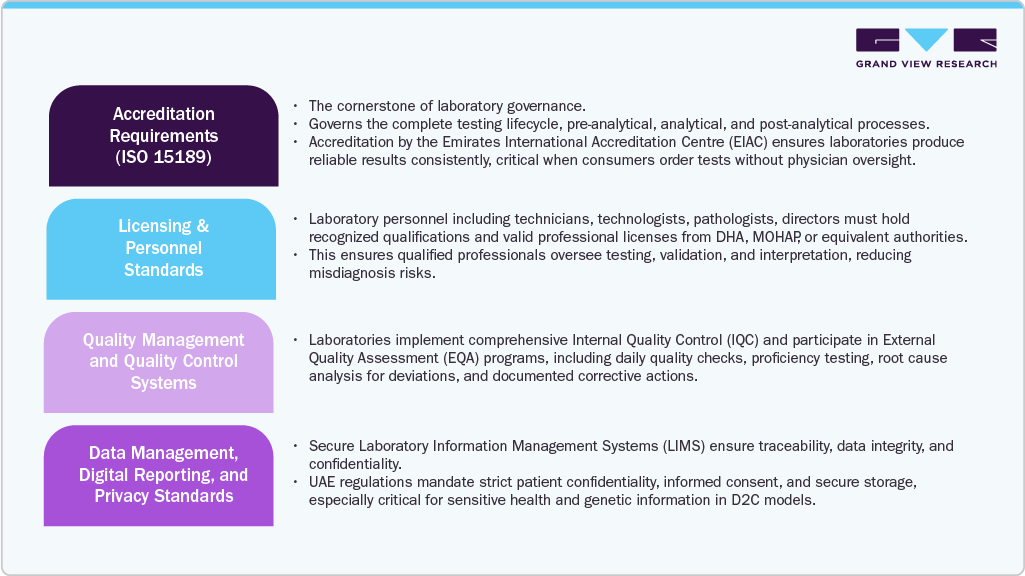
Regulatory Standards and Quality Frameworks: The UAE D2C clinical laboratory diagnostics market operates within a well-defined regulatory framework designed to ensure diagnostic quality, patient safety, and data security. International quality standards, mandatory laboratory accreditation, and stringent licensing requirements have established a trusted environment for consumer-initiated testing. As D2C diagnostics expand, compliance with these standards strengthens clinical reliability while supporting broader adoption of digital and home-based diagnostic services across the UAE.
 To learn more about this report, Download Free Sample Report
The UAE's robust regulatory framework provides a strong foundation for the expansion of the D2C clinical laboratory diagnostics market by ensuring high-quality testing, strengthening consumer confidence, and promoting standardized clinical practices. The coordinated oversight of federal and emirate-level authorities also supports digital health integration, responsible innovation, and sustainable long-term market growth.
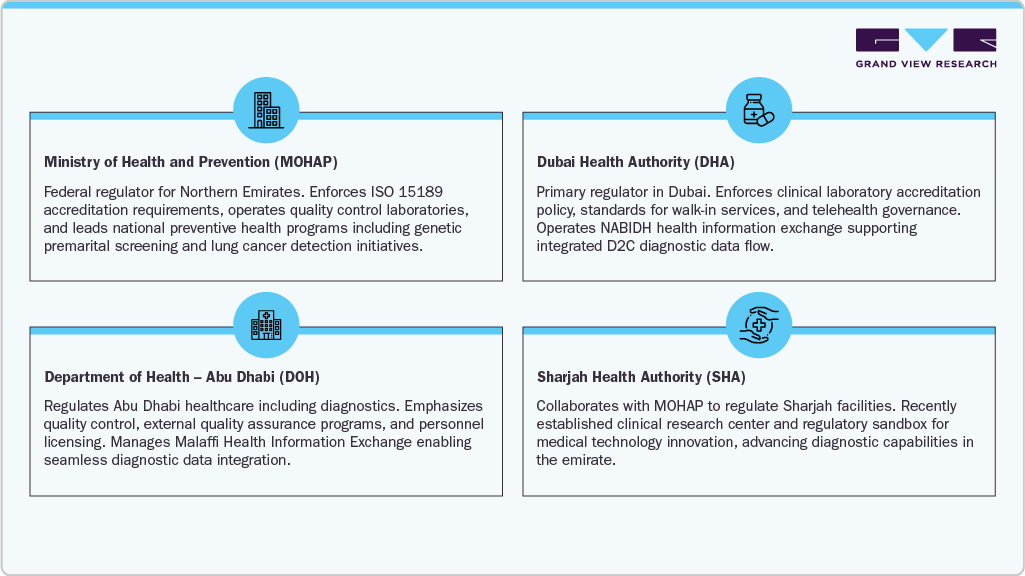
Licensing Authority And Their Potential Impact On The D2C Landscape
The UAE follows a multi-tier regulatory model in which federal and emirate-level authorities collectively oversee laboratory licensing, quality assurance, digital health integration, and consumer protection. This coordinated governance framework promotes standardized diagnostic practices while supporting innovation in direct-to-consumer healthcare services.
 To learn more about this report, Download Free Sample Report
Collectively, these regulatory authorities establish a robust governance framework that ensures consistent quality standards, strengthens consumer confidence, and supports the sustainable growth of the UAE D2C clinical laboratory diagnostics market through effective oversight and digital healthcare integration.
Ministry of Health and Prevention (MOHAP)
-
Higher Quality Standards:Mandatory ISO 15189 accreditation ensures consistent diagnostic quality and laboratory reliability.
-
Consumer Confidence:Standardized compliance enhances trust in D2C diagnostic services and supports wider market adoption.
-
Structured Market Entry:Regulatory requirements create a quality-driven and competitive operating environment.
Dubai Health Authority (DHA)
-
Standardized Operations:Ensures D2C diagnostic providers comply with the same quality standards as clinical laboratories.
- Patient Safety & Ethical Governance:Promotes responsible testing, transparent reporting, and ethical consumer engagement.
Department of Health (DoH)
-
Clinical Excellence:Enforces stringent quality and reporting standards to ensure accurate and clinically reliable diagnostic services.
- Defined Service Framework:Establishes clear guidelines for D2C diagnostic offerings, minimizing inappropriate or misleading service claims.
Advertising And Promotion In The D2C Space
Market and Innovation Trends: Strategic partnerships are playing an increasingly important role in the evolution of the UAE D2C clinical laboratory diagnostics market by expanding service accessibility, strengthening preventive healthcare delivery, and accelerating digital health adoption. Diagnostic providers are collaborating with employers, insurers, wellness platforms, telehealth providers, and technology companies to develop integrated diagnostic ecosystems that improve consumer convenience and engagement. These partnerships support corporate wellness initiatives, insurance-linked screening programs, and digital health platforms, enabling broader access to diagnostic services while improving operational efficiency. As collaborative care models continue to evolve, strategic alliances are expected to drive innovation, market expansion, and the adoption of consumer-centric diagnostic solutions across the UAE.
Digital-first marketing strategies are playing a pivotal role in expanding the UAE D2C clinical laboratory diagnostics market by improving consumer awareness, engagement, and service accessibility. Providers are leveraging search engine optimization, paid digital advertising, social media campaigns, multilingual educational content, and home-based service promotion to increase visibility and encourage preventive health screening. The integration of automated booking systems, personalized notifications, and digital communication channels is further enhancing the consumer experience and driving repeat utilization. The report evaluates the effectiveness of these promotional strategies and their impact on consumer acquisition, market penetration, and long-term growth of D2C diagnostic services.
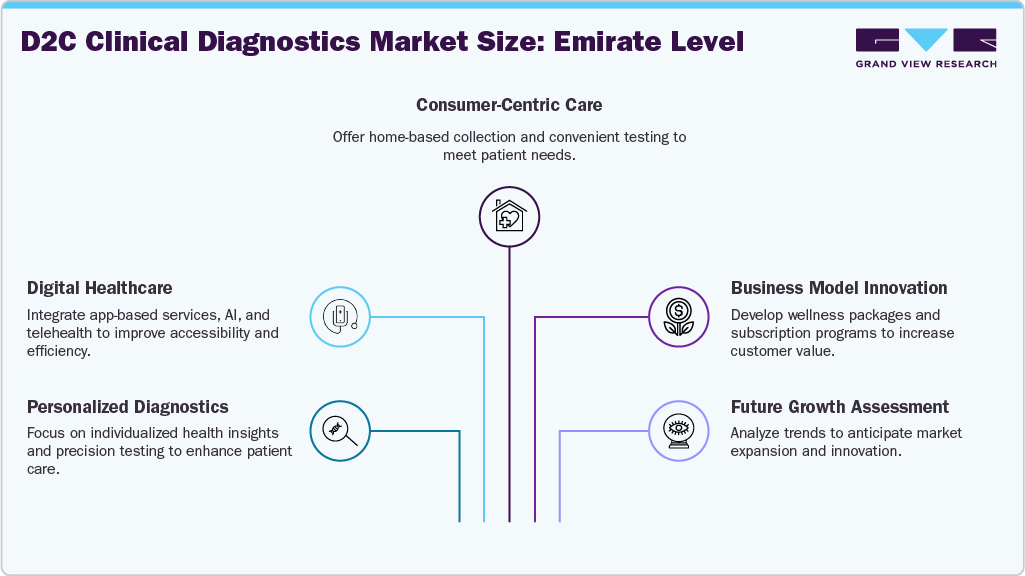
The UAE D2C clinical laboratory diagnostics market is undergoing a significant transformation, driven by the convergence of digital health technologies, consumer-centric care models, and preventive healthcare initiatives. The market is witnessing increasing adoption of AI-enabled diagnostics, personalized testing, home-based sample collection, telehealth integration, and digitally connected healthcare platforms that enhance accessibility and patient engagement. At the same time, strategic partnerships, wellness-focused diagnostic packages, and subscription-based service models are reshaping provider business strategies by strengthening customer retention and expanding market reach. These innovation-driven trends are expected to improve diagnostic accessibility, support preventive healthcare adoption, and create sustainable long-term growth opportunities across the UAE through 2033.
 To learn more about this report, Download Free Sample Report
Driver - Growing Preventive Health Awareness
Growing emphasis on preventive healthcare is accelerating the adoption of D2C clinical laboratory diagnostics across the UAE. Consumers are increasingly seeking routine health assessments, chronic disease screening, and wellness-focused diagnostic services to enable early disease detection and continuous health monitoring. In response, healthcare providers are expanding preventive testing through home-based sample collection, employer-sponsored wellness programs, and digitally enabled service models. This transition from reactive treatment to proactive health management is increasing testing frequency, strengthening consumer engagement, and supporting the sustained expansion of the UAE D2C clinical laboratory diagnostics market.
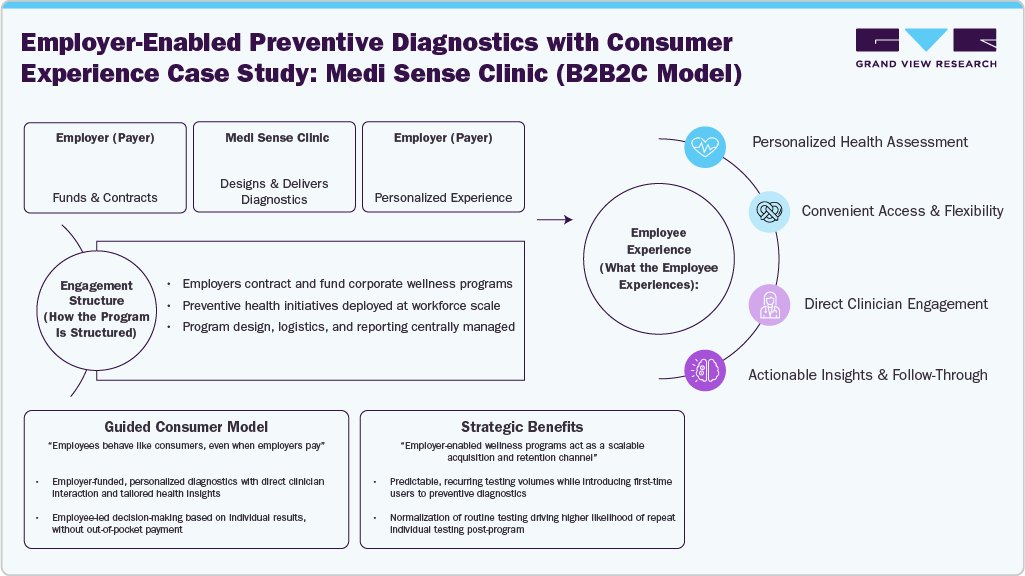
Case Study - Medi Sense Clinic
Medi Sense Clinic collaborates with employers to deliver preventive diagnostic programs in which organizations fund employee health assessments while the clinic manages testing, reporting, and personalized follow-up. The model improves participation in preventive screening, introduces consumers to D2C diagnostic services, and encourages continued engagement beyond employer-sponsored programs. This case illustrates how corporate wellness initiatives can expand access to preventive diagnostics, improve customer retention, and accelerate adoption of consumer-centric laboratory testing across the UAE.
 To learn more about this report, Download Free Sample Report
The UAE D2C clinical laboratory diagnostics market is evolving into a consumer-centric healthcare ecosystem, supported by rising preventive health awareness, digital healthcare adoption, and expanding home-based diagnostic services. Employer-sponsored wellness programs, personalized testing, and AI-enabled diagnostic platforms are improving accessibility and consumer engagement. As healthcare providers continue to strengthen digital capabilities and preventive care offerings, the market is well positioned for sustained long-term growth and increasing adoption across the UAE.
Purpose Insights
The routine testing segment accounted for the largest revenue share of 78.4% in 2025, driven by sustained demand for general health assessments, chronic disease monitoring, infection screening, and preventive wellness testing. High testing volumes from annual health check-ups, employer-sponsored screening programs, and routine physician referrals continue to support segment dominance. The widespread availability of digital appointment scheduling, walk-in laboratory services, and home sample collection has further improved accessibility and consumer adoption. For instance, in September 2025, the Ministry of Health and Prevention (MoHAP) launched the National Health Screening Campaign, expanding nationwide preventive screening for diabetes, hypertension, obesity, and cardiovascular risk factors across primary healthcare centers. Such initiatives are expected to increase routine diagnostic volumes and reinforce the long-term growth of routine laboratory testing services in the UAE.
The advanced testing segment is expected to witness the fastest growth over the forecast period, supported by increasing demand for precision diagnostics, genetic testing, advanced biomarker analysis, and comprehensive preventive health assessments. Rising consumer awareness of early disease detection, coupled with growing adoption of personalized healthcare and AI-enabled diagnostic technologies, is accelerating the uptake of high-value diagnostic services. The expansion of genomic medicine initiatives, digital health infrastructure, and specialized laboratory capabilities is further strengthening demand for advanced testing. As consumers increasingly seek predictive and personalized health insights beyond routine diagnostics, advanced testing is expected to become a key growth driver in the UAE D2C clinical laboratory diagnostics market through 2033.
Channel Insights
The home collection segment accounted for the largest revenue share of 59.8% in 2025, driven by growing consumer preference for convenient, time-efficient, and patient-centric diagnostic services. Increasing demand for at-home sample collection, digital appointment scheduling, and online report delivery has accelerated adoption, particularly among working professionals, elderly individuals, and patients requiring routine health monitoring. Healthcare providers continue to expand home collection capabilities through mobile phlebotomy services, telehealth integration, and digital health platforms, enhancing accessibility and service efficiency. For instance, in May 2026, PureLab, a subsidiary of PureHealth, launched its Home Collection Service across the UAE, expanding access to laboratory-quality diagnostics and reinforcing the country's transition toward preventive, patient-led healthcare. Such initiatives are expected to further strengthen consumer adoption of home-based diagnostics and reinforce the segment's leading position throughout the forecast period.
The walk-ins to healthcare facilities segment is expected to witness lucrative growth over the forecast period, supported by the continued expansion of outpatient healthcare infrastructure and increasing consumer demand for convenient access to diagnostic services. Walk-in facilities remain a preferred option for individuals seeking immediate testing, professional consultation, and rapid turnaround times, particularly for routine health assessments and preventive screening. Healthcare providers are further strengthening this channel through integrated digital appointment systems, enhanced laboratory capabilities, and comprehensive diagnostic service portfolios. For instance, in November 2025, Mediclinic Middle East launched a redesigned digital platform integrating appointment booking, teleconsultations, and medical records to enhance access to outpatient care and improve the overall patient journey. These advancements are expected to strengthen consumer engagement and create favorable growth opportunities for the walk-in segment during the forecast period.
Willingness Insights
The corporate wellness and employee health programs segment accounted for the largest revenue share of 65.5% in 2025, driven by the growing adoption of employer-sponsored preventive healthcare initiatives and increasing organizational focus on workforce well-being. Employers across the UAE are expanding access to routine health assessments, chronic disease screening, and wellness-focused diagnostic programs to improve employee health, productivity, and healthcare outcomes. The integration of digital health platforms and preventive diagnostic services is further strengthening participation in workplace wellness programs. For instance, in October 2025, MOHAP, FAHR, and Emirates Health Services launched the updated Ajr Wa Aafya initiative to simplify employee fitness screening and health services, reinforcing the role of preventive healthcare within workplace wellness programs across the UAE.
The individually driven segment is expected to register lucrative growth over the forecast period, driven by increasing consumer awareness of preventive healthcare, rising demand for personalized wellness monitoring, and the growing adoption of digitally enabled diagnostic services. Consumers are increasingly opting for self-initiated health assessments, routine screening, and wellness-focused testing to support early disease detection and proactive health management. The availability of convenient online booking platforms, digital health applications, and home-based diagnostic services is further enhancing accessibility and encouraging independent healthcare decision-making. These factors are expected to support sustained adoption of consumer-led diagnostic testing and create significant growth opportunities for the segment throughout the forecast period.
Specialty Insights
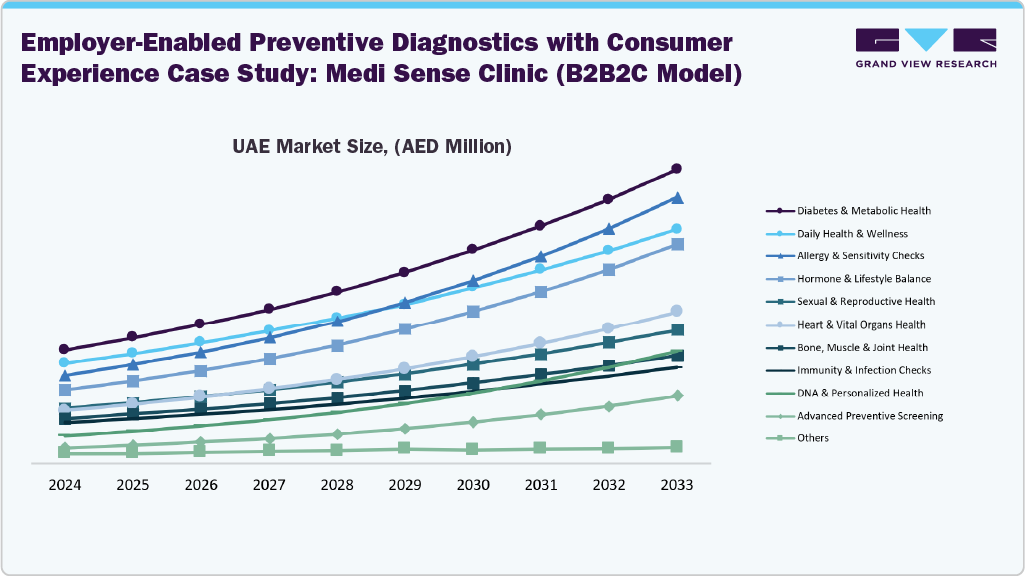
The diabetes & metabolic health segment accounted for the largest revenue share of 18.2% in 2025, driven by the high prevalence of diabetes and increasing demand for routine metabolic health monitoring across the UAE. According to the International Diabetes Federation (IDF), approximately 20.7% of the UAE adult population was living with diabetes in 2024, highlighting the significant need for early diagnosis and continuous disease management. Growing consumer awareness of preventive healthcare and expanding access to wellness-focused diagnostic services continue to support segment growth. In October 2025, the Department of Health Abu Dhabi introduced AI-enabled tools for the early detection of diabetes and other chronic diseases, reinforcing the country's focus on preventive screening and precision healthcare.
 To learn more about this report, Download Free Sample Report
The Advanced Preventive Screening segment is expected to register the fastest CAGR of 17.9% during the forecast period, driven by rising consumer awareness of early disease detection, increasing demand for comprehensive wellness assessments, and growing adoption of precision and predictive healthcare. Consumers are increasingly opting for advanced screening panels for cancer risk, cardiovascular health, genetic predisposition, and metabolic disorders to support timely intervention and personalized health management. Continuous advancements in diagnostic technologies, expanding availability of specialized screening programs, and the integration of digital health platforms are further enhancing access to preventive diagnostics. These factors are expected to accelerate the adoption of advanced preventive screening and support robust segment growth throughout the forecast period.
UAE Market Assessment
Abu Dhabi Clinical Laboratory Diagnostics Market Trends
The Abu Dhabi D2C clinical laboratory diagnostics market accounted for the largest revenue share of 37.1 2025, supported by strong government-led preventive healthcare initiatives, extensive public healthcare infrastructure, and high adoption of digital health technologies. Demand is driven by employer-sponsored wellness programs, preventive screening initiatives, and integrated diagnostic services aligned with the emirate's public health objectives. Abu Dhabi continues to strengthen its diagnostics ecosystem through investments in precision medicine and advanced laboratory capabilities. For instance, in January 2026, M42 expanded its Omics Centre capacity to accelerate genomic testing and precision medicine applications in Abu Dhabi, reinforcing the emirate's leadership in advanced diagnostics and personalized healthcare.
Dubai D2C Clinical Laboratory Diagnostics Market Trends
The Dubai D2C clinical laboratory diagnostics market is expected to witness significant growth, driven by a strong private healthcare sector, high digital health adoption, medical tourism, and increasing consumer spending on preventive healthcare. The emirate serves as the commercial hub for innovative diagnostic service models, supporting rapid adoption of personalized testing, wellness programs, and digitally enabled healthcare platforms. For instance, in February 2026, Fakeeh University Hospital expanded its preventive health screening portfolio by introducing AI-assisted executive health assessment programs integrated with digital patient management, strengthening Dubai's position as a leading center for premium preventive diagnostics.
Sharjah D2C Clinical Laboratory Diagnostics Market Trends
The Sharjah D2C clinical laboratory diagnostics market is emerging as a value-oriented market, supported by improving healthcare accessibility, growing preventive health awareness, and increasing demand for affordable diagnostic services. Standardized routine diagnostics and home-based testing continue to gain traction among price-conscious consumers, while investments in healthcare infrastructure are improving service availability. For instance, in May 2025, the Sharjah Health Authority established a Clinical Research Center and Regulatory Sandbox to accelerate healthcare innovation and support the adoption of advanced diagnostic technologies, strengthening the emirate's long-term diagnostic capabilities and innovation ecosystem.
Competitive Analysis
Competition Matrix Analysis: Regional Players
The competitive landscape of the UAE D2C clinical laboratory diagnostics market is increasingly defined by digital engagement rather than pricing alone. Digital-first providers such as Valeo Health and Justlife have established differentiated positions by combining premium service offerings with app-based consumer journeys, integrated home collection, and seamless digital experiences. In contrast, traditional laboratory and hospital-affiliated providers continue to compete on clinical credibility, geographic reach, and service breadth, but generally demonstrate lower levels of consumer engagement. As consumer expectations shift toward convenience, personalization, and end-to-end digital healthcare, sustained competitive advantage will increasingly depend on platform capabilities, user experience, and the ability to deliver integrated, consumer-centric diagnostic services beyond conventional laboratory testing.
Digital Experience: Regional Players
The digital maturity of the UAE D2C clinical laboratory diagnostics market remains differentiated across provider categories, with digital-native platforms demonstrating a clear competitive advantage over traditional laboratory operators. Companies such as Valeo Health and Justlife deliver integrated digital journeys through online booking, digital report access, teleconsultation, and corporate engagement platforms, strengthening customer convenience and retention. Established diagnostic laboratories and hospital-affiliated providers have largely adopted essential digital capabilities but continue to rely on conventional service delivery models with comparatively limited consumer engagement features. As the market evolves, digital experience, platform integration, and seamless patient interaction are expected to become critical competitive differentiators, influencing consumer preference, repeat utilization, and long-term market positioning.
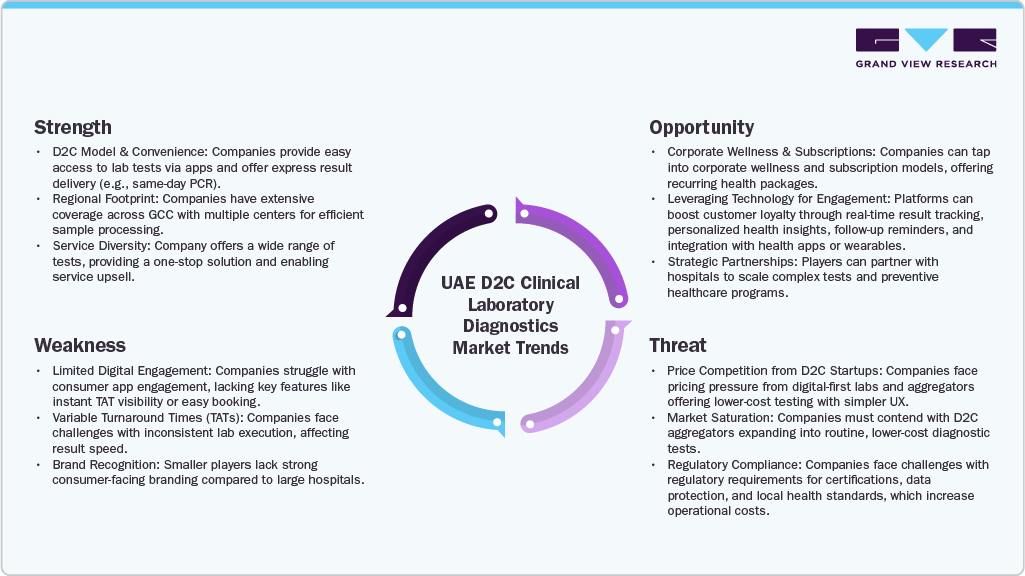
SWOT Analysis: Regional Players
The UAE D2C clinical laboratory diagnostics market is evolving into a digitally enabled, consumer-centric ecosystem driven by preventive healthcare, home-based testing, and integrated digital platforms. While established laboratory networks provide strong infrastructure and service capabilities, digital-first providers are reshaping competition through superior consumer engagement and convenience. Future growth will be supported by AI adoption, corporate wellness initiatives, and strategic partnerships, although increasing competition, regulatory compliance, and pricing pressures will require continuous innovation and service differentiation.
 To learn more about this report, Download Free Sample Report
Competitive Landscape: Local Players
The competitive landscape of local players in the UAE D2C clinical laboratory diagnostics market varies significantly across major emirates, reflecting differences in healthcare infrastructure, consumer behavior, and regulatory environments. Dubai has emerged as the most mature D2C ecosystem, where providers compete through digital-first platforms, home sample collection, and preventive wellness offerings. Abu Dhabi follows an institution-led model, with diagnostic services integrated into hospital networks, employer programs, and regulated healthcare pathways, emphasizing clinical quality and coordinated care. In contrast, Sharjah represents a hybrid market, balancing traditional walk-in diagnostics with selective adoption of digital booking and home collection services. These regional distinctions create diverse competitive strategies while collectively supporting the expansion of accessible, consumer-focused diagnostic services across the UAE.
Location
Providers
Digital Experience
Consumer Experience
Operating Model
Dubai
Housecall
Medlife
DIO Life
AIMS HealthcareOnline booking widely available
Digital report delivery is standard
App- or platform-led patient journeys are commonConsumer-led, convenience-first engagement
Home sample collection positioned as the default entry point
Preventive and wellness packages actively promotedPlatform-led
Home-first
Package-drivenAbu Dhabi
Mediclinic
Reem Hospital
First Response HealthcareDigital access through hospital or enterprise portals
Diagnostics embedded within structured healthcare systems
Limited consumer-focused digital UX; automation-related modules such as plate readers, cell prep modules, hotel systems, and incubators.Care-pathway-led experience
Diagnostics accessed via insurers, employers, or hospitals
Home collection positioned as a coordinated healthcare serviceInstitution-led
Regulated
Program-basedSharjah
Medsol
Diagnostics
HeyLabSelective digital booking availability
Limited app-based engagement
Digital reports offered by selected providers; loaders, cell prep modules, hotel systems, and incubators.Community-based experience
Walk-in and referral-led diagnostics remain prominent
Home collection positioned as a complementary serviceHybrid
Clinic-linked
Gradual Digital AdoptionUAE D2C Clinical Laboratory Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 71.2 million
Estimated Market size in 2026
USD 79.3 million
Projected Market size by 2033
USD 175.3 million
Growth rate
CAGR of 11.9% from 2026 to 2033
Base year for estimation
2025
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2024 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Purpose, channel, willingness, specialty
Key companies profiled
VALEO; Justlife; Life Diagnostics; Proficiency Healthcare Diagnostics (PHD); Aster DM Healthcare; Al Borg Diagnostics; UNILABS Middle East; First Response Healthcare; Mediclinic Middle East; and Vesta Care Home Health Center, Housecall, Medilife, DIO Life, AIMS Healthcare, Medsol Diagnostics, HeyLab, Mediclinic, and Reem Hospital.
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
UAE D2C Clinical Laboratory Diagnostics Market Segmentation
This report forecasts revenue and volume growth at the UAE level and provides an analysis of the latest market trends and opportunities across each segment from 2024 to 2033. For this study, Grand View Research has segmented the UAE D2C clinical laboratory diagnostics market based on purpose, channel, willingness, and specialty.
Purpose Outlook (Revenue, USD Million; Volume, Number of Orders, 2024 - 2033)
Channel Outlook (Revenue, USD Million; Volume, Number of Orders, 2024 - 2033)
Willingness Outlook (Revenue, USD Million; Volume, Number of Orders, 2024 - 2033)
Specialty Outlook (Revenue, USD Million; Volume, Number of Orders, 2024 - 2033)
Emirate Outlook (Revenue, USD Million; Volume, Number of Orders, 2024 - 2033)
Delivered Customizations
UAE D2C Clinical Laboratory Diagnostics Market.
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
UAE D2C Clinical Laboratory Diagnostics Competitive Landscape & Digital Benchmarking
Assessed the UAE D2C clinical laboratory diagnostics ecosystem by benchmarking leading regional and local providers based on digital experience, home sample collection, test portfolio, turnaround time, pricing strategy, engagement models, and competitive positioning. Evaluated platform capabilities, consumer experience, and market differentiation across major participants.
Enabled the client to benchmark competitors, identify digital differentiation opportunities, evaluate service gaps, and understand competitive positioning to strengthen market strategy and customer acquisition initiatives.
GCC Market Expansion Assessment
Evaluated market size, growth opportunities, regulatory landscape, competitive intensity, reimbursement environment, and consumer adoption trends across Saudi Arabia, Qatar, Kuwait, Oman, and Bahrain to identify priority expansion markets and commercialization opportunities.
Helped the client prioritize high-potential GCC markets, optimize regional expansion strategy, assess country-specific entry barriers, and identify investment opportunities for sustainable business growth.
Market Entry & Commercialization Strategy
Assessed commercialization pathways, partnership opportunities, pricing models, distribution channels, employer wellness collaborations, home diagnostics strategy, regulatory requirements, and go-to-market approaches for launching and scaling D2C laboratory diagnostic services across the UAE.
Supported strategic decision-making by identifying optimal market entry routes, partnership opportunities, commercialization risks, and scalable business models, enabling faster market penetration and long-term competitive advantage.
Frequently Asked Questions About This Report
The UAE D2C clinical laboratory diagnostics market was valued at USD 71.2 million in 2025 and is estimated at USD 79.3 million in 2026 to USD 175.3 million by 2033.
The UAE D2C clinical laboratory diagnostics market is growing at a CAGR of 11.9% from 2026 to 2033 to reach USD 175.3 million by 2033.
Based on purpose, the routine testing segment led the market with the largest revenue share of 78.4% in 2025.
The Abu Dhabi D2C clinical laboratory diagnostics market accounted for the largest revenue share in the UAE in 2025.
The market is driven by increasing digital health adoption, growing consumer preference for preventive and personalized testing, expanding home-based sample collection services, and continued investments in AI-enabled diagnostics and integrated digital healthcare infrastructure.
Abu dhabi is the fastest growing emirates in the UAE D2C Clinical Laboratory Diagnostics market.
The UAE D2C clinical laboratory diagnostics market have several operating players including VALEO, Justlife, Life Diagnostics, Proficiency Healthcare Diagnostics (PHD), Aster DM Healthcare, Al Borg Diagnostics, UNILABS Middle East, First Response Healthcare, Mediclinic Middle East, and Vesta Care Home Health Center, Housecall, Medilife, DIO Life, AIMS Healthcare, Medsol Diagnostics, HeyLab, Mediclinic, and Reem Hospital.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


