
- Home
- »
- Beauty & Personal Care
- »
-
U.S. Color Cosmetics Market Size And Share Report, 2033GVR Report cover

U.S. Color Cosmetics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Face Color Cosmetics, Lip Color Cosmetics, Eye Color Cosmetics), By Distribution Channel (Specialty Beauty Stores, Online/E-commerce), And Segment Forecasts
Market Size, 2025
$23.3BMarket Estimate, 2026
$25.3BMarket Forecast, 2033
$44.5BCAGR, 2026–2033
8.4%U.S. Color Cosmetics Market Summary
The U.S. color cosmetics market size was valued at USD 23.3 billion in 2025 and is projected to grow from USD 25.3 billion in 2026 to USD 44.5 billion by 2033, at a CAGR of 8.4% from 2026 to 2033. The growth of e-commerce platforms and technological advancements has greatly reshaped the color cosmetics industry.
Key Market Trends & Insights
- By product: Face color cosmetics segment held the largest market share of 38.8% in 2025.
- By distribution channel: Hypermarkets & supermarkets segment held the largest market share of 34.2% in 2025.
Market Size & Forecast
- Market size in 2025: USD 23.3 Billion
- Estimated market size in 2026: USD 25.3 Billion
- Projected market size by 2033: USD 44.5 Billion
- CAGR (2026-2033): 8.4%
GVR research-powered AIAsk Prism AI about the U.S. color cosmetics marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
Consumers now enjoy easier access to a diverse selection of products, while brands can connect with a wider audience through digital channels. Innovations like augmented reality (AR) virtual try-ons have elevated the online shopping experience by enabling users to preview products before buying. This digital transformation has enhanced both convenience and personalization, playing a key role in driving market expansion.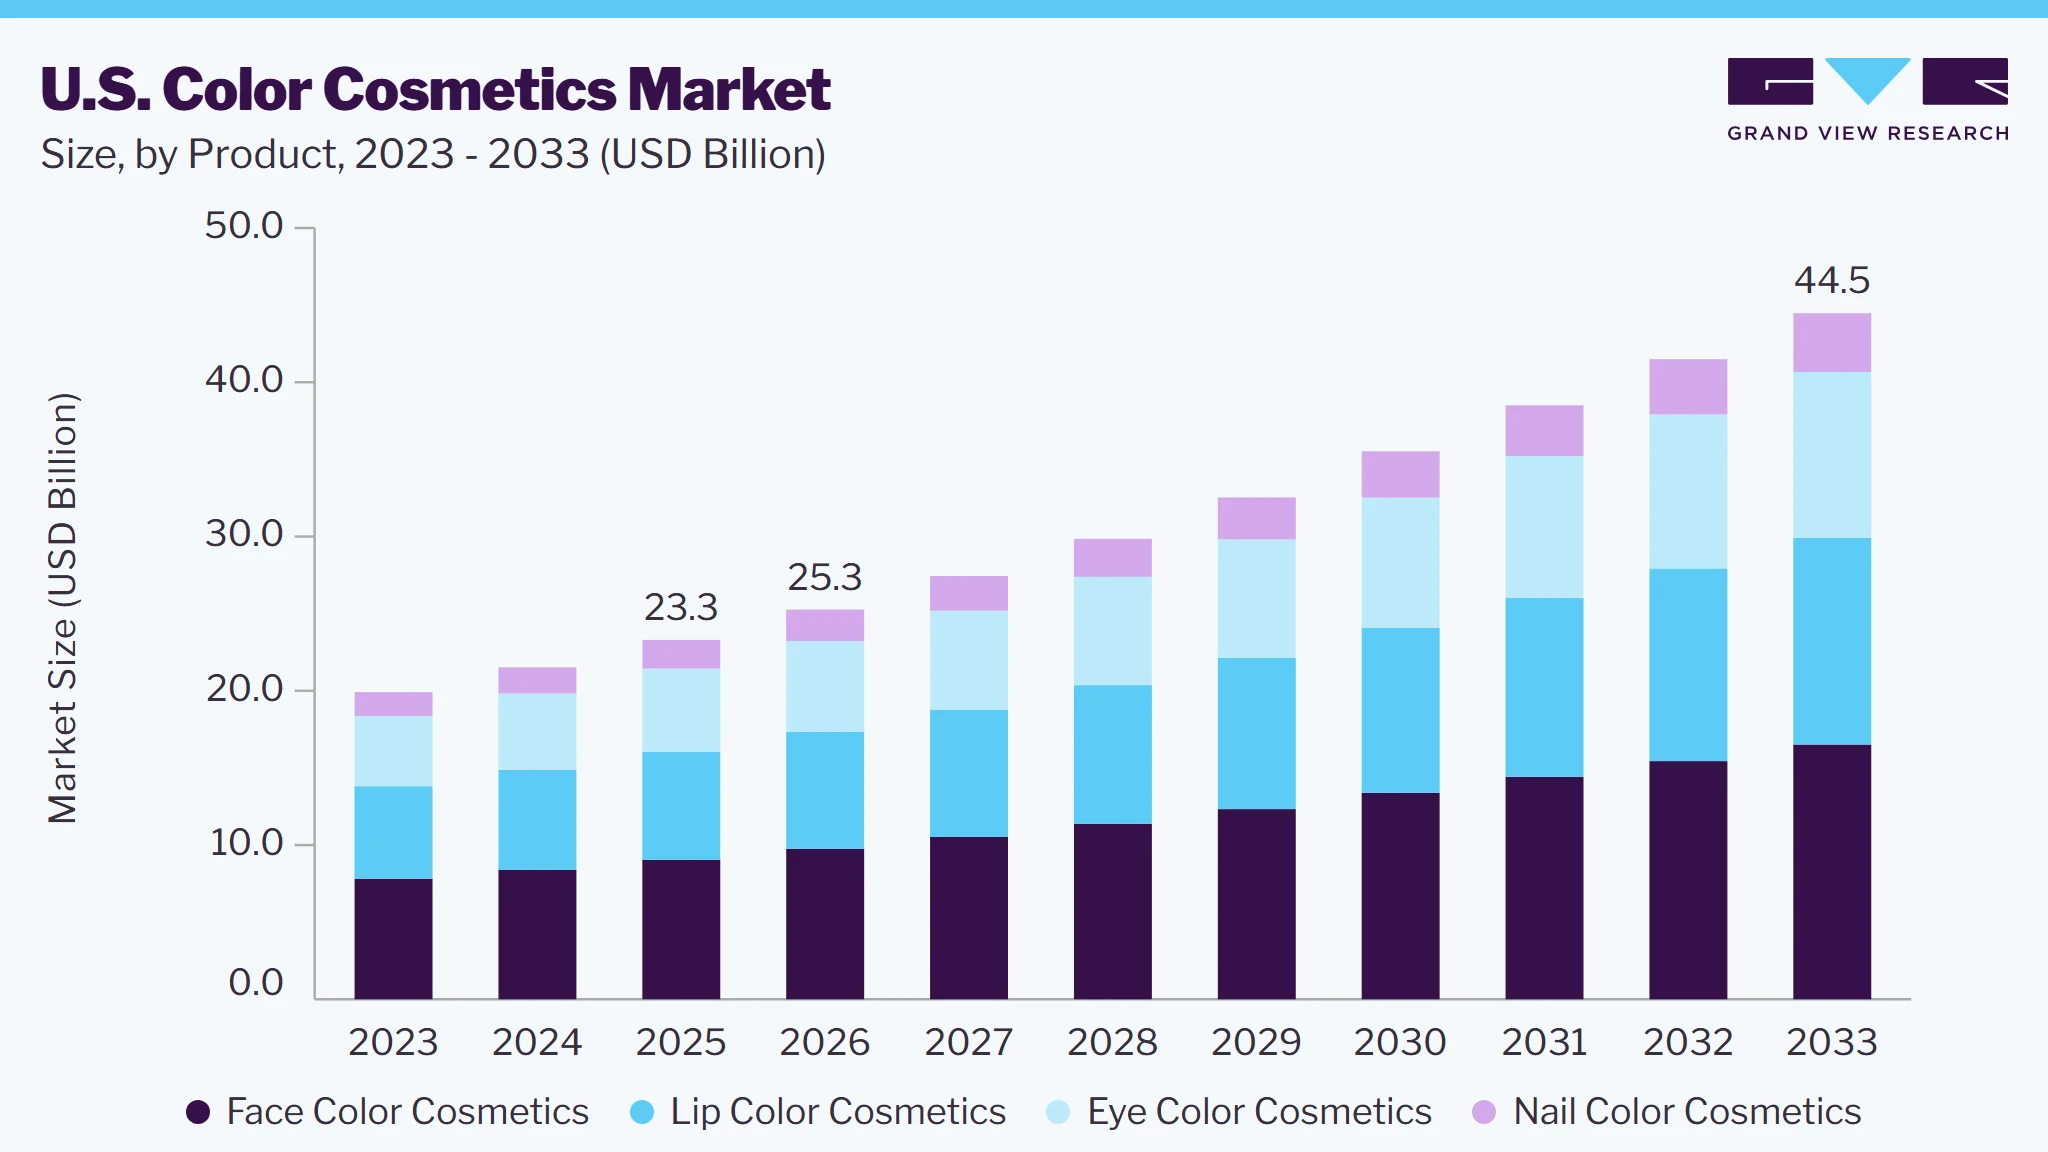 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Social media platforms like Instagram, YouTube, and TikTok have become crucial in shaping beauty trends and influencing consumer preferences. Beauty influencers and makeup artists use these platforms to share tutorials, product reviews, and new techniques, which greatly affect purchasing decisions. Brands are increasingly turning to social media to launch products, engage with their audiences, and create viral trends that boost sales and foster brand loyalty. In 2024, the men's grooming and skincare market is rapidly growing, driven by shifting societal norms and the influence of platforms like TikTok, where hashtags like #mensskincare have gone viral. More men are embracing skincare and beauty routines, prompting brands to expand product lines tailored to male consumers. This trend reflects changing attitudes toward masculinity and highlights how social media is shaping both consumer behavior and marketing strategies in the beauty industry.
Alongside this digital influence, there is a rising consumer demand for natural and organic color cosmetics. Shoppers prioritize products made with natural ingredients, cruelty-free practices, and eco-friendly packaging. This shift toward sustainability is encouraging many brands to reformulate their offerings and adopt more transparent and responsible supply chains to meet consumer expectations. A recent Nosto report highlights that 68% of consumers look for products labeled as “clean,” and 59% are influenced by products advertised as “natural and organic.” This trend reflects a growing awareness of the impact of synthetic chemicals on health and the environment.
Modern consumers seek beauty solutions that enhance appearance and support skin health. This demand has led to the development of hybrid products that combine makeup's aesthetic qualities with skincare's nourishing properties. Products infused with ingredients like hyaluronic acid, peptides, niacinamide, foundations with SPF protection, or hydrating lipsticks, aligning with the wellness-driven approach of modern consumers, are becoming increasingly popular. These components offer benefits such as hydration, anti-aging effects, and improved skin texture, making them appealing to consumers seeking both cosmetic enhancement and skincare benefits. This trend reflects a broader shift towards 'skinification,' in which makeup products are formulated to support skin health, blurring the lines between skincare and cosmetics. As consumers become more informed and health-conscious, the demand for products that offer dual benefits continues to rise, driving the growth of the color cosmetics market in the U.S.
The growing emphasis on inclusivity and diversity in the U.S. color cosmetics industry significantly influences its expansion. Consumers increasingly expect beauty brands to offer products that cater to a wide range of skin tones and reflect diverse identities. This shift is not merely a trend but a response to a long-standing demand for representation and equity in the beauty industry. Brands that prioritize inclusivity are seeing positive consumer responses. For instance, offering a broad spectrum of foundation shades allows individuals to find products that match their unique skin tones, fostering a sense of belonging and validation. This approach not only meets the practical needs of consumers but also builds brand loyalty and trust. Moreover, inclusivity extends beyond product offerings to encompass marketing strategies. Brands that feature diverse models and authentic narratives in their advertising resonate more deeply with a wide audience. Such representation ensures that all consumers feel seen and valued, which can enhance a brand's reputation and consumer engagement.
Major Trends in the U.S. Color Cosmetics Market
Trend Details Makeup is shifting from color-only products to skincare-infused formulations
U.S. consumers are increasingly looking for makeup that delivers both cosmetic coverage and skincare benefits. In 2024, prestige lip sales grew 19%, driven by hybrid formats such as lip oils and balms, while face makeup with moisturizing, brightening, and mattifying claims outperformed comparable skincare products. In 2025, this continued through hybrid lip treatments and complexion products. Recent examples include Glow Recipe Watermelon Glow Niacinamide Hue Drops, which combine a bronze tint with niacinamide-based skincare, and Merit The Uniform Tinted Mineral Sunscreen SPF 45, combining complexion coverage with mineral SPF.
Lip products are moving toward treatment-led formats
Lip oils, balms, liners, stains, and treatment products continue to outperform traditional lipstick formats. In the first half of 2025, lip was the strongest contributor within U.S. prestige makeup, while lip products were the only makeup area showing growth in the mass channel. Circana specifically identified hybrid tint-and-skincare products, lip contouring, lip liner, oils, and treatments as major areas of momentum. Recent launches and product development increasingly combine hydration, barrier care, shine, tint, and longer wear.
Blush and bronzer are expanding through new textures and formats
Face color is moving beyond traditional powder blush toward liquid, cream, balm, stick, jelly, and hybrid formats. U.S. sales data show continued strength in blush and bronzer, with 2026 data indicating double-digit growth for both in prestige makeup. Product launches increasingly emphasize buildability, glow, hydration, portability, and easy application. Examples include Rhode Pocket Blush, Milk Makeup Cooling Water Jelly, NARS The Multiple, and Charlotte Tilbury Unreal Lip + Cheek Glow Blush Stick.
Lightweight complexion products are replacing heavy foundation routines
The U.S. complexion category is increasingly shifting toward skin tints, tinted moisturizers, serum foundations, lightweight concealers, and buildable coverage rather than traditional full-coverage foundation. Allure’s 2025 product coverage highlights the expansion of skin tints and tinted moisturizers across finishes and levels of coverage. Examples include Wyn Beauty Hydrating Skin Enhancing Tint SPF 30, Supergoop! Protec(tint) SPF 50, and Fenty Beauty Hydra Vizor Huez Tinted Moisturizer SPF 30.
K-beauty is influencing U.S. makeup textures and application styles
K-beauty is increasingly influencing U.S. color cosmetics through sheer coverage, blurred lips, glossy tints, cushion-like textures, dewy finishes, blonzer formats, and multi-use products. Allure identified K-beauty as a major influence on 2025 U.S. makeup trends, while Beauty Independent reported the U.S. arrival of additional Korean makeup brands, including Amuse, Entropy, Two Slash Four, Unleashia, and Dinto, through a 2025 U.S. launch platform.
Expressive eye makeup is returning after the minimalist makeup cycle
Eye makeup is moving beyond the subdued “clean girl” aesthetic toward shimmer, metallics, glitter, colored mascara, graphic liner, multidimensional shadows, and larger palettes. Prestige eye makeup returned to growth in 2025 after declining in 2024, supported partly by mascara. By late 2025, major brands were launching new 8-, 12-, and 18-pan palettes featuring multichromes, metallics, pearls, and glitter.
Market Dynamics
U.S. color cosmetics are benefiting from consumers’ willingness to experiment with trend-driven products, new formats, and lower-priced alternatives rather than committing to expensive, traditional products. This supports frequent purchases of lip liners, lip oils, blush, bronzer, and makeup sets, while encouraging brands to launch products aligned with fast-moving beauty trends. The trend is particularly relevant as consumers increasingly balance novelty with affordability. In 2025, only 14% of U.S. beauty buyers said higher prices indicate better quality, while value-priced prestige and premium-priced mass brands outperformed their counterparts. In addition, in 2026, U.S. mass-market makeup sales increased 5%, with growth concentrated in lip liner, blush, bronzer, and makeup combination products.
Higher costs for specialty pigments, active ingredients, sustainable packaging, and formulation testing can increase color-cosmetics prices and pressure brand margins. Smaller brands face additional challenges when scaling compliant formulations across multiple shades, finishes, and product formats. Frequent reformulation requirements can also disrupt product consistency and increase development costs, particularly for products positioned around clean, vegan, or sensitive-skin claims.
Hybrid products combining makeup with targeted skincare benefits offer brands an opportunity to increase product value without relying solely on color or finish. Foundations with SPF, complexion products with niacinamide, peptide-infused lip treatments, and barrier-supporting blushes can address both cosmetic and skincare needs, creating opportunities for premiumization and higher purchase frequency.
Consumer Insights & Surveys
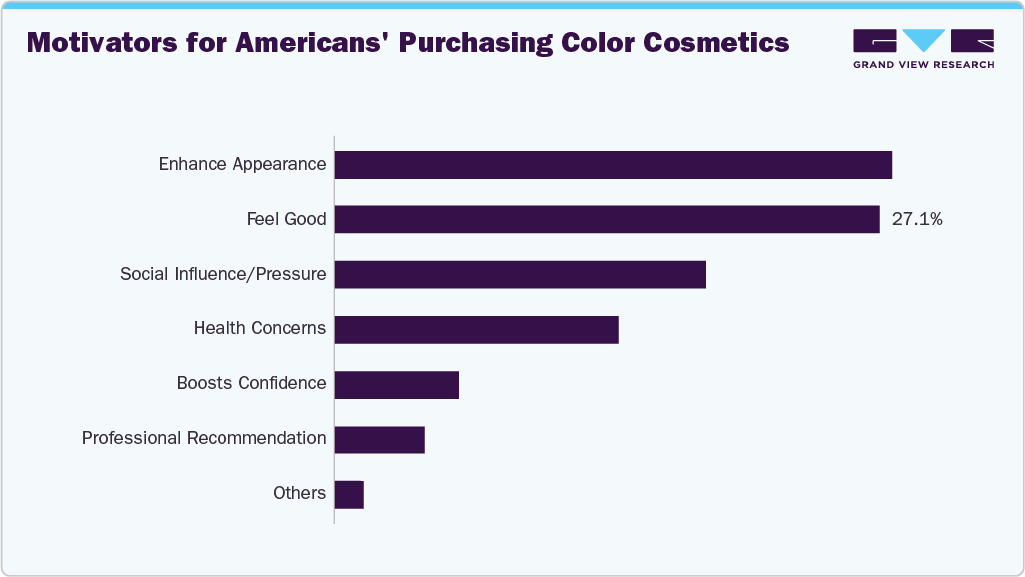
According to the survey conducted by Grand View Research of over 500 Americans, the findings show that Beauty and confidence are key motivators behind the purchase of skincare and cosmetics, though several other factors also influence consumer choices.
 To learn more about this report, Download Free Sample Report
A majority of respondents-56%-identified the desire to enhance their appearance as the main reason for buying these products. Close behind, 55.6% said they make such purchases to feel better about themselves. Additionally, 37% of participants reported using skincare and cosmetics to boost their self-confidence, underscoring the empowering effect these products can have on self-esteem.
The frequency of color cosmetics purchases in the U.S. reveals that beauty shopping forms a regular part of the monthly routine for 23.4% of Americans, who may prioritize beauty as part of their lifestyle or profession. In comparison, 26% opt to refresh their beauty collections every few months to stay up to date. Among more dedicated beauty enthusiasts, 22% engage in weekly purchases, often to keep up with the latest trends and product launches. Interestingly, 19.9% of respondents reported never purchasing color cosmetics, indicating a notable segment that is either uninterested in or does not use these products-potentially due to personal preference, demographic differences, or lifestyle choices. Only 8.7% of consumers make such purchases annually, reflecting that cosmetics are generally viewed as more routine than one-off buys.
 To learn more about this report, Download Free Sample Report
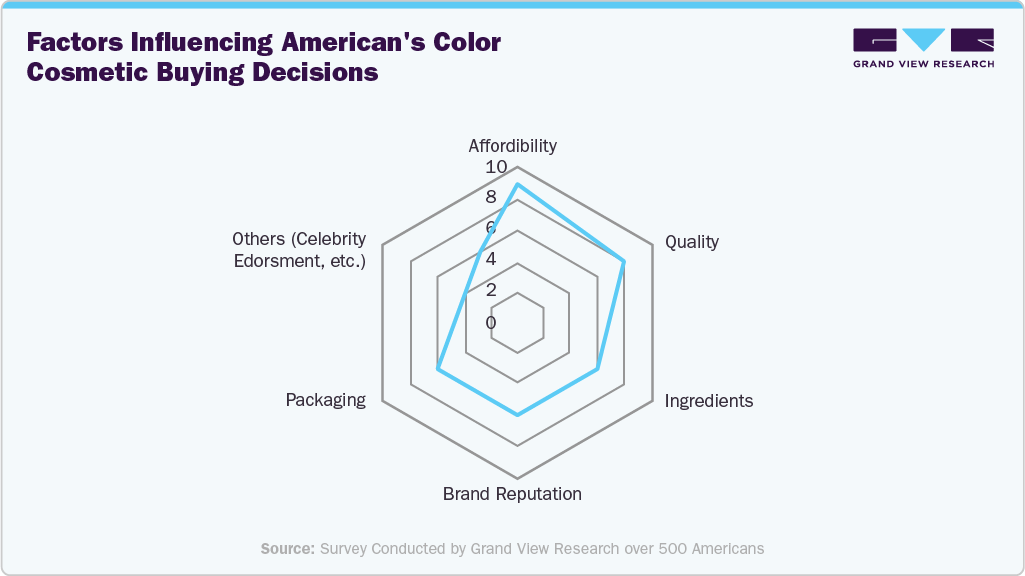
When selecting skincare and cosmetic products, a vast majority of Americans-around 90%-prioritize affordability, closely followed by quality, which is important to roughly 80% of consumers. These two factors stand out as the most influential in driving purchase decisions. Ingredients are also a key consideration for about 60% of buyers, underscoring a strong consumer preference for products made with natural, effective ingredients. Though brand reputation still matters to approximately 50% of consumers. Meanwhile, packaging appeals to about 30%, showing that aesthetic presentation plays a moderate role in product appeal. Celebrity endorsements, however, have minimal impact-only about 10% of respondents consider them influential in their decision-making process. This suggests that authenticity and value outweigh star power in beauty purchases.
Gen Z Is Highly Engaged With Makeup Despite Representing a Smaller Shopper Base
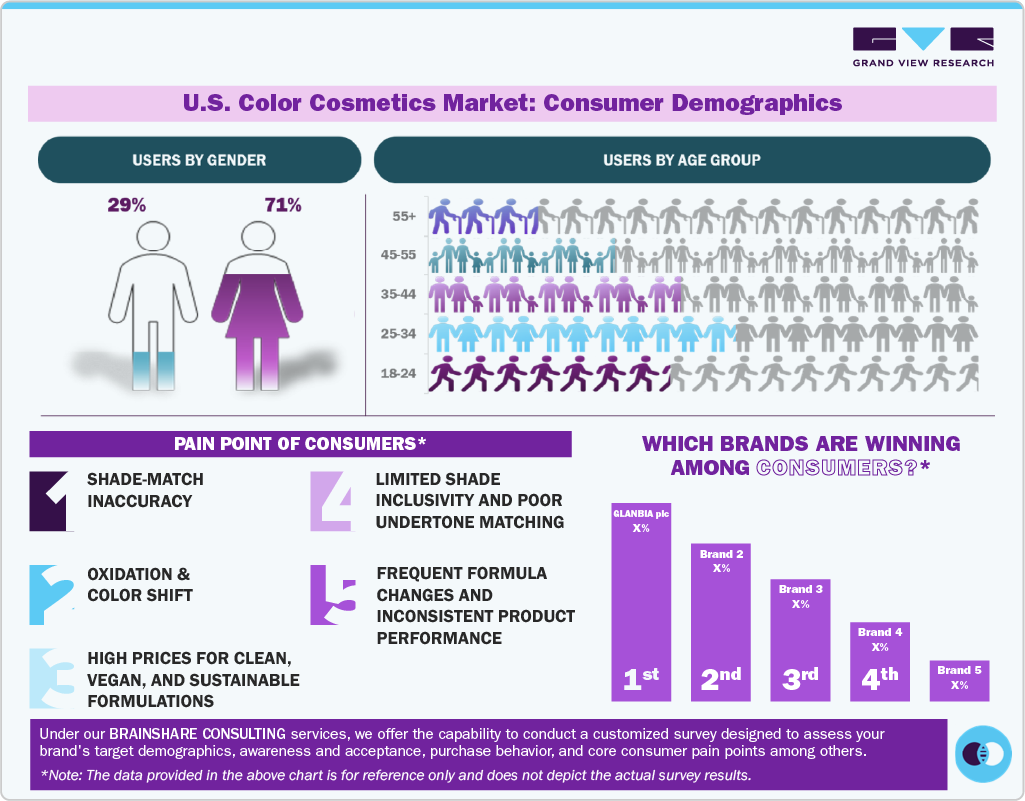
Gen Z accounted for 23% of U.S. color-cosmetic shoppers, but 71% of Gen Z consumers use makeup, highlighting significantly higher category engagement within the generation. YouGov found that Gen Z is more likely to use lip gloss (19%) and concealer (16%), while 34% prioritize natural or organic ingredients and 44% look for products suited to their specific skin type. BCG's 2025 U.S. survey of more than 1,200 teens also found that younger consumers are entering beauty earlier and spending more.
Price and Product Value are Reshaping Makeup Purchase Behavior
Price has become a particularly important purchase criterion as consumers evaluate makeup across mass, masstige, and prestige tiers. Tinuiti's 2025 U.S. beauty study found that 65% of consumers selected price as one of their three most important purchase influences, ahead of quality and brand name. YouGov's 2025 dupe study found that 9% of U.S. adults had knowingly purchased a makeup dupe, increasing to 17% among 18-34-year-olds; 44% of dupe buyers cited lower cost, while 43% believed the quality was close to the original.
Social Discovery is Converting Makeup Trends into Purchase Opportunities
Digital discovery has become particularly important for color cosmetics because products are highly visual and easily demonstrated through short-form content. YouGov's 2026 analysis found that 11% of U.S. adults had spent USD100+ on makeup in the previous three months, rising to 15% among women and 25-34-year-olds. Among daily TikTok users who discover products through influencers and have spent at least USD 25 on makeup, e.l.f.'s ad awareness reached 30%, versus 7% among the general population; NYX reached 13%, versus 3%.
 To learn more about this report, Download Free Sample Report
Analyst Perspective
The U.S. color cosmetics market is evolving from conventional makeup toward multifunctional, skincare-infused, and trend-led formulations, with growth concentrated across complexion, lip, blush, and hybrid products. Consumers continue to balance accessible mass and masstige offerings with prestige and luxury makeup, while demanding broader shade ranges, longer wear, skin-compatible formulations, and convenient formats. Product innovation is increasingly focused on skin tints, lip oils, cream and liquid blushes, multi-use sticks, treatment-infused makeup, and SPF-infused complexion products. Social-led beauty trends are accelerating product discovery and shortening innovation cycles, while MoCRA is increasing compliance requirements for product safety, facility registration, adverse event reporting, and cosmetic records.
Product Insights
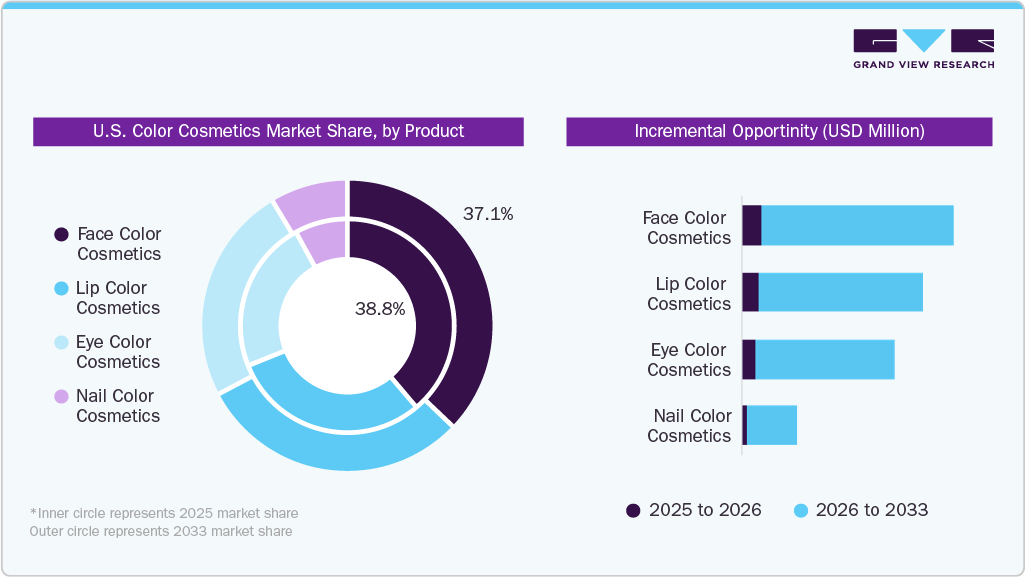
The facial color cosmetics segment led the market with the largest revenue share of 38.8% in 2025, due to its essential role in daily beauty routines and the wide variety of products it encompasses. Items such as foundations, concealers, blushes, primers, and setting powders are fundamental for creating a flawless base, making them indispensable for many consumers. This segment's dominance is further reinforced by the growing consumer demand for products that enhance appearance and offer skincare benefits, reflecting a trend toward multifunctional beauty solutions. India-based beauty brand Ibaeuty expanded its gender-neutral product offerings with the launch of 'Gulabo' in May 2024. Designed for brown skin tones, Gulabo is a hybrid product that combines skincare and makeup, providing a pink tint while addressing skin concerns like inflammation and breakouts. The product is marketed as gender-neutral, aligning with Ibaeuty's philosophy of inclusivity and breaking conventional beauty standards.
 To learn more about this report, Download Free Sample Report
The nail color cosmetics segment is projected to grow at the fastest CAGR of 9.4% from 2026 to 2033. The rising demand for nail color cosmetics in the U.S. is largely fueled by the growing popularity of do-it-yourself (DIY) beauty routines and significant advancements in product formulations. Brands like Olive & June have tapped into this trend by offering comprehensive at-home gel systems that allow consumers to achieve salon-quality manicures conveniently and affordably. At the same time, innovations such as gel-based, breathable, and non-toxic nail polishes have appealed to health-conscious consumers. These products, often labeled as "3-free," "5-free," or even "10-free," eliminate harmful chemicals without compromising on quality or durability, highlighting the industry's commitment to safer, more consumer-friendly solutions.
Distribution Channel Insights
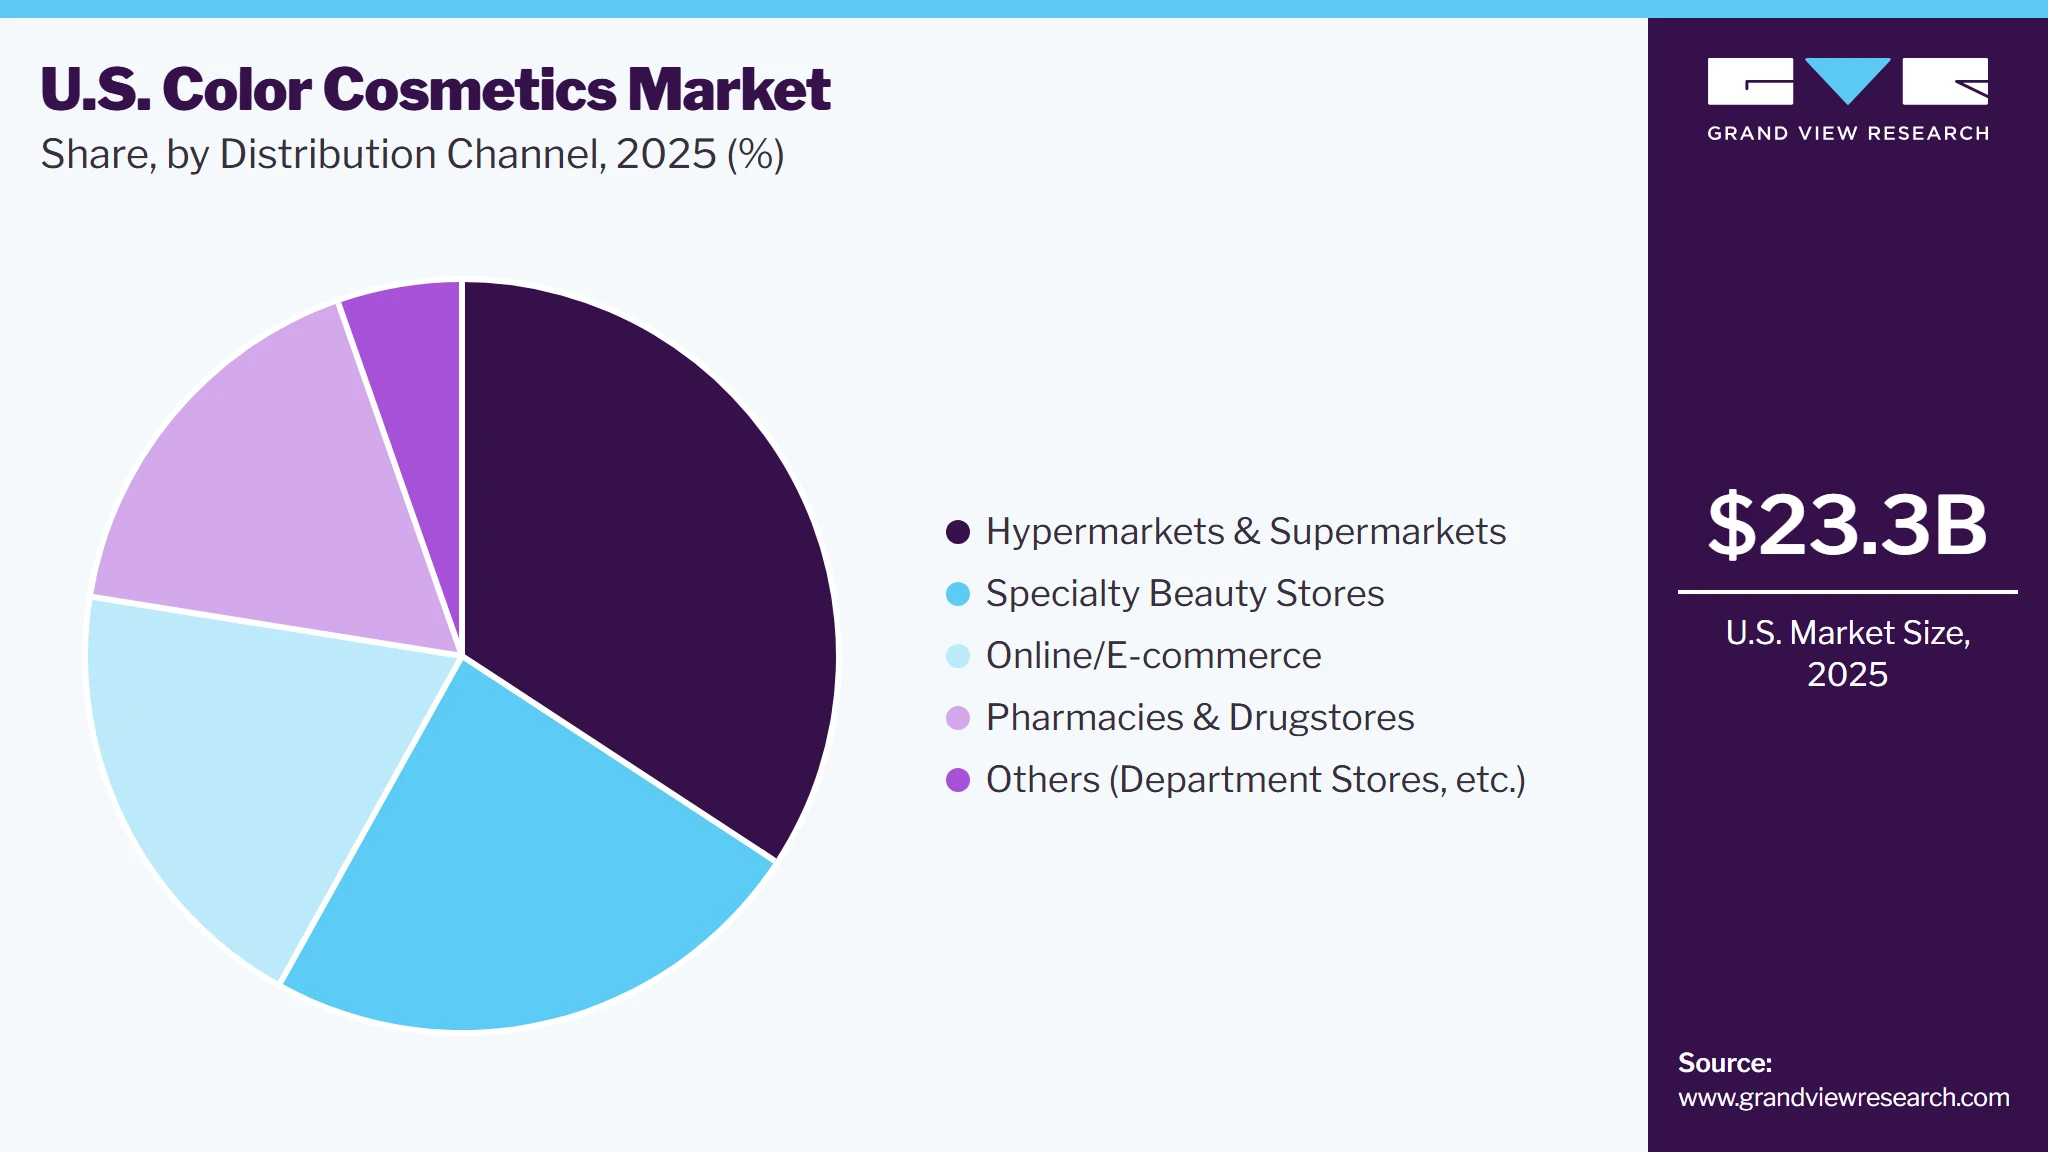
The hypermarkets and supermarkets segment led the market with the largest revenue share of 34.2% in 2025. The retail formats offer unparalleled convenience and accessibility. Consumers can purchase cosmetics alongside their regular grocery shopping, streamlining their shopping experience. This one-stop-shop approach caters to time-conscious shoppers who prefer to consolidate their purchases in a single location. Moreover, the physical presence of products allows customers to examine items firsthand, fostering immediate purchasing decisions and enhancing customer satisfaction.
 To learn more about this report, Download Free Sample Report
In response to tightening profit margins in traditional grocery sectors, supermarkets are diversifying their product offerings to include higher-margin items like beauty products. By expanding their beauty aisles, retailers aim to increase overall profitability and attract a wider customer base interested in affordable yet quality cosmetics. Retailers are increasingly partnering with popular and emerging beauty brands to offer trendy, affordable products that resonate with consumers. For instance, Kroger's collaboration with MCoBeauty introduces over 250 new beauty products, providing customers with access to fashionable cosmetics at accessible price points.
The online segment is projected to grow at the fastest CAGR of 10.1% from 2026 to 2033. Online channels have revolutionized the U.S. color cosmetics industry, enabling brands to transcend effortlessly. This expands market penetration and enhances brand visibility and accessibility to a diverse consumer base presented in the U.S. Moreover, advanced algorithms and sophisticated customer data analytics empower brands to deliver personalized shopping experiences. By analyzing consumer preferences and behavior, brands can offer tailored product recommendations, targeted promotions, and customized marketing campaigns. This personalized approach fosters stronger customer engagement and increases satisfaction and loyalty, driving growth in the competitive color cosmetics landscape.
Cross-Segmentation Analysis
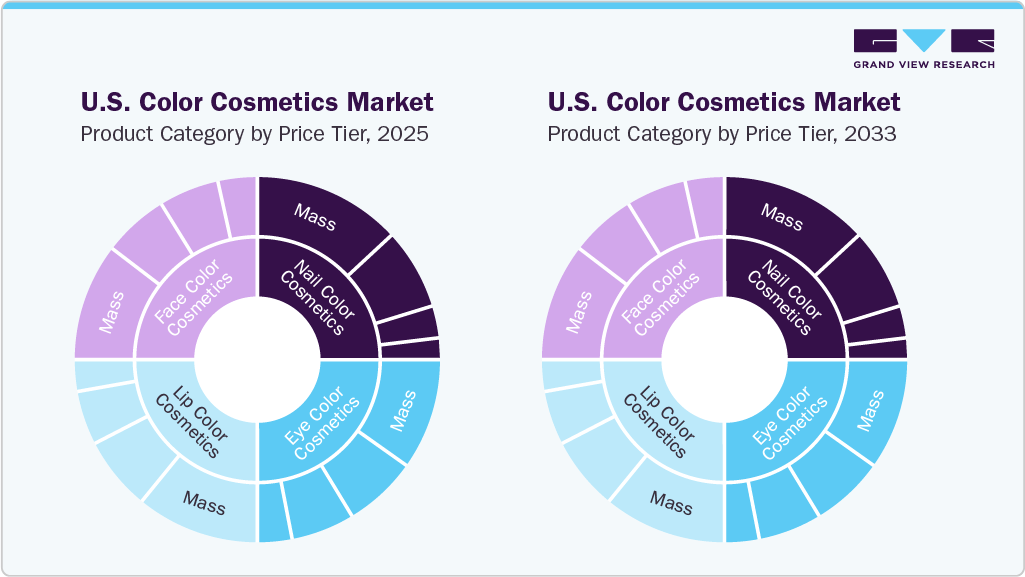
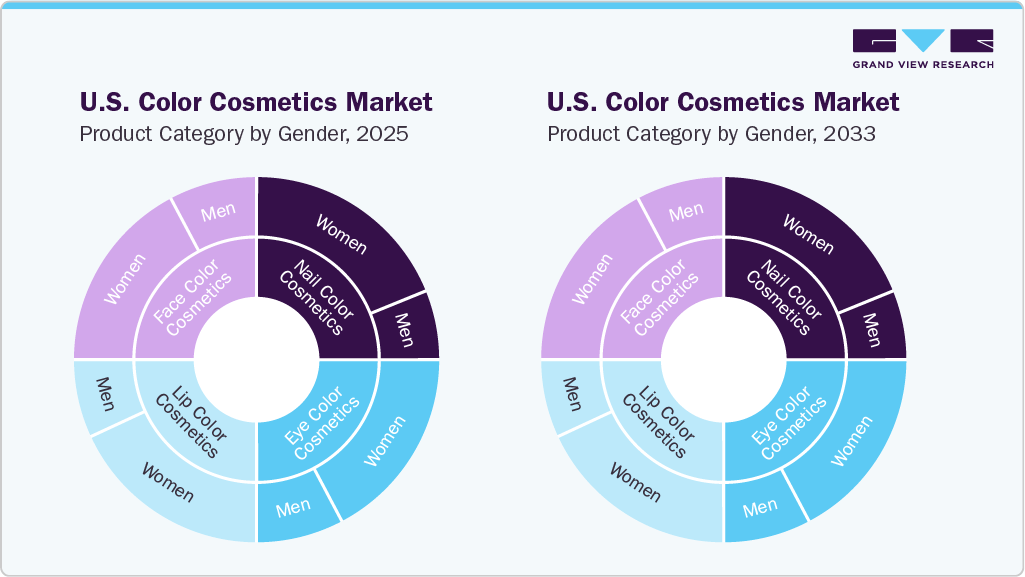
The study provides a detailed cross-segmentation analysis of the U.S. color cosmetics industry to identify how demand differs across price tiers, product types, and consumer groups. Beyond individual segment analysis, the report evaluates face, lip, eye, and nail color cosmetics across mass, masstige, premium, and luxury price tiers, providing a more granular view of how the color cosmetics are positioned in the market. The analysis also cross-segments the color cosmetics by gender, enabling assessment of differences in product demand between male and female consumers. These cross-segment insights help identify premiumization opportunities, the positioning of color cosmetics, gender-specific product opportunities, and areas where brands can expand targeted formulations and price-tier offerings.
 To learn more about this report, Download Free Sample Report
 To learn more about this report, Download Free Sample Report
Key U.S. Color Cosmetics Company Insights
The dominance of major color cosmetics companies such as L’Oréal USA, The Estée Lauder Companies Inc., e.l.f. Beauty, Huda Beauty continues to define the upper tier of the competitive spectrum.
-
L'Oréal S.A, a beauty products manufacturing company, offers a wide range of products catering to diverse consumer needs, including foundations, concealers, lipsticks, eyeshadows, mascaras, and nail polishes. Their color cosmetics brands, such as L'Oréal Paris, Maybelline New York, Lancôme, and NYX Professional Makeup, are well-regarded for their innovative formulations, vibrant color palettes, and trendsetting products.
-
The Estée Lauder Companies Inc., established in 1946 by Estée and Joseph Lauder, is recognized as one of the world’s top manufacturers, marketers, and sellers of high-quality skincare, makeup, fragrance, and hair care products. It is widely acknowledged for managing a portfolio of luxury and prestige brands. The company operates globally, with its products available in around 150 countries and territories under several renowned brand names such as Estée Lauder, Clinique, Origins, M·A·C, Bobbi Brown Cosmetics, La Mer, Aveda, Jo Malone London, TOM FORD, Too Faced, Dr.Jart+, and The Ordinary.
Key U.S. Color Cosmetics Companies
-
L’Oréal USA
-
The Estée Lauder Companies Inc.
-
Coty Inc.
-
e.l.f. Beauty
-
Revlon
-
Shiseido Americas
-
LVMH Moët Hennessy Louis Vuitton SE
-
Fenty Beauty
-
Huda Beauty
-
Haus Labs by Lady Gaga
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (L’Oréal USA; The Estée Lauder Companies Inc.; Coty Inc.; Revlon; Shiseido Americas; LVMH Moët Hennessy Louis Vuitton SE)
- Expand portfolios across face, lip, eye, and nail cosmetics, covering foundations, concealers, blushes, lip products, mascaras, eyeshadows, and nail color.
- Strengthen presence across department stores, specialty beauty retailers, drugstores, mass retailers, and e-commerce while investing in product launches, shade expansion, digital marketing, and omnichannel distribution.
- Increasingly focus on skincare-infused makeup, long-wear formulations, multifunctional formats, and trend-responsive products.
- Strong brand recognition, broad category portfolios, extensive retail relationships, and established distribution networks provide substantial U.S. market reach.
- Large R&D, marketing, and innovation capabilities support rapid launches across price tiers, product formats, and consumer needs.
- Large brand portfolios and corporate structures can slow product development and responses to fast-moving makeup trends.
- Competition across mass, masstige, prestige, and luxury tiers requires sustained spending on innovation, promotions, influencer marketing, and retail visibility.
Specialized & Digital-First Players (e.l.f. Beauty; Fenty Beauty; Huda Beauty; Haus Labs by Lady Gaga)
- Focus on digitally driven, trend-responsive makeup across complexion, lip, eye, and multi-use formats, with strong emphasis on shade inclusivity, social-led launches, and accessible premium positioning.
- Leverage social media, creator partnerships, owned digital channels, specialty beauty retailers, and e-commerce to accelerate product discovery and consumer engagement.
- Differentiate through distinctive formulations, inclusive shade ranges, viral product formats, and rapid response to emerging beauty aesthetics.
- Strong digital engagement, distinctive brand identities, and ability to translate social and cultural trends into product launches.
- Focused portfolios enable faster experimentation with textures, finishes, shades, and multifunctional formats than many diversified beauty companies.
- Greater dependence on trend momentum, digital visibility, and a limited number of hero products can increase volatility in demand.
- Compared with established groups, narrower portfolios and retail footprints can limit penetration across traditional mass and department-store channels.
Recent Developments
-
In February 2025, L’Oréal USA marked a significant milestone with the grand opening of its new North America Research & Innovation (R&I) Center in Clark, New Jersey. This $160 million investment represents the company's largest R&I facility outside of France, spanning approximately 250,000 square feet. The state-of-the-art center is designed to bolster L’Oréal's capabilities in developing innovative, high-quality, and safe beauty products tailored to consumers' diverse needs. Housing over 600 scientists, engineers, and researchers, the facility underscores L’Oréal's commitment to scientific advancement and its strategic focus on the U.S. market. This development not only enhances the company's research endeavors but also contributes to local economic growth and employment opportunities.
-
In October 2024, e.l.f. Beauty has made significant strides in sustainability, inclusivity, and product innovation. In its report, the company highlighted that over 85% of its products are manufactured in Fair Trade Certified facilities and that more than 2,500 ingredients are excluded from its formulations, thereby surpassing FDA and EU restrictions. Notably, e.l.f. Beauty stands out as the only publicly traded U.S. company with a board comprising over 78% women and 44% members from diverse backgrounds. The company also launched the "Dupe That!" campaign, encouraging consumers and other businesses to embrace affordable, high-quality beauty alternatives and to join in making positive impacts on people, products, and the planet.
-
In December 2024, Coty entered a long-term partnership with Swarovski to rejuvenate Swarovski's fragrance division. This collaboration aims to leverage Coty's expertise to reintroduce Swarovski's fragrances, with the first new release scheduled for 2026. The partnership aligns with Coty's strategy of acquiring licenses with multi-category potential to boost growth.
U.S. Color Cosmetics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 23.3 billion
Estimated market size in 2026
USD 25.3 billion
Projected market size by 2033
USD 44.5 billion
Growth rate
CAGR of 8.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel
Country scope
U.S.
Key companies profiled
L’Oréal USA; The Estée Lauder Companies Inc.; Coty Inc.; e.l.f. Beauty; Revlon; Shiseido Americas; LVMH Moët Hennessy Louis Vuitton SE; Fenty Beauty; Huda Beauty; Haus Labs by Lady Gaga
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Color Cosmetics Market Report Summary
This report forecasts country-level revenue growth and provides an analysis of the latest industry trends and opportunities across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. color cosmetics market report based on the product, and distribution channel:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Face Color Cosmetics
-
Foundation
-
Concealer
-
Blush and Bronzer
-
Powder
-
Others (Highlighter, etc.)
-
-
Lip Color Cosmetics
-
Lipstick
-
Lip Liner
-
Lip Gloss
-
Lip Tint
-
Others (Lip Powder, Plummer, etc.)
-
-
Eye Color Cosmetics
-
Eye Shadow
-
Eye Liner
-
Mascara
-
Eye Pencil
-
False Eyelashes
-
Others (Eye Primer, etc.)
-
-
Nail Color Cosmetics
-
-
Distribution Channel (Revenue, USD Billion, 2021 - 2033)
-
Hypermarkets & Supermarkets
-
Specialty Beauty Stores
-
Pharmacies & Drugstores
-
Online/ E-commerce
-
Others (Department stores, etc.)
-
Research Methodology
The U.S. color cosmetics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. color cosmetics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Distribution Channel
Revenue capture definition
Hypermarkets & Supermarkets
The study covers color cosmetics sold through large-format grocery and general merchandise stores, including makeup aisles and beauty sections. Includes face, lip, eye, and nail cosmetics across mass, masstige, and premium price tiers.
Specialty Beauty Stores
The study covers color cosmetics sold through beauty, cosmetics, and specialty retailers, including beauty chains and professional beauty stores. Includes mass, masstige, prestige, and luxury products across all major categories.
Pharmacies & Drugstores
The study covers color cosmetics sold through pharmacy and drugstore chains, including products available in beauty, personal-care, and cosmetics sections. Primarily includes mass and masstige products across face, lip, eye, and nail categories.
Online/E-commerce
The study covers color cosmetics sold through brand websites, retailer websites, online marketplaces, beauty e-commerce platforms, and direct-to-consumer channels. Includes all major product categories and price tiers.
Others (Department Stores, etc.)
The study covers color cosmetics sold through department stores, salons, specialty non-beauty retailers, professional outlets, and other relevant physical or hybrid retail formats. Includes products across major categories and price tiers.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Color Cosmetics Consumer Base Layer
Who has a recurring need for color cosmetics?
Identify consumers purchasing foundation, concealer, blush, bronzer, highlighter, and setting products for complexion enhancement and makeup routines.
02
Usage & Product Accessibility Layer
Who regularly uses commercially available color cosmetics?
Identify consumers purchasing lipsticks, lip glosses, lip liners, lip stains, and balms for color enhancement and everyday makeup applications.
03
Purchase Frequency & Replacer Layer
How frequently are color cosmetics purchased?
Identify consumers purchasing eyeshadows, eyeliners, mascaras, and brow products for eye definition, enhancement, and varied makeup looks.
04
Revenue Generation Layer
How much revenue is generated?
Identify consumers purchasing nail polishes, gels, treatments, and nail color products for at-home manicures, nail styling, and personal grooming.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis of Color Cosmetics Product, Price Tier & Category
Detailed cross-segmentation of the U.S. color cosmetics industry across face, lip, eye, and nail categories, mass, masstige, prestige, and luxury price tiers, and key product formats. The analysis mapped category positioning, pricing, product claims, and channel exposure.
Identified how category preferences and product formats varied across price tiers, highlighting premiumization opportunities and areas where value-oriented propositions remained relevant.
Brand Portfolio & Price-Positioning Benchmarking
Comprehensive benchmarking of leading U.S. color cosmetics brands across category presence, price architecture, product formats, shade ranges, claims, innovation focus, and retail channels. The analysis compared mass, masstige, prestige, and luxury brand portfolios.
Identified gaps in brand positioning, category expansion, and price architecture, highlighting whitespace across complexion, lip, eye, and nail offerings.
Color Cosmetics Need-State & Format Opportunity Mapping
Mapped color cosmetics offerings by consumer need state and product format, including coverage, hydration, long wear, skin enhancement, shine, color correction, and treatment benefits across foundations, blushes, lip oils, liners, mascaras, and multi-use products.
Identified emerging format opportunities and areas where makeup was moving beyond basic color application toward multifunctional, skincare-infused, and convenience-led propositions.
Frequently Asked Questions About This Report
Hypermarkets/supermarkets accounted for the largest market share of 34.2% in 2025, while the online/e-commerce stores segment the fastest-growing distribution channel.
The facial color cosmetics segment led the market with the largest revenue share of 38.8% in 2025, while nail color cosmetics segment is the fastest-growing product.
The growth of e-commerce platforms and advancements in technology have greatly reshaped the color cosmetics industry. Consumers now enjoy easier access to a diverse selection of products, while brands can connect with a wider audience through digital channels. Innovations like augmented reality (AR) virtual try-ons have elevated the online shopping experience by enabling users to preview products before buying.
Some of the key players in the U.S color cosmetics market include L’Oréal USA, The Estée Lauder Companies Inc., Coty Inc., e.l.f. Beauty, Revlon, Shiseido Americas, LVMH Moët Hennessy Louis Vuitton SE, Fenty Beauty, Huda Beauty, and Haus Labs by Lady Gaga.
The U.S. color cosmetics market is expected to grow at a CAGR of 8.4% from 2026 to 2033 to reach USD 44.5 billion by 2033.
The U.S. color cosmetics market was valued at USD 23.3 billion in 2025 and is estimated at USD 25.3 billion in 2026.
About the Author(s)
Beauty & Personal Care Research Team
Consumer Goods · Beauty & Personal CareThis report was authored by the beauty & personal care research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the beauty & personal care segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


