
- Home
- »
- Medical Devices
- »
-
U.S. Freestanding Emergency Department Market Report, 2033GVR Report cover

U.S. Freestanding Emergency Department Market (2026 - 2033)
Size, Share & Trends Analysis Report By Ownership (OCED, IFSED), By Services (Emergency Department Service, Laboratory Services, Imaging Services), By Region (Northeast, Southeast), And Segment Forecasts
Market Size, 2025
$17.5BMarket Estimate, 2026
$18.5BMarket Forecast, 2033
$29.6BCAGR, 2026–2033
6.9%U.S. Freestanding Emergency Department Market Summary
The U.S. freestanding emergency department (FSEDs) market size was valued at USD 17.5 billion in 2025 and is projected to grow from USD 18.5 billion in 2026 to USD 29.6 billion by 2033, at a CAGR of 6.9% from 2026 to 2033. This growth is driven by the increasing demand for rapid emergency care, increasing patient preference for convenient healthcare access, and rising emergency department overcrowding at hospitals. Increasing incidences of trauma, cardiovascular emergencies, respiratory conditions, and other acute illnesses are further driving patient visits to FSEDs, which offer 24/7 emergency services with shorter waiting times and advanced diagnostic capabilities.
Key Market Trends & Insights
- By services: Emergency department (ED) service segment held the largest market share of 44.7% in 2025.
- By ownership: Off-campus emergency department (OCED) segment held the largest share in 2025.
Market Size & Forecast
- 2025 Market Size: USD 17.5 Billion
- Estimated market size in 2026: USD 19.6 Billion
- Projected market size by 2033: USD 29.6 Billion
- CAGR (2026-2033): 6.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
For instance, in August 2025, UNC Health announced plans to develop freestanding emergency and urgent care facilities in North Carolina, including on-site laboratories and advanced imaging services. This initiative highlights the continued expansion of community-based emergency care models in the U.S.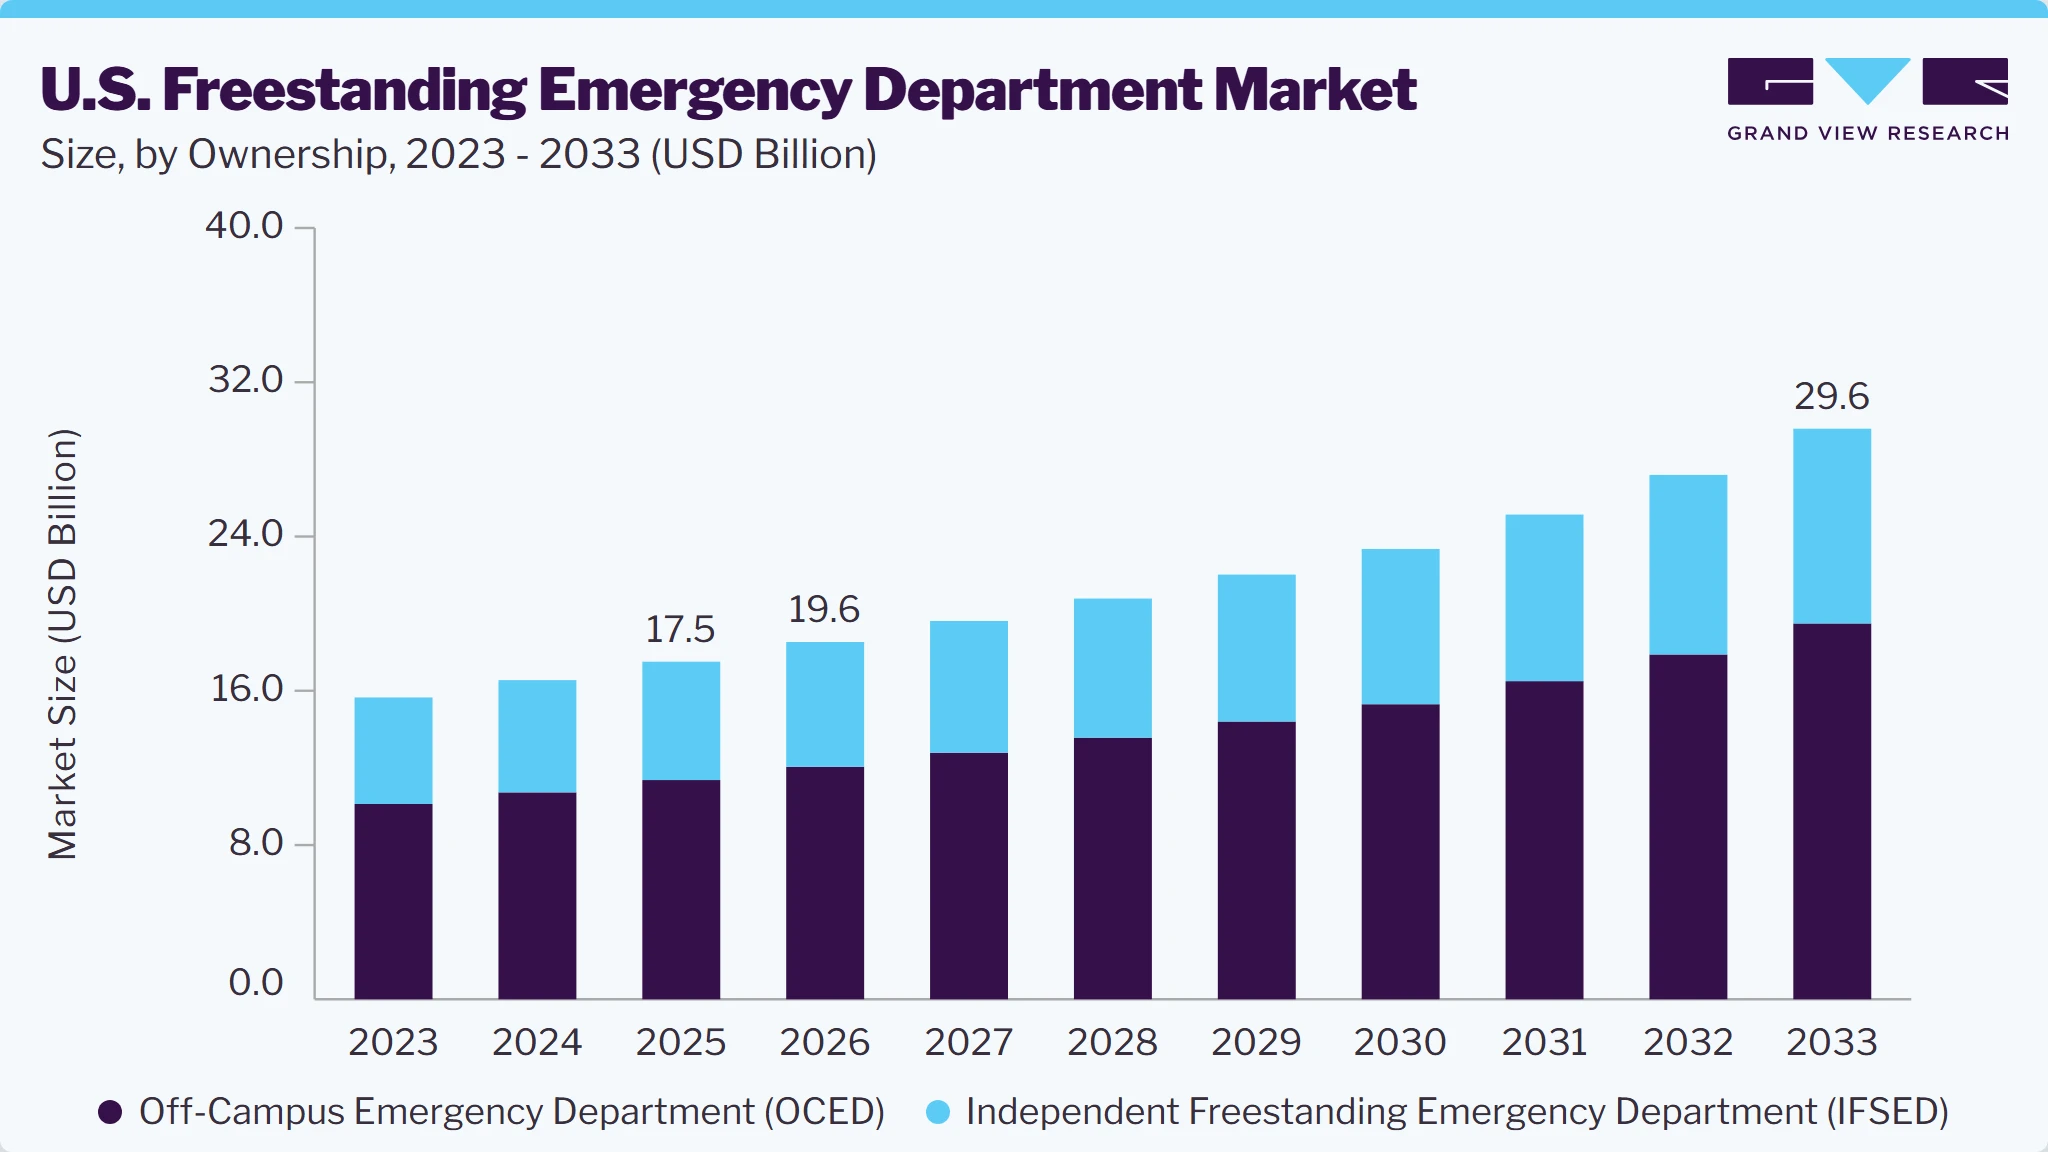 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The section below outlines the key factors driving the growth of the U.S. freestanding emergency department industry, highlighting the rising incidence of road accidents, sports injuries, fractures, and orthopedic trauma cases across the region. It also examines increasing healthcare investments, expanding access to advanced orthopedic care, growing adoption of minimally invasive trauma fixation technologies, and the rising presence of international medical device manufacturers supporting market expansion.
Market Dynamics
The volume of emergency department (ED) visits serve as a key indicator of hospital utilization and the growing demand for acute and unscheduled healthcare services in the U.S. Hospitals with high ED visit volumes are often major regional referral centers that manage a significant number of medical emergencies, trauma cases, and complex patient presentations. Rising ED utilization reflects factors such as population growth, increasing chronic disease burden, limited access to primary care services, and higher demand for emergencies and urgent care. The table below highlights the top U.S. hospitals by emergency department visits in 2025, illustrating the institutions that experience the highest patient inflow and play a critical role in delivering emergency healthcare services nationwide.
U.S. Hospitals by Emergency Department (ED) Visits, 2025):
Hospital Name
ED Visits (2025)
Parkland Health and Hospital System
228,759
Lakeland Regional Medical Center
199,320
Yale New Haven Hospital
190,436
Inova Fairfax Hospital
184,524
MultiCare Good Samaritan Hospital
175,011
John Peter Smith Hospital
162,964
Wellstar Kennestone Hospital
153,518
Hackensack University Medical Center
152,385
Los Angeles General Medical Center
148,004
NYC Health + Hospitals/Lincoln
142,868
Montefiore Medical Center - Moses Campus
141,131
UMass Memorial Medical Center
140,622
Source: Becker's Hospital Review, "77 Hospitals with the Most ED Visits in 2025"
This imbalance between emergency care demand and hospital capacity contributes to ED boarding, in which admitted patients remain in emergency departments while waiting for inpatient beds. As ED beds remain occupied, hospitals face reduced treatment capacity, longer waiting times, and lower operational efficiency. For instance, the capacity crisis reported at Massachusetts General Hospital highlights the need for healthcare systems to expand emergency care access beyond traditional hospital campuses. Hence, healthcare providers are increasingly considering alternative emergency care models, including freestanding emergency departments (FSEDs), to expand local emergency capacity and improve patient flow.
Alcohol-Related Emergency Department (ED) Visits in the U.S., 2024:
- According to the 2024 national estimates published by SAMHSA's Drug Abuse Warning Network (DAWN), an estimated 3,256,312 alcohol-related emergency department (ED) visits occurred in the U.S.
- Alcohol was involved in approximately 38.9% of all DAWN-reported ED visits, highlighting the substantial burden of alcohol-related conditions on emergency healthcare services.
- The estimates include ED visits in which alcohol use was either the primary or a contributing factor and encompass a broad range of health outcomes, including acute intoxication, alcohol poisoning, injuries, mental health crises, and complications associated with chronic alcohol consumption.
- The findings underscore the significant impact of alcohol misuse on healthcare utilization and emphasize the growing need for emergency care resources, substance use treatment programs, and preventive public health initiatives in the U.S.
Metric
Value (2024)
Total Alcohol-Related ED Visits
3,256,312
Share of Total DAWN ED Visits
38.9%
Source: SAMHSA
The advanced healthcare infrastructure in the U.S. supports establishing and operating FSEDs. These facilities are equipped with modern diagnostic tools and treatment capabilities that effectively handle a wide range of emergencies. The integration of technology within these departments enhances patient outcomes and operational efficiency. For instance, as per the Medical University of South Carolina updates published in February 2024, MUSC Health has been at the forefront of healthcare innovation, particularly in its ED. The ED is often the first point of contact for patients requiring urgent care, making it a critical area for improving patient outcomes and experiences. Recent advancements at MUSC Health aim to enhance efficiency, reduce waiting times, and improve overall patient care through various innovative strategies.
The U.S. government offers various financial assistance programs aimed at supporting hospitals, particularly in the development of FSED’s, which is expected to drive market growth during the forecast period. For instance, in March 2023, the U.S. Department of Homeland Security (DHS) allocated USD 89.14 billion through the Federal Emergency Management Agency (FEMA) to improve management and preparedness capabilities. This funding will be directed toward creating adaptable, sustainable, secure, strategically located, and fully interoperable Emergency Operations Centers (EOC), addressing previously identified deficiencies and requirements.
High operating costs and financial sustainability concerns continue to restrain growth in the market. FSEDs require significant capital investment for facility construction, advanced imaging systems, laboratory infrastructure, emergency equipment, and compliance with hospital-level emergency care standards. In addition, these facilities must maintain 24/7 operations with emergency physicians, registered nurses, and technical staff, resulting in high fixed labor expenses.
The financial challenge is further intensified by reimbursement uncertainty and changes in emergency care payment models. The implementation of the No Surprises Act (2022-2025) has reduced the ability of some independent emergency providers to receive higher out-of-network payments, increasing pressure on facility margins. For instance, in July 2025, a study published in JAMA Network Open highlighted that freestanding emergency departments face sustainability challenges due to high fixed costs, staffing requirements, and dependence on patient volume, indicating that some FSED models may require strong hospital-system support to remain financially viable.
The growing need to improve access to emergency care in rural and underserved communities is creating significant growth opportunities for the market. Government initiatives and healthcare system investments are supporting the expansion of emergency-focused facilities in regions facing challenges with healthcare access. The implementation of the Rural Emergency Hospital (REH) designation in January 2023, established by the Consolidated Appropriations Act, 2021, created a new pathway for rural hospitals to maintain emergency and outpatient services while reducing the financial burden of inpatient operations. By 2025, multiple rural hospitals had transitioned to the REH model to preserve emergency care availability in communities affected by hospital closures and declining financial sustainability. This trend highlights the growing acceptance of smaller emergency care facilities and creates opportunities for FSED operators to collaborate with rural healthcare providers.
In addition, healthcare systems are actively expanding FSED networks to improve emergency access in rapidly growing communities. In July 2025, HCA Florida Trinity Hospital announced the development of Sunlake Emergency in Pasco County, Florida, an 11,000-square-foot freestanding emergency department designed to provide 24/7 emergency services, imaging capabilities, and laboratory support while connecting patients with HCA’s broader hospital network for advanced care needs. Similarly, in January 2025 Bon Secours St. Francis Health System announced a USD 23 million investment in a new freestanding emergency department in South Carolina, driven by population growth and increasing demand for convenient emergency services. These investments demonstrate the growing role of FSEDs as strategic extensions of hospital networks to improve geographic coverage and manage rising emergency care demand.
Market Concentration & Characteristics
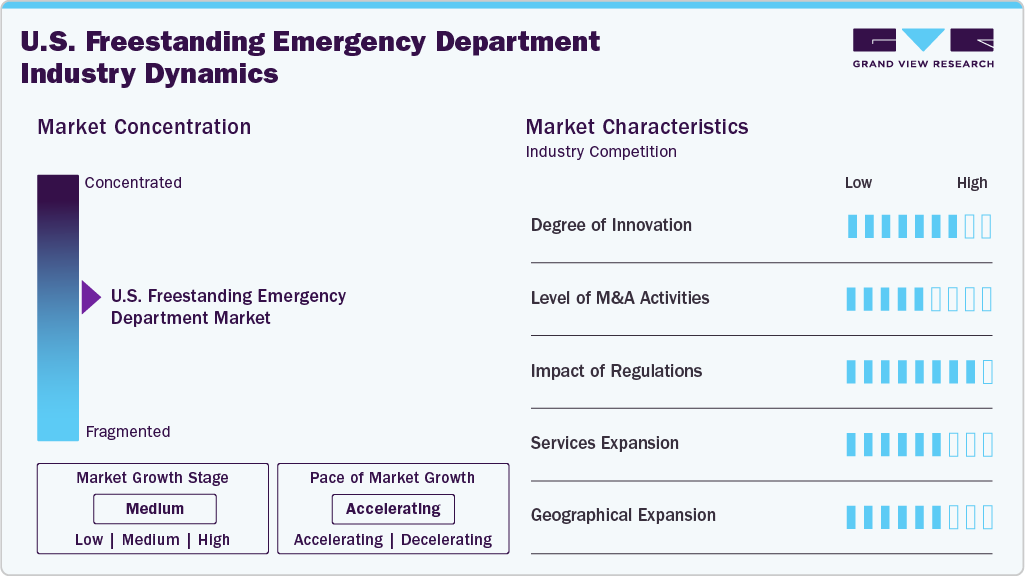
The chart below represents the relationship between industry concentration, industry characteristics, and industry participants. The industry is fragmented, with numerous hospital-affiliated and independent freestanding emergency departments operating across the U.S. There is a medium to high degree of innovation, moderate level of merger & acquisition activities, high impact of regulations, moderate service expansion, and moderate geographical expansion. The market is currently in the medium growth stage with an accelerating pace of growth.
The market is witnessing a medium to high degree of innovation as healthcare providers increasingly adopt digital technologies to improve emergency care delivery and operational efficiency. Hospitals are implementing artificial intelligence (AI)-enabled clinical documentation, electronic health records (EHRs), remote specialist consultations, and advanced diagnostic tools to reduce administrative burden and enhance patient care. For instance, HCA Healthcare's rollout of Augmedix Go, a generative AI-powered ambient documentation solution for emergency departments. Following successful pilots, Augmedix announced the commercial launch in April 2024, enabling emergency physicians to automatically generate clinical notes from patient conversations, reducing documentation time and allowing clinicians to spend more time with patients. This reflects the growing adoption of AI-driven workflow solutions across U.S. emergency care settings.
 To learn more about this report, Download Free Sample Report
The level of mergers and acquisitions remains moderate, with market growth primarily supported through strategic joint ventures and regional expansion instead of large-scale consolidation. Hospital systems continue to collaborate with specialized FSED developers to increase emergency care access in growing communities. For instance, in February 2024, Emerus Holdings and AdventHealth expanded their joint venture network with the opening of additional neighborhood hospitals and freestanding emergency departments, strengthening emergency care access in Florida while minimizing the capital investment required for full-service hospitals.
The market experiences a high regulatory impact, as federal and state regulations significantly influence facility development, reimbursement, staffing requirements, and operational standards. Compliance with EMTALA, CMS reimbursement policies, physician licensing requirements, and state-specific regulations continue to shape expansion strategies. In November 2024, the Centers for Medicare & Medicaid Services (CMS) finalized the Calendar Year 2025 Outpatient Prospective Payment System (OPPS) Rule, updating reimbursement policies and quality reporting requirements that directly affect hospital outpatient departments and hospital-affiliated freestanding emergency departments. In addition, state-level regulations continue to determine whether independent FSEDs are permitted, limiting expansion in several regions.
Service expansion in the market remains moderate, as healthcare providers continue to strengthen emergency care access by opening new freestanding emergency departments and adding advanced diagnostic and clinical services. Providers are increasingly integrating CT and X-ray imaging, on-site laboratory testing, pediatric care, and other hospital-level emergency capabilities into FSEDs. For instance, in November 2025, Halifax Health opened a new freestanding emergency room in Daytona Beach, Florida, featuring 26 exam rooms, on-site CT and X-ray imaging, a full-service laboratory, and dedicated pediatric and family care areas. This expansion highlights the continued broadening of services offered through FSEDs to provide more comprehensive emergency care closer to patients.
The market continues to expand geographically, particularly in rapidly growing suburban and underserved communities where hospital emergency departments are overcrowded or distant. Healthcare providers are strategically establishing new facilities in high-growth regions to improve emergency access. For instance, in March 2025, Clear Choice ER expanded its presence in Laredo, Texas, to meet increasing healthcare demand driven by rapid population growth, while other health systems continue extending emergency care networks into suburban markets. This measured but sustained expansion supports broader access to emergency services without the cost of constructing full-scale hospitals.
Analyst Perspective
Rising demand for accessible and efficient emergency care is driving growth in the U.S. freestanding emergency department market, as patients and providers seek alternatives to overcrowded hospital emergency departments. Increased emergency visits, hospital capacity constraints, and population growth are fueling the expansion of off-campus and independent facilities. The adoption of advanced imaging, laboratory testing, electronic health records, and telehealth is enhancing efficiency and broadening services. Greater investment in community-based emergency care and the expansion of hospital-affiliated networks are also supporting market growth. These trends are expected to sustain steady market expansion over the forecast period.
Ownership Insights
Based on ownership, the off-campus emergency department (OCED) segment held the largest market share in 2025. The segment is driven by the rapid expansion of hospital health systems establishing off-campus emergency departments to improve access to emergency care while extending their referral networks. Hospital systems are also expanding OCED networks to reduce overcrowding in main emergency departments and improve patient flow across their healthcare facilities. For instances, in April 2025 Methodist Healthcare, part-owned by HCA Healthcare, announced a USD 3.45 million expansion of the emergency department at Methodist Hospital Landmark in San Antonio after experiencing strong patient demand. The health system also announced plans to develop another emergency department and medical office campus in an underserved area of the city. The investment demonstrates how hospital systems are expanding off-campus emergency facilities to improve patient access, support population growth, and reduce congestion at flagship hospitals.
The independent freestanding emergency department (IFSED) segment is expected to grow at a significant CAGR during the forecast period. Growth is supported by rising demand for convenient, 24/7 emergency care outside traditional hospital settings, particularly in states with favorable regulatory environments. Independent FSEDs are expanding through physician-led groups and private healthcare operators, offering rapid diagnosis, emergency stabilization, laboratory services, and advanced imaging without requiring hospital affiliation. Increasing consumer preference for accessible emergency care, coupled with investments in digital registration, telemedicine integration, and operational efficiency is expected to accelerate the expansion of independent freestanding emergency departments across the U.S.
Service Insights
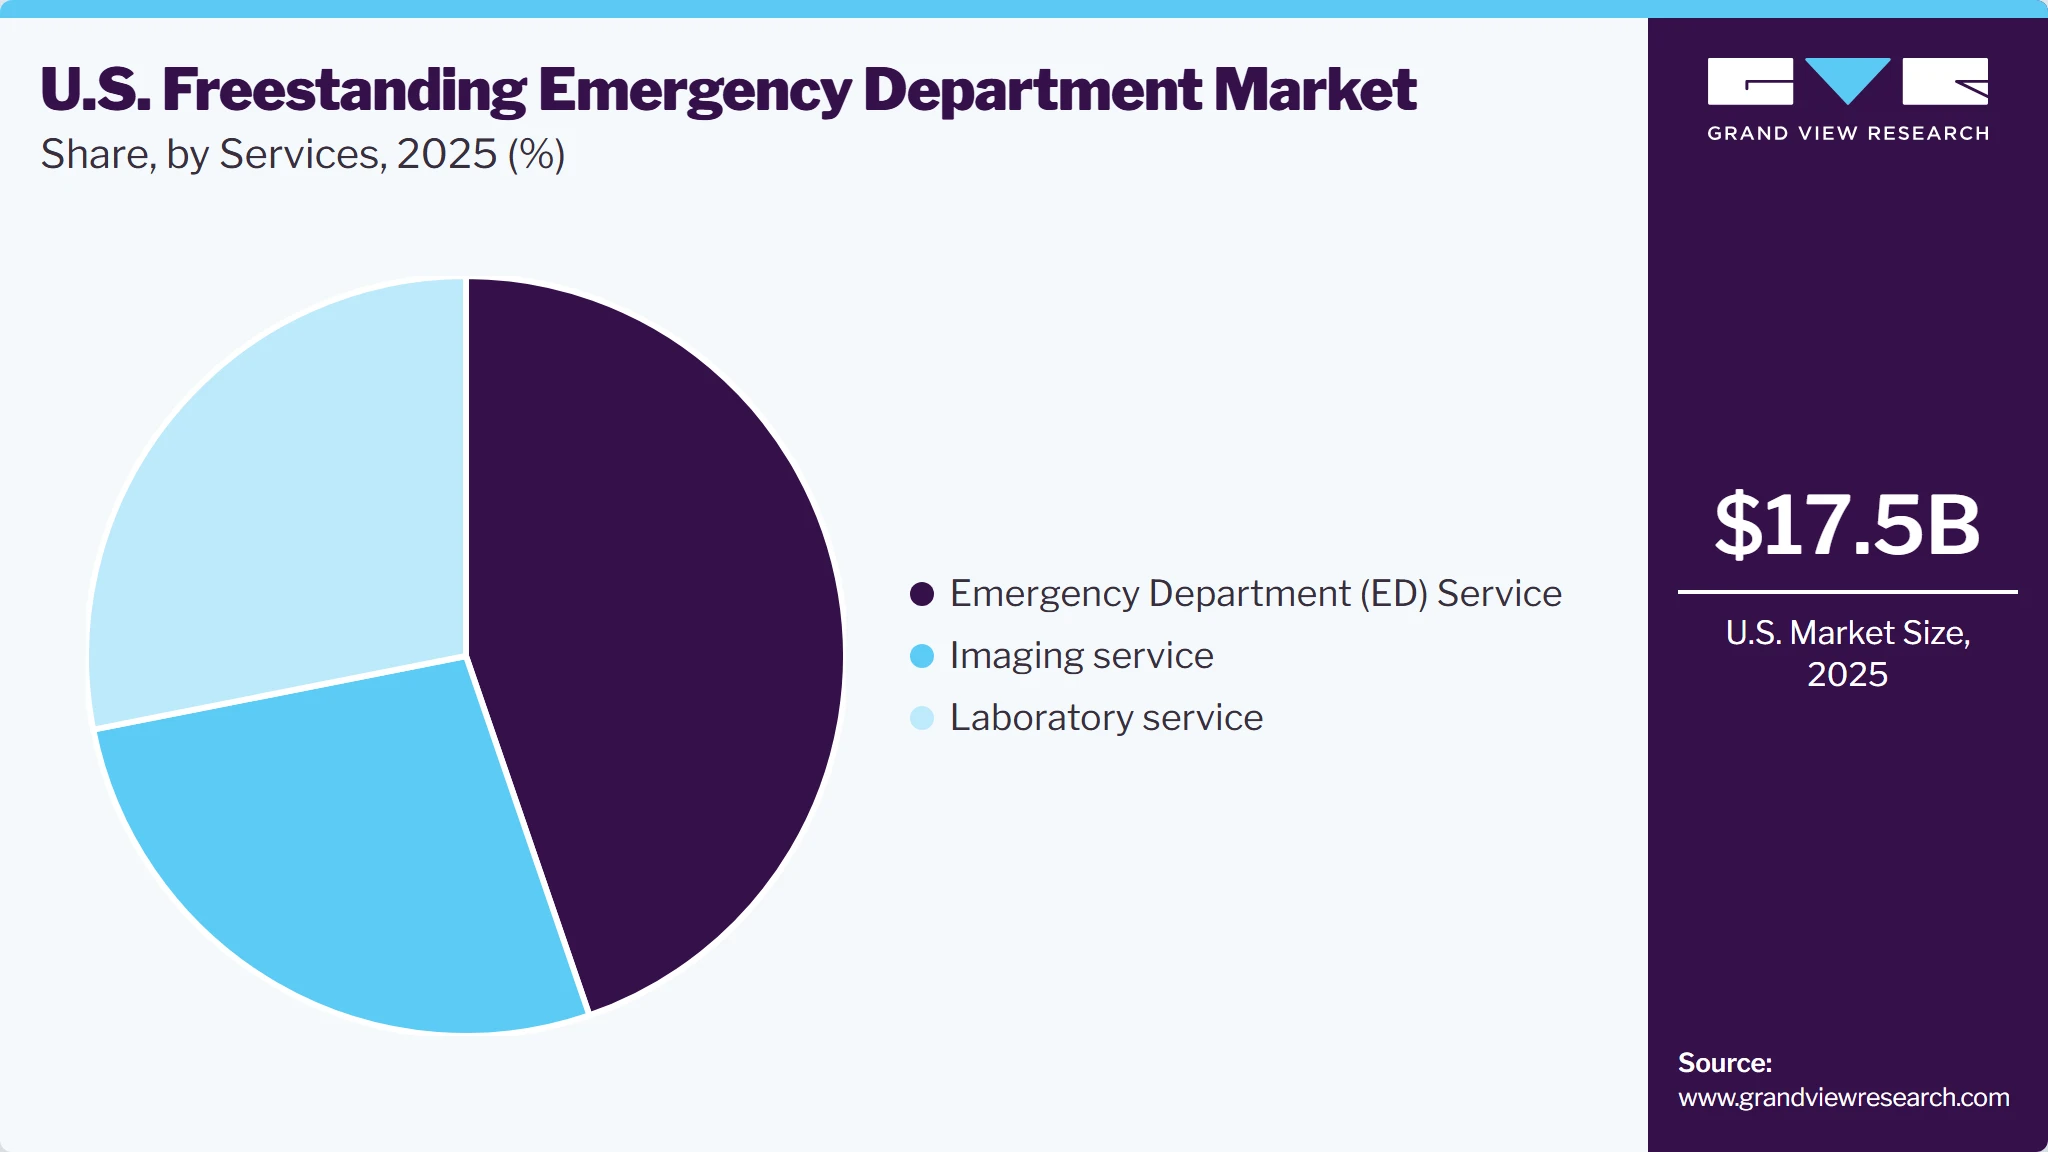
Based on services, the emergency department (ED) services segment held the largest market share of 44.7% in 2025. The segment is driven by the increasing demand for immediate treatment of acute illnesses, traumatic injuries, cardiac emergencies, respiratory conditions, and other time-sensitive medical conditions outside traditional hospital settings. Freestanding emergency departments provide 24/7 physician-led emergency care with rapid triage, stabilization, and treatment while offering significantly shorter wait times than many hospital emergency departments. Rising patient preference for convenient emergency care, coupled with the continued expansion of hospital-affiliated and independent FSED networks across suburban and underserved communities, is supporting sustained demand for emergency department services.
 To learn more about this report, Download Free Sample Report
The laboratory services segment is expected to grow at a significant CAGR during the forecast period. Growth is driven by the increasing need for rapid diagnostic testing to support timely clinical decision-making in emergency care settings. Freestanding emergency departments are expanding their in-house laboratory capabilities to provide immediate testing for cardiac biomarkers, infectious diseases, blood chemistry, hematology, and toxicology, enabling faster diagnosis and treatment initiation. The growing adoption of point-of-care testing technologies, automation, and integrated laboratory information systems is improving operational efficiency, reducing turnaround times, and enhancing patient outcomes across U.S. freestanding emergency departments.
Country Insights
The southeast region is expected to witness strong growth due to population expansion, increasing healthcare demand, and continued investment in community-based emergency care facilities. For instance, in February 2025, Broward Health broke ground on a new freestanding emergency department in Lighthouse Point, Florida. The facility is expected to include 10 emergency exam rooms and serve approximately 18,000 patients annually, expanding access to 24/7 emergency care in the local community. This development highlights the continued expansion of freestanding emergency care infrastructure across the Southeast and the growing use of decentralized facilities to meet rising regional healthcare demand.
Thewest region is expected to experience continued demand for freestanding emergency departments due to population growth, geographic barriers, and the need to improve access to emergency care in rapidly expanding suburban communities. For instance, in January 2025, AdventHealth broke ground on an USD 81 million medical campus in Aurora, Colorado, with the first phase including an 88,000-square-foot freestanding emergency room with eight exam rooms, two trauma rooms, and a helipad. The development is intended to expand emergency care access in the rapidly growing Aurora Highlands community and demonstrates continued investment in freestanding emergency infrastructure across the Western U.S. Therefore, ongoing population growth and healthcare system expansion are expected to support demand for FSEDs across the west.
Key U.S Freestanding Emergency Companies
-
TH Medical
-
Universal Health Services, Inc.
-
CHSPSC, LLC.
-
C-HCA, Inc.
-
Lifepoint Health, Inc.
-
Ardent Health Management Services (AHS Management Company, Inc.)
-
Ascension
-
Deerfield (Adeptus Health, Inc.)
-
Emerus Hospital Partners, LLC
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players:
- Operate extensive networks of hospital-affiliated and licensed freestanding emergency departments across multiple states.
- Expand through acquisitions, hospital integration, and strategic partnerships with physician groups.
- Invest in digital triage, electronic health records (EHR), telehealth, and advanced diagnostic capabilities.
- Focus on high-acuity emergency care while strengthening referral pathways to affiliated hospitals
- Strong brand recognition and patient trust supported by large healthcare systems.
- Broad geographic footprint and financial resources enable rapid expansion and technology investments.
- Integrated hospital networks improve continuity of care, specialist access, and patient transfers.
- Strong payer relationships and operational efficiencies enhance long-term competitiveness.
- High capital expenditure for facility development, staffing, and regulatory compliance.
- Significant dependence on reimbursement rates from Medicare, Medicaid, and commercial insurers.
- Large organizational structures can slow expansion into underserved markets.
- Rising labor costs and physician shortages continue to pressure operating margins.
Emerging Players: Emerus Hospital Partners, LLC.; LifePoint Health, Inc.; Ardent Health Management Services; Adeptus Health (Deerfield Management); Regional physician-owned FSED operators
- Focus on developing freestanding emergency departments in rapidly growing suburban and underserved communities.
- Partner with regional hospitals and health systems to expand emergency care access while limiting infrastructure costs.
- Emphasize shorter wait times, convenient locations, and patient-centric emergency services.
- Adopt flexible expansion models through joint ventures and local healthcare partnerships
- Faster decision-making and greater operational flexibility than large health systems.
- Ability to enter underserved markets with lower initial investment through partnership models.
- Strong focus on patient experience, convenience, and efficient emergency care delivery.
- Agile adoption of innovative care models and digital patient engagement solutions.
- Limited geographic reach and lower brand recognition compared to national hospital systems.
- Smaller financial capacity restricts rapid multi-state expansion.
- Greater exposure to reimbursement changes and local regulatory policies.
- Dependence on partner hospitals for specialist support and inpatient admissions may limit scalability.
Recent Developments
-
In January 2026, Emerus announced that it had surpassed five million patients treated across its nationwide network of neighborhood hospitals and freestanding emergency departments, highlighting the rapid expansion and growing adoption of the FSED model in the U.S. The company continues to partner with leading health systems to expand access to emergency care in underserved and high-growth communities.
“Reaching five million patients isn't just a number. It signals that our model works, that communities trust us, and that patients value care delivered close to home.”
- Vic Schmerbeck, Chief Executive Officer, Emerus-
In September 2025, The Emergency Department (ED) Services of Providence, in partnership with Emerus, broke ground on the new Gateway Freestanding Emergency Department in El Paso, Texas. The 10-bed, 24/7 emergency facility will provide advanced emergency care, on-site laboratory services, and diagnostic imaging, strengthening access to emergency services in one of the fastest-growing communities.
“This groundbreaking is more than the start of a construction project-it’s a promise to our neighbors that we are here for them, ready to deliver the very best care.”
- Eddie Rivas, Market CEO, The Emergency Department (ED) Services of Providence Emergency Room Gateway-
In August 2025, UNC Health partnered with Intuitive Health to launch a new network of hybrid freestanding emergency departments and urgent care centers across North Carolina. The facilities are designed to improve access to emergency care while reducing unnecessary emergency department utilization by directing patients to the appropriate level of care.
“This partnership represents a significant advancement in our mission to enhance the health and well-being of all North Carolinians.”
- Dr. Cristy Page, Interim CEO, UNC HealthU.S. Freestanding Emergency Department Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 17.5 billion
Market size value in 2026
USD 19.6 billion
Revenue forecast in 2033
USD 29.6 billion
Growth rate
CAGR of 6.9% from 2026 to 2033
Actual data
2021 - 2025
Forecast data
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Ownership, services, region
Key companies profiled
TH TH TH Medical; Universal Health Services, Inc.; CHSPSC, LLC.; C-HCA, Inc.; Lifepoint Health, Inc.; Ardent Health Management Services (AHS Management Company, Inc.); Ascension; Deerfield (Adeptus Health, Inc.); Emerus Hospital Partners, LLC
Customization scope
Free report customization (equivalent to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Freestanding Emergency Department Market Report Segmentation
This report forecasts country-level revenue growth and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. freestanding emergency department market report based on ownership, service, and region:
-
Ownership Outlook (Revenue, USD Billion, 2021 - 2033)
-
Off-campus Emergency Department (OCED)
-
Independent Freestanding Emergency Department (IFSED)
-
-
Services Outlook (Revenue, USD Billion, 2021 - 2033)
-
Emergency Department (ED) Services
-
Laboratory Services
-
Imaging Services
-
-
Region Outlook (Revenue, USD Billion, 2021 - 2033)
-
Northeast
-
Southeast
-
Southwest
-
Midwest
-
West
-
Research Methodology
The U.S. freestanding emergency department market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. freestanding emergency department segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Segment Definition
By Ownership
Off-campus Emergency Department (OCED)
This segment includes hospital-affiliated emergency departments located outside the main hospital campus. Revenue is captured from emergency care, diagnostic testing, imaging, and related services provided through off-campus facilities operated under a hospital system’s license or ownership structure.
Independent Freestanding Emergency Department (IFSED)
This segment includes freestanding emergency facilities that operate independently of a hospital campus and are not physically located within a hospital facility. Revenue is captured from emergency medical treatment, diagnostic procedures, imaging, laboratory testing, and other billable services provided directly to patients.
By Services
Emergency Department (ED) Services
This segment includes revenue generated from emergency medical evaluation, diagnosis, treatment, stabilization, and other urgent care services delivered to patients presenting with acute illnesses or injuries.
Laboratory Services
This segment includes revenue generated from laboratory testing performed to support the diagnosis and treatment of emergency patients. Services include blood tests, urine analysis, infectious disease testing, metabolic panels, and other diagnostic laboratory procedures.
Imaging Services
This segment includes revenue generated from diagnostic imaging procedures performed for emergency evaluation and clinical decision-making. Services include X-ray, computed tomography (CT), ultrasound, and other imaging procedures available within the freestanding emergency department.
Estimation Model
Model Details
This research methodology outlines the process for estimating the size of the U.S. freestanding emergency department market from 2021 to 2033. The study covers key ownership segments, including OCEDs and IFSEDs. It also includes major service segments such as emergency department services, laboratory services, and imaging services.
The objective is to develop a robust and defensible market estimate by combining bottom-up and top-down approaches, supported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis based on the number of FSED facilities, patient visits, emergency department encounters, service volumes, average revenue per visit, and facility-level revenues.
-
Top-Down Analysis using U.S. emergency department utilization, healthcare expenditure, emergency department overcrowding, hospital capacity constraints, population growth, insurance coverage, and healthcare infrastructure data.
-
Primary Research with FSED operators, hospital systems, emergency physicians, healthcare administrators, facility managers, payers, healthcare consultants, and industry experts.
Step-by-Step Market Estimation Process
• FSED Patient Volume and Revenue Model
This model estimates the market size based on the number of patients receiving emergency care at freestanding emergency departments and the average revenue generated per patient visit.
Step 1: Facility-level data on FSEDs operating in the U.S. from 2021 to 2025 were collected from state healthcare databases, hospital system disclosures, emergency medicine associations, healthcare directories, company websites, and industry sources.
Step 2: The number of annual patient visits was estimated using facility-level utilization data, emergency department encounter statistics, hospital system disclosures, payer data, and primary interviews.
Step 3: Average revenue per patient visit was estimated using emergency department reimbursement rates, facility billing data, insurance claims, service mix, payer mix, and interviews with FSED operators.
Step 4: Market size was calculated using:
Number of FSED Patient Visits × Average Revenue per Patient Visit
Step 5: Calculations were performed at the state level and aggregated to regional and national levels.
Step 6: Historical and forecast growth rates were incorporated based on increasing emergency department demand, hospital ED overcrowding, population growth, expansion of healthcare systems, rising insurance coverage, and new FSED openings.
• FSED Facility Revenue Extrapolation Model
This model estimates the market size based on revenues generated by freestanding emergency department facilities.
Step 1: The number of active OCED and IFSED facilities was identified by state using healthcare facility databases, state licensing records, hospital system disclosures, company reports, and industry databases.
Step 2: Average annual revenue per FSED was estimated using company financial disclosures, facility-level benchmarks, patient volume, reimbursement data, and primary interviews.
Step 3: Facility revenues were adjusted based on differences in patient volumes, geographic location, payer mix, ownership structure, service availability, reimbursement rates, and facility size.
Step 4: The market size was calculated using:
Number of FSED Facilities × Adjusted Average Annual Revenue per Facility
Step 5: State-level estimates were aggregated to calculate regional and national market values.
Step 6: Annual adjustments were applied to account for new facility openings, hospital system expansion, healthcare consolidation, changes in reimbursement, emergency care demand, and the expansion of diagnostic capabilities within FSEDs.
• Service Volume and Revenue Model
This model estimates the market size based on the volume of services delivered and the average revenue generated from each service category.
Step 1: Service volume data were collected from FSED operators, hospital systems, healthcare databases, payer data, state healthcare agencies, emergency medicine organizations, and industry publications.
Step 2: Services were categorized into:
-
Emergency Department (ED) Services
-
Laboratory Services
-
Imaging Services
Step 3: Average reimbursement and service prices were established using provider billing data, insurance reimbursement schedules, claims databases, facility pricing information, and primary interviews.
Step 4: Revenue generated by each service category was calculated using:
Number of Procedures / Services × Average Revenue per Procedure / Service
Step 5: Service-level revenues were aggregated to determine the total U.S. FSED market size.
Step 6: Forecast assumptions incorporated rising emergency care utilization, increasing demand for faster treatment, hospital ED overcrowding, greater use of point-of-care diagnostics, expansion of CT and imaging capabilities, and continued growth of hospital-affiliated and independent FSED networks.
• Ownership-Based Market Estimation
The market was further assessed based on the ownership structure of FSED facilities.
Step 1: FSED facilities were classified into:
-
Off-campus Emergency Departments (OCEDs)
-
Independent Freestanding Emergency Departments (IFSEDs)
Step 2: The number of facilities and patient visits associated with each ownership category was estimated using state licensing data, healthcare system disclosures, facility databases, and industry research.
Step 3: Average revenue per facility and average revenue per patient visit were calculated separately for each ownership category.
Step 4: Segment revenue was calculated using:
Segment Patient Visits × Average Revenue per Patient Visit
or
Segment Facilities × Average Revenue per Facility
Step 5: Ownership-level estimates were cross-checked against total FSED market revenues to avoid double counting.
• Market Validation and Forecasting
The estimates derived from the FSED patient volume and revenue model, facility revenue extrapolation model, service volume and revenue model, and ownership-based estimation model were cross-validated through data triangulation.
Findings were further verified through primary interviews with FSED operators, hospital executives, emergency physicians, healthcare administrators, payers, healthcare consultants, and industry experts.
Final market forecasts were developed by evaluating U.S. population growth, emergency department utilization, hospital capacity constraints, ED overcrowding, healthcare spending, insurance coverage, reimbursement policies, healthcare system expansion, and technological advancements in emergency diagnostics.
Forecast assumptions also considered the expansion of hospital-affiliated OCED networks, independent FSED operators, advanced imaging services, point-of-care laboratory testing, and the increasing demand for convenient emergency care outside traditional hospital settings.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Emergency Care Demand & Patient Volume Analysis
Delivered a customized evaluation of emergency care demand across hospital-based and independent freestanding emergency departments (FSEDs). The study analyzed patient visit volumes, acuity levels, seasonal demand patterns, payer mix, and regional population growth to identify high-demand markets and future service requirements.
Provides actionable insights into patient flow trends, demand hotspots, resource allocation, capacity planning, and regional expansion opportunities, enabling providers to optimize FSED network development and operational efficiency
AI-Based FSED Location Intelligence & Demand Forecasting
Developed an AI-driven market forecasting model integrating demographic growth, emergency department utilization, chronic disease prevalence, injury incidence, travel time analysis, healthcare accessibility, and physician supply to identify optimal locations for new FSED facilities and forecast future patient volumes.
Enables healthcare providers and investors to identify underserved markets, prioritize high-growth regions, improve site selection strategies, optimize capital investments, and enhance long-term forecasting accuracy for FSED expansion.
.
Feasibility of New Manufacturing Plant
Delivered a customized assessment of emergency healthcare accessibility by evaluating geographic coverage, population density, insurance coverage, hospital overcrowding, EMS response patterns, and state-level regulatory environments influencing FSED establishment. The study also identified opportunities for expanding emergency services in underserved suburban and rural communities.
Supports strategic decision-making for market entry, expansion planning, partnership development, and regulatory compliance while identifying regions with unmet emergency care demand and strong long-term investment potential.
Frequently Asked Questions About This Report
The U.S. freestanding emergency department market was valued at USD 17.5 billion in 2025.
The U.S. freestanding emergency department (FSEDs) market is anticipated to witness growth at a rate of 6.9% over the forecast period to reach a value of 29.6 billion by 2033.
Some key players operating in the U.S. freestanding emergency department market include Adeptus Health Inc.; Tenet Healthcare Corporation; Universal Health Services, Inc.; HCA Healthcare, Inc.; Community Health Systems, Inc.; Ascension Health; Legacy Lifepoint Health, Inc.; Ardent Health Services; and Emerus
Key factors that are driving the U.S. freestanding emergency department market growth include overcrowding of the emergency departments at the hospitals, a growing number of patients opting for immediate treatment options, advanced healthcare infrastructure of the country, rising number of injuries due to accidents, and rising incidence of chest pain or disease like epilepsy and stroke, which require immediate attention.
Which service segment accounted for the largest U.S. freestanding emergency department market share?The emergency department (ED) services segment held the largest market share of 44.7% in 2025. The growth is driven by the increasing demand for immediate treatment of acute illnesses, traumatic injuries, cardiac emergencies, respiratory conditions, and other time-sensitive medical conditions outside traditional hospital settings.
The southeast region is expected to witness strong growth due to population expansion, increasing healthcare demand, and continued investment in community-based emergency care facilities.
The Off-campus emergency department (OCED) dominated the ownership segment in 2025. This is attributable to the overcrowding of the hospital emergency department, and availability of high reimbursement for the treatment at OCED when compared with independent freestanding emergency department (IFSED).
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


