
- Home
- »
- Homecare & Decor
- »
-
U.S. Hot Tub Market Size, Share & Growth Report, 2033GVR Report cover

U.S. Hot Tub Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Above-Ground Hot Tubs, In-Ground Hot Tubs), By Seating Capacity (4-5 Persons, 6-8 Persons), By End Use, By Price Tier, By Distribution Channel, And Segment Forecasts
Market Size, 2025
$2.0BMarket Estimate, 2026
$2.1BMarket Forecast, 2033
$2.7BCAGR, 2026–2033
3.7%U.S. Hot Tub Market Summary
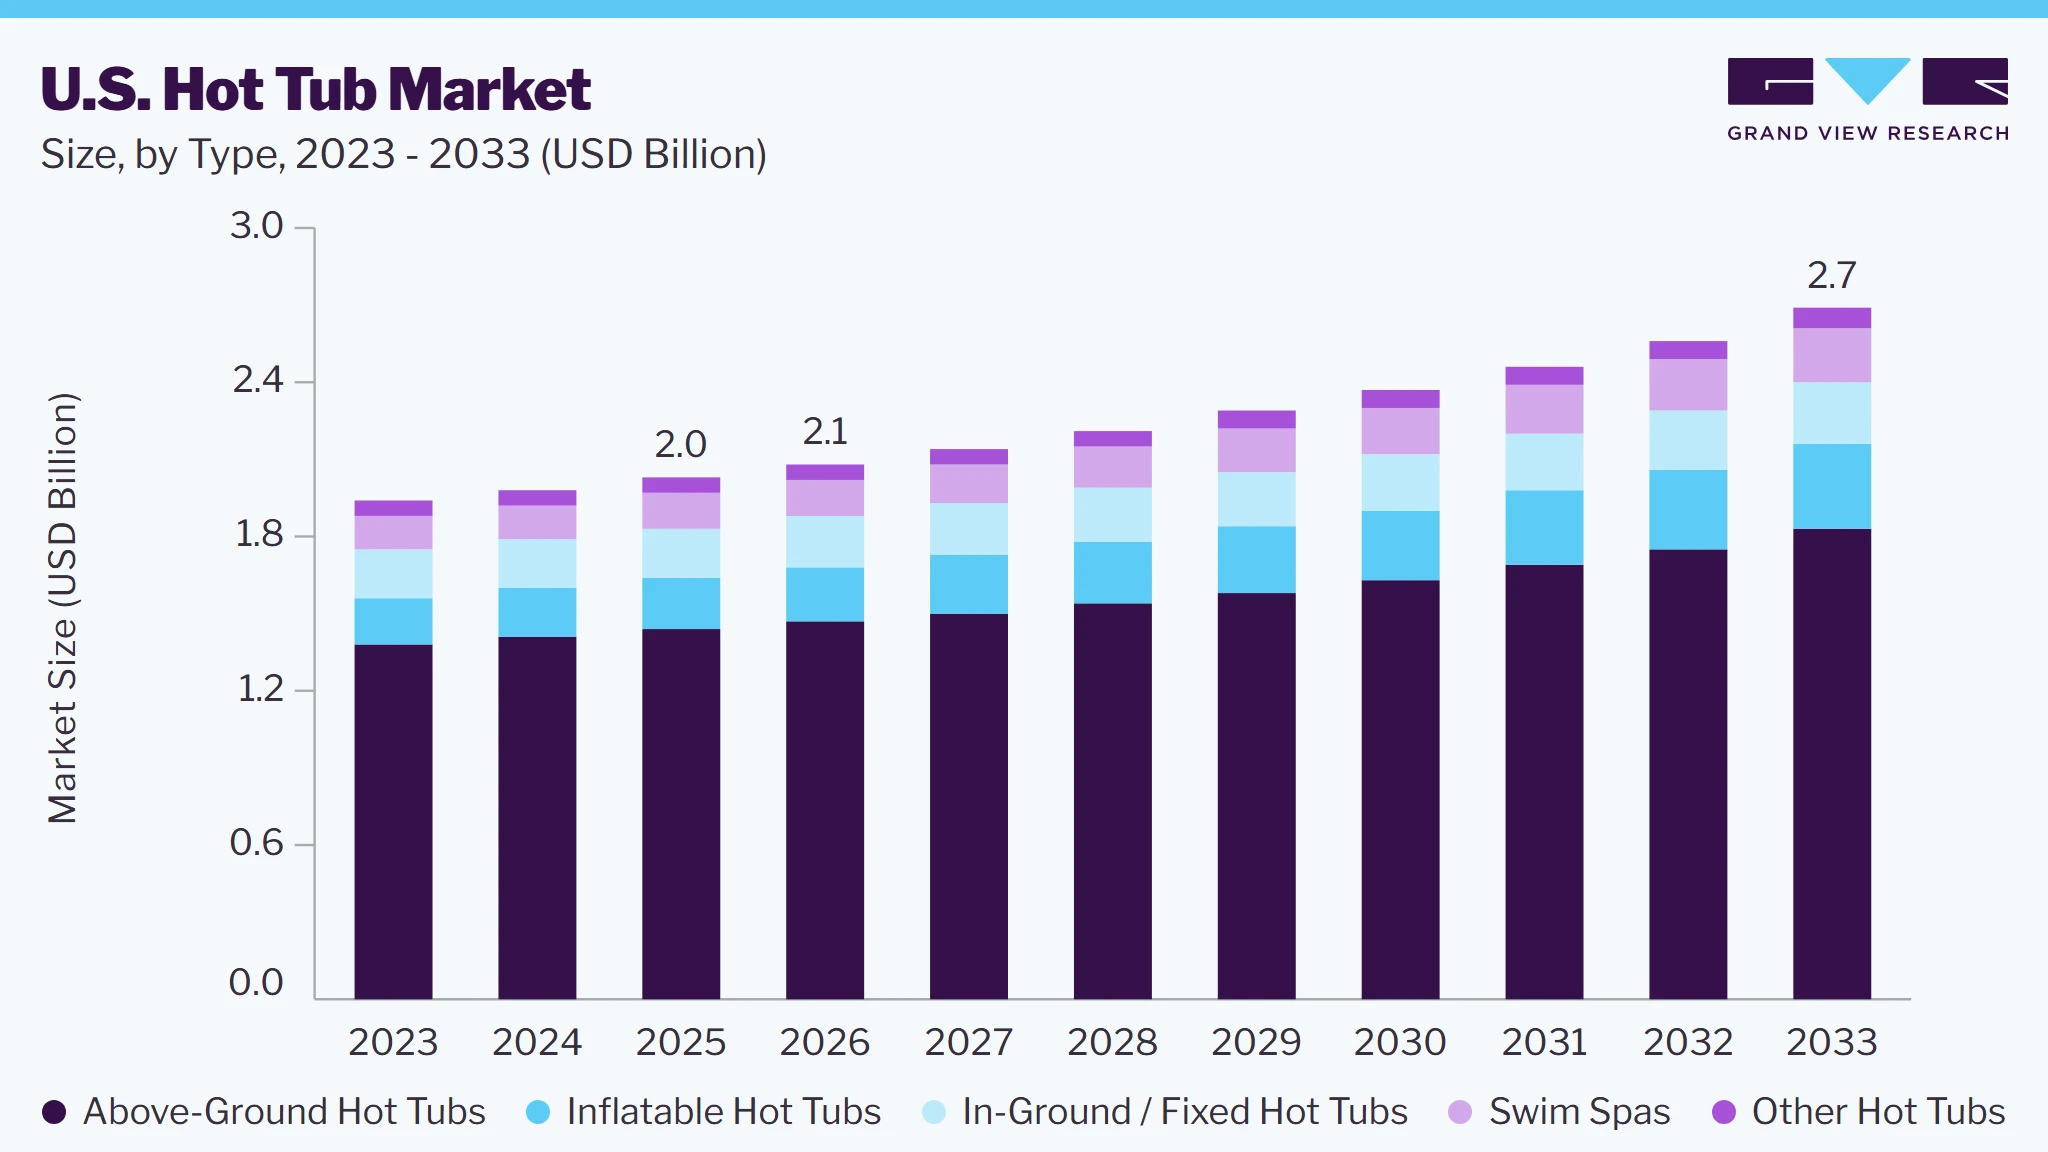
The U.S. hot tub market size was valued at USD 2.0 billion in 2025 and is projected to grow from USD 2.1 billion in 2026 to USD 2.7 billion by 2033, at a CAGR of 3.7% from 2026 to 2033. Market growth is being supported by sustained consumer spending on backyard recreation, rising interest in home-based relaxation and hydrotherapy, renovation of outdoor residential spaces, and demand for premium wellness-oriented amenities.
Key Market Trends & Insights
- By type: The above-ground hot tubs segment dominated the U.S. market with a 70.8% share in 2025.
- By seating capacity: The hot tubs for 4-5 person segment represented the largest share, accounting for a 41.3% in 2025.
- By price tier: The mid-range hot tubs segment held the largest revenue share, accounting for 47.1% in 2025.
- By end use: The residential applications dominated the U.S. market with an 80.5% share in 2025.
- By distribution channel: The specialty retail stores accounted for the largest distribution share, representing 67.6% of the U.S. market in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.0 Billion
- Estimated market size in 2026: USD 2.1 Billion
- Projected market size by 2033: USD 2.7 Billion
- CAGR (2026-2033): 3.7%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. hot tub marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The U.S. market benefits from a large installed base, established hot tub manufacturers and dealers, and strong consumer familiarity with spa and hydrotherapy products. Growth is increasingly shifting toward higher-value products as consumers seek improved insulation, energy efficiency, ergonomic seating, advanced water-care systems, and smart controls. At the same time, inflatable hot tubs and compact models are gaining relevance among consumers seeking lower upfront costs and flexible installation. Commercial demand from hotels, resorts, fitness facilities, and wellness establishments is also expanding, although residential applications continue to account for the majority of market revenue.The U.S. hot tub industry is increasingly shaped by the economics of year-round ownership and backyard installation, making energy consumption a more important purchase consideration than in many less-established markets. Hot tubs are commonly installed as permanent outdoor amenities, requiring continuous temperature management across seasonal weather conditions. As a result, U.S. consumers are placing greater emphasis on full ownership costs, including electricity consumption, heating efficiency, water replacement, chemicals, and routine servicing. This is strengthening demand for well-insulated cabinets, high-efficiency circulation and heating systems, insulated covers, and improved water-retention technologies. The issue is particularly relevant in colder U.S. states, where maintaining water temperature during winter can materially affect operating expenses. Manufacturers that can demonstrate lower standby losses and more predictable energy consumption therefore have a stronger value proposition beyond the initial purchase price.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The market is simultaneously moving toward smart ownership and automated maintenance, with connected functionality becoming increasingly integrated into premium U.S. spa offerings. Jacuzzi's SmartTub system provides remote temperature, jet and lighting control, energy-use monitoring, maintenance alerts, diagnostics and scheduling. Its latest SmartTub functionality includes Smart Heat, which adjusts heating according to factors such as usage patterns, weather, spa volume and insulation; Jacuzzi states that Smart Heat can reduce standby power by up to 25%. The system also supports on-peak/off-peak energy monitoring and vacation mode, directly linking connectivity with operating-cost management. Similarly, Watkins Wellness's Hot Spring brand has expanded connected functionality across its portfolio: the Hot Spring app can monitor pH, chlorine and salt levels, activate water-care dosing, control temperature and jets, and enable Energy Saving Mode. The Connected Spa Kit is available on 2024-and-newer Highlife and Limelight models and 2025-and-newer Hot Spot models. The introduction of FreshWater IQ Precision Dosing, which combines automated water monitoring with one-touch chemical dosing, further demonstrates how manufacturers are shifting from simple remote control toward semi-automated ownership.
This technological shift is changing the basis of premiumization. Hydrotherapy remains central, but manufacturers are increasingly combining therapy, water care, energy management and digital convenience into a single ownership proposition. For example, Master Spas' 2025 Michael Phelps Legend Series LSX 900 introduced a redesigned cabinet with integrated LED lighting while retaining 72 jets, a Master Blaster foot-therapy system, an Xtreme Therapy seat and a saltwater option. Its redesigned 2025 Twilight TS 7.2 similarly combined redesigned jets, an upgraded cabinet, a dedicated neck-and-shoulder therapy seat and saltwater compatibility. These launches illustrate how premium products are expanding beyond traditional specifications such as jet count and seating capacity toward multi-dimensional wellness experiences that include aesthetics, targeted hydrotherapy and simplified water management.
The competitive structure remains strongly influenced by brand reputation, dealer coverage and after-sales service, because hot tubs are relatively complex, high-ticket outdoor products requiring delivery, electrical installation, site preparation, water-care guidance and periodic servicing. The importance of the dealer ecosystem is reflected in manufacturers' connected-service strategies. Jacuzzi's SmartTub, for example, can send service-related alerts to the owner and authorized dealer, while its diagnostic functionality allows dealers to identify potential issues remotely. Hot Spring similarly emphasizes a dealer-installed Connected Spa Kit and maintains a dealer network for installation, maintenance and product support. Consequently, companies such as Jacuzzi, Watkins Wellness/Hot Spring, Master Spas, Bullfrog, Cal Spas and Sundance compete not only on the physical spa but also on dealer accessibility, installation support, warranty coverage, water-care services and post-sale responsiveness. This creates a structural advantage for established brands with broad U.S. distribution and service infrastructure.
Residential applications remain the core demand base, but the addressable opportunity is expanding into second homes, vacation rentals and broader wellness-oriented properties. The relevance of remote management is particularly evident in Hot Spring's current connected-spa positioning, which explicitly includes managing a spa at a second home or rental property through its app. This type of functionality is commercially important because a remotely located spa can otherwise require physical monitoring for temperature, water chemistry and equipment status. At the same time, the convergence between hot tubs and exercise products is strengthening the swim-spa opportunity. Master Spas' 2025 H2X Fitness range, for example, introduced 21-foot Trainer and Challenger models with separate swimming and hot-tub zones, allowing consumers to combine exercise, hydrotherapy and leisure within one backyard installation. The development supports a broader backyard wellness positioning in which hot tubs, swim spas, recovery products and fitness equipment increasingly overlap.
A further U.S.-specific opportunity is the premiumization of outdoor living spaces, where hot tubs increasingly compete for discretionary spending alongside pools, patios, outdoor kitchens and other backyard improvements. Manufacturers are responding with products designed to function as architectural and lifestyle elements rather than standalone appliances. The 2025 Master Spas LSX 900, for example, added an integrated LED cabinet design alongside its premium hydrotherapy package, while Hot Spring's current Hot Spot range emphasizes metallic corners, exterior LED lighting, natural-material-inspired cabinet finishes and contemporary styling. This supports higher-ticket positioning by allowing manufacturers to sell the hot tub as part of the overall outdoor environment. At the other end of the market, affordability remains relevant: Hot Spring's current portfolio spans premium Highlife models starting at $289/month, Hot Spot models from $165/month and Freeflow models from $91/month under its advertised financing structures, illustrating the industry's effort to maintain multiple price-access points.
Overall, the U.S. market is developing along two distinct but complementary pathways. The value-oriented segment emphasizes accessible pricing, simplified installation and basic wellness functionality, while the premium segment is increasingly defined by energy efficiency, sophisticated hydrotherapy, automated water care, connected controls, aesthetics and remote ownership. The product direction of Jacuzzi's SmartTub, Hot Spring's FreshWater IQ and Connected Spa ecosystem, and Master Spas' 2025 product updates demonstrates that competition is moving from “more jets and larger capacity” toward lower ownership friction and a more integrated wellness experience. This makes energy consumption, automation and maintenance increasingly important competitive variables alongside traditional measures of hydrotherapy performance.
Market Dynamics
The U.S. market for hot tub is benefiting from the increasing integration of wellness, recovery, and relaxation into residential outdoor spaces. Hot tubs are increasingly positioned as home-based wellness amenities rather than occasional-use leisure products, with manufacturers expanding hydrotherapy configurations around specific therapeutic needs. For example, Bullfrog Spas' JetPak Therapy System allows users to select and interchange different jet configurations designed around areas such as the neck, shoulders, back, hips and feet, giving consumers a more personalized hydrotherapy proposition than conventional fixed-jet systems.
The wellness positioning is also extending into home recovery and fitness. Master Spas has continued to market its hot tubs and swim spas around relaxation, recovery and wellness at home, while its dealer network has promoted products alongside cold tubs and saunas, indicating a broader convergence between hot-tub ownership and the home-recovery category. In its 2025 Global Sales Event, Master Spas specifically grouped hot tubs, swim spas, cold tubs and saunas within its home-wellness offering, with discounts of up to $2,000 across these categories. This broadening product ecosystem increases the addressable consumer base beyond traditional recreational users toward households seeking post-exercise recovery, relaxation and convenient wellness experiences without leaving home.
The market is also seeing greater emphasis on space-efficient and flexible residential installation. Caldera's Fantasy Series, for example, includes plug-and-play models designed for patios, smaller yards and second homes, while its Aspire model measures only 6 ft × 4 ft 5 in and seats two adults. The model requires a standard 115V outlet rather than special wiring, demonstrating how manufacturers are lowering physical and installation barriers to residential adoption. This expands the potential market beyond households with large dedicated backyard areas and supports demand for compact 2-3 person products in addition to conventional family-sized spas.
The biggest constraint on wider U.S. hot tub penetration is the total cost of ownership, which extends well beyond the purchase price. Permanent installations can require site preparation, delivery, electrical work, steps, covers and ongoing water-care products, while owners must also account for filtration, maintenance and eventual component replacement. The installation burden is particularly relevant for conventional 230V spas, where electrical work can add to the upfront cost and may require coordination with licensed electricians and local permitting requirements.
Manufacturers are responding by developing products that reduce installation complexity, but these products also illustrate the trade-off between accessibility and product capability. Caldera's Fantasy Series is positioned as a plug-and-play alternative requiring no special wiring and can operate from a standard 115V outlet. The Aspire model is priced at a current MSRP of $5,499, considerably below Caldera's Utopia portfolio, where listed models range from approximately $18,499 to $29,499. The substantial price difference across the same manufacturer's portfolio demonstrates the wide affordability gap within the U.S. market and the challenge of converting price-sensitive consumers into permanent hot-tub owners.
Operating costs create an additional barrier because hot tubs must maintain elevated water temperatures and circulate water regularly. Energy consumption is influenced by insulation, cover performance, ambient temperature, water temperature and operating behavior, making the economics particularly important in colder regions. Manufacturers are therefore increasingly using energy certification and efficiency-oriented construction as selling points. Caldera's Fantasy models, for instance, are certified to California Energy Commission and APSP 14 energy-efficiency standards and use insulated covers and foam insulation. This indicates that energy efficiency is not simply a technical specification but is increasingly being used to address consumer concerns around recurring ownership costs.
A significant opportunity for U.S. manufacturers lies in combining lower maintenance requirements, automated water care and intelligent control systems into premium hot tubs. The opportunity is particularly relevant in a mature market where replacement buyers already understand the basic functionality of conventional spas and are more likely to pay for improvements that directly reduce ownership effort.
Recent product development from Caldera illustrates this transition. Its FreshWater IQ system combines smart monitoring of pH, chlorine and salt levels with automated recommendations and one-touch chemical dosing. The company's 2026 product messaging specifically highlights new precision-dosing functionality, through which users can dispense pH Up, pH Down or phosphate remover from the system. Caldera's broader FreshWater system also states that properly maintained water can remain clean and fresh for up to a full year, reducing the frequency of draining and refilling. These features directly address one of the major friction points in hot-tub ownership-the time and knowledge required for water maintenance-rather than merely adding cosmetic or entertainment features.
Connected control is creating another premiumization opportunity. Caldera's Connected Spa Kit is available for 2024-and-newer Utopia and Paradise models and 2025-and-newer Vacanza models. Through the Caldera app, owners can monitor water chemistry, trigger water-care dosing, adjust temperature, lighting and jet strength, activate energy-saving mode and manage a spa located at a second home or rental property. This is particularly relevant to the U.S. market because second-home and vacation-property owners may not be physically present to monitor their spas every day.
Energy management can therefore become a quantifiable premium feature rather than a generic efficiency claim. Caldera's Utopia Series combines an isolated base pan with an EnergyPro circulation pump designed to operate at low wattage, while heat generated by pump operation is transferred back into the water. At the more accessible end of the portfolio, the Fantasy Series combines plug-and-play installation, CEC/APSP 14 energy certification and simplified water care. The contrast between these products suggests a clear opportunity for manufacturers to develop a tiered value proposition: entry-level products reduce installation barriers, while premium products monetize automation, energy optimization and maintenance reduction.
Analyst Perspective
The U.S. hot tub industry is being driven by the shift toward at-home wellness, backyard recreation, and hydrotherapy, with replacement purchases supporting a mature installed base. Premium brands are competing through energy-efficient insulation, advanced water-care systems, app-enabled controls, and targeted hydrotherapy jets, while inflatable and entry-level above-ground units broaden affordability. Rising installation and operating costs are making energy efficiency increasingly important in purchase decisions. The market also benefits from strong showroom-based selling, where consumers can test seating, jet configurations, and comfort before purchase, reinforcing the importance of dealer networks and experiential retail.
Consumer Insights
 To learn more about this report, Download Free Sample Report
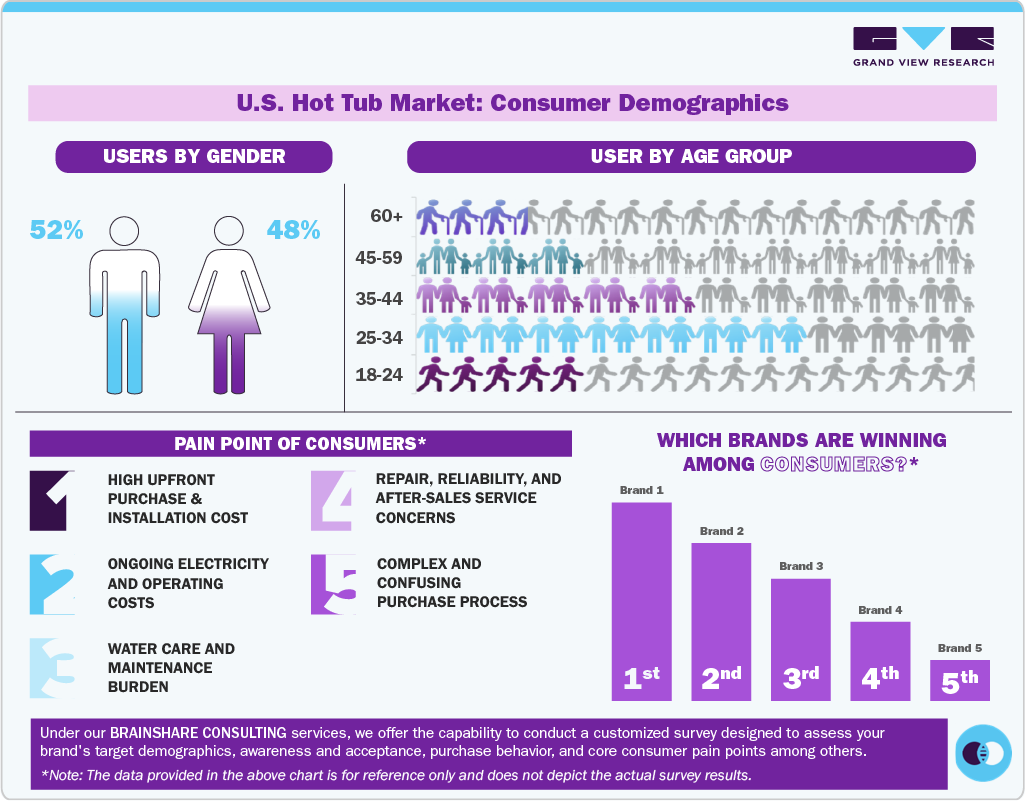
Consumer behavior in the U.S. hot tub industry reflects a high-consideration, lifestyle-driven purchase process in which consumers balance wellness benefits with space, price, maintenance, and long-term ownership considerations. Unlike smaller recreational products that can be purchased largely online, hot tubs involve installation, electrical requirements, water management, delivery, and after-sales service. Consequently, U.S. consumers typically conduct extensive research before purchase and increasingly assess the product as part of a broader home-wellness and outdoor-living investment.
-
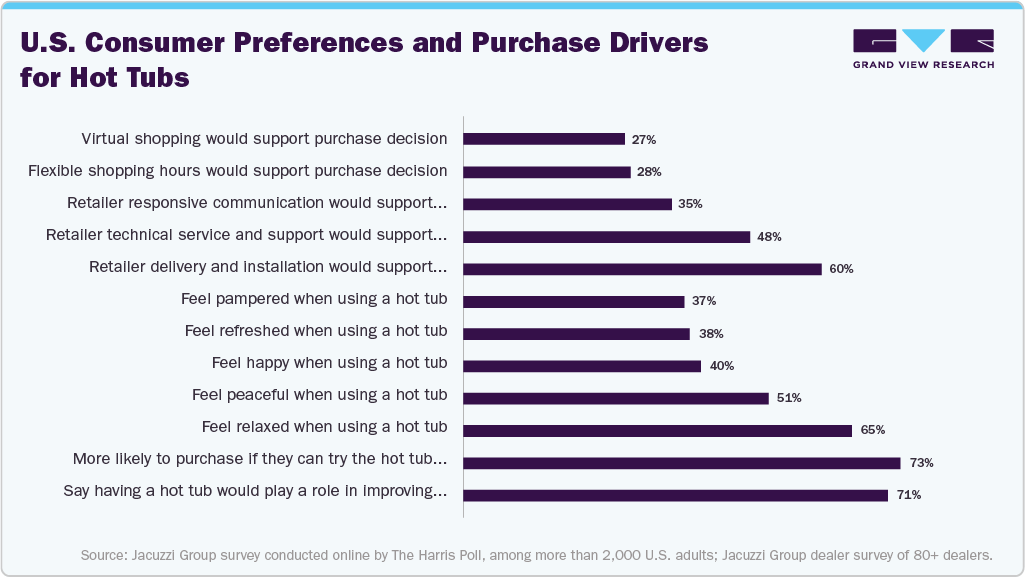
Wellness is increasingly influencing how Americans perceive the product: A Jacuzzi Group survey conducted by The Harris Poll among more than 2,000 U.S. adults found that 71% believed having a hot tub would play a role in improving their lifestyle. Respondents most commonly associated hot tubs with feeling relaxed and peaceful. This indicates that U.S. consumers increasingly connect hot tubs with lifestyle enhancement rather than viewing them only as recreational equipment. Brands such as Jacuzzi and Hot Spring therefore increasingly position hydrotherapy, relaxation, recovery, and everyday wellness as central components of the product proposition.
-
Consumers want to experience the product before committing: Physical interaction has an unusually strong role in the U.S. purchase process. The same Jacuzzi/Harris Poll research found that 73% of surveyed Americans would be more likely to purchase from a store where they could try a hot tub first. This supports the continued importance of dealer showrooms, wet-testing, product demonstrations, and seating trials. A consumer can compare dimensions and specifications online, but cannot fully determine whether a seat provides adequate lumbar support or whether jet placement feels comfortable without physically entering the product.
 To learn more about this report, Download Free Sample Report
Source: Jacuzzi Group survey conducted online by The Harris Poll, among more than 2,000 U.S. adults; Jacuzzi Group dealer survey of 80+ dealers.
-
Capacity is a practical starting point for product selection: U.S. consumers frequently begin their product evaluation by determining who will actually use the hot tub. AQUA Magazine's U.S. retailer research identified bather capacity as the No. 1 consumer consideration, followed by hydrotherapy/rehabilitation and ease of use. This means retailers are often helping consumers translate household composition and intended usage into a suitable configuration rather than simply selling a specific brand. A couple may prioritize compact seating and lower operating requirements, while a family may place greater emphasis on multiple seats, open footwells, and social-use layouts.
-
Hydrotherapy is being assessed as a functional benefit: Consumers are increasingly evaluating how a hot tub will perform for relaxation, recovery, and physical comfort rather than focusing exclusively on the number of jets. AQUA's retailer research placed hydrotherapy/rehabilitation immediately behind capacity among consumer priorities. This is creating opportunities for manufacturers such as Bullfrog International, Master Spas, Jacuzzi, and Hot Spring to differentiate through targeted jet placement, ergonomic seating, massage zones, footwell configurations, and specialized hydrotherapy systems.
-
Online research is changing the role of the U.S. dealer rather than eliminating it: Consumers are arriving at showrooms with greater prior knowledge of brands, specifications, pricing, reviews, and available technologies. AQUA's 2025 retailer research specifically notes that consumers are often well researched before entering stores but continue to rely on personal recommendations, quick answers, and ongoing support to make confident decisions. The purchasing journey is therefore becoming hybrid: digital channels are increasingly used for discovery and comparison, while dealers remain important for product validation, installation advice, financing, and service.
-
The physical showroom remains an important conversion environment: U.S. consumers are not treating hot tubs as products that can be selected purely from a specification sheet. AQUA reported that 57% of retailers still generated all their sales in-store in 2025, despite growing investment in e-commerce and digital tools. This demonstrates that physical retail continues to play an important role in a category where consumers need to evaluate comfort, size, jet performance, appearance, and dealer credibility before making a high-value purchase.
-
Consumers are becoming more conscious of sustainability and operating efficiency: Energy efficiency and low-maintenance operation are increasingly entering the U.S. purchase conversation. AQUA's 2025 retailer research found that 34% of retailers had observed increased customer demand for green alternatives, with energy-efficient hot tubs, chlorine-free systems, solar-powered equipment, and low-chemical water-care solutions specifically identified. This indicates that some consumers are moving beyond the initial purchase price and considering how the product will perform throughout its ownership period.
-
Maintenance convenience is becoming part of perceived product quality: Consumer expectations do not end after installation. Actual customer-interaction research from Epic Hot Tubs covering more than 14,000 interactions from January 2025 through mid-April 2026 found that post-purchase questions shifted toward water chemistry, warranty, and electrical setup, while shoppers were particularly interested in size and seating before purchase. This suggests a clear behavioral transition: consumers initially focus on whether the product fits their needs, but after purchase they become much more concerned with making ownership straightforward.
-
Consumers increasingly expect support beyond the transaction: Hot tub ownership involves installation, water care, troubleshooting, replacement components, and servicing, so dealer support influences the perceived value of a brand. AQUA's 2025 retailer research found that consumers expect expert recommendations, rapid answers, and continuing support. This gives established manufacturers with extensive dealer networks an advantage because consumers can evaluate not only the hot tub itself but also the availability of local installation and service.
-
Wellness categories are increasingly being considered together: U.S. consumers are broadening their definition of home wellness beyond conventional hot tubs. AQUA reported that retailers were seeing interest across hot tubs, saunas, cold plunges, and swim spas, while 55% of surveyed retailers said they currently sold swim spas. This suggests that some consumers are approaching the category with a broader wellness objective and comparing different products according to relaxation, recovery, exercise, available space, and investment level.
-
Compact outdoor spaces are influencing alternative wellness-product consideration: Smaller residential lots and increasing development costs are affecting how consumers evaluate aquatic wellness products. AQUA's coverage of the U.S. swim-spa market highlights the ability of compact products to combine exercise and therapeutic functionality where traditional pools may be impractical. This creates a competitive environment in which hot tubs are increasingly evaluated against swim spas and other compact wellness products rather than against other hot tubs alone.
-
Economic conditions are making consumers more deliberate about discretionary purchases: U.S. retailers reported that inflation, interest rates, and consumer spending pressures continued to affect larger discretionary purchases. In AQUA's 2025 retailer survey, 48% of retailers reported lower revenue in 2024, while retailers also described greater consumer hesitation around larger purchases. At the same time, hot tubs remained one of the categories generating significant in-store activity. This indicates that consumers have not abandoned the category but are becoming more selective about the value proposition, timing, financing, and features associated with the purchase.
The U.S. hot tub consumer is therefore becoming more informed, more experience-oriented, and more focused on ownership value. The decision begins with practical questions around capacity, space, budget, and intended use, then moves toward hydrotherapy performance, comfort, energy efficiency, water care, and brand reliability. Digital research increasingly shapes consideration, but physical testing and dealer expertise remain important for conversion. For manufacturers, this means the strongest proposition is no longer simply “more jets or more features.” Companies such as Jacuzzi, Hot Spring, Master Spas, and Bullfrog can differentiate by demonstrating how their products improve the complete ownership experience, from showroom testing and ergonomic comfort through hydrotherapy, energy management, simplified maintenance, connected controls, warranty coverage, and local service. This is particularly important in a mature U.S. market where consumers have access to multiple established brands and can increasingly compare products before entering a dealer showroom.
Type Insights
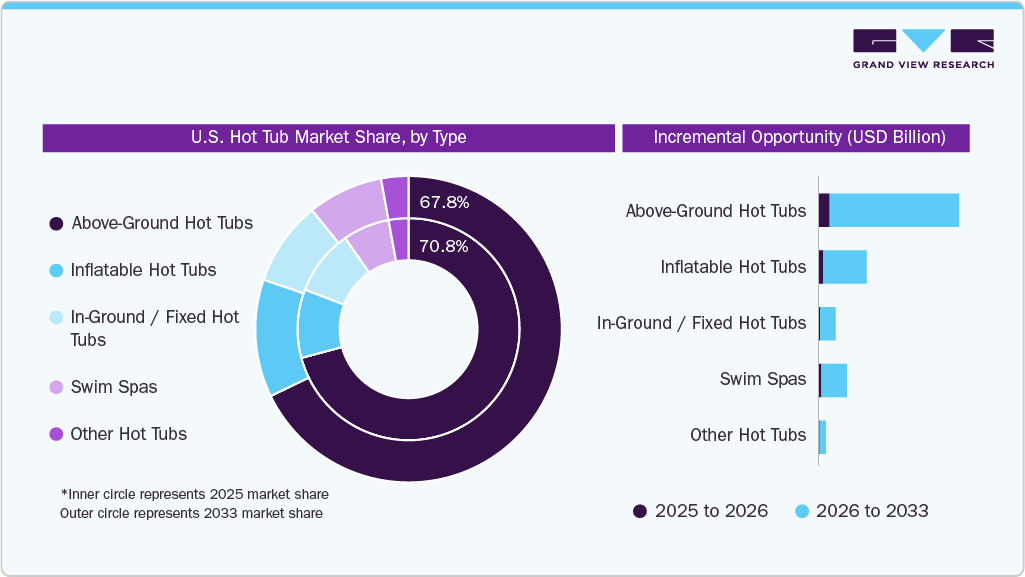
The above-ground hot tubs segment accounted for the largest revenue share of 70.8% in 2025, equivalent to approximately USD 1.4 billion, making them the dominant product type in the U.S. market. Their position reflects the strong preference for products that can be installed with comparatively limited structural modification to existing residential outdoor spaces. Above-ground units are available across a wide range of configurations, from compact two-person spas to larger family-oriented models, allowing manufacturers to address different household requirements and price points. The segment is also strongly supported by established U.S. brands such as Jacuzzi Brands LLC, Watkins Wellness, Master Spas, and Bullfrog International, which offer above-ground models incorporating hydrotherapy, insulation, digital controls, lighting, and water-management technologies.
 To learn more about this report, Download Free Sample Report
The inflatable hot tubs segment is projected to be the fastest-growing type, with a 6.6% CAGR during 2026-2033. The segment benefits from lower entry costs, portability, easier installation, and the ability to accommodate consumers who may not want to make a permanent investment in a rigid-shell spa. This positioning is particularly relevant to first-time buyers, smaller households, seasonal users, and consumers with limited outdoor space. However, the widening share of inflatable models does not materially threaten the dominance of above-ground rigid-shell products because conventional models continue to offer advantages in durability, insulation, seating ergonomics, hydrotherapy performance, and long-term ownership.
Seating Capacity Insights
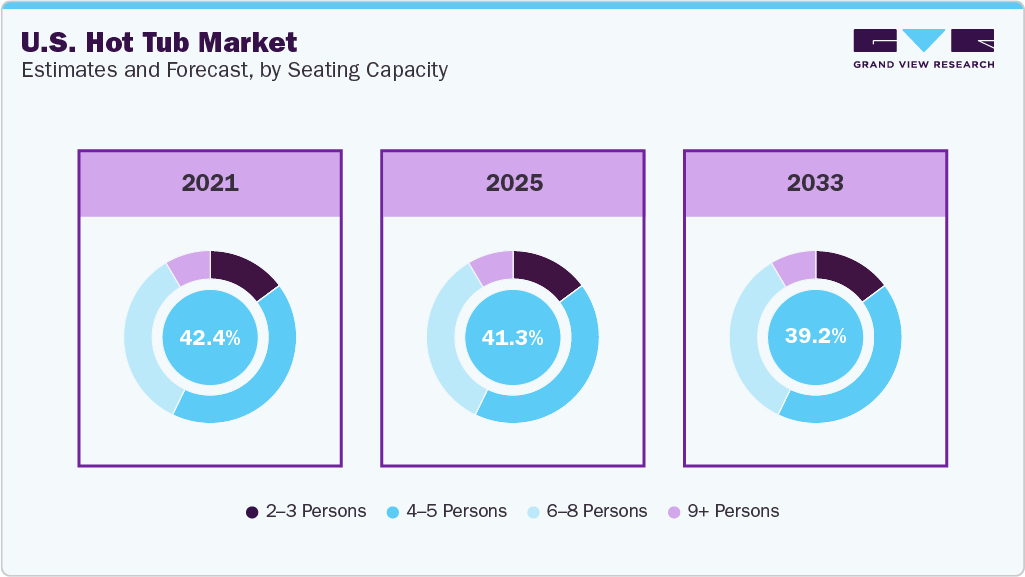
The hot tubs for 4-5 person segment represented the largest seating-capacity segment, accounting for 41.3% of U.S. market revenue in 2025, equivalent to approximately USD 0.8 billion. This configuration occupies a commercially attractive middle ground, it is sufficiently large for couples, families, and small social gatherings while avoiding the higher space, water, heating, and installation requirements associated with larger spas. U.S. manufacturers commonly position this capacity across mid-range and premium portfolios, with configurations featuring lounge seats, targeted hydrotherapy zones, adjustable jets, LED lighting, Bluetooth connectivity, and automated water-care systems. The segment nevertheless gradually loses share, reaching 39.2% by 2033, as demand expands toward both compact and larger-capacity products.
 To learn more about this report, Download Free Sample Report
The hot tubs for 2-3 person segment is projected to be the fastest-growing capacity segment, recording a 5.4% CAGR during 2026-2033. Growth reflects the increasing relevance of compact outdoor wellness products for consumers with smaller patios, decks, gardens, or limited installation areas. Compact spas also provide a lower-consumption alternative for households that do not require a large seating configuration. The segment is therefore particularly suited to couples and individual users who prioritize relaxation and hydrotherapy over social entertaining. Its expansion also aligns with the growth of inflatable and entry-level products, which provide consumers with lower-commitment ways to enter the hot tub category.
End Use Insights
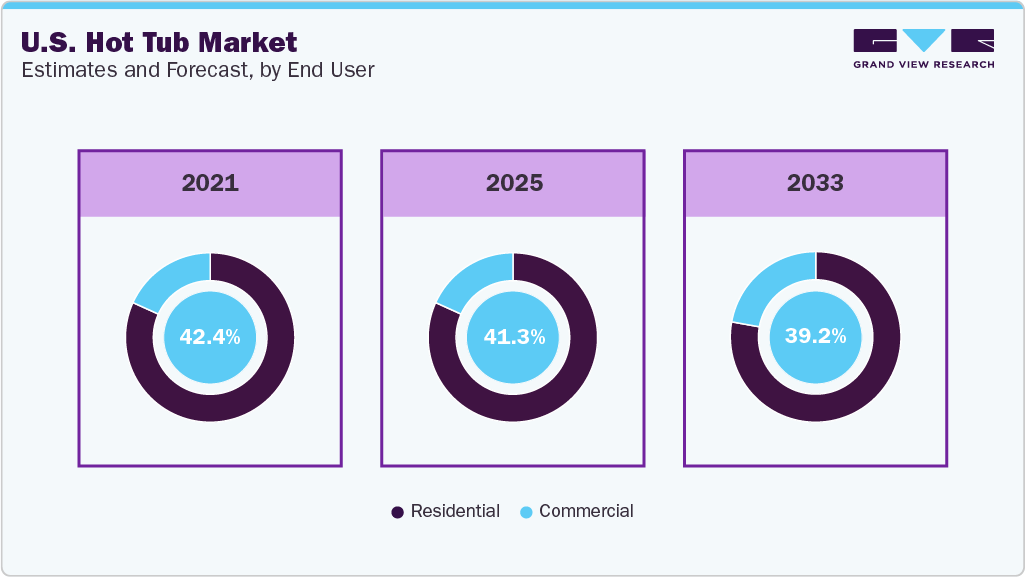
The residential applications segment accounted for the largest revenue share of 80.5% in 2025, representing approximately USD 1.6 billion. Household demand remains the foundation of the U.S. market because hot tubs are increasingly integrated into residential outdoor spaces as wellness, relaxation, recreation, and social-use amenities. The residential category encompasses homeowners purchasing spas for backyard use as well as households replacing older units. Demand is supported by the broad availability of products through specialized dealers, manufacturer networks, and direct sales channels. The segment is expected to remain dominant through 2033, although its share is projected to decline gradually, indicating increasing penetration of commercial applications.
 To learn more about this report, Download Free Sample Report
The commercial applications segment is projected to record the fastest growth, with a 5.4% CAGR during 2026-2033. Demand is supported by hotels, resorts, spas, wellness centers, fitness facilities, vacation-rental properties, and other hospitality-oriented establishments using hot tubs as guest amenities. Commercial buyers typically place greater emphasis on durability, maintenance requirements, operating reliability, warranty coverage, and service availability than residential buyers. Vacation-rental properties are particularly relevant because a hot tub can function as a differentiating outdoor amenity, while hotels and resorts can integrate spas into broader pools, wellness, and recreation facilities.
Price Tier Insights
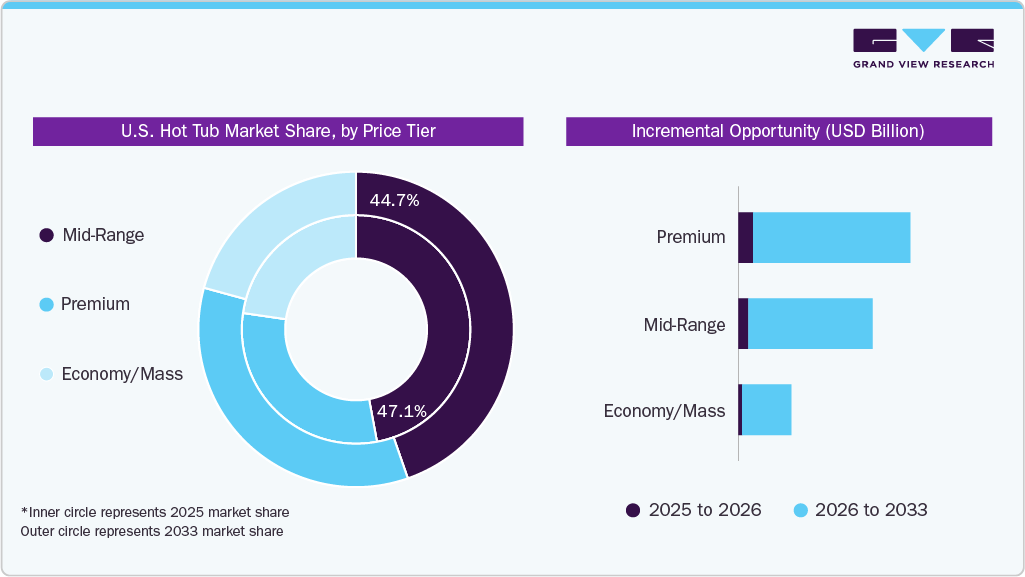
The mid-range hot tubs segment represented the largest price-tier segment in 2025, accounting for 47.1% of market revenue, or approximately USD 1.0 billion. The segment benefits from its ability to combine relatively accessible pricing with features that consumers increasingly associate with a modern hot tub. U.S. buyers in this category can access products offering multiple hydrotherapy zones, improved insulation, digital controls, filtration, LED lighting, ergonomic seating, and enhanced water-care systems without moving into the highest-priced customized configurations.
 To learn more about this report, Download Free Sample Report
The premium hot tubs segment is projected to be the fastest-growing price tier, expanding at a 5.5% CAGR during 2026-2033. This trend reflects increasing consumer willingness to pay for enhanced hydrotherapy, advanced seating designs, superior insulation, smart controls, upgraded finishes, and greater customization. Premium positioning is particularly evident among established manufacturers such as Jacuzzi, Watkins Wellness, Master Spas, Bullfrog International, and Sundance Spas, which differentiate higher-end models through proprietary hydrotherapy systems, ergonomic designs, connected controls, and enhanced energy-management features. The increasing premium share suggests that value growth is being generated not only through additional unit demand but also through consumers moving toward higher-specification products.
Distribution Channel Insights
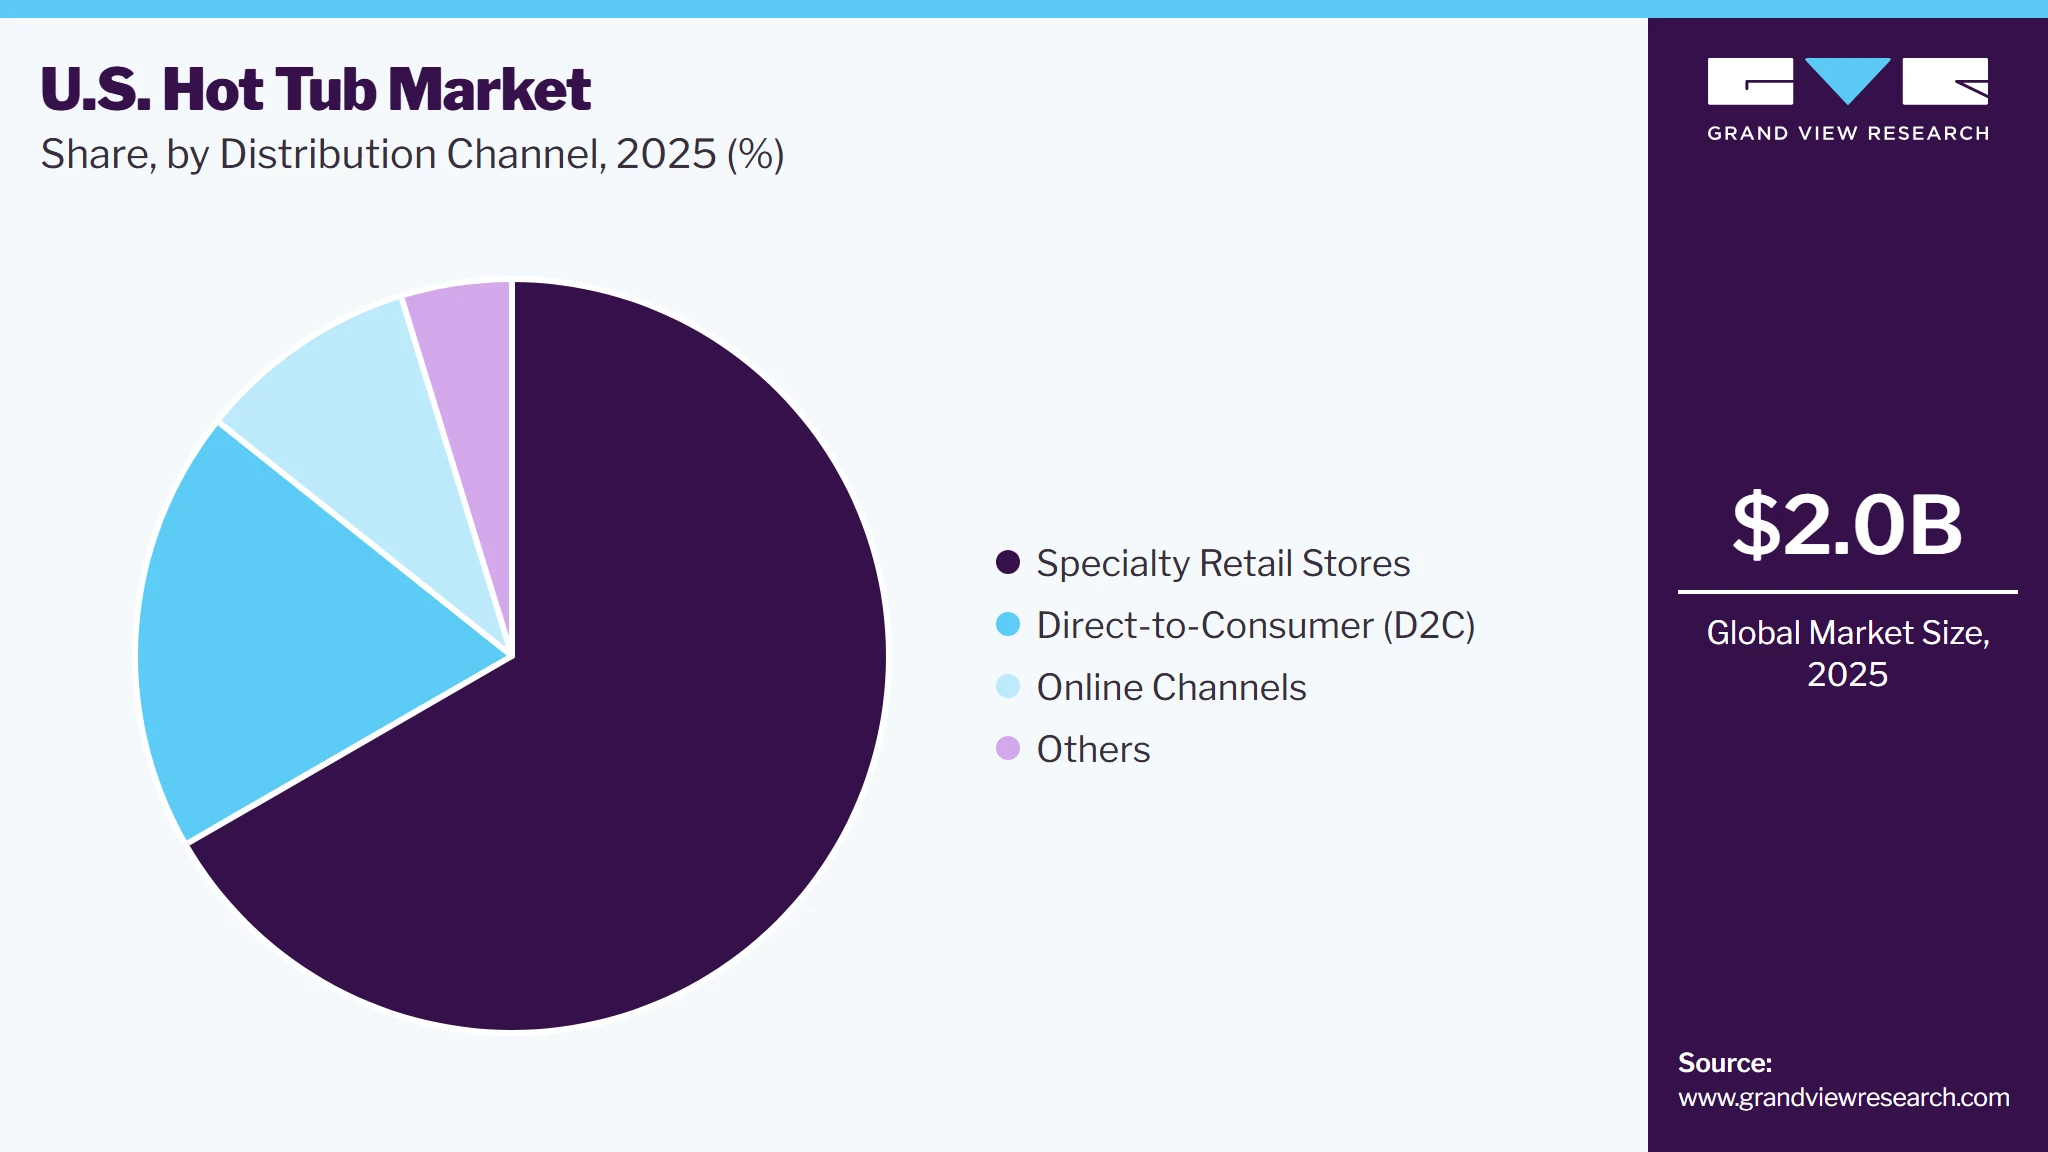
The specialty retail stores segment accounted for the largest distribution share at 67.6% in 2025, representing approximately USD 1.4 billion in sales. Their dominance reflects the unusually complex purchasing process associated with hot tubs. Consumers often need assistance with model selection, site suitability, electrical requirements, delivery, installation, financing, warranty, and ongoing service. Physical dealers can also provide showroom demonstrations and, where available, wet-testing, allowing buyers to evaluate seating comfort and hydrotherapy performance before committing to a high-value purchase. The channel remains important even as consumers increasingly conduct initial product research online. Its share is nevertheless projected to decline gradually by 2033 as alternative purchasing routes expand.
 To learn more about this report, Download Free Sample Report
The online channels segment is projected to be the fastest-growing distribution channel, with a 7.1% CAGR during 2026-2033. Digital channels are particularly relevant for product discovery, price comparison, specification research, customer reviews, and comparison of compact or inflatable models. The channel's growth is therefore likely to be strongest where installation requirements are relatively straightforward and consumers are comfortable making purchase decisions without extensive physical testing.
Key U.S. Hot Tub Company Insights
The U.S. hot tub industry is moderately fragmented, with competition led primarily by established domestic manufacturers and North American brands that have extensive dealer networks, showroom presence, installation capabilities, and after-sales service infrastructure. The competitive structure differs from the global market because U.S. demand is strongly influenced by residential backyard wellness, replacement purchases, home improvement spending, climate-specific product requirements, and showroom-led purchasing.
-
Leading U.S. Market Participants: Jacuzzi Brands LLC and Watkins Wellness (Hot Spring Spas) maintain particularly strong competitive positions through long-established brands, extensive dealer networks, broad product ranges, and high consumer recognition. Master Spas, Bullfrog International, Cal Spas, Sundance Spas, and Artesian Spas strengthen the competitive field across mid-range and premium hard-shell spas. Their presence is supported by dedicated U.S. manufacturing or distribution infrastructure and established relationships with specialty spa dealers. Jacuzzi Brands LLC and Watkins Wellness benefit from significant brand equity in the U.S. market. Their competitive advantage extends beyond the hot tub itself to dealer-supported consultation, installation, warranties, replacement components, water-care products, and ongoing maintenance. This integrated ownership and service proposition makes established brands particularly competitive in higher-value residential purchases.
-
Premium Technology Competition: Bullfrog International, Sundance Spas, Master Spas, and Jacuzzi compete strongly in premium U.S. households by emphasizing hydrotherapy, ergonomic seating, jet configuration, insulation, filtration, lighting, audio systems, and digital controls. Bullfrog's JetPak Therapy System provides a particularly differentiated configuration, while other manufacturers increasingly use smart controls and upgraded hydrotherapy systems to support premium pricing.
-
Regional Manufacturing Creates Competitive Differentiation: Cal Spas and Artesian Spas compete through product breadth, customization, dealer relationships, and manufacturing specialization. Their competitive relevance is particularly strong where consumers value access to nearby dealers and service providers. Meanwhile, Blue Falls Mfg. (Arctic Spas), Coast Spas, and Canadian Spa Company participate in the U.S. market through established distribution and dealer networks, bringing additional competition from Canadian manufacturers with products engineered for colder operating environments.
-
Climate Performance Is Particularly Relevant in the U.S.: The country's wide climatic variation creates different product requirements between regions. Cold-weather states place greater emphasis on insulation, freeze protection, heating efficiency, durable covers, and year-round operation, whereas warmer states can place greater emphasis on cooling, outdoor entertainment, aesthetics, and lower operating requirements. This gives Arctic Spas and other manufacturers with strong cold-climate positioning an opportunity to differentiate in northern U.S. markets rather than competing solely on brand recognition.
-
Dealer Networks Remain a Major Competitive Barrier: U.S. hot tubs are generally high-ticket, bulky products that require delivery, site preparation, installation, warranty servicing, and periodic maintenance. Consequently, manufacturers with extensive authorized-dealer and showroom networks have a structural advantage. Physical showrooms also allow consumers to compare seating layouts, jet performance, dimensions, finishes, and comfort before purchase. This makes dealer coverage particularly important for maintaining market share in the U.S., even as manufacturers expand direct-to-consumer and online lead-generation channels.
-
Replacement and Upgrade Demand Supports Established Brands: A substantial part of U.S. demand comes from existing spa owners replacing older units or upgrading to larger, more technologically advanced models. Established manufacturers are positioned to capture this demand because existing customers are already familiar with their brands, dealer networks, maintenance services, and replacement-parts ecosystems. This creates customer retention advantages that are less accessible to new entrants competing primarily through low prices.
-
Premiumization Is Driven by Backyard Wellness: U.S. consumers increasingly view hot tubs as part of residential outdoor-living and wellness infrastructure rather than solely as recreational products. Manufacturers are therefore differentiating through hydrotherapy zones, ergonomic seating, specialized jet systems, LED lighting, waterfalls, entertainment systems, app connectivity, filtration improvements, and energy-management functions. These additions allow premium brands to increase transaction values while addressing consumers seeking a more personalized home wellness experience.
-
Energy Efficiency Is a Key U.S. Purchase Consideration: Heating represents a major component of hot tub operating costs, making insulation, thermal covers, circulation pumps, heating systems, and control technologies important competitive attributes. This is especially relevant in colder states where spas may operate throughout winter. Manufacturers that can demonstrate lower energy consumption and better heat retention can differentiate their products on total cost of ownership, rather than competing solely on upfront price.
-
Market Share Remains Concentrated Among Established Brands but Not Dominated by One Company: The U.S. market does not appear to be controlled by a single manufacturer. The leading brands collectively capture a substantial portion of the organized hard-shell spa market, while numerous independent manufacturers, regional brands, dealers, smaller specialty producers, and value-oriented suppliers account for the remaining demand. Exact company-level shares should therefore be treated cautiously because the major manufacturers generally do not report standalone U.S. hot tub revenue; corporate disclosures may combine hot tubs with swim spas, accessories, chemicals, replacement parts, services, or other products.
-
Competitive Advantage Is Increasingly Based on the Full Ownership Experience: In the U.S., competition extends beyond the initial sale. Product availability, financing, delivery, installation, warranty response, water-care support, replacement parts, maintenance, and dealer accessibility can materially influence consumer choice. As a result, manufacturers with strong brands + broad dealer coverage + reliable service + differentiated product technology are better positioned than companies competing only through product pricing.
The U.S. competitive environment is expected to remain fragmented but brand-led, with established manufacturers retaining an advantage in premium and mid-range hard-shell spas. Future differentiation is likely to center on energy-efficient operation, advanced hydrotherapy, smart controls, customization, showroom experience, financing, and after-sales service. Jacuzzi Brands, Watkins Wellness, Master Spas, Bullfrog International, Cal Spas, Sundance Spas, and Artesian Spas are particularly relevant to the core U.S. competitive set, while Arctic Spas, Coast Spas, and Canadian Spa Company add competition from Canadian manufacturers with established U.S. market access.
 To learn more about this report, Download Free Sample Report
Key U.S. Hot Tub Companies:
-
Jacuzzi Brands LLC
-
Watkins Wellness (Hot Spring Spas)
-
Master Spas
-
Bullfrog International
-
Cal Spas
-
Sundance Spas
-
Blue Falls Mfg. (Arctic Spas)
-
Artesian Spas
-
Coast Spas
-
Canadian Spa Company
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Jacuzzi Brands LLC; Watkins Wellness (Hot Spring Spas); Master Spas; Cal Spas; Sundance Spas)
- Expand portfolios across premium, mid-range, and energy-efficient hot tubs while strengthening dealer networks, showroom presence, and direct consumer engagement. Invest in hydrotherapy technologies, smart controls, energy-efficient systems, insulation, and premium customization to address residential wellness and backyard-lifestyle demand.
- Strong brand recognition, extensive dealer and showroom networks, established manufacturing capabilities, and broad product portfolios across different price points and seating capacities. Long-standing relationships with dealers, contractors, and consumers support recurring sales and replacement demand.
- Higher operating and manufacturing costs can limit pricing flexibility. Large established organizations may face longer product-development cycles and greater exposure to housing-market conditions, discretionary spending, and fluctuations in component and material costs.
Emerging & Specialty Players (Bullfrog International; Blue Falls Mfg. (Arctic Spas); Artesian Spas; Coast Spas; Canadian Spa Company)
- Focus on differentiated hydrotherapy systems, modular seating configurations, energy efficiency, cold-climate performance, premium finishes, and specialized backyard wellness solutions. Leverage dealer partnerships, product demonstrations, digital marketing, and showroom experiences to target affluent residential buyers and consumers seeking customized hot tub experiences.
- Strong product differentiation, engineering expertise, premium positioning, and ability to address specific consumer requirements such as targeted hydrotherapy, extreme-weather performance, customization, and energy efficiency. More focused portfolios can enable faster adaptation to changing wellness and backyard-living preferences.
- Smaller scale and narrower distribution reach compared with the largest established brands. Higher concentration in premium residential demand can increase sensitivity to economic slowdowns, housing conditions, and reductions in discretionary spending.
Recent Developments
-
In May 2026, Olympic Hot Tub acquired Spa Warehouse, an established Pacific Northwest retailer and exclusive Caldera Spas dealer. The acquisition expanded Olympic Hot Tub's presence across the greater Puget Sound region and added Caldera Spas to its existing Hot Spring Spas offering. Both brands are manufactured by Watkins Wellness, creating greater product breadth under a common manufacturer relationship. The transaction illustrates continued consolidation at the U.S. specialty-dealer level, where retailers are expanding their geographic coverage and brand portfolios to capture more of the customer lifecycle, including sales, installation, service, maintenance, and replacement demand.
-
In October 2025, King Technology acquired Unique Solutions of North Dakota, the manufacturer of Ahh-some and Hot Tub Serum water-care products. The acquisition expanded King's portfolio of hot tub, pool, and swim-spa water-treatment products by adding jet-cleaning and water-care solutions alongside its existing FROG brands. For the U.S. market, the transaction is significant because it demonstrates increasing strategic interest in the recurring-revenue ecosystem surrounding installed hot tubs, including chemicals, cleaning, maintenance, and water-treatment products, rather than relying solely on one-time spa sales.
-
In June 2025, Platinum Spas launched its six-model Luxury Collection, incorporating advanced hydrotherapy, PlatinumGuru water monitoring, Wi-Fi connectivity, enhanced controls, and a five-layer Platinum Premium Shield Plus insulation system. Although Platinum Spas is a U.K.-based manufacturer, the development is relevant to the U.S. competitive environment because it reflects the type of premium product specification entering the North American market, particularly in energy efficiency, automated water management, connectivity, and wellness functionality. The company is part of Superior Wellness.
-
In May 2025, Bullfrog Spas highlighted continued expansion of its U.S.-based operations and retail footprint. The company reported hundreds of employees across Utah and elsewhere, sales through hundreds of retail locations worldwide, and 25 factory-owned stores. Its Herriman, Utah manufacturing facility remains central to its U.S. production strategy. Bullfrog continues to differentiate through its customizable JetPak Therapy System, allowing customers to select and reposition different massage configurations. This reinforces the importance of customization and differentiated hydrotherapy within the U.S. premium spa segment.
-
In February 2026, Masco reported that Watkins Wellness generated double-digit sales growth from the integration of Sauna360 into its dealer network and expanded into cold-plunge products during 2025. The development is particularly relevant to the U.S. market because Watkins is using its established hot-tub dealer infrastructure to broaden its presence across adjacent wellness categories. This creates an opportunity to increase revenue per customer and dealer while positioning hot tubs within a wider home-wellness ecosystem encompassing spas, saunas, and cold therapy.
U.S. Hot Tub Market Report Scope
Report Attribute
Details
Market size in 2025
UDA 2.0 billion
Estimated market size in 2026
USD 2.1 billion
Projected market size by 2033
USD 2.7 billion
Growth rate
CAGR of 3.7% from 2026 to 2033
Base Year
2025
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, seating capacity, end use, price tier, distribution channel
Key companies profiled
Jacuzzi Brands LLC; Watkins Wellness (Hot Spring Spas); Master Spas; Bullfrog International; Cal Spas; Sundance Spas; Blue Falls Mfg. (Arctic Spas); Artesian Spas; Coast Spas; Canadian Spa Company
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Hot Tub Market Report Segmentation
This report forecasts revenue growth at country level and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2026 to 2033. For this study, Grand View Research has segmented the U.S. hot tub market report based on type, seating capacity, end use, price tier, and distribution channel.
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Above-Ground Hot Tubs
-
Inflatable Hot Tubs
-
In-Ground / Fixed Hot Tubs
-
Swim Spas
-
Other Hot Tubs
-
-
Seating Capacity Outlook (Revenue, USD Billion, 2021 - 2033)
-
2-3 Persons
-
4-5 Persons
-
6-8 Persons
-
9+ Persons
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
-
Price Tier Outlook (Revenue, USD Billion, 2021 - 2033)
-
Economy/Mass
-
Mid-Range
-
Premium
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Specialty Retail Stores
-
Direct-to-Consumer (D2C)
-
Online Channels
-
Others
-
Segment Definition
Segment - Type
Revenue capture definition
Above-Ground Hot Tubs
Covers portable or permanently positioned hot tubs in U.S. installed above ground level, including acrylic, fiberglass, molded, and other rigid-shell units. Includes indoor and outdoor configurations, integrated seating, water jets, heating systems, filtration, controls, covers, and standard accessories. Excludes swimming pools and standalone bathtubs without hydrotherapy functionality.
Inflatable Hot Tubs
Covers portable hot tubs manufactured primarily with inflatable or air-supported structures, including PVC and reinforced multilayer materials. Includes compact and family-sized models, integrated heating, bubbling or hydrotherapy systems, filtration, control units, inflatable covers, liners, pumps, and associated accessories supplied as part of the product.
In-Ground / Fixed Hot Tubs
Covers hot tubs permanently installed into ground-level structures, decks, terraces, floors, or purpose-built outdoor and indoor installations. Includes fixed acrylic, concrete, fiberglass, tile, and other constructions incorporating hydrotherapy jets, heating, filtration, circulation, controls, seating, lighting, covers, and installation-related components.
Swim Spas
Covers elongated spa systems combining hydrotherapy seating with swimming or resistance-training functionality. Includes single-zone and dual-zone configurations, integrated current-generation systems, hydrotherapy jets, heating and filtration equipment, exercise features, seating areas, covers, controls, and related accessories sold with residential or commercial swim-spa installations in U.S.
Other Hot Tubs
Covers hot-tub products not classified as above-ground, inflatable, in-ground/fixed hot tubs, or swim spas. Includes specialized compact units, unconventional constructions, wood-fired or wood-bodied spa systems, and other hydrotherapy-oriented soaking products incorporating heating, water circulation, jets, filtration, seating, or related control systems.
Segment - Seating Capacity
Revenue capture definition
2-3 Persons
Covers hot tubs designed and marketed for simultaneous occupancy of two to three users. Includes compact portable, rigid-shell, inflatable, and fixed configurations with corresponding seating layouts, hydrotherapy jets, heating and filtration systems, controls, covers, and standard accessories. Capacity is based on the manufacturer-specified intended number of users.
4-5 Persons
Covers hot tubs designed for simultaneous use by four to five people, including portable, rigid-shell, inflatable, and permanently installed configurations. Includes product models with multiple seating positions, lounge seating where applicable, hydrotherapy jets, heating, filtration, circulation, controls, covers, steps, and standard manufacturer-supplied accessories.
6-8 Persons
Covers hot tubs specified for simultaneous occupancy of six to eight users across residential and commercial configurations. Includes above-ground, inflatable, fixed, and applicable spa models with multiple seats or loungers, hydrotherapy jets, heating, filtration, circulation, control systems, covers, steps, and other standard product accessories.
9+ Persons
Covers large-capacity hot tubs designed for simultaneous occupancy of nine or more users. Includes residential, hospitality, wellness, recreational, and other commercial configurations with multiple seating positions, hydrotherapy systems, heating and filtration equipment, circulation systems, controls, covers, access components, and standard accessories supplied with the installation.
Segment - End Use
Revenue capture definition
Residential
Covers hot tubs purchased or installed for use in private residences in U.S., including detached homes, apartments, condominiums, vacation properties, and private recreational spaces. Includes indoor and outdoor installations, portable and fixed units, and associated heating, filtration, hydrotherapy, controls, covers, maintenance equipment, and accessories intended for household use.
Commercial
Covers hot tubs used within commercial, institutional, hospitality, wellness, recreational, and shared-use facilities. Includes installations in hotels, resorts, spas, gyms, clubs, rental properties, healthcare and wellness facilities, and other establishments, together with commercial-grade heating, filtration, hydrotherapy, controls, maintenance systems, covers, and supporting equipment.
Segment - Price Tier
Revenue capture definition
Economy / Mass
Covers hot tubs positioned within entry-level and mass-market pricing, including basic rigid-shell, inflatable, and selected portable configurations. Products may include fundamental heating, filtration, circulation, jet, seating, control, and covering systems, with pricing reflecting standardized specifications, mainstream materials, limited customization, and broad retail or online availability.
Mid-Range
Covers hot tubs positioned above entry-level products and below premium offerings, incorporating enhanced materials, construction, seating configurations, hydrotherapy features, heating, filtration, insulation, controls, and accessories. Includes products sold through specialty retailers, D2C channels, dealers, and online platforms with broader feature combinations and moderate customization.
Premium
Covers higher-priced hot tubs featuring advanced construction, premium materials, enhanced insulation, sophisticated hydrotherapy systems, greater seating configurations, advanced controls, lighting, water-management features, energy-efficiency components, and extensive accessories. Includes high-specification residential and commercial models with greater customization, upgraded finishes, and specialized installation requirements.
Segment - Distribution Channel
Revenue capture definition
Specialty Retail Stores
Covers sales of hot tubs through dedicated spa, pool, wellness, and specialty home-improvement retailers operating physical stores or dealer showrooms. Includes manufacturer-authorized dealers and independent specialty retailers where customers can evaluate products, receive specifications, obtain installation services, and purchase hot tubs, accessories, maintenance products, and related equipment.
Direct-to-Consumer (D2C)
Covers hot-tub sales conducted directly by manufacturers or brands through their own branded websites, company-owned stores, showrooms, sales teams, or direct sales programs. Includes transactions where the brand controls customer acquisition and sales, with products covering hot tubs, swim spas, configurations, accessories, installation services, and related direct offerings.
Online Channels
Covers hot-tub transactions conducted through third-party digital marketplaces, multi-brand e-commerce platforms, online retailers, and other independent internet-based sales channels. Includes inflatable and portable units as well as selected rigid-shell products available for online purchase, together with associated accessories, equipment, delivery arrangements, and digitally facilitated transactions.
Others
Covers hot-tub sales through distribution routes not classified under specialty retail stores, D2C, or online channels. Includes independent dealers without dedicated specialty-store classification, pool and landscape contractors, builders, project-based suppliers, hospitality procurement, distributors, wholesalers, and other intermediary or institutional procurement channels.
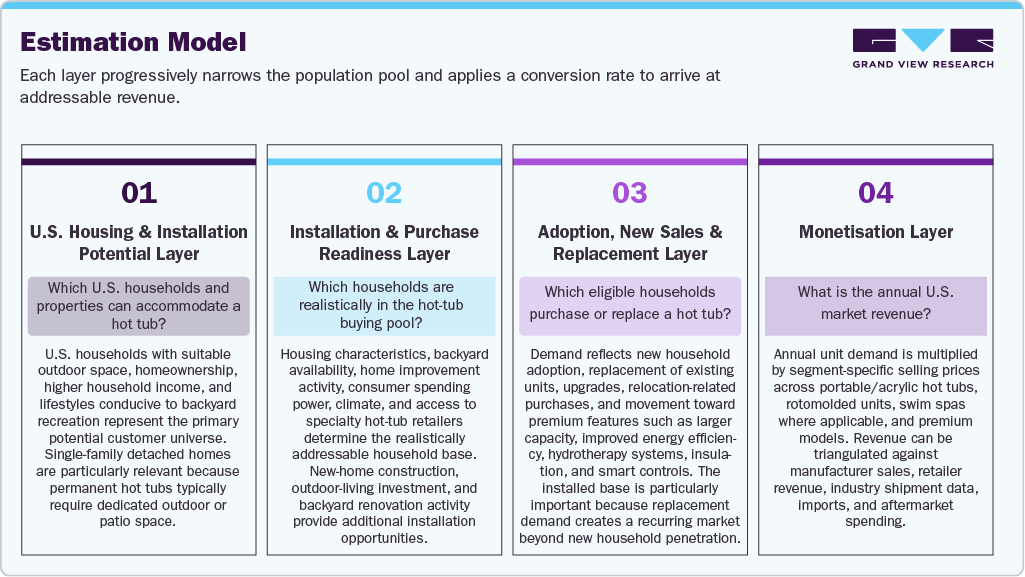
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis of Hot Tub Types, Seating Capacities, and End Uses
Detailed U.S.-specific cross-segmentation of above-ground, inflatable, in-ground/fixed hot tubs, swim spas, and other formats across 2-3, 4-5, 6-8, and 9+ person capacities, further mapped across residential and commercial users. The analysis considers the suitability of each configuration for detached homes, townhouses, apartments, vacation homes, hotels, resorts, spas, health clubs, and fitness facilities across the U.S.
Identifies which product configurations have the strongest fit within the U.S. market rather than treating all hot tubs as a homogeneous category. The analysis captures the importance of 4-5 and 6-8 person configurations for mainstream residential backyard use, while larger units and swim spas are more relevant to family-oriented properties, wellness facilities, hospitality applications, and fitness/recovery settings. It also distinguishes the role of inflatable units as an accessible entry point and hard-shell spas as the core premium and replacement market.
Residential vs. Commercial Hot Tub Opportunity Mapping
Assessment of U.S. residential and commercial demand, covering primary residences, second homes, vacation homes and rental properties, hotels, resorts, destination spas, health clubs, fitness facilities, and other hospitality locations. The analysis compares purchase drivers, installation requirements, utilization intensity, replacement cycles, maintenance needs, financing considerations, and purchasing decision-makers.
Provides a clearer understanding of the different economics of residential and commercial hot-tub demand in the U.S. Residential purchases are primarily influenced by backyard wellness, relaxation, family use, aesthetics, hydrotherapy, available space, and affordability. Commercial buyers place greater emphasis on durability, high-frequency utilization, sanitation, service response, warranty coverage, operating costs, and lifecycle economics. This helps identify where premium, commercial-grade, and high-capacity products have stronger opportunities.
U.S. Hot Tub Wellness & Lifestyle Application Mapping
Analysis of U.S. demand according to major applications including relaxation and stress relief, sleep and recovery, hydrotherapy, exercise and athletic recovery, family/social use, outdoor leisure, and hospitality/wellness experiences. These applications are mapped against product type, seating capacity, technology level, price positioning, and target consumer groups.
Moves the analysis beyond overall hot-tub ownership to identify why U.S. consumers and businesses purchase hot tubs. This is particularly valuable for premium segmentation, where manufacturers compete through hydrotherapy systems, ergonomic seating, targeted massage, water features, lighting, smart controls, and wellness-oriented functionality. The analysis also highlights the growing overlap between hot tubs, home wellness, outdoor living, athletic recovery, and hospitality experiences in the U.S.
Frequently Asked Questions About This Report
The U.S. hot tub market was valued at approximately USD 2.0 billion in 2025.
The U.S. hot tub market is expected to grow at a CAGR of 3.7% from 2026 to 2033, reaching USD 2.7 billion by 2033.
Above-ground hot tubs dominated the market, accounting for approximately 70.8% of the market in 2025.
Inflatable hot tubs are expected to record the fastest growth, with a projected 6.6% CAGR from 2026 to 2033.
The provided market data indicates continued growth across residential and commercial applications, increasing demand for premium hot tubs, inflatable hot tubs, larger-capacity models, and online purchasing channels. The commercial segment and online channels are also projected to grow faster than their respective counterparts during the forecast period.
The hot tub for 4–5 Persons segment led the market with a 41.3% revenue share in 2025, while the 2–3 Persons segment is projected to be the fastest-growing seating-capacity segment at a 5.4% CAGR.
Specialty retail stores held the largest revenue share of 67.6% in 2025, while Online Channels are projected to be the fastest-growing distribution channel, with a 7.1% CAGR from 2026 to 2033.
The mid-range segment dominated the market with approximately 47.1% of the revenue share in 2025, while Premium hot tubs are projected to be the fastest-growing price tier at a 5.5% CAGR.
The residential segment held the largest revenue share of 80.5% in 2025, while Commercial hot tubs are projected to grow faster, with a 5.4% CAGR from 2026 to 2033.
About the Author(s)
Homecare & Decor Research Team
Consumer Goods · Homecare & DecorThis report was authored by the homecare & decor research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the homecare & decor segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


