
- Home
- »
- Medical Devices
- »
-
U.S. In Vitro Fertilization Market Size & Share Report, 2033GVR Report cover

U.S. In-vitro Fertilization Market (2026 - 2033)
Size, Share & Trends Analysis Report By Procedure Type (Frozen Non-Donor, Frozen Donor, Fresh Donor), By Instrument (Culture Media), By End-use (Fertility Clinics, Hospitals & Others Setting), By Region, And Segment Forecasts
Market Size, 2025
$5.9BMarket Estimate, 2026
$6.2BMarket Forecast, 2033
$8.0BCAGR, 2026–2033
3.7%U.S. In-vitro Fertilization Market Summary
The U.S. in vitro fertilization market size was valued at USD 5.9 billion in 2025 and is projected to grow from USD 6.2 billion in 2026 to USD 8.0 billion, at a CAGR of 3.7% from 2026 to 2033. The rising prevalence of infertility among couples is driving the growth of the U.S. IVF market. According to the U.S. Centers for Disease Control and Prevention (CDC), in a report published in December 2025, 1.6% of women aged 20-49 years in the U.S. had used in vitro fertilization (IVF) or other assisted reproductive technology (ART) procedures during 2022-2023, highlighting the utilization of assisted reproductive treatments to address fertility challenges.
Key Market Trends & Insights
- By instruments: The culture media segment dominated the market and accounted for the largest share in 2025.
- By procedure type: Fresh non-donor segment dominated the market and accounted for a share of around 46.6% in 2025
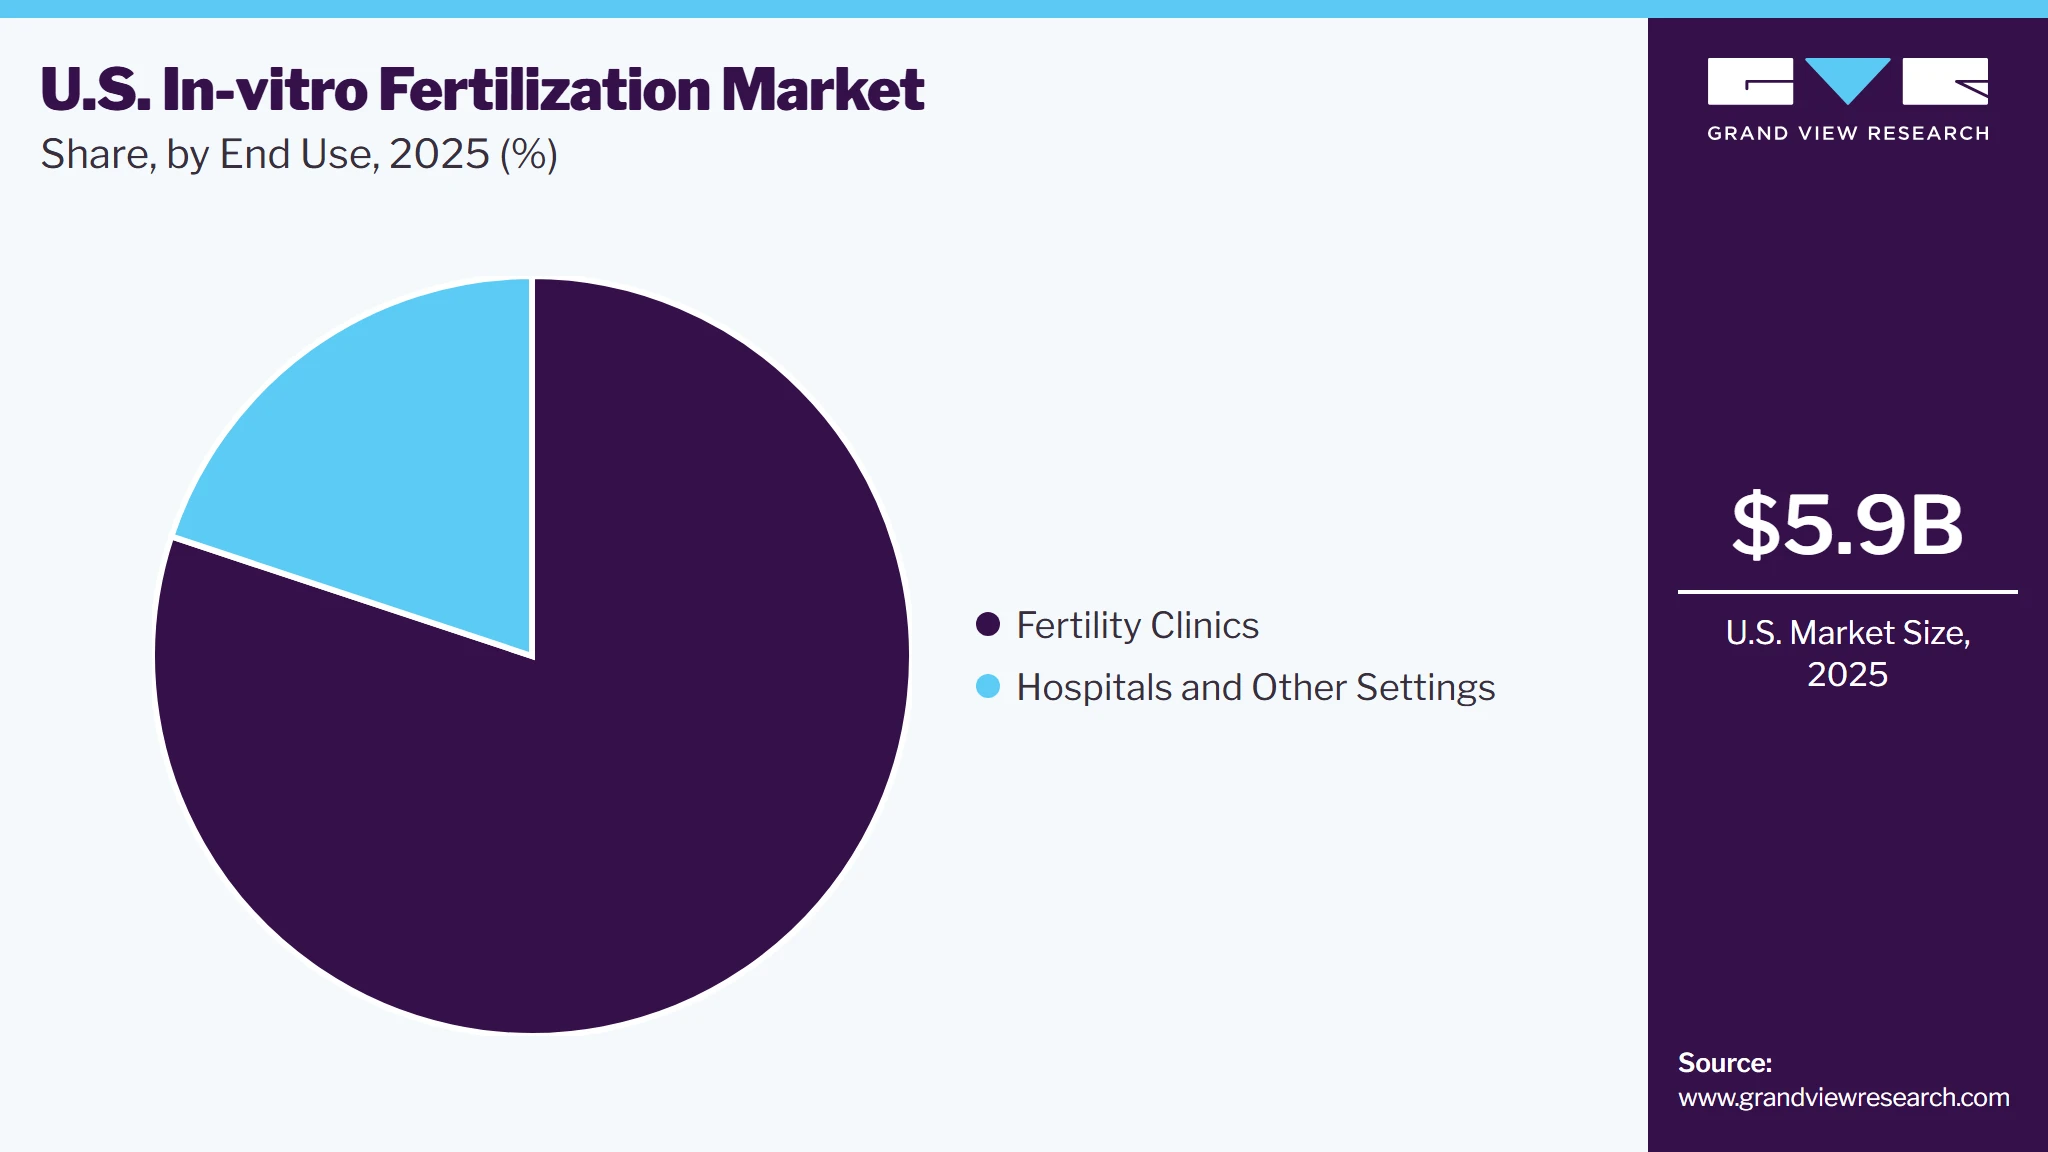
- By end use: The fertility clinics segment dominated the market with the largest share of 80.1% in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.9 Billion
- Estimated market size in 2026: USD 6.2 Billion
- Projected market size by 2033: USD 8.0 Billion
- CAGR (2026-2033): 3.7%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. in-vitro fertilization marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →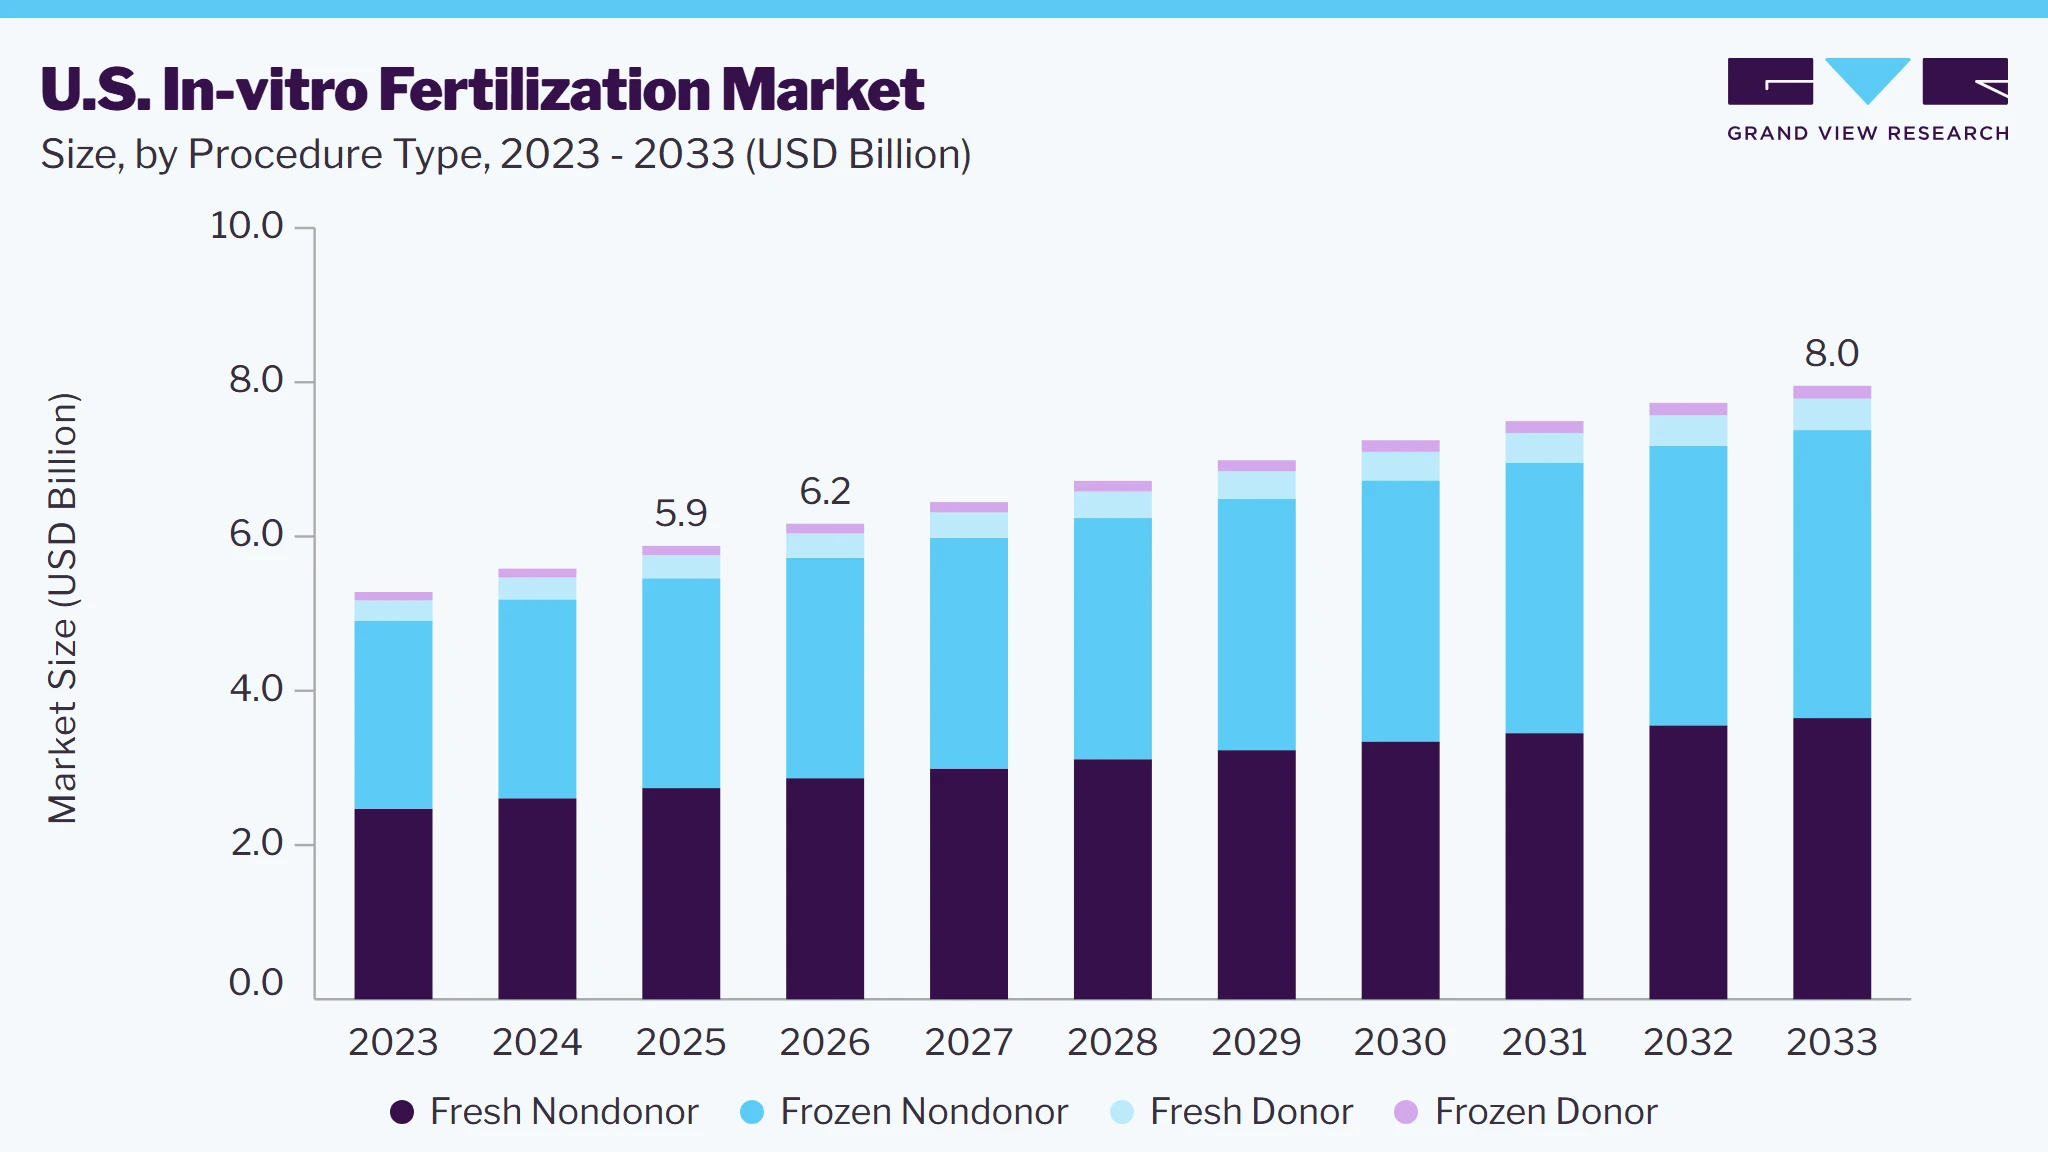 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market Dynamics
The growing use of IVF procedures is supporting the market by increasing the need for fertility treatment cycles, embryo transfers, and related laboratory services. IVF is widely used to address infertility and support family building among individuals and couples requiring assisted reproductive treatment. The increasing number of treatment cycles and births achieved through IVF reflects the expanding role of assisted reproductive technology in fertility care. For instance, in March 2026, the American Society for Reproductive Medicine (ASRM) reported that U.S. fertility clinics belonging to the Society for Assisted Reproductive Technology (SART) performed 449,772 IVF treatment cycles in 2024, resulting in 100,158 babies born through IVF. This marked the first time annual IVF births in the U.S. exceeded 100,000, highlighting the growing use of IVF procedures and the continued need for fertility services. The increase in treatment activity also supports demand for embryology laboratory equipment, embryo culture systems, cryopreservation services, and related clinical infrastructure. Continued use of IVF across fertility clinics is expected to sustain demand for specialized reproductive services and laboratory capabilities.
Improvements in IVF laboratory technology are supporting the growth of the market by enhancing embryo assessment, laboratory workflow standardization, and the management of clinical data. Advances in embryo imaging, artificial intelligence (AI)-based assessment, and digital laboratory systems are helping embryologists organize embryo records and support embryo selection and transfer decisions. These technologies also improve laboratory documentation and operational efficiency, supporting the integration of advanced systems into fertility clinics. For instance, in March 2025, Alife Health expanded its partnership with US Fertility to provide AI-powered IVF laboratory summary reports across its network of more than 100 clinics and 32 IVF laboratories in the U.S. The reports include embryo images, laboratory-generated grading, clinical information, and next steps, giving patients greater insight into their treatment. The collaboration reflects growing investment in digital and AI-enabled IVF laboratory tools to improve workflow consistency, data management, and patient communication, supporting demand for advanced reproductive laboratory technologies.
Case Study published by Sceintific Reports in May 2025: ECOVACS Launches Lilmilo Emotional AI Companion Robot
Background
In May 2026, ECOVACS, a global leader in home robotics, launched LilMilo, its first emotional AI companion robot. The launch marked the company's strategic expansion beyond home automation into emotionally intelligent companion robotics, addressing the growing demand for AI-powered solutions that support social interaction and emotional wellbeing.
Strategic initiative
LilMilo was designed to deliver a more human-centered companionship experience through emotional responsiveness, intelligent conversations, and personalized interactions. The robot leverages advanced artificial intelligence to provide cognitive engagement, emotional support, and interactive assistance, expanding the role of companion robots beyond conventional household tasks.
Market significance
The introduction of LilMilo reflects the industry's shift toward integrating emotional AI into companion robots, enabling them to address mental wellbeing, social engagement, and personalized care. The launch also demonstrates how robotics companies are diversifying their portfolios to capitalize on the growing demand for intelligent companion technologies across home and healthcare environments.
Key takeaway
The launch of LilMilo reinforces the growing importance of emotional AI in the companion robotics market and highlights the transition from function-oriented robots to socially intelligent systems capable of enhancing users' quality of life through empathetic and personalized interactions.
The high cost of IVF treatment is restraining the growth of the market by limiting access to fertility services among patients without adequate insurance coverage or sufficient financial resources. The overall treatment expense includes fertility medications, diagnostic testing, egg retrieval, embryo culture, and embryo transfer, while unsuccessful attempts may require additional cycles and increase the cumulative financial burden. These expenses may lead patients to postpone treatment, discontinue care, or seek lower-cost alternatives. For instance, in October 2026, KFF published findings from its 2026 Women’s Health Survey highlighting the financial barriers to fertility care in the U.S. The findings identified treatment costs and limited insurance coverage as major obstacles to accessing fertility services, with cost remaining a leading barrier among women who reported needing but not receiving care. The financial burden associated with IVF may therefore restrict treatment uptake and limit market expansion, particularly among patients facing substantial out-of-pocket expenses.
The growing use of frozen embryo transfer (FET) procedures presents an opportunity for the market by increasing the need for embryo cryopreservation, storage, warming media, and transfer-related laboratory services. Improvements in vitrification and embryo-warming techniques support embryo preservation and subsequent use during fertility treatment. For instance, in September 2025, the U.S. Food and Drug Administration (FDA) cleared Fujifilm Irvine Scientific's Fast Warm-NX, a ready-to-use medium intended for thawing vitrified human blastocyst-stage embryos during assisted reproductive procedures. The product uses a single-step warming protocol, supporting laboratory workflows for frozen embryo transfers. This regulatory clearance highlights continued product development in embryo-warming technologies and creates opportunities for suppliers of specialized reproductive media and cryopreservation-related products.
Market Concentration & Characteristics
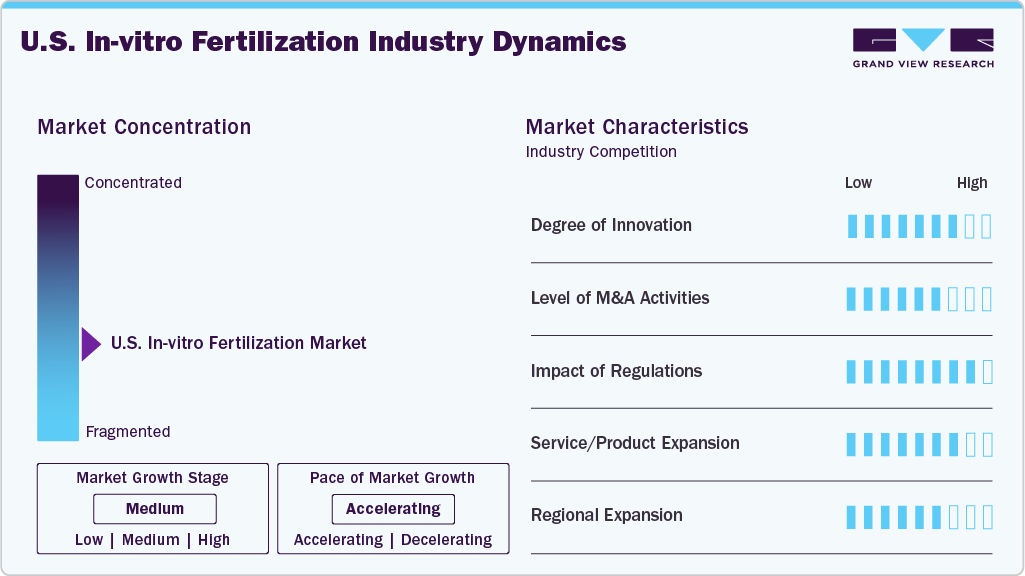
The chart below illustrates the relationship between industry concentration, industry characteristics, and industry participants. The X-axis represents the level of market concentration, ranging from low to high. The Y-axis represents various market characteristics, including industry competition, degree of innovation, level of mergers & acquisition activities, regulatory impact, product substitutes, and regional expansion.
The industry is experiencing continued innovation in embryo assessment, with AI-based tools supporting embryo selection and laboratory decision-making. For instance, in May 2026, Alife Health received FDA clearance for Embryo Predict, an AI-powered software tool that analyzes images of blastocyst-stage embryos and provides additional information to fertility specialists evaluating embryos for transfer or freezing. The product was supported by a randomized, multicenter clinical trial involving 440 patients across seven U.S. clinics. This development highlights the growing role of AI-enabled software in IVF laboratory workflows.
 To learn more about this report, Download Free Sample Report
Fertility care providers are expanding their clinic networks through acquisitions and affiliations, supporting their geographic reach and access to reproductive medicine services. For instance, in February 2026, INVO Fertility completed its acquisition of Family Beginnings, an Indiana-based fertility clinic. The transaction expanded INVO Fertility’s clinic portfolio and strengthened its presence in the Midwest. Such transactions illustrate how providers are using acquisitions to broaden their service networks and patient access.
Regulatory changes affecting insurance coverage are influencing patients’ access to IVF services and may affect treatment affordability. For instance, in January 2026, California’s Senate Bill 729 coverage requirements took effect for applicable large-group health insurance policies issued, amended, or renewed on or after January 1. The law requires coverage for infertility diagnosis and treatment, including IVF, while applicable small-group plans must offer such coverage. These requirements may improve access to treatment for eligible insured patients, although coverage depends on plan eligibility and applicable exclusions.
Companies are expanding fertility-care offerings through digital services and new laboratory technologies, creating additional ways for patients to access treatment and support. For instance, in March 2026, Sesame announced a fertility-care program with Costco and IVI RMA, offering virtual consultations, care coordination, medication management, and referrals to in-person fertility specialists. The program adds a digital access pathway for patients beginning fertility treatment and may help connect them with specialized IVF services.
Fertility providers are opening clinics in new locations to bring reproductive services closer to patients and reduce travel requirements during treatment. For instance, in May 2026, Columbia University Fertility Center announced the opening of a new clinic in Teaneck, New Jersey, which began operating in February 2026. The clinic offers fertility evaluations, IVF-related services, embryo genetic testing, and treatment monitoring, extending the center’s reach to patients in northern New Jersey. This expansion illustrates how providers are broadening their local presence to improve geographic access to fertility care.
Analyst Perspective
The market’s growth potential is increasingly linked to the ability of fertility providers to improve treatment success rates, optimize laboratory processes, and manage the rising complexity of ART procedures. Embryo assessment systems, AI-enabled decision-support tools, and advanced cryopreservation technologies are becoming important areas of differentiation for fertility clinics, creating demand for specialized equipment, software, and laboratory consumables. From a competitive standpoint, suppliers offering integrated ART solutions and technologies that improve workflow efficiency may be better positioned to secure long-term relationships with fertility centers. However, the adoption of advanced technologies remains dependent on clinics’ investment capacity, clinical validation, and compatibility with existing laboratory infrastructure. High out-of-pocket treatment costs and inconsistent insurance coverage also constrain patient volumes and limit the adoption of premium fertility services, making affordability and demonstrable clinical value important factors shaping future market opportunities.
Procedure Type Insights
The fresh non-donor segment accounted for the largest market share of 46.6% in 2025. Fresh cycles are often perceived as more cost-effective due to potentially requiring fewer treatment cycles to achieve a successful pregnancy. In addition, some insurance plans may cover fresh cycles, further supporting demand for fresh non-donor IVF. For instance, in October 2025, US Fertility reported findings from a randomized, double-blind clinical trial involving 400 patients undergoing egg retrieval. The study found comparable reproductive outcomes among patients with proceeded fresh embryo transfer despite differences in postoperative pain-management protocols, providing further clinical evidence on fresh-transfer outcomes.
Frozen donors are expected to register the fastest CAGR during the forecast period, owing to the convenience and flexibility offered by frozen donor eggs. Advances in egg-freezing technology have improved the use of frozen donor eggs in IVF procedures, while egg banks provide recipients with access to donors from different geographic locations and backgrounds. For instance, in March 2026, The World Egg and Sperm Bank launched its Give & Receive program, allowing eligible egg donors to donate eggs to intended parents while preserving a portion of their eggs for their own future use at no cost. This initiative highlights the continued expansion of egg donation and fertility preservation services.
Instruments Insights
The culture media segment dominated the market and accounted for the largest share in 2025. This is attributed to factors such as the availability of funding and an increase in research activities to improve culture media. For instance, in January 2025, FUJIFILM Irvine Scientific announced an agreement to sell its Medical Media Business Unit to Astorg, expanding Astorg’s portfolio of products serving the assisted reproductive technology and IVF industry. The transaction reflects continued strategic investment in the IVF medical media sector.
Disposable devices are expected to grow at the fastest CAGR over the forecast period. The growth is attributed to the introduction of disposable devices, including needles, chambers, and slides, by industry players to comply with sterility and regulatory standards. These advancements are anticipated to boost the adoption of disposable IVF devices. Recent innovations in the market include disposable slides for sperm counting, imaging-based systems for tracking and isolating motile sperm, and disposable microchips.
End-use Insights
The fertility clinics segment dominated the market in 2025 and is expected to grow at the fastest CAGR over the forecast period. This is attributable to increasing demand for ART treatments, expansion of specialized fertility services, and the availability of advanced reproductive technologies at dedicated clinics. Fertility clinics provide comprehensive services, including fertility evaluations, ovarian stimulation, egg retrieval, embryo culture, and embryo transfer, supporting patient access to specialized care. For instance, in April 2026, CCRM Fertility announced the opening of its newest clinic in Greenville, South Carolina, expanding its geographic presence and access to specialized fertility care and reproductive services in the region. Such expansions support the availability of dedicated treatment facilities and strengthen the role of fertility clinics in delivering ART procedures.
 To learn more about this report, Download Free Sample Report
Hospitals and other segments are expected to grow at a significant CAGR over the forecast period. The cost of providing IVF treatments in hospitals is higher compared to fertility clinics due to the presence of highly skilled physicians and staff for performing these complex procedures. Hospitals also offer access to specialized diagnostic facilities, multidisciplinary medical teams, and laboratory infrastructure required for managing patients with complex fertility needs. In addition, the availability of integrated medical services supports IVF treatment for patients requiring additional clinical monitoring or care for underlying reproductive health conditions.
Key U.S. ENT Endoscopy Company Insights
Some of the key players operating in the market include Merck & Co., Inc., FUJIFILM Irvine Scientific (FUJIFILM Holdings Corporation), Vitrolife and others.
-
Merck & Co., Inc., plays a significant role by providing a range of products and services that cater to the needs of fertility clinics and hospitals.
-
FUJIFILM Irvine Scientific specializes in providing innovative cell culture media and reagents for the assisted reproductive technology (ART) field, particularly in vitro fertilization (IVF). The company plays a crucial role in the U.S. IVF market by offering a wide range of products and services that support various stages of the IVF process.
Key U.S. In Vitro Fertilization Companies
-
Bayer AG
-
Cook Medical LLC
-
EMD Serono, Inc.
-
Ferring B.V.
-
FUJIFILM Irvine Scientific (FUJIFILM Holdings Corporation)
-
Genea Biomedx
-
EMD Serono, Inc. (Merck KGaA)
-
Merck & Co., Inc.
-
The Cooper Companies, Inc.
-
Thermo Fisher Scientific, Inc.
-
Vitrolife
-
Nova IVF
-
RMA Network (Reproductive Medicine Associates)
-
U.S. Fertility
Competitive Benchmarking
Category Operating Strategies
Competitive Edge
Weaknesses
Mature players
- Bayer AG
- Cook Medical LLC
- EMD Serono, Inc.
- Ferring B.V.
- FUJIFILM Irvine Scientific
- Merck & Co., Inc.
- The Cooper Companies, Inc.
- Thermo Fisher Scientific, Inc.
- Vitrolife
- RMA Network
- U.S. Fertility
- Bundle drugs, culture media, disposables, and lab equipment into broad portfolios
- Expand through acquisitions, clinic partnerships, and distribution alliances
- Invest in R&D for embryo culture, genetic testing, and AI-enabled lab workflows
- Large installed base and long-standing clinic relationships
- Established FDA clearances, quality systems, and national distribution
- Full-line portfolios, strong R&D, and brand trust
- pressure on drug and consumable prices
- Heavy regulatory and compliance burden (FDA, CLIA, CDC reporting)
- Slower to adopt new formats and automation
Emerging players
- Genea Biomedx
- Nova IVF
- Enter with differentiated culture media, incubators, and lower-cost care models
- Stay compatible with existing clinic lab workflows and equipment
- Grow through new clinic sites, network affiliation, and distributor partnerships
- Agile development for under-served clinics and patients
- Simplified, lower-cost offerings
- Newer technology and early adoption of automation
- Limited brand recognition and clinical evidence in the U.S.
- Smaller sales, service, and training reach
- Narrow portfolio and scale-up risk
Recent Developments
-
In October 2026, IVI RMA North America introduced its Artemis technology platform and AiVA AI Assistant, an AI-powered tool designed to provide clinical insights and support personalized patient care in reproductive medicine.
-
In January 2025, Gameto received FDA clearance for the Investigational New Drug application for Fertilo, enabling the launch of a U.S. Phase 3 clinical trial for its induced pluripotent stem cell-based approach to egg maturation.
-
In January 2025, NewGen IVF announced a strategic acquisition agreement for MicroSort, a sperm-sorting technology that separates X- and Y-chromosome-bearing sperm cells to support selected reproductive applications. The acquisition was completed in February 2025.
-
In January 2024, IVI RMA announced the acquisition of the North American Operations of Eugin Group, comprising the Toronto-based TRIO and Boston IVF fertility network. The strategy is aimed at providing evidence-based fertility solutions along with assuring success for a large number of patients.
U.S. In-vitro Fertilization Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.9 Billion
Estimated market size in 2026
USD 6.2 Billion
Projected market size by 2033
USD 8.0 Billion
Growth Rate
CAGR of 3.7% from 2026 to 2033
Actual data
2021 - 2025
Forecast data
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Procedure type, instruments, end-use
Regional scope
U.S.
Key companies profiled
Bayer AG; Cook Medical LLC; EMD Serono, Inc.; Ferring B.V.; FUJIFILM Irvine Scientific (FUJIFILM Holdings Corporation); Genea Biomedx; EMD Serono, Inc. (Merck KGaA); Merck & Co., Inc.; The Cooper Companies, Inc.; Thermo Fisher Scientific, Inc.; Vitrolife
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. In-vitro Fertilization Market Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global U.S. in-vitro fertilization (IVF) market report based on instruments, procedure type, and end-use:
-
Instrument Outlook (Revenue, USD Billion, 2021 - 2033)
-
Disposable Devices
-
Culture Media
-
Cryopreservation Media
-
Embryo Culture Media
-
Ovum Processing Media
-
Sperm Processing Media
-
-
Capital Equipment
-
Sperm Analyzer Systems
-
Imaging Systems
-
Ovum Aspiration Pumps
-
Micromanipulator Systems
-
Incubators
-
Gas Analyzers
-
Laser Systems
-
Cryosystems
-
Sperm Separation Devices
-
IVF Cabinets
-
Anti-vibration Tables
-
Witness Systems
-
Other
-
-
-
Procedure Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Fresh Donor
-
Frozen Donor
-
Fresh Non-Donor
-
Frozen Non-Donor
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Fertility Clinics
-
Hospitals & Others Setting
-
Research Methodology
The U.S. in vitro fertilization market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. in vitro fertilization segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Instrument
Revenue capture definition
Disposable Devices
Single-use consumables and media used across IVF laboratory and clinical workflows, including culture media for handling, culturing, and storing gametes and embryos. Revenue is recurring and tied to the number of IVF cycles performed.
Culture Media
Specially formulated solutions that support gametes and embryos outside the body by providing nutrients, pH buffering, and osmotic balance. Revenue covers the media used at each stage of an IVF cycle, from sperm and ovum processing to embryo culture and cryopreservation.
Cryopreservation Media
Solutions used to freeze and thaw oocytes, sperm, and embryos, including vitrification and warming media containing cryoprotectants. These are used in egg freezing, embryo banking, and frozen embryo transfer cycles.
Embryo Culture Media
Media that support fertilized oocytes and embryos from fertilization through the cleavage and blastocyst stages. These include single-step and sequential media used in incubators.
Ovum Processing Media
Media used to collect, wash, hold, and prepare oocytes after retrieval and before fertilization, such as flushing, handling, and fertilization media.
Sperm Processing Media
Media used to wash, separate, and prepare sperm for IVF, ICSI, and IUI, including density gradient and swim-up media that isolate motile sperm and remove seminal fluid.
Capital Equipment
Reusable laboratory and clinical instruments used to retrieve, assess, manipulate, culture, and store gametes and embryos. Revenue is driven by new clinic setups, lab expansions, and replacement of ageing equipment.
Sperm Analyzer
Systems that measure sperm concentration, motility, and morphology, often automated or computer-assisted. They are used for male fertility evaluation and sperm selection.
Imaging Systems
Ultrasound and microscopy systems used for follicle monitoring, oocyte retrieval guidance, and embryo observation, including time-lapse imaging platforms.
Ovum Aspiration Pumps
Controlled vacuum pumps used during transvaginal oocyte retrieval to aspirate follicular fluid and oocytes at regulated pressure.
Micromanipulator Systems
Precision systems that hold and position oocytes and sperm for ICSI, embryo biopsy, and assisted hatching. They are mounted on microscopes.
Incubators
Temperature- and gas-controlled chambers that maintain stable conditions for fertilization and embryo development, including benchtop, multi-gas, and time-lapse incubators.
Gas Analyzers
Devices that measure and verify CO₂, O₂, and nitrogen levels in incubators. They are used for lab quality control and calibration.
Laser Systems
Laser tools used for assisted hatching, embryo biopsy, and ICSI-related procedures, as an alternative to mechanical or chemical techniques.
Cryosystems
Equipment for freezing and storing gametes and embryos, including controlled-rate freezers, vitrification tools, and liquid nitrogen storage tanks.
Sperm Separation Devices
Devices that isolate high-quality motile sperm from semen, including microfluidic and filtration-based systems used in IVF, ICSI, and IUI.
Segment - Procedure Type
Revenue capture definition
Fresh Donor
IVF cycles embryos are created from freshly retrieved donor oocytes, or fresh donor sperm, and transferred without freezing. Revenue covers the associated procedures, laboratory work, media, and consumables.
Frozen Donor
IVF cycles using cryopreserved donor oocytes, donor sperm, or donor embryos that are thawed before fertilization or transfer. This segment includes the use of donor banks.
Fresh Non-Donor
IVF cycles is a patient’s own freshly retrieved oocytes are fertilized and the resulting embryo is transferred in the same cycle.
Frozen Non-Donor
IVF cycles is a patients own previously cryopreserved oocytes or embryos are thawed and transferred. This includes frozen embryo transfers and cycles that follow a freeze-all strategy.
Segment - End-Use
Revenue capture definition
Fertility Clinics
Specialized reproductive medicine centers and clinic networks that provide IVF, diagnostics, and fertility preservation. Revenue captured is from IVF procedures, instruments, and consumables used in these settings, accounted for most U.S. IVF activity.
Hospitals & Others Setting
IVF services delivered in hospital-based fertility programs, academic medical centers, and other settings such as research institutes and cryobanks.
Estimation Model
More Details
This research methodology outlines the process for estimating the size of the U.S. in vitro fertilization (IVF) market from 2021 to 2033. The study covers key instrument categories, including Culture Media, Disposable Devices, and Capital Equipment; procedure types, including Fresh Donor, Frozen Donor, Fresh Non-Donor, and Frozen Non-Donor; and end-use settings, including Fertility Clinics and Hospitals & Other Settings.
The objective is to develop a robust and defensible market estimate by combining bottom-up and top-down approaches, supported by primary industry validation.
A triangulated market-sizing approach was used, combining:
-
Bottom-Up Analysis based on IVF treatment cycle volumes, procedure mix, fertility clinic activity, instrument utilization, sales of IVF consumables and equipment, average selling prices, and revenues generated across the value chain.
-
Top-Down Analysis using U.S. IVF treatment expenditure, assisted reproductive technology (ART) cycle statistics, fertility treatment spending, healthcare expenditure, insurance coverage, patient demographics, and revenues reported by IVF service providers and product manufacturers.
-
Primary Research with fertility clinic operators, reproductive endocrinologists, embryologists, IVF laboratory managers, medical device manufacturers, culture media suppliers, distributors, industry consultants, and other market participants.
Step-by-Step Market Estimation Process
IVF Treatment Cycle Volume and Procedure Revenue Model
This model estimates the market size based on the number of IVF treatment cycles performed annually and the average revenue generated per treatment cycle.
Step 1: Historical U.S. IVF treatment cycle volumes from 2021 to 2025 were collected from national ART registry reports, government databases, fertility societies, clinic disclosures, published research, and other relevant industry sources.
Step 2: Treatment cycles were classified by procedure type, including Fresh Donor, Frozen Donor, Fresh Non-Donor, and Frozen Non-Donor. Cycle volumes were estimated using available ART statistics, donor egg utilization, embryo transfer data, fertility clinic reports, and primary interviews.
Step 3: Average revenue per IVF cycle was estimated using treatment charges, ovarian stimulation and monitoring costs, egg retrieval, fertilization procedures, embryo culture, embryo transfer, cryopreservation, laboratory services, and other relevant treatment-related charges.
Step 4: Market size was calculated using:
Number of IVF Treatment Cycles × Average Revenue per IVF Treatment Cycle
Step 5: Procedure-level estimates were aggregated and reconciled with national IVF expenditure and available industry revenue data to establish the overall U.S. market size.
Step 6: Historical and forecast growth rates were incorporated based on ART treatment volumes, infertility prevalence, patient age profiles, insurance coverage, treatment affordability, procedure mix, and changes in fertility treatment utilization.
IVF Instrument Revenue Model
This model estimates the market size based on revenues generated by instruments and consumables used during IVF procedures.
Step 1: The market was classified into the following instrument categories:
-
Culture Media
-
Disposable Devices
-
Capital Equipment
Step 2: Product-level information was collected from manufacturer disclosures, product catalogs, regulatory databases, distributor information, company reports, industry databases, and primary interviews.
Step 3: Product demand was estimated using IVF laboratory volumes, treatment cycles, equipment installations, product replacement requirements, consumable usage per cycle, and utilization rates across fertility clinics and hospitals.
Step 4: Average selling prices were estimated using manufacturer pricing information, distributor quotations, procurement benchmarks, product specifications, and primary research.
Step 5: Instrument market revenue was calculated using:
Units Sold × Average Selling Price
For consumables, estimates also considered the number of IVF cycles and the average quantity of products used per cycle. For capital equipment, the model considered installations, replacement purchases, and average equipment prices.
Step 6: Revenue estimates were aggregated across product categories and reconciled with overall market estimates. Forecast assumptions incorporated changes in IVF procedure volumes, laboratory capacity, product replacement cycles, consumable usage, equipment purchases, and technology adoption.
Culture Media Revenue Model
This model estimates market revenues generated by culture media used during different stages of IVF treatment.
Step 1: Culture media demand was assessed across relevant applications, including embryo culture, sperm processing, ovum processing, and cryopreservation.
Step 2: Product utilization was estimated using IVF cycle volumes, laboratory protocols, media requirements per procedure, product usage rates, and information obtained from manufacturers and fertility clinics.
Step 3: Average selling prices were estimated based on product type, packaging, usage volume, supplier pricing, and available procurement benchmarks.
Step 4: Culture media revenue was calculated using:
Volume of Culture Media Sold × Average Selling Price
Step 5: Revenue estimates were aggregated and reconciled with the overall instrument market to maintain consistency and avoid double counting.
Step 6: Forecast assumptions considered changes in IVF cycle volumes, laboratory throughput, media consumption, product pricing, embryo culture practices, and demand for specialized reproductive laboratory consumables.
Disposable Devices Revenue Model
This model estimates market size based on single-use devices used during IVF procedures.
Step 1: Disposable devices were assessed across relevant product categories, including embryo transfer catheters, needles, pipettes, aspiration-related products, and other single-use IVF devices.
Step 2: Product demand was estimated using IVF cycle volumes, the number of procedures performed, device usage per cycle, replacement requirements, and purchasing patterns among fertility clinics and hospitals.
Step 3: Average selling prices were estimated using manufacturer and distributor pricing, procurement information, product specifications, and primary interviews.
Step 4: Market revenue was calculated using:
Number of Disposable Devices Sold × Average Selling Price per Device
Step 5: Product-level revenues were aggregated to determine total disposable device revenue and cross-checked against overall instrument market estimates.
Step 6: Forecast assumptions incorporated IVF procedure volumes, sterility requirements, single-use product preferences, product availability, purchasing patterns, and changes in disposable device utilization.
Capital Equipment Revenue Model
This model estimates market size based on equipment used in IVF laboratories and clinical procedures.
Step 1: Capital equipment was assessed across relevant categories, including incubators, imaging systems, sperm analyzers, micromanipulator systems, ovum aspiration pumps, cryosystems, laser systems, and other IVF laboratory equipment.
Step 2: Equipment demand was estimated using fertility clinic numbers, laboratory installations, equipment utilization, replacement cycles, facility expansion, and procurement information.
Step 3: Average selling prices were estimated using manufacturer disclosures, distributor quotations, equipment specifications, procurement benchmarks, and primary research.
Step 4: Market revenue was calculated using:
Number of Equipment Units Sold × Average Selling Price per Unit
Step 5: Equipment revenues were aggregated and reconciled with total instrument market estimates.
Step 6: Forecast assumptions considered new fertility laboratory openings, capacity expansion, equipment replacement, laboratory automation, imaging requirements, and investment in advanced reproductive technologies.
End-Use-Based Market Estimation
This model estimates market size based on revenues generated by facilities providing IVF treatments.
Step 1: The market was segmented into:
-
Fertility Clinics
-
Hospitals & Other Settings
Step 2: Facility-level data were collected from fertility clinic directories, hospital databases, ART registries, provider disclosures, company reports, and industry sources.
Step 3: IVF treatment volumes and average revenue per cycle were estimated separately for fertility clinics and hospitals & other settings using facility activity, procedure mix, laboratory capacity, treatment pricing, and primary interviews.
Step 4: End-use revenue was calculated using:
Number of IVF Treatment Cycles by Setting × Average Revenue per Cycle
Step 5: Facility-level estimates were aggregated to determine total end-use revenue and reconciled with national IVF market estimates.
Step 6: Forecast assumptions considered fertility clinic expansion, hospital-based reproductive services, patient access, availability of specialized medical staff, laboratory infrastructure, and changes in treatment volumes across care settings.
Market Validation and Forecasting
The estimates derived from the IVF treatment cycle model, instrument revenue model, culture media model, disposable device model, capital equipment model, and end-use model were cross-validated through data triangulation. Findings were further verified through primary interviews with fertility clinic operators, reproductive endocrinologists, embryologists, laboratory managers, product manufacturers, distributors, and industry consultants.
Final market forecasts were developed by evaluating historical IVF cycle volumes, infertility trends, treatment affordability, insurance coverage, procedure mix, instrument utilization, product pricing, fertility clinic expansion, and investment in reproductive medicine.
Forecast assumptions also considered changes in patient demographics, demand for donor and non-donor procedures, fresh and frozen treatment cycles, advances in embryo culture and cryopreservation, use of single-use IVF devices, equipment replacement, laboratory expansion, and changes in healthcare spending through 2033. The model incorporated product-level demand, end-use distribution, provider activity, and procedure volumes to maintain consistency between segment estimates and the overall market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Coverage: Northeast, Southeast, Midwest, Southwest, and West (Note: Market estimates and forecasts will be provided at the overall U.S. level and at the regional level for each covered segment.)
Delivered a customized regional analysis of the U.S. In-vitro Fertilization (IVF) Market across the Northeast, Southeast, Midwest, Southwest, and West. Revenue estimates (2021-2025) and forecasts (2026-2033) in USD million are provided at the overall U.S. level and at the regional level for each covered segment.
Enables stakeholders to compare regional market size, identify areas with higher IVF demand, and support regional sales, distribution, and resource allocation strategies.
Installed Capital Equipment Base (2021-2033)
Delivered an analysis of the installed IVF capital equipment base for 2021-2033 at the overall U.S. level and at the regional level for each covered segment. The analysis captures the installed base of incubators, imaging systems, micromanipulator systems, laser systems, cryosystems, and other instruments across fertility clinics and hospital settings, and reflects replacement requirements over the forecast period.
Helps manufacturers and distributors assess the existing equipment base, replacement demand, and future servicing, upgrade, and procurement requirements.
Realized ASP / Price Range (USD), 2021-2033
Provided realized average selling price (ASP) and price range analysis in USD for 2021-2033 at the overall U.S. level and at the regional level for each covered segment. The analysis reflects differences in pricing across disposable devices, culture media, and capital equipment.
Supports pricing assessment, revenue modeling, margin analysis, and evaluation of pricing differences across product segments.
Number of Units Sold (2021-2033, in 000’s)
Delivered unit sales analysis in 000’s for 2021-2033 at the overall U.S. level and at the regional level for each covered segment. The analysis covers sales of disposable devices, culture media, and capital equipment, and reflects new procurement, replacement demand, and consumable use across IVF cycles.
Enables stakeholders to quantify unit demand, assess procurement patterns, and align production, inventory, distribution, and sales planning with market requirements.
Annual IVF Procedure Volume (2021-2033, in 000’s)
Provided annual IVF procedure volume in 000’s for 2021-2033 at the overall U.S. level and at the regional level for each covered segment. The analysis captures cycle activity across fresh donor, frozen donor, fresh non-donor, and frozen non-donor procedures and across fertility clinics and hospital settings.
Helps stakeholders connect procedure growth with instrument and consumable demand, estimate utilization levels, and assess the relationship between clinical activity and product sales.
Frequently Asked Questions About This Report
The U.S. in vitro fertilization market size was valued at USD 5.9 billion in 2025.
The U.S. in vitro fertilization market is projected to grow at a compound annual growth rate (CAGR) of CAGR of 3.7% from 2026 to 203 to reach USD 8.0 billion by 2033.
The culture media segment dominated the market and accounted for the largest share in 2025.
Some of the key players operating in the U.S. IVF market include Microsoft Corporation; Merck & Co., Inc., FUJIFILM Irvine Scientific (FUJIFILM Holdings Corporation), and Vitrolife, among others.
The rising prevalence of infertility among couples is one of the primary drivers for the growth of the U.S. IVF market. According to the CCRM Fertility article published in June 2022, over 10% of women and around 9% of men suffer with infertility issues. Over 10% of females falling in the age group of 15 to 45 in the U.S. faces infertility.
In terms of procedure type, fresh nondonor segment dominated the market and accounted for a share of around 46.6% in 2025.
In terms of end use, the fertility clinics segment dominated the market with the largest share of 80.1% in 2025. This is attributed to factors such as the availability of funding and an increase in research activities to improve culture media.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


