
- Home
- »
- Clinical Diagnostics
- »
-
U.S. Infectious Respiratory Disease Diagnostics Market, 2033GVR Report cover

U.S. Infectious Respiratory Disease Diagnostics Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Instruments, Reagents, Services), By Technology (Molecular Diagnostics, Immunoassays, Microbiology), By Application (COVID-19, Influenza, Tuberculosis), By End-use, And Segment Forecasts
U.S. Infectious Respiratory Disease Diagnostics Market Summary
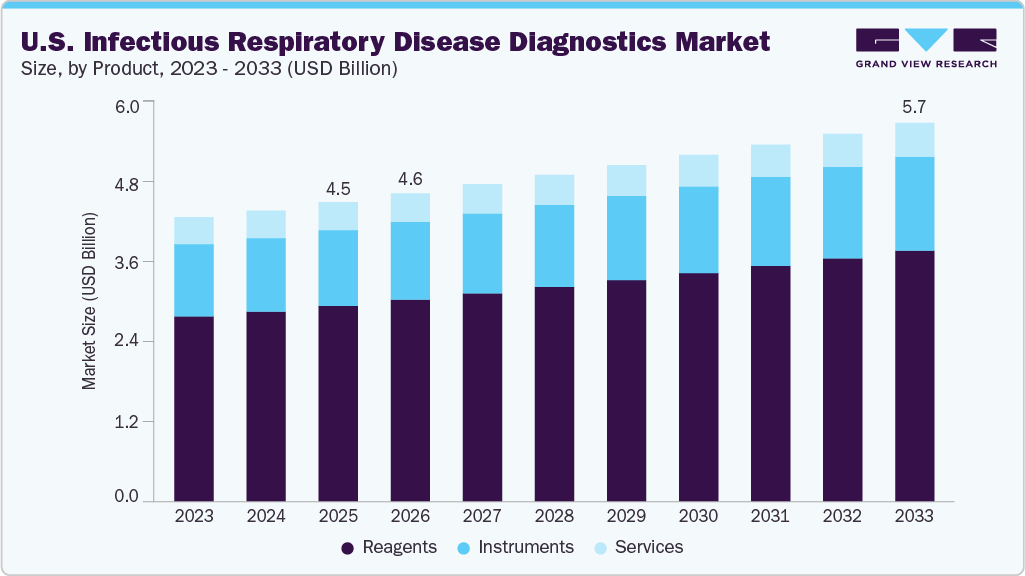
The U.S. infectious respiratory disease diagnostics market size was estimated at USD 4.5 billion in 2025 and is projected to reach USD 5.7 billion by 2033, growing at a CAGR of 3.0% from 2026 to 2033, driven by the sustained and recurring burden of viral and bacterial respiratory infections, including influenza, respiratory syncytial virus (RSV), COVID-19, tuberculosis, and other emerging respiratory pathogens. Seasonal outbreaks, periodic waves of respiratory infections, and increasing urbanization have strengthened the demand for early, accurate, and scalable diagnostic solutions across hospitals, public health laboratories, and decentralized care settings throughout the U.S.
Key Market Trends & Insights
- Based on product, the reagents segment dominated the market with a 65.38% revenue share in 2025.
- Based on technology, the molecular diagnostics diagnosis segment held the largest revenue share of 67.82% in 2025.
- Based on application, the COVID-19 segment held the largest revenue share of 46.25% in 2025.
Market Size & Forecast
- 2025 Market Size: USD 4.5 Billion
- 2026 Estimated Market Size: USD 4.6 Billion
- 2033 Projected Market Size: USD 5.7 Billion
- CAGR (2026-2033): 3.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The industry is driven by the high and persistent burden of respiratory infections, which continues to generate strong demand for accurate and rapid diagnostic solutions. Diseases such as influenza, RSV, tuberculosis, and bacterial pneumonia contribute significantly to healthcare utilization across the country. For instance, RSV alone leads to approximately 177,000 hospitalizations and 14,000 deaths annually among adults aged 65 years and older in the U.S., while the CDC estimated around 40 million influenza cases and over 470,000 hospitalizations during the 2023-2024 season. This sustained disease prevalence reinforces the need for reliable diagnostics across hospitals, outpatient settings, and public health surveillance programs.Technological advancements are significantly reshaping the market landscape, with a clear transition toward multiplex molecular diagnostics and automated platforms. Modern diagnostic systems now enable simultaneous detection of multiple pathogens such as SARS-CoV-2, influenza A/B, and RSV from a single sample, improving clinical decision-making and reducing turnaround times. For example, Roche’s cobas Respiratory 4-flex test, which received FDA 510(k) clearance in August 2025, can identify four major respiratory viruses in one run, while the upgraded cobas 6800/8800 systems launched in December 2025 enhance laboratory productivity and efficiency. These innovations, along with automation and sequencing technologies, are enabling laboratories to handle higher testing volumes and improve diagnostic accuracy.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Rising investments in research and development are further accelerating market growth by supporting innovation in diagnostic platforms and expanding testing capabilities. Government agencies, nonprofit organizations, and private companies are increasingly funding initiatives to improve early detection and disease monitoring. In October 2025, the American Lung Association invested USD 22 million in research grants supporting over 130 scientists working on respiratory diseases, including diagnostic advancements. Additionally, public-private partnerships and pharmaceutical collaborations are fostering the development of companion diagnostics for RSV, influenza, and COVID-19, enhancing both clinical trials and post-market surveillance.
Furthermore, increasing government support and funding for infectious disease control programs, particularly for tuberculosis, is strengthening diagnostic infrastructure and expanding access to testing. The U.S. government allocates over USD 400 million annually toward TB programs through organizations such as U.S.AID and the Global Fund, promoting better detection and management. Combined with the growing focus on antimicrobial resistance and rapid pathogen identification highlighted by innovations such as NG Biotech’s rapid assays for drug-resistant infections receiving FDA Breakthrough Device Designation in February 2026, the market is expected to witness sustained growth, supported by continuous technological evolution and strong institutional backing.
Market Concentration & Characteristics
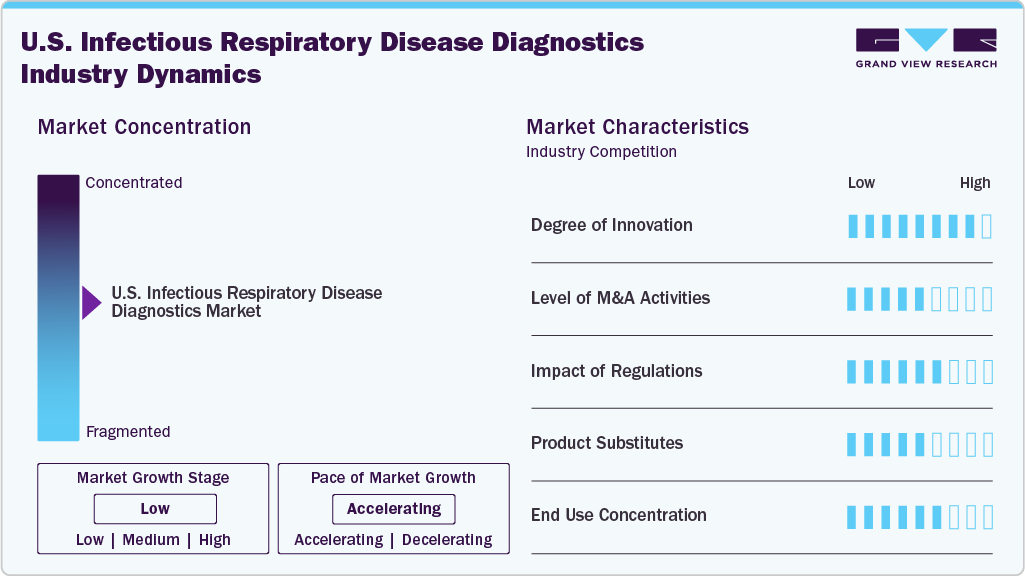
Innovation in the U.S. infectious respiratory disease diagnostics industry remains at a high level, driven by continuous advancements in molecular diagnostics, multiplex testing platforms, and point-of-care technologies. The market is characterized by the rapid evolution from single-pathogen testing toward syndromic multiplex panels capable of detecting multiple respiratory pathogens such as SARS-CoV-2, influenza A/B, and RSV from a single sample. Advancements in automation, sequencing, and digital microbiology are significantly improving diagnostic speed, accuracy, and laboratory efficiency. For instance, as highlighted in the report, in February 2026, Roche’s cobas Respiratory 4-flex test (August 2025) enables simultaneous detection of four major respiratory viruses in a single run, while NG Biotech’s rapid assays can detect multidrug-resistant pathogens in approximately 15 minutes without PCR. These innovations are enhancing clinical decision-making, supporting antimicrobial stewardship, and strengthening competitive differentiation among diagnostic manufacturers.
The industry exhibits a moderately consolidated yet competitive structure, with the presence of large multinational diagnostics companies alongside specialized assay and platform developers. Key players such as Abbott, Thermo Fisher Scientific, Roche, BD, bioMérieux, and Danaher (Cepheid) dominate through extensive product portfolios spanning molecular diagnostics, immunoassays, and rapid testing solutions. According to the report, companies are actively adopting product launches, regulatory approvals, and strategic partnerships as core growth strategies, particularly to expand multiplex testing capabilities and point-of-care offerings. Collaborations with hospitals, diagnostic laboratories, and public health agencies play a critical role in expanding testing access and scaling diagnostic infrastructure, especially during seasonal outbreaks and public health emergencies. This ecosystem supports steady market expansion while maintaining strong competitive intensity.
 To learn more about this report, Download Free Sample Report
The regulatory environment plays a pivotal role in shaping market dynamics, acting as both a growth enabler and a barrier to entry. Regulatory bodies such as the U.S. FDA and CMS enforce stringent requirements for clinical validation, performance evaluation, and post-market surveillance of diagnostic tests. While Emergency Use Authorizations (EUAs) accelerated innovation during the COVID-19 pandemic, post-pandemic regulatory pathways have become more rigorous, requiring multicenter trials and validation across multiple pathogens and variants. Additionally, CLIA regulations govern laboratory testing standards, influencing adoption across point-of-care and high-complexity laboratory settings. Reimbursement policies under Medicare, Medicaid, and private insurers further impact market penetration, as coverage decisions and pricing frameworks determine the adoption of advanced diagnostics such as multiplex PCR panels and rapid molecular tests.
The industry demonstrates moderate substitutability, with multiple diagnostic technologies available but limited alternatives outside established in-vitro diagnostic approaches. Internal substitution occurs across molecular diagnostics, immunoassays, microbiology, and rapid/point-of-care tests, depending on clinical requirements, turnaround time, and cost considerations. Molecular diagnostics dominate due to their high sensitivity and early detection capabilities, accounting for a significant share of the market, while rapid antigen and point-of-care tests are widely used for decentralized and immediate testing needs. Additionally, the growing adoption of integrated and combination diagnostic approaches, including multiplex panels and automated high-throughput systems, is reshaping testing workflows and improving efficiency. This evolving landscape continues to influence procurement decisions and drive innovation across hospitals, diagnostic laboratories, and public health systems.
Product Insights
The reagents segment dominated the market with a 65.38% revenue share in 2025, due to the rising volume of infectious respiratory disease testing in hospitals, diagnostic laboratories, and point-of-care settings. Frequent use and ongoing replenishment of reagents for molecular and immunoassay tests further drive sustained demand across diagnostic fields workflows. The increasing demand for multiplex and automated molecular diagnostic solutions is driving market growth, as healthcare providers seek to improve diagnostic accuracy, shorten testing times, and better manage patient care in high-volume clinical settings. In August 2025, Roche received FDA clearance for its cobas Respiratory 4-flex assay, which enabled simultaneous detection of four major respiratory viruses using TAGS technology, improving diagnostic accuracy, streamlining laboratory workflows, and supporting faster, targeted treatment decisions in healthcare settings.
Furthermore, the instruments segment is expected to grow steadily, driven by demand for rapid, accurate, and wide-ranging respiratory pathogen detection. Clinicians increasingly require quick identification of infection-causing pathogens, especially in high-acuity environments like emergency departments, ICUs, and pediatric care units, where timely treatment decisions are critical. The market is driven by the availability of advanced multiplex diagnostic instruments. In May 2024, QIAGEN received FDA clearance for the QIAstat-Dx Respiratory Panel Plus, which enabled rapid detection of 21 viral and bacterial respiratory pathogens in about one hour, supporting clinical decision-making, improving co-infection detection, and enhancing antimicrobial stewardship in healthcare systems. These systems allow hospitals and laboratories to reduce testing time while improving clinical outcomes, encouraging investment in automated diagnostic instruments.
Technology Insights
The molecular diagnostics segment held the largest revenue share of 67.82% in 2025. The increasing threat of new and returning respiratory infections is prompting diagnostic companies to create rapid molecular testing solutions. PCR-based technologies allow for early detection of new pathogens, aiding quicker outbreak responses, better surveillance, and timely clinical decisions across healthcare systems. For instance, in April 2025, HealthTrackRx partnered with the Centers for Disease Control and Prevention to develop a rapid PCR diagnostic test for Avian Influenza A (H5N1), enabling earlier detection of infections and strengthening the U.S. capacity to monitor and respond to emerging respiratory disease outbreaks.
The rapid/point-of-care diagnostics segment is expected to grow at the fastest CAGR of 7.14% during the forecast period, driven by the growing focus on test-to-treat strategies and early detection of respiratory viral. These technologies enable clinicians to quickly identify respiratory pathogens and initiate targeted treatment, improving clinical outcomes, reducing hospitalizations, and supporting efficient clinical trial workflows. The increasing focus on improving clinical decision-making speed and supporting antimicrobial stewardship is driving the adoption of rapid point-of-care diagnostic solutions in the U.S. respiratory disease diagnostics market. Healthcare providers are increasingly adopting POC tests that can differentiate between bacterial and viral infections within minutes, enabling appropriate antibiotic use, improving patient outcomes, and reducing the risk of antimicrobial resistance. For instance, in July 2025, PHASE Scientific launched FebriDx, a rapid point-of-care diagnostic test for respiratory infections in the U.S. through an exclusive distribution partnership with Lumos Diagnostics.
Application Insights
COVID-19 continues to be the largest segment, with a 46.25% revenue share in 2025. This is driven by the ongoing need for disease surveillance, clinical diagnosis, and monitoring of new variants. Although large-scale testing demand has decreased since the pandemic's peak, diagnostic testing still plays a vital role in managing respiratory diseases in hospitals, clinical laboratories, and point-of-care settings. Healthcare providers depend on diagnostic testing to distinguish COVID-19 from other respiratory infections like influenza and respiratory syncytial virus (RSV), especially during seasonal surges of respiratory viruses.
Tuberculosis is a significant segment in the U.S. market, as early detection and surveillance are vital for stopping disease spread. Although the rate of tuberculosis in the U.S. is lower than in high-burden areas, it still presents public health challenges, especially among high-risk groups such as immunocompromised individuals, foreign-born populations, and those living in congregate settings. According to the Centers for Disease Control and Prevention, 2024 reported 9,615 tuberculosis cases in 2023, corresponding to an incidence rate of approximately 2.9 cases per 100,000 population. Ongoing surveillance and screening efforts are crucial to prevent outbreaks and aid in the nation’s tuberculosis elimination goals. The increasing demand for improved tuberculosis diagnostics in the U.S. fuels market expansion.
End-use Insights
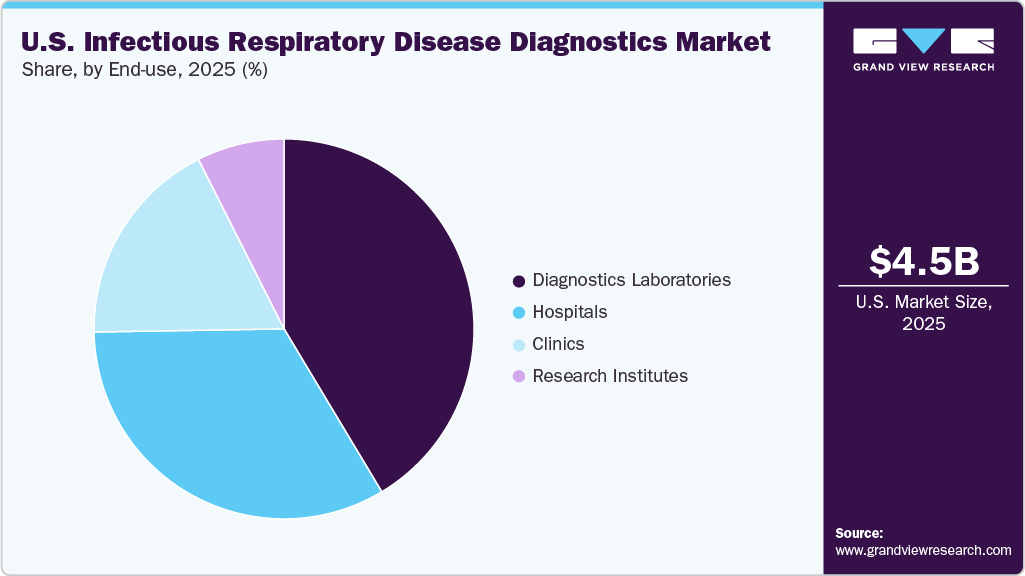
Diagnostic laboratories led the U.S. market with a share of 41.40% in 2025, due to the ongoing spread of respiratory infections, rising demand for precise pathogen detection, and the adoption of advanced molecular and multiplex testing technologies. Post-pandemic healthcare awareness has enhanced public health surveillance, and a growing aging population is also contributing to increased diagnostic testing volumes. Major U.S. diagnostic laboratory networks such as Labcorp and Quest Diagnostics perform millions of infectious disease tests annually and have significantly expanded their respiratory testing capabilities after the COVID-19 pandemic. For instance, Quest Diagnostics operates more than 2,000 patient service centers across the U.S. and performs over 200 million tests annually for patients across all age groups, supporting large-scale respiratory disease detection.
 To learn more about this report, Download Free Sample Report
The hospital segment holds a significant share in the U.S. market in 2025 as hospitals rely on advanced diagnostic technologies to ensure early and accurate detection of respiratory infections. With rising patient inflows, greater disease complexity, and the need for quick clinical decisions, hospitals are investing heavily in advanced molecular assays, imaging systems, and rapid point-of-care diagnostic tools. These capabilities enable clinicians to identify infections such as influenza, pneumonia, tuberculosis, and emerging viral diseases at their earliest stages, improving treatment outcomes and reducing the risk of complications.
Key U.S. Infectious Respiratory Disease Diagnostics Company Insights
Some of the leading players operating in the U.S. infectious respiratory disease diagnostics market include Abbott, Siemens Healthineers AG, and QIAGEN. Companies focus on capturing the market by increasing their presence using various business initiatives, such as partnerships & collaborations with the government. Moreover, these companies have a well-established product portfolio, which helps capture major market share.
QuidelOrtho Corporation, BD, Cepheid (Danaher Corporation) are some of the emerging market participants in the U.S. infectious respiratory disease diagnostics market. Developing & launching new and improved diagnostic tools that offer faster results, higher accuracy, and easier usability are observed as prevalent operating strategies by these companies. The players may face challenges in penetrating the market due to competition and regulatory hurdles.
Key U.S. Infectious Respiratory Disease Diagnostics Companies:
- Abbott
- Bio-Rad Laboratories, Inc
- Siemens Healthineers AG
- BIOMÉRIEUX
- BD
- QIAGEN
- QuidelOrtho Corporation
- F. Hoffmann-La Roche
- Koninklijke Philips N.V.
- Cepheid (Danaher Corporation)
Recent Developments
-
In December 2025, BD launched enhancements to its BD MAX molecular diagnostic system, enabling laboratories to conduct high-throughput respiratory pathogen detection with improved automation and workflow efficiency.
-
In April 2025, bioMérieux launched WATCHFIRE, a molecular testing solution (22-target respiratory panel) that runs on the BIOFIRE FILMARRAY TORCH and integrates with FIREWORKS software for real-time wastewater surveillance/outbreak detection.
-
In February 2025, Thermo Fisher’s TaqPath COVID-19, Flu A, Flu B, RSV Select Panel progressed from EUA/CE status to FDA 510(k) clearance, enabling broader clinical IVD adoption in the U.S.
-
In January 2025, Thermo Fisher entered into a collaboration with leading clinical laboratories in the U.S. to expand access to multiplex molecular respiratory testing solutions and strengthen diagnostic capacity for infectious respiratory diseases.
U.S. Infectious Respiratory Disease Diagnostics Market Report Scope
Report Attribute
Details
Market Size in 2025
USD 4.5 billion
Estimated Market size in 2026
USD 4.6 billion
Revenue forecast in 2033
USD 5.7 billion
Growth rate
CAGR 3.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, application, end-use
Country scope
U.S.
Key companies profiled
Abbott; Bio-Rad Laboratories, Inc; Siemens Healthineers AG; BIOMÉRIEUX; BD; QIAGEN; QuidelOrtho Corporation; F. Hoffmann-La Roche; Koninklijke Philips N.V.; Cepheid (Danaher Corporation)
Customization scope
Free report customization (equivalent to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
U.S. Infectious Respiratory Disease Diagnostics Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. infectious respiratory disease diagnostics market report on the basis of product, technology, end-use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments
-
Reagents
-
Services
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Molecular Diagnostics
-
Immunoassays
-
Microbiology
-
Rapid/Point-of-Care Diagnostics
-
Other Technologies
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
COVID-19
-
Influenza
-
Tuberculosis
-
Respiratory Syncytial Virus (RSV)
-
Non-tuberculosis Mycobacterium Testing
-
Bacterial Pneumonia Testing
-
Other Respiratory Diseases
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Diagnostics Laboratories
-
Research Institutes
-
Frequently Asked Questions About This Report
The U.S. infectious respiratory disease diagnostics market is expected to grow at a compound annual growth rate of 3.0% from 2026 to 2033 to reach USD 5.7 billion by 2033.
Based on technology, molecular diagnostics accounted for the largest share of 67.8% in 2025, owing to the high usage of PCR tests for Covid-19 testing.
Some key players in space include Abbott; Bio-Rad Laboratories, Inc; Siemens Healthineers AG; BIOMÉRIEUX; BD; QIAGEN; QuidelOrtho Corporation; F. Hoffmann-La Roche; Koninklijke Philips N.V.; and Cepheid (Danaher Corporation).
Key factors that are driving the U.S. infectious respiratory disease diagnostics market growth include rising disease prevalence and approval of multiplex tests for the simultaneous diagnosis of RSV & influenza.
The U.S. infectious respiratory disease diagnostics market size was estimated at USD 4.5 billion in 2025 and is expected to reach USD 4.6 billion in 2026
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


